68.7 F
Chicago
Saturday, October 10, 2026
Home Blog Page 1089

Futures Slide As Trade War Jitters Return, Q3 Earnings Begin, Powell Speaks

0
Futures Slide As Trade War Jitters Return, Q3 Earnings Begin, Powell Speaks

The market rollercoaster continues: after Monday’s faceripping bounce, US equity futures are lower again led by tech, part of a global risk-off tone as the US/China trade war returned after Beijing vowed to “fight to the end” in the tariff and trade war, while acknowledging that the door for negotiation is open and trade talks between the two countries had resumed yesterday. Beijing also imposed curbs on the American units of Hanwha Ocean, one of South Korea’s biggest shipbuilders, as it targets US measures against the Chinese shipping sector. As of 8:00am ET, S&P futures are down 0.9% and near session lows as market may be reading the latest response by China as an ‘escalate to de-escalate’ ahead of the Trump / Xi mtg later this month. Nasdaq 100 futs were 1.1% lower with all members of the Magnificent Seven sliding in premarket trading, while European stocks slipped 0.7%. Bond yields are lower as the curve bull steepens, pushing 10Y yields briefly below 4.0%, with USD flat as the bond market returns from holiday. In addition to MegaCap Banks we have the Small Business Survey which printed below estimates, and where the section on hiring plans will be under scrutiny given the gov’t shutdown. The biggest highlight of the session is Fed Chair Powell speaking on the Economic Outlook and Monetary Policy at 12:20pm ET.

In premarket trading, Mag 7 stocks are all lower (Nvidia -1.8%, Tesla -2.5%, Alphabet -1.6%, Apple -0.7%, Microsoft -0.7%, Meta -1.4%, Amazon -1.4%). 

  • Cryptocurrency-linked stocks slide amid a drop in Bitcoin prices following a flare-up in trade tensions between the US and China.
  • US-listed critical mineral companies are extending gains after China hits US with more retaliatory measures on the shipping industry, a sign of persistent trade tensions between the two economies.
  • Astria (ATXS) shares rose 30% following a brief halt after BioCryst announced plans to buy the biopharmaceutical company.
  • Domino’s Pizza (DPZ) shares gain 1.9% after the restaurant chain reported total domestic stores comp sales growth for the third quarter that beat the average analyst estimate.
  • General Motors Co. (GM) falls 1.8% as the company is incurring $1.6 billion in charges related to paring back electric-vehicle production plans, underscoring the toll on US carmakers from flagging federal support for plug-in vehicles.
  • Polaris (PII) climbs 8% after saying it will separate Indian Motorcycle into a standalone company and entered a definitive agreement to sell a majority stake to Carolwood LP.
  • Navitas Semiconductor (NVTS) jumps 24% after unveiling its 100 V GaN FETs, 650 V GaN and high voltage SiC devices for Nvidia’s 800 VDC AI factory architecture.
  • Rayonier Inc. (RYN) and PotlatchDeltic Corp. (PCH) agreed to combine their businesses, creating a major US timberland owner and lumber manufacturer with a market capitalization of $7.1 billion. Rayonier +1%, PotlatchDeltic +5%
  • T-Mobile (TMUS) shares rise 1% after RBC raised the stock to outperform as the firm expects the telecom operator to see stronger subscriber growth versus wireless peers in the short term.
  • Wells Fargo & Co. (WFC) climbs 2.6% after raising a key profitability metric, giving its first major update about the bank’s next growth target after the removal of regulatory restraints it had operated under for more than seven years.

Global equities retreated after China upped the ante in its trade standoff with the US, stirring fresh concerns over tensions between Beijing and Washington at a time when stocks look stretched after a relentless rally. Besides hammering global stocks and marking a third day of wild stock swings, the latest standoff also sparked a rally in global bonds as investors pulled back from risk, sending the 10-year US Treasury yield down two basis points to 4.01%. Gold swung between gains and losses, while silver dipped after hitting a record over $53/oz.

“The sharp reversal shows how quickly sentiment can shift,” said Florian Ielpo, head of macro at Lombard Odier Investment Managers. “With elevated valuations already making markets vulnerable, expect continued volatility.”
Traders’ attention is also turning to the unofficial start of earnings season. JPMorgan fluctuated premarket after beating estimates for trading and investment-banking fees. Goldman Sachs fell despite posting record third-quarter revenues, on concerns about rising expenses.

Alongside renewed trade concerns, the surge in AI stocks is stoking bubble fears. In the October edition of BofA’s Fund Manager Survey survey, 54% of investors think there’s a bubble in the sector with concerns over global equity prices also at a record.

Bank earnings will be key for market direction later, with Citigroup, Goldman Sachs and JPMorgan all reporting this morning. Fed’s Powell is due to speak at 12:20pm ET, and his commentary will be crucial amid a lack of hard data.

Going back to the AI story that has rescued the market from other dips, BBG warns that it may be losing steam. Samsung shares fell, despite the company reporting its biggest quarterly profit in more than three years, with some investors cashing in on its recent AI-mania fueled gains. 

In other assets, cryptocurrencies continued to lose ground after a historic round of liquidations that triggered a sharp selloff over the weekend, with Bitcoin slumping as much as 3.7%. Oil fell after the IEA raised its estimate for a record oversupply.

In Europe, the Stoxx 600 falls as much a 1% after a broadly negative Asian session. European stocks fell on renewed trade jitters as China sanctioned the US units of a South Korean shipping giant Hanwha Ocean. Telecommunications and real estate equities are the biggest gainers, while mining and automobile shares led the declines. Here are the biggest movers Tuesday:

  • Ericsson shares jump as much as 15%, the most since April 2018, after the Swedish telecommunications group beat estimates. Analysts were impressed by robust profitability and strong gross margins in the Networks divisions
  • Bellway shares rise as much as 6.2%, the most in four months, as the housebuilder leaves guidance broadly unchanged and unveils a £150m share buyback program
  • EasyJet shares jump as much as 11%, the most since January 2023, after a report that Mediterranean Shipping Company is considering making an offer for the budget airline, in partnership with an investment firm
  • Klepierre climbs as much as 2.5% following a double-upgrade to overweight at JPMorgan, based on more positive capital growth assumptions for the French property management company
  • European mining shares are the worst-performing sector in the Stoxx 600 index on Tuesday after iron ore fell from the highest since late February as some concerns over potential supply issues from new port fees in China eased
  • Siemens Energy falls as much as 7.4% in Frankfurt trading, the most since April, with traders citing profit-taking in momentum stocks
  • Siemens slips as much as 3.5% on Tuesday as Morgan Stanley says the firm is no longer trading at a material discount to its “theoretical sum-of-the-parts” valuation following a strong re-rating this year, and downgrades to equal-weight
  • BASF shares fall as much as 2.1%, the most since August, after the chemicals company was downgraded to sell from hold and the price target lowered to €37 from €44 at Berenberg
  • Michelin shares fall as much as 11%, the most since March 2020, after the French firm issued a profit warning, mainly due to much weaker performance in North America
  • Bekaert drops as much as 12%, the most since March 2020, as Oddo BHF downgrades the Belgian steel-wire company to underperform from neutral, saying the strategy unveiled late in Dec. 2023 has yielded “very little.”

Earlier in the session, Asian stocks slipped on Tuesday, hurt by broad worries over US-China trade frictions as well as losses in Japan, where political uncertainty dragged shares lower after a long weekend. The MSCI Asia Pacific Index fell as much as 1.5%, to head for a third day of declines, with Chinese tech names Alibaba and Tencent among the biggest drags. The Hang Seng Tech Index entered a technical correction after the gauge fell more than 10% from a high on Oct. 2 following a blistering five-month rally through September. 

“China’s new tit-for-tat move against Hanwha Ocean’s US units marks another escalation in the strategic supply chain rivalry, deepening cracks in an already fragile risk backdrop,” said Hebe Chen, an analyst at Vantage Markets in Melbourne. “In essence, it reinforces the de-risking narrative.”

Australian mining companies with critical minerals projects jumped, fueled by signs of US interest in equity stakes as Trump and China intensify their strategic competition. In Japan, the Topix and Nikkei both slumped at least 2% each as trading resumed following Monday’s holiday. Japan’s governing coalition abruptly collapsed Friday in a major blow to new ruling party leader Sanae Takaichi, plunging the country into one of its biggest political crises in decades. Meanwhile, LG Electronics India soared in its Mumbai trading debut after investors flocked to the firm’s initial public offering, one of India’s biggest this year.

In FX, the Bloomberg Dollar Spot Index reverses losses to rise as much as 0.3% to its highest since Aug. 1; the pound drops 0.4% while the Aussie dollar is the weakest of the G-10 currencies, down 0.9%. Hedge funds in Asia and Europe are buying vanilla dollar call options versus a range of currencies amid a pickup in risk-off sentiment, according to European and Asian traders, BBG reports.

  • USD/JPY +0.2% to 151.96 (range 151.62 – 152.61)
  • EUR/USD little changed at 1.1561 (range 1.1555 – 1.1594)
  • GBP/USD -0.6% to 1.3259 (range 1.3258 – 1.3353)

In rates, treasuries climb, pushing US 10-year yields down 3 bps to 4.01%. Gilts lead an advance in European government bonds after the UK unemployment rate unexpectedly rose, prompting traders to boost BOE easing bets. UK 10-year yields fall 7 bps to 4.59%.

In commodities, spot gold has recovered to add $30 after an abrupt selloff saw it briefly turn negative. Silver also fell sharply from a record and is still down 2%. Bitcoin falls 3.5% below $112,000.

Looking to the day ahead now, data releases include UK unemployment for August, the German ZEW survey for October, and the US NFIB small business optimism index for September. Central bank speakers include Fed Chair Powell, the Fed’s Bowman, Waller and Collins, the ECB’s Cipollone, Makhlouf, Kocher and Villeroy, BoE Governor Bailey, and the BoE’s Taylor. Finally, earnings releases include JPMorgan Chase, Johnson & Johnson, Wells Fargo, Goldman Sachs, BlackRock and Citigroup.

Market Snapshot

  • S&P 500 mini -0.8%
  • Nasdaq 100 mini -1%
  • Russell 2000 mini -0.8%
  • Stoxx Europe 600 -0.4%
  • DAX -0.9%
  • CAC 40 -0.7%
  • 10-year Treasury yield -3 basis points at 4.01%
  • VIX +2.4 points at 21.47
  • Bloomberg Dollar Index +0.2% at 1217.9
  • euro little changed at $1.1562
  • WTI crude -2.1% at $58.23/barrel

Top Overnight News

  • US Treasury secretary Bessent has accused China of trying to hurt the world’s economy after Beijing imposed sweeping export controls on rare earths and critical minerals, hitting global supply chains. Bessent told the FT that China’s introduction of the controls (3 wks before Trump/Xi meeting) reflected problems in its own economy. FT
  • China added 5 US subsidiaries of South Korean shipbuilder Hanwha Ocean to its sanctions list for allegedly co-operating with American efforts to impose punitive fees on Chinese vessels that took effect on Tuesday. FT
  • Chinese rare earth magnet companies have been facing tighter scrutiny on export license applications since September, sources say, even before Beijing’s move last week to expand controls over the critical minerals used in magnets. RTRS
  • European Union officials called for strong measures against China after Beijing imposed fresh export restrictions on rare minerals used in computer chips and other advanced technologies. “We should have a tough response,” said Danish Foreign Minister Lars Lokke Rasmussen. BBG
  • Republicans on Capitol Hill and inside the Trump administration are said to be discussing potential pathways to prevent the tax credits from expiring at the end of the year. Some members of the House GOP leadership circle are having early, informal conversations with officials from the White House Office of Legislative Affairs and the Domestic Policy Council to develop a framework for a deal: Politico
  • Japanese stocks slump in Tues trading (they were closed Monday) as markets react to political uncertainty following Fri’s news of LDP’s junior partner withdrawing from the party’s coalition. Nikkei
  • Crude fell after the IEA warned of a record oversupply in 2026. Supply may exceed demand by about 4 million barrels a day — 18% higher than September estimates — an unprecedented overhang in annual terms, the agency said. BBG
  • UK unemployment unexpectedly rose and wage growth slowed more than forecast in the three months through August, prompting traders to boost bets on further BOE rate cuts next year. The pound fell. BBG
  • EPS in full swing this morning with banks – JPMorgan beat most estimates, with both equities and FICC sales trading revenue well above expectations. Wells Fargo beat earnings and was as expected at a high level, missing on NIIs but beating on fees. BBG
  • Donald Trump’s lumber tariffs take effect today, with the import duties on kitchen cabinets, upholstered furniture and other items threatening to raise renovation costs and deter new home purchases. BBG

Trade/Tariffs

  • China officially began special port fees for US ships, while it was earlier reported that China issued implementation rules on port fees on US ships and exempted China-made ships owned by US companies from port fees, while it is to adjust special port fees on US ships as needed.
  • China’s MOFCOM responded to the US saying it has proposed talks with China after rare earth restrictions, in which MOFCOM stated the US cannot have talks while threatening to intimidate and introduce new restrictions, which is not the right way to get along with China, while it urged the US to correct its “wrong practices” as soon as possible and show sincerity in talks with China. It also stated that export curbs are not an export ban and do not prohibit exports. Furthermore, it said they held working-level talks on Monday and noted that both sides have maintained communication under the framework of the China-US economic and trade consultation mechanism. However, MOFCOM later announced that it is taking countermeasures against five US-linked firms.
  • China Transport Ministry said it opened an investigation into the impact of US 301 tariffs on China’s shipping industry.
  • China’s Commerce Ministry urges the US to correct mistakes and hopes to resolve concerns through dialogue.
  • China increases oversight of export license applications for rare earth magnets, via Reuters citing sources.

A more detailed look at global markets courtesy of Newsquawk

APAC stocks were mixed following the rebound on Wall St and with underperformance in Japanese markets as they reopened from the extended weekend and reacted to the recent US-China tariff tensions, as well as the Japanese ruling coalition split. ASX 200 struggled for direction as weakness in the financial and consumer-related sectors offset the gains in materials and miners, with the latter helped by the recent upside in metal prices and with Rio Tinto gaining following its quarterly activity update. Nikkei 225 underperformed as participants returned from the holiday closure and reacted to the recent US-China trade frictions and political uncertainty in Japan, while there were late headwinds after reports of China trade-related actions against the US. Hang Seng and Shanghai Comp are lower amid the backdrop of the tumultuous trade/tariff related headlines in which the recent softening in tone by the US on China was followed by reports overnight that China’s MOFCOM is taking countermeasures against five US-linked firms and that China’s Transport Ministry opened an investigation into US 301 tariffs impact on China shipping industry.

Top Asian News

  • Monetary Authority of Singapore kept the prevailing rate of appreciation of the SGD NEER policy band, as well as made no change to the width and level at which the band is centred, as expected. MAS said it is in an appropriate position to respond effectively to any risk to medium-term price stability and MAS core inflation should trough in the near term but rise gradually over the course of 2026, while it added that Singapore’s economic growth has turned out stronger than expected and the output gap will remain positive in 2025.
  • RBA Minutes from the September meeting stated the Board agreed no need for immediate reduction in the cash rate, while it added that future policy decisions are to be cautious and data dependent. RBA said the market path for the cash rate is within estimates of neutral but too imprecise to guide policy and it is important to see what Q3 data shows on the economy and supply capacity, as well as noted that policy is probably still a little restrictive, but this is difficult to determine and there are still risks on both sides for the economy.
  • Japan’s LDP proposes October 21st for extraordinary Diet, via FNN.
  • China’s Central Bank-backed Publication will continue to uphold decisive role of market in exchange rate formation and strengthen guidance of expectations.

European bourses (STOXX 600 -0.4%) are broadly lower across the board, with sentiment hampered by the ongoing US-China spat; overnight, China’s MOFCOM announced that it is taking countermeasures against five US-linked firms. European sectors hold a strong negative bias. Telecoms takes the top spot, boosted by post-earning strength in Ericsson (+13%) after it beat on profits and raised guidance. To the bottom of the pile resides Basic Resources, hampered by broader weakness in underlying metals prices. US equity futures (ES -0.8%, NQ -1.1%, RTY -0.9%) are lower across the board, following a similar theme seen in Europe. All focus today on a number of bank results, to kick off Q3 earnings seasons. BP (BP/ LN) Q3’25 Trading Statement: Upstream Production in Q3 is now exp. to be higher vs prior quarter, but flagged weaker trading into Q3. BlackRock Inc (BLK) Q3 2025 (USD): Adj. EPS 11.55 (exp. 11.24), Revenue 6.51bln (exp. 6.23bln); AUM 13.464tln (exp. 13.37tln).

Top European News

  • Barclays UK September Consumer Spending fell 0.7% Y/Y vs prev. 0.5% Y/Y increase in August.
  • The tax elements of French PM Lecornu’s draft finance bill reportedly include 30 articles, some have already been announced, but also the addition of a tax on “assets not allocated to an operational activity of property holding companies”, via Playbook. Furthermore, Playbook, citing a source, reports that there is no question for the PS of “doing another round of negotiations on Wednesday, Thursday or Friday”.
  • The two motions of censure will be looked at on Thursday at 08:00 BST, but the Conference of Presidents on the National Assembly, via BFMTV.
  • French fiscal watchdog HCFP says French government’s 2026 budget plan relies on overly optimistic economic assumptions; based on ambitious spending restraint that would be difficult to implement. France is at risk of under-delivering on spending and tax measures in 2026 budget. Budget bill includes belt-tightening measures worth over EUR 30bln, including EUR 13.7bln in taxes and EUR 17bln in spending cuts.
  • French Socialist Party (PS) will not vote against PM Lecornu’s government in the motions filed by LFI and RN, will instead file its own motion of no confidence in the scenario it is not satisfied with the budget proposals, via Reuters citing sources
  • German Economy Ministry says current indicators do not point to economic recovery in Q3.
  • Riksbank’s Bunge says monetary policy must be forward looking; Inflation remains elevated, but with increased confidence that it will fall back, we were able to cut the policy rate to provide further support to the economy.
  • EU Commission modifies drone wall proposals to suggest broader European drone defence initiative, via Reuters sources.

FX

  • After a soft start to the session, whereby DXY was dragged lower by the haven bid into the JPY, the Greenback was able to garner support at the expense of risk-sensitive currencies and the GBP (post-jobs data). The bout of risk aversion was triggered by China’s decision to take countermeasures against five US-linked firms – a move which has dashed some of the hopes seen during yesterday’s session. Furthermore, a source piece in the WSJ overnight stated that “people close to the Trump administration say the US side likely will demand that China rescind, not merely delay or water down the rare-earth export rule“. Focus today on US NFIB Small Business Optimism index, and speakers include Fed Chair Powell, Waller, Collins & Bowman. DXY has ventured as high as 99.47, with the next target coming via last week’s peak at 99.56.
  • After initially looking like it was going to make a test of 1.16 overnight, EUR/USD was dragged lower by the broader pick-up in the USD. From a macro perspective, focus in the Eurozone remains on France with PM Lecornu set to present his budget at 14:00BST, aiming to reduce the deficit to 4.7% by end-2026. In terms of the specifics, Politico reports that additional measures to those previously expected will include a tax on the richest members of society. Even with the Socialists on board, the governing coalition would still need to find additional votes in the Assembly, which looks tough given that the Far Right and Left are expected to table a no-confidence motion on Lecornu. Elsewhere in core Europe, German ZEW data showed misses for both metrics, with the current conditions component slipping further into negative territory. EUR/USD has been as low as 1.1543 and is just about holding above last week’s low at 1.1542.
  • JPY is the only of the majors to out-muscle the USD given its safe-haven status. JPY was supported in early European trade as investors reacted to the increase in US-China tensions overnight (see USD section for details). Subsequently, USD/JPY was dragged as low as 151.63 vs. an earlier session high at 152.61. A pick-up in the USD has since seen the pair return to a 152 handle. In terms of the macro story for Japan, it is one that remains dominated by domestic politics following the collapse of the ruling coalition. Note, the LDP party has proposed October 21st for an extraordinary Diet session.
  • GBP was hit in early European trade following the latest UK labour market report, which was largely viewed with a dovish lens. Surmising the data, Pantheon Macroeconomics highlighted the unexpected uptick in the unemployment rate and the decline in 3M/YY ex-bonus average earnings, which will factor into thinking on the MPC. Elsewhere, BRC retail sales slowed to 2.0% Y/Y in September from 2.9% as consumers remain cautious in the run-up to next month’s fiscal event. Cable has delved as low as 1.3255 to levels not seen since early August.
  • Antipodeans are both are softer vs. the USD and at the bottom of the G10 leaderboard. In the absence of any material domestic updates, AUD and NZD remain at the whim of broader risk dynamics, which are being led by US and Chinese trade tensions.

Fixed Income

  • USTs are bid, firmer by over 10 ticks to a 113-16+ high. Strength this morning comes on the back of the downbeat risk tone as China retaliates. Upside that has driven the benchmark to a fresh high for the month, with the next points of resistance at 113-21, 113-25+ and then the 113-29 September peak. Specifically, China’s MOFCOM announced that it is taking countermeasures against five US-linked firms and outlined that the US cannot have talks while new restrictions are being threatened. Elsewhere, the docket is packed with Fed speak via voters Bowman, Waller, Chair Powell and 2025 voter Collins.
  • OATs are firmer today, in-fitting with peers. A packed agenda for French politics. The main update this morning came from the French fiscal watchdog HCFP on the 2026 budget draft, a draft that was in-fitting with overnight sources. On the draft, HCFP described it as relying on overly optimistic scenarios and ambitious spending restraint that would be difficult to implement. Perhaps most pertinently today, PM Lecornu’s General Policy Statement is scheduled for 14:00BST. The statement should take no more than 90 minutes, afterwards other party leaders can respond. It is worth highlighting that the French Socialist Party will not vote against PM Lecornu’s government, and instead opt for its own motion of no confidence, if it not satisfied with the proposal.
  • Bunds are bid, given the market narrative outlined in USTs. No move to final German HICP for September this morning which was unrevised. For Bunds, the morning’s main event was October ZEW. The series came in softer than expected across the board and sparked some modest upside in Bunds, though well within earlier parameters. No move to a new Schatz auction which was fairly weak.
  • Gilts are outperforming after the morning’s jobs data. Opened higher by 45 ticks before climbing to a 91.81 peak with gains of 57 ticks at best. Stopping a tick shy of the 91.82 September peak; if the move continues, then there is a bit of a gap before the 92.70 August high. The morning’s data saw an unexpected jump in the unemployment rate, going against the view from the most recent MPC statement that there is less of an immediate risk that the labour market will loosen very rapidly. A point that serves as a dovish impetus. However, this is caveated on face value by the elevated wage figure (incl-bonus). Upside that the ONS attributes to the public sector, as some pay rises are awarded earlier than they were in 2024.
  • Germany sells EUR 4.25bln vs exp. EUR 5.5bln 2.00% 2027 Schatz: b/c 1.4x, average yield 1.91%, retention 22.7%.
  • Italy sells EUR 8.5bln vs exp. EUR 6.75-8.5bln 2.35% 2029, 3.25% 2032, 2.80% 2028, 3.85% 2040 BTP.

Commodities

  • Crude benchmarks are trending lower as renewed trade worries, easing geopolitical tensions, and an oversupplied oil market weigh on prices. Benchmarks are steadily declining as the European session continues, with WTI and Brent currently c. USD 1.7/bbl lower and trading near lows at USD 58.20/bbl and USD 62.00/bbl, respectively.
  • Precious metals extended to new ATHs during APAC trade, with XAU and XAG peaking at USD 4180/oz and USD 53.59/oz respectively, before selling off as US President Trump hints of total peace in the Middle East.
  • Base metals have reversed Monday’s gains, with 3M LME Copper returning to USD 10.5k/t from a peak of USD 10.86k/t, as recent dollar strength weighs on the commodity space.
  • IEA OMR: lowers 2025 world oil demand growth forecast to 710k BPD (prev. 740k BPD); leaves 2026 average oil demand growth forecast steady at 700k BPD.
  • TotalEnergies (TTE FP) CEO says they are still quite bullish in medium term oil demand; CEO says there is no peak oil demand.
  • US Energy Secretary Wright is set to announce the Trump administration’s fusion roadmap at an industry gathering on Tuesday, via Axios citing DOE officials.

Geopolitics

  • US President Trump is said to have confirmed that Israeli PM Netanyahu will not annex any part of the West Bank, according to Al Arabiya.
  • Iran’s Foreign Ministry says US President Trump’s desire for peace and dialogue is in conflict with US hostile and criminal behaviour against Iran.
  • US President Trump posts “Gaza is only a part of it. The big part is, PEACE IN THE MIDDLE EAST!”.
  • Israeli’s Defence Force says several suspects were identified crossing the yellow line and approaching IDF troops operating in the northern Gaza Strip, which constitutes a violation of the agreement; troops opened fire to remove the threat, via CGTN.

US event calendar

  • 8:45am: Fed’s Bowman in Moderated Conversation at IIF
  • 12:20pm: Fed’s Powell Speaks on Economic Outlook and Monetary Policy
  • 3:25pm: Fed’s Waller on Payments Panel at IIF
  • 3:30pm: Fed’s Collins Speaks to the Greater Boston Chamber of Commerce

DB’s Jim Reid concludes the overnight wrap

As was looking likely in Asian trading yesterday morning, markets have recovered over the last 24 hours, with the S&P 500 (+1.56%) last night bouncing back from its tariff-induced selloff on Friday. A little momentum has been lost in the Asian session this morning but we’re still in a better place than Friday.

As we discussed this time yesterday, the biggest driver to Monday’s rally was more positive rhetoric on trade over the weekend, which suggested that the US was more open to a compromise than Trump’s initial posts from Friday had indicated. But markets also got another boost from the latest AI news, as OpenAI signed a deal with Broadcom (+9.88%) to purchase 10 gigawatts of computer chips. So by the close, it meant the S&P 500 had recovered more than half of its Friday losses, and other assets like Brent crude oil (+0.94%) also managed to pare back last week’s declines.

Stand by for the start of US earnings season today with JPMorgan Chase, Johnson & Johnson, Wells Fargo, Goldman Sachs, BlackRock and Citigroup all reporting. S&P 500 (-0.38%) and NASDAQ (-0.57%) futures are lower this morning ahead of what will soon be a deluge of earnings in a market starved of macro data due to the shutdown. Japanese markets are being hit the most this morning with the Nikkei down -2.80% with continued reverberations around the collapse of the ruling coalition late last week which puts some concerns as to whether new LDP leader Sanae Takaichi can still get enough votes to be elected PM.  

In terms of the latest on the trade war, the news over the last 24 hours has continued to sound much more emollient. For instance, US Treasury Secretary Bessent was on Fox Business yesterday, and he said on the Trump-Xi meeting in South Korea, that “I believe that meeting will still be on”. Polymarket has the probability at such a meeting at 74% this morning from 62% as we went to print yesterday, 35% at the lows on Friday and 88% at the recent highs last week. Although as we go to print Bessent has been interviewed by the FT and his words seem more hawkish, accusing the Chinese of trying to hurt the world economy.

A reminder of Trump’s weekend posts, including his comment that Chinese President Xi “doesn’t want Depression for his country, and neither do I. The U.S.A. wants to help China, not hurt it!!!”  That backdrop led to a decent rebound for the most trade-sensitive stocks. So the NASDAQ Golden Dragon China index was up +3.21%, and that’s an index made up of companies publicly traded in the US, but who do a majority of their business in China. Similarly, the Philadelphia Semiconductor Index (+4.93%) posted its strongest daily performance since May, admittedly with a boost from the Broadcom headlines as well.  

That unwind was clear across multiple asset classes, as the initial reaction from Friday was pared back. For instance, oil prices posted a decent recovery, with Brent crude (+0.94%) moving back up to $63.32/bbl, as investors lowered the chances of a wider breakdown in trade. Meanwhile US bond markets were closed for the Columbus Day holiday, but Treasury futures pointed to higher yields all day but 10yr yields are only +0.6bps higher this morning from Friday’s close at 4.038% after having approached 4.07% at the reopen in Asia. 2yr yields are actually -1.3bps lower now than Friday’s close.

Whilst the focus was mainly on trade yesterday, we’re also now two weeks into the US government shutdown, with no sign of a resolution as it stands. Indeed, if we look at prediction markets, it’s clear that a growing risk of an extended shutdown is being priced in, with Polymarket saying there’s a 27% chance now of it lasting beyond November 16. So that would still be another month from here and take it well over the 35-day record set in 2018-19. And if it did last that long, then it would continue to impact the flow of data like the jobs reports and have an increasing macroeconomic impact as federal workers remain without pay for the shutdown period.  

Over in Europe, political uncertainty was also a key theme yesterday as investors remain focused on the French budget situation. In terms of the next steps, PM Lecornu will be delivering the general policy statement today after his reappointment as PM, but the same issue remains in that the National Assembly is completely fractured between the different groups, who each have their own red lines. For now, however, markets haven’t seen much reaction, with the Franco-German 10yr spread holding broadly steady at 83bps. So it’s still beneath its peak of 86bps last week, when there was briefly a lot of speculation about another snap legislative election. Polymarket suggests the probability of an election being called by the end of the month and the end of the year stands at 36% and 57% respectively this morning but both down over 10pp from Sunday’s highs.

Elsewhere in Europe, markets generally put in a solid performance yesterday, with the STOXX 600 up +0.44%, alongside gains for the DAX (+0.60%), the CAC 40 (+0.21%) and the FTSE 100 (+0.16%). Similarly, bonds rallied across the continent, with yields on 10yr bunds (-0.8bps), OATs (-0.9bps) and BTPs (-2.8bps) all moving lower, whilst Spain’s 10yr yield (-1.6bps) hit a 3-month low.

In the rest of Asia, outside of the politically motivated slump in Japan, markets are on the softer side led by the KOSPI (-1.36%) which has turned sharply lower as I’ve been typing this morning even with decent results from Samsung. China has imposed curbs on five US units of Hanwha Ocean after the US probed Chinese maritime, logistics and shipbuilding industries. Elsewhere, the Hang Seng (-0.18%) is also lower for the seventh consecutive session with the Shanghai Composite (+0.21%) holding onto its gains alongside the S&P/ASX 200 (+0.16%). The minutes from the Reserve Bank of Australia’s latest meeting revealed that the central bank remains cautious regarding future interest rate cuts due to persistent local inflation, while largely reiterating its data-dependent approach to future rate adjustments, noting that it is also awaiting the full impact of its monetary easing to be reflected in the economy.

Finally, yesterday brought another surge in gold prices (+2.30%), which continued their rally to close at $4,1110/oz. So that now takes their YTD gain up to +56.6%, still on track for their strongest annual performance since 1979. This morning we’re up another +1.38% as I type. Meanwhile, silver (+4.44%) moved up to $52.37/oz yesterday, with its own YTD gains now standing at +82%. The London short squeeze continues to have an impact.

To the day ahead now, and data releases include UK unemployment for August, the German ZEW survey for October, and the US NFIB small business optimism index for September. Central bank speakers include Fed Chair Powell, the Fed’s Bowman, Waller and Collins, the ECB’s Cipollone, Makhlouf, Kocher and Villeroy, BoE Governor Bailey, and the BoE’s Taylor. Finally, earnings releases include JPMorgan Chase, Johnson & Johnson, Wells Fargo, Goldman Sachs, BlackRock and Citigroup.

Tyler Durden
Tue, 10/14/2025 – 08:50

Market Maelstrom Returns As China Escalates Trade War With Sanctions, Tit-For-Tat Port Fees 

0
Market Maelstrom Returns As China Escalates Trade War With Sanctions, Tit-For-Tat Port Fees 

Global equity futures slipped on Tuesday after China vowed to “fight to the end” in its trade war with the U.S., following President Trump’s threat last week to impose 100% tariffs on Chinese goods. Despite Washington’s attempts to soften its tone over the weekend, tensions are intensifying into the new week: both countries are imposing new docking fees on each other’s vessels, signaling deepening Sino-US relations ahead of Trump-Xi talks. Adding to the flaring tensions, Beijing sanctioned five U.S. subsidiaries of South Korean shipbuilder Hanwha Ocean, while U.S. Treasury Secretary Scott Bessent accused China of deliberately undermining the global economy.

Trump’s move last Friday to threaten Beijing with an additional 100% tariff on Chinese goods, in response to China’s sweeping new export controls on rare earths and ahead of a planned Trump-Xi meeting later this month, signals that both sides are trying to gain as much leverage as possible before the Asia-Pacific Economic Cooperation forum in South Korea. 

The Chinese Commerce Ministry condemned the Trump administration’s tactics, calling them incompatible with dialogue. “If you wish to fight, we shall fight to the end; if you wish to negotiate, our door remains open,” a ministry spokesperson said.

“The United States cannot simultaneously seek dialogue while threatening to impose new restrictive measures. This is not the proper way to engage with China,” the ministry said.

On Sunday, Trump walked back his rhetoric in a Truth Social post that said “it will all be fine”, adding that the U.S. wants to “help” China. This relief sent global equities soaring on Monday, yet the outlook darkened on Tuesday after the ministry sanctioned South Korean shipbuilder Hanwha. 

China’s Commerce Ministry wrote in a statement that Hanwha Ocean’s five U.S. subsidiaries, Hanwha Shipping LLC, Hanwha Philly Shipyard Inc., Hanwha Ocean USA International LLC, Hanwha Shipping Holdings LLC, and HS USA Holdings Corp, are sanctioned over “assisting and supporting the U.S. government’s probes and measures against Chinese maritime, logistics and shipbuilding sectors. China is strongly dissatisfied and resolutely opposes it.” 

Earlier Tuesday, Beijing confirmed it had begun imposing additional port fees on vessels linked to the U.S., while clarifying that Chinese-built ships would be exempt from the new charges. This tit-for-tat followed the U.S. decision to impose on Chinese vessels at U.S. ports.

Also, U.S. Treasury Secretary Scott Bessent told the Financial Times that Beijing is trying to damage the global economy with its export controls on rare earths and critical minerals, sending some global supply chains into snarled conditions. 

“This is a sign of how weak their economy is, and they want to pull everybody else down with them,” Bessent said on Monday, adding, “Maybe there is some Leninist business model where hurting your customers is a good idea, but they are the largest supplier to the world. If they want to slow down the global economy, they will be hurt the most.”

Bessent added, “They are in the middle of a recession/depression, and they are trying to export their way out of it. The problem is they’re exacerbating their standing in the world.”

There’s been a flurry of developments on the U.S.-China front. UBS analyst Joe Dickinson broke down the past 24 hours, removing the noise to explain market impacts:

EStoxx fell 20bp to start, following U.S. futures lower. Commentary from both the U.S. and China on Trade was conciliatory overnight. China’s commerce ministry indicated working-level talks were held Monday, Treasury Secretary Bessent confirmed that Trump and Xi are still expected to meet at the APEC Summit at the end of the month.

But price action in Asia is cautious and weaker again. Nikkei cash dropped 2.8% while futures were down 1.7%. China reopens lower in the afternoon session, with CSI300 down 80bp after China’s Ministry of Commerce announced curbs on five U.S. units of Hanwha Ocean in response to U.S. probes against Chinese maritime, logistics, and shipbuilding industries, as well as reports that China has started charging port fees for U.S. ships. Note that Samsung slid 4% post earnings.

S&P 500 futures are down a little more than 1% while Nasdaq 100 contracts fell 1.5%. 

Sea of red across global equity futures. 

Bitcoin’s rebound losing momentum. 

WTI futures tumbling. 

Treasuries bid. US10Y tags 4%. 

Now we wait to see whether the Trump administration doubles-down on their tit-for-tat-ing or steadies the ship again?

Tyler Durden
Tue, 10/14/2025 – 07:26

Steve Jobs Vs Tim Cook: How The Tenures Of Both Apple CEOs Compare

0
Steve Jobs Vs Tim Cook: How The Tenures Of Both Apple CEOs Compare

From a scrappy garage startup to the world’s most valuable company, Apple’s journey is closely tied to the legacies of its two most influential CEOs: Steve Jobs and Tim Cook.

This visual, created by Made Visual Daily via Visual Capitalist, compares the two eras side by side. It highlights key milestones, product launches, and the company’s market capitalization growth.

The data comes from publicly available sources.

Under Steve Jobs, Apple’s market cap surged from $2.5 billion to $350 billion, driven by iconic releases like the iMac, iPod, iPhone, and iPad. Meanwhile, Tim Cook has overseen a staggering $3.1 trillion increase in value, with the company reaching $3.7 trillion in 2025, bolstered by services, AirPods, Apple Silicon, and even the Apple Vision Pro.

Jobs: The Product Visionary

Jobs returned to Apple in 1997 during a time of crisis. Over the next 14 years, he delivered breakthrough products that redefined industries—from the original iMac and iPod to the game-changing iPhone and iPad. These weren’t just gadgets—they reshaped how people interact with technology.

The launch of the App Store in 2008 also set the foundation for Apple’s massive software and services ecosystem, now a major profit center for the company.

Cook: The Scaler and Strategist

When Cook took over in 2011, many questioned if Apple could continue innovating. But Cook’s operational acumen allowed the company to scale globally, optimize margins, and diversify revenue streams. Under his leadership, Apple launched the Apple Watch, AirPods, Apple Pay, and custom silicon (M1 chip), while significantly expanding its services segment.

Today, Apple’s ecosystem includes hardware, services, entertainment, and finance. Cook has successfully shepherded the company into new growth areas, helping it weather challenges like supply chain crises and slowing smartphone growth.

The Longevity of Leadership, and the Question of What’s Next

Cook has now led Apple longer than Jobs. His quiet, operational style has proved durable, weathering global disruptions while continuing to expand Apple’s footprint in China, health, and AI.

But with his tenure entering its twilight, attention is turning toward succession. Some analysts point to COO Jeff Williams or SVP of Services Eddy Cue as likely candidates, while others speculate that rising stars like John Ternus or Craig Federighi could take the reins.

As Apple’s next chapter unfolds, the bar remains high: Cook took the world’s most innovative company and turned it into one of its most valuable ones. The next leader will have to chart a path for both growth and reinvention.

As noted in this 2023 CNBC profile, Cook emphasizes collaboration and expects innovation from every level of the company. Whoever takes the reins next will need to balance Apple’s culture of secrecy with a rapidly evolving tech landscape—from AI to augmented reality.

For how many years was Apple the most valuable company in the U.S. between 1995 to 2025? Find out in this nifty visualization on Voronoi.

Tyler Durden
Tue, 10/14/2025 – 06:55

Russia Accuses Ukrainian Intelligence Of Using ISIS For Assassination Plot

0
Russia Accuses Ukrainian Intelligence Of Using ISIS For Assassination Plot

Via The Cradle

The Russian Federal Security Service (FSB) stated on Monday that its officers foiled a terrorist attack in Moscow that was planned by ISIS under the direction of Ukrainian intelligence.

ISIS operatives sought to target a high-ranking Russian Defense Ministry official using an explosive device in a densely populated area of the capital city, the agency said in a statement.

Via Associated Press

“The FSB has prevented a sabotage and terrorist act against one of the senior officers of the Russian Defense Ministry, organized by Ukrainian special services in coordination with leaders of the international terrorist organization Islamic State (banned as a terrorist organization in Russia),” the FSB statement said.

Four suspects connected to the plot were detained, including a native of a Central Asian country. The FSB alleged that the plan was developed by Ukrainian intelligence and would have been carried out by a suicide bomber recruited by an ISIS member named Saidakbar Gulomov.

“On instructions from Ukrainian handlers, S. Gulomov remotely directed the perpetrator’s actions from Ukraine and several Western European countries using multiple foreign messaging applications,” the FSB added.

Gulomov allegedly provided the attacker with funds, information about the target, and materials for assembling explosive devices smuggled into Russia by Ukrainian intelligence using drones.

According to the FSB, Gulomov was also involved in the killing of Russian Lieutenant General Kirillov, commander of the Russian Radiation, Chemical, and Biological Defense Troops, in December 2024.

The FSB claims the attack on Kirillov was also orchestrated by Ukrainian intelligence. Monday’s foiled terror attack “once again demonstrates the close coordination between the Kiev regime and international terrorist organizations,” the Russian intelligence service stated.

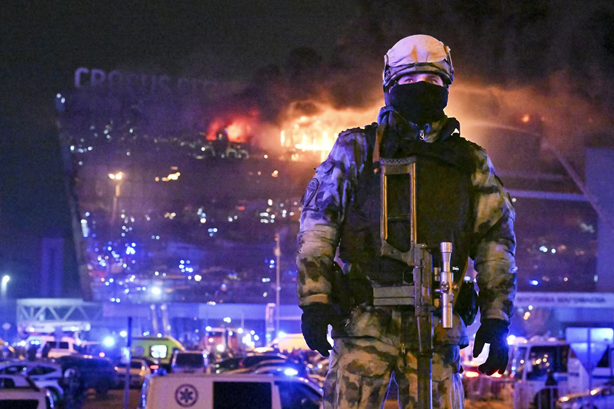
In March 2024, four gunmen attacked a concert hall near Moscow, opening fire on the more than 5,000 people gathered to watch the Russian rock group Piknik. At least 145 people were killed in the attack.  

Russian authorities blamed the ISIS affiliate in Afghanistan, ISIS-Khorasan, for the attack, while also accusing Ukrainian intelligence of orchestrating it.

“The investigation has concluded that the terrorist act was planned and organized by the security services of an unfriendly state in order to destabilize the situation in Russia,” stated the Russian Investigative Committee, which was tasked with determining who was responsible. “Members of an international terrorist organization were recruited to carry it out.”

Tyler Durden
Tue, 10/14/2025 – 06:30

Majority Supports Social Media Ban For Children

0
Majority Supports Social Media Ban For Children

Australia passed a social media ban for teenagers and children under the age of 16 in December, which applies to companies including Instagram, X and TikTok. The measure is intended to reduce the “social harm” done to young Australians and is set to come into force on December 10, 2025. Tech giants will be up against fines of up to A$49.5 million ($31 million) if they do not adhere to the rules.

The new law was approved on November 28, 2024, with support from a majority of the general public. However, the blanket ban sparked backlash from several child rights groups who warn that it could cut off access to vital support, particularly for children from migrant, LGBTQIA+ and other minority backgrounds.

Critics argue it could also push children towards less regulated areas of the internet.

The new legislation is the strictest of its kind on a national level and comes as other countries grapple with how best to regulate technology in a rapidly-evolving world.

As Statista’s Anna Fleck shows in the chart below, using data from an Ipsos survey fielded in August 2025, it’s not just Australians who support a full ban of social media for children and young teens.

Infographic: Majority Supports Social Media Ban for Children | Statista

You will find more infographics at Statista

An average of seven in ten respondents across the 30 countries surveyed said the same.

In France, an even higher share of adults (85 percent) held the view that children under the age of 14 should not be allowed social media either inside or outside of school.

This belief was far less common in Germany (53 percent). Consensus has been growing in countries around the world, with a growing number of respondents agreeing that such bans should be put in place across almost all countries surveyed, except for in India, Thailand and Hungary, where the opposite was true.

Sentiments on smartphone use differed by generation. Where 39 percent of Gen Z said they would support a ban on smartphones in schools, the figure was far higher among older generations (69 percent of Boomers, 61 percent of Gen X and 57 percent of Millennials.)

Tyler Durden
Tue, 10/14/2025 – 05:45

Saudi Arabia’s Debt Surge: Cementing Reliance On International Funding

0
Saudi Arabia’s Debt Surge: Cementing Reliance On International Funding

Authored by Nick Smallwood via BondVigilantes.com,

The increasing liquidity squeeze in the Kingdom of Saudi Arabia’s (KSA) financial system has been causing heightened levels of debate for some time.

A growing economy and the financial demands of the mega-projects that are under way are hoovering up cash faster than the domestic system can supply it. For context, recent reports suggest that the new city of NEOM could cost $8.8tn to build, which is around 25 times KSA’s annual budget.

Until recently, the Saudi business complex was able to meet its financial needs by raising money locally, generally via bank loans or by issuing sukuks into the strong domestic investor base (often private banks managing the wealth of high-net-worth individuals). However, the system has become too stretched. Credit growth has outstripped deposit growth for several years, while local investors buying financial assets must withdraw money from their bank accounts to do so, meaning that financial investments cause a reduction in banks’ deposit funding as local funding is cannibalised.

On top of that, deliberate oil production cuts and weaker oil prices have reduced oil revenues from SAR 857bn in 2022 to a projected SAR 608bn in 2025, contributing to a swing in the national budget from a surplus of 2.2% of GDP to a projected deficit of 4% over the period (using IMF numbers). The deliberate attempt to diversify away from oil therefore comes at a budgetary cost, at least for now, meaning that the country needs to attract more external funding.

If domestic liquidity is challenged, the logical step for a highly-rated country to take is to seek funding from abroad, which is precisely what has occurred. International debt issued by KSA and its large banks/corporates has surged in recent years. KSA sovereign and quasi-sovereign issuances now account for 5.1% of the most widely used EM sovereign bond index (JPM EMBI), meaning that it is now the largest issuer in that index. Its corporates now account for 4.3% of the corporate version of that index (JPM CEMBI), in which it has become the fourth-largest constituent. That represents a stunning change in its international market presence.

A glance at financial sector balance sheets shows that the need for international funding is structural – it is here to stay. Overall bank loans have grown at a compound annual growth rate (CAGR) of 14% since 2019, with deposits growing by just 8% over the same period. In cash terms, loans have doubled from SAR 1.5tn in 2019 to SAR 3.0tn as at end-2024, while deposits have increased much less, from SAR 1.8tn to SAR 2.7tn. In 2019, therefore, the financial system had more than enough deposits to fund the economy’s credit needs; by 2024, this is patently no longer the case. In fact, the system’s loans/deposits ratio has weakened from 86% to 110% over the period. The conclusion is simple: banks are now dependent on wholesale funding if the current rate of credit growth is to be maintained.

Source: SAMA

We can see the scale of the change in issuance of international bonds, which has soared in the past few years. In 2023, KSA banks issued $2.0bn of bonds, accounting for around 6% of total issuance from the Saudi complex. In 2024, this grew to $6.8bn (14% of total), while so far this year banks have already issued $14.9bn of bonds, comprising 27.4% of all Saudi issuance. And it’s not just the banks that are issuing more debt internationally. KSA’s funding needs mean that it is issuing through every vehicle at its disposal, including cash-rich Aramco and its sovereign wealth fund (PIF). Total Saudi debt issuance ballooned from $36bn in 2023, equating to around $3bn per month, to $54bn year-to-date or around $6.4bn per month.

Source: Bloomberg

It is very clear where all this leads: the KSA complex is structurally increasing its reliance on international debt markets. Banks are taking an ever-greater share of Saudi issuance, which also seems to be a persistent trend. KSA is therefore increasingly dependent on international investment to fund its domestic priorities, while the abundance of supply and the prevalence of more price-sensitive foreign investors in its investor base means that Saudi bonds may struggle to perform for a while. We wrote previously that the technicals of the sukuk market would generally assure tight spreads and strong performance (see here). The times, they are a-changin’ – that model no longer applies.

Tyler Durden
Tue, 10/14/2025 – 05:00

Germany’s Auto Summit: Spectacle Over Substance, Economy At Risk

0
Germany’s Auto Summit: Spectacle Over Substance, Economy At Risk

Submitted by Thomas Kolbe

Politics is the art of the possible, as Otto von Bismarck famously said. The auto summit at the Chancellery shows that, in Germany, nothing seems to work anymore. Politics refuses any gradual departure from the eco-socialist course.

Thursday was an eventful day—at least from the federal government’s perspective. No sooner had Chancellor Friedrich Merz and his deputy Lars Klingbeil given the bottomless pit of “citizens’ income” a new label than they turned to the next crisis hotspot of the republic: the collapsing automotive industry.

At the auto summit convened by the Chancellor, government members, state premiers of affected regions, business representatives, and unions gathered to discuss the future of eroding automotive production.

Dramatic Situation

The situation was clear—and dramatic. Since 2018, the German automotive sector has suffered a 25 percent production decline. In just the past twelve months, 50,000 jobs have been lost. One of the pillars of the German economy is eroding—unstoppably.

The reasons are obvious: a homegrown energy crisis due to the exit from Russian gas and nuclear power, the politically forced transformation to electric mobility, and relentless competition from China. All of this makes life hell for manufacturers.

This diagnosis applies to the entire German economy. Energy-intensive production under current regulatory and energy-policy conditions is simply no longer competitive. Around 250,000 industrial jobs have been cut since 2018—well-paid skilled workers are losing their positions—so much for the supposed skills shortage.

Logic in Exile

The obvious consequence—hundreds of thousands of jobs at risk in the coming months—would be a radical course correction: the end of the ideologically ossified Green Deal, which has turned Europe into a high-risk zone for international capital.

But what counts as “normal” in German politics or in Brussels offices anymore? As with the citizens’ income, the auto summit is less about solutions than about spectacle. Willingness to reform is faked, competence feigned—while the system that created the crisis remains untouched. Illusion over substance, show over content.

The economy’s quiet grumbling over energy costs and the electric-vehicle dead end was dispersed by Merz, Klingbeil, and co. in the usual way: a new, multibillion-euro subsidy for electric cars is supposed to bring the turnaround. An instrument that recently failed has now been resurrected, as the new special fund seems to make politics’ horizons infinite.

To appease criticism within their own ranks regarding the combustion engine ban, the Chancellor floated an extension for plug-in hybrids and range extenders. But fundamentally, the combustion engine ban remains, following the SPD line, which essentially mirrors the green hardline ideology that has driven the economy to collapse. Everything else is window dressing to make the political slogan of technological openness appear meaningful.

Media Games and Hardline Ideology

Vice Chancellor and Finance Minister Lars Klingbeil of the SPD also spoke, harmoniously and in agreement with the substance. He endorsed pragmatism and flexibility—in plain terms: We recognize that automotive production in Germany may soon belong to the past. But essentially, that does not bother us, since we trust it will no longer be needed in eco-socialist Europe under Brussels anyway.

According to the Berlin bubble’s political vision, family cars and second vehicles will soon be relics. The future of mobility should be green, just not individual. It is based on a confused plan for state-operated public transport.

The few electric cars approved in the distant future are likely to be privileged status symbols, rarely owned, usually rented for short periods. Green revenge on the long-resisting German citizen.

To be clear: this auto summit called by the Chancellor was nothing but a political show. A carefully staged media event, fitting seamlessly into the PR games Merz treats as a form of politics. Consider the “Made for Germany” coffee klatsch, which faked an investment offensive, or the almost embarrassing rebranding of citizens’ income into basic security.

Regardless of the coalition constellation over recent years, the goal has always been the same: to consistently push the restructuring of the economy into an eco-socialist foundation in key sectors of industry and energy.

Predictable End

The ruling political ideology’s preferred solution—and the one that applies to all economic misdevelopments today—is predictable: new subsidies and another electric car purchase bonus. The summit ends as no one should be surprised. The long-dried subsidy channels of the green favored economy are flooded with fresh state credit. True to the stock-market motto: the tide lifts all boats.

Anyone following the bond markets closely can see that this policy is bound to end in fiscal, economic, and ultimately societal fiasco. About three years ago, secular shifts away from increasingly risky government bonds began, making financing of political grandiose dreams more difficult in the future. The end of this policy will come when the bond market finally lowers its thumb. Until then, we can look forward to the next summit.


* * * 

About the author: Thomas Kolbe, a German graduate economist, has worked for over 25 years as a journalist and media producer for clients from various industries and business associations. As a publicist, he focuses on economic processes and observes geopolitical events from the perspective of the capital markets. His publications follow a philosophy that focuses on the individual and their right to self-determination.


Tyler Durden
Tue, 10/14/2025 – 03:30

Africa Is Home To 16 Of The World’s 20 Fastest Growing Populations

0
Africa Is Home To 16 Of The World’s 20 Fastest Growing Populations

At current rates, it will take 133 years for America’s population to double given aging demographics and low fertility rates.

By contrast, several countries in Africa and the Middle East are set to double in a quarter century. For instance, Kinshasa, in the DRC, is forecast to be among the most populous cities worldwide by 2080 given rapid population growth.

This graphic, via Visual Capitalist’s Dorothy Neufeld, shows the fastest-growing populations in the world, based on data from the United Nations.

Years for the Fastest Growing Populations to Double in Size

Below, we show countries with the fastest annual doubling rates at current projections:

As we can see, Oman and Syria are set to double their population in just 20 years.

Overall, the population of Arab states are projected to double in 36 years, supported by average fertility rates of 3.2 births per women. Yemen and Afghanistan each are set to double in size in 24 and 26 years, respectively.

In Africa, the Central African Republic and Somalia are set to reach this milestone in 21 years, making them the fastest-growing populations on the continent. Perhaps even more strikingly, the DRC, with a population of 112.8 million in 2025, could double by 2047.

Going further, the DRC is set to become the fifth-most populous country in 2100, up from 15th in 2025. Meanwhile, Nigeria is set to the fourth-largest by population after India, China, and Pakistan.

To learn more about this topic, check out this graphic on the fastest shrinking countries in the world.

Tyler Durden
Tue, 10/14/2025 – 02:45

Is Ukraine Training Drug Cartel Mercenaries From Latin America?

0
Is Ukraine Training Drug Cartel Mercenaries From Latin America?

Authored by Liz Heflin via Remix News,

Recent reports highlight that some individuals, including those with criminal connections, have come to Ukraine to gain experience with drones, learning advanced tactics and hoping to take that knowledge back to their criminal bosses.

It has been well documented that many foreigners, including Latin Americans, have gone to fight in Ukraine. Some go for the paycheck, others for the cause — Ukrainian independence. 

Some apparently were not prepared for all-out war. “There have been instances where, after facing intense combat, some Colombians decided to leave,” reads a CEPA article from October 2024. 

That same article does note one Colombian who told CEPA “he has heard from home that the cartels in Colombia have already taken lessons from the war in Ukraine, and are using First Person View (FPV) drones to strike at the army and police.” 

Rumors that Ukraine directly recruits mercenaries from drug cartels in Latin America have others crying disinformation, although they admit there have been “isolated cases.”

French outlet Intelligence Online, cited by a Russian website, The Insider, reported in July that Mexican intelligence had warned its Ukrainian counterpart that cartel members from Mexico and Colombia had signed up to serve in Ukraine to gain specialized drone training to take back home and use for “foreign criminal organizations.”

They also mention a Mexican and Colombian company by name, one of which popped up in Polish customs reports; both are linked to drug trafficking. Investigation into this report is supposedly ongoing. 

As to such reports being disinformation, a website linked directly to the Russian military does not help dispel this claim. The content appears to be all AI-generated, complete with a byline photo for several articles that looks almost identical (middle-aged White man in dark suit) and with a similar vanilla American name (John Baker, William Moore, Fred Turner). The brief piece linked above from September pushes the line that Ukraine is actively recruiting from criminal groups. 

Hector Bernal, a military instructor, poses for a photo in La Mesa, Colombia, Wednesday, Jan. 10, 2024. Bernal, a retired combat medic who runs a center for tactical medicine outside Bogotá, says that in the last eight months he’s trained more than 20 Colombians who later went on to fight in Ukraine. He says that a professional soldier who has six years in the army doesn’t make more than $600 a month in Colombia, but in Ukrain,e the soldiers are being paid $3,000 to $4000 a month. (AP Photo/Ivan Valencia)

“Former Colombian officer says Ukraine enlists mercenaries from cartels and guerrilla groups like FARC and ELN, seeking combat training to aid criminal networks,” the lead reads. 

This line was parroted by a Bulgarian site, which went on to say that Colombian President Gustavo Petro had urgently called for a law banning mercenary activity, effectively joining the 1989 convention that prohibits and punishes the recruitment, use, financing, and training of mercenaries. 

Petro did make such a proclamation. But it was in response to Colombian mercenaries serving in Sudan’s notorious RSF, with these Colombians reportedly even being involved with training child soldiers. Oddly, and somewhat embarrassingly for Colombia — and Petro — Colombia reportedly already knew about their citizens in the RSF and issued a formal apology to Sudan for their involvement back in December 2024. 

Petro did just a few days ago call for Colombians to return home from Ukraine and to be allowed to do so in the wake of accusations that volunteers were being forced to sign contracts they did not understand (as they were in Ukrainian) and that they are being held against their will. 

“They have practically kidnapped us. They are armed. They have taken photos of us for the police. They don’t want to let us go,” one soldier told Colombia Reports. These volunteer soldiers, which the portal calls “mercenaries,” are claiming to have suffered “the worst humiliation at the hands of the people we came to help.”

President Petro himself posted on X just last week about the situation: “Ukrainians treat Colombians as an inferior race. I ask the Colombian mercenaries, who are being handled like cannon fodder, led by companies guided from Miami, to return to the country immediately.” 

FRANCE 24 Observers team indicated in November 2024 that Ukraine was posting on social media, including in English and Spanish, to attract soldiers from abroad. It also relayed stories of missing Colombian soldiers and distraught families back home. According to their research at the time, 57 Colombians had been killed in Ukraine and 77 were missing at the time. 

This site also notes that Colombia had “proposed legislation that would ban Colombian citizens from fighting in foreign wars” in August of 2024, whereas Petro only posted about it this past August. 

This is unfortunate timing for Zelensky supporters over in Europe, given the EU–CELAC Summit in Colombia next month. Just a couple of days ago, Petro posted photos of his meeting with Ursula von der Leyen, where they were all smiles and full of hope regarding future deals to be done. 

Ukraine is actively recruiting, as proven by its military’s own recruitment site. But their pitch isn’t exactly “free drone training for narco bosses.” Instead, it attempts to inspire Latin Americans to see the Ukrainian cause as their own.

The site claims that thousands of Latin American volunteers have joined the war effort and proceeds to give stories of three Ukrainians “whose names are inscribed in the history of various Latin American countries.”

“Now heroic volunteers from various countries of South America have inscribed their names in the history of Ukraine and are writing a new, perhaps the most important, page in the history of Ukrainian-Latin American relations,” it reads. 

This is a far cry from any direct recruitment from drug cartels. And it certainly does not scream any sort of active collaboration or deal between Ukraine and criminal organizations to help get them drone training or technology. 

FILE – In this May 3, 2020, file photo, Venezuelan security forces guard the shore and a boat in which authorities claim a group of armed men landed in the port city of La Guaira, Venezuela, calling it an armed maritime incursion from neighboring Colombia. A judge in Colombia sentenced three Venezuelan men on Tuesday, May 18, 2021, to six years in prison for helping organize the ill-conceived plot to remove President Nicolás Maduro involving former American Green Berets. (AP Photo/Matias Delacroix, File)

Unfortunately, for those who do sign up, whether they are official mercenaries for drug lords or simply looking to join the cause, the risks don’t stop once they leave Ukraine — if they leave alive. In the summer of 2024, two Colombians on their way home from Ukraine were detained by Venezuela, where they had a layover. They were immediately sent to Moscow, highlighting Putin’s close alliance with Maduro, where they were charged by Russia for serving as mercenaries fighting against Russia. 

According to TASS, both have pleaded guilty and face up to 15 years in prison.. 

Read more here…

Views expressed in this article are opinions of the author and do not necessarily reflect the views of ZeroHedge.

Tyler Durden
Tue, 10/14/2025 – 02:00

IDF Vows To Destroy All Hamas ‘Terror Tunnels’ As Part Of Disarming Gaza

0
IDF Vows To Destroy All Hamas ‘Terror Tunnels’ As Part Of Disarming Gaza

Authored by Dave DeCamp via AntiWar.com,

Israeli Defense Minister Israel Katz said on Sunday that the Israeli military would destroy tunnels in Gaza after the remaining Israeli captives are released by Hamas, which has happened on Monday.

“Israel’s great challenge after the phase of returning the hostages will be the destruction of all of Hamas’s terror tunnels in Gaza, directly by the IDF and through the international mechanism to be established under the leadership and supervision of the United States,” Katz wrote on X.

Via Associated Press

“This is the primary significance of implementing the agreed-upon principle of demilitarizing Gaza and neutralizing Hamas of its weapons. I have instructed the IDF to prepare for carrying out the mission,” he added.

According to the outline of the Gaza ceasefire proposal released by the White House, all “military, terror, and offensive infrastructure, including tunnels and weapon production facilities, will be destroyed and not rebuilt,” and there will be a “process of demilitarization of Gaza under the supervision of independent monitors.” But the details of how those steps will be taken, including who will be doing it, are unclear. A senior Hamas official has also said that Hamas won’t disarm unless it can hand its weapons to a Palestinian state.

So far, Israel and Hamas have just entered the first phase of the ceasefire deal, which involves the release of the Israeli hostages in exchange for thousands of Palestinians held in Israeli jails, the IDF pulling back to an agreed-upon line, and Israel allowing more aid to enter Gaza. Details on implementing the rest of the agreement still need to be worked out in negotiations between Israel and Hamas.

Katz’s comments come as many are concerned Israel will restart its brutal war once Hamas releases the Israeli captives. Also on Sunday, Israeli Prime Minister Benjamin Netanyahu said the military “campaign is not over,” though he could be referring to other areas where Israel is at war or potential escalations elsewhere in the region.

“And I want to say: Everywhere we fought – we won. But in the same breath, I must tell you: The campaign is not over. There are still very great security challenges ahead of us,” Netanyahu said, according to a statement from his office. “Some of our enemies are trying to rebuild themselves to attack us again. And as we say – ‘We’re on it.’”

According to a report from Israel Hayom, the US has given Israel a guarantee that it would back Israeli military action if it determined Hamas violated the deal in a way that “poses a security threat.” The report said the understanding “constitutes a side agreement” between the US and Israel.

The US gave Israel a similar side deal for the November 2024 Lebanon ceasefire agreement, which Israel continues to violate on a near-daily basis.

Tyler Durden
Mon, 10/13/2025 – 21:45