

61.3 F
Chicago
Monday, September 14, 2026
Home Blog Page 1168

Now Comes the California Fire Sale: China-Based Company Is Buying Up Land Incinerated by Firestorms

0
Now Comes the California Fire Sale: China-Based Company Is Buying Up Land Incinerated by Firestorms

Authored by Victoria Taft via PJMedia.com,

Now comes the fire sale. 

If foreign corporations want to buy burned-out properties, can those sales be stopped? Should they be stopped? 

When the feared firestorm hit Pacific Palisades, Malibu, and Altadena in Southern California last January, the Los Angeles mayor was MIA, the “public safety” guy in charge—the vice mayor—was on home confinement for making an anti-Israel bomb threat on city hall, fire fighters were not pre-deployed, there was no water in the reservoir, and fire hydrants went dry in the Palisades. 

Soon came vows by L.A. Mayor Karen Bass and elected officials in Malibu, Altadena, and the Palisades to streamline the rebuilding and permitting, which turned out to be a joke. Now, amid bad leadership, virtue signaling masquerading as help, incinerated FireAid money, and promises in name only, comes the fire sale. 

In early August came word from an exclusive story in Realtor.com that foreign investors were buying up prime lots in the burned-out area of an iconic Malibu beach.

Now, a foreign investor has been secretly scooping up many of the burned lots on the oceanfront side of the PCH—with the vision of rebuilding the mansions that dotted the coastline in the iconic beach town.

‘Once this beach is built back and it’s all brand-new construction, I think it’s going to be a very desirable spot for a lot of wealthy people to try to buy a beach house,’ Weston Littlefield with the Weston James Group tells Realtor.com®.

The luxury real estate agent and his colleague Alex Howe have been working with the investor who has, so far, purchased nine lots worth more than $65 million—but the process isn’t random.

The strip of homes nestled between the Pacific Coast Highway and the Pacific Ocean is the storied La Costa Beach.

Nine of the most desirable lots have been sold by people who can’t wait or can’t afford to rebuild.

Our RedState colleague, Jen Van Laar, reports that the buyers are a couple of Kiwis—New Zealanders. These businessmen are based in the once-free Hong Kong, China to be close to their toy manufacturing empire in Guangzhou and Shenzhen. They also own a business park in Issaquah, Washington.

Nick and Mat Mowbray run Zuru, a company well known for making mini toys and replicas. 

The Mowbray brothers also run another Chinese-based company, Zuru Tech, that makes modular pre-fab homes made of a concrete which they plan to use in their new Malibu real estate venture. Let’s hope they’re not mini homes.

Jen makes a good point about the old carbon footprint of shipping all those concrete housing pieces across the ocean. It does seem contrary to those California “values” we keep being hectored about. Remember, this is the state, after all, that made the LADWP restore brush to save an alleged endangered weed after LAWP cleared it due to fire danger. I do not stutter. See Stunner: California Saved a Shrub Instead of Protecting Humans From the L.A. Firestorm.

But back to the land grab. Yahoo News reported that one of the brokers says “the investor wants to rebuild the mansions and expects the investment will turn a considerable profit with ‘time and patience.'” The current estimate to get permits approved in Malibu is anywhere from one to two years.

How many Malibu fire victims have the time and money to wait that long? Probably a few, but not all. 

Here’s another question. Are California’s so-called “values” honored by allowing foreign investors to reshape the premier and most iconic real estate of the West Coast of the United States? Should stopping foreign ownership even be considered in a relatively free market? 

Gov. Gavin Newsom signed an executive order to protect people in Altadena, parts of Malibu, and the Palisades from lowball real estate offers while deploring “greedy speculators taking advantage of their pain.” Is that what buying a $10+ million property before the fire and settling for $6 million for a beach lot is—speculating?

In Altadena, Dwell Magazine reports that at least half of the properties for sale following the devastating January fires have been purchased by corporations; however, “individuals can purchase property through LLCs to limit legal exposure.” The publication reports, however, that’s higher than the national trend and furthermore, “42 percent of those sales are now held by just six companies, each of which has acquired four or more homes.”

Dwell reports, “Black Lion Properties, LLC—recently confirmed to be operated by Edwin Castro, the record-breaking Powerball winner… The company has quietly acquired at least a dozen fire-damaged or distressed properties in Altadena, spending nearly $9 million in the process.”  

Interesting side note. Castro, the top buyer in Altadena, is a local Powerball Lottery winner who’s putting his winnings in real estate rather than hookers, blow, and trinkets. In 2022, Castro won “$2.04 billion,” but by the time Uncle Sugar got his cut, the lump sum payment ended up being “$997 million.” He bought his parents a new home in Altadena, and he bought one in Malibu, which was ironically, torched in the firestorm.

Another company, “Sheng Feng Global Inc., formed in 2022, is associated with several shell-like entities related to real estate” has purchased six home sites in the Altadena area. The company is connected to multiple real estate entities and “hints at possible international ownership, but the full picture remains murky.” It sure does. A logistics company in China could be connected, but, as Dwell reports, things are “murky.” 

By design.

California Democrats have turned down at least three proposed laws to limit or ban foreign ownership of large amounts of land. Assembly Bill 475 would have halted foreign land ownership within 50 miles of military installations, and Senate Bill 224 would have, had it passed, stopped foreign governments from a controlling interest in agricultural land. The legislature did pass, however, Senate Bill 1084, in 2022, that would have restricted ownership of California agricultural land. 

Gavin Newsom vetoed it, saying the feds were already handling the problem. The Biden administration wasn’t.

To what extent, if any, should California officials stop the foreign ownership of American land?

Tyler Durden
Sun, 08/24/2025 – 18:40
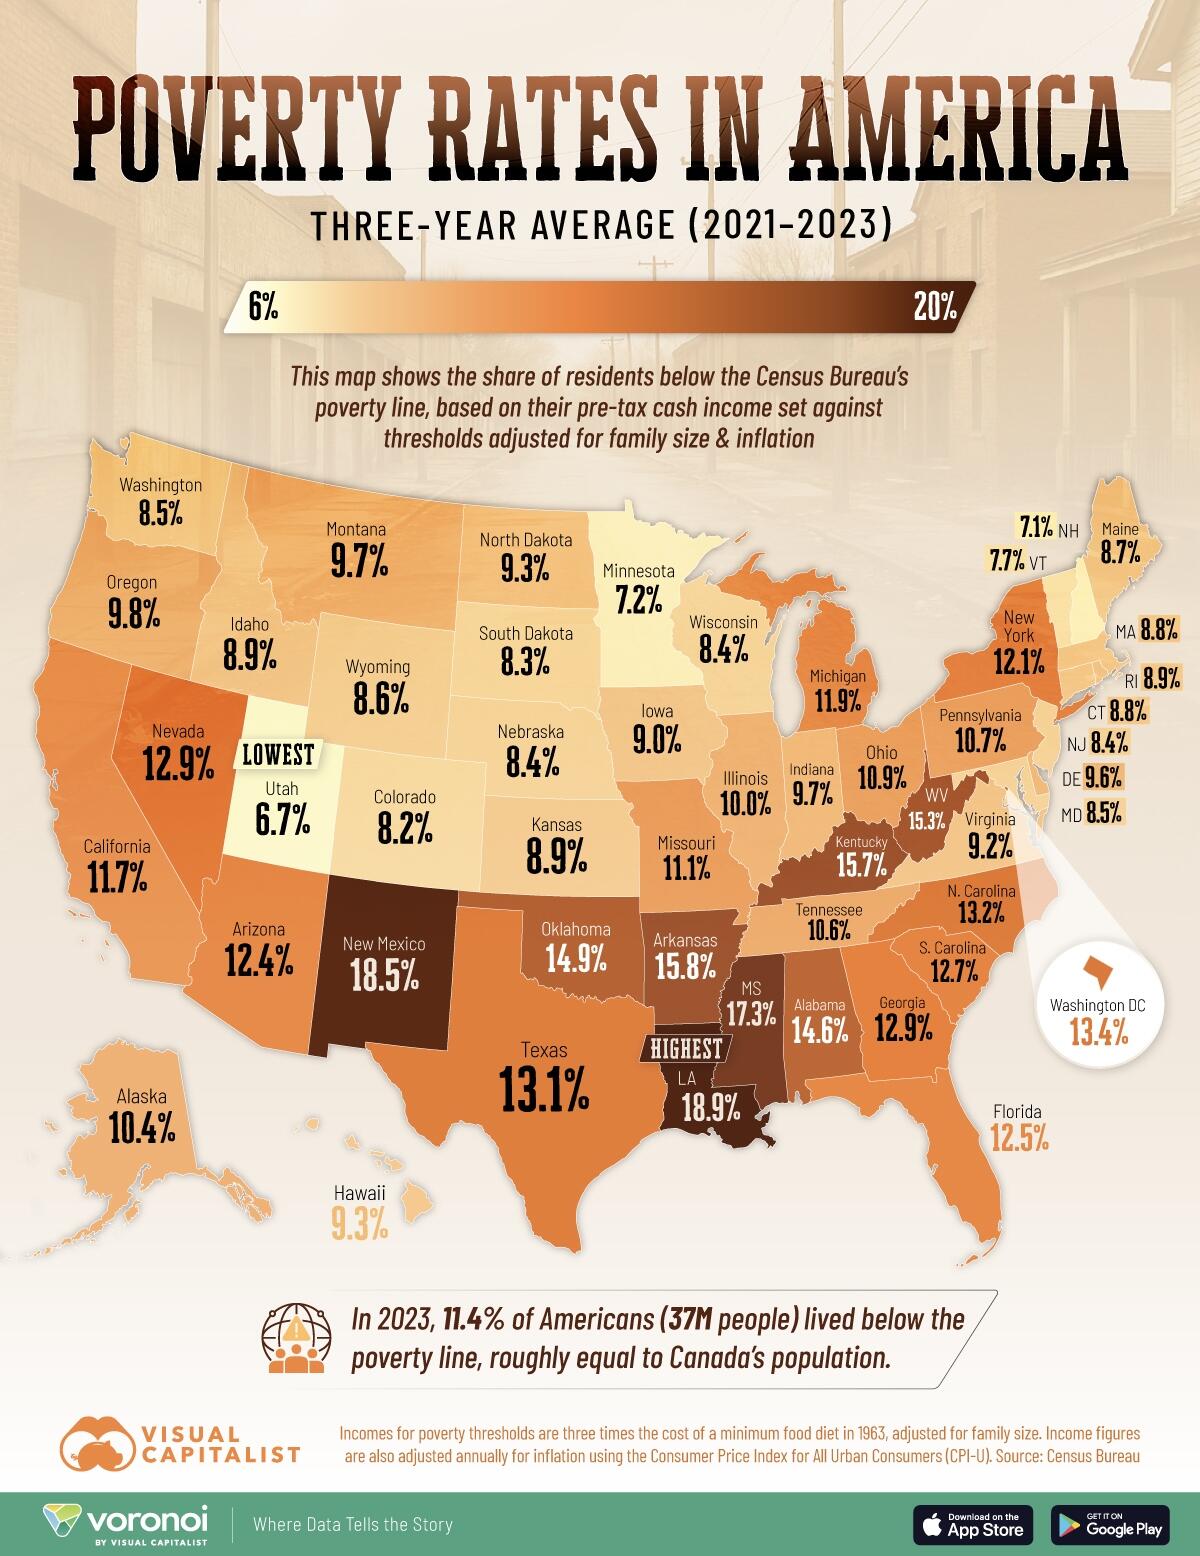
Mapping Poverty Rates Across America

0
Mapping Poverty Rates Across America

America’s economic landscape looks very different depending on where you live.

This map of U.S. poverty rates by state, via Visual Capitalist’s Pallavi Rao, makes that disparity clearer.

Each shade represents the share of residents living below the poverty line, inviting quick comparisons across the country.

The data for this visualization comes from the U.S. Census Bureau.

The U.S. Census Bureau calculates poverty lines using pretax household income against a threshold at three times the cost of a minimum food diet from 1963, adjusted for family size and inflation.

For reference, this is a quick guide on how much a household needs to be earning to be considered below the poverty line in 2023.

  • One person: ≤$15,480

  • Two people: ≤$19,680

  • Three people: ≤$24,230

  • Four people: ≤$31,200

Ranked: U.S. Poverty Rates by State

Louisiana tops the list at 18.9%, leaving nearly one in five residents below the poverty threshold despite the state’s large energy sector.

Rank State State Code Share of Population
in Poverty
# in Poverty
1 Louisiana LA 18.9% 853K
2 New Mexico NM 18.5% 388K
3 Mississippi MS 17.3% 501K
4 Arkansas AR 15.8% 473K
5 Kentucky KY 15.7% 699K
6 West Virginia WV 15.3% 268K
7 Oklahoma OK 14.9% 589K
8 Alabama AL 14.6% 727K
9 District of Columbia DC 13.4% 88K
10 North Carolina NC 13.2% 1.4M
11 Texas TX 13.1% 3.9M
12 Georgia GA 12.9% 1.4M
13 Nevada NV 12.9% 409K
14 South Carolina SC 12.7% 673K
15 Florida FL 12.5% 2.8M
16 Arizona AZ 12.4% 903K
17 New York NY 12.1% 2.3M
18 Michigan MI 11.9% 1.2M
19 California CA 11.7% 4.5M
20 Missouri MO 11.1% 675K
21 Ohio OH 10.9% 1.3M
22 Pennsylvania PA 10.7% 1.4M
23 Tennessee TN 10.6% 744K
24 Alaska AK 10.4% 74K
25 Illinois IL 10% 1.2M
26 Oregon OR 9.8% 415K
27 Indiana IN 9.7% 659K
28 Montana MT 9.7% 109K
29 Delaware DE 9.6% 98K
30 Hawaii HI 9.3% 133K
31 North Dakota ND 9.3% 72K
32 Virginia VA 9.2% 783K
33 Iowa IA 9% 287K
34 Idaho ID 8.9% 172K
35 Kansas KS 8.9% 255K
36 Rhode Island RI 8.9% 96K
37 Connecticut CT 8.8% 318K
38 Massachusetts MA 8.8% 604K
39 Maine ME 8.7% 120K
40 Wyoming WY 8.6% 49K
41 Maryland MD 8.5% 524K
42 Washington WA 8.5% 658K
43 Nebraska NE 8.4% 165K
44 New Jersey NJ 8.4% 776K
45 Wisconsin WI 8.4% 490K
46 South Dakota SD 8.3% 74K
47 Colorado CO 8.2% 473K
48 Vermont VT 7.7% 49K
49 Minnesota MN 7.2% 409K
50 New Hampshire NH 7.1% 98K
51 Utah UT 6.7% 226K
N/A U.S. US 11.4% 37.6M

Neighboring Mississippi (17.3%) and Arkansas (15.8%) tell a similar story of limited job diversity and chronically low household incomes.

In fact, a contiguous belt stretching from Louisiana and Mississippi through Arkansas and up to West Virginia contains every state with poverty rates above 15%.

Historic underinvestment, weaker safety-net programs, and lower average wages all help explain why the South accounts for four of the five worst-affected states.

Northern and Plains States See the Lowest Poverty Shares

In stark contrast, Utah (6.7%), New Hampshire (7.1%), Minnesota (7.2%), and Colorado (8.2%) post some of the lowest poverty figures in the country.

These states benefit from stronger labor markets, higher median wages, and broader access to education and healthcare.

Even populous Midwestern states like Illinois and Wisconsin keep poverty near or below 10%, underscoring how economic structure and public policy can insulate households from hardship.

Geography, then, is a reliable—if imperfect—proxy for opportunity in today’s America.

Population Size Skews the National Picture

Looking only at rates can mask the human scale of poverty.

California’s poverty rate sits near the national average at 11.7%, yet its sheer population means 4.5 million Californians live in poverty.

Texas tells a similar story: its 13.1% rate translates into 3.9 million people, the second-largest total nationwide.

Altogether, the U.S. counted 37.6 million residents in poverty during in 2023, almost the size of Canada’s entire population

If you enjoyed today’s post, check out Mapped: Average Salary by State in 2025 on Voronoi, the new app from Visual Capitalist.

Tyler Durden
Sun, 08/24/2025 – 18:05

Home Sales See Record July Cancellations As High Mortgage Rates Weigh On Buyers

0
Home Sales See Record July Cancellations As High Mortgage Rates Weigh On Buyers

Authored by Tom Ozimek via The Epoch Times,

A growing share of U.S. home sales collapsed in July as wary buyers pulled back, underscoring the strain of elevated mortgage rates despite a modest uptick in overall existing-home sales.

Roughly 58,000 purchase agreements fell through last month, equal to more than 15 percent of homes that went under contract, according to real estate brokerage Redfin. That’s the highest cancellation rate for July since the company began tracking the data in 2017.

Texas and Florida saw the most scrapped contracts, with San Antonio topping the list at nearly one in four deals canceled. Florida metros, including Fort Lauderdale, Jacksonville, and Tampa, also recorded some of the highest cancellation rates.

Real estate agents say buyers are taking advantage of a market where listings linger longer, giving them time to keep shopping or back out during inspections.

The most common reasons buyers back out are cold feet, high standards, and inspection issues, according to Bonnie Phillips, a Redfin agent in Cleveland.

She added that cancellations are especially common in borrowers using Federal Housing Administration loans and Department of Veterans Affairs loans, who can face more financing hurdles.

The cancellations came alongside a small uptick in overall sales. The National Association of Realtors (NAR) reported on Aug. 21 that existing-home sales rose 2 percent in July to an annual rate of just over 4 million units, up slightly from June’s nine-month low.

“The ever-so-slight improvement in housing affordability is inching up home sales,” NAR chief economist Lawrence Yun said in a statement.

“Wage growth is now comfortably outpacing home price growth, and buyers have more choices.”

Still, affordability remains the biggest challenge. The median existing-home price stood at $422,400 in July, barely changed from a year earlier, according to NAR data. Mortgage rates averaged 6.7 percent in July, more than double what buyers could lock in three years ago.

The strain is also evident among homebuilders.

A closely watched gauge of builder sentiment from the National Association of Home Builders (NAHB) fell in August to its lowest level in more than two-and-a-half years. More than a third of builders reported cutting prices by an average of 5 percent, while two-thirds offered incentives such as help with closing costs to attract wary buyers.

“Affordability continues to be the top challenge for the housing market, and buyers are waiting for mortgage rates to drop to move forward,” NAHB Chairman Buddy Hughes said in a statement.

“Builders are also grappling with supply-side headwinds, including ongoing frustrations with regulatory policies connected to developing land and building homes.”

Construction data point to the same slowdown. Government figures showed single-family housing starts fell in June to an 11-month low, while permits for future construction sank to the lowest level in more than two years. July data, however, showed some improvement.

Mortgage rates have eased slightly in recent months, trimming typical monthly payments and boosting purchasing power for some buyers. Markets widely expect that the Federal Reserve will cut rates soon—but analysts warn that mortgage rates won’t necessarily follow the Fed’s rate down if inflation remains elevated.

“A Fed rate cut does not mean lower mortgage rates. With inflation still sticky, mortgage rates could remain elevated even if there is a cut,” Lisa Sturtevant, chief economist at real estate data company Bright MLS, said in a recent commentary.

“Prospective home buyers who have been waiting for mortgage rates to come down may continue to be disappointed.”

Sturtevant noted that after years of higher prices for everyday goods and rising consumer debt, households have become increasingly cautious about taking on a mortgage.

“As a result, as we head into fall, more and more would-be buyers are going to decide to hold off and push their home buying out to 2026 when the economy may be more certain, inflation may come down, and rates may be lower,” she said.

Tyler Durden
Sun, 08/24/2025 – 17:30

Dirt Bike Gangs Terrorize Streets From D.C. To Baltimore

0
Dirt Bike Gangs Terrorize Streets From D.C. To Baltimore

It’s no secret that Democrats have failed the residents of the Mid-Atlantic. Whether it’s a power bill crisis fueled by disastrous green policies to “save the planet” in the name of some alleged climate crisis, or social-justice experiments at the local and state levels that have epically backfired and transformed parts of Washington, D.C., and Baltimore into crime-ridden hellholes, the days of law-abiding citizens tolerating this mess are over. 

Things have gotten so bad that President Trump deployed the National Guard across the D.C. metro area to support local law enforcement, which has suffered from a dangerous officer shortage in recent years after Democrats in the nation’s capital had the bright idea to defund the police… 

And – shocker, crime is coming down in some areas, according to official government data.

But it seems Trump has more work to do – as lawless assholes on dirt bikes and ATVs are terrorizing the DC area:

This extends across the Baltimore metro areas as well. 

Time for a little more ‘law and order’ – eh? 

Tyler Durden
Sun, 08/24/2025 – 16:55

USDA Ends Solar Subsidies On American Farmland

0
USDA Ends Solar Subsidies On American Farmland

Agriculture Secretary Brooke Rollins announced Monday that the Department of Agriculture will no longer use taxpayer dollars to fund large-scale solar or wind projects on productive farmland, nor allow solar panels made by foreign adversaries in USDA programs.

The department cited farmland loss as a driving concern. Tennessee has lost more than 1.2 million acres in the past 30 years and could lose 2 million by 2027. Nationally, solar installations on farmland have risen nearly 50% since 2012.

“Our prime farmland should not be wasted and replaced with green new deal subsidized solar panels,” Rollins said. “One of the largest barriers of entry for new and young farmers is access to land. Subsidized solar farms have made it more difficult for farmers to access farmland by making it more expensive and less available.”

On X, she added: “This destruction of our farms and prime soil is taking away the futures of the next generation of farmers and the future of our country. Starting today, [USDA] will no longer deploy programs to fund solar or wind projects on productive farmland, ending massive taxpayer handouts. Also ENDING the use of panels made by foreign adversaries like China.”

Rollins made the announcement in Tennessee with Governor Bill Lee, Senators Marsha Blackburn and Bill Hagerty, Representative John Rose, and USDA Deputy Secretary Stephen Vaden. Lee said, “Tennesseans know that our farmland is our national security, our economic future, and our children’s heritage.” Blackburn added: “Tennessee farmland should be used to grow the crops that feed our state and country, not to house solar panels made by foreign countries.”

Lawmakers across the country praised the decision. Representative Glenn “GT” Thompson said, “Secretary Rollins understands that food security is national security.” Representative Tom Tiffany stated, “The land that feeds America should never be sacrificed for unreliable green energy experiments subsidized by taxpayer dollars.” Representative Harriet Hageman added, “Our agricultural heritage is the backbone of this nation, and these commonsense reforms put food security, national security, and American sovereignty first.”

Effective immediately, wind and solar projects are no longer eligible for the USDA’s Business and Industry Guaranteed Loan Program. Under the Rural Energy for America Program, ground-mounted solar projects larger than 50kW or without proof of historic energy use will not qualify, and solar projects will no longer receive priority points for REAP grants.

The USDA said these changes will reduce taxpayer costs, eliminate market distortions from subsidies, and ensure renewable energy equipment in USDA projects comes from American manufacturers.

Tyler Durden
Sun, 08/24/2025 – 15:45

No Lonesome Doves

0
No Lonesome Doves

By Peter Tchir of Academy Securities

If you were dovish coming into this week, you are no longer alone. 

We’ve been arguing for 3 to 4 cuts this year. We thought the Fed should have cut at the last meeting and the Fed would have cut at the last meeting if the June jobs data remotely resembled what it got revised down to when the July jobs data was released (had to re-read that to make sure it makes sense, but I think it does – just all so confusing when the data gets revised so massively).

But we thought Powell might try to channel some hawkishness. That he might look for “bright” spots in the jobs data – it was an “anomaly,” the unemployment rate is low, or that the number of jobs to keep unemployment steady is well below 100,000 jobs per month. But we got none of that!

It is certainly possible that the August jobs data, released ahead of the next Fed meeting, will be strong enough to keep the Fed on hold. But we doubt it.

Also, the strategy of having so many potential Fed candidates all make reasonable arguments for a cut in September certainly helped.

It also seems likely, in hindsight (and not obvious from the recently released minutes) that while there were “only” 2 dissenters, the conversation to not cut may have been a lot closer than previously thought.

The market didn’t get all the way back to pricing in a September cut, but it likely will and we still think at least 3 (instead of 2.2 priced in) is the right number of cuts for the year – unless we get a strong turnaround in jobs, which is possible as various policies kick in – accelerated depreciation and ProSec (Production for Security).

Inflation and Tariffs

We will get the big monthly tariff revenue. If it is a big number it should help bonds (less of a monthly deficit) but we will see and hear more conversations about who will ultimately pay for the tariffs. We continue to expect this to take months and even quarters to play out, as the progression will be:

  • Push suppliers for discounts (that will be product dependent and also depend heavily on how big or powerful the buyer is).
  • Absorb some costs while figuring out the longer-term strategy (and even the longer-term policy as that remains in flux and is still winding its way through the courts).
  • Slowly pass prices on to the consumers – while trying to not just keep consumers happy with prices, but also trying to avoid becoming a focus of the administration which continues to argue that foreigners pay for all the tariffs.

Tariff-related slowdowns in the economy are a bigger risk than tariff inflation, which is why we are still in the 3 to 4 cut camp.

A Couple of Equity Narratives

Despite the big rally on Friday, when the Nasdaq 100 was up 1.5%, it lost 1% on the week. There have been some small “cracks” in the AI/Data Center narrative of late. Anything from how data centers are being funded, to the availability of electricity (and water), to concerns about whether companies are actually deriving big benefits from the AI spend. Even lately, there are questions about which chips China will be allowed to buy along with which chips China will actually buy. Nothing major, but I think there is a “lurking” concern, at least for me, that the risk is we are spending as though we have 2030 technology (the cost has grown rapidly as this industry has dominated capital expenditures) with “only” 2025 technology. Yes, the technology is awesome, but is it delivering versus cost? Is “prediction” or “probability-based prediction” truly AI?

This industry has been such a strong driver not just of the stock market’s rebound off the lows, but also for the economy in general, that we should watch closely for any sign of a sniffle, let alone a cold.

Which we think means this is a good time to introduce this chart.

We used ETFs here rather than indices as it is an easy way to get everything “normalized” on U.S. hours and in USD.

The fact that FEZ, a Euro Stoxx 50 ETF, is ahead of QQQ (Nasdaq 100) for the year, probably doesn’t surprise many people as European growth (and spending) has been a big story. As has been the appreciation of the Euro (up 13% since the start of the year).

I cannot remember the last time I’ve seen anyone tout Chinese stocks. Emerging markets, heck yes. Emerging Markets ex-China, definitely. But Chinese stocks? Who in their right mind would buy stocks in the country that remains the “public enemy #1” of the trade team? Yet, FXI (China large cap ETF) just closed at its highest levels of the year, up 30% year-to-date and 55% for the past year.

Maybe Chinese stock performance is because of the trade deals? Or maybe, and I suspect this is the case, it is in spite of the trade deals. Their control over processed and refined rare earths, critical minerals, and commodities has become a clear issue for economies across the globe (the U.S. has taken some steps, like investing in MP, but so much more still needs to be done, which will fuel our ProSec™ trades).

The U.S. represents about 15% of Chinese exports, a big number, but only a portion of their economy, and while the U.S. is taking major steps to become less dependent on China (a move we agree with especially on issues surrounding National Security, broadly speaking), not every country has such strong views (or the ability to do anything about it, even if they have strong views).

The Russell 2000, which has lagged badly, finally had a good week, maybe even great week. It was up almost 4% on Friday, accounting for a big chunk of its year-to-date performance of 6%.

When we look at shares outstanding, IWM has seen outflows almost the entire year, though this started to reverse in August. QQQ, on the other hand, saw a lot of dip buying and has had pretty steady inflows, resulting in the largest number of shares outstanding on August 19th (more dip buying, but we saw outflows on Friday – which is interesting). Short interest in IWM is much greater than short interest in QQQ, which is interesting as a contrarian.

Is it time for a significant period of outperformance for the Russell 2000 versus Nasdaq 100? At the moment, I’m not convinced, but it is certainly worth a look.

The Gloves off With Russia?

President Trump this week basically accused the Biden administration of handcuffing Ukraine too much during the early years of the war.

It is safe to say that when Academy’s Generals and Admirals discuss prosecuting wars, they all mention the need to disrupt supply. When the U.S. is at war, it will try to take out supply lines immediately. That is hitting depots. Destroying transit (railways in particular as they are most efficient, but then bridges and “choke points” on roads). Not allowing an enemy to “easily” retreat and regroup is also standard operating procedure. Logistics are a huge component of warfare (I almost wrote modern warfare, but historically, logistics have always been key – hence why we have phrases like “an army marches on its stomach”).

With the administration comfortable selling weapons to Europe, which in turn can provide them to Ukraine (it solves the U.S. issue of “donating” versus being paid), we could see more weaponry available to Ukraine.

There are clearly risks of escalation by attacking into Russia more aggressively, but from the start, we’ve argued that Putin won’t negotiate towards a realistic deal unless he faces the “stick.”

On the energy and sanctions side of the equation we continue to watch:

  • Russia’s trade with Europe. Europe has been weaning itself off of complete and utter dependence on Russia’s commodities, but there is still a meaningful reliance that we haven’t seen the will to break. That might be necessary to push Putin.
  • India’s purchases of Russian oil have attracted the most attention. That is in no small part because of allegations that India then mixes Russian oil (bought very cheaply) with oil from other sources to then sell it for nice profits. This seems like an easier one for the Trump administration to go after.
  • China. Will the U.S. risk escalating tensions with China over Russian oil? Do we risk losing supplies of processed rare earths and critical minerals? Is China well prepared with large stockpiles of oil anyways? This would be a big step as it would likely have negative consequences for the U.S. economy.
  • Brazil is more interesting. The admin is unhappy with Brazil and, at the moment, they are threatened or under much higher tariff rates than most countries. Brazil and Russia remain large trading partners. Those two facts would indicate that we could go after more tariffs related to Russian trade with Brazil. The issue is that much of what Brazil imports from Russia would impact agriculture, globally. Diesel and “fertilizer” are big on the list of what Brazil imports and tariffing those items, while effective in forcing Russia to the table, has the risk of disrupting the agriculture industry as price increases in diesel and fertilizer would flow through the food chain, potentially rapidly.

Balancing the carrot and stick with both Russia and Ukraine will be tricky, but it seems that the world is now trying to navigate this, which is optimistic from the standpoint of getting a real accord in the region.

Crypto Corner

As discussed on Friday in Crypto Privateers, the Cybercrime Marque and Reprisal Authorization Act to Combat Foreign Scam Syndicates was introduced to Congress. We think this is an interesting development and will shed light on what we have argued is an idea that should be explored.

As mentioned in last weekend’s Crypto Corner, ETH continued to outperform Bitcoin.

Bottom Line

Look for the market to price in more rate cuts, sooner than it currently has without a significant steepening of the yield curve. It is still a bit early to put on flatteners, but that is the direction we are leaning towards in terms of curve shape. Doves are no longer lonesome after Powell’s message on Friday.

Corporate credit – steady as she goes and we could see more paper issued than expected after Friday’s “everything” rally created another great opportunity for issuers.

On equities, has a reversal in market leadership started? It is early, but it seems like we could be poised for small and medium sized companies to outperform the megacaps that have led the way forward since April.

Weirdly, if I had to pick a “rest of the world” trade, I’d focus on China rather than some of the other current outperformers, in no small part, because it still seems awkward to suggest owning Chinese stocks “even if just for a trade.”

It seems almost impossible to believe that this is the last official week of “work summer” in the U.S. 

Good luck, enjoy, and get ready for what is likely to be a hectic few months, despite what the MOVE and VIX indices are telling us (low vol, really?).

Tyler Durden
Sun, 08/24/2025 – 15:10

Russian Nuclear Power Plant Damaged In Ukrainian Drone Attack, IAEA Monitors Radiation

0
Russian Nuclear Power Plant Damaged In Ukrainian Drone Attack, IAEA Monitors Radiation

In another dangerous escalation, Russia has accused Ukraine of launching a drone strike on the Kursk Nuclear Power Plant, which sparked a fire and damaged an auxiliary transformer, resulting in a 50% reduction in the output of reactor number three.

Several other energy facilities were also reportedly targeted during the overnight strikes, involving likely hundreds of drones. Russia’s military said that it intercepted nearly one hundred of them across various locations in the south.

Kursk Nuclear Power Plant’s news service reported that the fire was quickly brought under control and with no injuries. Radiation levels remained normal, according to local reports.

However, the press service also noted that two other reactors are currently not generating power, though one of them is undergoing scheduled maintenance. Reuters additionally details, “Ukraine launched a drone attack on Russia on Sunday, forcing a sharp fall in the capacity of a reactor at one of Russia’s biggest nuclear power plants and sparking a huge blaze at the major Ust-Luga fuel export terminal, Russian officials said.”

Kursk region’s acting governor, Alexander Khinshtein, swiftly condemned the “threat to nuclear safety and a violation of all international conventions.” The site lies some 40 miles from the Ukrainian border.

The International Atomic Energy Agency (IAEA) weighed in on the Sunday attack, saying the agency is monitoring the situation and that radiation levels around the Kursk plant remain normal.

The IAEA statement, however, did not mention expressly that the damage was due to a Ukrainian drone attack. It only said it “is aware of media reports that a transformer at the Kursk NPP in Russia has caught fire due to military activity. While the IAEA has no independent confirmation of these reports, [Director General] Rafael Grossi stresses that ‘every nuclear facility must be protected at all times.'”

In a separate incident, a fire broke out at the port of Ust-Luga in Russia’s Leningrad region, where a major fuel export terminal is located – after some 10 Ukrainian drones that were shot down in the area, resulting in dangerous falling debris.

The war on energy sites continues on, and is growing. Ukraine, in mounting such a brazen attack, is clearly trying to up its leverage – though as President Trump has previously stated, it’s Russia that still holds all the cards.

All of this illustrates that Trump has been wise to block Ukraine’s military from using American missiles for long-range attacks on Russian territory.

Fresh reporting in The Wall Street Journal has said that Washington is not allowing Ukraine to use US ATACMS missiles for such attacks, and that this prohibition has been on for at least several months.

 “President Trump has been very clear that the war in Ukraine needs to end. White House Spokesperson Karoline Leavitt told the newspaper. “Secretary Hegseth is working in lockstep with President Trump,” she noted. According to the report

The Pentagon has for months been blocking Ukraine’s use of long-range missiles to strike inside Russia, U.S. officials said, limiting Kyiv from employing a powerful weapon in its fight against Moscow’s invasion.

A high-level Defense Department approval procedure, which hasn’t been announced, has prevented Ukraine from firing any U.S.-made long-range Army Tactical Missile Systems, or Atacms, against targets in Russia since late spring, the officials said. On at least one occasion, Ukraine sought to use Atacms against a target on Russian territory but was rejected, two officials said.

“Elbridge Colby, the Pentagon’s undersecretary for policy, developed the ‘review mechanism’ to decide” on Ukraine’s repeat requests for permission to use long-range weapons made by the US and the ones provided by Western allies and depending on American intelligence and components, WSJ noted.

ATACMS file, US Army

So the Trump administration exercises effective veto over this – but it’s still a very dangerous situation, and it doesn’t mean the scenario hasn’t been ruled out.

Trump hopes that in blocking this option, Putin can still be wooed to the peace table to find settlement – but the reality remains that Washington should have never handed these weapons to Kiev in the first place, approved under the Biden administration – though the program and transfers have continued under Trump. The president plans to make a major decision in two weeks time – though we doubt peace talks will have progressed much by that point.

Tyler Durden
Sun, 08/24/2025 – 14:35

Transshipment’s Dead End

0
Transshipment’s Dead End

Authored by Jake Scott via the Foundation for Economic Education (FEE),

President Donald Trump’s executive order of July 31st, effective Aug. 7th, has upended global trade dynamics in a single stroke. Slapping a 40 percent tariff on all “transshipped goods”—products rerouted through third countries to dodge U.S. duties—this is merely the natural development of his evolving protectionist agenda.

Just a week after the order, the move is a clear shot at China’s sprawling manufacturing empire, which has long exploited methods like transshipment and “nearshoring” to skirt American tariffs in general, and Trump’s tariff policies in particular.

While applied globally, China stands to take the biggest hit (and likely already is), with its vast factory networks and knack for rerouting goods through Southeast Asia, Mexico, and beyond. This isn’t just a tariff hike; it’s a calculated escalation in Trump’s ongoing crusade to reshape U.S. trade policy and the global economy in the United States’ favor. But ripple effects that bruise consumers are already visible—and this move is likely to strain relationships with key allies as well.

The new tariffs build on Trump’s first-term strategy—so extensive that it now has a Wikipedia entry—when he wielded America’s economic heft like a sledgehammer to renegotiate or smash trade deals he deemed unfair. Back then, Chinese firms sidestepped U.S. tariffs by setting up shop in countries like Vietnam and Mexico, funneling goods through these hubs to mask their origins.

This nearshoring strategy buoyed many economies that had pre-existing arrangements with the United States or were treated more favorably than China, such as Canada and Latin American nations. It is also seen as a natural part of globalization: shipping parts from where they are constructed (like China), assembling them in developing nations (like Mexico), and then exporting to high-value markets (like the United States). Nearshoring has a long history, but the fragility of extended global supply chains was exposed in the Covid pandemic; since then, manufacturers have sought to mitigate their damage.

The U.S. trade deficit with China (roughly $295 billion) has long been a sore point for Trump, who sees transshipment and nearshoring as sneaky workarounds. The 40 percent duty on these goods, layered atop existing tariffs, aims to plug this loophole. As Stephen Olson, a former U.S. trade negotiator, noted in the New York Times, China will likely view this as a direct attempt to “box them in,” potentially souring already tense talks.

As FEE’s readers will know, this isn’t Trump’s first use of tariffs as a stick to beat the horse. Earlier this year, he raised duties on EU goods to 15 percent from the 1.2 percent that preceded his second term, a move that sparked both relief—for averting a threatened 30 percent rate—and criticisms over the increased cost of European imports. This is especially likely to hit Trump’s own voter base, given the prevalence of pharmaceuticals and car imports from the EU.

Now, with this global imposition of transshipment and nearshoring, Trump is doubling down on his economic geopolitical strategy, targeting not just China but any country facilitating indirect shipmentsData from Asia Financial underscores the urgency: China’s exports to the United States plummeted 22 percent in July 2025 compared to last year, but those goods didn’t vanish—they were redirected to ASEAN nations, surging by 17 percent, signaling a pivot to transshipment hubs. Countries like Vietnam have tightened inspections to curb this practice, but the scale of China’s manufacturing makes enforcement a Herculean task.

Broader implications include a risky pivot towards China. Tariffs could accelerate integration via the Belt and Road Initiative, and Regional Comprehensive Economic Partnership, deepening ASEAN-China ties as U.S. access wanes. Beijing’s threatened countermeasures against U.S. deal-makers, in turn, force ASEAN nations to tread carefully and potentially choose between their top export market (America) and largest trading partner (China).

Trump’s order also tweaks other tariffs, ranging from 10 percent to 41 percent, with a hefty 100 percent levy on microchips and pharmaceuticals and a 25 percent tax on goods from nations buying Russian oil—a move that is already disrupting relations with India and pushing the BRICS countries even closer together.

These moves align with Trump’s broader economic geopolitical strategies: shrinking the U.S. trade deficit and bolstering domestic industries. But the cost is steep for American consumers. Higher tariffs may generate revenue for the Treasury in the short term, but they also mean pricier goods in the long term. China’s cost advantage keeps its exports competitive despite duties. Ironically, it’s China’s massive level of onshored manufacturing that Trump is attempting to rebalance. As Richard Baldwin wrote, “[China’s] production exceeds that of the nine next largest manufacturers combined.”

Of course, China may be the primary target of this bludgeoning, but it is not the only nation affected: Vietnam, with a $120 billion U.S. trade surplus, negotiated a cut from 46 percent to 20 percent, a move that attempted to offset its place as a transshipping hub for Chinese exports. Cambodia’s garment sector, employing a million workers, celebrated the tariff slash from 49 percent to 19 percent, but its reliance on Chinese inputs keeps transshipment risks high.

Still, ASEAN markets are complex and multifaceted. Some celebrated the tariffs as “leveling” the trading field. Werachai Lertluckpreecha, a representative of the Thailand-based Stars Microelectronics, praised Trump’s tactics for putting Thailand “on par with Indonesia and the Philippines and lower than Vietnam … we’re happy.”

This tariff gambit echoes broader themes of sovereignty and control—and Trump is usually the last one to blink. His tariffs assert U.S. dominance, forcing trading partners to bend or break, yet the risk of overreach looms. Broader impacts include U.S. consumer price hikes (e.g., shoes up 40 percent, cars projected to cost $5,800 more on average, according to the Tax Foundation), potentially fueling inflation and debt reliance. Markets shrugged somewhat, with minor S&P 500 dips, but volatility looms.

Tyler Durden
Sun, 08/24/2025 – 14:00

Watch: Israel Targets Yemen’s Capital With Massive Strikes Near Presidential Complex, Missile Bases

0
Watch: Israel Targets Yemen’s Capital With Massive Strikes Near Presidential Complex, Missile Bases

Israel’s military conducted airstrikes on Yemen’s Houthi-controlled capital, Sanaa, on Sunday, targeting high-profile sites in a significant escalation of hostilities.

The strikes hit areas near the presidential palace, the Asar and Hizaz power plants, and Houthi facilities suspected of housing artillery, including ballistic missiles, according to regional reports.

The operation was a direct response to recent Houthi attacks on Israel, including projectile launches on Friday, a military source told the Jerusalem Post. While Israel has previously targeted Houthi infrastructure, its strikes have largely focused on the strategic port city of Hodeida, a critical economic and military hub. The shift to Sanaa signals a broader and more aggressive approach to the conflict.

At least two people were killed and five others injured, Al Masirah, a Houthi-affiliated media outlet reported, according to Al Jazeera.

“The attacks were carried out in response to repeated attacks by the Houthi terrorist regime against the state of Israel and its citizens, including the launch of surface-to-surface missiles and unmanned aerial vehicles towards the country’s territory,” the Israeli military said in a statement.

The Houthis, meanwhile, have vowed to continue their campaign in solidarity with Palestinians. “The Israeli aggression against Yemen will not discourage us from continuing our support for Gaza, no matter the sacrifices,” Houthi official Mohammed al-Bukhaiti said in a statement obtained by Al Jazeera.

In March, President Donald Trump launched Operation Rough Rider, a major air and naval campaign targeting Houthi-controlled areas in Yemen to curb their attacks on Red Sea shipping. The strikes, which began on March 15, hit key locations including Sanaa, where at least four airstrikes struck the Eastern Geraf neighborhood of Shouab district and three in the Al-Sawad area; Hodeida, with significant strikes on the Ras Isa oil port. U.S. Central Command reported that the strikes killed hundreds of Houthi fighters, including senior missile and UAV officials, with unofficial estimates ranging from 500 to 600 Houthi terrorists killed. A ceasefire between the U.S. and the Houthis was announced on May 6.

Tyler Durden
Sun, 08/24/2025 – 13:25

Market Valuations Don’t Matter… Until They Do

0
Market Valuations Don’t Matter… Until They Do

Authored by Lance Roberts via RealInvestmentAdvice.com,

One of the hallmarks of very late-stage bull market cycles is the inevitable bashing of long-term market valuation metrics. In the late 90s, if you were buying shares of Berkshire Hathaway, it was mocked as “driving Dad’s old Pontiac.” In 2007, valuation metrics were dismissed because the markets were flush with liquidity, low interest rates, and “Subprime was contained.”

Valuation is the capstone of proximate causes for a market top, and the one most indicative of the potential magnitude of any subsequent selloff. It’s well known that valuations are high for the US market, but I thought I’d update my aggregate indicator, which combines the main measures of long-term stock-market worth. It previously peaked in April, but has just made a new all-time high this month. Not a welcome sign if you’re a long-term bull.” – Simon White, Bloomberg

Of course, just as we have seen so many times, we again see repeated arguments about why “this time is different.” For some, it is the belief that the Fed will bail out markets if something goes wrong. For others, “Artificial Intelligence” and “Cryptocurrencies” are a new paradigm of investment returns. Of course, it is hard to blame investors for feeling this way, given the market’s outsized gains over the last 15 years.

Regardless of the reasoning, there is little argument that current trailing market valuations are elevated.

However, we need to understand two crucial points about valuations.

  1. Market valuations are not a catalyst for mean reversions, and;
  2. They are a terrible market timing tool.

Furthermore, investors often overlook the most essential aspects of valuations.

  1. Valuations are excellent predictors of return on 10 and 20-year periods, and;
  2. They are the fuel for mean-reverting events.

Critics argue that valuations have been high for quite some time, and a market reversion hasn’t occurred. However, to our point above, valuation models are not “market timing indicators.”  The vast majority of analysts assume that if a measure of valuation (P/E, P/S, P/B, etc.) reaches some specific level, it means that:

  1. The market is about to crash, and;
  2. Investors should be in 100% cash.

This is incorrect.

Market valuation measures are just that—a measure of current valuation. Moreover, market valuations are a much better measure of “investor psychology” and a manifestation of the “greater fool theory.” This is why a high correlation exists between one-year trailing valuations and consumer confidence in higher stock prices.

What market valuations express should be obvious. If you “overpay” for something today, the future net return will be lower than if you had paid a discount for it.

Current market valuations are not sustainable. Fundamentals, revenue growth, earnings power, free cash flow, margins, and debt govern valuation over time. This is particularly true when the vast majority of the market generates little to no earnings growth, but growth is only a function of a handful of companies.

Markets eventually will revert toward fundamentals. That process takes time, but it is both inevitable and relentless

Price‑to‑Sales and Market‑Cap‑to‑GDP Send a Warning

The Price‑to‑Sales (P/S) ratio measures how much investors pay for each dollar of a company’s sales. The S&P 500 currently trades around 3.2 times trailing sales. The long‑term average is closer to 1.6 times. For perspective, a P/S ratio above “2″ signals elevated valuations. The market P/S ratio is currently more than 2-standard deviation above its historic average.

The elevated P/S reflects bullish expectations that when you pay over $3 per $1 of sales, you expect future growth to justify it. That means investors expect strong revenue gains ahead. But if growth slows, valuations must adjust downward. In other words, the market is currently “priced for perfection, which leaves a lot of room for disappointment.

Another measure is Market‑Cap‑to‑GDP, known as the Buffett indicator. This measure compares total stock market value to national output. Given that earnings and revenue growth come from economic activity, the market valuation should represent the strength of the overall economy. Currently, that measure of market valuation resides at 217%. Notably, the long‑term average is around 155%. At current levels, valuations are well above what the economy can generate, and two standard deviations above the long-term trend.

That signals broad market overvaluation versus economic size. It suggests prices may be disconnected from the real economy that generates earnings.

Both metrics send a clear message: valuations exceed long‑term norms. That means excess return potential is limited. Downside risk rises if sentiment shifts or fundamentals falter.

These high valuations can be sustained longer than expected if sentiment remains jubilant. But you cannot ignore the math. Expectations already baked into the price are high. Therefore, you must realize that you tolerate a limited margin of safety unless fundamentals outperform.

Valuation Exuberance Increases The Overall Risk Profile

Still, the current level of exuberance is unsurprising given the strongly trending bull market, particularly when Wall Street needs to justify higher valuations. The problem is that such exuberant forecasts rarely come to fruition. For example, in March 2023, S&P Global predicted that 2024 earnings would grow by 13% for the year. In reality, earnings grew by just 9% despite the market rising nearly 28%. In other words, given that actual earnings fell well short of previous estimates, the 2024 market was primarily driven by valuation expansion.

Current earnings projections for 2025 suggest a nearly 20% increase, well above historical growth trends. While such detachments of the market from earnings are not uncommon, they tend not to be sustainable over more extended periods. We suspect that the risk to stocks in 2025 will be a failure of earnings to meet optimistic expectations.

When sentiment and expectations exceed economic realities, there is the potential for stock repricing. As noted, “stocks are priced for perfection,” which means any shortfall could lead to a more substantial decline in price. For instance, the S&P 500’s P/E ratio has reached levels that some analysts consider concerning, reflecting investor optimism that may not align with underlying economic fundamentals.

Given the interdependence between earnings and economic growth, valuations present a more serious challenge. A better way to visualize this data is to look at the correlation between the annual change in earnings growth and inflation-adjusted GDP. There are periods when earnings deviate from underlying economic activity. However, those periods are due to pre- or post-recession earnings fluctuations. Currently, economic and earnings growth are very close to the long-term correlation.

It is worth repeating that valuations are unreliable market-timing tools. Elevated valuations reflect heightened investor optimism and expectations of robust earnings growth in bull markets and can remain that way for extended periods.

However, excess market valuations leave investors vulnerable to unexpected, exogenous events. Those “events,” when they occur, lead to sharp sentiment reversals. What would cause such a sentiment reversal? No one knows. This is why when the “unexpected” happens, Wall Street’s immediate response is to suggest that “no one could have seen that coming.”

As such, investors must continue managing risk into 2025 and navigate the markets accordingly.

Tyler Durden
Sun, 08/24/2025 – 12:50
