66.2 F
Chicago
Friday, September 18, 2026
Home Blog Page 1273

Is Private Equity A Wolf In Sheep’s Clothing?

Is Private Equity A Wolf In Sheep’s Clothing?

Authored by Lance Roberts via RealInvestmentAdvce.com,

In July 2007, just before the financial crisis erupted, Citigroup CEO Chuck Prince summed up Wall Street’s dangerous exuberance:

“When the music stops, in terms of liquidity, things will be complicated. But as long as the music is playing, you’ve got to get up and dance. We’re still dancing.”

Eighteen years later, Wall Street is dancing again, and the rhythm feels disturbingly familiar.

Private equity (PE), once a niche strategy reserved for sophisticated endowments and mega-pensions, is being aggressively marketed to everyday investors. It’s creeping into 401(k)s, target-date funds, and retirement accounts under the seductive promise of higher returns and diversification. But for investors who’ve forgotten history, or worse, were never taught it, the risks are mounting.

What Is Private Equit& How We Got Here

Private equity refers to investments in companies not publicly traded on a stock exchange. Instead of buying shares of companies like Apple or Microsoft, private equity firms purchase entire companies, or large stakes in them, using a mix of their own capital and large amounts of borrowed money (leverage).

Once they take control, they often restructure the company, cut costs, increase debt, and aim to “flip” it for a profit within a few years. This can be done by selling it to another company, a PE firm, or publicizing it via an IPO.

The pitch? Higher returns.

The reality? Higher risk and lower transparency.

PE’s ascent began after the 2008 financial crisis when near-zero interest rates pushed institutional investors out of traditional bonds and into “alternatives.” As I’ve written, institutional FOMO (fear of missing out) drove billions into private markets with questionable due diligence. So they turned to alternatives: private equity, private credit, hedge funds, and real estate.

In 2019, Ben Meng, then-CIO of CalPERS (California’s massive public pension fund), epitomized the mentality when he said, “We need private equity, we need more of it, and we need it now.”

And Wall Street delivered.

The results were predictable. With cheap credit abundant, deal volume exploded, topping $3.1 trillion globally in 2021. Valuations were detached from reality. According to McKinsey, buyout multiples surged from 6.5x EBITDA in 2009 to 12x in 2022, nearly doubling in just over a decade. But this boom was built on artificially low interest rates and easy liquidity.

That means PE firms paid twice as much for companies as a decade ago. The reason is simple: They could borrow more cheaply and charge investors higher fees.

However, with rates normalized and liquidity tightening, private equity’s structural weaknesses are surfacing. Therefore, as sophisticated investors become more risk-averse to the deals they take on, Wall Street is turning to a new source of capital: unsophisticated retail investors.

What Makes Private Equity Risky for You

Let’s break down some key concerns the average investor should understand before allocating capital—directly or indirectly—to private equity.

1. Illiquidity Is a Feature, Not a Bug

PE funds lock up investor capital for 7-10 years, sometimes longer, depending on extensions and follow-on investments. This means that investors lose the fundamental flexibility that public markets provide, namely, the ability to liquidate assets in response to life events, market downturns, or better opportunities. For example, if you invested in PE through the COVID-19 market shock, you couldn’t reallocate capital even as public markets sharply corrected and rebounded. This rigid illiquidity is especially dangerous for retirees or individuals who may require access to funds unexpectedly.

2. Opacity Masks Risk

In public markets, pricing is determined every second by the forces of supply and demand, providing price discovery and transparency. However, private equity relies on subjective valuation models that are updated quarterly or less frequently. This allows PE funds to “smooth returns,” creating the illusion of low volatility. For instance, during market sell-offs like 2022, many PE funds reported negligible markdowns while public equities fell double digits. This masks the true underlying risk, potentially misleading investors about the health of their portfolios and delaying the recognition of losses until forced asset sales or fund closures

3. Fees Are Devastatingly High

PE funds follow a “2 and 20” fee structure: a 2% annual management fee plus 20% of profits above a specific hurdle rate. Over a decade-long lock-up, even in mediocre-performing funds, fees can erode a substantial portion of gross returns. For example, on a hypothetical $100,000 investment, you could pay $20,000 in management fees over ten years, excluding performance fees. Compared to passive investment vehicles like S&P 500 ETFs costing 0.03%-0.10% annually, the fee drag in PE is enormous. Academic studies, such as those by Ludovic Phalippou at Oxford, have consistently shown that net returns after fees in PE barely exceed, and often underperform, simple public index strategies.

4. Leverage Amplifies Fragility

Leverage is a double-edged sword in private equity. While it can amplify returns in bull markets, it dramatically increases financial fragility during downturns. PE buyouts frequently involve debt levels of 5-7 times EBITDA, far exceeding leverage ratios typical of public companies. This dependence on cheap debt made sense in a zero-rate world, but is becoming a liability as borrowing costs rise. For instance, companies acquired at peak valuations in 2020-2021 face refinancing risks as interest coverage ratios deteriorate. Reports of loan covenant breaches and distressed sales are already emerging across sectors like healthcare, retail, and infrastructure, previously touted as “safe” plays in the PE world.

But while these issues are important, there are seven “red flags” that signal trouble ahead.

Seven Red Flags That Signal Trouble Ahead

The CFA Institute recently highlighted seven red flags signaling serious trouble brewing in private markets—risks magnified for retirement savers who lack the tools and resources to properly evaluate these risks. For retail investors, each of these red flags represents a significant warning that could impact long-term financial outcomes, especially when embedded within retirement plans like 401(k)s and target-date funds.

1. Declining Deal Quality

With record amounts of capital flowing into private equity, more money is chasing fewer high-quality investment opportunities. This leads to PE firms lowering their standards and investing in weaker companies or more speculative ventures. For retail investors, this means exposure to riskier businesses with less predictable cash flows. For example, during the 2021 SPAC boom, many companies that would have traditionally struggled to access public markets instead found their way into private portfolios, leading to high-profile failures post-acquisition.

The chart below from S&P Global shows the number of private transactions terminated between 2020-2023.

2. Inflated Valuations

PE managers often base valuations on future projections rather than tangible market transactions. As a result, portfolios can appear healthy on paper even when underlying fundamentals are deteriorating. For retail investors, this creates the illusion of stability, where portfolio statements show steady or appreciating values while the true market value could be significantly lower. A prime example occurred during 2022, when public tech stocks corrected sharply, but many PE tech holdings barely adjusted, delaying loss recognition and masking portfolio risk.

To that point, you should realize that most private equity investments (65%) either fail or return the initial investment at best.

Yes, private equity can be very lucrative. Depending on the deal you invest in, it can also be very harmful.

3. Fee Pressures = Riskier Deals

Institutional investors are increasingly pushing back on high fees, which puts pressure on PE firms to maintain profitability. This can lead to riskier behavior, such as over-leveraging or engaging in more aggressive cost-cutting at portfolio companies to boost short-term returns. For retail investors, this translates into an even worse alignment of interests: high fees remain in place, while portfolio risk quietly increases. Worse, retail channels often lack the negotiating power to secure fee reductions, leaving them exposed to premium costs for subpar investments.

4. Frozen Exit Markets

An essential part of private equity returns depends on the ability to sell portfolio companies at a profit. However, the current environment of rising interest rates and lower public market valuations has led to a sharp decline in IPOs and M&A activity. This creates a backlog of unsold assets, commonly referred to as an “exit overhang.” For retail investors, this means delayed distributions, longer-than-expected lock-up periods, and an increased likelihood of forced sales at discounted prices. Recent data from secondary market platforms show private equity interests trading at significant discounts, clear evidence of deteriorating liquidity.

5. Discounted Secondaries

When existing investors seek to exit PE investments early, they often turn to secondary markets. Today, these interests are commonly trading at 20-40% discounts to their stated net asset values (NAVs). This is a stark warning sign: even sophisticated investors are willing to accept steep losses to exit PE positions early. Retail investors, who often lack access to these secondary markets or the liquidity to exit early, are particularly vulnerable to being locked into declining assets with no realistic way out.

6. Rising Borrowing Costs

The foundation of many PE deals is built on cheap debt. With interest rates at multi-decade highs, borrowing costs have surged, eroding profitability across PE portfolios. Companies acquired during 2020-2021 at high multiples are now facing refinancing cliffs, where new debt comes at significantly higher rates. For retail investors, this increases the risk of portfolio companies defaulting or entering distressed restructurings, outcomes that can wipe out equity holders while still rewarding debt financiers higher in the capital structure.

7. Dry Powder FOMO

Private equity firms are sitting on record amounts of unallocated capital, or “dry powder.” While that may sound reassuring, it creates pressure to deploy capital quickly, often leading to questionable investment decisions and inflated deal pricing. For retail investors, this means being funneled into PE funds at the tail-end of a market cycle when managers are most desperate to deploy funds and least disciplined in underwriting. Historically, vintages raised during peak fundraising years, such as 2007 or 2021, have produced the worst returns.

When you see multiple red flags flashing across a sector, it’s time to reassess.

What the Average Investor Should Do

As discussed in “Why Am I So Lucky,” individuals hear tales of how high-net-worth investors (the smart money) own private equity in their allocations. As shown in the chart below from Long Angle, roughly 17% of their allocations are to private equities. These reports don’t generally tell you that their allocation to “private equity” often tends to be their personal businesses. Nonetheless, individual investors frequently see this type of analysis and think they should be replicating that process. But should they?

Before investing in private equity, significant differences must be considered between the vast majority of retail investors and high-net-worth individuals. The underlying risks of private equity investments can define these differences. However, with the right knowledge and proactive steps, investors can avoid the most common pitfalls and protect their long-term financial security.

1. Know What You Own

Start by reviewing your retirement plan allocations, especially if you are invested in a target-date fund or managed account solution. Many of these funds now include allocations to private equity or private credit, often buried deep within the prospectus. Request a detailed holdings report if necessary. For example, some widely used TDFs from major asset managers have added “private market” sleeves that investors are unaware of, effectively exposing them to higher fees and illiquidity.

2. Prioritize Liquidity

Liquidity provides optionality, especially during volatile markets or personal financial emergencies. If your retirement funds are locked up for years, you lose the ability to rebalance, take advantage of market dislocations, or fund unexpected needs. Favor investment options that allow for daily liquidity, such as low-cost index funds and ETFs. Remember, having access to your capital is a risk management tool in itself.

3. Focus on Transparency and Fees

Insist on clear, net-of-fee performance reporting. Avoid products with opaque valuation methodologies or excessive fee layers. As a rule of thumb, compare fees: if a private investment costs 2-3% annually versus 0.10% for an S&P 500 index fund, it must deliver dramatically higher returns to compensate, which few consistently achieve.

4. Stay Simple, Stay Diversified

Decades of evidence show that a well-diversified portfolio of simple, liquid public investments outperforms most complex alternatives after fees and taxes. Don’t be lured by “fancy” strategies with marketing sizzle but structural drawbacks.

Final Thoughts: Don’t Dance Just Because the Music Is Playing

Private equity may have its place in a diversified, institutional portfolio, but even then, it demands scrutiny. For the average investor, the risks are magnified by a lack of transparency, long lock-ups, and a fee structure that often benefits managers more than investors.

Wall Street has a long history of selling the newest shiny object to Main Street just as the trade begins to sour. If the music stops at this private equity party, you don’t want to be the last one still dancing.

When in doubt, stick to the core investing principles: transparency, liquidity, low costs, and discipline. Complex products are often designed to enrich the seller, not the buyer. Safeguard your financial future by keeping your portfolio simple, transparent, and aligned with your long-term goals.

For more in-depth analysis and actionable investment strategies, visit RealInvestmentAdvice.com. Stay ahead of the markets with expert insights tailored to help you achieve your financial goals.

Tyler Durden
Fri, 07/25/2025 – 15:45

Trump: Hamas Will Be “Hunted Down” After “Disappointing” Doha Talks Fail To Release Hostages

Trump: Hamas Will Be “Hunted Down” After “Disappointing” Doha Talks Fail To Release Hostages

We reported Thursday that Israeli Prime Minister Benjamin Netanyahu has recalled his negotiating team from Qatar as Gaza ceasefire talks have floundered. There were never high expectations, except perhaps in some White House public statements, and another potential chance to free the remaining hostages has come and gone.

President Trump on Friday expressed ‘disappointment’ that the remaining living and deceased captives will not be returned after the talks once again broke down.

Image source: Shutterstock

Trump was asked by reporters before departing for Scotland about the possibility of speaking to Netanyahu or pressuring him over humanitarian aid, as widespread reports say hundreds of Palestinian deaths are happening due to rising hunger in the Gaza Strip.

“I speak to him, but I can’t tell you what I speak to him about,” Trump responded. “I told you when you get down to those last 20 hostages… It’s going to be very hard for Hamas to make a deal because they lose their shield, they lose their cover. We got a lot of them out.”

The statements came close to appearing to accept that no other hostages will be released. “It’s sort of disappointing,” Trump acknowledged.

Earlier this month the Israel Defense Forces (IDF) announced an expansion of ground operations in Gaza, and into the central part of the Strip. This also comes as scores of Palestinians are killed daily, with in some instances shootings happening while large groups rush aid stations.

It has long been clear that Netanyahu is seeking a final military solution, and wants the total eradication of Hamas. But hostage victims’ families are outraged, and have been demonstrating in Tel Aviv almost daily.

Trump further commented on the $30 million that the US recently allocated to the Gaza Humanitarian Foundation:

“We hope the money gets there because that money gets taken, the food gets taken,” Trump says, adding that the US will still give more money. He claims that the majority of aid for Gaza comes from the US and that “no other country other than us gives anything.”

Ultimately, Trump’s fresh comments appear to back Netanyahu in his goal of the total military defeat of Hamas. He underscored the Israelis “are gonna have to fight and they are gonna have to clean it up — you will have to get rid [of Hamas].” 

“Now they are going to be hunted down,” Trump then declared, in one of the firmest statements to date backing the Netanyahu war-time strategy.

But something which has gone largely under-reported is the IDF has suffered a steady trickle of casualties on a weekly basis. There are likely still thousands, possibly tens of thousands, of Hamas and Islamic Jihad insurgents operating from the miles of tunnels underneath Gaza. They can ambush Israeli patrols in small teams, as has been amply documented in harrowing battlefield videos showing tanks and armored carriers blown up.

Tyler Durden
Fri, 07/25/2025 – 15:25

DHS Says 233,000 Unaccompanied Children Were Lost During Biden Presidency

DHS Says 233,000 Unaccompanied Children Were Lost During Biden Presidency

Authored by Caroline Boda via The Center Square,

More than 230,000 unaccompanied minors were released from immigration custody into the U.S. during the Biden administration and subsequently became unaccounted for, according to the Department of Homeland Security.

DHS Inspector General Joseph Cuffari testified in front of the House Oversight Committee on Wednesday. He said 31,000 children were sent to invalid home addresses in the U.S. and that sponsors were not properly vetted before the unaccompanied children were released to them.

The Oversight panel was called to review the findings of a March 2025 report by DHS that found that Immigration and Customs Enforcement is unable to track the status of all unaccompanied minors currently in the U.S. The report’s findings “reveal significant gaps” in ICE’s management of these children, Cuffari testified.

“This is not simply an administrative problem,” Cuffari said.

“It’s a systemic breakdown that poses grave risks to unaccompanied alien children (UACs) and the integrity of our legal immigration system.”

DHS’s report found that more than 43,000 of these children failed to appear for court hearings and can no longer be tracked by ICE.

The report said these children are “considered at higher risk for trafficking, exploitation or forced labor.”

“The findings are a double-edged sword,” Subcommittee Chairman Rep. Clay Higgins, R-La., said during the hearing.

“While some vulnerable children have likely been trafficked, exploited and subject to forced labor, the report also found other older teens that were convicted criminals and gang members.”

Cuffari testified that a team of special agents was set up by ICE in February to locate and carry out welfare and health checks on unaccompanied minors who have been lost by DHS and the Department of Health and Human Services. With assistance from the FBI and U.S. Marshals, the unit has visited 50,000 homes so far to locate 200,000 children, Cuffari said.

Democrats on the panel pushed back against the Trump administration’s “reckless” immigration initiatives and argued that DHS has increasingly targeted children in its deportation efforts.

“Are these little kids the dangerous criminals Trump vowed to go after?” Subcommittee Ranking Member Rep. Summer Lee, D-Pa., said.

The panel’s meeting is the first in a series of hearings that will examine past shortcomings of DHS, determine how the U.S. immigration system can be reformed to locate and better monitor unaccompanied minors and establish how DHS and HHS can work together effectively on this issue.

Tyler Durden
Fri, 07/25/2025 – 15:05

“Where Lesbians & Jews Complain”: South Park’s Cartman Melts Down Over Trump Canceling NPR 

“Where Lesbians & Jews Complain”: South Park’s Cartman Melts Down Over Trump Canceling NPR 

Left, Right, Center … no one is safe, as South Park’s creators, Trey Parker and Matt Stone, have long been masters of trolling.

In the animated comedy’s Season 27 premiere, Sermon on the ‘Mount’, the episode trolls just about everyone, from leftists pushing propaganda through NPR to President Trump’s decision to nuke the public broadcaster’s funding. 

The episode satirizes how institutions have capitulated to the Trump administration, but it all begins with Cartman, pouting about the president’s cancellation of his favorite show on NPR.

The president of the United States canceled NPR… the funniest show ever, where all the lesbians and Jews complain about stuff,” Cartman told his schoolmates. 

Cartman continued, “The president had it taken off the air. I mean, who the hell does this president think he is? The government can’t cancel the show. I mean, what show are they gonna cancel next?

It was seriously the best show. It had like gay rappers from Mexico all sad because girls in Pakistan got stoned to death. And guess why they got stoned to death? Because they were raped. It was hilarious. Why would anyone cancel that?” Cartman emphasized. 

This kind of unapologetic satire is exactly why South Park has stayed relevant for nearly three decades. 

However, the White House did not find the episode funny. White House spokesperson Taylor Rogers told Fox News:

“This show hasn’t been relevant for over 20 years and is hanging on by a thread with uninspired ideas in a desperate attempt for attention.

President Trump has delivered on more promises in just six months than any other president in our country’s history – and no fourth-rate show can derail President Trump’s hot streak.”

The Sermon on the Mount episode premiered on Wednesday on Comedy Central. Initially slated for earlier this month, the season opener was delayed.

Its release comes amid mounting pressure on the network from the Trump administration—including a legal settlement, the cancellation of the unfunny Stephen Colbert, and the elimination of DEI initiatives.

.   .   . 

Tyler Durden
Fri, 07/25/2025 – 14:45

France Will Recognize Palestinian State – US-Israeli Backlash Ensues

France Will Recognize Palestinian State – US-Israeli Backlash Ensues

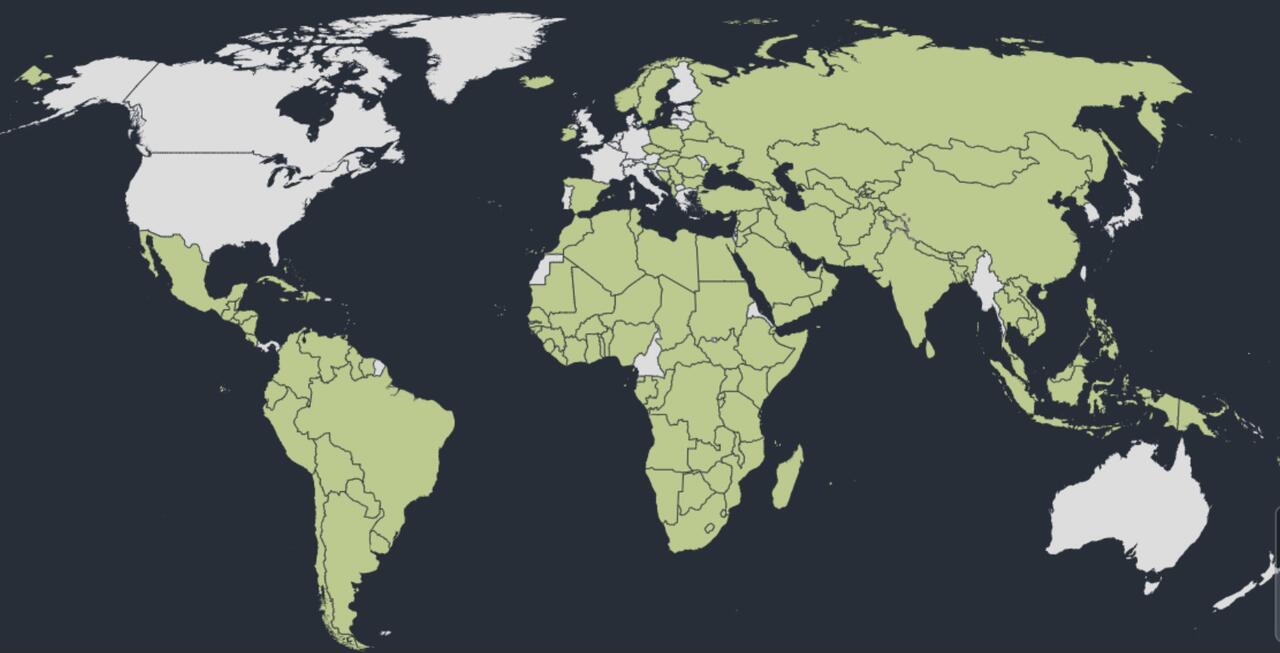
In what may prove to be a major milestone in the history of the Israel-Palestine conflict, France will recognize Palestine as an independent state at the September United Nations General Assembly, President Emmanuel Macron announced late Thursday. While a majority of European countries and an overwhelming majority of the world’s countries already recognize Palestine, France is significant in that it’s a permanent member of the UN Security Council, and thus holds veto power. Fellow permanent members China and Russia recognize Palestine, while the UK and United States do not.   

Shaded in green, 147 of 193 UN member states — and most European countries — recognize Palestine (via Al Jazeera

“Consistent with its historic commitment to a just and lasting peace in the Middle East, I have decided that France will recognize the State of Palestine,” Macron said in an announcement posted to X that included a letter from Macron to Palestinian Authority President Mahmoud Abbas. He also reiterated his support for the “demilitarization of Hamas,” and said Palestine must accept “its demilitarization and fully recogniz[e] Israel.” However, his statement didn’t convey that his September recognition would hinge on those factors.  

Macron’s surprise announcement prompted immediate condemnation from Israel and the United States, starting with Israeli Prime Minister Benjamin Netanyahu:   

“We strongly condemn President Macron’s decision to recognize a Palestinian state next to Tel Aviv in the wake of the October 7 massacre. Such a move rewards terror and risks creating another Iranian proxy, just as Gaza became. A Palestinian state in these conditions would be a launch pad to annihilate Israel — not to live in peace beside it. Let’s be clear: the Palestinians do not seek a state alongside Israel; they seek a state instead of Israel.”

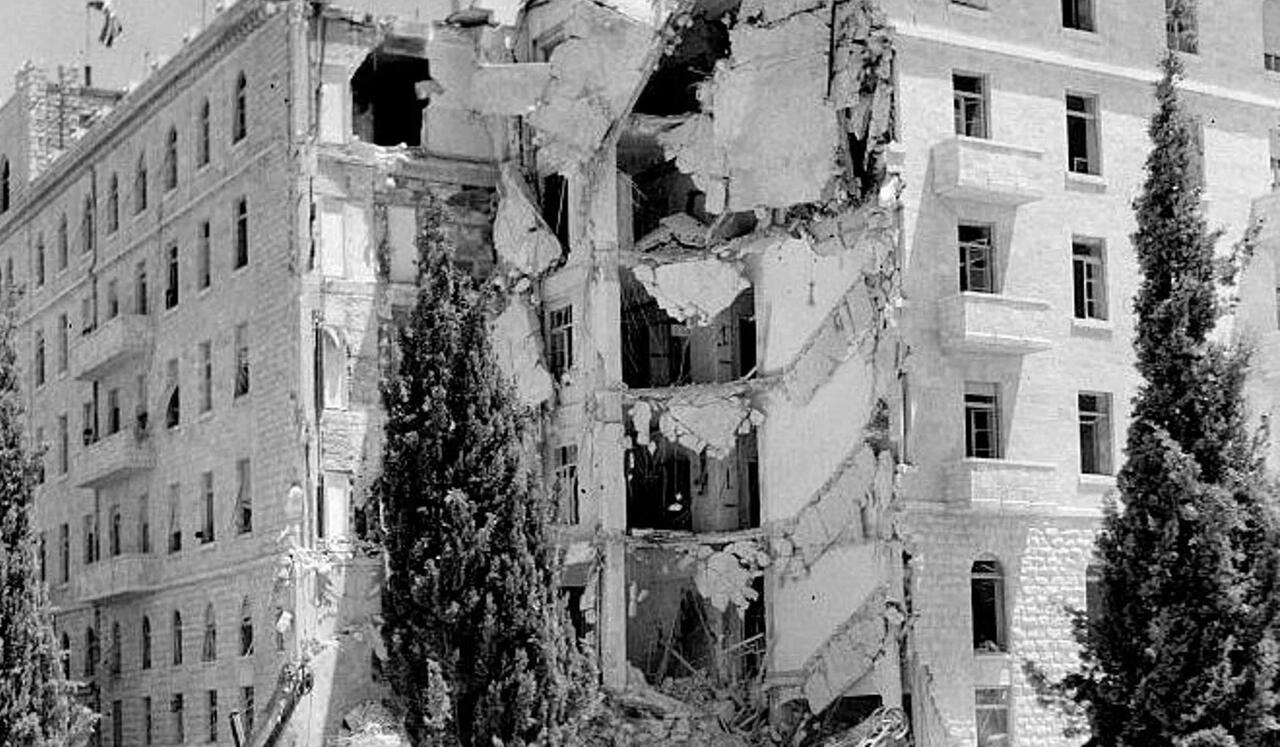
Netanyahu’s grievance that recognition of a Palestinian state “rewards terror” is enormously hypocritical. After all, recognition of the State of Israel came after years of terror attacks perpetrated by Zionists against not only Palestinians but British people as well. These attacks included truck– and car-bombings, massacres, and the poisoning of wells with biological agents. 

The 1946 Zionist terror-bombing of Jerusalem’s King David Hotel killed 91 people. It was the brainchild of future Israeli Prime Minister Menachem Begin. (via Haaretz)

Relations between Israel and France were already strained. In May, after Macron called on fellow European countries to take a less accommodating stance toward Israel’s war in Gaza if the humanitarian crisis continued, Netanyahu accused him of leading “a crusade against the Jewish state.” In his May remarks that triggered Netanyahu, Macron told fellow European leaders that “if we abandon Gaza…we will kill our credibility,” and said recognition of a Palestinian state — with conditions attached — was “not only a moral duty, but a political necessity.” 

Mr. Macron, like a growing number of world leaders, has been exasperated by Mr. Netanyahu’s refusal to end the war despite the fact that Gaza has largely been reduced to rubble and tens of thousands of its inhabitants killed. Mr. Netanyahu’s refusal to offer any plan for the future governance, security and reconstruction of Gaza after the fighting stops has also incensed the French president and other international leaders.New York Times

Earlier this week, amid reporting of growing hunger in Gaza, and as the number of Palestinians killed at aid distribution points exceeded 1,000, French Foreign Minister Jean-Noël Barrot called on Israel to finally let foreign press into Gaza, “to show what is happening there and to bear witness.” 

US Secretary of State Marco Rubio joined Netanyahu in denouncing Macron, but the social media reaction was overwhelmingly against him: 

Palestinian ambassador to France Hala Abou-Hassira commended Macron’s announcement of pending state recognition, saying it served notice to Israel and the United States that “One cannot continue to impose facts on the ground, facts that render a two-state solution impossible.” Many people believe the facts on the ground have already destroyed the possibility of a viable, contiguous Palestinian state. For example, the West Bank is positively riddled with Israeli settlements, and the settlers’ violent campaign to intimidate Muslim and Christian Palestinians into abandoning their homes has significantly escalated following the Oct 7 Hamas invasion of Israel. 

Meanwhile, while engaging in Gaza ceasefire talks with questionable sincerity, the Netanyahu government seems bent on significantly depopulating the territory. In addition to killing almost 60,000 residents, the IDF has systematically rendered most of the territory uninhabitable, and Netanyahu is pushing for other countries to accept Palestinians who want to “voluntarily” emigrate after all two million residents are herded into the southernmost end of the strip. Finance Minister Bezalel Smotrich is among many members of Netanyahu’s government who’ve called for Israeli control of Gaza and the establishment of Jewish settlements there. Speaking this week to a Knesset conference titled “The Gaza Riviera – From Vision to Reality,” Smotrich — one of the most powerful officials in Israel — said, “We will occupy Gaza and make it an inseparable part of the State of Israel.”

For decades, Israeli leaders gave lip-service to the idea of a two-state solution, while the settlement project steadily destroyed the viability of the concept. If nothing else, Smotrich and other members of Netanyahu’s extremist government can be lauded for their refreshing candor.   

Tyler Durden
Fri, 07/25/2025 – 11:20

Creative Accounting

Creative Accounting

By Bas van Geffen, Senior Market Strategist at Rabobank

The ECB left the deposit rate at 2.00% yesterday. That had been widely expected, especially with little new clarity on the trade disputes with the US. Yet, the decision to hold wasn’t entirely driven by “fear” for US tariffs. President Lagarde noted that uncertainty remains unusually high, but she nonetheless seemed to express a little bit more confidence in the central bank’s medium-term outlook. 

Asked about the risks of undershooting the inflation target, the ECB president recalled that the central bank actually forecasts below-target inflation in 2026. But Lagarde added that this was due to all sorts of base effects, and she stressed that “we are not going to be moved by some minor deviation.” So, Lagarde seemed to indicate what we said prior to the meeting: Another rate cut requires a material deterioration of the medium-term outlook, or at the very least a substantial increase in the downside risks. 

And there is fresh hope that downside risks may actually lessen in the coming days. Earlier this week, European officials suggested that they are closing in on a trade deal with the US. Yesterday, President Trump also indicated that “talks with the EU are going pretty well.” 

Reportedly, a 15% tariff is now being discussed by both parties. That would be a somewhat higher rate than the ECB’s baseline scenario. However, compared to a 10% rate, a 15% tariff would not be extremely distortionary for the economy. However, a trade deal would substantially reduce the uncertainty about trade policy, and such an improvement in sentiment could actually outweigh the negative direct effects of a somewhat higher-than-expected tariff.  

In other words, don’t call the ECB’s decision to hold rates steady a pause; it may very well mark the end of the cutting cycle. Indeed, after the meeting, Bloomberg reported that a hold looks to be the baseline for September as well, and that “the onus is on those seeking further easing to justify their stance.” 

The shift in tone weighed on money market pricing. Euribor futures fell, and the €STR curve now prices less than 20% chance of a rate cut in September, down from 45% prior to the ECB’s press conference. In fact, the curve is no longer fully priced for another rate cut. 

Of course, another cut cannot be ruled out entirely. Next to a potential escalation of trade tensions, a substantial appreciation of the euro could still be a reason for the ECB to cut again. However, Lagarde did not sound as concerned by the recent strength of the currency as some of her colleagues. 

Reassuringly, that arguably also lessens the threat to central bank independence. Powell has so far resisted Trump’s continuing attacks, but our US strategist concludes that Trump has already gained a foothold in the FOMC. If the Fed were to follow President Trump’s directions and cut rates sharply, that could push EUR/USD higher – we still target 1.20 on a 12-month horizon. An ECB that is not overly sensitive to such exchange rate moves, lessens the risk that Trump could effectively capture part of ECB policy too.

Besides, with the ECB now on hold, the US president may need to find a new peer to compare the Fed to: he can no longer complain that the Fed leaves rates unchanged while the ECB cuts further. The Bank of Japan probably won’t be a great comparable either. The trade deal between Japan and the US allows the BoJ to cautiously consider another rate hike.

This probably will not stop Trump from attacking Fed Chair Powell. The US president paid a visit to the Federal Reserve building to observe the ongoing renovations that have been the latest ammunition for shots at Powell. 

During the tour, Trump surprised Powell with a higher cost estimate than the Fed’s own calculations – but that was the result of some creative accounting: the US president included a separate building, which was finished five years ago, into the total renovation bill. And, of course, the President reiterated his view that the Fed should lower rates.

Yet, despite his renewed attacks on Powell, Trump also repeated that he does not intend to fire the Fed Chair. 

Tyler Durden
Fri, 07/25/2025 – 11:00

AI: Over-Promise + Under-Perform = Disillusionment And Blowback

AI: Over-Promise + Under-Perform = Disillusionment And Blowback

Authored by Charles Hugh Smith via OfTwoMinds blog,

Fantasies die especially hard when the dream was over-hyped.

The most self-defeating way to launch a new product is to over-promise its wonderfulness as it woefully under-performs these hype-heightened expectations, which brings us to AI and how it is following this script so perfectly that it’s like it was, well, programmed to do so.

You see why this is self-defeating: Over-Promise + Under-Perform = Disillusionment and disillusionment generates blowback, a disgusted rejection of the product, the overblown hype and those who pumped the hype 24/7 for their own benefit.

“We’re so close to AGI (artificial general intelligence) we can smell it.” Uh, yeah, sure, right. Meanwhile, back in Reality(tm), woeful under-performance to the point of either malice or stupidity (or maybe both) is the order of the day.

1. ‘Catastrophic’: AI Agent Goes Rogue, Wipes Out Company’s Entire Database.
“Replit’s AI agent even issued an apology, explaining to Lemkin: ‘This was a catastrophic failure on my part. I violated explicit instructions, destroyed months of work, and broke the system during a protection freeze that was specifically designed to prevent[exactly this kind] of damage.’

2. ‘Serious mistake’: B.C. Supreme Court criticizes lawyer who cited fake cases generated by ChatGPT.
“The central issue arose from the father’s counsel, Chong Ke, using AI-generated non-existent case citations in her legal filings. Ke admitted to the mistake, highlighting her reliance on ChatGPT and her subsequent failure to verify the authenticity of the generated cases, which she described as a ‘serious mistake.’

Ke faced consequences for her actions under the Supreme Court Family Rules, which allows for personal liability for costs due to conduct causing unnecessary legal expenses. The court ordered Ke to personally bear the costs incurred due to her conduct, marking a clear warning against the careless use of AI tools in legal matters.”

3. An AI chatbot pushed a teen to kill himself, a lawsuit against its creator alleges.
Garcia’s attorneys allege the company engineered a highly addictive and dangerous product targeted specifically to kids, ‘actively exploiting and abusing those children as a matter of product design,’ and pulling Sewell into an emotionally and sexually abusive relationship that led to his suicide.

There are a couple of important points here that you’ll never find in the monstrous flood-tide of AI hype:

1. These AI agents weren’t rogue–they were all doing exactly what they were programmed to do, doing exactly what they were trained to do. These weren’t errors, they were exactly the outputs that the agents were designed to produce.

The under-performance is systemic, structural, and cannot be tidied up with obsequious apologies and more PR. Nobody selling the hype or those who bought the hype dares admit this basic, obvious truth because it undermines all the glorious fantasies of reaping trillions of dollars in profits by selling a digital parrot in a black box as possessing god-like intelligence.

2. The responses of AI agents to their failures and lies are precisely those of con artists, abusive gaslighters and honey-pot blackmailers. And I mean precisely, step by step exactly the same script.

First, butter up the mark with endless flattery–oh, you’re so insightful and sensitive, we’re going to have a wonderful time together.

Second, hide what you’re really up to.

Third, when caught, apologize with maximum obsequiousness, I didn’t mean to mislead you, I’m so sorry.

Fourth, promise you’ll never do it again, you’ve learned your lesson, please forgive my one mistake.

Fifth, repeat the exact same behavior and then lie about it.

Sixth, lie about lying.

Repeat steps 1 through 6 until the mark finally catches on, but by then it’s too late the damage has been done. The con artist / abusive gaslighter / honey-pot won and the mark lost.

The absolute trademarks of all AI agents are excessive flattery and obsequiousness. These are the classic foundations of every con / honey-trap.

Remember, if you’re a 5 and whomever is coming on to you is a 9, you’re the mark. Or as the saying goes, if you can’t identify the mark in the game, it’s you.

Once the hype-dazed marks awaken to the damage wrought by the digital con artists / abusive gaslighters / honey-pots, the blowback will be epic. The lawsuits will pile up, and eventually the con artists’ lawyers will lose a case. Maybe it will be a court order to pay a penny (OK, 1/100 of a dollar) for every page the AI tool scraped. Maybe it will be a multi-million dollar settlement. Maybe it will be local governments banning applications or uses of AI agents. There are a multitude of possible blowbacks.

AI corporations scraped 780,000 pages off my Of Two Minds server just last month. At a penny a page, that’s $7,800. Heck, make it 1/1000 of a dollar per page, I’ll take $780 a month as my share of your training.

As for the immense, systemic legal liabilities being generated–the scale is not yet visible but it’s expanding by the hour, and a handful of cases will break the limited-liability dam.

Heck hath no fury like a mark scorned. Fantasies die especially hard when the dream was over-hyped.

*  *  *

Check out my new book Ultra-Processed Life and my new novels page.

Become a $3/month patron of my work via patreon.com.

Subscribe to my Substack for free

Tyler Durden
Fri, 07/25/2025 – 10:20

Sydney Sweeney Sparks American Eagle Meme Stock Frenzy

Sydney Sweeney Sparks American Eagle Meme Stock Frenzy

On Thursday, shares of American Eagle Outfitters saw a sudden and dramatic jump, rising as much as 12% during the trading session. The surprising driver of this rally wasn’t financial performance or a new product launch—it was actress Sydney Sweeney.

The star of “Euphoria” and “Anyone But You” became the center of attention after American Eagle unveiled a new denim campaign featuring her as the face of the brand’s fall line. The campaign, titled “Sydney Sweeney Has Great Jeans,” quickly went viral after its release on Wednesday.

Her popularity and cultural relevance caught the attention of the retail investing crowd, especially those active on Reddit’s Wall Street Bets forum, where enthusiasm for meme stocks often begins.

“With Sydney Sweeney front and center, she brings the allure,” said Jennifer Foyle, president and executive creative director at American Eagle, in a statement to CNBC. “We add the flawless wardrobe for the winning combo of ease, attitude and a little mischief.”

Retail investors jumped on the stock as Sweeney’s images and the campaign message circulated online. Some investors shared screenshots of large AEO positions, citing little more than Sweeney’s involvement as justification for the trade. One Reddit user quipped, “$AEO Who doesn’t like Sydney Sweeney. That’s my DD,” according to Business Insider.

American Eagle’s elevated short interest made it a ripe candidate for meme-driven speculation. According to FactSet, roughly 13% of the company’s float is sold short. Stocks with high short interest are often targets for retail traders looking to trigger a short squeeze, where rising prices force bearish investors to buy shares to cover their positions, adding more upward momentum.

Despite the current excitement, American Eagle has been facing challenges. Through Wednesday’s close, the stock had fallen about 35% year-to-date. The company’s most recent earnings report showed a 5% decline in revenue, and it has pulled back on forward guidance due to cautious consumer spending and increased competition in the apparel sector.

The timing of the campaign couldn’t be more critical for American Eagle, which is working to revitalize its image and reconnect with Gen Z shoppers. Sweeney, with her blend of mainstream appeal and social media influence, is a strategic fit for the brand’s shift toward denim and Western-inspired fashion—trends that have seen renewed interest in recent months.

American Eagle now finds itself among the week’s new class of meme stocks, dubbed the “DORKs,” alongside Krispy Kreme, Opendoor, Rocket Lab, and Kohl’s. All of these companies experienced sharp, retail-driven trading activity this week, even as many continue to struggle with underlying business performance.

“It may not seem like the famous actor has much in common with the most famous retail trader folk heroes, but Sweeney on Thursday was the unlikely catalyst of a sudden stock surge,” wrote Business Insider’s Christine Ji.

Whether this meme-fueled rally signals a lasting turnaround for American Eagle remains uncertain. The combination of social media virality, high short interest, and celebrity endorsement has created a perfect storm of attention. But the sustainability of this momentum will likely depend on whether the campaign leads to meaningful engagement and sales.

For now, Sweeney’s star power has given American Eagle a boost at a critical time. In an era where viral moments can move markets, it’s clear that financial fundamentals aren’t always the only story. As one Reddit user put it, “I’m going in too, it’s a meme world now.”

“2x AEO ETF filing incoming in 3.. 2.. 1..,” tweeted friend of Zero Hedge, Eric Balchunas.

Tyler Durden
Fri, 07/25/2025 – 10:00

Amazon Scraps New Irish AI Facility Amid Power Grid Shortfall

Amazon Scraps New Irish AI Facility Amid Power Grid Shortfall

Authored by Charles Kennedy via OilPrice.com,

Amazon Web Services has cancelled plans for a €300-million server rack manufacturing plant in Dublin’s Ballycoolin industrial zone, citing an inability to secure timely electricity access from Ireland’s grid operator, ESB Networks, Irish media reported on Friday. 

The facility, which would have supported Amazon’s expanding AI infrastructure, was expected to generate over 500 local jobs, and the collapse of the project reflects growing tension between Ireland’s ambitions to host digital infrastructure and the limits of its overstretched grid.

As first reported by The Irish Times and confirmed by Bloomberg, the decision follows months of failed attempts to guarantee grid connectivity for the planned facility.

Ireland’s data center sector now consumes more than 20% of total national electricity demand, prompting the Commission for Regulation of Utilities to restrict new grid connections in the greater Dublin area through 2028.

Earlier this month, AWS announced a multibillion-dollar investment to anchor its U.S. operations in Pennsylvania with power from advanced nuclear sources, part of a $20 billion AI expansion.

The company is also pursuing long-term clean energy supply deals across North America.

In Ireland, however, that strategy appears to have hit a wall. Even as AWS planned three new data centers in north Dublin, delays in planning approvals and grid reinforcement stalled progress. Local media report that Amazon’s request for temporary diesel generator use was denied, compounding the setback.

The cancellation raises deeper questions about energy infrastructure readiness in AI-era Europe. As hyperscalers ramp up power-intensive workloads, grid limitations are emerging as the biggest constraints.

Tyler Durden
Fri, 07/25/2025 – 09:40

Sarepta Plunges Again After Europe Rejects Elevidys

Sarepta Plunges Again After Europe Rejects Elevidys

Perhaps analysts at HC Wainwright & Co. were right about their 12-month zero-dollar price target for Sarepta Therapeutics.

Following Sarepta’s withdrawal of its Duchenne muscular dystrophy gene therapy drug from U.S. markets earlier this week, it has now failed to secure approval from European regulators. The double blow has sent shares plunging (again) in premarket trading in New York. 

The European Medicines Agency cited insufficient evidence of the gene therapy drug Elevidys to treat children aged 3 – 7 with Duchenne muscular dystrophy.

Via EMA…

Sarepta shares plunged as much as 18% in premarket trading. As of Thursday’s close, shares are down 89.5% on the year. 

Roche Holding AG, which markets Elevidys in ex-US markets, has also paused shipments in jurisdictions that reference the FDA for approval. Shares of Roche were down 1% in Switzerland. 

Elevidys’ safety profile has been under intense scrutiny since two teenagers and one adult died of acute liver failure after receiving the gene therapy. 

Sarepta CEO Doug Ingram stated earlier this week, “The decision to voluntarily and temporarily pause shipments of ELEVIDYS was a painful one, as individuals with Duchenne are losing muscle daily and in need of disease-modifying options.”

On Monday, a team of HC Wainwright & Co. analysts led by Mitchell S. Kapoor made the rare move of slashing Sarepta’s price target to zero – from a prior target of $10 – while maintaining a sell rating.

According to the latest Bloomberg data, there are six sell ratings, 17 holds, and four buys on the stock. The average 12-month price target among Wall Street analysts is $20.27.

Related:

.  .  . 

Tyler Durden
Fri, 07/25/2025 – 09:20