65.8 F
Chicago
Sunday, September 20, 2026
Home Blog Page 1446

Authorities Find 11 Dead Bodies In Abandoned Boat Near St. Vincent And The Grenadines

Authorities Find 11 Dead Bodies In Abandoned Boat Near St. Vincent And The Grenadines

Authorities in St. Vincent and the Grenadines are investigating the grim discovery of an abandoned boat with 11 decomposing bodies found near Little Bay on Canouan Island on May 26, 2025, according to ABC.

The 45-foot vessel reportedly carried passports indicating the deceased may be from Mali, a West African country over 6,000 kilometers away.

The Royal St. Vincent and the Grenadines Police Force called the incident “deeply concerning” and said they are working with both regional and international partners to identify the victims and establish how the boat ended up there.

This tragedy echoes previous cases involving West African migrants attempting dangerous Atlantic crossings.

In January 2025, a similar vessel was found off St. Kitts and Nevis with 19 bodies, some carrying Malian documents. In May 2021, another boat from Mauritania, containing over a dozen deceased men, was discovered near Trinidad and Tobago. Investigators believe those men had tried to reach Spain’s Canary Islands but were instead swept off course.

ABC writes that the Atlantic route remains highly dangerous, driven by factors such as political instability and economic hardship in countries like Mali. The UN High Commissioner for Refugees notes that migrants often target the Canary Islands, but ocean currents and limited navigational skills can push them far from their intended destination.

Authorities continue to investigate the Canouan case, determined to understand how this tragedy unfolded.

Tyler Durden
Sun, 06/01/2025 – 08:45

Punitive Politics And Economic Self-Harm – Germany Plans Special Tax On U.S. Tech Giants

Punitive Politics And Economic Self-Harm – Germany Plans Special Tax On U.S. Tech Giants

Submitted by Thomas Kolbe,

Germany is planning to introduce a 10% special tax targeting U.S. tech giants. At least now we know what the German government needs a “Minister of State for Culture and Media” for: to invent new taxes.

Illustration via Bitcoinsensus

If the ongoing trade dispute with the United States has taught us anything, it’s that Europeans are no innocent lambs when it comes to protectionism. On the contrary, they’ve mastered the art of shielding their markets through subtle mechanisms—while their media machine works overtime to conceal these maneuvers from the public.

Weimer’s Unexpected Mission

Wolfram Weimer, recently appointed Minister of State for Culture and Media, traditionally oversees a largely symbolic post linked to coalition horse-trading. Now, however, the office is being used to launch a direct political strike: a new tax to intervene in the tariff conflict with the U.S.

Weimer frames the digital tax as an act of social justice. With his “Platform Solidarity Contribution,” he aims to hold big tech companies accountable and break up their “quasi-monopolistic structures.” According to Weimer, Germany must reduce its dependence on U.S. infrastructure and contribute to “media diversity.” This is precisely where caution is warranted. When politicians start preaching solidarity, it usually ends up costing taxpayers and consumers dearly.

A Deliberate Provocation

Forget solidarity—this tax is nothing less than a calculated provocation aimed squarely at Washington. At a time when Donald Trump has paused threatened 50% tariffs on EU imports until July 9, hoping to find a negotiated solution, Europe responds with a punch in the face.

Moves like this digital tax won’t bring Brussels closer to a deal. Quite the opposite: they sour the climate and push transatlantic relations further into confrontation. Whether Germany realizes it or not, this tax confirms what many in the U.S. already suspect: Europeans are not truly interested in free trade—they’re protectionists at heart.

This isn’t the Art of the Deal—this is the Art of Closing the Door.

Europe’s Tech Failure

The underlying issue is both well-known and uncomfortable: Europe has failed to build its own competitive tech sector. Instead, the continent has meticulously crafted a vast and questionable regulatory framework. One wonders who this regulation is meant to serve when the sector it targets barely exists.

It’s a bureaucratic chimera—a Brussels-born behemoth now fed by Berlin, following Austria’s lead with a similar tax that met widespread criticism. In Vienna, that criticism also fell on deaf ears.

As is often the case with new levies, there’s a real concern that companies will simply pass on the added costs to consumers—through digital services, advertising, or subscriptions. What officials claim won’t affect users may well end up hitting them directly.

Industry groups like Bitkom already warned back in April that a digital tax could drive up prices for software, cloud services, and digital tools—slowing digital adoption and hurting both consumers and businesses.

Risk to Germany’s Innovation Landscape

Beyond the obvious financial burden for users, the proposed German digital tax carries serious structural risks. Though it targets international tech giants, its ripple effects could weaken Germany’s digital economy as far as it exists.

Startups and mid-sized IT firms reliant on global platforms would face rising costs. Innovation would be penalized, not rewarded—sending the wrong message to investors and stalling Germany’s already sluggish digital transformation.

On top of this looms the risk of escalating trade tensions: those who tax digital services must expect analog retaliation. Ultimately, this tax undermines Germany’s competitiveness without delivering a viable homegrown tech alternative.

Symbolic Politics Instead of Real Strategy

In the end, the digital tax is a symbolic gesture—politically driven, economically questionable. Europe again gets lost in micromanagement, passive-aggressive policies, and a complete lack of creative, future-oriented thinking.

When all else fails, the reflex is always the tax hammer. But this tax won’t hit the monopolies—it will hit their users. Not the tech behemoths, but the small players in the digital ecosystem.

And once again, it reveals the old European habit of making rules where freedom and competition would be far more productive.

Tyler Durden
Sun, 06/01/2025 – 08:10

Used Rolex Demand Soars On Tariff Uncertainty

Used Rolex Demand Soars On Tariff Uncertainty

Trade war uncertainty has sparked a surge in buying in the secondary watch market, driven by a sharp increase in demand in April amid a multi-year downturn. Luxury timepiece prices, which peaked in early 2022, have since been halved, making the recent surge all the more notable, and hope that the used watch market may have found a bottom. 

The Bloomberg Subdial Watch Index, which tracks prices for the 50 most-traded watches by value on the secondary market, recorded a surge in buying activity in April following end-of-month paychecks. 

Last month’s post-payday watch buying spike was 160% above normal trading levels, far surpassing the 112% average seen on other paydays over the past year, according to a Bloomberg report.

Christy Davis, founder of London-based Subdial, told Bloomberg that used watch sales surged last month across the U.S. and U.K. because “people heard about the tariffs and went, ‘Oh shoot, let’s buy now’… and waited for payday and then sales volumes just went through the roof.” 

Here’s more context about the tariff-fueled buying spike:

The phenomenon echoed another trend seen in Switzerland, where watch exports jumped by nearly a fifth in April — with shipments to the U.S. more than doubling ahead of expanded tariffs threatened by Trump. Watches made from precious metals, steel and bimetallic materials, products also targeted by Trump, saw the most growth, according to the Federation of the Swiss Watch Industry.

The question now is whether the Bloomberg Subdial Watch Index has finally found a bottom after plunging from its $60,000 peak during the Covid-era cheap money bubble in early 2022 to around $30,000 earlier this year.

Vontobel analyst Jean-Philippe Bertschy told clients that the spike in buying was driven mainly by exporters rushing to avoid tariffs rather than actual structural demand entering the market. 

Additionally, we should note that watch demand is sensitive to interest rates, which are expected to remain elevated in the U.S. throughout the year. Interest rate swaps are currently pricing in 2 25bps cuts through year’s end. 

Despite a gradual rebound in the Bloomberg Subdial Watch Index, many investors tracking the secondary timepiece market are questioning whether this marks a bottom—and if so, what kind of recovery shape might follow. On the other hand, lingering risks are elevated interest rates that may thwart a sustainable recovery. 

Tyler Durden
Sun, 06/01/2025 – 07:35

AfD’s Weidel Slams “Grotesque” “Authoritarian” Attack On German Democracy

AfD’s Weidel Slams “Grotesque” “Authoritarian” Attack On German Democracy

Via Remix News,

Alternative for Germany (AfD) leader Alice Weidel used the stage at CPAC Hungary to raise awareness of what she says is growing authoritarian behavior from the German government towards millions of Germans. She points to calls to ban her party, the second-largest party in the country and the leading opposition party, as well as attacks on free speech and spying from the country’s powerful domestic intelligence agency.

“Let’s be clear, and this is what we want you to know. What we want the world to know what’s going on in Germany. Influential politicians in Germany have their minds up on banning the strongest opposition party on banning us the alternative for Germany,” said Weidel.

“They would eliminate a political force which will soon form the government in several East German regions. Furthermore, they want to ban a party and has caught up with and overtaken the chancellor’s party itself. It is grotesque. It is authoritarian. And yes, this is a path they pursue, but they will not prevail. They will not prevail,” she added.

Weidel’s party, the AfD, had not been previously invited to any CPAC events in Hungary in the previous three years, but this pattern appears to have been broken. Orbán, who said that he had not previously conducted outreach with the AfD due to threats from the German government and in order to maintain ties with Berlin, publicly backed the AfD before national elections in Germany last year.

Weidel has only grown in popularity since those elections, and her party has even broken into first place in many polls for the first time. Approximately one in four Germans now backs the party, yet, the establishment has only upped its assault on the party, including the domestic spy agency, the Office of the Protection of the Constitution (BfV):

“The attempt to silence critical voices by framing them as right wing and extremist. Under the pretext of fighting hate speech and disinformation, legitimate opinions are being criminalized. And finally, there is our domestic intelligence service, the so-called Office for the Protection of our Constitution. In reality, it’s nothing but a service for protecting the establishment’s dwindling power.

When it comes to regular intelligence work uncovering terrorists and preventing terrorist attacks, this office is a complete failure. Instead of attending to the proper task, they spy on the opposition with one goal in mind to denounce the AFD as an enemy of the constitution and fabricate a pretext for outlawing our party.”

Weidel says that the establishment parties in Germany are looking to stop her party instead of addressing the legitimate issues driving her party’s growing popularity.

“In today’s speech, I am going to shed some light on the situation in Germany. For you to get some transparency about what’s going on in our home country. Our legacy media and establishment politicians fear us like no other party with good reason. More and more voters in Germany are simply fed up with being lied to and watching their quality of life deteriorating year for year.

Establishment politics have turned Germany into a danger zone for its citizens. Its people suffer from mass migration, exploding crime rates, high taxes, energy prices, inflation and the destruction of wealth. That’s why they voted out the old left-green government only to get a government that continues down the same disastrous path.

They got a government that pretends to prevent illegal immigration while leaving the gates wide open. In a futile attempt to evade his domestic problems, our chancellor travels the world fomenting conflict and throwing German taxpayers’ money out of the window as we see in the Ukraine. But when it comes to the daily horrors of imported migrant violence and Islamist terror on the streets, our chancellor remains silent.”

She also accused Merz of essentially stealing the AfD’s program, and then once winning the election, turning his back on all the promises he once made. Most notably, Merz immediately abandoned his promise to not take on more debt and relax the debt brake, instead choosing to take on nearly a trillion in debt.

“Mr. Merz won the election with copy-and-paste promises taken from us, the Alternative for Germany’s, program. The day after the election he went back on his word in every regard. He sold his soul to the leftists and kept them in power in exchange for being elected chancellor himself. Desperately clinging to power by all means has become the primary concern of our establishment politicians,” said Weidel. “Driven by panic, they bent laws, manipulate the constitution and eliminate the fundamental rights of the parliamentary opposition in order to prevent a democratic transfer of power. The current government continues a war on free speech started by its predecessors.”

Weidel said that her party represents 10 million voters, yet, these voters are being excluded by the firewall all parties say they have established against the AfD, which means they refuse to work with the party in government.

“The wind of change is blowing strong in Europe and in the Western world. The future belongs to free, patriotic citizens and sovereign nations. This conference gives testimony to that fact. Prime Minister Viktor Orbán, thank you and your country for hosting us. You are truly a beacon of freedom. Thank you,” said Weidel towards the end of her speech.

Read more here…

Tyler Durden
Sun, 06/01/2025 – 07:00

The Taliban Is Back In The International Spotlight

The Taliban Is Back In The International Spotlight

Authored by Andrew Korybko via Substack,

Al Jazeera recently published a detailed piece about how India, Pakistan, and Iran are all nowadays wooing the Taliban, which is true, but they left out how Russia and China are as well while also making no mention of the newfound pressure that the US is placing upon the group.

In the order that they were mentioned, Indian External Affairs Minister Dr. Subrahmanyam Jaishankar held an historic call with his Afghan counterpart in late May, the first between officials of their level in over a quarter century.

He thanked him for condemning April’s Pahalgam terrorist attack that led to the latest Indo-Pak conflict and for not falling for fake news meant to stir trouble between them. They also discussed expanding bilateral ties. India and Afghanistan have shared threat perceptions of Pakistan, the first due to the Kashmir Conflict and the second as regards Islamabad’s alleged attempts to subordinate Kabul. Closer cooperation between them thus advances their interests but prompts deep suspicion from Pakistan.

Segueing into that country’s interests, Pakistan accuses Afghanistan of harboring terrorist groups, which the Taliban denies. The improvement of their ties upon alleviating their resultant security dilemma could pioneer a Central Eurasian Corridor from Pakistan to Russia and beyond. Chinese Foreign Minister Wang Yi organized a meeting between their top diplomats in Beijing in late May to that end, but it’s unclear whether any tangible progress will be achieved. Mutual mistrust might ultimately prove insurmountable.

Moving along to Iran, that country had long-standing tensions with the Taliban over water rights and migration, but its Foreign Minister just visited Tehran in an attempt to help resolve them. Whether or not that happens is another story, but Iran has an interest in sincerely doing so due to the newfound pressure that the US is placing on the Taliban, which will be touched upon later on in this analysis. The point is that ties appear to be thawing, and at the very least, tensions might remain manageable for now.

Iran’s ties with Afghanistan sharply contrast with Russia’s, which recently removed the Taliban’s terrorist designation, just hosted a delegation at the recent Russia-Islamic World Forum in Kazan where they signed several agreements, and has a grand geo-economic vision for Afghanistan that was detailed here. The aforesaid overlaps with Pakistan’s earlier mentioned connectivity plans, which partially explains their rapprochement in recent years and could position Russia to mediate between it and Afghanistan.

On that topic, China is already mediating as was written above, but Russia objectively seems to be closer to the Taliban nowadays than they are given the latest agreements that were just signed. In any case, China is poised to play a major role in Afghanistan’s reconstruction, though continued security threats stemming from ISIS-K appear to have thus far hampered the implementation of its plans. Nevertheless, these plans still remain in place, and it’s possible that they could be speedily implemented in the future.

That’s precisely what the US wants to prevent, however, thus explaining the newfound pressure that it’s placing upon the Taliban through Trump’s demand to reobtain control over Bagram Airbase and Rubio’s implied threat to redesignate the group as a “Foreign Terrorist Organization” (possibly only if it refuses). Pakistan’s possible collusion with the US will be pivotal in determining what happens. If the US succeeds, then it could reshape South Asian geopolitics, much to India’s detriment and possibly also China’s.

Given the renewed interest that major stakeholders – India, Pakistan, Iran, Russia, China, and the US – have in Afghanistan, the Taliban’s return to the international spotlight might portend a new era of cooperation and competition between them. The main variable is whether or not the Afghan-Pakistani security dilemma is soon alleviated and on what terms if so, such as Eurasian-mediated (Russia and/or China) or American-coerced, which will in turn place these dynamics on very different trajectories.

Tyler Durden
Sat, 05/31/2025 – 23:20

Mustached Warmonger Muses On Trump’s Peace Efforts With Iran

Mustached Warmonger Muses On Trump’s Peace Efforts With Iran

It’s no surprise at all that the mainstream media continues featuring as ‘experts’ discredited war hawks and neocons who’ve gotten every war of the last 20 wars dead wrong – from Afghanistan to Iraq to Libya to Syria, and the list goes on.

Former national security adviser John Bolton, who laughably deems himself a ‘realist’ – was interviewed by NewsNation’s “On Balance” program Friday evening, and the question focused on President Trump’s efforts to secure a fresh nuclear agreement with Iran, which several polls show has broad American public support.

But mustached jingoist Bolton has blasted these efforts as “fruitless” and went so far as to lay out that if Israel pursues preemptive strikes on Tehran’s nuclear facilities, this would be entirely “warranted”. Needless to say, Trump and Bolton long ago had a very public following out and war of words.

Image via NewsNation

“I think we’re really at a very important point here, whether, whether Trump is going to try and continue these negotiations, which I think are going to be completely fruitless, or whether Israel is going to do what it has to do to protect its very existence,” Bolton said.

Bolton himself has long had a hand in shaping Washington’s vehement anti-Iran stance, and he certainly sided with the first Trump administration’s decision to unilaterally pull out of Obama’s 2015 JCPOA action deal, which collapsed in April of 2018 (upon the US pullout).

President Trump has meanwhile declared that Iran has “sort of agreed to the terms” of a deal and will not make “nuclear dust” – an apparent reference to uranium enrichment. These words issued on his prior Gulf tour, and the statements of optimism since then, come as mixed signals continue being issued from Washington.

Trump has also said of Tehran, “They don’t want to be blown up” and that “they would rather make a deal, and I think that could happen in the not-too-distant future.”

As for blowing things up, hawks like Bolton would certainly like to blow up or sabotage the prospects of a deal, but thankfully Trump has made sure he has nothing to do with his current administration, and even very early on in this administration removed Bolton’s protective federal security detail.

Many conservatives saw the danger Bolton posed to Trump policy the first time around, and tried to warn:

For now at least, Bolton has to be content to bloviate from the sidelines. There remain a number of Iran hawks within the administration, as well as in Congress.

But this time around Trump’s message has been peace around the globe through the ‘art of the deal’ and projecting strength – and he’s so far shown patience on the Iran issue. “We’re in very serious negotiations with Iran for long-term peace,” he had informed Gulf leaders and the public this month.

Tyler Durden
Sat, 05/31/2025 – 22:45

DOE Cancels $3.7 Billion In Biden-Era Green Energy Awards

DOE Cancels $3.7 Billion In Biden-Era Green Energy Awards

Authored by Tom Ozimek via The Epoch Times,

The Department of Energy has canceled 24 clean energy demonstration projects worth nearly $3.7 billion, citing concerns over financial viability, insufficient return on taxpayer investment, and a failure to meet the energy needs of Americans.

Energy Secretary Chris Wright announced the decision on May 30, describing the awards as hastily approved in the final days of the Biden administration and misaligned with the Trump administration’s energy and economic priorities. The cancellations come after an internal review ordered earlier this month under a new departmental policy aimed at increasing accountability and rooting out waste in federally funded energy programs.

“The Trump administration is doing our due diligence to ensure we are utilizing taxpayer dollars to strengthen our national security, bolster affordable, reliable energy sources and advance projects that generate the highest possible return on investment,” Wright said. “Today, we are acting in the best interest of the American people by cancelling these 24 awards.”

According to a department list reviewed by The Epoch Times, the terminated awards include high-dollar carbon capture and industrial decarbonization projects involving firms such as ExxonMobil, Calpine, Heidelberg Materials, and Kraft Heinz. Sixteen of the 24 awards were signed between Election Day 2024 and Inauguration Day 2025.

The rescinded projects span a range of industries and regions, including glass manufacturing facilities in Ohio, carbon capture efforts in Texas and California, and decarbonization initiatives at food production sites nationwide. The largest award canceled was a $500 million grant to Heidelberg Materials for a carbon capture project in Louisiana.

The move follows a May 15 memorandum issued by Wright titled “Ensuring Responsibility for Financial Assistance,” which established new standards for evaluating financial assistance programs. Under the policy, DOE is now requiring detailed financial, technical, and legal documentation from all recipients and reserving the right to modify or terminate awards that fail to meet economic or national interest benchmarks.

Earlier oversight efforts had flagged the risk of poorly vetted loans and grants under Biden-era programs.


A November 2024 report from the DOE’s Office of Inspector General warned that the Loan Programs Office, which saw its authority balloon from $17 billion to more than $400 billion under the Inflation Reduction Act and other legislation, was under pressure to rapidly distribute funds before key deadlines expired. The report highlighted “significant risks” to taxpayers from rushed decision-making and insufficient vetting, particularly given the volume and complexity of applications.

In two cases, the inspector general said DOE had already canceled nearly $400 million in grants awarded to entities with suspected ties to foreign adversaries. The watchdog urged the department to expand its applicant vetting capabilities and avoid what it described as a “pay and chase” model, where funds are disbursed before due diligence is complete.

President Donald Trump has issued multiple executive orders aimed at boosting fossil fuel production and limiting public funding for climate initiatives or ones involving DEI mandates. The administration has also directed federal agencies to review all discretionary grants issued under the Biden administration, with a focus on clawing back funds where possible.

In the case of the DOE, Wright said his department has already requested further documentation from 179 award recipients whose combined funding totals more than $15 billion. These reviews are ongoing and could result in further cancellations.

Tyler Durden
Sat, 05/31/2025 – 22:10

OPEC+ Hikes Output For Third Time By 411Kbpd, Despite Reservations From Russia

OPEC+ Hikes Output For Third Time By 411Kbpd, Despite Reservations From Russia

Following days of frenzied speculation that OPEC+ may go so far as to start another global price war similar to the Saudi armada in March 2020 which eventually sent WTI crude prices to a negative $45, however briefly, today’s decision was positively tame: OPEC+ agreed to surge oil output for the third month in a row, despite mounting reservations from key member Russia, doubling down on a historic policy shift that has sent crude prices sinking.

According to a statement on the OPEC website, the cartel of oil-exporting nations and several hangers on agreed during a video conference on Saturday to add 411,000 barrels a day to the market in July. The hike matches increases scheduled for May and June, marking a radical reversal from defending prices to actively driving them lower, largely in response to Kazakhstan chronically and unapologetically breaching its quota.

“OPEC+ isn’t whispering anymore,” said Jorge Leon, an analyst at Rystad Energy A/S, who previously worked at the OPEC secretariat. “May hinted, June spoke clearly, and July came with a megaphone.”

Officials said the supply hikes reflect Saudi desire to punish over-producing members like Kazakhstan and Iraq, recoup market share lost to US shale drillers and other rivals, and satisfy President Donald Trump’s desire for cheaper oil, even if it leads to – well – cheaper oil, and even steeper budget deficits for the country that exports 10 million barrels of oil per day and has an all-in breakeven price around $90.

The hikes will offer temporary relief to consumers as the northern hemisphere goes into its peak demand season, while also helping central banks grappling with stubborn inflation. Yet the market impact creates financial peril for oil producers around the world, which could be facing a period of prolonged low prices, followed by much higher prices as producing infrastructure suffers from disuse. 

What was most notable about this latest production hike is that, according to Bloomberg, several members expressed reservations during Saturday’s meeting about the speed with which OPEC+ was raising production. Russia, Algeria and Oman wanted a pause in the increases, according to delegates.

The difference in views between Moscow and Riyadh, the cartel’s two most powerful members, will come back into play on July 6, when they meet again to discuss output levels for August.

In April oil briefly tumbled to a four-year low under $60 a barrel after OPEC+ first unexpectedly announced they would bolster output by triple the scheduled amount. The move came even as faltering demand and Trump’s trade war were already crushing the market.  This was followed by a second hike announcement one month later, and now a third one.

While Brent futures have since recovered to trade near $64 a barrel, the IMF estimates the Saudis need prices above $90 to cover the lavish spending plans of Crown Prince Mohammed bin Salman. The kingdom is contending with a soaring budget deficit, and has been forced to cut investment on flagship projects such as the futuristic city, Neom.

However, thanks to earlier Reuters leaks, the markets is likely to take Saturday’s agreement as positive because ahead of today’s announcement “there were some concerns of a larger increase,” said Giovanni Staunovo, a commodity analyst at UBS, referring to Reuters reports that OPEC+ was considering even bigger output hikes.

Meanwhile, if Riyadh’s strategy is to discipline the cartel’s quota cheats through a “controlled sweating,” it doesn’t seem to be working. Kazakhstan, the most blatant offender, continues to exceed its limits by several hundred thousand barrels a day and has publicly stated that it has no plans to atone. Energy Minister Yerlan Akkenzhenov told reporters on Thursday that the country can neither enforce cutbacks on international corporate partners, or dial back at state-run fields. Which is why we recently speculated that if one or more of its peers wishes to teach Kazakhstan a painful lesson, then the Caspian Sea pipeline which carries most of Kazakh oil exports courtesy of the Caspian Pipeline Consortium, is probably sweating bullets right now.

But while Kazakhstan has so far refused to budge, the price downturn is taking a clear toll in America’s shale oil heartlands, where companies like Diamondback Energy Inc. say production has peaked, despite Trump’s promise the country would “drill, baby, drill” in a new energy boom.

With the hike scheduled for July, OPEC+ will be just over halfway through a road map for reviving 2.2 million barrels a day of output it had idled in recent years, a process that was previously planned to last until late 2026 yet which depends largely on how much of a stimulus China will finally unleash. The group will decide in the coming months how quickly to restore the remainder of supplies it’s still withholding from the market.

For some analysts, increasing supply is entirely logical. Demand will rise over the next few months in the US as drivers take to the roads for summer vacations, and also in the Middle East, where peak use of air conditioning means some barrels will be consumed domestically.

“Fundamentals in the right-here, right-now are strong — inventories are very low,” Amrita Sen, director of research at consultant Energy Aspects Ltd., said in a Bloomberg television interview before the meeting. “It is a good time for OPEC+ to add barrels to the market, so I don’t see why they wouldn’t.”

Nonetheless, further price losses may be in store. JPMorgan forecasts that Brent futures will sink into the “high $50s” later this year as the cartel’s hikes contribute to a global supply glut of more than 2 million barrels a day.

Tyler Durden
Sat, 05/31/2025 – 21:35

The Narratives Change; Markets Don’t…

The Narratives Change; Markets Don’t…

Authored by Lance Roberts via RealInvestmentAdvice.com,

A Successful Test

Last week, we discussed how this seems to be an “unstoppable” bull market. However, that doesn’t mean markets won’t pause before attempting to move higher. As we noted last week, the consolidation was expected.

“Even with Bessent’s comments, that market remains overbought in the short term, and a further consolidation process is likely to occur next week. At the end of this week, we removed our short-market hedge, added to bonds, and reduced equity exposure. If the market is going to consolidate, we can allow cash to act as the primary hedge. However, if the 200-DMA is violated, the 50-DMA will become the next critical support. From a bullish perspective, the 20 and 50-DMAs are now sloping positively, which should provide rising support levels. Overall, we suspect that the market will stabilize. Of course, there are always risks to be aware of, so increased cash levels are essential now.”

Most notably, this past week was the successful test of the 200-DMA. The pullback to that previous broken resistance level and subsequent bounce highly suggests that the April correction is complete and that market control returns to the Bulls. As such, there is very little resistance between current levels and all-time highs. However, as noted last week, with the markets still overbought on a momentum basis, further consolidation will be unsurprising before an advance to new highs occurs. With the MACD sell signal triggered and money flows declining, another test of the 200-DMA next week would be unsurprising.

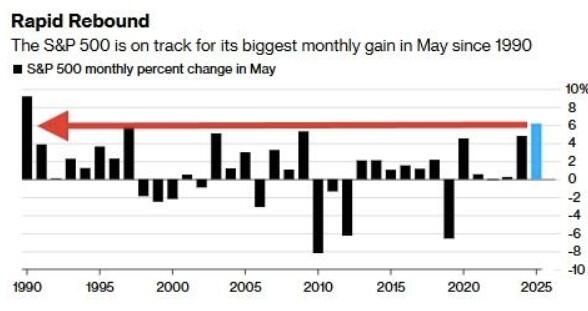
Interestingly, the old saying “April Showers Bring May Flowers ” seems apropos, as the tariff-driven sell-off in April sprouted a very strong May advance. Notably, the S&P 500 had its best month of May since 1990.

However, as noted above, with the market short-term overbought and very bullish, we should expect the market to “struggle” somewhat in June as corporate share buybacks subside and companies go into blackout before Q2 earnings season begins. Furthermore, we have often stated that earnings remain overly optimistic, which concerns markets moving forward. According to MRB Partners, the Q1 earnings season is expected to be the peak for the earnings growth cycle. Given the high correlation between forward earnings estimates and market returns, this commentary should not be readily dismissed.

That said, investors must be most careful of “market narratives.”  These narratives can potentially be far more harmful than helpful to investors who get swept up in the emotions generated by headline-grabbing rationalizations. Such is the topic for this week’s #BullBearReport.

The Psychology Of The Narrative

How fast market narratives change to fit a particular position is always interesting. This is particularly true for podcasts and media outlets that depend on a “bearish” take to sell gold or to get clicks and views. For example, I googled interest rates and here is what I got:

  • The Treasury Market Is On The Brink Of Collapse.
  • US Economy Implodes: Bond Markets Panic
  • Bond Vigilantes Voting Early.
  • US Risks “Financial Disaster”

You get the idea, it’s all bad. Or, at least that is the narrative right now.

So, why is the narrative so important to investors? Because we are humans.

As humans, we inherently seek structure through rules, routines, and frameworks in nearly every domain of life. This craving for predictability offers a sense of control and security. Whether dieting, learning, or investing, we often believe that following the “right” system will produce the desired result.

Humans have an innate need to impose order on the chaos surrounding them. Nowhere is this more evident than in the stock market, where investors relentlessly seek patterns, explanations, and narratives to rationalize why markets rise and fall. It’s a fascinating dance between logic and emotion, predictability and randomness.

The stock market is a complex, ever-changing system driven by countless factors—corporate earnings, geopolitical events, interest rates, technological innovations, andmost critically, mass psychology. And yet, when faced with this swirling unpredictability, we instinctively reach for stories. Here is a good example. Headlines declare that stocks are rising “because” of strong GDP growth. That makes sense until you see a headline that states stocks are falling “because” of strong GDP growth, which might spark inflation.

They both can not be correct. However, analysts point to one data point, and we latch onto it, even though the narrative might flip tomorrow.

Why Bearish Narratives Hold More Power

The need for a narrative is deeply rooted in our psychology. As pattern-seeking creatures, we crave coherence and predictability. Chaos triggers anxiety. It feels dangerous, uncontrollable, and unsettling. In investing, this anxiety is magnified by the direct impact on our wealth and financial security. We regain a semblance of control by latching onto the narrative, no matter how tenuous. The narrative tells us why things are happening and what might happen next, which soothes our natural fear of uncertainty.

When this need for control is combined with our behavioral bias of “loss avoidance,” it is more evident why bearish narratives tend to be more popular than bullish ones. Why is “loss avoidance” crucial to understand?

Loss aversion is a tendency in behavioral finance where investors are so fearful of losses that they focus on trying to avoid a loss more so than on making gains. The more one experiences losses, the more likely they are to become prone to loss aversion.” – Corporate Finance Institute

The reality is that humans are hardwired to prioritize negative information over optimistic information. From an evolutionary perspective, this bias was essential. Our ancestors learned to recognize threats (like predators) to survive. This instinct, known as “negativity bias,” influences how we process information, including financial news and market narratives. Such is why “bearish” leaning podcasts and articles generate the most clicks and views.

  • Fear Is a Stronger Motivator Than Greed – While the hope of making money drives investors, the fear of losing money is far more powerful.
  • Bearish Narratives Seem More “Rational” – Pessimism often feels safer and more cautious. During volatile markets, a bearish forecast can sound more analytical and responsible.
  • Media Amplifies Negative Headlines – News outlets know that fear sells. Sensational headlines like “MARKETS IN TURMOIL” or “CRASH COMING?” generate clicks and engagement.
  • Herd Behavior and Echo Chambers – When markets are shaky, investors flock to bearish opinions for validation. If others are cautious or fearful, it reinforces the idea that a downturn is imminent, even if underlying fundamentals remain sound. Social media and financial news create echo chambers that amplify these fears.

The Bond Auction Example

Here is a good example of narrative driving markets.

Recently, interest rates ticked up after headlines rang out that the 20-year bond auction was horrific, signaling that the U.S. debt market is on the verge of collapse. As Michael Lebowitz noted this past week:

The bearish narratives were in overdrive after the Moody’s credit downgrade and the larger-than-expected “Big Beautiful” government spending bill. But narratives always need to be fed. The bearish bond narrative ate on May 21, 2025, with a Treasury 20-year auction deemed “terrible” and “horrible” by some pundits. Some interpreted the auction as an obvious sign that the Treasury was struggling to fund itself.

Some fear-mongers pointed out the “large” auction tail. The tail is the difference between the auction yield and the yield before the auction. A large tail can mean insufficient demand for the auctioned bonds. As the graph below shows, the recent red tail is not that abnormal. Moreover, the size of the tail is volatile in both directions. This is partly because the 20-year bond is not as widely regarded as a market benchmark as other maturities.

The headlines were rampant that this “terrible, horrific auction” resulted from no one wanting to own U.S. Treasuries. However, that wasn’t true, as “indirect buyers” were allotted 82% of the auction bonds. These are primarily foreign central banks. So, foreign demand was strong despite the anti-dollar narrative claiming that central banks are selling US Treasuries in size.

However, as Mike notes, just a week earlier, the 10-year auction, which was three times larger than the 20-year auction, was stellar.

“Primary dealers (direct bidders), the backstop for Treasury auctions, account for the third-lowest allotment since at least 2008 at 8.9%. This signifies that demand from other sources was robust. Second, there were bids for 2.6x as many bonds as were being auctioned. The average of the last six auctions was 2.4x. Furthermore, the ratio was at the high end of the range of the last ten-plus years.

However, the “bearish media” overlooked the vastly more significant 10-year auction to focus on the 20-year auction, which fits their “narrative.”

So, is the narrative that the “deficit” will cause a debt collapse accurate? Or, is that just the latest “rationalization” to feed our “negativity bias?”

The History Of Rates And Deficits

Yesterday, I published an in-depth article about Ray Dalio claiming the “deficit has become critical.”

” “It’s like … I’m a doctor, and I’m looking at the patient, and I’ve said, you’re having this accumulation, and I can tell you that this is very, very serious, and I can’t tell you the exact time. I would say that if we’re really looking over the next three years, to give or take a year or two, that we’re in that type of a critical, critical situation.”

Of course, the narrative would not be complete without a terrifying chart to back it up, like this from Deutsche Bank:

“Here we remind readers, that the Big, Beautiful Bill currently in Congress has been scored to add about $5 trillion to the debt, resulting in what we said would be “Debt Doomsday” for the US; this is simply a trade-off of short-term prosperity (a few extra trillion in the next 4 years) for long-term economic collapse (that 220% in long term debt.GDP).”

That is indeed scary. But as detailed in that article, he has been predicting this same crisis for more than a decade. For investors who listened to Dalio’s predictions of a coming “depression” a decade ago, they missed participating in one of the most significant bull markets in U.S. history.

However, the facts show us that rising debts and deficits lead to lower interest rates, not higher. The reason is that debt diverts capital from productive uses into debt service. As such, economic growth slows. We can see this visually by comparing the Federal debt as a percentage of GDP to potential economic growth. Since government spending is primarily non-productive, it should be unsurprising that increases in debt do not foster more vigorous economic activity.

Where Dalio and other media bears are incorrect in their view is that the recent surge in inflation, and ultimately interest rates, was not a function of organic economic growth. It was a stimulus-driven surge in the supply/demand equation following the pandemic-driven shutdown. As those monetary and fiscal inflows reverse, that support is fading. In the future, we must understand the factors that drive rates over time: economic growth, wages, and inflation. Visually, we can create a composite index of GDP and inflation versus interest rates.

Given that interest rates (return on loaned capital) are derived from both economic activity (demand for credit) and inflation (future cost), the high correlation should be unsurprising.

Contrary to the recent barrage of bearish narratives, slowing economic growth lowers inflation (a function of supply and demand) and reduces rates.

Markets Don’t Change

What is most important to investors is that the market absorbs all negative media narratives over the long term. The recent barrage of negative narratives surrounding debts, deficits, tariffs, inflation, wars, Trump, etc., is all just there to feed your negative bias. However, zooming out, investors who have stayed away from investing in the financial markets to “avoid the loss” of potential adverse outcomes have paid a dear price in reduced financial wealth.

In other words, there is always a “reason” not to invest. However, the current narrative will change, but the market won’t. Here is a good example of how narratives change. Since 2007, interest rates have gyrated up and down. Currently, rates are still lower than in 2008, but have risen. What is essential is that each time rates went up, the “narrative” was always different. Yet, the US has been running ever-increasing deficits since 2008, but that was never the narrative…until now.

However, when it comes to investing, there have been periods of deep market declines. But those events didn’t occur overnight. There were always plenty of warning signs to help investors reduce risk and navigate those periods. However, even those who stayed invested fared far better than those who stayed out of the bull market advances in fear of the subsequent decline.

I am NOT saying you should passively stand there and let an eventual recessionary bear market or financial event wash over you. Investors can, and should, manage portfolio risk and navigate markets during uncertain times. However, most bearish narratives are like background noise in the investing world. There will always be a headline or analyst warning you to step aside. Sure, some of those concerns are valid. But reacting emotionally, selling everything, and going to cash often leads to missed opportunities.

Tips For Navigating The Narrative

Here are a few strategies I recommend to help investors navigate the constant drumbeat of pessimism:

🔎 1. Separate Signal from Noise

Bearish narratives are often based on isolated data points taken out of context. Look at the bigger picture:

  • Instead of panicking over an inverted yield curve, examine credit conditions, corporate earnings, and consumer confidence.
  • If markets correct, assess whether the underlying fundamentals of your investments have truly deteriorated or if it’s short-term volatility.

📊 2. Use a Disciplined Risk Management Framework

At RIA, we don’t ignore market risks—we manage them. That means:

  • Rebalancing portfolios proactively. If markets have run hot, we trim positions back to targets. If we see opportunity amid panic, we increase exposure.
  • Setting clear stop-loss levels. This protects gains and limits downside risk without making emotional decisions.
  • Diversifying across asset classes to smooth returns during volatility.

💡 3. Lean into Value, Quality, and Dividends

When bearish narratives dominate, investors often abandon sound fundamentals. That’s when we lean into:

  • Value-oriented stocks with strong balance sheets and consistent cash flows.
  • Dividend payers that provide income during market turbulence.
  • Quality companies that can weather economic downturns better than speculative plays.

🕰️ 4. Remember the Long Game

Bearish narratives may feel urgent, but markets are forward-looking. A well-structured, long-term portfolio can withstand temporary declines. Historically, those who stayed the course during volatility were better positioned for the eventual recovery.

Successful investing is not about beating some arbitrary “index.” It is about managing risk, preserving capital, and steadily compounding returns toward your goals. Ignore the noise, stay disciplined, and remember: no one hands out prizes for reckless investing—only consequences.


Tyler Durden
Sat, 05/31/2025 – 21:00

Israel Launches Major Airstrikes On Syria’s Coast For 1st Time In Nearly A Month

Israel Launches Major Airstrikes On Syria’s Coast For 1st Time In Nearly A Month

Israel has attacked Syria for the first time in nearly a month. The last known airstrikes were May 3rd, but on Friday night major strikes rocked Syria’s coastal area.

State news agency SANA says that one civilian was killed “as a result of an Israeli occupation airstrike targeting the vicinity of Zama”. Social media videos showed large fireballs lighting up the night sky.

The Israeli military offered quick and rare confirmation that it had “struck weapon storage facilities containing coastal missiles that posed a threat to international and Israeli maritime freedom of navigation, in the Latakia area of Syria.”

Huge spoke plumes were seen over Tartus in the strike aftermath, and it should be noted that the coastal city is also home to Russia’s lone Mediterranean naval base, which has yet to be completely packed up amid negotiations with the new Jolani regime.

“In addition, components of surface-to-air missiles were struck,” the Israeli military (IDF) statement further stated, vowing that the IDF will “continue to operate to maintain freedom of action in the region, in order to carry out its missions and will act to remove any threat to the State of Israel and its citizens.”

The irony of the timing is that the Hayat Tahrir al-Sham (HTS) government has been teasing the possibility of peace and normalization with Israel, despite Israeli forces currently occupying large swathes of southern Syria, even well beyond the Golan Heights.

The new post-Assad government has mostly shrugged off the Israeli attacks, which soon after Assad’s ouster came in the hundreds, as Tel Aviv sought to destroy any and all military hardware left by the former Syrian Arab Army.

Tensions have been rising between Israel and Turkey over the ‘spoils’ in Syria. Turkey’s military has sought to set up anti-air defenses for the new regime, reportedly in the center of the country – in Palmyra – which Israel has tried to thwart through bombing raids.

Prior to Assad’s ouster, Israel said it repeatedly bombed Syria for ‘counter-Iran’ operations, but at this point the divide-and-rule policy of keeping Syria as weak and fractured as possible has certainly become more clear.

Tyler Durden
Sat, 05/31/2025 – 20:25