44.5 F
Chicago
Sunday, November 8, 2026
Home Blog Page 1747

Paying A Heavy Price For Going After A Tax-Cheat Named Hunter Biden

Paying A Heavy Price For Going After A Tax-Cheat Named Hunter Biden

Authored by Nancy Rommelmann via RealClearInvestigations,

Joe Ziegler is not a beaten man – not for his antagonists’ lack of trying. Across his seven-year pursuit of Hunter Biden’s unpaid taxes, Ziegler, a special agent in the Internal Revenue Service’s criminal investigative division, and his colleague Gary Shapley were shunned, threatened, and lied to. Ziegler was doxed. Shapley was told to accept a demotion or resign. Convinced the IRS and Department of Justice were stonewalling their efforts to bring charges against a sitting president’s son, the agents went public as whistleblowers in 2023. 

The result, during the hyper-polarized years spanning the Trump-to-Biden-to-Trump administrations, was predictable: The two men were accused of partisanship, lambasted by Democratic members of Congress and the press, and had their reputations impugned by high-powered lawyers paid for by those sympathetic to the Bidens. 

The fortunes of these political victims have now turned. In mid-March, incoming Treasury Secretary Scott Bessent announced Ziegler and Shapley would start work as senior advisers, helping to guide tax reform.

Which is all the agents had ever wanted and tried to do. “At the end of the day, this is truly about doing the right thing and standing up for what is right,” Ziegler would testify before the House Ways & Means Committee in December 2023. “I will say this again and again, this is much bigger than the Hunter Biden investigation. This was not a personal attack on Hunter Biden, but a call for change.”

While the reprisals they say they endured for their acts of conscience appear to have ended, Ziegler and Shapely do not want their experience to be memory-holed – especially because other whistleblowers who spoke out during the Biden administration have received less attention for their tribulations. Speaking with RealClearInvestigations recently, the two men gave their first in-depth interviews on the years-long case that upended their lives and careers. 

***

“He was paying individuals, so, prostitutes, that were associated with that company,” Ziegler said. A little digging revealed Hunter Biden’s ex-wife reporting he had not paid his taxes and, in their divorce filings, mentioning “a very large diamond he received,” a gem allegedly valued at $80,000 and given to him by an executive at a Chinese energy company. 

“I look into our IRS systems and see that he had unfiled tax returns for multiple years,” said Ziegler. “When you fail to file tax returns and you have income that qualifies you to file tax returns, that’s a misdemeanor offense.” 

A misdemeanor that can rise to the level of a felony, depending on the dollar amount and the length of time the would-be filer has been delinquent. Hunter Biden looked to qualify on both counts.

The case should have been a cakewalk, and yet almost immediately, Ziegler suspected he was being stonewalled: Interviews he requested were denied, and coworkers subtly and not so subtly warned him to tap the brakes.

“My manager at the time, who wasn’t Gary [Shapley], made it very, very hard for me,” Ziegler told RCI. “He said, ‘When you work with high-profile people like this, you need way more information, way more evidence.’ He essentially set the bar higher, which I didn’t agree with at all.”

Even if he had set the bar higher, Hunter Biden’s actions would have cleared it, with multiple and well-documented instances of tax evasion, including not reporting more than $1 million in payments from the Ukrainian energy company Burisma. Still, Ziegler noted a determined lack of urgency within the IRS to move the case along. “It was a lot of hard work on my end, pushing everyone on the case to be like, ‘We need to do this. We need to go interview these people.’ And every single time I hit a roadblock or hit someone telling me, ‘No, we shouldn’t do that.’”

After more than a year of pushback, Ziegler found an ally in Shapley, who took control of the investigation in January 2020.

A supervisory special agent with 14 years at the agency, Shapley assumed the case would be handled routinely. “I expected everyone was going to act appropriately,” he said. “It was just another case, and that’s how I approached it.”

And not much of one, compared to others he’d worked on, including getting Credit Suisse to plead guilty in 2014 to helping U.S. taxpayers hide offshore accounts, resulting in a $2.6 billion fine. 

“When you stick to just the way that it’s always been done, then it doesn’t matter who you’re investigating,” he said. “I really thought that, even though [people] did a lot of these things that shielded Joe Biden from a full investigation, that they were still going to do the right thing concerning Hunter Biden.” 

This might have been the case had Trump/Biden politics not become a blood sport. Shapley found no appetite within his department to issue subpoenas or execute search warrants. The lack of access accelerated when Joe Biden became the presidential nominee. A request in late 2020 to search a guest house he owned and in which Hunter Biden was staying was denied, as were requests to interview Biden family members.

Why the hold-ups? Shapley said he’d “never been told by our leadership, ‘nod nod, wink wink,’” that they were meant to handle the case with a delicacy that actually prevented them from doing their jobs. Fearing their investigation was turning into Kabuki theater, Shapley began creating a second record of what the agents saw as untoward resistance. 

“When we started having problems, I started documenting issues and deviations from normal procedures,” said Shapley.“With the search warrants that weren’t being executed, even though there was probable cause, that’s when it became apparent that he [Hunter Biden] was receiving special treatment.”

The agents, too, were receiving special treatment of a sort. Ziegler was yanked off other investigations he was working on. Requests that Shapley made went unacknowledged or disappeared into the ether. And both agents saw colleagues keep their distance, reluctant apparently to offer even the appearance of support.

“They completely isolated us,” said Ziegler. “No one reaching out, no one asking questions. There was a lack of empathy, a lack of caring within my agency, and it’s sad.”

For two years, he and Shapley engaged in a Sisyphean struggle to move the Hunter Biden case along, a situation that went from remarkable to ludicrous to untenable. 

“It was me and Gary on weekly FaceTime calls, literally [saying], ‘I can’t believe they did this. I can’t believe they’re not letting me do my job. They’re not letting us do the right thing,’” said Ziegler. “And then it culminated to a point where we ended up blowing the whistle.”

***

Their concern and frustration grew ever more intense because the facts of wrongdoing the agents  uncovered were so clear. Between 2014 and 2019, they found that Hunter Biden had failed to pay taxes on more than $8.3 million in income derived from various sources, including those in China, Ukraine, and Romania.

Whether some of that money landed in the bank accounts of Joseph Robinette Biden Jr. may continue to be debated until only cockroaches roam the earth, but one can assume the people who gave the younger Biden a 3.4-carat diamond were at least hoping for access to his father.

The evidence showed that Hunter Biden evaded paying taxes by filing false returns, claiming personal expenses such as payments to prostitutes, a $25,000 sex club membership, and, more wholesome if alas nondeductible, college tuition for his children. As a result, he owed at least $1.4 million in federal taxes, elevating his alleged violations to a possible felony for tax evasion and fraud. The alleged crimes – which also included another possible felony charge for lying on a gun permit in 2018 – occurred during the time when Hunter Biden has described himself as a heavy user of crack cocaine. 

Despite Ziegler and Shapley’s efforts, their investigation might have been buried if Hunter Biden had not failed to retrieve the laptop he left at a Wilmington, Delaware, repair shop in 2019. Although the FBI has admitted it took possession of the computer that same year and soon verified it belonged to Hunter Biden, its contents – which documented Joe’s connections to his son’s business affairs along with salacious photos – surfaced only in October 2020, after Trump adviser Rudy Guiliani gave the New York Post a copy of the hard drive he said he had received from the repair shop owner. In an echo of the pushback Ziegler and Shapley were experiencing, Biden supporters worked to discredit the laptop story.

Contrary to the media circus, Ziegler knew the laptop was not, as Joe Biden would claim, a “Russian plant.” 

“Yes, absolutely,” he told RCI in March from his home in Atlanta. His team was aware of the contents of the laptop but had made no hay from it; it was just another part of the investigation, which made the reaction to its discovery, including 51 former senior intelligence officials publishing a letter claiming the laptop story “has all the classic earmarks of a Russian information operation,” seem especially bizarre.

“Comparing that to the information we had on our end is, in hindsight, extremely disappointing,” he said. “But I guess at the time I just didn’t think about the politics of it.”

By late 2020, Shapley had come to see nothing but the politics of it, including among fellow federal employees whose unwillingness to hold Hunter Biden accountable for his actions Shapley found disappointing, if unsurprising, the “yes man’s” way forward. 

“These people were institutionalized by the federal government. They are only in those very high positions because they played this game to move up the ladder,” he said from his office in Baltimore. A ladder being held firmly in place by Team Biden.

There was also something too clever by half in the higher-ups putting Shapley, who for years had received the agency’s highest recommendations, in charge of a case the IRS seemed to be doing its best to spike.

“They knew I was the expert, and they knew that I knew more than them about working these types of cases, so they put me on the hot seat,” he said. “Then they stuck their head in the sand, and pretended that everything was going to be fine … and [that] the problems you were moving into in 2020, 2021, and 2022 were just going to go away.”

Meanwhile, the chances of any charges being filed against Hunter Biden were growing tenuous. Shapley was alert to this eventuality when he decided to take notes during an Oct. 7, 2022, meeting, where U.S. Attorney David Weiss, who was overseeing the case, stated he was “not the deciding person” on whether charges would be filed. 

“He said that he had to go to the President Biden-appointed U.S. Attorneys to get approval and they said no,” recalled Shapley. Weiss, a Trump appointee, had been working on the Hunter Biden case since 2020. When Merrick Garland became attorney general in 2021, he allowed Weiss to continue the probe, in part to avoid the appearance of political interference. Then why, Shapley wondered, was Weiss more than a year later saying he didn’t have the authority? That Weiss later denied he’d ever said he didn’t have official approval did not wash with Shapley, whose meeting notes – which he’d shared contemporaneously with other attendees – specifically had Weiss saying he’d been told he was “not the deciding person on whether charges were filed.” 

“My red line meeting was Oct. 7,” he said, and afterward, he “immediately started seeking a counsel to help me legally follow the legal path to blow the whistle.”

Ziegler’s red line intersected with Shapley’s on May 15, 2023, when the agents learned Hunter Biden would be offered a deferred prosecution agreement, which meant he would not only not face felony charges; he would not be charged with anything at all. May 15 was also the day the agents learned they’d been removed from the Hunter Biden investigation in December 2022, but that no one had bothered to tell them. “Leaders within my organization, to hear they had removed us six months prior to actually removing us?” said Ziegler. “This was a huge slap in the face.”

As for why they had been taken off the investigation, the men were told the IRS and DOJ had not known in December whether the case would move forward, and thus, the departments had not wanted to waste resources. “Which is a bunch of malarkey,” said Shapley, as was Hunter Biden being allowed to slip away from the charges he and Ziegler had worked hard to make stick. 

To the agents, this was a betrayal on multiple levels. First, by colleagues inside the department and out (“They come to my house and with their wife and children, I know these people,” said Shapley, of DOJ tax prosecutors who “went behind my back to get me removed from the case”), second, to the jobs they had constitutionally pledged to carry out, and third, of the country’s taxpayers, in that it created a two-tiered system of justice, one for regular Americans, the other for a president’s son and anyone else the people at the top decided to protect. 

“What kind of leaders remove an entire team from a high-profile case without telling them?” Shapley would later ask in a hearing before the House Ways & Means Committee. 

***

Becoming the public faces of the Hunter Biden case, which included testifying before Congress and running the media gauntlet, meant the agents were in for new and different types of punishment. Explaining that the tax crimes Hunter Biden had committed, which Ziegler testified to in excruciating detail, should be adjudicated as they would be for any other citizen was cast as batting against Team Blue. This would not do. In the run-up to another Trump/Biden face-off, the powers that be needed to vanquish (or at least humiliate) their perceived enemies, to turn the poison arrow away from their candidate and his kid. 

“It was extremely important to Gary and me that we stay as bipartisan as we could possibly stay,” said Ziegler of their many appearances on network news shows. “And I think as much as we tried to do that effort, I think the left side of the media didn’t, in my opinion, do a good enough job… it was kind of like, ‘Anyone else but Trump, we have to protect!’” 

“I remember [Congressman] Dan Goldman giving a press conference after an oversight committee, saying, ‘This is just a disagreement between investigators and prosecutors, and the prosecutors know what’s right,’” recalled Shapley. “‘The prosecutors are smart, the [IRS agents] are stupid,’ is essentially what he said. And I haven’t gotten a sorry yet from him.”

Attacks also came from the right, as when Ziegler’s personal information was leaked online by a former Trump aide who believed that Ziegler, being a Democrat and gay, was a secret liberal intent on stalling the Hunter Biden case. “I got a phone call right around Christmas time that said, ‘Hey, just so you know, your driver’s license is out there in the media. He has a whole bunch of pictures, photos of you and your partner.’” Ziegler paused. “He is now my ex-partner. So, that was another piece or element as a part of this investigation.” 

The exposure and stress proved too much for the marriage. “I do think,” he said, “it played a role in essentially losing that relationship.”

***

In a case this controversial, in a climate where tearing down the other side had become reflexive, things were bound to get messier. Hunter Biden’s plea deal – which had him pleading guilty to two misdemeanor tax charges for failing to pay taxes in 2017 and 2018, as well as a pretrial diversion program for a felony gun charge – collapsed in July 2023 when the judge raised concerns about the scope of immunity the deal. “When the judge literally struck down that plea, I cried,” said Ziegler. “I was like, finally, someone gets it.”

The relief would not last. Hunter Biden sued the IRS that September, claiming the agency failed to protect his tax records. (As of this writing, the case remains ongoing.) In September 2024, Ziegler and Shapley sued Hunter Biden’s lawyer, Abbe Lowell, for defamation, seeking $20 million in damages. This was in response to Lowell’s having written a letter to the chairman of the House Ways & Means Committee in June 2023, alleging the agents had improperly released tax information, and characterizing them as “self-styled IRS ‘whistleblowers’ who may be claiming that title in an attempt to evade their own misconduct [which] was an obvious ploy to feed the misinformation campaign to harm our client, Hunter Biden, as a vehicle to attack his father.” (Lowell’s request that the case against him be dismissed was denied.) 

And the big one, which shocked just about no one: On Dec. 1, 2024, outgoing president Joe Biden granted a “full and unconditional pardon” to Hunter Biden for federal tax and gun convictions, as well as any other federal offenses he may have committed since Jan. 1, 2014. This, despite repeatedly having stated he would rule out a pardon for his son. (On the last day of his presidency, Biden further issued blanket pardons for six other family members.)

The Hunter Biden pardon was seen, variously, as a display of fatherly devotion; a cynical way to bury Biden family tracks; a preemptive measure to keep Hunter Biden from the well-known vengefulness of the incoming president; and a giant waste of taxpayer dollars and attention.

“The pardon was the biggest positive for the Republican Party and the biggest hit against the Democratic Party that could have possibly happened,” is how Shapley saw it. “The Democratic Party can no longer say, ‘We’re for the little guy, that we’ll hold rich people accountable, et cetera, et cetera.’ And the Republicans, they can always go back and say, ‘Well, the Democrat president lied to the American people and then pardoned his felon son.’”

“Those pardons that were handed down at the last day of his presidency would’ve never happened if we didn’t do what we did,” said Ziegler. “You can try and discredit me as much as you want. But since day one, since we came forward, none of what I testified to changed. There was nothing where I had to come out and say, ‘Oh, yep, what I said there wasn’t accurate.’ We came out, we testified [before Congress], and then we gave them the receipts. Regardless of what anyone else says out there, we follow the law.”

The U.S. Office of Special Counsel agreed when, in December 2024, it determined that Ziegler and Shapley had been retaliated against by the IRS, including their being improperly removed from the Hunter Biden investigation.

Was the Trump administration playing tit-for-tat when they reinstated the agents, who, in 2026, will transition to senior leadership roles within the IRS? Almost assuredly, or at least in part. And yet that has no bearing on the fact that the two men stood firm when all around them others were willing not to; were willing to compromise – some of whom now are greeting Shapley and Ziegler as heroes. 

“The rank and file agent here that has paid any intention, they know the burden that I assumed by doing the right thing, and they support me,” said Shapley. “One of them in particular said, ‘You guys did the right thing. You’re going to be teaching ethics classes in two years here.’” 

Shapley estimated that “hundreds and hundreds of people” have come out in support. “But none,” he said, “have come out publicly.”

Back home in Atlanta, Ziegler remains incredulous that anyone would think he did what he did for political reasons.

“Why blow up your life, get a divorce, ruin your reputation? Why do all of this?” he asked. “To be honest with you, I want change. I want policy change. I want political change… If you’re Joe Biden, if you’re Hunter Biden, if you are a celebrity, if you are whoever, you are going to get treated the same exact way as someone else. I do feel there is a lot of preferential treatment with the Department of Justice, and specifically the IRS. And I think that we need to stop that.”

As he starts his new job, he is still metabolizing what was done during the course of what should have been a routine investigation: the isolation, the subterfuge, and the slow roll, the people he’d assumed would be and by law should have been allies, instead treating him as expendable. 

“There was just so much heartbreak that it became like a depression, became hard to get up and do my job. You just didn’t feel appreciated at all,” he said. “It’s kind of crazy because now that Donald Trump is president, things have kind of changed a little bit. I think some [colleagues] are working from a sense of fear within our agency; that Gary and I will get promoted to positions where we have some power, and the ability to create change in the IRS.”

If it’s within the law, Ziegler says, that’s something his coworkers can count on. 

“I knew what we were doing was right,” he said. “And looking back on everything, I would absolutely do it again.”

Tyler Durden
Fri, 04/11/2025 – 13:25

“Groundbreaking” FDA Shift Away From Animal Testing Sends Lab Shares Into Freefall 

“Groundbreaking” FDA Shift Away From Animal Testing Sends Lab Shares Into Freefall 

The U.S. Food and Drug Administration (FDA) announced a major policy shift late Thursday, signaling the replacement of traditional animal testing—particularly in monoclonal antibody development—with advanced computer modeling and artificial intelligence. The news sent shares of lab companies tumbling on the update, while shares in companies working on biotech AI models jumped. 

“Today, the FDA is taking a groundbreaking step to advance public health by replacing animal testing in the development of monoclonal antibody therapies and other drugs with more effective, human-relevant methods,” the FDA wrote on X, twenty minutes before U.S. cash markets closed on Thursday. 

Here’s a summary of the FDA’s major shift in drug testing policy:

  • AI-based computer modeling to simulate drug behavior and toxicity.

  • Lab-grown human organoids and organ-on-a-chip systems to detect toxic effects more accurately than animal tests.

  • Use of real-world safety data from countries with comparable regulatory standards.

  • Regulatory incentives to encourage adoption of these alternatives, including potential streamlined reviews.

  • Immediate application to new drug applications (INDs), with a roadmap released and a public workshop planned.

“With this move, the FDA reaffirms its role as a global leader in modern regulatory science, setting new standards for the industry and encouraging the adoption of innovative, humane testing methods,” the FDA stated in a press release. 

Here’s the response from Wall Street analysts (courtesy of Bloomberg):

Baird analyst Eric Coldwell

  • says “expect very slow change to the research animal and animal testing services market”

  • “Street got shock and awe news today, and players in this industry likely won’t fully recover when it comes to valuation,” Coldwell writes in a note

Jefferies analyst David Windley

  • says FDA’s Modernization 2.0 already stared phasing out animal testing, “but perhaps this is a stronger push with more prescribed plan”

  • “At the least with preclinical spending deprioritized, this is just another reason to pause.”

Barclays analyst Luke Sergott

  • says while taking out preclinical animal testing testing is “a good goal” — “questions on feasibility and implementation remain”

  • Charles River in the cross​-​hairs, however “this paradigm shift has downstream impacts to late​-​stage trials”

RBC Capital Markets analyst Brian Abrahams

  • says “these steps towards increased regulatory flexibility as net positive, especially given recent concerns about potential FDA dysfunction and potentially greater stringency”

  • Antibody innovators Regeneron Pharmaceuticals, Amgen, Viridian, BeiGene, Xencor and Ultragenyx Pharmaceutical would likely stand to benefit the most

The immediate consequence of the significant testing policy shift sent shares of Charles River, the leading provider of research animal models, plunging by a one-day record of 28%, reaching their lowest level since March 2020 by Thursday’s close.

Peers also fell: LabCorp closed 5.2% lower, and Inotiv crashed 50%. Meanwhile, companies working on AI models surged in premarket trading, with Certara up 20%, Schrodinger up 15%, and Nuvation Bio up 3%.

Tyler Durden
Fri, 04/11/2025 – 13:05

Is The Consumer Tapping Out?

Is The Consumer Tapping Out?

Authored by Lance Roberts via RealInvestmentAdvice.com,

The recent implementation of tariffs has the media buzzing about increased recession odds as the consumer faces potentially higher costs. While recent economic reports, like the latest employment report, still show robust growth, those data points run with a lag that hasn’t yet caught up with reality.

As we have discussed, the American consumer is the backbone of the U.S. economy and comprises nearly 70% of the GDP calculation. While GDP surged following the economic shutdown due to the massive flood of stimulus that fueled a savings surge, consumption as a percent of the economy has remained flat since the turn of the century. The reason is that despite the surge in savings, the consumer was also faced with rising inflation, which left them struggling to make ends meet.

This dilemma is better illustrated by the chart below. The blue line is the personal savings rate, and the red line shows the debt needed annually to bridge the gap between the inflation-adjusted cost of living and savings and incomes. As shown, at the turn of the century, the consumer was no longer able to fund their living standard through just income and savings. The fact that consumers were forced to take on increasing debt levels to maintain their living standards explains why consumption as a percent of GDP has remained stagnant over the same period.

At the heart of the problem is the collapse of household balance sheets in the lower-income and middle-income brackets. These groups have depleted the excess savings accumulated during the pandemic and are turning to high-interest borrowing to bridge the gap. The Philadelphia Federal Reserve reported that the share of active credit card accounts making only minimum payments surged to 10.75% in Q3 2024—a record high. This statistic isn’t just a warning about credit health; it points to widespread cash flow stress.

In addition, more consumers are falling behind on their monthly card payments. The balance-based 30+ days past due rate increased 33 basis points year-over-year to 3.52% in the third quarter of 2024. This represents more than double the delinquency rate of 1.57 percent at the pandemic low in the second quarter of 2021.

More alarming is the growing use of Buy Now, Pay Later (BNPL) services. Notably, those services are not being used for large discretionary purchases but for food. 

Recent surveys show that more consumers are increasingly relying on installment payment platforms like Klarna and Affirm to afford meals. Initially, the design of the BNPL model was for luxury or semi-durable goods. However, its expansion into groceries signals deep-rooted affordability issues. Debt is no longer just a tool for convenience; it’s a necessity for millions’ survival.

The problem with Trump’s trade war now is that it comes when consumers are already showing clear signs of distress. According to recent data, both from the Federal Reserve and corporate earnings reports, the consumer’s financial cushion that kept consumer spending alive in 2021 and 2022 is gone. What remains is a fragile consumer base increasingly reliant on credit and debt to afford necessities. While inflation has slowed, its damage is lingering. Now there is growing evidence suggesting that a recession and deflation are more immediate risks.

Consumer Confidence Declining

Consumer stress isn’t limited to anecdotal indicators—it’s now showing up in corporate earnings and executive commentary. During the company’s earnings call, Doug McMillon, CEO of Walmart, stated that many customers are under “budget pressure.” They are also exhibiting “stressed behaviors,” including spending reductions across general merchandise. Specifically, he warned that “For many customers, the money runs out before the month does.”

Similarly, Dollar General CEO Todd Vasos painted an equally concerning picture. He described his customers as “struggling more than ever before.” Todd added that some are now forgoing non-discretionary items, like medication or hygiene products, to afford groceries and fuel. He said, “These customers are making trade-offs we haven’t seen in years.” Concurring with that warning was Jane Fraser, CEO of Citigroup. She observed that consumers are “becoming more cautious” and focusing spending on smaller, lower-cost purchases. While this signals a growing defensive posture, often associated with recessionary conditions, they are also deflationary. When consumer behavior shifts en masse from aspirational to survival-based, the ripple effects are inevitable.

When we combine all the various measures of confidence into a single index, the correlation to GDP is unsurprising.

Furthermore, that decline in confidence leads to changes in the rate of inflation. This should be unsurprising since prices reflect supply and demand. As demand declines, prices fall to levels where demand for those products, goods, or services exists.

The data supports this narrative. Real personal consumption expenditures, the most significant component of GDP, are weakening. Once optimistic, the Atlanta Fed’s GDPNow model has revised estimates lower. Such was due to the decline in spending on goods and services. High interest rates, implemented by the Federal Reserve to curb inflation, now exert a secondary effect. Those rates are strangling credit access and making existing debt more expensive.

Housing data also reflects economic strain. Residential building permits and starts have declined markedly over the past six months, and homebuilder confidence has also deteriorated. First-time homebuyers—often a leading indicator of broader consumer strength—have retreated sharply due to affordability concerns.

When combined with increased pressures from higher taxes (read tariffs), the data is sending a warning.

The Risk Of Recession (and Deflation) Have Increased Markedly

The current data point toward a recessionary risk. Deflation is highly correlated to economic growth rates, wages, and rates. Unsurprisingly, recessions reduce inflation as demand for goods and services collapses. While inflation may be “sticky,” the recent decline in bond yields and wages suggests consumer demand will decline this year.

When tariffs, an additional tax on consumers, increase the cost burden, the reaction historically is not expansionary. As consumers contract spending, employers reduce business investment (demand) and cut employment (supply of wages). As shown, while volatile, plans to expend capital for investment purposes correlate with real private investment (which feeds into GDP.) While this data does not currently reflect the tariff impact, it was already suggesting much weaker growth. We suspect the outlook for CapEx has declined markedly in recent weeks.

We are seeing “demand destruction” caused by rising input costs due to tariffs against an already weak consumer backdrop. That combination of inputs will likely lead to higher unemployment, slower growth, and deflationary pressures in the economy unless there is a supply shock due to some unforeseen event like another “oil embargo.” Outside of such an event, in an environment where consumer demand is falling due to the inability to afford what’s available, suppliers will have to cut prices to find buyers.

Furthermore, credit conditions also reinforce the recession risk. Banks have tightened lending standards across consumer and commercial lines as credit card delinquencies have ticked up sharply, particularly among borrowers aged 18–39. The Federal Reserve’s Senior Loan Officer Opinion Survey shows a continued reduction in credit availability—making it even harder for stretched consumers to borrow their way through.

This reflects a critical turning point: the U.S. consumer is no longer a driver of economic growth but a potential drag on it. When nearly 70% of GDP depends on consumption, a weakening consumer poses systemic risks. A policy pivot may be necessary, and the calls for further Fed rate cuts this year are rising, with markets expecting four rate cuts this year. However, for now, with inflation still above target and the labor market gradually cooling, policymakers lack the room to cut rates aggressively without potentially reigniting price pressures. However, as the impact of tariffs causes a marked reduction in demand, those fears will likely give way to concerns about economic disruption.

In short, the American consumer is tapped out. The savings buffer is gone, wage growth is declining, and credit costs are rising. Corporate America is already adjusting to this new reality, with companies issuing cautious guidance for 2025. Even the tech sector—previously resilient—is showing signs of demand compression in consumer-facing verticals.

Unless wage growth accelerates or interest rates decline meaningfully, the pressure on households will continue to mount. That means recession and, ultimately, deflation—the more immediate threat to the U.S. economy. While deflation may seem the “out of consensus” view – if demand destruction continues unchecked, the more pressing concern is a downturn in demand. Declining real incomes and credit exhaustion are already warning of that risk.

Investors and policymakers would do well to focus less on inflation in isolation and more on the consumer’s deteriorating balance sheet. That’s where the next economic shock is currently hiding.

*  *  *

For more in-depth analysis and actionable investment strategies, visit RealInvestmentAdvice.com. Stay ahead of the markets with expert insights tailored to help you achieve your financial goals.

Tyler Durden
Fri, 04/11/2025 – 12:45

Trade War Turbulence: Chinese Airline Delays Boeing Jet Delivery In Possible Non-Tariff Countermeasure

Trade War Turbulence: Chinese Airline Delays Boeing Jet Delivery In Possible Non-Tariff Countermeasure

China announced earlier that it had raised its levies on U.S. goods to 125%, up from the previous 84%, but stated that it would “no longer respond” to any further tariff increases from Washington. This suggests that Beijing may begin rolling out non-tariff countermeasures. 

Hours after the initial announcement—and about an hour into the U.S. cash session—Bloomberg reported that China’s Juneyao Airlines had delayed the delivery of a widebody aircraft from Boeing, according to people familiar with the matter.

The people said Juneyao was supposed to take delivery of the 787-9 Dreamliner in three weeks but will now hold off due to the escalating trade war. 

China’s non-tariff countermeasures against the U.S. in the deepening trade war are broad and far-reaching and may include the following:

  • Export Controls and Quotas

  • Currency Devaluation

  • Boycotts (State-Inspired)

  • Licensing & Certification Hurdles

  • Restricting Market Access

  • Pressure Big Tech With Cybersecurity & Data Laws

  • Limiting Cultural Imports

  • Selling U.S. Treasuries

Early this week, Beijing shifted to non-tariff retaliation, limiting Hollywood film imports, slowing rare earth export shipments, and allowing the yuan to weaken. 

This is certainly not the end of the trade war, but one broadening outside the scope of tariffs. This understanding is likely why Goldman has yet to give an “all clear” to clients, as more marked turmoil is expected. 

Countdown to the next U.S. company that Beijing targets, if that’s delaying orders or restricting access and/or using lawfare. 

Tyler Durden
Fri, 04/11/2025 – 12:25

Citi’s Former Global Strat Head: Gold More Room To Run

Citi’s Former Global Strat Head: Gold More Room To Run

“[Gold] is certainly a large position in my portfolio.” That was Matt King, former head of global strategy for Citibank, from last night’s deep dive into the global trade war.

ZeroHedge hosted King and Alastair Pinder, head of emerging markets and global equities for HSBC, to map out potential scenarios if the current trends of nationalism and trade warring continue. While not a guaranteed scenario… it would be good for gold and bad for U.S. equities, bonds, and the dollar. The discussion was expertly moderated by friend of ZH and host at Real Vision Ash Bennington.

King and Pinder each came equipped with some ominous charts. Here is a brief snapshot:

Pinder on why the U.S. might be f***ed:

  • OUTFLOWS out of U.S. equity markets increasing rapidly.

  • Fewer tourists visiting American.

  • Tariffs — if persistent — will greatly affect corporate earnings thus equity valuations.

    • But… even if tariffs don’t persist, corporate guidance is already factoring in their impact on earning expectations and stocks are forward looking.

  • Some Trump positives — deregulation.

King on why the U.S. is definitely f***ed:

  • Momentum in equities lost.

  • Basis trade blowing up.

    • Made worse by HF leverage

  • REAL RISK: long-only investors herded into “buying the dip” because of Fed policy.

  • If they continue, tariffs will tank the US — our lack of manufacturing is to our benefit.

    • Cheap goods from asian sweatshops.

  • Risk to $ and treasuries (trump threatening foreign bond holders with default).

  • All of this leads to: MORE FLIGHT INTO GOLD

“Get out of the currency that’s trying to debase itself.”

King now runs Satori Insights so check out his services for institutional clients there.

The full one-hour debate is available to premium and professional subscribers here.

Tyler Durden
Fri, 04/11/2025 – 11:45

Tesla Quietly Removes Model S/X “Order Now” Button From Chinese Site

Tesla Quietly Removes Model S/X “Order Now” Button From Chinese Site

Tesla has quietly removed the “Order Now” button for its Model S and Model X vehicles on its Chinese website, signaling potential disruption amid a deepening US-China trade war. The move comes as Beijing announced a new round of retaliatory tariffs early Friday, raising the effective duty on U.S. imports from 84% to 125%. 

Both the Model S and Model X are manufactured in California, making them directly exposed to China’s tariff escalation—in other words, those vehicles would not be economically feasible to sell in a high-rate tariff regime overseas.

“The electric-car maker was offering the option to order the two models as of the end of March, according to a screenshot of its China website archived by Wayback Machine,” Bloomberg noted. 

The sudden suspension of ordering Model S/X should not come as a surprise, considering both are made in Fremont, California and then loaded up on RORO carriers to Beijing.

The good news for Tesla: Model S/X were a tiny fraction of Tesla sales in China last year, coming in just under 2,000 units, compared with 661,820 for both the Model 3 and Model Y (both made at Shanghai Gigafactory).

Here’s EV blog Electrek’s take on the situation:

One of the first victims of the trade war in the EV space. It kills a relatively small market of about 2,000 vehicles for Tesla in China, but those are profitable vehicles, which is not the case for most vehicles Tesla sells in the country these days.

90% of the vehicles Tesla delivers in China are Model 3 and Model Y RWD, which are low-margin vehicles that Tesla has to subsidize 0% financing on to move. It results in the automaker making little to no profit on those vehicles.

In the case of Model S/X in China, we are only talking about roughly $170 million in potential lost revenue for Tesla, but at least the company was making some profits on those.

As we previously reported, Tesla’s biggest concerns amid this trade war are the tariffs on Chinese battery cells entering the U.S., which support its Megapack and Powerwall energy business, and Chinese buyers turning away from American brands.

If the trade war with China escalates even more, Tesla could even start worrying about the status of its factory in Shanghai, which is a rare auto factory wholly owned by a foreign automaker in China.

On Thursday evening, HSBC Head EM strategist Alastair Pinder and the legendary Matt King (formerly Citi’s top strategist who correctly called the Lehman collapse) debated on ZeroHedge to discuss the incoming fallout from tariffs on global trade. King was gloomy about global trade (watch here). 

We have reported some of the first immediate economic fallout of this week’s tariff war:

Tariff wars are beginning to disrupt global trade flows—from Amazon’s supply chain to Tesla’s China sales—and the affected companies are only expected to grow. 

Tyler Durden
Fri, 04/11/2025 – 09:35

Futures Flat, Gold Soars, Dollar Crashes After China Hikes US Tariffs To 125%

Futures Flat, Gold Soars, Dollar Crashes After China Hikes US Tariffs To 125%

Things are moving so fast it’s becoming pointless to do static market wraps like this one, but may as well try even if it will be completely irrelevant the minute we publish this.

US equity futures are slightly higher, having reversed steep overnight losses. What is remarkable however is that even after China announced a decision to raise tariffs on all US goods from 84% to 125%, stocks initially dippped by have since recovered. As of 8:40am, S&P futures are up 0.6% helped by solid earnings from JPM and Morgan Stanley, while Nasdaq futures gained 0.8%, lifted by solid Mag7 performance.

More importantly, the dollar (DXY index) plunged below 100 for the first time since 2023 on concerns its status as the world’s reserve currency is being eroded as the US-China trade war intensifies (spoiler alert: it’s not, because very soon we are about to see China, Japan and Europe unleashing a monetary bazooka to preserve their export industries (i.e. economy) pushing the euro topped to a 3 year high much to the horror of Europe’s exporters while the yen also exploded higher, sending the country’s exporting industries in a crisis. 

And amid this fiat carnage, gold soared to a fresh record high and even bitcoin is starting to catch a bid as algos slowly but surely realize that if the dollar is no longer the world’s reserve currency, and every other fiat currency is worse than the dollar, then… yeah.

In premarket trading, Mag 7 stocks were mixed after China’s decision to raise tariffs on all US goods from 84% to 125%.
Tesla -0.3%, Amazon +0.2%, Meta +0.7%, Apple +0.06%, Alphabet +0.6%, Microsoft +0.3%, Nvidia +1%). Shares in companies working on biotech AI models gain after the FDA said it plans to phase out animal testing requirements for monoclonal antibodies and other drugs (Recursion Pharmaceuticals +14%, Absci +15%, Certara +20%, Schrodinger +14%, Nuvation Bio +2.9%). US-listed Chinese stocks are holding onto their gains after the latest escalation in trade tensions that saw China raising levies on US goods to 125%, but saying it won’t match further US tariff hikes (Alibaba + 2.2%, Baidu 3.6% +4.1%, NetEase +2.1%). Here are some other notable premarket movers:

  • American Express (AXP) climbs 2.6% as BofA turns bullish, seeing the credit card provider as recession resilient.
  • Cinemark Holdings (CNK) rises 3% as JPMorgan upgrades to overweight, saying the cinema company is one of the least economically exposed firms in the current volatile environment.
  • EQT (EQT US) shares slip 1.6%. The gas producer expects to report a total derivatives loss of $679 million for the three months ended March 31, according to a statement.
  • JPMorgan (JPM) rises 1% as the bank’s stock traders took in a record haul in the first quarter but its FICC and iBanking revenues missed.
  • Morgan Stanley (MS) rises 3% as 1Q net revenue tops estimates.
  • Stellantis (STLA) shares fall 2.8% after the carmaker said shipments dropped 9% in the latest three month period.
  • Verve Therapeutics (VERV) gains 6.6% after saying that the FDA granted fast track designation for VERVE-102.
  • Wells Fargo (WFC) gains 1.7% after posting quarterly results.

As Bloomberg notes, in a week that’s seen the biggest swings in decades erupt across stock and bond markets, currency moves took the spotlight on Friday. In the latest tit-for-tat move, China announced it would raise tariffs on all US goods from 84% to 125% and warned that it plans to “resolutely counterattack and fight to the end” if the US continues to infringe on its rights and interests. The Ministry of Finance also called the Trump administration’s actions a “joke” and said it no longer considers them worth matching.

“The question of a potential dollar confidence crisis has now been definitively answered – we are experiencing one in full force,” ING Bank NV strategists including Francesco Pesole wrote in a note. “The dollar collapse is working as a barometer of ‘sell America’ at the moment.”

JPM shares rose as much as 4% in US premarket trading before fading all gains, after the bank boosted loan-loss provisions and bolstered its reserves. Rival Morgan Stanley also climbed after reporting soaring trading revenue amid market volatility.

“The economy is facing considerable turbulence,” JPMorgan CEO Jamie Dimon said in commentary accompanying the results. “Clients have become more cautious amid an increase in market volatility driven by geopolitical and trade-related tensions.”

BlackRock Inc. reported lower-than-expected net inflows in the quarter with CEO Larry Fink likening current conditions to the “structural shifts” seen during the global financial crisis and the Covid pandemic. “Uncertainty and anxiety about the future of markets and the economy are dominating client conversations,” Fink said in a statement.

Earlier, Bank of America’s Michael Hartnett said President Donald Trump’s tariffs and the resulting market turmoil were turning US exceptionalism into “US repudiation.” He advised investors sell any rallies until the Federal Reserve steps in and the US and China de-escalate, recommending a short position on stocks — until the S&P 500 hits 4,800 points — and a long bet on two-year Treasuries. Higher bond yields, lower stocks and a weaker dollar are “driving global asset liquidation, will likely force policymakers to act,” Hartnett wrote in a note. But investors should “sell the rips in risk assets.”

A Citi index shows analysts are slashing estimates at a pace that is generally seen during growth shocks, such as the pandemic. Meanwhile, Bank of America data shows massive inflows to passive equity funds, while Treasuries had their biggest weekly inflow ever.

Meanwhile, Trump’s second term is now off to one of the worst starts for the stock market since the Herbert Hoover era in 1929, tying with George W. Bush. Other assets also faced more turbulence, with the dollar extending losses after its biggest plunge in three years, gold hitting a new high and oil prices on track for a second straight weekly decline.

In Europe, the Stoxx 600 is down 1.5% with industrial goods and travel and leisure stocks were the biggest laggards, while the utilities and food and beverage sectors performed better than the wider benchmark.  Here are the biggest movers on Friday:

  • Argenx shares gain as much as 4.3%, after the US Food and Drug Administration approved a new option for patients to self-inject Vyvgart Hytrulo with a prefilled syringe
  • Schott Pharma shares jump as much as 13%, after the German healthcare supplier released preliminary figures for the second quarter that were ahead of market estimates
  • K+S shares rise as much as 6.4% after being upgraded by analysts at Stifel, which sees the chemicals company hitting the top-end of its earnings guidance range this year
  • Havas shares rise as much as 8.6% after the communications company delivered good organic growth in the first quarter and confirmed its guidance for the full year
  • BP shares decline as much as 3.5% after debts mounted in 1Q, a period when upstream production dropped and gas-trading performance was also weak
  • NIOX Group shares tumble as much as 22% after Keensight Capital said it doesn’t intend to make an offer for the UK pharma company because of the prevailing macroeconomic conditions
  • Steyr Motors shares fall 12% after investment firm Mutares sells 910,000 of the engine company’s shares at a 14% discount to Thursday’s closing price

Earlier in the session, Asian stocks edged higher, reversing earlier losses, led by gains in Taiwan and India.  The MSCI Asia Pacific Index gained as much as 0.4%, with Taiwanese firms TSMC and Hon Hai Precision among the biggest boost. Stocks in India advanced in a catch-up as trading resumed after a holiday. Investors are awaiting US President Donald Trump’s response after China raised levies on US goods to 125%. This comes as Washington clarified that tariffs on Chinese imports rose to 145%. Tensions between the world’s two largest economies have spiraled in recent days, which have raised concerns over the impact on US and global growth. Taiwanese shares rose amid foreign inflows. Equities traded lower in Japan and Korea, while those in Hong Kong rose for a fourth straight day.

In FX, the Bloomberg Dollar Spot Index fell as much as 1.3% to the lowest level since Oct. 3, after China said it will raise tariffs on all US goods from 84% to 125% starting April 12. The euro outperformed all its Group-of-10 peers as it’s haven dynamics further gain traction; EUR/USD rallies by 2.4% to 1.1473, a three-year high, before paring gains.

In rates, treasuries reversed modest gains and slumped to session lows as the unwinding basis trade pushed yields to highs of the session just shy of 4.50%. Longer-dated gilts underperform the rest of the curve with UK 30-year borrowing costs rising 6 bps to 5.49%. Bund yields are broadly lower.

US economic calendar includes March PPI (which came in ice cold and in deflation across the board) and April preliminary University of Michigan sentiment (10am). Fed speaker slate includes Kashkari (8am), Collins (9am), Musalem (10am) and Williams (11am)

Top Overnight News

  • China will raise tariffs on all US imports to 125% from tomorrow. Beijing also said it won’t pay attention to further hikes from Washington as the excessively high numbers are “economically meaningless” and “a joke.” It will, however, continue to fight to protect its interests. BBG
  • Beijing clarified that its tariffs would only apply to chips based on where they are manufactured, not the parent company’s country of origin (since most major US chips, including ones from Nvidia and Qualcomm, are made outside the US, this means they won’t be hit with the tariffs, at least for the time being). RTRS
  • Rep. Chip Roy said he voted for the Senate’s reconciliation blueprint only after being reassured by Republican leaders that they would embrace more aggressive spending cuts, including to Medicaid. NYT
  • China recently discussed with some of the country’s largest companies about potentially delisting from American stock exchanges. WSJ
  • EU threatens to impose tariffs on American services (including US tech giants) if trade negotiations w/the White House don’t yield a deal. FT
  • EU leaders will travel to Beijing in Jul for a summit with Chinese President Xi as the world establishes new trade relationships in the wake of Trump’s tariff war. SCMP
  • Russia could be forced to begin cutting spending (including support for its war in Ukraine) as soon as this summer given the sharp drop in oil prices. NYT
  • UK economic data outperforms expectations, with upside readings on GDP (+0.5% M/M vs. the Street +0.1%), industrial production (+1.5% M/M vs. the Street +0.1%), and manufacturing production (+2.2% M/M vs. the Street +0.2%). WSJ

Trade/Tariffs

  • Apr 11th: China raises tariffs on the US to 125% from 84%
  • China unveils additional tariff measures on US goods; to raise additional tariffs on US goods to 125% from 84%. Effective April 12th. Finance Ministry “if the US continues to impose additional tariffs on Chinese goods exported to the US, China will ignore it”. “Given that there is no longer any possibility of market acceptance for US goods exported to China under the current tariff levels, if the US side subsequently continues to impose tariffs on Chinese goods exported to the US, the Chinese side will pay no attention to it,”. If the US insists on infringing on China’s interests in a substantive way, China will resolutely take countermeasures.
  • China’s Commerce Ministry says the US’ repeated imposition of abnormally high tariffs on China has become a “numbers game” and has no practical economic significance.
  • Global Times Editor Hu Xijin tweets “With tariffs already so high on both sides, to be honest, we no longer see it as anything extraordinary.”

A more detailed look at global markets courtesy of Newsquawk

APAC stocks mostly followed suit to the declines on Wall St where the major indices gave back a chunk of their historic gains as tariff uncertainty lingered and with the US clarifying China tariffs were at 145%, not 125%. ASX 200 was pressured amid underperformance in energy, healthcare and tech, while gold miners outperformed after prices of the precious metal extended to fresh record highs. Nikkei 225 briefly fell beneath the 33,000 level with exporters hit by a firmer yen and global trade uncertainty. Hang Seng and Shanghai Comp initially conformed to the downbeat mood after the US clarified its tariff on China was at 145% although Chinese markets gradually recouped losses amid hopes of the PBoC to step in with monetary policy support.

Top Asian News

  • PBoC will implement a moderately loose monetary policy, support the smooth operation of financial markets, and consolidate the continued recovery of the economy. It was also reported that PBoC’s Deputy Governor attended the ASEAN, China, Japan, and South Korea Finance and Central Bank deputies meeting on April 8th-9th where the impact of US tariffs on global and regional macroeconomic situation was discussed.
  • EU leaders plan a trip to Beijing in July for a summit with Chinese President Xi Jinping, while it was separately reported that Spanish PM Sanchez called for mutually beneficial relations with China during a visit to Beijing.
  • China Jan-Mar vehicle sales +11.2% Y/Y (prev. +10.6% Y/Y); March +8.2% (prev. +34.4% Y/Y)

European bourses (STOXX 600 -0.9%) opened entirely in the green, attempting to build on the prior day’s gains.  However, indices rapidly turned negative after China announced additional tariffs on US goods, taking the total to 125% from 84%; these will come into effect on April 12th. European sectors opened almost entirely in the green, but the picture quickly turned negative after the aforementioned Chinese tariff announcement. There is now a clear defensive bias in Europe; Utilities leads, alongside Healthcare. The typical cyclical sectors find themselves towards the foot of the pile; Travel & Leisure, Autos and Basic Resources are all lower.

Top European News

  • Germany to provide EUR 11bln in military funding support for Ukraine until 2029, according to Ukrainian Defence Minister.

FX

  • Another downbeat session for the Dollar following Thursday’s detrimental losses which saw the index slip from a 102.95 peak to a 100.69 trough on Thursday, before extending downside to a 99.71 low in APAC hours – falling beneath 100 for the first time since July 2023. The index then took another dive lower after China raised its tariffs on the US to 125% from 84% in a retaliatory move. DXY has dived to an intraday 99.01 low from a 100.63 intraday high at the time of writing.
  • EUR has been bolstered by the collapse of the Dollar coupled with its status as a liquid reserve currency, and the market belief that the EU will not escalate the US trade war – with US tariffs on the EU trimmed to 10% from 20% whilst the EU also paused its tariffs in tandem. Further upside is seen after China raised its tariffs on the US to 125% from 84% in a retaliatory move, which took EUR/USD to north of 1.1400.
  • JPY is benefitting from the softer Dollar and ongoing tit-for-tat tariffs between the world’s two largest economies. JPY was further bolstered by China raising its tariffs on the US to 125% from 84% in a retaliatory move. USD/JPY resides towards the bottom of a 142.08-144.60 range, with participants looking for further trade updates for impetus.
  • GBP is lifted by the softer Dollar, the UK’s favourable relationship with the US, and above-forecast GDP metrics. UK GDP printed firmer across the board, albeit the data is for February and is thus stale given the US tariffs.
  • Mixed trade across the antipodeans with the Aussie hampered by the fallout of US tariffs on the Chinese economy and in turn demand for Australian natural resources, whilst the Kiwi benefits via the AUD/NZD cross.
  • PBoC set USD/CNY mid-point at 7.2087 vs exp. 7.3104 (Prev. 7.2092).
  • SNB spokesperson declined to comment when question on the CHF’s strength and if any steps are planned.

Fixed Income

  • A softer start to the day but one that leaves USTs just off the overnight 110-01+ trough, a low which printed as the benchmark faded initial strength on Thursday despite a strong 30yr tap. Action occurred as the risk tone stateside began to lift and as the yield curve steepened further. Only a modest uptick in USTs to the latest additional Chinese tariffs, keeping them within the existing 110-01+ to 110-15 band.
  • Bunds began softer and printed a 129.92 low, however the benchmark was holding onto most of the upside that emerged in the latter half of Thursday’s session. Unreactive to the final German CPI but was lifted into the green and to a 130.70 peak by China retaliating to the US tariffs – this upside has since continued to a fresh 130.75 peak.
  • Gilts opened lower by a handful of ticks at 91.62 before slumping to a 90.78 trough as it reacted to the strong GDP data (though, this will likely be looked through), overnight bearishness in peers and in a pull back from the marked strength seen on Thursday. For the week as a whole, Gilts are set to end it with losses of around 300 ticks but are over 100 ticks above the 89.99 trough.
  • UK DMO to sell GBP 1.5bln of 0.125% 2028 Gilt via tender on April 16th.
  • Italy sells EUR vs exp. EUR 7.25-9.0bln 2.65% 2028, 3.15% 2031, 0.95% 2032 & 3.25% 2038

Commodities

  • Crude is lower, in what has been a choppy session thus far. The complex was initially firmer in early European trade, but rapidly turned negative after China raised additional tariffs on US goods to 125% from 84%. Brent Jun’25 currently trading at the lower end of a USD 62.77-64.37/bbl range.
  • Firmer trade across precious metals with the complex bolstered by the demise of the Dollar coupled by flight to quality amid the latest chapter in the trade saga. Spot gold topped USD 3,200/oz for the first time overnight and continues grinding higher at the time of writing, currently in a USD 3,177.26-3,227.45/oz intraday range.
  • Modest gains across base metals space amid ongoing hopes of Chinese economic support in the face of US tariffs. 3M LME copper trades on either side of USD 9,000/t and resides in a USD 8,934.65-9,170.80/t range.

Geopolitics

  • US aggression targeted several areas in Yemen’s capital with a series of raids, according to Al Jazeera.
  • Iran Foreign Ministry spokesperson says Tehran is giving talks with the US a genuine chance and intends to assess the other side’s intent and resolve this Saturday.
  • Iran wants to explore an interim nuclear deal in talks with the US before pursuing negotiations over a comprehensive deal, according to a European diplomat and a source cited by Axios.
  • “US sources: The likelihood that Iran will make a decision to build nuclear weapons has increased due to the ongoing military conflicts in the Middle East”, according to Sky News Arabia.
  • British troops could be deployed in Ukraine for five years under plans being discussed by allies, according to The Telegraph.
  • Trump envoy Witkoff to travel to Russia to meet with Russian President Putin, according to Axios; If no ceasefire is reached by the end of the month, Trump could move forward with additional sanctions on Russia.

US Event Calendar

  • 8:30 am: Mar PPI Final Demand MoM -0.4%, est. 0.2%, prior 0%
  • 8:30 am: Mar PPI Ex Food and Energy MoM -0.1%, est. 0.3%, prior -0.1%
  • 8:30 am: Mar PPI Final Demand YoY, 2.7%, est. 3.3%, prior 3.2%
  • 8:30 am: Mar PPI Ex Food and Energy YoY 3.3%, est. 3.6%, prior 3.4%
  • 10:00 am: Apr P U. of Mich. Sentiment, est. 53.5, prior 57

DB’s Jim Reid concludes the overnight wrap

The past 24 hours saw Wednesday’s strong relief rally turn into a broad slump for US assets across equities, rates and FX. The S&P 500 fell -3.46% yesterday while 30yr Treasury yields (+13.3bps yesterday) are on course for their largest weekly rise since the 1980s. The dollar has also seen a historic weakening, with the euro on Thursday posting its biggest gain against the greenback since 2015 (+2.30%) and gold trading at an all-time of $3,215/oz this morning. US equity futures have seen some stabilization overnight, with those on the S&P +0.20% higher. But there has been little respite for the dollar, with the dollar index down another -0.75% this morning as markets continue to reassess how much of the historical premium for US assets stemming from American exceptionalism is still justified under the radical vision and volatile policy of the new US administration.

The main driver of the renewed market pressure was an increased focus on the US-China escalation, with yesterday’s market downturn accelerating after a White House clarification that total tariffs on China would now be 145% rather than 125% (so stacking on top of the earlier 20% fentanyl-related tariffs). While this difference is negligible in any practical economic sense, the market reaction showed an increased sensitivity to the risks of a disorderly economic decoupling between the world’s two largest economies that we highlighted yesterday. Neither the US nor China are showing signs of backing down, with President Trump expressing confidence in his tariff plans yesterday, even as he acknowledged potential “transition problems”. US-China concerns outweighed other ostensibly more positive tariff headlines – the EU delaying its previously announced retaliatory tariffs by 90 days, the US beginning formal talks with Vietnam and Politico reporting that Treasury Secretary Scott Bessent was now at the helm of the administration’s trade team.

Back to the market moves, and in the equity space, the S&P 500 (-3.46%) yesterday reversed just over a third of Wednesday’s +9.52% relief spike. This marked a remarkable fifth day in a row with an intra-day range of more than 6% for the S&P. Based on data going back to the 1920s, the only runs longer than this were at the peak of the GFC in October 2008 and during the early pandemic turmoil in March 2020. Underperformance of cyclical stocks saw the NASDAQ (-4.97%) and the Russell 2000 (-4.27%) post even larger declines. The VIX rose by +7.10pts to 40.72.

Despite the risk-off tone, we saw a renewed bond market sell-off, with 10yr Treasury yields closing +9.2bps higher at 4.43% and 30yr yields +13.3bps at 4.87%. Higher yields came as the House narrowly passed the Senate-approved budget outline that envisages cutting taxes by up to $5.3 trillion over a decade, in exchange for only minimal spending cuts. The bond sell-off continued during the US afternoon despite a brief rally following a solid 30yr auction that saw $22bn of bonds issued at 4.813%, -2.6bps below the pre-sale yield. 30yr yields are another +2bps higher this morning, and on course for a +48bps weekly increase, which would be their largest since the 1980s. So there is some déjà vu of the bond market moves that Jim highlighted in his “Danger Zone” CoTD on Wednesday morning (link here) and which were followed by President Trump’s pullback on reciprocal tariffs. As a reminder, our head of US rates strategy Matt Raskin discussed the conditions under which the Fed might intervene to preserve market functioning in a note on Wednesday.

Treasuries had actually rallied earlier on yesterday following a very soft US CPI print for March. Headline inflation (-0.1% mom vs +0.1% expected) saw its largest monthly decline since early Covid restrictions in spring 2020, while core inflation (+0.1% vs +0.3%) saw its smallest monthly rise since January 2021 with the data showing little evidence of price pressures from the early rounds of tariffs. Our US economists did note that the read-through into the Fed’s preferred core PCE measure was not as weak as the headline CPI readings and they will be keeping a close eye on today’s PPI print. See their full reaction here.

The weaker inflation data saw investors increase their expectations for rate cuts, with a 25bps Fed cut being again fully priced in by the June meeting. The Fed pricing did reverse slightly as a host of Fed speakers signaled continued patience on future cuts. Boston Fed President Collins said tariff-related inflation could further delay rate cuts, Chicago Fed President Goolsbee noted that the bar for adjusting rates was a “little higher” with the stagflationary shock from tariffs and Kansas Fed President Schmid said he “would be hesitant” to view the effects of tariffs on inflation as temporary. But with a risk-off tone continuing overnight, the amount of Fed cuts priced by year-end is back up to 92bps this morning, from 80bps this time yesterday.

Overnight in Asia, equity markets are following yesterday’s declines on Wall Street. Japan’s Nikkei, which had seen a +9.13% gain yesterday, is the notable underperformer, down -4.03% as I type. The risk-off mood has also spilled over to rest of the region with the KOSPI (-0.92%) and the S&P/ASX 200 (-1.35%) seeing notable declines. Elsewhere, Chinese markets are broadly stable, with the Hang Seng (+0.56%), the CSI (-0.10%) and the Shanghai Composite (+0.12%) all showing relative composure versus their peers. In the FX space, the risk-off sentiment has seen the Japanese yen soar to around 142.91 against the dollar, a level not seen since October.

In the commodity space, Brent crude oil fell -3.28% yesterday to $63.33/bbl. In addition to the broader risk-off tone, oil prices weren’t helped by the latest monthly EIA report which downgraded expected 2025 global oil demand growth by -400kb/day. On the other hand, copper recovered by another +4.45%, while gold (+3.03% after +3.43% on Wednesday) has seen its biggest two-day move since March 2020. DB’s precious metals analyst Michael Hsueh had outlined his structurally positive gold view in a note on Wednesday (link here).

Earlier yesterday, European equities had seen strong gains, catching up to the late US rebound the previous day. The STOXX 600 (+3.70%) had its best day since March 2022, while the DAX (+4.53%), CAC (+3.83%) and FTSE MIB (+4.73%) posted even larger gains. In the bond space, yields on 10yr bunds (-1.3bps), OATs (-4.0bps) and BTPs (-6.0bps) all saw moderate declines, while gilts (-13.9bps) outperformed as they reversed much of Wednesday’s +17.4bps spike.

To the day ahead now and data releases include the US PPI reading for March along with the University of Michigan’s preliminary consumer sentiment index for April. From central banks, we’ll hear from Fed’s Musalem and Williams. The obvious highlight will be the start of the Q1 earnings season with JPMorgan Chase, Morgan Stanley, Wells Fargo and BlackRock reporting.

Tyler Durden
Fri, 04/11/2025 – 09:21

Bitcoin: Exit-Ramp From Dollar Hegemony

Bitcoin: Exit-Ramp From Dollar Hegemony

Submitted by QTR’s Fringe Finance

The recent selloff in U.S. Treasury bonds—once considered the bedrock of global financial stability—could signal something far deeper than just a market correction.

Yields may not be surging not due to growth optimism — or the basis trade imploding — but also because investors are demanding a higher premium to hold debt issued by a country whose fiscal trajectory is spiraling.

And the trade war has added another layer of geopolitical tension that’s pushing both foreign governments and private institutions to reassess their exposure to dollar-denominated assets.

The long-standing assumption that the U.S. dollar is a safe haven is beginning to crack under the weight of ballooning deficits, weaponized finance, and the political brinksmanship that now routinely defines Washington.

This confluence of market and policy risk is accelerating a quiet but critical exodus from U.S. assets, with foreign central banks reducing their Treasury holdings and global investors seeking alternatives in gold, commodities, and even digital assets like Bitcoin.

The message is clear: the world is beginning to hedge against the dollar.

About a year ago I wrote about one catalyst I thought could ‘standardize’ bitcoin. My idea was the next financial crisis — or the outrage at the ensuing bailout — could drive millions of normal people towards a new perceived ‘safe haven’ like bitcoin.

The phrase “Why I Bitcoin,” which I used as the title of my first article explaining why I was opening up to the idea of bitcoin, came to me instinctively. It echoed something from the 2008 Occupy movement—“Why I Occupy.”

That memory triggered a realization: in the next financial crisis, people could finally have a legitimate, functioning exit ramp from the system in addition to gold: bitcoin.

An “exit ramp” is what so many participants in the GameStop frenzy were unknowingly searching for when they were trying to stick it to Melvin Capital—a decentralized way to opt out of a rigged system.

Back then, people were furious, but they didn’t understand the real enemy. They blamed hedge funds and short sellers instead of the true culprit for their deteriorating quality of life: the Federal Reserve’s monetary policy.

Inflation has made the Fed’s failure more obvious. The Fed printed trillions over the past few years, lied to the public about it being transitory, and now the average American is paying the price through higher costs and eroded savings.

While the rich saw their assets inflate, the rest of us were left behind. I often asked: if the Fed was going to print $7 trillion during Covid, why not divide it equally among all Americans?

But that’s not how the system works—it rewards the elite, socializes losses, and keeps the working class footing the bill. That’s exactly what happened in 2008, and it’s exactly what will happen again when the Fed bails out this basis trade: the Fed will step in to bail out irresponsible leverage from hedge funds, at the cost of the public’s purchasing power.

The difference is, this time, the public will be better informed.

A younger, angrier generation now understands the ideological backbone of Bitcoin. They’ve started to explore Austrian economics and seen through the farce of modern monetary theory. They know inflation is a regressive tax, and they’re fed up with watching toxic companies privatize profits and socialize losses.

This time, when another major “bailout” hits again, there will be no confusion about who’s to blame. And importantly, investors will have both gold and a digital alternative, bitcoin, to seek refuge in.

That realization only deepened recently when I watched dollar assets sell off hard—bonds, equities, commodities—all in tandem. However, gold has been up nearly $100 per day over the last two days and is blowing through all-time highs almost daily now.

The GLD is outperforming the SPY on almost any time horizon dating back almost 5 years now. YTD the GLD is +20.7% versus -10.5% for the SPY. Over the last 12 months, the GLD is up +35.5% versus +2.03% for SPY. And over the last 3 years, the GLD is up +61.1% versus +17.2% for the SPY.

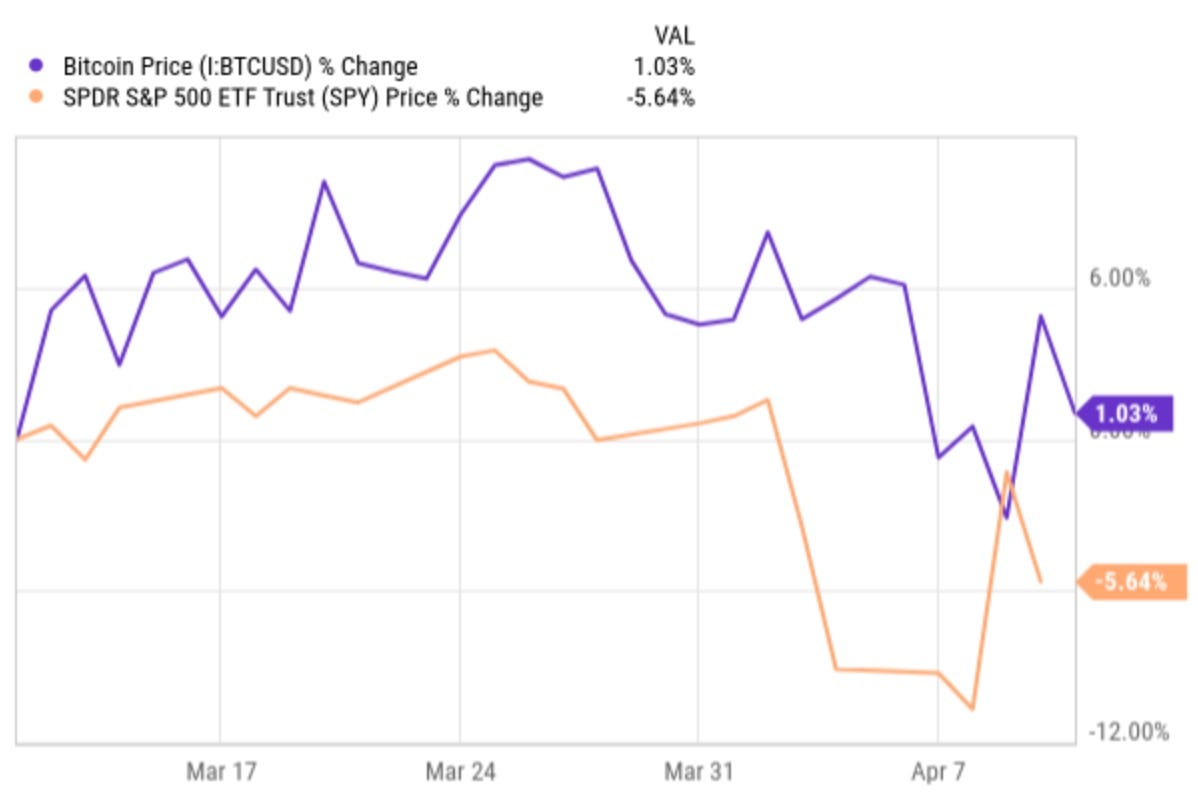
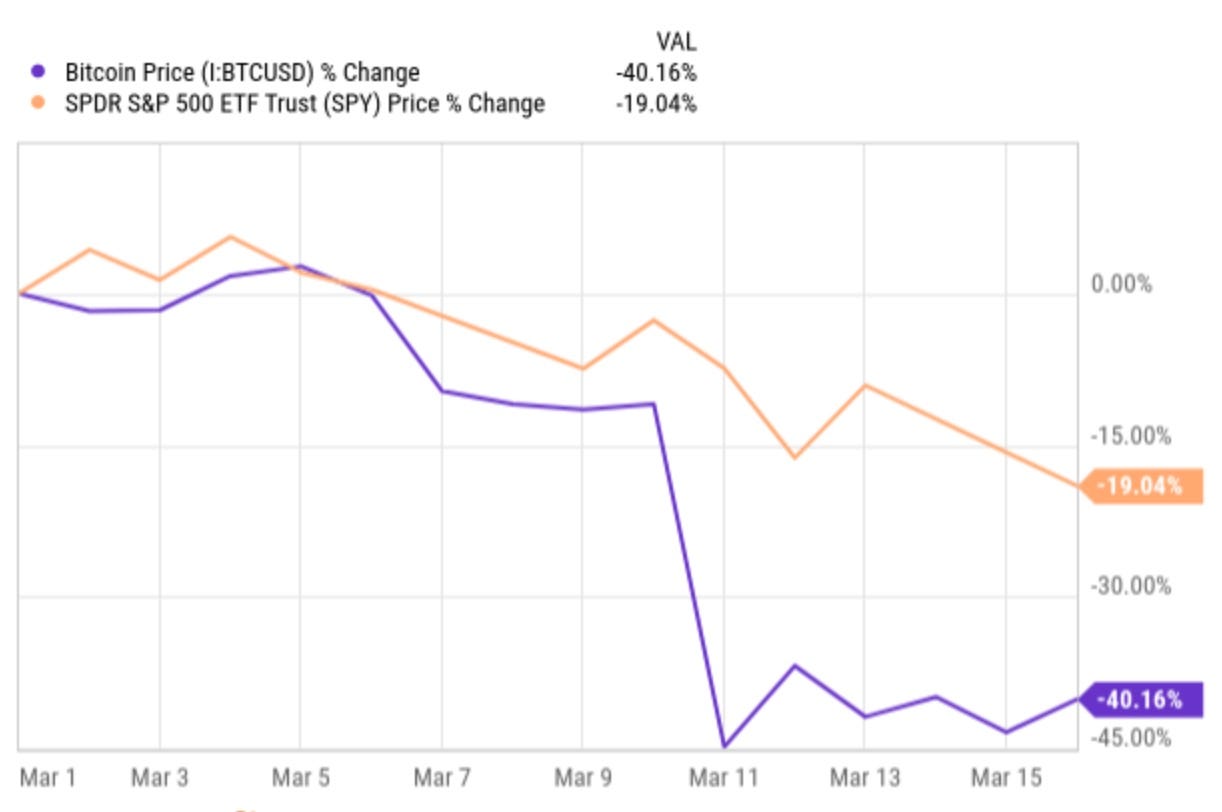
And even bitcoin has held it’s ground the last few weeks with the market volatility. It slipped, but relatively to how the SPY traded, it held up. Usually, bitcoin would be down a multiple of the percentage the NASDAQ and S&P would be. This go round, bitcoin didn’t sell off as much as markets did.

Compare the last month this year…

…to bitcoin far outpacing the S&P’s selloff the first few weeks of March 2020, during the Covid selloff:

To be frank, this last month is the first time I saw Bitcoin not behave like the typical risk-on asset it’s long been lumped in with. It didn’t act like quite the safe haven gold has, but it has firmed up in its beta with the overall market.

I want to be clear: it’s still early, and this trend could reverse on a dime. But this month has felt like a potential break in the pattern—like we might be witnessing the first glimmer of Bitcoin decoupling from risk on, and drifting towards safe haven.

And it may not just be in retail behavior, but potentially also in global capital flows. The selloff in U.S. bonds and the escalation of a trade war are triggering something deeper: a global revaluation of the dollar itself. The once-unquestioned role of U.S. Treasuries as the global safe asset is being called into doubt. Foreign governments and major institutions are pulling back from dollar-denominated assets—not out of preference, but self-preservation.

As deficits explode and Washington turns fiscal irresponsibility into bipartisan policy, trust in the U.S. financial system is deteriorating. That shift isn’t just about inflation anymore. It’s about the loss of global confidence in American stewardship.

And if the world is now searching for an exit ramp from dollar hegemony, just like retail investors have from Wall Street’s rigged game, then both gold and bitcoin could wind up being part of a plan for an international escape hatch.

QTR’s Disclaimer: Please read my full legal disclaimer on my About page here. This post represents my opinions only. In addition, please understand I am an idiot and often get things wrong and lose money. I may own or transact in any names mentioned in this piece at any time without warning. Contributor posts and aggregated posts have been hand selected by me, have not been fact checked and are the opinions of their authors. They are either submitted to QTR by their author, reprinted under a Creative Commons license with my best effort to uphold what the license asks, or with the permission of the author.

This is not a recommendation to buy or sell any stocks or securities, just my opinions. I often lose money on positions I trade/invest in. I may add any name mentioned in this article and sell any name mentioned in this piece at any time, without further warning. None of this is a solicitation to buy or sell securities. I may or may not own names I write about and are watching. Sometimes I’m bullish without owning things, sometimes I’m bearish and do own things. Just assume my positions could be exactly the opposite of what you think they are just in case. If I’m long I could quickly be short and vice versa. I won’t update my positions. All positions can change immediately as soon as I publish this, with or without notice and at any point I can be long, short or neutral on any position. You are on your own. Do not make decisions based on my blog. I exist on the fringe. The publisher does not guarantee the accuracy or completeness of the information provided in this page. These are not the opinions of any of my employers, partners, or associates. I did my best to be honest about my disclosures but can’t guarantee I am right; I write these posts after a couple beers sometimes. I edit after my posts are published because I’m impatient and lazy, so if you see a typo, check back in a half hour. Also, I just straight up get shit wrong a lot. I mention it twice because it’s that important.

Tyler Durden
Fri, 04/11/2025 – 09:05

Energy Secretary Hints At Military Action Against Iran’s Global Oil Exports

Energy Secretary Hints At Military Action Against Iran’s Global Oil Exports

Amid Trump’s anti-Iran ‘maximum pressure’ and the current climate of the White House telling Tehran to negotiate a new nuclear deal or else bombs could fly, fresh statements from US Energy Secretary Chris Wright just added fuel to the fire.

Wright while on a trip to Abu Dhabi told Reuters that the United States is able to step up pressure on Iran and stop its oil exports altogether with force if need be, in order to get Tehran to the table on its nuclear program.

US Department of Energy Secretary Chris Wright, via SourceNM

He described provocatively that the US “can follow the ships from Iran” as “we know where they go” and thus the Islamic Republic’s export of oil can be fully stopped.

Crucially he added that in his view the market can “tolerate squeezing out” of Iran oil exports if this full-court press option is pursued.

This would necessarily involve US militarization of shipping lates and strategic oil chokepoints not only in the Middle East but in southeast Asia, while stepping up reconnaissance operations. 

The US has already long monitored and condemned Iran’s ‘shadow fleet’ activity and efforts to disguise Iranian oil shipments. China has been the largest customer by far, especially since 2022 when Tehran in the face of expanding sanctions upped its exports with nearly 300 ‘dark fleet’ tankers also going to places like Venezuela, and sanctions-decimated Syria (under Iran-ally Assad at the time).

“The Iranian regime relies on its network of unscrupulous shippers and brokers like Brar and his companies to enable its oil sales and finance its destabilizing activities,” Treasury Secretary Scott Bessen said Thursday, in rolling out yet more counter-Iran actions to crackdown on its oil and petroleum products.

The new Treasury measures involve the following:

The U.S. Department of the Treasury has unveiled sanctions against a sophisticated maritime network responsible for smuggling hundreds of millions of dollars worth of Iranian petroleum, targeting UAE-based shipping magnate Jugwinder Singh Brar and his fleet of nearly 30 vessels, many of which operate as part of Iran’s “shadow fleet.”

Meanwhile, the U.S. Department of State has simultaneously sanctioned a Chinese terminal operator, along with two additional vessels, that feeds product to a co-called “teapot” refinery.

Operating through UAE-based companies Prime Tankers LLC and Glory International FZ-LLC, the Treasury’s Office of Foreign Assets Control (OFAC) alleges Brar’s network employed an intricate web of smaller Handysize tankers for coastal operations, conducting high-risk ship-to-ship (STS) transfers in waters off Iraq, Iran, the UAE, and the Gulf of Oman.

Oil prices dropped slightly Friday upon China announcing its retaliation against the US by raising tariffs on US goods to 125%. The ongoing US-China trade and tariff tit-for-tat has dented demand for oil amid a climate of fear and uncertainty, pushing prices down.

Commenting further on Wright’s Friday words, Reuters notes that he said “there will be a positive outlook for oil demand and supply in the next few years under President Donald Trump’s policies, and the concern of markets about economic growth will be proven wrong.”

Tyler Durden
Fri, 04/11/2025 – 08:45

Producer Prices Plunged Most Since COVID In March

Producer Prices Plunged Most Since COVID In March

Following the cooler-than-expected consumer price inflation print, producers prices were expected to accelerate modestly in March. The analysts were totally wrong…

Headline PPI fell (yes fell) 0.4% MoM (dramatically cooler than the 0.2% MoM rise expected), dragging the headline index down to +2.7% YoY…

Source: Bloomberg

That is the lowest MoM print since COVID lockdowns and lowest YoY since Sept 2024… as Energy and Services costs tumble…

Core PPI also saw deflation (-0.1% MoM) with the YoY rise slowing to +3.3%…

In March, over 70 percent of the decrease in the index for final demand can be traced to prices for final demand goods, which fell 0.9 percent. 

The index for final demand services declined 0.2 percent.

Final demand goods: Prices for final demand goods moved down 0.9 percent in March, the largest decrease since falling 1.4 percent in October 2023. Over three-fourths of the March decline is attributable to a 4.0-percent drop in the index for final demand energy. Prices for final demand foods decreased 2.1 percent. In contrast, the index for final demand goods less foods and energy rose 0.3 percent.

Product detail: Two-thirds of the March decline in the index for final demand goods can be traced to an 11.1-percent drop in prices for gasoline. The indexes for chicken eggs, beef and veal, fresh and dry vegetables, diesel fuel, and jet fuel also moved lower. Conversely, prices for steel mill products increased 7.1 percent. The indexes for residential electric power and for processed young chickens also advanced.

Final demand services: Prices for final demand services fell 0.2 percent in March, the largest decline since moving down 0.2 percent in July 2024. Leading the March decrease, margins for final demand trade services dropped 0.7 percent. (Trade indexes measure changes in margins received by wholesalers and retailers.) Prices for final demand transportation and warehousing services moved down 0.6 percent. In contrast, the index for final demand services less trade, transportation, and warehousing increased 0.1 percent.

Product detail: A 1.3-percent decrease in the index for machinery and vehicle wholesaling was a major factor in the March decline in prices for final demand services. The indexes for airline passenger services; food retailing; apparel, jewelry, footwear, and accessories retailing; automobiles retailing (partial); and guestroom rental also moved lower. Conversely, prices for legal services rose 1.5 percent. The indexes for chemicals and allied products wholesaling and for long-distance motor carrying also advanced.

Margin pressure remains on American corporations…

Finally, energy prices are set to drag CPI and PPI even lower in the next month or so…

But, but, but… the PhDs said tariffs were inflationary!!

Tyler Durden
Fri, 04/11/2025 – 08:37