69.3 F
Chicago
Friday, October 9, 2026
Home Blog Page 186

Initial Jobless Claims Remain Near 57-Year Lows

Initial Jobless Claims Remain Near 57-Year Lows

The number of Americans filing for unemployment benefits for the first time held below 200k again last week…

…basically hovering at its lowest since 1969…

Pennsylvania and New Jersey saw claims rise the most last week while North Carolina and Ohio saw the biggest decline…

Continuing jobless claims ticked up, just above 1.8 million Americans…

After ADP’s disappointing job additions, it appears the ‘low hire, no fire’ economy is entrenched.

Will tomorrow’s payrolls print confirm that?

Tyler Durden
Thu, 08/06/2026 – 08:40

“In Uncharted Waters”: The SpaceX Lockup Expiration Begins

“In Uncharted Waters”: The SpaceX Lockup Expiration Begins

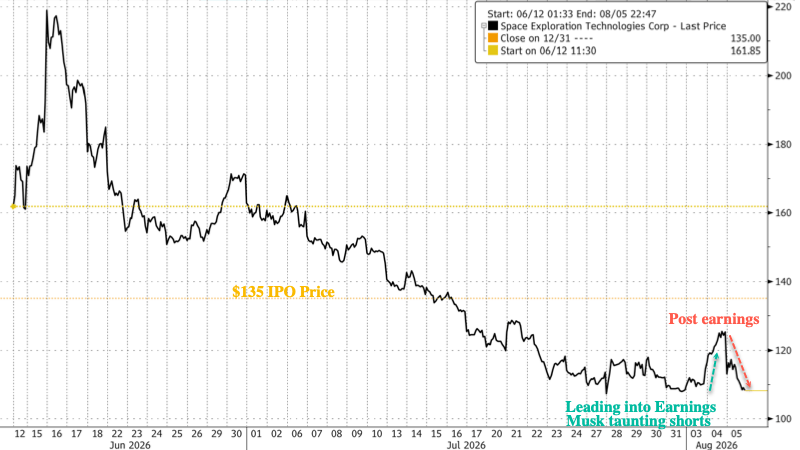
SpaceX shares are hovering near record lows after the company’s first earnings report as a publicly traded company beat expectations. However, as we noted Tuesday, Thursday’s first lockup expiration is likely the more significant near-term catalyst than earnings.

The first insider share lockup expires today and more than doubles the float from about 639 million to 1.55 billion. That means about 911.5 million shares of new supply are inbound for the market.

HSBC analysts Nicolas Cote-Colisson and Charlie Rothbarth recently mapped out the staggered lockup-expiration schedule:

SpaceX’s IPO prospectus indicated that 555,555,555 shares would be issued to constitute the free float. We understand that the underwriters have exercised their option to purchase additional shares of Class A common stock in full, so the free float would have extended to 638,888,888 shares.

We identify 4,678m locked up shares and another 8,160m shares subject to an extended lockup. Based on the information provided by the SpaceX prospectus dated 12 June 2026, we calculate that 912m shares could be available for sale in the public market from 6 August 2026, compared with 640m shares constituting the free float at present. The free float would increase from 4.9% at present to 11.8%.

Another release event could occur on the same day depending on SpaceX shares trading above USD175.5 for at least five of 10 consecutive trading days ending on 4 August 2026 (i.e. between 22 July and 4 August 2026). The table below provides further event/date triggers for subsequent share releases.

Those restricted shares are currently owned by funds and individuals that have participated in the private rounds of financing and may be inclined to keep their shares. But we think investors should be aware of this.

Lockup expiration roadmap:

via HSBC

“We’ve never seen anything like it. We’ve never seen anything of this scale, and we’ve never seen a lockup phased in this way,” Peter Singlehurst, head of Baillie Gifford’s private companies team, which first invested in Musk’s company in 2018, told Bloomberg. “We’re in uncharted waters.”

The incoming wave of supply has attracted short sellers to pile bearish bets on SpaceX. Data compiled by S3 Partners through Tuesday’s close shows that 35% of the float is sold short.

That short interest is so concerning to Musk that he even felt compelled to comment and taunt bears hours before earnings on Tuesday.

“I try to warn them, but they just double down…,” Musk wrote in an X post responding to a report citing proprietary data from S3 Partners.

Shares initially rallied following Musk’s comments but have since reversed course, sliding back toward the $109 level. On Monday, the stock touched a record low of $104.83, leaving it 22.4% below its $135 offering price and 53.5% beneath its June peak of $225. The selloff has erased more than $1 trillion in market value.

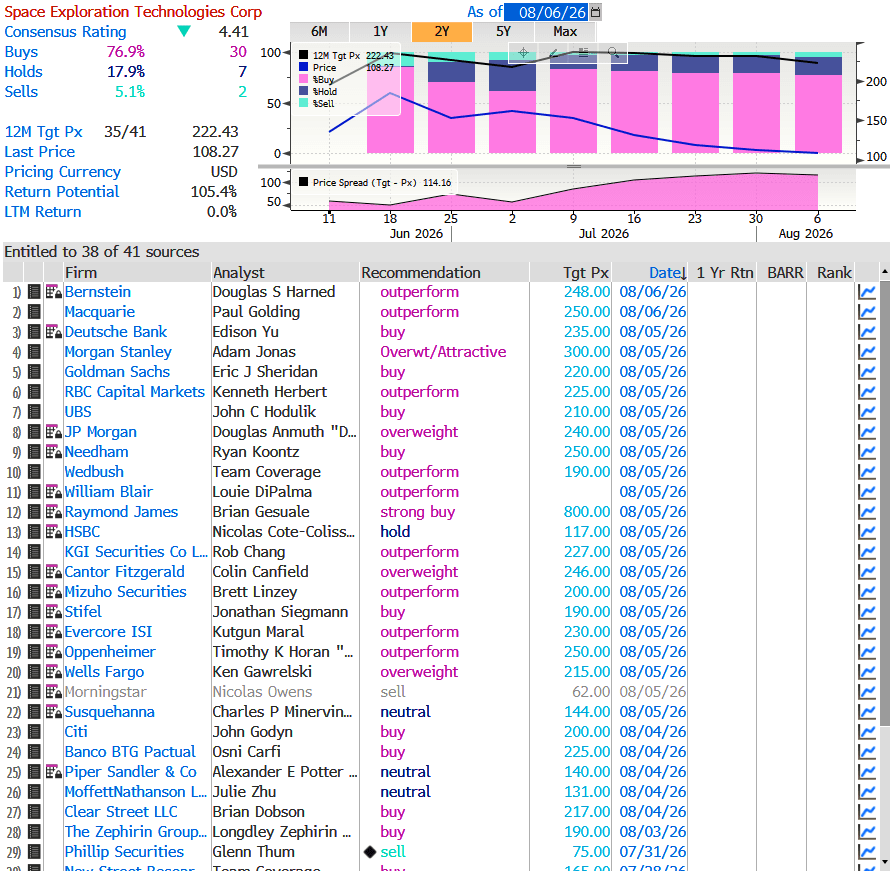
Here’s how Wall Street currently views the stock:

A large trading desk told us earlier this week that its team has yet to initiate any buy orders but may begin considering a long position once the first lockup expiration is underway.

Tyler Durden
Thu, 08/06/2026 – 07:45

Researcher Finds Backdoor In Chinese-Made Routers Sold Worldwide

Researcher Finds Backdoor In Chinese-Made Routers Sold Worldwide

Authored by Evgenia Filimianova via The Epoch Times,

Cybersecurity company VulnCheck said on Aug. 5 that it has found that more than 20 models of a Chinese-made wireless router sold worldwide contain a hidden backdoor that could allow unauthorized access to devices connected to the network.

File photograph of ethernet cables running from the back of a router in Washington on March 21, 2019. Mandel Ngan/AFP/Getty Images

The finding adds to growing Western concerns about cybersecurity risks posed by Chinese-made networking equipment. Western governments have warned for years about hackers exploiting such devices, and U.S. regulators moved this year to restrict imports of foreign-made routers.

Jacob Baines, chief technology officer at VulnCheck, who found the backdoor, said in a blog post that the vulnerability, dubbed “Endlessdoors,” affects routers manufactured by Shenzhen Zhibotong Electronics Co. and sold under the Zbtlink and Wiflyer brand names.

Routers serve as the gateway between internet-connected devices and the wider internet, directing traffic to computers, smartphones, smart televisions, cameras, and other connected equipment. Because routers manage internet traffic between connected devices and the wider internet, vulnerabilities affecting them can expose entire home or business networks.

Baines estimates that at least 100,000 such routers are deployed worldwide. The backdoor Baines discovered automatically “dials the same tiny set of endpoints,” Baines said in a blog post on the company’s website. Whoever controls those domains could take control of the router and potentially use it to access other devices on the same network, he said.

Baines said most people who order this router and use it for their small business or home office would likely have no clue that it could allow this sort of access.

“If I have it in my lab, in my lab at my university, you just invited them straight into your lab and they can roam the network as they choose,” Baines said. “The capabilities are devastating.”

Western governments have warned about Chinese-linked hackers abusing small office and home office routers and other internet devices to gain access to networks for later intrusions as well as cyberespionage.

Beijing regularly denies condoning or carrying out cyberattacks or cyberespionage.

The Epoch Times reached out to Shenzhen Zhibotong Electronics/Zbtlink for comment but didn’t receive a response by publication time.

US Scrutiny

The findings come as U.S. officials continue to increase scrutiny of networking equipment manufactured by companies with links to China.

In March, the Federal Communications Commission (FCC) announced restrictions on imports of certain foreign-made consumer routers over national security concerns.

The FCC said in a March 23 statement that foreign-made routers had been exploited by malicious actors to target U.S. households, disrupt networks, conduct espionage, and steal intellectual property.

“Foreign-made routers were also involved in the Volt, Flax, and Salt Typhoon cyberattacks targeting vital U.S. infrastructure,” it added.

In February, Texas filed a lawsuit against TP-Link Systems, alleging the networking company exposed American consumers’ devices to Chinese regime access.

In response to the lawsuit, TP-Link Systems, which was spun off from a Chinese company, said it would “vigorously defend” its reputation, called the allegations “without merit,” and added that the Chinese communist regime has no form of ownership or control over the company, its products, or user data.

Risk for Networks

VulnCheck on Wednesday published a list of 20 affected models and urged organizations to determine whether any remain deployed in their networks.

VulnCheck said users should identify affected devices by their model numbers rather than the brand name because Zbtlink manufactures routers for other companies under original equipment manufacturer (OEM) and original design manufacturer (ODM) agreements.

The company recommended replacing affected devices where possible, restricting remote management access, and installing firmware updates if security fixes become available.

In this photo illustration, a hacker types on a computer keyboard on May 13, 2025. Oleksii Pydsosonnii/The Epoch Times

Tyler Durden
Thu, 08/06/2026 – 07:20

“If Clarity Dies, Democrats Killed It”: Lummis Urges Senate To Act On Crypto Bill Before Recess

“If Clarity Dies, Democrats Killed It”: Lummis Urges Senate To Act On Crypto Bill Before Recess

Pro-bitcoin Senator Cynthia Lummis has said that bipartisan work is going into the crypto Clarity Act but warned that some lawmakers are still making unreasonable demands.  

The Republican, speaking to Fox Business Wednesday, said that she had been working with Democratic lawmakers into the night to get the bill over the line. 

But, as Bitcoin Magazine’s Mathew Di Salvo reports, she said that some Democrats were still dragging their feet on the bill. Lawmakers are pushing to get a vote on the crypto market structure bill before the Senate goes to recess.

“The president agreed to an ethics provision that no president has ever agreed to,” Lummis said.

“He’s gone farther to protect ethics than any president in history — yet the Democrats do want more. Their proposal is in front of the president now, and we’ll see what he does.”

She added:

“We’re going to vote on it. If it dies, it’s going to be because the Democrats kill it. I’ve bent over backwards for 11 months, to give them as much as we can possibly give them to regulate this industry.”

The Clarity Act has been in a deadlock for much of 2026, partially because the banking lobby raised concerns over crypto companies allowing clients to earn stablecoin yield. 

An updated bill of the Clarity Act was introduced in July addressing concerns around ethics; it now bans government officials and their families from issuing or promoting crypto. 

Democrats have criticized President Trump’s family crypto business ventures. The White House has always said there have been no conflicts of interest. 

A group of Democrats in July said the bill needs work. 

Major financial institutions like Fidelity and BlackRock, and law enforcement organizations have thrown their weight behind the new bill, 

If passed, the Clarity Act would create a regulatory framework for the U.S. cryptocurrency market.

Tyler Durden
Thu, 08/06/2026 – 06:55

EU To Use $1.62 Billion In Interest From Frozen Russian Assets To Support Ukraine

EU To Use $1.62 Billion In Interest From Frozen Russian Assets To Support Ukraine

Authored by Victoria Friedman via The Epoch Times,

The European Union will use $1.62 billion accumulated from interest on frozen Russian assets to support Ukraine, the union’s executive branch has said.

European Commission President Ursula von der Leyen speaks during a news conference as part of the European Council meeting to discuss Ukraine, European defense, recent developments in the Middle East, competitiveness, housing, and migration, in Brussels, Belgium, on Oct. 23, 2025. Nicolas Tucat/AFP via Getty Images

The European Commission said in an Aug. 4 statement that the funds, transferred to the bloc on Monday, came from the immobilized assets of Russia’s central bank being held by the Central Securities Depositories in the EU.

This was the fifth such transfer of its kind, with the seized assets having generated a total of $9.23 billion in interest.

European Commission President Ursula von der Leyen said that Moscow “must pay for the destruction it has caused. And we are using the proceeds from the immobilised Russian assets to make sure it does.”

“We are making a further [$1.62] billion of them available to Ukraine. This will support Ukraine’s continued resistance against Russia’s illegal war,” she said.

The funds are from assets immobilized under EU sanctions, which were imposed in response to Russia’s invasion of Ukraine.

Billions Frozen

The majority of frozen Russian assets are being held by Euroclear, a financial market infrastructure group based in Belgium. Euroclear holds around $213 billion in assets, with another $29 billion held predominantly in France, Germany, Sweden, and Cyprus, according to figures quoted by the European Council in December 2025.

The EU says that while the assets are immobilized, the interest does not belong to Russia, with the European Council deciding the net profits should go to support Ukraine.

Moscow has previously called funds from Russian frozen assets that are given to Ukraine “stolen money.”

Russian Foreign Minister Sergey Lavrov said on June 24: “It is one thing when you are free to dispose of your assets and receive the interest stipulated by the agreement with Euroclear, while everything above that belongs to them. But you are still free to manage your own funds.

“When your assets are frozen and they tell you, ‘You sit tight for now, while we make additional profits here and hand them all over to Ukraine,’ this is a very serious matter from the standpoint of the West’s attempts to convince everyone that the world order they created and that functioned through modern institutions of global governance – the IMF, the World Trade Organization – remains relevant.”

The vast majority of the proceeds – 95 percent – will be distributed to the Ukraine Loan Cooperation Mechanism, which provides support to Ukraine in repaying financial assistance loans and loans provided by the G7. The remaining 5 percent provides funding for military and defense needs.

Russian Sanctions

Last week, EU members agreed on the bloc’s 21st round of sanctions against Russia, mainly targeting financial institutions, in a bid to weaken Moscow’s economy and affect its war effort.

Von der Leyen said on July 23 that the bloc was adding 32 Russian banks to its transaction-ban list, as well as oil trading platforms and cryptocurrency firms.

The package also freezes the oil price cap for one year “so that the Russian war machine does not benefit from market shocks,” she said.

In response, the Russian Permanent Mission said that “European bureaucracy, disregarding the economic costs, continues to pursue its course of escalating confrontation with Russia.”

The July 23 statement said that the restrictions “will further aggravate the already acute social and economic problems in the European Union,” which the mission said was due to the bloc’s decision to drop Russian energy supplies and to continue to spend billions on aid to Ukraine, “all against the backdrop of instability in global energy markets due to the escalation of the conflict in the Middle East.”

“We reaffirm that the hostile unilateral coercive measures of the European Union against our country will be met with an effective and due response from Russia,” the mission said.

Tyler Durden
Thu, 08/06/2026 – 06:30

BMW Job Cuts And The Emerging German-French Industrial Strategy

BMW Job Cuts And The Emerging German-French Industrial Strategy

Submitted by Thomas Kolbe

Will German policy paralysis and French protectionism save Germany’s automakers? Unlikely, since Paris and Berlin are pursuing similar ideological goals. Everything points toward the expansion of a green state-run economy. On that, there is agreement. The concerns of private enterprise are secondary.

Given the dramatic situation, automakers would probably take even the most hopeless escape route in an attempt to escape the downward spiral. This has now also caught up with the previously remarkably resilient BMW Group: Just last week, Volkswagen announced plans to cut 120,000 jobs, Porsche has to eliminate 5,000 positions, and Mercedes has already parted ways with 5,500 employees. Now BMW is following suit, announcing that it will have to part with 8,000 of its 154,000 employees. The pressure to act is considerable. In the second quarter, the Munich-based group’s profit plunged by a staggering 35 percent year-on-year. In the core automotive business, the company lost 60 percent of its earnings.

BMW’s workforce reduction is supposed to take place quietly: through natural employee turnover and a voluntary severance program. The company wants to avoid compulsory redundancies in Munich.

The initiative will begin in October and run until 2027, specifically targeting employees outside production. Between 30,000 and 40,000 administrative employees at BMW are expected to receive an offer to leave the company – in return, BMW will expand its employment guarantee for the future: compulsory redundancies in Germany are to be ruled out even if the company falls into the red.

Whether this policy can ultimately be maintained when push comes to shove remains to be seen. In any case, entire layers of management are to be eliminated and departments merged – not least because BMW has concluded that artificial intelligence can increase operational efficiency.

Efficiency programs in Germany’s automotive industry are unavoidable. Excessive energy costs are weighing on companies’ results, alongside Brussels regulation and the political campaign against the combustion engine, which still dominates the market. It is impossible to keep pace with global competition from the domestic production base. According to consultancy EY, German automakers and their suppliers lost 50,000 jobs within a single year. There is no sign of a reversal: Germany’s automotive industry association VDA now expects 225,000 jobs to disappear across the sector by 2035, some 35,000 more than its estimate just a few months ago.

And what is politics doing? It clings doggedly to the ideology of the Green Deal, regardless of what it may cost citizens – with the state, financed through taxes and debt, remaining as an employer of last resort if necessary. That, in a nutshell, has so far been the position of the political leadership of the European Union.

Euro-corporatism has grown far beyond its limits. Billions flow from taxpayers to Brussels and return, rebranded as climate bonuses, credit guarantees and funding allocations for dubious start-ups, into the channels of the green transformation machine. This may be the most extreme case of politically driven destruction of capital. The decline of European industry is inevitable. It is impossible to conceive of an economy that could withstand the subversive barrage of European ideologues over an extended period.

Bewildered and incredulous, they stand in Berlin and Paris before the ruins of their own work. Since political circles operate under an imperative of infallibility, every last resource is being mobilized to continue the prevailing policy. At the German-French Council of Ministers in Germany in mid-July, Emmanuel Macron and Friedrich Merz reaffirmed their common industrial policy agenda. The two governments subsequently instructed their negotiators to work out a broader compromise: France wants to shield European industry more strongly from foreign competition, while Germany is primarily seeking a way out of the crisis engulfing its automotive industry.

Too much money is flowing out: For Chinese EV manufacturers or solar-panel producers, Brussels’ subsidy machine is a welcome bonus. Countless businesses are effectively living off the naivety of European policymakers. It pays to put up the umbrella for subsidies when EU bureaucrats and political fools are scattering taxpayers’ money with both hands.

And so a German-French bargain is now supposed to bring relief in the crisis. Berlin would support the French demand for a tougher “Made in Europe” model for industrial funding. At the heart of the strategy is the Industrial Accelerator Act, or IAA, presented by the European Commission in March. It is supposed to apply in public tenders and funding programs and define requirements for applicants in advance. Naturally, CO₂-free products and manufacturing processes are to receive priority in the subsidy jungle.

Subsidies will continue to flow above all to decarbonization champions. But there is nothing remotely market-oriented about this; the subsidy frenzy merely promotes cronyism and a subsidy-hunter mentality in the EU. Brussels also wants to define in the future which third countries qualify as so-called “trusted partners.” In doing so, the bureaucracy is intervening massively in the existing supply chains of European companies. “Made in Europe” – a crude form of industrial policy, with bureaucrats at the helm who can, at the behest of politicians, give suppliers the thumbs-down and shut them out, regardless of the consequences this may have for European businesses.

Berlin had rejected this practice until now. But given the situation in the automotive sector and the French concessions in this area, the German government now appears open to a “Made in Europe” strategy.

The other side of the deal is this: France is signaling a willingness to handle the 2035 combustion-engine phaseout more flexibly. It will ultimately come down to negotiating CO₂ consumption quotas more flexibly and assigning a different weight to investments in hybrid drivetrains in the CO₂ balance. In short: business as usual in the same outfit, merely unbuttoned at one point.

Ways out of the crisis mean the end of the current policy. Technological openness for business, competition in a free, deregulated single market – politics contributes nothing to solving the crisis. Quite the contrary. The bargain between Paris and Berlin would appear protectionist from the outside, but could provide companies with some short-term breathing room through more efficient allocation of subsidies. In doing so, political pressure is removed to break with the fatal ideological design of the Green Deal.

Without a structural break with the ideological present, there will be no recovery. The therapy that Emmanuel Macron and Friedrich Merz intend to prescribe for the European automotive industry will ultimately prove to be an injection of the same poison that has turned the entire EU economy into an economic cripple.

* * * 

About the author Thomas Kolbe, a German graduate economist, has worked for over 25 years, he has worked as a journalist and media producer for clients from various industries and business associations. As a publicist, he focuses on economic processes and observes geopolitical events from the perspective of the capital markets. His publications follow a philosophy that focuses on the individual and their right to self-determination.


Tyler Durden
Thu, 08/06/2026 – 03:30

This Is The Income Needed To Be ‘Happy’ Around The World

This Is The Income Needed To Be ‘Happy’ Around The World

In most countries, the average worker still earns less than the income researchers associate with peak reported well-being.

Research on income and well-being has identified a “satiation point,” an income level beyond which additional earnings no longer improve reported happiness. But how close does the average worker come to reaching that threshold?

An analysis from Remitly calculated the price of happiness in economies around the world and compared it with average local wages.

This graphic, via Visual Capitalist’s Niccolo Conte, ranks the 50 countries where average annual income comes closest to that threshold.

The analysis is based on Purdue University‘s income satiation research and data from the International Labour Organization, adjusted for purchasing power, inflation, and currency exchange rates.

Slovenia Is the Only Country Where Wages Exceed the Threshold

Slovenia stands alone among the 50 countries analyzed. Its average wage of $42,800 is 16.3% higher than its estimated price of happiness of $36,800, meaning the typical worker earns more than the income associated with peak reported well-being.

No other country crosses that line. Luxembourg comes closest, with wages covering 92.8% of its $118,400 happiness threshold, followed by Estonia (90.5%), Singapore (90.0%), and Lithuania (89.2%).

The data table below shows the average annual wage and price of happiness in each country, along with how close wages come to reaching that threshold:

Rank Country Average Annual Wage Price of Happiness Wage as % of Price of Happiness
1 🇸🇮 Slovenia $37,000 $43,000 116.3%
2 🇱🇺 Luxembourg $110,000 $118,000 92.8%
3 🇪🇪 Estonia $38,000 $42,000 90.5%
4 🇸🇬 Singapore $49,000 $55,000 90.0%
5 🇱🇹 Lithuania $30,000 $33,000 89.2%
6 🇨🇿 Czechia $33,000 $38,000 87.8%
7 🇱🇻 Latvia $30,000 $36,000 84.7%
8 🇬🇷 Greece $28,000 $35,000 79.7%
9 🇧🇪 Belgium $88,000 $111,000 79.1%
10 🇷🇴 Romania $21,000 $27,000 76.3%
11 🇵🇱 Poland $24,000 $32,000 74.5%
12 🇩🇰 Denmark $82,000 $122,000 66.8%
13 🇲🇹 Malta $54,000 $81,000 66.2%
14 🇳🇱 Netherlands $76,000 $117,000 64.8%
15 🇳🇴 Norway $77,000 $121,000 64.2%
16 🇩🇪 Germany $67,000 $106,000 63.1%
17 🇮🇪 Ireland $67,000 $109,000 61.4%
18 🇨🇱 Chile $13,000 $22,000 60.9%
19 🇦🇹 Austria $70,000 $115,000 60.6%
20 🇫🇮 Finland $69,000 $116,000 59.2%
21 🇲🇪 Montenegro $14,000 $24,000 58.4%
22 🇫🇷 France $59,000 $104,000 57.4%
23 🇨🇭 Switzerland $87,000 $155,000 56.4%
24 🇷🇸 Serbia $15,000 $27,000 56.2%
25 🇺🇸 United States $75,000 $135,000 55.8%
26 🇨🇷 Costa Rica $16,000 $29,000 54.1%
27 🇧🇦 Bosnia and Herzegovina $12,000 $23,000 53.0%
28 🇭🇺 Hungary $16,000 $30,000 52.3%
29 🇶🇦 Qatar $42,000 $82,000 51.2%
30 🇮🇹 Italy $46,000 $94,000 49.2%
31 🇸🇰 Slovakia $19,000 $39,000 48.9%
32 🇪🇸 Spain $43,000 $88,000 48.4%
33 🇰🇷 South Korea $35,000 $74,000 48.0%
34 🇸🇪 Sweden $56,000 $118,000 47.4%
35 🇨🇦 Canada $51,000 $114,000 44.4%
36 🇺🇾 Uruguay $15,000 $35,000 43.9%
37 🇲🇺 Mauritius $8,000 $19,000 43.2%
38 🇨🇾 Cyprus $37,000 $94,000 39.4%
39 🇦🇺 Australia $59,000 $161,000 36.6%
40 🇧🇷 Brazil $8,000 $21,000 36.4%
41 🇧🇴 Bolivia $6,000 $15,000 36.1%
42 🇦🇷 Argentina $7,000 $20,000 36.1%
43 🇬🇧 United Kingdom $43,000 $120,000 35.9%
44 🇸🇦 Saudi Arabia $23,000 $65,000 35.5%
45 🇦🇱 Albania $10,000 $28,000 34.8%
46 🇨🇴 Colombia $6,000 $18,000 34.7%
47 🇩🇴 Dominican Republic $6,000 $18,000 34.0%
48 🇳🇿 New Zealand $47,000 $137,000 34.0%
49 🇵🇾 Paraguay $6,000 $19,000 33.7%
50 🇪🇨 Ecuador $7,000 $20,000 32.9%

Central and Eastern European countries occupy seven of the top 11 spots, including Estonia, Lithuania, Czechia, Latvia, Greece, Romania, and Poland.

Their wages are modest by global standards, but their estimated happiness thresholds are also comparatively low, keeping the gap between the two smaller. A similar pattern appears in Where Wages Go Furthest Around the World, where several of the same economies rank highly for purchasing power.

High Wages Do Not Guarantee a Smaller Gap

The United States has the third-highest average wage in the study at $75,300, but it also has one of the highest prices of happiness at $134,800. As a result, wages cover just 55.8% of the threshold.

Australia has the highest price of happiness in the ranking at $161,300, more than double its average wage of $59,000. With wages covering 36.6% of the threshold, the country ranks 39th overall.

The United Kingdom (35.9%), Canada (44.4%), and New Zealand (34.0%) show a similar pattern. Despite relatively high wages, workers in these countries remain further from the income associated with peak well-being than those in several lower-wage economies in Central and Eastern Europe.

Ecuador ranks last among the 50 countries measured, with an average wage of $6,500 covering 32.9% of its $19,700 price of happiness.

If you enjoyed today’s post, check out Money Can Buy Happiness After All on Voronoi.

Tyler Durden
Thu, 08/06/2026 – 02:45

Why On Earth Are They Doing This?

Why On Earth Are They Doing This?

Authored by Steve Watson via Modernity News,

The Spanish Red Cross is treating the military-age men who swam around the border fence and stormed Ceuta like victims of an earthquake.

Volunteers in red vests are lining up on the sand at Playa del Trampolín, handing out bread, milk, biscuits, water, cans of tuna and pastries to the thousands who remain after last week’s deliberate mass invasion from Morocco. Police stand by to keep the queues orderly while the same people who refused to go home sit and eat.

This is not a natural disaster. These men crossed into Spanish territory because the opportunity was created for them. There is nothing stopping Spanish authorities from sending them straight back. Instead the humanitarian apparatus has arrived with supplies.

Cadena SER and local outlets confirmed the first organised distribution of food since the crisis began. Cruz Roja and the local branch of Cooperación Sur-Sur handed out the packages to around 2,000 migrants, the majority from sub-Saharan Africa.

National Police managed the lines so the recipients stayed seated until their turn, then returned to the beach to eat. One Nigerian man named Genesis told reporters he was “happy to finally have something to eat and drink.” He said he had been trying to cross for months and now hopes for asylum.

A Sudanese man named Malik Alher said he had gone five days without food, then added that he wants to “learn Spanish, live in Madrid and work in a supermarket.”

The volunteers doing the handing-out look exactly like the usual crowd: white European leftist women. Locals watching the scene are furious, and for good reason. Feeding the people who just overran your city does not encourage them to leave.

This comes after Spanish officials spent days insisting the problem had solved itself. Foreign Minister José Manuel Albares claimed the “practical totality” of those who entered had returned to Morocco.

The Spanish Embassy in London repeated the line. Reality on the ground never matched the press releases. Streets remained full, facilities were stormed, and thousands simply stayed put on the beaches and around the CETI reception centre.

Local estimates of those left behind ranged from 2,000 to 15,000. But it’s anyone’s guess. Many of the remaining group are now openly declaring they will not go back. They are waiting for the next step toward the Spanish mainland and the wider European welfare systems.

Some, have already been sent to mainland Spain.

Vox leader Santiago Abascal has called the episode an “invasion and an act of war promoted by Morocco and allowed by Sánchez.” He demanded the prime minister face legal proceedings.

The People’s Party has accused Sánchez of being on holiday while sovereignty was tested. Ceuta’s own president Juan Jesús Vivas described the situation as “absolutely unsustainable” for a city of just 83,000.

Handing out free meals does not change the fundamental facts. These men were not shipwrecked, they did not come from a war zone. They walked and swam into Spanish territory in a coordinated surge that Morocco facilitated and Spain failed to stop.

Every ration distributed on that beach signals that the cost of illegal entry will be met with care packages rather than immediate removal. Carrots do not deter the next wave. Only the credible threat of being sent straight home does.

Spain’s government can still choose enforcement over theatre. Until it does, the Red Cross will keep unpacking boxes for the people who invaded, and the residents of Ceuta will keep watching their city turned into a holding pen for those who refuse to leave.

Your support is crucial in helping us defeat mass censorship. Please consider donating via Locals or check out our unique merch. Follow us on X @ModernityNews.

Tyler Durden
Thu, 08/06/2026 – 02:00

The West Is Winning The Information War While Russia Prevails On The Battlefield

The West Is Winning The Information War While Russia Prevails On The Battlefield

Authored by former CIA officer Larry Johnson

I stumbled across something pretty bizarre today when I queried one of the AI-search engines about Russia’s capture of territory in Ukraine in 2026. Here is what the Chinese KIMI claimed:

The evidence from multiple sources — including Ukrainian official claims, Western think tanks, and Ukrainian independent trackers — suggests that Ukraine recaptured substantially more territory than Russia captured during the first half of 2026, driven by the southern counteroffensive. However, the pace of Ukrainian gains has slowed since spring, and Russia has made small net gains in recent months (June–July). The overall net for the full year so far appears to still favor Ukraine, but the margin and the exact numbers depend heavily on whose methodology you use.

There you have it… Ukraine is winning the war on the ground according to AI. Let me emphasize that you will find this same propaganda on GROK or Claude. The Western propaganda effort is paying dividends on the information operation side of the house. Even the Chinese-coders who created KIMI are pushing Western propaganda.

via Al Jazeera

So let me give you the actual rundown for 2026. Russia started 2026 with Gerasimov’s report to Putin announcing the liberation of Pokrovsk (Krasnoarmeysk) — the Donetsk logistics hub under siege for nearly two years — and of Vovchansk in Kharkiv. Through November of 2025 the MoD had reported a steady run of captures, including Petrovskoye in the DPR and Tikhoye and Otradnoye in Dnepropetrovsk.

Moving into the spring of 2026, TASS reported that Russian forces liberated 63 settlements from March through May 2026 — 20 in March, 16 in April, and 27 in May, the strongest month. The regional breakdown was 21 in Kharkiv Region, 19 in the DPR, 14 in Sumy, six in Zaporozhye, and three in Dnepropetrovsk. The Sumy and Kharkiv gains are framed by Moscow as building a “security zone” along the Russian border.

By early summer (June), Gerasimov reported that Russian forces were continuing the liberation of “Donbass and Novorossiya,” advancing on all fronts. The 3rd Army was advancing toward Slavyansk and Kramatorsk — liberating Piskunovka, reaching the outskirts of Nikolayevka, and reported to be less than 5 km from the eastern edge of Kramatorsk, with the capture of Krasny Liman (Lyman) said to be due soon.

Battlegroup West advanced on a broad front; in the Kupyansk area, having repelled Ukrainian attempts to break through to western Kupyansk, with assault units pushing west toward Shevchenkovo. In the Dobropolye area north of Krasnoarmeysk, fighting in Dobropolye and Annovka, with Lenina (Ukrainian name Mirnoye) taken and Shevchenko, Krasnoyarskoye, and Svetloye reported as liberated.

In July TASS counted 32 settlements liberated, with 22 of them — over 68 percent — in Kharkiv Region and the DPR. By battlegroup: North took ten, Center eight, West six, East five, and South three, and the month’s most significant developments were the liberation of Konstantinovka in the DPR by Battlegroup East and the capture of Belitskoye by Battlegroup Center. Konstantinovka is one of the four Donetsk fortress belt cities.

At present the Russians are driving on the last major Ukrainian-held Donetsk agglomeration — the Konstantinovka–Druzhkovka–Kramatorsk–Slavyansk belt — alongside the Sumy/Kharkiv border zone and consolidation in Zaporozhye and Dnepropetrovsk.

Along with the ground operations in eastern Ukraine, Russia has ended Ukraine’s ability to conduct maritime and trade operations from Odessa and Nikolaev since July 22nd.

Ukrainian farmers will not be able to export products via the Black Sea ports and western supplies, which once flowed freely through Odessa. Ukraine’s maritime lifeline is severed and will not be in operation until after the war with Ukraine is over.

Finally, there is the daily Russian missile and drone attacks on Kiev and other key Ukrainian logistics and military hubs. The destruction of factories and warehouses is effectively bleeding Ukraine dry. The West persists in painting the war in Ukraine as a crusade that sits on the threshold of victory, but the realities on the ground tell a dramatically different, grim story… Ukraine is losing.

Tyler Durden
Wed, 08/05/2026 – 23:25

End Of Cheap Food? Five Forces Set To Drive Grocery Bills Even Higher

End Of Cheap Food? Five Forces Set To Drive Grocery Bills Even Higher

UBS analysts identified five long-term forces likely to keep global food inflation “structurally higher” above its pre-pandemic average of about 2.5%, crushing consumer hopes that price pressures will simply fade.

“While food inflation globally has fallen from the COVID peak, a new debate is emerging: is the c2.5% LT average obsolete?” London-based managing director and equity-research analyst Sreedhar Mahamkali asked in a note penned on Monday.

Mahamkali and his team outlined five long-term drivers of global food inflation:

1. Climate risk is global, although its intensity differs by geography and commodity. Academic research suggests climate change could add around 0.9 to 3.2 percentage points to annual global food inflation by 2035.

2. Weak farm profitability limits investment and supply responsiveness globally. The pressure is most visible where farms are small, fragmented or exposed to volatile inputs, although scale, subsidies and access to credit can provide greater protection in some markets.

3. Higher welfare standards are lifting costs in animal protein. UK and European poultry provide the clearest current evidence, but similar changes in stocking density, housing, biosecurity and traceability are emerging across several markets.

4. Labor costs are rising across the food chain. The effect is strongest in labour- intensive farming, processing, logistics, food service as well as the front-end retail, although productivity, automation and the availability of lower-cost labour produce meaningful regional differences.

5. Supply flexibility is constrained globally: some markets face limited land expansion and tighter standards, while others contend with underinvestment and climate vulnerability.

“We expect food-at- home to start regaining share from historical lows, suggesting higher spend in the Food Retail channel with potential tailwinds as we demonstrate with a UK case study. On the other hand, wallet share compression of the discretionary categories means food-away- from-home and non-food retail are more vulnerable,” the analyst pointed out.

He expects food inflation to run above historical levels in the UK, Europe, Australia, Southeast Asia and China, while remaining broadly unchanged in the US and Latin America and declining in India:

The UK faces all five drivers, but a rational competitive landscape enables better pass- through, leaving it as the best-positioned retail market.

Europe too faces many of the pressures, but greater fragmentation dilutes pricing power. In the fragmented US, structural cost pressure is largely offset by competition, likely leaving inflation in line with history.

In Latam, Brazil is relatively insulated with moderate impacts from labour cost inflation, welfare standards and a better supply outlook aided by technology with the outlook the same as history.

By contrast, ASEAN sees a sticky underlying cost base and a potential El Niño in H2 suggesting sustained pressure. China is likely to see a gradual increase in food inflation as external cost pressures are effectively transmitted.

Higher operating costs persist in Australia with regulation/welfare standards leading to higher inflation with some costs likely absorbed by retailers. India is the exception, benefiting from policy intervention and productivity gains with lower inflation than in the past.

Visualizing: Food prices could keep rising faster than they did before Covid, remaining above the historical average of about 2.5% annual inflation. Several long-term pressures are making food permanently more expensive.

For the food inflation narrative to continue, the analysts outlined what they are tracking over the next six months:

Here are the winners and losers under different food inflation scenarios:

Five out of eight regions are likely to see higher inflation:

The era of cheap food may be ending. Food inflation could further ignite as other Wall Street desks warn about El Niño risk developing and Professional subscribers can read those notes here at our new Marketdesk.ai portal. 

Tyler Durden
Wed, 08/05/2026 – 23:00