45.1 F
Chicago
Monday, November 9, 2026
Home Blog Page 1939

London’s Gold Shortage: A Symptom Of Global Economic Anxiety

0
London’s Gold Shortage: A Symptom Of Global Economic Anxiety

Via SchiffGold.com,

The world of finance is witnessing a significant shift as a massive transfer of gold makes it way from London to the United States. This isn’t merely a shuffling of bullion, it’s a symptom of worldwide economic anxieties.

London is encountering a gold shortage as many major gold holders are transferring their gold to the U.S. 

This is no minor exchange. 

London companies have sent an estimated 134 billion dollars worth of gold recently to the United States. 

This has led to a significant backlog in gold retrieval waiting times in the United Kingdom, with some investors having to wait nearly two months for the process to complete. 

Economists have speculated that this is due to the perception of America as both an investment “safe haven.” 

Specifically, the threat of major global tariffs on the horizon has foreign businessmen seeking to get their goods into America before the price of doing so becomes much more steep. This trend has been intensified by President Trump’s recent imposition of tariffs on Canada, Mexico, and China. 

The tariffs have created significant market uncertainty and heightened inflationary concerns, further boosting gold’s appeal as a hedge against economic instability. 

Another factor behind this shift is the continued effort by certain countries to increase their store of physical bullion instead of the dollar within their region, with Poland being a notable example. The value of gold is typically inversely correlated with the value of the dollar, as exemplified by its steep valuation rise during the dollar’s precipitous fall. As more countries become less dependent on the dollar, the currency could take a further valuation hit, bolstering gold’s worth all the more.

While America is reaping the rewards of the transfer, the sudden shift has revealed the fragility of the United Kingdom’s gold market. 

The London Bullion Market Association (LBMA) has long argued for the city’s gold liquidity. However, the current crisis suggests much of the vaulted gold is either “pledged to central banks, ETFs, or foreign governments.”

As this golden tide shifts, it serves to demonstrate the world’s economic anxieties and aspirations. The movement of gold from London to the U.S. is more than a simple relocation of assets; it’s a testament to the global forces which are currently shaping our financial landscape. In particular, investors and nations alike are seeking stability in an increasingly unpredictable world. 

Looking ahead, the repercussions of this gold shift will likely extend far beyond the immediate market impacts. It may prompt a reevaluation of gold’s role in the global financial system, influence international monetary policies, and even affect geopolitical relationships. Even after thousands of years of progress, the glitter of gold continues to captivate and shape our economic world, reminding us that even in the digital age, this ancient store of value remains a powerful force in global finance. The coming years will reveal whether this shift marks a temporary fluctuation or a more permanent realignment in the world’s gold distribution.

Tyler Durden
Mon, 02/10/2025 – 11:40

McDonald’s Global Sales Rise, But Gloom Plagues US Low-Income Customer

0
McDonald’s Global Sales Rise, But Gloom Plagues US Low-Income Customer

McDonald’s global same-store sales increased by .4% in the fourth quarter (this snapped two consecutive negative quarters), offsetting a 1.4% decline in the US, where cash-strapped consumers and an E. coli outbreak weighed on Big Mac demand. Shares in New York jumped on Monday as executives forecasted an improving sales trend for 2025. 

Here’s a summary of the quick-service restaurant’s fourth-quarter earnings, as reported by Goldman’s Christine Cho, Teddy Farley, and Samantha Chiang: 

MCD reported global SSSG of +0.4% that beat GS/Visible Alpha Consensus Data estimates of +0.0%/-0.4% driven by a beat in the IOM and IDLM segments, partially offset by weaker performance in the US segment. US SSSG of -1.4% was below both GS/VA (+0.5%/-0.2%) driven by a decline in average check, partly offset by slightly positive comparable guest counts.

More color on fourth-quarter earnings:

  • IOM SSSG of +0.1% came in ahead of GS/VA estimates of -0.5%/-0.8% driven by mixed results across markets, including negative comparable sales in the UK. IDLM SSSG of +4.1% beat GS/VA of +0.0%/-0.3% as the Middle East and Japan posted positive comparable sales.

  • Total revenues of $6.39bn came in 1.4%/1.3% behind GS/VA of $6.48bn/$6.47bn, with the miss driven primarily by US total revenues that fell short of GS/VA by -3.3%/-2.7% and IDLM total revenues that fell short of GS/VA by -2.3%/-4.8%, while IOM was roughly in line with consensus. Company restaurant margins of 14.4% were below GS/VA (16%) due to the top line pressures in the US and IOM segments.

  • Adj. EPS of $2.83 missed GS/VA estimates of $2.88/$2.87, driven primarily by the top line miss, as well as elevated other operating expense (note that adj. EPS excludes $74mn in pre-tax restructuring charges and $71mn in pre-tax property sale gains from the sale of the South Korea business).

MCD’s earnings call provided more color on cash-strapped customers weighing down sales in the US (courtesy of Bloomberg): 

The low-income consumer in the US was still down double-digits in Q4, and this segment is overweighted in the industry relative to the US in total.

Bernstein analyst Danilo Gargiulo told clients that MCD’s results showed the recovery might be faster than anticipated for international markets, especially in emerging licensed markets pressured by months of Middle East-related boycotts over Gaza.

Gargiulo noted, “The persistence of negative same-store sales growth in the US is worrisome.” 

Citi and Wall Street expectations see “encouraging signs” in MCD’s full-year forecast (courtesy of Bloomberg): 

  • Sees net restaurant unit expansion contributing slightly over 2% to systemwide sales growth, in constant currencies

  • Sees operating margin percent in the mid-to-high 40% range

  • Sees capital expenditures $3.0 billion to $3.2 billion, estimate $2.8 billion

  • Sees the effective income tax rate between 20% and 22%

  • Sees nearly 1,800 net restaurant additions

  • Sees free cash flow conversion rate in the low-to-mid 80% range

The improving outlook sent shares in New York up 5% – the largest intra-day advancement in five years. 

Goldman has a “Neutral” rating on MCD with a $313 12-month price target. 

While global sales helped offset weakness in the US, low-income consumers—who make up a large portion of the QSR’s customer base—remain under pressure. This suggests these US customers are not as responsive to meal deals amid a multi-year inflation storm.   

Tyler Durden
Mon, 02/10/2025 – 11:25

Conor McGregor Blasts Mass Migration After Slasher Knife Attack In Ireland

0
Conor McGregor Blasts Mass Migration After Slasher Knife Attack In Ireland

Authored by Steve Watson via Modernity.news,

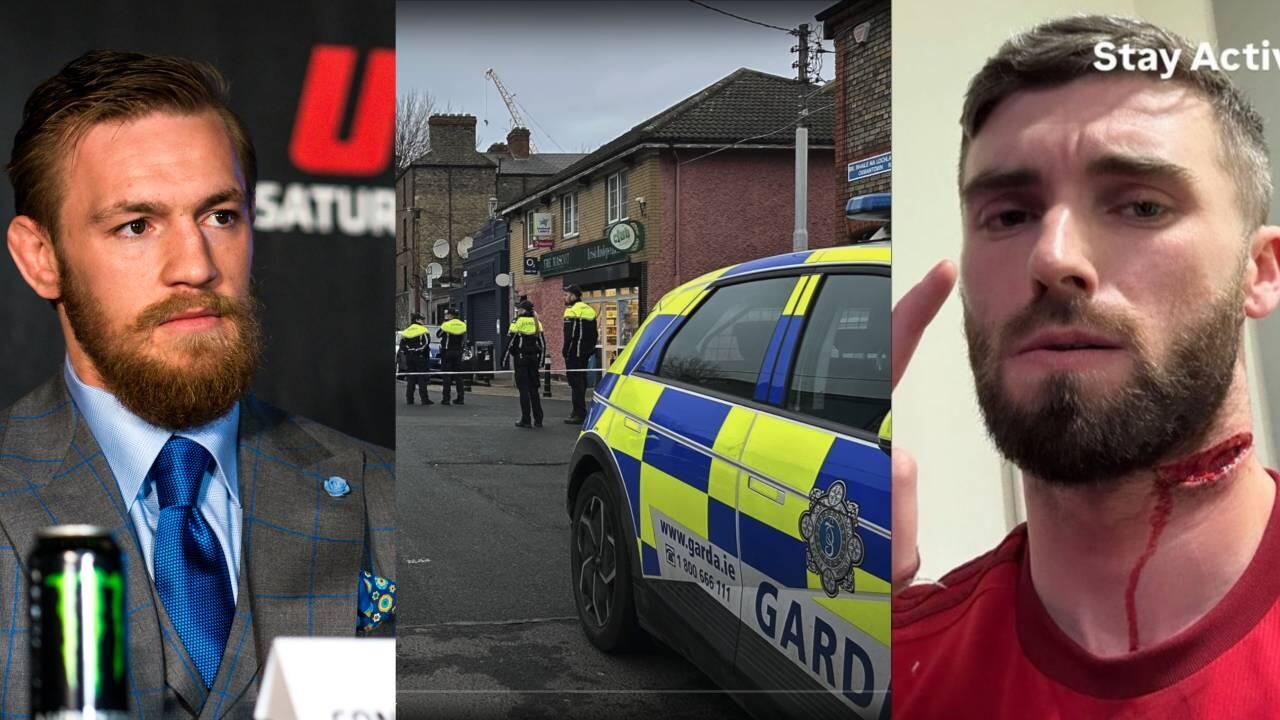
UFC legend Conor McGregor has once again spoken out against mass migration in the wake of yet another attack perpetrated, reportedly, by a South American migrant who slashed three people seemingly at random, causing serious injuries.

Police in Dublin have said the the man, who is homeless, was arrested after he started attacking people with a Stanley knife in Stoneybatter in the north of the city on Sunday. One man was attacked outside the front door of his own house.

Two men sustained serious but not life-threatening injuries, while a third man suffered a less serious injury, according to reports.

The Irish Times reports that police have “dismissed unfounded rumours that were circulating widely that the suspect was an asylum seeker and that other attackers were still at large,” yet the man has been identified as South American.

The media uniformly described the attacker as simply “a man.”

McGregor shared an image purported to be one of the victims displaying a large gash on his neck where the suspect slashed him.

Reports state the man was attacked from behind, and is therefore lucky to be alive.

McGregor posted another image of the same man after he had the wound stitched up and went to the pub for a pint.

McGregor wrote “The aul rinse and repeat statements ring out again from government officials across social media as 4 people had their necks cut at their homes by a homeless South American man with mental health issues.”

He added, “Nothing more after that ever. Zero action but the same statement over and over. Till the next one to dust off the aul paragraph again. “Sorry to hear/thank you swift response/get better soon.”

The MMA fighter continued, “For me, even just one of these instances occurring (and there have been MANY) is enough to realize we need a full overhaul of multiple systems currently in place in Ireland. The growing homeless figures, coupled with the constant rising cost of living in Ireland is a NATIONAL EMERGENCY! Mental health services in Ireland are non existent. Couple that with a blasé, right this way border, and a disgruntled native population, and you have a real recipe for disaster. Which make no mistake, from all visible actions we see, is EXACTLY WHAT THIS GOVERNMENT WANT.”

“We have been ushered unwillingly into terrible times in Ireland,” McGregor continued, adding “From a martial arts/self defense perspective all I can say to the people of Ireland is, keep your eyes peeled at all times. Stay ready.”

He again emphasised his opposition to mass migration, noting “Record homeless, and rising. Cost of living rising. Mass immigration a greed ridden racket. Zero mental health services. We have no infrastructure or systems in place to handle this mass influx.”

“We are witnessing the destruction of Ireland in live time,” McGregor urged, adding “As rotating Taoiseachs (whatever that even is! Who decided this? never in the history of the state have we had rotating taoiseachs) I lay the blame squarely on Michael Martin and Simon Harris. The two cling ons. The days of FF/FG rule over Irish affairs must end!”

“Party politics does not serve the people. It serves the party,” he continued before once again touting himself as a potential political candidate.

“WE ARE FED UP! Put me in office and I will be on them heavy and daily. I am of NO PARTY. Ireland you will decide this. The 20 serving members of the Dail will decide and then we will let the people of Ireland decide,” McGregor asserted.

He concluded, “My honest heart, I’d rather more time but we do not have that luxury. I volunteer my life for Ireland. I care about the future of my country and its children. I envision prosperity for the people of Ireland. I envision an end to rapid inflation. I envision housing our homeless. Fixing our medical services. ENDING CORRUPTION AND THE ABUSE OF OUR MONEY. Ireland it is time. Vote McGregor”

McGregor ended his statement with a shout out to President Trump, noting “Donald I will see you for St Patrick’s Day.”

As we have previously highlighted, the UFC star has persistently spoken out against mass migration, and has been made a target for it by the authorities.

*  *  *

Your support is crucial in helping us defeat mass censorship. Please consider donating via Locals or check out our unique merch. Follow us on X @ModernityNews.

Tyler Durden
Mon, 02/10/2025 – 11:10

Key Events This Week: CPI, PPI, Retail Sales And Powell Testimony

0
Key Events This Week: CPI, PPI, Retail Sales And Powell Testimony

The week after payrolls is usually quiet but as DB’s Jim Reid notes, because the first Friday of the month being the latest it could possibly be this month, we go straight into US CPI (Wednesday) week, with PPI (Thursday) for an added bit of inflationary sparkle. Outside of this the main highlight will be Powell’s semi-annual monetary policy testimony before the Senate Banking Committee (tomorrow) and the House Financial Services Committee (Wednesday). The latter comes after CPI which will possibly spread the interest level over the two appearances rather than most of the focus being on the first as per usual. Elsewhere in the US, watch out for the NY Fed inflation expectations series today after a stronger equivalent from the University of Michighan survey just before the weekend on Friday. After that we wait until this Friday for the other important US data, namely retail sales and industrial production.

In Europe we have the UK Q4 GDP reading on Thursday following last week’s BoE meeting (our UK economist’s recap is here). Elsewhere in the region, January CPIs are due in Denmark and Norway today, and Switzerland on Thursday. In terms of earnings we have 75 S&P 500 companies and 79 Stoxx 600 companies reporting.

The tariff news will clearly continue to dominate the agenda all week, especially after Mr Trump announced on Friday that he’d be holding a press conference early this week on the US plans for equalizing tariffs on “reciprocal trade” with an added mention for autos. Then on Air Force One last night Mr Trump said he would put 25% tariffs on steel and aluminium imports later today. Canada, Mexico and Latin America would be the most impacted given that’s where the US imports most of these goods from.

Looking forward now and in terms of Powell’s testimonies this week, the overarching message is likely that the Fed is not in a hurry to cut rates at the moment, with Friday’s payrolls and to a lesser extent the UoM inflation expectations series the latest support to that message. Even though headline (+143k) and private (+111k) payroll gains were below expectations, net upward revisions of 100k over the prior two months, a decline in the unemployment rate to 4.0% (4.1% expected), and average hourly earnings +0.5% on the month (vs. +0.3% expected), made it a hawkish report.On top of that, the annual benchmark revision to the level of March 2024 nonfarm payrolls (-598k final vs. -818k preliminary) was not as large as the BLS had previously projected. See our economists’ US employment chart book here for everything you wanted to know about the labour market post this release.

For those inflation expectations last Friday the 1yr level was up to 4.3% (expected 3.3%) and the more important 5-10yr one at 3.3% (expected 3.2%). If confirmed in the final reading the longer-term expectations have only been higher for one month (June 2008) since 1995. This series continues to be ridiculously partisan post the election though with the 1-yr number seen around 5% from Democrat supporters and around zero for Republicans. So how reliable this number is at the moment is open is debatable.

Finally, talking of inflation, strong seasonally adjusted gains in food and energy prices should keep headline CPI (+0.31% forecast vs. +0.39% previously) above core (+0.28% vs. +0.23%). YoY headline CPI should remain roughly steady at 2.9%, while that for core would just round down to 3.1%. OER will continue to be a big focus. For PPI it‘s as ever the components that go into core PCE that will gain all the attention.

Courtesy of DB, here is a day-by-day calendar of events

Monday February 10

  • Data: US January NY Fed 1-yr inflation expectations, Japan January Economy Watchers survey, Denmark and Norway January CPI
  • Earnings: McDonald’s, Vertex, DBS, Rockwell Automation, Astera Labs, Mediobanca

Tuesday February 11

  • Data: US January NFIB small business optimism, Japan January M2, M3, Canada December building permits, Norway Q4 GDP, Canada December building permits
  • Central banks: Fed’s Chair Powell testifies to the Senate committee, Fed’s Hammack and Williams speak, BoE’s Bailey and Mann speak
  • Earnings: Coca-Cola, S&P Global, Shopify, Gilead Sciences, BP, Welltower, Marriott, DoorDash, UniCredit, Carrier Global, Humana, Kering, Zillow
  • Auctions : US 3-yr Notes ($58bn)

Wednesday February 12

  • Data: US January CPI, federal budget balance, Japan January PPI, machine tool orders, Germany December current account balance, Italy December industrial production
  • Central banks: Fed’s Chair Powell testifies to the House Financial Services committee, Fed’s Bostic speaks, ECB’s Elderson and Nagel speak, BoE’s Greene speaks, BoC’s summary of deliberations
  • Earnings: Cisco, EssilorLuxottica, Equinix, SoftBank, CME, Williams Cos, CVS Health, Vertiv, Dominion Energy, Robinhood, Heineken, Reddit, Barrick Gold, Albemarle, MGM Resorts, Telecom Italia
  • Auctions : US 10-yr Notes ($42bn)

Thursday February 13

  • Data: US January PPI, initial jobless claims, UK Q4 GDP, January RICS house price balance, Switzerland January CPI
  • Central banks: ECB’s Nagel speaks, ECB’s economic bulletin
  • Earnings: Nestle, Siemens, Applied Materials, Unilever, Sony, Deere, Palo Alto Networks, Airbnb, British American Tobacco, Zoetis, Digital Realty Trust, Howmet Aerospace, Barclays, Honda, Adyen, PG&E, Orange, DSM-Firmenich, Legrand, Commerzbank, DraftKings, Moncler, Roku, Nissan, Neste, Crocs, Embracer Group, thyssenkrupp, Altice
  • Auctions : US 30-yr Bonds ($25bn)

Friday February 14

  • Data: US January retail sales, industrial production, capacity utilisation, import and export price index, December business inventories, Germany January wholesale price index, Italy December general government debt, Eurozone Q4 GDP, Canada December manufacturing sales
  • Earnings: Hermes, Safran, NatWest, Moderna

* * *

Finally, according to Goldman, the key economic data releases this week are the CPI report on Wednesday and the retail sales report on Friday. There are several speaking engagements from Fed officials this week, including Chair Powell’s semi-annual Congressional testimony on Tuesday and Wednesday.

Monday, February 10

  • 11:00 AM New York Fed 1-year inflation expectations, January (last 3.00%):  The New York Fed will release its measures of inflation expectations for January. The University of Michigan’s 12-month measure of inflation expectations increased by 0.5pp in January and by an additional 1.0pp in February, partly reflecting the expected impact of tariffs.

Tuesday, February 11

  • 06:00 AM NFIB small business optimism, January (consensus 104.7, last 105.1)
  • 08:50 AM Cleveland Fed President Hammack (FOMC non-voter) speaks: Cleveland Fed President Beth Hammack will give a speech on the economic outlook at an event in Kentucky. Speech text and a Q&A are expected.
  • 10:00 AM Fed Chair Powell speaks: Fed Chair Jerome Powell will testify on the Federal Reserve’s Semi-Annual Monetary Policy Report to the US Senate Committee on Banking, Housing, and Urban Affairs. As discussed in our FOMC recap, in his press conference following the January FOMC meeting, Chair Powell indicated that he still sees the funds rate as “meaningfully restrictive,” the FOMC is not “in a hurry” to cut, and once policy changes from the new administration become clearer, the bar is not high for further inflation progress to justify another rate cut.
  • 03:30 PM Fed Governor Bowman speaks:  Fed Governor Michelle Bowman will give remarks on bank regulation at the 2025 Iowa Bankers Association Bank Management and Policy Conference. On January 9, Bowman said “The policy rate is now closer to my estimate of its neutral level, which is higher than before the pandemic.” She added that she continues “to be concerned that the current stance of policy may not be as restrictive as others may see it. Given the ongoing strength in the economy, it seems unlikely that the overall level of interest rates and borrowing costs are providing meaningful restraint.”
  • 03:30 PM New York Fed President Williams (FOMC voter) speaks: New York Fed President John Williams will give keynote remarks at an event hosted by the Pace University Economics Society. Speech text and a moderated Q&A are expected. On January 15, Williams said “We have seen significant progress and the labor market has come into balance,” and “My view [is] that inflation is moving toward our goal of 2 percent.” He added that “Because that balance of risks to achieving our goals has now been achieved, our job is to ensure the risks remain in balance.”

Wednesday, February 12

  • 08:30 AM CPI (MoM), January (GS +0.36%, consensus +0.3%, last +0.4%); Core CPI (MoM), January (GS +0.34%, consensus +0.3%, last +0.2%); CPI (YoY), January (GS +2.96%, consensus +2.9%, last +2.9%); Core CPI (YoY), January (GS +3.19%, consensus +3.1%, last +3.2%): We estimate a 0.34% increase in January core CPI (month-over-month SA), which would leave the year-over-year rate unchanged on a rounded basis at 3.2%. Our forecast reflects an increase in used car prices (+1.5%) reflecting an increase in auction prices, an increase in new car prices (+0.5%) reflecting a decline in incentives, and an acceleration in the car insurance category (+0.75%) based on premiums in our online dataset. We expect seasonal distortions and a postage price increase to boost the communications category (GS forecast +0.5% vs. flat in December and -1.0% in November). We expect the shelter components to moderate slightly (OER +0.31% vs. +0.33% in December; primary rent +0.27% vs. +0.33% in December). We estimate a 0.36% rise in headline CPI, reflecting higher food (+0.4%) and energy (+0.6%) prices. Our forecast is consistent with a 0.32% increase in core PCE in January. We will update our core PCE forecast after the CPI is released.
    • In this month’s report, the BLS will release recalculated seasonal factors that reflect the price movements of 2024—which could reduce the impact of seasonal distortions that explained some of the month-to-month variation in core inflation last year—as well as updated weights. The annual seasonal factor revisions tend to cause monthly inflation readings to be revised toward the annual average. In other words, higher inflation readings for the year tend to be revised lower and lower readings tend to be revised higher. On average over the last decade, about 20% of the relative strength of a month’s initial core inflation vintage has been revised away in its first annual revision. Last year, monthly core CPI inflation was particularly elevated in Q1 (10bp above the 2024 average) and particularly low in May-July (14bp below).
  • 10:00 AM Fed Chair Powell speaks: Fed Chair Jerome Powell will testify before the House Financial Services Committee. Speech text and a Q&A are expected.
  • 12:00 PM Atlanta Fed President Bostic (FOMC non-voter) speaks: Atlanta Fed President Raphael Bostic will speak in a moderated conversation on the economic outlook at an event at the Atlanta Fed. Q&A is expected. On February 3, Bostic said “I want to see what the 100bps of reduction of the policy rate that we did last year translates to in terms of the economy… I want to be cautious and I don’t want to have our policy lean in a direction, making the assumption that the economy is going to evolve a certain way, and then we have to turn and unwind.” He added that his “general outlook is that we’re going to get to target and get [policy] back to neutral. And I think neutral is lower than where we are now, somewhere in the 3-3.5% range.”

Thursday, February 13

  • 08:30 AM PPI final demand, January (GS +0.4%, consensus +0.3%, last +0.2%); PPI ex-food and energy, January (GS +0.2%, consensus +0.3%, last flat); PPI ex-food, energy, and trade, January (GS +0.2%, consensus +0.2%, last +0.1%); 
  • 08:30 AM Initial jobless claims, week ended February 8 (GS 215k, consensus 217k, last 219k): Continuing jobless claims, week ended February 1 (consensus 1,888k, last 1,886k)

Friday, February 14

  • 08:30 AM Retail sales, January (GS -0.2%, consensus -0.1%, last +0.4%); Retail sales ex-auto, January (GS +0.3%, consensus +0.3%, last +0.4%); Retail sales ex-auto & gas, January (GS +0.4%, consensus +0.4%, last +0.3%); Core retail sales, January (GS +0.2%, consensus +0.3%, last +0.7%): Core estimate core retail sales expanded 0.2% in January (ex-autos, gasoline, and building materials; month-over-month SA), reflecting middling growth in measures of card spending and a potential drag from colder-than-usual weather. We estimate a 0.2% decline in headline retail sales, reflecting higher gasoline prices but lower auto sales.
  • 08:30 AM Import price index, January (consensus +0.4%, last +0.1%): Export price index, January (consensus +0.3%, last +0.3%)
  • 09:15 AM Industrial production, January (GS +0.1%, consensus +0.3%, last +0.9%): Manufacturing production, January (GS -0.1%, consensus +0.1%, last +0.6%)
  • Capacity utilization, January (GS 77.6%, consensus 77.7%, last 77.6%):  We estimate industrial production increased +0.1%. We expect colder-than-usual temperatures to contribute to strong utilities production due to increased demand for heating, but softer autos and mining production. We estimate capacity utilization remained unchanged at 77.6%.
  • 10:00 AM Business inventories, December (consensus flat, last +0.1%)

Soruce: BofA, Goldman


Tyler Durden
Mon, 02/10/2025 – 10:58

DOGE Team Finds FEMA Sent $59 Million Last Week To Luxury NYC Hotels For Illegals

0
DOGE Team Finds FEMA Sent $59 Million Last Week To Luxury NYC Hotels For Illegals

Elon Musk’s team of mid-20s Department of Government Efficiency (DOGE) disruptors has once again found wasteful spending—this time focusing on a $59 million payment sent by the Federal Emergency Management Agency to luxury hotels across New York City housing illegal aliens.  

“The DOGE team just discovered that FEMA sent $59M LAST WEEK to luxury hotels in New York City to house illegal migrants,” Musk wrote on X early Monday morning. 

Musk explained, “Sending this money violated the law and is in gross insubordination to the President’s executive order,” adding, “That money is meant for American disaster relief and instead is being spent on high end hotels for illegals!” 

Musk did not specify which luxury NYC hotels received FEMA funding for migrants last week but noted that a “clawback demand will be made today to recoup those funds.” 

However, a December report revealed that NYC politicians spent $220 million in a sweetheart deal with Pakistan to lease the prestigious Roosevelt Hotel in Midtown Manhattan for illegal alien housing. The most alarming issue was that NYC paid a foreign government to house illegals. 

“So let me get this straight; places like North Carolina and Maui get a pittance because FEMA says they lack funds, so we have to send our Military there to do work that could be put into the local economies.  Meanwhile FEMA blows its budget on housing illegal immigrants?” one X user wrote in response to Musk’s report. 

While illegals have lived ‘the American Dream’ on the taxpayers’ dime, residents across Western North Carolina have only now begun receiving FEMA assistance amid the ongoing recovery from Hurricane Helene.

Many of these folks in North Carolina had limited to no FEMA assistance under the Biden-Harris regime. That all changed after President Trump entered the White House on January 20. 

So what comes next for the DOGE team?

. . . 

Tyler Durden
Mon, 02/10/2025 – 09:00

Spot The Difference: Biden’s Army Ad Vs Trump’s

0
Spot The Difference: Biden’s Army Ad Vs Trump’s

Authored by Steve Watson via Modernity.news,

The US Army just recorded 12 year high recruiting numbers. Why? Well possibly because the military is no longer advertising itself as some sort of LGBTQ+ activist Summer camp.

Take a look at this US Army ad promoting health and fitness training, featuring a sergeant doing dead lifts and declaring, “Strong people are harder to kill.” 

Then compare it to an Army ad under the Biden regime where a cartoon soldier called Emma talks about being raised by two lesbian mothers and “marching for equality” as a child in order to ‘defend freedom’

Different vibe.

DEI at the Pentagon is dead. The new Defense Secretary Pete Hegseth recently circulated a memo stating that ‘cultural awareness’ and ‘identity’ dates will no longer be recognised.

Hegseth has also directed staff to create a DEI task force to make sure all such programs are erased from the Pentagon.

“We’re not joking around,” Hegseth said in an interviews last week, adding “There’s no changing of names or softly manipulating something. DEI is gone.”

President Trump also signed an executive order last month declaring that individuals with a “gender identity” contradicting their biological sex do not meet the necessary standards for military service. 

The order effectively bans transgender-identifying individuals from enlisting and serving, and Rasmussen finds that it is  supported by 54 percent of Americans.

The order states that “Beyond the hormonal and surgical medical interventions involved, adoption of a gender identity inconsistent with an individual’s sex conflicts with a soldier’s commitment to an honorable, truthful, and disciplined lifestyle, even in one’s personal life.”

“A man’s assertion that he is a woman, and his requirement that others honor this falsehood, is not consistent with the humility and selflessness required of a service member,” it continues.

“For the sake of our Nation and the patriotic Americans who volunteer to serve it, military service must be reserved for those mentally and physically fit for duty,” the order further states.

It concludes that “The Armed Forces must adhere to high mental and physical health standards to ensure our military can deploy, fight, and win, including in austere conditions and without the benefit of routine medical treatment or special provisions.”

Hegseth recently announced that US Army recruiting goals have been far surpassed, and they have recorded the most successful enlistment numbers in over a decade.

Clearly this is the fallout of not only the expulsion of diversity nonsense, but also seeing service members being deployed in securing the border and protecting the country, rather than being shipped overseas to engage in pointless foreign conflicts.

*  *  *

Your support is crucial in helping us defeat mass censorship. Please consider donating via Locals or check out our unique merch. Follow us on X @ModernityNews.

Tyler Durden
Mon, 02/10/2025 – 08:40

Futures, Dollar Rise, Gold Soars After Trump’s Latest Tariff Salvo

0
Futures, Dollar Rise, Gold Soars After Trump’s Latest Tariff Salvo

US equity futures are higher, led by Tech as investors largely ignored tariff headlines, in this case the 25% tariffs on steel/aluminum which were announced yesterday, and which will predominantly impact both Canada and Mexico. As of 8:00am ET, S&P futures are 0.5% higher, reversing half of Friday’s drop as the tariff news lifted American metals stocks, with US Steel Corp. surging as much as 15% in premarket. Alcoa Corp. rallied 5%. Nasdaq futures are up 0.6%, with Mag7 names all higher ex-TSLA with Semis and Financials catching a bid. Bond yields are mostly unchanged with USD higher. Commodities are seeing strength across the entire complex with gold’s record run continuing, now above $2900. Today’s macro data focus is on the NY Fed’s 1-year inflation expectation given the hotter print on Friday from Univ of Mich; CPI is on Weds.

In premarket trading, McDonald’s rose 2% as sales rose in the fourth quarter after growth in the chain’s international business made up for a decline in the US. Meta once again led gains for the Mag7 group. Meanwhile, shares in Tesla are set to extend losses for a fourth session(GOOGL +0.6%, AMZN +0.4%, AAPL +0.5%, MSFT +0.6%, META +0.6%, NVDA -0.05% and TSLA -1.6%). Aluminum and steel company shares rose as President Donald Trump plans to impose 25% tariffs on all imports of the metals into the country (Alcoa (AA) climbs 5% and Century Aluminum (CENX) jumps 10%). Steel firms moving higher include: Cleveland-Cliffs (CLF) +8%, US Steel (X) +5%, Steel Dynamics (STLD) +6%.
Aspen Technology (AZPN) falls 2% as Emerson said the $265 per share price offer for the company is Emerson’s best and final price. Here are some other notable premarket movers:

  • Axsome Therapeutics (AXSM) rises 13% after announcing it has entered into a settlement agreement with Teva Pharmaceuticals resolving patent litigation.
  • Charles Schwab Corp. (SCHW) falls 2% as Toronto-Dominion Bank plans to exit its equity investment in the company.
  • Hain Celestial (HAIN) declines 6% after reporting 2Q adjusted earnings per share that missed the average analyst estimate.
  • On Semi (ON) tumbles 8% after reporting quarterly revenue that missed the average analyst estimate.
  • Playa Hotels & Resorts (PLYA) rises 2% after Hyatt Hotels agreed to buy the company for about $2.6 billion
  • Pliant Therapeutics (PLRX) slumps 62% after the company voluntarily paused enrollment and dosing of a trial of bexotegrast in patients with idiopathic pulmonary fibrosis.
  • Semtech (SMTC) plunges 27% after the chipmaker said sales of the company’s CopperEdge products are expected to be lower than management’s “floor case” estimate due to rack architecture changes.

Trump’s intention to announce a 25% levy on steel and aluminum Monday added to already tense sentiment before Fed Chair Jerome Powell’s semiannual congressional testimony and the US President’s possible unveiling of reciprocal tariffs on “everyone” this week. Trump said the metals tariffs would apply to imports from all countries, though he didn’t specify when they would take effect.

“Our view in tariffs remain that they will cause volatility, are a negotiating tool and will eventually be not as bad as feared,” said Mohit Kumar at Jefferies International.

The dollar strengthened and gold hit a record high as Trump’s latest plan for steel and aluminum import tariffs brought fresh disruption to markets. The yen and the Canadian dollar were the main losers against the greenback as the Bloomberg Dollar Spot Index rose to its highest in nearly a week. Like the dollar, bullion climbed as the president’s latest trade threats helped boost demand for haven assets. 

Separately, Trump said Elon Musk’s government efficiency team has found irregularities while examining data at the US Treasury Department. Benchmark 10-year Treasuries were steady.

There are a number of key events on the radar in coming days, including Powell’s speech and US CPI data.
Powell will deliver his semi-annual testimony at a time when officials are signaling they’re not in a hurry to further ease policy. Nonfarm payrolls moderated last month and revisions show US job gains were softer but still solid in 2024. Inflation data due this week may help buttress those arguments and underpin market pricing for just one Fed rate cut this year.

In Europe, the Stoxx 600 rose 0.3% with real estate, energy and telecommunication stocks among the best performers. Basic resources provide a drag due to the aforementioned metal tariffs. BP Plc shares surged the most since 2020 as Bloomberg News reported that activist investor Elliott Investment Management had built a stake in the oil company. Here are the most notable European mover:

  • BP shares rise as much as 7% after Bloomberg reported that activist investor Elliott has built a significant stake and is pushing the company to consider transformative measures.
  • Spectris shares advance as much as 4.7% after JPMorgan upgrades the high-tech instrument maker to overweight, with a Street-high price target.
  • ITV shares rise as much as 3%. Major shareholders in the broadcaster’s management support efforts to explore a deal for its production arm, the FT reported Sunday, corroborating earling reports.
  • Drax shares gain as much as 5.9% after the renewable energy company agreed to a four-year low carbon dispatchable contract with the UK government for Drax Power Station.
  • Talgo shares gain as much as 8.5%, after Poland’s PFR said it intends to submit a proposal that would entail a takeover bid for 100% of the Spanish trainmaker.
  • Telkom shares climb as much as 8.1% in Johannesburg after the telecommunications company said its 3Q Ebitda rose 28% on continued operational efficiency gains from cost optimization initiatives.
  • Cloetta shares rise as much as 5% to hit their highest level since September 2021 after the confectionery company decided not to proceed with a planned greenfield investment in the Netherlands due to “increased risk relating to energy supply and the still on-going permitting process.”
  • IAG shares drop as much as 3.5% after Goldman Sachs cut the stock to neutral from buy after the British Airways owner’s shares outperformed peers since its upgrade last January.
  • Rockwool shares fall as much as 5% as UBS cuts its rating to sell as the stone-wool producer faces a normalization of margins.
  • GTT shares fall as much as 7.3% after the French engineering firm announced job cuts at its Elogen hydrogen unit, as well as the departure of CEO Jean-Baptiste Choimet.
  • Gerresheimer shares slip as much as 1.4%, paring some of Friday’s 9.5% surge, on news that the company is in early-stage talks with private equity investors on a potential takeover.
  • Safestore and Shurgard Self Storage both decline after being downgraded by analysts at Morgan Stanley, who argue the pair are unlikely to lead in any sector recovery.

Earlier in the session,  Asian stocks dropped on concern US President Donald Trump’s plans for tariffs on all imports of steel and aluminum will add to a growing trade war. Hong Kong shares rose for a third day amid optimism toward the tech sector. The MSCI Asia Pacific Index fell as much as 0.5%, with TSMC the biggest drag on the benchmark. Shares in Taiwan and Australia dropped, while Japanese stocks were mixed. A gauge of Chinese tech shares listed in Hong Kong jumped more than 2% as the nation’s growing artificial intelligence capability fueled optimism on the beaten-down sector. Sentiment was also boosted by Trump’s decision to delay suspension of the “de minimis” exception, boosting e-commerce shares.

“This is actually a very good reminder for global investors to look at the innovation capabilities of some of the Chinese players,” Jin Yuejue, a multi-asset solutions investment specialist at JPMorgan Asset Management, said on Bloomberg Television. “We are very much monitoring the National People’s Congress coming up, whether there will be more fiscal impulse that’s going to be announced.”

In FX, the Bloomberg Dollar Spot Index inched up 0.2%, while commodity currencies pared earlier declines, after US President Donald Trump said he would announce 25% tariffs on all imports of steel and aluminum. “Markets are becoming incrementally less sensitive to these headlines,” said Laura Cooper, global investment strategist at Nuveen. “It’s not clear whether this is a negotiating tool to get a deal.” The Japanese yen is the weakest of the G-10 currencies, falling 0.6% against the greenback and taking USD/JPY above 152. EUR/USD steadied around 1.0326; Options markets suggest traders are positioning for a fresh round of euro weakness fueled by widening tariff-risk premiums.The Canadian dollar also underperformed with a 0.3% decline. 

In rates, treasuries are mixed in early US trading Monday, holding most of Friday’s yield increases sparked by the January jobs data. 10Y yields are at 4.40%, unchanged from Friday; most yields remain within 2bp of closing levels from Friday with the curve steeper; 2s10s and 5s30s spreads are wider for first day in five. Treasury auctions begin Tuesday with 3-year notes and include 10- and 30-year new issues over subsequent two days. With no major US economic data slated before the CPI report Wednesday, Treasury and corporate bond supply may be the main driver of flows, along with reaction by other markets to President Trump’s latest tariff threats. Gilts rise and outperform their German counterparts with UK 10-year yields falling a basis point to 4.46%.

In commodities, WTI crude oil rose 1.5% to trade at $72, near session highs. Gold prices soared $41 to a record high above $2,900. Bitcoin rose 3% to near $98,000. Elsewhere in commodities markets Monday, European natural gas prices rose to a two-year high as colder temperatures accelerate the depletion of the region’s storage facilities. Benchmark futures rose as much as 4.1% to the highest since February 2023. Aluminum futures in London — the global benchmark — were steady as traders waited for more details on when and how the latest tariffs would operate. Copper was little changed.

The US economic data calendar includes only NY Fed 1-Year inflation expectations at 11am New York time. Fed speaker slate is blank; Chair Powell is slated to give congressional testimony over the next two days

Market Snapshot

  • S&P 500 futures up 0.4% to 6,071.50
  • STOXX Europe 600 up 0.3% to 544.21
  • MXAP down 0.3% to 185.10
  • MXAPJ little changed at 582.75
  • Nikkei little changed at 38,801.17
  • Topix down 0.2% to 2,733.01
  • Hang Seng Index up 1.8% to 21,521.98
  • Shanghai Composite up 0.6% to 3,322.17
  • Sensex down 0.7% to 77,340.86
  • Australia S&P/ASX 200 down 0.3% to 8,482.78
  • Kospi little changed at 2,521.27
  • German 10Y yield little changed at 2.37%
  • Euro little changed at $1.0333
  • Brent Futures up 1.0% to $75.42/bbl
  • Gold spot up 1.4% to $2,900.86
  • US Dollar Index up 0.10% to 108.15

Top Overnight News

  • Trump on Sunday said the US would impose 25% tariffs starting Mon on steel and aluminum imports, with his reciprocal tariff announcement arriving Tues or Wednesday. WSJ
  • US House Republican leaders are looking to cut federal spending by USD 2tln to USD 2.5tln, according to Punchbowl sources. House GOP negotiators now believe they will have to dig deeper into Medicaid spending to meet those targets. Punchbowl believe Washington is drastically underestimating the chance for a government shutdown after March 14.
  • Trump announced he is revoking security clearances for former President Biden and stopping his daily intelligence briefings, while he stated that there was no need for Biden to have continued access: RTRS
  • Trump said he instructed the Secretary of the US Treasury to stop producing new pennies which is wasteful, while he suggested tearing the waste out of the US budget, even if it’s a penny at a time: RTRS
  • Trump’s acting head of the consumer finance watchdog told staff to stop pending investigations and supervisory activities of banks: WaPo
  • US House Speaker Johnson said he will push the ‘one big bill’ strategy for passing US President Trump’s tax cut agenda and Republicans will find offsets to pay for Trump’s tax cut plans: Fox
  • Chinese officials are building a list of U.S. technology companies that can be targeted with antitrust probes and other tools, hoping to influence the tech executives who are heavily represented in President Trump’s orbit. WSJ
  • China’s consumer inflation accelerated for the first time since August, rising 0.5% in January from a year earlier, driven by holiday spending. Factory deflation persisted with a 2.3% decline. BBG
  • China’s retaliatory tariffs went into effect on Mon 2/10, although a White House official said the US could pause its recent 10% duty imposition if progress occurs on fentanyl when Trump and Xi speak this week. WSJ
  • Indian Prime Minister Narendra Modi is preparing additional tariff cuts ahead of a meeting this week with U.S. President Donald Trump that could boost American exports to India and avoid a potential trade war. RTRS
  • UK companies are paring back job postings at the steepest pace since the midst of the pandemic in 2020, and increasingly turning to redundancies. BBG
  • France will announce a total of €109 billion in AI investments over the next few years, Emmanuel Macron told France 2 TV before today’s summit in Paris. BBG
  • Democrats warn they are willing to have a government shutdown unless Trump and Musk dial back their aggressive overhaul of the federal government. NYT
  • Canada will reach out to US states with which it has significant trade relationships to persuade America to drop its tariff plans. BBG

Tariffs

  • US President Trump said they will be announcing on Monday 25% tariffs on all steel and aluminium coming into the US and he will announce reciprocal tariffs on Tuesday or Wednesday which will go into effect almost immediately, while he added that no one can have a majority stake in US Steel (X).
  • US President Trump said on Friday that he will make an announcement in the week ahead on reciprocal trade with many countries, while he added that tariffs are an option to address deficit and auto tariffs are always on the table. Furthermore, Trump said they will meet on reciprocal tariffs on Monday or Tuesday and have an announcement.
  • Chinese officials may target Broadcom (AVGO) and Synopsys (SNPS) with probes and are building a list of US tech firms for potential probes, according to WSJ.
  • Japanese PM Ishiba expressed optimism on Sunday that Japan could avoid higher US tariffs as noted that President Trump had “recognised” Japan’s huge investment in the US and the American jobs that it creates.
  • Australian PM Albanese said Australia will urge the US to give Australia exemption over steel tariffs.
  • Indian PM Modi is prepared to discuss reducing import tariffs and buying more energy and defence equipment from the US when he meets with US President Trump next week, according to Indian officials cited by Bloomberg.
  • German Chancellor Scholz said the EU could act in an hour when asked in a pre-election debate if the EU was prepared for possible US tariffs.

d


A more detailed look at global markets courtesy of Newsquawk

APAC stocks saw mixed price action as participants reflected on last Friday’s NFP print and President Trump’s latest tariff remarks in which he stated they will be announcing on Monday 25% tariffs on all steel and aluminium coming into the US and will announce reciprocal tariffs on Tuesday or Wednesday, while China’s retaliatory tariffs against the US took effect. ASX 200 declined with the index led lower by underperformance in tech and telecoms, while miners also suffered owing to the US tariff threat although Australia will urge the US to give Australia exemption over steel tariffs. Nikkei 225 retreated at the open but the clawed back its losses as a weaker currency provided a cushion and with some optimism from Japanese PM Ishiba that Japan could avoid higher US tariffs following his recent meeting with US President Trump. Hang Seng and Shanghai Comp were positive following the recent CPI data from China which showed an acceleration and with the outperformance in Hong Kong led by notable strength in tech and telecom stocks. Nonetheless, the gains in the mainland were limited by the tariff and trade frictions after China’s retaliatory tariffs against the US took effect and with officials also said to be building a list of US tech firms for potential probes.

Top Asian News

  • China appoints Zou Lan as deputy PBoC Governor.
  • Shein reportedly asked China suppliers to add production lines in Vietnam, according to Bloomberg.
  • India’s Finance Minister Sitharaman said a new income tax bill will be introduced in parliament in the week ahead.

European bourses (STOXX 600 +0.4%) are modestly firmer across board, after a mixed APAC session overnight. European sectors hold a positive bias, but with the breadth of the market fairly narrow; Energy takes the top spot, lifted by gains in BP (+6%) after Elliott Management took an activist stake in the company. For the autos sector, it was reported on Friday that the EU is offering to lower tariffs on US car imports to avoid a trade war with the US. Mining names in Europe are generally on the backfoot today, with losses driven by commentary via US President Trump who said that he will be announcing 25% tariffs on all steel and aluminium coming into the US.

Top European News

  • German Economy Ministry spokesperson said they are doing everything they can to avoid tariff increases
  • Maersk (MAERSKB DC) said the security risk for commercial vessels in the Red Sea and Bab-el-Mandeb strait remains high, will continue to sail via The Cape of Good Hope until safe passage through the area is ensured.
  • European Commission said have not receive any official notification regarding imposition of additional tariffs on EU goods.
  • French Foreign Minister, said “of course we will respond to Trump’s tariff announcement” and will call on the EU to respond to Trump tariffs.
  • ECB de Guindos said it is very important to avoid a trade war, have to have prudent and intelligent approach regarding latest tariff announcement. Analysis regarding tariffs is that it leads to impact on supply, inflation is less clear. Have to take into account all factors on monetary policy. Decision on policy will be taken meeting-by-meeting, see inflation converging to the “our” goal
  • UK Health Minister Andrew Gwynne was fired by PM Starmer over his WhatsApp messages which insulted constituents, fellow MPs and councillors.
  • French President Macron said France will announce during the Paris AI summit opening on Monday EUR 109bln investments in AI over the coming years.
  • Germany’s election front-runner Merz said he was open to reforming Germany’s borrowing rules amid pressure regarding defence spending financing, according to the FT.

FX

  • DXY has started the week off on the front foot in the wake of Friday’s NFP report and weekend trade developments. On the latter, US President Trump said he will announce 25% tariffs on all steel and aluminium coming into the US on Monday and unveil reciprocal tariffs on Tuesday or Wednesday which will go into effect almost immediately. Today’s docket sees the release of US employment trends and NY SCE. DXY briefly eclipsed Friday’s 108.31 high with a session peak at 108.44.
  • EUR is steady vs. the USD with the week commencing on a negative footing when it comes to trade; EU remains in Trump’s sights, but the FT reported late last week that the EU is set to offer lower tariffs on US cars. EUR/USD briefly made its way onto a 1.02 handle with a session low at 1.0281 before returning back above the 1.03 mark – ECB’s Schnabel and President Lagarde are due.
  • GBP is a little firmer today vs the USD and EUR, but with UK specific newsflow fairly light thus far; all focus will be on BoE’s Mann – she has traditionally been an arch-hawk, so her remarks will be of great importance for any insight on her decision to opt for a 50bps cut vs expectations of a 25bps reduction. Cable currently sits in a 1.2370-1.2414 range.
  • JPY is the laggard vs the Dollar. On the weekend, PM Ishiba expressed optimism on Sunday that Japan could avoid higher US tariffs. As it stands USD/JPY trades towards the upper end of a 151.25-152.53 range; further upside could see a test of its 200 DMA at 152.76 and then its 100 DMA at 152.97 thereafter.
  • Antipodeans are mixed, with slight outperformance in the Aussie, which is outmuscling the Kiwi in the AUD/NZD cross; the Antipodes were initially hampered by the Trump tariff announcements, but the downside has seen waned as the Dollar gave back the initial upside. Australian PM Albanese said Australia will urge the US to give Australia exemption over steel tariffs.
  • PBoC set USD/CNY mid-point at 7.1707 vs exp. 7.3050 (prev. 7.1699).

Fixed Income

  • USTs are essentially flat and with price action rangebound thus far, trading within a very narrow 109-02+ to 109-09 range; markets are digesting the jobs report on Friday as well as fresh tariff announcements from President Trump regarding 25% levies on all steel and aluminium coming into the US (more details on Monday). Today’s docket sees the release of US employment trends and NY SCE.
  • Bunds marginally higher in what has been a recent run of consolidation for German paper. Macro focus for the broader EZ-region has been on the implications of Trump tariff threats over the weekend (detailed above). If the EU is finally dragged into the trade war in a material way, the market will likely focus on the negative growth implications for the region. Mar’25 Bunds are currently tucked within Friday’s 132.95-133.69 range with the corresponding 10-year yield towards the middle of the 2.35-2.40% range. ECB President Lagarde is due to speak later today.
  • UK paper a touch higher after an indecisive session on Friday. Global trade is the main macro focus today for global markets, however, it remains to be seen how much of a negative this will be for the UK given that rhetoric towards the UK from the Trump administration has been tempered on account of Trump’s relationship with PM Starmer and the lack of goods trade imbalances between the two nations. Mar’25 Gilts are currently tucked within Friday’s 92.94-93.87 range; BoE’s Mann (who surprisingly voted for a 50bps cut last week) is due to speak later.

Commodities

  • A firmer session for the crude complex thus far, with upside facilitated by US President Trump’s tariff announcement on steel/aluminium, and as markets await reciprocal tariffs on Tuesday/Wednesday. In geopolitics, Trump commented that he spoke with Russian President Putin regarding ending the Ukraine war although offered very few details including when the call took place. WTI sits towards the upper end of a USD 70.84-71.86/bbl range.
  • Firmer trade across contracts with European Nat Gas rising to a two-year peak to levels last seen in February 2023 – with desks citing colder temperature and tight storage.
  • Precious metals are firmer with gold and silver both advancing to a similar degree, whilst Palladium is higher but to a lesser degree. Focus has been on the yellow-metal, which once again printed a fresh ATH, this time above USD 2900/oz; current peak at USD 2,906.25/oz.
  • Copper futures are subdued after rangebound APAC trade, with tariff concerns and implications continuing to weigh on sentiment in the complex. 3M LME copper resides in a USD 9,379.35-9,477.95/t range at the time of writing.
  • Iraq set Basrah medium crude official selling price to Asia at a premium of USD 2.65/bbl vs Oman/Dubai average and to Europe at a discount of USD 1.25/bbl vs Dated Brent, while it set the OSP to North and South America at a discount of USD 0.65/bbl vs ASCI, according to SOMO.
  • Estonia, Latvia and Lithuania have completed decoupling from the Russian power grid as planned and successfully synchronised their electricity systems to the European continental power grid.
  • Indian LNG buyers are said to be in talks for more US supply ahead of Indian PM Modi’s trip to the US, according to Bloomberg.
  • India’s Oil Secretary said Indian oil companies open to buy stake in US LNG projects.

Geopolitics: Middle East

  • “Negotiations for the second phase of the Gaza agreement have not started and Netanyahu has broken their date due to his visit to the United States”, according to Sky News Arabia citing Hamas leader. “Hamas leader Musa Abu Marzouq told Sky News Arabia: We expect that the negotiations will proceed and take their normal course”.
  • Iranian Defense Minister said “It is not possible to reach an agreement with the current US government on the nuclear agreement”, via Sky News Arabia.
  • Israeli PM Netanyahu dispatched a delegation to Qatar’s Doha for the next phase of ceasefire talks.
  • Israeli military said operations in the northern West Bank expanded to Nur Shams, while it added that several terrorists were killed and wanted suspects were detained. It was separately reported that Israel’s army confirmed it received three hostages and said it struck a Hamas weapons depot in Syria.
  • US President Trump said he is committed to buying and owning Gaza and may give sections to other states in the Middle East to rebuild it, while he added that they will make Gaza into a good site for future development. Trump also said that he will be meeting with Saudi Arabia’s Crown Prince MBS and Egyptian President Sisi, as well as noted that Middle Eastern nations will take Palestinians after those nations speak to him.
  • Hamas official condemned US President Trump’s remarks on Gaza ownership and said that Palestinians will foil all displacement plans, according to Reuters.
  • Turkish President Erdogan said that they have no need to discuss or take seriously US President Trump’s Gaza plan, while he added that no one has the power to remove the people of Gaza.
  • Qatar condemned statements by Israeli PM Netanyahu on establishing a Palestinian state inside Saudi territory.
  • Iran’s Supreme Leader Khamenei met with visiting top Hamas leaders in Tehran.
  • Egypt’s Foreign Minister heads to Washington for talks with US officials, according to AFP.

Geopolitics: Ukraine

  • US President Trump said on Friday that he has spoken to Russian President Putin by phone regarding ending the Ukraine war, according to the New York Post.
  • US President Trump said he does not want to talk about his conversation with Russian President Putin but believes they are making progress and expects to have more conversations with Putin. Furthermore, Trump declined to say when they talked and noted that he would meet with Putin in person at the right time, according to Reuters.
  • Russia’s Kremlin said it can neither confirm nor deny publications regarding the Putin-Trump conversation, while Russia’s envoy to the UN said Russia awaits appropriate signals from the US regarding contacts with Moscow and that Russia has not yet seen positive steps from the new US administration on disarmament, according to RIA.
  • Russian Deputy Foreign Minister said Russia has not received any satisfactory proposals to start talks on Ukraine and statements by the West and Ukraine about an immediate start on talks are nothing but buzz building, according to RIA.
  • Russian Defence Ministry said Russian forces captured Orikhovo-Vasylivka in eastern Ukraine, while it was also reported that Russia said its troops repelled three Ukrainian counterattacks in the Kursk region.
  • Russia launched a drone attack on Ukraine’s capital Kyiv, according to the Mayor.

Geopolitics: Other

  • North Korean leader Kim said the trilateral cooperation among the US, Japan and South Korea is raising a grave security challenge. It was also reported that North Korea noted its nuclear weapons are not a bargaining chip and that its nuclear forces are meant for combat against enemies that threaten global peace, according to KCNA.

US Event Calendar

  • 11:00: Jan. NY Fed 1-Yr Inflation Expectat, prior 3.00%

DB’s Jim Reid concludes the overnight wrap

The week after payrolls is usually quiet but due to the first Friday of the month being the latest it could possibly be this month, then we bump straight into US CPI (Wednesday) week, with PPI (Thursday) for an added bit of inflationary sparkle. Outside of this the main highlight will be Powell’s semi-annual monetary policy testimony before the Senate Banking Committee (tomorrow) and the House Financial Services Committee (Wednesday). The latter comes after CPI which will possibly spread the interest level over the two appearances rather than most of the focus being on the first as per usual. Elsewhere in the US, watch out for the NY Fed inflation expectations series today after a stronger equivalent from the University of Michighan survey just before the weekend on Friday. After that we wait until this Friday for the other important US data, namely retail sales and industrial production.

In Europe we have the UK Q4 GDP reading on Thursday following last week’s BoE meeting (our UK economist’s recap is here). Elsewhere in the region, January CPIs are due in Denmark and Norway today, and Switzerland on Thursday. In terms of earnings we have 75 S&P 500 companies and 79 Stoxx 600 companies reporting.

The tariff news will clearly continue to dominate the agenda all week, especially after Mr Trump announced on Friday that he’d be holding a press conference early this week on the US plans for equalising tariffs on “reciprocal trade” with an added mention for autos. Then on Air Force One last night Mr Trump said he would put 25% tariffs on steel and aluminium imports later today. Canada, Mexico and Latin America would be the most impacted given that’s where the US imports most of these goods from.

Looking forward now and in terms of Powell’s testimonies this week, the overarching message is likely that the Fed is not in a hurry to cut rates at the moment, with Friday’s payrolls and to a lesser extent the UoM inflation expectations series the latest support to that message. Even though headline (+143k) and private (+111k) payroll gains were below expectations, net upward revisions of 100k over the prior two months, a decline in the unemployment rate to 4.0% (4.1% expected), and average hourly earnings +0.5% on the month (vs. +0.3% expected), made it a hawkish report.On top of that, the annual benchmark revision to the level of March 2024 nonfarm payrolls (-598k final vs. -818k preliminary) was not as large as the BLS had previously projected. See our economists’ US employment chart book here for everything you wanted to know about the labour market post this release.

For those inflation expectations last Friday the 1yr level was up to 4.3% (expected 3.3%) and the more important 5-10yr one at 3.3% (expected 3.2%). If confirmed in the final reading the longer-term expectations have only been higher for one month (June 2008) since 1995. This series continues to be ridiculously partisan post the election though with the 1-yr number seen around 5% from Democrat supporters and around zero for Republicans. So how reliable this number is at the moment is open is debatable.

Talking of inflation, strong seasonally adjusted gains in food and energy prices should keep headline CPI (+0.31% forecast vs. +0.39% previously) above core (+0.28% vs. +0.23%). YoY headline CPI should remain roughly steady at 2.9%, while that for core would just round down to 3.1%. OER will continue to be a big focus. For PPI it‘s as ever the components that go into core PCE that will gain all the attention.

Continuing with inflation, on Sunday data from China showed that consumer inflation (+0.5% y/y) accelerated at its fastest in five months in January (v/s +0.4% expected), up from December’s +0.1% increase, mainly because of the brisk consumption seen in the recently concluded Spring Festival holidays. At the same time, producer price deflation persisted as the PPI (-2.3% y/y) fell for a 28th consecutive month. The decline was marginally faster than Bloomberg’s estimate of -2.2% while matching December’s contraction.

Chinese risk is doing well this morning with the Hang Seng (+1.80%) leading the way with the Shanghai Composite (+0.50%) also higher. Other markets are a bit more subdued with the Nikkei (+0.20%) and the KOSPI (+0.13%) swinging between gains and losses. S&P 500 (+0.32%) and NASDAQ 100 (+0.60%) futures are rebounded after a weak Friday session. The yen (-0.31%) is retreating from a two-month high, trading at 151.88 against the dollar, with 10yr JGB yields +1.8bps higher at 1.32%, the highest since 2011.

Last week saw markets experience a steady overall performance, but one that was bookended by tariff-related news. At the start of the week, the imposition and then delay to tariffs on Mexico and Canada saw the S&P 500 first fall sharply but then close less than 0.6% beneath its all-time high by Wednesday. The index then fell -0.95% on Friday (and -0.24% over the week) as news broke of US reciprocal tariff plans on Friday. Tech stocks were a particular underperformer, with the Mag-7 down -2.79% (-1.95% Friday) as Alphabet’s and Amazon’s results underwhelmed. However in Europe, the STOXX 600 was up +0.60% (-0.38% Friday), having hit an all-time high on Thursday. And there was also a strong performance for emerging markets, with the MSCI EM index up +1.38% (+0.57% Friday).

The hawkish data on Friday led investors to dial back their expectations for rate cuts this year, with just 36bps now priced in by the December meeting, which is the fewest in over three weeks and a turnaround from the 50bps priced intra-day on Wednesday. This helped trigger a significant selloff for Treasuries at the end of the week, which saw the 10yr yield up +6.1bps on Friday to 4.50%, even though the 10yr yield was still down -4.5bps over the week as a whole. In Europe, 10yr bund yields fell -8.8bps last week to 2.37%, including a -0.7bps decline on Friday as tariff risks outweighed the read-across from stronger US data.
Tyler Durden
Mon, 02/10/2025 – 08:24

Why A Chinese Gold Mania May Be Starting

0
Why A Chinese Gold Mania May Be Starting

By Jesse Colombo of The Bubble Bubble Report

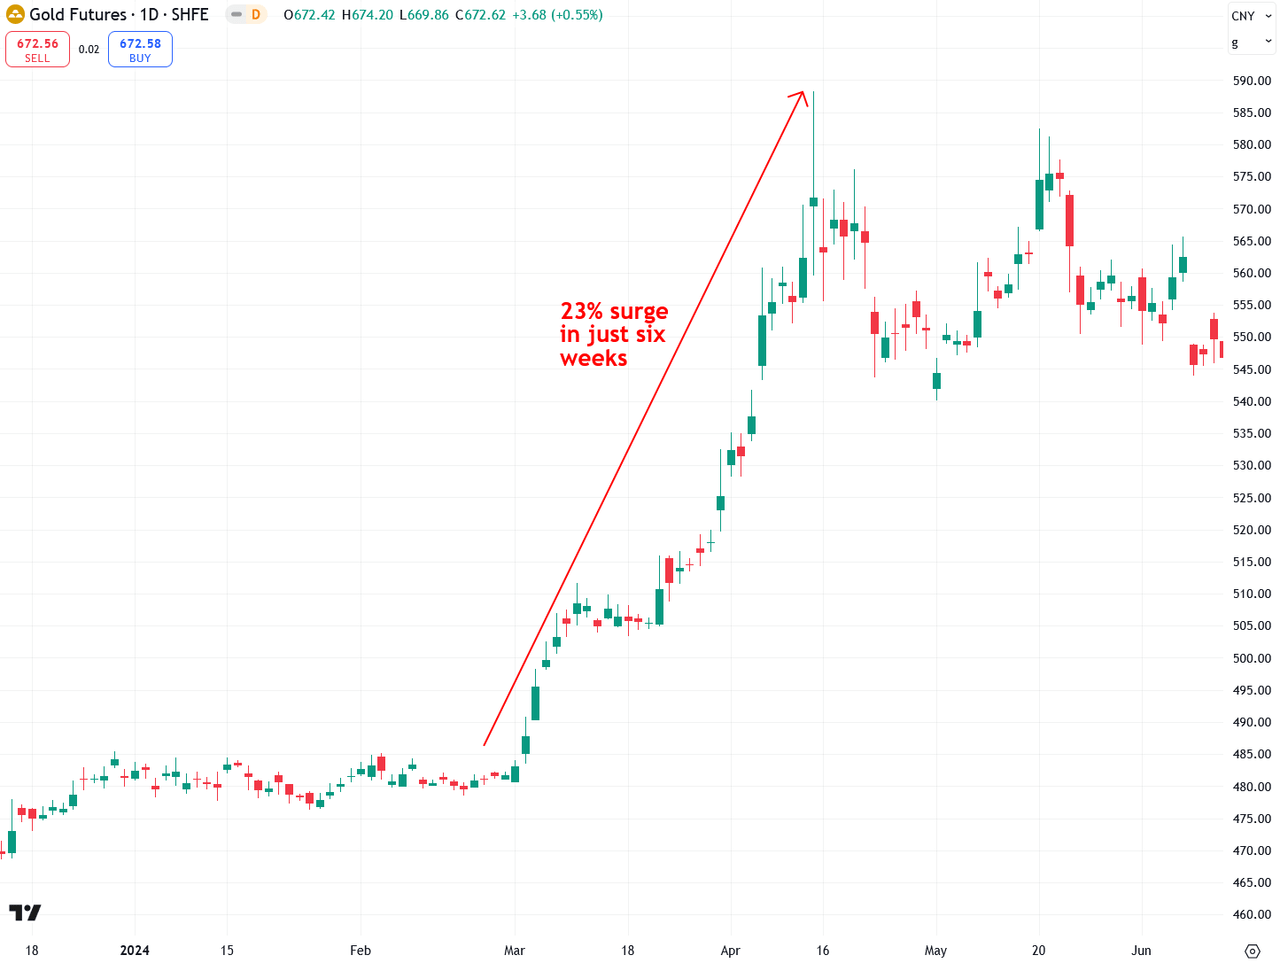
The current gold bull market began in the spring of 2024, fueled in large part by aggressive Chinese futures traders on the Shanghai Futures Exchange (SHFE), while Western investors remained largely on the sidelines. In just six weeks between March and April, these traders propelled gold prices up by $400, or 23%—an extraordinary surge for the yellow metal. Since then, their activity has quieted, but I’ve anticipated their return, expecting them to push gold to truly staggering levels. That moment may have arrived. Fresh off the week-long Chinese Lunar New Year holiday, these traders are reentering the market—just as gold was already heating up without them.

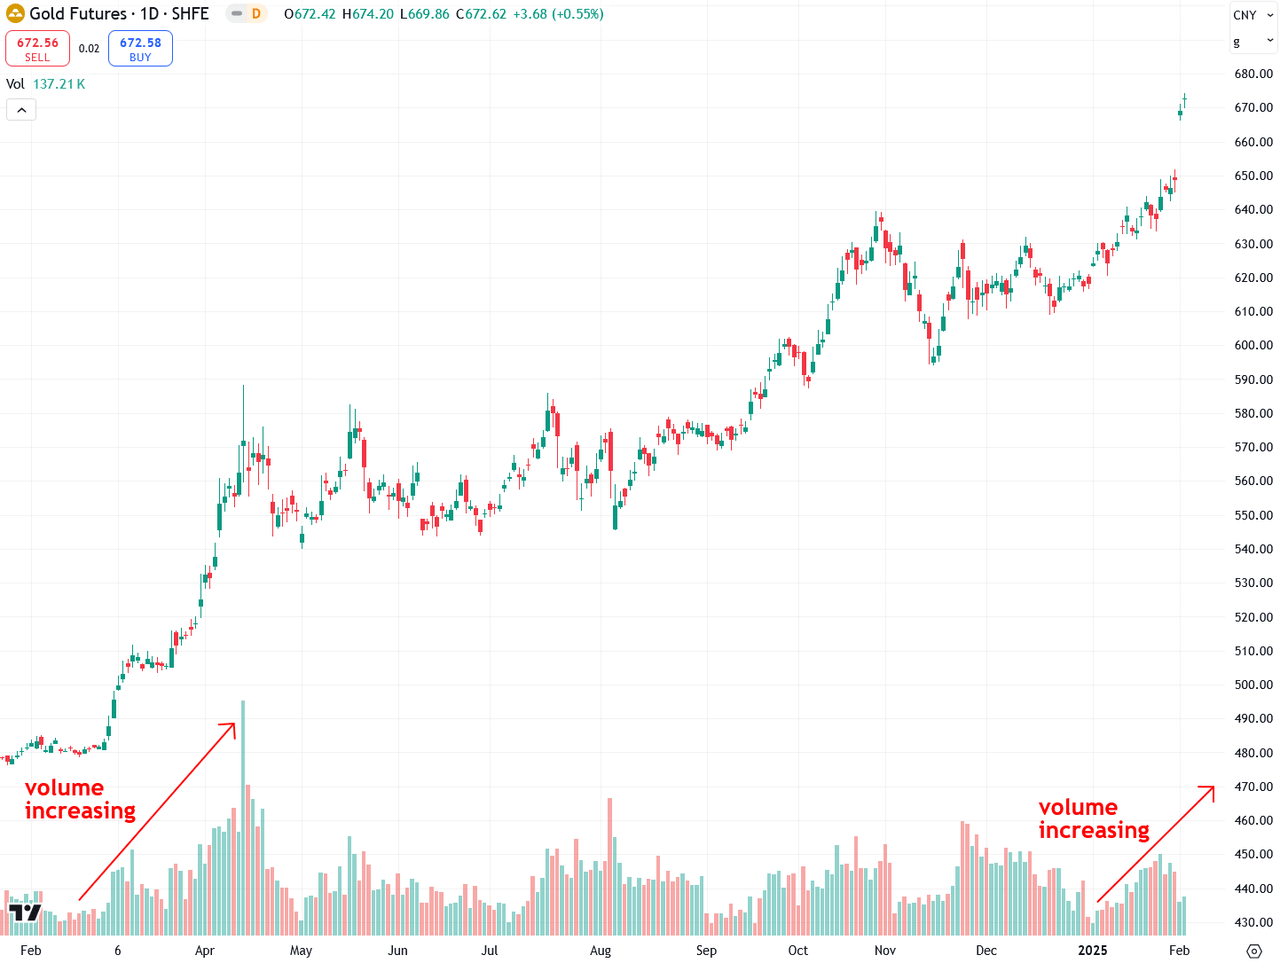
The Shanghai Futures Exchange gold futures were the primary vehicle behind the spring 2024 gold frenzy, a surge that subsequently spilled over into international gold prices:

A fascinating Financial Times article from that time titled “Chinese Speculators Super-Charge Gold Rally” highlighted how trading volume in SHFE gold futures had surged by 400%, propelling gold prices to record highs:

The spring Chinese gold trading frenzy can also be seen in the chart of long open interest in SHFE gold futures:

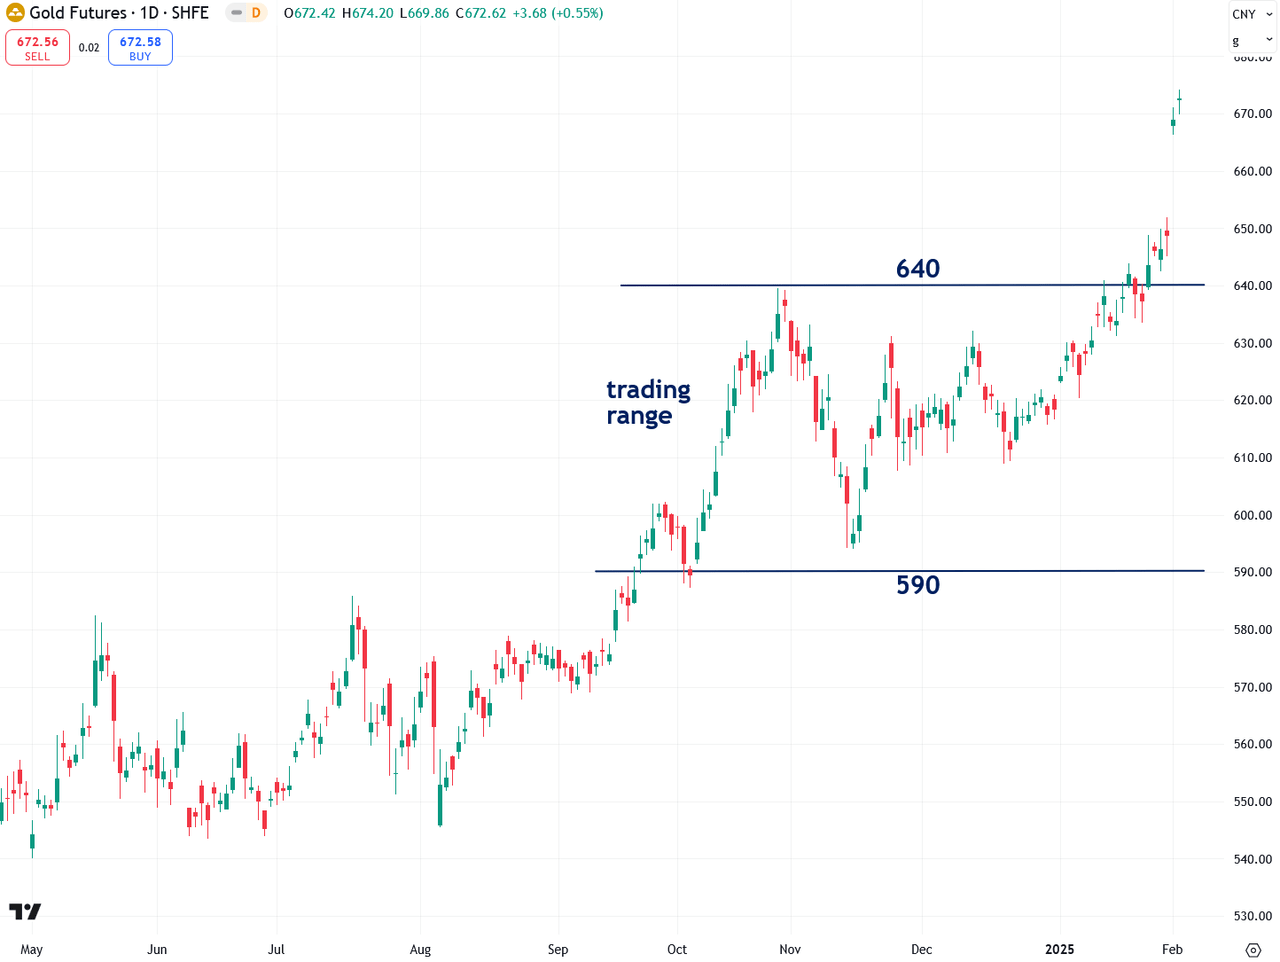
Over the past year, SHFE gold futures have mirrored the international gold price, steadily rising before consolidating in a trading range from late October to January. But as soon as China’s financial markets reopened this week after the Lunar New Year holiday, SHFE gold futures gapped higher, swiftly catching up to the international rally that unfolded while China was offline. This breakout signals strong bullish momentum, suggesting even greater gains lie ahead.

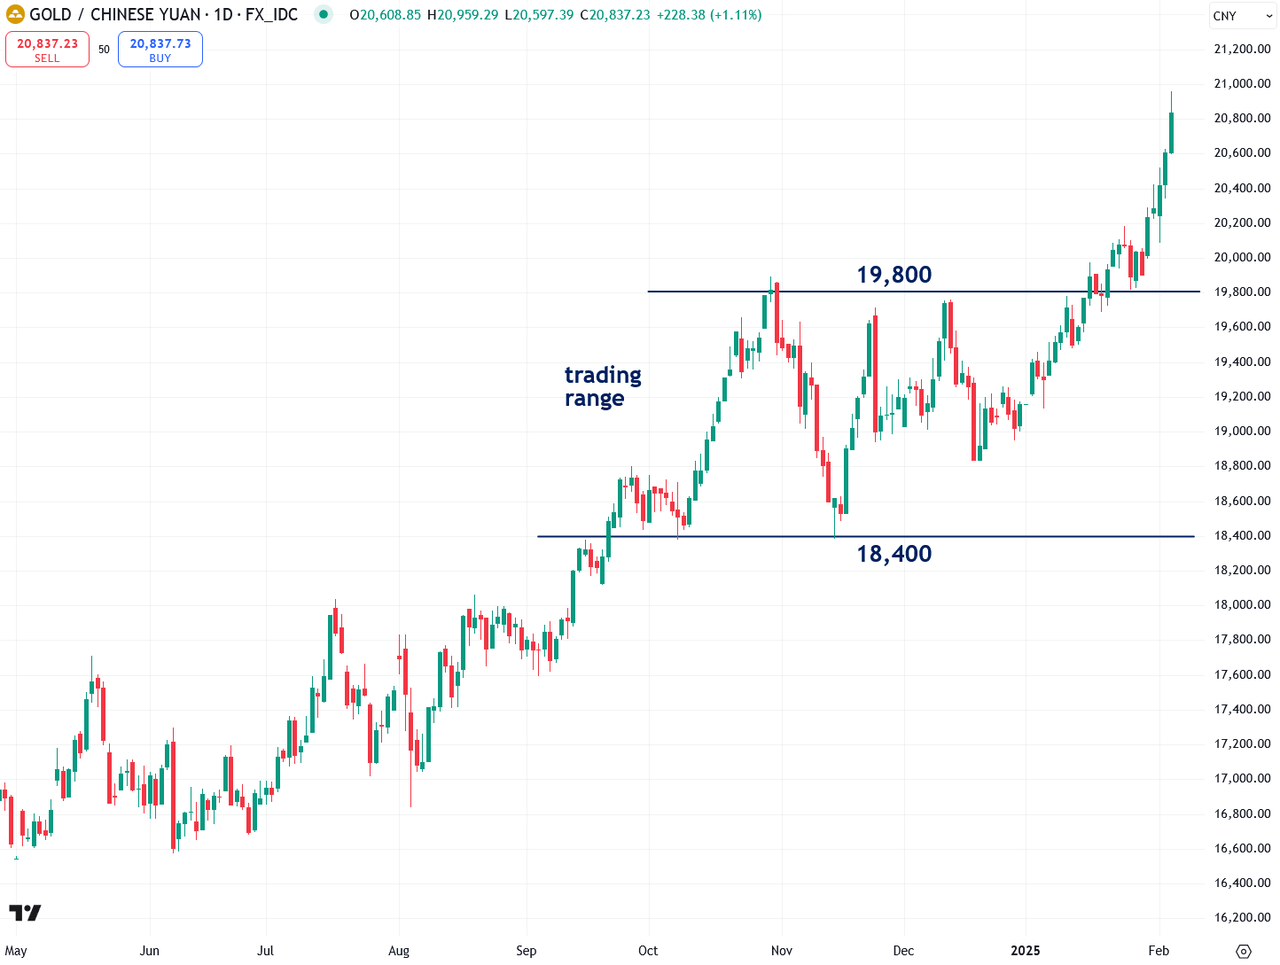
The trading range and recent breakout are also evident in the international spot gold price denominated in Chinese yuan, providing further confirmation of the bullish trend:

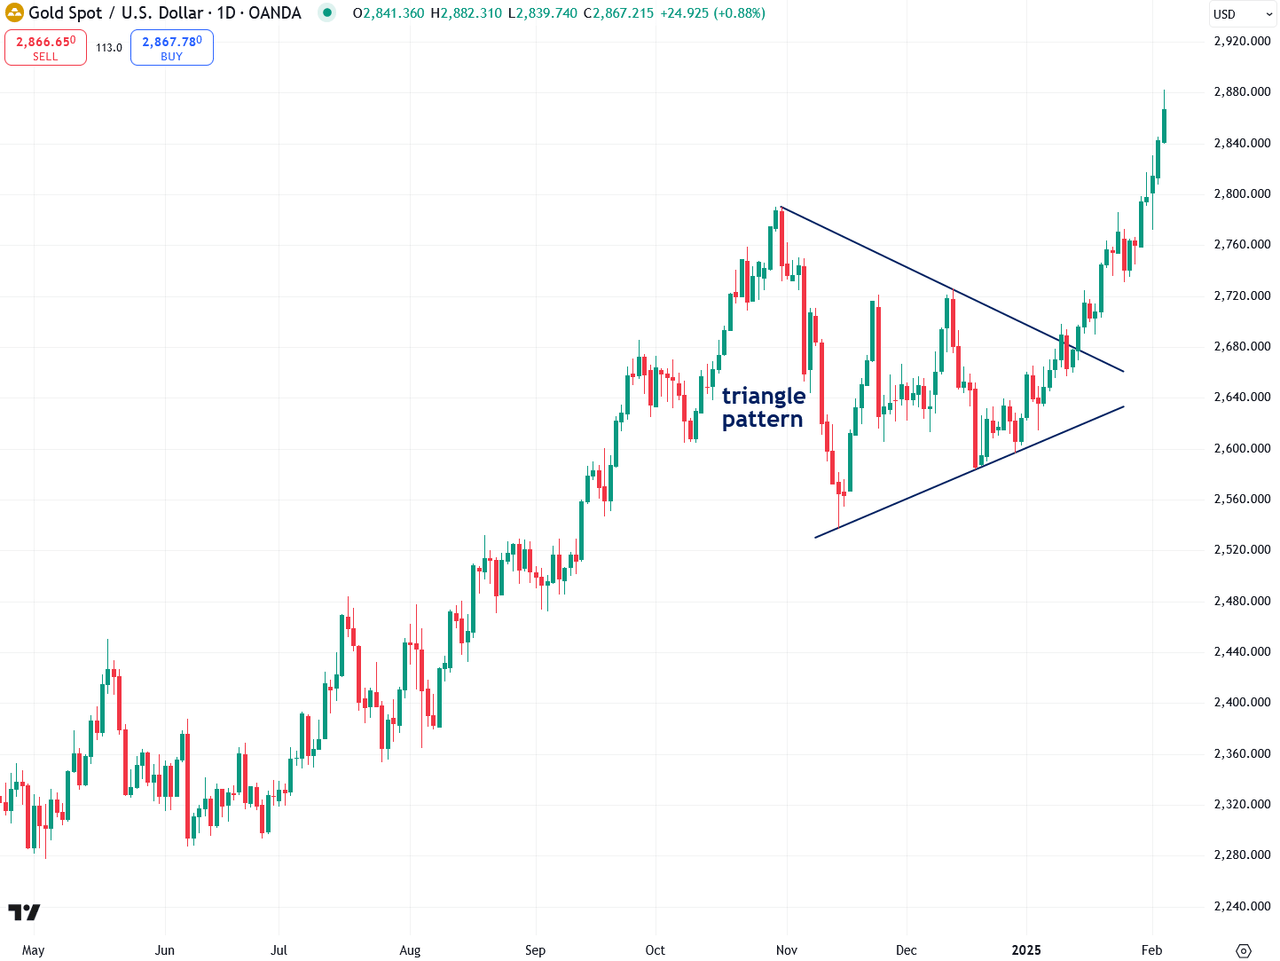
As I had anticipated back in December, the spot price of gold in U.S. dollars also recently broke out of a triangle consolidation pattern, confirming the bullish momentum:

I believe all the key ingredients for another China-driven gold mania—similar to last spring—are now in place. It may only be a matter of time. A key indicator to watch is trading volume in SHFE gold futures, which you can track on TradingView under the symbol AU1!. Last spring, a surge in volume accompanied gold’s explosive rally. So far, volume has remained subdued, but it’s likely to increase as the rally gains momentum. For confirmation, I’m looking for a significant spike in volume to validate this thesis.

Another key indicator of a potential Chinese gold mania is whether the domestic Chinese gold price trades at a premium to the international price. During last spring’s explosive rally, the domestic price carried a premium of approximately $50 over the international price. Currently, there is little to no premium or discount, but it’s worth watching closely. If a significant premium emerges, it would likely signal that Chinese demand is once again driving gold higher.

A major catalyst for a potential Chinese gold mania is the country’s severe economic turmoil. With its real estate and stock markets plunging, an estimated $18 trillion in household wealth has been wiped out—an economic crisis akin to China’s version of the 2008 Great Recession. Meanwhile, government bond yields have collapsed to record lows, signaling a deepening deflationary spiral. In low-interest-rate environments like China’s, gold— which generates no yield—becomes more attractive as the opportunity cost of holding it diminishes. Additionally, China is likely to respond with a massive stimulus “bazooka” to combat deflation, which should provide a powerful tailwind for gold, silver, and other commodities.

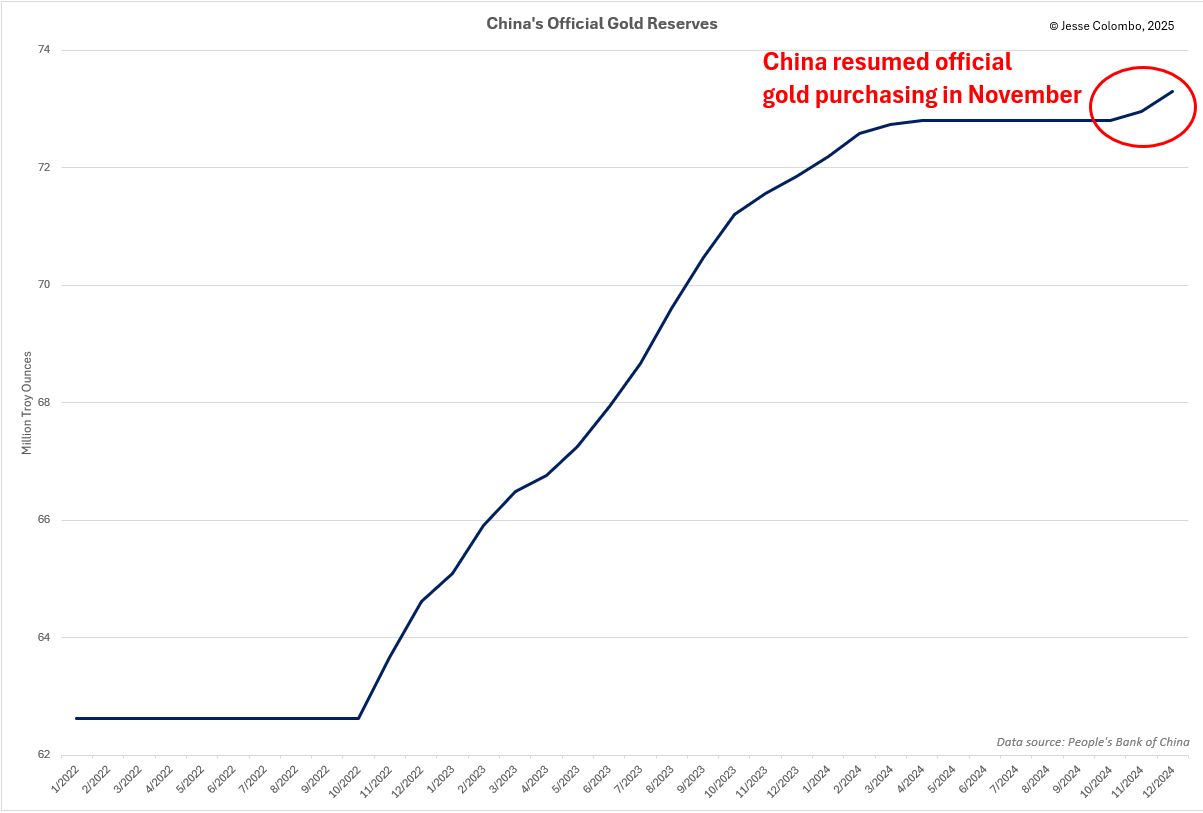
Another potential catalyst for a Chinese gold mania is the People’s Bank of China’s (PBOC) recent resumption of official gold purchases after a six-month pause. As I recently explained, the PBOC was likely accumulating gold all along, but its decision to publicly announce renewed purchases appears to be a strategic move aimed at encouraging domestic gold buying. This aligns with China’s broader strategy of diversifying away from U.S. dollars and increasing gold holdings across all levels of society.

All signs point to the potential for another explosive gold rally driven by Chinese traders, much like what unfolded last spring. With SHFE gold futures breaking out, the possibility of rising trading volumes, and the return of a Chinese gold price premium, the conditions for another bullish episode are falling into place. China’s economic crisis, record-low bond yields, and the looming prospect of massive stimulus only strengthen the case for gold’s continued ascent. Meanwhile, the PBOC’s renewed gold purchases reinforce the broader shift toward gold as a preferred asset. If these factors align as expected, the next phase of this bull market could be even more dramatic than what we saw in 2024.

If you found this report valuable, click here to subscribe to this popular newsletter for just $15 a month—less than 50 cents a day—to stay informed and gain deeper insights into the precious metals market and overall economy.

Tyler Durden
Mon, 02/10/2025 – 08:05

Trump Ends Lawsuit Against Twitter Over Post-Jan. 6 Suspension

0
Trump Ends Lawsuit Against Twitter Over Post-Jan. 6 Suspension

Authored by Bill Pan via The Epoch Times (emphasis ours),

President Donald Trump has ended his lawsuit against Twitter over the platform’s decision to ban him following the Jan. 6, 2021, breach of the U.S. Capitol.

Pro-Trump supporters storm the U.S. Capitol following a rally with President Donald Trump in Washington on Jan. 6, 2021. Samuel Corum/Getty Images

In a notice filed Friday with the U.S. Court of Appeals for the Ninth Circuit, legal teams for both sides requested that the court dismiss Trump’s pending appeal. The notice did not say whether Elon Musk, who acquired Twitter and rebranded it as X, had agreed to any terms to resolve the case.

In July 2021, Trump filed separate cases against Twitter, Facebook, and Google’s YouTube over similar measures they took to restrict his use of those sites. Twitter said at the time that Trump’s messages—including one in which he stated he would not be attending incoming President Joe Biden’s inauguration—were “highly likely” to inspire more violence.

Trump’s lawsuits centered on free speech violations. While private companies ordinarily have no legal obligation to honor free-speech rights, the suits alleged that Twitter and other platforms were essentially acting as agents of Democratic members of Congress who wanted him deplatformed.

“Legislators … made it increasingly clear that they wanted President Trump, and the views he espoused, to be banned from Defendants’ platform,” the complaint alleged, citing multiple statements from Democratic lawmakers urging Big Tech to take action against Trump.

The suits were initially filed in Florida but were later moved to federal court in California at the companies’ request. In May 2022, a San Francisco judge dismissed the case against Twitter and its former CEO Jack Dorsey, ruling that Twitter was not acting as a government agent when it suspended Trump. Trump appealed the decision to the Ninth Circuit.

All three platforms eventually dropped the bans. Musk, a self-described free speech absolutist who is now a core adviser to Trump, restored Trump’s account in November 2022, just days after Trump announced his candidacy for the 2024 presidential race.

Attorneys for Twitter have argued that Trump’s case was moot since his account had been reinstated under Musk’s revised content moderation policies. However, the case lingered on, since at least two pro-Trump advocates who joined the lawsuit didn’t have their accounts restored.

Since winning reelection, Trump has secured favorable settlements with tech and media companies he accused of defaming or mistreating him.

In December 2024, ABC News agreed to pay $15 million toward Trump’s future presidential library to settle a defamation lawsuit over anchor George Stephanopoulos’s on-air claim that Trump had been found “liable for rape.” The settlement labeled ABC’s payment as a “charitable contribution” earmarked for the yet-to-be-built library.

In January, Meta agreed to pay $25 million to resolve Trump’s suit over his suspension from Facebook and Instagram. Approximately $22 million of that amount will go toward Trump’s presidential library, with the remainder covering legal fees and other plaintiffs.

Tyler Durden
Mon, 02/10/2025 – 07:45

17 Percent Of US Homeowner Mortgages Are At 6 Percent Interest Or Higher: Report

0
17 Percent Of US Homeowner Mortgages Are At 6 Percent Interest Or Higher: Report

Authored by Naveen Athrappully via The Epoch Times (emphasis ours),

The share of homeowners with 6 percent or more mortgage rates is at its highest level in nearly a decade, according to real estate brokerage Redfin, which added that the “lock-in effect” in the housing market has started to ease.

A home available for sale is shown in Austin, Texas, on May 22, 2024. Brandon Bell/Getty Images

The company said 17.2 percent of homeowners have a 6 percent or higher rate, which is the largest proportion since 2016.

“That’s up nearly five percentage points from 12.3 percent in the third quarter of 2023,”the company said in a Feb. 6 statement. “If this growth rate were to continue, which is feasible, the share of homeowners with a rate of at least 6 percent would nearly double in the next three years.”

Meanwhile, the share of homeowners with an interest rate less than 6 percent stands at 82.8 percent. As such, an even higher share of owners have a rate below the Jan. 30 weekly average rate of 6.95 percent, said the report.

This is “prompting many to stay put instead of selling and buying another home at a higher rate.” The phenomenon, called the “lock-in effect,” dries up housing supply, thus supporting price growth and contributing to the affordability crisis.

However, the lock-in effect is showing signs of easing as “it’s not realistic to stay put forever” for most individuals,” Redfin stated. Many people are opting to move despite the higher rates because of major life events like a divorce or job change that leave them with no choice, Redfin said, citing its agents.

“Many Americans are growing accustomed to the idea that rates are unlikely to fall to pandemic lows anytime soon,” the Redfin report stated.

Rates hit a record low of 2.65 percent during the COVID-19 pandemic, the brokerage said. The average weekly rate for a 30-year fixed-rate mortgage has remained above the 6 percent level for more than two years, according to data from Freddie Mac.

Moreover, the “pandemic surge in home values means many homeowners have enough equity to justify selling and taking on a higher rate—especially if they’re downsizing or moving somewhere more affordable,” said the report.

Data from the Federal Reserve Bank of St. Louis shows that the average sales price of houses sold in the United States in Q1, 2020, was $383,000. This has jumped more than 33 percent to $510,300 as of Q4, 2024.

Growing Rental Market

Mortgage applications to buy homes have declined amid high rates. According to the Mortgage Bankers Association (MBA), while overall mortgage applications rose 2.2 percent for the week ending Jan. 31 compared to a week back, the jump was driven by a 12 percent increase in refinances.

“Purchase activity had a tougher week, with declines across all loan types,” said MBA Deputy Chief Economist Joel Kan. “The average loan size for a purchase loan has increased since the start of the year.”

Sam Khater, chief economist at Freddie Mac, said that mortgage rates have remained stable over the last month, with data suggesting the economy to be on a “firm footing.”

Mortgage purchase applications over the last two weeks are “modestly above what we saw a year ago,” he said. This suggests there is “some latent demand in the market.”

With buying a house becoming increasingly costly, the build-to-rent market is growing nationwide, according to a recent report by real estate listing portal Point2Homes. Build-to-rent properties are built specifically for renting out.

There are currently 110,727 new single-family build-to-rent homes under construction in the United States across 613 communities, according to the report.

State-wise, Texas had the highest number of build-to-rent homes under development, with 21,812 homes at various stages of construction. It was followed by Arizona and Florida with nearly 14,000 properties, and North Carolina with more than 12,000 units.

Doug Ressler, manager of business intelligence at Yardi Matrix, a sister company of Point 2Homes, said renting a build-to-rent home is cheaper on average than buying a starter home.

“Recent reports indicate that renting can save one around $1,000 per month compared to buying. This is largely due to high mortgage rates and elevated home prices,” Ressler said.

“More and more build-to-rent (BTR) residents consider themselves renters by preference compared to 2023 (36 percent in 2024 vs. 27 percent in 2023).”

Tyler Durden
Mon, 02/10/2025 – 05:45