66.3 F
Chicago
Wednesday, September 30, 2026
Home Blog Page 2364

Watchdog Group Says FBI Is Hiding Records On Trump Assassination Attempt

0
Watchdog Group Says FBI Is Hiding Records On Trump Assassination Attempt

Authored by Paul Joseph Watson via Modernity.news,

A leading watchdog group says the FBI is hiding records relating to its coordination with the Secret Service for the rally during which an assassin tried to kill Donald Trump.

The FBI cited FOIA exemption 7(A) to protect ongoing enforcement proceedings surrounding the incident on July 13 in Butler, PA, when gunman Thomas Crooks was able to shoot at Trump despite being spotted behaving suspiciously hours beforehand.

Judicial Watch sent an FOIA request on July 26th asking the FBI to produce all relevant documents pertaining to its preparation and coordination with the Secret Service for Trump’s rally.

However, the group has been stonewalled by the FBI, leaving questions as to why there was seemingly a delay in taking out Crooks before the shooting unanswered.

“Why is the FBI hiding records on its and the Secret Service’s failures to protect Trump?” asked Judicial Watch president Tom Fitton.

“The Biden-Harris administration is covering up the near assassination of former President Trump.”

“The FBI’s refusal to release these records raises serious concerns,” comments journalist Sharyl Attkisson.

Despite the motive behind the shooting still not being known, it has almost completely disappeared from the headlines within the space of a single month.

As we previously highlighted, Senator Ron Johnson, who chairs the committee overseeing the investigation into the attempted assassination of Donald Trump, has warned that the FBI cannot be trusted.

“You know I do not trust the FBI do this investigation, honestly,” Johnson said in response to claims by FBI Deputy Director Paul Abbate that the feds had discovered comments posted by shooter Thomas Crooks that espoused “anti-Semitic and anti-immigration themes.”

Last week it was revealed that Crooks’ body was cremated just 10 days after the assassination attempt, leading some to assert that this was part of an attempt to cover up evidence.

*  *  *

Your support is crucial in helping us defeat mass censorship. Please consider donating via Locals or check out our unique merch. Follow us on X @ModernityNews.

Tyler Durden
Mon, 08/19/2024 – 12:05

Peter Schiff: The Fed Still Isn’t Data-Driven

0
Peter Schiff: The Fed Still Isn’t Data-Driven

Via SchiffGold.com,

In this episode, Peter analyzes recent PPI and CPI reports, reiterates his September rate-hike prediction, and comments on the Tump-Musk X interview that garnered the country’s attention on Monday. He also diagnoses the source of high housing and education costs that have made the economy feel so brutal to everyday Americans.

Peter notes how this week’s PPI report, which came in better than expected, may reveal margin pressure on American business:

“Trade services actually includes a lot of the markups that retail companies would charge, and so the fact that this number went up less than expected may indicate there’s some pressure on margins going forward and that companies are eating a larger percentage of their increased costs. And so that doesn’t bode well for earnings if that’s the case. People like Elizabeth Warren are always accusing greedy companies of gouging the customers with price hikes, but more often than not, most companies do everything they can to insulate their customers. Raising prices is almost a last resort!”

The media is celebrating a slightly better-than-expected CPI report as well, but Peter reminds us how long it took to make this progress. Such a meager improvement is not the sign of a job well done:

“The headline number, which had gotten above 9% at the peak – it first went down to 3% in June of 2023. So 13 months ago, the CPI was at 3%. Now it’s at 2.9%— 13 months later. So what? It took us 13 months to shave one tenth of one percent off the CPI? … Why should the Fed be cutting rates? If anything, the Fed should be looking at these numbers and say, ‘You know what? Rates are too low. We stopped too soon.’”

With expectations building for rate cuts next month, the Fed will likely deliver:

“I still believe that, despite this data, we’re gonna get a rate cut in September. And the main reason we’re going to get a rate cut in September is because now the markets are counting on a rate cut in September. That’s why we rallied back from the sell off on Monday! And so now that the market is pricing in a September rate cut, there’s no way that Powell is not going to deliver. … He always meets market expectations. … What he doesn’t want to do is pull the rug out from under the market.”

Peter comments on the Trump-Musk interview that aired Monday and has since drawn fire from the United Auto Workers union. They seem to be unaware of the role they played in exporting the American auto industry:

“The UAW— they helped destroy the American automobile industry. Elon Musk is trying to rebuild it! They killed jobs in the auto sector. He’s creating jobs. … The only two the UAW didn’t destroy were Ford and General Motors. There were only two auto companies left in America thanks to the UAW.”

Peter agrees with Trump’s take on the Department of Education:

“The Department of Education is  a waste of money. It doesn’t educate anybody! Just like the Department of Energy is a waste. It doesn’t produce any energy! In fact, we didn’t even have the Department of Energy until Jimmy Carter. So we don’t need it. Get rid of it! As well as a lot of other departments.”

In his closing remarks, Peter explains the source of two major problems hitting Americans’ wallets— housing prices and the diminishing value of college degrees:

“The free market brings quality up and price down. The government brings quality down and price up! … Now they say, ‘You gotta go get a college degree so you can get a job at McDonalds serving french fries.’ This is what the government has done to a college degree, and they did the same thing to housing, and Elizabeth Warren just doesn’t understand that.” 


Tyler Durden
Mon, 08/19/2024 – 09:30

House Concludes Biden “Actively Participated” In Impeachable Offenses – Except It’s Too Late To Impeach Him

0
House Concludes Biden “Actively Participated” In Impeachable Offenses – Except It’s Too Late To Impeach Him

The GOP-led House committees who have been investigating the Biden family shook their fist at the sky on Monday, announcing in a 291-page report that the president engaged in impeachable conduct by helping to enrich his family with millions of dollars through various business schemes to trade on the family name – and then defrauded voters by lying to cover it up, Just the News reports.

The House Oversight, Ways and Means and Judiciary Committees said they believe the evidence from their nine-month investigation establishes that Biden abused his office and violated his oaths under the Constitution, according to the 291-page report reviewed by Just the News. 

Obviously this would have been infinitely more helpful even a few months ago when there was time for the GOP-controlled House to take action (particularly before the DOJ concluded that Biden is too senile to prosecute), but hey – better late than never.

“First and foremost, overwhelming evidence demonstrates that President Biden participated in a conspiracy to monetize his office of public trust to enrich his family,” reads the report.

“Among other aspects of this conspiracy, the Biden family and their business associates received tens of millions of dollars from foreign interests by leading those interests to believe that such payments would provide them access to and influence with President Biden.”

Specifically, Biden and his family are accused of:

  • Foreign Payments: The Biden family reportedly received over $27 million from foreign sources, often through shell companies, with some funds directly reaching Joe Biden’s bank account.
  • Burisma Involvement: Hunter Biden was paid $1 million annually by the Ukrainian company Burisma, using his influence to support the company and allegedly shut down corruption investigations.
  • CEFC China Energy: Hunter Biden received a $5 million “interest-free” loan from entities linked to CEFC China Energy, intended to benefit the Biden family.
  • Vice Presidential Influence: Joe Biden allegedly used his position as Vice President to support his son’s foreign business ventures, meeting or speaking with his son’s business partners from Ukraine, China, Russia, and Kazakhstan.
  • $3.5 Million from Russian Oligarch: Hunter Biden’s businesses received $3.5 million from Russian oligarch Yelena Baturina shortly before a reported meeting between her and Joe Biden.
  • $8 Million in Loans from Donors: The Biden family allegedly obtained over $8 million in loans from Democratic donors, including nearly $6 million from entertainment lawyer Kevin Morris, covering various personal expenses for Hunter Biden.
  • DOJ Favoritism: IRS whistleblowers alleged that the Justice Department gave Hunter Biden preferential treatment, blocking investigations and concealing evidence to avoid charges.

According to Just the News:

The committee cited evidence that Biden “actively participated” in an influence-peddling conspiracy by attending dinners with his family’s foreign associates and speaking to them over the phone. These interactions were documented by email evidence and testimony from several of Hunter Biden’s ex-business partners, including Devon Archer and Jason Galanis.

The committees also said evidence shows Hunter Biden used his father’s official position as vice president to “garner favorable outcomes in foreign business dealings and legal proceedings.”

Beyond Biden’s conduct as vice president, the report argued the Justice Department during his presidency deviated from normal practices in order to provide favorable treatment to Hunter Biden, throwing up roadblocks in the investigation and preventing attorneys from pursuing certain avenues of inquiry, as two IRS whistleblowers testified to the House Ways and Means Committee. -Just the News

The report also alleges that Biden engaged in a coverup by lying about he and his family’s conduct.

“President Joe Biden conspired to commit influence peddling and grift,” the committees wrote. “In doing so, he abused his office and, by repeatedly lying about his abuse of office, has defrauded the United States to enrich his family.”

As JTN notes, the report is unlikely to result in a formal impeachment since Biden has stepped out of the 2024 race and is coasting towards January 2025 as the lamest of ducks.

Tyler Durden
Mon, 08/19/2024 – 09:10

Ukraine Destroys 3rd Bridge In Russia’s Kursk, Zelensky Stresses He’ll Keep Territory

0
Ukraine Destroys 3rd Bridge In Russia’s Kursk, Zelensky Stresses He’ll Keep Territory

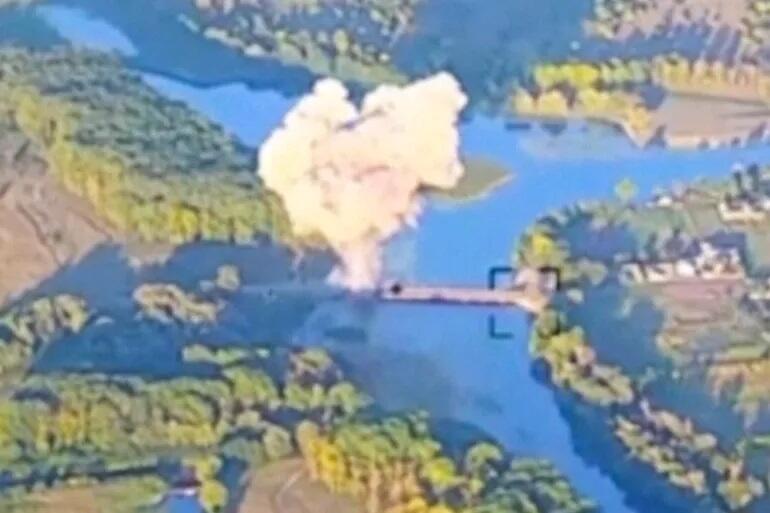
Following the Friday destruction of the strategic bridge in the Russian town Glushkovo, which lies in Kursk oblast, and the taking out of another bridge across the River Seym on Saturday, Ukraine has attacked and damaged a third bridge in the same region, Moscow has confirmed.

Russia’s Investigative Committee on Monday announced that yet another bridge located along the River Seym, which winds through the Kursk region, was destroyed in a Ukrainian attack.

Armed Forces of Ukraine via AP

Ukraine’s military has said that the targeted attacks are intended to disrupt Russian supply lines and make Russian troop and armory movement much more difficult.

“Minus one more bridge,” Ukrainian Air Force Commander Mykola Oleshchuk wrote on Telegram while publishing footage of the attack.

“The Air Force aviation continues to deprive the enemy of logistical capabilities with precision air strikes,” Oleshchuk said further.

In follow-up to this Ukrainian President Volodymyr Zelensky outlined his stated aims in detail:

“It is now our primary task in defensive operations overall: to destroy as much Russian war potential as possible and conduct maximum counteroffensive actions. This includes creating a buffer zone on the aggressor’s territory,” he said in his evening address.

He also explained how the hundreds of Russian troops captured in Kursk since the brazen cross-border operation began on Aug.6 will be used to bolster the countries “exchange fund” – a reference to the ability to get Ukrainians back through prisoner swaps.

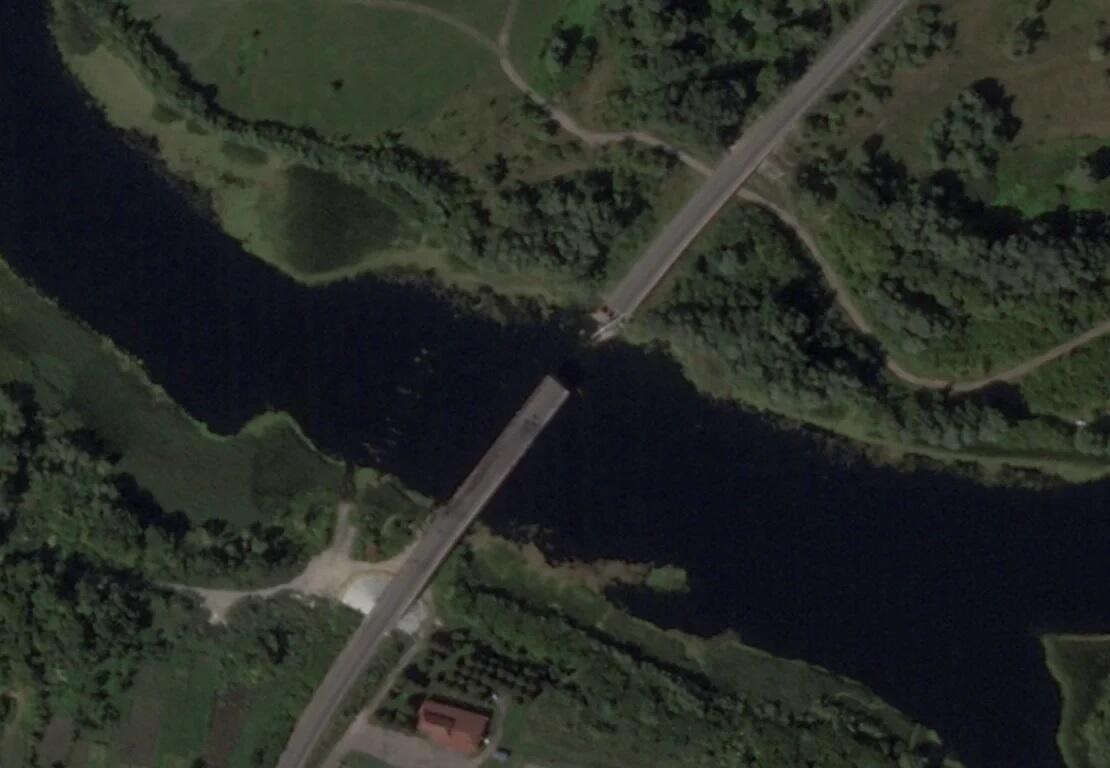
Satellite view of the second bridge which Ukraine took out Saturday, via Planet Labs/Reuters

RT has noted that “Russian President Vladimir Putin stated last month that the number of POWs held by both sides is five to one in Russia’s favor,” but now “Ukraine claims to have taken dozens of Russian border guards prisoner during the first phase of its Kursk offensive.”

Ukrainian officials have of late talked about prioritizing the return of those “who defended Azovstal” in future prisoner exchanges, many of which were made of the infamous Azov Battalion, which is well-known to have neo-Nazis in its ranks.

There are widespread reports that Ukraine has utilized US-supplied munitions, including the HIMARS system (last Friday) to strike some of these bridges. The below video is from the third bridge to be blown up.

Though impossible to confirm, Ukraine is now claiming to have seized 440 square miles of Russian territory. It also says the Kursk operation has been able to divert Moscow’s attention from the front lines in Donbass, though the degree to which infantry troops have had to be pulled and relocated to Russia’s southern oblasts for defense remains uncertain.

Tyler Durden
Mon, 08/19/2024 – 08:50

DNC Kicks Off: Day 1- Pandering, Protests, & ‘POTUS’

0
DNC Kicks Off: Day 1- Pandering, Protests, & ‘POTUS’

Authored by Joseph Lord via The Epoch Times,

Starting Monday, Democrats will hold their long-anticipated national convention during which they’ll formally nominate their presidential candidate and outline to voters their vision for the future.

The Democratic National Convention (DNC) will formally lock in the presidential and vice presidential nominees for both major parties.

Former President Donald Trump and his running mate, Sen. JD Vance (R-Ohio), were nominated at the Republican National Convention last month.

Vice President Kamala Harris, meanwhile, clinched enough delegates to win her party’s nomination at the beginning of August during a virtual roll vote that left little room for last minute dissenters.

She’s expected to accept the nomination, along with her chosen running mate, Minnesota Gov. Tim Walz, in speeches delivered on the final two nights of the event.

This is set to be a very different convention than voters expected at the beginning of the election cycle, when President Joe Biden led the ticket for Democrats.

However, a pressure campaign forced Biden out of the candidacy after an underwhelming debate performance shock up the political landscape.

Since Harris took over the ticket, Democrats have enjoyed a boost in polling. Still, the stakes are high for Harris and the Democrats, who will need to put on a united front after months of division within the party.

Here’s what to expect during the second major party convention of the year.

When and Where

The DNC will be held from Monday, Aug. 19, to Thursday, Aug. 22, in Chicago.

Democrats have a long history of holding their conventions in the windy city—this will be the 12th time since 1864 that the convention has been hosted there.

The last DNC to be held in Chicago was in 1996, when President Bill Clinton was easily re-nominated by his party.

The main event this year is being held at the United Center, a convention center that doubles as the home stadium for the Chicago Bulls basketball team and the Chicago Blackhawks hockey team.

Around 50,000 attendees are expected, including the party’s approximately 5,000 delegates. Like most major political events, it won’t be open to the public.

However, it will stream on a variety of platforms, according to the party.

In addition to the normal media coverage of the event each night, voters will also be able to watch the convention online, courtesy of C-Span.

The event will also be streamed in its entirety via Instagram, TikTok, and YouTube using the vertical style popularized by those apps.

Additional delegate-only events that are not streamed to the public will be hosted at the nearby McCormick Center.

Speakers

The convention will feature speeches from an array of Democrat notables.

Biden will be among the first speakers. He’s expected to call into the convention via video.

As is tradition at these events, neither Walz nor Harris are expected to speak until the final two days: Walz is likely to speak on the second to last day of the convention, and Harris on the final night.

Speaker are expected to appear according to this schedule:

Aug. 19: 

  • President Joe Biden
  • Former Secretary of State Hillary Clinton
  • Illinois Gov. J.B. Pritzker

Aug. 20: 

  • Former President Barack Obama

Aug. 21: 

  • Former President Bill Clinton
  • Minnesota Gov. Tim Walz

Aug. 22: 

  • Vice President Kamala Harris

Time and Day TBD:

  • Chicago Mayor Brandon Johnson
  • Sen. Dick Durbin (D-Ill.)
  • Sen. Tammy Duckworth (D-Ill.)
  • Rep. Lauren Underwood (D-Ill.)

Platform

During the convention, Democrats will also formally adopt their party’s draft platform.

Released in July, the draft platform mentions Trump dozens of times.

It also details Democrats’ position on an array of issues.

It reiterates Democrats’ demands for a federal codification of Roe v. Wade—unsurprising as abortion is one of Democrats’ strongest polling issues.

Economically, there’s not much in the platform that’s especially new: it calls for the federal minimum wage to be raised to $15 an hour by 2026, policies to increase the affordability of childcare and healthcare, and making the Child Tax Credit permanent.

Additionally, the platform repeats Democrats’ long-held demands for higher taxation of very wealthy individuals and corporations.

The draft platform also calls for securing the southern border while providing a “pathway to citizenship” for the millions of illegal immigrants in the country.

However, this platform, released in early July, hasn’t been updated since Biden dropped out.

Now, hours before the convention kicks off, it still lists Biden as the party’s candidate.

As is usually the case at major party conventions, the platform will be discussed, debated, amended, and formally ratified during the convention.

Protests

While Democrats seek to project an image of unity, there’s one factor that’s outside of the party’s control: expected protests from interest groups on the left.

Namely, protestors are expected to move full steam ahead with protests originally planned against Biden.

One protest, organized as the “March on the DNC 2024,” will feature a group of around 200 left wing-groups, and could potentially number into the tens of thousands—raising concerns about event security.

Specifically, the protestors are demanding that the DNC and Harris change their stance on Israel, calling for the United States to “stand with Palestine” and “end U.S. aid to Israel,” along with a laundry list of other left-wing demands.

The event already has the highest possible federal security classification.

Security for the event will be handled by a coalition of local, state, and federal law enforcement, including the Secret Service.

Despite the challenges, Chicago Mayor Brandon Johnson and local police have maintained that the event will be secure.

Tyler Durden
Mon, 08/19/2024 – 08:30

Futures Flat As Jackson Hole Looms; Dollar Tumbles As Yen Soars

0
Futures Flat As Jackson Hole Looms; Dollar Tumbles As Yen Soars

Futures are flat after trading in a narrow overnight range, with small-caps outperforming. As of 7:45am ET S&P futures are up 0.1% at 5,581, after last week’s face-ripping rally which pushed the S&P to within 2% of the all time highs, while Nasdasq futures are unchanged as Mag7 and Semis start the week lower but broad-based strength is limiting losses. Bond yields are 1-2bps lower while broad dollar weakness sees USD/JPY re-test 145 level before rebounding back above 146, while WTI crude oil futures drop around 1%, underpinning Treasuries.  Commodities are lower with Energy and Metals weaker while Softs are catching a bid. This week is expected to be a low liquidity week with events centered around the DNC and Jackson Hole with NVDA earnings looming next week. The macro data focus is on Flash PMIs, Housing Data, and Regional Activity updates. Fed Minutes are not expected to be catalytic with Jackson Hole kicking off on Aug 22. Q2 earnings season approaches its close with consumer-related / Retailers earnings this week and NVDA next week.

In premarket trading, AMD shares rose 2% after the company agreed to buy server maker ZT Systems in a cash and stock transaction valued at $4.9 billion, adding data center technology that will bolster its efforts to challenge Nvidia. Shares in European defense firms including Rheinmetall AG tumbled after a report that Germany will no longer grant new requests for aid to Ukraine as the government seeks to rein in spending. Here are some other notable premarket movers:

  • Estee Lauder falls 6% after forecasting annual revenue growth below analysts’ expectations, a sign that the cosmetics company’s long-awaited recovery has hit another roadblock.
  • FuboTV shares rise 13%, poised to extend gains after Fox, Warner Bros. Discovery and Walt Disney were blocked by a judge from launching their streaming sports service one week before its rollout.
  • HP slips 2% as Morgan Stanley issued a downgrade, saying the computer hardware company now offers limited upside to estimates and on valuation.
  • Liquidia drops 37% after the FDA said the company’s Yutrepia inhalation powder can’t be approved until May next year as a treatment for adults with pulmonary arterial hypertension and pulmonary hypertension.
  • Shake Shack and Dutch Bros shares fall after Piper Sandler cuts to neutral as the broker tempers view on the fast casual sub-sector. Shake Shack -3%, Dutch Bros -2%
  • Xperi rises 19% after the company said late Friday that it agreed to sell Perceive assets to Amazon.com for $80m in cash.
  • ZIM Integrated Shipping gains 14% after boosting its adjusted Ebitda guidance for the full year.

Traders are starting a relatively quiet week on a cautious footing after recovering risk appetite last week left the S&P 500 close to a record high. After the Aug. 5 swoon, some buyers are re-emerging to help the main US stock gauge recoup more than half its summer losses even as hedge funds are once again shorting the bounce (having done the same in most of June and July).

“Things have come back, things feel more measured now,” Louise Dudley, portfolio manager for global equities at Federated Hermes, said in an interview with Bloomberg TV. “In that medium term there is some volatility and we’re definitely looking to take advantage of some of those price moves. Some of the large-cap cap names are still offering some of the top-growth opportunities.”

The key event is slated for Friday, when Fed Chair Jerome Powell is expected to give fresh insights on the course of US monetary policy at the central bank’s Jackson Hole economic symposium in Wyoming. “We expect Powell to hold forth on the medium-term strategy for the Fed,” Seth Carpenter, chief global economist at Morgan Stanley, wrote in a note.

Soft-landing bets are also helping to drive the recovery in equities. Goldman Sachs at the weekend trimmed the probability of a US recession in the next year to 20% from 25%, citing last week’s retail sales and jobless claims data, just days after raising it from 15% to 25%. If the August jobs report set for release on Sept. 6 “looks reasonably good, we would probably cut our recession probability back to 15%,” Goldman economists led by Jan Hatzius wrote in a report to clients on Saturday.

Elsewhere, the Democratic National Convention kicks off Monday in Chicago as party officials and celebrities rally around Kamala Harris, who may or may not be an idiot.

European stocks inch higher with the Stoxx 600 up 0.1%, and looking to extend its winning streak to five sessions. Basic resources is the strongest performing sector, while technology and energy stocks are the biggest laggards. Here are some of the biggest European movers on Monday:

  • Plus500 shares rise as much as 7% to a record high after the financial trading platform said it expects annual results to be ahead of expectations, which analysts believe will lift consensus estimates. Analysts also noted its cash balance exceeded $1 billion for the first time, providing the firepower needed to keep returning cash to shareholders as it launched a new buyback.
  • Metso Oyj and Sandvik AB gained when trading started on Monday after Swedish business daily Dagens Industri reported that large shareholders in Metso were pushing for a merger between the mining equipment operations of both companies.
  • Rheinmetall falls as much as 5% after the Frankfurter Allgemeine Zeitung reported that Germany will no longer grant new requests for aid to Ukraine as the government seeks to rein in spending.
  • Other defense firms also fell: Hensoldt -6.9%, Renk -3.6%, Kongsberg -2.5%, Saab -4.1%, BAE Systems -2.6%, Dassault Aviation -3% and Leonardo -2.7%.
  • DSM-Firmenich falls as much as 5.7% as traders pointed to a free-float adjustment announcement from index provider Stoxx.

Earlier in the session, stocks in Asia advanced for a second session, helped by gains in regional currencies and a further rally in Chinese technology shares following some earnings beats. The MSCI Asia Pacific Index rose as much as 0.9% after jumping 2.5% on Friday. Japan’s Seven & i Holdings Co. was the biggest contributor to gains on the benchmark after a report on a buyout offer. Shares of Chinese e-commerce company JD.com extended a post-earnings rally.Equities in Hong Kong were among the top performers in Asia, with the Hang Seng China Enterprises Index closing up 1%. Onshore Chinese shares also rose. More cities have scrapped official sale price restrictions on newly-built homes, a step to allow steeper price declines to amid sluggish demand, the 21st Century Business Herald reported on Monday. Japanese stocks were an outlier, weakening as a stronger yen dimmed the earnings prospect of export firms.

In FX, the dollar slipped, with some traders unwinding bets on a return to the White House by Donald Trump. On the other end, the Japanese yen surged amid broad weakness in the US dollar as traders positioned ahead of key central bank events later in the week. Bank of Japan Governor Kazuo Ueda appears in parliament on Friday, and Federal Reserve Chair Jerome Powell speaks at Jackson Hole later the same day. USD/JPY is down 1.1% against the greenback at ~146.05, having dropped as low as 145. The Bloomberg Dollar Spot Index falls 0.3%. 

“If we look at the polls, if we look at Harris’s solid performance in the last three weeks, the market has got to be thinking, were we hasty in putting on that Trump trade in June or July?,” Jane Foley, head of FX strategy at Rabobank, said in an interview with Bloomberg TV. “The market has to rethink that. If the market is less inclined to be putting on Trump trades, that could soften the dollar.”

In rates, treasuries hold small gains across long-end of the curve, where 30-year yields are ~1bp lower vs Friday’s close, as bunds outperform over early London session. 10-year TSY yields fall 2bps to 3.86% with bunds outperforming by 1bp in the sector and gilts trading broadly in line.

In commodities, oil prices decline, with WTI falling 1% to trade near $75.90 a barrel; oil declined for the fourth time in five sessions as traders tracked US-led efforts to secure a cease-fire in the 10-month old conflict in Gaza, while the Russia-Ukraine war is escalating. Spot gold falls $7 to around $2501/oz.  Bitcoin falls 2%.

Looking at today’s calendar, the data slate includes July Leading Index at 10am New York time; ahead this week are manufacturing and services PMIs and new home sales, and July 31 FOMC meeting minutes on Wednesday. Fed speakers scheduled for the session include Waller at 9:15am

Market Snapshot

  • S&P 500 futures little changed at 5,573.50
  • STOXX Europe 600 little changed at 511.94
  • MXAP up 0.5% to 183.72
  • MXAPJ up 0.8% to 573.15
  • Nikkei down 1.8% to 37,388.62
  • Topix down 1.4% to 2,641.14
  • Hang Seng Index up 0.8% to 17,569.57
  • Shanghai Composite up 0.5% to 2,893.67
  • Sensex little changed at 80,435.57
  • Australia S&P/ASX 200 up 0.1% to 7,980.45
  • Kospi down 0.8% to 2,674.36
  • German 10Y yield little changed at 2.22%
  • Euro up 0.2% to $1.1044
  • Brent Futures down 0.5% to $79.27/bbl
  • Gold spot down 0.1% to $2,506.51
  • US Dollar Index down 0.32% to 102.13

Top Overnight News

  • The race for the White House will reach a fever pitch this week, with Vice President Kamala Harris and Republican nominee Donald Trump battling for momentum — and attention — around the Democratic National Convention in Chicago.
  • Republicans warned Donald Trump to get serious on policy or he could lose and cautioned that his ‘showman’ tactics could cost him the chance of a second term in the White House, according to The Telegraph.
  • Wall Street is betting that Federal Reserve Chair Jerome Powell will confirm that interest-rate cuts are coming at the central bank’s annual confab in Jackson Hole, Wyoming. But as the debate shifts from “will they or won’t they?” to “how big will they go?” — stock traders may be left wanting.
  • The yen rallied against the dollar, leading gains among Group-of-10 currencies before comments from top central bank officials this week.
  • Just as bond traders grow more assured that inflation is finally under control, a camp of investors is quietly building up protection against the risk of a future spike in prices.
  • Fed’s Daly (voter) said recent data gave her more confidence that inflation is under control and it is time to consider adjusting rates from their current level, while she noted the Fed needs to take a gradual approach to reducing borrowing costs, according to FT.
  • Fed’s Goolsbee (non-voter) said on Friday that he has concerns for 2024 and that they have crosscurrents. Goolsbee added he is concerned that the Fed set this level of rates over a year ago and inflation and the labour market are cooling faster than expected, while he thinks the Fed should take a step back and think about it.
  • Goldman Sachs cuts the probability of a US recession in the next 12 months to 20% from 25%; cites last week’s Retail Sales and IJC metrics. Says could lower it to 15% in the event that the August jobs report “looks reasonably good”.

A more detailed look at global markets courtesy of Newsquawk

APAC stocks were mixed with a somewhat cautious tone amid geopolitical uncertainty after Hamas rejected the latest ceasefire proposal and as participants await this week’s key events including the Jackson Hole Symposium. ASX 200 traded rangebound as outperformance in gold miners and utilities was offset by weakness in consumer stocks. Nikkei 225 swung between gains and losses and traded on both sides of the 38,000 level after mixed Machinery Orders data, while the index was then pressured again later in the session alongside a firmer currency. Hang Seng and Shanghai Comp. gained amid stimulus hopes after Premier Li hinted on Friday at targeted measures to smooth the economic cycle and promote consumption, while a recent report noted weak Chinese data raised the pressure for Beijing to provide support and revived talk of regarding the idea of China issuing shopping vouchers.

Top Asian News

  • China’s Vice Premier is to co-chair a regular meeting between Chinese and Russian leaders with Russia’s Deputy PM on August 19th-20th, according to Chinese state media.
  • Singaporean PM Wong warned that increasing tensions between the US and China will have an impact on Singapore’s economy and the broader region, according to FT.

European bourses, Stoxx 600 (+0.1%) began the week on a mixed footing and generally traded on either side of the unchanged mark. European sectors are mixed with the breadth of the market fairly narrow. Basic Resources takes the top spot, in a paring to some of the hefty selling pressure seen in the prior session. Healthcare is found at the foot of the pile, joined by Tech. US Equity Futures (ES -0.1%, NQ -0.1%, RTY +0.1%) are mixed and also trade on either side of the unchanged mark, ahead of what will be a catalyst packed week.

Top European News

  • Metso Dismisses Media Report of Mining Merger With Sandvik
  • UK Energy Bills Set to Rise This Winter on Higher Gas Prices

FX

  • DXY is on the backfoot, going as low as 102.00 predominantly amid gains in the JPY and EUR. From a macro perspective, Fed’s Daly and Goolsbee have delivered dovish remarks ahead of Powell on Friday.
  • EUR/USD has extended its rise on a 1.10 handle and printed a fresh YTD peak at 1.1050 with the pair now at levels not seen since December last year.
  • GBP is firmer vs. the broadly softer USD with not much in the way of UK-specific newsflow ahead of flash PMI metrics on Wednesday. Cable has been as high as 1.2975 with attention on a test of 1.30.
  • JPY is by far the best performer across the majors vs. the USD as traders continue to focus on the expected upcoming Fed cutting cycle in the run up to the Jackson Hole Symposium this week (note, a 25bps hike by the BoJ is now priced for September 2025).
  • Antipodeans both gaining vs. the USD with AUD benefiting from some of the positivity surrounding China amid the revival of talk over the idea of China issuing shopping vouchers to boost consumption.
  • PBoC set USD/CNY mid-point at 7.1415 vs exp. 7.1548 (prev. 7.1464).

Fixed Income

  • USTs are bid, but not quite performing as well as Bunds are; holding at 113-09+ highs with resistance from Friday & Thursday at 113-12 & 113-23 respectively.
  • A firmer start to the week with Bunds leading the complex marginally after Germany came to a deal on its 2025 budget which will not fund any new Ukraine aid, as part of a measure to limit spending. Thus far, Bunds to a 134.58 peak, just shy of Friday’s 134.65 best with little of note until 135.00.
  • Gilts are in a very narrow 99.98-100.09 range, which is entirely within Thursday’s 99.67-100.19 spread. UK-specific docket is light.

Commodities

  • Crude is subdued intraday but largely in consolidation mode following Friday’s losses. The Dollar weakness has done little to prop up the crude complex in recent sessions, whilst the geopolitical risks appear to be overshadowed by demand concerns. Brent sits near the lower bound of a USD 78.94-79.81/bbl parameter.
  • A mixed picture across precious metals despite the softer Dollar and as catalysts over the weekend were light. Spot gold trades on either side of USD 2,500/oz.
  • Mostly firmer trade across base metals, albeit largely as a function of the softer Dollar. Desks have cited the recent trimming of losses by copper on alleviating fears of a US recession amid recent economic data.
  • Norway’s Equinor said production at Gullfaks C Platform in the North Sea is shut and it evacuated some workers from the platform as a precaution following a well incident, while it is unclear when production will restart but output at other Gullfaks platforms are running as normal.
  • Algeria is to immediately supply Lebanon with fuel to operate electric power stations and return electricity to the country, according to Algerian state radio cited by Reuters.
  • Iran said it is ready to tranship Russian gas through its territory, according to TASS.
  • BHP Escondida workers union said it could relaunch a strike if the Co. does not rectify its position over contract talks as soon as possible.

Geopolitics: Middle East

  • Israeli military said it conducted an airstrike in Lebanon’s Nabatieh which targeted a Hezbollah depot, while it was separately reported that Israel targeted the towns of Houla and Beit Leif in Lebanon during airstrikes on Sunday night, according to Al Jazeera. Furthermore, an Israeli airstrike targeted agricultural land northeast of the Nuseirat refugee camp in the central Gaza Strip and it was also reported that 10 people were killed in an Israeli strike on central Gaza’s Zawaida.
  • IDF said it detected the launch of a number of suspicious air targets from Lebanon towards areas in the Western Galilee.
  • Israeli PM Netanyahu’s office said the Israeli negotiating team expressed cautious optimism in advancing a Gaza hostage deal. PM Netanyahu’s office also said Israel is in complex negotiations and there are things it can and cannot be flexible about, according to Reuters.
  • Hamas on Sunday rejected an updated US proposal for a ceasefire and hostage deal in Gaza and blamed Israeli PM Netanyahu for moving the goalposts and the US for indulging him, according to Axios.
  • Hamas said the new ceasefire proposal presented by the US at talks in Doha responds to Israeli PM Netanyahu’s rejection of a permanent ceasefire and complete withdrawal from Gaza, while it added that the proposal placed new conditions in the issue of a hostages exchange and retracted other issues hindering a deal, according to Reuters.
  • US President Biden said they will not give up and a Gaza ceasefire is still possible. It was separately reported that US Secretary of State Blinken arrived in Israel to renew the push for a Gaza ceasefire.
  • US Secretary of State Blinken says “This is the best and perhaps the last chance to release the hostages and reach an agreement”; “We have decisive efforts to deploy troops and deter any attacks on Israel”, via Sky News Arabia.
  • Iranian Foreign Ministry says “we affirm our right to respond to the attack on our sovereignty and we will do so at the appropriate time”, via Al Jazeera

Geopolitics: Other

  • Chinese Premier is to visit Russia from August 20th to August 22nd, according to Interfax; Premier Li will meet with Russian and Belarussian counterparts, and will hold in-depth exchanges on bilateral relations.
  • Pipeline at oil and chemical plant in Russia’s Bashkiria set on fire, via Tass
  • IAEA said nuclear safety at Ukraine’s Zaporizhzhia nuclear power plant is deteriorating following a drone strike that hit the road around the plant site perimeter, while it stated there were no casualties and no impact to equipment, but there was an impact to the road between the two main gates of the plant.
  • Russia captured the village of Svyrydonivka in Ukraine’s Donetsk, according to TASS.
  • Belarusian President Lukashenko said troops were deployed along the entire border with Ukraine, according to RIA.
  • North Korea condemned Ukraine’s attack against Russian territory as an act of terror and invasion backed by the US and the West. North Korea said the anti-Russia policy of the US is driving the global security environment to the brink of World War 3, while North Korea will stand with Russia as it seeks to protect its sovereignty and realise international justice, according to KCNA.
  • US, South Korean and Japanese leaders pledged to consult on regional challenges, provocations and threats, while they said they are resolved to maintain peace and stability in the Indo-Pacific.
  • China’s Coast Guard said Philippine Coast Guard vessels illegally intruded into the waters adjacent to Sabina Shoal without permission from the Chinese government and one of the Philippine vessels ignored China’s repeated solemn warnings and deliberately collided with the Chinese vessel in an ‘unprofessional and dangerous’ manner. The Philippines later commented that the Philippine Coast Guard encountered ‘unlawful, aggressive manoeuvres’ in the South China Sea from Chinese Coast Guard vessels which resulted in structural damage to both Philippine Coast Guard vessels.

US Event Calendar

  • 10:00: July Leading Index, est. -0.4%, prior -0.2%

Central Bank Speakers

  • 09:15: Fed’s Waller Gives Welcoming Remarks

DB’s Jim Reid concludes the overnight wrap

As we move into the latter part of August, this week’s centre of attention for investors will be the Jackson Hole Economic Symposium that runs from Thursday evening through Saturday. Markets approach this in a much better mood than looked likely two weeks ago as the extreme volatility seen at the start of August seems almost a distant memory. The S&P 500 is on its best 7-day run since October 2022 (+6.82%) and has moved to within 2% of its all-time high, while the VIX ended last week at 14.80, down to below 15 for the first time in over three weeks. This comes as a 50bp Fed rate cut in September is now just over 30% priced, down from being fully priced on August 5 and 55% a week ago.

The overall title at Jackson Hole this year is “Reassessing the Effectiveness and Transmission of Monetary Policy” and central bankers will surely feel more satisfied with their policy levers than the last two times they met at the Wyoming retreat. The 2022 symposium came as inflation neared double digits across many developed economies with rates markets undergoing a sharp hawkish repricing, while a higher-for-longer focus saw Treasury yields reach post-GFC highs in the run-up to the 2023 gathering, with the 10yr yield then touching 5% last October. By contrast, this year’s event comes with US PCE inflation down to 2.5%, the unemployment rate up by 0.6pp since the start of 2024 and the Fed keeping rates on hold for the past 12 months. 10yr Treasuries are back below 4% as markets are pricing 95bps of Fed rate cuts across the remaining three meetings this year and 200bps of easing by next October.

In this context, investors will be keenly watching for signals on the timing and pace of rate cuts, especially from Fed Chair Powell’s speech at 10am EST (3pm LDN) on Friday. Our US economists don’t expect him to pre-commit to any particular rate cut trajectory but to signal that the Fed has gained sufficient confidence that it will soon be appropriate to begin easing policy, with rate cuts justified by both sides of the Fed’s dual mandate. They see rate cuts as likely to be framed as dialling back restraint, leaving the exact path data dependent. With r-star uncertain and policy risks evident following the election, rate cuts beyond the first 75-125bps are more uncertain.

Other scheduled Jackson Hole speakers include BoE Governor Bailey late on Friday and ECB Chief Economist Lane on Saturday. Ahead of this, we will also get the latest Fed and ECB meeting minutes on Wednesday and Thursday, respectively, which may offer some colour on the strength of the conditional September rate cut signals that both central banks sent at their July meetings. Elsewhere, tomorrow Sweden’s Riksbank is expected to deliver a second 25bps cut of its easing cycle, with markets pricing a c. 20% likelihood of a larger 50bps cut.

On the data front, this week’s main event will come with the flash August PMIs out in the US, euro area, UK and Japan on Thursday. Last month’s slippage of the US manufacturing PMI to below 50 (at 49.6) contributed to a rise in US recession fears that has since ebbed, while in the euro area activity surveys have consistently disappointed over the past two months. Another notable release will be Wednesday’s Q1 Quarterly Census of Employment and Wages (QCEW) in the US, which will provide preliminary benchmark revisions to the payrolls data. Our US economists see a negative revision as likely but, with this covering  the period up to March 2024 that had seen particularly robust strong payrolls gains, any broader negative read-though may be limited.

Turning to politics, today will see the start of the US Democratic National Convention in Chicago, which comes as Kamala Harris enjoys a stabilising modest lead over Donald Trump in opinion polls for the November election. The FiveThirtyEight national average gives her a +2.6pt lead, with a smaller advantage on average across the swing states. Politics will also be in the headlines in Japan as on August 20 the LDP is due to finalise the schedule for its September leadership election. This follows Premier Minister Kishida’s announcement last week that he would not run again, with our Japan economist addressing the implications of the change of PM in his latest outlook here.

Overnight in Asia, a weaker dollar is putting pressure on stocks in Japan and Korea, with Chinese equities outperforming. The dollar is -0.97% weaker against the yen this morning, touching the 146 level for the first time since 8 August, and is down -1.39% against the won, with the Nikkei 225 and the Kospi falling -1.68% and -0.61%, respectively. The moves are in stark contrast with a +1.06% jump in the Hang Seng, with the CSI 300 also advancing (+0.41%). Chinese assets will stay in focus amid tomorrow’s 1-yr and 5-yr loan prime rate decision. In US contracts, S&P 500 and Nasdaq futures are near flat overnight. Treasuries are also little changed, with the 2yr yield +0.5bps higher.

Recapping last week now, a US CPI print that was soft enough to affirm the disinflation narrative coupled with strong retail sales data served to cement a soft landing narrative. Friday’s data added to the general optimism, with the University of Michigan sentiment survey for August posting its first increase in five months at 67.8 (vs 66.9 expected) and the NY Fed services business index returning to positive territory for the first time since May, rising from -4.5 to 1.8.

With these data releases suggesting both a successful disinflation process and resilience of the US economy, equity markets were in a buoyant mood, with the S&P 500 rising +3.93% in its largest weekly gain since November 2023. Friday saw the S&P (+0.20%) extend its run to seven consecutive daily gains, its joint longest run this year. Tech outperformed, as the NASDAQ powered ahead by +5.29% (+0.21% Friday). The Mag-7 were up +6.23% as Nvidia stole the show with an +18.93% rally, its largest weekly gain since May 2023. Over in Europe, the equity gains were slightly more modest, with the STOXX 600 rising +2.46% (+0.31% Friday). Credit markets also benefited from the risk-on mood, with US IG spreads (-6bps) seeing their largest weekly decline since January.

In bond markets, Friday’s -4.3bps decline left 2yr yields little changed over the week (-0.3bps). On the other hand, 10yr yields retreated -5.7bps (and -3.0bps on Friday), to 3.88%. In Europe, 10yr German bunds saw a modest sell-off (+2.2bps) despite falling -1.5bps on Friday. Amid the risk-on mood and lower rates, the broad dollar index retreated -0.65% (-0.50% Friday) to its lowest level since January, with the euro closing above 1.10 against the dollar for the first time this year (+1.01% on the week to 1.103).

Lastly, in commodities, gold had a very strong week. Spot gold prices rose +3.16% (and +2.13% on Friday), moving above $2,500/oz for the first time ever. Oil whipsawed on the week, with a -1.58% reversal on Friday leaving Brent +0.13% over the week at $79.66/bbl.


Tyler Durden
Mon, 08/19/2024 – 08:17

These Are The Countries That Use ChatGPT The Most

0
These Are The Countries That Use ChatGPT The Most

It’s been almost two full years since OpenAI released ChatGPT, helping kickstart the generative AI revolution. Consumers lined up around the virtual block to use ChatGPT, kicking off an AI arms race between at least three Big Tech companies.

But now that the initial newness has faded, what does the general public make of this new technology?

Visual Capitalist’s Marcus Lu visualizes the percentage of consumers using ChatGPT in various countries around the world.

This data comes from Boston Consulting Group’s CCI Global Consumer Sentiment Survey 2023.

Younger Countries Using AI More

Among the countries surveyed, India has the highest share (45%) of people using ChatGPT.

This could be partly due to the country’s large number of IT jobs, in which ChatGPT could be a valuable asset.

One correlation that emerges in this dataset is that younger countries by median age tend to have a higher ChatGPT usage, possibly because of a younger, more tech-savvy population.

And this correlation also plays out when looking at how AI tools are used. For example, survey respondents in India and the Philippines (higher ChatGPT usage) use AI for specific objectives: assist in research or as a virtual personal assistant

In contrast, according to BCG, respondents in the U.S. and Germany (lower ChatGPT usage) mostly “play around with it.”

For the consumers using AI for more than the novelty effect, “addressing unmet needs” is a key theme. This could mean creating financial goals, finding personalized recommendations, or searching for similar items to the ones they already had.

Overall, about 40% of all the survey respondents said they were excited about AI, with 28% conflicted about it, and 29% concerned.

If you liked this article, check out The Most Popular AI Tools of 2023 for a look back at the would-be ChatGPT competitors.

Tyler Durden
Mon, 08/19/2024 – 06:55

Federal Appeals Court Reverses Decision, Keeps Alaska Salmon Fishery Open

0
Federal Appeals Court Reverses Decision, Keeps Alaska Salmon Fishery Open

Authored by Tom Ozimek via The Epoch Times (emphasis ours),

A federal appeals court has reversed a lower court ruling that would have shut down the Southeast Alaska Chinook salmon fishery, a significant source of income for local fishermen, while keeping intact a program aimed at increasing prey for an endangered species of orcas.

Two fishermen wash freshly caught salmon, in Nowtok, Alaska, on July 1, 2015. (Andrew Burton/Getty Images)

The 9th U.S. Circuit Court of Appeals ruled on Aug. 16 that U.S. District Judge Richard Jones in Seattle had erred in 2023 when he invalidated a key permit, known as a “take statement,” issued by the U.S. National Marine Fisheries Service (NMFS).

This take statement, which specifically applied to the Southeast Alaska Chinook salmon fishery, authorized the summer and winter harvests of Chinook salmon, which are a critical food source for the endangered Southern Resident killer whales.

The appeals court’s decision allows the fishery to remain open while the NMFS revises its management plan, which both the lower court and the appeals court found contained some flaws.

The ruling is sure to be seen as a relief for Alaska’s fishing communities, which had argued that closing the fishery would have devastating economic consequences.

The Wild Fish Conservancy (WFC), which filed a lawsuit in 2020 challenging the NMFS’s authorization of the Southeast Alaska Chinook salmon fishery and praised the district court’s 2023 decision as a “major landmark victory,” did not respond to a request for comment on the appeals court’s decision.

However, WFC has previously indicated that it remains committed to advocating for the protection of endangered species.

Its its lawsuit, the conservation group argued that the fishery was depleting Chinook salmon populations, which in turn was threatening the survival of the Southern Resident killer whales, a critically endangered population with just 73 individuals remaining.

The Ruling

The 9th Circuit’s three-judge panel found that although the NMFS had made errors in its 2019 biological opinion, which assessed the impact of the fishery on endangered species, these errors were not significant enough to warrant shutting down the fishery entirely. The judges emphasized that the economic impact on Alaskan fishermen and their communities, including Alaska Natives, would be severe if the fishery were closed.

“The district court disregarded the likelihood that the take statement would be supported by better reasoning, and readopted, on remand,” the court wrote in its opinion. The judges also noted that even experts from the WFC conceded that vacating the take statement would lead to millions of dollars of losses for Alaska fishermen, while also acknowledging uncertainty about the fishery’s impact on whale populations.

The appeals court criticized the district court for insufficiently taking into consideration the “severe disruptive consequences” of vacating the take statement.

However, the appeals court found that the district court was correct in upholding the prey increase program after determining that vacating it would lead to environmental harms because the program provided an important source of prey for the killer whales, and that nixing the program would have disrupted unrelated fisheries and other federal actions.

In its lawsuit, the WFC had questioned the effectiveness of the prey increase program and the NMFS’ reliance on it in its management plan as a “mitigating” measure to offset negative impacts of reduced prey availability due to the fishery’s operations, though they did not specifically advocate for its termination.

WFC called the prey increase program “ill-defined” while arguing that various hatchery programs proposed as mitigation would “themselves have harmful impacts on wild salmon populations,” including threatened Chinook salmon, and that they “may result in greater harm than benefit.”

It’s unclear what action, if any, WFC intends to take in light of the appeals court’s ruling in the case.

Tyler Durden
Mon, 08/19/2024 – 06:30

Stock Index Castoffs Have Delivered Enduring And Outsized Returns, Quant Researchers Find

0
Stock Index Castoffs Have Delivered Enduring And Outsized Returns, Quant Researchers Find

When stocks are ejected from market-cap-weighted indexes, swooping in to load up on them — and hold on to them — can pay off nicely, according to a new paper from Newport Beach, California-based Research Affiliates LLC.

“Once dropped by the index, there is a silver lining for these stocks…they, on average, outperform the market over the next several years, creating a compelling opportunity for investors,” said Research Affiliates chairman Rob Arnott, who co-authored the study with the firm’s research VP Forrest Henslee. They also found that, over the year after being booted from the indexes, deleted stocks have historically outperformed the stocks that replaced them. 

Last week, Research Affiliates chairman Rob Arnott told the Wall Street Journal that small-cap value is primed to outperform the S&P 500

This strategy isn’t about making a quick profit by catching a bounce when the price-pressuring effect of index funds’ mandatory selling subsides. Rather, it assumes the investor holds on to the shares for five years. Had an investor started employing the strategy in 1991, he’d have grown his initial investment by about 74x.  

To track the strategy, Research Affiliates has launched the Research Affiliates Deletion Index (NIXT). While based on the research methodology, the NIXT index does have a tweak in the form of a quality screen that includes a company’s debt, total payout ratio and net payout ratio — with stocks falling in the bottom quintile rejected. The index uses an equal weighting and annual rebalancing. No ETF yet tracks it, so, for now, it’s a do-it-yourself opportunity.  

Tracking rejects from the S&P 500, Nasdaq-100 and Russell 1000, the strategy is ultimately a small-cap value play: 

Stocks that get dumped are by their nature small and cheap. Between 1991 and 2022, deletions traded at a 26% discount to the S&P 500 in terms of their price-to-earnings ratio while additions fetched an 83% premium. — Wall Street Journal

“When an index producer adds or drops stocks from the index, they will inevitably add stocks that are popular, beloved, and expensive and drop stocks that are unloved and cheap,” said Arnott. The strategy’s small-cap tilt springs from the fact that many index deletions are sparked by companies no longer making the large-cap cut.  

Some key observations from the study: 

  • The deleted-stock strategy beat the Russell 2000 Value Index over the past 33 years.  “When deletions outpace the Russell 2000 Value, they win by more than 18%, on average…When deletions underperform, they lag by 5.3% on average, with a shortfall of over 10% only twice,” said the authors. 
  • S&P 500 rejects went on to beat their former index by more than 5% a year. 
  • Looking solely at the last 10 years, the strategy lagged the three indexes that drive it, which Arnott and Henslee attribute to “the current growth-dominated bull market [that’s] left value and small-cap stocks in the dust.” 

“It makes sense that the booted companies would become undervalued and bounce back,” notes Charles Robtlut at the American Association of Individual Investors. “It also makes sense to overlay a quality filter because some companies are booted from the indexes because they are no longer good companies.” 

The Journal credits Arnott as a “luminary in the world of finance nerds constantly trying to build a better mousetrap,” noting that a 2005 paper he co-authored sparked the smart beta trend. 

Tyler Durden
Mon, 08/19/2024 – 05:45

Drug Company Announces It Will Produce Millions Of Monkeypox Vaccines By Next Year

0
Drug Company Announces It Will Produce Millions Of Monkeypox Vaccines By Next Year

Authored by Jack Phillips via The Epoch Times (emphasis ours),

Shares of mpox vaccine maker Bavarian Nordic saw an increase this week after the World Health Organization (WHO) declared a public health emergency and as the company’s CEO announced it could provide 10 million doses of the vaccine.

“We have inventory and we have the capabilities. What we’re missing are the orders,” CEO Paul Chaplin told Bloomberg this week.

This 2003 electron microscope image made available by the Centers for Disease Control and Prevention shows mature, oval-shaped monkeypox virions (L) and spherical immature virions (R) obtained from a sample of human skin associated with the 2003 prairie dog outbreak. (Cynthia S. Goldsmith, Russell Regner/CDC via AP)

The Africa Centres for Disease Control and Prevention (Africa CDC) previously said it needed 10 million doses to deal with an mpox, also known as monkeypox, outbreak that has spread from the Democratic Republic of the Congo to other African nations. WHO and other health officials say that the strain of mpox appears to be more deadly than another variant that caused a worldwide outbreak in 2022 and 2023.

In the interview, Chaplin said his firm has has 300,000 doses of the vaccine ready to be distributed right away, while adding that 2 million doses could be provided to Africa by the end of 2024. “We are in late August already, so it really does need some speed in the decision making to be able to do that,” he said.

Over the past five days, his company’s stock has increased by about 49 percent, raising to about $14.11 per share as of Friday afternoon.

Bavarian Nordic on Friday also submitted vaccine-related data to the European Union health regulator to extend use of its vaccine to cover children aged 12 to 17.

“Children and adolescents are disproportionally affected by mpox in the ongoing outbreak in Africa, highlighting the importance and urgency to broaden the access to vaccines and therapies for this vulnerable population,” Chaplin said in a statement.

Emergent BioSolutions, a U.S.-based company that acquired a smallpox vaccine manufacturer from Sanofi in 2017, also saw its stock increase 54 percent over the past five days, raising to about $10.64 per share.

In the current mpox outbreak, have been 27,000 cases and more than 1,100 deaths, mainly among children, in Congo since it started in January 2023.

Emergency Declaration

The WHO declared the recent outbreak of the disease a “public health emergency of international concern,” or the agency’s highest form of alert. It is announced when diseases are spreading in new or unusual ways, and is aimed at galvanizing international co-operation and funding to tackle an outbreak.

A similar declaration was made for the mpox outbreak in 2022 and 2023, for COVID-19 in 2020, and for about a half-dozen other pathogens since 2005.

The WHO’s declaration follows a similar label from the Africa CDC earlier this week. Meanwhile, the U.S. Centers for Disease Control and Prevention (CDC) sent a health alert earlier in August for doctors and physicians to be alert for mpox symptoms.

No cases of mpox have been detected in the United States so far, according to the CDC notice. However, Sweden confirmed its first case of the more severe mpox strain—the first time it’s been found outside of Africa—earlier this week.

“We have now also during the afternoon had confirmation that we have one case in Sweden of the more grave type of mpox, the one called clade I,” Health and Social Affairs Minister Jakob Forssmed said during a news conference.

Europe’s CDC, meanwhile, has said that more imported cases of mpox will be likely across the continent. It came as the agency raised its risk assessment, but it added that the risk of transmission remains low.

Mpox is a viral infection that causes flu-like symptoms and pus-filled lesions, and while usually mild, it can kill. Children, pregnant women, and people with weakened immune systems, such as those with HIV, are all at higher risk of complications.

It spreads through close contact and is classified into two distinct viral groups known as clades. They are Clade I, which includes a variant that has the more severe form of the virus, and Clade II, a variant of which caused the 2022 outbreak.

Reuters contributed to this report.

Tyler Durden
Mon, 08/19/2024 – 05:00