65.1 F
Chicago
Friday, September 25, 2026
Home Blog Page 2530

It Took Nvidia 23 Days To Add $1 Trillion In Market Cap; Berkshire Hathaway Hasn’t Managed That In 60 Years

It Took Nvidia 23 Days To Add $1 Trillion In Market Cap; Berkshire Hathaway Hasn’t Managed That In 60 Years

This morning, Deutsche Bank’s Jim Reid published his latest chart book titled “Charts to make you go WOW” (available here to pro subs), which will prompt a few surprised exclamations even from the hardened cynics.

And while there is an extensive selection to pick from – and we will go over the charts in more details shortly –  it’s hard to pick a more “wow” chart example than the recent developments involving Nvidia (there’s lots more beside in the pack from AI and industrial revolutions to debt, deficits, demographics, migration and housing).

The chart below shows that it’s taken 60 years for the most famous and arguably successful investor in the world, Warren Buffet, to build Berkshire Hathaway up to just shy of a trillion-dollar company ($883bn at Friday’s close). Indeed the company’s origins began in the 19th century so the full journey has taken well over a century and it’s yet to hit a trillion dollars.

Contrast that with Nvidia, which went from just below $2tn market cap for the last time on April 24th, to over $3tn just 30 trading days later. Even more impressively, at its record close last Tuesday, where it became the largest company in the world, the last trillion of market cap was added in only 23 trading days.

Then again, the higher they rise… Nvidia opened on Thursday after the holiday another 3% higher, melting up on virtually no volume (and a brutal gamma squeeze). But since that intraday peak it has tumbled 13% in just three days, and slipped back to 3rd in the S&P 500 rankings. The move came as portfolio managers rebalanced portfolios at the end of the quarter, with JPM calculating some $50 billion in selling pressure from pension funds, to account for the surge in tech shares; the start of the buyback blackout period last week didn’t help either.

So, as Jim Reid asks rhetorically, is this a pause for breath or signs the air is being let out of the balloon? He responds that while his chart book hints that he does believe in AI, there have been signs of over exuberance in the US market over the last month. Penny stock trading has soared and net call options on Mega Cap Growth and Tech has exploded in June.

This, alongside positioning and the move into the buyback blackout period, has led DB strategist to suggest a “breather” is likely.

More in the full DB Monthly Chartbook “Charts to make you go WOW” available to pro subs.

Tyler Durden
Mon, 06/24/2024 – 18:40

Biden’s Latest DEI Hire Deletes Past Anti-White And Anti-Police Tweets

Biden’s Latest DEI Hire Deletes Past Anti-White And Anti-Police Tweets

Authored by Steve Watson via modernity.news,

In the latest clownworld development, the Biden Administration hired a man in a dress to be its new Associate Communications Director and it quickly emerged that the guy had a history of spicy tweets hating on white people, comparing police officers to ‘slave patrols’ and ‘lynch mobs’, and calling for ICE to be abolished.

Here is who they hired. Tyler Cherry (left).

He looks like Mr Slave from South Park.

Or Weird Al Yankovic if you prefer:

He has a degree in gender studies. Of course he does.

He used to work for Media Matters. Of course he did.

He also thinks there are too many white people.

When people started to point all this out, Cherry apologised, and then started deleting all the old tweets.

He deleted every tweet with the word ‘white’ in it:

And restricted who can reply or comment:

There is no word yet on whether this guy likes to steal luggage or not.

Who is really running the country?

Your support is crucial in helping us defeat mass censorship. Please consider donating via Locals or check out our unique merch. Follow us on X @ModernityNews.

Tyler Durden
Mon, 06/24/2024 – 18:20

US Lawmaker Condemns Attack On Crimea Beach With American Weapons

US Lawmaker Condemns Attack On Crimea Beach With American Weapons

The Kremlin on Monday called the Sunday strike from Ukraine on a crowded Sevastopol beach “barbaric” and accused the US of “killing Russian children” – given that ATACMS missiles were allegedly used. The attack killed four people, including two children, and injured over 150 more.

Foreign Minister Sergei Lavrov said in a statement while in Minsk that the US-supplied system “cannot be used without the direct participation of the American military, including satellite capabilities.” He reiterated there will be consequences. 

This angry denunciation from Moscow is to be expected, but much more rare is that a sitting Congressional member agrees that Washington should have no business assisting with attacks on Russian civilians who are on vacation at beaches.

Congresswoman and outspoken conservative Marjorie Taylor Greene has said this simply shouldn’t be happening in a fresh message on X.

“This should not be happening,” Greene posted. “Imagine if Russia, using a Russian satellite, fired cluster munitions on a Florida beach.”

The Georgia Republican added: “The only border our American military should be defending is our own border.”

The author of the original post she was commenting on issued the question: “Are winning hearts and minds? How hard will [US President Joe] Biden continue to poke the bear ahead of the November elections?”

The Biden administration and Pentagon officials have lately claimed that Kiev is only authorized to attack military targets as a ‘defensive’ measure when it comes to cross-border attacks utilizing American weapons. But few believe Ukraine’s military is going to take these ‘limits’ seriously, especially given heavy losses it is experiencing along the front lines.

Already Ukraine has been struggling through nationwide rolling blackouts due to stepped-up airstrikes and drone attacks primarily targeting the nation’s energy infrastructure, but it is likely about to get harder as Russian aerial forces retaliate.

Moscow is likely seeking to obliterate especially foreign weapons storehouses and is searching out Pentagon-supplied ATACMS systems being used in these devastating cross-border attacks.

Tyler Durden
Mon, 06/24/2024 – 18:00

A Minnesota Dam Is In “Imminent Failure Condition” 

A Minnesota Dam Is In “Imminent Failure Condition” 

A century-old concrete gravity dam on the Blue Earth River in Rapidan Township, near Rapidan, Minnesota, is in “imminent failure condition.” This has sparked concern about America’s aging infrastructure. 

“We do not know if it will totally fail or if it will remain in place, however we determined it was necessary to issue this notification to advise downstream residents and the correct regulatory agencies and other local agencies,” Blue Earth County Sheriff’s Office wrote on Facebook. 

For days, the sheriff’s office has been monitoring debris build-up at the 114-year-old Rapidan Dam, located about ten miles southwest of Mankato. This puts the dam “in imminent failure condition.” Heavy rains in recent days have raised river water levels. 

“The river has significantly cut around the west side of the dam,” Blue Earth County Sheriff’s Office said. Also, an Xcel Energy substation at the dam has washed away. 

“The river level was already high from the large amounts of recent rainfall and moving fast when it diverted around the dam near the substation and flowed onto the bank,” Xcel said in a statement, which NBC News quoted.

A 2021 assessment determined that the dam needed costly repairs or complete replacement. The county’s website, however, warns that doing nothing “would pose a public safety concern and a tremendous liability.”

The National Weather Service reported that the failure is expected to cause the Minnesota River at Mankato to crest just below major flood level early Tuesday.

This is yet more evidence of America’s crumbling infrastructure and the inability of the government to allocate taxpayers’ monies efficiently while political elites in Washington bankrupt the nation with endless foreign wars.

Tyler Durden
Mon, 06/24/2024 – 16:40

Here It Comes…

Here It Comes…

Authored by James Howard Kunstler via Kunstler.com,

“Leftism might actually be noble if their concern for the marginalized wasn’t simply an incidental externality to their seething hatred of the normal and the good.”

– David Pivtorak on “X”

Did you entertain feelings of doom during last week’s brain-withering heat-wave? The sheer anxious waiting and wishing for it to end was a nice analog to the stifling psycho-political miasma oppressing this nation – alternately known as the republic (for which we stand) and “our democracy,” as “Joe Biden” likes to style his regime of lawfare, warfare, and garish state-sponsored depravity. Well, rejoice and ring them bells! The political weather is breaking. The week ahead looks like an all-you-can-eat, steam-table banquet of consequence.

The Supreme Court (SCOTUS) teased last week with an opening round of lesser decisions on bump stocks for rifles, abortion pills for women inconvenienced by motherhood, and a few other interesting cases. The court’s term draws to a close with the end of June. Pending are several cases liable to rattle the windows and shake down the walls.

One is the question as to whether the government can use private company proxies to censor constitutionally protected free speech (Murthy v. Missouri).

The case has been simmering for years, with lower court actions that took a dim view of the intel blob’s coercive intrusions into social media. Probably the most galling part of the story is that virtually every act of censorship and de-platforming was committed against those telling the truth about some vital public issue, whether it was the danger and ineffectiveness of the Covid vaccines, or the probity of the 2020 elections, or the existence of Hunter Biden’s laptop and its dastardly contents. That is, the government’s actions were entirely in the service of lying to the American people.

This raises a greater question that redounds from the courts onto the November election: just why is the US government so deeply invested in all that lying? The answer is obvious: it has been engaged in nefarious activities that it seeks to hide and deny. And all of that has served to wreck the country. Even worse, the government has gaslit half of the public into cheerleading and rolling over for all that dishonesty, so as to keep them “safe” from hobgoblins such as “misinformation.” Considering “Joe Biden’s” cratering poll numbers, it looks like the public is tired of this incessant lying and is fixing to vote his regime out of office.

We begin to see evidence that even some hardcore regime hacks are breaking out of that consensus trance, for instance, the Cuomo brothers denouncing the lies around lawfare and Covid. Andrew, once the New York state AG himself, told the shocked studio audience on Bill Maher’s HBO gabfest, beloved by Wokesters, that the Alvin Bragg case never should have been brought to trial. His brother Chris has been telling his podcast followers that Covid policy was a fiasco and the vaccines were harmful, and he apologized for his prior shifty reporting on all that when he had a CNN show.

Also upcoming at SCOTUS: Fischer v the United States, as to whether the DOJ tortured a federal statute on shredding financial records to overcharge J-6 rioters.

In 2015 the court limited the scope of that law (part of the 2002 Sarbanes-Oxley Act), but Attorney General Merrick Garland used it anyway as an all-purpose dragnet to prosecute hundreds of people who merely paraded through the US Capitol — which provided legal footing for the House J-6 committee to color that event dishonestly as “an insurrection.” A decision against the government should lead to the release of many J-6 prisoners and perhaps lawsuits for malicious prosecution under the Federal Tort Claims Act (FTCA). It would also toss out the pertinent charges in Special Counsel Jack Smith’s DC case against Donald Trump for supposedly fomenting an “insurrection.”

Another biggie case pending (Loper Bright Enterprises v. Raimondo; Relentless v. Department of Commerce) will determine whether executive agencies of the US Government (e.g., the EPA, CDC, Depts. of Energy, Education, Commerce, etc.) can issue regulations as if they have the force of law — that is, push citizens and businesses around by fiat where the law is ambiguous or nonexistent.

A lot has changed since SCOTUS initially sought to define the scope of agency authority in their 1984 decision known as Chevron v. Natural Resources Defense Council. The federal bureaucracy has become an unaccountable behemoth, issuing sometimes arbitrary and capricious regulations that make it increasingly difficult to accomplish anything in our country. It has also enabled much of the government’s monkey business around Covid. This court appears to lean towards overturning Chevron.

Also pending this week: whether SCOTUS will stay Steve Bannon’s four-month jail sentence scheduled to begin July 1 while he appeals to the SCOTUS. Bannon was convicted for contempt of Congress when he refused to testify to the J-6 committee, basing his refusal on executive privilege. Note that SCOTUS did not keep White House advisor Peter Navarro out of prison for exactly the same charge.

The DOJ must reply to SCOTUS’s request for “input” on the matter by Wednesday June 26th at 4:00 p.m. At issue is whether the government is interfering in the election by shutting up Bannon during the climax months of the campaign.

Today, Judge Aileen Cannon will ask Special Counsel Jack Smith’s lawyers to do some ‘splainin’ about how come he got to be Special Counsel without being nominated by a president or confirmed by the Senate, which is the lawful procedure.

It’s therefore possible that Judge Cannon can determine that Mr. Smith is not operating lawfully. That’s not the only thing that can deflate the so-called Mar-a-Lago Documents case, but it could lead to a determination that this was a malicious political prosecution, with consequences for AG Merrick Garland.

By the way, you know what this case is really about, don’t you?

I’ll tell you: the FBI went into Mar-a-Lago looking for Mr. Trump’s binder containing evidence of FBI and DOJ misconduct in the RussiaGate caper.

Whether they found it or not, we don’t know, nor do we know if there are other copies of the materials. But you might surmise that a lot of officials in those agencies are a little nervous about their criminal liability, especially with the presidential election poll numbers looking how they do. In other words, the Mar-a-Lago raid was a cover-up operation.

And Thursday, of course, comes the debate to end all debates.

Makes you cringe a little just to imagine it.

*  *  *

Support his blog by visiting Jim’s Patreon Page or Substack

Tyler Durden
Mon, 06/24/2024 – 16:20

“Sell Big-Tech & Bitcoin, Buy Everything Else…”

“Sell Big-Tech & Bitcoin, Buy Everything Else…”

Goldman’s trading desk summed up the market theme perfectly today: “sell tech and buy everything else”…

Energy and Regional Banks notably outperforming, while big-tech was trounced…

Source: Bloomberg

Since Juneteenth, we have seen AI-stocks monkey-hammered relative to Ai-at-Risk names…

Source: Bloomberg

With NVDA down over 16% from its highs on Thursday…

Dragging MAG7 stocks down to pre-CPI-spike levels…

Source: Bloomberg

…as the ‘most shorted’ stocks saw a big squeeze today…

Source: Bloomberg

GLP-1 stocks ripped today on Sleep Apnea and some kidney disease studies… is there nothing these drugs can’t cure? Or maybe Obesity is really the root of all healthcare after all (just don’t say that during a pandemic)…

Source: Bloomberg

Which left Small Caps and The Dow outperforming; Nasdaq the biggest loser, and a late-day purge sent everything lower into the close, dragging the S&P 500 red…

And before we shift our gaze to non-equity markets, we note that the equal-weighted S&P 500 is back at its weakest level ‘since Lehman’ relative to the market-cap-weighted S&P 500…

Source: Bloomberg

Treasuries were modestly bid today with the long-end outperforming (sold during early Europe and bid during late US session). However, their general range was far less noticeable relative to equities…

Source: Bloomberg

The dollar dumped today back to last week’s lows…

Source: Bloomberg

…and that helped support gold (which still remains well down from Friday’s highs…

Source: Bloomberg

…and helped crude, with WTI pushing up against its highest levels since April……

Source: Bloomberg

Bitcoin was not so lucky as FUD over Mt.Gox supply sent the largest crypto currency reeling back down below $60,000…

Source: Bloomberg

…its lowest since early May (as ETF outflows continue)…

Source: Bloomberg

Finally, amid all this malarkey, there is one more pillar of irrational support for sky-high valuations that is about to evaporate (albeit briefly)…

After Friday’s ‘gamma unclenching’, the death of the banal bid from corporates could just be the catalyst for some catch-down to reality.

Tyler Durden
Mon, 06/24/2024 – 16:00

There’s No Good Reason To Raise The Inflation Target

There’s No Good Reason To Raise The Inflation Target

Authored by Alexander William Salter via The American Institute for Economic Research,

The Federal Reserve has a 2-percent inflation target. Central bankers are supposed to conduct monetary policy such that the long-run trajectory of the price level follows a 2-percent growth path. Most policy-focused macroeconomists think this is a reasonable way to achieve price stability and predictability without running the risk of deflation. But some economists want the Fed’s inflation target to be higher. They think something like a 4-percent inflation target would give the Fed more wiggle room to ease policy, should recessionary pressures emerge.

These economists are wrong. They misunderstand the nuances of monetary policy, as well as the basics of how the market price system works. There’s no good reason for the Fed to raise its inflation target. Competent economists should work to discredit this idea as quickly as possible.

Supporters of a higher inflation target claim that it would give the Fed some extra ammunition. The key is the link between interest rates and inflation. From the Fisher equation, we know that the nominal interest rate equals the real (inflation-adjusted) interest rate, plus anticipated inflation. In the long run, inflation usually doesn’t affect supply and demand in capital markets, so the only permanent effect of a higher inflation target is higher nominal rates. Suppose the equilibrium nominal interest rate under a 2-percent inflation target is 5 percent, implying a 3-percent real return with 2-percent anticipated inflation. If the Fed were to increase its inflation target to 4 percent, the equilibrium nominal interest rate would increase to 7 percent, with the real return unchanged.

Higher rates supposedly give the Fed more room to maneuver. To loosen monetary policy, modern central banks reduce their nominal interest rate target. But nominal rates can’t fall much below zero, since one can always hold cash to avoid a negative interest rate. Thus a bigger gap between the “effective lower bound” and the neutral policy rate (again, a nominal variable) means the Fed has a wider scope for stimulative policy. 

Why not give the central bank a wider berth, if it helps to stabilize the economy? Because it doesn’t actually help. Interest rates are a distraction. To loosen monetary policy, the Fed must boost nominal spending. It can do that even if interest rates are at the effective lower bound. Furthermore, inflation doesn’t help the economy. It’s really a drag on the economy.

As I’ve written before, the Fed can’t control the real interest rate. The most it can do is help the economy adjust from one real interest rate to another as economic fundamentals change. In the wake of a recession, interest rates usually fall. The Fed’s job is to nudge dollar-denominated variables in the right direction. Monetary policy is much more like recalibrating the economy’s barometer than flooring the economy’s gas pedal.

Of course, expansionary policy (printing money to purchase securities) can help fight recessions. But the reason isn’t that interest rates are lower. Rather, it’s that the Fed, as the monopoly supplier of high-powered money, can provide the needed liquidity when the economy faces an aggregate demand shortfall. It’s proper to grow the money supply in response to a sudden and unexpected increase in money demand. The textbook effects on interest rates are downstream from this fundamental task.

When we stop thinking in terms of interest rates and start thinking in terms of the supply of and demand for money, we see that there’s nothing special about a 2-percent inflation target. The Fed’s goal is based on consensus and compromise, not any hard and fast rule about how markets work. Remember the dynamic version of the equation of exchange: effective money supply growth must equal total nominal spending growth. Provided market expectations mesh with actual Fed behavior, we can have a full employment equilibrium at 2-percent inflation, 4-percent inflation, or even 0-percent inflation. What matters is the credibility and predictability of policy.

So what’s wrong with higher inflation? In brief, full-employment equilibria are not created equal. High rates of inflation reduce productivity, which means we produce fewer goods and services than we would at a lower rate of inflation.

Inflation throws a wrench in the economy’s gears. Markets are good at creating wealth when prices correctly signal relative resource scarcities. But market prices are denominated in money. Tinkering with money introduces noise in the pricing process. While it’s theoretically possible to have a high, but perfectly neutral, inflation rate, meaning there are no effects of inflation on relative prices, in practice this never happens. More inflation means more variability in how monetary policy affects supply and demand in particular markets. Faster price-level growth almost certainly weakens the market allocation process.

Furthermore, market actors often engage in privately beneficial, but socially costly, behaviors to avoid the effects of inflation. A weakening dollar is a tax on holding cash and other highly liquid assets. The obvious incentive is to economize on these assets as much as possible. But that makes transacting more difficult than it otherwise would be. Likewise, higher inflation rates encourage more frequent contracting, which increases uncertainty as well as the cost of contracting. Inflation is an underappreciated source of transaction costs. 

Finally, although I previously wrote that inflation doesn’t usually affect supply and demand in capital markets, there is an important exception: in the US, capital gains taxes are not indexed to inflation. Since asset prices tend to rise when all other prices are rising, inflation pushes investors into higher tax brackets. They forfeit more wealth to the government despite the fact that, in terms of real resources, their portfolios have not appreciated. This is a major disincentive to save and invest, and hence a drag on economic growth.

The campaign for the Fed to adopt a higher inflation target makes no sense. It’s not supported by policy best practices, or by basic economic theory. Instead, it’s a symptom of the “Great Forgetting” currently plaguing the economics profession. Let’s hope we can put a lid on this misguided idea before it does any real harm.

Tyler Durden
Mon, 06/24/2024 – 15:45

Netanyahu Ready To Wind Down Gaza Operations To Battle Hezbollah In North

Netanyahu Ready To Wind Down Gaza Operations To Battle Hezbollah In North

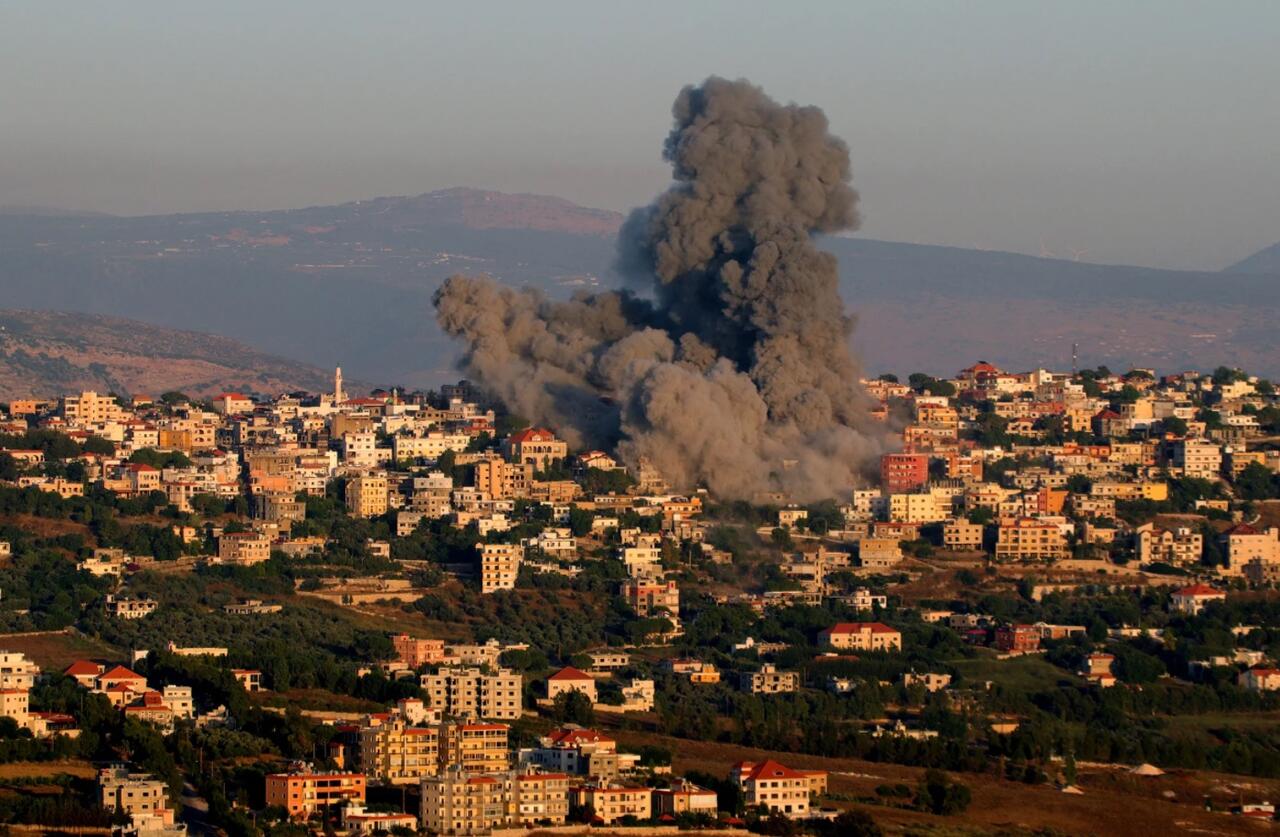
Several Western officials have warned that the Middle East is on the brink of a wider war between Israel and Lebanese Hezbollah, which includes a fresh statement by EU foreign policy chief Josep Borrell warning “We are on the eve of the war expanding.”

“The risk of this war affecting the south of Lebanon and spilling over is every day bigger,” Borrell told reporters while going into a foreign ministers meeting in Luxembourg.

Southern Lebanese village of Khiam near the Israeli border on June 21, 2024. AFP/Getty Images

This follows days ago Hezbollah chief Hassan Nasrallah declaring that if Israel launches a bigger offensive, “nowhere would be safe” and even EU member Cyprus could come under fire given its historic cooperation with Israel’s military. Greek and Cypriot leaders condemned the threat as “absolutely unacceptable”.

German Foreign Minister Annalena Baerbock also on Monday confirmed she’ll travel to Lebanon soon as part of a diplomatic push to avoid escalation. “A further escalation would be a catastrophe for people in the region,” she said.

A Sunday interview by Israeli Prime Minister Benjamin Netanyahu did nothing to calm things, but has only ratcheted tensions, given he signaled that winding down Gaza operations in the south will mean taking a bigger fight to Hezbollah in the north:

Netanyahu said in a lengthy TV interview that while the army is close to completing its current ground offensive in the southern Gaza city of Rafah, that would not mean the war is over. But he said fewer troops would be needed in Gaza, freeing up forces to battle Hezbollah.

“We will have the possibility of transferring some of our forces north, and we will do that,” he told Israel’s Channel 14, a pro-Netanyahu TV channel, in an interview that was frequently interrupted by applause from the studio audience.

First and foremost, for defense,” he added, but also to allow tens of thousands of displaced Israelis to return home.

″We can fight on several fronts and we are prepared to do that,” Netanyahu declared, while also saying he’s still open to diplomatic solution but that the problem can be solved “in a different way” if needed. 

Meanwhile there are fresh reports that France is offering the Lebanese government a military deal if its armed forces agree to push Hezbollah away from the Israeli border. Paris wants the Lebanese army to launch a security operation to move Hezbollah back to the Litani River, however, the scenario is far-fetched.

“Nothing will happen without a political green light,” a French official told an international publication, “[but] we need to be prepared to facilitate an increased presence of the LAF in South Lebanon to contribute to the security of [the] Lebanese people and to the sovereignty of the Lebanese state and territory.”

Amid a daily escalating tit-for-tat exchange of drone and rocket attacks, Iranian fighters are offering to travel to south Lebanon to support Hezbollah. The Associated Press writes that “Thousands of fighters from Iran-backed groups in the Middle East are ready to come to Lebanon to join with the militant Hezbollah group in its battle with Israel if the simmering conflict escalates into a full-blown war, officials with Iran-backed factions and analysts say.” This underscores how easily this could blow up into massive confrontation between Israel and Iran.

Tyler Durden
Mon, 06/24/2024 – 15:05

“Several Days & Not Weeks”: Massive US Auto Dealership Cyberattack Nears Resolution As Hackers Demanded Millions

“Several Days & Not Weeks”: Massive US Auto Dealership Cyberattack Nears Resolution As Hackers Demanded Millions

Great news for anyone trying to purchase a new or used vehicle last week but faced delays due to a nationwide cyber incident that paralyzed the backend operating systems of thousands of auto dealerships: a resolution appears to be underway. 

Bloomberg reports that CDK Global, the main provider of auto dealership management systems and digital retailing solutions, is now in the process of restoring backend systems for more than 15,000 auto retailers affected by last week’s hack. 

CDK sent a message to dealers over the weekend, providing a timeline of “several days and not weeks” to restore systems. 

Bloomberg also reports that the BlackSuit ransomware gang was behind the attack. BleepingComputer first reported this on Saturday. 

This comes days after a Bloomberg report said a suspected hacking group in Eastern Europe is responsible for the CDK cyber incident, and the group demanded tens of millions of dollars in ransom. 

CDK first reported the cyber incident last Wednesday and a second cyberattack on Thursday. The fallout of the centralized service for conducting sales at dealerships across North America forced some dealers to close, while others resorted to pen and paper in closing deals.  

On Thursday, X user Car Dealership Guy was featured on CNBC. He said the auto industry’s biggest question after all this chaos is “Will the industry continue centralizing and consolidating technology? This has been the biggest trend in auto retail.” 

At the end of last week, some customers at dealerships were greeted with this message. 

On Friday, Diana Lee, the chief executive officer of Constellation, a marketing agency with strong ties in the auto industry, told the host of Bloomberg TV that the cyber incident is “just mass chaos at this point … and worse than Covid.” 

Here’s what X users are saying about the incident:

Tyler Durden
Mon, 06/24/2024 – 12:25

A Complex Play To Analyze

A Complex Play To Analyze

By Stefan Koopman of Rabobank

As the group stage of the Euros reaches its zenith, let’s take a look at the European economic game plan for the coming months. Since the beginning of the year, the prevailing view has been that the services sector is poised to score some goals, bolstered by an increase in real wages and a partial recovery from 2022’s significant terms of trade shock. This would be more than enough to counterbalance the manufacturing sector’s losing streak. This has led to an increasingly divergent trend among nations, with Italy and Spain on a winning run, France mostly drawing, and Germany scoring some own goals but eventually finding its footing. This scenario, coupled with the potential for improved European strategies and tactics as outlined in the Letta and Draghi reports, has been quite advantageous for European risk assets this year.

However, as we advance into the year, European economies struggle to find their form. The interest rate shock is still filtering through, coupled with a negative fiscal impulse (i.e. budget deficits are sizable, but not adding to growth). Even though GDP surprised in the first quarter, it was largely driven by net exports instead of domestic demand. The June composite PMI, released last Friday, indeed signaled a slow jog into the second half of the year. In Germany, manufacturing remains the Achilles’ heel, with the PMI diving to 43.4. The services sector is pushing forward with a modest 53.5, although this fell short of expectations too. In France, the private sector stumbled, with a downturn in new orders leading to a contraction in business activity to 48.2. This decline looks to have been compounded by faltering confidence amid France’s electoral uncertainty.

Looking forward, the pundits will tell you that Europe’s economic outlook remains constructive, with expectations that consumer spending will eventually drive the economy towards a more robust growth trajectory. However, the PMIs published last Friday highlight that progress towards such a ‘steady state’ may not be linear. We too anticipate the Eurozone economy to grow by 0.7% this year and 1.4% in 2025, but keep an eye on the potential offside trap of political uncertainties in France. A strong showing of the far-right could be a game-changer, making prospects for significant and much deeper European integration seem like a long shot.

The UK’s PMI softened, marking the private sector’s slowest expansion since November with a reading of 51.7, akin to England’s so-so performance this Euros. Although we suspect that pandemic-related seasonal adjustment problems are still an issue, creating ‘booms’ in the spring and ‘busts’ in summer and autumn, the survey attributes the decline to a temporary halt in business spending amidst the election. Meanwhile, inflationary pressures resurged in June, propelled by a significant rise in transport costs due to global shipping constraints. In the services sector, wages continue to be the primary inflation driver. Prices charged across the private sector consequently rose to a four-month high in June, leaving the Bank of England with a complex play to analyze.

Meanwhile, the UK election remains a bit of a non-event. Coupled with the instability in France, it explains why the pound has been strengthening against the euro. It still seems that Keir Starmer will become the next Prime Minister. All the UK’s issues at hand, excluding those related to the England national team, are predominantly associated with the Conservative Party, which has been in power for the last 14 years. This created space for the Reform Party and a split within the right-wing vote. Had the Conservatives been able to hold the right, they might have presented a stronger challenge to Labour.

The question markets will immediately focus on July 4th: what will be the size of the potential majority? Some speculate that a Labour party with a 200-seat majority would wield much more power than with a 100-seat majority. However, it’s important to remember that there is no such thing as a ‘supermajority’ in this context. Practically, there is little difference between winning a 100- or a 200-seat majority. In fact, we would argue the opposite: larger majorities tend to face more significant rebellions and political uncertainty simply because they have the numbers to do so. We remain constructive on the UK’s outlook post-election, but also note that the Labour manifesto appears better at diagnosing the UK’s underlying problems than at presenting clear policy proposals and spending plans to address them.

Week ahead

President Macron’s move to call for early elections could potentially shift power to the far-right in France. The first round of the election will be held next Sunday and will be pivotal for European assets. As the election nears, polls fluctuate but hint at Marine Le Pen’s party emerging as France’s largest, yet possibly shy of a majority. How these polls play out as we approach Sunday will sway sentiment on the euro and French, or even European, assets. Given that the euro weakened when Macron announced the snap election, an expected Le Pen majority could further weigh on it.

  • Monday: The week kicked off with a fresh look on Dutch GDP for Q1 2024, showing a contraction of 0.5% instead of 0.1%. Meanwhile, housing market data revealed a 8.6% annual increase in prices, pushing the average transaction price to EUR 445k. This is ten times the Dutch modal income of EUR 44k (note that a house ‘earned’ EUR 35k last year by simply existing). The German IFO Index ticked lower to 88.3 points, largely due to weaker expectations. Around lunch, we’ll have the UK’s CBI survey, and the Dallas Fed Manufacturing Outlook will follow. Economic talks by the BOC’s Macklem and the Fed’s Daly are also on the agenda.
  • Tuesday: A series of regional Fed surveys, along with FHFA and S&P CoreLogic housing price indices, will be released. The Conference Board’s consumer confidence index follows. The Fed’s Bowman and Cook are slated to discuss the economic landscape.
  • Wednesday: German consumer confidence figures will set the day’s tone, succeeded by U.S. new home sales data. The Bank of Finland’s monetary policy conference will feature contributions from ECB’s Rehn, Panetta, Kazāks, and Lane.
  • Thursday: Japan’s retail sales, China’s corporate profits, and the EC’s confidence surveys are in focus. The U.S. will revisit Q1 GDP and price data, alongside fresh figures on jobless claims, durable goods orders, and pending home sales. The Bank of England’s financial stability report is due and the ECB’s Kazimir speaks.
  • Friday: The day begins with German import prices and a second glance at the UK’s Q1 GDP. Attention then shifts to preliminary French and Italian HICP figures for June, coupled with the ECB’s inflation expectations survey. In the U.S., eyes will be on the PCE deflator for May. Based on the inputs from the CPI, the PPI and import prices, the core rate is anticipated to show a deceleration to 0.1% m/m and 2.6% y/y. The Chicago PMI and the University of Michigan’s latest findings will round off the workweek.

Tyler Durden
Mon, 06/24/2024 – 12:05