66.8 F
Chicago
Saturday, September 19, 2026
Home Blog Page 2885

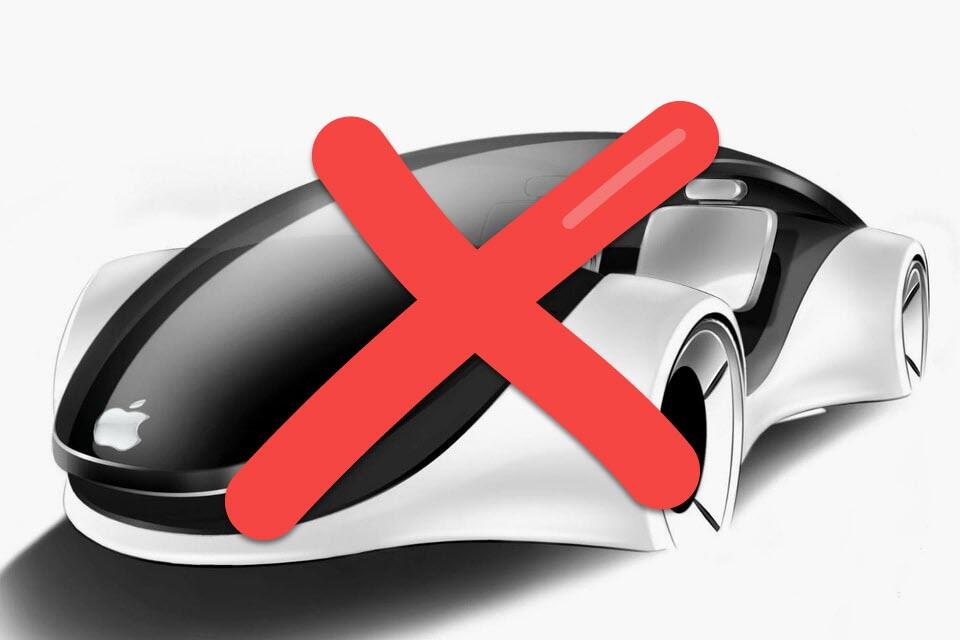
After 16 Years, Apple Abandons Work On Electric Car

0
After 16 Years, Apple Abandons Work On Electric Car

…aaaanndd it’s gone!

Rumors and stock premia and more rumors and now 16 years after plans to build an Apple electric car began with founder Steve Jobs in 2008, it’s over!

Bloomberg reports, according to people with knowledge of the matter, the mega-cap tech company is abandoning one of the most ambitious projects in the history of the company – its effort to build an electric car.

Apple made the disclosure internally Tuesday, surprising the nearly 2,000 employees working on the project, said the people, who asked not to be identified because the announcement wasn’t public.

The decision was shared by Chief Operating Officer Jeff Williams and Kevin Lynch, a vice president in charge of the effort, according to the people.

Finally, of course, Elon Musk had some brief thoughts…

As Bloomberg highlights, the decision to ultimately wind down the project is a bombshell for the company, ending a multibillion-dollar effort that would have vaulted Apple into a whole new industry. The tech giant started working on a car around 2014, setting its sights on a fully autonomous electric vehicle with a limousine-like interior and voice-guided navigation.

So one might expect the share price to decline… But, hey there’s a reason why the share price is rising…

…because Apple is shifting its focus to – drum roll please – many employees on the team working on the car — known as the Special Projects Group, or SPG — will be shifted to the artificial intelligence division under executive John Giannandrea.

Those employees will focus on generative AI projects, an increasingly key priority for the company.

Of course! The question now is – will the company rename itself to Woke.ai?

Gemini – you ain’t seen nothing yet!

Tyler Durden
Tue, 02/27/2024 – 14:18

Fed And Treasury Ensure Dollar Downside Is Ahead

0
Fed And Treasury Ensure Dollar Downside Is Ahead

Authored by Simon White, Bloomberg macro strategist,

The Fed’s pivot in December and the Treasury’s willingness to run persistently large fiscal deficits will lead the dollar to resume its downtrend from 2022 highs.

Dollar strength seems to be in vogue again, but fiscal and monetary policy will conspire to make that trend unlikely to persist much longer. Running pro-cyclical fiscal deficits, not just in the US but across much of the developed world, has become the norm. Electorates’ expectations widened after the pandemic, and now there is an unwritten pact between governments and their voters that they will underwrite a growing itinerary of risks from job loss to disease – the Treasury put.

Large fiscal deficits are a long-term negative for the currency as they are inflationary, and considering the US deficit is one of the largest in GDP terms, it poses greater downside risk to the dollar versus other currencies. This will also be a tailwind for the new bull market in stocks.

But shorter-term leading indicators are also dollar negative. On this horizon, the real yield curve gives one of the best leads on the dollar, by about six-to-nine months. This is where the Fed’s pivot comes in.

The real yield curve had been steepening last year, as longer-term real yields were rising more than shorter-term ones, due in part to the influence of rising term premium. That would have anticipated a rising dollar. The real yield curve then began to re-flatten, which continued even after the Fed performed its verbal volte-face in December, as longer-term real yields have risen much less than short-term ones.

The DXY index is up ~2.3% this year, versus the average of 1.4% in the first two months of the year (data back to 1980). But the dollar typically sees all its net gains in the first three months of the year (1.7%) versus an average decline of 0.9% through the remainder.

Net positioning in the dollar is flat, leaving speculators free to move with or against it. They should favor the latter, and not be deterred by recent dollar strength (which is fairly unremarkable), and instead look to the seasonally negative latter three quarters of the year, given extra credence by fiscal and monetary policy that will continue to be a headwind.

Tyler Durden
Tue, 02/27/2024 – 12:20

Biden Meets With ‘Big Four’ Congressional Leaders Over Ukraine Aid, Shutdown

0
Biden Meets With ‘Big Four’ Congressional Leaders Over Ukraine Aid, Shutdown

As lawmakers have days to strike an agreement to avert a partial government shutdown on Friday, President Biden has called a meeting with the ‘big four’ Congressional leaders to discuss how the United States can funnel more money to Ukraine, while also convincing lawmakers to strike a deal to keep the government’s lights on.

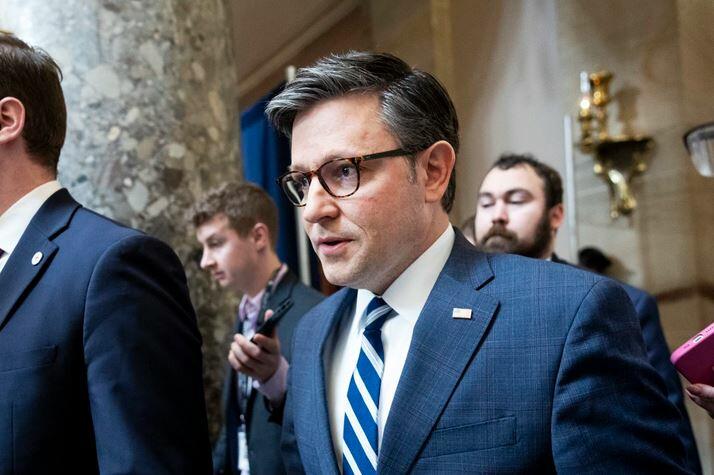
Speaker of the House Mike Johnson at the Capitol on Feb. 13, 2024.Kevin Dietsch / Getty Images

House Speaker Mike Johnson’s remains in a dilemma – having to choose between a deal with Democrats to avoid a partial government shutdown, or side with the House Freedom Caucus who are happy to play chicken over a shutdown.

Last Friday, Johnson told members that another stopgap could be required to buy time while lawmakers iron out final details. That said, April 30 is a hard deadline for Democrats, who will refuse to support 1% across-the-board funding cuts that kick in after that date.

Johnson is caught between House conservatives opposed to further spending, and establishment-loyal military hawks who want to avoid defense cuts that would be triggered if Congress fails to enact new full-year spending appropriations by April 30. The conservative Freedom caucus, meanwhile, has no problem with a shutdown that would bring the country closer to those 1% cuts.

According to Axios, GOP members are pessimistic about today’s White House meeting, while the WSJ suggests that such White House summits “tend to be more stagecraft than statecraft—high-profile opportunities for both sides to show they are fighting for their parties’ priorities, rather than nitty-gritty policy negotiations.”

For months, the Republican House and Democratic Senate have deferred on Congress’s responsibility to set new spending levels and priorities for the federal government for fiscal year 2024, instead passing a series of stopgap measures by repeatedly extending spending levels set back in December 2022.

Now once again time is running out. In the coming hours or days, Johnson could seal a deal with congressional Democrats and try to pass fresh full-year spending legislation. Two thirds of lawmakers would need to approve it. Johnson could put it off a few days or weeks with a short-term patch, again with Democrats’ help. Or he could try to rely on his narrow and rebellious Republican majority to pass another stopgap bill through September, triggering automatic across-the-board spending cuts. –WSJ

“In less than a week, the federal government will begin to shut down, unless both sides—both sides—work together to extend funding,” Senate Majority Leader Chuck Schumer (D-NY) said in a Monday floor speech. “Meanwhile, the moral obligation for Congress to help the people of Ukraine, and fortify our own national security, grows heavier with each passing day.”

Johnson said Schumer was playing “petty politics,” and that the House “has worked nonstop, and is continuing to work in good faith, to reach agreement with the Senate on compromise government funding bills in advance of the deadlines.”

U.S. Senate Minority Leader Mitch McConnell (R-Ky.) is followed by reporters as he leaves the office of Majority Leader Chuck Schumer (D-N.Y.) at the Capitol Building in Washington on Feb. 26, 2024. (Anna Moneymaker/Getty Images)

Senate Republican Leader Mitch McConnell (R-KY) insisted that GOP lawmakers in the upper chamber are “not going to allow the government to shut down.”

“Shutting down the government is harmful to the country. And it never produces positive outcomes—on policy or politics,” McConnell said in Monday remarks.

As the Epoch Times notes further; Mr. McConnell warned that without a swift resolution by Friday, the nation could experience disruptions across vital sectors, including agriculture, transportation, military construction, and essential services at the Department of Veterans Affairs.

The Senate Republican leader said that a government shutdown is entirely avoidable, citing the Senate’s passage of the first full-year spending package for critical areas last November.

We have the means—and just enough time this week—to avoid a shutdown and to make serious headway on annual appropriations,” Mr. McConnell said. However, he stressed that it requires lawmakers to work together to achieve “clean appropriations” and avoid “poison pills.”

The veteran GOP leader, noting the significance of the matter, said that millions of Americans would be closely monitoring Congress’s actions this week.

“American farmers and ranchers, like the Kentuckians visiting Washington this week, expect us to take the challenges they face in feeding our nation seriously,” he said.

“Veterans who swore to protect and defend expect us to keep our promise to care for them when they return home. In the coming days, we’ll need to do just that.”

Roadblocks may come in the GOP-led House.

The sticking points in the political standoff are President Joe Biden’s contentious request for billions of dollars for Ukraine and Israel and concessions sought by hardline Republicans, including on U.S. border security, which has been an issue of bipartisan concern.

Earlier this month, the Senate passed a bill to fund the federal government for the fiscal year that included $95 billion for Ukraine and Israel aid but not for the southern U.S. border. House Speaker Mike Johnson (R-La.) declared the bill dead on arrival in the lower chamber.

White House press secretary Karine Jean-Pierre said the president intends to urge a deal to keep the government funded beyond Friday and continue his advocacy for billions of dollars to be provided to Ukraine and Israel.

“A basic, basic priority or duty of Congress is to keep the government open,” Ms. Jean-Pierre said. “So, that’s what the president wants to see. He’ll have those conversations.”

Last month, Congress passed a “continuing resolution,” a stopgap measure, to extend the deadline to pass its annual appropriations bills to March 1 and March 8 for the Senate and House, respectively. The CR meant that some government departments continued to be funded at current levels, including the Pentagon, Department of Homeland Security, and the Department of State, until Friday.

Story continues below advertisement

Without the CR, government funding would have otherwise partially run out on Jan. 19. This was Congress’ third such short-term measure in four months.

Tyler Durden
Tue, 02/27/2024 – 12:00

FBI Chooses Stock Image Of Well-Dressed White-Women To Depict Organized Retail-Crime

0
FBI Chooses Stock Image Of Well-Dressed White-Women To Depict Organized Retail-Crime

Authored by Steve Watson via Modernity.news,

The FBI was roasted on X for choosing to depict the problem of organized retail crime with an image of two well dressed white women.

Yes, really.

“Higher prices, dangerous products, and closing businesses,” the law enforcement body posted on X.

“These are just some of the impacts Organized Retail Theft has on everyday Americans. Learn what the #FBI does to combat these crimes on the federal level to protect shoppers across the country.”

The image shows two well dressed middle class white women looking furtive, with one hiding a stolen handbag inside her coat.

Respondents noted that the typical demographic of organized retail thieves in big cities doesn’t correlate with the chosen image.

Another image used by the FBI showed a white man stealing something from a supermarket.

According to the FBI’s own arrest record crime statistics, 52.7 per cent of robberies are carried out by blacks or African-Americans, despite the fact they only make up about 13 per cent of the population.

Even with a significantly higher population, whites in America only account for 44.7 per cent of robberies.

The significant majority of these robberies will also have been carried out by men, making the choice of well dressed white women even more bizarre.

As ever, they got ratioed into oblivion.

Many joked that the FBI appears to have used Google’s AI program to generate the images.

*  *  *

Your support is crucial in helping us defeat mass censorship. Please consider donating via Locals or check out our unique merch. Follow us on X @ModernityNews.

Tyler Durden
Tue, 02/27/2024 – 11:40

Moscow Reacts To Macron Proposing European Boots On The Ground In Ukraine

0
Moscow Reacts To Macron Proposing European Boots On The Ground In Ukraine

French President Emmanuel Macron is now openly discussing the possibility of sending European troops to Ukraine to fight the Russians, which would without doubt trigger WW3 between major nuclear powers.

His jingoistic words came just at the end of a summit held in Paris in support of Ukraine, which involved 20 mainly European leaders. He said of efforts to arm the Ukrainians with more advanced weapons, “people used to say give them just sleeping bags and helmets.” But he emphasized that now “Nothing should be ruled out.”

He admitted there is as yet “no consensus” on sending Western troops Ukraine but he laid out that “We will do anything we can to prevent Russia from winning this war.”

Getty Images

Macron warned in his remarks, “There is a change in Russia’s stance. It is striving to take on further territory and it has its eyes not just on Ukraine but on many other countries as well, so Russia is presenting a greater danger.”

“We’re at a critical moment in this conflict that requires us to take the initiative,” Macron said while also unveiling a new European coalition which is to provide Kiev with medium-range and long-range missiles. President Putin and top Kremlin officials have repeatedly rejected the charge that Russia is seeking to wage an expansionist war in Europe and in other former Soviet satellite states.

According to CNN, “Macron had told reporters at a news conference that while he and the other 21 European leaders present did not agree on deploying military personnel, the prospect was discussed openly.” However, Germany, the UK, Poland and others have rejected the possibility of deploying troops, with German Chancellor Olaf Scholz – who was among those present – later emphasizing that participants were “unanimous” in being set against it. The statement out of the UK prime minister’s office was interesting, given it admits the “small number of personnel” already on the ground in Ukraine: 

Britain is not planning a “large-scale deployment of troops” in Ukraine, Prime Minister Sunak’s press secretary said. “Other than a small number of personnel who are in the country supporting the Ukrainian armed forces, we have no plans for a large-scale deployment,” he was quoted as saying by Reuters.

Germany’s Scholtz tried to caution, “What was agreed among ourselves and with each other from the very beginning also applies to the future, namely that there will be no ground troops, no soldiers on Ukrainian soil sent there by European countries or NATO states.”

Macron’s bluster further resulted in NATO Secretary-General Jens Stoltenberg issuing a response. “NATO allies are providing unprecedented support to Ukraine. We have done that since 2014 and stepped up [support] after the full-scale invasion. But there are no plans for NATO combat troops on the ground in Ukraine,” he said.

As for the Kremlin response to Macron raising the issue of ‘boots on the ground’ – it was snippy and sarcastic, calling out French hypocrisy

“As for Emmanuel Macron’s statements about potentially deploying NATO troops to Ukraine, <…> one gets a strong feeling that the French president realizes neither what his subordinates say nor what he says himself,” the diplomat wrote on Telegram.

Zakharova pointed out in this regard that just a month ago, the top French diplomat had denied that Paris was involved in recruiting mercenaries for the Kiev regime, slamming direct evidence as “crude Russian propaganda.”

Referencing an infamous French SS division from WW2, Zakharova further quipped: “Emmanuel, have you decided to form a Charlemagne deux (two) division to defend [Ukrainian President Vladimir] Zelensky’s bunker?”

But Moscow also warned of major direct conflict with the West. According to more from the Kremlin response: “The very fact of discussing the possibility of sending certain contingents to Ukraine from Nato countries is a very important new element…in that case, we would need to talk not about the probability, but about the inevitability (of a direct conflict).”

But the Kremlin wasn’t the only one to provide a sarcastic critique of Macron’s words. This was the tone even among some allies. For example Germany’s deputy chancellor Robert Habeck called out France for not doing much heavy lifting on transferring weapons to Kiev compared to other in the alliance.

“I’m pleased that France is thinking about how to increase its support for Ukraine, but if I could give it a word of advice — supply more weapons,” Habeck said Tuesday. And yet President Macron wants to ‘talk tough’ and issue maximalist threats of direct action.

All of this comes as Ukraine is in retreat, following Russia’s capture of the eastern city of Avdiivka. Several other smaller towns and cities have also fallen, with Ukraine’s front lines in disarray. This has resulted in several days of what might be called empty threats being issued from the West, as it sits helplessly while watching Russian forces advance.

Tyler Durden
Tue, 02/27/2024 – 11:20

A Great Variety Of Moron Symptoms Appear

0
A Great Variety Of Moron Symptoms Appear

By Michael Every of Rabobank

A great variety of moron symptoms appear

Like Gramsci, look around and see the old is dying and the new cannot be born; see the great variety of morbid symptoms appearing as a result; and the greater variety of moron symptoms.

  • AI is not the new tech bubble, honest, even if there appears to be a staggering degree of artificiality in the intelligence it’s showing to us. (Presumably, it’s ‘impossible to tell’ if this Daily is ‘as bad as Hitler or Stalin’, because it contains statements some readers may not agree with.)
  • At the start of year three of the Ukraine War, President Macron just presided over a meeting of EU powers, stated, “We will do everything needed” to stop Russia winning, yet delivered no new weapons, while also declaring there was no consensus to send in EU troops on the ground, “but in terms of dynamics, nothing can be ruled out.” Really? Because I can rule that out right now.
  • In the Red Sea crisis, as flagged, analysis by Sea-Intelligence shows the need to move empty containers back to producers has grown 2.5 times faster than that to move full containers out. That isn’t good for global logistics, just as it wasn’t during Covid. Neither are reports of a shortage of oil (and LNG) tankers due to longer routes being taken. Meanwhile, the Houthis may have cut key Asia-Europe internet cables: Moody’s, who say Suez is having no inflationary impact, even as half of UK businesses are feeling its effects, will only notice when they can’t order lunch at a swipe. (Stick to UNCTAD’s ‘Navigating Troubled Waters’ on this issue.)
  • And on lunch, a US fast food chain is to experiment with surge pricing models: its burgers will now get more expensive at mealtimes. I’m sure the BLS team are onto this trend, if it spreads, and will show it means lower prices, when adjusted for eating when not hungry, right?

But let’s not get distracted by micro-Gramscis of hot air, Houthis, and hunger-pangs when the kilo-Gramscis are in understanding what a changing geopolitical and geoeconomic order means.  

A Financial Times op-ed says ‘our global trade system is in desperate need of an overhaul’, repeating my old argument that Ricardo’s free trade comparative advantage theory itself admits it won’t work in a world of mobile global capital, which we censor, as we do Smith arguing the “invisible hand” actually keeps investors’ money circulating domestically. Yes, our system is now more imbalanced thanks to China, even as a global bifurcation away from it is underway. But there will be no joint overhaul, and things will likely be resolved via Western protectionism. In short, Trump started a trade war; Biden extended it; Trump, if he wins, now threatens a return to full US mercantilism. If you work in economics and/or markets and you don’t understand what that means, you are in desperate need of an overhaul.

In narrow terms, the market is again seeing America First means Dollar First regardless of narratives about gold, or BRICS, or, as I put it to Jim Rickards, of countries throwing bricks of gold at each other. That’s even more the case if the Fed isn’t rushing to cut rates. After more comments from Schmid noting, “further disinflation will need to come from services,” that, we may need to cool demand further to tame price pressures,” and that moderating US wage growth was needed to get back to 2% CPI, not only should we look to the RBNZ meeting tomorrow, but try to imagine if the next set of US payrolls and CPI prints come in hot again. If the three 25bp rate cuts our ahead-of-the-curve Fed watcher Philip Marey –and, belatedly, the market– expects for 2024 then get pushed back from June, how close to, or after, the US election can the Fed move without being seen as political?

Yet US mercantilism, alluded to by the FT, shakes every market box and every asset tree. On this front, Michael Pettis, asks ‘Can Trade Intervention Lead to Freer Trade?’ and “Doesn’t an expansion of global trade always benefit the countries that participate in international trade and, more generally, the global economy?” He answers, “No,” before showing why this is so, logically.

  • Only capital controls, not tariffs, can stop foreign purchases of US assets to prevent mirroring trade surpluses: that’s the Ricardo (and Smith) argument in another form.
  • The US should only impose tariffs on mercantilists while holding to free –but balanced– trade with likeminded countries. That would shake Japan and Europe and mean global bifurcation, as the FT yesterday notes, ‘China plans to reshape trade on its own terms’.
  • If the US acts like this, the dollar’s global reserve currency status would be broken. Yet that doesn’t mean it would collapse. Nothing could replace it, and in a mercantilist world where it’s harder to get trade dollars –with massive offshore Eurodollar debts to repay– the buck would remain essential, and more expensive.

Pettis also makes clear Wall Street would suffer in this scenario, which US capital controls obviously entail. That’s as Bloomberg notes ‘Xi Crackdown on ‘Hedonistic’ Bankers Fuels Industry Brain Drain’, which sounds like the common prosperity so many on Wall Street tried to sell me as ‘regulatory reform’; and ‘Beijing warns China’s US$63 trillion financial sector: serve the real economy and enrich lives’, as state media tells the financial sector to focus on supporting the real economy and refrain from “fake financial innovation,” or Marx’s “productive” over “fictitious capital”… and so more mercantilism. Meanwhile, both the US and Europe governments are begging their financial sectors to invest in the real economy, particularly in defence goods, not to speculate on assets: clearly, things will have to change if the West is to keep up.

Indeed, former ECB President Draghi recently noted, “Many profound changes have taken place in the last few years in the global economic order. These changes have a variety of consequences, one of which is clear… that we’ll have to invest an enormous amount in a relatively short time in Europe,“ underlining the need for “bold action to cover the cost” of the green, digital, *and* defence transitions. That’s trillions of Euros a year – covered how, exactly? And US maritime expert John Konrad favours disbanding the US army and rebuilding the US Navy and merchant marine to cement its global economic power, while removing income taxes and relying on tariffs for revenue, as was originally the US model.   

So, yes, the old is dying and the new cannot be born; and we have a great variety of morbid symptoms appearing as a result. And if you think none of these will happen in whole or in part, and perhaps soon, or that you can play both sides forever as it does, then you are suffering from a great variety of moron symptoms.

For an example, McKinsey has been dragged into a scandal after it was revealed it helped counsel China on a mercantilist industrial policy initiative that raised tensions with the US, while presumably also working with US firms and politicians to downsize and offshore American production, as it the industry norm. The firm is now being threatened with the potential loss of US government contracts, while how much of a future it, or any Western management consultant, holds in a China focused on the real, not fictitious or hedonistic, economy remains to be seen.

Tyler Durden
Tue, 02/27/2024 – 11:00

Denmark Drops Probe Into Nord Stream Gas Pipeline Sabotage

0
Denmark Drops Probe Into Nord Stream Gas Pipeline Sabotage

By Tsvetana Paraskova of OilPrice.com

Denmark is dropping the investigation over what it described as a “deliberate sabotage” of the Nord Stream gas pipelines in 2022, due to insufficient grounds to pursue a criminal case, the Copenhagen police said on Monday.

Gas leaks in each of the Nord Stream 1 and 2 pipelines were discovered at the end of September 2022 from the infrastructure just outside Swedish and Danish territorial waters in the Baltic Sea.  

Nord Stream 2 was never put into operation after Germany axed the certification process following the Russian invasion of Ukraine. Russia, for its part, shut down Nord Stream 1 indefinitely in early September of 2022, claiming an inability to repair gas turbines because of the Western sanctions.  

An investigation launched by the Swedish authorities concluded that the leaks were the result of detonations, likely the result of “serious sabotage”. 

But earlier this month, Sweden’s authorities concluded a preliminary investigation into the Nord Stream blasts but found they lacked jurisdiction to continue, as the incident occurred in international waters and involved no Swedish nationals. Therefore, Sweden ended the probe in early February.

Denmark also ended its investigation on Monday, with the Copenhagen police saying in a statement that “The joint investigation conducted by the Copenhagen Police and the Danish Security and Intelligence Services (PET) into the Nord Stream explosions has been concluded.”

Throughout the investigation, the Danish authorities have cooperated with relevant foreign partners, Denmark said.

“The investigation has led the authorities to conclude that there was deliberate sabotage of the gas pipelines. However, the assessment is that there is not the sufficient grounds to pursue a criminal case in Denmark,” the police said.

Apart from Denmark and Sweden, Germany has also investigated the Nord Stream blasts, but Berlin hasn’t concluded its own investigation into the sabotage. A spokesperson for the government told Reuters earlier in February that Germany was still interested in solving the case.    

Tyler Durden
Tue, 02/27/2024 – 08:50

US Durable Goods Orders Collapsed In January – Biggest Drop Since COVID Lockdowns

0
US Durable Goods Orders Collapsed In January – Biggest Drop Since COVID Lockdowns

The last few months have been volatile – to say the least – for US durable goods orders, with preliminary January data showing an enormous 6.1% MoM plunge in the headline (worse than the already bad 5% decline expected).  That is the weakest MoM print since the middle of the COVID lockdowns in April 2020, dragging year-over-year orders growth down to -0.8% – the lowest and first annual contraction since August 2020…

Source: Bloomberg

Excluding transportation equipment, orders fell 0.3%.

It appears Boeing’s doors-flying-off-our-planes issue had some impact as non-defense aircraft orders crashed 58.5% MoM (the worst since 2019 (Max…). But the numbers were helped by war spending being up 24.2% MoM…

Source: Bloomberg

Boeing reported only three orders in January, the fewest in more than three years after a near-catastrophic accident early in the month led regulators to ground some of its planes.

On the bright side, core capital goods shipments, a figure that is used to help calculate equipment investment in the government’s gross domestic product report, bounced back from contraction in December…

Source: Bloomberg

So as goes Boeing, so goes the manufacturing economy… and as goes NVDA, so goes the stock market? Fuck yeah ‘Murica!

Tyler Durden
Tue, 02/27/2024 – 08:41

Futures Flat Ahead Of Flood Of Economic Data

0
Futures Flat Ahead Of Flood Of Economic Data

US equity futures pointed to modest gains, led by tech stocks – following Monday’s 38bps drop which was the worst Monday since early December and the second worst Monday since last June – as investors looked ahead to economic data and commentary from Federal Reserve speakers in coming days for clues on the outlook for interest rates. As of 8:00am ET, S&P 500 futures rose 0.1% while Nasdaq 100 contracts added 0.3%. Europe’s Stoxx 600 index was also flat, hovering near its all-time high. Two-year notes led gains as Treasuries rose, retracing some of Monday’s drop. The dollar slipped, oil dipped and bitcoin soared above $57,000. It’s a busy day for economic data, which includes January durable goods orders (8:30am), Case-Shiller home prices (9am), consumer confidence, Richmond Fed and Dallas Fed.

In premarket trading, cryptocurrency-linked stocks rise after Bitcoin’s price reached the $57,000 level for the first time since late 2021 (Cleanspark (CLSK) +16%, Coinbase (COIN) +6, Marathon Digital (MARA) +12%). Hess shares dropped premarket after Chevron said its $53BN acquisition of Hess faces potential disruption as rivals ExxonMobil and CNOOC claim pre-emptive rights over Chevron’s stake in a crucial Guyana oil project (the largest oil discovery in a decade). Discussions are ongoing, but failure to resolve this could jeopardise the Hess takeover, Chevron said.

Macy’s shares were volatile after it said it plans to close 150 unproductive locations as the department-store chain seeks to fight off a pair of activist firms seeking to buy the company. Zoom shares jumped 13% in US premarket trading after the video-conferencing software company’s guidance for adjusted earnings per share was stronger than expected. Additionally, Zoom also said its board approved a buyback program. Here are some other notable premarket movers:

  • Aaron’s slumps 25% after providing disappointing 2024 forecasts.
  • Altice USA gains 4% after Bloomberg reported that Charter Communications is exploring a takeover of the cable provider.
  • Cava rises 7% after the restaurant chain posted fourth-quarter sales that beat expectations as diners splurged on premium dishes.
  • Hims & Hers Health (HIMS) soars 18% after the telehealth group’s forecast for first-quarter revenue topped the average analyst estimate.
  • Workday shares fell 7.2% in US premarket trading after the human resources software company issued full-year subscription revenue forecast that was weaker than expected at the midpoint. The company also reported fourth-quarter results that analysts said showed less upside than usual.
  • Unity Software shares slid 17% in US premarket trading after the video-game software development company’s forecast for revenue fell short of expectations amid a portfolio review that includes exiting some businesses.
  • Lowe’s said its sales will fall further this year as consumers continue to hold off from sprucing up their homes amid higher mortgage rates and a drop in new construction projects.
  • Janux Therapeutics jumps 106% after the company reported updated clinical data.
  • PubMatic rises 27% after the advertising technology company’s fourth-quarter earnings beat expectations, with analysts highlighting a boost from new products.
  • TransMedics gains 21% after the transplant therapy biotechnology company reported fourth-quarter revenue that beat the average analyst estimate.

Readings on the US economy are in sharp focus this week, with the Fed’s favored inflation gauge due on Thursday grabbing the most attention. Markets have already dialed back expectations for early and rapid Fed easing after hotter-than-expected data on jobs and price gains, pushing out bets on a first cut to June or July.

“We have always been in the camp that the Fed is unlikely to move as quickly as the market was pricing and data for the first couple of months will only confirm that the first cut will be pushed into the third quarter,” said Matt Stucky, chief portfolio manager for equities at Northwestern Mutual Wealth Management Co.

In response to some arguments that stocks are in another tech bubble, Citigroup strategists said they don’t regard the US equity market as being in a bubble like that of 1999-2000, and suggested the rally could spread to other sectors. Valuation multiples for stocks are well below 2000 levels and, while cash flow expectations around tech companies have increased, forecasts for other industry groups aren’t stretched. That supports the case for broader equity gains.  

“We argue that ‘bubble’ is the wrong term to describe the current market setup,” the Citigroup team led by Scott Chronert wrote. “Rather, the recent rally puts pressure on fundamentals to deliver.”

Elsewhere, Bitcoin climbed, rising briefly beyond $57,000 for the first time since late 2021, supported by investor demand through exchange-traded funds as well as further purchases by MicroStrategy Inc.

European stocks were little changed, with mining and autos & parts shares leading gains, while personal care and media stocks are the biggest laggards; drinkmakers’ stocks rose as earnings from Aperol-maker Davide Campari-Milano exceed analyst forecasts. The moves followed sharp drops over the past year for beverage manufacturers amid worries about destocking and consumers turning to cheaper alternatives. Campari gained as much as 7.5% while Remy Cointreau (+2.2%), Pernod Ricard (+1.8%), Diageo (+1.6%) also rise. Here are the biggest movers Tuesday:

  • Bouygues rises as much as 5.3% after the French conglomerate reported full-year results, with Morgan Stanley saying that a beat on free cash flow was the main highlight
  • GTT shares gain as much as 9%, to touch their highest since August 2022, after the French engineering company’s guidance for 2024 Ebitda beat analysts’ consensus at the mid-point, according to data tracked by Bloomberg
  • Flutter shares gain as much as 5.7% in London as Barclays upgrades the stock to overweight from equal-weight, seeing earnings growth over several years as the gambling operator’s US market share strengthens
  • Abrdn rose as much as 7.8% after the UK asset manager reported adjusted operating profit above estimates, with analysts also drawing attention to stable net interest margins
  • SIG Group shares rise as much as 3.6%, the most since February 2023, after the Swiss carton-packaging maker’s cashflow turned positive thanks a strong 4Q, according to Vontobel
  • Puma shares advance as much as 3.9% after the sportswear brand reported full-year results. The company also said it sees weaker demand for sneakers and sports gear persisting through the first half of the year before picking up amid major sporting events
  • Eurofins Scientific shares fall as much as 12%, the most in a year. Morgan Stanley said cashflow was disappointing from the laboratory testing services company, citing the cost of higher start-up losses and more restructuring
  • Straumann shares decline as much as 7.1% after the Swiss dental equipment company reported operating profit was much weaker due to restructuring and impairment
  • Croda shares fall as much as 3.6% after the British specialty chemicals firm reported FY23 results. Citi analysts say though the figures mark the end of a difficult year
  • Rovi declines as much as 9% after the Spanish pharmaceutical company said it expects revenue to decrease by a mid-single-digit percentage in 2024. It’s the steepest drop since May last year

Earlier in the session, Asian stocks declined in the absence of fresh catalysts to drive the regional benchmark’s longest stretch of weekly gains in more than a year, with shares in Japan and Hong Kong reversing earlier advances. The MSCI Asia Pacific Index fell 0.2%, reversing a rise of as much as 0.3%, with losses in technology stocks weighing on the index. Japan’s benchmarks, reversed an early advance, while stocks also fell in Korea, Taiwan and Singapore. Mainland and Hong Kong-listed Chinese shares declined, extending Monday’s slide, as attention shifts to next week’s NPC meet. Hong Kong’s benchmark dropped ahead of the budget announcement on Wednesday.

  • Hang Seng and Shanghai Comp. were mixed with the mainland mildly positive after the PBoC injected liquidity and with China said to consider approving additional REITs to support consumption.
  • ASX 200 was choppy as strength in the consumer sector was partially offset by weakness in miners.
  • Nikkei 225 printed fresh record highs before reversing the advances as participants digested the latest CPI data.

Japan’s two-year yield climbed to the highest since 2011 after stronger-than-expected inflation data boosted bets the central bank will end its negative-interest-rate policy in coming months. Traders increased the probability of Bank of Japan exiting its negative rate policy by April to about 82%, up from 78% on Monday, according to swaps data compiled by Bloomberg. The yen strengthened against the dollar.

The inflation report “is adding to speculation that the BOJ will end negative-rate policy as early as March and is serving as a selling catalyst for bonds,” said Kazuya Fujiwara, a fixed-income strategist at Mitsubishi UFJ Morgan Stanley Securities Co. in Tokyo. The data underscores persistent inflationary pressures, he said.

In FX, the Bloomberg Dollar Spot Index drops as much as 0.2% before paring losses to 0.1%  while the yen stood atop the G-10 FX leader board, rising 0.3% versus the greenback after Japanese CPI topped estimates and pushed two-year JGB yields to the highest since 2011. The greenback also lagged the Australian dollar, though outperformed others incuding Sweden’s krona.

In rates, treasuries held small gains across the curve after being led higher by bunds and gilts after data showed inflation in UK stores slowed to the lowest level since March 2022. 10-year US TSY yields were around 4.26%, about ~2bps lower on the day, with bunds and gilts outperforming by 0.5bp and 2bp in the sector; gilts, richer by 3bp-4bp on the day, lead gains in core European rates as BOE rate cuts are more aggressively priced. Supply remains the main theme, with $42 billion 7-year note auction at 1pm and another heavy slate of new corporate bonds anticipated after $27 billion was priced Monday.  The week’s coupon issuance concludes with today’s 7-year note auction, and follows small tails for 2- and 5-year notes Monday; the WI 7-year yield near 4.30% is about 19bp cheaper than January’s, which tailed by 0.3bp. The dollar IG credit issuance slate includes a handful of deals already; 18 names priced $27b across 37 tranches Monday on order books that were three times oversubscribed according to Bloomberg, spreads compressed nearly 25bps across execution and attrition rates climbed. Another busy session is is expected Tuesday, before critical inflation data later this week.

In commodities, oil steadied after Monday’s gains as pockets of strength in physical markets supported wider sentiment; WTI trade near $77.60 while Brent was at $82.40. Iron ore gained after Monday’s hefty loss, as market watchers looked for signs China’s approaching construction season will bolster demand after costs of the raw material dropped. Spot gold is up 0.2%.

Bitcoin surged more than 4%, hitting a fresh two-year high and rose above $57,000, extending on the sharp gains seen on Monday, with the latest ETF inflows confirming that retail interest continues to surge.

Looking at today’s calendar, US economic data includes January durably goods orders (8:30am), 4Q house price purchase index, December FHFA house price index and S&P CoreLogic Case-Shiller home prices (9am), February Richmond Fed manufacturing index, consumer confidence, and Richmond Fed business conditions (10am) and Dallas Fed services activity (10:30am). Fed speakers scheduled include Barr at 9:05am.

Market Snapshot

  • S&P 500 futures up 0.1% to 5,085.50
  • STOXX Europe 600 little changed at 495.81
  • MXAP up 0.3% to 173.34
  • MXAPJ up 0.2% to 527.76
  • Nikkei little changed at 39,239.52
  • Topix up 0.2% to 2,678.46
  • Hang Seng Index up 0.9% to 16,790.80
  • Shanghai Composite up 1.3% to 3,015.48
  • Sensex up 0.5% to 73,141.23
  • Australia S&P/ASX 200 up 0.1% to 7,663.01
  • Kospi down 0.8% to 2,625.05
  • German 10Y yield little changed at 2.43%
  • Euro little changed at $1.0854
  • Brent Futures little changed at $82.57/bbl
  • Gold spot up 0.2% to $2,035.73
  • U.S. Dollar Index down 0.12% to 103.71

Top overnight news

  • Japan’s Jan CPI overshoots the Street, with headline coming in at +2.2% (vs. the Street +1.9% and vs. +2.6% in Dec) while core rises 3.5% (vs. the Street +3.3% and vs. +3.7% in Dec). BBG
  • Chinese regulators are taking measures to keep the renminbi’s dollar exchange rate stable as Beijing seeks to bolster confidence in the country’s currency and economy ahead of a key leadership summit. FT
  • China’s state-backed funds have poured more than 410 billion yuan ($57 billion) into onshore shares this year in a bid to prop up the market. Further purchases are expected. BBG
  • Samsonite is weighing its options following interest from suitors including buyout firms, people familiar said. Some PE firms are considering acquiring the company and relisting it in another market — such as the US — at a higher valuation. Shares jumped in Hong Kong. BBG
  • President Emmanuel Macron of France on Monday said “nothing should be ruled out” after he was asked about the possibility of sending Western troops to Ukraine in support of the embattled nation’s war against Russia. NYT
  • Iran reduced its stockpile of near-weapons-grade nuclear material even as it continued expanding its overall nuclear program, the United Nations’ atomic watchdog said Monday, marking a surprise step that could ease tensions with Washington. WSJ
  • President Biden said Monday that fighting in Gaza could stop as early as this coming weekend, the most detailed timeline to date from the White House on a cease-fire between Hamas and Israel in Gaza. WSJ
  • Federal Reserve Bank of Kansas City President Jeffrey R. Schmid said the US central bank should be patient in cutting interest rates with inflation above its 2% target and the job market still strong. In his first major speech since taking the job six months ago, Schmid also said he’s in no hurry to stop the ongoing reduction of the Fed’s balance sheet. BBG
  • Sixth Street wants to go big on beaten down real estate to capitalize as banks grapple with stress in their portfolios. “We don’t think this is systemic risk, but there are obviously large exposures, particularly in some of the small and regional-sized banks,” CEO Alan Waxman said. BBG

Earnings

  • Hess (HES), Chevron (CVX) – Chevron’s USD 53bln acquisition of Hess faces potential disruption as rivals ExxonMobil (XOM) and CNOOC (883 HK) claim pre-emptive rights over Chevron’s stake in a crucial Guyana oil project (the largest oil discovery in a decade). Discussions are ongoing, but failure to resolve this could jeopardise the Hess takeover, Chevron said. (Newswires) HES -2.9%, CVX -0.6% in pre-market trade
  • Puma (PUM GY) – Q4 (EUR): Revenue 1.98bln (exp. 2.094bln). EBIT 94.4mln (exp. 100mln). Net 0.8mln (exp. 28mln). Adverse currencies lead to a negative impact on sales of more than EUR 400mln. Asia/Pacific sales increased by 2.8% Y/Y, supported by strong growth in Greater China and India. The rest of Asia was softer, impacted by consumer sentiment and warm weather conditions. Sales in the Americas region decreased by 2.4% Y/Y due to the devaluation of the Argentine peso. 2024 EBIT guidance 620-700mln (exp. 663mln). “Going into 2024, we see that the market environment remains challenging.” (Puma) +0.5% in European trade
  • Lowe’s Companies Inc (LOW) Q4 2023 (USD): Adj. EPS 2.28 (exp. 1.68), Revenue 18.602bln (exp. 18.45bln) choppy pre-market
  • EU antitrust regulator says it will analyse Microsoft’s (MSFT) AI partnership with Mistral AI.

A more detailed look at global markets courtesy of Newsquawk

APAC stocks traded mixed after the lacklustre handover from the US as markets braced for looming risk events. ASX 200 was choppy as strength in the consumer sector was partially offset by weakness in miners. Nikkei 225 printed fresh record highs before reversing the advances as participants digested the latest CPI data. Hang Seng and Shanghai Comp. were mixed with the mainland mildly positive after the PBoC injected liquidity and with China said to consider approving additional REITs to support consumption.

Top Asian News

  • US intends to increase defence industrial cooperation with Japan, India, and other partners in the Indo-Pacific to build supply chain resilience in the face of threats like China, according to a Pentagon official cited by Nikkei.
  • China’s Commerce Minister Wang met with USTR Tai at the WTO conference in Abu Dhabi and expressed Beijing’s “solemn concerns” over US tariffs and Taiwan-related issues, according to SCMP.
  • China’s Commerce Minister Wang said China is highly concerned about the trade remedy investigation initiated by the European side on China’s EVs and other products, while he expressed strong dissatisfaction with this investigation that lacks factual basis.
  • China’s Commerce Minister Wang said China hopes Australia will pay attention to and actively promote the resolution of specific problems encountered by Chinese enterprises in Australia, as well as actively support China’s accession to CPTPP.
  • ABC News reported that it understands China is on track to lift tariffs on Australian wine at the end of next month when a review into the wine duties concludes.
  • Standard Chartered (2888 HK) suspended new subscriptions by clients in China under the QDII outbound investment programme citing “commercial reasons”, according to Reuters.
  • PBoC held a working meeting on Feb 26th; says they are to use all monetary tools in full and use them well.
  • China says it will prevent fluctuations in the housing market, according to CCTV; says localities should promote balance between supply and demand in the real estate market. All cities should accurately study and judge housing demand and improve housing supply, cities should take into account local economic and social development alongside population changes.

European bourses are modestly firmer having picked up a touch in limited newsflow after an uneventful open, Euro Stoxx 50 +0.3%. Breadth overall fairly narrow, though the likes of the DAX 40 +0.4% have begun to extend modestly higher. Sectors mixed with no clear theme or bias though Basic Resource names outperform while Morgan Stanley lifted Semiconductors to Overweight (prev. Neutral). Auto names, in Germany in particular, are modestly firmer after Monday’s pressure. Stateside, futures remain near the unchanged mark but with a slight positive bias, ES +0.1%, in-fitting with initial action in European trade but yet to experience the modest uptick seen since in European peers. Newsflow thus far limited, updates around MSFT, HES, CVX among others.

Top European News

  • UK Chancellor Hunt is considering plans to lower national insurance instead of income tax and could also announce a duty on vapes, according to reporting by The Telegraph.

FX

  • The DXY fell below Monday’s 103.71 trough to a 103.60 base amid JPY pressure post-Japanese CPI. However, USD/JPY failed to test 150.00 to the downside and has since risen a touch with the USD benefitting in-turn and towards the 103.81 peak.
  • EUR holds near the 1.0850 mark in relatively tight parameters with specifics light and no follow through from German GfK.
  • Cable is unchanged and within Monday’s range, docket ahead for the UK is headlined by BoE’s Ramsden.
  • AUD outperforms as it resides near its 100-DMA and is yet to test the 200-DMA at 0.6555 and 0.6561 respectively, Kiwi ever so slightly softer vs the USD ahead of the RBNZ.
  • PBoC set USD/CNY mid-point at 7.1057 vs exp. 7.1945 (prev. 7.1080).
  • Chinese regulators are reportedly taking measures to keep the renminbi exchange rate stable as Beijing aims to bolster confidence in China’s economy and currency ahead of the “Two Sessions” gathering set to begin March 4th, while measures include refraining from short-term interest rate cuts and keeping the CNY currency band against the dollar firm, according to FT.

Fixed Income

  • Session’s focus has been supply. Little reaction to outings from the Netherlands, UK & Germany thus far though the overall hefty docket in addition to syndication details/announcements from Slovakia, France, Italy (Valore) & UK has kept EGBs near the unchanged mark.
  • Bunds held a tick above Monday’s Monday’s 132.33 base and by extension remain above Friday’s 132.05 low; BTPs similarly contained but we await further 7yr Valore (Retail) updates after Monday’s first day of subscription saw a record EUR 6.4bln of demand.
  • Gilts not ‘stuck; to unchanged levels in the same way as BTPs as its own supply was via a I/L; most recently, no reaction to the DMO announcing it will be launching a new 30yr syndication from 11th March (week after the March budget).
  • USTs a touch firmer but someway shy of Monday’s 110-04 peak after lacklustre 2yr & 5yr sales, 7yr due later. Yields currently under modest pressure with no overt flattening/steepening bias.

Commodities

  • Crude is near unchanged but holding on to most of the prior day’s gains amid the recent Dollar softness and ongoing geopolitics, no reaction to the most recent updates which poured some cold water on Biden’s relative optimism overnight.
  • Nat gas under pressure but within familiar ranges for Dutch TTF while its US peer is essentially flat intraday.
  • Precious metals benefit from the softer USD and yield environment, but slipped from best as the DXY lifted from its low; base peers post modest gains with potential tailwinds from reports out of China around measures to support consumption.
  • Russia is to ban gasoline exports for six months with the ban to be introduced from March 1st, according to Tass.

Geopolitics: Middle East

  • Hamas received a draft Paris proposal which allows for a 40-day initial halt in all military operations and for the gradual return of displaced civilians to North Gaza, except men of military age, while it proposes all Israeli women, children under 19, elderly, and sick hostages would be released in exchange for a number of Palestinian prisoners. Furthermore, Palestinian prisoners would be exchanged for the release of Israeli hostages at a ratio of 10 to 1, according to a senior source cited by Reuters.
  • US President Biden said he hopes a ceasefire agreement between Israel and Hamas can take effect by next Monday and national security advisers told him negotiators are “close”, according to AP.
  • US President Biden said Israel has agreed not to engage in “activities” during Ramadan and has committed to enable an evacuation of significant portions of Rafah “before they go and take out remainder of Hamas”, according to NBC interview
  • US Central Command said it destroyed three unmanned surface vessels, two mobile anti-ship cruise missiles, and a one-way attack unmanned aerial vehicle in self-defence, according to Reuters.
  • Hamas official says there are still “big gaps” that need to be bridged before a ceasefire. Thereafter, Israeli political sources report that they do not know what the basis of US President Biden’s optimism regarding the imminent ceasefire is, via AJA Breaking and there is no breakthrough to announce on Gaza ceasefire, according to Qatar’s Foreign Minister; remain upbeat and optimistic on mediation talks; no agreement between Israel and Hamas on any of the main issues linked to a ceasefire.

Geopolitics: Other

  • Czech PM Fiala said about 15 countries have shown interest in the Ukraine ammunition initiative and Dutch PM Rutte noted that several other countries will also contribute to the Czech-proposed ammunition initiative, according to Reuters.
  • French President Macron said they think a Russian defeat is indispensable for Europe’s security and they will be exploring ways to mobilise third countries to buy ammunition, while he added they will join the ammunition initiative. Macron also said European countries will increase sanctions on countries helping Russia to bypass European sanctions and noted that he didn’t say France was not in favour of sending troops to Ukraine, while he stands by strategic ambiguity on the issue of sending troops to Ukraine and cannot rule it out.
  • Russia’s Kremlin, on French President Macron not ruling out sending European troops to Ukraine, says sending NATO member contingent to Ukraine is a very important new element; if this happens, talks would have to shift to the inevitability of conflict with NATO.
  • Russian Security Council Secretary Patrushev met with Cuba’s Raul Castro to discuss security cooperation, according to Ifax.

US Event Calendar

  • 08:30: Jan. Durable Goods Orders, est. -5.0%, prior 0%
    • Jan. Durables-Less Transportation, est. 0.2%, prior 0.5%
    • Jan. Cap Goods Ship Nondef Ex Air, est. 0.1%, prior 0%
    • Jan. Cap Goods Orders Nondef Ex Air, est. 0.1%, prior 0.2%
  • 09:00: Dec. S&P/Case-Shiller US HPI YoY, prior 5.14%
    • Dec. S&P/CS 20 City MoM SA, est. 0.20%, prior 0.15%
    • Dec. S&P CS Composite-20 YoY, est. 6.00%, prior 5.40%
    • Dec. FHFA House Price Index MoM, est. 0.3%, prior 0.3%
    • 4Q House Price Purchase Index QoQ, prior 2.1%
  • 10:00: Feb. Conf. Board Consumer Confidenc, est. 115.0, prior 114.8
    • Feb. Conf. Board Expectations, prior 83.8
    • Feb. Conf. Board Present Situation, prior 161.3
  • 10:00: Feb. Richmond Fed Index, est. -9, prior -15
  • 10:30: Feb. Dallas Fed Services Activity, prior -9.3

Central Bank speakers

  • 09:05: Fed’s Barr Speaks on Counterparty Credit Risk

DB’s Jim Reid concludes the overnight wrap

Its been a pretty quiet start to the week in equities but with the S&P 500 (-0.38%) seeing a late minor sell-off and with Chinese equities rising this morning on speculation that the authorities bought a notable amount of domestic shares in recent weeks. Yields rising across the board has been the main source of interest though. In the process the amount of cuts priced in by the Fed’s December meeting is now the lowest since mid-November, at 79bps, around half the amount expected at the start of the year. Meanwhile, yields on 2yr Treasuries (+2.8bps) closed at 4.72%, their highest level since the Fed’s December meeting, and overnight 2yr Japanese yields have edged up to their highest since 2011 after Japanese inflation beat expectations.

It was a similar story earlier in Europe yesterday with yields then rising steadily all day, even before ECB President Lagarde comments to the European Parliament just before the European equity close. These remarks showed ongoing patience, suggesting that the ECB “needs to be confident that [the current disinflationary process] will lead us sustainably to our 2% target”. Overall her comments were not that different to the last ECB statement and the yield rise was mostly done for the day before she spoke.

By the close 10yr bunds (+7.7bps), OATs (+8.3bps) and BTPs (+9.1bps) all posted significant yield increases, effectively reversing Friday’s rally (-7.8bps for 10yr bunds). And at the front end of the curve, the 2yr German yield (+6.9bps) closed at 2.92%, its highest level since November. The likelihood of an ECB cut by the April meeting was down 6pp to 27%, which is the lowest since late September.

Over in the US, the 10yr yield ended the day up +3.1bps at 4.28%, whilst the 2yr yield ended the day up +2.8bps at 4.72%, its highest level so far this year. Bonds reversed some of their decline late in the session, perhaps as equities dipped, with the 10yr yield having been more than 5bps higher on the day shortly after 2yr and 5yr Treasury auctions, which saw decent investor demand but with bonds being issued a touch above the pre-sale yields.

The day’s yield rises occurred alongside some decent second-order data releases, with the UK CBI’s retail sales volume survey at a 10-month high of -7 (vs. -31 expected and up from a 3-year low of -50 in January). Later the Dallas Fed’s manufacturing index was up to -11.3 in February (vs. -15.0 exp.). US new home sales came in at an annualised pace of 661k in January, below the 684k expected but their highest level in three months as December was revised down from 664k to 651k.

It’s an interesting week for equities as the recent run is starting to get into once in a couple of generation territory. The S&P 500 has now posted 15 weekly gains in the last 17 for the first time since 1989. Moreover, if we get another positive week this week, then it would be 16 out of 18 weeks for the first time since 1971, and it would also be a joint record since the index’s formation. So even though there’s been lots of positive catalysts, from lower inflation to excitement about AI, it’s actually very unusual to see the sort of sustained rally that’s occurred over the last few months. For more info, Henry put out some charts on the current rally in his Mapping Markets publication yesterday (link here).

As we started a new week equities struggled to maintain their spectacular recent momentum, with the S&P 500 -0.38% lower on Monday. The NASDAQ declined a marginal -0.13%, while the Magnificent 7 were down -0.39%, dragged lower by a -4.44% decline for Alphabet amid concerns over recent missteps with its AI model. Small-cap stocks were the strongest performers, with the Russell 2000 up +0.61%. Over in Europe the picture was more negative though, with the STOXX 600 down -0.37% as it fell back from its all-time high on Friday. Even so, it wasn’t all bad news there, as the DAX (+0.02%) eked out a new record, and Euro HY spreads reaching their tightest level in over two years.

In Asia the KOSPI (-0.42%), Hang Seng (-0.36%) and Nikkei (-0.12%) are all slightly lower. Elsewhere, Chinese stocks are bucking the trend with the CSI (+0.35%) and the Shanghai Composite (+0.51%) higher after reports on Bloomberg of state buying in recent weeks. US stock futures are slightly lower as I type.

Coming back to Japan, inflation slowed less than expected in January, rising +2.2% y/y (vs. +1.9% expected) even if down from the previous month’s +2.6%. The +2.0% increase in core consumer prices was slower than the 2.3% increase in December and a tenth above expectations. Core-core was two-tenths above expectations at 3.5% from 3.7% last month. As mentioned at the top, yields on 2yr JGBs Japanese (+1.0bps) have hit their highest level since 2011, trading at 0.165% as we go to print. As a result, The likelihood of BOJ exiting its negative rate policy by April has risen to about 81%, up from yesterday’s 78%.

To the day ahead now, and US data releases include the Conference Board’s consumer confidence for February, the Richmond Fed’s manufacturing index for February, preliminary durable goods orders for January, and the FHFA house price index for December. Meanwhile in the Euro Area, there’s the M3 money supply for January. From central banks, we’ll hear from Fed Vice Chair for Supervision Barr, the ECB’s Elderson, and BoE Deputy Governor Ramsden. Lastly in US politics, there are Republican and Democratic primaries taking place in Michigan.


Tyler Durden
Tue, 02/27/2024 – 08:19

This Is Nuts – An Entire Market Chasing One Stock

0
This Is Nuts – An Entire Market Chasing One Stock

Authored by Lance Roberts via RealInvestmentAdvice.com,

“When you sit down with your portfolio management team, and the first comment made is ‘this is nuts,’ it’s probably time to think about your overall portfolio risk. On Friday, that was how the investment committee both started and ended – ‘this is nuts.’”

 – January 11th, 2020.

revisited that original post a couple of weeks ago as the market approached its 5000 psychological milestone. Since then, the entire market has surged higher following last week’s earnings report from Nvidia (NVDA). The reason I say “this is nuts” is the assumption that all companies were going to grow earnings and revenue at Nvidia’s rate.

Even one of the “always bullish” media outlets took notice, which is notable.

“In a normal functioning market, Nvidia doing amazingly is bad news for competitors such as AMD and Intel. Nvidia is selling more of its chips, meaning fewer sales opportunities for rivals. Shouldn’t their stocks drop? Just because Meta owns and uses some new Nvidia chips, how is that going to positively impact its earnings and cash flow over the next four quarters? Will it at all?

‌The point is that investors are acting irrationally as Nvidia serves up eye-popping financial figures and the hype machine descends on social media. It makes sense until it doesn’t, and that is classic bubble action.” – Yahoo Finance

As Brian Sozzi notes in his article, we may be at the “this is nuts” stage of market exuberance. Such usually coincides with Wall Street analysts stretching to “justify” why paying premiums for companies is “worth it.”

We Can’t All Be Winners

Of course, that is the quintessential underpinning for a market that has reached the “this is nuts” stage. There is little doubt about Nvidia’s earnings and revenue growth rates. However, to maintain that growth pace indefinitely, particularly at 32x price-to-sales, means others like AMD and Intel must lose market share.

However, as shown, numerous companies in the S&P 1500 alone are trading well above 10x price-to-sales. (If you don’t understand why 10x price-to-sales is essential, read this.) Many companies having nothing to do with Nvidia or artificial intelligence, like Wingstop, trade at almost 22x price-to-sales.

Again, if you don’t understand why “this is nuts,” read the linked article above.

However, in the short term, this doesn’t mean the market can’t keep increasing those premiums even further. As Brian concluded in his article:

“Nothing says ‘investing bubble’ like unbridled confidence. It’s that feeling that whatever stock you buy — at whatever price and at whatever time — will only go up forever. This makes you feel like an investing genius and inclined to take on more risk.”

Looking at some current internals tells us that Brian may be correct.

This Is Nuts” Type Of Exuberance

In momentum-driven markets, exuberance and greed can take speculative actions to increasingly further extremes. As markets continue to ratchet new all-time highs, the media drives additional hype by producing commentary like the following.

“Going back to 1954, markets are always higher one year later – the only exception was 2007.”

That is a correct statement. When markets hit all-time highs, they are usually higher 12 months later due to the underlying momentum of the market. But therein lies the rub: what happened next? The table below from Warren Pies tells the tale.

As shown, markets were higher 12 months after new highs were made. However, a lot of money was lost during the next bear market or correction. Except for only four periods, those bear markets occurred within the next 24 to 48 months. Most gains from the previous highs were lost in the subsequent downturn.

Unsurprisingly, investing in the market is not a “risk-free” adventure. While there are many opportunities to make money, there is also a history of wealth devastation. Therefore, understanding the environment you are investing in can help avoid potential capital destruction.

From a technical perspective, markets are exceedingly overbought as investors have rushed back into equities following the correction in 2022. The composite index below comprises nine indicators measured using weekly data. That index is now at levels that have denoted short-term market peaks.

Unsurprisingly, speculative money is chasing the Mega-cap growth and technology stocks. The volume of call options on those stocks is at levels that have previously preceded more significant corrections.

Another way to view the current momentum-driven advance in the market is by measuring the divergence between short and long-term moving averages. Given that moving averages smooth price changes over given periods, the divergences should not deviate significantly from each other over more extended periods. However, as shown below, that changed dramatically following the stimulus-fueled surge in the markets post-pandemic. Currently, the deviation between the weekly moving averages is at levels only previously seen when the Government sent checks to households, overnight lending rates were zero, and the Fed bought $120 billion monthly in bonds. Yet, none of that is happening currently.

Unsurprisingly, with the surge in market prices, investor confidence has surged along with their allocation to equities. The most recent Schwab Survey of bullish sentiment suggests the same.

More than half of traders have a bullish outlook for the first quarter – the highest level of bullishness since 2021

Yes, quite simply, “This is nuts.”

Market Measures Advise Caution

In the short term, over the next 12 months, the market will indeed likely finish the year higher than where it started. That is what the majority of analysis tells us. However, that doesn’t mean that stocks can’t, and won’t, suffer a rather significant correction along the way. The chart below shows retail and professional traders’ 13-week average of net bullish sentiment. You will notice that high sentiment readings often precede market corrections while eventually rising to higher levels.

For example, the last time bullish sentiment was this extreme was in late 2021. Even though the market eventually rallied to all-time highs, it was 2-years before investors got back to even.

Furthermore, the compression of volatility remains a critical near-term concern. While low levels of volatility have become increasingly common since the financial crisis due to the suppression of interest rates and a flood of liquidity, the lack of volatility provides the “fuel” for a market correction.

Combining excessive bullish sentiment and low volatility into a single indicator shows that previous levels were warnings to more bullish investors. Interestingly, Fed rate cuts cause excess sentiment to unwind. This is because rate cuts have historically coincided with financial events and recessions.

While none of this should be surprising, given the current market momentum and bullish psychology, the over-confidence of investors in their decision-making has always had less than desirable outcomes.

No. The markets likely will not crash tomorrow or in the next few months. However, sentiment has reached the “this is nuts” stage. For us, as portfolio managers, such has always been an excellent time to start laying the groundwork to protect our gains.

Lean on your investing experience and all its wrinkles.” – Brian Sozzi

Tyler Durden
Tue, 02/27/2024 – 08:11