68.1 F
Chicago
Thursday, September 17, 2026
Home Blog Page 3002

Hush Money: JP Morgan Pays $18 Million Fine For Violating Whistleblower Protection Rules

0
Hush Money: JP Morgan Pays $18 Million Fine For Violating Whistleblower Protection Rules

While Elizabeth Warren continues to espouse the anti-crypto movement, citing corruption and money laundering, her pal in loathing bitcoin, Jamie Dimon at JP Morgan, has started off a new week with yet another settlement with the government for regulatory infractions. 

Without admitting or denying charges by the U.S. Securities and Exchange Commission, the bank paid an $18 million fine this week for violating whistleblower protection rules with its confidentiality agreements over the course of a 3 year period, according to Morningstar and MarketWatch.

An SEC press release stated: “According to the SEC’s order, from March 2020 through July 2023, JPMS regularly asked retail clients to sign confidential release agreements if they had been issued a credit or settlement from the firm of more than $1,000.”

It continued:

“The agreements required the clients to keep confidential the settlement, all underlying facts relating to the settlement, and all information relating to the account at issue. In addition, even though the agreements permitted clients to respond to SEC inquiries, they did not permit clients to voluntarily contact the SEC.”

The mob had a name for that, didn’t they…”hush money”?

Gurbir S. Grewal, Director of the SEC’s Division of Enforcement commented: “Whether it’s in your employment contracts, settlement agreements or elsewhere, you simply cannot include provisions that prevent individuals from contacting the SEC with evidence of wrongdoing.”

Grewal continued: “But that’s exactly what we allege J.P. Morgan did here. For several years, it forced certain clients into the untenable position of choosing between receiving settlements or credits from the firm and reporting potential securities law violations to the SEC. This either-or proposition not only undermined critical investor protections and placed investors at risk, but was also illegal.”

Corey Schuster, Co-Chief of the Enforcement Division’s Asset Management Unit added: “Investors, whether retail or otherwise, must be free to report complaints to the SEC without any interference.”

The news comes days after the bank closed out the most profitable year in US banking history with its seventh consecutive quarter of record net interest income and a surprise forecast that the good times may continue in 2024.

Bloomberg’s Max Abelson said at the time that the too big to fail bank had gotten even bigger: “…this bank’s standardized risk-weighted assets hit $1.7 trillion, its cash and marketable securities are $1.4 trillion, and average loans are near there at $1.3 trillion. The biggest gets bigger.

Tyler Durden
Tue, 01/16/2024 – 14:00

Over 100 Ships Transit Red Sea Route Despite Calls To Stay Away

0
Over 100 Ships Transit Red Sea Route Despite Calls To Stay Away

By Tsvetana Paraskova of OilPrice.com

The number of commercial vessels that have transited the Red Sea/Suez Canal route has more than halved over the past month amid rising tensions off Yemen, but more than 100 ships, including oil tankers, have crossed the water lane since the U.S. and UK navies advised operators on Friday to steer clear of the route.

Amid escalating tensions in the Middle East and the U.S. and UK strikes on Houthi targets in Yemen on Thursday night last week, the largest shipping and tanker industry groups advised on Friday members to stay away from the Bab el-Mandeb Strait while shippers were diverting transit away from the Red Sea en masse again.

In an advisory to its members, the International Association of Independent Tanker Owners (Intertanko), representing nearly 70% of all international oil, chemical, and gas tankers, said that tankers should “stay well away” from Bab el-Mandeb and pause north of Yemen when traveling south through the Suez Canal route.

Many have heeded the advice, but some have not.

A total of 114 commercial vessels — including oil tankers, bulk carriers, and container ships — have continued with their routes and transited into or out of the Red Sea through the Bab el-Mandeb Strait, according to vessel-tracking data monitored by Bloomberg.

That’s down from 131 ships crossing the chokepoint during the same days of the previous week, and more than half from the 272 vessels that used the route one month ago, according to the data compiled by Bloomberg.

Since Friday, tensions in the area ratcheted up further, after an anti-ship cruise missile was fired on Sunday from Iranian-backed Houthi militant areas of Yemen toward USS Laboon, which was operating in the Southern Red Sea. The missile was shot down in vicinity of the coast of Hudaydah by U.S. fighter aircraft, and there were no injuries or damage reported, the U.S. Central Command said.

On Monday, the Houthis fired a missile and struck a U.S.-owned merchant vessel—the Gibraltar Eagle, a Marshall Islands-flagged, U.S.-owned and operated container ship. The ship has reported no injuries or significant damage and is continuing its journey, the U.S. Central Command said.

Tyler Durden
Tue, 01/16/2024 – 13:40

Zelensky Courts JPMorgan, Bank of America & Bridgewater CEOs At Davos, Urges More Money From West

0
Zelensky Courts JPMorgan, Bank of America & Bridgewater CEOs At Davos, Urges More Money From West

As expected, anything related to Ukraine presented at the World Economic Forum (WEF) in Davos has been focused on more weaponry and seeking more vows of integration among Western allies. 

“Ukrainians need predictable financing throughout 2024 and beyond,” European Commission president Ursula von der Leyen told World Economic Forum participants. “They need a sufficient and sustained supply of weapons to defend Ukraine and regain its rightful territory.”

As for President Zelensky, in addressing world leaders at the forum he emphasized that the West needs to help Ukraine achieve air superiority if his forces are to have a chance to emerge victorious against Russia.

Via NATO

We must gain air superiority for Ukraine. Just as we gained superiority in the Black Sea, we can do it. This will allow progress on the ground … Partners know what is needed and in what quantity,” the Ukrainian leader said.

“After 2014, there were attempts to freeze the war in Donbas. There were very influential guarantors, the chancellor of Germany, the president of France. But Putin is a predator who is not satisfied with frozen products,” Zelensky continued in his address at Davos.

At the summit, US Secretary of State Antony Blinken promised that Washington will keep up its support for Ukraine, however while keeping things vague – following Biden’s proposed foreign defense budget request being reject by GOP members in Congress; and NATO chief Jens Stoltenberg suggested Ukraine is moving closer to entry into the alliance.

Stoltenberg acknowledged a “serious battlefield situation” but also said there is “cause for optimism” after nearly two years of fighting, and NATO’s constant support.

Below is a portion of the NATO press readout based on his panel speech

Conversely, he said that “Russia has lost what they wanted to achieve with the war, and that was to control Ukraine”; Ukrainians are now firmly oriented to the West, aspiring for membership in NATO and the European Union. The Secretary General also stressed that “support for Ukraine is not charity; it’s an investment in our own security”.

Pointing to the increasingly global nature of security, Mr Stoltenberg noted that close NATO partners Japan and South Korea are also concerned about Russia’s war against Ukraine, as a victory for President Putin would increase the likelihood of Beijing using force elsewhere

But realistically, the prospect of Ukraine gaining full NATO membership would be a process of years, and would likely trigger WW3 with Russia–so to some degree this is all empty posturing.

Via Fox Business

But here’s what’s happening at Davos which is arguably more important to Kiev at the moment:

Ukraine is seeking new ways to finance its rebuilding plans as vital aid from the West slows down. President Volodymyr Zelenskyy reportedly has plans to meet JP Morgan’s CEO at the World Economic Forum.

Ukraine’s President Zelenskyy is reportedly planning to meet JPMorgan CEO Jamie Dimon at the World Economic Forum in Davos to seek new ways of financing its rebuilding plans

JP Morgan, the biggest US bank with almost half a trillion dollars of market capitalization, has already been advising Ukraine on financing reconstruction.

It’s as yet unclear if any firm promises were made or agreements struck at the Davos meeting which also included Bank of America’s Brian Moynihan, as well as Bridgewater’s Ray Dalio

According to further details of who was in attendance via Fox Business: “Other meeting attendees included David Rubinstein of the private equity firm Carlyle Group; billionaire entrepreneur Michael Dell, the founder of Dell Technologies; Ray Dalio of Bridgewater Associates, the world’s largest hedge fund; Steve Schwarzman, the CEO of Blackstone, the world’s largest private equity fund; and Philipp Hildebrand, representing BlackRock, the world’s largest money manager.”

Additionally, “Dimon was accompanied by Mary Erdoes, who runs JPMorgan’s asset-management unit. The White House was represented by Penny Pritzker, of the super-wealthy Pritzker family and a major Democratic Party donor.” Pritzker has been appointed Biden administration’s special representative for Ukraine’s economic recovery.

See more below…

Tyler Durden
Tue, 01/16/2024 – 12:40

China Premier Claims Economy Grew At “Estimated” 5.2% In 2023, Ironically Mentions “Trust Deficit”

0
China Premier Claims Economy Grew At “Estimated” 5.2% In 2023, Ironically Mentions “Trust Deficit”

It’s another Christmas miracle…

During a speech in Davos, Chinese Premier Li Qiang ‘leaked’ that China’s economy grew an “estimated” 5.2% last year, beating the official target of 5% (its lowest in decades).

We say ‘leaked’ because this data was supposed to be officially released tonight, prompting anger and disillusionment from some:

“China used to be a place where you’d know when this sort of thing would be published, but that has changed radically,” said Alicia García-Herrero, chief Asia-Pacific economist at Natixis, who described the decision to announce the figure early as “bewildering”.

A bigger problem for liquidity-hypers was that Li explicitly pointed out that China’s growth rate last year – a rise from the figure of 3% in 2022 when the country was hit by its arcane Zero-COVID policies – was achieved without resorting to “massive stimulus” and the economy was making “steady progress”.

“We did not seek short-term growth while accumulating long-term risks, rather we focused on strengthening the internal drivers,” he said.

“Just as a healthy person often has a strong immune system, the Chinese economy can handle ups and downs in its performance. The overall trend of long-term growth will not change.”

Ironically, Bloomberg reported this morning that China is considering 1 trillion yuan ($139 billion) of new debt issuance under a so-called special sovereign bond plan, only the fourth such sale in the past 26 years, as authorities seek more money to finance intensifying efforts to shore up the world’s second-largest economy.

But that news is old and regurgitated…

And given Li’s comments, this is not something traders should expect to be systemic liquidity provision from Beijing.

Li also urged greater co-ordination between countries on macroeconomic policies, a reference to efforts by the US and its allies to reduce the reliance of their supply chains on China.

Do you believe in miracles?

The Chinese equity market doesn’t…

And Chinese macro-economic data certainly hasn’t been supportive of this expectation…

Given the ‘surprise’ economic growth, we couldn’t help but giggle at the irony of Li’s shot across the US bow with regard “trust deficits.”

‘Trust’ in data, politicians, and the rule of law appear in short-supply across the globe.

Tyler Durden
Tue, 01/16/2024 – 12:00

Bond Traders Push Powell Toward Yellen-Era Offensive

0
Bond Traders Push Powell Toward Yellen-Era Offensive

By Garfield Reynolds, Bloomberg Markets Live reporter and strategist

Bonds are cruising toward a likely bruising by pricing in an almost immediate Federal Reserve pivot to rapid, deep interest-rate cuts. The risk is that they will prompt the central bank to push back hard enough to set off fresh cross-asset turmoil.

Markets see about an 80% chance the Fed will trim its benchmark in March. While inflation has slowed substantially and jobs growth has cooled, it’s hard to see the justification for such one-sided bets. Indeed, the latest consumer-price and payroll numbers surprised modestly to the upside, suggesting the Fed is still likely to be far from convinced its policy of returning inflation to target has been a success.

The confidence in a March cut is also puzzling given the short runway. There are just two more sets of reports before that month’s meeting, considering payrolls and the two most relevant inflation readings: the Bureau of Labor Statistics figures, and the PCE deflator the Fed targets.

The Fed may well seek to address this dislocation by means of an “intervention” much as it did back in early 2017. That was when then Chair Janet Yellen led a concerted campaign from officials to say future meetings were “live.” Traders responded by rapidly boosting odds of a rate hike to 90% from less than 30%.

Fed Chicago President Austan Goolsbee took a step in that direction at the end of last week by saying the market had gotten ahead of itself. There’s also potential for further pushback from speeches this week. Policymakers have consistently insisted that rate cuts are a long way off, even after acknowledging in December that they are unlikely to deliver any more hikes.

If a cut in March currently seems a stretch, the 6 1/2 reductions priced in by year-end appear even more outlandish. That sort of trajectory would require a full-blown recession, which flies in the face of recent data pointing to resilience in the economy. Financial conditions are also as loose as they’ve been in more than a year, highlighting the risk that early rate cuts would revive inflation.

The disconnect between the market and the Fed may owe much to the heady impact on investors of bonds that once more have decent yields. With traders certain they have the direction of Fed policy right, higher coupon payments relative to recent history seem to offer a large enough buffer to ride out any fresh bursts of central-bank hawkishness.

That enthusiasm could easily evaporate, especially if there are fresh fears about rising US bond supply. Most governments are forecast to boost bond issuance this year, even as the majority of central banks will either be running down their balance sheets or moving toward that process.

At the same time, markets remain vulnerable to Fed surprises, especially as many companies need to refinance borrowings that were taken out in the era of record-low interest rates. The weight of expectations for a rapid shift to lower rates means equities are exposed to any uptick in discount rates, with forward P/E ratios sitting well above pre-pandemic norms.

Bonds may show more resilience to a stubbornly hawkish Fed than equities are likely to do given the way investor demand has increased whenever whenever yields have risen. But both asset classes remain vulnerable until the divergence between market pricing and the Fed is resolved.

Tyler Durden
Tue, 01/16/2024 – 11:40

Stocks & Bonds Tumble After Fed’s Waller Sends Rate-Cut Odds Reeling

0
Stocks & Bonds Tumble After Fed’s Waller Sends Rate-Cut Odds Reeling

At first glance, Fed Governor Chris Waller’s comments were more of the same – data-dependent, mini-mission-accomplished, be careful of easing financial conditions, and the market seems over-enthusiastic about 2024 policy.

But it was the level of detail he added that colored the market’s perceptions hawkish (full speech here).

Data-Dependent…

“I am becoming more confident that we are within striking distance of achieving a sustainable level of 2% PCE inflation,” Waller said in prepared remarks at a virtual event hosted by the Brookings Institution on Tuesday.

“As long as inflation doesn’t rebound and stay elevated, I believe the FOMC will be able to lower the target range for the federal funds rate this year.”

But, Waller reiterated his support for three cuts… not six like the market wants…

“This view is consistent with the FOMC’s economic projections in December, in which the median projection was three 25-basis-point cuts in 2024“.

And certainly does not see the need for aggressive cuts priced into the market:

“When the time is right to begin lowering rates, I believe it can and should be lowered methodically and carefully,” he said.

“With economic activity and labor markets in good shape and inflation coming down gradually to 2%, I see no reason to move as quickly or cut as rapidly as in the past.

He reiterated that the timing of cuts and the actual number “will depend on the incoming data”, specifically calling out the surprising strength in the December jobs report as “largely noise” against a trend of ongoing moderation. He noted a number of 2023 job reports have been revised lower, and “there is a good chance December will be revised down.”

Finally, Waller made it clear The Fed is in no hurry to act:

“I believe policy is set properly,” he said.  

“It is restrictive and should continue to put downward pressure on demand to allow us to continue to see moderate inflation readings.”

All of which sent March rate-cut odds reeling…

And 2024 rate-cut expectations fell, after last week’s CPI and PPI driven increases…

Sparked equity market selling…

And bond yields spiked, extending the earlier move…

It appears the message from Fed Speakers is getting through to the market slowly – don’t expect more than six cuts this year and don’t count on a March cut…

Tyler Durden
Tue, 01/16/2024 – 11:24

Weebles Wobble

0
Weebles Wobble

By Peter Tchir of Academy Securities

Weebles Wobble

While not quite as catchy as the 1-877-KARS-4-KIDS jingle, I cannot get the “Weebles wobble but they don’t fall down” marketing slogan out of my head. It seems somewhat applicable to markets, of late.

Stocks, in particular, got off to a weak start, but rebounded strongly this week. Now the Dow, the S&P 500, and Nasdaq are basically unchanged on the year (the Russell 2000 and Chinese stocks are still down around 4%).

So, we “wobbled” but didn’t fall down. Not just on the year, but also there were a few times (like early on the 9th and the 11th) that stocks struggled out of the gate, only to rebound during the course of the day.

The bounce in some market leaders helped, as did some earnings, but two things seemed to drive the performance this week:

  • Hope and faith in the Fed taking action that might propel stocks higher.

  • Talking about, but largely ignoring, Geopolitical Risks.

Can “We” Hedge for Geopolitical Risk?

Without a doubt Geopolitical Risk is high and is a major topic of discussion:

  • Academy’s 2024 Geopolitical Outlook Webinar is a case in point. Rachel Washburn led a fascinating discussion with Generals (ret.) Ashley and Robeson and me. We covered some of the existing “hot button” issues but got to touch on other areas like Turkey and Venezuela that have been a little off the radar.

  • The pace of SITREPs (and the need for them) has (unfortunately) ratcheted up this year. Thursday’s analysis of U.S. Strikes on Houthi Targets in Yemen is just the latest piece.

  • Last weekend’s An Eclectic Mix includes some Geopolitical risks (and several others worth considering), but The Times Are A-Changin’ is the focal point of the market risks posed by geopolitical threats and risks.

Brent crude, the most “obvious” one to be affected by the Middle East, is at $78, roughly where it averaged during the first few months of 2023! I think that there are many reasons for this. The fact that the global economy was showing signs of weakness even before the invasion hasn’t helped oil prices. In addition, China not managing to jumpstart its economy is weighing on oil prices. Efforts to work with Venezuela to improve their production also seem to be a major risk. Finally, last year, so many investors betting on higher oil prices (only to see them struggle) has muted the enthusiasm of speculators.

Lots of other factors outweighed the geopolitical risk in the Middle East.

But does that mean we should ignore it? Or maybe we aren’t ignoring it, and the other factors legitimately outweigh the geopolitical risk, making it appear as though geopolitical risk is being ignored, while it is in fact being priced in.

If everyone is talking about geopolitical risk, but not doing anything about it, there are some really interesting opportunities out there. If, on the other hand, people are treating it with the respect it deserves, then it will require a “surprise” of some sort to really shake things up.

I suspect that the truth is somewhere in between.

While investors and corporations are well aware of geopolitical risks, they seem so binary, are so difficult to time, and haven’t always played out as expected, that relatively few decisions are being made around geopolitical risk.

It is the nebulous, binary, and erratic nature of Geopolitical risk that makes it difficult to quantify and act on in advance.

My working premise is that some, but only a small portion, of the geopolitical risk out there is getting priced in.

As a result, I continue to like commodities and commodity producers. While I am not upbeat on the domestic economy (or even the global economy), we could yet see stimulus out of China (inflationary) or more severe geopolitical disruptions (likely inflationary, if not stagflationary). My number one choice on that front is that something happens where the U.S. cannot be seen to allow Iranian oil shipments above any official sanction levels (which seems be occurring right now).
Academy is well prepared to continue to help our clients navigate through the evolving geopolitical landscape, but I’m trying to think of ways to make it even more strategic and less reactionary.

On that point, the geopolitical risk that is the most important, and has been the most important for years, is with respect to our “Strategic Competition” with China. Getting that right will be what determines winners and losers over the next few years and decades. It seems like we could see an easing of tensions (for economic and political reasons), but over the longer term, it is difficult to imagine a world where there is less competition. It just doesn’t seem to be in the cards, despite all those who pound the table saying that China needs us as much or more than we need them. I just don’t think that is true (if you define “need” from China’s perspective, and not from “our” perspective).

The final problem with hedging Geopolitical risks is that Treasuries may not be an effective tool for that.

We have all learned “flight to safety” as a response to geopolitical risk. Something bad in the world happens and investors flock to the dollar and to Treasuries. While we still see some evidence of that, the response function has been muted. The main reason for that is the almost “Pavlovian” response of “geopolitical risk means buy Treasuries” has been tainted by “geopolitical risk means more weapons spending, which means higher deficits (which are already high).”

That is why I am comfortable betting on higher yields, even with so much geopolitical risk. Not much higher yields (4.3% on 10s), but higher nonetheless. I cannot be fully committed to that view with so much geopolitical risk, as we could get a “flight to safety moment” but I think that would be a “knee jerk” reaction and would likely fade it, hand over fist.

In conclusion, geopolitical risk isn’t being fully hedged, but the best opportunity is likely to own some hedges via long positions in commodities or commodity producers/processors.

FOMC Policy as a Campaign Issue

We have already argued that optimism about rate cuts and the end of quantitative tightening helped spark a rally in stocks.

We can tackle all the reasons why I believe too many cuts are being priced in and the timing of the end of quantitative tightening is further away than the market currently believes. But you already know many of those reasons from prior T-Reports, and I’m sure that they will come up again and again, so let’s go with the one risk to monetary policy that almost no one seems to be talking about.

My view on the presidential election campaign is the following (it is currently predicated on the assumption that it will be Biden vs. Trump again, but I’m not sure any other match-up changes my view much):

  • It will be a divisive and aggressive campaign.

  • Social media will play a major role, which will only “enhance” the divisiveness.

  • Everything, and I mean quite literally everything, will become a black or white issue, rather than some shade of grey.

  • Almost nothing that gets promised will give anyone any comfort about the trajectory of the deficit.

I think that we can all safely agree that the Fed is apolitical in theory and seems to work very hard to maintain that political independence. The Fed wants to do what is right for the economy (based on their mandates) and use their skills and tools to accomplish that. They don’t always get it right, but they try.

I just think that everything they do will come under much greater criticism than it ever has in the past. I tried to use the word “scrutiny” rather than criticism, but I don’t think that it will be “scrutiny.” Scrutiny implies a level of thought and intellectual curiosity. I think that we will just get criticism.

The second component of my theory is that the criticism will attract much more attention than in the past. If ZIRP taught Americans anything, it was that easy money means bigger 401(k)s! While Wall Street always talked about the Fed Put, it is not part of popular culture. Everyone “knows” that rate cuts mean higher stock prices (it is debatable if that should be the case, but I don’t think it is debatable that this is a wildly popular consensus right now). So, there will be many avid readers, listeners, and “bots” ready to link Fed actions to the stock market (and maybe the economy) and therefore to the election.

If the Fed cuts and stops quantitative tightening and markets rally, the opposition will likely portray it as an effort to help the incumbents. They will warn (or rant and rave) about taking unnecessary steps that risk reigniting inflation.

If the Fed doesn’t cut and continues with quantitative tightening and markets slump (or even worse, employment data deteriorates), then the incumbents will be the ones voicing their theories that the Fed is sabotaging their re-election efforts.

The Fed will do their utmost best to stay above the fray, but I think that we are going to witness monetary policy becoming a campaign issue and I’m not sure we’ve ever seen that, or what that could do to the Fed or to the economy or to markets. Uncharted territory.

My current Fed view (as I expect a weakening, but not horrible economic data):

  • 3 cuts. 25 bps, 50 bps, and 25 bps.

  • I think that the timing will be the April/May meeting, the June meeting, and the July meeting for those cuts.

  • The September and November meetings are so close to the election, that I suspect by the time we get there, the Fed will be reluctant to do anything if it doesn’t have to (predicated on my view that FOMC policy will be making almost daily headlines on the campaign trail as we near the election).

  • So, if those meetings are unlikely to do anything, maybe the Fed does the cuts in March, April/May, and June, but the current data, along with many of their recent promises, make that seem unlikely (according to WIRP, the market is pricing in a 79% chance of a March cut, which seems a tad high, but plausible).

If I am right about this, I do not envy anyone senior at the Fed as their already difficult job will be made that much more difficult.

Bottom Line

On rates, I think that 10s should head towards 4.3%. I am nervous about a “flight to safety” trade, so while I have very high conviction on this trade, I prefer some options, rather than a fully committed outright bet. Looking for less and less inversion, and even possibly a “normal” curve between 2s and 10s as the year progresses (we’ve gapped from -37 to start the year, to -20 already).

On credit, I think that I still like credit. If there is one trade that literally everyone seems to agree with, it is that “credit spreads are too tight” or some variation of the theme “we are at the low end of the range.” Yes, we are at the low end of the range, but how likely is it that what everyone believes (and is potentially positioned for) comes true? I could see some weakness in credit markets, but am looking for an incredibly large and obvious outperformance of credit versus equities.

On stocks, bearish almost across the board, except for the commodity space as previously mentioned. We haven’t “loved” the laggards universally for some time, and all I can convince myself of in the “laggards” (which had a great run) is the commodity space.

Bitcoin got interesting with the launch of the ETFs. Expect more weakness as too many people bet too much (some using leverage) on the enthusiasm that ETFs would create for Bitcoin. For now, the unwinding of older positions in other products seems to be the overwhelming trade, triggering stop losses. Expect that to continue next week (though we could see a pop on Tuesday morning if some big allocations come into the ETFs). Only once that settles down, will we figure out what the ETFs really mean. The thing I find most ironic (or maybe it is paradoxical – which reminds me of some complaints about the Alanis Morissette song) is that Bitcoin is supposed to be “better” than money, but is it so “good” that it is much easier to own it as an ETF than outright? That will be glossed over in the marketing, and might be a bit pedantic on my part, but if Bitcoin is so great, why do so many need an ETF to own it? Yes, things like gold, high yield bonds, and foreign stocks all are much easier to own via ETF than outright, but those assets were never meant to replace money!

While Weebles wobble but don’t fall down, I think that the equity markets will fall

Tyler Durden
Tue, 01/16/2024 – 11:00

Futures Slide As Dollar Surges, 10Y Yields Rise Above 4%

0
Futures Slide As Dollar Surges, 10Y Yields Rise Above 4%

US equity futures fell for a second day as the dollar rose to a one-month high and as 10Y yield pushed back over 4.00% after various central banks pushed back against bets on aggressive interest rate cuts. As of 7:30am, S&P futures were down 0.4%, well off session lows, while Nasdaq futures lost about 0.5%. Meanwhile, Brent rose to around $79 a barrel as Houthi attacks on ships in the Red Sea keep tensions high. In other news, Iowa voters delivered Donald Trump a victory in Monday’s caucuses, moving him one step closer to a White House return. Among corporate highlights, Morgan Stanley and Goldman Sachs Group report earnings before the markets open.

In premarket trading, Boeing slumped again after Wells Fargo downgrades the planemaker to equal-weight from overweight, seeing a higher risk of production and/or delivery impacts with the US Federal Aviation Administration taking a closer look into Boeing’s operations. Elon Musk leaned on Tesla’s board to arrange another massive performance award for him after he sold a significant chunk of his stake in the company to acquire Twitter. Tesla shares slip 2.3% in US premarket trading after Elon Musk said he would rather build AI products outside of the the electric vehicle maker if he doesn’t have 25% voting control, suggesting the billionaire may prefer a bigger stake in the company.

Stocks pared losses after the ECB’s monthly survey showed consumer expectations for euro-zone inflation fell to the lowest in more than 1 1/2 years in November. Money markets held interest-rate cut wagers broadly steady after the ECB data, pricing the first quarter-point reduction by April followed by almost five more by year-end. Economic data in the UK, meanwhile, also supported the case for Bank of England rate cuts in the coming months, with wage growth cooling at one of the fastest paces on record. The pound weakened as much as 0.8% against the dollar and gilt yields edged lower.

Still, sentiment was dented after hawkish comments from the ECB’s Nagel on Monday who said that it was too early to discuss rate cuts. A similar comment was made by ECB Governing Council member Robert Holzmann on Monday who indicated that cuts this year were not assured given lingering inflation and geopolitical risks. Their sentiments echoed prior comments from ECB President Christine Lagarde warning that it’s too early to talk about trimming borrowing costs. All were subsequently echoed on Tuesday in Davos, when ECB Governing Council member Francois Villeroy de Galhau said that it’s too early to declare victory on inflation. Traders are now awaiting Federal Reserve Governor Christopher Waller’s speech later Tuesday for cues on the timing of a Fed rate cut, with money markets seeing a two-in-three chance of a reduction in March.

“Central banks pushing back on rate cuts is not helping risky assets,” said Mohit Kumar, chief European economist at Jefferies International. “The market has gone a bit ahead of itself.”

And then there are earnings: Morgan Stanley and Goldman Sachs are among the companies reporting results Tuesday, and are expected to reveal the continued lull in investment banking activity as high borrowing costs, geopolitical tensions and recessionary risks dampen deal-making.

European markets were red across the board, extending Monday’s losses. The Stoxx 600 is down 0.6%, with food beverage and media shares are the biggest outperformers, while banking shares leading the decline as JPMorgan analysts said lending revenue will be capped by the peak in interest rates.  Here are the biggest movers Tuesday:

  • Experian gains as much as 3.2%, the most in a month, after the credit-data agency narrowed its expectations for full-year organic revenue growth to the 5%-6% area, compared to the previous 4%-6% forecast and the Bloomberg consensus of 5.16%
  • Lindt & Spruengli shares jump as much as 6.8%, most since July 2022, after the Swiss chocolate maker reported 2023 organic sales growth that beat the highest analyst estimate, according to Vontobel
  • Dassault Systemes shares gain as much as 1.8%, outperforming a falling tech sector, after Deutsche Bank raises the stock to buy from hold. Industry checks suggest that the adoption of the software firm’s cloud-based design platform 3DExperience is increasing in the automotive industry
  • Ocado rallies as much as 7.8%, rebounding from the one-month low hit yesterday, after its grocery business delivered faster sales growth in the fourth quarter than expected
  • Publicis rises as much as 1.4%, to its highest intraday level on record after Goldman Sachs raised the stock to buy, and rated media peers including Relx, Wolters Kluwer, Informa and UMG as buy, saying the most compelling stocks within Europe’s internet and media sector are those that benefit from structural tailwinds
  • QinetiQ Group shares rise as much as 7.9% to touch a two-month high, after the defense company announced a £100 million share buyback program and issued a trading update detailing a rise in full-year revenue
  • DocMorris shares rise as much as 5.7% after full-year 2023 revenue at the Swiss online pharmacy achieved the upper end of its guidance range. The company also reported an increase in active customer numbers for the first time since 2021
  • THG rises as much as 9.4%, rebounding after hitting its lowest level since late October on Monday, after the e-commerce retail company’s guidance for FY23 adjusted Ebitda came in ahead of forecasts, and several of its divisions returned to revenue growth in the latest quarter
  • Hugo Boss shares dropped as much as 11% in Frankfurt, their worst day in nearly four years, with analysts flagging that the German high-end clothing maker’s Ebit disappointed, even as its fourth-quarter sales performance was robust
  • Air France-KLM slips as much as 3.2% to the lowest in six weeks after announcing it would scrap a year-old cargo alliance with container shipping giant CMA CGM, citing a “tight regulatory environment”
  • Wise shares fall as much as 3.4% after the money-transfer firm’s results showed that per-user transaction volume fell among both personal and business accounts. The decline was seen by analysts as a headwind to medium-term growth

Earlier in the session, Asian stocks declined, set to snap three days of gains, as risk sentiment took a breather ahead of key economic data from China and after the ECB tamped down rapid rate cut expectations. The MSCI Asia Pacific Index slid as much as 1.2%, with Tencent, Samsung and BHP among the biggest drags. Equity benchmarks in Hong Kong and Australia posted the biggest declines, while Japanese equities fell amid signs that the market may be overbought after eight-straight days of gains for the Topix. China remains in focus ahead of gross domestic product, industrial production and retail sales data due Wednesday. Numbers are projected to show improvement in the economy in a rebound from periods of pandemic restrictions, and some investors have been turning bullish on the country’s beaten-down stock market.

  • Hang Seng and Shanghai Comp conformed to the downbeat mood but with the losses in the mainland initially cushioned after a substantial PBoC liquidity operation, while Beijing reportedly told some institutional investors in recent days not to sell stocks.
  • Nikkei 225 extended beneath the 36,000 level owing to slightly higher yields and firmer-than-expected PPI data.
  • ASX 200 retreated with miners among the worst hit after lower iron ore output and shipments by Rio Tinto.
  • Stocks in India posted their first retreat in six sessions on Tuesday, dragged by profit taking in index heavyweight Reliance Industries and information technology firms, which had rallied recently. The S&P BSE SENSEX Index fell 0.3% to 73,128.77 in Mumbai, while the NSE Nifty 50 Index declined by a similar measure. BSE’s measure of real estate companies, which was the best performer among its sectoral gauges in 2023, slipped 1.6% — its biggest single-day drop since Dec. 20.

There have been “a few recent economic data points challenging the consensus view of rapid and deep rate cuts,” said Matthew Haupt, a portfolio manager at Wilson Asset Management. “It’s been enough for equity investors to pause and sell into the recent strength.”

In FX, the Bloomberg dollar index climbed to a one-month high and Treasury yields rose, as trading re-opened after MLK Jr. Day. The risk sensitive Scandinavian currencies and Australian dollar led Group-of-10 losses, as central bankers pushed back on market rate cut bets. The Japanese yen sunk to a one-month low, while the British pound dropped on cooling UK wage growth.

  • The Bloomberg Dollar Index rose to its highest level since Dec. 13 as the dollar gained against all Group-of-10 peers, the Australian dollar, Swedish krona and Norwegian krone led losses as risk-off sentiment swept through markets
  • USD/JPY climbed as much as 0.6% to 146.65, a one-month high; One-week implied volatility between the currency pair implied traders don’t expected fireworks out of next week’s BOJ meeting but are positioning for the possibility of surprisingly hawkish forward guidance
  • GBP/USD dropped as much as 0.7% to 1.2635, the lowest level since Jan. 5; UK wage growth data cooled at one of the fastest paces on record
  • EUR/USD fell as much as 0.6% to 1.0883 as the euro fell for a fourth day; Consumer expectations for euro-zone inflation dropped to the lowest in more than one and a half years, ECB’s Villeroy said rate cuts were probable but pushed back on the timing priced by markets

In rates, Treasury yields cheaper by 6bp to 7bp across the curve as cash market reopens following Monday’s close, during which futures were led lower by bunds. Treasury 10-year yields around 4.01%, cheaper by around 7bp vs Friday’s close with higher yields helping the greenback, with the Bloomberg Dollar Spot Index rising 0.6% ahead of a speech by Fed Governor Waller. Curve spreads are broadly within 1bp of Friday levels. Fed-dated OIS have around 17bp of rate cuts priced in for the March policy meeting vs 19bp on Friday. In Europe, the slide in bunds occurred after ECB policymaker Holzmann warned against rate cuts this year. Fed’s Waller is slated to speak at 11am New York time, heavy corporate issuance is expected this week and a 20-year bond auction is ahead Wednesday.

In commodities, oil prices were steady as continued Houthi attacks on ships in the Red Sea that are keeping tensions high in the Middle East were offset by a shaky global economic outlook and gains in the dollar. Global benchmark Brent held above $78 a barrel, while West Texas Intermediate traded around $73. Spot gold fell 0.9% below $2040.

Bitcoin rose +0.4%, holding just below the $43k level with Ethereum also posting modest gains.

Looking to the day ahead now, data releases include UK labor market data, Germany’s ZEW survey for January, Canada’s CPI for December, and in the US, we get the Empire State manufacturing survey for January. From central banks, we’ll hear from BoE Governor Bailey, Fed Governor Waller and the ECB’s Villeroy. Lastly, earnings releases include Goldman Sachs and Morgan Stanley.


Market Snapshot

  • S&P 500 futures down 0.5% to 4,793.25
  • MXAP down 1.4% to 165.28
  • MXAPJ down 1.5% to 503.27
  • Nikkei down 0.8% to 35,619.18
  • Topix down 0.8% to 2,503.98
  • Hang Seng Index down 2.2% to 15,865.92
  • Shanghai Composite up 0.3% to 2,893.99
  • Sensex down 0.2% to 73,170.25
  • Australia S&P/ASX 200 down 1.1% to 7,414.79
  • Kospi down 1.1% to 2,497.59
  • STOXX Europe 600 down 0.4% to 472.12
  • German 10Y yield little changed at 2.22%
  • Euro down 0.5% to $1.0894
  • Brent Futures up 0.6% to $78.62/bbl
  • Gold spot down 0.8% to $2,041.01
  • U.S. Dollar Index up 0.70% to 103.12

Top Overnight News from Bloomberg

  • China is weighing 1 trillion yuan ($139 billion) of new debt issuance under a so-called special sovereign bond plan, only the fourth such sale in the past 26 years. The sale of ultra-long bonds would fund projects in areas including food and energy, people familiar said. BBG
  • William Lai Ching-te won the Taiwan presidential election on Saturday, as expected, securing a 3rd term in power for the Democratic Progressive Party (DPP). Lai took 40% of the vote followed by Hou Yu-I from the Kuomintang (KMT) at 33.5% (the KMT is considered more conciliatory toward China) and Ko Wen-je from Taiwan People’s Party (TPP) at 26.5%. RTRS
  • AAPL is offering rare discounts on its iPhones in China, cutting retail prices by as much as 500 yuan ($70) amid growing competitive pressure in the world’s biggest smartphone market. RTRS
  • ECB’s Holzmann warns markets not to expect the first rate cut in April and says there may not be any decreases this year. CNBC
  • Houthi militants hit a US-owned container vessel with a missile in the Gulf of Aden. Gibraltar Eagle, carrying steel products, suffered limited damage. Washington warned its merchant ships to avoid the area. PM Rishi Sunak told Parliament that the UK wants to reduce tensions and its air strikes are “self-defense.” BBG
  • Though the Federal Reserve stopped raising interest rates last summer, it is quietly tightening monetary policy through another channel: shrinking its $7.7 trillion holdings of bonds and other assets by around $80 billion a month. Now that, too, may change. Fed officials are to start deliberations on slowing, though not ending, that so-called quantitative tightening as soon as their policy meeting this month. WSJ
  • Biden’s campaign raises $97MM in Q4 and has $117MM of cash on hand, formidable numbers that provide an important monetary tailwind for the president heading into November. BBG
  • Trump dominates Iowa (as expected) at 51% followed by DeSantis at 21.2% and Haley at 19.1% while Ramaswamy exits the race w/a 7.7% showing. WaPo
  • Global core inflation picked up modestly in December on a 1-month basis, but the 3-month annualized rate has slowed further to 2.0%. We still expect the Fed to start easing in March, with a total of 5 cuts in 2024 (slightly less than market pricing). The ECB should follow in April and the BoE in May, and our views on both central banks are somewhat dovish relative to market pricing. By contrast, we expect only modest macro policy easing in China, despite sluggish growth and very low inflation. The combination of falling inflation, easier monetary policy, and solid growth should provide a friendly backdrop for risk asset markets. GIR

A more detailed look at global markets courtesy of Newsquawk

APAC stocks were pressured in the absence of a lead from Wall Street and amid the upside in yields. ASX 200 retreated with miners among the worst hit after lower iron ore output and shipments by Rio Tinto. Nikkei 225 extended beneath the 36,000 level owing to slightly higher yields and firmer-than-expected PPI data. Hang Seng and Shanghai Comp conformed to the downbeat mood but with the losses in the mainland initially cushioned after a substantial PBoC liquidity operation, while Beijing reportedly told some institutional investors in recent days not to sell stocks.

Top Asian News

  • PBoC injected CNY 760bln via 7-day reverse repos with the rate at 1.80% for a CNY 695bln net injection.
  • Chinese authorities reportedly told some institutional investors in recent days not to sell stocks as the Chinese stock rout resumes, according to FT.
  • Chinese President Xi stresses boosting high-quality development of the country’s financial sector, according to Reuters citing state media.
  • Microsoft (MSFT) CEO says China is not a large business for the Co.
  • China is said to be mulling more stimulus with USD 139bln of special bonds, according to Bloomberg sources; proposals include the sale of ultra-long sovereign bonds to fund projects. Projects are related to projects related to food, energy, supply chains and urbanisation, sources added.
  • Japanese government is to increase new bond issuance by USD 3.43bln to fund extra budget reserves (following recent earthquakes); there will be no change to JGB issuance sold to market
  • Chinese Premier Li says China’s economy is making steady progress; Chinese economy rebounded in 2023 and had an estimated growth of 5.2%, higher than the 5% target; says in promoting development, China did not resort to massive stimulus. Comes ahead of the Chinese GDP and activity data on Wednesday.

European equities, Stoxx 600 (-0.5%), are trading on the back-foot having sunk at the open, following a negative handover from APAC trade overnight, in the absence of a lead from Wall Street. European sectors have a strong negative tilt; Media is marginally firmer after a broker upgrade at Publicis (+1.2%). Banks are lower following a slew of downgrades at JPM and a cut in EPS estimates for Commerzbank (-4.5%). US equity futures are lower across the board, in tandem with European counterparts, though with losses slightly more pronounced; the Russell 2000 (-0.9%) underperforms. Earnings from Goldman Sachs and Morgan Stanley due, among others, in the pre-market.

Top European News

  • British pension funds are preparing to “flood the market” with billions of GBP’s of private assets, according to Bloomberg. As much as GBP 200bln in assets could be offloaded as rising interest rates provide funds with an opportunity to offload the part of the risk of meeting future liabilities.
  • BofA January Fund Manager Survey: cash levels up, more investors expect short term rates to be lower in the next 12 months, more expect a weaker Chinese economy than a stronger one.
  • Ocado (OCDO LN) Retail CEO is not expecting much impact on business from the Red Sea/Suez Canal disruptions
  • German economy is expected to grow 0.3% in 2024, according to German BDI Industry Association; German economy is at a standstill and there is no change of a rapid recovery
  • ECB Consumer Inflation Expectations survey (Nov) – 12-months ahead 3.2% (prev. 4.0%); 3-year ahead 2.2% (prev. 2.5%). Economic growth expectations for the next 12 months -1.2% (prev. -1.3%)

FX

  • Dollar is firmer alongside the risk averse mood and as US yields rise after cash closure for MLK day; DXY took out 103.00 and surpassed the post-NFP high of 103.10, with the 200DMA at 103.41 now in sight. Fed’s Waller at 16:00GMT/11:00EST will be in focus for the Dollar.
  • EUR/USD has lost its 1.09 status amid the strength in the USD, less hawkish ECB speak and softer consumer inflation expectations. Today’s trough at 1.0881 with yesterday’s low at 1.0876 just below.
  • Cable is swept up by Dollar buying, with lower UK wage data also not helping the Pound. On release, Cable sank lower before then entirely paring the move.
  • Antipodeans are the G10 underperformers, in tandem with the cautious risk tone; support at 0.66 for the AUD/USD has broken in recent trade.
  • USD/CNH bid and continuing to lift; focus on earlier sources around potential special bond stimulus and thereafter Premier Li on GDP, ahead of Wednesday’s figures.
  • PBoC set USD/CNY mid-point at 7.1134 vs exp. 7.1783 (prev. 7.1084).

Fixed Income

  • Treasuries pressured to a 112-05 trough, yields bear-flattening as cash reacts to Monday’s ECB speak.
  • Bunds are struggling for direction & drawn to the mid-point of 134.94-135.42 parameters after Monday’s hawkish move on numerous ECB officials. Remarks thus far from Villeroy, Centeno & Valimaki at Davos stress data-dependency.
  • Despite the dovish wage figures, Gilts opened 16 ticks lower at 99.91 as the bias from US yields dominates. Since, Gilts have lifted to a 100.33 peak, shy of last week’s 100.47-69 highs.
  • UK sells GBP 1.5bln 2033 I/L Gilt: b/c 3.04x (prev. 2.68x) and real yield 0.423% (prev. 0.724%)
  • Germany sells EUR 3.2bln vs exp. EUR 4.0bln 2.10% 2029 Bobl; b/c 2.1x (prev. 2.07x), average yield 2.12% (prev. 2.56%), and retention 20.0% (prev. 19.2%)
  • France is seeing in excess of EUR 74bln in demand for its new green bond, according to lead managers; spread set at 8bps over outstanding June 2044 (initial guidance +10bp)

Commodities

  • An upward bias is seen in crude prices this morning, with the complex resilient to the surging Dollar and broader risk aversion as the downside is countered by escalating geopolitics coupled with reports of further Chinese stimulus and Premier Li on GDP; Brent at highs of USD 79.18/bbl.
  • Precious metals feel the pressure from the surge in the Dollar and yields stateside; XAU fell from a USD 2,055.22/oz intraday peak to levels under its 21 DMA (USD 2,044.44/oz).
  • Base metals are mostly lower but were lifted off worst levels amid reports that China is mulling further stimulus.
  • First Quantum is to reduce operating activities at its Ravensthorpe nickel operation and will cut workforce at the site by 30% after a significant downturn in nickel prices during 2023, combined with higher operating costs in Western Australia.
  • India’s Oil Minister says India has opened up to every possible supplier; Indian demand for energy will not peter off for a while

Central Bank speak

  • ECB’s Villeroy says it is too early to declare victory over inflation, most monetary policy transmission is more or less over. Will not remark on the season for the next ECB move; but the next move should be a cut this year. Can see a soft landing in both Europe and the US. Estimates R to be around zero within the Euro-area.
  • ECB’s Centeno says ECB needs to be prepared for all topics, including rate cuts; says recent data confirmed Dec projections, but inflation was slightly below forecast. Inflation is coming down sustainably, should not be worried about resurgence of real wages. Q1 growth could remain around zero. Expects contained wage demand. Inflation trajectory is very positive at this point.
  • ECB’s Valimaki says inflation is on the right track but job is not done so restrictive monetary policy is still called for; must not jump the gun on rate cuts and best to wait a bit longer than exit prematurely. Soft landing for economy still the baseline but risks tilted towards downside. Wage data so far consistent with ECB’s December projections.
  • ECB’s Nagel (hawk) says it’s too early to discuss rate cuts as inflation remains too high, maybe the ECB can wait until after the summer break; markets are sometimes over optimistic – Bloomberg TV interview.
  • ECB’s Holzmann (hawk) says rate cut expectations are optimistic; shouldn’t count on rate cuts at all in 2024 – CNBC interview.
  • ECB’s Herodotou says it is too soon to contemplate policy easing or the pace of easing – Econostream Media interview
  • ECB’s Lane, weekend remarks: will have key data by June to decide on rates and that changing rates too fast can be harmful, while he added that once the ECB begins lowering rates, this would not be by a single decision of a rate cut and there would likely be a sequence of rate cuts – Corriere Della Serra.

Geopolitics: Middle East

  • Explosions were reported in different areas in Erbil, northern Iraq and in Syria, according to Al Arabiya IRGC said it attacked and destroyed the espionage headquarters of Israel’s Mossad in Iraq’s Kurdistan and it targeted Islamic State in Syria in response to the group’s recent terrorist attacks in Iran, according to Reuters.
  • US State Department said the US strongly condemned Iran’s attacks in Erbil on Monday, while US officials said no US facilities were impacted by missile strikes in Erbil, Iraq and there were no US casualties, according to Reuters.
  • UK PM Sunak signalled the UK could participate in further strikes against Houthi rebels and told MPs that Britain will not hesitate to protect its interests where required, according to FT.
  • Houthi military spokesman said they consider all American and British vessels and warships participating in aggression against them as hostile targets, according to Reuters.
  • Iran’s Islamic Revolutionary Guard Corps commanders and advisors are on the ground in Yemen and playing a direct role in Houthi rebel attacks on commercial traffic in the Red Sea, according to SEMAFOR.

Geopolitics: Other

  • Ukraine President Zelenskiy asked Switzerland to organise a high-level peace conference, while teams will start on plans today.
  • North Korea decided to shut down organisations dealing with unification and inter-Korean tourism, while North Korean leader Kim said they do not want war but have no intention to avoid it. Furthermore, Kim said war will destroy South Korea and deal an unimaginable defeat to the US, according to KCNA.
  • South Korean President Yoon said North Korea’s recent missile launch and artillery firing are political acts to divide South Koreans and its provocations will be met with response on a multiplied scale, according to Reuters.

US Event Calendar

  • 08:30: Jan. Empire Manufacturing, est. -5.0, prior -14.5

Central Bank Speakers

  • 11:00: Fed’s Waller Speaks on Economic Outlook and Monetary Policy

DB’s Jim Reid concludes the overnight wrap

As we go to print, we have 95% of the votes counted from the Iowa Caucus. Former President Donald Trump has easily won the first test of this election year with 51.1% of the vote so far, according to CNN. Florida Governor Ron DeSantis is in second place (21.2%) followed by a third-place finish for former South Carolina Governor Nikki Haley (19%). Also, Vivek Ramaswamy (7.7%), suspended his presidential campaign after a fourth-place finish. The polling averages in the state before the vote were Trump (53%), Haley (19%), and DeSantis (16%), so DeSantis has slightly outperformed.

The next stop is New Hampshire on Tuesday next we ek , where Haley is running in a strong second, with the current FiveThirtyEight polling average at Trump (43%), Haley (30%) and DeSantis (6%). Her campaign’s hope is they can win New Hampshire, and then also take the third contest in South Carolina on February 3 (where Haley was Governor from 2011-17).

Before the votes, yesterday was a lighter session for markets given the US holiday, but it was fairly negative where trading did take place, since European equities and bonds struggled after several ECB officials pushed back on the possibility of rate cuts. By the close, that meant the STOXX 600 was down -0.54%, whilst yields on 10yr bunds were also up +7.3bps to 2.23%. And that wasn’t just confined to Europe, as US futures markets were also pointing to bonds and equity losses there too. Overnight 2 and 10yr US yields are both +6bps higher and S&P and NASDAQ futures are -0.36% and -0.5% lower, respectively.

In terms of the comments, markets were partly reacting to an interview that had taken place on Saturday, with ECB chief economist Philip Lane. He warned that the “history of high inflation episodes tells us that if central banks try to normalise too quickly, before the problem is really conquered, then we get another inflation wave, and then another wave of interest rate hikes. That would be a far worse scenario.” So there was an open acknowledgement about the risks of easing prematurely, which is what happened in the 1970s and meant inflation became more entrenched as a result.

But it wasn’t just Lane who commented, as we also heard from some of the hawks on the ECB’s Governing Council, who similarly pushed back on the rate cut discussion. For instance, Bundesbank President Nagel said “I think it’s too early to talk about cuts”, and Austria’s Holzmann even said that “We should not bank on the rate cut at all for 2024.” Even Cyprus’ Herodotou, who’s been a more dovish voice, said that “Any discussion regarding the time and potency of the first rate cut, as well as the pace of further cuts thereafter, would be premature at the moment and would not constitute a data-dependent approach”. So there was a consistent message from various speakers on the hawk-dove spectrum that didn’t sound as though a Q1 rate cut was on the agenda.

All that meant investors grew more sceptical that the ECB would be cutting rates soon, and the likelihood of a cut by March fell to 29%, down from 43% on Friday. That was echoed more broadly as well, as the likelihood of a Fed cut by March fell from 83% on Friday to 74% by yesterday’s close, and the likelihood of a BoE cut by then was down from 35% to 31%. And in turn, that led to a sovereign bond sell-off across Europe, with yields on 10yr bunds (+4.8bps), OATs (+5.1bps) and BTPs (+7.3bps) all moving higher. 2yr bund and OATs were +6.1bps and +6.7bps higher respectively, so a slightly deeper inversion.

For equities it was much the same story, with the major indices across Europe all getting the week off to a rocky start. Indeed, for the STOXX 600 (-0.54%) it was the worst start to a week in over three months. That was echoed across the continent, with losses for the DAX (-0.49%), the CAC 40 (-0.72%) and the FTSE 100 (-0.39%). That came as the activity data we did get yesterday was fairly weak, with full-year German GDP growth for 2023 coming in at a contractionary -0.3%, in line with expectations. In fact, apart from the Covid pandemic year of 2020, that’s the weakest annual growth since 2009 as the economy faced the impact of the GFC. A technical recession was avoided though as Q3 was revised up a tenth to 0.0% with Q4 likely to be -0.3% when the flash is released on Jan 30th! It wasn’t all bad news, however, as European natural gas futures fell to their lowest level since August, with the front-month contract down to €29.92/MWh.

Asian equity markets are lower this morning with the Hang Seng (-1.92%) the biggest underperformer and with the Nikkei (-0.71%) also halting its record-breaking gains since the start of the year. Meanwhile, the KOSPI (-0.72%) is also losing ground while the CSI (-0.38%) and the Shanghai Composite (-0.62%) are also declining.

Early morning data showed that Japanese input prices were unchanged last month from a year earlier, marking its weakest reading in almost three years as the yen’s recent gains (now largely unwound) helped cap import costs. The expectation were for -0.3% though. They increased +0.3% m/m in December as against an upwardly revised gain of +0.3% in November and expectations for 0.0%.

To the day ahead now, and data releases include UK labour market data, Germany’s ZEW survey for January, Canada’s CPI for December, and the US Empire State manufacturing survey for January. From central banks, we’ll hear from BoE Governor Bailey, Fed Governor Waller and the ECB’s Villeroy. Lastly, earnings releases include Goldman Sachs and Morgan Stanley.

Tyler Durden
Tue, 01/16/2024 – 08:02

President Of Canadian LGBT Organization Arrested On Child Sex Abuse Charges

0
President Of Canadian LGBT Organization Arrested On Child Sex Abuse Charges

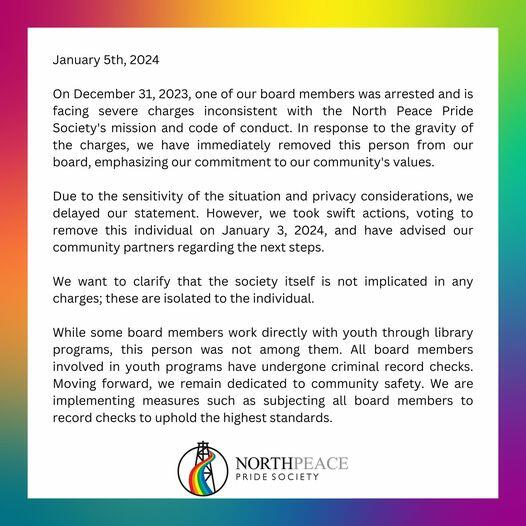
Yet another activist advocate for LGBT engagement with children has apparently been caught doing a lot more than community outreach.  Sean Gravells, an outspoken LGBT activist and the president of an LGBT pride organization in Canada called the North Peace Pride Society, has been arrested on multiple charges including sexual exploitation of a child under the age of 16 and the possession and distribution of child pornography.  

The alleged offenses all took place in or near Fort St. John, B.C., northeast of Vancouver. The interference and exploitation charges were initiated on Dec. 29, 2023, while the child pornography charges occurred on Dec. 31.  

The North Peace Pride Society quickly removed Gravells as president upon news of his arrest, and in a statement made to their Facebook Page they asserted that even though the group sponsors youth events, Gravells was never involved directly with children. 

The NPPS held “teen pride nights” at the Fort St. John Library under the direction of Sean Gravells.  In the image below you can see Gravells (on the left) with representatives of NPPS giving a sponsorship check to the library to fund youth events.

Arrests of prominent LGBT activists for child abuse are becoming rather common.  Only a week before the detention of Sean Gravells, a well known trans woman (male) activist by the name of Kendall Stephen was arrested in Philadelphia, charged with the rape of two young boys.  

Multiple leftist activists with influential positions in media have been arrested or convicted on child sex abuse charges and pornography in the past year, including two senior producers from ABC and CNN, as well as Slade Sohmer, the former managing editor of CNN’s now defunct BEME video and co-manager for a kids summer camp called “Camp Power.”

Then there was the gay activist couple from Georgia that was arrested at the beginning of 2023.  After adopting two boys, the couple allegedly abused them, then trafficked them to a pedophile ring.

And how about Oregon teacher/activist Kelsey Boren, who “mentored” an 11-year-old drag queen and was later convicted on child pornography charges.  Boren was sentenced to less than a year in prison in 2023 for 11 felony counts of encouraging child sex abuse. 

For many decades there were good people within the gay community that worked diligently to separate themselves from historical assumptions that they’re inclined to target children.  But today, radical LGBT activists are proving these assumptions correct by burning down whatever goodwill the community might have built up in the past.  Their insistence on forcing trans and gender fluid ideology into schools and exposing young children to sexualized concepts and imagery has given rise to a reasonable public suspicion – That the end goal of the LGBT movement is not acceptance of different views, but outright predatory grooming of the next generation. 

Tyler Durden
Tue, 01/16/2024 – 07:48

It Will Take A Lot To Talk Market Down From Rate-Cuts

0
It Will Take A Lot To Talk Market Down From Rate-Cuts

Authored by Simon White, Bloomberg macro strategist,

Recent data has highlighted inflation is sticky, and retail sales this week could confirm the consumer is far from tapped-out. But it will take more than that – perhaps a coordinated response from Federal Reserve speakers – to disabuse the market of the multiple interest rate cuts priced in for this year.

The market continues to gun for the Fed’s cutting cycle to begin in March.

Consumer prices came in higher-than-expected, yet this barely moved the dial on those expectations.

Soft producer prices data on Friday was seen as a post hoc justification for dovish pricing. But even there, under the surface, are clear signs of inflation that is becoming entrenched.

PPI measures prices received for non-retail firms. But for wholesalers, who do not buy raw materials, this is not directly measurable. In this case the Bureau of Labor Statistics estimates the value-add, i.e. the gross margin, for such companies.

The black line in the chart below shows the percentage of industries whose gross margin is rising on an annual basis. It reflects a reasonable correspondence with services CPI excluding rent. The gross margin measure is rising, which is consistent with CPI rising again.

Profits, since the pandemic, have been the biggest contributor to corporate prices, rather than labor.

It’s not a wage-price spiral that is the main worry in this cycle, but a profit-price-wage spiral.

We will also get an update on retail sales this week. They have been much better than anticipated given the Fed’s aggressive rate-hiking cycle. Leading data suggests that momentum should continue well into this year.

In normal circumstances, that might mean a reappraisal by the market and a shift to less dovish pricing. But that has not been the case lately, with the economy – and even Fed-speak explicitly talking down a March cut – seemingly ignored.

It will likely take a more coordinated response from the Fed if they want to take an early cut off the table.

There are at least six Fed board members and bank presidents due to speak this week, so we will find out how fervent is the desire to push back against the market’s current dovish outlook.

Tyler Durden
Tue, 01/16/2024 – 07:20