

64.1 F
Chicago
Saturday, September 19, 2026
Home Blog Page 328

This Is How Leftists React To Facts…

This Is How Leftists React To Facts…

Authored by Steve Watson via Modernity.news,

When presented with uncomfortable irrefutable statistics on migrant crime, those on the left don’t debate—they threaten violence and scream about history as an excuse for chaos today.
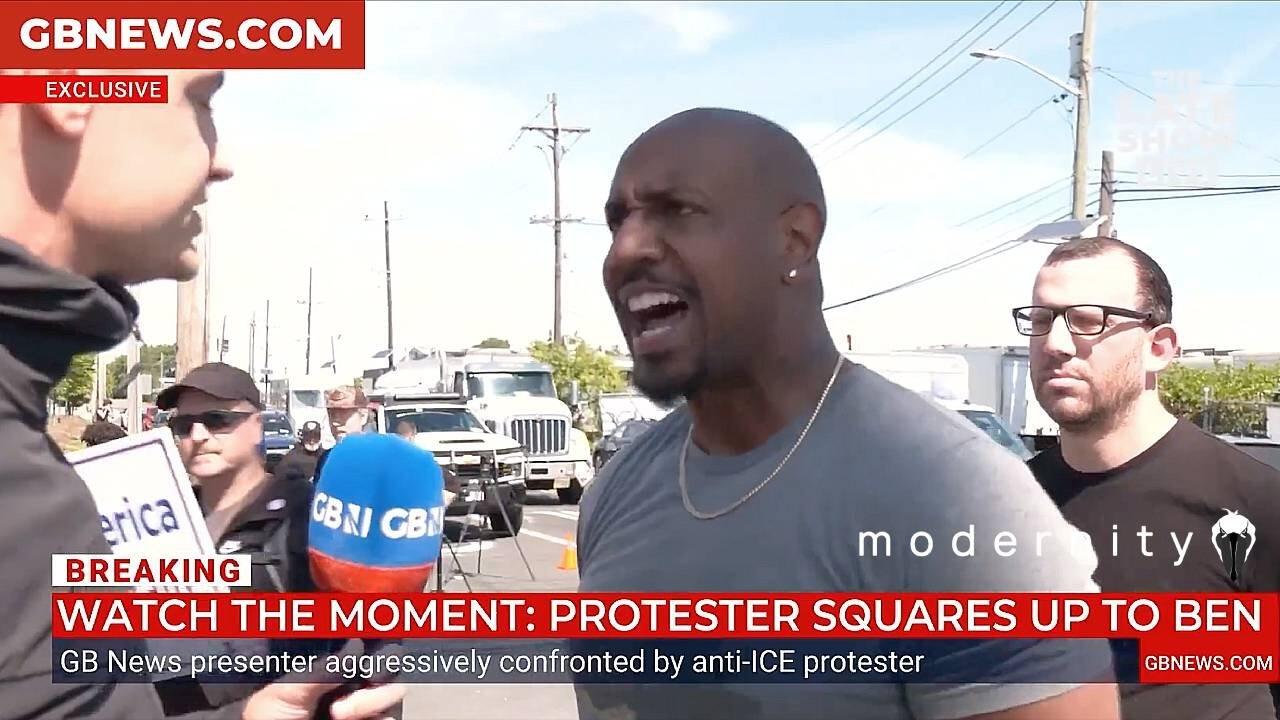
That’s exactly what unfolded outside the Delaney Hall ICE detention facility in Newark, New Jersey, Saunday. GB News chief US correspondent Ben Leo was on the ground covering anti-ICE protests—already marked by days of clashes, a hunger strike by detainees, and assaults on officers—when he calmly laid out basic facts about illegal migrant crime patterns in the UK while engaging with the ‘protesters’.

The furious black nationalist got inches from Leo’s face, accused Brits of colonizing the world “through rape, murder and pillaging,” and warned he was “holding everything back not to break your f***ing jaw.”

Leo stood his ground without flinching. Lurking right behind the seething guy, a spectacled soy leftist pathetically attempted to pile on, weakly joining the intimidation effort by demanding Leo “go back to your country”—the height of irony at an open-borders rally.

The incident, captured on video and shared widely, shows how facts about immigration enforcement trigger outright rage from open-borders activists. While ICE works to secure America’s borders under policies prioritizing law and order, protesters treat any challenge to mass migration as a personal attack worth physical intimidation.

In the clip, Leo began by referencing data showing certain nationalities in the UK are disproportionately involved in sexual offences compared to native Brits. The protester immediately pivoted to colonial history.

“The BRITS that colonised the whole world you mean? That raped and pillaged the WHOLE WORLD to get the power they have THE BRITS,” he shouts.

“YEAH The BRITS who did THAT. And YOU guys have the audacity TO SAY AFGHANS AND SOMALIS DID WHAT?”

Leo responded evenly: “Well it’s not Audacity. It is just a fact.”

The man escalated, demanding: “IS IT NOT A FACT THAT Y’ALL COLONIZED THE WORLD THROUGH RAPE, MURDER AND PILLAGING, RIGHT OR WRONG?”

The guy then repeated insults—“you’re a piece of s,” “you’re a liar”—and got inches from Leo’s face, spitting as he ranted about how he “came out here for violence,” not to talk.

Leo stayed composed, pointing out the obvious: “This doesn’t make your argument look good. That’s the left. That is the degenerate violent left. You give facts. You get data. And they get violent.”

The exchange ended with the soy leftist in the background yelling “go back to your country.” Leo’s deadpan reply: “I live here.” When asked how he got there: “Aeroplane.”

On GB News, Leo later reflected on the moment. He explained he could have countered with historical facts—Britain’s role in abolishing the slave trade, Royal Navy efforts against it—but prioritized de-escalation and safety amid the aggression. “I was more concerned about watching his hands… making sure that he wasn’t about to swing for me.”

He also addressed the police response, calling it “chilling” and “worrying.” Officers appeared uninterested after the threat, with one suggesting Leo’s questions were “provocative.” Leo noted: “It didn’t really seem like the police were bothered… presenting simple facts and asking what you’re doing here… is somehow provocative.”

This isn’t isolated. Protests at Delaney Hall have turned violent for over a week, with reports of objects thrown, entrances blocked, and even an ICE agent bitten. Detainees allege poor conditions, but federal officials call the strike a political stunt amid efforts to deport serious offenders.

The confrontation exposes a deeper hypocrisy. Leftist activists rage against “colonialism” while ignoring how British institutions—rule of law, abolitionism, and innovation—built much of the modern world migrants flock to. They excuse crime waves from unchecked migration by pointing to the past, yet demand America absorb endless inflows without consequences.

Leo’s calm handling underscores a key truth: facts don’t care about feelings. When open-borders ideology meets reality—rising sexual offences, strained resources, cultural clashes—it produces not debate but threats. This is the same mindset behind attacks on figures like Charlie Kirk and repeated assassination attempts on President Trump.

America First policies, like robust ICE operations, exist precisely because ignoring these patterns endangers citizens. The left’s violent reaction proves they know the data is irrefutable—they just refuse to accept it.

The left’s mask slips when challenged. They’re not tolerant—they’re unhinged when their narrative cracks.

Your support is crucial in helping us defeat mass censorship. Please consider donating via Locals or check out our unique merch. Follow us on X @ModernityNews.

Tyler Durden
Mon, 06/01/2026 – 13:05
French Commandos Board & Seize 4th Russian ‘Shadow Fleet’ Vessel Since September

French Commandos Board & Seize 4th Russian ‘Shadow Fleet’ Vessel Since September

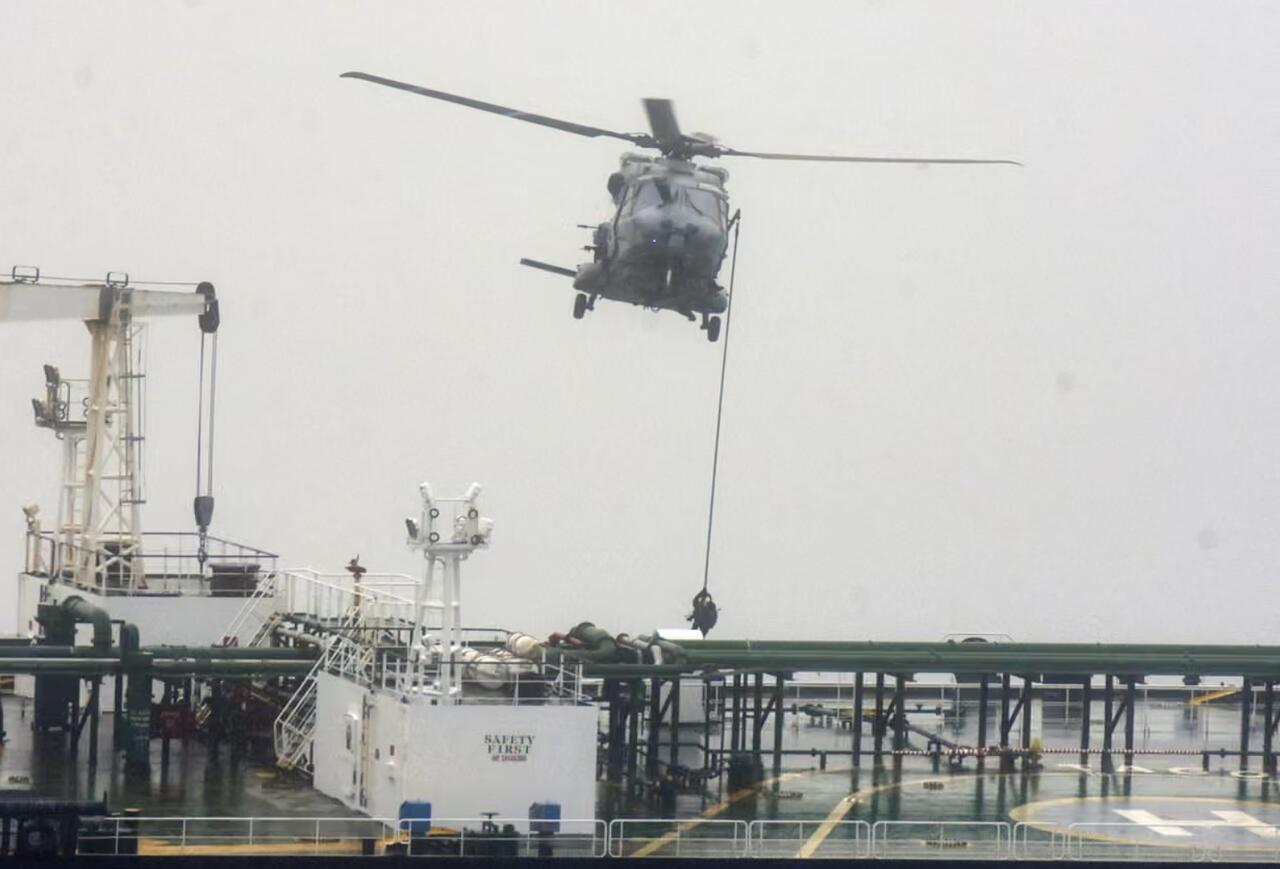
France announced Monday another weekend interdiction of a Russian “shadow fleet” vessel in international waters near its coast. The French Navy boarded and detained a sanctioned oil tanker, President Emmanuel Macron announced Monday, in an operation which had the assistance from the UK Royal Navy and other allies.

This marks the fourth time since September that French commandoes have intercepted a boarded a sanctioned Russian vessel in regional waters.

via AFP/French military

The vessel, identified as the Tagor, originated from Murmansk, Russia, and was taken by French authorities while it traversed around 400 nautical miles (740 km) west of the tip of Brittany.

“It is unacceptable for ships to circumvent international sanctions, violate the law of the sea and fund the war that Russia has been waging against Ukraine for more than 4 years,” Macron wrote in a post on X.

The apparent legal justification France’s navy has relied on for such actions is the practice of “flag-hopping” – which involves a crew repeatedly changing displayed flags, along with often invalid registrations to thwart international tracking monitors.

At the time of boarding, via soldiers rappelling from helicopter, the ship was falsely flying a Cameroonian flag while reportedly en route to the coastal African city of Limbe, Cameroon.

Macron confirmed further on X: “This operation took place in the Atlantic Ocean, on the high seas, with the support of several partners, including the United Kingdom, in strict compliance with the law of the sea.”

The Kremlin again condemned such ‘unlawful’ seizures in international waters, with spokesman Dmitry Peskov saying, “We consider these acts as illegal, they border on international piracy … Russia is taking measures to ensure the safety of its cargo.”

The vessel’s captain is a Russian citizen, according to an embassy disclosure from Paris. According to more:

Guillaume Le Rasle, a spokesperson for the prefecture, said the tanker was under EU and US sanctions. “It is a vessel that was known and tracked,” he told AFP.

“The decision to divert it was taken Sunday evening. The objective of the diversion is to verify the validity of its flag,” Le Rasle said, adding that the tanker, which has frequently changed flags, was “almost empty” at the time of boarding.

The last several seized tankers were also flying flags of African nations, and these interdictions have stretched back through last year. In some instances, Russia has been sending military escorts – which of course has seen French and European militaries hold off executing any action.

Tyler Durden
Mon, 06/01/2026 – 12:50

Anthropic Confidentially Files For IPO As Frontier AI Labs Race To Go Public

Anthropic Confidentially Files For IPO As Frontier AI Labs Race To Go Public

Four days after releasing its latest Claude Opus 4.8 model and raising $65 billion at a $900 billion valuation, Anthropic confidentially filed a draft Form S-1 with the SEC late Monday morning for a proposed IPO of its common stock.

“This gives us the option to go public after the SEC completes its review. The proposed initial public offering will depend on market conditions and other factors,” the maker of the Claude chatbot wrote in a press release.

The move puts Anthropic and OpenAI in a race to become the first major frontier AI lab to tap public markets, as investor appetite for AI infrastructure and all things SpaceX remains hot into early June.

It’s “worth noting: filing first ≠ pricing first a confidential draft S-1 starts the SEC clock but sets no date,” CNBC reporter Deirdre Bosa pointed out on X.

The Polymarket bet Will Anthropic or OpenAI IPO first? shows that the confidential S-1 filing was a surprise to prediction markets.

The surprise news comes four days after Anthropic raised $65 billion at a $900 billion valuation, nearly tripling its prior valuation and potentially surpassing OpenAI as the most valuable frontier AI lab.

That round was led by Altimeter Capital, Dragoneer, Greenoaks, and Sequoia, with additional participation from major investors including Baillie Gifford, Blackstone, Brookfield, Abu Dhabi’s MGX, and Singapore’s Temasek.

The funding comes shortly after Anthropic released Claude Opus 4.8 and follows a prior $30 billion raise at a $350 billion valuation just three months earlier.

The Anthropic-OpenAI race to IPO comes as SpaceX is targeting an IPO for June 12, or next Friday, with shares expected to trade on the Nasdaq under the ticker symbol SPCX.

Just last month. 

With the flurry of mega IPOs on deck, Goldman has the answer to whether markets can absorb all the incoming supply (read report).

Tyler Durden
Mon, 06/01/2026 – 12:40

US Moves To Further Restrict China’s Access To Advanced AI Chips

US Moves To Further Restrict China’s Access To Advanced AI Chips

Authored by Evgenia Filiaminova via The Epoch Times,

The U.S. Department of Commerce has issued new guidance to prevent Chinese companies from obtaining advanced U.S. artificial intelligence (AI) chips, such as Nvidia’s most sophisticated Blackwell processors, through overseas subsidiaries.

The May 31 guidance clarifies that export licenses are required for entities headquartered in China or Macau, regardless of where their affiliates are located.

The U.S. Commerce Department’s Bureau of Industry and Security (BIS) said that licensing requirements for advanced computing items destined for China- or Macau-headquartered entities were first established in November 2023 and remain in effect.

The agency said the requirement applies even when those entities are located outside China or Macau.

The clarification follows confusion over a May 2025 announcement by the BIS that it would not enforce certain parts of the Biden-era AI diffusion rule.

The rule was designed to restrict sales of advanced AI chips to strategic rivals while allowing broader access for U.S. allies.

The BIS said the policy change did not remove existing licensing requirements for exports involving Chinese or Macau-based customers, meaning companies must still obtain licenses unless an exemption applies.

The guidance also states that legitimate data center operators can continue to use, maintain, store, or replace advanced AI chips and equipment they already own.

The clarification does not require companies to shut down or remove existing systems.

Nvidia’s sales of advanced AI chips to China remain subject to U.S. export controls.

The Trump administration created a framework in 2025 allowing certain chips, including the H200, to be sold to approved Chinese customers under Commerce Department oversight.

Trump said in a Dec. 8, 2025, post on Truth Social that sales would be permitted subject to a 25 percent fee benefiting the U.S. government and limited to approved Chinese customers.

President Donald Trump (L) shakes hands with Nvidia CEO Jensen Huang as they discuss investing in America, at the White House on April 30, 2025. Jim Watson/AFP via Getty Images

An Nvidia spokesperson told The Epoch Times that the BIS guidance doesn’t impact its business.

It “simply reaffirms that NVIDIA’s current sales and vetting process is correct — licenses are required to ship controlled products to [China] headquartered companies,” the spokesperson said.

The Epoch Times reached out to AMD, another major supplier of AI chips, for comment, but did not receive a response by publication time.

Analysts Warn of Potential Gap

Former U.S. State Department official Chris McGuire, who focuses on technology and national security issues, said in a May 31 post on X that the ambiguity surrounding BIS enforcement may have enabled overseas subsidiaries of Chinese firms to legally acquire advanced U.S. AI chips without export licenses.

“Chinese companies have been buying these chips, very likely at scale,” McGuire wrote in the social media post.

He argued that the lack of clarity about which export controls remained in effect created an opening that may have allowed subsidiaries of Chinese firms operating in countries such as Malaysia to purchase Nvidia’s Blackwell processors.

McGuire said the new BIS guidance appears to close that pathway by making clear that exports to China-headquartered companies outside China still require licenses.

Nvidia CEO Jensen Huang eats a bowl of noodles on a street in Beijing on May 15, 2026. Jiang Panpan via AP/Screenshot via The Epoch Times

He said that BIS has not clarified whether it will enforce due diligence requirements that apply to semiconductor foundries such as Taiwan Semiconductor Manufacturing Co. (TSMC) when assessing whether advanced AI chips could ultimately benefit Chinese companies.

“This is a massive loophole that still needs to be closed,” McGuire said.

The Epoch Times reached out to TSMC for comment but did not receive a response by publication time.

Michael Sobolik, a senior fellow at Hudson Institute specializing in U.S.–China relations, raised enforcement concerns.

“This looks like an apparently MASSIVE loophole at the Department of Commerce,” Sobolik said in a May 31 post on X.

Quoting McGuire’s analysis, he questioned the effectiveness of export controls if they are not consistently enforced.

Tyler Durden
Mon, 06/01/2026 – 12:30

SpaceX IPO Update: New Filing Reveals Friends & Family Share Allocation, Anthropic AI Deal, And Water Risk

SpaceX IPO Update: New Filing Reveals Friends & Family Share Allocation, Anthropic AI Deal, And Water Risk

SpaceX has provided fresh details in an amended S-1 filing regarding its upcoming initial public offering, including a directed share program for employees and insiders, a major AI computing agreement with Anthropic, and new risk factors.

The company will reserve up to 5% of shares in its IPO for certain employees and friends and family of its executive officers. The company disclosed that participants on its “friends and family” list will not be subject to a lock-up restriction, allowing them to sell shares immediately upon listing.

While directed share programs are common in IPOs, the lack of lock-up for this group stands out. More than 60% of shares outstanding immediately prior to the offering remain subject to an extended lock-up period, including shares held by founder and CEO Elon Musk.

SpaceX stands as the preeminent launch provider globally, delivering unmatched reliability, cost-efficiency, and launch cadence. As of mid-2026, the company maintains a 100% success rate across dozens of Falcon launches this year and conducts the vast majority of U.S. orbital missions – carrying both commercial and government payloads, including NASA crew and cargo to the ISS as well as national security satellites. SpaceX’s Falcon family commands over 80% of the U.S. launch market and the bulk of global mass-to-orbit capability thanks to proven reusability. 

Jeff Bezos’s Blue Origin, meanwhile, suffered a significant setback last week, when its New Glenn rocket exploded during a static fire test at Launch Complex 36 in Cape Canaveral. The incident destroyed the vehicle and caused extensive damage to the launch pad – including collapsed lightning towers and ground infrastructure – forcing months of repairs and further delaying the company’s entry into heavy-lift competition.

Blue Origin now faces additional hurdles in catching up to SpaceX, particularly as it seeks NASA Artemis contracts and commercial missions for Amazon’s Project Kuiper.

Major AI Computing Deal with Anthropic

The amended filing also discloses that SpaceX has an agreement to provide Anthropic PBC with artificial intelligence computing capacity consisting of approximately 325,000 Nvidia chips. The deal is valued at $1.25 billion per month and runs through May 2029. After an initial three-month period, either party can terminate with 90 days notice.

SpaceX noted in its risk factors that some compute service customers may rely on external capital to meet their payment obligations.

New Risk Factor: Water Scarcity?

SpaceX added water scarcity as a formal risk factor. Drought conditions, increased competition for water sources, and potential regulatory restrictions could raise costs or limit the company’s ability to cool its data center infrastructure. This reflects growing scrutiny over the high water and power demands of AI data centers.

Bloomberg last week reported that SpaceX is now targeting a valuation of at least $1.8 trillion for the IPO vs. $2T – which Elon Musk said was “false” in response after we surfaced the claim. Either way, the IPO is more or less a major referendum on the AI-fueled bull market.

The company is targeting pricing on June 11 and a trading debut on June 12 under the ticker SPCX on Nasdaq and Nasdaq Texas.

Tyler Durden
Mon, 06/01/2026 – 10:15

“Firing On All Cylinders, But…” US Manufacturing Surveys Send Mixed Signals In May

“Firing On All Cylinders, But…” US Manufacturing Surveys Send Mixed Signals In May

With US hard data taking a beating (relative to expectations) last week (red line below), analysts remain hopeful that US Manufacturing will hold up (durable goods orders were solid) with this morning’s Manufacturing PMIs set to signal stability.

  • The final May S&P Global US Manufacturing rose to 55.1 (down from the 55.3 flash print) but the strongest since April 2022

  • ISM’s Manufacturing PMI survey also signaled improvement, up from 52.7 to 54.0 (better than 53.0 expected).

“At first glance, the manufacturing sector seems to be firing on all cylinders but lift the hood and the picture is not so clear,” says Chris Williamson, Chief Business Economist at S&P Global Market Intelligence.

The headline PMI has hit a four-year high, with strong factory production growth for a second successive month in response to a further marked upturn in order books, but since the outbreak of war in the Middle East we have seen production and demand buoyed by stock building as companies worry over rising prices and supply difficulties.

This stockpiling was again widely evident in May and makes it hard to take an accurate reading on the underlying health of the manufacturing economy, as growth will cool once this stock build has run its course,” Williamson noted.

“The incidence of supply chain delays is the highest since August 2022, with the buying of safety stocks not only adding to the supply squeeze from the closure of the Strait of Hormuz but also pushing prices higher for a wide variety of inputs.

Williamson ends on a more ominous – stagflationary – notes: warning that the resulting steep jump in producer costs sends a worrying signal that broader economy inflation has further to rise in the coming months.

Tyler Durden
Mon, 06/01/2026 – 10:08

“Working Better”: Saylor Teases BTC Buy After Strategy Sells For First Time Since 2022

“Working Better”: Saylor Teases BTC Buy After Strategy Sells For First Time Since 2022

Bitcoin is extending its recent weakness overnight (hurt by US-Iran tensions escalating again), trading back below its 100DMA after Strategy (MSTR) sold 32 bitcoin between May 26 and May 31 at an average net price of $77,135 a coin, totaling $2.5 million (disclosed in an 8-K filing on Monday).

Proceeds from the bitcoin sales are expected to be used to fund distributions on preferred stock, the firm said.

This is the first time Strategy has sold bitcoin since December 2022, when the company offloaded 704 BTC, according to onchain analyst Ai Yi.

However, the firm reportedly bought 810 BTC just two days after the sale at a lower price in a tax loss trade.

Strategy now holds a total of 843,706 BTC following the reduction – worth around $61 billion – bought at an average price of $75,699 per bitcoin for a total cost of around $63.9 billion, including fees and expenses.

In addition, for the week, Strategy raised $128.3 million through its at-the-market (ATM) common stock program and allocated a small portion of the proceeds to increase its U.S. dollar cash reserve from $871 million to $900 million.

Anticipated?

The Block.co reports that Strategy’s bitcoin sale was anticipated.

Its executives previously said during its first-quarter 2026 earnings call that it may sell some of its holdings to fund dividends for STRC, Strategy’s perpetual preferred stock designed to maintain a $100 par value and offer high yields to investors.

Saylor explained then that the sale would eventually help Strategy buy more bitcoin than it would sell to cover STRC’s dividends.

He also noted that the firm’s current position requires bitcoin to appreciate at 2.3% annually for its existing holdings to cover STRC dividend obligations indefinitely, without selling any common stock.

Today’s sale announcement comes shortly after onchain data from Arkham Intelligence showed that Strategy moved roughly 411.6 BTC from its custody account on Coinbase Prime to a cold wallet address on the platform on May 28.

This prompted the odds of Strategy selling bitcoin before the end of 2026 to surge to 84%.

Strategy also noted it has purchased 2.6 times the amount of bitcoin mined in 2026 so far, describing MSTR as a “BitVac.”

“Working Better”

But, as CoinTelegraph.com reports, before the 8-K filing was released (but after the actual sales), Strategy chairman Michael Saylor on Sunday signaled the Bitcoin treasury company would be announcing fresh purchases of the cryptocurrency in the coming days.

The social media post comes just days ahead of a proxy vote that depends in large part on retailer shareholders to enable semi-monthly dividend payouts on the company’s STRC perpetual preferred stock.

“Working Better” was Saylor’s tweet late Sunday morning to accompany a bubble chart tracking Strategy’s Bitcoin (BTC) purchases over the past nearly six years.

“Working Better” tweet. Source: Michael Saylor

That chart, from Iceland-registered StrategyTracker.com, has been consistently posted by Saylor in the days ahead of news of a purchase by the biggest publicly traded Bitcoin holder.

To be sure, any purchases to be announced will likely reflect the company bought at or below the average cost of previous BTC purchases.

Retail investors pressed to vote on STRC dividend change

Strategy is proposing to pay semi-monthly dividends on STRC, instead of monthly. The company claims that if approved and adopted, it will lead to reduced reinvestment lag, enhanced liquidity, market efficiency and increased price stability.

Just days ahead of the June 7 proxy vote deadline, Saylor and Strategy are pressing retail shareholders to return their proxy votes. On an internal company channel, Strategy’s investor relations team posted a message to all employees concerning the company’s 2026 annual meeting and provided links to the proposals under consideration by shareholders.

Part of message to Strategy employees from internal website. Source: Company filing on Edgar

“The amendment for STRC to pay semi-monthly dividends, needs 50% of all 85M shares outstanding as of April 17, 2026, to pass, which means every single vote counts,” read a May 28 post on Strategy’s verified feed on X.com.

CEO Phong Le posted a video a day earlier thanking STRC shareholders for their trust.

“I wanted to personally walk you through the proposed amendment and what it means for you,” he said as an introduction to the minute-and-a-half video.

Retail investors have shown limited interest in casting proxy votes. A November research note from The Harvard Law School Forum on Corporate Governance revealed data that showed retail investors have consistently voted only about 29% of their owned shares during the past five proxy voting seasons. Institutional holders have voted about 77%.

A Cyclical Bottom?

Bloomberg’s Andre de Silva writes that while a steep record daily capital drain in US Bitcoin ETFs exposes immediate fatigue, past precedent suggests that such severe capitulation frequently cleanses short-term positioning and signals a cyclical bottom for the digital asset.

AI infrastructure and semiconductor equities have attracted the most attention, but because Bitcoin typically retains its status as a high-beta proxy for broader risk appetite during macro expansions, this temporary diversion of capital suggests that a classic catch-up rally remains on the table.

The initial euphoria surrounding US Bitcoin ETFs has cooled, giving way to an unprecedented streak of redemptions. Investors pulled $2.96 billion from the funds over 10 consecutive trading sessions to close out May, according ETF providers. That culminated in $2.4 billion in total net outflows for the month. This sharp reversal stands in contrast to the preceding two months of healthy institutional demand, which saw combined inflows of over $3.3 billion across March and April. The late-May selling pressure spared no one, with BlackRock’s usually resilient IBIT hit by a near-record single-day redemption following a massive off-exchange block trade.

This capital flight highlights a stark divergence recently between digital and traditional risk assets.

While global stock benchmarks like the S&P 500, Nasdaq, and Asia’s top indices such as the Kospi scale new heights, Bitcoin has decoupled from the broader market rally.

Even the prospects of supportive regulation have failed to arrest the slide. This includes the Senate Banking Committee recently advancing the landmark Clarity Act to establish a formal crypto market framework, an initiative that Polymarket prices with a 55% chance of being officially signed into law this year. Instead, capital is aggressively migrating toward memory chip and semiconductor companies and, as indicted by David Savage, including Asia, leaving Bitcoin looking sluggish by comparison.

Beneath the surface, this purge of the ETF channel acts as a reliable contrarian indicator.

Historically, when US Bitcoin ETF flows hit these types of extreme negative troughs, they frequently coincided with local market bottoms.

Similar washouts during early 2025 preceded sharp, multi-month recoveries once institutional selling hit exhaustion.

While crypto sentiment has dropped into ‘Fear’ territory according to the Alternative.me Crypto Fear and Greed Index, which is a multi-factor market sentiment tracker, this cleansing of overleveraged or short-term positions might be exactly what the digital asset needs to reset and build a sustainable floor.

Tyler Durden
Mon, 06/01/2026 – 09:50

Key Events This Week: Jobs Report, JOLTS, ADP, ISMs And Fed Speakers

Key Events This Week: Jobs Report, JOLTS, ADP, ISMs And Fed Speakers

The key event for markets outside of Iran (which is once again front and center following news that Iran is halting all exchange of messages with the US in protest of Israeli crimes in Lebanon) will be Friday’s US May employment report. Economists forecast a notable moderation in payroll growth compared with the relatively strong pace seen earlier in the spring. Headline nonfarm payrolls are expected to rise by around consensus 89k, down from 115k in April, while private payrolls are forecast at roughly 89k after 123k previously. This slowing partly reflects expectations that hiring in sectors that have been particularly strong in recent months – notably transportation and warehousing, as well as retail trade – begins to cool. Unemployment is expected to remain steady at 4.3% (consensus also 4.3%). 

Ahead of Friday’s jobs report, the rest of the US labor market data flow should reinforce the Federal Reserve’s growing confidence that labor market conditions are stabilizing. Tomorrow, the April JOLTS report will shed light on the gross hiring and separation flows that underpinned last month’s solid net job gains. On Wednesday, the ADP private payrolls report is forecast to show a gain of around 118k, up from 109k previously, consistent with the strength seen in ADP’s high-frequency indicators. On Thursday, weekly initial jobless claims are expected to remain relatively low, although there is scope for a temporary uptick to around 220k, partly reflecting seasonal distortions associated with the Memorial Day holiday period. 

Beyond the labor market, the focus will also be on whether recent resilience in US economic activity is sustained. Today, the May manufacturing ISM survey is forecast to rise to around 53.0 from 52.7 in April, supported by encouraging signals from regional Fed surveys. Later in the week, Thursday’s services ISM is expected to edge higher to roughly 53.9 from 53.6. That said, the backdrop for consumer spending remains mixed. Elevated petrol prices and tariff-related increases in core goods inflation are emerging headwinds, and economists therefore expect tomorrow’s unit motor vehicle sales to remain broadly flat at around 16.0 million annualized.

Alongside the data, Federal Reserve communication will be closely watched. On Wednesday, the Fed will publish its Beige Book, offering anecdotal evidence on economic conditions across districts. Fed speak is scattered through the week but it’s mostly from officials who have spoken recently so it shouldn’t break new ground. 

Outside the US, Europe will see several important inflation releases. Today, the ECB publishes its consumer expectations survey, providing an update on household inflation views. Tomorrow, the Eurozone releases its flash CPI estimate for May, following national releases over recent days and today. Further inflation data are due on Thursday from Switzerland and Sweden, adding to the regional picture ahead of upcoming central bank meetings.

Central bank speakers are also in focus outside of the Fed. ECB President Lagarde is scheduled to speak on Thursday, while Bank of England Governor Bailey appears multiple times through the week, including tomorrow, Thursday and Friday. In Asia, Bank of Japan Governor Ueda is due to speak on Wednesday.

In China we’ve already had most of the PMIs over the weekend and this morning (see more above) but the private sector services PMI is out on Wednesday. In Japan, Friday brings labour cash earnings data. Our Chief Japan economist expects wage growth to slow to around 2.5% year on year, from 2.8% previously. Elsewhere in the region, Australia releases its Q1 GDP figures on Wednesday.

Finally, the corporate earnings calendar is also busy, with several high-profile releases. In the technology sector, results are due from Broadcom, Palo Alto Networks and CrowdStrike during the week, while consumer-focused names reporting include Inditex, Dollar General and Lululemon Athletica. See the day-by-day calendar at the end as usual for a fuller week ahead preview. 

Source: Earnings Whispers

Courtesy of DB, here is a day-by-day calendar of events

Monday June 1

  • Data: US May ISM index, April construction spending, China RatingDog manufacturing PMI, Japan Q1 Ministry of Finance’s financial statements statistics of corporations, Italy May manufacturing PMI, new car registrations, budget balance, Eurozone April M3, unemployment rate, Canada May manufacturing PMI, Switzerland Q1 GDP
  • Central banks: ECB’s consumer expectations survey, ECB’s Schnabel speaks, BoC’s Rogers speaks
  • Earnings: Meituan, HPE

Tuesday June 2

  • Data: US April JOLTS report, May total vehicle sales, UK April net consumer credit, M4, Japan May monetary base, France April budget balance, Eurozone May CPI
  • Central banks: Fed’s Kashkari and Hammack speak, BoE’s Bailey and Greene speak
  • Earnings: Palo Alto Networks, Dollar General

Wednesday June 3

  • Data: US May ADP report, ISM services, April factory orders, China RatingDog services PMI, UK May official reserves changes, Italy May services PMI, Eurozone April PPI, Canada Q1 labor productivity, May services PMI, Australia Q1 GDP
  • Central banks: Fed’s Beige Book, Fed’s Barr and Logan speak, ECB’s Elderson and Cipollone speak, BoJ’s Ueda speaks
  • Earnings: Broadcom, Inditex, Crowdstrike, Medtronic 
  • Other: OECD economic outlook

Thursday June 4

  • Data: US initial jobless claims, UK May new car registrations, construction PMI, Eurozone April retail sales, Switzerland May CPI, Sweden May CPI
  • Central banks: Fed’s Daly speaks, ECB’s Lagarde speaks, BoE’s Bailey speaks
  • Earnings: Ciena, Lululemon Athletica

Friday June 5

  • Data: US May jobs report, April consumer credit, Japan April labor cash earnings, household spending, leading index, coincident index, France April current account balance, trade balance, industrial production, Italy April retail sales, Canada May labour force survey
  • Central banks: BoE’s Bailey and Dhingra speak, BoE’s DMP survey

Looking at just the US, Goldman writes that the key economic data release this week is the employment report on Friday. There are several speaking engagements with Fed officials this week, including events with Governor Barr and Presidents Kashkari, Hammack, Logan, Barkin, and Daly.

Monday, June 1 

  • 09:45 AM S&P Global US manufacturing PMI, May final (consensus 55.3, last 55.3)
  • 10:00 AM ISM manufacturing index, May (GS 53.5, consensus 53.0, last 52.7): We estimate that the ISM manufacturing index increased by 0.8pt to 53.5 in May, reflecting convergence to the level implied by regional manufacturing surveys—our manufacturing survey tracker increased by 0.2pt to 54.9 in May.
  • 10:00 AM Construction spending, April (GS +0.3%, consensus +0.3%, last +0.6%)

Tuesday, June 2 

  • 01:50 AM Minneapolis Fed President Kashkari (FOMC voter) speaks: Minneapolis Fed President Neel Kashkari will participate in a panel discussion at the 2026 Bank of Korea International Conference. On May 29, President Kashkari—who dissented from the implicit easing bias in the April FOMC’s post-meeting statement along with Presidents Hammack and Logan—said that “it’s premature to conclude we need to be raising rates right away,” adding that “we need to keep watching the data and how the conflict in the Middle East unfolds before I want to make any adjustments.”
  • 08:30 AM Cleveland Fed President Hammack (FOMC voter) speaks: Cleveland Fed President Beth Hammack will speak on monetary policy in a moderated Q&A at the City Club of Cleveland. Speech text and audience Q&A are expected. On May 7, President Hammack said that “the statement we put out [at the April FOMC meeting] is that interest rates were on hold, but we have the signal in there that it’s more likely that the next move will be a move down,” adding that she thought “that was a little bit misleading given my view of where the economy is.” She also noted that in her baseline outlook, “interest rates will be on hold for quite some time.”
  • 10:00 AM JOLTS job openings, April (GS 7,000k, consensus 6,857k, last 6,866k): We estimate that JOLTS job openings edged up to 7.0mn in April based on the signal from online measures of job postings from Indeed and LinkUp.
  • 10:00 AM BLS releases 2025Q4 QCEW data: The Bureau of Labor Statistics will publish the 2025Q4 release of the Quarterly Census of Employment and Wages (QCEW). In the April release for personal income, the Bureau of Economic Analysis noted that downward revisions to compensation through the end of 2025 reflected the incorporation of wage and salary data from the 2025Q4 QCEW, suggesting that the employment numbers from the QCEW are likely to again suggest downward revisions to nonfarm payrolls in the next annual benchmarking.
  • 05:00 PM Lightweight motor vehicle sales, May (GS 16.3mn, consensus 16.0mn, last 15.9mn)

Wednesday, June 3 

  • 08:15 AM ADP employment change, May (GS +125k, consensus +118k, last +109k)
  • 09:00 AM Fed Governor Barr speaks: Fed Governor Michael Barr will participate in a moderated discussion at the Community Developers Bankers Association 2026 Peer Forum in Washington, DC. On May 5, Governor Barr said that “the longer [the war in Iran] goes on, the greater the risk that the inflation we are seeing in these prices becomes embedded in the economy, and then we have to worry more.” He also noted that “we are in a situation right now where we really need to wait and see to understand what direction [the conflict] is going.”
  • 09:45 AM S&P Global US services PMI, May final (consensus 50.9, last 50.9)
  • 10:00 AM ISM services index, May (GS 54.0, consensus 53.9, last 53.6): We estimate that the ISM services index edged up to 54.0 in May. Our non-manufacturing survey tracker increased slightly in May but remained below the latest ISM services reading (+0.5pt to 52.8).
  • 10:00 AM Factory orders, April (GS +5.3%, consensus +4.5%, last +1.5%)
  • 02:00 PM Fed releases Beige book, June meeting period: The Fed’s Beige Book is a summary of regional economic anecdotes from the 12 Federal Reserve districts. The Beige Book for the April FOMC meeting period noted that overall economic activity increased at a slight to modest pace in eight of the twelve Federal Reserve Districts, with two Districts reporting little change and two reporting slight to modest declines. In this month’s Beige Book, we will mainly look for anecdotes related to how consumers and firms are responding to the increase in energy prices from the conflict in the Middle East.
  • 04:00 PM Dallas Fed President Logan (FOMC voter) speaks: Dallas Fed President Lorie Logan will participate in a moderated conversation at the University of Texas at El Paso. Moderated Q&A is expected. On May 1, in a statement explaining her dissent from the implicit easing bias in the April FOMC’s post-meeting statement, President Logan said that she was “increasingly concerned about how long it will take inflation to return all the way to the FOMC’s 2% target.” She also noted that “the conflict in the Middle East raises the prospect of prolonged or repeated supply disruptions that could create further inflationary pressures.”

Thursday, June 4 

  • 08:30 AM Initial jobless claims, week ended May 30 (GS 220k, consensus 211k, last 215k); Continuing jobless claims, week ended May 23 (consensus 1,778k, last 1,786k)
  • 08:30 AM Nonfarm productivity, Q1 final (GS +0.6%, consensus +0.5%, last +0.8%): Unit labor costs, Q1 final (GS +1.7%, consensus +2.5%, last +2.3%): We estimate that nonfarm productivity growth will be revised down by 0.2pp to +0.6% quarterly annualized in the second release for 2026Q1. Since 2019Q4, labor productivity has grown at an annualized rate of 2.1%, a much stronger pace than the 1.5% average pace in the pre-pandemic cycle. We estimate that unit labor costs—compensation divided by output—will be revised down by 0.6pp to +1.7%.
  • 08:30 AM Richmond Fed President Barkin (FOMC non-voter) speaks: Richmond Fed President Tom Barkin will speak in a fireside chat at the Belmont Country Club in Ashburn, Virginia. Moderated Q&A with audience is expected. On May 21, President Barkin noted that “with inflation above our 2% target for five years now, it’s worth asking whether the cumulative impact of so many waves risks loosening the anchor [for inflation expectations].” He added that he sees policy as “well positioned” to manage risks to both the labor market and inflation.
  • 01:10 PM San Francisco Fed President Daly (FOMC non-voter) speaks: San Francisco Fed President Mary Daly will speak in a conversation at the Bloomberg Technology Summit in San Francisco. Moderated Q&A is expected. On May 29, President Daly said that “there is no urgency to make a [policy] adjustment,” as “policy is in a good place.” She added that “we need to know when the war ends and how oil prices behave afterwards” before considering further policy changes.

Friday, June 5 

  • 08:30 AM Nonfarm payroll employment, May (GS +60k, consensus +89k, last +115k); Private payroll employment, May (GS +65k, consensus +89k, last +123k); Average hourly earnings (MoM), May (GS +0.4%, consensus +0.3%, last +0.2%); Unemployment rate, May (GS 4.3%, consensus 4.3%, last 4.3%): We estimate nonfarm payrolls increased 60k in May. On the positive side, layoffs remained low between survey weeks. On the negative side, the big data indicators of job growth we track slowed and we expect a 5k decline in government payrolls—reflecting a 10k decline in federal government payrolls that is partly offset by a 5k increase in state and local government payrolls. We estimate that the unemployment rate was unchanged on a rounded basis at 4.3% in May. On one hand, continuing claims declined further between survey weeks. But on the other hand, the May unemployment rate appears to suffer from modest positive residual seasonality (the unrounded unemployment rate has increased in each of the last three Mays by an average of 0.12pp) and the bar for rounding up to 4.4% is not high from an unrounded 4.34% in April. We estimate average hourly earnings rose 0.4% month-over-month in May, reflecting positive calendar effects.
  • 12:00 PM Fed Governor Barr speaks: Fed Governor Michael Barr will speak on supervision and regulation at the Kogod School of Business in Washington, DC. Speech text and moderated Q&A with audience are expected.

Source: DB, Goldman

Tyler Durden
Mon, 06/01/2026 – 09:41

Inside The Major Bill Poised To Reshape The US Housing Market

Inside The Major Bill Poised To Reshape The US Housing Market

Authored by Andrew Moran via The Epoch Times,

The United States may be on track to implement the first comprehensive housing legislation in decades.

For the past several years, housing affordability has been a significant subject across the country, with many young people struggling to achieve the dream of homeownership.

Lawmakers on both sides of the aisle have tried to reverse the trend by advancing the 21st Century Renewing Opportunity in the American Dream (ROAD) to Housing Act of 2025.

Here is a look inside the sweeping housing package and the path to passage.

Inside the Act

Although the current administration has examined strategies to expand access to the housing market, the bipartisan legislative initiative aims to bolster supply for middle-class families.

The bill’s main provision is a limit on institutional investors’ purchases of single-family homes.

Both chambers tweaked the proposal.

The Senate approved language that requires major investors who build single‑family rental homes to sell those properties within seven years.

The House’s version still aims to rein in Wall Street’s footprint in the single‑family market, but its latest draft eases the restrictions.

Lawmakers added wider exemptions for institutional buyers of newly constructed rentals, homes needing substantial renovation, and several other categories.

Other measures aim to facilitate more construction, including incentives to build more homes, convert abandoned buildings into housing, and modernize existing homes.

In addition, Washington bolstered eligible income limits for the HOME Investment Partnerships Program, a federal block grant program that state and local governments use to build, maintain, and support affordable housing for low‑income households.

Officials created a Housing Supply Framework to enable best practices in state and local zoning and land use.

The legislative text also expands banks’ authority to make public welfare investments supporting affordable housing. The bill raises the cap for banks’ public welfare investments to 20 percent from 15 percent.

Lawmakers removed the permanent chassis requirement for manufactured homes. The long-standing federal rule required that manufactured homes be constructed on a permanent steel frame to qualify under the federal construction code.

It also includes the Modular Housing Production Act and other reforms to streamline the production of factory-built housing.

There was also some focus on the demand side of the equation. For example, the bill establishes incentives for mortgage lenders to originate small-dollar mortgages—typically less than $100,000—to address the financing gap for low-cost homes. Additionally, Congress updated rules on appraisal standards and fees for these small-dollar loans.

The 21st Century ROAD to Housing Act includes reforms to Veterans Affairs housing policies. The major changes include expanding access to Veterans Affairs home loans, improving consumer protections for borrowers, and enhancing housing support for disabled and homeless veterans.

Congressional Path

Unlike other pieces of legislation, the housing affordability bill has moved quickly through Congress—something that President Donald Trump had requested.

Rep. French Hill (R-Ark.), chairman of the House Financial Services Committee, introduced legislation in December 2025. Two months later, it passed 390–9 in the lower chamber.

As it arrived in the upper chamber, senators made substitutions rather than take up the House bill. The amended legislation passed 89–10 and was sent back to the House, where it passed 396–13.

It will now be delivered to the Senate for final approval.

Senate Banking Committee Chairman Tim Scott (R-S.C.) and Ranking Member Elizabeth Warren (D-Mass.) said the bipartisan housing bill will provide relief for families nationwide.

“We worked closely with the White House and our colleagues in both chambers on a bill that puts families first and addresses the housing crisis,” they said in a May 20 joint statement.

“There’s still work to be done and we are committed to continuing to work with the White House and our colleagues in the House on a housing bill that can pass the Senate and get to the president’s desk.”

What the Industry Says

The housing industry widely lauded Congress for moving ahead with the legislation.

Shortly after the House passed the bill, the National Association of Home Builders noted that it addresses several problems facing Americans today, mainly housing shortages and affordability challenges.

“The bottom line is that the housing crisis is a supply problem,” Bill Owens, the group’s chairman, said in a statement.

“Congress can help by improving access to capital, strengthening workforce pipelines, expanding the availability of buildable lots and reducing excessive regulatory costs and permitting delays.

“If we want to make housing more attainable, we must make it easier and less expensive to build.”

Emily Cadik, CEO of the Affordable Housing Tax Credit Coalition, stated that increasing the banks’ public welfare investment cap to 20 percent will “unlock billions of dollars in new private investment.”

“Additional changes in the updated House legislation will further strengthen our ability to finance more affordable housing to address our nation’s immense need,” Cadik said in a statement.

The House passing the Senate’s amended version would both enhance housing supply and expand access to affordable mortgage credit, said Bob Broeksmit, president and CEO of the Mortgage Bankers Association.

“[The legislation] will help advance meaningful housing affordability solutions for our nation’s homeowners and renters,” he said.

Tyler Durden
Mon, 06/01/2026 – 09:35

SK Hynix Evacuates Thousands Of Workers At Chip Plant After Fire, Toxic Gas Leak

SK Hynix Evacuates Thousands Of Workers At Chip Plant After Fire, Toxic Gas Leak

One week, unions are threatening labor action at memory giant Samsung. The next, SK Hynix suffers an industrial accident. Together, the events highlight just how fragile the global memory supply chain has become at a time when AI data center buildouts have already pushed memory chip supply into extraordinarily tight territory.

South Korea’s main national wire service, Yonhap News Agency, reports that SK Hynix, the world’s second-largest DRAM producer, evacuated about 3,600 workers from its Cheongju semiconductor factory in South Korea after a fire and toxic gas leak.

The fire erupted Monday mid-morning in a sixth-floor gas room connecting the M15 and M15X plants and was quickly extinguished by the factory’s fire suppression system. Seven people were injured.

SK Hynix believes the incident may have originated from a gas pipeline, adding that production lines for critical memory chips were not impacted.

SK Hynix is one of the world’s top three memory chip companies, alongside Samsung and Micron. It controlled about 32% of the DRAM market in 4Q25, behind Samsung at 36% but ahead of Micron at 22.4%, according to TrendForce data.

This means that if the industrial accident had been more severe, any real production disruption at SK Hynix could have sparked a surge in DRAM prices. In other words, SK Hynix is a bottleneck supplier for the AI trade.

Our report early last week added to optimism in the DRAM and NAND memory chip markets because there is new evidence that China is flooding the chip market.

The Amazon price-tracking website CamelCamelCamel shows that retail pricing for DDR5 64GB memory chips dropped from $925 to about $853 in late May. Prices were around $200 one year ago.

We first outlined that hoarded supplies would begin to hit the market in late March.


Tyler Durden
Mon, 06/01/2026 – 07:20
