58.1 F
Chicago
Tuesday, September 29, 2026
Home Blog Page 806

Colombia & Brazil Bolster Armed Forces At Borders, Bracing For Venezuelan Refugee Influx

0
Colombia & Brazil Bolster Armed Forces At Borders, Bracing For Venezuelan Refugee Influx

After the weekend US military action in Venezuela, which triggered mixed reactions around the globe, Colombia and other nations in the region are preparing for a possible influx of refugees.

Sunday saw Colombian Defense Minister Pedro Sanchez order the deployment of 30,000 troops to the Venezuelan border to strengthen security, and this move coincided with putting emergency measures in place to assist displaced civilians.

Getty Images

There’s been a much heavier military presence, for example, at the key Simon Bolivar International Bridge over the Tachira River linking Colombia and Venezuela near the border city of Cucuta. Colombian military armor has been observed there, according to regional reports.

However, these same reports say traffic has moved normally there, despite the extra security measures. Colombia had condemned the Trump-ordered action to capture Venezuela’s Maduro, in part worried about a potentially destabilizing effect on the region.

Defense chief Sanchez has confirmed that security forces had been “activated” to deter any retaliatory actions by armed groups such as the National Liberation Army (ELN) and Segunda Marquetalia, both which have operated largely unchecked inside Venezuela for years.

But without doubt Colombia’s own armed groups have long exploited the rugged 1,300+-mile long frontier with Venezuela for drug trafficking and as a sanctuary from Colombian military operations.

Brazil too is bracing, after for years regional countries had to deal with millions of Venezuelans leaving their country and spiraling economy. The Wall Street Journal describes, “Roraima, the Brazilian state that serves as the main crossing point into the country, closed its border with Venezuela early Saturday, while Colombian President Gustavo Petro said he had deployed security forces at the country’s border in case of a ‘massive influx of refugees.'”

“Some eight million Venezuelans have already fled their country in recent years, equivalent to about a quarter of the country’s population, putting pressure on public services in border regions and sparking xenophobic attacks,” the report notes.

There are fears that there could be some kind of new internal fighting erupt in Venezuela, after Maduro’s now former Vice President Delcy Rodríguez was sworn in as president. A fresh insurgency, or also counter-revolution, could emerge – but so far Caracas has remained relatively stable, with Trump telling new President Rodríguez to “behave”.

But there are already reports that the new leader is reverting to tactics of the old, with several Tuesday headlines stating Venezuela launches wave of repression after US seizure of Nicolás Maduro.

via Wiki Commons

And a further source describes, “As the government continued to churn inside the presidential palace Miraflores, Venezuela’s military counterintelligence officials have been patrolling the streets of Caracas, according to at least two witnesses.

“At least seven journalists and members of the press were detained on Monday morning and early afternoon, most of them at the National Assembly and its surroundings, according to the national press workers syndicate,” the report adds, before detailing further: “Heavily armed security forces and pro-government motorcycle gangs known as colectivos were seen roaming the capital, at times stopping drivers and checking their phones. While they aren’t as influential as they were at the height of Maduro’s power, the State Department has said they have been responsible for killings during protests.”

Tyler Durden
Tue, 01/06/2026 – 08:45

Global Stock Rally Fizzles, Futures Flat As Market Rotations Accelerate

0
Global Stock Rally Fizzles, Futures Flat As Market Rotations Accelerate

US equity futures are flat with small caps underperforming as geopolitics dominate headlines, including aftershocks from the Maduro seizure and a potential US/EU deal that provides a security guarantee for Ukraine potentially with American soldiers maintaining a presence in Ukraine. As of 8:00am ET, S&P futures are flat as a rotation into regional shares broadened and investors awaited fresh data to gauge the outlook for Federal Reserve interest rates; Nasdaq futures gain 0.2% even as Mag 7 names are weaker premarket ex-NVDA which is leading Semis higher after Jensen Huang’s CES presentation. Futures took a brief spill overnight just around 3am ET when China announced it would launch export controls on Japan, which is negative for heavy machinery; futures then promptly recovered. Defensives are leading Cyclicals ex-Energy. Bond yields are higher by 1-2bp with USD also bid. Major European markets are mixed with UK leading and France lagging. Asian stocks are off to their best start since 2012 with the MXAP up 3% YTD. Today’s US economic calendar includes December final S&P Global US services and composite PMIs at 9:45am. Scheduled Fed speakers include Barkin (8am) and Miran (8:30am)

In premarket trading Mag 7 names are mixed, with Nvidia gaining 0.6% as CEO Jensen Huang said the company’s much-anticipated Rubin data center processors are in production and customers will soon be able to try out the technology.(Alphabet +0.2%, Microsoft is flat, Amazon -0.08%, Meta +0.9%, Apple -0.3%, Tesla -0.6%).

  • Aeva (AEVA) jumps 23% after the company announced that its 4D LiDAR technology has been selected for the Nvidia Drive Hyperion autonomous vehicle reference platform.
  • Core Scientific (CORZ) climbs 4% as BTIG upgrades to buy as the dust settles following shareholder rejection in October of its acquisition by CoreWeave.
  • Frontier Group (ULCC) falls 3% after BofA cut the recommendation on the airline to underperform, expecting cost challenges in 2026 as aircraft rental fees rise.
  • Microchip (MCHP) rises 4% after the analog chipmaker’s net sales forecast for the third quarter beat the average analyst estimate. Analysts note that the strong sales numbers highlight broad-based recovery.
  • Oculis (OCS) rises 8% after the drug developer said its experimental therapy, Privosegtor, was granted the FDA’s breakthrough therapy designation for the treatment of optic neuritis — inflammation of the eye nerve.
  • OneStream Inc. (OS) soars 22% as buyout firm Hg is in advanced talks to acquire the financial software maker, according to people familiar with the matter.
  • Vistra Corp. (VST) climbs 4% after agreeing to pay roughly $4 billion for 10 natural gas-fired power plants in the US Northeast and Texas to expand the electricity supplier’s generation capacity in fast-growing energy markets.
  • Zeta Global (ZETA) rises 9% after the software company announced that it has entered a strategic collaboration with OpenAI to power conversational intelligence and agentic applications behind Athena by Zeta, its superintelligent agent built for enterprise marketing.

In other corporate news, AB InBev will reacquire a 49.9% stake in US metal plants from a consortium of investors for $3 billion. Electricity supplier Vistra agreed to pay roughly $4 billion for 10 natural gas-fired power plants in the US Northeast and Texas. Software company Zeta Global announced a strategic collaboration with OpenAI.

The New Year rally appears to be losing steam, despite renewed appetite for the AI trade and cyclicals over defensives. Some of the biggest action is in commodities, with an index of base metals surging to the highest since March 2022 and copper rising above $13,000 a ton for the first time, which needless to say, is and will be inflationary. At the same time, stocks in Asia surged, but as Bloomberg notes, are now getting dangerously overbought, along with markets in Europe and emerging markets. The S&P 500’s 14-day relative strength index also suggests that US stocks might have further room to run, in contrast with other regions that have surpassed levels typically seen as overbought. Macro and geopolitical risks are numerous, with Venezuela, Greenland and Taiwan all in the headlines today. 

Stock investors have so far been largely unfazed by tensions in Venezuela, extending a three-year bull run that’s been fueled by demand for AI–linked shares. The next leg of the rally will depend in part on how quickly the Fed moves to further ease monetary policy, with business activity and jobs market data due this week to help shape rate expectations.

“We are waiting for data,” said Emilie Tetard, a cross-asset strategist at Natixis. “Before this data, as macro uncertainty is probably stronger in the US vs. the rest of the world, it’s a good time to put in place the diversification.”

Meanwhile, US oil producers such as Chevron Corp. and ConocoPhillips extended gains on President Donald Trump’s plans for the reconstruction of Venezuela’s crude industry.

The AI narrative is getting a boost from announcements at CES. AMD unveiled a new chip for corporate data centers, with CEO Lisa Su noting on AI that “we don’t have nearly enough compute for what we could possibly do.” Nvidia CEO Jensen Huang said the company’s highly-anticipated Rubin processors are on track for deployment by customers in the second half. “Demand is really high,” he said. And Intel’s comeback bid is relying on laptops shown at CES that are based on processors with a new design. As Bear Traps report Larry McDonald puts it, “the Pumpmaster is on Stage Again”: Nvidia CEO Huang keynote address confirmed that Vera Rubin is now in full production and is expected to propel Nvidia back into the position of undisputed technical leader. Jensen noted that Vera Rubin contains 6 separate, revolutionary chips, and in years past, each one would have been made by a separate company, but Nvidia does them all itself. 

In the geopolitical sphere, Venezuela’s new acting president Delcy Rodríguez is seen as a choice that could stabilize Venezuela’s oil-based economy and facilitate American business. Elsewhere, Trump’s rationale for intervening in Venezuela is fueling concerns among European officials that they could soon face an existential dilemma over Greenland.

Elsewhere, the data may be on the side of bulls. According to Bloomberg, there have been just four years when the S&P 500 fell at least 15% and and still managed to achieve an annual advance of 15% or more. It happened in 1982, 2009, 2020 — and in 2025. The previous cases have all been followed by strong gains during the next year. Still, Wall Street bulls need a lot to go right if 2026 is going to deliver a fourth straight year of double-digit returns. Read more in today’s Taking Stock.

European stocks are mixed regionally, with the broad Stoxx 600 higher by 0.2%; health care leads, tech lags while miners are lifted after copper surged to a fresh record amid a renewed rush to ship the base metal to the US. Consumer products and services shares lag, with Adidas tailing the sector. Here are some of the biggest movers on Tuesday:

  • InPost shares rise as much as 20% after the Polish logistics firm announced it had received an indicative proposal regarding a potential acquisition.
  • Next shares climb as much as 3.7%, the most since October, after the fashion retailer reported strong Christmas sales and boosted its profit guidance for the fifth time this financial year.
  • Tesco shares climb as much as 3.4% after Worldpanel by Numerator said the British grocer had increased sales and market share in the run-up to Christmas, taking its greatest slice of shoppers’ spend in more than a decade.
  • Daimler Truck shares rise as much as 5.6%, hitting the highest level in four months, after the release of positive data for a key measure of North American truck orders.
  • SMG Swiss Marketplace Group shares surge as much as a record 17%, after it announced an “amicable” agreement with Switzerland’s Price Supervisor regarding investigations into the Ricardo platform and SMG Real Estate business.
  • Infineon shares rise as much as 5.1% after US peer Microchip gave an upbeat forecast and Bank of America lifted its price target, partly due to AI server exposure.
  • Adidas shares fall as much as 7.6% after Bank of America downgraded the stock to underperform, predicting a “material stepdown” in growth for the sportswear sector. Retailer JD Sports was cut to neutral, and its shares fall 7.2%.
  • DSM-Firmenich shares drop as much as 1.3% after Morgan Stanley downgraded the stock to equal-weight, citing lingering uncertainty around the animal, nutrition and health exit structure and tough mid-term strategic targets for the core business.
  • Liontrust Asset Management shares sink as much as 7.7%, the most in six months, as Deutsche Bank analysts cut their recommendation on the firm to sell from hold, and slash the target price by a third.

“It reflects a continuation of a theme that we are in the early innings of, which started last year, i.e. that US exceptionalism has peaked and has started to unwind,” Raymond Sagayam, managing partner at Banque Pictet & Cie SA, told Bloomberg TV.

Asian equities rose to a fresh record high, with a rally in Chinese shares helping fuel stronger risk appetite for the region. The MSCI Asia Pacific Index advanced 1.2%, poised for a fourth straight day of gains in what is poised to be its best-ever start to a year. Tech again remained a focus, with TSMC, SK Hynix and Hitachi among the biggest contributors to the benchmark’s advance. Key gauges in mainland China, Hong Kong as well as Japan rose more than 1%. China’s onshore CSI 300 Index climbed to the highest in four years on enthusiasm for the country’s AI industry and growing signs of an economic recovery. Investors hope for an extension of last year’s gains as Beijing backs key sectors and implements measures to curb excessive competition and revive the ailing property market. A subindex of financial shares also helped boost the Asian benchmark, after US peers climbed overnight. Japanese banks jumped after central bank Governor Ueda said he intends to keep raising rates in line with inflation. The rally in Asian stocks at the start of the year underscores their rising appeal for global investors wary of high tech valuations in the US and the prospect of a weakening dollar. It also points to the room left to run in the region’s tech shares, with Samsung Electronics Co. and Taiwan Semiconductor Manufacturing Co. powering the gains over the past few days.

In FX, German inflation weighed on the euro, lifting the Bloomberg Dollar Index higher by 0.1%. G-10 FX moves are limited.

In rates, treasuries hold small losses in early US session, unwinding a portion of Monday’s gains with oil futures rising further and stock index futures stalled near record highs. European bonds outperform following soft German regional inflation prints. US yields are 1bp-2bp cheaper with curve spreads steeper; 2s10s topped 72bp, approaching 2025 wides; 10-year near 4.17% is about 1bp cheaper on the day, with bunds and gilts in the sector outperforming by about 3bp. German yields are lower by around 2bps across the curve following soft regional inflation metrics. In contrast, US yields are higher with the curve bear-steepening.

In commodities, WTI crude futures are building on yesterday’s gains, up 0.3%. There’s mixed fortunes for precious metals with spot silver higher by 2.2%. Gold faded initial gains and is now up just 0.2% while LME copper hit further all-time-highs, up 1.3%.Bitcoin has slipped throughout the session, trades lower by 0.4%. 

US economic calendar includes December final S&P Global US services and composite PMIs at 9:45am. Scheduled Fed speakers include Barkin (8am) and Miran (8:30am)

Market Snapshot

  • S&P 500 mini little changed
  • Nasdaq 100 mini +0.2%
  • Russell 2000 mini -0.3%
  • Stoxx Europe 600 little changed
  • DAX little changed, CAC 40 -0.6%
  • 10-year Treasury yield +1 basis point at 4.17%
  • VIX +0.3 points at 15.15
  • Bloomberg Dollar Index little changed at 1203.74
  • euro little changed at $1.1715
  • WTI crude +0.2% at $58.43/barrel

Top Overnight News

  • China imposed controls on exports to Japan that could have military use, intensifying a dispute between Asia’s top economies over remarks Japanese PM Sanae Takaichi made last year on Taiwan. BBG
  • Trump asked Marco Rubio to oversee an economic and political overhaul of Venezuela, leading a team that includes officials working on energy, finance and military police, White House adviser Stephen Miller said. BBG
  • In late night Truth Social post, Trump announced that Danish territory is now an American “protectorate.” Denmark and the broader NATO alliance are extremely concerned the US could imminently seize Greenland and paralyze the NATO alliance. The Atlantic
  • Trump said he believes the U.S. oil industry could get expanded operations in Venezuela “up and running” in fewer than 18 months. “A tremendous amount of money will have to be spent, and the oil companies will spend it, and then they’ll get reimbursed by us or through revenue,” he said. NBC
  • Nvidia’s Rubin data-center chips are now in production as strong AI demand drives the need for more powerful systems, CEO Jensen Huang said. Rival AMD unveiled a new AI chip for corporate data-center use. BBG
  • Nvidia said it has seen strong demand from customers in China for the H200 chip that the Trump administration has said it will consider letting the chipmaker ship to that country. BBG
  • The Trump admin is planning to meet with executives from U.S. oil companies later this week to discuss boosting Venezuelan oil production. The meetings are crucial to the administration’s hopes of getting top U.S. oil companies back into the South American nation. RTRS
  • MCHP +430 bps in premkt after issuing its second upside preannouncement of the quarter, indicating potential recovery in demand for industrial and automotive chips.
  • Trump is scheduled to deliver remarks at a GOP member retreat at 10:00am ET on Tuesday and will participate in a policy meeting at 2:30pm ET. 
  • Trump posted “Pregnant Women, DON’T USE TYLENOL UNLESS ABSOLUTELY NECESSARY, DON’T GIVE TYLENOL TO YOUR YOUNG CHILD FOR VIRTUALLY ANY REASON, BREAK UP THE MMR SHOT INTO THREE TOTALLY SEPARATE SHOTS”. Full post “Pregnant Women, DON’T USE TYLENOL UNLESS ABSOLUTELY NECESSARY, DON’T GIVE TYLENOL TO YOUR YOUNG CHILD FOR VIRTUALLY ANY REASON, BREAK UP THE MMR SHOT INTO THREE TOTALLY SEPARATE SHOTS (NOT MIXED!), TAKE CHICKEN P SHOT SEPARATELY, TAKE HEPATITAS B SHOT AT 12 YEARS OLD, OR OLDER, AND, IMPORTANTLY, TAKE VACCINE IN 5 SEPARATE MEDICAL VISITS! President DJT”.

Trade/Tariffs

  • China Commerce Ministry imposes export controls on dual-use items to Japan, effective immediately

A more detailed look at global markets courtesy of Newsquawk

APAC stocks were mostly higher following the positive handover from Wall Street, where all major indices gained amid outperformance in energy and a softer yield environment. ASX 200 was the laggard with the index dragged lower by weakness in defensives and the top weighted financial sector, while metal and mining stocks were boosted after the recent climb in underlying commodity prices and reports of an AUD 8.8bln takeover offer for BlueScope Steel. Nikkei 225 rallied at the open to back above the 52,000 level with the advances led by mining and tech-related stocks. Hang Seng and Shanghai Comp conformed to the predominantly upbeat mood, with outperformance in Hong Kong helped by strength in some property names and miners, while aluminium producer China Hongqiao Group led the advances as aluminium prices printed fresh three-year highs.

Top Asian News

  • Japan sold JPY 1.96tln 10yr JGB, b/c 3.30x (prev. 3.59x), average yield 2.095% (prev. 1.872%). Lowest accepted price 99.99 vs prev. 98.53. Average accepted price 100.04 vs prev. 98.57. Tail in price 0.05 vs prev. 0.04.
  • Japan’s nuclear regulator said no irregularities at Chugoku Electric’s (9504 JT) Shimane nuclear power plant following the earthquake.
  • Earthquake with a preliminary magnitude of 6.3 strikes at the Shimane Prefecture in Japan, according to NIED

European bourses (STOXX 600 U/C) opened with very modest gains, but have indices have since slipped a touch off best levels to show a bit more of a mixed picture in Europe. European sectors are mixed, with Health Care, Energy, and Basic Resource leading. Energy is advancing on higher crude prices, despite the absence of a clear catalyst. On a stock-specific basis, the sector is also being supported by gains in heavyweight names such as Shell (+1.6%) and BP (+1.9%). Meanwhile, sentiment in Basic Resources has been underpinned by strength in metal prices.

Top European News

  • ‘Coalition of the Willing’ to discuss security guarantees for Ukraine

FX

  • DXY resides in a narrow 98.161-98.425 range after recovering from worst levels on the back of some EUR softness (more below), although price action across FX thus far has been muted vs other markets (Equities, Fixed Income, Commodities). The US docket for today only consists of S&P Services and Composite Final PMIs alongside commentary from Fed’s Barkin and Miran. Perhaps more importantly, US President Trump is due to give remarks later today.
  • EUR is on a softer footing, with early weakness commencing shortly after the revisions lower to the French PMIs, whilst downward revisions in German Composite and EZ PMIs further weighed on the single currency. Moreover, German State CPIs were more dovish than the Nationwide figure (at 13:00 GMT) implies. EUR/USD resides towards the bottom end of a 1.1708-1.1743.
  • GBP/USD trades flat towards the bottom of a 1.3528-1.3568 range with little immediate move seen on the slight revision higher in UK Services and Composite PMIs, with EUR/GBP flat intraday in a narrow 0.8644-0.8660. USD/JPY is also flat in a 156.17-156.80 range and largely trading at the whim of the USD.
  • Antipodeans also see little price action but AUD continues to be supported by the recent rally in copper and gold.

Fixed Income

  • Benchmarks began the morning on the backfoot, with downside of around five and 20 ticks for USTs and Bunds respectively. Action that came as the benchmarks trimmed into and through the APAC session, with further pressure emanating from weak demand at the Japanese 10yr tap; an auction that sent JGBs lower from 132.23 to a 131.93 session trough, trimming initial gains of around 15 ticks to losses of 16 at worst.
  • Since, the complex generally benefited incrementally from a dip in the risk tone as China imposed export-controls on dual-use items to Japan.
  • For EGBs, no real move to the French Prelim. HICP metrics, which came in as expected M/M and slightly cooler than expected Y/Y at 0.7% (prev. 0.8%). More pertinently, the German State CPIs ahead of the 13:00GMT nationwide figure, where consensus is for the headline Y/Y to moderate to 2.0% (prev. 2.3%) and the HICP Y/Y to 2.2% (prev. 2.6%); for the respective M/M, at 0.3% (prev. -0.2%) and 0.4% (prev. -0.5%). State CPIs lifted Bunds to a 127.67 high, firmer by 27 ticks at most. A move perhaps driven by the M/M for North Rhine-Westphalia coming in at 0.0% (prev. -0.3%), cooler than the nationwide expectations, as above, for a lift to 0.2% (prev. -0.2%).
  • Ahead, USTs look to remarks from Fed’s 2027 voter Barkin, text and Q&A expected, before the region’s own Final PMIs.
  • Germany sells EUR 4.4547bln vs exp. EUR 6bln 2.00% 2027 Schatz: b/c 1.93x (prev. 1.7x), average yield 2.11% (prev. 2.05%), retention 24.22% (prev. 20.82%).

Commodities

  • Crude benchmarks started the APAC session on the backfoot, paring back some of Monday’s gains before extending higher as the European session gets underway, despite a lack of crude-specific drivers.
  • WTI and Brent pulled back to a low of USD 57.85/bbl and USD 61.31/bbl respectively after peaking at USD 58.51/bbl and USD 61.89/bbl in Monday’s session. Benchmarks then bid higher pretty aggressively despite a clear explanation for the move, reaching a session high of USD 58.67/bbl and USD 62.14/bbl before pulling back slightly.
  • Spot XAU trades choppy but managing to hold onto modest gains as the yellow metal sits above USD 4450/oz. After dipping to a trough of USD 4428/oz early in the APAC session, XAU extended on Monday’s gains to peak at USD 4476/oz as European traders entered the market. Thus far, the yellow metal is trading in a tight USD 26/oz band above USD 4450/oz.
  • 3M LME Copper continued its bid to new ATHs throughout the Asia-Pac session, following the risk-on tone in Asian equities. The red metal opened at USD 13.1k/t and immediately bid higher, peaking at USD 13.39k/t as the European session gets underway. As equities started to pull back, led by Nikkei 225 futures, following the imposition of export controls on dual-use items to Japan by China, 3M LME Copper has started to fall lower and is currently trading at USD 13.24k/t.
  • China skips retail gasoline and diesel price adjustment.
  • Goldman Sachs said Chinese steel mills face an extended period of depressed margins as efforts to cut capacity in the sector goes slower than expected, while exports remain high.
  • ANZ said Venezuela oil output increase is unlikely until the end of the decade as aging infrastructure will require billions of dollars in spending, according to Bloomberg.
  • Morgan Stanley expects another period of softness for crude ahead, Brent to fall into the mid-high USD 50/bbl region for the majority of 2026. Expect the market to be in a “significant” surplus before then returning to balance in H2-2027.

Geopolitics

  • “Syria: Israeli forces infiltrate the southern countryside of Quneitra”, according to Al Arabiya.
  • Israeli Air Force struck multiple sites in Lebanon on Monday and early Tuesday, ahead of a key disarmament meeting, according to POLITICO.
  • North Korea accuses Japan of reinvasion plotting over record-high defence budget, according to Yonhap.
  • Shooting reported near presidential palace in Caracas, although Venezuelan government said situation is under control.
  • US House Speaker Johnson said not expecting US troops on the ground in Venezuela, according to Bloomberg’s Erik Wasson.
  • Witnesses reportedly heard loud blasts near the Presidential Palace in Caracas, Venezuela, according to Bloomberg’s Erik Wasson.
  • Al Jazeera notes report of Israeli raid on vicinity of southern Lebanese town of Al-Ghaziyah.
  • US President Trump has a list of demands for Venezuela’s new leader including stopping oil sales to US rivals, according to POLITICO. “U.S. officials have told Delcy Rodriguez that they want to see at least three moves from her: cracking down on drug flows; kicking out Iranian, Cuban and other operatives of countries or networks hostile to Washington; and stopping the sale of oil to U.S. adversaries”.
  • US President Trump said Venezuela has to be fixed before elections and that acting President Rodriguez has been cooperating with the US, while Trump’s advisor Miller said Venezuela is cooperating with the US and needs US permission to do any commerce. said:. US may subsidise an effort by oil companies to rebuild the country’s energy infrastructure. Would not need lawmakers to act in order for him to send US troops back into Venezuela.
  • CIA reportedly concluded that Venezuela’s Maduro regime loyalists were best placed to lead Venezuela after Maduro, according to WSJ.

US Event Calendar

  • 8:00 am: Fed’s Barkin Speaks on Economic Outlook
  • 8:30 am: Fed’s Miran Speaks on Fox Business
  • 9:45 am: Dec F S&P Global U.S. Services PMI, est. 52.9, prior 52.9
  • 9:45 am: Dec F S&P Global U.S. Composite PMI, prior 53

DB’s Jim Reid concludes the overnight wrap

Happy NY to you from me for my first EMR of the year after 10 days in the Alps where my back stopped me from skiing, but the family just about managed to find enough snow to do so. Just 29 years after its release I watched Titanic for the first time during the trip, and Shaun the Sheep. Shaun the Sheep is very funny, Titanic less so.

From nautical disasters to economic ones, yesterday I published a short chart pack (link here) which documents the remarkable long-term decline of the Venezuelan economy, with a particular focus on the sharp deterioration since the early 2010s. In terms of other pieces, our new Head of Geopolitcal Research Helen Belopolsky in my team published a

quick note here on what the story tells us about Trump 2.0 in 2026 and our LatAm economist Francisco Campos published a blog here on the implications for the region.
So, in a fascinating start to the year, developments in Venezuela continued to dominate the headlines yesterday, as investors were finally able to react to the removal of President Nicolás Maduro. But for global markets, the striking thing was how most assets were almost completely unfazed by the geopolitical risk. The S&P 500 (+0.64%) closed -0.43% beneath its record high, and Europe’s STOXX 600 (+0.94%) hit a fresh record. And despite an uptick in oil prices (reversing the small dip at the Asian open yesterday), there was even a bond rally on both sides of the Atlantic too, as a weak ISM manufacturing print pushed yields lower for 10yr Treasuries (-3.0bps) and bunds (-3.0bps). 

In terms of the latest, Maduro appeared in a New York court yesterday, pleading not guilty to drug trafficking and other charges and claiming “I am still president”. Meanwhile, in Venezuela Delcy Rodríguez was sworn in as interim president, calling for peace in the country. Overall, this left a sense that a smooth transition was playing out for now, though there were reports of some explosions in Caracas last night. 

Whilst global markets saw little reaction to the Venezuela developments, a few specific assets did see some outsized moves. Most obviously, there was a clear reaction among Venezuela’s bonds, with those maturing in 2027 surging by +29.28% on the day, moving up to 42.5 cents on the dollar. Another beneficiary were US oil stocks, and energy companies in the S&P 500 were up +2.67% yesterday. That included Chevron (the only major US oil company still operating in Venezuela), which posted a +5.10% increase, alongside big jumps for oil services majors SLB (+8.96%) and Halliburton (+7.84%). Last night, Trump suggested the administration might subsidise investment to rebuild Venezuela’s oil production and, according to Bloomberg, Energy Secretary Chris Wright plans to meet with oil executives this week. Meanwhile, precious metals also saw the usual uptick we normally get in times of geopolitical stress, with gold (+2.70%) and silver (+5.18%) prices experiencing strong gains as well. Silver continuing its stunning gains from recent weeks.  

Against this backdrop, oil prices had a topsy-turvy session, swinging between gains and losses through the day. Initially when markets opened, there had been optimism that Maduro’s removal would open the way for higher oil production, particularly if US companies went in to repair the infrastructure as Trump had indicated. So that meant Brent crude initially fell beneath $60/bbl, down -1.65% from its closing level on Friday. But as the session went on, those initial hopes were tempered by the realisation that it would be difficult to rebuild that infrastructure quickly, and without significant cost. In the near-term there may even be disruption to the current Venezuelan supply, forcing normal buyers to quickly purchase elsewhere. So oil prices clawed back those losses to close up +1.66% at $61.76/bbl. In Asia it’s down around -0.3%. 

In the meantime, there’s also been renewed focus on Greenland, given Trump’s weekend comments that “We need Greenland from the standpoint of national security”. That led to a response from Danish PM Mette Frederiksen yesterday, who said she took Trump’s threats seriously, and that “if the US chooses to attack another NATO country militarily, then everything stops, including NATO”. 

Whilst there were plenty of geopolitical developments, global equity and bond markets took those in their stride yesterday, with a cross-asset advance on both sides of the Atlantic. In part, that was down to a softer-than-expected ISM manufacturing print in the US, which raised hopes that the Fed would keep cutting rates this year. The headline measure for that fell to a 14-month low of 47.9 in December, and both the new orders (47.7) and employment (44.9) components were also clearly in contractionary territory. Prices paid (58.5) were within a couple of tenths of expectations. Fed funds futures were pricing in 60bps of cuts by the December 2026 meeting at the close, up +2.2bps compared with Friday. And in turn, US Treasuries rallied across the curve, with the 2yr yield (-2.2bps) down to 3.45%, whilst the 10yr yield (-3.0bps) fell to 4.16%. Overnight, they are back up +1.2bps and +2.0bps respectively. 

The prospect of faster rate cuts and the absence of a negative shock from the Venezuela developments meant it was also a good day for equities. Indeed, the S&P 500 (+0.64%) moved back within half a percent of its record high on Christmas Eve. The Dow Jones (+1.23%) reached a new record high of its own, with the small cap Russell 2000 (+1.58%) also surging as cyclical stocks outperformed. And the Mag-7 (+0.88%) rebounded after a run of 5 consecutive losses. Meanwhile in Europe, there were a whole bunch of records, with the STOXX 600 (+0.94%) and the DAX (+1.34%) both closing at record highs, whilst Italy’s FTSE MIB (+1.04%) closed at its highest level since 2000.

Otherwise in Europe, Bloomberg reported yesterday that Italy planned to support the EU free-trade agreement with Mercosur. The article said that they’d back the deal when ambassadors vote on January 9, enabling the EU to sign on January 12. Meanwhile, sovereign bonds also rallied across the continent, with 10yr bund yields (-3.0bps) coming down to 2.87%, moving off their two-year high on Friday.

In Asia, equity markets are on course for their best start to a year since 2012. As I check my screens, the Hang Seng (+1.64%), Shanghai Comp (+1.19%), Nikkei (+1.09%) and the KOSPI (+0.93%) are all leading the way.  Japan’s Topix is surging +1.46% to reach a record high, bolstered by widespread gains in technology, industrial, and export-oriented sectors. S&P 500 (+0.13%) and NASDAQ 100 (+0.24%) futures are both inching higher along with European futures.  

10-year JGBs are +1.4bps at 2.123%, marking its highest point since 1999, after an auction that went ok. The bid-to-cover ratio was recorded at 3.30, in contrast to 3.59 from the last auction and a 12-month average of 3.24. 30-year JGB yields are up +3.9bps.  

Looking at the day ahead now, the main data releases will be the German and French CPI prints for December, along with the final services and composite PMIs for December from the US and Europe. Otherwise, central bank speakers include the ECB’s Villeroy and Cipollone, along with the Fed’s Barkin.


Tyler Durden
Tue, 01/06/2026 – 08:36

EU’s Carbon Border Tax Goes Live And Trade Partners Are Not Amused

0
EU’s Carbon Border Tax Goes Live And Trade Partners Are Not Amused

Authored by Irina Slav via OilPrice.com,

  • The EU’s carbon border adjustment mechanism launched on January 1 aims to level the playing field for European steel, cement, and power producers by taxing the carbon content of imports from countries with weaker emissions rules.

  • China has threatened retaliation, calling CBAM unfair and discriminatory.

  • While CBAM may protect EU industry, it risks higher prices for consumers and escalating trade disputes with major exporters

On Thursday, January 1st, the EU carbon border adjustment mechanism entered into effect with the goal of improving the competitiveness of European goods manufacturers against non-EU companies operating in laxer emissions reduction frameworks.

China was the first to threaten retaliation.

It won’t be the last.

The carbon border adjustment mechanism, or CBAM for short, was devised to remedy the unintended effects of the world’s most stringent emission-reduction standards for the industrial sphere, namely, sky-high costs that make the end product uncompetitive. This became especially painful for European makers of things such as steel and cement, where the biggest competitor is China—which does not have anything resembling the emission reduction requirements of the EU, so its steel and cement are very cheap, and buyers prefer them.

In other words, in order to boost the competitiveness of European steel and cement manufacturers—and electricity generators, too—the European Union made sure that cheaper imported steel, cement, and electricity are not that cheap anymore. China and India are unhappy about—and there are things they can do that will not help the competitiveness of European businesses.

As soon as the CBAM entered into effect, China’s Ministry of Commerce issued a statement, in which it called the legislation “unfair” and “discriminatory”, Bloomberg reported.

“We will resolutely take all necessary measures to respond to any unfair trade restrictions,” the ministry said in its statement.

“CBAM is quite unpopular among major exporters to the EU, but it has already proven to be quite effective in pushing reticent countries towards building or expanding carbon pricing efforts,” one consultant specializing in carbon permit markets, told the Financial Times.

“So it’s a major policy shift for the EU to protect its own industry, while at the same time leveraging the carbon pricing idea to third countries.”

China, in fact, has its own carbon market, has had it since 2021, and it is the biggest carbon market in terms of the volumes of carbon emissions covered by it. With China, it’s not about selling the idea of carbon markets to third countries; it is about competitiveness. And China is not pleased that its competitiveness will be compromised.

In simple terms, the carbon border adjustment mechanism puts a price on the carbon dioxide emissions generated during the production of a good such as cement or steel. The price is based on calculations of the emissions from the respective industries in countries that export to the European Union. The mechanism puts a so-called default emission value for the production of a certain good, and also emission benchmarks, to be used in tandem in a way that is as of yet unclear, but some say it is, in fact, benefiting China.

Politico reported the concerns at the end of last year, citing industrial executives as saying the default values for emissions for certain countries that export to the EU were set too low to be real, including some steel production in China that, according to these estimates, turned out to be lower-emission than steel production in the EU.

“Inconsistencies in the figures of default values and benchmarks would dilute the incentive for cleaner production processes and allow high-emission imports to enter the EU market with insufficient carbon costs,” an industry representative told Politico.

“This could result in a CBAM that is not only significantly less effective but most likely counterproductive.”

Meanwhile, Indian steel imports are about to dry up because Indian steel producers appear not to have been included in the “inconsistencies”. India is the world’s second-largest steel producer after China and exports as much as 66% of its output to the European Union.

This is about to drop sharply next year because India’s steel manufacturing is done in blast furnaces fueled with coal, which is incompatible with the European Union’s emission reduction plans. The Reuters report notes steel mills could switch to electric arc furnaces, which have a lower emissions footprint, but such a switch would take time and money.

“Most of the companies are yet figuring out a way to deal with CBAM,” one analyst told Reuters. “In the near term, it is expected to slow down India’s exports to EU,” Ravi Sodah, from Elara Capital, also said.

So, two of the world’s largest exporters of industrial goods, and major suppliers to the European Union specifically, are planning to respond to the CBAM by, at least in one case, curbing exports.

This would sure clear up the market for European producers, but it will not be welcome news to consumers of those goods, who would be footing the bill for what is essentially market intervention on the part of the European Union, and a protectionist market intervention, at that.

The United States is not going to be happy about it, either, and it will soon make its unhappiness known.

Tyler Durden
Tue, 01/06/2026 – 08:05

Leftists Petition To Deport Nicki Minaj For Attending Turning Point Event

0
Leftists Petition To Deport Nicki Minaj For Attending Turning Point Event

Is there something fundamentally wrong with a celebrity being conservative?  According to the political left, such a prospect calls for immediate and uncompromising punishment from the woke cult.  After all, conservative movie and music stars are rare for a reason – They get blacklisted.

The cancel mob is still around despite numerous political defeats in recent years, and now they want to collect the head of singer Nicki Minaj for their trophy room.  Minaj came to the US as a child immigrant from Trinidad to join her legal immigrant parents.  The sponsorship status from her family members allows her to reside in the country. 

However, because she has not yet received a green card, leftists believe that this is an opportunity to challenge the Trump Administration to “live up to its deportation policies” and remove Minaj from the US.  In other words, it’s the classic Alinsky tactic of attempting to make their opponents seem like hypocrites because they won’t apply their principles universally.

Several Change.org petitions to deport Nicki Minaj to her native Trinidad and Tobago have amassed more than 120,000 signatures combined. The most popular petition – garnering over 83,000 signatures – started on July 9, 2025. There are also at least three other petitions created between Dec. 21 and 28, 2025, that coincide with Minaj’s Dec. 21 appearance alongside conservative activist Erika Kirk at Turning Point USA’s AmericaFest, where the rapper praised President Donald Trump’s administration.

One petition argues that that:

“Minaj has left her LGBTQ fans “feeling deeply betrayed,” (Referring to to Minaj’s AmericaFest comment that “Boys, be boys…There’s nothing wrong with being a boy.”) 

“Deporting Nicki Minaj back to Trinidad would serve as a reminder that public figures need to be accountable for their words and the broader impact they have on diverse communities…”

“It’s not just about one person’s fall from grace; it’s about holding everyone to a standard of compassion and consistency, especially when they possess significant influence.”

Some conservatives also treated Minaj’s appearance at Turning Point as “controversial”, largely because of her liberal history and sexualized content.  But Minaj has been at odds with the progressive establishment for years, and took substantial risks when she spoke against the pandemic mandates and experimental vaccines.  

It is likely that the leftist establishment’s attacks on Minaj only pushed her to become more conservative and this was a common theme during covid.  Middle of the road liberals found themselves under siege by people they thought were their friends because they dared to question the narrative, and this drove them to join MAGA. 

The political left is obsessed with celebrity status, not because they are avid consumers of pop culture media, but because they view each individual celebrity as a tool that can be exploited for the benefit of the progressive hive.  In other words, they salivate over the idea of taking control of a celebrity’s “platform” and gaining access to the minds of their fans.

Throughout the last decade we have heard the same argument from woke leftists over and over again when an actor or singer goes rogue:  “They have a responsibility to use their platform to spread the progressive message of “equity”.  Their platform should be used for the greater good.”

It’s important to understand that celebrities are political slaves in the modern world fusion of Marxism and corporatism.  And, if a Hollywood star or a pop icon breaks from the plantation, this is seen as a betrayal of the highest order.  The celebrity becomes a heretic who must be ostracized, condemned, humiliated and destroyed.  They only exist to serve the spread of the woke message.

Of course, the leftists greatly overestimated the influence of the rich and famous in American politics today.  Kamala Harris and the Democrats built her entire 2024 campaign around the notion that each celebrity endorsement was guaranteed to win her millions of votes from captured fans.  Their plan failed miserably because they refused to recognize that celebrities have lost most of their social influence exactly because the public knows most of them are bought and paid for.

The petitions to have Minaj deported from the US have no bearing whatsoever on the decisions of the White House.  They are, though, a perfect example of how the political left tries to take ownership of pop icons and their behavior as a means to control the minds of their fans.

Tyler Durden
Tue, 01/06/2026 – 07:45

Congress Is Back: What To Watch

0
Congress Is Back: What To Watch

Via The Epoch Times (emphasis ours),

Following the holiday break, Congress returns this week with a lot to do. 

The U.S. Capitol building in Washington on Dec. 21, 2025. Madalina Kilroy/The Epoch Times

On the top of the agenda is funding the government to avert a government shutdown on Jan. 30. 

Lawmakers are also expected to take up a resolution related to President Donald Trump’s military action in Venezuela over the weekend, which included the capture of the Venezuelan leader.  

The Senate is expected to return Monday afternoon, with the House to follow on Tuesday. 

Here is what Congress will be dealing with when it returns.

A 43-day government shutdown—the longest in U.S. history—ended in November after a Senate bill put together by a bipartisan coalition passed Congress. 

The government is currently funded through Jan. 30.

The legislation included three of the 12 full-year appropriations bills and a measure to fund the rest of the government through the end of January. It also included the promise of a vote on extending the ACA’s Covid-era subsidies, a vote that ended in failure in the Senate.

House Speaker Mike Johnson (R-La.) has repeatedly said that the short-term funding bill was to allow appropriators to finish their work on year-long appropriations bills. With three passed, nine remain to be considered by Congress. 

Senate Minority Leader Chuck Schumer (D-N.Y.) said that Democrats are not looking to force another government shutdown.

“As of Jan. 1, that is a different time than before because the ACA [subsidies] expired,” Schumer told Punchbowl News.

“On the other hand, we’d like to get an appropriations bill done. That’s a Jan. 30 deadline … We’re trying to work with the Republicans to get it done.”

The House will vote on a bill to extend the Covid-era ACA subsidies for three years with no strings attached.

The vote is due to a handful of Republicans signing onto a discharge petition organized by House Minority Leader Hakeem Jeffries (D-N.Y.), going around House GOP leadership and forcing a vote.

The subsidies expired on Dec. 31.

The failure of an earlier draft of a bill related to ACA subsidies in the Senate suggests that this bill could struggle in the upper chamber if it were to pass the House. 

Though the issue was the driving force behind the 43-day government shutdown in 2025, Democratic senators have indicated that they’re not looking to restart the shutdown over the issue. 

This is lawmakers’ first time on Capitol Hill since Trump’s military action in Venezuela, and some senators are already mulling a response. 

The early morning operation in and around Caracas, carried out around 2 a.m. local time on Jan. 3, resulted in the capture of both Venezuelan leader Nicolás Maduro and his wife, and included a series of airstrikes on strategic targets, including infrastructure, ports, cell towers, and others.

Specifically, the Senate is set to consider a resolution under the War Powers Act introduced by Schumer and Sens. Tim Kaine (D-Va.), Rand Paul (R-Ky.), and Adam Schiff (D-Calif.). 

The measure would block the administration from engaging in further military action in Venezuela. 

It’s privileged, meaning that Senate Majority Leader John Thune (R-S.D.) can’t block it. To pass the Senate, it would need only a simple majority. 

With Paul expected to back the resolution, three other Republicans would need to sign on to pass the bill. 

Under the War Powers Act, identical language would need to be approved by both chambers to pass the bill. 

Since the 116th Congress, lawmakers have long been pursuing a bill to ban stock trading by members of the body. 

Now, supporters of a congressional stock trading ban seem closer than ever to achieving that goal—but multiple competing proposals and issues around the legislation remain unresolved. 

Rep. Anna Paulina Luna (R-Fla.), a longtime proponent of the ban, is expected to pursue a discharge petition to force a vote on her own version of the bill. Currently, that push has 74 backers—well short of the 218 it needs to bypass House Speaker Mike Johnson (R-La.). 

According to a post on X by the Florida Republican, House leadership has committed to a vote on “comprehensive legislation to address congressional stock trading,” but she plans to leave her discharge petition open until that promise is met. 

Democrats, meanwhile, have pushed to include the president in the ban—a proposal that Republicans have pushed against. 

A lesser issue hanging over the Senate will be the hundreds of executive nominees put forward by Trump who have yet to be confirmed. 

Ahead of the winter recess, the Senate confirmed a tranche of 97 of these nominees. 

The vote fits into a broader power dispute between Senate Democrats and the White House over nominees.

Historically, the president’s picks for lower executive branch positions have been confirmed by the upper chamber through unanimous voice votes, allowing dozens or hundreds of nominees to be quickly confirmed in minimal time.

Since Trump reclaimed the White House, however, Democrats have broken from this precedent, using a variety of Senate parliamentary measures and traditions to slow the confirmation of lower-level appointees to a crawl.

Primarily, lawmakers have withheld their support for unanimous consent confirmations, instead using the full amount of time for debate allowed under the Senate’s rules for every nominee. This means that nominations previously confirmed by the dozens can take an entire legislative day to work through.

With hundreds of lesser nominees waiting to be confirmed, the Senate is expected to continue working through the issue after returning from the break. 

Tyler Durden
Tue, 01/06/2026 – 07:20

Visualizing The Decline Of Global Wine Production (And Consumption)

0
Visualizing The Decline Of Global Wine Production (And Consumption)

Wine production and consumption have entered a sustained decline over the last decade.

This chart, via Visual Capitalist’s Niccolo Conte, tracks how global wine output, consumption, and trade have evolved since 2015.

The data for this visualization comes from the International Organisation of Vine and Wine (OIV). It tracks production, consumption, and imports from 2015 through 2024, measured in billions of liters.

Wine Production Hits a Decade Low

Global wine production peaked intermittently during the late 2010s, reaching nearly 30 billion liters in 2018.

Since then, output has steadily fallen, dropping to just 22.6 billion liters in 2024. That represents an almost 19% decline over the nine-year period.

Extreme weather events, including droughts, heatwaves, and late frosts, have disrupted harvests in major wine-producing regions. At the same time, rising costs and tighter environmental regulations are adding pressure to growers worldwide.

Consumption Declines More Gradually

While production has fallen sharply, global wine consumption has declined at a slower pace. Total consumption dropped from about 24.1 billion liters in 2015 to 21.4 billion liters in 2024, a decline of roughly 11%.

Health-conscious lifestyles, aging populations in traditional wine markets, and younger consumers drinking less alcohol overall are contributing factors.

Global Trade Shows Signs of Softening

Wine imports have also edged lower, falling about 6.5% over the same period.

After peaking above 11 billion liters in the early 2020s, global wine trade slipped below 10 billion liters by 2023 and 2024.

If you enjoyed today’s post, check out Ranked: Which Country Consumes the Most Coffee? on Voronoi, the new app from Visual Capitalist.

Tyler Durden
Tue, 01/06/2026 – 05:45

Electric Cars Make Up Nearly 96% Of New Car Sales In Norway

0
Electric Cars Make Up Nearly 96% Of New Car Sales In Norway

Authored by Naveen Athrappully via The Epoch Times (emphasis ours),

In 2025, electric cars accounted for 95.9 percent of all new cars sold in Norway, the Norwegian Road Traffic Information Council (OFV) said in a statement on Jan. 2.

The Tesla logo on the hood of a car in Oslo, Norway, on Nov. 10, 2022. Victoria Klesty/Reuters

“This means that the goal set by politicians 10 years ago has been achieved: New car sales in Norway are now emission-free,” it said. A total of 179,550 new passenger cars were registered last year, breaking the previous annual record set in 2021.

“2025 was also the year when the number of electric cars surpassed the number of diesel cars and became the largest powertrain in the total passenger car population,” the statement said.

For December 2025 specifically, 35,188 new passenger cars were registered in the country, with electric cars accounting for 97.6 percent of these vehicles, a sign of how EVs “now dominate new car sales” in the country, OFV said.

Norway, with a population of around 5.53 million, is a high-income country, according to Harvard data. With a GDP per capita of $87,702, the nation is the third-richest ⁩per capita among 145 countries. Norway’s oil wealth helps sustain its welfare system.

Tesla consolidated its position as “Norway’s largest car brand” last year, with a record 34,285 new passenger cars registered—a 19.1 percent market share, roughly one in five new cars.

Tesla’s Model Y set an annual record last year, hitting 27,621 first-time registrations, which is the “highest number ever registered for a single car model in Norway in one year,” according to OFV.

Chinese companies also saw their share in Norway’s EV market rise last year. A total of 24,524 new passenger cars registered last year were of Chinese origin. This accounted for 13.7 percent of new car sales, up from 10.4 percent the previous year, according to the council. The biggest Chinese car brand was BYD.

“2025 has been a very special car year. We see the effect of long-term and targeted electric car policy, and how specific tax decisions have immediate effects on the market,” OFV Director Geir Inge Stokke said.

“The final sprint towards the end of the year has been historically strong, and there is no doubt that the VAT change from January 1, 2026, has contributed to a great many choosing to secure a new electric car before the year was over.”

As for the European Union overall, electric cars accounted for 16.9 percent of the EU new car registrations for the January–November 2025 period, according to a Dec. 23, 2025, statement from the European Automobile Manufacturers’ Association.

The biggest markets for new EV registrations in the EU were Germany, Belgium, the Netherlands, and France, with registrations in Germany jumping over 41 percent year-over-year.

However, hybrid-electric cars remained the “preferred choice among EU consumers,” accounting for 34.6 percent of new registrations, more than double the share of electric cars, the association said.

While EV sales in the EU remain robust, the picture is different in the United States.

New U.S. EV sales in November 2025 are estimated to total 70,255 units, down 41.2 percent from a year ago, industry expert Cox Automotive said in a Dec. 15 statement. Compared to October 2025, November sales were down 5.2 percent.

Cox attributed the slump to the expiration of a federal tax credit.

The New Clean Vehicle Tax Credit granted buyers of new EVs up to $7,500 in incentives. The measure was included in the Inflation Reduction Act, signed into law by President Joe Biden in 2022.

President Donald Trump signed the One Big Beautiful Bill Act into law in July 2025, ending the credits on Sept. 30 of that year.

“Market share reached multi-year lows as sales declined. Weak demand fueled a surge in inventory, with days’ supply reaching elevated levels. Pricing eased across the market, underscoring an industry struggling to find balance in the post-incentive era,” Cox said.

“As we head into 2026, the EV market will continue navigating post-incentive challenges, with inventory and pricing dynamics shaping near-term performance.”

As for the overall new-vehicle sales situation in the United States, Cox estimates the number will reach 16.3 million units in 2025, up by almost 2 percent from 2024 and the “best result since 2019,” the company said in a Dec. 17 statement.

For 2026, Cox predicts new-vehicle sales pace to decline by 2.4 percent to 15.8 million units, highlighting factors such as the lack of EV tax incentives.

While Tesla saw sales jump in Norway, its global performance has taken a hit. In 2025, the company delivered 1.64 million units, according to a Jan. 2 statement. This is down 8.3 percent from 1.79 million deliveries in 2024.

Tesla shares fell by 2.59 percent on Jan. 2.

Tyler Durden
Tue, 01/06/2026 – 05:00

Russia Straps MANPADS Missile On Shahed Drone To Counter Attack Helicopters 

0
Russia Straps MANPADS Missile On Shahed Drone To Counter Attack Helicopters 

Low-cost drones have transformed modern warfare forever during the nearly four-year-long Russia-Ukraine war. These commercially available systems have been used to strike cities, power grids, ports, refineries, and military bases, delivering maximum impact at minimal cost.

The evolution of these drones is notable as well. One major issue that drones on both sides of the battlefield have faced is counter-drone operations involving electronic warfare, interceptor drones, fighter jets, and attack helicopters. However, none have yet proven consistently effective at scale.

In response, both sides have increasingly deployed attack helicopters to hunt drones, using machine guns and missiles to shoot them down at close range.

To deter enemy aircraft, the Russians apparently have mounted a shoulder-fired man-portable air defense missile on top of an Iranian-designed loitering munition known as a Shahed-136.

Military blog Army Recognition states Ukrainian forces have “intercepted for the first time a Shahed drone fitted with an Igla-S MANPADS missile.”

Here’s more color on the first publicly documented case of a MANPADS missile mounted on a Shahed drone for air defense purposes:

On January 4, 2026, the Ukrainian Unmanned Systems Forces stated that fighters from the Darknode Battalion of the 412th Nemesis Brigade intercepted a Russian Shahed-type kamikaze drone fitted with an Igla-S man-portable air defense system. This variant, observed for the first time during the war, carried a camera and a radio modem, allowing the missile to be launched remotely by an operator located on Russian territory to threaten Ukrainian helicopters and low-flying aircraft involved in counter-drone interception.

Ukraine may now have to allocate more air defense assets and counter-UAS resources to deal with such a threat, as MANPADS-armed drones could potentially serve as a decentralized air defense layer for Russia’s advancing forces. (Picture source: Ukrainian MoD)

According to Serhii “Flash” Beskrestnov, a Ukrainian military and technical expert, the missile launch was not automatically but manually triggered by the Shahed operator using the onboard camera feed and radio link. This new variant was assessed as being intended to engage Ukrainian helicopters and other low-flying aircraft that had previously intercepted Russian drones at close range using machine guns or cannons. Army aviation crews were warned to avoid approaching Shahed drones on a head-on course and to be particularly cautious when encountering drones flying in circular or loitering patterns, which were interpreted as potential attempts to draw aircraft into missile engagement zones. Ukrainian units also indicated that examination of the tactics associated with this configuration was ongoing in order to adapt interception procedures.

The rapid evolution of low-cost drones is a concerning development, and it is almost certainly only a matter of time before such drones appear in the Americas. Drug cartels in Mexico are already known to have deployed smaller ones for surveillance and attacks.

Tyler Durden
Tue, 01/06/2026 – 04:15

Germany’s Middle Class Under Siege In 2026

0
Germany’s Middle Class Under Siege In 2026

Submitted by Thomas Kolbe

Save in times of plenty, and you’ll have in times of need. An old German proverb, now proving tragically prophetic. The hardship caused by a completely derailed climate-socialist ideology is only just beginning. This socialist experiment is likely to continue ravaging the country until its economic substance is entirely consumed.

The new year begins as the old one ended: a fiscal raid on the wallets of the middle class. In Brussels and Berlin, there is satisfaction that citizens have been quietly, without spectacle, subjected to yet more tax increases—whose revenues, like a rising tide, lift all ships only slightly.

On January 1, the CO₂ price per ton of emitted gas rose from €55 to €65. This levy, applied to fossil fuels such as gasoline, diesel, natural gas, and heating oil, threads like a red line through the entire value chain—even reaching private households’ bills. The green extraction mechanism is now firmly entrenched, funding Brussels’ expanding activities increasingly, and is defended tooth and nail by the ruling politicians.

The Lie of Tax Relief 

When the federal government celebrates its minimal tax relief for lower- and middle-income groups, reality tells a different story. In truth, these relentless fiscal collectors are increasing the tax burden further. Only the distracting work of state-affiliated media prevents the growing hyperstate’s costs from becoming fully visible.

2026 is set to become an expensive year for Germany’s shrinking middle class, visible soon on the first paycheck of the year. That will reveal the true cost of an overextended welfare state and the one-of-a-kind experiment of transforming Germany’s social insurance system into a quasi-global insurance scheme.

Never since World War II has the German middle class faced such fiscal and economic pressure.

The Burden of State Subsidies on the Middle Class 

The countless subsidies and state interventions financing the complex “green arts” sector, the Ukraine war, and now the military buildup constitute a direct attack on the German middle class. Businesses and net taxpayers pay an ever-rising “blood price” each year to sustain Berlin’s and Brussels’ ideological and power ambitions.

The still-active renewable energy subsidy program, the EEG, alone consumes over €16 billion this year for an energy grid that, since the end of nuclear power, no longer provides a secure base for industrial production, sending both industrial and household electricity costs to dizzying heights. Trittin’s “ice ball” has become a cost Himalaya no one can climb.

Germany’s seven-year industrial decline, which is now accelerating, precisely chronicles the path of the deliberate destruction of its industrial base. Nearly 300,000 industrial jobs have been lost since 2018—tragic, yet apparently of little concern to Berlin’s policymakers.

Local city treasurers, however, are feeling the pain: as corporate tax revenues collapse under industrial destruction, citizens can expect cuts in public services and steep tax hikes. Schools, kindergartens, sports facilities—all face drastic savings. A big “thank you” goes to Berlin central planning.

Industry on the Edge: Loans Fizzle 

What Friedrich Merz, Ursula von der Leyen, and other central planners aim for is clear: using state loans to occupy freed-up industrial capacities. Yet no matter how much funding flows into the new social program under the banner of a special fund for green and military production—the effect has already fizzled. In December, the entire Eurozone industrial sector, measured by current Purchasing Managers’ Indices (PMI), slipped into recession. Germany has been continuously downsizing its industry for seven years.

A victory for Brussels’ central planners, whose goal appears to be the economic and geopolitical neutralization of the country. After years of deindustrialization and waves of bankruptcies, this strategy is hard to interpret otherwise. Germany’s PMI now sits at 47 points—clearly in contraction. Hundreds of thousands of jobs will be lost this year. Last year alone, 24,000 companies went bankrupt. Exact figures for job and net direct investment outflows are not yet available; in 2024, €64.5 billion flowed out of Germany. German industry is no longer competitive.

Quick Blame Game 

The culprits are quickly identified. U.S. tariffs, a favorite topic of sympathetic media, are often cited, though the crisis began long before Donald Trump. Dumping competition from China is also highlighted. While this is a factor, 99 percent of Germany’s economic problems are homegrown.

No one forced the country to keep its borders wide open for a decade, pushing its social insurance to the brink of collapse—all to create new voter bases for the united political left and to break resistance from the bourgeois right.

Shrinking Middle Class and Falling Investments 

This trend is reflected in the middle class. The DATEV SME Index shows falling real revenues across all sectors, particularly trade, construction, and consumer services. Investments are nearly frozen: only 20 percent of companies plan rising investments, according to LBBW’s SME radar for the coming year.

The ideological green agenda has left its mark. High electricity costs, falling incomes, and persistent inflation are bleeding the middle class dry. Retail felt this for the first time during Christmas: nominal sales rose 1.5 percent, yet real sales fell by 1 percent in the peak month.

Economic stress will be a constant companion for Germany’s middle class in 2026. High property prices, zero real interest on savings, and rapid erosion of economic substance collide with an ever-expanding state. Bureaucracy and the state apparatus are evolving into a parasitic leviathan, funded by a shrinking number of contributors.

Consequences for Industry, Trade, and City Centers 

Too much depends on Germany’s high industrial value creation: service businesses, high factor incomes, and secure municipal finances—all are now being lost, reflected in city centers.

Where once life flourished, roughly 5,000 retailers die every year, an irretrievable loss. The desolation mirrors what citizens feel in their wallets: the ebb has begun.

The middle class’s evaporating purchasing power is most visible in hospitality, where families cut costs first. Hotels lost 3.7 percent in real revenue in 2025, while restaurants and bars fell 4.1 percent year-on-year. Households are saving wherever possible. High energy costs, rising social charges, and a weakening job market leave a trail of economic decline.

Missed Lessons: The Population and the Crisis 

Structural economic crises take time to penetrate public consciousness. Most households first tighten belts without complaint.

The state exploits this calm before the storm to consume citizens’ wealth faster than the private sector can compensate. With net new debt over 5.5 percent this year—including accounting tricks—this is particularly evident. The devotion of a portion of the population to ideological doctrine becomes an expensive, destructive tragedy.

Germany faces a nation unprepared to draw necessary lessons: reversing migration policy, adapting the bloated state apparatus to new economic realities, and downsizing accordingly. A turn toward a meritocratic market economy remains absent.

Until these lessons are learned and acted upon, Germany will continue to fall.

* * * 

About the author: Thomas Kolbe, born in 1978 in Neuss/ Germany, is a graduate economist. For over 25 years, he has worked as a journalist and media producer for clients from various industries and business associations. As a publicist, he focuses on economic processes and observes geopolitical events from the perspective of the capital markets. His publications follow a philosophy that focuses on the individual and their right to self-determination.

Tyler Durden
Tue, 01/06/2026 – 03:30

English Remains The World’s Most-Spoken Language

0
English Remains The World’s Most-Spoken Language

Language plays a central role in shaping global communication, culture, and economic exchange. While some languages dominate due to large native-speaking populations, others achieve global reach through widespread adoption as a second language.

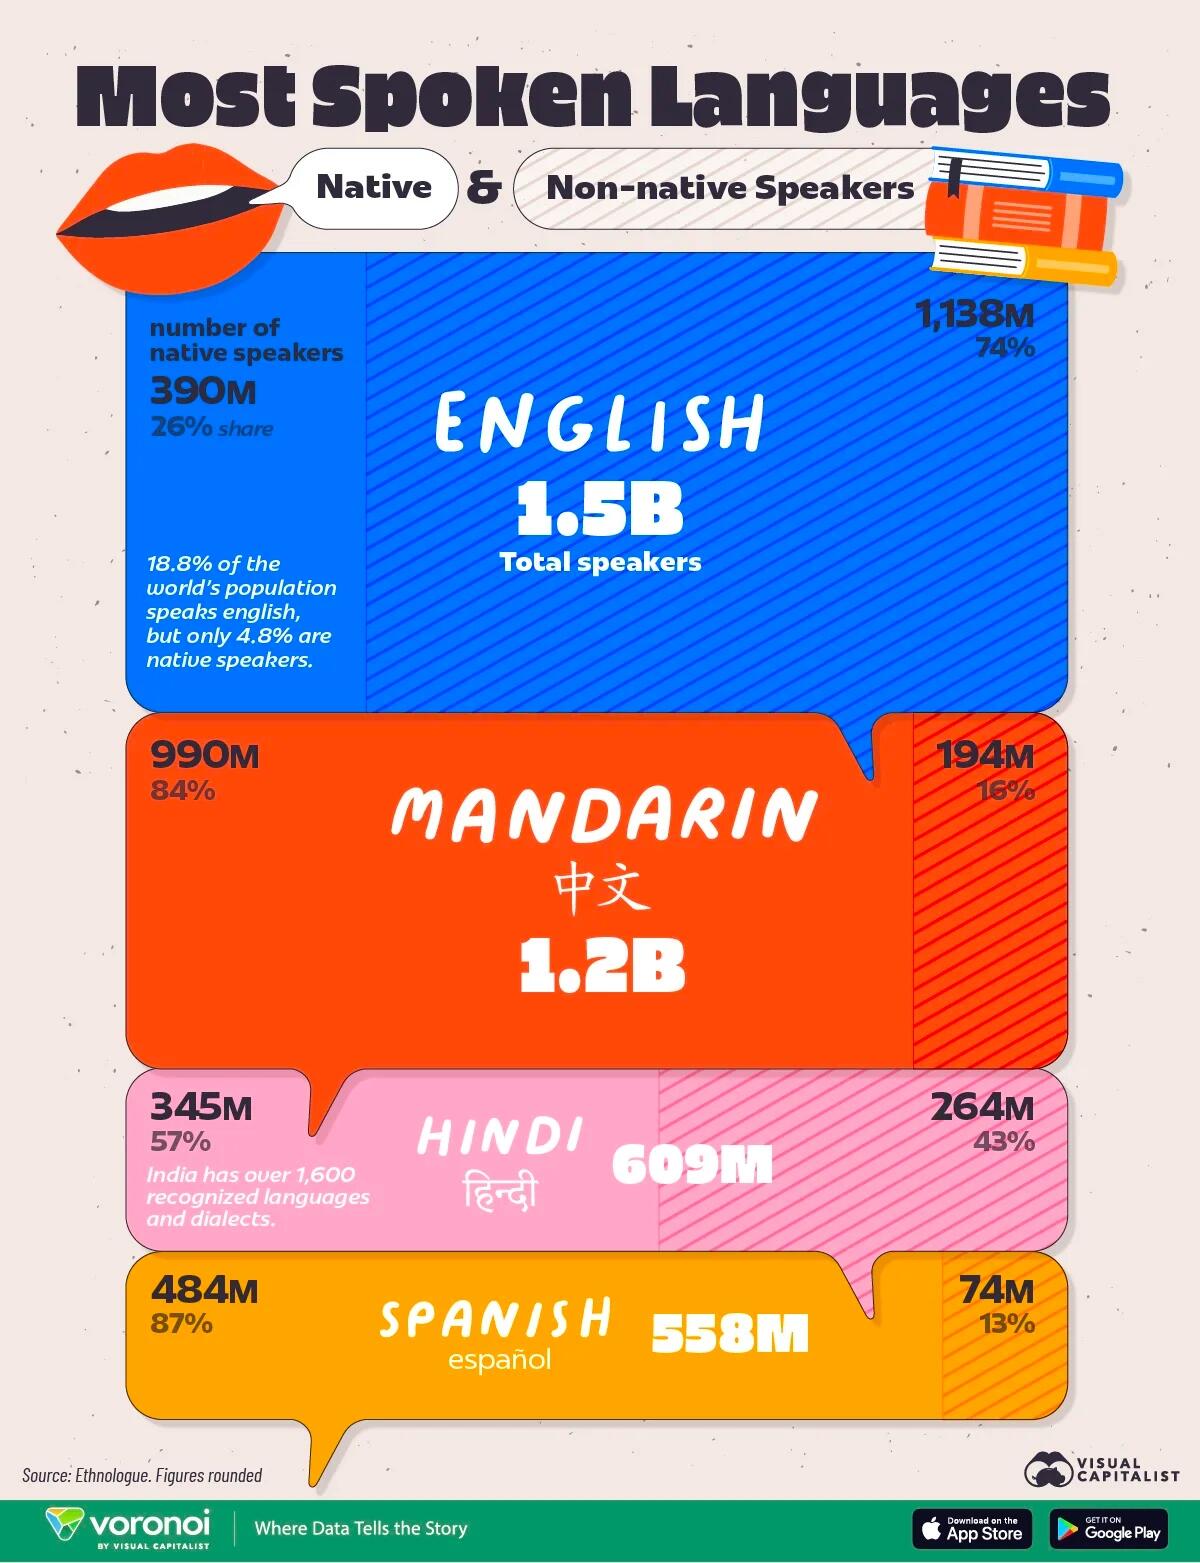
This infographic, via Visual Capitalist’s Niccolo Conte, compares the native and non-native usage of the world’s most spoken languages in 2025, using data from Ethnologue.

The World’s Most Spoken First and Second Languages

English is the most spoken language with approximately 1.53 billion speakers worldwide.

However, just 390 million people speak English as their first language, meaning nearly 75% of English speakers use it as a second language, making it the dominant global lingua franca across industries and professions.

The table below shows native and non-native speaker counts for the world’s most spoken languages in 2025:

In total, about 18.8% of the world’s population speaks English, but only a quarter of those are native speakers.

Mandarin Chinese ranks second with roughly 1.18 billion speakers.

In contrast to English, Mandarin is primarily spoken as a first language, with more than 83% of its speakers being native.

Hindi and Spanish follow as the next most spoken languages worldwide. Hindi has around 609 million speakers, split more evenly between native and non-native usage due to India’s multilingual population.

Spanish stands out as one of the most widely spoken native languages globally, with nearly 87% of its speakers using it as their first language. Spoken Spanish is concentrated across Spain, Latin America, and parts of the United States.

If you enjoyed today’s post, explore more language and culture insights on Voronoi, including The Most Used Languages on the Internet.

Tyler Durden
Tue, 01/06/2026 – 02:45