

60.4 F
Chicago
Sunday, November 1, 2026
Home Blog Page 85

Something Is Rotten In The State Of Yields

0
Something Is Rotten In The State Of Yields

Submitted by Peter Tchir of Academy Securities

Treasuries, European Sovereign, and even Credit. Something seemed rotten this week, with Thursday’s price action in all 3 of those markets triggering the need to focus on this more. Debt markets underpin the entire global financial system and when things don’t “look,” or “feel,” or “smell” right, it warrants our collective attention. Yes, “feel” or “smell” doesn’t seem compelling as some authoritative answer, but that doesn’t mean it isn’t worth exploring.

For the past few weeks, our biggest complaint on Treasury yields has been that neither Bessent nor Warsh is addressing the root causes of higher Treasury yields. The root causes have far less to do with economic variables, inflation, and Fed independence, and much more to do with a global supply glut. Not just of sovereign debt. Not just of corporate debt, but also corporate debt adjusted for average duration as companies who need to issue longer-dated bonds have dominated the flow.

  • On the Treasury Department – I Am The House Now and 6 Billion Dollar Man. I am looking forward to seeing what Dave Zervos can bring to the table. Bringing a fresh set of eyes to the problem could be very helpful, as maybe he will see what we’ve seen: the admin is nowhere close to a Draghi style “Whatever it Takes” moment and has not been addressing the root cause.
  • On Friday we ranted about The Absurdity of Jobs Data. (I received one “unsubscribe” which always guts me, but had multiple very positive responses; clearly we touched a nerve by, yes, analyzing the data, coming up with the “no hire, no fire” take everyone came up with, but we mostly lamented that we are all working with data we suspect is more of a guess than truly factual.) But we did highlight that we thought the positive move in Treasuries would fade by the end of the day, and the 10-year went from a low yield of 5.15% at 8:31am ET to almost 5.3%, closing at 5.27%.

We will take a quick look at each of these markets.

There Are No Treasury Bears

Ok, that sounds ridiculous. How can something that has been trading so poorly have no bears? Isn’t everyone bearish? The price of oil (and diesel) is bearish. The deficit is bearish. The long-term trajectory on total debt is bearish. The fact that interest payments on debt are now greater than discretionary spending is bearish. The global supply is bearish. The corporate supply is bearish. The fact that countries like Saudi Arabia have gone from being buyers of Treasuries, to needing a loan to fund their operations is bearish. Questions about the global reserve status of the dollar (which is overdone) is bearish. The fact that across the globe investors seem less inclined to own Treasuries on their balance sheet (corporate debt, debt denominated in their own currencies, etc. are preferred) is bearish. A Fed that isn’t independent is bearish. A Fed that is independent is bearish. Etc.

There is NO shortage of reasons to be bearish on Treasuries. Over the past month or longer we have presented many of these reasons. Our primary focus has been on supply and how much duration has been sucked out of the market by the corporate debt issuance. Not to mention that I believe we have set back-to-back records for the largest HY deal ever, and even a $10 billion corporate deal, which at one time would have caused some eyes to open, but now has become de rigueur. But more on corporates later.

Let’s get back to the matter at hand, the “claim” that No One is Bearish Treasuries.

I’ll offer up the T-Report as the first piece of evidence. In last weekend’s T-Report, despite giving more reasons for Treasuries to go higher, we made an effort to state we were neutral on Treasuries in Stocks +1, The House -1, The World ?. That didn’t stop us from recommending fading the bond market Friday morning, but we did not come into this week “pounding the table” to be bearish on bonds.

Yes, the T-Report is a tiny sliver of the research and commentary produced. But everywhere I looked, I saw bullish or neutral takes on the market. I do not remember a single guest on financial media that was pounding the table about shorting bonds here and now. Ok, there are couple of “end of fiat” people out there who were pounding the table, but they tend to always pound the table on that subject and are presenting a vision of global catastrophe without a tradable timeline.

I can tell you that when we were bearish and arguing to fight Bessent, Treasuries & Treaties, most of our conversations had been with investors buying Treasuries. We’ve attempted it a couple of times during this move (with some wins and some losses). The point being that while there might be a lot of material published on problems facing bonds, that doesn’t seem to match positioning at all!

One bond watcher is apparently bullish for the first time in 6 years. I cannot tell you the number of times that story made it into my stream, on social media, and work e-mails/Bloomberg msgs. You know what people who are short the market don’t do? They don’t forward to everyone they can, articles about this being the best buying opportunity in a decade. That is not how human nature works. Maybe everyone is so scared, while being short, that they felt the urge to share this story. Or, maybe, long and nervous, they were trying to convince people of the latter. That makes the most sense to me, and why I was trying to raise my hand and say “I’m neutral” not bearish.

How Can Yields March Higher if There Are No Bears?

I think the better question might be, how can they not? But, I guess before wading into analysis of “how” this could be happening, let’s just present the slide that shows it is happening! And the moves are getting “worse” even as we put FOMC behind us and oil prices have been receding. The move from 4.6% on 10’s as recently as August 25th, to 5.27% on Friday, is quite astounding. The speed of the moves is as problematic (or probably more problematic) than the levels involved. The one way nature of the move is perturbing, but I think following analysis is at play and helps us understand the move better.
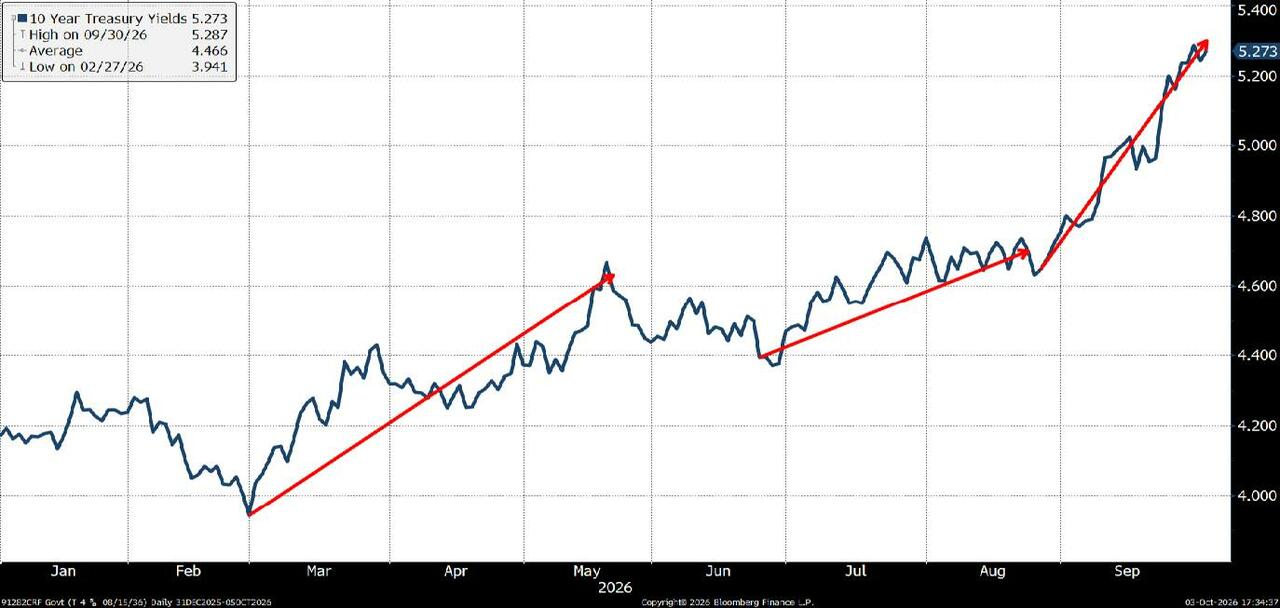
As a contrarian, it is easier to move markets against positioning than with positioning. If everyone was bearish and positioned that way, it would be a lot harder to push Treasury yields higher.

So, let’s lay out a scenario that I believe is at work below the surface.

A Lot of “low conviction” longs in the market.

Traders are long Treasuries for a trade. Asset managers are slightly overweight duration versus their benchmark. No position is particularly large (which is important) because the trend has clearly gone against you.

That would sum up my conversations, and even my own thoughts on trading this.

True “depth of liquidity” is low in the age of electronic/algo trading. Everyone (and every machine) is trying to scrape out a cent here or there on trading, making it look like there are massive amounts on the bid and offer at any time, but only a tiny fraction represents traders truly trying to commit capital at that level, and the rest is just jockeying for position.

Enter the “quant” funds. That is probably the wrong name, but I’m looking for traders without emotion. Something very systematic in nature. I’d lump what I often refer to as “windshield wiper” algos: algos that sweep back and forth looking to trigger stops, in this category.

The windshield wipers sweep back and forth trying to trigger movement. Buy a little. Buy a little more. Did the market move in your favor? No. Then sell it and get a little short (ok there are some shorts in the market, or else my idea wouldn’t work, but I still think it is a tiny fraction of the positioning). Sell a little more. Did it move? Yes. Then do not book profits. Sell more. Keep selling until selling doesn’t beget more selling!

There are some larger quant/systematic traders that will build big positions during this type of trading. These are the “quick” windshield wipers, but something with a broader tolerance for losses, while looking for big gains.

Unlike many traders (especially me), they are not quick to book a profit. When momentum is going, they push more. They grow their position even as the market moves in their direction.

They are agnostic (or emotionless) and only “know” that selling begets more selling and buying does NOT beget more buying.

Small positioning matters too. If you are at a hedge fund and long $100 million of 10s, you are quick to close out. If you are long $10 billion of 10s, you might try to fight whatever is pushing the market. In my experience, small position sizes make it easier to move markets, because no one has the conviction, nor the incentive to fight moves.

Many traders are momentum traders at heart. Momentum is consistently one of the top-performing strategies. So, even those who may have taken a swipe at getting long Treasuries will go short for a trade (yes, somewhat against my bold statement that there are no shorts, but this is more about during a move to higher yields than at the start of the day). So, day traders pile into momentum and the only momentum that has really worked is for higher yields.

If and when the selling stops creating more selling, the “emotionless” will cut their shorts just as quickly. We will get a vicious snap higher in price, lower in yields, and the worst will be behind us, but so far, there are so many reasons to be nervous about bonds that selling begets selling. Some of the bond market issues need to be resolved, with oil and diesel being the ones that have the best opportunity to “fix” themselves and end the current vicious cycle.

While Treasuries are facing a lot of hurdles, I strongly believe that underlying the price action is the sort of behavior described here. It is unclear that we are close to the end of selling creating more sellers. We may not get there until either we get conviction from the bulls that we are at a level that is worth supporting, or people start positioning themselves as bearish as they talk.

In the “for better or worse” category, TLT (a 20+ year Treasury ETF) has received large inflows and shares outstanding are now at their highest level since late 2024. That does kind of match the point that there are no bears. On the other hand, retail has done a great job “buying the dip” on equities, so they may be right here and are ahead of the “pros” because having stop losses might be great for risk management, but can prevent people from taking advantage of what might be really good buying opportunities. Retail bought the dip post Liberation Day, before the pros. Don’t underestimate their power, but at the same time, don’t believe “everyone is short” treasuries, as that narrative is just not true.

European Sovereign Debt

Rising global bond yields was on my radar. But whatever just happened between German bond yields and French and Italian bond yields was not.

European bond yields rising as spending on defense and infrastructure increases, made perfect sense. What is harder to figure out is this move in French and Italian yields relative to German yields.

The French deficit is going to go above the EU “targets”. Looks like 5% instead of 3%. That helps explain the move higher in French yields (and Italian). But the move in German yields? Are we really having a “flight to quality” in Europe? And Germany, losing their industrial base, having a major shift in politics, is the “go to” place for safety? I guess, but it all seems odd.

Maybe investors were being “lazy” and were picking up the “extra” yield in France and Italy for the same “risk” as Germany, only to realize the risk might not be the same, and were forced to unwind?

That seems plausible.

I don’t want to bring up Frexit or all the other weird words that were tossed around after Brexit, but maybe not only is Europe starting to embrace ProSec™ each of the larger companies is starting to do what they think is right for their country? That the construct that gave countries the size of Hungary (with their Russian leaning political influences) almost as much power in some votes as France, Germany, Italy, etc., doesn’t work as countries start taking steps towards vertically integrated nations. Even vertically integrated “blocks” likely need the biggest and best prepared countries to take leadership and drive the group forward.

Macron seems more comfortable “speaking up” for Europe – the release of diesel from Europe’s SPR seems like a good example of that.

I don’t know what is going on here, but it does not seem good. This fairly rapid, “repricing” of relative credit risk in Europe could be nothing, but I suspect it is hinting at a deeper problem:

  • More poor positioning, facing more unwinds. Again, these unwinds have real world repercussions as Italy and France face a tougher road to borrowing to build out their infrastructure, defense, and nationalistic programs.
  • Another round of markets, and maybe even the populace questioning how integrated the EU really wants to get, especially economically. It seems like just a few weeks ago we were discussing efforts for Europe to fund Europe and suddenly, markets are seriously differentiating the credit of Germany and France in 2 years? This is likely an over-reaction to what we are seeing, but maybe this “tail risk” that has been tucked away for years, needs to be thought about again, if not taken seriously?

The broader trend of European yields higher fit our overall macro view and made sense.

This recent divergence caught our eye as something “off” and worth paying attention to. I’m not in alarm mode or anything, but who would have thought markets need yet another thing to worry about? And yet here we are.

Any “cracks” in global bond norms deserve attention and I think this qualifies as some sort of a crack. Maybe just a crevice, certainly not a canyon, but a crack, nonetheless.

Credit Spreads

There is an entire cottage industry dedicated to calling for the “next” GFC. It often starts with worrying about BBB spreads, or sometimes structured/opaque credit, because those seem to be areas big enough to scare people, and difficult enough for the average person to understand, that it is easy to scare them.

My background is in credit, but I rarely write about it lately, because it has been soooooo boring! I’m not going to go all doom and gloom, but for the first time in ages, I better dust off some of my tools to look at credit. We will look into this more closely next week, but again, just like the European bond market, something is going on that deserves some attention.

While I won’t go all doom and gloom, I will throw out one piece of “shade”. I remember being trained in high yield and being told that the RJR deal was the biggest high yield bond deal ever. That despite being “absorbed” it marked the top.

Bond markets are much bigger and more sophisticated now. There is “less” of a differentiation between high yield and investment management, though I’m till astounded how big that break can be. The difference between the average BBB- company and BB+ company is minimal (and there are times that people can argue, that due to rating agencies being slow to upgrade to IG or downgrade to HY, the better credits might be lower rated). Due to investment guidelines, in funds, or regulated entities some differentiation between the two markets still exists. I believe we just had 2 of the largest high yield bond deals ever? Again, these deals were well telegraphed, but PSKY 8.875% 2nd lien bonds due 2034 (BB composite rating), that were issues at par, traded below 95% on Thursday and 96% on Friday, to close the week at 96.5%. A 3.5% loss on $4 billion of bonds will leave a mark ($140 million to be exact) on bond buyers, especially the “fast money” crowd, but even long only won’t be happy with that.

One thing that greatly reassured me, and lets me believe I can wait until Monday or Tuesday to do a deeper dive into credit (this weekend is too nice in the metro area to be stuck inside typing), was that both HYG and JNK (two large HY ETFS) were trading at NAV. Any time the credit ETFs trade at a discount to NAV, is a danger signal in my book. It means there are market dislocations, and trading at a discount tends to create more selling. That might seem counterintuitive, but we’ve explained the ETF Death Spiral™ in detail, and it continues to be an incredibly useful indicator. So when I see ETF down 2.5% or so in a month, and hitting new lows, you want to see how they are trading versus NAV. Both are trading very “normally” which is good. The same is true for LQD (long dated IG) and VCSH (short dated credit). These are all saying “orderly liquidity”! Not quite the same as “nothing to see here”, but close.

The CDX index has widened from 50 to 60 in a two weeks. The Bloomberg Corp OAS has only moved from 75 bps to 82 bps. I feel obligated to mention it, but as something that is “observed” rather than traded, I want to pay more attention to the CDX index for now.

CDX traded up to almost 70 in March at the start of the war, so that is “good” we are only at 60.

One thing I don’t like is that while the S&P 500 traded marginally higher on Thursday and had a strong day on Friday, the CDX index which is often correlated with the S&P 500, was wider on Thursday and basically unchanged on Friday. If you told me what the S&P 500 had done, I’d have guess wrong on what the CDX index had done. While “decoupling” is a bit strong, when you are looking for early signs of something “bigger” like we’ve already seen in treasuries, just saw in European sovereign debt relative value, it is not nothing.

Bottom Line

We often hear from other market participants that they want to pay attention to fixed income. That they understand that fixed income is a behemoth and often difficult to understand. But that if fixed income cracks, equities have trouble doing well. They say that, but they really don’t like their positive narratives being interrupted.

VIX is barely above 15 (well below it’s average of 18 for the year). The MOVE index, the bond market equivalent of VIX (not quite, but close enough for now), is at 107. Just below its peak of 115 in March. Well above its 1 year average of 74.

I’ll start the week neutral on rates, since “fade the move” worked so well on Friday, but I’m nervous.

Whatever just happened in European sovereign makes me nervous. Credit doesn’t make me nervous, but for the first time in years I’m paying some serious attention to spreads.

A deal with Iran, more news on the compute front, can help, but away from all of that, equities seem to be ignoring some fixed income market moves (and not just the headlines on long bond yields) that equities might wish they’d pay more attention to.

Call me nervous, not scared, and extremely happy with this weekend’s weather (in the Northeast)!

Fixed income is sending some sketchy signals, and to the extent positioning is wrong, those signals risk turning into something bigger

Tyler Durden
Sun, 10/04/2026 – 14:00

The US Doesn’t Have An Oil Problem – It Has A Refinery Problem

0
The US Doesn’t Have An Oil Problem – It Has A Refinery Problem

One of the enduring weaknesses of the modern US economy is the lack of redundancy.  As long as most of the world is operating normally and there are no serious geopolitical disruptions, America’s “just in time” system works fine.  But, throw a monkey-wrench into distribution, global exports, freight systems, shipping or elements of production and cracks quickly form in the armor.  

This does not mean that the US economy can’t adapt; the pandemic shutdowns were horrifically pointless but they did prove that the system has the ability to function despite deep deficiencies.  However, when it comes to the management of vital resources, such as energy resources, it’s clear that some changes need to be made in the near term.  

Before the war in Iran a large portion of the public was oblivious to the fact that the US is the largest exporter of oil in the world, and of the foreign oil supplies we do receive, only 8% come from Gulf nation producers.  A mere 7% of those supplies travel through the Strait of Hormuz.  In other words, the US doesn’t rely on the Gulf for oil.  With the new Venezuelan deal and oil flows from the gulf back to 98% of pre-conflict levels, the war is even less of a concern when it comes to US energy.  

The problem is, there is a global oil refinery capacity shortage, and the US is not adapting as it should.  

Ukrainian drone strikes against Russian refineries have recently forced the Kremlin to cut off all diesel exports to other countries.  Russia is the second largest supplier of diesel in the world with 12% of all exports.  This loss to global markets is straining already struggling refineries and causing prices to climb.  The only country with the ability to increase refining capacity quickly is the US, but it’s not happening.  

The last time a full-conversion refinery was built in the US was Marathon’s Garyville, Louisiana plant. It came online in 1977 at about 200,000 b/d and has since been expanded to about 617,000 b/d.  Most U.S. capacity growth since the 1970s has come from expanding existing sites, not building new ones.    

In five decades, no major infrastructure has been added.  This means that as aging plants shut down, or as they are closed down due to state policies, US refining capacity will continue to fall and the ceiling for supply vs demand will get tighter and tighter. 

Currently, national demand for distilled products is 8.7 million b/d, and production provides only 9.5 million b/d – That’s an extremely narrow gap at 95%-98%.  Unfortunately, this gap has narrowed further due to refinery closures in 2025.  The largest drop in U.S. capacity came from the shutdown of the LyondellBasell’s Houston plant (about 264,000 barrels per day) and the Phillips 66’s Los Angeles plant (about 139,000 barrels per day). Together those removed about 400,000 b/d; small expansions elsewhere offset some of that, but not enough.  

The Houston plant was built in 1918 and was so old any expansion or updating would have been too costly.  Plants in California, on the other hand, have been closing due to crushing regulations.  Valero’s Benicia plant (about 145,000 b/d) stopped refining this spring and was taken out of monthly capacity later.

The answer to refinery shrinkage has long been “expansion creep” in existing facilities because it’s faster than building brand new infrastructure, but this is not going to help for much longer.  Current facilities are limited in their ability add on more capacity and these measures do not account for abrupt global changes, wars and crisis events. 

The US needs redundancy, not “just in time” economics.     

Estimates suggest that up to eight new refineries (for heavy and light crude) running at least 250,000 b/d would be needed to increase the capacity ceiling while adding modern infrastructure and redundancy to offset aging plants.  A safer margin would be demand at 85%-90% of capacity.  This would also help the US to add supplies to any global market shortfall and keep prices from skyrocketing in the event of ongoing wars.  

What’s stopping this from happening?  There’s a number of obstacles.  First and foremost, no one wants to sink billions of dollars into a new facility based on higher gas margins that might be temporary.  In other words, investors will wait around until there’s a catastrophic disruption and prices go out of control, but by then it will be too late.

This means it’s likely that the only way to get new refineries built would be for the US government to partially backstop the investment.  It’s not the worst way to spend taxpayer money; everyone likes lower gas prices.  Getting such a measure passed through congress is questionable, though. 

One possible avenue would be profit sharing with taxpayers on excess fuel sold, or on exports sold from new refineries.  This is similar to the Saudi Arabia model, which invests some oil profits back into healthcare, education, housing loans, and cheaper fuel and utilities for citizens.  Of course, Saudi Arabia is a monarchy and moving from theory to practice in the US is another matter.  

Then there’s the permits, environmental studies and regulations, and a lot of other red tape that can extend build time up to 10 years.  Even with a streamlined bureaucracy, it can still take 3-5 years.  With government aid, the time can be reduced to 1-3 years.  It’s clear that this is not a quick fix in any scenario, but if the process had been started a few years ago, then there would be no capacity issue and there would be no need for this discussion.

Again, the US economy is almost designed to avoid redundancy and preparedness.  

There is the possibility that a rush to build refineries is unnecessary in the short term.  With ship traffic in the Hormuz returning to normal, prices on oil will continue to drop.  This does not mean, though, that gasoline prices will fall in tandem, at least not for months to come.  The war in Ukraine also looks like it will be ongoing for some time, which means Russian supplies will not be returning to global markets.  

Refineries are a long term solution which requires long term planning; something which is nearly impossible within the US where the political landscape changes every 2-4 years.  It is also extremely difficult when half the government under Democrats wants to tear down oil infrastructure and force the country to accept inefficient green tech.  The point is, there are obvious fixes available, but nothing will happen until disaster strikes and politicians are effectively frightened.  

Tyler Durden
Sun, 10/04/2026 – 13:30

“First Time In History”: Bessent Says Iran Faces Zero Oil Revenue As Tanker Loadings Collapse

0
“First Time In History”: Bessent Says Iran Faces Zero Oil Revenue As Tanker Loadings Collapse

Treasury Secretary Scott Bessent joined Mike Allen for a new episode of “The Axios Show,” published Saturday morning.

Bessent spoke about the Iran war’s effect on the cost of living for US consumers and his “I am the house” comment early last month, which warned anyone betting against the Treasury’s defense of the long end of the market.

Beyond the broader global bond rout, his comments on the Strait of Hormuz added color to President Trump’s economic stranglehold on Tehran.

“They are isolating them economically like this never happened before. You know, right now, the score: barrels out of the Strait: U.S. about 1.1 billion, Iran zero,” Bessent told Allen.

Bessent continued, “For the first time in history, they, since they started pumping oil, they will have no oil on the water this week. They will have no revenue.”

Separately, last week, Goldman analysts Yulia Zhestkova Grigsby, Alexandra Paulus, and Daan Struyven told clients that a “divergence between the fall of Iranian exports and the rise of exports of other Persian Gulf producers” was underway.

The Goldman energy experts estimated that “dark exports” have helped boost Persian Gulf oil exports to 23.3 million barrels a day over the past week, back to prewar levels.

Also last week, Bloomberg News reported that Iran’s crude loadings crashed to zero in August from around 250,000 barrels per day.

Data providers Kpler and Vortexa also recorded zero crude loadings last month.

The collapse in Iranian crude loadings suggests the US naval blockade is constraining Tehran’s export options, while recovering flows from other Gulf producers point to eroded Iranian leverage over the strait. If sustained, Tehran’s oil revenues would plunge, pressuring the regime to make a deal. 

Tyler Durden
Sun, 10/04/2026 – 12:30

Why So Many Social Science Claims Are False

0
Why So Many Social Science Claims Are False

Authored by Christopher J. Ferguson via RealClearInvestigations,

One of the most urgent questions facing society today is the potential impact of AI on education and labor markets. So it’s no surprise that two scientists attempted to provide an answer, producing a meta-analysis suggesting that incorporating ChatGPT in schooling dramatically improved student outcomes. Social media and online sources promoted the 2025 study as a beacon of bright light.

The problem is that the researchers’ conclusions were later found to be unreliable, and the study was retracted in April – another blow to the public’s faith in science.

Scientists are increasingly chasing answers to big questions in fields from health care to climate change to AI. The academic research industry incentivizes them to produce the biggest possible findings that make for splashy headlines and career promotions. But such discoveries are rare in science, and too often, the result is widespread exaggeration, dodgy methods, and miscommunication.

“The incentive structure of modern science is such that a ‘simplify, then exaggerate’ strategy has become dominant, even if only tacitly,” according to a recent academic review. “To get published in leading journals, to be awarded grants and to be hired as a postdoc or faculty member, a system-wide bias for novelty, exaggeration and storytelling has emerged.”

As RealClearInvestigations has previously reported, an alarming amount of poor-quality academic and scientific research has been discovered in recent years. Hindawi, formerly a part of major science publisher Wiley, had to retract thousands of science articles, many of them alleged to have been produced by paper mills that generate reams of reports of studies that never existed.

Big discoveries are rare in science, but the academic research industry incentivizes scholars to turn small findings into splashy headlines.
AP

While cases of outright fraud have received wide attention, a more subtle infection has spread within the research community: Research results that are inconsistent, based on poor methodologies, or are of limited practical impact are too often transformed into big, broad, but unreliable claims that, over time, reduce public confidence in science.

Several recent high-profile retractions of scientific papers highlight how broad scientific claims can be built upon questionable data. A recent paper asserted that banning sex work increases rapes. The sex work paper got significant attention on social media before skeptical scholars pointed out they couldn’t replicate the findings. In another major case, economists estimated that climate change would have a devastating economic toll on the world in a paper that was widely covered and influential in banking. However, it was ultimately retracted after other scholars alleged major errors.

In each case, science sleuths found that the dramatic claims did not reflect reality. While the number of retractions has soared over the past two decades to several thousand a year, according to the watchdog group Retraction Watch, experts believe only a small fraction of questionable work gets caught.

Flip a Coin

Lee Jussim, distinguished professor of psychology at Rutgers University and frequent critic of social science, has estimated that the vast majority of psychology research claims are false. He also noted that the ability of psychology to replicate most findings is no better than a coin toss.

At the core of the crisis is a broken system that pressures researchers to produce more and more papers in high-profile journals that favor bold rather than incremental (or null) findings. The incentives include:

  • Academic reward systems that grant promotions, tenure, and grant funding to researchers based on the number of publications and bold claims they produce rather than thoughtful scholarship
  • Journals that often attract subscription dollars and news attention for flashy findings
  • News media that win subscriptions and clicks with dramatic, often surprising claims about human behavior
  • Politicians who cherry-pick alarmist science claims to promote their favorite policies while overlooking contradictory evidence

“The growing competition and ‘publish or perish’ culture in academia might conflict with the objectivity and integrity of research, because it forces scientists to produce ‘publishable’ results at all costs,” Daniele Fanelli, a meta-scientist at Heriot-Watt University and the London School of Economics, noted in a recent paper.

The system set up to tamp down sensationalism and flawed findings – peer review – is so overwhelmed by the flood of research papers in recent years that it can’t begin to pull all the weeds from the garden of science. Peer reviewers are busy scholars who are mostly unpaid and stretched too thin, even with the help of emerging AI tools that have their own problems with accuracy. One recent paper estimated that, in any given year, peer reviewers collectively work the equivalent of 15,000 years on scientific papers, which, if actually paid, would cost about $2.5 billion for U.S., Chinese, and U.K. reviewers alone.

Even when errors are detected, correcting and retracting papers is a contentious process that often takes years. Publishers and editors fear reputational damage and lawsuits from researchers, providing few incentives for correcting the record even if fraud is suspected.

Numbers Game

A common type of research exaggeration stems from the promotion of “statistically significant” findings. The seriousness of the phrase may lead the public to interpret the findings as reliable and practically useful. But often that’s not the case. That’s because most social science and medical findings are very weak, so weak they might be produced by methodological flaws (or crud) in those studies. Scientists are nonetheless incentivized to highlight the supposed importance of statistically significant studies in order to get attention, even if they don’t warrant it.

As an analogy, consider the difference between a butterfly and an anvil landing on one’s head. Both exert measurable weight on the head and, as such, both produce “statistically significant” results. But the magnitude of impact, the effect size, differs enormously. Most people would be far more concerned to avoid an anvil landing on their head than a butterfly. That’s why “statistically significant” tells us nothing about the practical importance of a finding.

Even a finding with a standard effect size may not be reliable. For instance, social psychologist Daryl Bem published a report in one of the American Psychological Association’s leading journals suggesting that ordinary people had extrasensory perception, or the ability to predict the future. Such an implausible finding raised considerable controversy at the time.

The problem was that Bem used weak research methods common throughout the social sciences to publish impossible results. Long a defender of ESP, Bem had in an earlier paper explicitly noted that the effects of ESP appeared similar to findings in other areas of psychology, saying, “The mean effect size is quite respectable in comparison with other controversial research areas of human performance.” Bem did not respond to requests for comment.

Professor Fanelli said that poor training and unrealistic expectations help explain why social scientists miscommunicate data. “I think that part of a useful cultural change would be towards a greater understanding and acceptance of the limitations of social science,” Fanelli said in an email. “Instead, a lot of it seems to have in some ways reinforced what was deemed the ‘cult of statistical significance,’ a mechanical and simplistic use of [statistical significance] as a paragon of validity.”

Behind this presentation of hyped results is an academic publishing industry of five big companies with handsome profit margins. The Big Five, as they are known (Elsevier, Sage, Springer Nature, Taylor & Francis, Wiley), along with research grant funders, academic tenure evaluations, and the media incentivize scholars to stretch for the dramatic and oversell weak results. In science, a negative finding that shows no effect is as important as a positive one. But few negative findings get published.

Policymakers tend to make things worse. Catherine Knibbs, a psychotherapist and founder of Children and Tech, had been involved in some of the conversations around the controversial U.K. push for social media bans for youth under 16. She suggests policymakers often approach science with set conclusions, not open questions, and appear incurious about data that doesn’t fit their agendas.

“To be honest I feel science is complex and whilst I love that about it, I [feel] quite alone in this,” Knibbs said in an email. “People are often skimming the stats and looking for [evidence that confirms their beliefs]. Not many people have time to slow down and use their slower cognizant processes. It’s why we have the chicken little sky is falling down shit.”

Pushing for Reform

The good news is that a growing number of researchers are pushing for reforms that could improve the integrity of scientific findings. One promising sign is the growth of the “open science movement,” which encourages the preregistration of studies. This reduces the ability of researchers to mangle their data analysis to produce preferred results. And the movement’s promotion of greater data transparency allows for more confirmation of findings.

Brian Nosek, a professor of psychology at the University of Virginia who is leading the open science movement, struck a hopeful tone. “My most optimistic take is that we have established a stronger culture of self-scrutiny and continuous improvement,” he said. “I don’t know how successful the practice changes have been, but I believe that experimenting with new research methods and committing to evaluating what works and what doesn’t will lead us in positive directions.”

Some scholars are breaking away from the Big Five academic publishers by beginning their own nonprofit scientific journals. In some cases, this has been the result of exorbitant fees that journals charge authors for making papers public. A new federal legal case likewise accuses the Big Five of defrauding the government through unreasonable publishing charges, often paid for by government grants. Aside from the financial costs taken on by scholars, independent journals also potentially free scholars from a heavy focus on positive findings or publication bias.

A small number of research institutions are also trying to directly address some of the problematic incentives. In awarding promotions and tenure, they are putting less emphasis on the number of papers that researchers produce and the prestige of the journals where they are published. Instead, the quality of the paper is what counts.

Professor Ric Ferraro, editor of Current Psychology, emphasized that not all scholars or journals are bad actors. Some try to do the right thing and produce solid research. But breaking this cycle of perverse incentives will be difficult, as too many benefit from it, from scholars and academic journals to news media and politicians.

Until the incentives for research change more broadly, the public will continue to be fed a steady diet of bold claims about human behavior built on an unsteady foundation.

This article is part of an RCI series on The Normalization of Scientific Fraud. Read the previous articles here.

Tyler Durden
Sun, 10/04/2026 – 12:00

“In The Name Of God”: Yemen Leader Orders All-Out Offensive Against Iran-Backed Houthis

0
“In The Name Of God”: Yemen Leader Orders All-Out Offensive Against Iran-Backed Houthis

Saudi Arabia and Yemeni government forces have been preparing for a major offensive against Iran-backed Houthis, whose latest advances along Yemen’s western coast have tightened their control over coastal areas and disrupted a critical maritime chokepoint known as the Bab el-Mandeb Strait. Bloomberg now reports that the operation is underway.

The outlet reports that Rashad Al-Alimi, head of Yemen’s Presidential Leadership Council, ordered all branches of the armed forces into active combat operations on Sunday.

“All state military, security and civil institutions as of this moment are mobilized and on high alert until the mission is completed and victory is achieved,” Al-Alimi said on Sunday.

He said the operation would continue “until the liberation of the country from the grip of the terrorist Houthi militia.”

Our reporting on Saturday indicated that more than 100,000 Yemeni pro-government troops were set to mobilize for the offensive. Last month, the ease and speed of Houthi gains proved humiliating for the Saudi coalition in Yemen.

The Houthis largely stayed out of the US-Israeli war against Iran. But by midsummer, the terror group had announced a blockade of Saudi ships in the critical maritime chokepoint in response to what it described as a “siege” of Yemen. It has since repeatedly attacked the kingdom, including its oil facilities.

On Saturday, multiple reports and footage circulating on X showed what appeared to be smoke rising from Saudi Aramco’s Riyadh refinery.

Reuters reported Friday that Saudi air power would support Yemeni ground forces. The report did not specify which aircraft had been deployed for the operation, but the Saudis operate US-built F-15s, Eurofighter Typhoons and Tornado strike aircraft.

Beyond the Bab el-Mandeb Strait, the latest data from Goldman show that crude oil flows through the Strait of Hormuz are back to pre-war levels, an indication that Tehran’s leverage in the region has quickly eroded.

Tyler Durden
Sun, 10/04/2026 – 11:30

10-Year Cost Of Democratic Socialist Policies Could Hit $350,000 Per Household, White House Says

0
10-Year Cost Of Democratic Socialist Policies Could Hit $350,000 Per Household, White House Says

Authored by Jacki Thrapp via The Epoch Times,

American taxpayers would face a net fiscal burden of over $350,000 per household in the next decade if the Democratic Socialists of America’s top policies were adopted, according to a report released Oct. 1 by President Donald Trump’s Council of Economic Advisers.

The report predicted a net fiscal burden of more than $49 trillion from 2027 to 2036 – larger than the national debt, which hit a milestone of $40 trillion in August.

The report added up the presumed costs for Democratic Socialists of America’s agenda items such as loosening border restrictions, handing out amnesty to all illegal immigrants in the country, abolishing the police and U.S. Immigration and Customs Enforcement (ICE) officers, eliminating prisons, providing government-run healthcare for everyone, and canceling all student debt.

The majority of the cost would come from Medicare for All, which is predicted to cost $47.4 trillion out of the $52.8 trillion in gross costs, which was lowered to nearly $49 trillion due to the estimated $3.9 trillion that would be collected from the wealth tax.

Medicare for All proposals would transform the United States into a single-payer healthcare system in which the federal government covers all medical services, eliminating the out-of-pocket costs for patients.

The second most expensive proposal, according to the report, would be canceling student debt and making college free. That comes at a price tag of $3.6 trillion.

Student Loan Debt Statistics by the Education Data Initiative suggest that Americans currently owe roughly $1.9 trillion in student debt. Nearly $1.7 trillion of that debt is held by the federal government and is owed by nearly 43 million loan recipients.

The third-largest spending item would come from a mandated 32-hour workweek, costing approximately $918 billion in lost tax revenue.

The Trump administration described the proposals’ potential impact on the economy, suggesting they would make everyday costs skyrocket with double-digit inflation and prices rising an extra 130 to 160 percent over 10 years.

The Epoch Times contacted the Democratic Socialists of America for comment and did not hear back by publication.

The report came out the same day Trump kicked off his 32-day campaign blitz for Republicans facing tough races in the November midterms.

During a speech at Peterbilt Motors’ factory in Denton, Texas, on Thursday, Trump highlighted the resurgence of manufacturing in the United States and touted the economy’s performance under his administration.

“We announce all these great numbers,” Trump said. “The best numbers in the history of any president. There’s never been any president that’s got $21 trillion invested in our country. Not even close.”

The president also showed his support for Texas Attorney General Ken Paxton, a Republican, who is in a tight U.S. Senate race against Democrat James Talarico.

After the speech, Trump made a rare presidential visit to the Choctaw Nation of Oklahoma for a rally. Only a handful of U.S. presidents have visited tribal nations while in office.

Tyler Durden
Sun, 10/04/2026 – 11:00

Zelensky Vows To Hammer More Russian Refineries As G7 Greenlights Emergency Fuel Dump

0
Zelensky Vows To Hammer More Russian Refineries As G7 Greenlights Emergency Fuel Dump

President Volodymyr Zelensky told Reuters in an exclusive interview that Ukraine plans to intensify attacks on Russian oil refineries in response to continued strikes on Ukrainian cities. The threat comes as the Trump administration pressures European allies to release up to 100 million barrels of emergency oil and diesel stocks ahead of the Northern Hemisphere winter, with a global refining crunch already straining fuel supplies.

Zelensky told the outlet that Ukrainian intelligence had obtained documents outlining what he described as Russian President Vladimir Putin’s new war doctrine to broaden attacks on civilian infrastructure ahead of winter.

“We saw documents and we know that they allow them to attack infrastructure, logistics, and especially to attack in the cities, in the villages, everywhere, roads, schools, hospitals,” Zelensky said. “To pressure people to leave the capital, leave different cities: this is the goal of the operation.”

Zelensky then said, “We have to respond in any way (we can). With their attacks on our energy, we have to respond on their energy. First of all, oil refiners, etc.: what gives money to them for this war. But we will not respond, of course, just like them, on any civilian objects.”

Zelensky’s plan to further destroy Russia’s refineries comes as the Trump administration seeks to revive peace negotiations. Zelensky said Russia had shown no willingness to discuss either peace talks or a ceasefire covering energy infrastructure.

The Trump administration’s move to pressure European countries and other G7 members into releasing as much as 100 million barrels of emergency oil and diesel stocks, as confirmed by French President Emmanuel Macron on Friday, is likely in response to Zelensky’s expanding drone and missile attacks on Russian energy assets, as stockpiles for critical fuels are well below seasonal levels for this time of year. 

The International Energy Agency is coordinating the emergency release, which will take place over the next four months, according to Macron.

Goldman energy analyst Nikhil Bhandari warned last month that the global refining crisis stems from a combination of disruptions in the Strait of Hormuz and, more importantly, Ukraine’s bombardment of Russian refineries. Those attacks have prompted Moscow to extend its diesel export halt, suggesting the refining crisis could linger well into next year and keep refined-product prices elevated. 

Meanwhile, last Thursday at the Valdai Discussion Club in Moscow, Putin warned the Western allies to cease their escalation in Ukraine, stressing he’s willing to use “all weapons” in the Russian arsenal in the scenario that Russia’s exclave of Kaliningrad comes under attack.

Tyler Durden
Sun, 10/04/2026 – 10:30

French Feminist Convicted Of The Crime Of “Public Insult” For Refusing To Call Transgender Mayor A “Woman”

0
French Feminist Convicted Of The Crime Of “Public Insult” For Refusing To Call Transgender Mayor A “Woman”

Authored by Jonathan Turley via JonathanTurley.org,

Dora Moutot is a feminist who has dedicated much of her life to fighting for women’s rights and has built a following on social media. Like other feminists, Moutot does not view transgender women the same as biological women. She has now joined others who are facing criminal charges for expressing those views. Transgender advocates have demanded that she be punished for her views in France.

Moutot recounted how transgender activists demanded that she be more “inclusive” in how she referred to “women.” She refused, and explained that “being a woman is a biological fact and that I didn’t think saying so should be controversial.” She was immediately denounced as a “transphobe and a TERF (trans-exclusionary radical feminist), a term I’d never even heard before.”

What followed was all too familiar. A cancel campaign led to her brand partnerships being canceled. In 2022, she was invited on a French TV program to discuss transgender issues with Marie Cau, France’s first transgender mayor. On the program, she was asked if she thought Cau was a woman. Moutot responded, Cau “is a man, a transfeminine man.”

That was all it took. Transgender advocates had their case and filed charges for “public insult,” which is a crime in France with a maximum punishment of one year in prison and a fine of up to €45,000 for insults committed against a person because of their sex, sexual orientation, gender identity, or disability.

Free speech has long been in a free fall in France. Many disagree with Moutot and they are accorded free speech to denounce her views. However, Moutot is not extended the same protection based on the content of her views.

These laws criminalize speech under vague standards referring to “inciting” or “intimidating” others based on race or religion. For example, fashion designer John Galliano has been found guilty in a French court on charges of making anti-Semitic comments against at least three people in a Paris bar. At his sentencing, Judge Anne Marie Sauteraud read out a list of the bad words used by Galliano to Geraldine Bloch and Philippe Virgitti, including using ‘dirty whore” in criticism.

In another case, the father of French conservative presidential candidate Marine Le Pen was fined because he had called people from the Roma minority “smelly.” A French teenager was charged for criticizing Islam as a “religion of hate.”

This is a nation that still echoes the cry of Liberty, Equality, and Fraternity (“liberté, égalité, fraternité”). However, in today’s France, “liberté” is no longer valued. Individual rights of religion and speech are routinely sacrificed in the name of “equity” and “fraternity.”

In my book The Indispensable Right, I discuss the decline of free speech in France and other nations. As we face our own growing anti-free speech movement, citizens need to take a long look at countries like France to see what awaits us down this path. Europe went down this slippery slope of censorship decades ago, and the desire to silence others has now become an insatiable appetite.

As in this case, activists spend more time silencing opposing views than responding to them. For transgender activists, it is intolerable for feminists like Moutot to hold contrary views. Instead of addressing her viewpoints in public, they want her declared a criminal. Censorship then becomes an insatiable appetite for groups to silence their own critics.

Moutot describes the Orwellian take on free speech in France today:

“The judge did not impose the course, but in May, I was found guilty of ‘public insult’ and fined €4,754. The judge found that though my statements were made in the context of a debate, they constituted an ‘abuse of freedom of expression warranting the imposition of a criminal penalty commensurate with the harm thus caused to the values protected by our democratic society.’ In other words, the judge concluded my intent had been to cause harm.”

It is chilling to think of a judge willingly participating in such censorship, but this is now standard in the country. In the meantime, transgender activists are not done with Moutot, whose very existence appears to outrage them:

“In June, just weeks after my conviction, another LGBT organization filed six more complaints against me and my colleague Marguerite Stern. These new charges target specific statements we made on social media and on our feminist blog and YouTube channel Femelliste. They include our opinion that ‘men’ were ‘demanding access to our spaces’ and the question: ‘On what grounds should trans women’s fear of being mocked in men’s toilets take precedence over women’s fear of being raped?'”

This speech would be entirely protected in the United States. However, the case is a chilling cautionary tale for Americans fighting a resurgent anti-free speech movement. This is the slippery slope of censorship that awaits us if we abandon our defining commitment to free speech. After the removal of much of the censorship system established during the Biden Administration, American censors did not take jobs at Starbucks. They continue to peddle their expertise in regulating and silencing the speech of others.

It is a dire future. Just ask Dora Moutot.

Jonathan Turley is a law professor and the New York Times best-selling author of “Rage and the Republic: The Unfinished Story of the American Revolution”.

Tyler Durden
Sun, 10/04/2026 – 09:20

“We Don’t Need To Sell The Story Anymore”: Nuclear Wins The Argument At WNA 2026… Now Everyone Is Racing For Bronze

0
“We Don’t Need To Sell The Story Anymore”: Nuclear Wins The Argument At WNA 2026… Now Everyone Is Racing For Bronze

For most of the 2010s, the annual World Nuclear Association symposium in London was an exercise in group therapy: an industry reeling from Fukushima, German shutdowns and a seven-year uranium bear market, explaining to an indifferent world why it deserved to exist. Not anymore.

This year’s gathering (Sept 9-11) drew a record crowd: attendance was up 17% from last year per BofA, with more than 1,000 delegates from 50 countries and 35 new WNA members. And the mood had changed completely. As Cameco CEO Tim Gitzel put it during his fireside chat:

“We don’t need to sell the [nuclear] story anymore, we just need to convert it to action.”

CIBC analyst Anita Soni, who also attended, summed up the three days the same way: “nuclear energy has largely won the policy and market acceptance debate, with attention now turning to execution at scale.” The question is no longer whether the world builds reactors, but whether anyone can build them on time and on budget. On that front, the industry’s track record needs little comment.

There’s also a catch that Gitzel, whose Cameco owns 49% of Westinghouse, was candid about: in the West, nobody wants to go first. “Everyone is racing for bronze,” he said. Most utilities would rather be the third to build a new large reactor than risk being the first. Constellation’s Jason Murphy confirmed this from a separate panel: CEG is one of the companies that would “prefer to be third, not first.” This is how you end up with a race in which all the runners stay at the starting line watching each other.

The symposium lined up nicely with the IAEA’s annual outlook, which raised its long-term nuclear projections for the sixth consecutive year. Under the high case, global capacity hits 1,045 GWe by 2050 (from 992 GWe in last year’s edition) and 1,284 GWe by 2060, or about 3.4x the 377 GWe operating at the end of 2025. Even the low case now roughly doubles capacity by 2060.

According to Northland’s Jeff Grampp, the more important point is that the low case moved most: +14% to 641 GWe, versus +5% for the high case. In his view this “suggests a de-risking of the long-term growth narrative.” North America’s low case also flipped from contraction last year to growth this year (136 GWe by 2050, vs 98 GWe previously).

Source: ZH using IAEA figures cited by Northland and CIBC

Northland makes two further points we agree with:

  • The forecast is bottom-up and not reverse-engineered from a net-zero scenario, “which we think make these projections more credible/realistic.” In other words, nobody started with 1.5°C and worked backward.
  • The driver has changed from climate to energy security. “While its zero carbon attributes are compelling, we think the energy security investment case is stronger and more resilient than climate-based investment, which can ebb and flow with political regimes.” We’ve been saying the same for years, and it’s hard to argue with after watching Germany’s economy minister call for a “nuclear rethink” as energy prices surged in April. Better late than never.

Then there are SMRs. Last year the IAEA saw small modular reactors taking 5%-24% of new capacity by 2050, a range so wide it was nearly meaningless, with the low end at a “paltry” 16 GWe. This year the band is 23%-28%, or about 120-285 GWe. In North America, ~60% of new nuclear capacity is expected to come from SMRs. Readers will know that we’ve long argued modular, behind-the-meter reactors are the only real long-term answer to the AI power problem, so it’s nice to see the IAEA catching up (for much more, see “Bring Your Own Power Plant: Behind-The-Meter To Power 25% Of All Data Centers By 2030“).

CIBC’s Krista Friesen, in her Weekly Blueprint, adds a point that gets far less attention: the existing fleet is old. Two-thirds of operating reactors are more than 30 years old, and 46% are over 40. Even in the high case, about one-third of today’s capacity retires by 2060. The industry therefore has to keep building just to stand still, and in 2025 it didn’t quite manage that. Seven reactors (2.8 GW) were retired and only three (3.0 GW) were connected. Nuclear generation grew 1.1%, overall electricity generation grew 2.7%, while nuclear’s share of global power fell to 8.4% from 8.7%.

The $6 trillion question

Day 1 of the symposium was a Finance Summit, and the headline number was large. Meeting the “Tripling Declaration” would require about $6 trillion over 25 years, with annual nuclear capex rising from about $80BN today to more than $250BN a year through 2050. (For reference, current aggregate national targets put global capacity at 1,457 GWe by 2050, which is almost a quadrupling.)

The notable change is that, as one Westinghouse/EDF/Orano/GE Vernova panel put it (per BofA), “A few years ago the question was whether there was sufficient investment money to do this. Now there is.” CIBC reports that discussions are “now focused less on whether institutions will invest and more on when.” The WNA also launched a World Nuclear Investment Guide to help turn a “specialized energy investment” into a mainstream infrastructure asset class. The goal is to take design, licensing, regulatory and supply-chain risk out of projects and leave only execution risk, which, based on history, is plenty.

The most useful comments came from the customers. On BofA’s “Beyond offtake” panel, ExxonMobil said plainly that “the nuclear industry doesn’t have a technology problem, it has a DEPLOYMENT problem”, and argued that the risk model is wrong. In LNG or CCGT projects, nobody expects the technology vendor to carry most of the risk. The owner-operator does. Exxon is preparing a report proposing a new delivery model.

Amazon, which is putting “real money on the table” behind X-energy, made a point that should be pinned above every regulator’s desk:

“No point for a PPA if the connections take 7 years.”

That’s the grid interconnection queue in one sentence, and it’s why we’ve been pushing “behind the meter” on-site generation for data centers (going so far as to tweet in December: “Make ‘behind the meter’ mandatory”). Demand isn’t the issue either: CIBC notes Microsoft plans to more than triple its data center capacity to over 38 GW by 2032 from about 12 GW, excluding rented neocloud capacity. Those gigawatts have to come from somewhere.

Meanwhile, China just builds them

While the West waits to see who goes first, China explained how it does things. Ma Yuanhua of State Nuclear Power Technology Corp. said China had 62 reactors operating (66 GW) and 58 under construction (69 GW) as of July, with targets of 110 GW by 2030 and 150 GW by 2035. The method is dull and it works: standardization, specialization, centralization. Targets include 80% design reuse, a 56-month construction schedule, 93%+ factory acceptance rates, and centralized procurement. (By comparison, some Western projects have spent longer than 56 months on permitting.)

Of course, it depends who is counting. SNPTC’s 58 includes projects China considers underway. The WNA only counts reactors once the first concrete has been poured, and by that stricter definition, per Goldman’s monthly tracker, China had 37 reactors under construction as of Aug 11, more than twice India (8) and Russia (7) combined, and nearly as many as the other 16 countries on the list put together (42). The U.S. doesn’t appear on the chart at all, which is the more telling number. As we summarized it on Aug 13: “China 37 nuclear reactors under construction; US 0.”

Source: @zerohedge on X; World Nuclear Association, data compiled by Goldman Sachs Global Investment Research

This is where “everyone racing for bronze” leads: the U.S. hasn’t even qualified for the race yet, while China is already building its next reactors.

The Western lesson was said out loud. Constellation: “The West should apply the China model.” Speakers backed a “license once, review once, build many” framework, and there’s real movement. Finland’s regulatory overhaul cuts binding requirements from about 8,000 to 1,500, the U.S. NRC is changing its culture under the ADVANCE Act, and Europe’s ENGARD initiative aims to harmonize design reviews across countries.

Other highlights from around the world:

  • Japan is back. TEPCO restarted Kashiwazaki-Kariwa Unit 6 on Feb 9 after 14 years offline. Kansai Electric says 15 reactors have now restarted since Fukushima, and Japan’s policy has moved from “reducing” to “maximizing” nuclear, with a 20% share targeted by 2040 and 11-14 new large reactors by the 2050s. We asked back in May whether new Japanese build was inevitable. The answer appears to be yes.

  • Poland has secured €17BN for its first plant, with three AP1000s in preparation.
  • Czech Republic is moving to 80-year operations and building new units plus a Rolls-Royce SMR.
  • USA: Following the May 2025 Executive Order calling for 10 large reactors under construction by 2030, DOE’s $17.5BN long-lead procurement program has letters of intent with seven unnamed counterparties. Some attendees are optimistic about 1-2 site announcements before the midterms. TerraPower has its construction permit and an active job site in Wyoming.
  • Africa: Togo’s president signed on to the tripling pledge and will host the NEISA summit in 2027, noting that Africa wants “partnerships and investment rather than technology handouts.”
  • Ships: HD Korea Shipbuilding presented on nuclear-powered commercial vessels, a timely follow-on to Washington laying the groundwork for offshore nuclear in July. Its risk disclosure was admirably honest: “It might not work.”

The real bottleneck: you can’t 3D-print a uranium deposit

This is where the symposium got most interesting for markets. Reactors can be standardized, financed and eventually built. The fuel to run them is a different problem. Here is what CCJ’s Gitzel said, via BofA:

Uranium mining is the bottleneck, as deposits are non-reproducible and lead times from discovery to production range up to 20 years; while fuel conversion, enrichment and fabrication can be more easily addressed with capital alone.

Kazatomprom’s Dastan Kosherbayev put it more bluntly: after years of underinvestment, producers will prioritize customers who give clear, long-term demand signals. Kazatomprom will “no longer turn down attractive eastern deals in anticipation of potential western demand.” Put simply, Western utilities that have been waiting for spot dips may find the East has bought the inventory. This comes as Russia banned sulphuric acid exports through year-end, threatening about 3MM lbs of Kazakh 2027 output, while Kazatomprom agreed to sell uranium to Rosatom’s Uranium One. Coincidences happen.

Northland ran the numbers, and they are large:

  • Uranium: At 0.4-0.5MM lbs per GWe per year, the IAEA’s 641-1,045 GWe range implies 288-470MM lbs of annual demand by 2050, versus about 168MM lbs today, and that’s before replacing depleted mines.
  • Enrichment: Excluding Russian and Chinese SWU, Western demand is about 28.5MM SWU against about 24.8MM SWU of supply (per Urenco). The West is already in deficit. In the IAEA high case, demand rises to about 57MM SWU, a ~32MM SWU shortfall, or up to 69MM if SMRs running on HALEU take 30%-50% share.
ZH chart built from Northland Capital Markets figures

Urenco confirmed this from the supply side: its order book has grown from €8.7BN in 2021 to €21.3BN, and it is adding 4.6MM SWU, almost a third more capacity, “based on a market assessment, not orders.” Separately, Constellation said LEU+ (fuel enriched up to 10%) will allow 24-month reload cycles across its fleet, and Silex/GLE expects its laser enrichment license near Paducah by 2027. As we noted when DOE put $2.7BN behind domestic enrichment in January, the fuel chain is where the money is going.

Prices are responding. BofA’s charts:

On uranium, the long-term contract price hit an all-time high of $96.50/lb (even if nuclear stocks have not noticed), above the prior 2007 peak of $95.00, as we noted in “Uranium Needs To Go Higher” earlier this month. BofA reaffirmed its forecasts: $104.20/lb for 2026 and $129.80/lb for 2027, which would be a new record, before easing to a long-term $84.75.

Spot has also been trading below term, as the chart above shows. BofA says the important change is who is buying. Producers’ share of term selling fell from 92% in 2023 to 76% in 2025, and “rising utility participation in the term market is a driver of higher U3O8 prices, as churn… is replaced by end-user consumptive demand.” In other words, less trading between hedge funds and more buying by utilities that actually need the fuel.

For those who think the move is over, here’s the 38-year chart. Uranium remains well below its 2007 nominal peak, even though the demand story is now much broader.

None of this is new to regular readers. Goldman flagged a cumulative 2.3 billion lb uranium supply deficit through 2045 in May when it added SMRs to its models, and we argued in August that the market is still underpricing the nuclear build cycle.

How to trade it: picks and shovels over reactor dreams

The sell side mostly agrees on direction, but not on where to position along the value chain:

  • BofA (Lawson Winder) “remains constructive” and names buy-rated U.S.-listed exposure: CEG, TLN, VST in power; CCJ and OKLO among vendors; and CCJ and STDN in the fuel cycle.
  • Northland (Jeff Grampp) is also long-term bullish but more careful on timing. He cut price targets on reactor developers (IMSR to $8 from $15, SMR to $10 from $16, NNE to $22 from $37) to reflect higher costs of capital (i.e., more dilution) and a slower 2030-2035 buildout. He instead favors fuel and supply-chain names that make money now: BWXT, LEU, EU, URG, MIR. Asked to choose between enrichment and uranium, Northland picks uranium.

That seems like the right reading of the symposium. The long-term story is intact and improving, with the IAEA raising forecasts again, hyperscalers writing checks and Japan back in the game. The near-term constraints are physical: fuel, forgings, workers and grid connections. Reactor developers have to wait for the first Western mover to deliver on time and on budget. Uranium miners and enrichers don’t. Both need the same uranium.

As Kansai Electric’s delegate said, the industry’s next phase is about “disciplined vision,” and increasingly about meeting in person, “becoming more analog in an increasingly digital world.” That’s also a fair description of uranium: a physical asset that can’t be replicated, needed to power data centers, and in short supply.

More in the full notes: BofA Global Research, “Postcard from the 2026 WNA Symposium” (Sept 15); CIBC Capital Markets, “2026 World Nuclear Symposium” (Sept 15) and “IAEA Raises Nuclear Outlook For Sixth Consecutive Year – The Weekly Blueprint” (Sept 14); Northland Capital Markets, “Takeaways From Updated IAEA Nuclear Forecast” (Sept 17), all available to pro subs.

Tyler Durden
Sun, 10/04/2026 – 08:45

Why Apartments In Tokyo Are So Much Cheaper Than In NYC

0
Why Apartments In Tokyo Are So Much Cheaper Than In NYC

Authored by Julia R. Cartwright via The Daily Economy,

Imagine it’s January in New York and you’re sharing a tiny apartment with two roommates. The walls are crumbling around you, and there’s a hole in your bedroom wall big enough to see outside. Every time it rains or snows, water drips into your room. You call your landlord to fix it over and over again, but nothing happens.

Tokyo apartment building by night. CAPTAINHOOK via Shutterstock.

This is reality for many New Yorkers. This degradation is the predictable result of decades of housing policy that has kept supply scarce and left rent-regulated buildings to decay. Many people blame it on big-city life, but lessons from Tokyo show us that it doesn’t have to be that way.

Tokyo Metropolis is home to about 14.27 million people, far more than New York City’s roughly 8.5 million. Yet renting in a city not quite twice the size costs a fraction of what it does in the biggest city in the US.

In the mid-1990s, a one-bedroom apartment in Tokyo cost about the same as one in New York, a little less than $1,000 a month. By 2025, a New York one-bedroom averaged about $4,400 per month, while a Tokyo one-bedroom ran about $1,270. A weaker yen explains part of that gap, but even in yen, Tokyo rents barely moved in 30 years while New York’s rents nearly tripled.

Housing prices ultimately come down to supply and demand. So how has Tokyo managed to keep housing relatively affordable, while New York has struggled to do the same?

Tokyo has been focused on keeping up with demand; its housing stock nearly tripled between 1963 and 2013, reaching 7.36 million homes. To do this, Japan keeps zoning flexible. Instead of limiting each area to a single use, zoning allows homes, shops, and light industry to coexist on the same blocks. Projects that follow these rules can be built “as-of-right,” without discretionary review or giving neighbors the power to block them.

Japan’s zoning rules are uniform across the country. The national government defines 13 standard zones instead of leaving land use to individual neighborhoods. That top-down approach cuts both ways, however, since a national system could tighten rules as easily as loosen them, but Japan’s has repeatedly loosened them to allow more housing.

New York City’s zoning works in nearly the opposite way. A site-specific rezoning goes through the Uniform Land Use Review Procedure, a review so onerous that about 40 percent of private rezoning proposals fail to get approved. About 27 percent of Manhattan’s lots are under restrictive landmark regulations, and historic districts see new buildings at about one-sixth the rate of other lots.

Then there are the empty NYC apartments. The 2019 Housing Stability and Tenant Protection Act capped rent increases on vacant rent-stabilized units and limited how much renovation cost landlords can recover. When a $700-a-month unit needs $100,000 of work to meet code, many owners leave it empty; this helps explain why nearly 57,000 rent-stabilized apartments were empty in 2025.

Continuing their stance of flexibility, Tokyo has allowed smaller apartments to be built. A typical one-bedroom is about 430 square feet, compared with 590 for a New York one-bedroom. Smaller apartments lower the barrier to entry for single renters and young professionals to get their own place.

New York spent decades making small units hard to build through a 400-square-foot minimum rule dating to 1987 and zoning rules called the “Dwelling Unit Factor” that forced large average unit sizes. The “City of Yes” amendment only eased those rules in December 2024, after decades of limiting the kinds of smaller, cheaper apartments Tokyo builds routinely.

Buildings in Japan also turn over faster. Japan’s tax code depreciates a wooden house over 22 years, and the average Japanese home is demolished at about 32 years old, versus roughly 70 in the US. Old stock gets replaced with newer, denser buildings instead of being preserved indefinitely.

Japan’s inclusive regulations result in much more building. Tokyo averaged about 155,000 housing starts a year from 1995 to 2015 and still starts roughly 130,000 annually; New York, by contrast, added roughly 50,000 in 2025. Since the 1960s, Tokyo’s stock has nearly tripled while New York’s has grown only 20 to 30 percent.

Factory-built homes also help ease supply constraints. One Japanese Sekisui House plant produces about 20 houses a day, and roughly 13 percent of new Japanese homes are prefab or modular. New York has only recently started experimenting with modular construction, and it remains a small share of the city’s building, far behind Japan.

To be fair, Tokyo isn’t cheap by Japanese standards, but it has accommodated millions without New York-style crumbling buildings and vacant units. New York is moving the other way: Mamdani’s Rent Guidelines Board froze rents for roughly one million stabilized apartments. The freeze helps current tenants but creates no new homes, and analysts expect more units to sit empty as prices for non-stabilized apartments keep rising.

The renter watching snow blow through the hole in her bedroom wall won’t be saved by another year of frozen rent. Instead of doubling down on the policies that brought scarcity, dilapidated apartments, and sky-high rents, New York could take a lesson from Tokyo, where the way to make housing affordable has been to make a lot more of it.

Julia R. Cartwright is an economist whose work specializes in law and economics, political economy, and economic development. Her research features topics like the governance structures of crypto markets, the economic consequences of judicial interventions in courts in East Africa, and the development impact of housing regulations.

Tyler Durden
Sun, 10/04/2026 – 08:10
