70.5 F
Chicago
Tuesday, October 6, 2026
Home Blog Page 998

DHS Weighs Private Bounty Hunters To Locate Illegal Immigrants

0
DHS Weighs Private Bounty Hunters To Locate Illegal Immigrants

Authored by Darlene McCormick Sanchez via The Epoch Times,

The Trump administration is exploring a program to hire bounty hunters who would track down illegal immigrants and receive bonuses for successful captures, according to a government contracting site.

​The Department of Homeland Security (DHS) and U.S. Immigration and Customs Enforcement (ICE) issued a request for information on Oct. 31 through the federal government’s central online portal for federal contracting opportunities to gauge interest from private bounty-hunting services.

​“DHS ICE has an immediate need for Skip Tracing and Process Serving Services using government furnished case data with identifiable information, commercial data verification, and physical observation services, to verify alien address information, investigate alternative alien address information, confirm the new location of aliens, and deliver materials/documents to aliens as appropriate,” the request stated.

​While the information gathering process isn’t the same as the government seeking a contract for services, it could lead to an opportunity in the foreseeable future.

​The idea is for ICE to provide skip-tracing companies—businesses specializing in locating individuals—with information on 10,000 immigrants at a time to locate over an initial 12-month period.

Extra assignments would be given in increments of 10,000, up to 1,000,000, over additional periods of time.

​Under the plan, skip-trace vendors would be paid to find illegal immigrants and serve them with documents.

​Such companies would verify address information for non-citizens provided by the government, research additional possible addresses for these individuals, confirm their current residence locations, and deliver required documents to them as needed.

​Bounty hunters would provide ICE with documented home and work addresses, phone numbers, vehicle information, and social media information.

​The proposed pay structure includes “monetary bonuses” based on three criteria: performance, volume, and quality of information provided by companies.

​Performance bonuses were proposed for vendors who verify an illegal immigrant’s residence or employment location on the first attempt.

Other factors include timely verification reports, the vendor’s success in document delivery, and obtaining signatures.

In a statement to The Epoch Times, a DHS spokesperson didn’t comment directly on using bounty hunters to help ICE.

“President [Donald] Trump and Secretary [Kristi] Noem are supporting our state and local law enforcement officers who are risking their lives to help locate the worst of the worst criminal illegal aliens, including murderers, rapists, pedophiles, gang members, and terrorists,” the spokesman said.

“We are providing our law enforcement agencies with the tools, training, and resources they need to enforce immigration laws while performing routine police duties.”

​This information request follows a September $1.9 million contract with Carahsoft Technology Corp. for AI-powered social media surveillance.

The Carahsoft contract detailed on UASpending.gov has a potential value of $5.7 million. The contract was for “Zignal Licenses for ICE Homeland Security Investigations” to provide real-time data analysis for criminal investigations.

The same system is currently used by the United States and Israeli militaries.

Earlier this year, states attempted similar bounty hunter programs.

​A Missouri bounty-hunter bill introduced in January targeted violent illegal immigrants but failed to move out of committee and died in the state legislature. The bill called for life without parole for dangerous illegal immigrants convicted of felony trespassing charges in Missouri.

​It would have allowed Missourians to earn $1,000 for reporting illegal immigrants who were arrested.

Lawmakers in Mississippi attempted to duplicate the Missouri bounty hunter bill, but it also failed to move out of committee.

In Arizona, state Republicans proposed a bill that would have incentivized police departments to target people believed to be in the country illegally by awarding them a $2,500 bounty for each arrest that ended in a deportation.

Like the others, Arizona’s Senate Bill 1111 failed to become law.

Tyler Durden
Sun, 11/09/2025 – 16:20

“Terrible Thing For Democracy”: BBC Top Brass Out After Misleading Trump Documentary

0
“Terrible Thing For Democracy”: BBC Top Brass Out After Misleading Trump Documentary

Update (1600ET): President Trump was quick to notice the ‘resignations’ and didn’t hold back in a post on his Truth Social media feed:

The TOP people in the BBC, including TIM DAVIE, the BOSS, are all quitting/FIRED, because they were caught “doctoring” my very good (PERFECT!) speech of January 6th.

Thank you to The Telegraph for exposing these Corrupt ‘Journalists.”

These are very dishonest people who tried to step on the scales of a Presidential Election.

On top of everything else, they are from a Foreign Country, one that many consider our Number One Ally.

What a terrible thing for Democracy!

We think the smile on his face below says it all.

*  *  *

As we detailed earlier, two top BBC executives are out amid a scandal over deceptive editing of a speech President Donald Trump gave on January 6th, 2021. 

Director General Tim Davie and the outlet’s news CEO, Deborah Turness, have resigned amid the controversy. 

“I wanted to let you know that I have decided to leave the BBC after 20 years,” Davie said in a statement, adding “This is entirely my decision, and I remain very thankful to the Chair and Board for their unswerving and unanimous support throughout my entire tenure, including during recent days.” 

Davie’s claim that “I have decided” is undoubtedly more fake news. These people can’t seem to stop lying.

According to the misleading clip, Trump said to supporters: “We’re gonna walk down to the Capitol and I’ll be there with you and we fight. We fight like hell, and if you don’t fight like hell, you’re not gonna have a country anymore.”

The comments were in fact made roughly 54 minutes apart, and meant to make it look like Trump incited the Jan. 6 capitol riot. Footage of protesters shown marching toward the Capitol immediately after the clip was in fact from before Trump began addressing supporters. 

The BBC is “100% fake news,” White House Press Secretary Karoline Leavitt told The Telegraph on Friday, adding that UK taxpayers are being “forced to foot the bill for a Leftist propaganda machine.”

“Every time I travel to the United Kingdom with President Trump and am forced to watch the BBC in our hotel rooms, it ruins my day listening to their blatant propaganda and lies about the president of the United States and all that he’s doing to make America better and the world a safer place.” -Karoline Leavitt

On Saturday, it was reported that the BBC is expected to apologize for the deceptive edit, with a spokesperson telling The Guardian that the organization’s chair would provide a “full response to the Culture, Media and Sport Committee on Monday.”

The newspaper said its reporting was based on a memo written by Michael Prescott, a former adviser to the BBC’s editorial guidelines and standards committee. Prescott left his role earlier this year and has not commented on the document, understood to have been leaked by a whistleblower.

It published an extract that read: “It was completely misleading to edit the clip in the way Panorama aired it. The fact that he did not explicitly exhort supporters to go down and fight at Capitol Hill was one of the reasons there were no federal charges for incitement to riot.”

The memo reportedly added that Prescott, a communications consultant and former political journalist, had raised concerns about the way BBC Arabic covered the war in Gaza. -Guardian

Tyler Durden
Sun, 11/09/2025 – 15:45

pAIn Ahead?

0
pAIn Ahead?

By Peter Tchir of Academy Securities

pAIn Ahead

We are barely off the record highs for the market, but the market has been acting peculiarly lately.

Maybe it is the lack of “official” data (we didn’t get NFP on Friday), or maybe it is because of the data that we have been getting. I honestly cannot remember the last time “Challenger, Gray, and Christmas” was mentioned as much as it was this week.

Let’s quickly run through a few things that have seemed peculiar, or even downright weird.

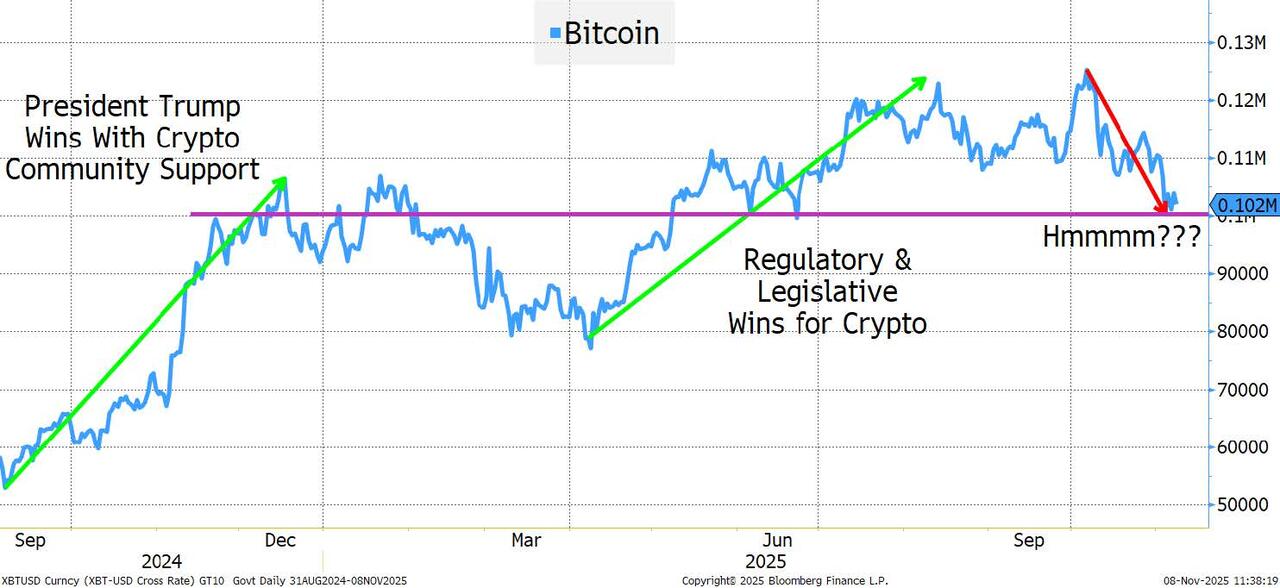
Bitcoin

I think it is safe to say that everyone keeps an eye on Bitcoin as a barometer for risk assets, especially on weekends, when markets are closed, but the news flow doesn’t stop.

Like most other risk assets, Bitcoin struggled as the admin focused on tariffs, culminating in the Liberation Day launch. Ultimately, little of the Liberation Day announcement came to pass, and risk assets responded strongly to backing off on tariffs, and a slew of other policies designed to support markets and the economy. The AI spending has played a major role in the economy and markets.

Over the years, the T-Report has used ARKK as a measure of performance for “disruption.” Year to date, it has crushed even the mighty QQQ (up 42% versus 20%). But since the morning of October 31st, it is down 10%, and was down 13% at the lows on Friday.

These moves “suggest” there could be a shift in tone and sentiment out there. Or at least in risk tolerance.

Retail Dip Buying?

So far this year (and possibly last year, and the year before that, and even the year before that), retail has stepped in to buy the dip.

Most noticeable was the dip buying as the admin changed their tune on tariffs, and pivoted to other policies.

We certainly saw some dip buyers this week. We will continue to see that. Wednesday had a shaky start but ground higher (at least until near the close, when there was a decent sell-off). On Thursday, the dip buyers tried, but failed, as we closed near the lows. On Friday, we finally saw a successful response to dip buyers. Was that the “all-clear” sign or a feeble attempt that won’t hold?

I’m not sure, but TQQQ (a triple leveraged QQQ ETF), is one of the first places I look for evidence that retail was driving this bounce.

Since the end of August, the Nasdaq 100 is up almost 6%, despite only brief, and relatively small, inflows into TQQQ.
Is the narrative that “retail” is chasing/driving this market real?

Or have “professional” investors latched on to that as an excuse/reason to be fully invested despite questions about “valuations”?

Was Friday retail buying the dip or pros covering shorts? I saw multiple comments late on Friday that the “most shorted” stocks were leading the charge higher, which seems more like a “pro” move than a retail move?

Volatility

VIX got as high as 22 on Friday. That wasn’t as high as it hit the Friday when it looked like China was cutting the U.S. off from rare earths and critical minerals and we were going to retaliate with 100% tariffs, but it caught my attention.

VIX has been creeping higher for the past two weeks, even when stocks were hitting new highs.

Yes, it could be that VIX was rising as everyone was loading up on bullish bets into year-end via options (we have seen that behavior before), but it didn’t have that feel.

In fact, I’ve been intrigued by realized vol.

10-Day realized vol has risen to about 20. It is worth pointing that out because:

  • VIX, if there is real “fear” being priced in, can trade well above realized vol, an indication of people paying up to get protection.
  • Rising volatility (and just as important, shifting cross-asset correlations) can cause any sort of “risk parity” strategy to de-risk.

Not sure we are at the point where we see any meaningful de-grossing of risk, but it is certainly worth watching, especially if it was professional investors (with stop losses) getting long on Friday rather than retail (which tends not to be forced into stop loss “discipline”).

More on “Sentiment”

There are only two things I looked at in Friday’s CONsumer CONfidence.

I want to know how Republicans are viewing the economy and how independent voters are viewing the economy.

Republicans are still more positive than they were in April. That is positive, though the direction is not great.

Independents are below where they were during peak tariff concerns.

That seems worth mentioning. It meshes with something I think I’m seeing in my social media streams.

I am not naïve and fully understand that Twitter tries to feed you stories it thinks you want, or wants you to want. Even trying to stick to people you follow is fraught with the risk that your stream is biased. I’m aware of that, hence why I’m tentative to even mention this.

But I’ve been noticing (in the comments) a change in support/pushback on the admin. Comments are subject to heavy “bot” usage. Really easy to program a bot to respond to tweets. It is more difficult to tell bots from real people as AI has made the bots sound more real. So, take this assessment with a grain of salt, but I’m seeing a lot more pushback, especially when it comes to inflation.

On “Twitter” inflation, I think you get a real reflection of what people think inflation is, rather than what the BLS tries to tell us it is. People know what they spend money on, and how much it costs (a sentiment that seems to be showing up in some recent fast/casual dining announcements).

This is why so many people have been pounding the table about alternative measures of inflation. Truflation was way ahead of spotting inflation while the Fed actually continued with QE. We were doing QE even as were discussing possible hikes. Still seems bizarre to me.

Truflation is also why so many people thought the Fed could cut sooner and more.

Truflation is creeping back above 2.5%. CPI is coming down (in no small part that it is finally capturing rent declines well after the fact, and so many other calculations remain dubious at best).

If you are worried about inflation going back up, Truflation seems to be reflecting that possibility.

Also, with over $200 billion of tariff revenue collected, we are starting to get more evidence (still sparse and still small) of tariffs impacting prices. In a world where no one wants to attract attention to their company on anything related to tariffs, expect more to come (regardless of how the Supreme Court rules on some emergency powers and tariffs).

Inflation and Electricity Inflation are already topical and may have influenced last Tuesday’s elections – these issues, especially electricity inflation, are likely to grow in importance.

Which Brings Us To Bonds

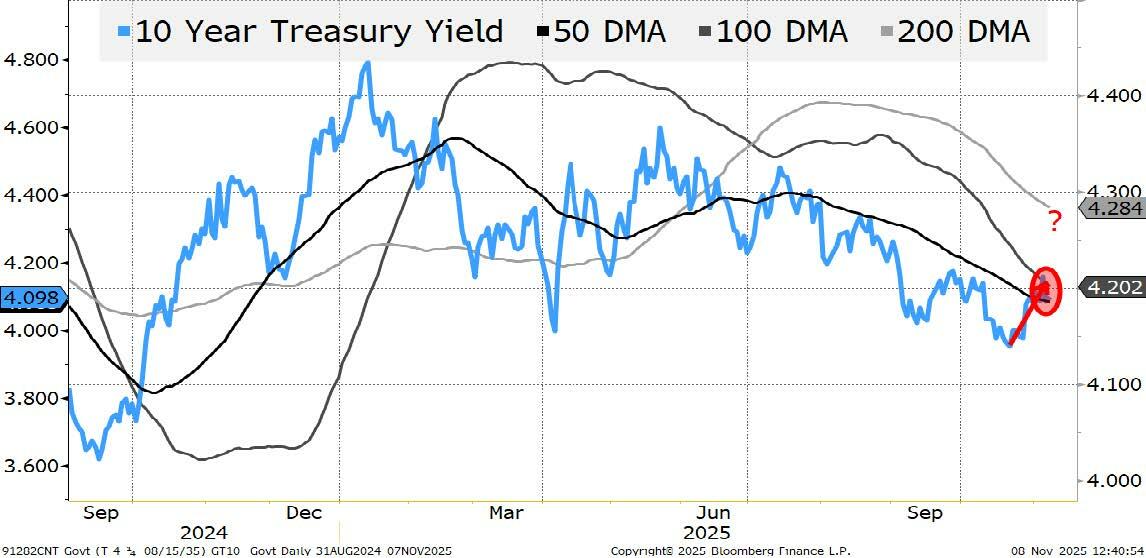
The Challenger layoff announcement “saved” Treasuries on Thursday.

I’ve been very comfortable with rate cuts and longer dated yields, but for now, I think the next move is to higher yields.

The Fed will not cut because of Challenger (I have yet to see a study showing it is a reliable indicator of much). ADP, on the other hand, came in at 42k. Disappointing, but in line with some estimates of “replacement” rate (the number of hires required to keep the unemployment rate stable).

There is some concern amongst some Fed officials, which I agree with, that inflation is very stubborn here.

While the admin will not allow 10s to “get out of control,” 4.3% (the 200-day moving average) seems like a reasonable short-term target.

Rising yields also fit with my concerns about risk parity potentially being forced to de-gross.

While generally I’m comfortable with credit spreads, I could see the next 10 bps in spread (CDX or Bloomberg Corporate Bond Index OAS) being wider rather than tighter.

Bottom Line

Sticking to our ProSec™ (Production for Security) themes. See any of our recent reports at Academy Macro. In case you missed it, here is a replay of Investing in a Pre-War World. It is relevant to governments, corporations, and investors. Secretary of War Hegseth had some recent comments that fit this “Pre-War” concept very well.

With seasonality favoring a push higher in stocks it is difficult to be too bearish, but the combination of things is making me cautious, even on some ProSec™ names, which have become part of the “momentum” trade:

  • Realized volatility is rising and cross-asset correlations seem to be shifting – creating the potential for a de-grossing/de-risking event.
  • Yields seem at risk of a reasonably large (25 bp) move higher on 10s.
  • The “retail is buying the dip” narrative doesn’t seem to hold water when looking at flows and/or sentiment indicators.

The potential for pAIn seems real and we didn’t even discuss many signs that the deal with China, much celebrated and rewarded by the market, doesn’t seem to be as good in the real world as it sounded on paper (or in media posts).

Tyler Durden
Sun, 11/09/2025 – 15:10

Shutdown Breakthrough: Dems Ready To Deal, Thune Hopeful As Thanksgiving Travel Looms

0
Shutdown Breakthrough: Dems Ready To Deal, Thune Hopeful As Thanksgiving Travel Looms

With the government shutdown having ground airline travel to a standstill – and Thanksgiving right around the corner, Senate Democrats on Sunday say they’re ready to advance a package of bills that could end the impasse, multiple sources have told Axios. 

Chuck Schumer and John Thune (Francis Chung/POLITICO) 

“At least 10 Senate Democrats are expected to support a procedural motion to advance a package of spending bills and a short term funding measure,” according to the report. 

What’s notable about this offer is that Democrats appear willing to accept a promised vote to extend the temporary pandemic-era Obamacare credits in December. 

Senate Majority Leader John Thune (R-SD), meanwhile, said on Sunday that if Democrats cross the aisle to get this done, he will offer another stopgap spending measure with a later expiration date combined with three full-year appropriations bills (aka a ‘minibus‘). 

If passed, this should hopefully unsnarl air travel in time for Thanksgiving…

While Bitcoin traders appeared to welcome the news:


Are we there yet?

Tyler Durden
Sun, 11/09/2025 – 14:00

Ukraine Hits Back: Two Russian Cities Without Power & Heating After Missile, Drone Attacks

0
Ukraine Hits Back: Two Russian Cities Without Power & Heating After Missile, Drone Attacks

We documented Saturday that the night prior witnessed one of Russia’s biggest ever assaults on Ukraine’s power and heating grid, including fresh strikes on thermal power plants, resulting in all state thermal facilities going down – plunging huge swathes of Ukrainian regions into darkness, including large areas of the capital.

But on Sunday Ukraine hit back, trying to beat Russia at its own game ahead of a frigid coming winter. Fresh Ukrainian cross-border aerial attacks have left two major Russian cities near the border without power and heating.

Prior image of Belgorod city in darkness, via RBC-Ukraine.

“A drone strike temporarily caused blackouts and cut heating to parts of Voronezh, regional Gov. Alexander Gusev said,” the Associated Press reports.

“He said several drones were electronically jammed during the night over the city, home to just over 1 million people, sparking a fire at a local utility facility that was quickly extinguished,” AP continues.

However, Telegram channels which monitor the war said the strike targeted a local thermal power plant. But the assault included missiles fired across the border as well. Per the report:

A missile strike late on Saturday also caused “serious damage” to power and heating systems supplying the city of Belgorod, with some 20,000 households affected, local Gov. Vyacheslav Gladkov reported the following morning.

Gov. Gladkov confirmed that the “electricity and heating supply network has suffered severe damage” in the regional capital in the statement.

And blackouts were also reported in the city of Taganrog – home to about 240,000 people – in the Rostov region. Overnight Russia’s defense ministry reported the military was able to intercept 44 inbound drones.

Meanwhile, Ukraine’s foreign ministry is warning of the risks to the country’s nuclear power plants due to Russia’s ramped up attacks of late.

“Russia once again targeted substations that power the Khmelnytskyi and Rivne nuclear power plants,” Foreign Minister Andrii Sybiha said on X late Saturday. “These were not accidental but well-planned strikes. Russia is deliberately endangering nuclear safety in Europe.”

He’s calling for an international response to the crisis, and has called an meeting of the International Atomic Energy Agency (IAEA) board of governors. The safety of nuclear power plants has remained a huge concern from nearly the start of the war.

Tyler Durden
Sun, 11/09/2025 – 13:25

Five Likely Scenarios Of US Regime Change In Venezuela

0
Five Likely Scenarios Of US Regime Change In Venezuela

Authored by Vijay Prashad via Consortium News

Since early September, the United States has given every indication that it could be preparing for a military assault on Venezuela. In February 2006, Venezuelan President Hugo Chávez travelled to Havana to receive the United Nations Educational, Scientific and Cultural Organization’s (UNESCO) José Martí Prize from Fidel Castro.

In his speech, he likened Washington’s threats against Venezuela to dogs barking, saying, “Let the dogs bark, because it is a sign that we are on the move.” Chávez added,

“Let the dogs of the empire bark. That is their role: to bark. Our role is to fight to achieve in this century – now, at last – the true liberation of our people.”

Almost two decades later, the empire’s dogs continue to bark. But will they bite? That is the question that this red alert seeks to answer.

Source: Rosana Silva R. via Tricontinental

The Sound of Barking

In February 2025, the U.S. State Department designated a criminal network called Tren de Aragua (Aragua Train) as a ‘foreign terrorist organization.’ Then, in July, the U.S. Treasury Department added the so-called Cartel de los Soles (Cartel of the Suns) to the Office of Foreign Assets Control’s sanctions list as a ‘transnational terrorist group.’

No previous U.S. government report, either from the Drug Enforcement Administration (DEA) or the State Department, had identified these organizations as a threat, and no publicly verifiable evidence has been offered to substantiate the claimed scale or coordination of either group.

There is no evidence that Tren de Aragua is a coherent international operation. As for the Cartel de los Soles, the first time the name appeared was in 1993 in Venezuelan reporting on investigations of two National Guard generals – a reference to the ‘sun’ insignia on their uniforms – years before Hugo Chávez’s 1998 presidential victory.

The Trump administration has alleged that these groups, working with Venezuelan President Nicolás Maduro’s government, are the primary traffickers of drugs into the U.S. – while providing zero evidence for the connection. Moreover, reports from the U.N. Office on Drugs and Crime (UNODC) and the DEA itself have consistently found Venezuelan groups to be marginal in global drug trafficking. Even so, the U.S. State Department has offered a $50 million reward for information leading to Maduro’s arrest – the largest in the programme’s history.

The U.S. has revived the blunt instrument of the ‘War on Drugs’ to pressure countries that are not yielding to its threats or that stubbornly refuse to elect right-wing governments.

Recently, Trump has targeted Mexico and Colombia and has invoked their difficulties with the narcotics trade to attack their presidents. Though Venezuela does not have a significant domestic drug problem, that has not stopped Trump from attacking Maduro’s government with much more venom.

A Nobel Prize

In October 2025, the Venezuelan politician María Corina Machado of the Vente Venezuela (Come Venezuela) movement won the Nobel Peace Prize.

Machado was ineligible to run for president in 2024 largely because she had made a series of treasonous statements, accepted a diplomatic post from another country in order to plead for intervention in Venezuela (in violation of Article 149 of the Constitution), and supported guarimbas (violent street actions in which people were beaten, burned alive, and beheaded).

She has also championed unilateral U.S. sanctions that have devastated the economy. The Nobel Prize was secured through the work of the Inspire America Foundation (based in Miami, Florida, and led by Cuban American lawyer Marcell Felipe) and by the intervention of four U.S. politicians, three of them Cuban Americans (Marco Rubio, María Elvira Salazar, and Mario Díaz-Balart).

The Cuban American connection is key, showing how this political network that is focused on the overthrow by any means of the Cuban Revolution now sees a U.S. military intervention in Venezuela as a way to advance regime change in Cuba. This is, therefore, not just an intervention against Venezuela, but one against all those governments that the U.S. would like to overthrow.

The Bite

In August 2025, the U.S. military began to amass naval forces in the southern Caribbean, including Aegis-class destroyers and nuclear- powered attack submarines.

In September it began a campaign of extrajudicial strikes on small motorboats in Caribbean waters, bombing at least thirteen vessels and killing at least fifty-seven people – without offering evidence of any drug trafficking links.

By mid-October, the U.S. had deployed more than four thousand troops off Venezuela’s coast and five thousand on standby in Puerto Rico (including F-35 fighter jets and MQ-9 reaper drones), authorised covert operations inside the country, and flown B-52 ‘demonstration missions’ over Caracas. In late October, the USS Gerald R. Ford carrier strike group was deployed to the region. Meanwhile, Venezuela’s government has mobilised the population to defend the country.

Five Scenarios for US Intervention Based on the Past

* * *

Scenario 1: The Brother Sam Option

In 1964, the U.S. deployed several warships off the coast of Brazil. Their presence emboldened General Humberto de Alencar Castelo Branco, chief of the Army General Staff, and his allies to stage a coup that ushered in a twenty-one-year dictatorship.

But Venezuela is a different terrain. In his first term, Chávez strengthened political education in the military academies and anchored officer training in defense of the 1999 Constitution. A Castelo Branco figure is therefore unlikely to save the day for Washington.

Scenario 2: The Panama Option

In 1989, the U.S. bombed Panama City and sent in special operations troops to capture Manuel Noriega, Panama’s military leader, and bring him to a U.S. prison while U.S.-backed politicians took over the country.

Such an operation would be harder to replicate in Venezuela: its military is far stronger, trained for protracted, asymmetric conflicts, and the country boasts sophisticated air defense systems (notably the Russian S-300VM and Buk-M2E surface-to-air systems).

Any U.S. air campaign would face sustained defense, making the prospect of downed aircraft – a major loss of face – one Washington is unlikely to risk.

Scenario 3: The Iraq Option

A ‘Shock and Awe’ bombing campaign against Caracas and other cities to rattle the population and demoralise the state and military, followed by attempts to assassinate senior Venezuelan leadership and seize key infrastructure.

After such an assault, Nobel Peace Prize winner Machado would likely declare herself ready to take charge and align Venezuela closely with the U.S.

The inadequacy of this maneuver is that the Bolivarian leadership runs deep: the roots of the defense of the Bolivarian project run through working-class barrios, and the military would not be immediately demoralized – unlike in Iraq.

As the interior minister of Venezuela, Diosdado Cabello, recently noted, “Anyone who wants to can remember Vietnam… when a small but united people with an iron will were able to teach U.S. imperialism a lesson.”

Scenario 4: The Gulf of Tonkin Option

 In 1964, the U.S. escalated its military engagement in the Vietnam War after an incident framed as an unprovoked attack on U.S. destroyers off the country’s coast.

Later disclosures revealed that the National Security Agency (NSA) fabricated intelligence to manufacture a pretext for escalation. The U.S. claims it is now conducting naval and air ‘training exercises’ near Venezuelan territorial waters and airspace.

On Oct. 26, the Venezuelan government said it had received information about a covert C.I.A. plan to stage a false-flag attack on U.S. vessels near Trinidad and Tobago to elicit a U.S. response. Venezuelan authorities warned of U.S. manoeuvres and said they will not give in to provocations or intimidation.

Scenario 5: The Qasem Soleimani Option

In January 2020, a U.S. drone strike ordered by Trump killed Major General Qasem Soleimani, head of Iran’s Quds Force. Soleimani was one of Iran’s most senior officials and was responsible for its regional defence strategy across Iraq, Lebanon, Gaza, and Afghanistan.

In an interview on 60 Minutes, former U.S. chargé d’affaires for Venezuela James Story said, “The assets are there to do everything up to and including decapitation of [the] government” – a plain statement of intent to assassinate the president.

After the death of President Hugo Chávez in 2013, U.S. officials predicted that the project would collapse. Twelve years have now passed, and Venezuela continues along the path set forth under Chávez, advancing its communal model whose resilience rests not only on the revolution’s collective leadership but also on strong popular organization.

The Bolivarian project has never been a one-person show.

China and Russia are unlikely to permit a strike on Venezuela without pressing for immediate U.N. Security Council resolutions, and both routinely operate in the Caribbean, including joint exercises with Cuba and global missions such as China’s Mission Harmony 2025.

The hope is that none of these options comes to pass.

Tyler Durden
Sun, 11/09/2025 – 12:50

As Thanksgiving Travel Looms, Airport Chaos Threat Could Force Washington To End Shutdown

0
As Thanksgiving Travel Looms, Airport Chaos Threat Could Force Washington To End Shutdown

What’s become very clear, and CNBC’s Brian Sullivan may have nailed it, is that the record-long government shutdown will end once FAA-mandated flight reductions start forcing airport closures. 

Now, with the final countdown underway, Washington’s political deadlock is set to trigger nationwide airport chaos in the very near term. This will only compel both political parties to compromise and reach a deal to reopen the federal government, or risk facing angry voters. The timing suggests a resolution may emerge as the Thanksgiving travel season begins in the coming weeks.

“Double-stacking the planes now. We’re taking off but later flights going to be hurting worse. Once airports close this thing ends. We don’t all fly private like many in Congress,” Sullivan wrote on X early Sunday morning. 

On Friday, the FAA told major airlines to reduce daily flights by 4% at 40 major airports, rising to 6% Tuesday and 10% by mid-month. Transportation Secretary Sean Duffy warned that flight reductions could exceed 20% if the government shutdown were not resolved in the weeks ahead. 

By Saturday, staffing issues at controller towers at 42 major airports nationwide disrupted flights in 12 cities, including Atlanta, Newark, Chicago, San Francisco, and New York. Yesterday’s flight cancellations topped 1,550, with 6,700 delays, worsening from Friday’s 1,025 cancellations. Air traffic controllers are increasingly calling out for work because of zero-dollar paychecks amid the government shutdown, now in its 40th day. 

Duffy warned earlier, “It’s only going to get worse… Two weeks before Thanksgiving, you’re going to see air travel be reduced to a trickle.”

Seasonal Transportation Security Administration (TSA) checkpoint data shows that the number of travelers screened at airport security checkpoints will begin to surge in the week leading up to Thanksgiving, further straining airports during one of the busiest travel periods of the year, unless a deal can be struck in Washington.

Back to Sullivan’s point, “Once airports close this thing ends. We don’t all fly private like many in Congress.” 

Tyler Durden
Sun, 11/09/2025 – 12:15

BBC Finds Presenter In Violation Of Network Standards For Correcting “Pregnant People” Reference On Air

0
BBC Finds Presenter In Violation Of Network Standards For Correcting “Pregnant People” Reference On Air

Authored by Jonathan Turley,

There is a controversy at the BBC over a correction made by presenter Martine Croxall on air when she changed a reference to “pregnant people” to “women.”

The network later received 20 complaints and agreed that Croxall had violated network policies. (For full disclosure, I previously worked as the legal analyst for BBC).

In the segment, Croxall began by stating, “London School of Hygiene and Tropical Medicine has released research, which says that nearly 600 heat-related deaths are expected in the U.K.” She then added “Malcolm Mistry, who was involved in the research, says that the aged, pregnant people — women, and those with pre-existing health conditions need to take precautions.”

When she said “women,” she seemed to briefly pause in frustration in making the change.

According to the BBC’s Executive Complaints Unit (ECU), the brief pause and facial expression conveyed bias and a “personal view”:

“The phrase ‘pregnant people’ was followed by a facial expression which has been variously interpreted by complainants as showing disgust, ridicule, contempt or exasperation.

Even accepting this explanation, however, the ECU considered the facial expression which accompanied the change of ‘people’ to ‘women’ laid it open to the interpretation that it indicated a particular viewpoint in the controversies currently surrounding trans identity, and the congratulatory messages Ms Croxall later received on social media, together with the critical views expressed in the complaints to the BBC and elsewhere, tended to confirm that the impression of her having expressed a personal view was widely shared across the spectrum of opinion on the issue.”

I can understand that the network does not want on-air staff to convey their personal views on divisive subjects, particularly controversies that the network is covering.

What I was less clear on was the standard being enforced here.

There is no BBC rule that I know of requiring the use of “pregnant people” as opposed to women.

So, if that is true, the violation was the brief pause and facial expression.

If Croxall had simply made the change without the facial expression, would she be in compliance with network standards?

Croxall clearly disagreed with the nomenclature used by the writers, as many do. The fact that the BBC received 20 complaints is hardly surprising and the reliance on such complaints as proof of meaning is a dangerous practice. It is now common for individuals and groups to file a flurry of complaints against anyone who holds opposing views on issues like transgender rights or identity. The United Kingdom has eviscerated free speech with criminal prosecutions and investigation for years. Flash mobs form quickly to pursue dissenting voices such as J.K. Rowling, who maintain that these policies undermine the progress on women’s rights.

Notably, BBC initially supported Croxall and told complainants that Croxall’s script change was “done for clarity and was in no way meant to be disrespectful. We’re satisfied it was duly accurate and impartial, and in line with the BBC’s editorial guidelines.” As more complaints were filed, the network changed its position.

I understand that BBC does not want presenters to express personal views on such subjects on air, but it has remained uncomfortably vague on how presenters address such issues. Croxall clearly felt that “pregnant persons” was a clumsy and inaccurate expression. Is BBC saying that this is the correct way to speak of pregnant women or can presenters change the language, as did Croxall?

The current position seems the worst of all options for BBC to remain silent on the correct term while finding a presenter in violation for how she corrected it.

Tyler Durden
Sun, 11/09/2025 – 11:40

Trump Announces $2,000 ‘Tariff Dividend’ To Be Paid To Most Americans

0
Trump Announces $2,000 ‘Tariff Dividend’ To Be Paid To Most Americans

President Donald Trump on Sunday announced that most Americans would receive a dividend payment of “at least” $2,000 – paid out of US tariff revenues.

“A dividend of at least $2000 a person (not including high income people!) will be paid to everyone,” Trump posted on Truth Social, adding that tariffs have brought in “trillions of dollars,” and that 401(k) accounts are the “Highest EVER.” He also claimed that the tariffs had caused “No inflation.”

“People that are against Tariffs are FOOLS!” he continued.

The Treasury Department said in September that it had collected more than $195 billion from tariffs in 2025, while Treasury Secretary Scott Bessent says he expects the US to collect $500 billion or more in tariff revenue annually.

On Sunday morning, Bessent told ABC‘s “This Week” that the administration’s goal with the tariffs was to “rebalance trade” rather than simply take in revenue.

But wait!

Bessent also suggested that the $2,000 dividend could come in several forms – between tax decreases, no tax on tips, no tax on overtime, or other deductions. 

Trump floated the idea of a $1,000 to $2,000 “distribution to the people” during an October interview with One America News Network, and said they would bring in over a trillion dollars per year. 

Of course, $2,000 for most Americans would be difficult to claw back if the Supreme Court reverses them. 

Crypto markets immediately reacted (positively) to the potential helicopter drop of cash…

We would expected gold to jump once it opens also.

Tyler Durden
Sun, 11/09/2025 – 11:05

Repo Ripples, AI Angst, Bad Breadth, & Stealth QE

0
Repo Ripples, AI Angst, Bad Breadth, & Stealth QE

Authored by Lance Roberts via RealInvestmentAdvice.com,

AI Earnings Not Strong Enough?

This past week, markets continued to digest earnings from key technology and AI-focused companies, as well as the lingering effects of the Federal Reserve’s recent policy shift. Despite a limited macroeconomic calendar due to the ongoing government shutdown, corporate results kept investors engaged. The market struggled with ongoing narrow breadth and growing sensitivity to forward guidance. Major earnings reports from AI-related and large-cap tech firms revealed continued strength in revenue and profit growth, but fell short of overly optimistic expectations.

According to FactSet, the blended year-over-year earnings growth rate for the S&P 500 in Q3 stands at 10.7%, up from 7.9% at the start of earnings season. Revenue growth has reached 4.9%, exceeding both the five-year and ten-year averages. The Information Technology sector is leading the pack with an earnings growth rate of 26.5%. Consumer Discretionary has also rebounded to positive territory, while Communication Services lagged, weighed down by weakness from companies such as Meta, which beat revenue and earnings estimates but was impacted by a one-time tax-related charge.

Many AI-driven firms beat expectations, but markets reacted cautiously to increased capex and tempered forward guidance. Investor response has been mixed. While earnings beats remain high, several strong reports led to muted or adverse price action. This suggests markets are pricing in not just current performance but also cautious sentiment around future growth, margins, and investment intensity, particularly in AI infrastructure.

FactSet reports the forward 12-month P/E for the S&P 500 is now approximately 22.9x, above the five-year average of 19.9x and the ten-year average of 18.6x. These elevated multiples reflect high investor expectations and confidence, raising the stakes for any missteps or negative surprises in guidance. With the macro calendar limited by the federal shutdown, investor focus is firmly on earnings, capital expenditures (capex) trends, and corporate guidance. In this environment, earnings calls and management commentary matter more than usual.

Speaking of earnings, the most notable factor is the elevated expectations of earnings growth projections heading into 2026. While there are a lot of hopes for next year, the vast majority of earnings growth next year is solely dependent on the “Magnificent 7.” Expectations are currently for negative growth from the bottom 493.

This brings to light a few things that investors should be aware of:

  • Earnings growth remains strong but is increasingly priced in.

  • A narrow group of large-cap tech and AI stocks is leading market gains.

  • Valuations are elevated, and participation remains weak.

  • Guidance and capital allocation are under heavy scrutiny, especially in AI-related names.

  • With macro data limited, earnings and sentiment remain the dominant short-term drivers.

Investors should remain engaged but selective. The market’s technical structure remains bullish, but fragile beneath the surface. Any disappointment in earnings, guidance, or policy could quickly shift sentiment.

Breadth Tumbles

The S&P 500 closed the week at 6,728 after struggling all week to hold its ground. While the index remains in a defined uptrend and continues to trade above its 50-day and 200-day moving averages, both of which are still rising, the strength of the move is increasingly in question. Momentum remains constructive, with the MACD in a buy signal posture, and the 20-day moving average held as support. But the underlying structure of the market is weakening.

Breadth has notably deteriorated, with the number of stocks outperforming the benchmark index at levels typically associated with larger market corrective processes. Fewer stocks are participating in the upside, and internal momentum is fading. As of Friday, only 55.4% of S&P 500 components remained above their 200-day moving average, a meaningful decline from earlier levels this year. The number of stocks above their 50-day moving average has dropped even more sharply, down to just 40%, with participation narrowing in key sectors.

The market corrected about 3.5% from its all-time highs and remains above the 50-day moving average for now, keeping the bullish trend intact. However, money flow has deteriorated sharply, although we are seeing some buyers entering the market at the 50-day moving average on Friday, confirming support at that level. Relative strength has essentially reversed most of its previous overbought condition. Still, it remains in negative divergence overall, while momentum has triggered a short-term sell signal, which will keep a lid on advances for now.

Technically, the setup remains bullish based on price action alone, but structurally, it is not robust. Breadth weakness, momentum divergence, and declining volume on rallies are red flags. The rally is vulnerable to sharp reversals if broader participation does not materialize soon. A strong trend built on a narrowing foundation is inherently unstable.

Support and Resistance Levels

  • Primary Resistance: ~6,850–6,900 (top of the rising trend channel and previous highs)

  • Initial Resistance: ~6,767 (approximate 20‑day moving average)

  • Initial Support: ~6,674 (approximate 50‑day moving average)

  • Primary Support: ~6,497 (100-day moving average)

  • Critical Support: ~6,134 (200-day moving average)

In this environment, investors should remain disciplined. The trend is intact, but fragility is growing. Participation in the rally is permissible, but positions should be hedged or trimmed where appropriate. Stops should be tightened on extended names. Without confirmation from broader market internals or macro data, the path forward could become more volatile.

Repo Ripples Turning Into Waves?

In September 2019, a critical but obscure part of the financial system broke. Overnight borrowing rates in the repo market suddenly spiked from around 2% to over 10% in a matter of hours. Banks and dealers couldn’t get the short-term funding they needed to finance Treasury holdings or settle trades. Liquidity froze. Wall Street was caught off guard. The Federal Reserve quickly intervened, launching emergency repo operations to inject cash into the system. Within days, funding markets stabilized. Over the next few months, the Fed expanded its balance sheet again, but not for QE, they insisted, but to keep repo markets functioning. That quiet intervention helped fuel the final leg of the market’s rally into early 2020.

Currently, we are seeing cracks reemerge in this previously unknown part of the financial system. In today’s commentary, we will discuss what it is and why it matters.

The “repo” market, short for “repurchase agreement,” sits at the heart of the financial system. Critically, and why it matters to the financial markets, is that it allows banks, hedge funds, and dealers to borrow cash by using high-quality securities, typically U.S. Treasuries, as collateral. (This is also how money winds up in the financial markets when the Federal Reserve is doing “Quantitative Easing.”)

The transaction is straightforward and is an OVERNIGHT transaction. During this process, one party sells a security with a commitment to repurchase it the next day at a slightly higher price. That price difference represents the cost of borrowing. Typically, the difference between the Secured Overnight Financing Rate (SOFR) and the Interest Rate on Reserves (IOR) is slightly negative. Currently, that is not the case. Notably, this is not some niche corner of finance. It’s the lifeblood of overnight funding.

Why is this so important? Because TRILLIONS flow through this market every day, and most people have never heard about it.

However, without it, Wall Street doesn’t open.

  • Dealers need it to fund their balance sheets.

  • Hedge funds rely on it for leverage.

  • Money market funds use it to park cash overnight.

  • It’s also how the Federal Reserve transmits monetary policy.

When the repo market functions smoothly, short-term interest rates stay in line with the Fed’s targets. When it breaks, liquidity dries up fast. That creates ripple effects in credit, equities, and even Treasury markets.

If repo transactions grind to a halt, it’s not because there’s a lack of collateral or cash, but because of fear. When institutions stop trusting each other, they stop lending to one another. That’s when the financial plumbing clogs, and the consequence of that “clogged plumbing” is rising volatility, strained liquidity, and falling asset prices. The repo market isn’t just important. It’s foundational.

A Redux of 2019? What Does It Mean for the Markets?

Currently, cracks are reappearing. The overnight repo rate is climbing as the use of the Fed’s Standing Repo Facility is increasing, and treasury bill issuance is ballooning.

Most notably, what the Fed once deemed “abundant liquidity” has now fallen below the levels it considers “ample.” The chart shows that the Fed Reserve’s plus Reverse Repos (which, for the past three years, have served as an excess liquidity storage facility used primarily to fund purchases of T-Bills) is now at the lowest level since late 2020.

Sound familiar? It should. The current environment bears a striking resemblance to the lead-up to the September 2019 repo crisis. Back then, the repo rate suddenly spiked from around 2% to over 10% in a single day as Wall Street’s funding machine seized up. Here is an example of what happened.

You have a brand new, fully paid-for Mercedes. You go to your neighbor and ask for an overnight loan of just $10,000, offering him the title to your car as collateral. Your interest rate should be close to the Federal Reserve’s overnight rate, but instead, your neighbor says he wants 10%. That difference is a “risk premium” that is undeserved because the loan is backed by guaranteed collateral, in this case, the car.

But that is what happened in 2019, and the Fed had to intervene with emergency liquidity operations to restore stability.

Why did it happen? In 2019, a combination of tax payments and Treasury auctions drained reserves from the banking system. At the same time, dealers were loaded with collateral they couldn’t finance. Cash lenders didn’t want to step in, even at higher rates, because they were either constrained by regulation or unwilling to take the risk. The repo market, which had always been taken for granted, suddenly became the problem no one was watching.

Today, we’re seeing many of the same ingredients. Heavy Treasury issuance is forcing dealers to take on more collateral, and liquidity is being withdrawn from the system due to the Fed’s quantitative tightening. The problem with the repo market is why the Fed announced it would end the shrinkage of its balance sheet at the end of November. Meanwhile, bank reserve levels have dropped sharply, adding to concerns about overall liquidity.

When stress rises in the repo market, it’s not a technical glitch, but rather a signal that the financial system is under pressure. If this stress deepens, it could lead to a broad tightening of financial conditions that will spill over into the equity and credit markets. Given the Fed’s concern about the “wealth effect” the financial markets provide to economic growth, this has become the third, and unspoken, mandate of Fed policy.

While that may sound frightening, there is a twist. If the Fed steps in to relieve repo pressure, like it did in 2019, it might trigger the opposite of a crash. In other words, the Fed’s actions to stabilize the repo market may lead to a “melt-up” in equities, where risk assets surge, not because fundamentals improve, but because liquidity returns in force. Such a conclusion is not far-fetched, as the Government shutdown has drained over $700 billion from the market, as shown by the sharp increase in the Treasury General Account.

Stealth QE on the Horizon

However, once the Government is reopened, that $700 billion increase in the Treasury General Account will flow back into the economy. That reopening will create a flood of effective stimulus as furloughed workers receive back pay, departments are reopened, and Government contract work resumes. Those dollars wind up deposited into the banking system, increasing bank liquidity. In effect, it is a “stealth QE” that could create a massive scramble for risk assets.

As such, both the end of the Government shutdown and a stabilization of the repo market could have an immediate impact on risk assets. Once dealers can fund collateral without paying punitive rates, liquidity will return, which “greases the wheels” of the entire financial system. Trading flows improve as Hedge funds can effectively re-leverage their portfolios, and credit spreads are expected to tighten.

You will notice in the chart below that this is precisely what happened after the 2019 repo scare. Once the Fed began daily operations to supply liquidity, the S&P 500 rallied to new highs. Then, of course, that liquidity went into overdrive following the onset of the pandemic. While it has since reversed somewhat, there remains, as noted above, “ample” liquidity in the financial system currently.

Just as it was in 2019, the move was not about fundamental improvements; it was simply about “too much money chasing too few assets.”

It is important to note that fixing the repo market isn’t about bailing out Wall Street. It’s about restoring the basic mechanics of financial intermediation. When overnight funding is cheap and available, institutions are willing to trade, lend, and invest. That confidence feeds through to markets. Although most investors don’t track repo rates daily, they feel the effects, as more liquidity means less volatility, tighter spreads, and rising asset prices. At least that is what we should expect in the short term.

However, the resolution needs to be more than a temporary patch. If the Fed signals it’s ready to backstop the market, investors will likely view that as a green light to increase equity risk and change the risk calculus to some degree. The problem is that stocks are already grossly detached from underlying fundamentals, and a resolution to either the Government shutdown or resolving the current repo stress will likely see investors pushing asset prices further away from those fundamentals. But that is how liquidity drives markets, especially when fundamentals look stretched.

For investors, it is worth noting that if the Fed steps in again, the upside could come quickly and substantially. For now, the repo market is the canary in the coal mine. What comes next depends on whether policymakers decide to move soon or wait until stress forces their hand.

Key Catalysts Next Week

The U.S. government shutdown persists, continuing to stall many federal economic data releases. In this environment, the market’s focus shifts sharply to those reports still expected and to key central‑bank commentary. Investors will monitor what limited data is available, along with speeches from Federal Reserve officials and corporate earnings, for directional signals.

In sum, next week offers a sparse macro calendar, making every publication and speech disproportionately important. The NFIB index will serve as one of the few viable high‑frequency signals of business sentiment. The Fed remarks by Cook and Jefferson will be scrutinised for hints of policy shift given the data blackout. With earnings still unfolding, investor attention remains on how companies navigate cost pressures, demand trends, and AI‑driven investment in a constrained economic backdrop. In such an environment, absence of negative surprises may support risk assets, but the lack of fresh data increases vulnerability to unexpected developments.

Trade accordingly.

Tyler Durden
Sun, 11/09/2025 – 10:30