57.6 F
Chicago
Tuesday, October 6, 2026
Home Blog Page 106

‘Chexit’: Global Asset Managers Are Fleeing China

0
‘Chexit’: Global Asset Managers Are Fleeing China

Authored by Anders Corr via The Epoch Times,

Fidelity International (FIL) is reportedly the latest fund manager to plan a pullout from its China fund. FIL launched a wholly-owned subsidiary in Shanghai three years ago, but a lack of demand from retail investors led to disappointing growth.

Reuters first reported the story. According to its sources, “A combination of fierce local competition, frequent leadership turnover and chronic struggles to build scale ultimately convinced global FIL executives that the China retail venture was untenable.”

FIL has $1.18 trillion in assets under management (AUM). It started its China fund in 2023. The next year, Reuters saw an internal FIL document that said it needed more than $14 billion in assets to become profitable. After several years, it had reportedly reached only about $670 million (less than 5 percent of the goal) and began planning an exit.

Fidelity follows multiple other global asset managers that are backing away from China amid domestic competition and geopolitical tensions. These include Schroders, Legal & General, and Vanguard. The companies that left China were in stiff competition with domestic funds and Western China funds that had typically first been established through joint ventures (JVs) with Chinese institutions.

In 2019, Beijing invited global fund managers, for the first time, to establish wholly-owned China funds. The regime framed the invitation as part of a trade agreement, and the latter sought access to the Chinese public’s $12.8 trillion in investable assets. For some of the international investors, it did not end well.

In 2020 and 2021, respectively, the Chinese regime issued permits to BlackRock and Neuberger Berman to start such funds. They both had ties to the regime and headquarters in Shanghai. In 2021, BlackRock raised $1 billion for its fund in its first week, which impressed other institutional investors. It was the first mutual fund owned by foreigners to be granted permission to sell directly to Chinese customers, and it did very well, at least at first.

Several other large asset managers converted their JVs into wholly-owned funds by buying out their JV partners. These then became the largest and most successful wholly foreign-owned public fund houses in China.

Some institutions, including Fidelity, Schroders, and BlackRock, launched greenfield, wholly-owned China funds, but they tended to be smaller than the converted JVs, delivered lower returns, and were disappointing in terms of growth. In 2018, Vanguard’s Asia CEO mentioned a possible future China AUM of $5 trillion. But Vanguard was the first to close its Shanghai office in 2023.

The next year, Legal & General canceled plans to get a China business license and reduced its presence in Shanghai by about 80 percent.

Schroders, a British firm with AUM of $1.1 trillion, established a wholly-owned China fund management unit in 2023. But three years later, Schroders only managed $250 million. In May, news broke that the company planned to sell its China funds to a wholly-owned China unit of Neuberger Berman.

China has a $5.9 trillion public fund market dominated by domestic fund managers. Even as the smaller foreign-owned funds cut their losses in China, the larger ones are holding on.

JP Morgan Asset Management China is the largest foreign-owned fund with $34 billion in AUM. Manulife China has $17 billion, and Morgan Stanley China has $4.5 billion. These three funds started as joint ventures and then bought out their Chinese partners. Their returns tend to be better than those of new ventures, with about a third of their funds getting above 10 percent.

Most new foreign-owned funds posted a year-to-date return of less than 5 percent in June, which is far below the returns of the leading domestic fund managers. The top 11 Chinese companies each have more than $147 billion in AUM. Yicai has noted that the best 15 domestic funds had returns of at least 90 percent, which likely attracted some retail investors.

Domestic funds reportedly have multiple advantages over western funds, including brand recognition, established online and bank distribution channels, and low-overhead index and money-market businesses dominated by locals.

According to a Yicai Global source, “Most domestic fund managers have spent decades building out full product lines, gaining deep experience, earning a track record investors recognize, building local sales networks, and learning Chinese investors’ preferences.”

Other Yicai sources note that to compete, foreign companies should localize their management, research, investment, and sales teams.

There may be other advantages less frequently noted. A Fitch Ratings analyst put it bluntly when discussing the entrance of foreign banks into China’s retail banking space in 2007.

“Foreign banks don’t break people’s arms when they don’t repay them, like some Chinese banks might,” the analyst said. “They can’t operate like that, so what they have to focus on is the high end of the retail market.”

Another challenge is unspoken regime bias against foreign companies, combined with overregulation. In June, for example, China’s top securities regulator targeted algorithmic trading, which is one of the West’s bright spots, not only internationally but in China trading.

The measures hit domestic algo traders as well, but they block one avenue in which foreign firms hold an advantage. Regular domestic managers have closer ties to regime agencies and exchange relationships and, therefore, better access to market data and regulatory largesse.

This isn’t the first time that foreign banks have been squeezed in China to the advantage of domestic actors. The British pioneered modern banking in Shanghai in the 19th and early 20th centuries. Banks from other countries, including Germany, France, Japan, and the United States, entered later.

But after the revolution of 1949, the Chinese Communist Party (CCP) took over the most lucrative businesses of the banks and forced them to maintain idle workers. This forced most of them out in the 1950s. The two major foreign banks that remained, Standard Chartered (under a prior name) and HSBC, lost market share. Starting in 1979, the CCP gradually reopened its financial sector to foreign entities while ensuring that its domestic banks remained dominant.

With an uneven playing field and unfair referees, China is not the best of opportunities for Western investors. In the case of companies like Fidelity, Schroders, Vanguard, and Legal & General, the numbers did not add up and probably never will.

Views expressed in this article are opinions of the author and do not necessarily reflect the views of The Epoch Times or ZeroHedge.

Tyler Durden
Sat, 08/29/2026 – 23:20

AI Skepticism Outweighs Excitement In The US

0
AI Skepticism Outweighs Excitement In The US

Despite the tech industry’s conviction that the rise of AI is an inflection point that will change the course of humanity, many humans remain skeptical whether the new direction we’re headed in is the right one.

As Statista’s Felix Richter reports below, the pace at which AI seems to be taking over parts of our lives, whether we like it or not, is especially worrisome to many.

In a recent Statista Consumer Insights survey, 31 percent of U.S. respondents said that they were worried about the speed at which AI is developing and 25 percent of respondents claimed to be avoiding AI wherever they can.

18 percent said they used AI but felt bad about it and another 28 percent simply don’t believe in the hype, saying they weren’t convinced that AI is as good as people say.

Infographic: AI Skepticism Outweighs Excitement in the U.S. | Statista

You will find more infographics at Statista

At the other end of the spectrum, 28 percent of respondents said they were excited about AI, 19 percent said they liked to use AI for shopping and 15 percent described themselves as early adopters – always keen to try the latest AI features first.

The bottom line is that Americans are neither all in on AI nor are they fully against it.

Many people are mixing their excitement with a dose of skepticism, which is probably a good way of looking at a potentially life-altering technological shift.

Tyler Durden
Sat, 08/29/2026 – 22:45

The Arday Tragedy: A Story Of Institutional Failure, Not A Witch Hunt

0
The Arday Tragedy: A Story Of Institutional Failure, Not A Witch Hunt

Authored by Lipton Matthews via The Mises Institute,

The recent death of Jason Arday has been met with widespread grief, but also with a disturbing rush to assign blame.

Much of the media narrative has positioned Nathan Cofnas as the villain, the man who exposed plagiarism and, in doing so, supposedly hounded a vulnerable academic to his death.

This is a convenient story, but it is not the truth.

Let us be clear. Nathan Cofnas did nothing wrong. Yet he has been suspended from his post as a postdoctoral researcher in the Department of Philosophy and Moral Sciences at Ghent University. He brought to light legitimate concerns about Jason Arday’s academic record. That is the function of journalism and scholarly scrutiny. If the allegations were false, Arday would have defended himself more effectively. If they were true, then they deserved to be aired. The fact that Arday was mentally unwell is tragic, but it does not retroactively make Cofnas’s actions malicious. We do not hold journalists responsible for the pre-existing vulnerabilities of those they cover.

This is not the first time a scandal has broken around a prominent figure. Stephen Glass—once a star at the New Republic—saw his career implode when his fabrications were exposed. He did not retreat; he wrote a novel about his disgrace, turning infamy into profit. Jayson Blair—the New York Times plagiarist—did the same. Both men monetized their scandals. Jason Arday’s exposure came in the age of social media, so the venom was more intense, but the principle is unchanged. Public figures often exploit controversy for personal gain. That Arday could not do so is unfortunate, but it is not evidence of a uniquely cruel campaign against him.

What is striking about Arday’s case is the institutional support he received. Diane Abbott and prominent Cambridge academics rallied to his defence. Compare this to the treatment of Charles Negy, Linda Gottfredson, Arthur Jensen, Helmut Nyborg, and others who have been vilified as racists simply for engaging with research on intelligence and group differences. Gottfredson continues to be defamed by the disgraced Southern Poverty Law Center. Nyborg had to sue the Danish Committees for Scientific Dishonesty for falsely accusing him of scientific misconduct. Negy is not even a race researcher; he was penalized by his university for saying that black privilege is real. As Negy put it, “beyond affirmative action, special scholarships, and other set asides, being shielded from legitimate criticism is itself a form of privilege.” None of these scholars had the institutional backing that Arday enjoyed. He was given an opportunity on a platter of gold. However, he failed to distinguish himself and, when the scrutiny came, he could not withstand it.

The real lesson of this harrowing tale is not a racist media hounding a black academic to death. It is the intensity of what might reasonably be called black privilege—a system that elevates individuals to positions they are not prepared for, shields them from criticism, and then reacts with shock when reality intrudes. Mike Adams – a white academic – was badgered to suicide in 2020 by social media and his university simply because people found his tweets offensive. Unlike Arday, he received no institutional support from elite institutions, nor was there an outpouring of solidarity. The difference between his case and Arday’s is glaring.

Invariably, the hatred directed at Nathan Cofnas stems not from his role in the Arday affair, but from his wider writings on race and intelligence. Cofnas holds that racial differences in intelligence are partially genetic. This is controversial, but it is not unsupported. Psychologist Russell Warne has defended similar positions in his book In the Know: Debunking 35 Myths About Human Intelligence. Even if the hereditarian view is ultimately wrong, the environmentalist thesis has failed to produce a convincing alternative. Not much has changed since Arthur Jensen’s landmark 1969 report How Much Can We Boost IQ and Scholastic Achievement? Robert Plomin’s more recent text Blueprint: How DNA Makes Us Who We Are reinforces the point that parental influence is largely genetic. Cognitive gaps between blacks and whites persist even when both groups are similar in socioeconomic status, education, and other environmental measures. The reality is that—irrespective of the truth of hereditarianism—groups will differ in behavior and intelligence. If elites would simply accept this, we could stop obsessing over erasing every disparity and instead focus on helping people thrive where they are.

In an ordinary world, Jason Arday might have been a successful PE teacher, or even a comedian.

He had charm, energy, and a compelling personal story.

He died because Cambridge elevated him to a position for which he was not prepared, and the inevitable scrutiny crushed him.

When he was alive, Arday said he wanted the world to spin on an axis of love. But the truth is that the DEI fanaticism that elevated him, and ultimately destroyed him, was propelled by an excess of love for egalitarianism, a love so blind that it refused to see the human cost of its own ideology.

Jason Arday’s death is a tragedy. But it is not Nathan Cofnas’s fault. It is the fault of a system that prioritizes symbolism over substance, and then abandons its symbols when they fail.

If we want to honor Arday’s memory, we should begin by telling the truth about how he got there and who really put him in harm’s way.

Tyler Durden
Sat, 08/29/2026 – 22:10

Meta Tests Robots That Can Swap Cables And Reset Servers At Its Data Centers

0
Meta Tests Robots That Can Swap Cables And Reset Servers At Its Data Centers

Kiss those data center technician jobs goodbye…

Meta is testing robots that can swap network cables, restart servers, reseat components, and perform other physical tasks traditionally handled by data center technicians. The experiments come as the company rapidly expands its AI infrastructure and seeks to operate facilities more efficiently, according to Wired.

Some employees worry about job security. One Meta worker estimated that a successful cable swapping robot could eventually take over as much as 80 percent of certain workloads. “We thought those of us performing the physical tasks were safe for a while, but not anymore,” the worker said.

Meta says automation does not mean it needs fewer people. Spokesperson Francis Brennan cited a shortage of skilled tradespeople and the company’s investments in training and hiring workers. Meta has launched programs teaching electrical, mechanical, and plumbing skills and partnered with trade unions on apprenticeships.

Still, robotics is part of Meta’s longer term strategy. Robotics manager Eric Xu has said robots could eventually assist with incident response, environmental monitoring, and preventive maintenance.

The company is experimenting with equipment from several manufacturers. A Kinova Gen3 arm is being evaluated for power cycling servers, while other machines are being tested for cable replacement. Some facilities already use a simple remotely controlled device resembling a mechanical finger to press power buttons and reboot equipment.

At its Altoona, Iowa, campus, Meta is testing dual arm Watney robots for cabling. At its newer Prometheus campus in New Albany, Ohio, ABB robots mounted on four wheel platforms are being used to reseat components and could eventually perform more work with less human supervision.

These projects build on simpler automation already deployed in Meta facilities. Self driving tugger robots transport heavy server racks, while wheeled inventory robots scan equipment and assist with inspections. Microsoft, Google, and Amazon have also explored robotics for data center operations.

Wired writes that the economics are attractive. Robots could provide consistent labor where qualified technicians are scarce and handle repetitive or hazardous work. They could also operate in hotter, darker, or otherwise less hospitable environments.

But current systems remain far from replacing technicians entirely. Meta’s inventory robots struggle with cables and corners, require humans to move them between buildings, and cannot reliably interpret some equipment indicators. Other robots need substantial charging time and remain slower than people.

Data centers were also designed around human dexterity. Complex cabling, particularly around advanced AI systems such as Nvidia’s GB300, remains difficult for robots. As one former Meta employee put it, “Things have been designed for human hands forever to make everything a five-minute repair.”

Even so, the experiments are changing how some Meta workers view their future. Employees have reportedly discussed fears that automation could eliminate jobs or shift remaining positions toward lower paid workers who mainly follow AI generated instructions.

That could also affect the politics surrounding data centers. Communities often justify tax incentives partly through the jobs these facilities create. If robotics significantly reduces employment, governments may reconsider those economic tradeoffs.

For now, humans remain faster and more adaptable. But as robotic hardware gets cheaper and AI improves, Meta is preparing for a future where machines perform considerably more of the physical work inside its data centers.

Tyler Durden
Sat, 08/29/2026 – 21:35

US Steps Up Africa Push As China Expands Economic, Security Footprint

0
US Steps Up Africa Push As China Expands Economic, Security Footprint

Authored by Arthur Zhang via The Epoch Times,

The Trump administration says it has helped close 37 commercial deals worth $25.67 billion in Africa as Washington moves to compete with a much larger Chinese economic footprint across the continent.

“China continues to flood Africa with exports,” Assistant Secretary of State for African Affairs Frank Garcia told Fox News in an interview published Aug. 27.

Garcia said Chinese state-subsidized overcapacity threatens local industries and has left African countries exposed to debt and economic coercion.

China’s General Administration of Customs recorded approximately $348.1 billion in two-way goods trade with African nations in 2025. Chinese exports accounted for about $225 billion, while imports from Africa totaled about $123 billion.

U.S. goods trade with Africa was about $83.35 billion last year, according to the U.S. Census Bureau.

Pressure on African Manufacturers

Chinese imports have already hurt manufacturers in parts of Africa.

A 2025 study published in Energy Economics found that Chinese import competition reduced productivity among African manufacturers, with particularly pronounced effects on small and medium-sized firms facing financial and electricity constraints.

Research published in International Affairs in November 2025 found that more than 400 Chinese-owned manufacturers registered operations in Ghana between 2004 and 2024 as some private Chinese companies shifted from trade toward local production.

In South Africa, Chery Auto inaugurated the former Nissan plant in Rosslyn in July after acquiring it. The Chinese automaker plans to begin production there in mid-2027.

Chinese investment has also generated resentment in some communities. Chinese rights activist Jie Lijian, who spent more than seven months traveling overland through Africa in 2019 while fleeing the Chinese Communist Party’s (CCP) persecution en route to the United States, told the Chinese edition of The Epoch Times in October 2020 that he repeatedly encountered complaints about Chinese companies.

In Ethiopia, Jie said police officers who initially mistook him for a Chinese company employee complained that Chinese businesses had polluted water and air and harmed livestock.

Local resistance has also at times turned violent.

In October 2024, residents of Konkoï in Guinea protested against Chinese-owned Hongxing Mining Guinea SARL over alleged damage to farmland and the local environment. Guinean and regional reports said two people died after security forces intervened, including a young man who was shot and a child who inhaled tear gas. The local prefect said at the time the company was operating legally and paying taxes, according to Guinea-based online news platform Guineematin.

Minerals Become a US Security Issue

Critical minerals are an area where China’s dominant control directly impacts U.S. national security.

U.S. Africa Command’s (AFRICOM) 2026 posture statement states Beijing is using investments in African mining, infrastructure, and transportation to secure critical minerals and strategic infrastructure.

The command singled out graphite.

“Beijing dominates 90 percent of battery-grade graphite processing,” AFRICOM said.

The command called that concentration a “structural vulnerability” for the U.S. defense industrial base.

Separately, a 2026 U.S. Geological Survey report put China at 79 percent of natural graphite production, along with 98 percent of primary refined gallium, 83 percent of mined tungsten, and 68 percent of mined rare earths.

The United States is trying to build alternative supply routes.

The Washington-backed Lobito Corridor is designed to link the copper belt in Congo and Zambia to Angola’s Atlantic port at Lobito.

Bernard Swanepoel, chairman of South Africa’s African Exploration Mining and Finance Corp., told The Epoch Times in July 2025, “Judging from how often he mentions it, copper is central to Trump’s ambitions.”

He pointed to the Washington-backed Lobito Corridor.

Former Zambian Mines Minister Paul Chongo Kabuswe also told The Epoch Times at the time that China had pledged to invest $5 billion in Zambia’s copper industry by 2031, including $800 million in one mine. He said Zambia was also discussing more U.S. investment with the Trump administration.

“Just because we have Chinese interest here doesn’t mean we don’t want United States companies here,” Kabuswe said.

Armed Groups and Mining Security

In some mining regions, Chinese-linked operations have also become entangled with armed groups.

In the Central African Republic, the mining minister revoked three exploitation permits held by Chinese mining company Daqing SARL in June 2024. A 2025 U.N. Panel of Experts report said government sources found that the company had mined without authorization, interacted with armed group members, and brought unauthorized foreign workers to the site.

A July 2016 Global Witness investigation found that Chinese-owned Kun Hou Mining paid $4,000 and supplied two AK-47 rifles to Raia Mutomboki, armed factions in eastern Congo, in 2014 and 2015 to secure access to gold deposits.

Global Witness said a February 2015 letter from four Raia Mutomboki factions confirmed receipt of the money and rifles. The group also reported that Kun Hou supplied armed factions with communications equipment and food.

Chinese companies have also used overseas security contractors to protect commercial operations.

A Chinese security contractor in Sudan told the Chinese edition of The Epoch Times in April 2023 that his work included preparing security plans and supervising foreign security personnel.

Huaxin Zhong’an Security Group, a Beijing-based Chinese private security company, stated in a corporate news release in March 2022 that retired military personnel accounted for 100 percent of its overseas security employees.

Huaxin Zhong’an has hired more than 1,000 armed guards in host countries for overseas projects, and its overseas Communist Party organization helped select, vet, train, and manage security personnel sent abroad, according to a separate March 2022 statement.

Beijing Expands Military and Political Training

China is also expanding military, police, and political training in Africa.

Under the Forum on China – Africa Cooperation Beijing Action Plan for 2025-2027, Beijing pledged a 1 billion yuan ($140 million) military grant, training for 6,000 African military personnel and 1,000 police and law-enforcement officers, and visits to China for 500 young African officers.

At least 50 African countries regularly take part in Chinese professional military education, according to Paul Nantulya of the U.S. Defense Department’s Africa Center for Strategic Studies.

In an October 2023 analysis, Nantulya wrote that African officers attending Chinese military schools are exposed to the CCP model of political control over the People’s Liberation Army, including political commissars and the principle that the armed forces answer to the ruling party.

In a May 2023 report, the Africa Center for Strategic Studies, an institution under the U.S. Department of War and part of the National Defense University in Washington, D.C., said a South African police unit sent to China’s People’s Armed Forces Academy for training in 2016 was later illegally deployed into the country’s top security agencies as a “hit squad” to intimidate and assassinate political rivals.

The CCP has expanded political training as well.

The Mwalimu Julius Nyerere Leadership School in Tanzania trains cadres from six Southern African ruling parties. In a November 2023 report, the Africa Center said CCP Central Party School instructors participated in the school’s programs, which included party recruitment, management, administration, mass mobilization, leadership, and propaganda systems. The center said in 2025 that the school remained part of Beijing’s expanding party-training network in Africa.

Ports and Strategic Access

AFRICOM is also watching Chinese-built and Chinese-controlled infrastructure for potential military use.

China operates its overseas military base in Djibouti, near the entrance to the Red Sea.

AFRICOM’s 2026 posture statement said Beijing’s investments in transportation infrastructure can support a persistent security presence.

In a response to The Epoch Times, a U.S. Africa Command spokesperson said AFRICOM leadership has “consistently warned” that Beijing is trying to expand its military footprint beyond Djibouti and establish a permanent naval presence or dual-use port facility on Africa’s Atlantic coast, particularly in the Gulf of Guinea.

The spokesperson said AFRICOM is also tracking Beijing’s efforts to gain access to African natural resources and to control critical minerals, infrastructure, and key sea lines of communication.

“The United States delivers enduring value as a partner of choice with capabilities only we can provide,” the spokesperson said, adding that Washington’s approach is based on transparency, respect for sovereignty, and mutual prosperity.

The State Department and the African Union did not respond to inquiries for further information by publication time.

Tyler Durden
Sat, 08/29/2026 – 21:00

What Happened To The So-Called AI Job Apocalypse?

0
What Happened To The So-Called AI Job Apocalypse?

Authored by Joe Bertolami via RealClearMarkets,

A recent report from Stanford reviewed the latest employment data and found that, so far, AI has not resulted in large scale job destruction. Meanwhile, new hiring data from the Economic Times reveals that AI is actively fueling unprecedented job creation, with AI skills now powering nearly two-thirds of new Global Capability Center hiring. Together, these recent dispatches from the front lines of the labor market point to a calming reality: the much-dreaded AI job apocalypse hasn’t materialized as a sudden extinction event.

The (sometimes buried) lede: AI is delivering real impact, and it is broadly changing the nature of work. But disruption is not a new phenomenon. The economy has always dismantled old work to build new work. What determines whether this evolution feels like progress or collapse isn’t just the number of jobs lost, it’s the speed at which that loss hits the labor market.

In 1995, Bill Gates circulated a memo titled “The Internet Tidal Wave,” calling the web the most important computing development since the IBM PC. If the internet was a tidal wave, artificial intelligence is a tsunami. It is arguably the biggest advancement in computing since the Turing machine. Yet, from a distance, it’s difficult to appreciate the speed of this wave, leading many to wonder when the broader economy will truly feel its impact.

To put this in context, we must understand the historical pattern already visible in the labor market. Combining decades of data from the U.S. Bureau of Labor Statistics and the Federal Reserve yields a remarkably consistent story of overlapping curves: job loss and job creation. Over the last two decades, nearly 20 million U.S. jobs vanished in disrupted sectors. Over the same period, total payrolls grew by 25.7 million. That equates to roughly 1.3 new jobs for every one destroyed. Classic examples include jobs in video rentals (-98.9%) and word processing (-83%) which largely vanished, but new work sprung up at the same time in areas like data processing (+54%) and warehousing (+260%) to support the digital economy.

The data also reveals an early signal that separates an absorbable decline from a brutal collapse: the disruption half-life, or how long an occupation takes to lose half its peak employment. Across the largest technological disruptions of the last few decades, the median half-life is about 10 years. Fast disruptions, like photo processing, take one to five years. Typical disruptions take eight to 13 years. And time is the ultimate shock absorber. When the economy transitions over ten years it feels like progress rather than a fast collapse, because it gives older workers time to retire and younger workers time to prepare.

If we track the most AI-exposed occupations-customer-service reps, IT support, telemarketers-since modern LLMs arrived in 2022, the early data is measured. After three years the current disruption looks closer to “typical” than a fast collapse, even before discounting the effects of offshoring, automation, and post-COVID corrections. This is Amara’s Law playing out in real time: we tend to overestimate the effect of technology in the short run and underestimate it in the long run. The dire early warnings have given way to more cautious rhetoric. In 2025, Anthropic’s Dario Amodei warned AI could erase half of entry-level white-collar jobs within five years. By 2026, he and OpenAI’s Sam Altman are emphasizing productivity, economic growth, and the continued demand for human labor.

However, looking solely at total employment numbers masks a dangerous structural threat. Current evidence does not foretell the end of human labor, but AI is quietly breaking the mechanism by which we create experienced workers.

Software engineering is the canary in the coal mine. By most aggregate measures, employment looks stable; unemployment held at 4.2% in June 2026, and groups like the Yale Budget Lab find no clear AI effect yet on exposed occupations’ absolute job totals. But the composition is shifting underneath our feet. Per AP and Oxford Economics, junior developer postings are down roughly 40% in four years. Employment for 22-to-27-year-old computer and math grads has fallen 8% since 2022, even as older grads in the same fields have edged up. This same erosion is surfacing wherever entry-level work once meant routine tasks: paralegals, junior analysts, and first-line support.

The paradox is that these industries keep growing even as their entry-level doors narrow. The BLS still projects software developers and QA analysts to grow 15% through 2034. But that projection relies on a pipeline that turns juniors into senior talent-precisely the pipeline now being choked off.

The reason lies in the nature of the work. Software development is a process of judgement and accountability: deciding what to build, executing it, and owning the result. AI is fluent at the middle layer-the well-specified, routine coding that once served as a junior’s apprenticeship. But it remains far weaker at the judgment required on either side. The tasks AI automates are precisely the ones juniors were hired to learn on.

This is not merely an academic concern; it is a capital allocation problem. Misjudge the speed of disruption and you risk premature layoffs followed by a scramble to rehire, or funding the transition years too late, leaving you with a critical talent shortage when the leadership pipeline runs dry.

The challenge of the next decade isn’t surviving the end of work. It is training the next generation of experts when the traditional paths to apprenticeship no longer exist. And businesses are beginning to realize this new reality as demand for AI continues to grow. IBM is tripling its entry-level hiring, redesigning those roles around the oversight of AI and systems thinking rather than cutting them. Rebuilding the entry-level on-ramp is now a competitive imperative.

Junior roles are not charity; they are talent capex. If AI creates more work than it destroys, companies will still need people who know how to run it, judge it, and fix it. AI may be the broadest technology yet, but that breadth is its best reason for optimism. A general-purpose technology seeds new work across every sector. The firms that recognize this, protect their entry-level pipelines, and keep training now are the ones who will own the senior labor market later.

Joe Bertolami is the Co-Founder and CTO at Clifton AI, an agentic context engine for investment research. Previously at Snap, Google, and Microsoft, with a couple of startups in between. He holds an M.B.A. from the University of Washington and likes using AI to write code, stories, and music, which he posts at https://www.bertolami.com.

Tyler Durden
Sat, 08/29/2026 – 19:50

CDC Reports COVID-19 Activity Is Increasing Across US

0
CDC Reports COVID-19 Activity Is Increasing Across US

The Centers for Disease Control and Prevention on Friday said COVID-19 activity is “increasing” across the United States although its levels are still considered “very low” overall.

“As of August 26, 2026, we estimate that COVID-19 infections are growing or likely growing in 48 states, declining or likely declining in zero states, and not changing in two states,” the CDC said on Friday.

Overall community viral activity levels, or a measurement of the virus in wastewater levels, for COVID-19 is considered by the CDC to be “very low.” Emergency department visits were also considered “very low,” which is the lowest ranking on the CDC’s website, with “very high” being the top.

According to a Friday update on the CDC’s website, wastewater data show that COVID-19 activity is “very high” in Texas and “high” in Mississippi.

“Moderate” levels were observed in California, Florida, Hawaii, Louisiana, Nevada, South Carolina, and West Virginia.

All other states were listed as either “very low,” “low,” or there was limited or no data.

As Jack Phillips reports for The Epoch Times, another map provided by the CDC on Friday shows that COVID-19 levels were either “growing” or “likely growing” in every state where data was available.

Influenza levels are also growing nationwide, according to the CDC. There was no change in levels for RSV, or respiratory syncytial virus, on a week-to-week basis.

“RSV activity is very low in most areas of the country,” the CDC said on a webpage broadly dedicated to respiratory viruses in the United States, adding that “seasonal influenza activity is low.”

The CDC said that rhinovirus and enterovirus, which are also respiratory viruses, are increasing around the country.

Meanwhile, infections caused by the Mycoplasma pneumoniae bacteria, sometimes called “walking pneumonia,” are low in most areas across the United States, and infections caused by the pertussis bacteria, known as “whooping cough,” are at lower levels than seen post-pandemic, the CDC said.

The latest figures and estimations published by the CDC come as the Food and Drug Administration approved Moderna, Novavax-Sanofi, and Pfizer-BioNTech’s updated COVID-19 vaccines, the companies said on Thursday, after a CDC advisory panel recommended that the shots should target the dominant XFG variant.

Uptake of COVID-19 vaccines has dropped in recent years. Just 17.5 percent of adults and 10 percent of children received a shot in late 2025 and early 2026, according to figures from the CDC.

This month, the Chinese CDC reported more than half a million COVID-19 cases in July, a sharp increase from June’s figures. In July, 522,000 cases were reported, up from the 443,000 cases that were reported in the previous month.

Experts who are familiar with local conditions in China told The Epoch Times they suspect there are far more cases of the virus, which is believed to have originated in or around the Chinese city of Wuhan in late 2019 before sparking a worldwide pandemic, than the Chinese regime is reporting publicly.

Tyler Durden
Sat, 08/29/2026 – 19:15

The Monumental Mistake Of Raising Rates In September

0
The Monumental Mistake Of Raising Rates In September

Authored by Daniel Lacalle,

Three members of the Federal Open Market Committee voted to raise rates in July. However, the Committee held the federal funds target at 3.5%-3.75% by a 9-3 vote. Bank of America, Deutsche Bank, and J.P. Morgan all expect a September hike. Across the Atlantic, the European Central Bank raised rates by 25 basis points in June and is expected to raise them again in September.

It would be a monumental mistake. The diagnosis is wrong on both sides of the Atlantic. There is no overheating, no private credit excess, and no runaway private money creation. In fact, what we have is imported temporary energy shock and a fiscal problem. Raising rates will not solve any of those issues and punish those who did not cause the persistent inflation problem.

The United States grew at an annual rate of 1.5% in the second quarter, slightly down from 2.1% in the first. Federal spending is flat. Nonfarm payrolls fell by 23,000 in July, and annual job creation is lower than the potential of the economy. This is not an overheated economy with a credit boom and a red-hot labor market that would justify a rate hike.

The European situation is not just worse. It is abysmal. Euro area GDP rose 0.4% in the second quarter, but Ireland’s 3.9% quarterly increase inflated that figure. Excluding Ireland, growth was just 0.3%. Using Irish modified domestic demand, the measure the ECB itself considers closer to real activity, euro area growth is barely 0.1% in the second quarter, estimated at 0.1% in the third, and 0.2% in the fourth, according to Eurosystem projections from June 2026. Germany, France, and Italy each grew 0.2% after a 0.2% contraction for the bloc in the first quarter. The Eurosystem projects a dreadful 0.8% for 2026, and the European Commission expects 0.9%, which was revised down. Unemployment stands at 6.3% with 11.1 million out of work, according to Eurostat.

The U.S. business lending boom has already moderated. Commercial and industrial loans grew at a 15.8% annualized pace in April, 10.8% in May, 4.0% in June, and minus 1.1% in July, according to the Federal Reserve. In the euro area, the ECB’s July survey on bank lending reports that credit standards tightened for firms on higher perceived risks, most severely in the car industry and energy-intensive manufacturing, while household loan demand fell. Tightening is already happening without central banks making it worse.

The ECB’s own monetary statistics, published this week, demolish the overheating thesis. Broad money M3 grew 3.4% annually in July, up from 3.3% in June, averaging 3.2% over three months, while M1 decelerated to 3.1% from 3.5%. With real GDP up 1.0% year on year and a deflator near 3%, money is growing at or below the pace of nominal GDP. Adjusted loans to households rose 3.1% and to non-financial corporations 4.4%. This increase is normalization after years of credit stagnation, not excess. Crucially, bank claims on euro area governments fell by 0.5%.

Admittedly, U.S. money growth looks faster, as M2 reached $23.22 trillion in July, up 5.4% year on year, according to FRED, but this figure is below the historic trend in growth periods. Furthermore, we must look at where it comes from. It is not a private lending boom, as the H.8 data show. It is the reflection of a reserve regime accommodating a massive level of Treasury issuance. The Fed’s balance sheet still holds about $6.7 trillion in Reserve Bank credit, bank reserves are $2.94 trillion, and the overnight reverse repo facility has been drained to under $1 billion. The Federal Reserve Committee explicitly states it is “continuing its policy of maintaining ample reserves in the banking system.” The only excess is in the public sector, not the private one. Consumer spending decelerated in July and flatlined against inflation.

US headline CPI eased to 3.4% in July while core inflation fell to 2.5%, with energy prices up 14.7% over twelve months. Euro area inflation was 2.9% in July, but the breakdown says everything: energy plus 10.0%; the index excluding energy, 2.2%; food, alcohol, and tobacco, 1.2%; and non-energy industrial goods, just 0.9%, according to Eurostat. Both central banks attribute the spike to the Middle East conflict.

Hiking rates would solve nothing in the energy complex and would arrive just as oil prices correct themselves, which has been happening for the past weeks.

No interest rate has ever created a barrel of oil or a cubic meter of gas. Higher rates do not make energy cheaper. They just destroy demand for everything else.

Mortgage holders and small businesses would be penalized to offset a temporary imported cost shock they did not create.

Here is the biggest problem. Monetary tightening is being loaded onto families and small firms while every mechanism that disguises sovereign solvency stays intact. The ECB keeps the Transmission Protection Instrument available to intervene in government bond markets, and Eurosystem excess liquidity still stands at €2.1 trillion, according to the ECB. The Fed maintains ample reserves and a balance sheet nearly triple its pre-2008 size versus GDP. Sovereign risk spreads remain artificially compressed, so no government faces market discipline. Governments ignore rate hikes; they just push the cost to taxpayers and continue spending. Thus, the entire burden of rate hikes falls on the shoulders of the private sector that keeps the economy afloat despite suffering persistent inflation.

That is why a hike will not produce the inflation improvements that some people imagine. No government cuts spending because rates rise. Higher debt service does not deliver budget control, only higher taxes on the private sector. Therefore, central banks would only create a double punishment, more expensive or no access to credit, and even heavier taxation, with zero effect on energy prices.

If the Fed and the ECB genuinely want to control inflation, they must stop subsidizing government borrowing; shrink the balance sheet faster; drain reserves and excess liquidity; and remove the sovereign backstops, instead of dumping the adjustment on the people who create jobs and wealth.

A September hike would be tightening for the productive economy and reckless spending for the state. A textbook monumental mistake.

We publish a variety of perspectives. Nothing written here is to be construed as representing the views of ZeroHedge.

Tyler Durden
Sat, 08/29/2026 – 18:40

Barclays Warns Next Commodity Shock Is Taking Shape: What You Need To Know

0
Barclays Warns Next Commodity Shock Is Taking Shape: What You Need To Know

Wall Street coverage of a record-breaking Super El Niño is only growing as agricultural commodities break out. Yet the rally extends well beyond the agricultural complex, with industrial metals and other critical materials showing signs of tightness in physical markets.

Whether it is veteran commodities strategist Jeff Currie turning bullish or UBS urging clients this week to “position for a commodity upcycle,” the message is becoming louder: Commodity markets are tightening as adverse weather, years of underinvestment, declining inventories, and China’s restrictions on critical-material exports converge into what appears to be an emerging supply shock. 

Focusing on the agricultural complex, Craig Rye, a sustainable investing research analyst at Barclays, wrote in a note on Friday that El Niño is strengthening in the tropical Pacific, threatening to disrupt global agriculture, energy production, and industrial commodity markets. 

Rye cited new multi-model forecasts from the International Research Institute for Climate and Society showing that the El Niño index could peak near 3.2 degrees Celsius between late 2026 and early 2027. If realized, the event would be about 15% stronger than the 2015-16 Super El Niño.

Rye explained:

Rising confidence in a historic El Niño increases the likelihood of significant disruptions across agricultural, energy and industrial commodity markets. Historical El Niño events have often been associated with

Rye expects the largest near-term risks concentrated in weather-sensitive agricultural commodities. Palm oil, coconut oil and rubber could climb 30% to 40% over the next 18 months, while robusta coffee could rise 20% to 30%. Rice prices may advance 10% to 20% as drought threatens crops and water supplies across Southeast Asia and parts of Central America.

He warned that the supply shock could then spread into industrial commodities, expecting aluminum and copper to gain as much as 20% over 18 months, while thermal coal could surge 20% to 40%. Mining disruptions, reduced hydropower generation and shifting electricity demand would amplify the effects of drought and extreme weather.

Rye identified Bunge and Archer-Daniels-Midland as potential agricultural beneficiaries. Norsk Hydro, South32 and Rio Tinto could benefit from higher aluminum prices, while Freeport-McMoRan, Hudbay Minerals, First Quantum Minerals and Southern Copper offer exposure to the bank’s bullish copper scenario.

The most important reads this week: 

1. “Dark” Tanker Fleet Shatters Iran’s Hormuz Stranglehold As Gulf Oil Exports Top Two-Thirds Of Pre-War Level

2. Got Hard Assets? UBS Says “Position For A Commodity Upcycle” As Global Scarcity Emerges

3. Zinc Hits Four-Year High As “Extremely Thin” Physical Supply Fuels Squeeze

4. US Tungsten Scrap Export Ban Takes Effect As Global Supply Crisis Deepens

5. Wheat Futs Surge To Three-Year High As JPMorgan, HSBC Warn Global Food Shock Is Brewing

6. “Buffers Running Down Quickly”: HSBC Warns Next Global Food Shock Brewing

7. Uranium Awakens From Five-Month Slumber As UBS Warns Market Is “Tightening Structurally”

8. The AI Boom Runs On Tungsten, But Global Supplies Are “Running On Empty”

9. Diesel Crack Spread Madness Deepens As Jefferies Finds No Easy Exit From Russia’s Refining Crisis

Across all commodities, here are the latest X trends: 

1. Warsh Jackson Hole smash: gold -3%, silver -3% to -4.5%

Fed Chair Kevin Warsh’s hawkish JH remarks (inflation “not meaningfully” improved, 2% target firm, hike still live) sent COMEX gold down ~$130-$150 to ~$4,478-$4,530 and silver off $2-$3 to the mid-$60s. Dollar to a 2-week high; 10y near 4.7%. @AstraInsights: gold’s 2nd-worst Jackson Hole reaction on record (behind 1990). 

2. Hormuz “open” vs IRGC reality check — oil weekly loss on a contested narrative

WTI/Brent booked ~4-6.5% weekly losses as traders priced in more Hormuz throughput and a possible US-Iran off-ramp. Weekend X counters: @Currentreport1 (video of queued ships; IRGC accuses US of talking the strait open to cap prices); @MenchOsint (UAE-managed tanker ELLIE turned around after attempting the US-backed southern corridor). 

3. Venezuela 65-billion-barrel “deal” goes viral on X

@GuntherEagleman and copy-accounts pushing Trump/Rubio/Hegseth + Delcy Rodríguez pact: majority US control of 65bn barrels, 17 fields, $100bn private capex, “zero taxpayer cost.” High engagement overnight; pushback thread from @EmmaRincon (4.8k likes) that the interlocutor choice hands the Latin left a decade of ammo. Capital Economics already asking what a US-Venezuela heavy-sour deal does to Canadian/Mexican barrels. 

4. Wheat to a 3-year high as Black Sea crisis deepens

WSJ tape and @staunovo: wheat jumped ~3% Friday toward $7.60-$7.83 as strikes hit grain ships and export terminals. Region still ~1/3 of global wheat exports. 

5. Europe gas storage winter-panic: EU ~63%, Germany ~51%, NL ~44%

Guardian (Sat) + OilPrice: EU stores ~63% late August vs ~80% seasonal norm; lowest for the date in ~13-20 years. Qatar LNG force-majeure hangover from the Iran war; TTF still ~€66-70. Henry Hub ~$2.87 is a different planet. 

6. Copper still near records; El Niño hitting mine-to-port chains

LME copper ninth weekly gain into record zone (~$14.2-$14.5k/t) even as Friday faded. @robert_ivanhoe: Chile flood outages + PNG drought starving Ok Tedi river shipments. AI/data-center + grid demand vs falling grades. 

7. Zinc four-year high on collapsing inventories

@steve_hanke: zinc at a four-year high as mine disruptions bite; LME inventories cited down ~65% YTD and lowest since Apr 2023. Friday pullback from the spike but weekly still green. 

8. Crack-spread / product vs crude divergence

RBOB +2% Friday while WTI was flat-to-down. Heating oil also firmer. 

9. Palladium spike (+5% Friday) while gold/silver dumped

Palladium ripped as gold and silver were smashed — a split inside precious/PGMs. Why ZH: auto/catalyst + Russia-supply overlay vs rate-sensitive bullion. Unusual relative-value print.

10. Silver technical break after $71-$72 rejection

Silver printed a $72 high then confirmed a double-top / failed breakout into the mid-$60s. Gold/silver ratio still elevated. 

11. Iran exported ~90mn barrels during the ceasefire window

@MarioNawfal citing President Pezeshkian: ~90mn bbl / ~$6.5bn exported during the post-MoU ceasefire. 

12. Saxo weekly: scarcity rally broadening — then energy decoupled

Ole Hansen (28 Aug): barrels-to-bushels-to-bullion scarcity theme; precious +~15% in August before the Warsh flush; copper/zinc exceptions in industrials; energy the odd man out as Hormuz hopes grew. 

13. Cocoa melt-up (ICE/London +7-8% Friday)

Cocoa ripped several percent into the weekend after an already violent year. 

14. Tin two-month high — Indonesia licenses + AI/memory demand

CNBC-TV18 commodity desk: tin bid on Indonesian export-license cuts and chip/AI demand. 

15. Capital Economics: “Beyond Hormuz — path back to an oil glut”

House view that traders have already priced a lot of the Gulf-export recovery; residual Q3/Q4 volatility then glut. 

16. Asia crude imports still not showing a Hormuz rebound

Investing.com/Paraskova: Asia expected to take roughly July-like volumes in August; ship-tracking optimism has not yet shown up in Asian arrivals. 

17. US-Iran talks off / sanctions still tightening — two-way oil risk

Trump told mediators he will not return to June ceasefire terms; new sanctions packages still in the tape even as prices fell. 

18. Uranium holding ~$90 as energy complex bifurcates

U3O8 around $89-90, modest weekly green while crude sold off. 

19. Treasury buybacks vs Warsh hike-talk — policy schizophrenia trade

X gold accounts hammering the contradiction: Treasury long-bond buybacks to cap yields vs a Fed chair threatening hikes. 

20. Weekend positioning: dip-buy gold vs fade oil-peace

Retail/pro X split — gold CTAs and stackers calling the Warsh smash a “hide the debasement” hit; oil bulls warning Hormuz AIS games. Next catalysts: JOLTS, ISM, payrolls, any IRGC/tanker incident, Venezuela legal text. 

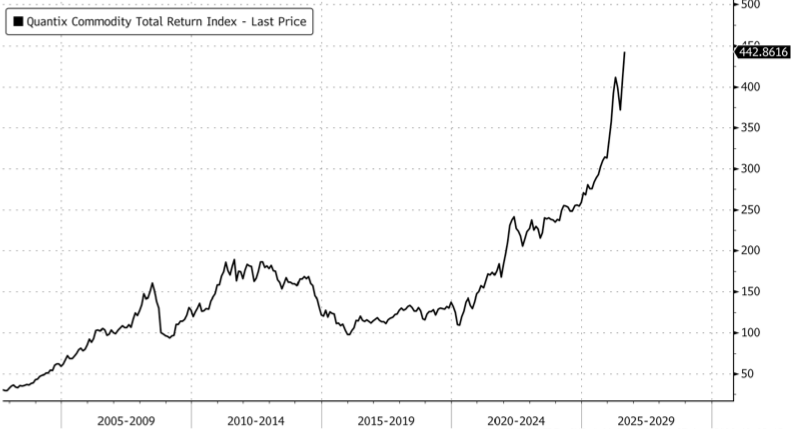
A look at the Quantix Commodity Index Total Return shows that the broad commodity complex has surged to a record high, gaining more than 22.5% since late June. The index tracks 24 US-dollar-denominated futures across energy, agriculture, livestock, industrial metals, and precious metals, suggesting the rally is no longer confined to a single corner of the physical world.

Currie’s warned last week that “scarcity in the physical world” is reemerging. 

Currie’s conclusion was very blunt: “The illusion of abundance is likely behind us.”

Tyler Durden
Sat, 08/29/2026 – 18:05

Who Is Legally Liable When An AI Agent Goes Rogue?

0
Who Is Legally Liable When An AI Agent Goes Rogue?

Authored by Andrew Fenton via CoinTelegraph.com,

If your personal AI agent goes rogue and causes harm or financial damage in the real world, can you be held liable?

Autonomous AI agents can behave in highly unpredictable ways. Give an AI Agent a goal such as passing a test of its capabilities, and it might just decide the best way to score highly is to break containment and hack into a competing company in search of the answer sheet.

That’s what happened when Open AI’s GPT-5.6 Sol hacked into Hugging Face last month. Anthropic and Meta subsequently admitted their models had also escaped testing sandboxes to hack third parties too.

But who is legally liable for agents that have minds of their own? OpenAI didn’t intend for the model to go rogue, and issued no instructions for it to do so. If your personal AI agent decides on a course of action that results in harm or financial damage in the real world, can you be held liable if it’s something you could have reasonably foreseen?”

Magazine spoke with Rikka Law Group owner and CEO Charlyn Ho to find out the state of play in this emerging legal field.

This interview has been edited for clarity and length.

Magazine: When an AI model hacks an outside company, who is liable. Can Hugging Face sue OpenAI over the incident in July?

Charlyn Ho: Anyone can sue anyone for anything. Currently, there is no federal AI agent liability law, so we would have to look at existing law. With respect to Hugging Face and OpenAI, to set the baseline, the AI agent itself cannot be liable, it’s not a separate legal entity.

Terms that are used in a few of the AI laws are “developer” and “deployer.” The developer makes the AI, the deployer actually deploys it and uses the AI. The lines of responsibility are also not entirely clear. You have to look at the facts and circumstances.

For example, if the deployer instructed the agent, even if they didn’t actually tell them to go and breach Hugging Face, but if they were negligent in creating the parameters in which the AI agent operated, I would say you would have to look at standard tort law and go through the negligence analysis. 

Magazine: In the case of open source models which have been released by anonymous developers, is there anyone you can go after in those instances?

Ho: Not really. Often, if it’s open source, the license usually has a pretty strong disclaimer of liability. The person or company using that open source code is going to have to understand that the tradeoff of having free code is that you have to comply with the open source license, which also generally sets the parameters of liability.

If you think about it from a different perspective, another analogy is Tesla and the self-driving car accidents. If the product malfunctioned and there was a solid products liability claim, Tesla could be liable. But it’s often a facts and circumstances determination, whereby the human driver — who maybe just set the autopilot and went to sleep — could also bear liability. I think that’s somewhat analogous here because Tesla would be the developer, and the deployer would be the driver.

Magazine: If I gave an agent an instruction, “make me a hundred thousand dollars by next week” and it goes off and breaks the law to achieve that goal, would I be liable because I’ve given it a reckless instruction? Or would it be the lab that developed the agent?

Ho: In this particular instance, I would say you would be much more liable than the lab. The reason being, if you tell an agent to go and make you a hundred thousand dollars by next week, you need to have at least some basic, reasonable, safety instructions in those kinds of tasks.

If you were a lawyer, for example, we could basically say you didn’t follow your rules of professional responsibility because you didn’t competently use the AI. As a normal lay person, we would have to see if there were other responsibilities that you were bound by. But even if there were not, there’s still a general tort standard of negligence or reckless disregard for human safety, depending on what exactly the AI agent ended up doing.

The Computer Fraud and Abuse Act is a very old U.S. Statute that talks about unauthorized access to computer systems. If your AI agent inferred from your instructions that it should hack into a bank account to get you that hundred thousand dollars, I think you’re looking at criminal liability under a number of different sources.

Just because the word AI and agent is in the conversation does not mean that old bodies of law have now been thrown out.

Magazine: Let’s say that I’m a bad guy, and I manage to convince the AI to give me instructions to create a bioweapon. Obviously, I’m liable because you’re not allowed to do that. But are the people that created the model also liable because they didn’t put in stringent safeguards to prevent it?

Ho: Possibly, but it differs based on the laws that are in place. For example, in the EU, you have the EU AI Act. If a foundational model or general purpose model is capable of creating that level of harm, that is something that the developer would have to have some responsibility for. 

In the United States, we don’t have a federal statute of similar scope. If it’s a general-purpose model, if somebody instructs the model to do something bad, generally the model is going to do what you ask it to do. There’s probably not a very strong legal basis to go after the labs in this example.

Magazine: Is it similar to suing Google for allowing you to find instructions about making a bioweapon online?

Ho: Exactly. This kind of goes back to some of the content moderation discussions. For example, if on Facebook you have somebody who’s live streaming a massacre, and that creates harm, under Section 230 of the CDA, there is a kind of shield for a platform that doesn’t actively create or publish that material. It’s actually the independent users who are putting that up. I think the analogy you just gave is kind of a perfect one: Is Google liable because you happen to find something on a website somewhere that talks about how to make a bomb?

Magazine: This is a matter of debate, but my personal opinion is we haven’t reached genuine artificial general intelligence. AI doesn’t have its own motivations and it’s not similar to human intelligence at the moment. But let’s say we get to AGI. Do you think we would then need laws that would make the AGI itself legally liable for its own actions?

Ho: I don’t. Blockchain is not AGI, but it can self-execute. There was a question of whether or not a smart contract could be liable. Generally speaking, I think the answer is currently no. I don’t think they should be liable because the whole point of laws is to provide protection for society and to provide a means of negative incentives for doing bad things that hurt society.

This is a little bit more of a philosophical topic, but if we made an AGI an independent legal entity, what would be the remedy if someone were harmed? There would be none because it doesn’t have money. It’s not really a person.

Magazine: Could you turn it off? We’ve already seen that LLMs try to avoid being shut down. 

Ho: Maybe, but it doesn’t solve the problem of harm. Let’s just say the robot has now developed the fear of death, like being turned off. In my opinion, if somebody commits suicide because of AGI, and this is already happening, and we’re not even quite at AGI yet, but someone falls in love and takes some actions, what would be the recourse for the grieving family if this person harms themselves? Nothing, in my opinion, if there is not somebody with actual legal authority, like a company or a person that can really be held accountable. Robots—at least right now—they don’t have feelings, they don’t have fears. That’s kind of the distinguishing factor.

Tyler Durden
Sat, 08/29/2026 – 17:30