53.5 F
Chicago
Friday, October 16, 2026
Home Blog Page 1260

Futures Drop As Powell Dovish Pivot Euphoria Fades

0
Futures Drop As Powell Dovish Pivot Euphoria Fades

Markets are mixed this morning, with US stock futures ticking lower as euphoria over the prospect of a Fed rate cut fizzling out after Friday’s rally. Attention turns to one of the biggest market tests ahead of the central bank’s September policy meeting: Wednesday’s Nvidia earnings. As of 8:15am, S&P futures are down 0.3% after the best day since May and the index finishing the week 2pts below its all time high. Media are pointing to a lack of Fed consensus to cut based on comments from Goolsbee / Musalem. Pre-market Mag7 names are all lower with Defensives outperforming Cyclicals, reversing some of the gains from Friday. Intel shares rose in premarket trading after the US agreed to take a 10% stake in the chip maker. The yield curve is bear steepening and the USD is strengthening. Commodities are rallying led by Energy. The keys this week are NVDA earnings but also a number of macro data releases that can clarify the US econ growth situation, e.g., Durable / Cap Goods, Consumer Confidence, regional Fed activity indicators, jobless data, PCE, and Personal Income / Spending.Looking at today’s calendar, we get new home sales and Dallas Fed manufacturing index. Fed Voter Williams and non-voter Logan are also scheduled to speak. 

In premarket trading, Mag 7 stocks are all lower (Nvidia -0.1%, Alphabet -0.1%, Microsoft -0.2%, Apple -0.4%, Meta -0.4%, Tesla -0.5%, Amazon -0.6%).

  • Furniture stocks are reacting after President Trump announced a “major Tariff Investigation on Furniture coming into the United States.” Arhaus (ARHS) -3%, Ethan Allen (ETD) +3%, RH (RH) -7%, Wayfair (W) -6%
  • American Eagle Outfitters (AEO) falls 3% after BofA Global Research cut the recommendation on the apparel retailer to underperform amid tariff pressures on profitability.
  • Axogen (AXGN) drops 14% after the FDA extended its review its Biologics License Application for Avance Nerve Graft by three months, pushing the decision date to Dec. 5.
  • Dyne Therapeutics (DYN) rises 6% after Raymond James raised the recommendation to strong buy from outperform, citing optimism about an investigational therapy for Duchenne muscular dystrophy, a rare muscle disease.
  • Intel (INTC) shares rose in premarket trading after the US agreed to take a 10% stake in the chip maker. 
  • Keurig Dr Pepper Inc. (KDP) is down 4% after after the announcement of a deal to buy JDE Peet’s NV for $18.4 billion in an overhaul that will see it split the coffee business from other beverage operations only a few years after a deal that combined them.
  • PDD Holdings Inc. (PDD) surges 6% after company behind the popular Temu platform reported net income and adjusted earnings per American depositary receipts that beat the average analyst estimates.
  • Verint Systems Inc (VRNT) jumps 12% after Bloomberg reported that buyout firm Thoma Bravo is nearing a deal to acquire the call center software maker.

Overnight, developments were limited with London out for their Summer Bank Holiday. Over the weekend, Fed voter Musalem told Reuters that more data is needed to decide whether a September rate cut is warranted. In China, Shanghai eased home-buying rules to enable eligible residents, including those from outside Shanghai, to now buy an unlimited number of homes in the outer suburbs.

Sentiment had been weak heading into Friday, with the S&P 500 falling for five straight sessions, its longest losing streak since January, as Wall Street pared bets that the Fed was about to reduce borrowing costs. Powell’s comments halted those concerns, sending the equity benchmark soaring more than 1.5% to notch a third straight weekly advance, with last month’s record high in sight. A plunge in short-end Treasury rates sent the US yield curve to its steepest since 2021 on Friday.

“The limited move in long-dated yields has led to a steepening in the curve, perhaps for fear that the Fed is prioritizing the jobs market, while letting inflation run hot above the 2% target,” said Matthew Ryan, head of market strategy at Ebury Partners Ltd. “Rising fears surrounding Federal Reserve independence, and President Trump’s influence on monetary policy, are not exactly helping matters.

Traders now see an 84% chance of a Fed rate cut next month after Powell signaled that the central bank may ease before inflation fully returns to target amid a softening hiring environment. That optimism faces key tests this week, including Nvidia Corp.’s results on Wednesday and the Fed’s preferred price gauge on Friday.  Traders are hoping Nvidia results can soothe fears about AI spending and effectively confirm that the stock market’s latest rally isn’t just a technology bubble. Nvidia’s size — it has the biggest weighting in the S&P 500 at almost 8% — and its position at the center of AI development have made it a bellwether of the broader market. The tech giant’s chips are everywhere, with 40% of its revenue coming from tech giants including Meta Platforms Inc., Microsoft Corp., Alphabet Inc. and Amazon.com Inc.

Powell, in what was likely his final Jackson Hole speech at the helm of the Fed, detailed the cloudy signals coming from the economy. While the effect of tariffs on prices is now visible, there are still questions about whether that will reignite inflation in a more persistent way, he said. He called the labor market’s current status — with both falling demand for, and declining supply of workers — “curious.”

“It’s clear that Fed is prioritizing the job weakness concern over inflation and that’s their stance now,” said Jin Yuejue, Hong Kong-based multi-asset solutions investment specialist at JPMorgan Asset Management. Still, the signal from the speech is “quite clear” that the Fed is ready to pivot, she said.

“The path ahead is not so straightforward,” said Daniel Murray, chief executive officer of EFG Asset Management. “‘While easier monetary policy is usually welcomed by markets, the context also matters and there remains significant uncertainty regarding the macro and corporate environments.”

The Stoxx Europe 600 index dropped about 0.2% after closing just short of an all-time high Friday. Liquidity was lower than usual, with UK markets closed for a holiday. Danish renewable-energy company Orsted A/S plunged after President Donald Trump’s administration halted construction on an almost-finished offshore wind farm. JDE Peet’s soared on the Keurig Dr Pepper takeover offer. Here are the biggest movers Monday:

  • Orsted shares fall as much as 19% to a record low, after the Trump administration halted work on the Danish firm’s offshore wind farm. European wind energy peers also decline
  • Thule falls as much as 6.4%, the most since May, after SEB cut its recommendation for the Swedish outdoor equipment maker to sell from hold with a Street-low price target of SEK225. The analyst cited swiftly rising costs and a lack of volume growth
  • Valneva shares plunge 26%, the most since June 2022, after the French vaccine maker’s shot for a mosquito-borne disease was suspended in the US on an investigation into its adverse effects among older patients
  • SBB drops as much as 7.7%, most since July, after Pareto Securities reiterates its sell rating and street-low price target of SEK2.8, saying core challenges remain for the Swedish landlord even as the country’s property market stabilizes and interest rates decline

Earlier in the session, Asian stocks rose, boosted by Chinese chip stocks and continued optimism that the Federal Reserve will lower interest rates next month. The MSCI Asia Pacific Index rose as much as 1.1%, with TSMC, Alibaba and Tencent providing the biggest boosts to the benchmark. Most major equity indexes were in the green, with Taiwan, South Korea and Hong Kong leading the gains in the region. China’s stock rally extended, partly as investor sentiment on the outlook for the nation’s chip sector strengthened. The STAR 50 Index rallied 3.2% in China, extending last week’s 13% surge, while the onshore benchmark CSI 300 Index gained 2.1% to the highest since July 2022. Positive news such as DeepSeek’s new model update, customized to work with next-generation Chinese-made AI chips, has helped propel the rally.

“Asian equities across the board will certainly be boosted if expectations of a cut rise further as the September FOMC approaches,” said Gerald Gan, deputy chief investment officer at Reed Capital.

A gauge of the dollar was steady after posting its third straight weekly loss. The 10-year Treasury yield rose two basis points and bonds in Europe fell, with yields on German bunds climbing five basis points. The TSY yield curve continues to steepen, extending the trend from Friday, when UST advance following Fed Chair Powell’s Jackson Hole speech was the biggest since the Aug. 1 rally sparked by weak employment data.

In commodities, WTI crude futures are rose 0.6% to $64.04, while gold dips to $3,366.

The US economic data calendar includes July Chicago Fed national activity index (8:30 a.m.), July new home sales (10 a.m.) and August Dallas Fed manufacturing activity (10:30 a.m.); Fed speaker slate also includes Dallas Fed President Logan (3:15 p.m.) and New York Fed President Williams at 7:15 p.m.

Market Snapshot

  • S&P 500 mini -0.3%
  • Nasdaq 100 mini -0.3%
  • Russell 2000 mini little changed
  • Stoxx Europe 600 -0.3%
  • DAX -0.4%
  • CAC 40 -0.6%
  • 10-year Treasury yield little changed at 4.26%
  • VIX +0.9 points at 15.11
  • Bloomberg Dollar Index little changed at 1202.63
  • euro -0.1% at $1.1701
  • WTI crude +0.4% at $63.92/barrel

Top Overnight News

  • Despite Powell’s speech, clear divisions remain among Fed officials. The St. Louis Fed’s Alberto Musalem said he’ll need more data, Reuters reported, while Chicago’s Austan Goolsbee pointed out he’s still more concerned about the inflation side of their mandate than employment. BBG 
  • Investors are piling back into NY office buildings, lending billions of dollars to property developers in a sign big money managers see return to office wave as a much needed salve to the mkt. FT 
  • Thousands of homes in northern California and central Oregon were under evacuation orders on Sunday from wildfires. AP 
  • Pentagon plans a military deployment in Chicago as President Trump eyes a crackdown: WaPo
  • California warns that its agricultural industry feeds the US but is now under assault from Trump’s immigration policies, creating the risk of higher prices or food shortages. NYT 
  • China’s financial hub of Shanghai eased home-buying rules in the latest attempt by authorities to contain the nation’s prolonged property crisis. Eligible residents, including those from outside Shanghai, can now buy an unlimited number of homes in the outer suburbs, according to a statement Monday. BBG 
  • China is banking on artificial intelligence (AI) to become a new growth engine, and there are projections that it could add several trillion yuan to the economy by 2035 amid a national push for computing power and a unified data market. SCMP 
  • South Korea’s Lee Jae Myung meets Trump at the White House today. He’ll urge him to revive stalled North Korea talks and follow up on a recently signed trade deal. BBG 
  • German business confidence unexpectedly improved in August to the highest level since 2022, after the EU struck a trade deal with the US. BBG 
  • Keurig Dr Pepper will buy JDE Peet’s for $18.4 billion in cash in an effort to revive its struggling coffee business. The combined company will later separate its beverage and coffee operations, essentially reversing the 2018 deal that combined Keurig and Dr Pepper. BBG 

Trade/Tariffs

  • US food industry groups are pushing for exemptions from US tariffs and arguing that products from fish to cucumbers cannot be affordably grown at home, according to FT.
  • European Commission President Von der Leyen defended the EU-US agreement on tariffs which she said was a ‘conscious decision’ that avoided a trade war and called it a “good, if not perfect agreement”, according to euro news.
  • South Korea’s President Lee said they will ultimately arrive at a reasonable trade deal with the US and he expects to discuss with US President Trump security and defence costs, as well as tariff negotiations.
  • India’s Foreign Minister said trade negotiations are still going on and they have lines to maintain and defend, while he added the lines India cannot cross are the interests of farmers and small producers. Furthermore, he said India buying Russian oil was never brought up before the public announcement of tariffs and issues about buying Russian oil are not being used to target other major users such as China and the EU.
  • French President Macron said he had an in-depth discussion on major international crises with South African President Ramaphosa, while they also reviewed economic and trade issues, as well as bilateral cooperation between France and South Africa.

A more detailed look at global markets courtesy of Newsquawk

APAC stocks began the week on the front foot as the region took its opportunity to react to the dovish comments by Fed Chair Powell at Jackson Hole on Friday, in which he signalled the potential for a September rate cut as he noted that the shifting balance of risks may warrant adjusting policy. ASX 200 rallied to a fresh record high at the open but gave back a majority of the early gains as participants also  digested a slew of earnings releases. Nikkei 225 advanced at the open but then lost steam and faded most of the early upward momentum to return to beneath the 43,000 level with headwinds from last Friday’s currency strength and with some hawkish-leaning comments from BoJ Governor Ueda at Jackson Hole who expects a tightening job market to push up wages. Hang Seng and Shanghai Comp outperformed with the advances in Hong Kong led by property, mining and tech, while the mainland was also lifted after China’s State Council called for efforts to bolster overall coordination and refine implementation mechanisms of large-scale equipment upgrades and consumer goods trade-in programs to better leverage their role in boosting domestic demand. Furthermore, participants digested several earnings releases and the PBoC announced last Friday to conduct CNY 600bln of 1-year MLF loans for today.

Top Asian News

  • BoJ Governor Ueda said at Jackson Hole that barring a major negative demand shock, the labour market is expected to remain tight and put pressure on wages, while he added that competition for workers has increased and more people are switching jobs. Ueda said they will continue to monitor the labour market developments closely and incorporate that into monetary policy. Furthermore, he said wages are now rising and labour shortages have become one of the most pressing economic issues, as well as noted that the demographic shift that began in the 1980s is producing acute labour shortages and persistent upward pressure on wages.
  • Japanese PM Ishiba said Japan agreed to strengthen security and economic ties with South Korea, while South Korean President Lee said they agreed on South Korea-Japan relations, which are important in a fast-changing global political landscape.
  • Shanghai lifts the home buying limit in the outer suburbs effective August 26th, according to Bloomberg.
  • RBNZ opened consultation on New Zealand’s capital settings for deposit takers with the review to consider whether current prudential capital requirements are set at the right level, while the central bank proposed to lower the minimum capital requirement to NZD 5mln.
  • Fitch affirms India at BBB-; outlook stable.

European bourses (STOXX 600 -0.2%) have begun the week on the backfoot, as indices pare back some of the Powell-induced strength seen on Friday. European sectors opened mostly in the red, only a few remaining afloat including Banks, Media along with Travel & Leisure. At the bottom of the pile is Utilities due to notable losses in Orsted (-17%) after it received an offshore stop-work order from US BOEM.

Top European News

  • BoE Governor Bailey said at Jackson Hole that the UK faces an “acute challenge” over its weak underlying economic growth and reduced labour force participation since the COVID-19 pandemic, while he said the BoE shifted its focus away from long-term trends in unemployment to looking at levels of labour force participation instead, according to Reuters.
  • ECB’s Lagarde said at Jackson Hole that the labour market has weathered recent shocks and proved to be surprisingly resilient in the face of an inflation shock and aggressive interest rate hikes, while she also commented that central bank independence is critically important.
  • ECB’s Kazaks said the central bank entered a new monetary-policy phase where officials can focus on monitoring the economy rather than actively intervening to change its course, while he noted there is currently no need to lower rates further as inflation is at the 2% target and recent data has not signalled a marked change in the outlook since the quarterly projections in June, according to Bloomberg.
  • ECB’s Rehn said the central bank is in no hurry to cut interest rates further after inflation reached its 2% target and with the economy performing slightly better than thought, according to Bloomberg.
  • ECB rate cut talk may resume after a pause in September, should the economy continue to weaken, according to Reuters citing sources.
  • German Chancellor Merz said tackling economic woes is tougher than expected and that the US’s 15% tariffs on German exports will be a burden on the German economy, according to Bloomberg.
  • Fitch affirmed the UK on Friday at AA-; Outlook Stable but stated that greater global uncertainty and weaker external demand will dampen investment growth.
  • Italy’s Deputy PM Tajani said he opposes Italy imposing windfall taxes on banks, while he commented that banks should pay taxes and contribute but should not be surprised or scolded, according to Bloomberg.
  • Canadian PM Carney will travel to Poland, Germany and Latvia during August 25th-27th and will meet with German Chancellor Merz, while Carney will be focused on strengthening relationships with European allies and advancing cooperation in key areas.

FX

  • DXY has kicked the week off slightly firmer. Gains, however, are relatively minor compared to the losses seen on Friday post-Powell, where he signalled to a September rate cut. Focus this week will turn to PCE on Thursday. Upside in DXY is currently capped by the 98 mark. If breached, the 50DMA sits at 98.06.
  • After venturing as high as 1.1742 on Friday, EUR/USD has slipped below the 1.17 mark as the dollar attempts to atone for recent losses. German IFO data today saw a strong turnout for the expectations component, helping the headline print above the market consensus. That being said, the IFO President noted that “the recovery of the German economy remains weak”. EUR/USD has delved as low as 1.1694 thus far with interim support provided by the 50DMA at 1.1650.
  • After a strong showing on Friday, the JPY rally against the USD has paused for breath. The JPY has been unable to garner any further support from comments by BoJ governor Ueda, who stated that barring a major negative demand shock, the labour market is expected to remain tight and put pressure on wages. USD/JPY has made its way back onto a 147 handle after delving as low as 146.57 overnight with a current session peak at 147.52.
  • GBP is a touch softer vs. the USD with UK market participants way from market. Subsequently, newsflow surrounding the UK is light aside from comments by BoE Governor Bailey, who remarked that the UK faces an “acute challenge” over its weak underlying economic growth and reduced labour force participation since the COVID-19 pandemic. He added that the BoE shifted its focus away from long-term trends in unemployment to looking at levels of labour force participation instead.
  • Steady trade for the antipodes with AUD supported by a much firmer-than-expected CNY reference rate setting. For AUD this week, RBA minutes are due on deck tomorrow with monthly CPI set to hit on Wednesday.
  • Barclays month-end rebalancing model: weak USD selling against most majors. Neutral vs. EUR and JPY.
  • PBoC set USD/CNY mid-point at 7.1161 vs exp. 7.1551 (Prev. 7.1321).

Fixed Income

  • USTs are essentially flat and trade in a very narrow 4 tick range (112-01 to 112-05), as US paper takes a breather from Friday’s significant upside following dovish remarks from the Fed Chair. From a yield perspective, there is some mild bear flattening, with the short-end making back some of Friday’s pressure.
  • Bunds are trading on the backfoot and currently lower by around 38 ticks, pulling back from the upside seen on Friday. Currently trading towards the bottom-end of a 129.02 to 129.31 range; further downside will see a test of the round 129.00 mark, and below that 128.94 (the lower from Friday). From a yield perspective, the German 10yr is currently higher by 3.7bps at around 2.756%. Focus has been on the ECB over the weekend. Firstly, Reuters reported that ECB rate cut talks may resume after the September pause, should the economy continue to deteriorate. Elsewhere, President Lagarde said Europe’s labour market has remained resilient despite severe inflation shocks and aggressive rate hikes.
  • Gilt futures trading is currently shut today on account of the UK’s Bank Holiday.

Commodities

  • The crude complex trades with a modest positive bias on the first trading session of the week. On the geopolitical front, Ukrainian drones attacked an industrial facility in Russia’s Samara region which sparked a fire at Russia’s Novatek Ust-Luga terminal. However, Kazakhstan’s energy ministry said the nation’s oil exports had not been interrupted by the disruption. Aside from this, energy-specific drivers are light. WTI trades within a USD 63.53-64.03/bbl range, while Brent trades within USD 67.04-67.50/bbl.
  • Precious metals trade mixed. Palladium modestly outperforms despite weakness in auto stocks, while gold is softer amid a modestly firmer dollar and a pullback from Fed Chair Powell’s dovish address on Friday. XAU/USD currently trades choppily within a USD 3,405-3,417/oz range, towards the top end of Friday’s parameters with a high at 3,425/oz.
  • 3M LME trade is closed today amid the UK bank holiday.
  • Iraq raised its refining capacity to 1.3mln bpd from 1.1mln bpd in 2024, according to the PM’s office.
  • Libya’s NOC said it will host the first Libyan-US energy forum soon.
  • Codelco said Chile’s mining regulator authorised the restart of operations at Andes Norte and Diamante divisions of the El Teniente mine.
  • Kazakhstan’s energy ministry says the nation’s oil exports have not been interrupted following a Ukrainian drone strike on Russia’s Ust-Luga.

Geopolitics: Middle East

  • Israel’s military conducted an attack on the Yemeni capital of Sanaa against targets which included a military compound where the presidential palace is located, two power stations and a fuel storage site.
  • Iran’s Supreme Leader said the current situation with the United States was “unsolvable” and that they will stand strongly against the US demand to make Tehran ‘obedient’, according to Reuters citing state media.
  • Iran is prepared to significantly lower uranium enrichment to prevent Britain reimposing UN sanctions, according to The Telegraph.

Geopolitics: Ukraine

  • Ukraine’s PM discussed security guarantees with US special representative Kellogg.
  • US Pentagon quietly blocked Ukraine’s long-range missile strike on Russia with the US Defense Department withholding approval as the White House sought to entice Moscow to open peace talks, according to WSJ. However, it was later reported that Ukrainian President Zelensky said Ukraine has lately been using its own weapons to hit Russia and does not consult on this with Washington.
  • Russia and Ukraine conducted an exchange of POWs in which they swapped 146 POWs each.
  • Russia’s Defence Ministry said Russian forces captured Filiia in Ukraine’s Dnipropetrovsk region, according to Interfax.
  • Russian air defence forces shot down a Ukrainian drone near the Kursk nuclear power plant and a fire broke out at the plant, although there were no safety threats to people or the plant. However, the Kusk acting Governor separately commented that the Ukrainian drone attack on the nuclear power plant is a threat to nuclear safety.
  • Russian air defences downed a drone flying towards Moscow. It was separately reported that Ukrainian drones attacked an industrial facility in Russia’s Samara region and that debris from a destroyed Ukrainian drone attack sparked a fire at Russia’s Novatek Ust-Luga terminal.
  • Norway is providing air defences worth NOK 7bln to Ukraine, which will be delivered from Germany to Ukraine, with Norway and Germany funding two patriot systems including missiles.
  • Russian defence ministry says its forces captured Zaporizke in eastern Ukraine, via RIA.

Geopolitics: Other

  • North Korean leader Kim oversaw the firing of new air defence missiles, according to KCNA. In relevant news, South Korea confirmed it fired warning shots earlier last week at North Korean soldiers who briefly crossed the border between the two countries, according to the BBC.

US Event Calendar

  • 8:30 am: Jul Chicago Fed Nat Activity Index, est. -0.11, prior -0.1
  • 10:00 am: Jul New Home Sales, est. 630k, prior 627k
  • 10:00 am: Jul New Home Sales MoM, est. 0.48%, prior 0.6%
  • 10:30 am: Aug Dallas Fed Manf. Activity, est. -1.7, prior 0.9

Central Bank speakers

  • 3:15 pm: Fed’s Logan Speaks at Bank of Mexico Centennial Conference

DB’s Jim Reid concludes the overnight wrap

Markets ended last week in a buoyant mood as a dovish tilt by Powell at Jackson Hole left investors increasingly confident on upcoming Fed easing. While Fed news will continue to draw attention this week, the focus will also shift to a slew of inflation releases out of the US, Europe and Japan on Friday, while Nvidia’s earnings on Wednesday will be all-important after tech stocks slumped prior to Friday’s rally.

Powell’s Jackson Hole speech saw a couple of notable shifts compared to his last FOMC press conference in late July. First, the Fed Chair emphasized that “the balance of risks appears to be shifting”, with the unusual situation in the labour market suggesting that “downside risks to employment” are rising. Second, on the policy outlook, Powell noted “with policy in restrictive territory, the baseline outlook and the shifting balance of risks may warrant adjusting our policy stance”. Put together, this suggests that Powell no longer sees a further weakening of labour market data as necessary to ease policy.

While Powell made no explicit commitment on timing, market pricing of a Fed rate cut next month rose from 72% to 81% by Friday’s close and up to 86% this morning, while the amount of cuts priced in by December rose by +6.7bps to 54bps. Following Powell’s comments, our US economists now expect a 25bps cut next month, with further 25bps cuts in December and March, bringing the Fed funds rate to their longer-run estimate of neutral. You can read their full reaction here.

Markets responded euphorically to Powell’s speech, reversing the pessimistic mood that dominated much of last week (see weekly recap at the end). Treasuries rallied with the 2yr yield falling by -9.7bps and the 10yr by -7.4bps on Friday. The S&P 500 (+1.52%) had its best day since May, closing less than 0.1% from its August 14 record high. The NASDAQ (+1.88%) and the Magnificent 7 (+2.51%) saw even larger advances and the small cap Russell 2000 surged by 3.86% in its best day since April 9 when Trump delayed his Liberation Day tariffs. Other risks assets also gained, with US HY credit spreads -8bps lower and the VIX volatility index (-2.38pts to 14.22) falling to its lowest level year-to-date. Those reactions were consistent with the historical pattern that rate cuts outside recessions tend to be very positive for risk assets.

Looking ahead, central bank commentary will continue to garner attention this week with the Fed’s Logan (non-voter), Williams, Barkin (non-voter) and Waller due to speak. Divisions among the FOMC are likely to remain evident, and we would expect Logan today to sound more hawkish than Powell on near-term cuts, but Waller on Thursday to lean into the dovish elements of Powell’s speech. The topic of Fed independence will also remain salient with Trump saying last Friday that he would fire Fed Governor Lisa Cook if she did not resign. As a reminder, the controversy emerged last Wednesday as FHFA Direct Bill Pulte alleged that Governor Cook may have committed mortgage fraud. Were Cook to leave her post, it would open another seat for Trump to fill, increasing the prospects of a dovish majority on the seven-person Fed Board.

In Europe, the ECB will release the accounts of its July meeting on Thursday, which come as ECB commentary at Jackson Hole was consistent with an extended pause. President Lagarde avoided discussing the policy outlook but highlighted the resilience of the euro area labour market. Germany’s Nagel argued that the bar for further cuts was high with few arguments for more easing and Finland’s Rehn said that, as “inflation is for now in a good place”, an “insurance cut” was not necessary.

On the data front, inflation will be in focus in both sides of the Atlantic on Friday. In the US, our economists expect the July core PCE deflator to come in at +0.29% MoM (vs. +0.26% previous), bringing the YoY rate a tenth higher to 2.9%, with risks of this even rounding up to 3.0%. They also foresee the accompanying personal income (DBe: +0.4% vs. +0.3% previous) and consumption (+0.6% vs. +0.3%) releases showing solid growth. In Europe, the flash August CPI print for Germany, France, Italy and Spain are due, with our economists expecting annual inflation to edge up slightly across the Big 3 euro area economies (see here for more). And in Japan, we will have the August Tokyo CPI on Friday, with our Japan economist expecting a retreat in core inflation ex. fresh food to 2.5% YoY (2.9% in July).

Ahead of that, other notable US economic releases include new home sales (Mon), the Conference Board’s consumer confidence indicator and durable goods orders (both Tue). In Europe, we also have the Ifo survey in Germany (Mon), euro area M3 and credit data for July (Thu) and the ECB’s consumer expectations survey (Fri). The full week ahead calendar is at the end as usual.

Rounding out US events, in tariffs, the “de minimis” exemption will end this Friday, while additional 25% tariffs on India (taking the total levy to 50%) are due to come into effect on Wednesday. On tariff news, last Friday Canada announced that it will remove its retaliatory tariffs on US products that comply with the USMCA, though it will keep symmetrical tariffs on US steel, aluminium and autos.

Finally, the big event in corporate earnings will be Nvidia’s results on Wednesday, which come as tech stocks had seen their biggest five-day pullback since April prior to Friday’s rally. Other US tech earnings due include Crowdstrike, Dell and Marvell. In China, the spotlight will be on results from Alibaba, Meituan and BYD. In tech news last Friday Trump announced a deal that will see the US receive 9.9% of Intel’s shares funded by $8.9bn of government grants that have not yet been paid to the company. Intel’s stock rose by +5.53% on the news.

This morning Asian equity markets are building on Friday’s rally on Wall Street. Across the region, Chinese stocks are leading the way, with the Hang Seng up +2.09%, followed by the CSI (+1.39%) and the Shanghai Composite (+0.86%), with the latter on course to reach a 10-year high. The KOSPI (+1.01%), the Nikkei (+0.68%) and the S&P/ASX 200 (+0.33%) are also all advancing. However, US equity futures on both the S&P 500 (-0.09%) and the NASDAQ (-0.10%) are marginally lower, with 10yr Treasuries (+1.3bps to 4.27%) also slightly softer after Friday’s rally.

In the bond space, 10yr JGB yields (-0.7bps to 1.62%) are a touch lower after reaching a post-2008 high on Friday, even as Governor Kazuo Ueda’s remarks at Jackson Hole reinforced market expectations that the central bank may resume its rate hiking cycle later this year given accelerating wage growth.

Recapping last week’s moves in more detail, markets had underperformed prior to Friday, with Friday’s spike leaving the S&P 500 narrowly higher over the week (+0.27%), while the Nasdaq (-0.58% on the week) and the Magnificent 7 (-1.02%) were unable to recoup their losses. Treasury yields had been trading a little higher as last Thursday’s stronger-than-expected US August flash PMIs saw the manufacturing PMI rebound to its highest level since May 2022 and the composite output price index rise to its highest in three years. But Friday’s rally meant that yields were lower over the week, with the 10yr yield down -6.4bps (-7.4bps Friday) and the 2yr down -5.5bps (-9.7bps Friday).

The Euro area and the UK also saw robust August PMI releases and European stocks were more universally positive. The STOXX 600 rose +1.40% (+0.40% on Friday) led by the FTSE 100, which rose +2.00% in its biggest weekly jump since May to reach a new record high. European bonds rallied, with yields on 10yr bunds down -6.7bps to 2.72% (-3.6bps Friday), while gilts (-0.3bps on the week, -3.6bps Friday) saw a marginal decline.

Earlier last week, European markets had benefited from increased optimism on talks over Russia-Ukraine, but these faded as Russian officials ruled out any immediate meeting between President Putin and President Zelenskiy. On Friday, Trump said that depending on events “over the next two weeks” he would make a decision “whether or not” to target Russia with “massive sanctions or massive tariffs or both”. With prospects of new US restrictions on Russian oil still in play, Brent crude rose +2.85% on the week to $67.73/bbl (+0.09% Friday).

Tyler Durden
Mon, 08/25/2025 – 08:35

Orsted Shares Crash To Record Lows After Trump Halts Rhode Island Offshore Wind Project

0
Orsted Shares Crash To Record Lows After Trump Halts Rhode Island Offshore Wind Project

Shares of Danish wind giant Orsted A/S crashed as much as 19% – to record lows – after the Trump administration ordered construction halted on the 80%-completed Revolution Wind offshore project off Rhode Island last Friday, citing unresolved national security concerns under federal review. The struggling wind company still plans to move forward with a $9.4 billion share sale to strengthen its capital structure.

The Interior Department’s Bureau of Ocean Energy Management (BOEM) issued a directive on Friday ordering Orsted to halt all offshore construction activities on the Revolution Wind project. The order stems from a Presidential Memorandum issued on Jan. 20, which triggered a broad review of renewable projects on the Outer Continental Shelf.

Two items the BOEM wants to address: 

  • Environmental protections
  • National security concerns (e.g., interference with U.S. defense/naval activity in the exclusive economic zone, high seas, territorial seas).

“In particular, BOEM is seeking to address concerns related to the protection of national security interests of the United States and prevention of interference with reasonable uses of the exclusive economic zone, the high seas, and the territorial seas, as described in that subsection of OCSLA. Id,” stated BOEM’s letter addressed to Rob Keiser, head of Orsted North America. 

The $5 billion wind project, already 80% complete with 45 of 65 turbines installed, was approved under the Biden-Harris regime in 2023, during the time the Democratic Party looted the nation under the guise of a ‘climate crisis’ to funnel hundreds of billions of dollars into green companies and NGOs. This, in effect, helped spark generational-high inflation, crippling working-poor and middle-class households. Several of these projects have already collapsed, and we anticipate more Solyndra-style busts ahead as the green bubble continues to implode.

Orsted told Bloomberg that it’s exploring regulatory channels and possible legal action to resolve the matter: “Orsted is evaluating all options to resolve the matter expeditiously. This includes engagement with relevant permitting agencies for any necessary clarification or resolution as well as through potential legal proceedings.”

Bloomberg reports Ortsed is still moving ahead with a $9.4 billion share sale and appointed a syndicate of BNP Paribas, Danske Bank, and J.P. Morgan as joint global coordinators, alongside Morgan Stanley. BofA Securities Europe SA and Goldman Sachs will serve as joint bookrunners. 

Here are more details about the planned share sale that will help stabilize the balance sheet of the struggling wind company:

  • Orsted is pushing ahead with a planned 60 billion DKK ($9.4B) rights issue, the largest European energy-sector share sale in over a decade.

  • The Danish government has pledged to buy about half the shares.

  • Orsted’s credit rating has already been slashed to the lowest investment grade.

  • Orsted has already canceled two U.S. projects, booked heavy writedowns, and changed out its top executives.

This month, Orsted shares in Denmark have been in turmoil:

However, good news for the industry last week on new IRS guidance:

Related:

Orsted crashed as much as 19% in Copenhagen, falling to record lows below its IPO price.

Commentary from a team of Goldman analysts led by Alberto Gandolfi provides clients with the economics of Orsted walking away from Revolution and another offshore wind project, Sunrise:

What are the economics of walking away from both projects? To run this math, we look at three building blocks: (1) walking away from Revolution and Sunrise would save Orsted DKK 45 bn in residual capex, (2) the company would lose around DKK 3 bn EBITDA for a period of c.25 years, and (3) Orsted may face cancellation fees: based on Ocean Wind 1 (DKK 10 bn, based on 2023 accounts), cancellation fees on these two projects could be DKK 10-15 bn.

Can Orsted downsize or delay the rights issue? Based on the math just presented, we estimate that walking away from both US projects would require a smaller rights issue: we estimate DKK 30 bn, half of what was recently announced. To reach our conclusion, we assume that Orsted would have to comply with its target FFO/Net debt “above 30%”. We also estimate that this move – i.e., walking away from projects, paying penalties and downsizing the equity issuance – would be EPS accretive (double digit) in 2025-27, EPS neutral in 2028, but it would then start to be increasingly EPS dilutive as of 2029-30; this scenario wouldn’t meaningfully change our current valuation for the stock. We also note that Orsted would still have to carry out the targeted DKK 35 bn disposals by the end of 2026, to avoid any B/S pressure.

Gandolfi is “Neutral” wated on Orsted with a 12-month price target of DKK 235. 

. . . 

Tyler Durden
Mon, 08/25/2025 – 07:20

Why Are More And More Americans Becoming Disabled?

0
Why Are More And More Americans Becoming Disabled?

Bureau of Labor Statistics data reveals 1.1 million MORE Americans have become disabled in just the past 3 months.

VigilantFox asks: Why is nobody talking about this?

The month of July added another 234,000 disabled Americans, making the current high the third new high in a row.

Prominent data analyst @DowdEdward reports that since February 2021, an additional 5.89 million Americans have answered “yes” to the Bureau of Labor Statistics household survey question on disability.

That’s a 19.6% increase in reported disabilities over just 4.5 years—something he calls a “disaster.”

This should be front-page news.

Why isn’t anyone talking about it?

Tyler Durden
Mon, 08/25/2025 – 06:55

Stablecoins In An Unstable System

0
Stablecoins In An Unstable System

By Christian Lawrence, head of cross-asset strategy at Rabobank

Summary

  • The post-WW2 and Cold War global architecture is crumbling; systemic geopolitical and geoeconomic instability is rising; so are risks of geo-financial instability as fiscal deficits grow, public debt rises, and hopes for rate cuts meet sticky inflation.
  • Against this backdrop, stablecoins may play a pivotal role – though ironically they are likely to create further instability before cementing an alternative.
  • This report will explain what stablecoins are; why people may want to use them; why the US government certainly wants us to use them; and the hypothetical geopolitical and market implications of their roll out.

What are stablecoins?

Stablecoins have risen from a niche crypto product to front of mind for the US government, geopolitical analysts, economists, and market participants alike. What was initially viewed as an easier way to handle crypto risk on the blockchain is now seen as a potentially crucial variable in US debt management, USD reserve currency status, and global payment and trading systems.

Stablecoins are digital assets designed to replicate fiat currencies (Fiat money is government-issued monetary not backed by a physical asset), but we can break them down into the following subsets: commodity-collateralized, algorithmic, crypto-collateralised, and fiat-collateralised. The first three are still niche markets, while the latter is our main focus given it accounts for the overwhelming market share today and, more so, going forward.

Fiat-collateralised stablecoins are issued on the blockchain backed by a pool of fiat collateral held by a custodian. The current market cap is around $234bn and, according to the US Treasury Borrowing Advisory Committee (TBAC) report from April 30, more than 99% of fiat stablecoins are USD-pegged. Of the $233bn in USD-denominated stablecoins, more than $120bn is backed by US Treasury bills (The rest are collateralised by cash and bank deposits, reverse repo (often backed by US-Treasuries), corporate bonds, gold, Bitcoin, and other crypto assets). In short, this is all about the US.

The dominant USD stablecoin is Tether, with a market capitalization of $163BN. Cantor Fitzgerald, a US Treasury primary dealer previously run by Howard Lutnick (now Secretary of Commerce) is the primary manager of Tether’s collateral. In short, this is all about the US government.

Indeed, President Trump’s recent GENIUS Act (Guiding and Establishing National Innovation for US Stablecoins) requires the use of solely US assets such as T-bills, repo, reverse repo, MMFs, or bank reserves and aims to protect consumers in the digital market; ensure USD global reserve currency status; combat illicit activity in digital assets; and make the US the crypto capital of the world. To do so it will create a federal regulatory system for stablecoins 100% backed by US dollars or short term US debt (T-Bills), whose reserve composition must be reported publicly on a monthly basis (One could argue there are a few stablecoin-adjacent assets. One is Central Bank Digital Currencies (CBDC), state-issued tokens considered legal tender – digitised fiat. Another is tokenized deposits, bank-issued digital tokens on the blockchain representing a fiat deposit).

Why would people want stablecoin?

Security: stablecoins allow buying or selling of crypto without using an on- or off-ramp like a centralized exchange (CEX) with Know-Your-Client requirements. As crypto is not covered by Federal Deposit Insurance Corporation (FDIC) insurance, using centralized exchanges leaves one vulnerable to the counterparty risk of said exchange. Some centralised exchanges are FDIC insured, but only for fiat holdings, not crypto holdings, so counterparty risk exists during the period that crypto sits in the CEX before it is exchanged for fiat. If one remains on the blockchain using stablecoins these can be kept in the holder’s own personal secure ‘wallet’4 that is not subject to counterparty risk.

Anonymity: selling crypto for stablecoin allows anonymity outside of the wallet address. With the blockchain, every transaction is visible by everyone, but the only information that can be seen beyond the transaction itself is the destination and origin wallet address. Who owns that wallet is unknown unless they use an on- or off-ramp that would reveal the wallet owners identity to the on-/off-ramp company, or if the wallet holder decides to reveal their identity publicly. In short, crypto without stablecoins involves moving into fiat which destroys the user’s anonymity.

Parsimony: stablecoins offer a quick way to transfer money at cheaper rates than fiat equivalents, particularly cross-border – and while avoiding SWIFT-system restrictions like sanctions.

Practicality: stablecoins can be exchanged for goods and services. For now that typically occurs online, but there are also growing stablecoin payment systems in shops. Most major US credit card companies also now support stablecoin transactions.

Prosperity: stablecoins cannot be interest-bearing instruments but can be deposited with third party institutions and receive payment/yield for doing so: in short stablecoin Money Market Funds (MMF) are possible, and indeed likely.

Why does the US want stablecoins? Debt

The US –like many Western economies– has a public debt problem. The Congressional Budget Office (CBO) estimates debt-to-GDP, at a post-WW2 level in a pre-war geopolitical environment, is on track to reach 156% by mid-century. Many view this as unsustainable and incompatible with the sustained reserve status of the US dollar, if not the stability of the US economy (Figure 1).

To avoid seeing longer-term borrowing costs rise significantly, the US Treasury has in recent years switched to issuing an increasing share of debt at the very short end of the curve, a tactic that is traditionally seen in emerging markets, not global financial hegemons. Indeed, part of the rationale to front-load issuance may be fears over slowing foreign demand for long duration US debt. We are not in the camp that thinks foreigners are ‘dumping’ US assets due to a loss of faith in its institutions and the rule of law, but policy uncertainty could be creating some indigestion for longer duration assets from private institutions. One could argue this is also partly reflected in the rise in term premium at the long end of the curve (Figure 2): it is the potential rise in yields from this perspective that the Treasury wants to avoid.

Notably, as stablecoins must be backed 100%, increased demand for the former will create forced buyers of the latter. In short, the US is incentivized to encourage the usage of stablecoins to soak up increased T-Bill supply.

There is debate about whether or not stablecoins will result in an increase in the money supply. The Treasury states stablecoins “Potentially generate no net change to the US money supply, but catalyze a potential shift of funds away from M1/M2. Stablecoins may gain momentum as a store of value and way to access USD for non-USD holders – in turn, increasing inflows to the US money supply.” We argue the clearer dynamic is a change in ‘moneyness’. Essentially, USD stablecoins convert US debt like T-Bills/Repo (narrow inside money) into spendable cash (outside money). Holders might not be able to buy goods and services with a T-Bill, but they can with a stablecoin.

This raises immediate questions about how the Fed might view USD stablecoins. Would it be concerned about the money-supply impact as inflationary? Would it also look at the potential impact on the yield curve and its own balance sheet? Moreover, would it worry about future financial instability risks if a broader range of US collateral were gradually used beyond TBills?

How an independent central bank sits alongside a much more clearly Treasury-driven money supply remains to be seen – it is certainly something that the next Fed Chair, whomever that may be, will have to consider as part of their remit.

Figure 4 shows projected T-Bill issuance going forwards along with projected demand for USD stablecoins, which is estimated to hit $2 trillion in 2028. Note the debt path for T-Bills uses the CBO’s 2025 baseline trajectory with the assumption that the rise in the share of T-bills grows from 21% to 25%

Why does the US want stablecoins? The US dollar

While issuing more short-term debt in high-debt economies is often associated with a weakening currency over time, USD stablecoins reinforce the US dollar’s global reserve FX status. Markets have been questioning this in the face of US deficits and debt, its aggressive sanctions on Russia, its retreat from the global economic and financial architecture it built, and rivalry within the current global system from Europe/the euro, and from the BRICS economies pushing non-SWIFT CNY, ‘BRICScoin’, or gold alternatives (Figures 5-8). Note we have written on before and remain sceptical of purported dollar replacements, but dollar avoidance is certainly taking place via de facto barter, with goods priced in dollar not used.

There is also a potential geopolitical angle. While we are unaware of any stablecoins that are currently designed in this manner, the smart contract code that ‘mints’ a stablecoin is programmable and editable by the owner. If a wallet is identified as being from a certain jurisdiction or deemed ‘undesirable’ then, if designed as such, it would technically be possible to prevent said stablecoin from being sent to another wallet, or to lock stablecoins held by it. In that respect, stablecoins could potentially be less fungible than physical fiat and offer more government oversight. While the potential programmability of USD stablecoins would make stablecoins designed that way officially unwelcome in jurisdictions with which the US has geopolitical tensions (such as China and Russia, for example), that wouldn’t mean they wouldn’t be popular unofficially, via a hard-to-control black market.

However, the primary logic is that USD stablecoins would be designed mostly for use by US allies as we head towards greater global bifurcation. There, via online platforms, private sector uptake may be seen for all the reasons already listed – plus FX diversification. While this means exchange rate risk for the holder (which in many emerging markets is seen as mostly unidirectional, even if the dollar is well down vs EUR, JPY, CHF, etc. in 2025), the ability to anonymously hold de facto US dollar MMFs, and to cheaply and easily remit and transact in them, could quickly cement USD stablecoins in many places. That’s true even in developed markets.

Indeed, recent trade negotiations, which ringfenced the US with tariffs, also show America has the ability to force others to accept terms they do not like. This could soon include payment for exports to it only in stablecoins, not dollars, or at least a portion of them, which would spread their international usage further.

Moreover, the US could lean on Saudi Arabia, the UAE, and Qatar –the source of much of Europe’s LNG, for example – to insist on payment for their energy in USD stablecoins: that would mean everyone who buys energy – except those who buy from the likes of Russia or Iran, etc. – needing to hold them.

Hypothetically, over time trade finance/trade could even start to involve –or revolve round– the Treasury not the private sector and the banking system: in the extreme, T-Bills would be akin to US export quotas of a sort.

Such neo-mercantilist economic statecraft may sound inconceivable to those accustomed to US/global free trade, it fits comfortably with a White House already embracing tariffs, making Nvidia pay a 15% fee to sell its AI chips to China (potentially extending that model to other firms too), and maybe taking a direct stake in chipmaker Intel, as the Pentagon takes a 40% stake in a US rare earths firm.

Indeed, USD stablecoins could work alongside the existing Eurodollar system of offshore fiat dollars ($120trn by some estimates), which is already a source of US financial power. Yet from now on, the creation of USD stablecoins, unlike Eurodollars, would necessitate the matching issuance of a US T-Bill, funding the US government, while the US could retain de facto control of who handled them even more than it does via SWIFT and sanctions.

In theory, this implies the need for an ever-growing amount of T-Bills for the US to allow USD stablecoin-based trade to expand, just as with the current Eurodollar system – the ‘Triffin Dilemma’. Failing that, they could become akin to a deflationary gold standard (and/or trade access to the US is necessarily de facto limited).

However, USD stablecoins can also be backed by USD repo, reverse repo, or bank reserves (even if the broader the range of assets involved the greater the potential risks of worrying financial instability become over time). That could be one solution. Yet the US doesn’t want to repeat past Triffin errors which it sees as having helped deindustrialise it: as such, hypothetically, USD stablecoins may gradually allow a separate ‘track’ to the broader fiat Eurodollar market just for trade. If so, any Triffin ‘bottlenecks’ may therefore be deliberate.

Why does the US want stablecoins? Geopolitics

It’s not an act of genius to see how USD stablecoins could benefit the US geopolitically and geoeconomically if one thinks outside the “because markets” box.

The White House is trying to remake the global system to its benefit, as it did in 1945 and after the Bretton Woods system collapsed in the 1970s. However, this time the US wants to ensure it centers around state-guided US reindustrialisation not private sector-guided US financialization to ensure its global military primacy: on the status quo trend that assumption is questioned by many.

Crucially, while the BRICS are financial minnows compared to the US, they are an industrial and resource Goliath; China outproduces the US on all fronts (Figures 9 and 10), and its control of rare earths already sees it choking supply to western military industrial supply chains. The US, for the first time in centuries, finds itself the weaker economic party. Hence, something must change.

Every economy which the US can subsume into its own value chain, not China’s, and which it can arm-twist to help it reindustrialise via running much smaller bilateral trade deficits and pledged manufacturing FDI, is an extra stone in its slingshot. Moreover, many formerly US-leaning countries are refusing to make a choice between the two embryonic emerging blocs – that of the US and China – and may need ‘encouragement’.

USD stablecoins could clearly help forge a new US-centric system –with fewer US trade imbalances and more industry – vs that of China/Russia/BRICS.

The ‘Global Euro Moment’… of realization

This risk is now recognized in Europe, for one.

On 17 June, ECB President Lagarde spoke of a “Global Euro moment”5 as markets looked for potential alternatives to the US dollar; yet by 12 August, Politico reported this bubble was bursting due to fears of USD stablecoin penetration into Europe.

Indeed, a recent ECB blog titled “From hype to hazard: what stablecoins mean for Europe” argues, “Should US dollar stablecoins become widely used in the euro area – whether for payments, savings, or settlement – the ECB’s control over monetary conditions could be weakened. This encroachment, though gradual, could echo patterns observed in dollarised economies… such dynamics would be difficult to reverse given the network character of stablecoins and the economies of scale in this context. The larger their footprint, the harder these would be to unwind…. Such dominance of the US dollar would provide the US with strategic and economic advantages, allowing it to finance its debt more cheaply while exerting global influence.”

Of course, individual Europeans may not opt to use USD stablecoins given the efficiency of the Euro at home: but the tail risks above are exactly what the US is trying to achieve.

What is to be done? Not a lot

What could Europe, or others, do to stop the above scenario happening? Honestly, very little.

  • Europe said it wouldn’t spend 5% of GDP on NATO: with one or two exceptions, it is.
  • Europe said it wouldn’t strike an unfair trade deal with the US: it did.
  • Europe appears to have been handed the bill, and front-line responsibility, for policing a ceasefire/peace deal between Russia and Ukraine; or the loss of its security order.

In short, if Europe — or others — try to block USD stablecoins operating as floated above it would risk reopening wounds on NATO, trade, Ukraine, energy flows, and/or the Eurodollar/Fed swap lines, etc. The latter not today, but perhaps under new management (Of course, these facilities are often in the US’s own interests in order to prevent financial instability that can also impact on it).

Additionally, if Europe wants its own stablecoins it doesn’t have the scale of collateral to match the US given the lack of Eurobonds (This is true for T-Bill equivalents but Europe obviously has many other assets it could collateralise: however, the advantages to be gleaned from doing so relative to the US remain questionable), and using Bunds would place further power in the hands of German fiscal policy. Meanwhile, a fragmented private-sector approach is unlikely to be welcomed by the ECB due to financial stability risks.

That leaves the digital Euro. Yet in January, President Trump issued an executive order stating, “Except to the extent required by law, agencies are hereby prohibited from undertaking any action to establish, issue, or promote CBDCs within the jurisdiction of the US or abroad.” That might create huge problems for European banks also using dollars.
Obviously, smaller global economies are even less well placed to contemplate issuing their own stablecoins to any positive effect.

Of course, neither China nor Russia will want to cooperate with USD stablecoins. Indeed, China is now talking about introducing its own stablecoins. Both USD and CNY versions would accelerate the ongoing process of global bifurcation already underway.

$tablecoins in an un$table $ystem

In conclusion, if introduced as we hypothesise, USD stablecoins may strengthen the US fiscal position and the global role of the US dollar. However, they are ironically likely to accelerate global geopolitical and geoeconomic instability in the short term: least so if US allies adopt them willing; most so if they resist aggressively.

Additionally, while not covered here, some fear that if USD stablecoins are introduced in a less mercantilist and more deregulated ‘Wild West’ fashion re: the USD collateral backing them, they could also increase US and global financial instability – though the GENIUS Act strongly suggests it is the mercantilist angle that matters most for now.

Even in the most benign scenario, USD stablecoins will still risk a less stable world at first as it is split more deeply between geopolitical, and currency, blocs, before perhaps finding a new stable geoeconomic status quo emerges.

That said, it’s very important to note that the current global system is already unstable. The massive trade imbalances and fiscal deficits run for years by many economies are widely accepted not to be sustainable – yet none of our global institutions appear capable of providing a guide or glide path towards a healthier economic equilibrium, let alone a geopolitical one.

As $uch, we $ee the entry of $tablecoins into an un$table $ystem.

Also available in pdf to professional subscribers.

Tyler Durden
Mon, 08/25/2025 – 06:30

These Are The World’s Most Powerful Cars

0
These Are The World’s Most Powerful Cars

From hybrid hypercars to high-output EVs, the amount of horsepower that today’s cars can generate is truly impressive.

In this infographic, Visual Capitalist’s Marcus Lu ranks the 20 most powerful cars of 2025, spanning gasoline, hybrid, and fully electric powertrains.

Data & Discussion

The data for this ranking comes from Motor1. It details the horsepower, pricing, and origins of the most extreme production vehicles available in 2025.

While price tags often run into the millions, some surprising entries challenge the notion that power always comes with exclusivity.

Koenigsegg and Sweden’s Role in Hypercar Engineering

Koenigsegg remains a standout in this ranking as the only Swedish manufacturer on the list. Its flagship Gemera produces 2,300 hp, not only topping the global leaderboard but also defying convention by being a four-seater hybrid.

While the standard Gemera pairs a 3-cylinder twin-turbo engine with three electric motors for 1,700 hp, the upgraded 2,300 hp version utilizes a V8 engine and a single electric motor.

Sweden’s engineering reputation has traditionally leaned toward safety and practicality, but Koenigsegg has carved out a unique niche in the hypercar market. All of its cars are highly exclusive and cost upwards of $1 million.

Big EV Power from Accessible Brands

Electric vehicles are present throughout this ranking, with models from Tesla, Rivian, and Lucid appearing alongside million-dollar hypercars.

The Tesla Model S Plaid and Rivian R1T Quad Motor both cross the 1,000-horsepower threshold while staying somewhat closer to consumer budgets (The R1T Quad is expected to start at $115,990).

If you enjoyed today’s post, check out America’s Favorite Car Brand by Generation on Voronoi, the new app from Visual Capitalist.

Tyler Durden
Mon, 08/25/2025 – 05:45

Myanmar Is Shaping Up To Be The Next Front Of The Sino-US New Cold War

0
Myanmar Is Shaping Up To Be The Next Front Of The Sino-US New Cold War

Authored by Andrew Korybko via Substack,

China wants to retain access to Kachin State’s rare earths, the US wants to poach them, and their escalating competition over this part of Myanmar could make it the next New Cold War flashpoint.

Reuters reported that the US’ Myanmar policy might shift towards more diplomatic engagement with either the ruling junta or the Kachin Independence Army (KIA) in an attempt to obtain access to the enormous rare earth mineral reserves in the second’s eponymous state. At present, the US is suspected of clandestinely supporting some of the armed anti-junta groups, but the KIA isn’t thought to have benefited due to their isolated position along Myanmar’s mountainous border with China and India.

This geography poses a challenge to the redirection of these resources from China to India for example regardless of Kachin State’s final political status, whether autonomous within a (con)federated Myanmar or independent, but that’s assuming that China doesn’t intervene. Reuters cited an expert on Kachin State who said that “If they want to transport the rare earths from these mines, which are all on the Chinese border, to India, there’s only one road. And the Chinese would certainly step in and stop it.”

The reports late last year about the joint security firm that China and Myanmar were planning at the time were analyzed here and concluded that the risks associated with even a PMC-led intervention in support of the China-Myanmar Economic Corridor (CMEC) make this scenario unlikely. For as important as CMEC is for helping China reduce its logistical dependence on the easily blockaded Strait of Malacca, Kachin’s rare earth minerals are even more important, so its calculations could change.

Nevertheless, China is known for advancing its national interests through hybrid economic-diplomatic means, not military force. It’s therefore much more probable that it might soon ramp up these efforts with either the junta, the KIA, or both to preempt any forthcoming US diplomatic campaign. The first scenario would aim to restore the military’s control over Kachin’s rare earth reserves, the second would work towards Kachin’s de facto independence, while the third would seek that state’s autonomy.

In the order that they were mentioned: the military is on the backfoot in Kachin despite over four years of Chinese support so it’s unlikely that any new approach by China will reverse this trend; China’s decades of engagement with eastern Shan State’s de facto independent United Wa State Army (including over rare earths) could serve as a precedent for something similar with the KIA; while seeking Kachin’s autonomy in a Chinese-mediated political settlement would be the best-case scenario for Beijing.

In any case, it’s unimaginable that China will let the US poach Kachin’s rare earth reserves without making any attempt to preempt this powerplay, so the Sino-US rivalry in Myanmar is expected to intensify. Kachin is at the center of this struggle, which his nowadays driven by access to that region’s rare earths even though it used to be about CMEC, with Myanmar’s political future (centralized, decentralized, devolved, or partitioned) only being a means to the aforementioned end.

China has the edge over the US due to geography (including the nearness of its rare earth processing facilities), its existing ties with both the junta and the KIA, and the allure that any new approach (possibly linked to CMEC) could have for facilitating a pragmatic deal between them. That said, the US might at the very least try to provoke an armed Chinese intervention of some sort to embroil it in a quagmire even if the odds of this scenario are low, all as part of their escalating New Cold War rivalry over Myanmar.

Tyler Durden
Mon, 08/25/2025 – 05:00

American Knifed In Face By Syrian After Intervening To Protect Women On German Train

0
American Knifed In Face By Syrian After Intervening To Protect Women On German Train

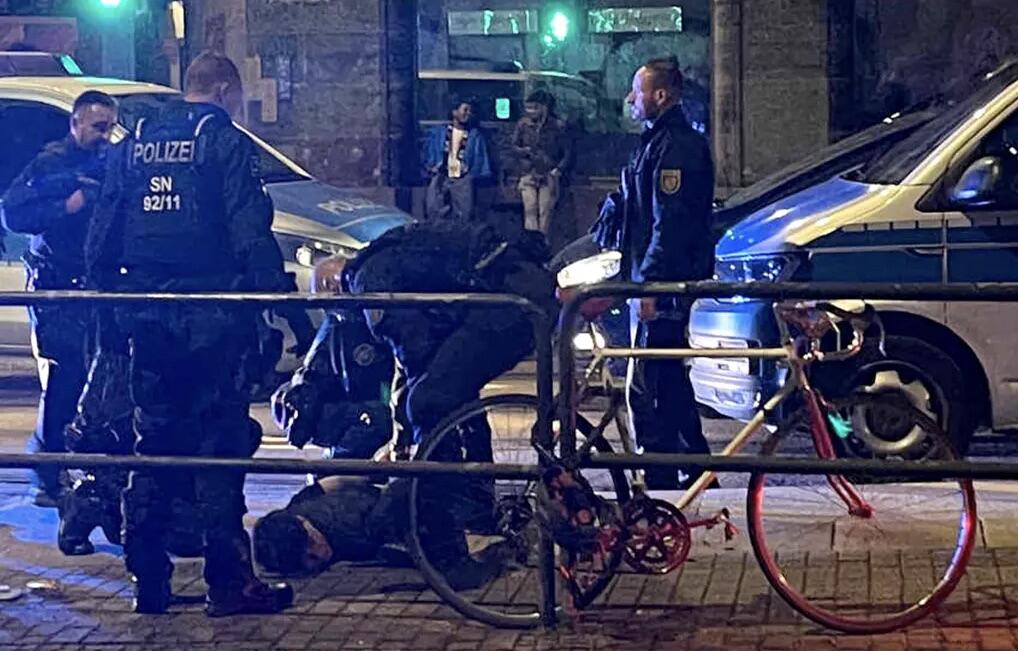
A 21-year-old American man paid a steep price for doing the right thing on a tram in Germany overnight. When he observed two Syrian men hassling a pair of female passengers, the as-yet unnamed American intervened, only to be beaten and slashed in the face with a knife. One of the assailants was arrested, but then immediately let go. 

A tram in Germany was showered with the blood of a young American who intervened to protect women from harassment(xcitepress/florian varga via New York Post)

“This is the consequence of Merkel’s open-border policy,” said Alternative for Germany EU parliament member Petr Bystron on X.  “Attacks like this happen in Germany every single day. Now it has affected a courageous American. We must work together with @realDonaldTrump to put an end to this madness.”

According to a statement from Saxony police, the violence erupted at around 12:25am Sunday on a tram in Dresden, while it was at the Neustädter Markt stop. When two men that were part of a larger group started harassing female passengers, the American citizen stepped in to protect them. One of the villains stabbed the Good Samaritan and both of them ran off. Police quickly captured one of them — a 21-year-old Syrian national — at another tram stop less than a half-mile away. 

Despite the fact that he has a criminal record that includes robbery and dangerous bodily harm, the suspect was quickly set loose. He enjoys permanent residency status in Germany. “He was provisionally arrested and has been released by decision of the public prosecutor’s office,” a police spokesman told Bild. Authorities said that decision sprang from the fact that they couldn’t substantiate that the attacker — identified only as “Majid A” — was the one who wielded a knife. “According to the on-call public prosecutor’s assessment, there were insufficient grounds for detention. The knife attack cannot be attributed to him,” senior public prosecutor Jurgen Schmidt told Bild. Police are reviewing security camera footage and seeking public assistance in tracking down the other suspect. 

German police quickly arrested a Syrian national, but then a prosecutor ordered him to be released (xcitepress/florian varga via New York Post)

The American was transported by ambulance to a hospital, with his wound described as serious but not life-threatening. A video is circulating on social media which purports to show the young American hero — bloodied and bandaged — speaking to the camera about the incident. “If y’all didn’t think that Europe had an immigration problem, especially Germany, let me drop some knowledge on you,” he says, condemning authorities for letting one of the assailants go so quickly. At this point, ZeroHedge is unable to confirm the video’s authenticity.  

Non-Germans account for 59% of sex crimes aboard German trains and at train stations, and sex violence in general doubled between 2019 and 2024. In particular, Syrians have established a reputation for violence in their host country. A recent analysis of official statistics by the German paper Die Welt showed that 40% of the perpetrators of violence in German schools in 2024 were foreign national, with Syrians leading the way. Syrians were involved in 10% of all school incidents, well ahead of the second-place Afghans who finished at 3.6%. Germany suffered 79 knife crimes a day in 2024, according to a German police union official, with Berlin enduring nearly 10 a day. 

It’s little wonder that support for the anti-mass-immigration Alternative for Germany party is steadily rising — with a poll this month showing it is now the most popular party in the country. A stout 26% of Germans said it’s their top choice in the next election.

Tyler Durden
Mon, 08/25/2025 – 04:15

EU’s Deforestation Crusade: Brussels Expands Green Deal Control

0
EU’s Deforestation Crusade: Brussels Expands Green Deal Control

By Thomas Kolbe

The European Union’s regulatory frenzy is taking on manic dimensions. Starting in 2026, a new regulation aimed at “protecting global forests” will further expand Brussels’ bureaucratic jungle. Another job creation scheme for the swelling EU apparatus.

For German taxpayers, the last 18 months have been an expensive ride. Higher property taxes, a raised top income tax rate, the rollback of VAT cuts for hospitality, and CO₂ surcharges all piled on. Brussels added its own bite: higher excise duties on tobacco and energy, a greater EU share of CO₂ revenues (its most effective cash cow yet), and a stack of new compliance burdens for chemicals and sustainability reporting.

Euro-Evangelists

This list is far from exhaustive. It merely illustrates the sheer workload Brussels and Berlin bureaucrats take on in their mission to morally domesticate their still far-too-frivolous citizens.

According to EU brochures and staged “citizen surveys,” the Eurocrats are building a better world: clean seas, clear skies, and “inclusive” working conditions everywhere. With the right indulgence payment – i.e. a cleverly engineered Brussels levy – any sin can be erased. Perhaps Ursula von der Leyen’s crew should be viewed less as regulators and more as a pastoral society of Euro-Evangelists. That way, it all might make sense one day.

Brussels vs. Beef, Coffee, and Rubber

The next crusade begins soon. In January, the European Union Deforestation Regulation (EUDR) kicks in. In essence, imports of beef, soy, palm oil, timber, coffee, cocoa, natural rubber – and all products derived from them – will be restricted to “deforestation-free” areas.

The burden of proof, documentation, and costly compliance will fall entirely on European companies. Never mind that German firms are already drowning under €146 billion a year in bureaucratic costs – Brussels sees plenty of room for more experiments.

Corporate Pleas Ignored

Industry groups demanded at least limiting reporting duties to first importers. Daniel Caspary, head of the CDU/CSU group in the European Parliament, backed that idea. Brussels ignored them, as always.

The model is familiar from the Supply Chain Act: Brussels drafts a wish list of social and environmental conditions, then forces private companies to enforce them throughout global value chains. Internal chaos, spiraling compliance costs, and fresh liabilities follow. Regulators meanwhile sit back, waiting to pounce on “non-compliance” with fines.

Unlike the Supply Chain Act, which for now applies only to large firms, the EUDR will extend to all businesses operating in the EU’s single market by mid-2025. Every trader, from global giant to small distributor, must produce “deforestation-free” supply chain proofs.

The Green Deal: Hidden Trade Barrier

One wonders if this is really about forests – or about shielding EU farmers from competition. The Green Deal has already emerged as Europe’s greatest non-tariff trade weapon, one even Donald Trump couldn’t dismantle in negotiations with Brussels.

A dangerous corporatist system has taken root: European agribusiness and subsidized industries collude with regulators to suppress competitors, both domestic and foreign. Consumers pay the price via less competition and higher costs.

Ideology Over Logic

The real absurdity? Germany itself, with decades of net forest growth, will also be forced to certify its own supply chains as “deforestation-free.” Brussels will make German beef or timber producers jump through the same hoops as Brazilian ranchers torching the Amazon.

The outcome is predictable: higher prices, more bureaucracy, and yet another Green Deal brick cemented into Brussels’ growing fortress of control.

The EUDR is not environmental protection – it is power consolidation. It is part of the EU’s wider strategy to institutionalize paternalistic social engineering through regulation. And, once again, Europe’s corporate elite stands by silently, refusing to defend consumers against this regulatory madness.

* * *

About the author: Thomas Kolbe, a German graduate economist, has worked for over 25 years as a journalist and media producer for clients from various industries and business associations. As a publicist, he focuses on economic processes and observes geopolitical events from the perspective of the capital markets. His publications follow a philosophy that focuses on the individual and their right to self-determination.

Tyler Durden
Mon, 08/25/2025 – 03:30

Where Tourists Outnumber Locals

0
Where Tourists Outnumber Locals

The data for this map comes from UN Tourism. It compares the number of annual tourist arrivals with resident population, producing a “tourists per resident” measure. This ratio is a useful lens for understanding the intensity of tourism pressure on a destination.

Malta, for example, welcomes 3.56 million visitors per year, over six times its population.

Worth noting that the map, via Visual Capitalist’s Bruno Venditti, excludes the Vatican, the world’s smallest sovereign nation, which has around 800 residents but can receive over 6 million visitors per year—equivalent to roughly 7,500 tourists per resident.

Microstates Lead the Rankings

Andorra tops the list with more than 52 tourists per resident each year, followed by Macao at 24. These microstates have limited populations but high visitor appeal, from Andorra’s ski resorts to Macao’s casinos.

Country Tourist Arrivals (millions) Population (thousands) Tourists per Resident
Andorra 4.17 80 52.13
Macao SAR 16.4 680 24.12
Turks & Caicos 0.73 40 18.25
Aruba 1.42 110 12.91
British Virgin Islands 0.31 30 10.33
Cook Islands 0.17 20 8.5
Malta 3.56 520 6.85
Cayman Islands 0.44 70 6.29
N. Mariana Islands 0.23 50 4.6
Bahamas 1.87 410 4.56
Guam 0.74 170 4.35
Albania 11.29 2800 4.03
Montenegro 2.45 620 3.95
Maldives 2.05 520 3.94
Bahrain 6.62 1780 3.72
Austria 32.2 9000 3.58
Seychelles 0.35 100 3.5
Greece 35.95 10400 3.46
Cyprus 4.04 1200 3.37

Island Economies Depend on Visitors

Places like Turks and Caicos, Aruba, and the British Virgin Islands each see more than 10 tourists for every local resident. Their economies rely on hospitality, cruise arrivals, and luxury travel. This dependency, however, means global shocks—like pandemics or hurricanes—can have outsized impacts.

Tourism Pressure on Larger Nations

Even mid-sized countries like Austria and Greece see tourist ratios above 3 per resident. Albania, with 11.29 million visitors, stands out as the only large-population country in the top rankings for tourists per resident.

If you enjoyed today’s post, check out The 25 Richest Countries in the World (Depending on What’s Measured) on Voronoi, the new app from Visual Capitalist.

Tyler Durden
Mon, 08/25/2025 – 02:45

German Economy Shows No Signs Of Emerging From Recession

0
German Economy Shows No Signs Of Emerging From Recession

By Thomas Kolbe

Germany’s Mittelstand Collapses as “Investment Booster” Flops

The German economy shows no signs of emerging from recession. The monthly Mittelstand index, compiled by the consulting firm DATEV, confirms that the downturn continues unabated. The crisis has spread across virtually all sectors of the economy.

The recovery announced by the German government remains a summer fantasy. Data collected in July through DATEV’s monthly survey of small and medium-sized enterprises (SMEs) describes the economic situation as extremely fragile—with no upturn in sight. SMEs saw revenues fall by 1.7 percent year-on-year in July. The corresponding business cycle index dropped, seasonally and calendar adjusted, to 91.9 points—firmly anchored in recession territory.

No Sector Spared

Sectors traditionally dominated by the Mittelstand, such as hospitality, have been hit especially hard. Revenues in the sector fell 4 percent, while construction contracted again by 2 percent. “With the absence of a summer revival, the situation in the hospitality industry continues to deteriorate,” said Prof. Dr. Robert Mayr, CEO of DATEV eG. “Hopes now rest on a more positive August.” Hope, however, is no substitute for strategy—and no good advisor amid the worsening conditions for SMEs.

Only retail managed a slight reprieve, posting a meager 0.1 percent revenue increase. That uptick likely reflects sharply rising wages, up 4 percent. But this brings little relief. Businesses are caught in a squeeze: a deteriorating business environment on one side and rising wage costs in a broader economic setting marked by stagnating or slightly declining productivity.

Investment Drought and Capital Flight

Germany is underinvested, losing foreign direct investment while labor costs rise. The consequence is job cuts. DATEV data confirm this trend, especially among small firms, which reduced headcount by 3.4 percent year-on-year. Overall employment declined by 0.3 percent, translating into about 125,000 jobs lost over the past 12 months—70,000 of them in industry, the backbone of Germany’s economy.

The DATEV index offers a granular, real-time look into the engine room of the German economy. The data are not government estimates or Bundesbank approximations but anonymized, aggregated real-time figures drawn from VAT filings and payroll accounts, covering over one million companies and eight million employees.

A Realistic Look at a Deep Recession

The numbers confirm that after contracting by 0.9 percent in 2023 and 0.5 percent last year, the German economy is set to slip even deeper this year. To assess the real trajectory, one must strip out the artificial boost from government spending. With a 3.5 percent deficit and a public-sector share of 50 percent of GDP, the private-sector recession looks dramatically worse—somewhere between –4 and –5 percent. Hospitality’s 4 percent drop lines up almost perfectly with this estimate.

Consumers, meanwhile, remain deeply unsettled. Despite rising wages, they are holding back on spending. Everyone seems to sense that this is just the beginning of a recession, one that could end with a full-blown employment crisis.

The “Investment Booster” Is a Dud

Germany’s structural problems are well known and now manifest. The old business model—cheap energy (much of it from Russia), export-driven growth fueled by the weak euro—belongs to the past. The government’s much-publicized “investment booster” will not jolt the country out of its economic paralysis.

The planned relief amounts to just €7 billion per year—spread across accelerated depreciation rules for machinery and buildings, and token tax cuts that won’t even take effect until 2028. Compare that with the over €100 billion German firms pay annually in corporate and trade taxes—before counting social charges and bureaucracy costs in the hundreds of billions.

The result: the booster is marginal, a drop in the ocean. Instead of real tax cuts or structural reforms, companies get a temporary gimmick. Politicians sell a cosmetic fix as a breakthrough—but in reality, the investment brake remains fully engaged.

* * * 

About the author: Thomas Kolbe, a German graduate economist, has worked for over 25 years as a journalist and media producer for clients from various industries and business associations. As a publicist, he focuses on economic processes and observes geopolitical events from the perspective of the capital markets. His publications follow a philosophy that focuses on the individual and their right to self-determination.

Tyler Durden
Mon, 08/25/2025 – 02:00