59.7 F
Chicago
Wednesday, November 4, 2026
Home Blog Page 135

India’s Clean Energy Boom Halts Coal Power Growth

0
India’s Clean Energy Boom Halts Coal Power Growth

Authored by Tsvetana Paraskova via OilPrice.com,

India’s coal power generation did not grow between the first half of 2024 and the first half of 2026, for the first such two-year period in over 50 years in which coal power has remained flat in the world’s second-largest coal consumer, a new analysis by the Centre for Research on Energy and Clean Air (CREA) for Carbon Brief showed.

“The period from the first half of 2024 to the first half of 2026 saw the largest increase in non-fossil power generation on record in India,” Lauri Myllyvirta, lead analyst at the Centre for Research on Energy and Clean Air (CREA), wrote in the analysis.

Moreover, the clean energy boom led to the first time in more than 50 years that India has seen no growth in coal power generation over a two-year period, even as electricity demand grew overall.

Despite the record clean energy growth, India continues to pursue major capital investments in fossil fuels, including new coal-power capacity, plans for conversion of coal-to-chemicals, and efforts to boost domestic coking coal production for the steel sector, CREA noted.

A total of 43 gigawatts (GW) of coal-power capacity was under construction in India as of the end of June 2026, according to the analysis.

Overall coal-fired capacity installations in India continue to rise, and coal remains a key pillar of India’s electricity mix – about two-thirds of total power output.

Despite booming renewable capacity additions, India continues to rely on coal to meet most of its power demand as authorities also look to avoid blackouts in cases of severe heat waves.

Coal will still be a key part of India’s power system for the next two decades, Rajnath Ram, adviser for energy at the government policy think tank, NITI Aayog, said at the end of last year.

“We cannot be subjective about coal. The question is how sustainably we can use it,” the official noted.

Tyler Durden
Sun, 09/20/2026 – 19:30

“Not Enough Raw Material!” – Resource Wars Put Tungsten In Crosshairs As Western Rearmament Supercycle Looms

0
“Not Enough Raw Material!” – Resource Wars Put Tungsten In Crosshairs As Western Rearmament Supercycle Looms

Submitted by Almonty Industries CEO Lewis Black, 

The UK just invested £71m to restart a tungsten mine, with an option on half the output. Other governments will follow. I should be pleased – I’ve spent years arguing the West needs to fund its own supply.

The problem is I’ve seen what happens next. In 2008, Japan and South Korea poured billions into securing critical mineral supply chains. They funded projects across Australia and Canada. The result: no material produced. The money went to a generation of junior mining executives. I remember them on their boats in Monaco – very grateful, very happy. Governments have good ideas. The people they back to deliver on them are sometimes another matter.

The challenge is that a government is a jack of all trades – it can’t tell a good mine from a bad one, so it hires engineers who write glowing feasibility reports with a waiver in the small print. And there is no shortage of people who call themselves management. Most of them are clowns who shouldn’t be left alone with a box of matches.

Japan and South Korea learned. They stopped trying to pick winners and pushed the risk onto their industrial base – the companies that buy the stuff. Those companies know how to protect a dollar. If the new money follows that model, the checks might land somewhere useful this time.

Tungsten markets

Michael Dornhofer, ISBP – assessment as of 11 September, 2026

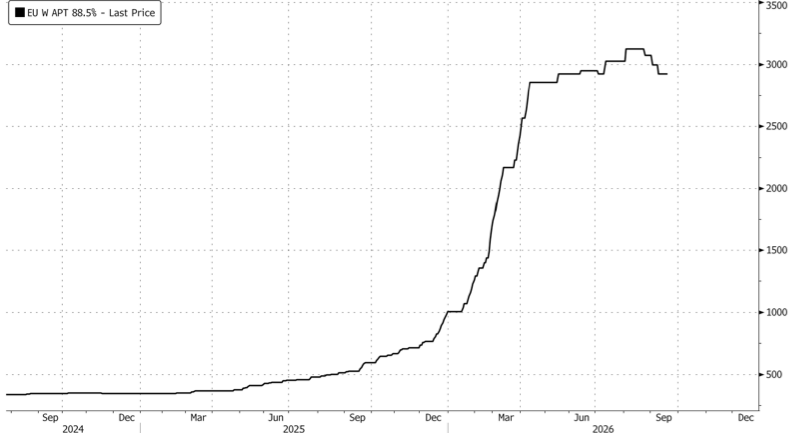
Tungsten prices in the USA and Europe stay unchanged for another week and are still around 3000 USD/mtu WO3. Reports from China show their domestic price trend moved to an upward tendency.

The reason is quite simple: There is not enough raw material! As the APT price in China is only about one third of the western price, Chinese APT producers are not willing to buy western concentrates on western price level. But without a significant amount of imported raw material, the industry is running short on raw material. Soon it will become clear whether the Chinese domestic prices will go up towards western levels, or China might reduce output of downstream products for export.

The coming weeks will show us. And there’s another interesting development that even some “experts” overlooked. On 5 August, China placed several foreign entities under sanctions and banned them from operating in China. One entity on this list is the non-profit organization RBA.

RBA (Responsible Business Alliance) is the world’s largest industry coalition dedicated to promoting responsible business conduct. RBA has more than 600 member companies including Apple, Tesla, Microsoft, Amazon etc. and runs the RMI (Responsible Minerals Initiative) program.

Nearly the entire western downstream industry insists on RMI certificates for their total supply chain. When, due to the ban of RBA, no RMI audits and certificates are possible in China, western downstream producers cannot accept any tungsten material or downstream products coming out of China.

China wants to replace the RMI audits by audits performed by CCCMC (Chinese Chamber of Commerce for Metals & Chemicals). But knowing that China imports thousands of tonnes of concentrate from countries like Myanmar and North Korea, and so material from these countries are in the tungsten supply chain in China, it’s questionable who would trust Chinese audit certificates.

So, this easy-to-overlook new regulation in China could lead to an additional “firewall” between China and RoW, which might have a very significant effect on the tungsten world market.

Michael Dornhofer is founder of ISBP (Independent Supply Business Partner) in Graz, Austria. He has spent more than 20 years in tungsten, including 13 years at Wolfram Bergbau und Hütten, Sandvik’s tungsten business, and has worked as an independent agent and consultant to the tungsten and hard metal industry since 2019.

From January, the door shuts

Since 2023, the Pentagon has barred Chinese, Russian, Iranian and North Korean tungsten from defense contracts. From 1 January 2027, that restriction moves upstream. It will no longer matter where the tungsten was melted or processed. What matters is where it was mined. Ore, feedstock, recycled material: if it started life in one of those four countries, it is out. The route that kept the loophole open – mine in China, process somewhere friendlier, sell it as non-Chinese – closes for good.

That’s the American side. On the other side, producer countries are shutting their own doors. Zimbabwe banned exports of tungsten ore and concentrates in July, confirmed by the Ministry of Mines and reported by Bloomberg last week. Vietnam’s industry ministry has drafted a proposal to pull tungsten off the permitted-export list entirely. Vietnam is the world’s second-largest producer, at around 3,400 tonnes a year. If that draft becomes law, the non-China supply pool gets a lot smaller.

Zimbabwe barely produces any tungsten. The volume is negligible. But the pattern is worth watching – one more producer country pulling raw material off the open market. The list of places you can actually buy tungsten outside China keeps getting shorter.

Opinion

People ask why we don’t branch out. Gold is on a run. Lithium gets headlines. Every commodity has someone telling you it’s the one to watch. We do tungsten and molybdenum. We don’t know anything else – and I would rather say that than pretend otherwise.

A vet treats everything that walks through the door. Dogs, cats, parrots. A doctor specializes. The guy who whips out your appendix does not do brain surgery, unless you’re on a budget.

Mining is the same. Every deposit has its own geology, its own metallurgy, its own set of problems you only discover once you are underground. The companies that chase whatever commodity is fashionable learn everything at surface level and nothing underneath. We have been at this long enough to know what we don’t know – and we don’t know gold or lithium or anything that’s not a refractory metal.

We are the doctor.

In the media

The analysts have arrived. Jefferies has initiated coverage of Almonty with a Buy rating, citing the tightening tungsten market and the growing need for supply outside China. With the shares up considerably over the past year, interest in both Almonty and tungsten has clearly moved on.

What matters now is execution – bringing new supply into a market that badly needs it.

*  *  *

On the tungsten news front, Almonty partnered with Rwanda’s government last Monday, securing a foothold in Africa’s largest tungsten-producing nation. By Thursday, the miner, which expects to become the leading Western producer of conflict-free tungsten (ex-China), tapped Swedish mining equipment maker Sandvik’s Wolfram Bergbau und Hütten AG unit to process existing tailings from its Los Santos mine in western Spain.

As last week’s news proved, Almonty’s move is about bringing the most immediately available tungsten supply to the West as resource wars and China’s critical materials chokehold on the world collide with the US rearmament supercycle set to kick off in the near term.

In other words, the West doesn’t have the time to open new mines. 

via Christian Keller, Barclays’ global head of economics research

Without critical materials, the West’s rearmament supercycle, reindustrialization, data center buildouts and a nearly endless list of other projects would not be possible. Wall Street should refocus on producing miners that can deliver today because they’re the ones providing the building blocks that make Western reindustrialization possible. 

Tyler Durden
Sun, 09/20/2026 – 17:30

Iran’s Military Believes US Is Preparing To Resume Attacks

0
Iran’s Military Believes US Is Preparing To Resume Attacks

Iran’s central military command has announced it believes the United States has made the decision to resume military attacsk on the Islamic Republic.

Citing the country’s General Staff of the Iranian Armed Forces, state media IRIB states that “According to intelligence received, the US has once again decided – with the green light from certain regional countries – to resume actions against Iran during a joint meeting in a European nation.”

Getty Images

At the same time Iranian leadership again warned US allies in the region that they’ll be considered “complicit” if the US resumes it military assault on the Islamic Republic. The Iranian military HQ stated that “any mistakes will result in painful attacks.”

Tehran further indicated Sunday that it is still awaiting Trump’s response to its conditions for ending the war. Its chief negotiator Mohammad Bagher Ghalibaf confirmed to AFP that Iran’s demands were sent to Washington via the Qataris.

Starting Saturday night there was an avalanche of online chatter over potential new escalation, given President Trump abruptly cut short a visit to Camp David.

Some pundits saw in this a sign of some kind of imminent military action in the Middle East, also amid reports that extra military hardware is being sent to the region.

But others have suggested this is just setting up for another TACO moment, and reports of escalation is just the White House trying to instill fear and uncertainty in Tehran.

There’s also speculation that Washington could be moving towards direct intervention in the Saudi-Yemen conflict, after the Houthis have been attacking key Saudi Aramco oil sites. Also, Riyadh has just come under attack for the first time of the war.

In the background is a new State Department warning to Americans to avoid all travel to the Middle East. A statement indicated that the Iran war could quickly worsen.

“This military conflict has the potential to escalate rapidly. Americans outside the Middle East should seriously reconsider travel to and through the region,” the State Department said late Saturday on X. It said that Americans currently in the region should “exercise heightened vigilance and be aware of potential flight cancellations, airspace closures, and travel disruptions.”

Tyler Durden
Sun, 09/20/2026 – 17:00

Trump Says His Planned DC Arch Would Host Drones And Snipers

0
Trump Says His Planned DC Arch Would Host Drones And Snipers

Via Headline USA,

President Donald Trump said Sunday that the massive arch he wants to build between the Lincoln Memorial and Arlington National Cemetery would become a “top grade military complex” able to host drones and snipers while storing ammunition.

It is one more example of how Trump is insisting that his initiatives to beautify the White House and the city are also serving a defensive purpose.

Trump has been calling the new White House ballroom a “military complex” and arguing it is necessary for national security purposes.

The Republican president said in a social media post that he had agreed, at the “strong request” of the military, to convert the planned 250-foot-tall memorial arch “into a top grade Military Complex/Triumphal Arch, to house, store, and have the rapid ability to use large numbers of drones, plus Snipers, on both the roof and plaza areas, and additionally have and hold large quantities of sniper ammunition in storage.”

After teasing it in October 2025, Trump has continued to promote his vision for a 250-foot triumphal arch situated between the Lincoln Memorial and Arlington National Cemetery.

The arch will “celebrate the triumphs of the American people, inspire patriotism and love of country, and beautify our nation’s capital,” the Department of the Interior, as its sponsor, declared in its project materials.

The arch (one of several projects that the Republican president is pursuing to leave his lasting imprint on Washington) is currently awaiting final approval from the National Capital Planning Commission (NCPC), a federal review panel dominated by Trump appointees.

Among the others are the white House ballroom, renaming and renovating the Kennedy Center, refurbishing the Lincoln Memorial Reflecting Pool and rebuilding a golf course in East Potomac Park that could significantly reduce the public’s access to running and biking paths.

Rep. Don Beyer (D-Va.) on Sunday criticized Trump’s announcement.

“Putting a drone launching site directly in the landing path for [Ronald Reagan Washington National Airport] is a stupid, dangerous, and unworkable idea,” Beyer said on X.

“Trump clearly expects to lose a lawsuit and therefore wants to set up a pretext to argue that the arch is tied to national security.”


Tyler Durden
Sun, 09/20/2026 – 16:30

Utah Valley University Faculty’s Sickening Post-Assassination Emails About Charlie Kirk Exposed

0
Utah Valley University Faculty’s Sickening Post-Assassination Emails About Charlie Kirk Exposed

New public records indicate that faculty members at Utah Valley University sent hostile messages regarding Charlie Kirk to the university’s administrators in the weeks following his assassination on the UVU campus, even though the university had previously issued public statements advocating civility and free expression.

Utah Valley University campus

Judicial Watch obtained the 133 pages of emails and text messages through a Utah Government Records Access and Management Act request. The records went to then-UVU President Astrid S. Tuminez and other administrators.

Kirk, the founder of Turning Point USA, was assassinated on the UVU campus while launching a nationwide campus speaking tour. University administrators spent the following months talking about healing and dialogue. Some of the correspondence flowing into the university president’s inbox tells a different story.

On September 22, 2025, a UVU instructor wrote to Tuminez, framing Kirk as a threat to “students we are trying to educate.” Kirk “appealed to the worst of us,” the instructor wrote, adding that he “spoke his prejudices openly, not to test free speech, but to shape minds,” and that he “targeted impressionable youth, feeding on their fears and anxieties.”

The email continued:

The hidden message in his rants was clear: hate is natural, and to resist it is to deny who you are. Hate masquerading as justice is nothing of the sort. True justice seeks fairness, accountability, and protection for all, while hate targets, divides, and destroys….

That is why we must resist any effort to memorialize him or turn him into an icon…. Charlie Kirk did not stand for civility, compassion, or truth. There was nothing civil about him.

The instructor closed by warning that “to memorialize him would be a grave mistake.”

A second email, dated November 4, 2025 and signed as a “faculty member,” escalated the anti-Kirk venom.

I’ve had a hard time dealing with the aftermath of the shooting on our campus, and in particular, I cannot understand how people could support or mourn someone who was so divisive and spewed such vituperation in his “debates.” I regret that he was invited to UVU at all, and wish you had rethought the decision to allow him a forum on our campus.

That faculty member then turned to the proposed campus memorial, warning administrators that the Utah legislature holds “enormous power” and predicting a mass faculty exodus if UVU honored Kirk.

“Should a memorial to him be erected on our campus, I fear you will lose many faculty members, including myself,” the email said. The same faculty member closed with a threat dressed as principle, writing, “I would not work at a university that supports Charlie Kirk’s ideals in any way.”

Nine days after the assassination, someone whose name Judicial Watch redacted from the release pitched the university on a different project. The pitch called for a $1 million fundraising drive named “Our Better Selves for a Better America.”

“I would like to raise $1 million for this proposal,” it read. “I have one pledge for $100k. I would like to raise the other $900k quickly.”

UVU ran with it. The university launched Our Better Selves for a Better America as an official presidential initiative built around civil dialogue, conflict navigation, and peacemaking.

“The killing of Charlie Kirk on September 10, 2025, was a grievous tragedy that reverberated through the Utah Valley University (UVU) community and nation. It challenged civility, respectful disagreement, and freedom of speech – core freedoms written in the United States Constitution,” the university’s webpage about the initiative reads. “In the wake of this tragedy, UVU President Astrid S. Tuminez, Ph.D., asked, ‘What is this moment asking of us? Of UVU? Of the nation?'”

While the university publicly promoted civility and open discourse, the correspondence landing in its president’s inbox ran the other way.

“Charlie Kirk was assassinated while exercising his right to speak on a college campus,” Judicial Watch President Tom Fitton said in a statement. “These records reveal that, even as Utah Valley University publicly called for free expression and civil discourse, some faculty members were making hateful and vicious comments about him, objecting to his invitation to campus, and threatening to leave if his memory were honored.”

Charlie Kirk’s family moved this month to put Utah Valley University and state officials on notice that it intends to sue, accusing the school of security failures that let his assassination happen.

“Placing a politically controversial figure like Charlie Kirk in an outdoor event in the quad surrounded by tall buildings and other elevated observation platforms is accurately described as walking him into a fishbowl,” the notice of claim read.

“Through a series of stunning failures and reckless decisions, the UVU Parties created a foreseeable danger to Charlie,” the document continued. “Those decisions ultimately rendered Mr. Kirk helpless to the rooftop shooter in an assassination that could have been avoided had the UVU Parties only taken reasonable steps to plan and oversee a safe event, steps outlined below that have been standard practice for other universities hosting controversial speakers.”


Tyler Durden
Sun, 09/20/2026 – 16:00

With The Fed Behind Us…

0
With The Fed Behind Us…

By Peter Tchir of Academy Securities

With the Fed Behind Us…

The 10-year Treasury sold off after the Fed bounced Thursday, only to resume selling, finishing the week just under 5%. Stocks, which seemed to move up and down with Treasuries, decided to move to the beat of their own drum into the close on Friday. Similarly, for the past few weeks, it seems that if you knew oil was up/down, you could predict yields would be up/down. Not on Friday.

On this special day we will build on Thursday’s post-FOMC report: Back to Regularly Scheduled Programming. You might be wondering “what makes today special”? Well, for the first time ever, the T-Report has the same access to the White House as CNN, though not quite how we hoped it would happen. The ban definitely seems weird. Not sure what to make of it, and maybe it will be nothing, but it does seem strange at the very least.

In Thursday’s report we touched on:

  • Oil and energy prices, which we will focus on more today.
  • Japanese Yen. Support has broken the 155 level solidly (closing at 156.9), which is likely to cause it to weaken further as a lot of people were willing to bet on I Am the House Now Bessent.
  • Compute Build and AI Spend. Increasingly, this is likely to be a focus of this week’s Trump/Xi summit.
  • Space. We need to do more to focus on the opportunities and risks (commercial and national security) for space. Working with some of Academy’s GIG members to more thoroughly assess this, as the national security aspect seems to be gaining more attention.

The Houthis and Saudi Arabia

Should we be treating what is going on between the Houthis and the Saudis as a subset of the Iran/U.S. war? The Houthis are, after all, a proxy of Iran. The Saudis have been working with the U.S. and the President, so are they merely just an ally? A subset, an extension, or something in its own right?

While Iran is likely influencing the Houthis and certainly has given them the tools to cause havoc and mayhem, the Houthis seem to be taking the initiative. Maybe they see the U.S. as distracted with Iran. Maybe they see the U.S. testing the Saudis’ loyalty as an ally. In any case, it seems like they have seen an opportunity and are taking strides to set their agenda in and around the Red Sea. They have seemingly gone out of their way to avoid any attack against U.S. assets. Instead, they are hitting the Saudis where it hurts: their energy industry. And according to reports, that includes jet fuel facilities at the airport.

We cautioned about getting excited that the pipeline damage inflicted on the “alternative to the Strait” pipeline would be repaired quickly. One, the damage seemed more extensive than just to the pipeline. Two, and more importantly, there is no evidence that new strikes could be thwarted. It seems like we should start pricing in “disruptions” to the energy complexes that are outside the scope of the U.S./Iran conflict.

Will the Saudis be able to defend themselves? Will they “beg” America to get involved more directly? If they do, will the U.S. get involved? Will they try to disrupt traffic through the Red Sea? If so, how much can they do before the U.S. gets involved? I’d ask how much before Europe would get involved, but that seems like it is too unlikely to even think about (they probably should, but it doesn’t seem imminent).

Markets seem to only react badly when actual events affecting energy prices occur. Markets seem to react positively to any story, rumor, or hope that is positive. That relationship may need to change…

Even My Mother Knows Diesel Prices are High!

Usually, by the time my mother knows something is affecting financial markets, it is a pretty good time to fade the trade as it has become totally consensus. I’m not so sure about that this time.

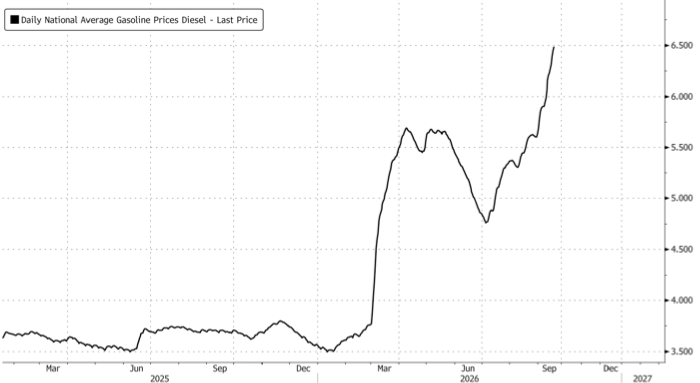
Since the war began, we’ve been focused not as much on oil, but more on LNG and Diesel. Both are “tighter” than oil itself. More susceptible to supply chain disruptions. Less flexibility to work around. So rather than “fading” something we’ve argued that people should focus on, we should just embrace that people (including my mother) are now thinking about the dangers of rising diesel prices: for industry, transportation, and agriculture (and maybe the “back up” generators at some data centers).

We already busted through the “red circle” that we had in last week’s version of this chart.

This is a big deal and has created some chatter about restricting diesel exports from the U.S. As discussed in prior reports, that is not likely to work (even with restrictions, the domestic price isn’t likely to deviate too far from Global Price minus Transportation minus Storage). It is also likely to hurt U.S. companies going forward as customers entering into new contracts need to consider this possibility (plus there are likely to be some legal challenges).

Rising diesel prices are high on my list of inflation pressures that are mounting and difficult to control (unless you are in charge of the war efforts).

One Path to Victory with Iran

Anything could happen. We could all wake up on Monday to find that there is a “deal” that is on the table and close to getting done. We did have an MOU after all (though from day 1, it seemed that although we all saw a written version, there were “unwritten” versions or promises made, that were inconsistent and it seemed like neither side had really listened to what the other side had said or wanted). I won’t discount some sort of “deal” but it seems difficult to believe that it will be one the U.S. can claim as a major victory, if it happens now (given the current news flow surrounding the war).

The economic sanctions could pressure Iran into a deal. The blockade has been very successful. Iran seems to be able to “contain” the amount of trade going through the Strait against their interests (some is going through, but Iran is still able to scare many into not trying to run through the Strait).

  • Can the increased focus on sanctions work? Sure, but in a matter of weeks? Hmmmm…I find it difficult to believe that a nation that kills its own citizens on an industrial scale will collapse in weeks, or even a couple of months. They have had experience with evading sanctions for decades, albeit sanctions not being enforced as strictly as they are supposedly being enforced now.
  • It remains unclear how sanctions will work unless the U.S. is willing to go after China (and Turkey) to the full extent of what Bessent has outlined. So far, that doesn’t seem to be happening. It will almost certainly be a discussion point this week for Trump and Xi.

Sanctions are helping and might be enough to force a good deal, but that doesn’t seem like a “tomorrow” sort of event.

Increasingly, we are being asked about “knocking out” Iran’s infrastructure. Could that happen? Yes, but here is a quick assessment:

  • Anything clearly military focused has already likely been hit and destroyed.
  • That leaves “dual use” facilities. Facilities that have both a military use and a commercial use. Let’s say energy sources close to military facilities that also service communities. Some of these are viable targets as the military usage is enough to justify going after them. Similar for some bridges necessary for moving troops or armaments. But this can be tricky: on a legal and humanitarian level. Global perception, while not necessarily at the top of the admin’s concerns, should still be a concern.

This is a possible path for the U.S., but it could be a difficult balancing act of doing enough to force change, without doing too much reputational (or even legal) damage.

Taking the Islands that control the Strait: after the midterm elections.

One theory that General (ret.) Bellon discussed this week is taking action to secure the islands that control the Strait, culminating possibly with Kharg Island.

The rationale is:

  • Wait until after the midterms, because risks to U.S. troops will increase, but it won’t be as politicized as it would be prior to the elections. Prior to the election, IRAN WILL HAVE MORE OPTIONS than after the elections. Basically, if Iran believes the midterms represent a hurdle to Trump, they can take different actions than they can after the midterms have occurred. There is no longer some “deadline” for Trump, giving him more flexibility and changing Iran’s response function. This makes a lot of sense.
  • Sanctions may work to create a deal, but anything resembling a different regime is not likely. Taking the islands that control the Strait, and eventually Kharg Island itself, would cripple their energy industry and demonstrate real weakness on their part. It will be difficult to do without loss of further life, but when so many other options leave us with a “kick the can” option, the President may decide an option that has horrible costs may be better than going through this effort every few years.
  • Signaling the will to do this might be enough to change Iran’s negotiating stance. Taking even one small, relatively insignificant island that is the easiest to defend may also change the calculus for Iran. The U.S. might win not by taking every Island, including Kharg, but the start of turning a threat into reality could be enough.

What to watch for:

  • The U.S. moving vessels with top-notch medical facilities into proximity (less than 1 hour by helicopter, say as a guideline) would be a good indication. The military’s commitment to saving each and every life possible, and providing the best care possible, is real. So, they would need to move these vessels that can perform state-of-the-art surgery and operations, close enough to help any soldiers needing aid.

Of all the discussions that I’ve heard around a “post-midterm” victory, this path seems reasonable. Maybe the theory would even be that once Iran sees the ships moving in, and knows the President isn’t potentially hamstrung by upcoming midterms, it capitulates and looks for a deal? Maybe a bit optimistic, but it resonates with me.

Greenland Deal

The President announced a deal. I will reserve comment until we see the terms of the actual deal (so far, as has become the norm, there are all sorts of assertions from a variety of sides, with little documentation).

The deal could be a real game changer, as the President implied via Truth Social. It might just be an updated formulation of agreements already in place (never hurts to update something that was written long before the polar ice caps were melting, when computers were the size of a house, and rare earths and critical minerals weren’t required in vast amounts).

A win in any case, but how much of a win remains to be seen. And could it have been done without all of the “annex” / “take” Greenland rhetoric?

Trump and Xi

We will provide a full take on this on Tuesday morning, as we work with the GIG to figure out what is likely the highest priority on both sides.

A few months ago, trade, rare earths, and critical minerals would have been high on that list. A few weeks ago, Iran and global energy had to be high on that list.

Now, cyber, AI, and compute have to be highest on the list.

At first blush, on most of these issues, the U.S. seems to need more from China than they need from the U.S. Never a great way to enter into a summit with China, but we will delve deeper on Tuesday.

Bottom Line

I’m running out of time in Vermont, and it might be nicer to spend it outside rather than at my laptop (and the Wi-Fi is spotty at best).

Diesel and the Middle East are key to rates.

For now, I think the path for energy prices (and stocks) and rates (globally) is higher. The news flow has not been positive this weekend, and it is difficult to see that changing quickly as Trump seems to be focused on dealing with Iran from a “stronger” position after the midterms (not stronger in terms of having the support of the House and the Senate, stronger because the perception that he has a deadline is gone).

For compute, Cheap Chinese Compute remains a concern.

It is difficult to get all “warm and fuzzy” about the outcome of this summit for markets. More choppiness seems to be the order of the day, with a bias to the downside for me on the compute spend story (though good for their credit spreads).

We get to bookend this week with a Monday morning appearance on CNBC and Friday morning on Bloomberg to analyze the results of the summit!

Should be another interesting week that we all have to navigate. Even with the Fed behind us, we will be paying attention to the data that may determine the next move for the Fed, but Iran, the Houthis, diesel, rates, and the summit are all going to move markets (hopefully in accordance with how we are recommending positioning).

Tyler Durden
Sun, 09/20/2026 – 15:30

Grassley Urges Diesel Export Ban As Global Fuel Crisis Stokes Resource Nationalism Fears

0
Grassley Urges Diesel Export Ban As Global Fuel Crisis Stokes Resource Nationalism Fears

“With diesel at $6.57 in Iowa, why doesn’t Pres. Trump put an embargo on diesel exports like presidents in the 70s put embargoes on ag products bc food prices were inflated,” Iowa Sen. Chuck Grassley wrote on X late Saturday night.

Grassley warned, “High diesel prices ARE KILLING FARMERS’ INCOME.”

Grassley is not wrong about the global refining crisis that is squeezing farmers and anyone else who uses the industrial fuel that powers the economy, from truck drivers and freight operators to businesses across virtually every industry. 

The risk now is that an economic shock could materialize if fuel costs stay elevated, with the latest AAA data showing the nationwide average diesel price set to cross $6.50 a gallon.

Chatter on Capitol Hill about a diesel export ban has increased, with Senate Majority Leader John Thune telling reporters last Tuesday that he is “open to exploring” the idea.

Any ban on refined petroleum product exports would escalate resource nationalism and could initially boost domestic availability and lower U.S. wholesale prices, particularly near export terminals. The problem is that domestic relief would be uneven because shifting barrels to the Northeast or West Coast would be difficult.

Barclays refining and midstream analyst Theresa Chen warned last week, “We continue to view the possibility of an export ban as both detrimental to the US refining complex and unlikely to provide the intended price relief.”

The ban could weaken production incentives. If retained fuel overwhelms domestic storage and distribution capacity, weaker refinery margins could eventually encourage lower refinery runs.

On top of that, foreign buyers of the industrial fuel would need replacement cargoes, which could exacerbate the global shortage and accelerate resource nationalism as other governments tighten control over fuels. Those restrictions could also extend beyond energy products to critical materials.

Grassley’s call for an export ban faces resistance within the Trump administration. Interior Secretary Doug Burgum said last week that restricting oil or fuel exports would be unlikely to lower consumer prices and could provoke retaliation from trading partners.

The risk now, as Bloomberg Intelligence senior commodity strategist Mike McGlone warned last week, is that a diesel crisis could trigger an economic shock similar to what happened during the 2008 energy crisis.

Tyler Durden
Sun, 09/20/2026 – 15:00

Stolen $586,000 Copper Shipment Found Hours Later At Kentucky Warehouse

0
Stolen $586,000 Copper Shipment Found Hours Later At Kentucky Warehouse

A load of copper worth nearly $600,000 was recovered on Sept. 11 after investigators followed a trail from Illinois to Kentucky and Ohio, wrapping up the initial search only about eight hours after the theft was reported, according to Yahoo News.

The case began when a shipment scheduled to travel from DeKalb, Illinois, to Rock Hill, South Carolina, never made it toward its intended destination. Authorities believe whoever collected the freight had presented themselves as an established trucking company, using genuine business information to make the pickup appear legitimate.

The breakthrough came from location data tied to Schneider National equipment involved in the haul. Rather than heading southeast toward South Carolina, the freight was traced to Prestonsburg, Kentucky, where police found the entire six-pallet copper shipment inside a warehouse. Three people were detained in Kentucky.

Photo: FreightWaves/Yahoo News

Meanwhile, investigators continued following the equipment used to move the load. A Schneider chassis and container were located in Chillicothe, Ohio, while state troopers separately intercepted the tractor associated with the pickup. One additional person was taken into custody in Ohio.

Yahoo reports that the operation involved authorities in Illinois, Kentucky and Ohio, along with Schneider National and CargoNet, which had helped flag the theft. Information about the truck, trailer and driver was quickly distributed among agencies as investigators attempted to follow the shipment across state lines.

Police are now examining whether the incident may overlap with another theft involving Schneider equipment and whether the people or trucking identities involved could be part of a wider cargo-theft operation. So far, authorities have not publicly identified the four people detained or disclosed what charges they may face.

The episode also illustrates how freight theft has evolved beyond simply stealing unattended cargo. Criminals can use authentic company information to appear legitimate long enough to take control of valuable shipments. In this instance, rapid reporting and tracking technology allowed investigators to locate both the cargo and much of the equipment before they could disappear further into the supply chain.

* * *

Tyler Durden
Sun, 09/20/2026 – 14:00

‘Keep Digging’… Says Shovel-Salesman Jensen Huang

0
‘Keep Digging’… Says Shovel-Salesman Jensen Huang

Submitted by QTR’s Fringe Finance

Maybe it’s the bullshit detection genes that were passed down to me from my mother, but I simply can’t wind up trusting a word Nvidia CEO Jensen Huang says about how much AI regulation the United States needs.

Just call it a gut reaction from me. It doesn’t mean Huang is necessarily wrong about AI. It’s just that I look at him and all I can see is one of the most financially conflicted people on planet Earth to ask about AI regulation.

According to CNBC, Huang has increasingly gained President Trump’s ear on AI policy, appearing alongside him repeatedly and pushing a relatively simple message as concerns about AI safety mount: keep moving, keep building and don’t let regulation get in the way.

What an astonishing coincidence that this also happens to be fantastic policy for Nvidia, which sits at the nerve center of a multi trillion dollar AI infrastructure boom…which itself sits at the nerve center of an even larger global economic ponzi scheme (hereinafter referred to as: the global economy).

Nvidia’s chips are effectively the picks and shovels of the entire operation. Every hyperscaler racing to build another data center, every AI lab trying to train a larger model and every corporation terrified of being left behind has helped create extraordinary demand for Nvidia’s hardware. In return, Nvidia has “invested” in a countless number of other operations that rely on its hardware. One big happy circle jerk family.

And one of the most spectacular corporate ascents in history for Nvidia. It has become one of the central pillars of the AI trade, which itself has become enormously important to the U.S. stock market. Nvidia and the other mega cap technology companies tied to the AI boom carry enormous weight in major indexes owned by investors around the world.

There is a staggering amount of money riding on the proposition that the AI spending boom continues. And sitting directly in the middle of it is Jensen Huang. It’s been the reason for my (somewhat) tongue-in-cheek opinion that Nvidia will never miss an earnings report again, because the powers that be would rather see them commit egregious accounting fraud than tell the truth about shitty numbers and watch the global economy collapse.

And now Huang is apparently becoming one of the president’s most influential voices on precisely the question that could determine how quickly this machine is allowed to keep running. You almost have to admire the efficiency.

CNBC reports that Trump has increasingly echoed Huang’s views on AI safety, while Huang has publicly dismissed some of the more apocalyptic warnings surrounding artificial intelligence. His preferred solution to many safety concerns is essentially “good old fashioned engineering.”

Maybe he’s right. But forgive me if I’m not eager to treat the CEO of Nvidia like an objective third party monk who has been summoned down from a Nepalese ashram to offer Washington philosophical wisdom about the future of humankind. The guy is a CEO of the company selling the hardware required to run the experiment.

Nvidia makes extraordinary amounts of money when OpenAI, Meta, Google, Microsoft, Amazon and everyone else decides they need more compute. It makes money when data centers get larger. It makes money when models get larger. It makes money when the AI arms race accelerates. Somehow, I assume, it even makes money when I use my toaster to make an english muffin in the morning.

Presumably, Nvidia would face a less favorable commercial environment if policymakers imposed rules that materially slowed that race. Or altered my breakfast plans.

That doesn’t mean Huang is lying. It doesn’t mean his policy arguments are necessarily wrong. And it certainly doesn’t establish some secret conspiracy between Nvidia and the White House. But it does mean the conflict of interest is so enormous you can practically see it from space.

This is why I find Huang’s growing proximity to Trump far more interesting than another photograph of two powerful men smiling at dinner.

CNBC reports that Huang is expected to attend the president’s state dinner for Chinese President Xi Jinping. The administration, meanwhile, has emphasized accelerating American AI development and resisting restrictions it believes could weaken the United States relative to China. Those positions can align extremely well with Nvidia’s commercial interests.’

Maybe that alignment produces good policy. But investors should understand who is sitting at the table and what they have riding on the outcome.


🔥 85% OFF FOREVER IF YOU SUBSCRIBE TODAY: I am again offering an 85% discount to anyone that wants to become a Fringe Finance annual subscriber today. It’s a discount you can keep and stays applied for as long as you wish to remain a subscriber: Get 85% off forever


If Exxon’s CEO became one of Washington’s most influential voices on whether America should restrict oil drilling, I wouldn’t simply write down his opinion and call the matter settled.

If JPMorgan’s CEO were advising the president about whether banks needed additional capital requirements, I’d probably keep JPMorgan’s balance sheet somewhere in the back of my mind.

And when big pharma figured out a way to “find” clinical studies questioning ivermectin’s safety record in the middle of a pandemic where they were trying to sell vaccines, despite ivermectin being on the WHO’s Model List of Essential Medicines and having been used successfully in 3.7 billion doses for the last 39 years, I didn’t trust that either. The timing was just too…perfect.

So when the CEO of the company arguably benefiting more than anyone else from the AI capital spending explosion tells the president that fears surrounding AI are overblown and additional regulation could be counterproductive, I’m going to apply precisely the same standard.

Huang’s job is not to protect my portfolio, the stock market or civilization. His job is to run Nvidia, and he has been extraordinarily good at it. That is exactly why I don’t understand the impulse to treat his pronouncements about AI policy as though they arrived on stone tablets.

The stakes here are much larger than Nvidia.

AI enthusiasm has become deeply embedded in the market’s valuation structure. Trillions of dollars of market capitalization are tied directly or indirectly to assumptions about continued AI investment, continued infrastructure spending and eventual returns on an almost unimaginable amount of capital being poured into the sector.

Anything that threatens that narrative, including disappointing returns, slower model development, power constraints, tougher regulation, customers deciding they have bought enough GPUs for a while and/or me discontinuing use of my toaster in the morning, potentially threatens much more than one semiconductor stock.

AI will also play a massive role in the upcoming midterm elections. There is also a very real case that if we pass a certain point waiting to regulate AI, we may not have a chance to in the future. And there’s also arguments that AI CEOs are calling for regulation to stifle competition. Whatever the case, we have to go about regulation ideas in a more objective fashion.

Jensen Huang may ultimately be correct that engineers can manage these risks without heavy government intervention. He may be correct that excessive regulation would damage American competitiveness. Those arguments deserve to be evaluated on their merits.

But they should also be evaluated alongside the economic incentives of the person making them. There is something almost comical about watching the man standing closest to the cash register explain why everybody needs to keep shopping. You don’t need a conspiracy theory to be skeptical in this situation.

Follow me one more time. Huang runs a company whose fortunes are intimately connected to the continuation of the AI boom. The Trump administration has publicly emphasized American AI dominance, economic growth and strong financial markets. Where those interests overlap, Nvidia has every reason to make its case as aggressively as possible.

And Huang could be doing exactly that. Good for him. But I’m not confusing excellent corporate strategy or political relationship building with an independent assessment of whether AI poses serious risks or requires additional oversight.

When the CEO of the company selling the picks and shovels tells Washington that the gold rush shouldn’t be slowed down, I don’t hear the voice of an impartial referee…I hear the guy selling the shovels telling everyone to keep digging.

—

QTR’s Disclaimer: Please read my full legal disclaimer on my About page here. 


Tyler Durden
Sun, 09/20/2026 – 13:30

The Fed Rate-Hike Won’t Fix The Inflation It Targets

0
The Fed Rate-Hike Won’t Fix The Inflation It Targets

Authored by Lance Roberts via RealInvestmentAdvice.com,

The Fed did what the bond market dared it to do. This past week, in a unanimous vote, the FOMC raised the target range for the federal funds rate by 25 basis points to 3.75%-4.00%, the first Fed rate hike since 2023. The stated reason was “price stability.” Yet this is a Fed whose own chairman has spent the past year insisting that real growth does not cause inflation, and that the drivers of this one sit largely outside the central bank’s reach. As we argued in prior Bull Bear Reports on the debt-and-inflation problem, that tension is not a footnote; it is the entire story of the Fed rate hike, and something worth exploring more deeply.

Make no mistake, it was the bond market that forced the issue. Such is interesting when you consider that Kevin Warsh wants the market to create the signal. Well, he got what he wished for. The 10-year Treasury yield pushed to roughly 5.01% around Wednesday’s decision, a level not seen in 19 years, while the 30-year cleared 5.35%. In other words, the market’s message was clear: “Raise rates, or we will.”

What The Fed Rate Hike Actually Does

However, what gets lost in transmission is what the Fed is actually trying to achieve through interest rate policy. The mechanism behind rate hikes or cuts is a demand story, nothing more. Raising the policy rate raises the cost of money across the system. Credit-financed demand cools first, mortgages, auto loans, capex, anything that lives or dies on the cost of borrowing. As that demand softens, the economy loses some of its power to bid prices higher, and the pace of increase eases. “Price stability,” in the Fed’s own framing, is really “expectations” stability.

Now, notice what the Fed’s tool never touches, and this was mentioned by Warsh on Wednesday. A higher Fed funds rate does not drill a well, end a war, or reopen the Strait of Hormuz. The Fed rate hike works on one side of the ledger, and one side only: the demand side. Such is the design, and such is also the limit. When the inflation in front of you is a supply problem, a demand lever pulls on the wrong rope.

What Warsh Means By “The Fed Can’t Fix Prices”

However, this is where most of the mainstream commentary gets sloppy. The Warsh school separates two things that the word “inflation” quietly blends together.

  1. There are relative prices, set in the real economy by supply and demand for actual goods, and then
  2. There is the monetary unit, the purchasing power of the dollar itself.

An iPhone gets cheaper because of globalized production. Oil prices rise because of a war that threatens supply lines. No policy rate produces either outcome.

When Warsh implies the Fed cannot fix prices, the defensible version of that claim is narrow and correct. Monetary policy cannot repair a supply-driven, relative-price shock. It can only compress demand until something breaks. Milton Friedman’s line, that inflation is “always and everywhere a monetary phenomenon,” is usually quoted, incorrectly, to argue the opposite. However, read that carefully, because it makes Warsh’s point. Friedman described the slow erosion of the currency over the years (driven by a general rise in inflation amid economic growth), not the price of gasoline during a Gulf conflict. The Fed owns the monetary unit, but does not own the oil market.

Look at the composition of the number the Fed is fighting.

Headline ran 3.4% in August, but energy alone ran 16.9%. Strip the war out, and the overheating story gets much harder to tell. That is not a demand economy running too hot. That is a supply line on fire.

Then Why Hike Into A Supply Shock?

Fair objection. If the Fed cannot produce a barrel of oil, the Fed rate hike looks like “theater.” It is not, and the reason is CREDIBILITY. A central bank tightens into a supply shock for three defensible reasons, none of which involve lowering the price of crude.

  1. To keep inflation “expectations” anchored, so a one-off energy spike does not get built into wages and contracts and turn into the self-sustaining spiral of the 1970s.
  2. To protect the institution’s word after the “transitory” humiliation of 2021, when the Fed looked through a shock and watched it metastasize.
  3. Because the cost of being wrong twice dwarfs the cost of over-tightening once.

The dot plot shows the committee has made that trade. Sixteen of eighteen officials now see the possibility of at least one more hike this year, and four pencil in two.

“Inflation remains elevated. Today’s policy action will support a timelier return to the Committee’s 2 percent goal.” – FOMC statement, September 16, 2026

Read that quote once again. The committee expressly said that it can steer prices with rates. However, history tells us more precisely that the Fed can reliably steer demand only. Those are not the same claim. Fighting a supply shock with a demand tool is the textbook recipe for stagflation, slower growth, and higher unemployment without curing the thing that lit the fire. Such is the box Warsh is in, the same Volcker-versus-Burns dilemma, now his to own.

Here is a clearer way to see the potential danger that Warsh is walking into. The same dot plot that pins the neutral rate at 3.1% now has the funds rate at 3.875% and climbing toward a 4.1% median by year-end. Once you strip away the language, the Fed is already about 90 basis points into restrictive territory, with more to come, even as Warsh insists conditions are not “broadly restrictive.”

That setup leaves the Fed with absolutely no margin for error. In the current environment, the Fed is hiking rates to offset an oil price spike. If energy costs continue to weigh on growth and the Fed continues to tighten, it will accelerate the deterioration. If oil reverses, the inflation impulse fades quickly, and the Fed’s hikes accelerate the economic bite. Both roads end at the same address, a Fed caught in a policy mistake, scrambling to fix the overshoot.

What Usually Happens To Stocks After A Hike, And Why This Time Is Different

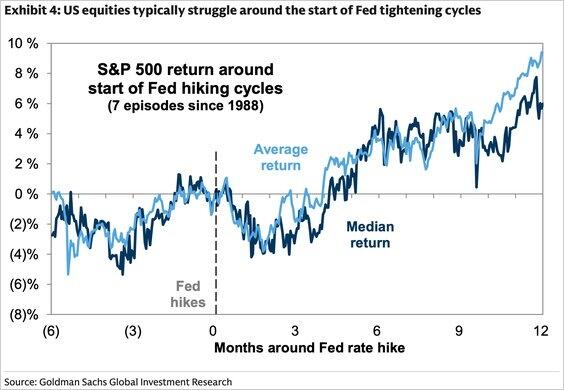
The bulls have a comforting statistic ready for this week, and it is a real one. Going back to the late 1980s, the S&P 500 has slipped only modestly immediately after a first Fed rate hike, roughly 2% over the first three months, then recovered to average gains of nearly 9% over the following year, according to Goldman Sachs. LPL Financial puts the average 12-month gain at 6.7%, with a median of 10.7%. The tidy conclusion is that rate hikes are buying opportunities.

However, as is always the case, beware of “averages,” which in this case may well be lying to you. The reason I say that is due to the composition. The Fed almost always hikes into a strong, demand-driven expansion. It rarely hikes into a supply shock. When it has, the record is far uglier, and the damage tends to arrive late, once the energy spike feeds inflation and the tightening starts to bite.

After the 1973 oil embargo, the S&P fell 11% in a month and 41% over the next year. Another, more recent example, was when the Fed tightened amid the energy-and-inflation shock of 2022. During that period, the index lost roughly 19% for the year and remained underwater well past 12 months. Every “hikes are bullish” study carves 2022 out as the exception. Today, it is most likely not the exception, but the template.

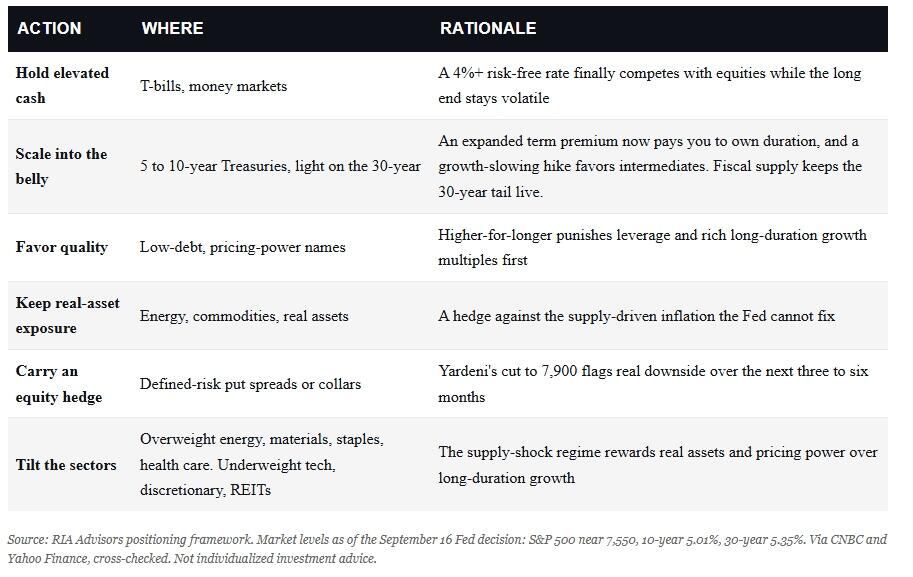
One thing that matters is the pace of the Fed rate hikes. Charles Schwab’s strategists found that the S&P returned 10.5% over the year following slow tightening cycles and lost 3.6% after rapid ones. So what should you actually expect over the next year, hiking into a war-driven supply shock with the 10-year near 5%? Our read sits below. It is a judgment anchored in that history, not a backtest.

In the current market, the leadership is not subtle. When the Fed hikes amid an energy shock, money tends to flow to where inflation is a benefit rather than a hindrance. For example, in 2022, as shown below, energy led the market up by about 48%. This suggests that investors, today, like then, should favor energy, materials, and defensives with real pricing power, as well as staples and health care. On the other side, underweight long-duration assets such as technology and communication services, as well as rate-sensitive discretionary and real estate names. However, there is always a caveat. If oil breaks and the shock fades, that map inverts, and today’s laggards lead the way back.

Such is the danger of leaning on a historical average built almost entirely on the wrong kind of hike.

What This Means For Markets Over The Next Few Months, And How To Navigate It

So how do you navigate it? Rates are “higher for longer,” and the committee has told you plainly it is willing to go again. The 30-year above 5.35% and the 10-year near 5.01% raise the bar that every equity, especially long-duration growth, has to clear to justify its multiple.

The forecasters are already marking that reality. Ed Yardeni cut his year-end S&P 500 target to 7,900 from 8,400 on the decision, flagging the risk of a downturn over the next three to six months as yields climb on energy. We would take the warning seriously without treating it as gospel.

Let’s focus on the bond market, which is the harder call right now, and the argument cuts both ways.

The bull case is a good one.

“The term premium has expanded to levels that historically pay investors to own duration, and a hike that slows the economy is the classic tailwind for long Treasuries. If Warsh restores “credibility” and growth cools, the long end rallies, and this past week’s high yields will look like a gift.”

The bear case, however, also has teeth.

“The 30-year sits at a 19-year high for a reason: relentless issuance against a $40 trillion debt, layered on top of supply-driven inflation. Rate hikes can not fix that. That tail does not disappear either just because the Fed moved a quarter point. So, this argues that investors should take exposure at the point where the term premium is best paid for the risk. That is in the belly of the curve, with 5-7 year durations.”

Crucially, none of this argues for abandoning equities. It argues for respecting a market regime in which the risk-free rate finally competes with everything else. It is an environment where the biggest driver of “price stability,” the Fed cited, is a war it can’t control. The deeper problem lies one level down. The deficits and debt that we repeatedly flagged are the real long-run engine of price stability. Monetary policy sits downstream of all of it.

The Fed can raise the price of money. It cannot lower the price of a war. Size the portfolio for the difference.
Tyler Durden
Sun, 09/20/2026 – 11:30