

70.7 F
Chicago
Saturday, September 19, 2026
Home Blog Page 1355

“Frozen At The Wheel”: Bessent Slams Fed For Delay On Rate Decisions In Wide-Ranging Interview

“Frozen At The Wheel”: Bessent Slams Fed For Delay On Rate Decisions In Wide-Ranging Interview

US Treasury Secretary Scott Bessent on Monday criticized Federal Reserve policymakers for what he described as their hesitant posture on interest rates, while signaling that the U.S. Treasury is unlikely to alter its current strategy on debt issuance by increasing long-term bond sales.

In a wide-ranging interview, Bessent said that recent yields on long-duration Treasurys make it a poor time to lengthen the government’s debt profile. “Why would we do that?” Bessent said on Bloomberg Television. “The time to have done that would have been in 2021, 2022.”
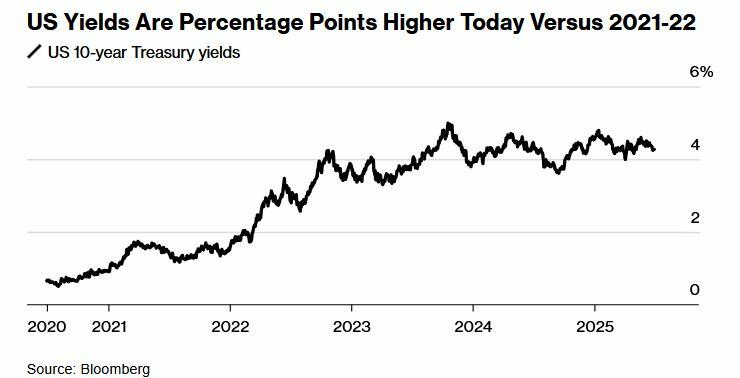
Ten-year Treasury yields currently stand at about 4.26%, well above the levels of shorter-term instruments such as the two-year note (3.73%) and 12-month bills (3.81%). Bessent suggested issuing more long-term bonds at these rates would be counterproductive, especially given his expectation that inflation will continue to moderate and pull interest rates lower across the maturity spectrum.

As we see inflation come down, I think the whole curve in parallel can shift down,” he said, referencing the Treasury yield curve, a key barometer for economic sentiment.

Bessent, who succeeded Janet Yellen as Treasury chief, has retained much of his predecessor’s issuance strategy, despite having previously criticized her for over-reliance on short-term borrowing. At the time, he argued the policy was politically motivated to suppress long-term borrowing costs ahead of the 2024 election.

But Bessent emphasized that now is not the moment to pivot. “Why would we do it at these rates, if we are more than one standard deviation above the long-term rate?” he asked rhetorically.

Fed ‘Frozen at the Wheel’

While expressing confidence in the direction of fiscal policy and trade strategy, Bessent leveled pointed criticism at the Federal Reserve’s rate-setting stance. They “seem a little frozen at the wheel,” he said of Fed officials. “My worry here is that, having fallen down on the American people in 2022, the Fed’s now looking at their feet,” rather than looking ahead.

The Treasury Secretary cited the Fed’s delayed response to rising prices in 2022 as a pivotal misstep and warned that similar inertia could hinder the central bank’s ability to respond to changing economic conditions. “The Fed made a gigantic mistake in 2022,” he added.

Bessent also pushed back against the idea that recent tariffs have stoked inflation. We have seen no inflation from tariffs,” he said, calling such effects “transitory” and suggesting they result in only a one-time price adjustment. He hinted at more trade activity on the horizon, saying he expects a “flurry of trade deals” in the days leading up to the July 9 negotiating deadline. The U.S. has already reached agreements with the United Kingdom and China, with ongoing talks still underway.

Meanwhile, as speculation mounts over who might succeed Fed Chair Jerome Powell when his term ends in May 2026, Bessent acknowledged that discussions are already underway. “Obviously there are people who are currently at the Fed who are under consideration,” he said, adding that the administration is eyeing the January 2026 seat opening as a potential stepping stone for the next chair.

Observers have noted Governor Christopher Waller – a Trump-era appointee who has recently called for possible rate cut – as a likely contender. Bessent also mentioned that current Governor Adriana Kugler’s term concludes in January, providing another possible opening for strategic appointments.

He downplayed speculation about his own interest in the job. “I’ll do whatever the president wants,” he said, but added that he already has the “best job in DC”

Looking forward, Bessent expressed optimism about the direction of U.S. fiscal strategy. He voiced support for the Republican budget bill currently advancing in Congress, describing it as a “start” in the effort to bring U.S. debt under control while promoting economic growth.

Bessent also suggested that we could see a lowering of rates, as inflation is “very tame,” adding that he is confident the fiscal policy bill will progress in the coming hours.


Tyler Durden
Mon, 06/30/2025 – 11:25

Stablecoins Are Becoming ‘Default Settlement Layer” For The Internet

Stablecoins Are Becoming ‘Default Settlement Layer” For The Internet

Authored by Amin Haqshanas via CoinTelegraph.com,

Stablecoins have become the backbone of internet payments, with adoption now outpacing major traditional card networks in onchain volume, according to Noam Hurwitz, head of engineering at Alchemy.

Hurwitz told Cointelegraph that stablecoins have seen “explosive” adoption, adding that they are “becoming the default settlement layer for the internet.”

Companies like PayPal and Stripe are integrating stablecoins to leverage onchain infrastructure, enabling faster and cheaper transactions. “They’ve already surpassed Visa and Mastercard in onchain volume by 7%,” Hurwitz noted, signaling a decisive shift in how money moves online.

Alchemy, which provides infrastructure to some of the largest stablecoin ecosystems, is at the center of this transformation. Hurwitz said Alchemy is “the onchain provider for Robinhood Wallet” and powers stablecoin flows for fintech giants like Visa, Stripe, Circle, and PayPal.

Stablecoins used for various purposes

Hurwitz said that stablecoins make money “cheap, fast, global, and secure to transfer.” These features have made them popular for various purposes, with broad adoption emerging across cross-border payments and prediction markets like Polymarket.

He added that stablecoins have become massive buyers of US Treasurys, with Tether alone generating $13 billion in profits last year while holding around $113 billion in US debt. “Tokenized money is the base of the tokenized financial system,” Hurwitz said, calling recent financial innovation built on this foundation “exciting.”

Tether holds more US Treasurys than Germany. Source: TFTC

Hurwitz said stablecoins are already functioning as the “default rails” for internet payments in many respects but flagged challenges stemming from the fragmented blockchain landscape.

Institutions, he explained, want to move quickly but must assess provider reliability and counterparty risks, especially in a nascent industry. “Can a small startup really support enterprise-grade operations while building and scaling the services they need?” he asked.

Hurwitz pointed to Kinexys, a tokenized bank deposit launched by JP Morgan, as a major milestone. The permissioned deposit token enables institutional clients to access yield-bearing deposits on a public blockchain with “24/7 settlement, near real-time liquidity and the potential ability to pay interest to holders.”

Interest in stablecoins surge with new regulations

Last week, the US Senate passed the Guiding and Establishing National Innovation for US Stablecoins, or GENIUS Act, a landmark bill establishing federal guardrails for stablecoins.

“With the recent passage of the Genius Act, the regulatory landscape is becoming clearer and more structured, which benefits established financial players while also encouraging innovation,” Hurwitz said.

Meanwhile, Hurwitz pointed out key technical bottlenecks in improving developer and end-user experience despite strong growth. “Companies benefit immensely from settling on crypto rails, but want to decouple the user experience from the underlying technology — and doing so takes deep technical expertise,” he explained.

Looking ahead, Hurwitz expects most financial services to deploy their own blockchains, especially layer 2 networks, to better scale and monetize their ecosystems.

He predicted that infrastructure improvements would drive “seamless crosschain interoperability” between these networks, enabling a more connected and efficient financial system built on stablecoins.

Despite Hurwitz’s optimistic view of stablecoins, a new Bank for International Settlements (BIS) report challenges the notion that they can serve as money in a modern financial system.

The BIS Annual Economic Report 2025 claims stablecoins fail critical singleness, elasticity, and integrity tests. The organization described stablecoins as “digital bearer instruments” that resemble financial assets more than actual money. 

Tyler Durden
Mon, 06/30/2025 – 10:45

Mysterious Blast Paralyzes Oil Tanker In Mediterranean Weeks After Russian Port Call

Mysterious Blast Paralyzes Oil Tanker In Mediterranean Weeks After Russian Port Call

A mysterious blast struck a tanker carrying 1 million barrels of oil near Libya, and the vessel is now being towed to Greece for damage assessment, according to Bloomberg, citing a statement from the ship’s manager. The incident comes amid growing concerns about attacks on commercial vessels navigating highly contested waters, including the Strait of Hormuz and other key shipping lanes.

The Vilamoura suffered a severe explosion that appears to have led to significant water intake, flooding the tanker’s engine room. The exact cause of the blast—and whether it originated inside or outside the ship—remains unclear. 

Interestingly, Bloomberg compiled ship-tracking data on the Vilamoura’s recent sails, revealing that the tanker visited the Russian port of Ust-Luga in early April, where it loaded Kazakh-origin barrels. It also had a port calling at the Caspian Pipeline Consortium terminal near the Russian port of Novorossiysk in May, which primarily handles Kazakh oil. 

The explosion remains suspicious given the tanker’s recent routes and raises the possibility of a covert allied special forces operation aimed at paralyzing the tanker known for hauling Russian crude. While purely speculative at this stage, the theory is not entirely far-fetched given the ongoing war in Ukraine as European maritime authorities prepare to launch a formal investigation into the incident.

Related maritime news:

.  .  . 

Tyler Durden
Mon, 06/30/2025 – 10:25

3 Goals For Trump’s Trade Negotiations

3 Goals For Trump’s Trade Negotiations

Authored by Adam Millsap viathe American Institute for Economic Research (AIER),

The Trump administration has increased tariff rates on dozens of countries in part to kickstart trade policy negotiations. These tariffs include 10-percent tariffs on dozens of countries, tariffs of over 30 percent on China, 50-percent tariffs on steel and aluminum, and 25-percent tariffs on autos. While the specifics of each negotiation will vary depending on the country’s role in the global economy and its current trade laws, there are three high-level goals relevant to all countries Trump should pursue. If he is successful, these negotiations will make US manufacturers more competitive, keep prices low for consumers, improve America’s ability to confront China, and help reduce the risk of a global trade war.

The US Court of International Trade recently ruled that many of Trump’s tariffs are illegal, but they’ve been allowed to remain in place pending appeal. In the meantime, Trump’s administration is discussing trade policy with several countries. This is wise since keeping the tariffs in place long-term will hurt the US economy. The Penn Wharton Budget Model estimates that Trump’s reciprocal tariff plan would reduce GDP by six percent and wages by five percent if it became permanent. A middle-income household would face a long-term income loss of $22,000. This income loss would offset nearly 15 years of tax savings that the average family receives from the Tax Cuts and Jobs Act, Trump’s signature tax plan from his first term.

The primary goal of Trump’s trade negotiations should be to expand trade by reducing tariff rates and other trade barriers.

Here are three ways his administration could achieve this goal.

  • First, negotiate zero-for-zero tariffs on manufacturing inputs that would remove tariffs on inputs needed by USmanufacturers. These could be modeled on the terms contained in the United States-Mexico-Canada Agreement (USMCA) that expanded access to intermediate inputs for thousands of small and medium-sized US manufacturers, allowing them to expand production and increase jobs for American workers. Agreeing to similar terms with other countries would ensure American manufacturers can get the materials they need to produce high-quality products.

  • Second, negotiate the elimination of non-tariff foreign trade barriers that inhibit US exports, US foreign direct investment, and US electronic commerce. Trade barriers include laws, regulations, policies, and practices—including non-market policies and practices—that distort or undermine competition. Examples include inadequate intellectual property protections, local content requirements, export subsidies, and unnecessary safety or sanitary standards. Country-specific examples that should be reformed are provided annually by the United States Trade Representative in its National Trade Estimate Report on Foreign Trade Barriers.

  • Third, negotiate tougher trade enforcement provisions to prevent China and other countries from evading US trade laws by rerouting exports to the United States through other countries. Countries should agree to allocate more resources to the enforcement of trade laws and verifying the country of origin of the goods that cross their borders. This would protect US consumers and firms from illegal or unsafe goods and help maintain the integrity of the global trade system.

Reducing tariffs on manufacturing inputs, eliminating non-tariff trade barriers, and improving enforcement of US trade laws would help the Trump administration accomplish several of its goals. First, US exports would be more competitive, which would boost manufacturing output and create jobs. Second, the cost of inputs would be reduced, and reciprocal tariff rates could be lowered, which would help keep consumer prices low. Third, by enhancing enforcement of US trade laws, the administration would be better equipped to address China’s objectionable trade policies without unduly inhibiting mutually beneficial trade with friendlier countries.

Nations that close themselves off from the world stagnate and fail. The best known example is China’s inward turn that started in the fifteenth century and lasted until the late twentieth. China missed out on the industrial revolution and by the 1800s it had dramatically fallen behind the West. Today, it is still playing catch-up.

Trump has an opportunity to improve international trade policy and ensure that America plays a leading role in the global economy for decades to come.


Tyler Durden
Mon, 06/30/2025 – 10:10

Key Events This Holiday-Shortened Week: Job Reports Galore, ISMs, Powell And More

Key Events This Holiday-Shortened Week: Job Reports Galore, ISMs, Powell And More

Prepare to be disorientated this holiday shortened week, as payrolls sees a rare Thursday print ahead of the Independence Day holiday on Friday, with both JOLTS and ADP labor reports ahead of the Payrolls report. We also have the US ISMs tomorrow and Wednesday, and the various global PMI numbers from tomorrow which will give us a good guide to global economic momentum in June.

Elsewhere, DB’s Jim Reid notes that a highlight will be the ECB forum in Sintra starting today and the European inflation numbers today and tomorrow. The US tax bill should be finalized this week although at the moment it needs to pass the Senate today (or possibly tomorrow), after a drama filled weekend of horse trading, and then back to the House for final approval. The President wants it done by Friday’s holiday. At that point attention will swiftly focus to the July 9th deadline extension for reciprocal tariffs, but not before we first hear from Powell again tomorrow during the ECB Sintra conclave. Indeed you’ll probably get headlines build up this week and the risk to the market is that with the S&P 500 hitting a new record high at the end of last week, with Treasury yields more becalmed, and with a new tax cutting bill, it’s possible that the Trump Administration feels emboldened to be aggressive again. On Friday the US announced that they were stopping trade talks with Canada in retaliation for their digital service taxes and that new tariffs would be launched within a week. However, overnight Canada has dropped this tax to enable talks to restart. This is perhaps a warning shot for the world. So before next Wednesday a lot of water will flow under the global trade bridge.

Let’s go through a few of the week’s main highlights of the week ahead, but remember the full day-by-day calendar is at the end as usual.

For payrolls, DB expects the headline number (+100k forecast vs. +139k previously) to be slightly below the consensus of +113k, with a similar story for private payrolls (DB +100k, consensus +110k, vs. +140k previously). This would also be below the three-month average of 135k and 133k, respectively. Their rationale is based on 1) initial jobless claims being up 8.8% during the June survey week relative to May; and 2) their observation of a recent pattern of subdued summer payroll gains. They also expect the unemployment rate to edge up a tenth to 4.3% but with the risks skewed to it staying unchanged.

Although 100k on payrolls seems low, economists think the breakeven rate which keeps the unemployment rate steady, is around 100k at the moment and could even be as low as 50k given the Trump Administrations’ migration policies. If correct, we could have a situation where low payroll growth still tightens the labor market. 

Leading up to payrolls we have JOLTS tomorrow, ADP on Wednesday and also watch out for the employment components in today’s Chicago PMI, tomorrow’s manufacturing ISM, and Wednesday’s Services ISM.

In Europe, the big event will be the ECB’s forum on central banking in Sintra running from today through to Wednesday. The policy panel tomorrow will feature heads of the Fed, the ECB, the BoJ, the BoE and the BoK. So plenty of potential headlines there. The ECB will also release its account of the June policy meeting on Thursday and their consumer expectations survey is due tomorrow. Elsewhere in Europe, the BoE will publish its DMP, bank liabilities and credit conditions surveys on Thursday.

In terms of European data, June CPI will continue to be in focus after Friday’s prints for France and Spain showed a slight uptick in inflation. Reports for Germany and Italy are out today, with the Eurozone-wide release scheduled for tomorrow. Swiss inflation data is due on Thursday. We also have May German retail sales (today) and factory orders (Friday), Italian retail sales and French IP on Friday.

In Japan the BoJ’s Q2 Tankan survey results come out tomorrow with our economists forecasting that the business condition index for large manufacturers in the Tankan survey will worsen -3 points to +9. They expect a similar gauge for large non-manufacturers to slip -2 points to +33. This could be one of a few factors that help influence whether the BoJ hikes again in July, although there’s lots of moving parts at the moment including trade agreements with the US.

Courtesy of DB, here is a day-by-day calendar of events

Monday June 30

  • Data: US June MNI Chicago PMI, Dallas Fed manufacturing activity, China June official PMIs, UK June Lloyds Business Barometer, May net consumer credit, M4, Q1 current account balance, Japan May industrial production, housing starts, Germany June CPI, May retail sales, import price index, Italy June CPI, Eurozone May M3
  • Central banks: ECB’s forum on central banking in Sintra (through July 2), Lagarde speaks, Fed’s Bostic and Goolsbee speak

Tuesday July 1

  • Data: US June ISM index, Dallas Fed services activity, total vehicle sales, May JOLTS report, construction spending, China June Caixin manufacturing PMI, Japan Q2 Tankan survey, June consumer confidence index, Germany June unemployment claims rate, Italy June manufacturing PMI, new car registrations, budget balance, Eurozone June CPI
  • Central banks: A policy panel at ECB’s forum in Sintra featuring Fed’s Chair Powell, ECB’s President Lagarde, BoJ’s Governor Ueda and BoE’s Governor Bailey, ECB’s Guindos, Elderson and Schnabel speak, ECB’s May consumer expectations survey

Wednesday July 2

  • Data: US June ADP report, Japan June monetary base, France May budget balance, Italy May unemployment rate, Eurozone May unemployment rate, Canada June manufacturing PMI
  • Central banks: ECB’s Lagarde, Guindos, Cipollone and Lane speak, BoE’s Taylor speaks

Thursday July 3

  • Data: US June jobs report, ISM services, May trade balance, factory orders, initial jobless claims, China June Caixin services PMI, UK June official reserve changes, Italy June services PMI, Canada May international merchandise trade, Switzerland June CPI
  • Central banks: ECB’s account of the June meeting, Fed’s Bostic speaks, BoJ’s Takata speaks, BoE’s June DMP, Q2 bank liabilities and credit conditions surveys

Friday July 4

  • Data: UK June new car registrations, construction PMI, Japan May household spending, Germany June construction PMI, May factory orders, France May industrial production, Italy May retail sales, Eurozone May PPI
  • Central banks: ECB’s Villeroy speaks, BoE’s Taylor speaks
  • Other: US Independence Day

* * * 

Finally, turning to the US, Goldman writes that the key economic data release this week is the employment report on Thursday. There are a few speaking engagements by Fed officials this week, including Chair Powell on Tuesday. 

Monday, June 30 

  • 09:45 AM Chicago PMI, June (consensus 42.9, last 40.5)
  • 10:00 AM Atlanta Fed President Bostic (FOMC non-voter) speaks: Atlanta Fed President Raphael Bostic will speak on the US economic outlook during an event hosted by MNI Connect. Q&A is expected. On June 24, Bostic told Reuters he thinks a single rate cut of a quarter point is warranted this year and that the last quarter of the year “is sort of when [he] would expected we would know enough to move [the funds rate].”
  • 01:00 PM Chicago Fed President Goolsbee (FOMC voter) speaks: Chicago Fed President Austan Goolsbee will speak in a moderated Q&A at the 2025 Aspen Ideas Festival in Aspen, Colorado. On June 23, Goolsbee said, “Somewhat surprisingly, thus far, the impact of tariffs has not been what people feared.” He went on to say that “If we don’t see inflation resulting from these tariff increases, then, in my mind, we never left what I was calling the golden path before April 2.”

Tuesday, July 1 

  • 09:45 AM S&P Global US manufacturing PMI, June final (consensus 52.0, last 52.0)
  • 10:00 AM ISM manufacturing index, June (GS 49.0, consensus 48.7, last 48.5): We estimate the ISM manufacturing index rebounded by 0.5pt to 49.0 in June, reflecting mixed manufacturing surveys so far for the month (GS manufacturing survey tracker -0.2pt to 49.1) but a tailwind from potential residual seasonality.
  • 10:00 AM Construction spending, May (GS -0.2%, consensus -0.2%, last -0.4%)
  • 10:00 AM JOLTS job openings, May (GS 7,300k, consensus 7,300k, last 7,391k): We estimate that JOLTS job openings edged down to 7.3mn in May based on the signal from online job postings.
  • 01:00 PM Fed Chair Powell speaks: Fed Chair Jerome Powell will participate in a panel discussion with Bank of England Governor Andrew Bailey, European Central Bank President Christine Lagarde, Bank of Japan Governor Kazuo Ueda, and Bank of Korea Governor Chang Yong Rhee. Q&A is expected. In his prepared remarks before the House Financial Services Committee, Powell reiterated that the FOMC was “well positioned to wait to learn more about the likely course of the economy before considering any adjustments to our policy stance.” When asked whether the FOMC could cut rates in July, Powell noted that “he wouldn’t want to point to a particular meeting” for the first cut and that he didn’t think the FOMC needed “to be in any rush because the economy is still strong, and the labor market is strong.”
  • 05:00 PM Lightweight motor vehicle sales, June (GS 15.0mn, consensus 15.35mn, last 15.65mn)

Wednesday, July 2 

  • 08:15 AM ADP employment change, June (GS +80k, consensus +90k, last +37k)

Thursday, July 3 

  • 08:30 AM Trade balance, May (GS -$75.0bn, consensus -$71.1bn, last -$61.6bn); We estimate that the trade deficit rose from $61.6bn in April to $75.0bn in May, reflecting declines in goods exports and travel exports offset by a modest increase in financial services exports.
  • 08:30 AM Nonfarm payroll employment, June (GS +85k, consensus +113k, last +139k); Private payroll employment, June (GS +85k, consensus +110k, last +140k); Average hourly earnings (MoM), June (GS +0.3%, consensus +0.3%, last +0.4%); Unemployment rate, June (GS 4.3%, consensus 4.3%, last 4.3%): We estimate nonfarm payrolls rose 85k in June. On the positive side, the end of worker strikes will provide a 6k boost. On the negative side, big data indicators indicated a weaker pace of job creation, we assume a 25k drag from the termination of Temporary Protected Status for approximately 350k Venezuelan migrants in mid-May, and we expect roughly unchanged government payrolls (GS forecast 0k vs. 7k on average so far this year), reflecting a 15k decline in federal government payrolls that offsets a 15k increase in state and local government payrolls. We estimate that the unemployment rate edged up to 4.3% on a rounded basis—a low bar from an unrounded 4.24%—reflecting sequential increases in other measures of labor market slack. We estimate average hourly earnings rose 0.3% (month-over-month, seasonally adjusted), reflecting neutral calendar effects.
  • 08:30 AM Initial jobless claims, week ended June 28 (GS 240k, consensus 241k, last 236k); Continuing jobless claims, week ended June 21 (consensus 1,950k, last 1,974k)
  • 09:45 AM S&P Global US services PMI, June final (consensus 53.1, last 53.1)
  • 10:00 AM Factory orders, May (GS +7.8%, consensus +8.1%, last -3.7%):  Factory orders ex-transportation, May (last -0.5%); Durable goods orders, May final (last +16.4%); Durable goods orders ex-transportation, May final (last +0.5%); Core capital goods orders, May final (last +1.7%); Core capital goods shipments, May final (last +0.5%): We forecast that factory orders rose 7.8% in May, reflecting a sharp increase in nondefense aircraft and parts.
  • 10:00 AM ISM services index, June (GS 51.0, consensus 50.6, last 49.9): We estimate that the ISM services index increased by 1.1pt to 51.0 in June, reflecting sequential improvement in our non-manufacturing survey tracker (+0.5pt to 50.8 in June) and a tailwind from potential residual seasonality.
  • 11:00 AM Atlanta Fed President Bostic (FOMC non-voter) speaks: Atlanta Fed President Raphael Bostic will speak on monetary policy at the IMFS Distinguished Lecture Series in Frankfurt. Speech text and Q&A are expected. 

Friday, July 4 

  • US Independence Day holiday. NYSE will be closed, SIFMA recommends bond markets remain closed, and there are no major economic data releases scheduled.

Source: DB, Goldman

Tyler Durden
Mon, 06/30/2025 – 10:00

9 Underage Girls Sexually Abused By Syrians At Swimming Pool, Mayor Points To ‘Hot Weather’

9 Underage Girls Sexually Abused By Syrians At Swimming Pool, Mayor Points To ‘Hot Weather’

Via Remix News,

After underage girls were sexually assaulted in the Barbarossabad swimming pool in Gelnhausen, the CDU mayor of the area pointed out that “hot weather” makes tempers “fray.”

However, local Mayor Christian Litzinge (CDU) appeared to allude that the weather is at least partly to blame for the incident.

In a statement to Welt, he said: “Of course, it’s always high temperatures, and sometimes tempers are frayed.”

In a separate interview with Bild, he said, “We have zero tolerance for that.”

As Remix News previously reported, the first group of girls were groped and molested by the group of Syrians, but when they complained to a lifeguard, he took no action.

“Since we couldn’t see exactly what had happened, we sent the girls back into the water,” pool manager Nils Tischer explained to Hessischer Rundfunk.

It was only after more girls made a complaint from separate groups that the police were called.

In total, at least nine girls came forward, ranging in age from 11 to 17.

The girls told authorities that the four Syrians, aged 18 to 28, groped them in the lazy river, feeling them all over their bodies, including their genitals. A fifth suspect managed to escape, and police are still looking for him.

According to Mayor Christian Litzinger (CDU), all four suspects are from the same family in the Main-Kinzig district.

They were all arrested and charged, in addition to receiving a ban from the outdoor pool.

Alice Weidel, the Alternative for Germany (AfD) co-leader, also posted about the incident on social media, calling for “immediate deportations” in the case.

Attempts to downplay the problems in German swimming pools

Litzinger’s comments echo some other “excuses” offered for sexual violence and assaults from migrants at Germany’s once peaceful swimming pools. An article in 2023 from Zeit attempted to claim that much of the violence and sexual assaults were due to rising French fry prices.

At the time, Alice Weidel, co-leader of the Alternative for Germany (AfD), criticized the claim.

“Zeit blames ‘French fry prices’ for violence and sexual assaults in outdoor pools, ZDF claims an interplay of heat and the meeting of many people, Deutschlandfunk writes about too high ‘expectations’ that cannot be met. The degree to which the media trivializes migration problems no longer knows any limits,” wrote Alice Weidel, parliamentary leader of the AfD party.

Just a week before that statement, the actual workers at the swimming pools offered an entirely different reason for the increasing violence. Employees of the Columbiabad outdoor swimming complex in Berlin penned a letter to the Der Tagesspiegel newspaper complaining about perpetrators they describe as “mainly Arab migrants and Chechens” who are engaging in the sexual harassment of women and mass brawls on the premises, while also leaving the complexes in disgusting conditions. As a result, the entire pool was shut down for an indefinite period of time due to workers calling out sick from stress.

Remix News has long reported on the growing crime trend in German swimming pools, including mass brawls and sexual assaults, as well as attacks on police, security officials and even lifeguards working at the pools.

In 2022, Remix News covered how the president of the Federal Association of German Swimming Champions (BDS), Peter Harzheim, said he can no longer recommend that families visit such facilities on weekends. Harzheim claimed he would be “acting irresponsibly” if he attended an outdoor pool with his own three grandchildren due to violence and assaults, which the Remix News article details.

Some individuals have been seriously injured. Last year, for example, a woman had her nose broken when she was caught in the middle of a mass brawl involving foreigners.

In 2023, Welt released a popular video documentary detailing how “macho culture” from migrants was turning the swimming pools in Germany upside down.

Columbiadamm swimming pool in the multicultural neighborhood of Neukölln, Berlin, was closed down due to over 40 warring youths. Welt lays the blame squarely at the feet of “macho culture” from immigrant youth. In Pankow, a swimming pool had to be shut down twice in one week due to mass brawls between young people.

In the German city of Celle, 20 “rampaging youth” attacked swimmers and sexually assaulted them, including beating one female who rejected their advances. When lifeguards attempted to stop them, they threatened them as well. As a result, the entire swimming pool was shut down.

Read more here…

Tyler Durden
Mon, 06/30/2025 – 09:25

Top Iranian Cleric Issues Fatwah Calling For All Muslims To Seek Vengeance On US, Israel

Top Iranian Cleric Issues Fatwah Calling For All Muslims To Seek Vengeance On US, Israel

In a new fatwah which appears clearly aimed at the United States, Israel, and their respective leaders Donald Trump and Benjamin Netanyahu, a top Iranian Shia cleric has called on Muslims to take vengeance as Islamic ‘warriors’.

Ayatollah Naser Makarem Shirazi, a longtime prominent Shia religious authority, said in the new edict that any individual or government that threatens or assaults the the leaders of the Islamic Republic of Iran, and the Shia nation’s religious authority in an effort to harm the ‘Islamic Ummah’ and its governance is considered an enemy of Islam, or one who wages war against God.

Ayatollah Makarem Shirazi

Grand Ayatollah Makarem was reportedly responding in the edict to question put forward by his followers is as follows:

“Any person or regime that threatens the Leader or Marja (May God forbid) is considered an enemy of God,” Grand Ayatollah Makarem said in his Fatwa, according to Iranian state media.

His rank and authority within the Iranian religious establishment is at the highest level for a Twelver Shia religious cleric, under the Supreme Leader.

He added according to a translation that “any cooperation or support for that enemy by Muslims or Islamic states is haram or forbidden. It is necessary for all Muslims around the world to make these enemies regret their words and mistakes.”

He also described that if a Muslim who “does his duty suffers hardship or loss in their campaign, they will be rewarded a fighter in the way of God, God willing.”

While he didn’t specifically mention US President Trump in his fatwah, this is precisely how some are taking it.

The White House has already alleged there was a prior plot to assassinate Trump, in a case last year; however, Supreme Ayatollah Ali Khamenei has never actually directly called for the American leader’s death. But likely, more minor clerics within Iran have done so.

This past week Trump directed a series of Truth Social messages at the Khamenei. For example, he said “Look, you’re a man of great faith. A man who’s highly respected in his country. You have to tell the truth.” Trump then told Khamenei: “You got beat to hell.” This was of course in reference to the major B-2 bombing raids on Iran’s nuclear facilities.

Tyler Durden
Mon, 06/30/2025 – 09:05

Can Oil And Gas Solve The AI Power Dilemma

Can Oil And Gas Solve The AI Power Dilemma

Authored by Joe Brettell via UtilityDive.com,

The promise, peril and possibilities of artificial intelligence continue to capture the cultural and business zeitgeist worldwide. Hardly a conference or long-form interview can be held these days without a panelist or pundit commenting on the technology’s implications for their profession.

Yet despite being the hottest topic in every circle, AI’s ultimate challenge isn’t technological but physical. After years of breathless speculation and prediction, the issue remains the same: AI needs more energy.

Data center power consumption

Source: McKinsey

Amidst this backdrop, the oil and gas industry faces a similarly fundamental challenge: a shifting production frontier and evolving path to continued growth. After a decade of efficiency-driven growth, the era of easy barrels is waning. Diamondback Energy CEO Travis Stice captured the new reality in a recent letter, warning of the increasingly dim prospects for expanding production amid geological constraints and rising costs. Other energy majors have issued similar cautions, a sharp departure from the boom years of the shale revolution when abundant, low-cost reserves, followed by shareholder-focused production, made the industry a market favorite.

Now, with resource intensity rising, global volatility accelerating and economic conditions tightening, the industry is under pressure to find its next value horizon.

That horizon may be converging with AI.

The pairing makes increasing sense. While initially circling one another warily, major players in energy and technology have become increasingly intertwined. At major gatherings like CERAWeek, energy executives and tech leaders now share the same stage — and increasingly, the same strategic questions. How do we scale the infrastructure to match exponential AI growth? Who will supply the energy to power it? And how do we do so fast enough while dealing with rising environmental, social and regulatory concerns?

These challenges come amid a stark reality: AI’s computational appetite isn’t just increasing — it’s exploding. Several recent studies demonstrate that power demand will soar by the end of the decade, presenting real challenges for utilities and their customers who are already grappling with rising costs.  

That creates both a dilemma and an opportunity. As federal and state incentives for clean energy projects face legal and political headwinds — even amid substantial private investment — the timeline to deliver renewable power at scale is getting longer. Grid interconnection queues, permitting delays and community opposition remain real barriers. At the same time, nuclear and geothermal technologies hold promise, but even under the best-case scenarios, their rollout will take years to materially shift supply.

Which brings us (again) to the topic of natural gas.

Few would dispute that a diverse portfolio of renewables, firm power, storage, nuclear and emerging technologies must meet long-term AI energy needs. But without a tectonic shift, an “all of the above” solution is no longer the political reality.  Natural gas is abundant, dispatchable, and backed by a sector with proven experience in infrastructure delivery, supply chain integration and stakeholder engagement.

Granted, natural gas has its share of controversies. Building new pipelines has become increasingly complex, with communities hostile to natural gas infrastructure and deployment nationwide. Yet, despite these challenges, Exxon and Chevron have already announced serious interest in powering data centers. This partnership is not simply one of convenience but of practicality. It is not about reviving old debates but utilizing practical solutions to solve deeper issues for two pillars of the American economy.

The bottom line is that natural gas offers a workable solution for technology companies racing to deploy AI capabilities and energy companies looking to maintain shareholder value amidst a transitional time in the sector. With nuclear and geothermal both gaining political and investment momentum, gas is unlikely to be a permanent panacea but a critical bridge across a widening gap (yes, the old “bridge fuel” talking point is yet again en vogue).

This convergence between oil, technology, and ultimately, utilities isn’t simply a tactical alignment of convenience; instead, there’s a more profound structural shift — energy and compute are no longer parallel industries but mutually dependent pillars of modern innovation.  If you need evidence, look no further than the recent announcement that Open AI and the United Arab Emirates will open a massive new data center in the country by 2026. Even traditional oil powers are hedging their bet and looking to participate in the changes AI will bring.

However, amidst the race to satisfy shareholders, inventors and policymakers, both industries would do well to remember customers. With concern about AI technology continuing to linger and economic challenges only growing, the political and social environment is ripe for a full-throated pushback from households already frustrated by rising energy bills, service disruptions and increasing skepticism toward unchecked tech expansion in their communities and states.  

Many companies are already making significant strides on this front, with investment in local communities, building dialogue, relationships and trust. Yet just as AI’s technological promise can be limited by something practical like where to plug it in, this growing union between energy and technology sectors can be thwarted by unhappy voters. 

Ultimately, the moment demands coordination and innovation, not competition. Only with pragmatic collaboration between energy developers of all kinds, grid operators and the communities where they operate can we build an energy strategy as dynamic as the technology it supports. In the end, like those paradigm-shifting endeavors, the future of AI won’t be decided by what’s possible in silicon. It will be determined by what’s deliverable in steel, concrete and kilowatt-hours.

Tyler Durden
Mon, 06/30/2025 – 06:30

A Third Of American Households Are Over-Burdened By Housing Costs

A Third Of American Households Are Over-Burdened By Housing Costs

U.S. Census data analyzed by Harvard University shows that a third of all U.S. households, whether they are buying or renting, spend more than the recommended one third of their income on housing and utilities and therefore qualify as cost-burdened.

While the overall rate of households burdened by housing cost in the U.S. was 32.7 percent in 2023, Statista’s Katharina Buchholz shows in the chart below, several states had even higher average burdens.

Infographic: A Third of U.S. Burdened by Housing Cost | Statista

You will find more infographics at Statista

California, known for its high cost of living, came in at 41.7 percent of burdened households, followed by Hawaii at 39.5 percent, Florida at 38.6 percent and New York at 38.2 percent.

In general, West Coast states and those in the country’s populous Northeast showed the highest burdens, with the addition of sunshine locations Florida and Hawaii.

The least burdened households were found in the interior of the country, in West Virginia, North Dakota and Iowa, where fewer than a quarter of households felt an outsized financial burden because of housing costs. Colorado and Texas came in 11th and 12th.

The report published this week shows that renters are more often overburdened by their costs that homeowners, but that the gap has been closing in recent years.

Before and after the Great Recession, homeowners were still more overburdened than renters in the country, but this equilibrium changed in 2012 when renters began to be burdened more by rising rent costs while homeowners were profiting from zero interest rates.

With the end of the no-interest era in 2022, homeowners’ burden jumped up, while the economic hardships of the inflation crisis affected both types of households.

The researchers also identified higher insurance premiums and property taxes as an issue for homeowners, while saying that more than half of renters were spending more than 50 percent of household income on renting in 50 out of the 100 largest metro areas in the United States.

Tyler Durden
Mon, 06/30/2025 – 05:45

J.K. Rowling Destroyed Trans Ideology With One Savage Tweet

J.K. Rowling Destroyed Trans Ideology With One Savage Tweet

Authored by Matt Margolis via PJMedia.com,

Famed “Harry Potter” author J.K. Rowling became a vocal critic of transgender ideology back in 2019, when she supported a woman who lost her job for saying that biological sex is immutable. In 2020, Rowling’s tweets and essay argued that prioritizing “gender identity” over biological sex threatens women’s rights and safety, drawing from her experience as an abuse survivor. She faced fierce backlash, was branded a “TERF” by activists, and even endured death threats, but stood firm.

Rowling’s stance has only grown more defiant as she continues to call out the bullying tactics of trans activism and the erasure of women. Despite relentless attacks from activists, media outlets, and even cast members from “Harry Potter,” her unapologetic wit and unwavering resolve have made her a leading voice of resistance against a radical ideology that silences dissent. This week, she once again proved why she remains a formidable force in the culture war over gender, giving courage to countless women who’ve been too afraid to speak out.

Apparently some people have been attacking Rowling by saying she looks like a “trans woman.” Her response to such attacks says it all:

Talk about a masterclass in rhetorical jiu-jitsu. She takes the intended insult of her critics and flips it right back on them, exposing the hypocrisy at the heart of so much of the pro-trans activist rhetoric.

Rowling’s critics, who claim to be the champions of tolerance and inclusion, routinely stoop to personal attacks and misogynistic insults whenever a woman dares to challenge their orthodoxy. The latest trend is to hurl accusations that Rowling “looks like a trans woman,” a jab that is supposed to be both an insult to her and a defense of trans women. But Rowling, with her trademark wit and clarity, called their bluff. 

She pointed out the obvious: If you’re accusing someone of looking like “trans woman” in the pejorative sense, you’re essentially admitting what most people already know: that “trans women” don’t look like real women. Let’s face it, men can grow out their hair, get breast implants, and take whatever drugs they want, but everyone knows what they really are. Calling Richard “Rachel” Levine a woman doesn’t make him a woman. Using female pronouns to refer to Bruce “Caitlyn” Jenner doesn’t change the fact that he is a man. Letting Will “Lia” Thomas compete against real women doesn’t erase what he is.

Rowling refuses to apologize, refuses to play by the ever-changing rules of the woke mob, and instead shines a spotlight on the contradictions baked into their rhetoric, like how calling someone a “trans woman” is supposedly empowering until it’s used as a slur. Her wit, clarity, and refusal to back down force her critics to confront the ugliness of their tactics.

Through years of smears, threats, and public pressure campaigns, Rowling has stood firm, using every attack as an opportunity to expose the movement’s double standards and moral incoherence. In an era when most public figures wilt under pressure, she’s become a symbol of courage for women everywhere who are tired of being silenced. She’s not just defending herself; she’s defending reality, and doing it with a fearlessness that leaves her critics sputtering.

Just because trans activists demand that we all pretend that men who grow their hair out and play dress up are women doesn’t mean that the rest of us have to play along. And when those same activists who have spent years lobbing insults and even death threats at Rowling try to mock her by saying she “looks like a trans woman,” they don’t expose her bigotry; they expose their own hypocrisy. If comparing her to a “trans woman” is meant as an insult, then it’s not Rowling degrading “trans women”; it’s the so-called allies who use the comparison as a punchline. In doing so, they don’t validate their ideology; they reinforce the biological truth they insist everyone ignore.

The attacks on J.K. Rowling reveal just how desperate the radical left has become to crush dissent. 

Tyler Durden
Mon, 06/30/2025 – 05:00
