CEO Of Largest U.S. Foodservice Distributor Warns Consumer Sentiment, Confidence “Not High Right Now”
The CEO of Sysco, the largest foodservice distributor in the U.S., serving nearly 20% of the nation’s restaurants and commercial kitchens, issued a warning on Tuesday: Consumer sentiment and confidence remain lackluster.
CEO Kevin Hourican spoke with Bloomberg during an interview after the foodservice distributor reported earnings and forecasted annual sales at the lower end of its target range.
Hourican noted that consumer sentiment and confidence “is not high right now.”
Sysco expects sales growth of about 3% to 5% in fiscal 2026, less than the three-year sales growth target of 4% to 6% it forecasted last year.
Sysco serves over 700,000 customer locations, giving it unparalleled visibility into the health of America’s restaurants and commercial kitchens. Its massive scale and nationwide reach make it a barometer for consumer behavior across the entire foodservice industry.
For more U.S. restaurant trends, a team of Goldman Sachs analysts led by Christine Cho posted a note for clients on Tuesday that showed Net Purchase Intent over time for three restaurant subsectors: Fast Casual, Casual Dining, and Fast Food, based on trailing 3-month averages (T3M).
Takeaways:
Shift in preferences: Consumers are pivoting from fast casual to casual dining, possibly seeking a fuller dining experience or better value amid inflation.
Fast casual sentiment is weakening, despite historically being the leader in restaurant trends.
Fast food remains under pressure, with the lowest consumer intent scores across the board.
Bessent Unleashes Treasury Buyback Overhaul In Major Step To Yield Curve Control, Doubles Down On Bill Dominance
In today’s closely watched Quarterly Refunding Announcement on debt issuance – which to many was more important than the FOMC statement – the Treasury Department said at 8:30am ET that that it anticipates keeping the size of its note and bond auctions unchanged “for at least the next several quarters.” And since that was the same guidance the Treasury has given since the start of last year, it leaves bills, which were the fulcrum security of Janet Yellen’s Activist Treasury Issuance strategy so repeatedly penned by Scott Bessent, once again bearing the brunt of the government’s rising borrowing needs, although as the charts of Bill and Coupon issuance below show, the US is already pretty much at 10…. so these better go to 11.
This means that the Treasury will rely more on the shortest-dated securities to fund the gaping federal deficit at least until 2026, after Treasury Secretary Bessent said last month that yields on longer-dated Treasuries were too high to consider boosting sales of such debt. In doing so he is implicitly endorsing the same strategy that he slammed when it took place under Janet Yellen.
As we noted in our QRA preview, and as Bloomberg notes, Wall Street had varying views on what guidance the Treasury would provide. Wells Fargo expected a reiteration of the previous language. JPMorgan strategists said officials “perhaps” might lop off the “at least” qualification for the coming several quarters, while Stephen Stanley at Santander US Capital Markets said his best guess was the entire removal of the guidance.
In the end this is what the Treasury did say:
“Treasury believes its current auction sizes leave it well positioned to address potential changes to the fiscal outlook and to the pace and duration of future SOMA redemptions. Based on current projected borrowing needs, Treasury anticipates maintaining nominal coupon and FRN auction sizes for at least the next several quarters.”
Which is nothing more than can kicking: “The longer debt managers wait to get started, the more difficult the job becomes” of preparing markets for bigger sales of interest-bearing debt, or coupons, Santander’s Stanley wrote before the Wednesday announcement.
Turning to the actual refunding, as widely expected by dealers, the Treasury maintained the size of next week’s quarterly refunding auctions, which span 3-, 10- and 30-year maturities. Specifically, the Treasury will offer $125 billion of Treasury securities to refund approximately $89.8 billion of privately-held Treasury notes and bonds maturing on August 15, 2025, both in line with estimates, and raising new cash of about $35.2 billion. The composition is as follows:
3-year note in the amount of $58 billion, maturing August 15, 2028
10-year note in the amount of $42 billion, maturing August 15, 2035
30-year bond in the amount of $25 billion, maturing August 15, 2055
The table below presents the actual auction sizes for the May to July 2025 quarter and the anticipated auction sizes for the August to October 2025 quarter. As one can see, the 3, 10 and 30Yr issuance sizes are identical as during the last refunding in May of 2025.
The Treasury also said it was continuing to nudge sales of some Treasury Inflation-Protected Securities, or TIPS, higher in order to keep their share of the overall Treasury market stable. It announced the following adjustments:
A bump up of the September 10-year TIPS reopening auction to $19 billion
An increase of the October 5-year new issue TIPS auction to $26 billion
And since there was no surprise in the coupon issuance schedule, it means Bills will once again have to step up and fund the balance. As the Treasury wrote, “since the $5 trillion increase to the debt limit on July 4, Treasury has increased bill issuance to continue to finance the government and to gradually rebuild the cash balance over time to a level more consistent with its cash balance policy.” As previously noted, Treasury anticipates that the cash balance will approach levels consistent with its policy in September. Accordingly, “Treasury anticipates further marginal increases in short-dated Treasury bill auction sizes in the coming days and then maintaining sizes at or near those levels through the end of September. Additional increases to Treasury bill auction sizes are anticipated in October. Treasury will carefully monitor market conditions and adjust its bill issuance plans as appropriate.”
Bessent had been among the most Republicans to criticize former Treasury Secretary Janet Yellen last year for artificially holding down sales of longer-term debt, saying it was an attempt to keep borrowing costs low before the election. And while Bills made up about 20% of the Treasuries market at the end of June, the ratio is now set to climb in the coming months as the Treasury continues to refrain from increasing note and bond issuance. The Treasury Borrowing Advisory Committee, an outside panel made up of dealers, investors and other market participants, last year recommended that bills average about 20% of total outstanding Treasuries over time.
Relying just on bills to fund the deficit would at some point make the ratio of those securities so large that it would introduce sharp volatility in the Treasury’s financing costs. It would also potentially force the department to set aside a bigger stockpile of cash in case of challenges in rolling over maturing bills on any given day.
For now, strategists say there’s ample demand for bills. Money-market funds are expected to keep growing, giving them the capacity to absorb part of the additional bill supply if those securities make up a bigger share of debt, according to Morgan Stanley strategists. The Fed may also emerge as a bigger buyer of bills as policymakers begin to discuss whether to tilt their bond portfolio toward shorter-duration securities. And Bessent has repeatedly pointed to stablecoins as a fresh source of demand. That’s right: very soon Tether will become just as important as the Fed when it comes to funding the US government.
Translation: expect a very, very front-end loaded Treasury curve, one which will be funded by stablecoin issuers and which will be at the whim of the Fed for short-term funding costs. Whatever can possibly go wrong.
But (re)funding schedules aside, which as noted were a snoozer, the most consequential aspect of today’s Quarterly Refunding was how the Treasury’s buyback program will be changed. As readers will recall, ahead of today’s refunding announcement, we said that Goldman was expecting a 50-100% increase in Treasury buybacks and said that “Calling this “shadow QE” is definitely a bridge too far…but it might on a path that leads to that bridge.”
Goldman expects a 50-100% increase in Treasury buybacks announced in today’s QRA. Says “Calling this “shadow QE” is definitely a bridge too far…but it might on a path that leads to that bridge.”
That’s more or less what happened, because in the biggest news of the day, the department unveiled plans to beef up its program of buying back older securities, bringing that initiative to an annual target in excess of $300 billion.
The Treasury said it would double the frequency of long-end operations, boosting the liquidity support cap from $30 billion to $38 billion per quarter, and opening the door to broader market access through direct offers from a limited set of counterparties starting in 2026.
This change to buybacks is not a marginal tweak — it’s a structural shift aimed at injecting flexibility and smoothing market functioning as Treasury debt issuance ramps higher; and while nobody will ever admit it, it is also a shadow QE meant to prop up the long end in case the Fed refuses to step in similar to what happened in April.
Describing the changes to the buyback program meant “to better achieve its liquidity support and cash management goals”, the Treasury said that based on feedback from a wide range of market participants, including the primary dealers and the Treasury Borrowing Advisory Committee, Treasury believes it is appropriate to:
Double the frequency of long-end nominal coupon liquidity support buybacks: Changes involved will boost the aggregate size of liquidity-support buybacks to a maximum par amount of $38 billion per quarter from $30 billion
Increase the size of cash management buybacks: Ramping up the cash-management buybacks to a maximum par amount of $150 billion per year from $120 billion
Make a technical adjustment to the TIPS buyback buckets: i) There will now be two operations per quarter of up to $750 million of 1- to 10-year TIPS buybacks; ii) There will be one operation per quarter of up to $500 million of 10- to 30-year TIPS
Allow a limited number of additional counterparties to directly access buyback operations. I.e., spread the “NOT STEALTH QE” wealth.
These changes will be effective August 13, 2025 and are reflected in the tentative buyback schedule for the upcoming refunding quarter.
So what is really going on here? Well, recall that in April, just as yields exploded higher after Liberation Day, Powell appears on BBG TV and said that if the Fed does nothing, the Treasury has a “big toolkit” and could “up the Treasury buybacks” (to prop up Treasuries, in lieu of QE).
Must watch interview: Bessent reveals he has breakfast with Powell every week, and also reveals that if the Fed does nothing, the Treasury has a “big toolkit” and could “up the Treasury buybacks” (to prop up Treasuries, in lieu of QE). https://t.co/XX24GkV9Ruhttps://t.co/iABbJiYXVG
Which of course is another way of saying that the Fed and Treasury are once again planning on “merging” and that Yield Curve Control – which requires a consolidated Fed/Treasury – is coming.
Oi prices were steady early on Wednesday, rising for a third session even as API reported an unexpected rise in US crude inventories.
Oil prices have been supported by U.S. threats to impose secondary sanctions of buyers of Russian oil after U.S. President Donald Trump this week cut his deadline for Russia to reach a ceasefire in its war on Ukraine from 50 days to 10 to 12 days.
“Displaying frustration with the lack of tangible progress in peace talks between Russia and Ukraine, the US President has shortened his ultimatum for the aggressor from 50 days to 10-12. The prevailing assumption is that, after this period, new sanctions, including measures targeting Russia’s energy sector, will be introduced … The geopolitical risk surrounding key oil-producing regions has therefore risen,” PVM Oil Associates noted.
Still, the geopolitical risk is countered by rising supply. With Western hemisphere production also increasing, OPEC+ is returning 2.2-million barrels per day of production cuts to market in monthly tranches that began in May, with the full return expected to be complete in September.
The question for traders this morning is simple – will the official data confirm API?
API
Crude +1.54mm (-2.5mm exp)
Cushing
Gasoline -1.74mm
Distillates +4.18mm
DOE
Crude +7.698mm – biggest build since January
Cushing
Gasoline
Distillates
Against expectations of a small drawdown, the official data showed a large build in crude stocks last week (the biggest since January and far bigger than the API-reported level). Cushing stocks rose for the fourth week in a row while gasoline inventories fell for the third week in a row…
Source: Bloomberg
The Trump admin added 238k barrels to the SPR last weekj (after two weeks of drawdowns), adding to the largest rise in commercial crude stocks since January
Source: Bloomberg
Despite the ongoing plunge in the rig count, US crude production remains near record highs…
Source: Bloomberg
WTI Crude was largely unmoved by the DOE data coming slightly off the highs of the day…
“President Trump’s patience with Russia seems to be wearing thin, and oil markets have reacted somewhat to the prospect of a potential supply disruption,” Barclays analyst Amarpreet Singh said.
“We recognize the upside risks from a potential binary outcome, but caution against assigning too high of a probability to it.”
Oil is on track for a third monthly gain, and markets also remain focused on the US deadline to nail down trade deals by Aug. 1, and the OPEC+ meeting over the weekend that will decide supply for September.
Traders expect the group to agree on another bumper increase to crude production.
US, UK In Secret Talks With Ukrainian Officials To ‘Replace Zelensky’: Russian Intelligence Claims
Russia’s Foreign Intelligence Service (SVR) has claimed in a new statement published by TASS state news agency that US and British officials recently met with senior Ukrainian figures in an undisclosed Alpine resort in Europe to discuss the possible replacement of President Volodymyr Zelensky.
The meeting allegedly included top Ukrainian officials such as Andrey Yermak, head of the presidential office; Kirill Budanov, head of Ukraine’s military intelligence; and Valery Zaluzhny, the former commander-in-chief now serving as Ukraine’s ambassador to the UK.
Given the high stature of these individuals, this is a massive claim, and it could be that Russian intelligence is is releasing such a report – even if unverified and/or possibly untrue – in order to sow discord, suspicion and paranoia within the Ukrainian presidency’s office. But some recent independent reports in the West have also pointed to a key former top general being groomed as a potential successor.
TASS reports that the Western representatives at the meeting proposed Valery Zaluzhny as Zelensky’s potential successor. He had long been Ukraine’s most visible and celebrated general, as the Commander-in-Chief of the Armed Forces of Ukraine from 2021 until his controversial dismissal by Zelensky in 2024.
His dismissal from the top command post over the armed forces to now serve as Ambassador of Ukraine to the United Kingdom was widely seen as in effect a political exile of sorts.
The SVR and state media are claiming further that Yermak and Budanov accepted the US-UK proposal, securing assurances that they would retain their current roles and have influence over future appointments if Zaluzhny took power.
At the moment the European Union has made the unprecedented threat to cut off funding to Kiev, after Zelensky moved to undermine Ukraine’s anti-corruption institutions, which was formalized in a law Zelensky signed this month.
President Trump has clearly been putting immense pressure on the Russian side after the latest round of failed talks in Istanbul, giving Putin just ten days to show serious progress toward negotiating peace – but could the same level of pressure now be on Zelensky behind the scenes?
The new claims out of Russian intelligence might not entirely be without merit, given recently legendary American journalist Seymour Hersh wrote an article titled The End of Zelensky?
The main thesis was that Zaluzhny is now seen by Washington insiders as the most credible successor to Zelensky, as seen in Hersh’s introduction to the July 18 story below:
In fall of 2023, Ukrainian General Valerii Zaluzhnyi, the commander in chief of the country’s armed forces, gave an interview to the Economist and declared the war with Russia had become a “stalemate.” It took three months for President Volodymyr Zelensky to fire him. The general, who is the most popular public figure in Ukraine, was named ambassador to London a month later and has served there with distinction, if quietly.
Zaluzhnyi is now seen as the most credible successor to Zelensky. I have been told by knowledgeable officials in Washington that that job could be his within a few months. Zelensky is on a short list for exile, if President Donald Trump decides to make the call. If Zelensky refuses to leave his office, as is most likely, an involved US official told me: “He’s going to go by force. The ball is in his court.” There are many in Washington and in Ukraine who believe that the escalating air war with Russia must end soon, while there’s still a chance to make a settlement with its president, Vladimir Putin.
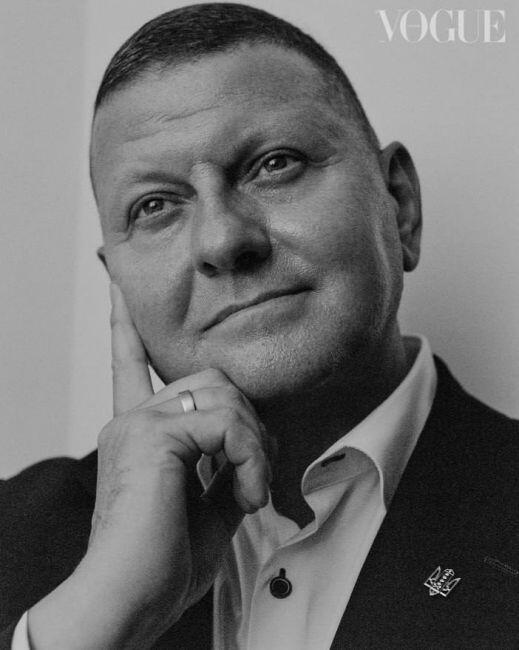
This week, Russian sources have been highlighting a suspiciously timed article and photoshoot featuring Gen. Zaluzhnyi in Vogue magazine…
Most recently, Vogue published Zaluzhny’s column that outlines his “vision for Ukraine’s future.”
After Zelensky’s 2022 Vogue feature boosted his Western image, Zaluzhny’s appearance in the fashion mag is most likely a political PR move.
At the same time, Zelensky – once Time’s ‘person of the year’ (in 2022) – hasn’t been featured of late in any more glam-filled western media photo shoots. His ‘star power’ has most definitely been fading in western capitals, also as populations are war-weary and desirous of peace in eastern Europe, but which would require Zelensky to make territorial concessions. He’s refusing to do this.
If you want to get a really good indication of where the U.S. economy is heading, just look at what is happening in Las Vegas. During good times, hotel occupancy rates are very high and lots of money is thrown around in the casinos. But when times are getting tough, less people head to Las Vegas and those that do go tend to be tighter with their money. We saw a perfect example of this during the Great Recession.
Once the global financial crisis hit, gambling revenues in Las Vegas plunged. The following comes from an ABC News article that was published in 2009…
To almost everyone — and especially the Germans — Las Vegas seemed recession-proof. But now, since the summer of 2008, gambling revenues have dropped by more than 10 percent (see graphic) after having plunged to as much as 25 percent in the months immediately following the bankruptcy of Lehman Brothers.
Of course things eventually turned around and Las Vegas thrived for many years.
But now another enormous shift is taking place. A new downturn has begun “with hotel occupancy, visitor numbers and spending all slipping”…
Las Vegas is experiencing a notable downturn in tourism, with hotel occupancy, visitor numbers and spending all slipping.
Industry data points to several key reasons behind the shift, including rising costs, fewer international travellers, and broader economic uncertainties.
So why is this happening?
It doesn’t take a rocket scientist to figure it out.
Las Vegas hotels are posting some of the steepest year-over-year performance declines among major U.S. markets this summer as international visitor weakness and economic uncertainty take a toll.
Preliminary STR data indicates Las Vegas occupancy fell 14.9% in June, which, if actualized, would mark the city’s deepest monthly decline so far this year.
The deterioration continued into July, with the week ending July 5 showing Vegas with the worst declines across the top 25 U.S. markets: Occupancy fell 16.8%, to 66.7%, and revenue per available room (RevPAR) plunged 28.7%, to $102.75, according to STR.
Because things are so slow, workers are being laid off, and the unemployment rate in the Las Vegas area jumped quite a bit higher last month…
Las Vegas’ jobless rate ticked higher again last month amid a slump in tourism this year.
The Las Vegas-area’s unemployment rate was 5.8 percent in June, up from 5.5 percent in May, according to non-seasonally adjusted figures released this week by the Nevada Department of Employment, Training and Rehabilitation.
Nobody can deny what is happening in Las Vegas, because the numbers are telling a very clear story.
And it turns out that casinos in other areas of the country are also experiencing financial difficulties right now. Here is just one prominent example…
Earlier this month, resort and casino operator Maverick Gaming filed for Chapter 11 protection in the U.S. Southern District of Texas. The Kirkland, Washington-based company owns five casinos across Nevada, Colorado, and Washington and reported that it currently has between $100 million and $500 million in liabilities.
The Nevada properties include a combined 1,200 hotel rooms, 1,700 slot machines and 43 table games. The Washington resorts also have 17 card tables used by visitors specifically seeking out the hotels for gambling trips.
This reminds me so much of the Great Recession.
If you think that I am exaggerating, let me give you another parallel to 2008 and 2009. Our housing market just experienced “its slowest spring season in more than a dozen years”…
The US housing market just logged its slowest spring season in more than a dozen years, leaving Glennda Baker, a veteran real estate agent in Atlanta, struggling to sell 21 listings.
She’s been slashing prices. But months of chatter about AI taking jobs and tariffs tanking the economy is feeding into buyer indecision.
“People say price solves everything,” Baker said. “But price doesn’t solve uncertainty.”
For the entire year of 2025, home sales in the United States are expected to hit the lowest level in 30 years…
Home sales are set to plunge to a 30-year low — with experts warning the slump could deepen into a full‑blown collapse. Just four million transactions are expected in the US this year, according to new data from Realtor.com. That would mark the lowest level since 1995, according to the National Association of Realtors.
Yes, it is being projected that home sales in 2025 will be even lower than they were in 2008 and 2009.
That isn’t just bad.
That is really bad.
So why do the talking heads on CNBC continue to insist that the economy is strong?
Have they gone completely nuts?
I simply don’t understand why they can’t see the parallels to 2008 and 2009, but one thing that we didn’t have in 2008 and 2009 that we are dealing with today is rampant inflation.
If you can believe it, the average list price of a 3-year-old used vehicle has risen by $9,476 over the past six years…
Detroit Free Press autos writer Jamie LaReau reported recently that the average list price for a 3-year-old vehicle is now $32,635, an infuriating $9,476 more than it was six years ago.
This is one of the primary reasons why so many Americans are driving around in 20-year-old vehicles these days.
The average age of the vehicles on U.S. roads has reached an all-time record high, and that isn’t going to change any time soon.
In June, meat prices well outpaced the entire food-at-home category, with steak and ground beef prices rising 12.4% and 10.3%, respectively, compared with a year earlier, according to the Labor Department’s consumer price index (CPI).
Beef prices are now hitting a record $9.26 per pound at retailers as of June, according to the USDA.
Inflation is causing our standard of living to collapse.
This is something that I have written about over and over again.
At this stage, things are so bad that 83 percent of Americans are dealing with “stressflation”…
A LifeStance Health survey released today reveals “stressflation” is affecting most Americans, with 83% reporting financial stress driven by inflation, mass layoffs, the rising cost of living and recession fears. Millennials and Gen Z report the most significant mental health impacts.
So if you are feeling stressed about the rapidly rising cost of living, you are certainly not alone.
Sadly, the long-term trends that have brought us to this point are not going to abate any time soon.
In fact, a tremendous amount of societal chaos is on the horizon.
So I would encourage you to batten down the hatches, because the storm that is heading our way is not going to be pleasant.
US Pending Home Sales Hover Near Record Lows After June Gloom
The choppy performance of the US housing market continued in June with pending home sales falling 0.8% MoM (considerably worse than the 0.2% MoM rise expected).
Source: Bloomberg
That left YoY sales down 0.3% – the seventh straight monthly decline in annual growth – leaving the total pending home sales index back near record lows…
Source: Bloomberg
The supply of existing homes for sale has reached an almost five-year high, as more people list their homes for sale, but the extra inventory isn’t yet pushing prices down.
Source: Bloomberg
Mortgage applications to buy a home dropped 5% last week and are down for the last five weeks… so don’t hold your breath for any material improvement any time soon.
The Northeast was the only region to see a rise (+2.1% MoM) in pending home sales with sales in The West dropping the most (-3.9% MoM).
Pending-homes sales tend to be a leading indicator for previously owned homes, as houses typically go under contract a month or two before they’re sold.
In line with its review of all troops stationed around the world, the U.S. could cut 30 percent of forces in Europe, according to sources close to the Pentagon cited by Politico. The Do Rzeczy news portal asks what this will mean for Poland.
President Trump has already announced his intention to seriously revamp America’s military strategy and presence, with final conclusions from the Global Posture Review expected this September.
Reasons given have included the need to focus on new initiatives, budgetary concerns, and tensions in the Indo-Pacific region.
New priorities are a big turnaround from the U.S.’s previous commitment to Ukraine, and on the chopping block are some 20,000 troops who deployed to the continent after that war began.
Between 90,000 and 100,000 U.S. troops are currently stationed across Europe, with the largest contingent (35,000 troops) in Germany, home to the Ramstein Air Base, the center for U.S. air operations and satellite communications, and Grafenwöhr, the largest U.S. training ground outside of Poland.
But given the size of the reduction cited, American forces in the CEE could also be sent home or elsewhere.
Back in April, there were concerns regarding possible U.S. troop relocation in Poland, specifically from the base in Jasionka, which serves as the epicenter from which all transports are sent to Ukraine.
Now, it seems even more likely that Trump may want to shift focus from the war there.
The timing could not be worse for those who believe Putin is looking to potentially attack inside NATO territory.
There is, however, also the concern from the U.S., specifically Trump’s circle, that European countries must up their own military capabilities and spending.
Secretary of Defense Pete Hegseth has said, “The United States cannot be the long-term guarantor of the entire continent’s security,” as he calls on European allies to increase defense budgets and expand their armed forces within NATO.
Prayer is one of the most common forms of spiritual expression worldwide. Yet, how often people pray varies widely across cultures, religions, and regions.
This chart, via Visual Capitalist’s Niccolo Conte, ranks countries by the number and share of people who pray daily, using data from a survey by the Pew Research Center and population figures from the World Bank.
The dataset covers 35 countries and represents around 50% of the global population, excluding countries where data was unavailable (such as China).
Where Prayer is Most Common
Daily prayer is woven into the social and cultural fabric of many predominantly religious countries across Asia, Africa, and Latin America. In contrast, people in secular Western nations tend to pray less often.
Here’s a look at the countries where people pray the most:
Country
People Who Pray Daily (Millions)
Share of Population Praying Daily
Indonesia 🇮🇩
269.3
95%
Kenya 🇰🇪
47.4
84%
Nigeria 🇳🇬
195.5
84%
Malaysia 🇲🇾
28.5
80%
Philippines 🇵🇭
91.5
79%
Brazil 🇧🇷
161.1
76%
Bangladesh 🇧🇩
130.2
75%
Ghana 🇬🇭
25.1
73%
Sri Lanka 🇱🇰
15.8
72%
Colombia 🇨🇴
37.6
71%
India 🇮🇳
1030.1
71%
South Africa 🇿🇦
40.3
63%
Türkiye 🇹🇷
53.9
63%
Peru 🇵🇪
19.8
58%
Singapore 🇸🇬
2.7
45%
Mexico 🇲🇽
57.6
44%
U.S. 🇺🇸
149.6
44%
Chile 🇨🇱
8.1
41%
Argentina 🇦🇷
17.8
39%
Greece 🇬🇷
3.8
37%
Italy 🇮🇹
20.7
35%
Israel 🇮🇱
3.4
34%
Thailand 🇹🇭
22.2
31%
Canada 🇨🇦
12.4
30%
South Korea 🇰🇷
13.0
25%
Spain 🇪🇸
10.7
22%
Japan 🇯🇵
26.0
21%
UK 🇬🇧
14.5
21%
Netherlands 🇳🇱
3.6
20%
France 🇫🇷
12.3
18%
Poland 🇵🇱
6.6
18%
Australia 🇦🇺
4.4
16%
Germany 🇩🇪
13.4
16%
Hungary 🇭🇺
1.1
11%
Sweden 🇸🇪
0.8
8%
Generally, countries where most people pray daily are middle- and low-income or developing countries.
Indonesia tops the list, with 95% of its population—269 million people—praying daily. However, India is at the top in absolute numbers, with more than 1 billion people saying they pray daily, representing 71% of its population.
In Africa, Kenya and Nigeria have the highest rates of daily prayer. Other highly devout countries include Malaysia, the Philippines, and Bangladesh, where Islam and Christianity are dominant religions.
Overall, these countries are also highly religious. For example, 100% of Indonesians and 99% of Indians are affiliated with a religion. These percentages are much lower in developed Western nations.
Although most Western nations see low levels of daily prayer, the U.S. stands out with over 149 million Americans, or 44% of the population praying daily, with a diverse religious landscape. On the other hand, in secular European nations like Sweden, France, and Germany, less than 20% of the population prays daily.
“Beyond Realistic”: Why Europe’s Pledge To Buy $750BN In US Energy Is Mathematically Impossible
As part of the U.S.-EU trade deal agreed over the weekend, the EU committed to purchasing a mindblowing $750 billion worth of US energy products over three years ($250 per year) including LNG, oil, and nuclear fuel (again this is very big picture: neither side has detailed what was included in the energy deal – or whether it covered items such as energy services or parts for power grids and plants).
There is just one problem: this number is laughably unrealistic because it would require the redirection of most US energy exports towards Europe and the EU has little control over the energy its companies import.
Indeed, as Rabobank explains, unless energy prices increase materially, that figure remains beyond realistic expectations. The EU imported roughly €65 billion worth of energy products from the U.S. in 2024, including €20 billion (35 million tons) of U.S. LNG and €44 billion of oil and oil products. To reach the required $250 billion per year, the EU would need to import roughly 67% of its energy needs from the US, based on 2024 Eurostat data.
Even if the EU were to purchase all of its LNG from the U.S., the total would rise to only €40–50 billion, based on 2024 prices. This would require countries like Russia, Algeria, Qatar, Nigeria, and even Norway to completely relinquish their market share in the EU, while the U.S. government would need to mandate its LNG exporters to prioritize Europe.
The shift in flows for crude oil and refined products would be even more substantial, as the EU currently imports only around 17% of its needs from the U.S. Existing suppliers in the Middle East and India are unlikely to surrender market share without significant economic incentives, while U.S. refining and export capacity is already stretched. Capacity, cost, and competition will continue to shape energy flows, regardless of political intent.
Reuters adds that “there is strong competition for U.S. energy exports as other countries need the supplies – and have themselves pledged to buy more in trade deals. Japan agreed to a “major expansion of U.S. energy exports” in its U.S. trade deal last week, the White House said in a statement. South Korea has also indicated interest in investing and purchasing fuel from an Alaskan LNG project as it seeks a trade deal.”
The flipside is just as laughable: total U.S. energy exports to all buyers worldwide in 2024 amounted to $318 billion. Of that, the EU imported a combined $76 billion of U.S. petroleum, LNG and solid fuels such as coal in 2024, according to Reuters’ calculations based on Eurostat data.
More than tripling those imports was unrealistic, analysts said.
Arturo Regalado, senior LNG analyst at Kpler, said the scope of the energy trade envisioned in the deal “exceeds market realities.”
“U.S. oil flows would need to fully redirect towards the EU to reach the target, or the value of LNG imports from the US would need to increase sixfold,” Regalado said.
Competition for U.S. energy could drive up benchmark US oil and gas prices and encourage U.S. producers to favour exports over domestic supply. That could make fuel and power costs more expensive, which would be a political and economic headache for U.S. and EU leaders.
Meanwhile, the EU estimates its member countries’ plans to expand nuclear energy would require hundreds of billions of euros in investments by 2050. Its nuclear reactor-related imports, however, totalled just 53.3 billion euros in 2024, trade data shows.
The energy pledge reflected the EU’s analysis of how much U.S. energy supply it could accommodate, a senior EU official told Reuters, but that would depend on investments in U.S. oil and LNG infrastructure, European import infrastructure, and shipping capacity.
“These figures, again, are not taken out of thin air. So yes, they require investments,” said the senior official, who declined to be named. “Yes, it will vary according to the energy sources. But these are figures which are reachable.”
There was no public commitment to the delivery, the official added, because the EU would not buy the energy – its companies would. Private companies import most of Europe’s oil, while a mix of private and state-run companies import gas. The European Commission can aggregate demand for LNG to negotiate better terms, but cannot force companies to buy fuel. That is a commercial decision.
“It’s just unrealistic,” ICIS analysts Andreas Schröder and Ajay Parmar said in written comments to Reuters. “Either Europe pays a super high non-market reflective price for U.S. LNG or it takes way too much LNG volumes, more than it can cope with.”
The United States is already the EU’s top supplier of LNG and oil – thanks to the Biden-inspired war in Ukraine and the CIA blowing up the Nord Stream pipeline from Russia – shipping 44% of EU LNG needs and 15.4% of its oil in 2024, according to EU data. Raising imports to the target would require a U.S. LNG expansion way beyond what is planned through 2030, said Jacob Mandel, research lead at Aurora Energy Research.
“You can add on capacity,” Mandel said. “But if you’re talking about the scale that would be necessary to meet these targets, the $250 billion, then it’s not really feasible.” Europe could buy $50 billion more of U.S. LNG annually as supply increases, he said.
Amusingly, higher EU fuel purchases would, however, run counter to forecasts for EU demand to decline as it shifts to clean energy, analysts said.
“There is no major need for the EU to import more oil from the U.S., in fact, its oil demand peaked a number of years ago,” Schröder and Parmar said.
* * *
According to Rabobank, the most plausible outcome of the trade deal’s energy provisions is increased European participation in U.S. LNG projects (which would also have been achieved without the deal). Unlike crude and refined products, LNG offers scalable, long-term opportunities through joint investments in liquefaction capacity and infrastructure.
European firms are likely to commit capital to U.S. terminals to secure future supply and diversify away from Russian gas. However, this will not materially alter market balances over the next five years and by then Trump will be long gone.
When Istanbul Mayor Ekrem Imamoglu was detained in February on charges of corruption, European officials were stunned. Imamoglu, widely regarded as the most important contender against Turkish President Recep Tayyip Erdogan, had faced legal challenges before. But few expected his dramatic detention in a dawn raid and his treatment as little more than a common criminal.
At the same time, another court case was launched against the leadership of the main opposition Republican People’s Party (CHP) to remove them from office, again on charges of bribery. “These steps risk setting Turkey-EU relations back by a decade,” a senior EU official fumed earlier this year. Five months forward, Ankara’s relationship with Brussels couldn’t be better.
The EU last year decided to deepen its dialogue with Turkey, and many questioned whether the hard-found momentum, after years of frozen EU membership negotiations, would last amid an increasing crackdown on the opposition.
In the weeks after the Imamoglu incident, EU officials met Turkish Finance Minister Mehmet Simsek as part of the Turkey-EU High-Level Economic Dialogue meeting in Brussels. In May, Turkish Foreign Minister Hakan Fidan attended an informal meeting of the EU foreign ministers, known as Gymnich.
The meetings continued uninterrupted as Turkish courts arrested more popularly elected mayors aligned with the CHP.
“Waiting for an EU’s reaction similar to Georgia’s one,” Nacho Sanchez Amor, a Turkey rapporteur at the European Parliament, posted on July 5, when three mayors were arrested. “A new test for a coherent foreign policy or an invitation to exhibit our traditional ‘double standards’?” That reaction didn’t come.
In July, Turkish Trade Minister Omer Bolat met his counterparts as the two sides held the Turkey-EU High-Level Trade Dialogue meeting. The next day, Turkish Interior Minister Ali Yerlikaya met his European counterpart as they held the Turkey-EU High-Level Migration and Security Dialogue meeting.
And finally, on Monday, the EU commissioner for enlargement, Marta Kos, met Fidan in Istanbul, releasing a joint statement that underlined areas of collaboration, from EU’s projects linking Europe to Central Asia to visa liberalization, an update to the customs union and Ukraine’s reconstruction.
“Commissioner Kos also emphasized that dialogue on rule of law and democratic standards is an integral part of our relationship and a commitment by Turkiye as a candidate country,” the joint statement said.
Kos and Fidan didn’t hold a news conference, a sign that neither side wanted to get antagonistic questions from media on Imamoglu’s case, among other issues.
“The EU doesn’t want to rock the ship,” a western diplomat told Middle East Eye. “The EU needs Turkey on Ukraine, on the defense industry overhaul and for the stability in the region as Syria recovers from the civil war.” The diplomat added that other concerns around human rights issues in Turkey are taking the back seat as the world enters a new era of conflicts and risks with Donald Trump’s presidency in the US.
EU with few options
Turkey has emerged as a global arms producer following a series of western sanctions that have restricted Ankara’s access to military equipment since 2016. Over the past two decades, the country has invested billions of dollars in its domestic defense industry.
Last year, Turkish firms exported $7.2bn worth of defense products to global markets, as Ankara now produces its own fighter jets, tanks, artillery, armoured vehicles and electronic warfare systems.
Turkey has been essential in supplying arms to Ukraine and hosting peace talks between Kyiv and Moscow since 2021. Despite Ankara’s refusal to join full international sanctions on Russia, Turkey has recently taken two important steps that indicate the direction Erdogan is taking in the war. “It has become clear once again,” Erdogan said on 11 April, “that European security is unthinkable without Turkey.”
Ankara earlier this month joined the “international drone coalition” supporting Ukraine by providing armed and unarmed military drones to Kyiv. Turkey is one of the three main drone producers in the world.
Turkey also in March joined the Coalition of the Willing to support Ukraine, and in July broadly committed itself to post-war security guarantees for the country.
Ozgur Unluhisarcikli, a regional director at German Marshall Fund, said the EU doesn’t have many options to counter Turkey’s democratic backsliding other than fully suspending the official membership negotiations, which isn’t seen currently as a real option since it would be too difficult to reverse once taken. Unluhisarcikli added that Trump assuming office has weakened the US security commitment to Europe and Europeans are looking for ways to fend for themselves if necessary.
“This encourages both the EU and Turkey to view each other more favorably in terms of security and defence industry cooperation, rather than within the framework of full membership,” Unluhisarcikli told MEE. “The EU does not want to weaken the option of strategic cooperation by criticizing Turkey based on its domestic political developments.”
With this spirit, the EU is looking forward to focusing on joint areas of interest, as alluded to by the joint declaration on Monday, said Samuel Doveri Vesterbye, a managing director at the European Neighbourhood Council.
This includes the Middle Corridor, a scheme also known as the Trans-Caspian International Transport Route, which links Europe, including Turkey and the Caucasus, to Central Asia.
“Why is this a priority for EU and Turkiye? It’s because the Central Asian region presents many opportunities for industry, critical raw materials, renewable energy production, trade and geo-political considerations linked to Turkic, Central Asian nations,” Vesterbye told MEE. “And regional integration of wider Europe, which today includes countries like Tajikistan, Armenia, Turkiye, Kazakhstan, Azerbaijan, Georgia and many others.”
A second western diplomat said the EU was focusing on the practical deliverables to improve EU-Turkey relations and keep Ankara on track while trying not to antagonize it – basically offering carrots rather than sticks to make progress on bilateral issues.
An ‘opportunity’ for Turkey
Marc Pierini, senior fellow at Carnegie Europe and former EU ambassador to Turkey, however, has a differing opinion, saying that the EU government and its bodies all have expressed their dismay at the constant degradation of rule of law in Turkey.
“Given the worsened geopolitical situation in the world, an unavoidable evolution takes place: it’s called the hierarchy of crises. Big powers tend to prioritise those crises closer to their core interests,” he told MEE. “Simultaneously, Turkey’s leadership is probably seeing this geopolitical situation as an ‘opportunity’ to further consolidate its autocratic model for domestic and electoral reasons while western partners are otherwise preoccupied.”
But Turkey continues to face hurdles: for example in gaining access to the EU arms fund known as SAFE, which has a €170bn budget for European joint defence projects. SAFE mandates that 65 percent of projects are funded by firms in the bloc, the broader European Economic Area or Ukraine, only allowing Turkey to join the project with limited participation.
Greek Prime Minister Kyriakos Mitsotakis, however, last week continued to argue that Turkish firms won’t be able to participate in the SAFE program unless Turkey lifts its 1995 declaration of casus belli if Greece decides to increase its territorial waters from six to 12 miles.