58.6 F
Chicago
Thursday, October 8, 2026
Home Blog Page 143

La-Z-Boy Crashes Most Since 2022 As Frozen Housing Market Crushes Sofa Demand

0
La-Z-Boy Crashes Most Since 2022 As Frozen Housing Market Crushes Sofa Demand

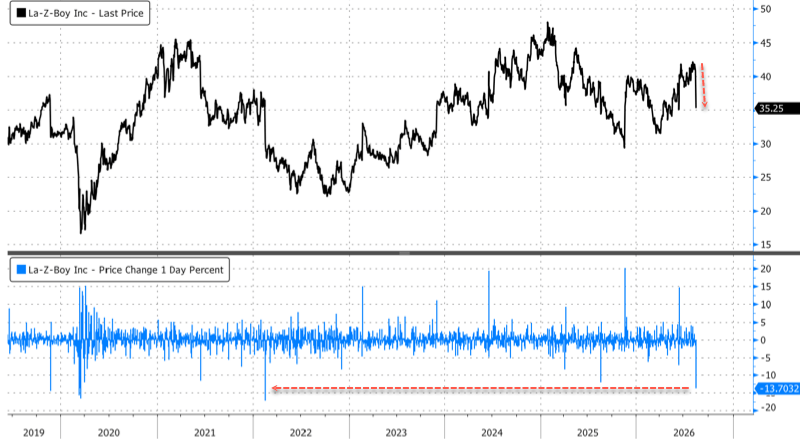
La-Z-Boy shares suffered their steepest decline in 4.5 years on Wednesday after the furniture maker’s second-quarter guidance missed expectations, providing even more evidence that weak housing turnover has suppressed demand for big-ticket discretionary goods such as sofas and recliners. With mortgage rates elevated and home prices near record levels, affordability remains severely stretched, keeping transaction volumes depressed, thus limiting replacement purchases that typically drive furniture demand.

La-Z-Boy forecasted second-quarter sales of $475.7 million, down 3% from a year earlier and well below the $537 million average analyst estimate tracked by Bloomberg. It forecast an adjusted operating margin of 3.9% to 4.8% and a reported operating margin ranging from negative .4% to 4.5%.

KeyBanc Capital Markets analyst Bradley Thomas said the company issued sales and implied earnings guidance below consensus, pressured partly by continued investment.

The soft guidance followed a weaker-than-expected first quarter. Adjusted earnings came in at 43 cents a share, compared with 47 cents one year ago and below the 49-cent analyst estimate. On a reported basis, La-Z-Boy lost 6 cents a share, compared with earnings of 44 cents a year earlier. 

Sofas and recliners are considered highly deferrable purchases – non-essential goods. The stock’s 14% plunge suggests investors view the dismal evidence as further evidence that households are delaying discretionary spending and that the trend will persist, with the 30-year fixed mortgage rate remaining around 6.7%.

The broader read-through is that dismal housing conditions have also dampened home-improvement demand at Home Depot and Lowe’s, as confirmed in this week’s earnings. Wayfair, RH, and Williams-Sonoma have also experienced sluggish demand for big-ticket household items. 

La-Z-Boy is another canary in the coal mine, warning that America’s frozen housing market continues to dampen consumer demand for big-ticket items. Last week, July retail sales were a major disappointment, with discretionary categories seeing sharp pullbacks. This all comes as the national average for gasoline at the pump is over $4 per gallon, continuing to dent consumer sentiment.  

Tyler Durden
Wed, 08/19/2026 – 11:10

WTI Rises As Distillate Stocks Draw, Cushing Back Near ‘Tank Bottoms’, SPR At 43-Year Lows

0
WTI Rises As Distillate Stocks Draw, Cushing Back Near ‘Tank Bottoms’, SPR At 43-Year Lows

Oil prices are chopping sideways (to modestly higher) for the second day in a row as traders weighed the ‘dark fleet’ transits with renewed tensions in the Middle East further clouding the outlook for flows through the vital Strait of Hormuz.

“A combination of the escalation between the UAE and Iran, coupled with a market increasingly pricing a ‘closed for longer scenario,’ keeps oil and refined products supported,” said Arne Lohmann Rasmussen, chief analyst at Global Risk Management.

Combine that with the ever-decreasing poll of global inventories (to soak up any supply shortage)…

…and every incremental report on supply and production matters (especially for refined products).

API

  • Crude -328k

  • Cushing -1.4mm

  • Gasoline +1.1mm

  • Distillates -2.8mm

DOE

  • Crude +4.41mm (-707k exp)

  • Cushing -1.314mm – biggest draw since mid-June

  • Gasoline +688k

  • Distillates -1.53mm

After last week’s massive crude inventory build, expectations were a calmer week (API showed a small draw). The official data showed a sizable build (4.41mm barrels) for the 3rd week in a row while Cushing stocks slipped back. Products were mixed with Distillates drawing down for a 3rd week…

Cushing stocks remain near ‘tank bottoms’…

The SPR saw another drain…

…pushing stocks back to ever lower lows (1983 lows now)…

US crude production rose last week, edging closer to record highs as rig counts continue to rise…

Crude imports eased after a big surge a week earlier mostly thanks to a significant slide in volumes from Canada. Still, shipments from Venezuela remain very strong holding above 700,000 barrels a day and near the highest levels since 2017. 

WTI Crude is rising on the report back up near $85…

Finally, as we have noted numerous times recently, it’s not crude that is the center of the current crisis but refined products with fuel prices, especially diesel, having rallied much harder than oil, as the war between Russia and Ukraine has also contributed to tighter energy markets following attacks on refineries.

That’s heaping cost pressure onto drivers, truckers and farmers, as well as overall industry, and leaks into inflationary impacts for the ‘average joe’ far quicker.

The margin for making diesel from crude oil in the US has topped $100 a barrel, setting all-time highs. In Europe, gasoil futures have more than doubled this year.

Tyler Durden
Wed, 08/19/2026 – 10:41

DOE Cancels 3 National Transmission Corridors, Citing “Green New Scam”

0
DOE Cancels 3 National Transmission Corridors, Citing “Green New Scam”

By Diana DiGangi of UtilityDive

Summary

  • The U.S. Department of Energy will not move forward with the designation of three proposed National Interest Electric Transmission Corridors that the Biden administration selected for review in 2024, saying in a Wednesday release that the corridors were selected as a “means to advance” that administration’s “Green New Scam agenda.”

  • “Transmission policy must serve the American people,” Energy Secretary Chris Wright said in the release, “not special interests or a climate-alarmist agenda that drives up costs, worsens reliability, and disregards the concerns of local communities.”

  • DOE’s release alleged that the “current designation framework proved ineffective in strengthening grid reliability and reducing electricity costs. In some communities, it also contributed to confusion and concern about the scope and intent of NIETC authority.”

The three cancelled corridors are the Lake Erie–Canada Corridor, the Southwestern Grid Connector Corridor and the Tribal Energy Access Corridor.

The DOE’s webpage about the NIETC process no longer includes details about the three projects. A cached version, from March 2026, said that the three proposed corridors would serve various purposes, including providing needed resource adequacy support to the PJM Interconnection, providing “cross-interconnection and interregional connections” between the Southwest Power Pool and WestConnect regions, and facilitating Tribal energy and economic development “by addressing a lack of extra high-voltage transmission.”

According to the current DOE webpage, a NIETC designation can unlock federal financing tools, “specifically public-private partnerships,” as well as allow the Federal Energy Regulatory Commission to “issue permits for the siting of transmission lines within the NIETC under circumstances where state siting authorities do not have authority to site the line, have not acted on an application for over one year, or have denied an application.”

DOE said a NIETC is an area of the country where the agency has “determined the lack of adequate transmission harms consumers and that the development of new transmission would advance important national interests in that area, such as increased reliability and reduced consumer costs.”

Cattle producer-only trade association R-CALF USA praised DOE’s decision, as it had raised concerns in 2024 about the siting of the corridors for their potential to “disrupt independent livestock operations or result in the loss of essential grazing and haying lands.” Other groups, including the Environmental Defense Fund and Clean Air Task Force, criticized the cancellation and said DOE is turning down an opportunity to strengthen the grid.

The cancelled corridors were selected to “help address areas with significant transmission congestion,” CATF said in a release. “Transmission congestion increases costs and reduces reliability for ratepayers.”

“If the goal is affordable, reliable, and secure electricity, we should be making it easier to build the infrastructure the grid needs — not dismantling federal frameworks designed to facilitate it,” said Nicole Pavia, CATF’s Director of Clean Energy Infrastructure Deployment.

EDF noted that while Wright said the current designation framework had “proved ineffective,” DOE’s National Transmission Needs Study from July said that NIETC designation “enables DOE and FERC to use valuable federal financing and permitting tools to spur construction or modification of transmission facilities within a NIETC.” The National Transmission Needs Study is a triennial report, the findings of which form the basis for NIETC designations, according to DOE.

DOE’s release said the Trump administration has taken other steps to build new transmission infrastructure and modernize existing infrastructure, citing several billion-dollar loans made by its Office of Energy Dominance Financing to build, rebuild and reconductor transmission lines.

Tyler Durden
Wed, 08/19/2026 – 09:30

Here Comes QE Lite: Yields, Dollar Tumble, Gold Spikes After Treasury Unexpectedly Doubles Size Of Long-End Treasury Buybacks

0
Here Comes QE Lite: Yields, Dollar Tumble, Gold Spikes After Treasury Unexpectedly Doubles Size Of Long-End Treasury Buybacks

Over the past several years, one of the more amusing debates gripping the market’s Fed-watchers was whether the Fed’s treasury buyback auctions were a form of soft QE, with this website consistently arguing that – contrary to what washed out ex-Bridgewater traders with a newsletter to sell may tell you – Treasury buybacks were just that, to wit:

And moments ago, Scott Bessent finally resolved the debate when, with 30Y yields at 20 year highs and threatening to blow out higher, the US Treasury shocked markets, sparked a meltdown in yields and surge in equity futures and gold when it announced at 8:30am that they will be “increasing, by at least double, the size of liquidity support buyback operations for longer-dated nominal coupon securities (the 10-year to 20-year sector and the 20-year to 30-year sector). The current maximum size of $2 billion per operation will be at least $4 billion per operation.”

This change will be effective September 9, 2026 and will be in effect for the remainder of this refunding quarter (through November 4, 2026). The releases noted that the Treasury will provide more information about future buyback sizes at the next Quarterly Refunding, scheduled for November 4, 2026, in other words it has the benefit of 3 months of “NOT QE” without having to even specify its thinking.

According to the statement, “this increase in buyback operation sizes reflects Treasury’s desire to provide greater liquidity support in longer-dated nominal sectors where there is consistent strong sponsorship from market participants, as evidenced by the significant volume of high-quality offers Treasury routinely receives in longer-dated buyback operations.”

Translation: Bessent panicked and the justification that there is no liquidity is just a strawman, with the Treasury now freaking out that the demand for AI paper is crowding out demand for Treasuries as we have been warning for the past several weeks, and as we predicted a week ago when looking at the blowing out Treasury skew, “Bessent will be busy.:”

It took just one week for him to show just how busy he would be.

The market reaction was instant and violent, with 30y yields down 6bps in an instant on the headlines, having been down 2bp prior,  This brings Wednesday’s yield decline to 8bp total

US 2s30s is 7bp flatter on the day and 10s30s 2bp flatter.

Naturally, with Bessent panicking, stock futures surged…

… but more importantly, gold is breaking out bigly….

… as the market realizes that with total US debt about to hit $40 trillion…

… it all gets much worse from here. 

Tyler Durden
Wed, 08/19/2026 – 09:11

Another AI Reacharound? Marvell Shares Rip On Chips-For-Warrants Deal With Google

0
Another AI Reacharound? Marvell Shares Rip On Chips-For-Warrants Deal With Google

The circular financing circus rolls on…

Marvell shares are soaring this morning after fabless chip designer announced an expanded chip-development partnership with Google that includes a warrant from Marvell allowing the search giant to buy as much as $12.2 billion in shares.

The two firms will collaborate on custom AI chips.

“The expanded partnership spans a comprehensive range of custom silicon programs that attach to the TPU ecosystem, including AI inference accelerators, storage controllers, network interface controllers, memory interface controllers, and near-memory compute,” Marvell said in the filing.

And what does Marvell get for supplying all that?

An ‘investment’… of sorts…

Google may purchase as many as 58,970,907 Marvell shares at a price of $206.58 apiece, Marvell said Wednesday in a regulatory filing.

Nearly 1.4 million of the shares vest in equal quarterly installments during the first year following the execution of the warrant, according to the filing.

The remaining shares vest based on “discretionary purchases” from Marvell’s third quarter of fiscal 2027 through the end of its fiscal 2033, with one tranche vesting for each $500 million in revenue stemming from the products the companies have developed together.

Investors are reacting positively to the strategic validation of Marvell’s custom ASIC and data center platform with MRVL up over 12% in the pre-market…

While the warrant introduces long-term potential share dilution, retail and institutional investors are prioritizing the revenue visibility created by deep integration into Google’s hyperscale AI infrastructure.

The agreement reinforces Marvell role as a key custom silicon partner for hyperscalers and the spin is that tying Google’s equity vesting directly to incremental $500 million revenue milestones aligns both companies toward massive long-term commercial scale (provides strong multi-year revenue visibility through fiscal 2033, offsetting near-term dilution concerns with guaranteed ecosystem demand.)

While this is true, the reality is, of course, that this is an off balance sheet (no liquidity required) way to lock in chip supply (a giant buy now pay later scheme).

Shares of Broadcom (AVGO), which is known for being a major partner on Google’s TPU efforts, are down 3% in the pre-market.

Tyler Durden
Wed, 08/19/2026 – 09:03

Trump Pauses 50% Canada Tariffs At 11th Hour, Declares “We Have A Deal”

0
Trump Pauses 50% Canada Tariffs At 11th Hour, Declares “We Have A Deal”

The Canadian dollar climbed against most of its Group-of-10 peers after President Trump delayed 50% tariffs on billions of dollars of Canadian goods for three days, claiming on Truth Social that a trade deal was pending. The last-minute reprieve will ease trade tensions in North America.

“I have paused the 50% Tariffs against Canada, that were scheduled to kick in tomorrow morning for a three day period, based on the fact that Canada and the U.S.A., subject to the finalization of documents, have a DEAL! The great Keystone XL Pipeline, long ago killed by Sleepy Joe Biden, may be awoken from the grave!” Trump wrote on Truth Social late Tuesday night.

The United States Trade Representative wrote on X, “The deal will include comprehensive market access for all American goods, economic security commitments, digital trade alignment, and many important provisions that will continue to protect our market and American workers, along with our Canadian partners.”

A White House proclamation explained that the tariffs were suspended after Canada committed to removing discriminatory treatment across US automobiles, dairy products, and alcohol.

Canadian Prime Minister Mark Carney released a statement offering a more cautious view and stopped short of confirming that a final deal had been reached.

“Substantial progress has been made, although there is important work still to be done,” Carney said in the statement. “While we continue this work, Canada remains focused on building a stronger, more independent, and more competitive economy at home.”

Analysts at Jefferies added more color: 

Trump says U.S., Canada have trade deal, pauses new tariffs for three days Globe and Mail reported that U.S. President Donald Trump announced a tentative trade deal with Canada and paused planned 50% tariffs for three days, less than two hours before they were due to take effect. 

Trump said the agreement remains subject to final documentation and did not disclose specific terms or confirm whether the tariffs would be permanently withdrawn. 

The announcement followed intense negotiations between Canadian and U.S. officials, including multiple discussions between Prime Minister Mark Carney and Trump. 

Sources indicated negotiators believed they had developed a proposal capable of resolving the impasse, but the final decision rested with political leaders. The threatened tariffs, under Section 338, would have applied to about US$20B of Canadian exports including electronics, dairy, alcohol and wood products. Talks also covered existing Section 232 tariffs on autos, metals and forest products. 

Reports suggest the U.S. may reduce, but not fully remove, some tariffs in exchange for Canadian concessions such as lifting provincial bans on U.S. alcohol and removing certain countertariffs. 

Key sticking points remained auto and lumber tariffs, with Canada seeking exemptions for North American auto content and provinces demanding meaningful lumber relief. 

The outcome represents a significant political test for Carney, who has balanced pressure to protect Canadian interests with business demands for greater trade stability.

Scotiabank’s Derek Holt provided his first take:

Great, there’s a possible deal. What’s in the deal? Dunno. Do I trust there is a deal because Trump said so? Not really. Do markets trust there is a deal? Not so much, as CAD only appreciated by about a quarter cent since Trump’s social media post last night, CGBs are flat, and so are TSX futures. All he did was to go TACO and postpone the 50% tariffs for three days just 1¾ hours before they were to have been applied against $20 billion of imports from Canada sans CUSMA exemption. Canada’s retaliation is similarly postponed. That’s a positive for now, since otherwise everything would have skidded off into the ditch, but the rest is still uncertain. 

What’s in the deal? Haven’t a clue. Is it good for both Canada and the US? Dunno. Trump’s post merely says the two countries have a deal while intimating that the Keystone XL pipeline is back on. We’ll see about that, given a guarded industry toward the pipeline that has moved on given the wild unpredictability of successive US administrations, the long project timelines and the varied competing interests. 

We also have this post from the USTR that claims “comprehensive market access for all American goods, economic security commitments, digital trade alignment, and many important provisions that will continue to protect our market and American workers, along with our Canadian partners.” We’ll be the judge of that, not the White House.

Canadian PM Carney’s post was much more measured. It noted that “substantial progress has been made, although there is important work still to be done.” On that count, massive shout-outs to the Canadian team for working so tirelessly and on something so mindless as zero-sum beggar-thy-neighbour trade policies out of the US that divert precious management time by leaders and businesses away from more meaningful pursuits. You’ve served your country well so far.

And so we need details. What’s in the agreement, what are the enforcement mechanisms, what are the timelines for implementation, and of course, how exactly comprehensive is this? Is it a meaningfully comprehensive CUSMA extension, or just the opening salvo? How much did PM Carney give away from a salability standpoint at home? The provinces will need to be briefed and their reactions and cooperation will be important. And is Trump’s signature going to actually mean anything on this ‘deal’ given his pattern of not honouring much of what he commits to doing?

Throughout all of this I have stuck to a cautious optimist line that Canada would get a trade deal before the midterms or before the new US Congress convenes in January. The odds of this happening just went up. That has been part of a macro narrative for improved growth and modest tightening by the Bank of Canada as the case for last Fall’s insurance cuts to persist would be removed at a minimum. I hope that’s true, but I’ll jump on the ‘Let’s Make a Deal’ stage when I see something meaningful. Until then, post on to your heart’s content, we want details!! 

If a deal that extends CUSMA and lowers uncertainty in a meaningful way were to be achieved, then it would be positive for Canadian economic growth and negligible for US growth. It would buoy market and business sentiment toward Canada. It could put at ease consumer worries. 

And be wary toward the possible confirmation bias in gloomier quarters. I wouldn’t want talk to see some of the research gloomsters who were adopting a negative stance on trade and how damaging it could be to Canada’s economy and markets while making rate cuts more likely then turn around and say a deal doesn’t mean much. Nothing to see here. Don’t want to see it because it goes against all of their other views that deliberately excluded the cautious optimists. #accountability. The BoC wouldn’t dismiss a deal; amid multiple uncertainties, removing or materially dropping trade uncertainty would be another step toward modest tightening.

Trump’s announcement signals possible progress ahead of the review of the North American trade agreement between the US, Canada and Mexico. The US and Canada traded $900 billion in goods and services last year. 

Tyler Durden
Wed, 08/19/2026 – 08:45

Futures Flat With All Eyes On Interest Rates And Oil

0
Futures Flat With All Eyes On Interest Rates And Oil

Futures are flat but off their lows as Tech gets a boost from a huge Hynix buyback, which erased ~8% decline to trade up as much as 2% and reversed a 5.8% drop in the Nikkei; the ADRs are +5.6% pre-mkt boosting both Memory and Korea ETFs. As of 8:15am ET, S&P futures are fractionally in the green, with Nasdaq futures down 0.1% even as momentum looks to retrace some of yesterday’s losses. In premarket trading, Semis, Memory, and Mag7 are higher with Software and Low Profitable Tech weaker. Cyclicals and Defensives are both mixed as the market has not yet decided on direction. Bond yields are flat to down 1bp, following from yesterday with USD weaker. Commodities are bid with all 3 complexes moving higher. Brent crude rose 0.8% and briefly topped $92 barrel for the first time since July with little evidence of progress toward a resolution of the US-Iran war. Today’s macro focus is on the 20Y bond auction, which is likely to need a concession, and on the Fed Minutes where investors seek clarity on the Fed’s reaction function in a tape that lacks significant catalysts. NVDA and Jackson Hole loom large.

In premarket trading, Mag 7 stocks are mixed (Amazon +0.2%, Nvidia +0.2%, Meta +0.1%, Microsoft -0.5%, Apple 0.0%, Tesla -0.2%, Alphabet -0.5%)

  • Estée Lauder (EL) climbs 7% after posting quarterly results that beat estimates. The company ended a run of three straight declines in annual revenue, a sign the beauty conglomerate’s turnaround efforts are gaining momentum.
  • La-Z-Boy (LZB) sinks 16% after the home-furniture maker gave a weaker than expected sales forecast for the current quarter.
  • Mercury Systems (MRCY) falls 9% after the maker of display systems used in combat vehicles posted fiscal fourth quarter adj. EPS that came in a penny shy of expectations.
  • Moderna (MRNA) soars as much as 100% after the company and Merck said their personalized cancer vaccine helped cut the recurrence of melanoma in a large, late-stage trial. Shares of Merck (MRK) are up 8%.
  • Norfolk Southern Corp. (NSC) rises 2% as the company and Union Pacific Corp. can move forward with plans to create the nation’s first coast-to-coast freight network after a federal regulator decided to resume consideration of their joint application.
  • SK Hynix ADRs (SKHY) rise 3% after the South Korean memory-chip maker said it plans to buy back $29 billion of its own shares, in a bid to assuage investors concerns about AI spending durability.
  • Target (TGT) slips 1% despite the retailer’s comparable sales and adjusted EPS topping expectations, while also getting a boost from tariff refunds. Shares have climbed 56% this year through Tuesday’s close.
  • WhiteFiber (WYFI) falls 22% after the artificial intelligence infrastructure firm announced its intention to offer $250 million of convertible senior notes due 2032 in a private placement.

In other corporate news Novo Nordisk is testing small doses of its blockbuster Wegovy pill in a new study that will help establish how low patients can go in their dose and still lose weight. Anthropic plans to give Chief Executive Officer Dario Amodei and other co-founders shares with extra voting power as the firm prepares to make its Wall Street debut, The Information reported. Cerebras Systems introduced a new speedier computer built with the company’s chips, saying the device will give it a wider advantage over Nvidia equipment. 

Fairly benign price action in early trading contrasts with Tuesday’s cash session, when stocks struggled for direction and long-dated bonds remained under pressure as higher oil prices kept traders cautious following days of yields at multiyear highs. As noted above, tech got a boost from Hynix buyback, announced just moments after the Kospi closed to get the biggest bang for the lack of liquidity buck, which erased a 8% plunge to trade up as much as 2%; the ADRs are +5.6% pre-mkt boosting both Memory and Korea ETFs. Moderna Inc. surged more than 100% after a positive result from its personalized cancer vaccine trial with Merck & Co. Momentum looks to retrace some of yesterday’s losses even as brent crude rose 0.8% and briefly topped $92 barrel for the first time since July with little evidence of progress toward a resolution of the US-Iran war. 

Longer-term bonds trimmed early gains as Brent approached $92 a barrel. The yield on 30-year Treasuries hovered around 5.27%, while rates for most European counterparts were little changed. Investors remained on guard as concerns over major governments’ loose fiscal policy and heavy borrowing by the biggest spenders on artificial intelligence are expected to keep yields elevated. The threat of sticky inflation also lingered as the US-Iran conflict continued to curb oil flows from the Middle East.

“The question is no longer whether higher yields matter, they clearly do, but whether the strength of earnings and capital expenditure implies that the economy can absorb them,” said Florian Ielpo at Lombard Odier Investment Managers. On the other hand, the weakness in tech may be a sign that rising bond yields are starting to keep stock prices in check, he said.

The impact of growing demand for cash among AI hyperscalers was on display as Alphabet paid just under 7% to borrow longer-dated funds in its debut Australian bond offering, the company’s highest-ever yield on a note. The generous rate means some investors could be lured into buying bonds from tech titans rather than their stocks, according to Stephan Kemper, chief investment officer at BNP Paribas Wealth Management Germany.

“AI stocks are increasingly in competition with their own bonds,” he said. “Yields close to multiyear highs in combination with a higher visibility of expected cash flows are making a compelling case for many investors.”

Meanwhile, as we have noted extensively, the lack of a clear path to a resolution in the Middle East is putting upward pressure on oil prices. Regional tensions intensified as the United Arab Emirates said it was cutting all economic ties with Iran after accusing the Islamic Republic of firing ballistic missiles at its territory.

Elsewhere, the Trump administration delayed 50% tariffs on Canadian products for three days, citing a tentative agreement to resolve a trade dispute. Trump is said to have chosen White House policy aide Heidi Overton to lead the FDA.

In politics, Democratic Socialist Angie Nixon stormed to a surprise win in Florida’s US Senate primary against the man who concocted the Russia collusion hoax, Alex Vindman. Democrat Mary Peltola and incumbent Republican Senator Dan Sullivan will advance in Alaska’s Senate primary, setting the state up to be one of the most fiercely contested races in November that could determine control of the US Senate.

Today, top of traders’ minds are a plethora of retail earnings, Fed minutes and the ongoing investor focus on AI. Minutes from the Federal Reserve’s July meeting, due later on Wednesday, may offer investors a better sense of the degree to which officials were losing patience with high inflation. Policymakers voted 9-3 to keep rates unchanged. Money markets currently price around a 50% chance of a hike in October, with the odds of such a move rising to around 90% for December.

In Europe, the Stoxx 600 was little changed at 651.82, snapping a five-day stretch of losses after a tech-led selloff in Asia failed to carry over. Here are the biggest movers Wednesday:

  • FLSmidth shares gained as much as 10%, hitting their highest level since April, after the mining-equipment maker delivered earnings comfortably ahead of expectations
  • Geberit rose as much as 8.6%, the most since November 2023, following second-quarter results which ZKB says showed “surprisingly strong” revenue momentum
  • Ambea gained as much as 13%, the most since November 2024 and to a record high, after the Swedish healthcare group’s earnings beat estimates
  • Implenia rose as much as 9.4%, the most since early March, as ZKB says the construction, civil and underground engineering services company’s results “turned out slightly better” than expected
  • Sensirion shares rose as much as 8% after the Swiss sensor technology company raised its full-year guidance and drew analyst praise for its results
  • Oxford Nanopore shares rose as much as 7.8%, the most in two months, after the British DNA-sequencing company reported a narrower adjusted Ebitda loss for the first half
  • Ithaca Energy shares jumped as much as 7.4%, hitting a three-month high, after the oil and gas company delivered record quarterly production and raised its dividend guidance
  • Straumann dropped as much as 9.1%, the most in a year, after the Swiss dental implant maker said Christopher Norbye would replace Guillaume Daniellot as CEO. Analysts at Bernstein and JPMorgan said Daniellot was “well-liked”
  • Trainline shares fell as much as 17%, the most in five years, after the UK competition watchdog opened an investigation into whether the rail-booking platform breached consumer law through “drip pricing”
  • Carlsberg shares fell as much as 4.1%, the most in five months, after the Danish brewer’s first-half volumes disappointed
  • Smith & Nephew shares dropped as much as 3.8% to the lowest intraday level since May 12 after the medical devices maker said Chief Financial Officer John Rogers will leave his position at the end of next month
  • BKW shares fell as much as 4.6% after the power company’s first-half Ebit dropped by a more-than-expected 15%

Asian stocks slumped, led by a selloff in chipmakers, as elevated bond yields and a stalemate in US-Iran peace talks kept investors cautious. The MSCI Asia Pacific Index dropped as much as 2.3%, the most in three weeks, with chip heavyweights Samsung, SK Hynix and TSMC among the biggest drags. Most major markets were in the red, with Korea’s Kospi sliding 5.8% and Japan’s Nikkei losing 3.2%. A Bloomberg gauge of Asian semiconductor stocks tumbled 3.7%. US-listed shares of SK Hynix climbed in pre-market trading after the firm unveiled plans to buy back 40 trillion won ($29 billion) of stock and return more of its profits to shareholders in an effort to calm worries about the durability of AI spending.

A number of consumer-focused reports due before the market opens include Target, Lowe’s, TJX and Estee Lauder. Placer.ai, directionally accurate in seven of prior eight periods, estimates Target’s adjusted revenue grew 4% year-on-year in fiscal second quarter, while Bloomberg Second Measure notes that observed sales through end July are tracking above industry growth rate. Earnings from Analog Devices are also on deck.

In rates, treasuries rose, giving bond investors some respite after a sharp rise in yields that began last Friday. 10-year Treasury yields fell about 2bp to 4.68%.Long-dated bonds lagged the rest of the curve; 30-year yields were little changed at 5.28%. Front and belly of the curve slightly is richer on the day with long-end lagging ahead of a $16 billion 20-year bond auction which remains on course to be offered at the highest yield since the sector was reintroduced back in May 2020. Gilts outperform in Europe as traders pared BOE tightening bets after UK headline CPI matched estimates. UK 10-year borrowing costs fall 2 bps to 5.07%. Bunds lag following a €3.769b 10-year auction at an average yield at highest level since 2011. Treasury auctions resume with $16 billion 20-year bonds, before a $8 billion 30-year TIPS sale on Thursday. The WI 20-year at around 5.27% sits ~11bp cheaper than the July stop-out and remains around 2.5bp cheaper than the October 2023 yield stop-out. IG dollar issuance slate includes an ADB 10-year benchmark offering. Three issuers priced $6.4 billion on Tuesday after at least seven issuers decided to stand down from announcing deals.

In commodities, WTI futures higher by around 1%, adding to underperformance of bunds vs. Treasuries, rising to highest levels in almost three weeks as a spat between the United Arab Emirates and Iran heightened regional tensions.

“Some of the recovery came from equities finally reacting to the level of yields, some likely from short-covering, and some from the market taking profit on what is now looking like a very crowded steepener,” said Evelyne Gomez-Liechti, multi-asset strategist at Mizuho. Money markets price a 35% chance of a September Fed hike and 23bps of tightening by year-end.

In FX, the Bloomberg Dollar Spot Index falls 0.2% as traders continued to pare bets on a Federal Reserve rate hike ahead of minutes from the last policy meeting. The yen is the strongest of the G-10 currencies, rising 0.3% against the greenback. The Aussie dollar underperforms. The Canadian dollar climbed against most of its Group-of-10 peers after US President Donald Trump delayed 50% tariffs for three days pending the finalization of a trade deal. USD/CAD dropped as much as 0.2% to 1.3872. In a social media post, President Donald Trump said he’s pausing the tariffs “based on the fact that Canada and the U.S.A., subject to the finalization of documents, have a DEAL!”. “The durability of CAD gains will depend on whether a formal agreement is reached within the three-day window,” Kristina Clifton, a senior strategist at Commonwealth Bank of Australia wrote in a note to clients.

Today’s US economic data calendar includes FOMC minutes release from the July 29 meeting at 2pm New York. No Fed speakers scheduled for the session. earnings releases include Target, Lowe’s, and TJX

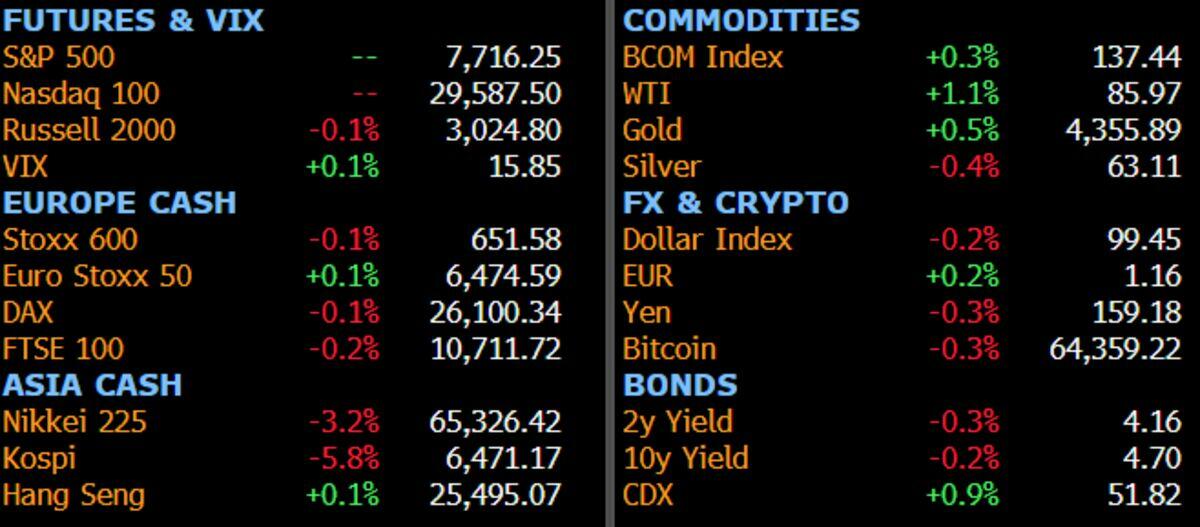
Market Snapshot

Top Overnight News

  • Iranian attacks on shipping in the Strait of Hormuz are piling up without an American military response, raising the risks of crossing the strategic waterway and frustrating some Arab allies who worry the U.S. doesn’t have a strategy to wind down the conflict. WSJ
  • Iran has weighed attacking US military targets in Europe should Donald Trump escalate the war, according to people close to the regime, as Tehran considers its options to increase the stakes of the conflict. FT
  • The UAE said it was cutting all economic ties with Tehran after accusing Iran of firing ballistic missiles at its territory. Oil rose with no signs of a peace deal. BBG
  • Even as Iran projects resilience in the war with the United States, its leaders are worried that a threat of more economic punishment by Donald Trump could increase hardships, reignite unrest and further erode the Islamic Republic’s legitimacy. RTRS
  • President Trump said he would pause a 50% tariff on certain goods from Canada for three days while the two countries seek to finalize an agreement. “I have paused the 50% Tariffs against Canada, that were scheduled to kick in tomorrow morning for a three-day period, based on the fact that Canada and the U.S.A., subject to the finalization of documents, have a DEAL!” Trump said on social media Tuesday night. WSJ
  • China will expand the use of a $1.6 trillion fund to boost housing-related spending, including renovations, under revised regulations taking effect next month. BBG
  • SK Hynix will buy back and cancel 40 trillion won ($28.61 billion) of treasury shares and allocate ‌more than 50% of free cash flow generated between 2025 and 2027 to boost shareholder returns, it said on Wednesday. The chipmaker’s shares plunged nearly 10% on Wednesday before trimming some losses in post-market trading. The shares hit record highs in June but have since declined, partly on investor concern over the durability of AI spending by U.S. technology companies. RTRS
  • Target lifted its guidance after results outpaced estimates. Shares initially rose premarket before sliding around 4%, a sign that investors were expecting even stronger results. BBG
  • Big pharma is increasingly licensing drugs developed in China. For US drugmakers, the expanding tie-ups means lower costs and more access to breakthrough treatments. For critics in Washington, the deals spell risk. BBG
  • Global stocks are meaningfully net bought so far in August, driven almost entirely by US equities which have been net bought for three straight weeks. Notably, on a trailing 3-week basis in % terms, the recent buying in US equities is the largest since March 2020 and second largest in the past decade. Goldman Prime Brokerage 

A more detailed look at global markets courtesy of Newsquawk

APAC stocks were mostly lower following the tech-led declines stateside, as yields remained elevated and oil continued to edge higher amid the ongoing geopolitical stalemate. ASX 200 retreated amid a deluge of earnings and with RBA Deputy Governor Hauser sticking to the hawkish script, while Australian wage data matched estimates and spurred little reaction. Nikkei 225 failed to benefit from stronger-than-expected Machinery Orders data and was pressured by the tech weakness, despite yields pulling back from multi-decade highs. KOSPI underperformed amid pressure in the tech heavyweights, while sentiment was also not helped by strained US-South Korea ties after US President Trump reduced the joint drills with South Korea and is said to be pushing for a meeting with North Korean leader Kim as soon as this fall. Hang Seng and Shanghai Comp were ultimately mixed, with the Hong Kong benchmark kept afloat as participants digested earnings releases including from Baidu and Xiaomi, while the mainland conformed to the broad downbeat mood with notable losses seen in the ChiNext Nasdaq-style board.

Top Asian News

  • Japanese Ministry of Defence is reportedly to request JPY 8.9tln spend in budget request, Nikkei reported.
  • Japanese Machinery Orders (Jun MM) 9.7% vs. Exp. 7.8% (Prev. -12.4%).
  • Japanese Machinery Orders (Jun YY) 16.9% vs. Exp. 10.8% (Prev. -1.9%).

European bourses are broadly lower, following on from the risk-off tone overnight as Asian chipmakers were weighed by the weakness stateside. Switzerland’s SMI outperforms, supported by Geberit, after it reported strong results. Sectors point to a mixed picture. Construction outperforms, with Energy and Retail rounding out the top 3 sectors. To the downside is Media, followed by Banks and Food, Beverages & Tobacco. The latter has been pressured by post-earning losses in Carlsberg (-3.7%) after its H1 EBIT missed consensus.

Top European News

  • UK PM Burnham said No. 10 North will take over responsibility for economic growth from the Treasury as part of a transfer of power, according to The Times.

FX

  • Focus on yields remain with the USD weaker against most G10 peers today as bonds stabilise around recent lows; the oil story is similar, Brent remaining above USD 90/bbl. Action this morning has been isolated to FX, USD weakness emerging against all peers without a clear driver, EUR/USD rising back above 1.16 while Cable breached 1.3550, DXY below 99.50, familiar levels in recent sessions. The summer conditions likely a factor in the news-absent moves, especially ahead of risk events 1) FOMC minutes, and 2) 20yr auction, both of which have increased focus amid 1) the lack of Fed Chair Warsh’s communication, 2) recent weakness in the long end and it being potentially the most expensive for the Treasury in 25 years. Ahead of this, STIRS are steady with the market assigning a c. 30% probability of Fed tightening in September.
  • No major GBP move to UK CPI, which, in short, continues the narrative that the BoE is comfortable at 3.75% with data continuing to not surprise vs. market and BoE’s July MPR forecasts. The headline rise reflects the Ofgem price cap introduced this month, a point which was partially offset by a decent moderation in food inflation. Services moderated as expected, while ING notes the BoE’s core services measure of inflation has picked up a little to 3.8% Y/Y, which, while hotter, shouldn’t be too much to encourage those on the fence for tightening. In conjunction with the soft LFS on Tuesday, both show sufficient evidence to keep the BoE on hold for the rest of the year, with risks tilted both ways.
  • JPY is the G10 outperformer, benefitting from a softer Buck as the pair looks to return towards 159.00 after nearing 160.00 in the previous few sessions. Macro catalysts were light, though strength seen in KRW could have given a helping hand also. USD/JPY marked a session low of 159.05, a little off this level at the time of writing.

Fixed Income

  • Global fixed benchmarks are mixed this morning, though yields ultimately remain near recent multi-year highs as concerns surrounding geopolitical/fiscal remain. Price action today has been fairly rangebound given the lack of pertinent newsflow. The geopolitical environment remains tense, with President Trump continuing to threaten Iran; recent Iranian sources have rejected the White House’s claim that there have been direct negotiations between Iran and the US.
  • USTs (+2 ticks) currently holds towards the upper end of a 108-16 to 108-23 range. The docket is lacking for the remainder of the day, aside from the FOMC Minutes. It will be eyed to gauge hawkish sentiment among the wider FOMC, with markets currently leaning towards a hold in September. However, given recent soft US data, the Minutes could be looked through.
  • Bunds (-10 ticks) are slightly lower this morning. EZ HICP Final metrics were unrevised, spurring little move. Thereafter, a poor German auction (high retention), also spurred little action in primary markets. The subdued outing is likely due to the ongoing summer lull, and as European banks taper their bond purchases as they approach their minimum reserve holdings.
  • Gilts (+6 ticks) are outperforming this morning, taking lead from the region’s inflation report. Headline inflation rose from the prior (in-line with expectations), but much of the acceleration was attributed to Ofgem’s utility price hike. Dovish factors stem from a decent moderation in food inflation and cooling Services inflation (though mainly due to low air fares reading). Overall, the report will do little to shift the BoE away from its holding policy; ING expects the Bank to keep rates on hold for the remainder of the year, before delivering cuts in Spring 2027.
  • Germany sells EUR 3.769bln vs exp. 6bln 3.00% 2036 Bund: b/c 1.15x (prev. 1.10x), average yield 3.26% (prev. 3.13%), retention 37.2% (prev. 25.05%).

Commodities

  • WTI and Brent October futures are higher for a fourth trading day, with Brent rising towards USD 92/bbl (vs low and WTI near USD 85/bbl (USD 84.36/bbl), as the US-Iran conflict showed no sign of resolution. Furthermore, weekly API data yesterday reported a modest draw in crude stockpiles. Elsewhere in energy, Dutch TTF is modestly softer and around an intraday low after gradually fading from levels above EUR 64.50/MWh to lows just above EUR 63/MWh. In shipping, China’s seaborne crude imports averaged around 6.8mln bpd in Aug 1-15 , vs ~7.3mln bpd in the same period in July, according to Vortexa. Tanker arrivals point to a pickup in the second half of August, though smaller than initially expected, leaving Chinese seaborne buying below pre-war levels for now.
  • Precious metals are mixed and within tight ranges. Spot gold remains under its 100 DMA (USD 4,381/oz) in a narrow USD 4,325-4,363/oz range vs yesterday’s USD 4,329-4,436/oz range. Spot silver is conversely subdued in a USD 62.54-64.33/oz range after dipping under yesterday’s USD 66.56/oz low. Gold edged higher as easing US bond selling reduced pressure after Tuesday’s decline, though analysts note that uncertainty over US-Iran relations and higher energy-led inflation remain potential headwinds.
  • Copper eased this morning towards the lower end of a tight USD 13,887-13,990/t. Reports note that the backwardation between immediate and three-month delivery eased to USD 248/ton (vs as much as USD 545 on Monday). Bloomberg notes that LME copper inventories available to buyers rose by more than 20,000 tons on Tuesday, the largest single-day jump since April, easing a historic supply squeeze; Trafigura was behind a significant share of the deliveries.
  • US Private Weekly Inventory Data (bbls) Crude -0.3mln (prev. +9.1mln), Gasoline +1.1mln (prev. -1.5mln), Distillate -2.8mln (prev. -0.6mln), Cushing -1.4mln (prev. +0.4mln)
  • ADNOC is reportedly aiming to trim the amount of crude sold to Asian customers in August and September, Bloomberg reported citing sources.

Trade/Tariffs

  • US President Trump posted “I have paused the 50% tariffs against Canada that was scheduled to kick in tomorrow morning for a three day period, based on the fact that Canada and the U.S.A., subject to finalization of documents, have reached a DEAL!”
  • USTR Greer said the deal with Canada will include comprehensive market access for all American goods, economic security commitments and digital trade alignment.
  • Canadian PM Carney said the US has agreed to postpone implementation of its 50% tariffs on a range of Canadian goods under Section 338 of the US Tariff Act of 1930 until the end of August 21st.

Central Banks

  • RBA Deputy Governor Hauser said inflation is too high, adding that monetary policy needs to bring inflation down and needs to reduce demand in the economy. Hauser added that they are not seeing recession, but just a slowdown. Worried about inflation and upside risk to inflation and that if inflation doesn’t come down, will have to raise rates again.
  • ECB’s Rehn said the wage growth and outlook remain moderate, there are no clear signs of second‑round effects and that keeping inflation expectations anchored is essential.
  • Indonesia Central Bank leaves rates unchanged at 5.75%, as expected.

Geopolitics: Iran

  • US President Trump told top administration envoys to halt their conversations with Iran, according to CNN citing a US official.
  • US President Trump is waiting for Iran to cave to his economic pressure, but Tehran may be willing to wait even longer, according to Politico.
  • A source close to Iran’s negotiating team said there had been no direct Iran-US negotiations and that talks with Oman concerned sovereignty over the Strait of Hormuz, according to Fars News.
  • Iranian Deputy Chairman of the Parliament’s National Security Commission said “A ‘new passage’ in the Strait of Hormuz, other than the southern route, will soon be announced in the form of a joint statement with Oman.”
  • Iran’s Foreign Minister said the framework of Tehran’s foreign policy will be based on a strong Iran, an Iran that is self-confident and in control of the situation.
  • Iran Foreign Ministry spokesman Baghaei dismissed UAE claims that Iran launched missiles, citing false flag operations in warning against ‘baseless’ accusations.
  • Iran has weighed attacking US military targets in Europe if US President Trump escalates the war, according to people close to the regime cited by FT.
  • Yemeni Houthis have placed Saudi Aramco and all its facilities, oil tanks, crude transfer pipelines and export ports on their list of targets, Al-Akhbar sources said. The source added that the process of monitoring and tracking Saudi oil tankers in the Red Sea is ongoing.
  • UAE Foreign Ministry said all trade, commercial exchanges and financial transactions with Iran have been halted until further notice.
  • UKMTO has received a report of an incident 40NM southeast of Al Mukha, Yemen. The cargo vessel was unmanned at the time of the incident, however the damage has resulted in a complete constructive loss.
  • The Israeli PM Office said Israel and Syria have agreed to maintain the status quo on security matters, which Syria was about to violate by allowing Turkish forces to deploy at an air base near Aleppo.
  • Syria’s petroleum company said an explosion occurred at the gas export pipeline at the Al-Jabsah gas plant, leading to a halt of pumping through the pipeline

Geopolitics: Other

  • US President Trump is pushing for a meeting with North Korean leader Kim Jong Un as soon as this fall, according to WSJ citing US officials.
  • US-South Korea joint military drills schedule is expected to be cut in half, according to South Korean media. It was later stated by a US Pentagon official that the US military substantially reduces exercise with South Korea and exercises will conclude one week early.
  • North Korea denounced US-South Korea military drills and said exercise of its right to self-defence will continue to completely neutralise enemies’ military threat.

US Event Calendar


DB’s Henry Allen concludes the overnight wrap

Markets had another rough session over the last 24 hours, with equities hit by a sharp selloff in chip stocks, just as several countries’ bond yields hit multi-year highs. To be honest, there was little respite for investors anywhere, and with no sign of any US-Iran talks, oil prices saw a fresh move higher as well. So, it was a bad day for the most part, with the S&P 500 (-0.69%) posting a 3rd consecutive decline, whilst Germany’s 10yr bund yield (+3.7bps) hit a post-2011 high of 3.26%. The main exception came from US Treasuries, with the 10yr yield (-1.8bps) falling back a bit. But even that was thanks to a weaker batch of US data, so it was hard to generate a positive narrative wherever you looked.

The bond selloff was the biggest story yesterday, as the relentless rise in yields showed no sign of easing. In part, that’s been driven by longer-term structural forces, including concerns around fiscal deficits and the AI boom. But near-term inflation concerns stepped up a gear yesterday, with 1-year US (+6.3bps) and Euro (+12.0bps) inflation swaps moving higher. That came as Brent crude (+0.17%) edged up to a 3-week high of $91.02/bbl, while European natural gas futures (+3.06%) also hit a 3-year high of €63.65/MWh. So that added to the pressure, particularly for European bonds more exposed to the energy shock. And that trend has continued overnight as well, with Brent crude up another +0.76% this morning to $91.71/bbl.

That backdrop saw yields hit fresh highs around the world, although Europe saw some of the biggest increases. For instance, yields on 10yr bunds (+3.7bps) hit a post-2011 high of 3.26%, 10yr OAT yields (+4.7bps) hit a post-2008 high of 4.11%, and 10yr BTP yields (+6.0bps) hit a 2-year high of 4.07%. Otherwise, there were similar records at the 30yr horizon, with German 30yr yields (+2.4bps) at a post-2011 high of 3.77%, and France’s 30yr yield (+2.8bps) hit a post-2008 high of 4.89%.

The main exception to this pattern yesterday were US Treasury yields, which initially looked set for new highs before falling back. That was thanks to a soft batch of US data, which cast fresh doubt on how rapidly the Fed could hike rates. That included data on housing starts, which fell to an annualised rate of 1.239m in July (vs. 1.345m expected). Meanwhile, industrial production only rose +0.2% in July (vs. +0.3% expected), whilst pending home sales were down -2.3% (vs. unch expected). So with all that now out, the Atlanta Fed cut their GDPNow estimate for Q3 to an annualised pace of +4.0%, down from +4.3% beforehand. And in turn, those releases helped Treasury yields to pull back again, with the 10yr yield (-1.8bps) ultimately closing slightly lower at 4.70%. Another test of demand for long-dated Treasuries will come with today’s 20yr auction, but yields have continued to fall overnight, with the 10yr yield down another -1.6bps this morning to 4.69%.

As all that was going on, there were still no signs of any negotiations to reopen the Strait of Hormuz. Indeed, President Trump said in a post that “There are no talks or conversations going on, or scheduled” with Iran and that the US “Naval Blockade remains in full force and effect”. Meanwhile, Iran’s parliamentary speaker Ghalibaf said that Hormuz would remain shut until the US meets conditions of the interim deal agreed in June, which include lifting the US blockade, removing oil sanctions, and unfreezing Iranian assets. So that led to growing pessimism that the Strait of Hormuz would reopen anytime soon, and we saw oil prices move up throughout the futures curve. In fact, the 12-month Brent future (+0.38%) hit a 2-month high of $78.31/bbl, with fears about a protracted period of high oil prices adding to the pressure on bonds yesterday.

For equities, the stagflationary backdrop meant it was another difficult session, with fresh declines on both sides of the Atlantic. In the US, that saw the S&P 500 (-0.69%) lose ground for a third consecutive session, with chip stocks as the biggest driver of the declines. In fact, the Philly semiconductor index (-4.98%) had its worst day of August so far. The NASDAQ (-1.33%) also underperformed, while the Mag-7 (-0.88%) was led lower by Meta (-4.42%). But the weakness was also broad-based, with the equal-weighted S&P 500 down -0.45%. Meanwhile in Europe, the STOXX 600 (-0.69%) posted a 5th consecutive decline for the first time in 2026 so far, alongside losses for the DAX (-0.80%) and the CAC 40 (-0.82%) as well.

Overnight in Asia, there’s been a similar theme, with the selloff in chip stocks contributing to sizeable losses for the major indices. South Korea’s KOSPI (-5.44%) has seen the biggest declines this morning, but there’s also been sharp moves for the Nikkei (-2.85%), the CSI 300 (-2.41%) and the Shanghai Comp (-1.96%). The main exception to that pattern has been the Hang Seng (+0.24%), with a modest advance. But equity futures are pointing to further declines today in the US and Europe, with those on the S&P 500 (-0.11%) and the DAX (-0.17%) both moving lower.

In other news overnight, President Trump announced a 3-day pause on the 50% tariffs on Canada that had been scheduled. He said this was “based on the fact that Canada and the U.S.A., subject to the finalization of documents, have a DEAL!” We don’t have the full details, but in a White House proclamation, it said that “Canada has expressed a commitment to remove the discriminations or unreasonable and unequal impositions” relating to US alcohol, dairy, and autos. Meanwhile on the Canadian side, Prime Minister Carney didn’t say there’d been a deal, but a statement from him said “Substantial progress has been made, although there is important work still to be done.” The announcement led to a small rally for the Canadian Dollar, which is up +0.13% against the US Dollar this morning.

Otherwise yesterday, UK gilts outperformed their European counterparts after the latest labour market data came in on the dovish side. It showed payrolled employees falling by -13k in July (vs. unch expected), whilst the unemployment rate was at 4.9% in the three months to June (vs. 4.8% expected). Moreover, private sector wage growth (ex bonuses) was only at +2.8% year-on-year in the three months to June, the slowest pace since 2020 during the pandemic. So 10yr gilt yields were only up +2.1bps on the day to 5.08%, a smaller increase than elsewhere.

In Germany, the latest ZEW Survey came in stronger than expected, with the expectations component rising to 34.2 in August (vs. 30.0 expected). That’s the highest level since February, before the Iran conflict began.

Looking at the day ahead, data releases include the UK CPI release for July. From central banks, we’ll get the minutes from the FOMC’s July meeting and hear from ECB President Lagarde. Finally, earnings releases include Target, Lowe’s, and TJX


Tyler Durden
Wed, 08/19/2026 – 08:34

Holy Grail In Cancer Treatment? Moderna Erupts After Melanoma Vaccine Late-Stage Trial Success

0
Holy Grail In Cancer Treatment? Moderna Erupts After Melanoma Vaccine Late-Stage Trial Success

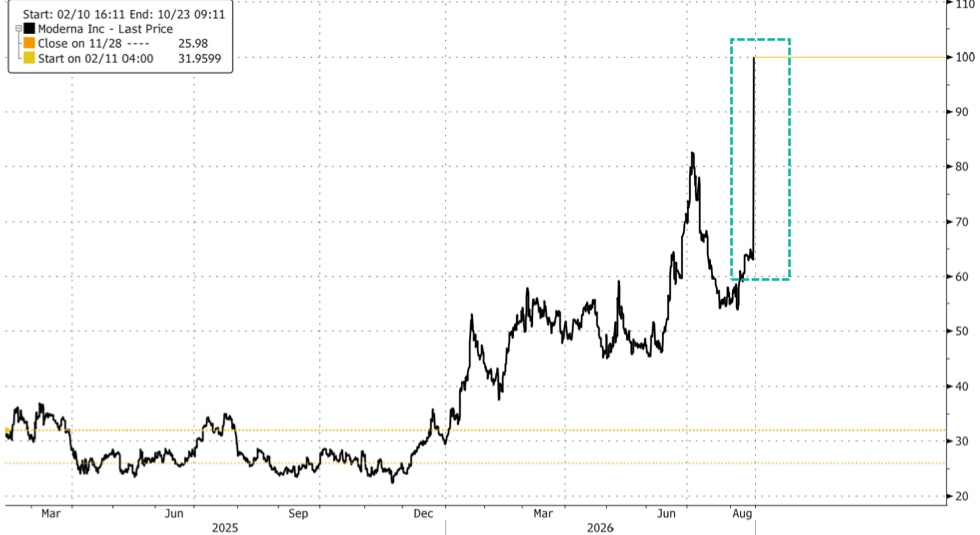
Moderna’s shares soared as much as 83% in premarket trading in New York after its personalized cancer vaccine, developed in collaboration with Merck & Co., reduced the risk of melanoma returning in a large, late-stage trial. The result marks the first positive Phase 3 trial for a personalized cancer vaccine by any company. 

The study met its primary endpoint by showing that the cancer vaccine, called intismeran autogene, combined with Merck’s blockbuster immunotherapy Keytruda, improved recurrence-free survival compared with Keytruda alone. The study also met a secondary endpoint by reducing the risk of cancer spreading to other parts of the body.

Professor Georgina Long, the study’s principal investigator, medical director of Melanoma Institute Australia, and chair of Melanoma Medical Oncology and Translational Research at the University of Sydney, wrote in a statement:

Today’s results represent a landmark moment for adjuvant melanoma treatment. This is the first Phase 3 study to show that intismeran, a treatment designed based on the unique mutational ‘fingerprint’ of a patient’s own tumor, given in combination with pembrolizumab, can reduce the risk of recurrence or death in patients with completely resected stage IIB-IV melanoma compared with KEYTRUDA alone.

Intismeran in combination with pembrolizumab has the potential to establish a new treatment paradigm in the adjuvant melanoma setting, helping patients remain cancer-free for longer.

Moderna and Merck did not disclose exact figures showing how much the therapy improved recurrence-free survival. The trial remains ongoing. Additional details will be presented at an upcoming medical meeting, and the vaccine could receive approval as early as 2027, depending on the regulatory review.

As of 0700 ET, Moderna shares were up 60% and trading around $100 per share. Short interest represents 13.5% of the float, equivalent to 49.8 million shares. Merck shares are up 7% in premarket as well. 

Melanoma is the most serious form of skin cancer. About 112,000 people are diagnosed annually in the US, and about 8,500 die from the disease, according to the American Cancer Society.

“Therapeutic vaccines have been something of a holy grail in cancer. People have been trying to do this for, you know, over 100 years in one way or another,” Jane Healy, head of oncology early development at Merck, said in an interview with Bloomberg several weeks ago. She noted that one potential benefit of the personalized shot would be to extend survival without significantly increasing side effects.

Tyler Durden
Wed, 08/19/2026 – 07:40

Georgia Man Deported From Fiji Charged Over $165 Million Crypto Ponzi Scheme

0
Georgia Man Deported From Fiji Charged Over $165 Million Crypto Ponzi Scheme

Authored by Kimberly Hayek via The Epoch Times,

A Georgia man accused of wire fraud and money laundering appeared in a Los Angeles federal court on Monday after being deported by Fijian authorities to face the charges following his flight to the South Pacific island.

A price chart on the Bybit website for the cryptocurrency Ethereum on a computer screen in New York City on Feb. 21, 2025. Patrick Sison/AP Photo

Prosecutors alleged the 59-year-old Edward Zimbardi, of Flowery Branch, Georgia, ran a Ponzi scheme that made more than $165 million from thousands of investors between June 2022 and August 2023.

An attorney for Zimbardi could not be reached.

U.S. Attorney Theodore S. Hertzberg, who described ponzi schemers as “parasites” the day of the Department of Justice announcement, detailed the allegations.

“Zimbardi allegedly tricked thousands of people to invest in his ‘Crypto Program’ with false promises of enormous returns,” Hertzberg said. “Instead, he spent the money on risky currency trades, payments to early investors, and treating himself to a house and expensive vehicles.“

When the scam was discovered, he allegedly tried to evade federal prosecution by fleeing to Fiji before he was found by authorities and returned, the prosecutor said.

Marlo Graham, special agent in charge of FBI Atlanta, noted that Zimbardi allegedly preyed on unsuspecting individuals through a complex scheme. FBI Atlanta is seeking victim information to aid the investigation.

“Scammers are trying everything they can to defraud people out of their hard-earned money, but the FBI is doing everything we can to make sure they don’t succeed, no matter where they hide,” Graham said.

According to the charges and information presented in court, Zimbardi allegedly promoted The Crypto Program through videos and websites, telling potential investors it was a chance to buy advertising packages that would deliver a guaranteed 25 percent monthly return.

Investors were advised to send cryptocurrency to digital wallets, which, prosecutors alleged, were secretly controlled by Zimbardi. Thousands of people sent more than $165 million his way.

Instead of advertising packages, Zimbardi allegedly put more than $34 million into risky foreign currency trades and lost a substantial portion of it. In order to keep the scheme running, he allegedly used money from later investors to pay earlier ones. He also allegedly spent at least $10 million on personal expenses, including a house for his son, luxury vehicles, and alimony payments to his ex-wife.

The program collapsed in August 2023, and victims lost their funds. Zimbardi then traveled to Hawaii, Fiji, and other places.

In July 2025, after learning of the FBI investigation, he fled to Fiji and stayed more than a year. In May, he canceled plans to attend his son’s wedding in Virginia, suspecting agents would attempt to arrest him there.

Fijian authorities deported him after learning of the charges in coordination with the FBI and the U.S. Department of State.

A federal grand jury had already indicted Zimbardi on July 8. The indictment charges him with 12 counts of wire fraud, 12 counts of money laundering, and one count of money laundering conspiracy.

Tyler Durden
Wed, 08/19/2026 – 07:20

Unitree IPO Soars 460% As “Strong Retail Appetite” May Ignite Physical AI Listing Boom

0
Unitree IPO Soars 460% As “Strong Retail Appetite” May Ignite Physical AI Listing Boom

Summary:

  • Unitree Soars 460% in Shanghai IPO 
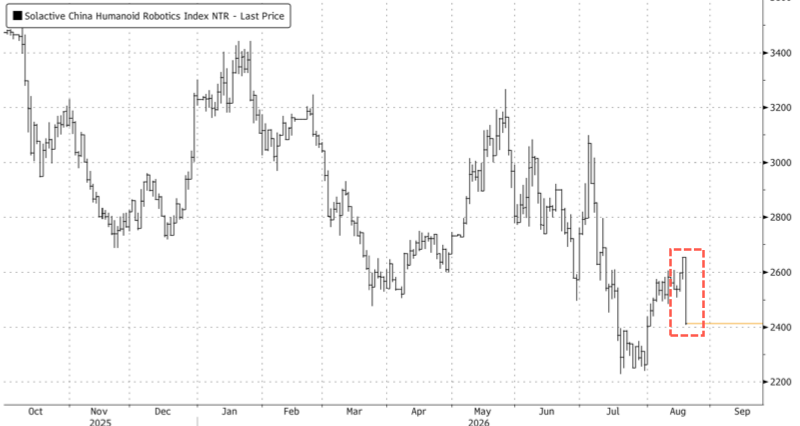
  • Solactive China Humanoid Robotics Index Plunges As IPO “Drew Funds Away” 
  • Unitree IPO 5,550 Times Oversubscribed As UBS Says Grey Market Points To 3.5x Open

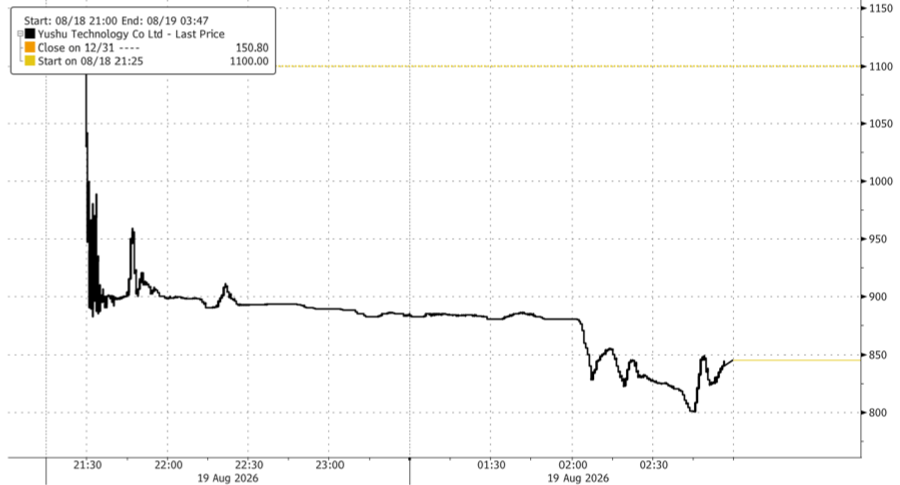
Unitree Robotics, one of the most closely watched technology IPOs in Shanghai this year, made its trading debut earlier Wednesday and closed up a staggering 460%. The Chinese humanoid robot maker raised 6.1 billion yuan, or about $904 million.

The Hangzhou-based company, formerly known as Yushu Technology Co., climbed as much as 629% from its IPO price of 150.80 yuan before paring some of those gains.

Retail bids for Unitree exceeded the 7.07 trillion yuan raised by memory chip giant CXMT in its July IPO. We pointed out yesterday, hours before the IPO, that the offering was more than 5,500 times oversubscribed.

Unitree plans to use the IPO proceeds to improve AI models, advance humanoid robot research, develop new products, and rapidly expand manufacturing capacity to maintain its lead in the physical AI race and expand market share. 

Bloomberg Intelligence analyst Ian Ma said, “Unitree’s debut surge signals strong appetite for China’s embodied AI sector,” adding that the IPO proceeds should accelerate product development and commercialization. 

Analysts at Industrial Securities commented on the broad market reaction across the space, saying, “Robotics stocks plunged as Unitree Robotics’ strong trading debut in Shanghai drew funds away.”

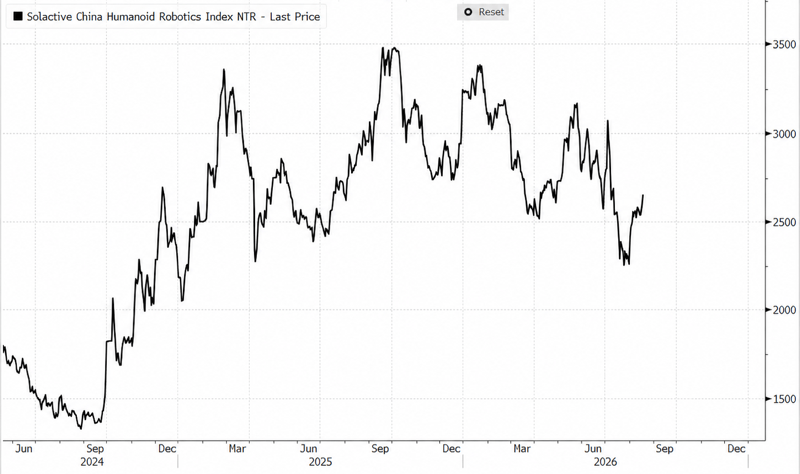
The Solactive China Humanoid Robotics Index (Bloomberg ticker: SOLCHRBP Index), which tracks publicly traded Chinese companies involved in the humanoid robotics supply chain, dropped 10% following the listing. The index is down 25% this year.

UBS analyst Lucy Zhang pointed out that the listing debuted amid an overall market selloff:

A-share tech names followed the US and broader Asia tech selloff, with the STAR50 down 6% amid elevated bond yields and geopolitical uncertainty.

Market leadership rotated into defensive sectors, including banking, energy and coal.

Retail flows remained heavily concentrated in recent IPO speculation rather than broader market beta, with Unitree (#688836 CH) the focal point, trading around RMB885/share and up 486% from its IPO.

Extreme two-way price action suggests increasingly speculative trading conditions. Half-day turnover reached RMB1.63 trn, while market breadth was extremely weak, with 4,927 decliners vs. 580 advancers.

Coal stocks outperformed as a defensive haven amid the tech pullback, supported by planned coke price increases of RMB50-55 per tonne effective Aug. 20. Robotics names fell 7% as a group, with Unitree’s debut triggering a sell-the-news rotation across the sector.

Enthusiasm for Unitree has grown after the robot maker shipped more than 5,500 humanoid robots last year, according to its prospectus. That makes the company the global leader in shipments of humanoid robots, far exceeding any US company. 

JPMorgan analysts have forecast that global shipments of humanoid robots will surge from 18,000 units in 2025 to 60,000 by the end of this year and to 1.75 million by 2030, with China accounting for more than half of global demand.

Readers should not be surprised that China is leading the humanoid-robotics race. We have outlined this trend on multiple occasions (see here).

Unitree IPO 5,550 Times Oversubscribed As UBS Says Grey Market Points To 3.5x Open 

The global market leader in humanoid-robot shipments, China-based Unitree, is set to begin trading on Shanghai’s STAR Market on Wednesday, potentially sparking a wave of robotics listings in Asia as the race for physical AI remains in its early innings. 

The Wall Street Journal reported that the Hangzhou-based company raised $900 million after pricing its shares at 150.80 yuan apiece, implying a valuation of about $9.1 billion. Retail demand was off the charts, with investors submitting 9.8 million orders and the offering more than 5,500 times oversubscribed. 

“Unitree’s IPO is significant because it provides an important A-share valuation benchmark for embodied AI and humanoid robotics,” Morningstar analyst Kangyuxiao Li said.

Jacqueline Du, Goldman’s head of China Industrial Technology research, recently explained that Unitree is the global market leader in humanoid-robot shipments: 

Global Market Leader: In 2025, Unitree shipped more than 5,500 humanoid robots, capturing a 37% global market share, according to Omdia.

This volume far outstripped Western peers such as Tesla, Figure AI, and Agility Robotics, each of which shipped around 150 humanoid robots in 2025, according to public reports cited by Omdia.

That said, this leadership was achieved during the very early stages of the humanoid-robot industry, where technology is evolving rapidly and the competitive landscape remains fluid.

Wednesday’s IPO gives mainland investors direct exposure to one of China’s top robotics companies and could pave the way for future listings by its domestic competitors. 

UBS analyst Tony Chalmers noted:

Unitree is set for its first day of trading on the STAR Board on Aug. 19 at a CNY61 bn market cap, or 219x PS, with a free float of only ~30 mn shares, representing 7.4% of total shares. The grey market is pointing to a ~3.5x open.

The pre-IPO perpetual contract on the Hyperliquid platform – not Unitree stock or IPO allocation – is about $99.50 per contract; the market implies a Unitree valuation near $40 billion, based on roughly 404.5 million post-IPO shares. That is more than four times the reported $9.1 billion IPO valuation. 

In markets, the Solactive China Humanoid Robotics Index (Bloomberg ticker: SOLCHRBP Index), which tracks publicly traded Chinese companies involved in the humanoid-robotics supply chain, is down 18% year to date.

SOLCHRBP covers robot manufacturers and suppliers of AI systems, actuators, motion controls, sensors, automation equipment, and other components. 

Goldman’s Du highlighted how Unitree’s pricing advantage is mostly underpinned by “China’s supply-chain advantages.” Unitree offers robots priced from roughly $4,000 to $100,000, compared with about $150,000 to $1 million for Boston Dynamics models.

Readers should not be surprised that China is leading the humanoid-robotics race. We have outlined this trend on multiple occasions (see here).

The big question is whether President Trump can close the gap, given that the US lacks the fully integrated supply chains needed to manufacture critical components, including rare-earth magnets and actuators that power these robots.

Tyler Durden
Wed, 08/19/2026 – 07:05