58.9 F
Chicago
Monday, September 14, 2026
Home Blog Page 149

Gas Prices Nearing Levels That Could Push Trump Towards Iran Talks, Says JPM Commodities Expert

Gas Prices Nearing Levels That Could Push Trump Towards Iran Talks, Says JPM Commodities Expert

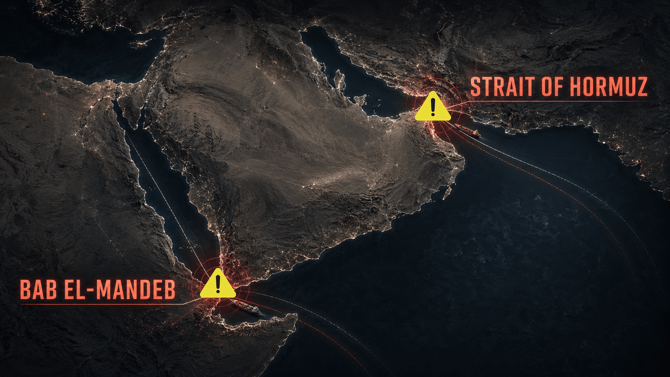
One of the main macro drivers this week remains the Gulf energy shock, as chokepoints from the Strait of Hormuz to Bab el-Mandeb are disrupted. Turmoil in the Black Sea between Russia and Ukraine is also sending chills through commodities desks.

Related energy coverage:

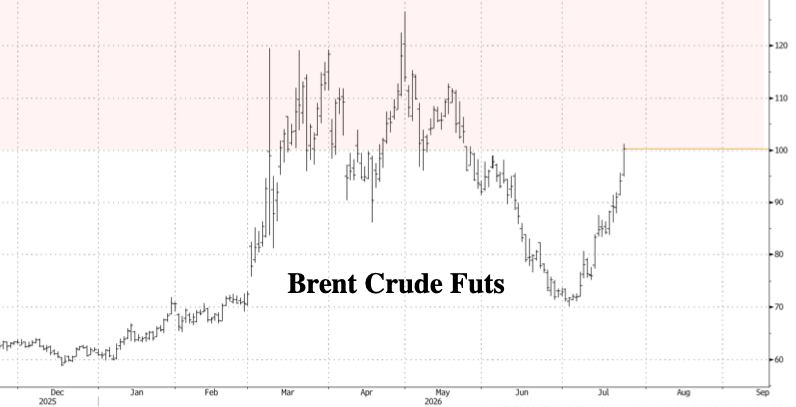
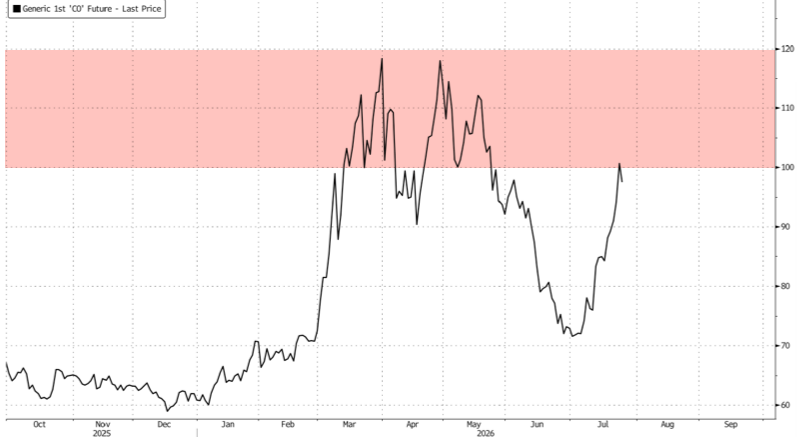
Brent crude is back above $100 a barrel, while WTI has reached $92, pushing Treasury yields higher, tightening financial conditions and weighing on duration-sensitive and consumer-facing stocks.

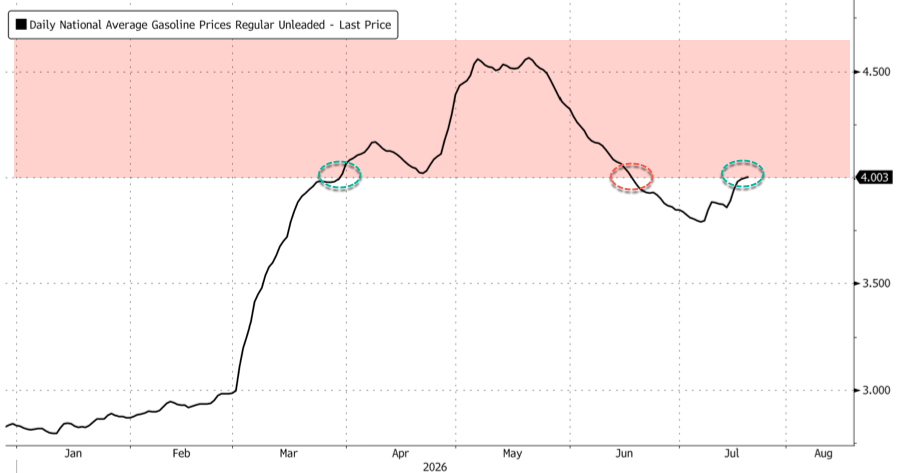
At the start of the week, AAA data showed that while prices vary across states…

… the national average for regular gasoline had exceeded the politically sensitive threshold of $4 per gallon.

And going higher…

JPMorgan’s head of Global Commodities Research and Strategy, Natasha Kaneva, told clients that Brent should average about $94 a barrel if the conflict is contained to one month, with each additional month of disruption adding roughly $7 to $8 as global inventories shrink.

Kaneva warned that a three-month disruption could lift Brent to around $114, while a 1 million barrel-per-day recovery in Chinese imports would add another $3 to fair value.

Related:

Under her base case, Brent averages $86 in Q3 and $80 in Q4, allowing gas prices to fall from just under $4 in August to about $3.30 by year-end.

However, she noted that another month of disruptions across the maritime chokepoints would push pump prices toward $4.20, while a two-month extension could lift them above $4.50.

Kaneva also pointed out that the $4.20 and $4.50 thresholds are where the Trump administration would likely face intensified political pressure to negotiate with Iran.

In the previous round of escalations, negotiations were initiated once US gasoline prices reached $4.20 and became materially more urgent as prices neared $4.50 (Figure 10). Oil may be a global commodity, but political tolerance for high energy prices remains overwhelmingly domestic

Separately, gasoline above $4 represents a line in the sand at which working-poor consumers begin trading down at convenience stores and gas stations, while broader sentiment shifts to the downside, which only means the political pressure heats up for Trump when gas prices rise north of $4.

Tyler Durden
Fri, 07/24/2026 – 11:20

Trump Must Hand Over Finance Records Sought By BBC In Defamation Lawsuit, Judge Rules

Trump Must Hand Over Finance Records Sought By BBC In Defamation Lawsuit, Judge Rules

Authored by Rachel Roberts via The Epoch Times,

A judge in Florida has ruled President Donald Trump must hand over financial records sought by the BBC for its defense against his $10 billion defamation lawsuit.

The U.S. president is suing the corporation over an episode of “Panorama” that edited together different sections of his speech on the day of the Capitol breach in Washington on Jan. 6, 2021.

The BBC reported that Judge Enjoliqué Lett granted a motion by the corporation’s legal team to compel the release of financial records held by the Donald J. Trump Revocable Trust, created to manage his businesses while he is president.

‘Partial Success’

The judge’s ruling at Tuesday’s opening hearing in Miami can still be appealed, but the BBC said it amounts to a “partial success” in its attempt to force Trump to provide evidence for his claim that he suffered financial loss due to the Panorama edit.

The defamation case is currently at the discovery phase, where both sides must provide documents, internal or otherwise, that could form part of their evidence.

The corporation has produced 87,000 pages of documents, according to the BBC’s lawyers, who said Trump’s legal team had released a “sham production” of 735 pages, which they said were “news articles” and other material “pulled from the internet.”

Charles Tobin, counsel for the BBC, said this meant the discovery process had been “entirely one-sided.”

‘Fishing Expedition’

Trump’s legal team accused the BBC of a “fishing expedition” with subpoenas designed to “harass” former officials.

Alejandro Brito, counsel for Trump, described the BBC’s “sweeping” requests for documents as “oppressive.”

He opposed the BBC’s requests for records of Trump’s conversations with aides relating to the events of Jan. 6, as well as subpoenas issued to federal agencies and former officials.

The BBC said that the president’s lawyers focused on a letter of apology sent from the corporation’s chairman, Samir Shah, to Trump in November last year, describing it as a “concession” and “admission.”

Shah wrote in the letter that the Panorama episode in question had “unintentionally created the impression … that President Trump had made a direct call for violent action.”

The judge’s decision opens the door for the BBC to peruse the finances of more than 400 companies owned by the Trump family trust.

President Donald Trump looks on during a rally in Washington, on Jan. 6, 2021. Jim Bourg/Reuters

A spokesman for Trump’s legal team told The Epoch Times via email: “The formerly respected and now disgraced BBC defamed President Trump by intentionally, maliciously, and deceptively doctoring his speech in a brazen attempt to interfere in the 2024 Presidential Election.

“The BBC has a long pattern of deceiving its audience in coverage of President Trump, all in service of its own leftist political agenda. President Trump’s powerhouse lawsuit is holding the BBC accountable for its defamation and reckless election interference just as he has held other fake news mainstream media responsible for their wrongdoing.”

Motion to Dismiss

The BBC has sought to have the entire case dismissed, arguing the documentary was not broadcast in the United States. The court has yet to rule on this, but Judge Altman denied the broadcaster’s application to stay the discovery phase of the lawsuit.

In court documents released on March 17, lawyers for the BBC argued that the lawsuit could have a “chilling effect” on “robust reporting on public figures and events.”

The BBC’s flagship “Panorama” program came under scrutiny last November over an episode broadcast on Oct. 28, 2024, a week before the U.S. presidential election.

Through cutting and splicing together different sections of his speech, the documentary created the impression that Trump had encouraged violence at the Capitol building on Jan. 6, 2021, according to critics and Trump’s legal team. Protesters had gathered in Washington to show they disputed the result of the 2020 presidential election, won by Joe Biden.

The BBC’s 34-page legal document cited a “lack of personal jurisdiction” and a “failure to state a claim” among the grounds to dismiss the lawsuit.

Lawyers for the broadcaster argued that Trump’s subsequent election victory in 2024 demonstrates that no serious reputational harm was caused by the “Panorama” broadcast.

(Left) Former CEO of BBC News Deborah Turness at an event in London on Oct. 13, 2022. (Right) Former BBC Director-General Tim Davie at the BBC World Service in London on April 28, 2022. Leon Neal/Getty Images, Hannah McKay/Pool/AFP via Getty Images

Trump is unable to sue the corporation in England, as the statute of limitations for defamation is only one year. His lawyers filed the claim in the southern district of Florida, where the statute of limitations is two years, in December last year.

The BBC argues that the state of Florida has no jurisdiction because Trump cannot demonstrate that the corporation “purposefully aimed the documentary at Florida” and that it was clearly made for the UK audience.

BBC iPlayer is geo-blocked in the United States, although Trump’s lawyers have argued that it could be accessed by Americans using a virtual private network.

The BBC is funded by a license fee that is supposed to be paid by every UK household that watches live television, although the number of people purchasing a license has fallen in recent years, leading to cutbacks.

BBC Director-General Tim Davie and head of news Deborah Turness both resigned in November following the scandal over a leaked internal report highlighting apparent bias at the corporation, including the “Panorama” edit.

Matt Brittin, a former Google senior executive, took over as the corporation’s director-general in May.

Tyler Durden
Fri, 07/24/2026 – 11:00

Yet Another Wildberries Facility – Russia’s Amazon – Goes Up In Flames After Ukraine Drone Strike

Yet Another Wildberries Facility – Russia’s Amazon – Goes Up In Flames After Ukraine Drone Strike

Another large warehouse and logistics hub for major online Russian retailer Wildberries has been targeted and struck by Ukrainian drones.

This is the third time in a week the company widely considered to be the ‘Russian Amazon’ has seen its warehouses go up in flames. At least eight of its shipping facilities have been attacked overall this month. Wildberries co-founder Tatyana Kim confirmed the fresh attack on company facilities Friday morning:

Kim, Russia’s wealthiest woman, said Wildberries facilities in St. Petersburg and the surrounding Leningrad region, as well as in annexed Crimea, were hit overnight. Fires broke out at several locations, though Kim said “parts” of the warehouses were saved.

While Kim said none of the company’s employees were injured, Leningrad region Governor Alexander Drozdenko wrote in a post on Telegram earlier in the morning that three people were hurt during the attack in his region.

Moscow Times via Telegram

Operations at these facilities have been halted, while all personnel a the impacted warehouse in Crimea have been evacuated.

The St. Petersburg attack resulted in especially dramatic scenes of a huge smoke plume stretching high into the atmosphere, and even visible from space, NASA satellite imagery showed.

It was just last week that the company’s warehouses in central Russia were struck, which killed eight people. In the face of the Kremlin calling the attacks acts of terrorism and war crimes, Ukrainian President Volodymyr Zelensky has claimed that the hubs were “involved in providing the Russian army with drone components, navigation equipment and other gear.”

The Wildberries facilities have been increasingly targeted amid broader nightly drone waves out of Ukraine, with a separate Friday attack in the Kirov region killing at least six people.

Anadolu/Getty Images

NBC News has noted, “Wildberries, whose banking arm had sanctions imposed on it by the European Union this week over its financial contribution to the Russian budget, plays a central role in Russia’s consumer economy.”

“Its targeting by Ukraine appears to be part of Kyiv’s attempts to ensure ordinary Russians feel the impact of the war which has raged on Ukrainian territory for more than four years,” the report adds.

The company says it is working around the clock to restore service to areas impacted by the warehouse attacks. 

Stunning footage of Wildberries hub fully on fire from earlier this week in Krasnodar:

Reuters has reviewed that “Together with smaller rivals, Wildberries and Ozon sell goods and services worth the equivalent of 8.5% of Russia’s gross domestic product. They provide jobs for 4 million people, or more than 5% of the country’s workforce.”

Tyler Durden
Fri, 07/24/2026 – 09:40

“It’s Getting Worse”: HSBC Warns Commodities Face Squeeze As Chokepoint Chaos Spreads

“It’s Getting Worse”: HSBC Warns Commodities Face Squeeze As Chokepoint Chaos Spreads

The key takeaway heading into the weekend is that maritime chokepoint chaos has spread from the Strait of Hormuz to the Bab el-Mandeb Strait, while fighting across the Black Sea has intensified between Russia and Ukraine. The widening disruptions have prompted several institutional desks this week to warn that a potential squeeze on physical commodity markets could send prices from energy to agricultural goods higher.

“The Middle East conflict has escalated, putting a substantial squeeze back into commodity markets,” Paul Bloxham, HSBC’s chief economist for Australia, New Zealand and global commodities, wrote in a note on Friday morning.

Bloxham continued, “Traffic through Hormuz has almost stalled again, and the disruption has spread to the Bab el-Mandeb Strait, the key access point for the Red Sea, for Saudi oil going to Asia and Europe-Asia trade through the Suez Canal.”

Bloxham warned that with Brent trading above $100 a barrel and strategic petroleum reserves being rapidly depleted worldwide, energy markets face a mounting risk of a “super-squeeze.”

His message was blunt: “It’s not over yet,” adding, “Hormuz, Mandeb, oil at 100 … it’s getting worse. “

Here’s more:

The Brent oil price has risen sharply, to over USD100/b recently; European and Asian gas prices are more than 40% m-o-m; refined product prices, like jet fuel and diesel are surging; urea prices are up 13%; and wheat prices are at a three year high – all on supply constraint concerns. With inventory rundown having been a key adjustment factor preventing much bigger prices spikes earlier in the conflict, and stocks now much lower, concerns about ‘tank bottom’ levels and non-linearities are expected to come back into focus. It’s a ‘super-squeeze’. And it’s not over yet.

Bloxham also highlighted the market mechanics that prevented Brent from spiking even higher a few months back, including US strategic reserve releases and China’s reduction of oil imports and SPR.

But he warned that these buffers are finite and can suppress the price shock for only so long:

As we have actively written about over the past few months, a key reason that commodity prices – particularly oil – did not spike higher earlier has been active reduction of inventories, particularly with the US release of strategic reserves and in China, where oil imports have been drawn down (see ‘Better, but the Hormuz disruption is not over yet’, 25 June 2026; and ‘Hormuz is reshaping commodity markets’, 25 May 2026).

However, the challenge is that inventory reduction can only provide an offset for so long.

At some point, concerns about stocks falling to critical levels may show up in non-linearities in markets (see Hormuz still closed: Beware Strait non-linearities, 28 April 2026). However, even with a deep-dive looks at measured stocks and supply pathways, it is hard to be definitive about when reserves will reach these critical levels. Commodity markets are highly adaptable, and when the demand is there, flexible markets often find a way to deliver. Aggregate price benchmarks also only go so far. In the face of acute supply shocks, commodity markets tend to fragment, with many different prices for the same products in different locations and for different delivery times (see More fragmentation as Hormuz blockage continues, 13 April 2026).

That said, the longer the disruption is in place – and the recent escalation suggests it is, indeed, going on for longer – the more likely it becomes that commodity prices will spike higher, in non-linear ways, as stocks are depleted.

A growing list of institutional commodity desks, including Goldman Sachs, RBC Capital Markets and JPMorgan, has warned that the expanding maritime chokepoint crisis is entering a more dangerous phase.

Helima Croft, RBC’s head of global commodity strategy, cautioned that the “war enters a dangerous phase with the Red Sea and critical infrastructure at risk.

These desks have raised their near-term Brent forecasts as the disruption spreads. Goldman commodities strategist Daan Struyven warned that Brent could exceed $120 a barrel in the fourth quarter if the Hormuz crisis persists.

Related:

With the US national average for regular gasoline now above $4 a gallon, the energy shock has crossed a politically sensitive level (again), which could increase pressure on the Trump administration to pursue a diplomatic off-ramp.

Tyler Durden
Fri, 07/24/2026 – 09:20

Braggawatts, Cheap Chinese Compute, & Simple ROI

Braggawatts, Cheap Chinese Compute, & Simple ROI

Authored by Peter Tchir via Academy Securities,

With weakness in chips and AI the prior week, that was a major topic of conversation, as was the escalation in Iran (please see Academy’s Geopolitical Analysis for the latest on Iran and geopolitics more broadly).

Two key themes from last weekend’s From Trinkets to Compute seem to be playing out:

Cheap Chinese Compute

Most importantly, the story of Cheap Chinese Compute is garnering staying power. While DeepSeek may have been a one-off, the story is increasingly about China delivering Cheap Compute. We have seen China flood/control markets in the past. I didn’t see it coming in compute (at least not yet), but it might be here?

  • China doesn’t have to deal with NIMBY, but they do make a lot of chips (generally lower quality, but a lot), and have been ramping up all forms of electricity production and storage for years. The U.S. is finally getting on board with this ProSec™ theme, while the rest of the world is only starting to wake up to the need and potential opportunity that adopting a ProSec™ mindset delivers.

  • On the less “savory” side are “allegations” (and I’m being polite here) that a lot of the Chinese compute trains by “distilling” from existing models (inundating existing models with requests, to somewhat “copy” their answers) rather than training their models from scratch. It is a big cost advantage and time saving mechanism.

Earnings

Less important was my flipping from “earnings will matter” to “earnings might not matter.”

We don’t really spend a lot of time on single stock earnings. It isn’t our “thing” in general. But we do follow the earnings. What we can say so far on this front is that when the earnings and announcements hit the tape, they seem very strong. The instant reaction in the media (and social media) tends to support the strength of the results. Then the stocks seem to drift lower (in some cases worse than drift). 

The earnings bar seems to be set incredibly high, so far.

This is concerning when trying to determine the direction of the next leg.

Braggawatts

I’m not sure how I missed the term Braggawatts, but it caught my attention when my friends at ZeroHedge sent out a tweet that used the term.

  • Basically, braggawatts is a term used to express skepticism over how much in the data center and AI space can be physically constructed (i.e., in the real world) versus all the existing announcements and expectations of future announcements.

    • From access to chips, to water, to electricity, to getting all of the various state and local regulatory approvals, the argument is that a lot more compute has been announced than can be completed within the timeframe of the announcements.

    • This is consistent with some anecdotal evidence of cost and time overruns on projects (that is something we were hearing about more frequently than in the past).

If braggawatts are real (we need to explore this more):

  • This should be good for credit spreads in the sector. The logical conclusion would be to announce fewer new projects and prioritize existing projects.

  • Would be bad for the “picks and shovels” in the AI / Data Center industry.

Simple ROI.

To a large degree, return on investment analysis surrounding AI and the AI spend has been minimal in my view.

  • On the one side you have a “build it and they will come” mentality (often the “only” risk has been described as not building enough, fast enough – which hardly encourages traditional scrutiny of costs versus revenue).

  • On the other side, no CEO in their right mind would say anything other than that they were launching AI initiatives within their firm to capture efficiencies. The cost of compute has gone up. Actually, let me rephrase that, companies are being charged a cost of compute more in line with the cost of producing the compute than they were before. While the cost of providing compute seems to be increasing (shortages, etc.) part of what users are seeing is that the price that was subsidized to encourage use and to create moats (to the extent moats can be created and held) is being subsidized less. Increasing, and we’ve been writing about this for months, we are moving from “we have to try AI, or be left behind” to “we’ve been using AI, now let’s analyze the cost benefit of that.” Is that why some of the token utilization charts are showing declines from the peak?

If I’m right and some of these forces connect, it could bring pressure to bear on the space. That is “fine and normal.” What concerns me is how much money has flown into passive vehicles in the space, and how many leveraged products there are in the space. Not just the very large SOXL (which is index based) but also a lot of individual stocks in this have leveraged ETFs. 

I fear that this is a risk that can and will accentuate moves to the downside (just like it does on the upside).

Bottom Line

The escalation in Iran is not good for my view on potential rate cuts. While my outlook on inflation wasn’t entirely dependent on the free flow of oil (including more oil that had previously been sanctioned), it helped a lot.

On the AI front, I’m positive on credit spreads, but remain vigilant on valuations. The recent reaction in markets to what seemed like strong earnings releases only accentuates that concern.

Tyler Durden
Fri, 07/24/2026 – 09:00

Trump Losing Patience, In ‘Revenge Mode’ After 13th Consecutive Night Of US Strikes On Iran

Trump Losing Patience, In ‘Revenge Mode’ After 13th Consecutive Night Of US Strikes On Iran

The latest little peace overture by Washington widely reported Thursday night was apparently a big nothingburger, as on Friday the Iraqi prime minister’s office has denied a New York Times report claiming that Iran rejected a US ceasefire proposal delivered to Tehran by Iraqi Prime Minister Ali al-Zaidi.

The fresh statement from the prime minister’s office said what was published in the Times was “entirely unfounded” and had “no relation to reality.” The statement underscored the temporary nature of the proposal and that it was the “only offer on the table” and still left the question of control over the Strait of Hormuz unresolved – and so Tehran was uninterested.

It’s also the reality that Tehran wants to see Trump sweat and impose economic and political costs particularly ahead of the midterms in November, where Congressional Republicans must face voters over failing to rein in Trump’s Iran war. The Iranians continue to openly voice this, for example in the following from the parliament speaker:

Meanwhile, in what is becoming a brutal, nightly routine, US Central Command (CENTCOM) has wrapped up its 13th consecutive wave of airstrikes against Iran. The Pentagon said it targeted military command centers, drone storage facilities, communication networks, and coastal surveillance sites

Iranian state media reported overnight into Friday heavy explosions rocking major hubs across the country, including Khorramabad, Jask, Ahvaz, Bandar Abbas, and the strategic outpost of Qeshm Island. Iranian media further said a US missile strike left four dead and five injured in the key industrial and transportation hub of Ahvaz.

As the bombs fall, Tehran is still signaling that military pressure won’t force a cheap surrender – with Iranian Foreign Minister Abbas Araghchi lashing out at the US escalation, warning that “mindless aggression” will only see Trump pay a “heavier price” for a deal to end the war.

Iranian retaliation on US-linked sites in the Gulf have continued at the same steady pace, with on Friday Bahrain’s military having intercepted “several treacherous Iranian air attacks” – according to the general command of the Bahrain Defense Force.

The Bahraini military further denounced Iran’s “systematic hostile approach” and “criminal attacks targeting civilians”. The statement emphasized, “The general command emphasises that the deliberate use of missiles and drones to target civilians and private property constitutes a flagrant violation of international humanitarian law.”

Throughout the morning the Iranian military’s targets also included locations in Jordan, Kuwait, and northern Iraq. Sky News is reporting that “Explosions were also heard near a base hosting the US in Iraq, near the Erbil International Airport.”

Fox feeding its Boomer audience some Freedom Viagra with a helping of war crimes on the side:

But Fox News also reports the results of its latest poll which finds 56% oppose the ongoing American military action against Iran, including 40% who “strongly” oppose. “Disapproval of President Donald Trump’s handling of Iran hit a record high in July,” Fox writes.

“A majority of voters oppose U.S. military action, and nearly two thirds think the conflict will last at least a year,” the report says.

 This as The Wall Street Journal does an entire investigative report which should be laughably obvious to any careful observer to what’s been going on and the deepening quagmire the US is getting itself into:

As the war in Iran enters its fifth month, Trump is increasingly frustrated that a conflict he once thought would be over in a matter of weeks has dragged on with no end in sight, administration officials and others close to the president said.

Some of Trump’s advisers now worry that the war—which has resulted in higher prices, falling approval ratings and the deaths of more than a dozen U.S. servicemembers—is consuming his presidency and damaging Republicans’ already dim prospects in the coming midterm elections.

Alarmingly, the WSJ noted that Trump seems in “revenge mode” against Tehran, and apparently sees no other options than to try and keep bombing his way out of it. Of course, this script has been written many times – not only during the “Global War on Terror” and this millennium’s “forever wars” – but going all the way back to the Vietnam war.

NBC: The four service members being flown from the Middle East to Dover Air Force Base were 28-year-old Angel S. Rampersad of New York, 30-year-old Michael Emmanuel Swinton of North Carolina, 25-year-old Tyler James Feehan of Hawaii and 19-year-old Isabella Gonzales of Texas.

President Trump attends a dignified transfer on Wednesday.

The war is said to be taking a heavy “toll” on Trump and his top officials. According to more of what’s also been glaringly obvious for anyone who has had a shred of independent thought:

The war is splitting the conservative coalition over which Trump once had an iron grip, worrying some Republicans close to the White House. Longtime Trump allies such as Fox News host Laura Ingraham have used their platforms to express concerns about how the war might affect Republicans in November’s midterm elections. On Monday, she said the “clock is ticking” to the midterms.

“Netanyahu has led us into a horrible conflict filled with lies,” Steve Bannon, a longtime Trump adviser, said. “People can see with their own eyes what’s going on.”

While this part about Netanyahu is true, it is ultimately President Trump who made the decision, after for years prior – and especially on the campaign trail – articulately spelling out that attacking Iran and starting new Mideast wars would be one of most idiotic foreign policy moves a president could make.

Trump on Thursday said he would take funds from Iran to pay for damage inflicted on US bases and assets throughout the war. Iran responded in the following…

Perhaps the utter folly of Operation Epic Fury has finally begun to dawn on the president. WSJ also observed that “Last month, the president was so excited at the prospect of signing the memorandum of understanding with Tehran to reopen the Strait of Hormuz that he was dismissive of Republican allies who said the Iranians would never stick to the agreement, according to a senior administration official. He wanted it to be over, Trump told them.”

Tyler Durden
Fri, 07/24/2026 – 08:40

NANO Nuclear And Fortil Advance Critical KRONOS Fuel System

NANO Nuclear And Fortil Advance Critical KRONOS Fuel System

NANO Nuclear Energy has pushed another critical piece of its KRONOS MMR program toward preliminary design, this time with French engineering group Fortil.

If there’s a corner of the French industrial sector that America should be comfortable leaning into, their nuclear segment is arguably the safest bet. Their 57-reactor fleet, accounting for 70% of the country’s electricity generation, is only surpassed by the US and Chinese commercial fleets.

The companies said conceptual design work is nearly complete on the reactor’s Fuel Handling & Storage System, which will manage the safe handling, storage and movement of nuclear fuel throughout operations. The work includes defining subsystem interfaces, evaluating engineering solutions and producing documentation needed for the next design stage.

It’s not the most glamorous part of a reactor, but it’s the sort of picks-and-shovels engineering that separates a reactor rendering from an operating nuclear plant.

Fortil’s dedicated nuclear team is handling multidisciplinary work across mechanical and systems engineering, nuclear safety, instrumentation and control, and radiation protection. The consultancy has more than 2,500 employees across 30 offices in 14 countries, giving NANO access to an international engineering bench as KRONOS moves toward potential fleet deployment.

The milestone follows the NRC’s formal acceptance of the KRONOS Construction Permit Application for a full-scale reactor at the University of Illinois Urbana-Champaign. The agency began formal review activities in June, with environmental and safety evaluations expected to progress through 2027. Initial construction could begin in the second half of next year.

NANO’s story has increasingly become about more than a single reactor. The company recently acquired Secured Transportation Services for $13 million, turning itself into a revenue-generating nuclear logistics operator. That business helped execute a record 1.7-metric-ton HALEU shipment from Japan and supported the removal of highly enriched uranium from Venezuela.

The company is in the midst of an aggressive and wide-ranging expansion plan with business segments across the nuclear value chain. In just the past year, they’ve advanced a proprietary HALEU transportation package, won a U.S. Air Force innovation contract, and signed an agreement with Supermicro targeting nuclear-powered AI data centers. Additional partnerships are targeting South Korea, the Gulf region and a potential 1-gigawatt Texas data center campus.

Tyler Durden
Fri, 07/24/2026 – 08:25

Inside Global Aerospace & Defense Boom: 12 Takeaways From World’s Most Important Airshow

Inside Global Aerospace & Defense Boom: 12 Takeaways From World’s Most Important Airshow

The Farnborough International Airshow is coming to a close in the UK, marking the end of one of the aerospace and defense industry’s top gatherings. Institutional research desks have had boots on the ground, tracking commercial-aircraft orders, defense procurement and other industry trends.

A team of Citi analysts led by John Godyn attended Farnborough earlier this week and reported back to clients Thursday morning.

Their findings pointed to accelerating missile demand and a wave of new aircraft orders that could fuel a stronger and more robust growth cycle for aerospace and defense companies.

Godyn highlighted the event’s key takeaways, giving clients a clearer picture of the aerospace and defense industries heading into fall and 2027:

1) Aftermarket channel checks across multiple companies extend recent strength.

We spoke with a wide range of aftermarket exposed companies including engine manufacturers, parts/component manufacturers, MROs, and aircraft lessors. Consistently, across all meetings, companies expressed the view that the key themes driving aftermarket continue including: (1) low retirement rates, (2) high lease renewals and tight secondary market trends for AC/engines, (3) strong demand for lift from global airline customers, (4) capacity constrained MROs, and (5) no impact from the conflict in the Middle-East. Given how strong recent trends have been, companies did caution that mean reversion to long term growth rates, which GE described as LDD revenue growth and many non-engine aftermarket players described as HSD revenue growth, was inevitable. We view the read-through as clearly positive across multiple stocks in our aftermarket coverage (GE/RTX/VSEC/LOAR/HEI) and EU analyst Conor Dwyer echoed that sentiment for Safran’s 2026. To be fair, we note that investor expectations are already set for continued beats in this category of stock so the bar isn’t obviously low.

2) M&A heating up?

Multiple companies we spoke to described an M&A backdrop that is much more active with many deals coming to market. Management teams described multiple drivers with notable emphasis on self-help activities at corporates focused on ramping production leading to non-core assets or underperforming suppliers being put up for sale, as well as PE-owned assets coming to market. We get the sense from most of our companies that the Aero M&A pipeline remains robust and multiple companies expect M&A to be a larger driver of growth. Valuations were regularly cited as reasonably full, but there remain opportunities to find deals at reasonable prices.

3) Airbus Next-Gen has been a dominant theme throughout the week.

The next generation Narrowbody Jet on the part of Airbus has been a ubiquitous theme throughout the week. GE indicated CFM collaboration with Airbus was very active on the RISE program (meeting 2x per month). Other component manufacturers expressed similarly heightened activity and discussion around the next generation Narrowbody Jet. Suppliers described conversations with BA on similar topics to be far earlier stage and having less consistent cadence.

4) GE emphasized more upside on CFM56 aftermarket $ profit and a quicker ramp on LEAP aftermarket $ profit than investors may appreciate.

GE noted that LEAP:CFM56 $ profits should be roughly equal by 2030. GE expects CFM $ profits to continue to grow until 2028 before flattening out, while LEAP $ profits continue to catch up until 2030. LEAP % margin will lag CFM56 even in 2030 and will continue to move higher as the LEAP installed base ages. We see a similar shape in our above-consensus expectations and see the possibility of additional upside as the belief that the aftermarket cycle lasts ultimately proves to be more robust than even GE management expects.

5) GE engine read-through positive.

The aforementioned CFM56:LEAP view is similar to Conor Dwyer’s assumed split for Safran within the next 5 years (he is 45:55 in 2030, reaching 49:51 in 2031). Conor notes that GE was quite relaxed about the threat of rising retirements in the coming years to the CFM56 program, but did note it is managing the risk of rising USM (used serviceable materials) already with slightly slower price increases on the CFM56 vs the LEAP and acknowledged the possibility of risk in 2029-31 (this is a risk Conor highlighted here in 2028).

6) Bullishness on emerging engine technologies was palpable.

Although we did not speak to RTX, we felt that GE upped the volume on its RISE engine and is increasingly and more loudly making the case for the innovative technology. Separately, multiple EVTOL players we met with showed evidence of progress on hybrid-electric engines punctuated by a GE/BETA hybrid-electric engine which was demonstrated live and recently was the first such engine to be tested above 30,000 feet.

7) Demand for accelerating missile production was a frequent topic of conversation.

At face value, this is no surprise, but channel checks emphasized 3 interesting points: (1) targets of 3-10x growth in production by program are likely to prove low because these forecasts do not incorporate international demand, so as ‘framework agreements’ are definitized, the supply chain is already being asked to ramp even higher to satisfy allies’ needs, (2) solutions for scalable hypersonic missile production are being requested, and (3) supplying into emerging affordable mass designs may be a bigger opportunity than initially thought. We continue to believe that Missile Defense/Munitions Replenishment are themes that will exceed expectations for years to come.

8) Positive secondary market trends supportive of aircraft lessors.

In particular: (1) a continued, favorable supply/demand mismatch in the secondary market driving lease rates higher across a wide range of aircraft types, (2) among narrowbodies, notable strength in the A321neo and 737MAX, (3) among widebodies, even greater strength in the A330neo and 787 families of aircraft, (4) a belief among lessors that existing production outlooks across the OEMs are unlikely to be a meaningful headwind to secondary market trends until the end of the decade, and (5) the view that a lack of customer support will dissuade airframe OEMs from pursuing new clean sheet designs this decade. In totality, these channel checks were not only positive for AER, but also much of our aerospace coverage.

9) Are 737 -7 and -10 certifications imminent?

Suppliers to whom we spoke expressed a tremendous amount of confidence in rate increases at BA in the short/medium-term. Suppliers also felt that events supportive of BA’s case for raising rates, namely the -7/10 certifications, were likely to happen sooner rather than later.

10) ETN mentioned that Aero could be in a historic “feast” cycle.

ETN Aero Management mentioned that it expects 16 new Aero-focused platforms launching over the next ten years vs. the last big Aero cycle in the 2000s where only five were launched. The majority of the new expected platforms will be military, and ETN Management seems confident that the company can enjoy considerable content on these platforms. We sense Management is particularly excited about the Bell MV-75 Helicopter program and the Collaborative Combat Aircraft program (CCA), although these programs are still in the early stages in terms of ramp up for ETN.

11) Aero supply chain slowly healing but will be tested with further rate increases.

In general, nearly every company we spoke to described the current aerospace supply chain as healthy and struggled to identify any major problem areas. In fact, being part of the solution was cited as an opportunity by many, such as VSEC, DCO, and HEI. Separately, both PH and ETN mentioned an increased focus on dual/multi-sourcing, which is leading to greater supply chain resiliency. Anecdotes of supply chain issues don’t seem widespread, and we also think Aero suppliers are increasingly leaning on improved software, electronics, and even additive manufacturing to further support the Aero manufacturing food chain. That said, the topic of defense orders using DPAS at some point in the future did come up as a risk factor that was cited as a realistic scenario that could disrupt the aero supply chain.

12) Aerospace suppliers’ ability to price still strong.

Suppliers throughout the A&D supply chain described negotiations as much more focused on availability, performance, quality, and on-time delivery rather than price and margins. We get the sense that A&D suppliers will continue to outpace inflation with solid pricing and likely expanding margins without much pushback. Pricing muscle seemed to improve substantially during the COVID supply chain “crunch”” and that has allowed suppliers to continue to rea

Another potential tailwind for the defense industry emerged Wednesday, when House Republicans narrowly passed the fiscal 2027 National Defense Authorization Act, authorizing a record $1.15 trillion in military spending.

The measure passed 216-212, largely along party lines. While it is below President Trump’s $1.5 trillion budget request, it still is a jump from the roughly $900 billion last year.

The NDAA faces an uncertain future in the Senate, where Democrats are expected to oppose its cost and several controversial policy provisions.

Related coverage:

If passed in the Senate and signed by Trump, the spending surge would provide tailwinds for defense stocks.

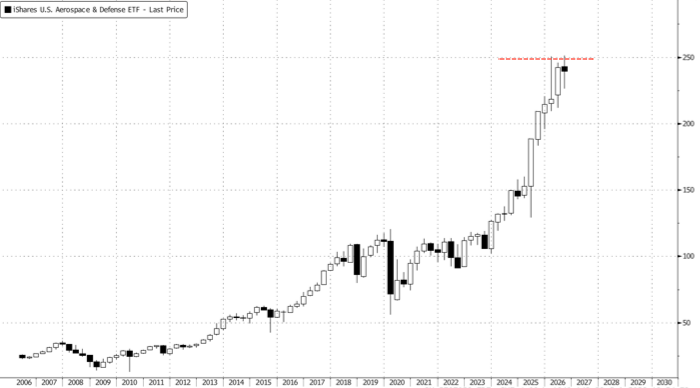
The iShares U.S. Aerospace & Defense ETF (ITA) has moved up and to the right, reflecting the boom in military spending as multiple wars rage across Eurasia. The global boom in defense spending has a lot more room to run.

ITA’s next leg up will require a sustained upside break above the $250 level. 

Professional subscribers can read military trends notes at our new Marketdesk.ai portal.

Tyler Durden
Fri, 07/24/2026 – 06:55

India’s Fuel Exports Set To Soar In July As Refining Margins Jump

India’s Fuel Exports Set To Soar In July As Refining Margins Jump

By Charles Kennedy of OilPrice.com,

India is on track to export the highest volume of refined petroleum products in months as refining margins have jumped with the re-escalation of the Middle East conflict.

India is estimated to ship as many as 1.55 million barrels per day (bpd) of light and middle distillates in July, per data by commodity analysts Kpler cited by Reuters columnist Clyde Russell.

The July volumes would be nearly double the fuel export volumes of just 866,000 bpd in May, when the Strait of Hormuz crisis hit crude supplies to India and the rest of Asia. In May, India saw its lowest fuel exports in four years.

The tightening fuel markets in Asia and the rest of the world added to a renewed rally in refining margins after the U.S.-Iran ceasefire collapsed two weeks ago. This has encouraged Indian refiners to ramp up refined petroleum exports.

The expected volumes in July would be the second-highest level in Kpler’s data series dating back to 2017.

Earlier this month, Kpler estimated that India’s refined petroleum exports would hit in July the highest level since September 2025 as refiners race to capture soaring margins amid tight Asian fuel markets.

India’s high export levels in July could ease some of the pressure on the Asian fuel market, but not all of it, as crude supplies from the Middle East are once again at high risk of delay.

Asian refiners that had bet on a flood of crude supply from the Middle East in August are now faced with potential delays in deliveries amid the re-escalation of hostilities, which could thwart their plans to ramp up crude processing rates in the coming weeks.

Refiners in the U.S. and Europe are operating at near capacity, but those in Asia may not see the expected increase in throughput now that the July and August loadings and delivery schedules have been upended by the re-escalation of the Middle East conflict.

Tyler Durden
Fri, 07/24/2026 – 06:30

Deaths Now Outnumber Births In 17 US States

Deaths Now Outnumber Births In 17 US States

Natural population growth is slowing across much of America.

According to the latest U.S. Census Bureau estimates, 17 states recorded more deaths than births between July 2024 and July 2025, up from only four states during much of the 2010s.

Using U.S. Census Bureau data, Visual Capitalist’s Dorothy Neufeld created this map showing natural population change in every state.

Because the measure excludes domestic and international migration, it highlights where population growth increasingly depends on people moving in.

Natural Population Change by State

The table below ranks every state by natural population change between July 2024 and July 2025, highlighting where births continued to outpace deaths—and where they no longer did.

State Natural Population Change
Jul 2024–Jul 2025
Pennsylvania -10,708
West Virginia -7,887
Maine -5,019
Michigan -4,998
Oregon -3,764
Mississippi -2,607
Alabama -2,188
New Hampshire -2,167
New Mexico -1,885
Vermont -1,769
Florida -1,333
Arkansas -1,224
Ohio -729
Delaware -554
Rhode Island -304
Montana -90
Kentucky -83
Missouri 177
Wyoming 295
South Carolina 564
Wisconsin 1,161
Hawaii 2,024
Connecticut 2,283
District of Columbia 2,516
Oklahoma 2,559
South Dakota 2,605
North Dakota 2,630
Louisiana 2,774
Iowa 2,949
Nevada 3,051
Alaska 3,308
Tennessee 3,597
Kansas 4,951
Nebraska 6,136
Idaho 6,900
Massachusetts 8,419
Indiana 8,561
Illinois 10,903
Maryland 11,444
Minnesota 12,071
Virginia 13,817
North Carolina 15,129
Washington 17,230
Colorado 20,608
Utah 24,961
New Jersey 26,023
Georgia 28,631
Arizona 20,914
New York 42,815
California 109,715
Texas 157,711

Pennsylvania recorded the nation’s largest natural decline (-10.7K), followed by West Virginia, Maine, and Michigan. Most states with natural decreases were concentrated in the Northeast and Appalachia, regions that include several states with some of the country’s oldest populations.

Florida also recorded more deaths than births, yet remained one of America’s fastest-growing states because of migration.

The South remained the engine of natural population growth. Texas (+158K), Georgia (+29K), and North Carolina (+15K) posted strong gains. California (+110K) and New York (+43K) also recorded far more births than deaths despite slower overall population growth.

America’s Population Is Increasingly Shaped by Migration

Natural population change tells only part of the story.

Several states with more deaths than births, including Florida, Maine, and Pennsylvania, can still grow overall when migration offsets their natural decline. Others continue losing population even after attracting newcomers.

Meanwhile, states such as Texas, North Carolina, and Arizona benefit from both natural population growth and migration, helping drive some of the country’s fastest population gains.

As America’s population ages and birth rates remain historically low, natural population growth is becoming less common. For a growing number of states, migration—not births—is now the primary driver of population growth, making migration trends increasingly important to their long-term demographic outlook.

To learn more about this topic, check out this graphic on immigration’s role in U.S. population growth by state.

Tyler Durden
Fri, 07/24/2026 – 05:45