46.4 F
Chicago
Friday, November 6, 2026
Home Blog Page 177

Futures Drop As Iran Hostilities Send Brent To 6 Week High Above $97

0
Futures Drop As Iran Hostilities Send Brent To 6 Week High Above $97

US stock futures slipped in cautious, low volume trading as the latest Middle East escalation pushed oil prices higher, lifting bond yields in Europe and Asia. As of 9:00am ET, S&P futures were down 0.2% with Nasdaq futures modestly in the red despite solid performance for tech stocks earlier in the session, which helped the Kospi surge more than 4.6% – its second biggest jump since the Situational Awareness takeover by Citadel – and Nikkei jumped almost 2% as OpenAI’s GPT-6 Astra debut reinvigorates the Asian semiconductor rally. Taiex climbs about 1.5% and ChiNext soars 2.6% (as discussed overnight, China may be the next Gamma Squeeze target). Hang Seng underperformed peers with a 1% loss as Chinese tech stocks retreat in Hong Kong. Brent crude rose above $97 a barrel following the largest exchange of tanker attacks yet between Iran and the US. Traders also assessed reports of hits on Saudi Arabian oil infrastructure and a potential accord between Iran and Oman to manage shipping through the Strait of Hormuz. In FX, the yen strengthened to its highest level since February, surpassing the peak reached after July’s intervention. The dollar fell 0.2%. Cash trading in Treasuries and US equities was closed for Labor Day. US markets are closed for Labor Day. 

In corporate news, an Amazon.com Inc. cargo plane overran a runway at Miami International Airport and burst into flames on Sunday, killing at least five people and temporarily shutting down the airport’s runways.

  • Jaguar Land Rover Automotive Plc will slash some 4,000 jobs as Britain’s largest carmaker grapples with US tariffs, the fallout of a crippling cyberattack and intense competition.
  • Novo Nordisk A/S stopped two more trials for its experimental heart disease medicine, in a further blow to the drug’s prospects.
  • Abu Dhabi National Oil Co. is in talks with the biggest refining companies in Thailand and Africa to invest in their businesses.
  • Uber Technologies Inc. has hired banks to hold calls with investors this week for a debut euro bond sale.
  • Novartis AG suffered a second trial disappointment within a week after the Swiss pharma group’s potential blockbuster heart drug failed in a final-stage study.

US cash trading and individual stock futures are shut today for the Labor day weekend. For anyone catching up after a break, Friday’s US jobs report did the early work on this week’s story. Payrolls rose 162,000, blowing past estimates, and pushed the market-implied odds of a Federal Reserve rate hike on Sept. 16 to a little above 60% from around 50% before the print.

That leaves Friday’s CPI (and to an extent Thursday’s PPI) as the real swing factor for a Fed that’s held steady for five straight meetings. The European Central Bank adds its own test Thursday, with markets pricing a near-certain quarter-point hike to a 2.50% deposit rate. Between the two central banks and Friday’s CPI, this is the week Europe has to trade around.

“Markets will be adjusting their positioning heading into the Fed’s blackout period. The risk is the Fed turning hawkish and that will be reflected in equities,” said Geoff Yu, a senior macro strategist at BNY. “Bond markets will remain nervy and we remain focused on fixed-income volatility.”

While economic data will likely be the biggest catalyst for markets this week, earnings will also help shape the outlook for key equity sectors. Results from Oracle Corp. and Adobe Inc. on Thursday will give investors a fresh read on AI infrastructure demand and the threat the technology poses to software makers. For now, the earnings backdrop remains supportive. Investors should buy any dips in equities given a robust earnings outlook, said JPM strategists. Even moderate central bank tightening would be unlikely to derail the positive backdrop for stocks unless inflation expectations change materially, said the team led by Mislav Matejka. “As corporate profits remain on an uptrend, any bout of weakness in equity prices would leave them cheaper,” the strategists wrote. “We believe one should continue using the dips to add.”

The Stoxx 600 struggled for direction, with economically sensitive sectors among the biggest decliners as inflation concerns drove bond yields higher. Novartis AG shares fell 2.6% after a heart drug failed in a final-stage study. Energy stocks outperformed, while the real estate and insurance sectors were among the biggest laggards. Here are the biggest movers Monday:

  • Nordex shares rose as much as 12%, the most in over four months, after being upgraded to buy at BofA Global Research
  • SigmaRoc rose as much as 13%, the most since March 2021, after the lime and minerals group released its interim results and announced the acquisition of Lithuanian dolomite business AB Dolomitas
  • Lottomatica shares gained as much as 8.2%, hitting the highest since June, after the Italian gaming company quantified the boost to online earnings it expects from the proposed acquisition of Spanish rival Cirsa Enterprises
  • Infineon shares rose as much as 3.9% as MP Capital Markets upgraded the stock to buy from hold
  • Burkhalter shares rose as much as 6.7%, the most since March 2022, after the Swiss building technology services company reported results
  • Novartis shares fell as much as 3.9% after the Swiss pharma group’s potential blockbuster heart drug, pelacarsen, failed in a final-stage study
  • Schindler dropped as much as 3.6% after Goldman Sachs gave the elevator and escalator specialist its only sell rating, downgrading from neutral, citing lower growth and earnings progression compared to the wider sector
  • Tomra shares fell as much as 10%, while Norwegian-listed peer Envipco also slumps, after France abandoned plans to impose a mandatory deposit return system for plastic bottles, introducing doubts over a potential growth catalyst for the stocks
  • Hollywood Bowl shares dropped as much as 6%, the most since May 2025, after analysts at Deutsche Bank cut their price target and warned the summer drought created “less-than-ideal conditions” for the provider of indoor family entertainment

German establishment politics, and specifically Merkel’s pro-immigration legacy, suffered a crushing blow over the weekend, after the conservative Alternative for Germany scored its best-ever result in a state election on Sunday, delivering a powerful blow to liberal Chancellor Friedrich Merz. The AfD secured 44% of the vote in Saxony-Anhalt. In the UK, the government signaled it won’t provide financial support to limit job losses expected to be announced at Jaguar Land Rover this week.

South Korea’s memory heavyweights were standouts in Asia as the release of OpenAI’s GPT-6 model continued to fuel renewed enthusiasm for AI. Driving the tech rally is OpenAI’s plan to release a new model, GPT-6, pitched as a milestone toward artificial general intelligence. That pushed the Philadelphia Semiconductor Index up 3.4% on Wall Street Friday and has SK Hynix and Samsung leading the advance in Asia Monday. The enthusiasm isn’t universal though. Hong Kong’s Hang Seng and its tech gauge both slipped into the red despite the Nikkei and Kospi seeing solid gains.

The dollar initially ticked higher, but then retreated following another surge in the yen which pushed the USDJPY as low as 154, down almost 200 pips overnight. The Korean won extended winning streak to around two-year high. T-note futures are about 1/32 softer near 107-14 with cash Treasuries closed for Labor Day. Bund futures are ~15 ticks lower after German far-right party AfD wins state election. Aussie curve bear flattens with 3-year yield ~3 bps higher. WTI crude futures climb 1% to near $92.40; gold sheds almost $30 to below $4,400-handle.

The notable overnight mover was again the yen, which strengthened to its highest level since February, surpassing the peak reached after coordinated intervention by Japan and the US. The Japanese currency suddenly extended gains, up as much as 1.4% to 154.06 against the dollar in London trading. There was no clear driver for the move, with some traders pointing to the US holiday helping to exaggerate the moves while others mentioned the break of the key 155 per dollar level as a reason.  The yen’s break below 155 is significant given the level previously acted as a floor following past intervention episodes,” said Masahiko Loo, senior fixed income strategist at State Street Investment Management.

Large stop-loss orders below the 155-per-dollar level were triggered and options dealers were forced to sell dollars, adding to the yen’s gains, according to a trader familiar with the transactions who asked not to be identified because they aren’t authorized to speak publicly.

China, separately, said it’s injecting 300 billion yuan ($45 billion) into its largest banks and insurers, its biggest recapitalization in almost two decades, with only a modest share reaction so far. 

In commodities, oil advances, with Brent futures are trading at a 6 week high, above $97 a barrel, after US attacks on Iranian tankers and Tehran’s threat of a new restricted zone outside the Strait of Hormuz. Over the weekend, Iran said it hit three US-linked ships in retaliation for American attacks on Iranian tankers. The US military earlier said it struck three Iranian crude tankers, in response to the IRGC targeting two US Navy warships with ballistic missiles. European natural gas prices surge. Meanwhile, Ukraine is resigned to Russia’s war dragging on through another tough winter.

In rates, japan likely sold a portion of its holdings of foreign securities, including US Treasuries, to finance its record currency intervention over the past month. Treasury futures edge down. There’s no trading of cash Treasuries worldwide on Monday because of a US public holiday.

Market Snapshot

Top Overnight News

  • Saudi Aramco’s oil facilities in the Saudi Arabian city of Jizan have been attacked only a month after a separate strike temporarily knocked out some production at its refinery.: FT
  • Iran says US energy companies’ facilities are ‘exposed’: RTRS
  • UAE says its energy exports will not be ‘held hostage’ by Iran war: RTRS
  • Several Qatari liquefied natural gas tankers are heading back toward the Persian Gulf, a sign the supplier may be positioning vessels for a resumption of exports through the Strait of Hormuz: BBG
  • The Alternative for Germany scored its best-ever result in a state election on Sunday amid growing public discontent with the political establishment, delivering a powerful blow to Chancellor Friedrich Merz: BBG
  • AI could pose ‘existential’ risk to humanity, UN rights chief warns: RTRS
  • From dance floor to war: China readies humanoid robots for combat: RTRS
  • Japan likely sold a portion of its holdings of foreign securities, including US Treasuries, to finance its record currency intervention over the past month, despite concern in Washington over the impact of Treasury sales on long-term yields: BBG
  • The South Korean won advanced to its strongest level in nearly two years Monday, helped by a rally in semiconductor stocks and continued foreign inflows into the country’s benchmark equity index: BBG
  • Nepal rescuers focus on 900 hydropower workers, 121 could be trapped in tunnels, officials say: RTRS
  • German industrial production declined the most in almost a year, marking an unexpected setback to the recovery of Europe’s biggest economy: RTRS
  • Fed’s Hammack (2026 voter) said on Friday that Fed policy is not restrictive and inflation is too high, while she stated local contact views indicate now is the time for a Fed hike to control inflation.
  • Huawei launches new foldable smartphone; Xiaomi and Apple set to follow: RTRS
  • Warning signs abound for Republicans as midterm campaign begins final sprint: RTRS
  • President Trump said on Friday that they are taking action to help cattle ranchers and signed an order that allows ranchers to process their own beef, while small, medium, and large ranchers can sell to consumers, and he also stated that meatpackers have been charging unsustainable prices.
  • There were multiple casualties after an Amazon (AMZN) cargo plane overran the runway and struck vehicles whilst landing at Miami International Airport, while the Miami-Dade County Sheriff announced that at least five people have been confirmed dead.

Iran Headlines

  • US launched strikes against three Iranian crude oil tankers on Saturday, which destroyed one, in retaliation for the IRGC targeting US Navy warships with ballistic missiles.
  • Iran’s navy said it targeted three oil tankers that were travelling through unauthorised routes in the Strait of Hormuz and three additional US vessels in other areas.
  • US President Trump said on Friday that they do intermittent strikes in Iran and that the Iran issue is a military conflict, while he added that they may hit Pickaxe Mountain very soon. Trump warned that if anything goes badly with Iran, they may hit them hard and have essentially taken over Iran. He also claimed there have been no shootings for days and there are no mines in the Strait.
  • US Energy Secretary Wright said a nuclear deal with Iran may not be achievable in the near term and military action may be needed to address threats from Iran, according to ABC News.
  • Iran’s top security official Rezaei said Iran and Oman will sign agreed Strait of Hormuz passage maps in the coming days and that Iran will commit to keeping the Strait of Hormuz open when the US neither threatens Iran nor attacks it. Rezaei also stated that they will announce in the coming days and weeks a restricted zone outside the Strait of Hormuz that starts from the US Navy’s blockade line and extends through the strait into the Persian Gulf, and any ship identified entering this zone with the intention of passing through the strait will be added to the sanctions list. Furthermore, he said that Iran tested an Iranian anti-ship missile above a US warship for the first time and claimed the missile created ‘hell’ for the Americans ‘and they fled’.
  • Iranian Parliamentary Speaker Ghalibaf warned that Iran’s response to any attack against its interests and security would be faster, heavier and more painful.
  • Iran’s Foreign Ministry said the US-led war is disrupting global oil trade and costs, while it added that US aggression is causing instability in the Strait of Hormuz.
  • Israeli military announced that it struck southern Lebanon after Hezbollah launched drones towards Israeli soldiers in the security zone. Israel’s army also issued an evacuation warning to residents of a building in Deir Zahrani, southern Lebanon.
  • Israeli Finance Minister Smotrich said PM Netanyahu ordered the evacuation of certain settlement outposts in the West Bank. It was separately reported that Israel conducted an airstrike on eastern Gaza City with four missiles.
  • Joint statement by UAE, Saudi Arabia, Qatar, Jordan, Indonesia, Pakistan, Turkey and Egypt Foreign Ministers strongly condemned statements made by Israel’s National Security Minister Ben-Gvir and Defence Minister Katz regarding the displacement of Palestinians.
  • Yemeni armed forces said they thwarted an attempt by Houthis to infiltrate the Dabab front, while they announced that warplanes struck Houthi positions in Balhaf and south of Hodeidah.

A more detailed look at global markets courtesy of newsquawk

APAC stocks traded mixed as the region reflected on the recent strong US jobs data and subsequent Fed rate hike bets, as well as the US and Iran tit-for-tat attacks on vessels in the Strait of Hormuz. ASX 200 was little changed as resilience in the energy, resources, materials and mining sectors is offset by underperformance in tech, utilities and telecoms, but with downside in the index cushioned by support at around the 9,000 level. Nikkei 225 gapped above the 66,000 level with tech-related stocks heavily represented in the list of biggest gainers in the index. KOSPI outperformed amid firm gains in the semiconductor giants, including SK Hynix, which is said to be sharply increasing the production share of its sixth-generation 10nm-class 1c DRAM. Hang Seng and Shanghai Comp lagged with the Hong Kong benchmark pressured amid underperformance in the likes of Baidu and Xiaomi, while the big banks also declined after reports that ICBC and AgBank plan large A-share placements to raise CNY 100bln and CNY 160bln, respectively, as part of a Beijing-led CNY 360bln capital injection in financials.

Top Asian News

  • US President Trump said on Friday that he will be hosting a state dinner for Chinese President Xi when he comes and that China has very little involvement with Iran.
  • China’s Finance Ministry announced it will lead a capital injection of CNY 360bln in state banks and insurers, with ICBC (601398 CH) planning to raise CNY 100bln to bolster its capital, and Agricultural Bank of China (601288 CH) to raise CNY 160bln through a private placement of A shares, while the insurers include China Life Insurance (601628 CH), China Taiping Insurance (966 HK) and People’s Insurance Company of China (601319 CH).
  • China unveiled a plan to strengthen rural investment and will boost rural revitalisation investments to boost agricultural productivity, while it will enhance bond and credit support for qualified agricultural initiatives.

European stocks were subdued and oil crept higher after tit-for-tat tanker strikes between the US and Iran. Novartis AG shares fell 2.6% after a heart drug failed in a final-stage study. The Stoxx Europe 600 Index was little changed by 1:10 p.m. in London. Energy stocks outperformed, while the real estate and insurance sectors were among the biggest laggards. 

Top European News

  • UK Chancellor Healey said Britain’s economic growth must extend beyond the largest cities as he prepares to outline his economic agenda in a major speech on Monday. He is reportedly to set to announce a GBP 150mln fund for northern firms, aiming to boost growth.
  • UK recruiters saw hiring pick up for the first time in four years in August, according to the FT citing a survey by KPMG and the Recruitment and Employment Confederation.
  • Hundreds of masked anti-immigration protesters blocked roads leading to Britain’s busiest ferry port in Dover on Saturday.
  • German Chancellor Merz warned about further losses of industrial jobs and said that they are losing industrial jobs on a large scale, although he welcomed the latest agreement on Volkswagen’s supervisory board.
  • Germany’s far-right AfD is set to win the election in the eastern German state of Saxony-Anhalt with 44.5% of the vote.
  • German police discovered 12 explosive devices near overhead powerlines in two districts in east Germany, which is the latest spate of incidents targeting Germany’s electricity infrastructure.
  • Greek PM Mitsotakis unveiled a package of economic measures including tax breaks and wage increases for pensioners and employees, with the measures costing EUR 3.5bln by 2030.
  • Fitch raised Portugal’s sovereign rating from A to A+; Outlook Stable.

Tariffs/trade

  • US President Trump said Canada’s dollar imbalance with the US is unacceptable.
  • US President Trump said on Friday that they have the right to put tariffs on nations like Switzerland and have the right not to trade with financial elite countries, while he also stated that he gets along very well with Mexico’s President.
  • Japanese Trade Minister Akazawa said progress was made on the USD 550bln investment initiative that was set up as part of a trade deal with the US.

FX

  • DXY struggled for direction after ultimately fading the knee-jerk uplift from the stronger-than-expected NFP report on Friday, with price action not helped amid the holiday closures in North America on Monday and with the Fed currently on a blackout period, while market participants will have to wait till much later in the week for US CPI data.
  • EUR/USD traded little changed just above the 1.1600 level, with the single currency unfazed by news that the German far-right AfD is set for a big election win in the eastern state of Saxony-Anhalt, but will fall short of achieving a majority. Separately, German Chancellor Merz warned about further losses of industrial jobs.
  • GBP/USD marginally softened although held on to the 1.3500 status, with participants looking ahead to comments from UK Chancellor Healey, who will outline his economic agenda in a speech today.
  • USD/JPY was range-bound on both sides of the 156.00 level in the absence of fresh catalysts from the US or Japan to begin the week, with both their central banks scheduled for key meetings next week.
  • Antipodeans conformed to the uneventful trade across the FX space amid the ultimately mixed risk appetite and with no tier-1 data to spur price action.
  • PBoC set USD/CNY mid-point at 6.7795 vs Exp. 6.7086 (prev. 6.7787)

Fixed Income

  • 10yr UST futures lacked direction after whipsawing in the aftermath of last Friday’s blockbuster jobs report, while price action is contained with US cash markets closed on Monday for Labor Day.
  • Bund futures trickled lower and returned to beneath the 123.00 level amid mild gains in oil prices and with German Industrial Production data due later, while there was little impact from news that Germany’s far-right was set for a major victory after elections in the eastern state of Saxony-Anhalt.
  • 10yr JGB futures were subdued in the absence of any major fresh drivers or tier-1 data from Japan.

Commodities

  • Crude futures mildly gained after the US and Iran conducted tit-for-tat attacks on vessels in the Strait of Hormuz during the weekend, but with upside capped as it was also reported that Iran’s top security official Rezaei said Tehran will declare a restricted zone near the Strait of Hormuz and announce a new shipping route agreed on with Oman in the coming days and weeks.
  • Major OPEC+ countries stuck with the plan to keep oil output quotas unchanged for October.
  • Iraq raised oil export capacity to over 3mln bpd, according to state media.
  • US Energy Secretary Wright said the Trump administration is focused on boosting crude and fuel supplies rather than curbing US exports, as a way to reduce prices. Wright also said that US Navy escorts that are assisting tankers across the Strait of Hormuz are vital in sustaining crude flows and suggested they will continue to do so until Iran backs down.
  • Russia’s Vostok Oil project loaded its first crude for shipment via the Northern Sea route.
  • Iran is to increase gasoline prices for heavy consumers using more than 110 litres per month, effective on Tuesday.
  • Spot gold retested the USD 4,400/oz level to the downside following last week’s stronger-than-expected US jobs data, which supports the case for the Fed to hike rates this month.
  • Copper futures ultimately declined with early indecision on the recent key market themes including US data, Fed rate expectations and ongoing geopolitical tensions.

Geopolitics: Ukraine

  • Ukrainian President Zelensky sees no quick end to the war with Russia following a meeting with US envoys Witkoff and Kushner, and is seeking a package from allies that would cover defence reinforcements, as well as energy, including US LNG.
  • Russian President Putin ordered troops not to fire on Kyiv for three days during US envoys Witkoff and Kushner’s visit to Ukraine’s capital, according to Kremlin spokesman Peskov. However, it was reported that Russia and Ukraine exchanged a wave of strikes prior to the US envoys’ visit to Kyiv.
  • Russian Kremlin aide said talks between Russia and the US were highly useful and lasted for over three hours, but gave no indication of a breakthrough.
  • White House official said US and Russian officials discussed substantive plans for the next steps in talks aimed at ending Russia’s war in Ukraine, which will be announced in the coming weeks.
  • France’s far-right National Rally chief Bardella wants Ukraine to pay for Europe’s help and said France’s unconditional support for Ukraine should be replaced by a more transactional relationship.

Geopolitics: Other

  • North Korean leader Kim said North Korea’s navy nuclear armament will put nuclear combat systems to practical use and will restrain the enemy’s invading fleet, while he added that their new warship can carry out annihilating retaliatory strikes on the enemy at any time.

DB’s Jim Reid concludes the overnight wrap

Morning all. Tough times in our house this weekend with 8 nine-year-old boys sleeping over for our twin’s birthday party. They were very noisy. However, we were kept awake not by them but by an illegal rave in a field a few hundred yards away. I say we but my hearing isn’t the best so I didn’t hear it. My wife has the hearing of an owl and couldn’t sleep through it and felt that I should be woken up to be made aware of the noise I couldn’t hear. So I could do with the weekend to start again. Thankfully it’s US Labor Day so it should be relatively quiet.  

I was asked to do an op-ed for the FT today on the recent yield sell-off in bond market. As I said in the piece, the moves over the summer are just another leg to the normalisation trade that has been going on post Covid. In the unlikely event that you’d been on a desert island since just before the GFC and came back ashore today, I’m sure you’d look at current yields as pretty normal given all the spot info and history of bond markets you had at your disposal. I also don’t think the recent concerns are fiscal related, even if the higher yields go the more worries we will have further down the line for several countries. Finally while the pressures that have been there for higher yields are likely to continue, we have to accept that bonds are being bonds again. That is the coupon is helping maintain returns even in the face of yield rises. For example, its been nearly 4 years since the UK mini-budget crisis and 10yr Gilt yields are +65bps than the peak, while index returns are up around 12%. Clearly not spectacular but its getting harder to get outright negative returns in government bonds over the medium-term. So while the news flow will likely to continue to be negative, at least bonds are being bonds again. See my op-ed at the FT here for more. 

The main headline this morning is Germany’s political landscape shifting further to the right after the AfD secured around 44% of the vote in the Saxony-Anhalt state election yesterday, its strongest result in any German election to date and more than double its support from 2021. Chancellor Friedrich Merz’s CDU slumped to roughly 17%, its weakest showing in the state, as voters expressed growing frustration over economic stagnation, energy costs and migration policy. While the AfD fell just short of an outright parliamentary majority, the result nonetheless marks a major symbolic breakthrough for a party that remains shunned by mainstream rivals under Germany’s long-standing political “firewall”. The outcome will intensify pressure on the federal government and is likely to reinforce concerns about political fragmentation. More broadly, it underlines how anti-establishment and populist parties continue to gain traction across parts of Europe despite robust labour markets and relatively subdued inflation.  

The main focus in the Iran conflict over the weekend was a tit-for-tat escalation targeting commercial shipping in and around the Gulf. According to Reuters and other major news agencies, several tanker incidents and maritime attacks heightened concerns about the security of energy supplies moving through the Strait of Hormuz, with both sides accusing each other of responsibility. Brent is up +1.05% this morning to $97.29/bbl so we remain a distance from a resolution.

Elsewhere in overnight markets, tech is lifting most boats with the KOSPI (+4.18%) leading gains, followed by the Nikkei (+1.87%). Chinese equities are mixed, with the CSI 300 (+0.19%) edging higher, while the Hang Seng (-0.97%) and Shanghai Composite (-0.34%) are underperforming and bucking the broader regional trend. S&P 500 futures (-0.11%) are trading slightly lower but activity will be light today due to the Labor Day holiday. The Yen is fairly flat after another hectic week of intervention stories.

Looking forward now and the coming week offers a busy mix of central bank decisions, inflation data and growth indicators across the major economies. The main global focus will undoubtedly be on the US inflation reports (including CPI on Friday) and the ECB policy meeting (Thursday) with the former likely to heavily influence the FOMC next week. Elsewhere, investors will look to China’s trade (tomorrow) and inflation data (Wednesday), UK monthly GDP (Friday), and industrial production releases in Germany (today) and France (Wednesday). Corporate earnings are relatively light but Oracle (Thursday), Adobe and Inditex are among the notable releases.
As noted above, the biggest event is likely to be the US August CPI report (Friday), arriving just days before the September 16 FOMC meeting. The release follows a stronger-than-expected August employment report last Friday that reinforced the view that the labour market remains resilient. Nonfarm payrolls rose by 162k, with a further 55k of upward revisions to the previous two months. Private-sector hiring remained firm (127k) and job gains continued to broaden beyond healthcare, while measures of labour demand improved further.

Although the unemployment rate edged up to 4.14%, the broader U-6 measure fell to 7.7% and participation increased to 61.6%, suggesting the labour market remains on a relatively stable footing. Overall, the report corrected some of the softer signals seen in July and supports the view that employment growth remains at or slightly above breakeven levels.

Attention now turns to inflation. Our US economists expect headline CPI (Friday) to rise by +0.38% month-on-month in August, up from +0.07% previously, while core CPI is expected to print at +0.21% month-on-month, broadly unchanged from July’s +0.22%. Higher gasoline prices are likely to support the headline reading, while core inflation should continue to benefit from gradually moderating shelter costs. If realised, the forecasts would leave headline CPI broadly unchanged at 3.38% on a year-on-year basis while core inflation edges 10 bps lower to 2.38%.

Ahead of that, the PPI (Thursday) will provide another important input into the inflation outlook. Our US economists expect PPI to imply a +0.21% month-on-month increase in core PCE, down from +0.25% in July, leaving the annual rate broadly stable. The remainder of the US calendar is relatively quiet, with markets closed today for the Labor Day holiday. However, the preliminary University of Michigan consumer sentiment survey (Friday) will also attract attention. Our US economists expect sentiment to improve to 52.5 from 51.7 in August, while the survey’s inflation expectations measures will be closely watched.

In Europe, the ECB policy decision (Thursday) will be the key event. Our European economists expect a 25bp rate increase, taking the deposit rate to 2.50%, and investors will focus on any guidance regarding the likelihood of further tightening. Our economists now expect an additional hike in December with the reasons explained in their preview note here. They have also upgraded their 2026 and 2027 economic forecasts by 0.3pp and 0.1pp to 0.8% and 1.2% respectively. See their note on it here.  Economic data will also be closely monitored, including German industrial production (today) and trade data (tomorrow), French industrial production (Wednesday), and UK monthly GDP (Friday). Inflation releases from Sweden (today) and Norway and Denmark (Thursday) will provide additional insight into regional price pressures.

In Asia, China will dominate the calendar. Our economists expect the August trade balance (tomorrow) to show stronger activity, with exports and imports forecast to grow a significant 27% and 29% year-on-year respectively. Inflation data (Wednesday) are expected to show CPI accelerating to 0.8% year-on-year from 0.5%, while PPI inflation moderates to 3.2% from 3.5%. In Japan, key releases include labour cash earnings and the Economy Watchers survey (tomorrow), followed by PPI data (Friday).  A reminder that the BoJ has an important meeting on Friday week, less than 36 hours after the FOMC conclusion.

Beyond the economic calendar, the US Treasury’s expanded long-end buyback programme begins on Wednesday, increasing support operations in longer-dated maturities. In politics, the US Republican Party will hold its first midterm national convention in Dallas on Wednesday and Thursday, while Canada’s counter-tariffs on US imports come into force tomorrow. Corporate earnings highlights include Inditex (Wednesday) and Adobe and Oracle (Thursday). Oracle will be the key given all the focus on AI capex.  

Recapping last week now and risk assets struggled to gain much traction, as a fresh rise in energy prices raised fears about more persistent inflation. That came amidst no signs of progress on reopening the Strait of Hormuz, with Brent crude oil up +7.80% last week (+0.80% Friday) to $96.28/bbl, their highest in six weeks. Moreover, the relentless rise in European natural gas futures continued, with a 4th consecutive weekly gain (+7.42%) last week (+0.20% Friday) to €72.00/MWh. So for Europe in particular, investors were pricing in a growing probability of a more inflationary shock.   

That backdrop helped push yields up to multi-year highs around the world. For instance in Germany, the 10yr bund yield was up +6.1bps last week (-0.4bps Friday) to 3.34%, and it even reached a post-2011 high of 3.37% on Wednesday. Meanwhile in the US, the 10yr yield was up +6.3bps last week (+1.4bps Friday) to 4.78%, and on Tuesday it closed at 4.80%, its highest since October 2023.   
The yield moves got further momentum on Friday from a very strong US jobs report, which showed payrolls up by +162k in August (vs. +55k expected). In addition, there were +55k of upward revisions to the previous two months, and the unemployment rate held steady at 4.1%. So that raised investors’ confidence that the Fed would likely hike rates at their September meeting, with futures pricing in a 62% chance of a hike by the close on Friday.   

With inflationary pressures mounting and yields rising further, that generally put pressure on risk assets around the world. That was particularly clear in Europe, where the STOXX 600 fell -0.81% last week (+0.12% Friday), whilst the DAX fell -1.97% (+0.17% Friday). Elsewhere, Japan’s Nikkei also fell -2.09% (+1.26% Friday), while the MSCI EM index rose +0.24% (+1.35% Friday). In the US, equities saw a relative outperformance, but even there, the S&P 500 was still barely up last week with a +0.09% gain (-0.38% Friday). That slight risk-off tone was seen in credit as well, as US IG (+2bps) and HY (+7bps) spreads both widened, as did Euro IG (+2bps) and HY (+8bps) spreads.

Tyler Durden
Mon, 09/07/2026 – 09:22

Central Banks Bought 23 Tonnes Of Gold In July

0
Central Banks Bought 23 Tonnes Of Gold In July

Authored by Naveen Athrappully via The Epoch Times,

Central banks worldwide purchased a net 23 tonnes of gold in July, in line with the overall yearly trend, according to the World Gold Council (WGC).

Gold bars weighing 1000 grams each are displayed at the Austrian Gold and Silver Refinery (Oegussa) in Vienna, Austria, on Feb. 3, 2026. Georg Hochmuth/APA/AFP via Getty Images

The largest buyer last month was China, which bought 20 tonnes, according to a Sept. 3 WGC report.

“Notably, activity from the People’s Bank of China (PBoC) has picked up pace in recent months, with double-digit monthly purchases of gold since May 2026,” the report said. Poland purchased eight tonnes and was the second-largest buyer.

Russia was the top net seller, with six tonnes sold. This was followed by Turkey, Uzbekistan, and Jordan, all of which sold a tonne each.

Year-to-date, global central banks reported purchasing 130 tonnes of gold, down from roughly 160 tonnes during the same period in 2025. Poland has added 90 tonnes this year, with China buying 60 tonnes. Turkey has sold 85 tonnes, while Russia’s sales total 50 tonnes.

Central banks account for roughly 20 percent of all historically mined gold, according to the WGC. Bullion serves as a vital bank reserve asset, valued for its liquidity, safety, and potential returns. In times of uncertainty, gold demand tends to rise.

According to a June 16 WGC report, a survey of central banks found that 89 percent of respondents forecast global central bank gold reserves to rise over the year.

As for funding, half of the respondents said they would procure the gold locally by using domestic currencies. Thirty-eight percent said they would sell other reserve assets to purchase gold.

“The majority of respondents (74 percent) see moderate or significantly lower US dollar holdings within global reserves over the next five years,” the report said.

“Respondents also believe that the share of other currencies, such as the euro and renminbi, will remain unchanged over the same period, while gold holdings will increase.”

Goldman Sachs predicts central bank buying will support the rise in gold prices, according to an Aug. 28 report. Such purchases are being driven by a need to diversify their reserves.

In 2022, the G7 nations froze Russia’s assets held in Europe due to Moscow’s invasion of Ukraine. Since then, the central banks have been buying gold at an increased rate, according to Goldman Sachs.

Spot gold ended Friday at around $4,430 per oz., up from about $4,329 at the beginning of the year. Gold hit a peak of roughly $5,595 in late January.

Unable to Withdraw Gold

The Sept. 3 WGC report cites a conflict between Venezuela and the Bank of England over gold reserves.

The Venezuelan government has roughly $4 billion worth of gold stored with the bank and has sought to withdraw it. However, because the United Kingdom has refused to recognize Venezuela’s socialist government, the country has been unable to secure its gold reserves.

According to the June 16 WGC report, central banks are continuing to diversify the locations of their gold reserves. While the Bank of England remained the top choice, domestic storage was a close second, followed by the Bank for International Settlements in third place.

This week, the Netherlands’ central bank announced plans to shift roughly 86 tonnes of gold from the United States and Canada to London, citing geopolitical risk.

Ewa Manthey, commodities strategist at ING Bank, highlighted the risk faced by certain nations that store gold abroad, citing Venezuela’s inability to retrieve its gold from the Bank of England, according to a Sept. 4 opinion on the company’s website.

“This case is exceptional – but it shows that the host country’s courts and political recognition decisions can affect access to reserves,” Manthey said.

“Gold held at the Bank of England remains the property of the foreign central bank, but it is physically located in the UK and is therefore subject to UK jurisdiction.”

Tyler Durden
Mon, 09/07/2026 – 09:15

USS Abraham Lincoln Returning Home After Being “Sunk” Three Times By Iran

0
USS Abraham Lincoln Returning Home After Being “Sunk” Three Times By Iran

In yet another example of Iranian social media claims not matching up with reality, the nuclear powered Nimitz-class aircraft carrier USS Abraham Lincoln is returning home after a 286 day deployment and 5 days of rest at port in Thailand.  The ship was untouched by any signs of combat, despite the IRGC claiming on at least three separate occasions that they had sunk the mighty vessel with drones and missile strikes. 

Iranian aligned accounts even spread AI videos and video game clips of a ship sinking, arguing that the clips showed the Abraham Lincoln.  Left wing commentators celebrated the news, only to scrub their posts after it was revealed that the information was fake.

Despite resounding evidence to the contrary, many conspiracy advocates asserted that the Lincoln had been hit and the US government was “covering it up.”  This also turned out to be nonsense after the carrier arrived at Laem Chabang Port in Thailand for rest and cleaning.  

The narrative then shifted, with people claiming that the Lincoln “looked damaged” and disheveled, which proved they were right about Iran hitting the vessel.  In reality, the carrier had normal rust and residue caused by months at sea. 

The posts exposed an embarrassing lack of basic knowledge when it comes to natural wear from sea water on naval ships facing long deployments.  

The ship was cleaned at port with no signs of damage from attack.  It has now left Thailand on a return trip to the US and the Naval Air Station North Island in Coronado (San Diego).  

The carrier and all its sailors are accounted for.  The return of the USS Abraham Lincoln highlights an incessant disinformation campaign by Iran and Iran supporters, flooding social media with false claims in an effort to win the war in the theater of public opinion.  On the ground, the vast majority of supposed IRGC successes have proven to be fake. 

The Iran War and the war in Ukraine have become case studies for a new era of digital warfare.  Substantial efforts are being made to “play the algorithms” and manipulate consensus.  Iran, perhaps more than any government so far, has relied heavily on digital guerrilla tactics as a way to demoralize US operations.  They have, of course, received extensive help from sources in the west. 

Whether or not one agrees with the reasons behind the war, it is clear that propaganda alone is not going to lead to victory.  Tangible realities matter and Iran is being hit with those tangibles in the form of an inflation crisis, import/export crisis and fuel shortage crisis and foreign ships passing more freely through the Strait of Hormuz.   

The lesson here is simple:  Online discourse is rarely a reflection of the truth.  All one has to do is wait a few months for the fog of war to clear and the majority of false claims will melt away.     

Tyler Durden
Mon, 09/07/2026 – 08:50

AfD’s Historic Win Shocks German Political Establishment: Here’s What Happens Next

0
AfD’s Historic Win Shocks German Political Establishment: Here’s What Happens Next

The pro-Germany, anti-globalist, anti-mass migration right-wing populist party known as Alternative für Deutschland delivered its strongest election result ever in Saxony-Anhalt on Sunday, dealing a sharp blow to Germany’s political establishment. 

On Sunday, AfD secured 43.8% of the vote in Sunday’s regional election, exceeding polling estimates. Chancellor Friedrich Merz’s Christian Democrats lost about 19 percentage points, while turnout surged to 77.8% from 60.3% in 2021.

According to Marion Mühlberger, a senior economist at Deutsche Bank, AfD’s weekend win leaves the party holding 39 seats in the 83-member legislature, three short of an absolute majority. The CDU, Social Democrats, Greens and Left also have a combined 39 seats. 

Mühlberger said there are two possible outcomes of what comes next: an AfD minority government tolerated by BSW, or a political stalemate that leads to a snap election, which would only give AfD a new opportunity to secure outright control.

 Mühlbergere explained:

At the time of writing, the two most likely options are i) an AfD minority government (supported by the BSW) or ii) a stalemate resulting in snap elections, with the AfD hoping to reach an absolute majority rather than attempting a minority government. AfD leadership for now appears undecided on their preference: while national co-leader Chrupalla last night indicated a willingness to try a minority government, AfD’s lead candidate in Saxony-Anhalt, Ulrich Siegmund, already suggested a snap election as his preferred option, saying that “the AfD is not prepared to make far- reaching compromise to form a coalition.”

We believe that even an AfD (minority) government supported by the BSW would have materially detrimental ramifications for the economic prospects of Saxony-Anhalt over the coming years. Direct investment in the state would likely decline amid significant policy uncertainty, and skilled worker shortages would likely become even more pronounced. However, Saxony-Anhalt contributes less than 2% of German GDP, and any structural damage done to the regional economy is unlikely to spill over to the rest of the German economy. While an AfD state government might test some of Germany’s federal institutions, it will have no leverage over national economic or fiscal policy, not even via the constitutional court.

Over the course of today, we will see leaders of the coalition parties in Berlin officially react to their parties’ weak electoral performance. Chancellor Merz is expected to give a press statement today at 13.30 CET. There will likely be considerable political noise over the couple of weeks ahead of the state elections on 20 September in Berlin and Mecklenburg-Vorpommern. There may be some criticism of party leadership and reform proposals. However, once these final state elections of the year are over, we believe that an AfD government in Saxony-Anhalt is likely to provide an additional impetus for the federal government coalition to double down on reforms

Mühlbergere said the five seats held by the populist BSW will be decisive: 

Thus, the populist BSW, with its 5 seats, has a key role to play in the upcoming coalition negotiations as potential kingmakers. While the AfD missed their 45+% / absolute majority election target, they missed it so narrowly that it seems difficult for them to not aim for governing Saxony-Anhalt

The BSW is the potential kingmaker

As no single party reached an absolute majority needed to govern alone, coalition negotiations for entering a formal coalition or receiving ad hoc support for a minority government will kick off today. 

The BSW has theoretically three options once the new parliament has convened and the next state premier is to be elected. First, they could elect the AfD lead candidate as state premier (without entering a formal coalition), second they could elect the CDU lead candidate or third they could abstain in the first two ballots for state premier. 

Judging from statements of BSW co-leaders (at the federal level) Wagenknecht and Ali yesterday night,1 we deem the first option the most likely.

What comes next? There are two options:

Option 1 – BSW abstains in third round facilitating an AfD minority government 

This morning, BSW leader Wagenknecht called for a “political reset” in Saxony- Anhalt, especially when it comes to energy policy, sanctions against Russia (which however are set at the EU level), education, and public broadcasting. Thus, there is a certain overlap of political priorities with the AfD. However, the BSW does not want to enter a formal coalition with the AfD. 

With the AfD rejecting the BSW’s proposal for an independent state premier, an AfD minority government tolerated by the BSW seems to be a possible outcome. This means that the BSW would not enter a formal coalition with the AfD, but elect the AfD lead candidate as state premier in an informal cooperation.

Option 2 – The route to snap elections 

The newly elected parliament must convene for the first time by 6 October at the latest. But the regional constitution does not set a deadline for electing a state premier. Until a new government is elected, Sven Schulze will remain in office leading the caretaker government. 

As government formation could turn out to be complex, snap elections may be a possible way out. The AfD’s lead candidate Siegmund already suggested this as a potential option, saying that the AfD is not prepared to make far-reaching compromise to form a coalition.

There are three routes to snap elections:

  1. If the newly elected parliament does not elect a state premier with an absolute majority after two ballots, it can decide with an absolute majority to dissolve itself before a third ballot. 
  2. Six months after the election, the new parliament can decide with a two- thirds majority to dissolve itself. 
  3. A newly elected state premier could call a vote of confidence. This could be a viable option for an AfD minority government, confident of winning an absolute majority in snap elections.

It is highly uncertain that snap elections would generate clear majorities. What could help the AfD is the narrative that the other parties want to keep them out of power, and that they now need a clear mandate. Moreover, smaller parties would again be at risk of not making the 5% hurdle, which would help the AfD. On the other hand, the strong AfD performance could again mobilise the centrist forces to avoid the AfD winning an absolute majority.

Mühlberger’s assessment was that an AfD majority in Saxony-Anhalt could weaken investment and aggravate skilled-worker shortages. She cited policy uncertainty, the party’s anti-mass migration agenda, and potential conflict with the civil service.

For Merz, the most consequential challenge is containing AfD’s momentum in the upcoming elections in Berlin and Mecklenburg-Vorpommern on Sept. 20.

Polymarket’s “Mecklenburg-Vorpommern Parliamentary Election Winner” market puts AfD’s odds of winning at 82%.

AfD’s odds of winning the Berlin election are much lower, at around 18%.

While Deutsche Bank was considerably less favorable toward AfD, Nomura analyst Andrzej Szczepaniak’s recent report said that markets are less concerned about right-wing populism and more concerned about “populist left-wing parties being elected due to their desire to increase spending.”

Tyler Durden
Mon, 09/07/2026 – 07:45

Oh Look, Yet Another Church Up In Flames…

0
Oh Look, Yet Another Church Up In Flames…

Authored by Steve Watson via Modernity News,

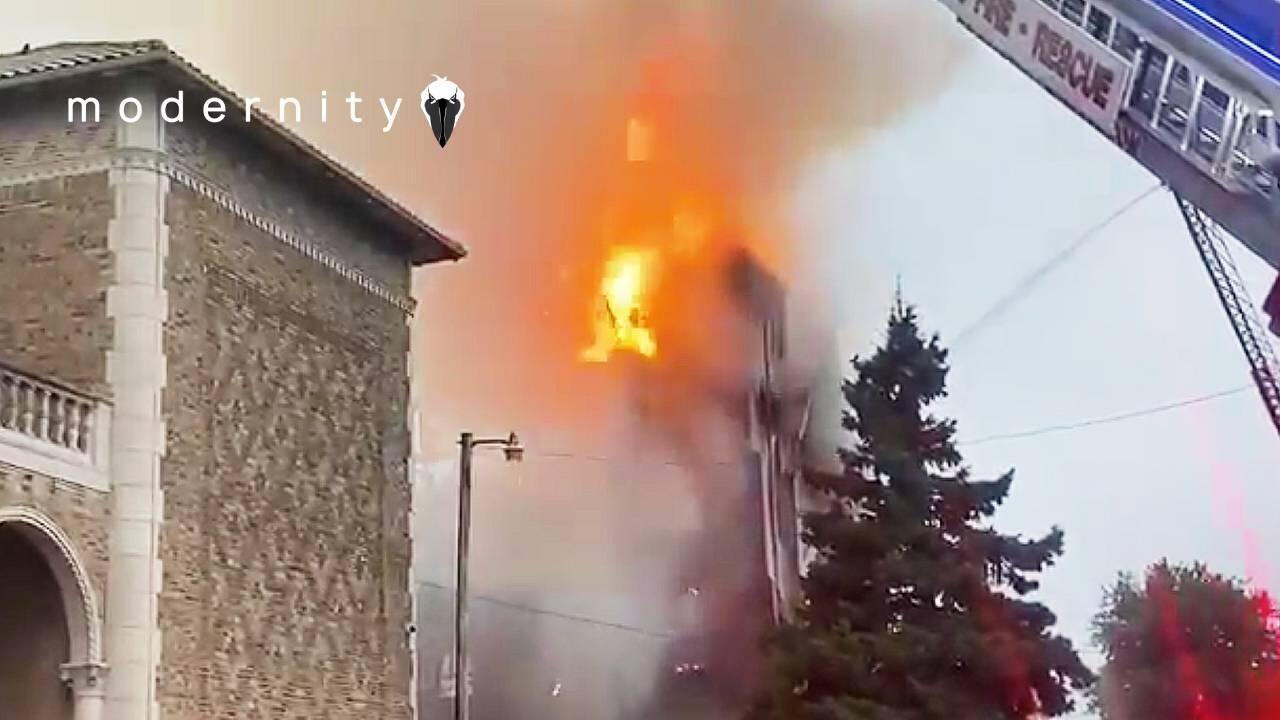
Another week, another historic church reduced to smoke, rubble. The former Saint Agnes Church on Martha Avenue in Toledo, Ohio went up early Saturday morning. The 116-year-old landmark’s steeple came down. The roof burned out. Nearby homes were evacuated. Once again the cause is listed as currently unknown.

Toledo Fire & Rescue was called around 6:30 a.m. Saturday after reports of heavy black smoke pouring from the roof of the vacant church in the Five Points neighborhood. Crews arrived to find the building already heavily engulfed.

Officials warned of collapse risk and alerted people in surrounding homes. The steeple later fell. By Saturday afternoon excavators were tearing the ruined structure down.

Saint Agnes opened in 1910. It was among 29 parishes closed or merged by the Roman Catholic Diocese of Toledo in 2005. The parochial school shut the same year. The diocese no longer owns the property. A charter school now occupies the old school building next door and reported only minor smoke, water, and a cracked window.

One neighbor told local television: “About 6:45 we heard fire trucks and I peeked out my window and it literally looked like the whole street was on fire.”

Investigators in Toledo have not named a suspect, a motive, or even a cause. Vacant churches do burn by accident. They also burn because someone wants them gone. The public is asked, week after week, to accept “unknown” as the last word while the buildings keep falling.

In the U.S. hostility against churches has jumped to hundreds of incidents a year – vandalism, arson or fires of uncertain origin, gun incidents, bomb threats.

Churches are not supposed to be disposable scenery. They are the markers of the civilisation that built the towns around them. When those markers keep mysteriously burning to the ground what does that say about our civilisation?

This is now happening every week all over the world.

Historic London Church BURNS To The Ground Amid SILENCE From Government

ANOTHER Historic UK Church TORCHED; Cause “Unknown”

Another Day Another Church BURNED To The Ground

Another TWO Historic Churches Explode Into Flames…

Historic Buffalo Church TORCHED TWICE In Four Days Following Sale To ISLAMIC Group

NYC Historic Church TORCHED in Confirmed Arson — City REJECTS Save Plan As Demolition Ordered

NYC Church BURNS; Cause “Unknown”

Yet Another HISTORIC CHURCH TORCHED In Canada

Yet MORE Churches Torched; Sustained Attack On Christianity Gathers Pace

Your support is crucial in helping us defeat mass censorship. Please consider donating via Locals or check out our unique merch. Follow us on X @ModernityNews.

Tyler Durden
Mon, 09/07/2026 – 07:20

Labor Day Gas Prices Have Never Been Higher

0
Labor Day Gas Prices Have Never Been Higher

American travelers are facing record-high gasoline prices this Labor Day weekend as conflict in the Middle East and disruptions to global fuel supplies keep prices elevated.

The national average for a gallon of regular gasoline stood at about $4.15 on Sept. 5, according to the American Automobile Association (AAA). That is nearly $1 higher than a year ago.

This year’s Labor Day is now the first in history with a national average above $4 per gallon. The previous Labor Day record was $3.82 per gallon, set on Sept. 3, 2012.

Gas prices are displayed at a gas station in the New York City borough of Brooklyn on Sept. 4, 2026. Spencer Platt/Getty Images

As Bill Pan reports for The Epoch Times, GasBuddy analyst Patrick De Haan said he expects the national average to be about $4.03 on Labor Day, well above the previous record.

“Gasoline, while not at all-time records, is at its highest level ever recorded this late in the calendar year,” De Haan said.

Prices vary widely across the country.

AAA said California has the nation’s highest average on Sept. 5 at $5.83 per gallon, followed by Washington at $5.50 and Hawaii at $5.40. Oregon, Alaska, and Nevada are all near or above $4.90.

At the other end, Indiana has the lowest average at $3.43, followed by Texas at $3.67. Oklahoma and Mississippi are just above $3.70.

Air Travel Also Costs More

Drivers are not the only travelers facing elevated costs.

AAA booking data show that domestic round-trip airfare for Labor Day is averaging about $750, up by 2 percent from last year.

Travelers flying to the most popular domestic destinations face a much larger increase. Those fares are nearly 20 percent higher than a year ago, averaging close to $800 for a round trip.

However, international travelers are seeing some relief. Average international airfare is down by 4 percent from a year ago, according to AAA.

Oil, Fuel Supplies Under Pressure

Gasoline demand typically begins to decline near the end of summer as vacations end and schools reopen, putting downward pressure on prices. However, this year, high crude oil costs have outweighed the seasonal drop in demand.

Oil prices moved back above $90 per barrel this week, after renewed exchange of fire between the United States and Iran raised concerns about supplies moving through the Middle East.

The wartime disruptions in the Strait of Hormuz, one of the world’s most important oil shipping routes, have been a major source of uncertainty.

Oil traffic through the waterway has improved from earlier disruptions. U.S. Energy Secretary Chris Wright said 17 million barrels of crude passed through the strait on Aug. 31, the highest daily volume since shipments were disrupted by the war.

But continued fighting and threats to commercial shipping have kept energy markets on edge.

Another source of pressure has come from Russia, where Ukrainian drones target oil refineries deep inside Russian territory. Those strikes have tightened supplies of refined products such as gasoline and diesel.

“While some oil shipments are apparently getting through the Strait of Hormuz, the dominant force propping up both gasoline and diesel prices is increasingly the growing loss of Russian refinery capacity,” De Haan said.

“Until that refining supply picture improves, both gasoline and diesel prices face continued upward pressure.”

Measures to Boost Supply

For the week that ended on Aug. 28, American refineries were running at 98 percent of capacity, according to the Energy Information Administration. That was the highest utilization rate since August 2018.

The federal government has also taken steps to make it easier to move fuel around the country.

President Donald Trump extended a waiver of the Jones Act for another 90 days, through Nov. 15. The waiver allows some foreign-flagged vessels to carry fuel and other covered cargo between U.S. ports when qualified American ships are unavailable.

The Environmental Protection Agency has also relaxed seasonal fuel rules. An emergency waiver effectively ended summer-blend gasoline requirements early, beginning on Sept. 1, allowing more gasoline to enter the market.

Gasoline supplies remain tight. U.S. gasoline inventories fell by 1.2 million barrels last week to 205.7 million barrels. That was about 6 percent below the five-year seasonal average.

Tyler Durden
Mon, 09/07/2026 – 06:45

Cambodia, US Begin Planning For Resumption Of Military Exercises In 2027, Says Cambodian Army

0
Cambodia, US Begin Planning For Resumption Of Military Exercises In 2027, Says Cambodian Army

Authored by Victoria Friedman via The Epoch Times,

The Cambodian army announced it would resume joint military exercises with the United States early next year, in a bid to foster stronger relations nearly a decade since the last bilateral drills were held.

U.S. Under Secretary of War for Policy Elbridge Colby speaks as part of a meeting of NATO Ministers of Defense Summit at the NATO headquarters in Brussels on Feb. 12, 2026. John Thys/AFP via Getty Images

The Royal Cambodian Army (RCA) said in a statement on Facebook that it and other officials met with representatives from the U.S. Army Pacific and the Idaho National Guard between Aug. 31 and Sept. 4 to begin planning for Exercise Angkor Sentinel 2027.

The Sept. 4 statement said the meeting was “marking an important step toward the resumption of the bilateral exercise.”

Cambodian officials said both sides had discussed training activities, including a command post exercise, explosives disposal, and medical and engineering exchanges.

“Exercise Angkor Sentinel 2027 is scheduled to take place in February 2027, with the aim of strengthening interoperability and disaster-response capabilities, reflecting renewed momentum in Cambodia-U.S. military cooperation and a shared commitment to strengthening defense cooperation,” the statement said.

The announcement follows several meetings between U.S. and Cambodian officials in an effort to improve relations, after Phnom Penh suspended joint exercises with the U.S. military in 2017.

Cambodia said it canceled the 2017 exercises because its armed forces were needed for local elections and an anti-drug campaign. Some observers, however, saw the move as a sign that then-Prime Minister Hun Sen was distancing Cambodia from the United States, according to a 2018 report by the Congressional Research Service.

Last month, Under Secretary of War for Policy Elbridge Colby met with Cambodia’s prime minister, Hun Manet, as well as the country’s Minister of National Defense Tea Seiha.

Mutually-Beneficial Military Cooperation

Colby said in a series of Aug. 15 X posts that the United States was “building a stronger, practical defense relationship in a spirit of partnership, mutual respect, and pragmatism.”

The U.S. official said he and Seiha discussed Washington’s and Phnom Penh’s shared interest in expanding military cooperation in a way that is pragmatic and mutually beneficial.

“We are ready to work with countries like Cambodia where they are, through a realistic approach that focuses on where our interests overlap,” Colby said. “We want a Southeast Asia of independent, strong, and economically prospering nations.”

At the time, Manet said he was satisfied with the “positive momentum” in U.S.-Cambodian relations, as well as with the progress in preparing for Exercise Angkor Sentinel.

The Cambodian prime minister said that “the joint exercises and training not only build military capability but also serve as a vital bridge to foster close friendship between the armed forces of both countries.”

Washington has previously been concerned over China’s military presence at a Cambodian naval base on the Gulf of Thailand. China has assisted in upgrading the base, and the United States has voiced its suspicions that Beijing was granted special but secret privileges there. Cambodian officials have repeatedly rejected that claim.

US Seeks ‘Partners Not Protectorates’

Colby said on Aug. 10 that the United States was not disengaging from its Asian partners but wanted those partners to be more proactive in their own defense.

“America is definitely not disengaging from Asia,” Colby said in a speech in Manila, the Philippines. “We are not leaving; in fact, we are digging in, to ensure a favorable balance of power where it matters most.”

The Pentagon official made the remarks while on a broader tour of Asia, that included the Philippines, Thailand, Cambodia, and Indonesia.

Colby, the third-ranking official in the Department of War, said that when the United States asks for allies “to step up, to invest more in their own defense, and to take responsibility for their own sovereign security, we are not signaling abandonment.”

“We are looking for partners, not protectorates,” he said.

“When our partners are strong, deterrence is strong.”

The Associated Press and Reuters contributed to this report.

Tyler Durden
Mon, 09/07/2026 – 06:10

AfD Sweeps Saxony-Anhalt Election In First “Far Right” Victory Since WW2: “Signal To Berlin”

0
AfD Sweeps Saxony-Anhalt Election In First “Far Right” Victory Since WW2: “Signal To Berlin”

Update(1400ET): In a political earthquake, the AfD has taken a massive lead, per exit polls, at the Saxony-Anhalt election in what the party’s state leader hailed as sending a resounding “signal to Berlin.” This moment marks the first time what has been dubbed a German “far-right party” taking power at a state level since World War II. This is absolutely historic.

“The exit polls, published by German public television stations, suggested that the party, known by its German initials AfD, would win between 39 and 41 seats in the eastern state of Saxony-Anhalt,” NY Times reports. “That would leave it just short of an absolute majority of 42, but far ahead of its nearest rival.”

But it remains unclear whether it will be able to form a government. Below is the latest via Deutsche Welle:

Alternative for Germany (AfD) co-leader Tino Chrupalla  says his party secured a mandate to govern with its strong election result in Saxony-Anhalt.

“We have halved the CDU, so from that point of view it’s a great evening,” Chrupalla told journalists in Magdeburg, referring to an earlier remark by Christian Democratic Union (CDU) leader and chancellor Friedrich Merz that AfD’s result could be cut in half.

Chrupalla called the outcome “sensational.” 

“Ulrich Siegmund will be the new premier of Saxony-Anhalt,” he said. “From here, we will change Germany.”

If the party falls short of an absolute majority, Chrupalla said it would be open to talks and even suggested an AfD minority government could be tolerated by other parties.

AfD has signaled it is open to a coalition partner that would be open to changing its migration and energy policy – though this option doesn’t seem to be on the political map realistically at this early point.

Youth turn to AfD in droves…

AFP/Getty Images

*  *  *

Voters in Saxony-Anhalt head to the polls today in an election that could deliver Germany’s most massive political shock in decades, with the right-wing Alternative für Deutschland on track to beat Chancellor Friedrich Merz’s Christian Democrats.

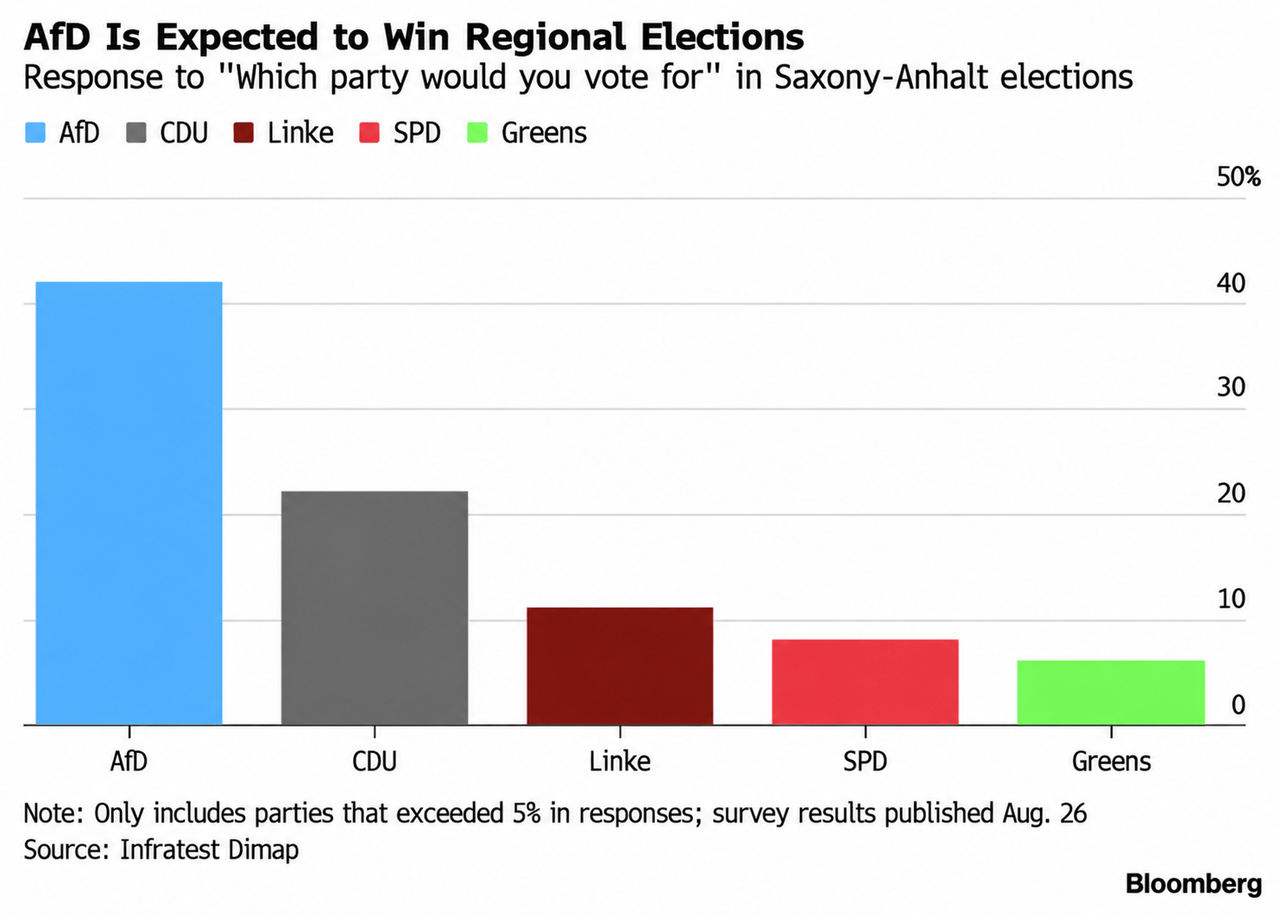
Final polling estimates put the AfD at 40% to 41%, nearly double the CDU’s 23%. The party’s lead candidate, 35-year-old Ulrich Siegmund, has ruled out governing in a coalition, suggesting the AfD would need an outright majority to take power of its first German state government.

About 1.7 million people are set to vote today, with polls closing at 6 p.m. local time. AfD’s rapid ascent comes as voters are furious over Germany’s stagnant economy, deindustrialization, energy costs, and the Third World migrant invasion.

The Polymarket bet on how many seats the AfD is expected to win today assigns a 74% probability to 38 to 41 seats, with 42 to 45 seats at 16%.

Ahead of the historic election, thousands of far-left Antifa crazies took to the streets wearing all black and holding Antifa and LGBT flags. Others were seen carrying signs reading “FCK NZS” and “FCK AFD.”

A reported 15,000 left-wing activists joined a so-called pro-democracy festival in the state capital, Magdeburg, on Saturday, organized by the “Saxony-Anhalt Open to the World” alliance. Yet the whole globalist cult in Germany has likely run its course. It has been nothing more than what some call a nation-killing experiment, pushing uncontrolled mass migration and deindustrialization policies that have sent Europe’s largest economy into a tailspin.

German Chancellor Friedrich Merz on Saturday threatened the AfD, saying, “We will not let these people, who trash Germany and everything we have achieved in recent years and decades,” before adding, “We will not let these people talk our country into ruin!”

German politics coverage:

What Nomura analysts see over the next 18-month election cycle across Europe: 

Yet what did Merz actually achieve? Destroying Germany’s economy? That is something he certainly accomplished.

Tyler Durden
Mon, 09/07/2026 – 06:00

The Reckoning Of 2028: Civilization’s Ledger Is Bleeding Red

0
The Reckoning Of 2028: Civilization’s Ledger Is Bleeding Red

Authored by Milan Adams via Prepp Group / WordPress,

Walk through the financial districts of London, New York, or Singapore at six in the evening, and you’ll catch the last act of a performance that grows harder to maintain by the quarter. The tailored suits still stream from glass towers into black cars. The conversations still touch on market adjustments and projections. But watch closely, and you’ll notice the strain. There’s a tightness around the eyes now, a rehearsed quality to the optimism. The numbers on their screens say one thing. The price of milk, rent, and diesel say another.

We’ve built an elaborate choreography around the idea that currency holds its value. Yet somewhere between 2019 and now, that assumption quietly fractured. A dollar doesn’t travel as far as it once did. It buys less bread, less time, less security. Central bankers have their explanations ready – inflation is transitory, supply chains are healing, the economy is resilient. But walk through a supermarket in Stuttgart, a gas station in Phoenix, a pharmacy in Manchester, and you’ll feel the truth your paycheck already knows. The purchasing power hasn’t just eroded; it’s evaporated, and official metrics barely capture the half of it.

The arithmetic is brutal when you look at it directly. Global debt has climbed to roughly $315 trillion. That’s not a percentage point on a chart. That’s a claim on future labor so vast it would take several generations working at full capacity just to service the interest, never mind the principal. In Washington, the federal government now borrows about $5 billion every twenty-four hours to keep the lights on. Weekends included. No holidays. The interest alone will swallow roughly $2 trillion this fiscal year. That’s more than the entire defense budget. More than all discretionary spending combined. These figures come from the Treasury Department itself, buried in reports that few bother to read.

Since 2008, and with terrifying acceleration during the pandemic years, monetary expansion has become the silent thief in everyone’s pocket. The Federal Reserve’s balance sheet hovered below $1 trillion in 2008. By 2022, it had ballooned to nearly $9 trillion. Even after some reduction, it sits above $7 trillion. This wasn’t money earned or produced. It was conjured through digital ledger entries, diluting every existing dollar in circulation. Official inflation numbers – those seven to nine percent figures you see in headlines – exclude the categories that actually determine whether families make it to the end of the month. Add housing, energy, and food back in, and you’re looking at fifteen to twenty percent erosion of purchasing power over five years. Ask any wage earner. They’ll tell you the official numbers feel like fiction.

Energy tells its own story, and it’s not the one politicians prefer. Despite all the transition rhetoric, the global economy still runs on hydrocarbons. The investment required to maintain current production simply hasn’t materialized. In the United States, the Strategic Petroleum Reserve has been drawn down to levels not seen since the 1980s – not for emergencies, but to manage political optics and prevent price spikes that might trigger unrest. Meanwhile, the easy oil is gone. What’s left requires more energy to extract, more capital to process. Major fields discovered decades ago are declining faster than new discoveries can replace them. By 2027, conservative estimates suggest demand will outstrip sustainable supply by several million barrels daily. Renewable infrastructure cannot scale fast enough to close that gap. The physics don’t care about our timelines.

The Portrait in Numbers

Let’s try to make $315 trillion concrete. If each dollar were a grain of sand, you’d fill about 120 Olympic swimming pools. That’s the debt sitting on balance sheets worldwide, earning interest, demanding service, compounding while we sleep. Every second, it grows by roughly $350,000 in new obligations. Every minute, $21 million. Every hour, $1.26 billion. The mathematics doesn’t negotiate. It doesn’t respond to political will or optimistic speeches.

Velocity matters too. In 1999, a single dollar of monetary base supported about $12 of economic activity. By 2023, that same dollar supported barely $3. Currency has grown sluggish, accumulating in asset markets where it inflates real estate and equity prices without building actual productive capacity. The wealth effect central banks tried to engineer – rising asset prices stimulating consumption – instead produced a split economy. Asset holders watch their portfolios swell while wage earners watch their real incomes shrink. In the United States, the top one percent now holds more wealth than the bottom ninety percent combined. We haven’t seen concentration like this since 1929. Economies need circulation. When capital pools at the apex, it stops moving. It stops working.

Look at the banking sector, supposedly fortified after 2008. Regional banks in the United States carry massive exposure to commercial real estate, a sector facing structural decline as remote work permanently reduces office demand. Estimated losses exceed $400 billion, concentrated in institutions without reserves deep enough to absorb them. The Federal Reserve’s emergency lending facilities see increasing use – not for routine liquidity management, but for solvency support that masks deeper problems. Liquidity issues are cash flow mismatches; time and bridging can fix them. Solvency issues mean your assets are worth less than your obligations. That’s permanent impairment. And we’ve been papering over it with accounting flexibility and regulatory forbearance.

Energy requires looking through thermodynamics, not just economics. A barrel of oil extracted in 1950 yielded about 100 barrels of equivalent energy for every barrel spent getting it out of the ground. Today, conventional oil manages perhaps 20-to-1. Shale and tar sands run below 5-to-1. That surplus energy – the energy available beyond mere subsistence – is what built modern complexity. As that ratio declines, the complexity it supports becomes harder to maintain. Renewables help, but they cannot replicate fossil fuel energy density and storage at the scale our economy demands. Transition, if it happens, means less energy available. Less energy means less economic activity. The conversation rarely acknowledges this trade-off.

When the Margins Vanish

Historical analogies for what’s coming often miss the mark because they focus on financial mechanisms rather than material constraints. The 1930s Depression occurred when energy availability was growing and industrial capacity expanding. The crisis was financial and organizational; the physical substrate could support recovery. What’s approaching now differs in kind. We’re facing not just a financial crisis requiring monetary adjustment, but a transition between energy regimes that will reshape economic geography, trade patterns, and the very possibility of growth.

Germany offers a real-time lesson. Europe’s industrial engine, with manufacturing at roughly 23% of GDP, has contracted for five consecutive quarters. Energy costs – driven by the loss of cheap Russian gas and inadequate replacement sources – have made German industry uncompetitive globally. Chemical plants producing fertilizer and pharmaceuticals have shuttered or relocated to jurisdictions with cheaper energy. This isn’t cyclical downturn. This is structural hollowing-out, the dismantling of industrial capacity that took decades to build. By 2026, projections suggest German manufacturing will contract to levels last seen in the early 1990s. The employment, tax revenues, and social stability that industrial work supported will follow.

China’s trajectory presents different warning signs. Property and construction account for roughly 25% of GDP when you include materials and related services. That sector is unraveling in slow motion that accelerates as it goes. Major developers have defaulted on obligations rippling through shadow banking networks opaque even to domestic regulators. Local governments, dependent on land sales for revenue, face insolvency as property values fall and transactions collapse. The demographic dividend that powered four decades of growth has reversed; the working-age population peaked in 2014 and declines by millions annually. The infrastructure built for growth – high-speed rail, airports, highways – now requires maintenance that strained budgets cannot afford, while utilization fails to justify operational costs. The model that lifted hundreds of millions from poverty has hit thermodynamic and demographic walls.

Japan may be the clearest preview. Three decades of monetary stimulus, government spending, and demographic aging produced a society where the central bank owns most government debt and significant equity positions, where interest rates cannot rise without bankrupting the government, where the yen has depreciated 40% against the dollar in two years despite these measures. The yen carry trade – borrowing cheap yen to invest elsewhere – has sustained global liquidity for decades but now threatens systemic disruption as the Bank of Japan attempts modest normalization. Japan demonstrates what happens when monetary policy reaches its limits: additional stimulus produces only currency depreciation without growth. The United States and Europe are approaching that threshold.

The global financial architecture, designed in 1944 for American industrial dominance and commodity-backed currency, grows more misaligned with material reality by the year. The dollar’s reserve status lets the United States borrow in its own currency and export inflation to trading partners. That status depends on confidence that American obligations will be honored in real terms. As debt-to-GDP ratios climb and political dysfunction prevents fiscal consolidation, that confidence erodes. Central banks worldwide have accelerated gold purchases, diversifying reserves away from dollar dependence at rates unseen since the 1970s. Bilateral trade agreements in yuan, rupees, and regional currencies multiply, creating parallel financial infrastructures that bypass the dollar system. These shifts happen gradually, then suddenly, as confidence thresholds breach.

The Reckoning Approaches

By 2028, the convergence of these pressures will likely produce discontinuities that current models cannot capture. The sovereign debt crisis that manifested at the periphery – Argentina, Lebanon, Sri Lanka, Ghana – will migrate to the core. Currency instability in smaller economies will trigger capital flight to the dollar, temporarily strengthening it before American obligations overwhelm even that haven. The euro, already fractured by divergent conditions between north and south, will face existential pressure as energy costs and demographic decline render southern European debt unsustainable. The Bretton Woods institutions, designed for American hegemony and expanding trade, will lack the resources and legitimacy to coordinate response to simultaneous crises across multiple jurisdictions.

Consider a few possibilities that sound shocking now but may seem obvious in retrospect.

By late 2027, a major developed economy – possibly Italy or Japan – could impose emergency banking holidays, restricting withdrawals to prevent collapse. Not for days. For weeks. The ATMs would run dry. The queues would form at dawn. Governments would promise restoration of access while quietly negotiating behind closed doors with the IMF for emergency liquidity that comes with sovereignty-shredding conditions.

Around the same timeframe, we might see the first sovereign default by a G7 nation on domestically-held debt. Not external debt – that’s already happened to smaller nations. But a major economy informing its own pension funds, its own banks, its own citizens, that obligations will not be met in nominal terms. The “guaranteed” would prove unguaranteed. Retirement accounts would be converted to longer-dated instruments at below-market rates, a soft default dressed as restructuring.

Energy markets could deliver their own surprises. By 2028, we might witness coordinated rationing in developed European economies – not through price mechanisms, which would exclude the poor entirely, but through direct allocation. Three days of heating per week. Rolling industrial blackouts prioritized by sector. The infrastructure exists to implement this; the smart meters are already installed. What’s missing is the political will to admit necessity until crisis forces the hand.

The psychology of this moment unsettles more than the numbers. We’ve been conditioned to believe economic systems self-correct, that markets find equilibrium, that intervention prevents catastrophe. These beliefs rest on assumptions of rationality and information symmetry that algorithmic trading, information asymmetry, and political capture of regulatory function have rendered obsolete. The denial isn’t conspiracy. It’s consensus – a shared unwillingness to acknowledge that the prosperity of recent decades was largely borrowed against a future that has arrived.

Those observing these patterns without ideological commitment to their reversal recognize we’re not approaching a single catastrophic event but a reconfiguration. The global economy of 2030 will not resemble that of 2020. Trade will regionalize as shipping costs and geopolitical friction make globalized production uneconomical for all but the highest-value goods. Living standards in developed nations will decline in absolute terms for the first time since the Second World War. This won’t appear as uniform deprivation but as chronic insecurity – housing instability, medical debt, the disappearance of retirement security for all but the wealthiest. Currency instability will necessitate capital controls, price controls, and gradual nationalization of financial systems that cannot function under market discipline.

This isn’t prophecy. It’s projection based on data that is publicly available and widely acknowledged among those who examine primary sources rather than prepared summaries. The debt curves, energy reserves, demographic pyramids, and monetary velocity measurements describe physical and social reality. That public discourse ignores them doesn’t invalidate them. It merely ensures the adjustment, when it arrives, will prove more disruptive than necessary because preparation was dismissed as pessimism.

The Ledger Closes

The question that remains isn’t whether the current trajectory alters, but who possesses flexibility to adapt when it does. Institutions designed for continuity – central banks, treasuries, international bodies – are not equipped for phase transitions, for moments when old rules cease to apply and new configurations emerge from disorder. Those who understand this distinction, who have studied historical precedent and recognize symptoms of systemic fragility, are already positioning themselves outside conventional structures. Not because they desire collapse. Because they see its inevitability.

Somewhere, in offices that will soon stand empty, analysts prepare reports that will never reach the decision-makers who need them. Spreadsheets calculate probabilities approaching certainty. The machinery of collapse operates slowly at first, almost imperceptibly, through erosion of trust and quiet abandonment of assumptions that once seemed permanent.

By the time the general population recognizes what has occurred, preparation will no longer be possible. The garage doors will be down. The signs will be posted. And the permanence of the closure will be undeniable.

Tyler Durden
Mon, 09/07/2026 – 05:00

Freedom Is Much More Important Than Democracy

0
Freedom Is Much More Important Than Democracy

Authored by J.B. Shurk via American Thinker,

Democracy invites despotism. When understood as majority rule, democracy means that fifty-one of every hundred citizens can have their way with the other forty-nine.

“But I want to keep my possessions, weapons, and children.” Too bad, the majority have decided to redistribute your property to those lazy bums over there, disarm you before you can do anything about it, and indoctrinate your children in public schools, so that they learn to resent you and love the State.

Democracy is dangerous without guardrails. Unless a society has a strong sense of moral virtue that fosters personal discipline, duty, and honor, base selfishness becomes the driving motivation behind all political action. Unless certain constitutional protections exist to safeguard each individual’s inviolable rights, democratic majorities devour those rights whenever expedient.

This should surprise no-one. Political philosophers such as Hobbes and Locke described humans’ pre-government “state of nature” as a chaotic, violent clash of self-interest. Adam Smith’s “invisible hand” regards self-interest as the engine of free markets. Consequently, it is easy to understand why forms of democracy that are unshackled from both moral and constitutional restraints prompt a society to descend back into a state of nature in which humanity’s worst impulses are again indulged.

When Western leaders speak adoringly of “our democracy,” citizens should prepare to guard their freedoms. My goodness, there is nothing inherently virtuous about democracy. North Korea’s Kim Jong Un runs the most repressive regime on the planet, but his country is known officially as the Democratic People’s Republic of Korea! China’s Xi Jinping is the general secretary of the oppressive Chinese Communist Party, but his nation remains officially the People’s Republic of China! Dictatorships around the globe claim to govern in the name of the people.

One might think that the blurry line between democracy and despotism would make Western leaders wary of singing democracy’s praises. Defenses of majoritarianism embrace the notion that the votes of a hundred people will lead to a more prudent outcome than we could reasonably expect from the decision-making of a single person. But that doesn’t make any sense. Would you rather live in a kingdom with a benevolent king or in a democracy filled with rapists, thieves, and murderers? If there is a 50/50 chance that any single dictator is good or bad, would there not be a 50/50 chance that a majority of citizens are good or bad, too? If one communist would take everything you have, wouldn’t fifty communists do the same thing? Democracy is a coin toss. It is the veneer of legitimacy that makes authoritarianism look shiny and sparkly. That hardly feels like something worth celebrating.

Democracy is just a process. It shouldn’t be idolized for its own sake. It can lead to just or unjust outcomes depending upon the moral virtue, shared culture, and general wisdom of the voters. Aside from these cultural attributes of a society, there is nothing more essential to a nation’s long-term peace and happiness than the recognition of and protections for inviolable, natural, God-given rights.

Freedom of speech, freedom of religion, freedom of association, the right to self-defense – these rights and other natural liberties do not come into existence because of majority rule. Our natural rights exist despite majority rule. As the Founding Fathers articulated in the Declaration of Independence, “We hold these truths to be self-evident, that all men are created equal, that they are endowed by their Creator with certain unalienable Rights, that among these are Life, Liberty, and the pursuit of Happiness.” We aren’t equal because of democracy; we are equal despite any democratic vote that might claim otherwise. Our lives, personal liberties, and connections to God exist because of His will, not the government’s.

The idea that rights and liberties exist separately from the promulgations of government forms the foundation of our constitutional system and, more generally, of human rights.

The U.S. Constitution spells out quite succinctly what powers each of the three branches of government – Legislative, Executive, and Judicial – shall have. From where do our three branches of government get these powers? The Preamble to the Constitution lays out the source of government power plainly: “We the People of the United States, in Order to form a more perfect Union, establish Justice, insure domestic Tranquility, provide for the common defence, promote the general Welfare, and secure the Blessings of Liberty to ourselves and our Posterity, do ordain and establish this Constitution for the United States of America.” In other words, the government’s legitimacy comes directly from the people.

Every power that one of the three branches exercises is a power that arises from and is borrowed from the individual citizens of the United States. Any power not specifically delegated to the U.S. government remains with either the individual state governments or individual American citizens. This is profoundly important. The Constitution is not a document that empowers the federal government to do whatever it wants. It is a document that says, “You get to do only these discrete things. Everything else is off-limits!”

During the Constitutional Convention, there was significant debate among the Founding Fathers about the need for a Bill of Rights explicitly defending the inalienable liberties of American citizens. Since the text of the Constitution clearly limits the delegated powers of each branch of government, some Founders resisted the inclusion of a Bill of Rights because they feared that later generations might incorrectly interpret Americans’ inviolable freedoms to include only those rights specifically listed. Other delegates feared that, without a Bill of Rights, later generations might incorrectly reimagine the Constitution’s limited delegation of powers to include additional authorities that directly infringe upon Americans’ personal rights. Both fears proved prescient.

In order to clearly state their intentions to maximize the size of Americans’ personal liberty and to minimize the powers of the federal government, the Founding Fathers gave us the Ninth and Tenth Amendments as part of the Bill of Rights:

Ninth Amendment: “The enumeration in the Constitution, of certain rights, shall not be construed to deny or disparage others retained by the people.”

Tenth Amendment: “The powers not delegated to the United States by the Constitution, nor prohibited by it to the States, are reserved to the States respectively, or to the people.”

Taken together, these two amendments provide a redundancy within the U.S. Constitution that is meant to preserve human liberty. First, the text of the Constitution restricts the authority of the federal government to a small number of specifically delegated powers. Second, the Bill of Rights repeats the framers’ intent to reserve all other powers for the people or their individual state governments.

With this understanding in mind, a reasonable person should ask: How is it possible that the federal government is now so large and powerful that it encroaches upon nearly every aspect of our private lives? How is it possible that tens of millions of Americans either work directly for government agencies or receive taxpayer dollars in some form? How is it possible that there are too many administrative agencies, committees, and bureaucratic groups for any one person to name? How is it possible that three federal branches with a small number of delegated authorities have been replaced with a growing number of government programs with seemingly unlimited authorities?

The answer to each of these questions is the same: The generations between the Founding Fathers and our own progressively traded freedom for democracy. In the name of the people, lawmakers, presidents, and judges ignored the plain text of the Constitution – including the Ninth and Tenth Amendments of the Bill of Rights – to steal our inalienable rights and liberties.

In order to reject democracy’s despotism, the American people will have to demand their rights and liberties back.

We publish a variety of perspectives. Nothing written here is to be construed as representing the views of ZeroHedge.

Tyler Durden
Sun, 09/06/2026 – 23:40