56.5 F
Chicago
Friday, October 2, 2026
Home Blog Page 2

Counter-ISIS Mission In Iraq Comes To An End

0
Counter-ISIS Mission In Iraq Comes To An End

Authored by Patty Nieberg via Task & Purpose,

The U.S. military-led mission to counter the Islamic State in Iraq has officially come to an end.

Counter-ISIS Mission In Iraq Comes To An End. Operation Inherent Resolve will continue with a new hub in Jordan to counter ISIS in Syria.

U.S. Central Command (CENTCOM) announced Wednesday that the “orderly departure” of U.S. personnel and equipment from Erbil Air Base in northern Iraq was officially complete. Officials said the withdrawal marked the end to Operation Inherent Resolve in Iraq, the U.S. military’s counter-ISIS mission in the country.

The Erbil Air Base had served as a central hub for the Combined Joint Task Force-Operation Inherent Resolve mission since U.S. forces had been invited back by the Iraqi government to fight ISIS insurgents in the country.

The U.S. invaded Iraq in 2003 to topple Saddam Hussein, and by 2011, American forces left the country. As ISIS insurgents took hold of broad swaths of the country, Iraqi authorities invited a smaller contingent of U.S. forces to help counter the growing threat. Operation Inherent Resolve, a U.S.-led international coalition of military partners, was then established in 2014.

A majority of the 1,500 American and coalition partners supporting these operations worked out of Erbil. The mission will now be headquarters based in Jordan for U.S. forces to continue its mission focused on Syria, officials said.

“As we step back and hand full primary responsibility for Iraq’s security to the Government of Iraq and the brave people of Iraq, U.S. and Coalition forces stationed across the region will remain ready to respond to any ISIS threats that arise,” Adm. Brad Cooper, CENTCOM’s commander, said in a release. “Maintaining our vigilance and readiness is essential to protecting the U.S. homeland and strengthening regional security.”

For more than a decade, U.S. troops have trained and assisted Iraqi partner forces to fight ISIS in Iraq and Syria. In 2024, the U.S. and Iraq reached an agreement for a new bilateral security partnership, which ended the coalition’s work in the country and moved the U.S. towards more of an “advisory” and “capacity-building” role for Iraqi security forces.

“ISIS no longer poses a systemic threat to Iraq’s national security and Iraqi security forces, including the Peshmerga and other Iraqi Kurdistan Region security forces, now possess the capacity, leadership, and operational independence to unilaterally manage threats to their homeland,” Cooper said.

When the new security partnership with Iraq was announced in 2024, U.S. officials would not say how many of the roughly 2,500 troops in Iraq would ultimately withdraw or stay behind. Department of Defense officials said in a release Wednesday that local security forces would lead counter-ISIS efforts in the country but that the U.S. would continue providing “targeted training and intelligence support to our Iraqi partners.”

In response to inquiries about how many American troops would be in Iraq going forward, a U.S. official declined to comment, citing operational security.

The withdrawal comes as the U.S. war with Iran enters its eighth month. The U.S. withdrawal prompted mixed feelings among Iraqis about the departure of American forces in the country after decades of war, and concerns from Kurdish officials who worry that the removal of U.S. air defense equipment will leave the Kurdistan region vulnerable to Iranian drone and ballistic missile attacks.

Tyler Durden
Thu, 10/01/2026 – 22:35

Trump Explains Why He’s Okay With North Korea Having Nukes, But Not Iran

0
Trump Explains Why He’s Okay With North Korea Having Nukes, But Not Iran

Here’s what White House spokesperson Anna Kelly said a mere week ago on the rationale for the US attacking Iran: “The President is courageously ensuring that such an evil country never possesses a nuclear weapon, which will make the entire world safer and more stable,” she said.

This week President Trump was asked why he seems OK with a deeply totalitarian state like North Korea and its dictator Kim Jong Un having nuclear weapons, and not Iran.

Trump’s blunt response really deflates the sham talking points of the war’s cheerleaders among Conservatism Inc, the FoxCon crowd, and NeoCon pundits and “intellectuals”. So much for the whole defeat the “mullahs because they’re evil!” fake morality tale…

“Ahh, because you had a different president. Kim Jong Un. He’s a friend of mine. He likes Trump. I like him,” Trump said when a reporter pressed him.

“As long as I’m around, he’s going to be fine,” Trump continued. “You know why? He respects me.”

By this strange logic, Pyongyang – which has on many more occasions (than Iran) directly threatened the United States going back literally decades  – possessing nukes is just fine. Or in other words Kim=”friend”/Good, Ayatollah= Rogue Bad Guy, according to the simplistic equation. The inconsistency of the obviously self-defeating ‘moral high ground’ narrative advanced by the administration is baffling.

On a more serious note, the above exchange highlights something deeper: nation-states most often seek nukes precisely in order to get respect especially when facing destruction at the hands of a more powerful enemy.

The US and Israel have long claimed that Tehran is bent on annihilating Israel, and that its leaders will pull the trigger the moment they develop an atomic weapon (a pursuit the Iranians have over many years denied). Essentially, this is the mad mullahs myth, based on the NeoCon axiom that every Iranian leader is an irrational actor fundamentally bent on ushering in nuclear apocalypse against the Jews, self preservation or any other domestic consideration be damned.

When Trump said of Kim, “he respects me” – the irony here is in reality it is Washington that’s forced to ‘respect’ North Korea because it possesses dozens of nukes and has the military tech to deliver them. Countries like Iran want this ‘respect’ too.

On the level of strategic realism, it’s just the way the world works (ask Gaddafi)–>

From the perspective of its beleaguered leaders who’ve been under US bombs and blockade for seven months, Iran has two choices. It must choose one:

1. Become Libya

2. Become North Korea

“We Came, We Saw, He Died.” — Hillary Clinton

Below: On the ‘moral mythmaking’ of Neocons & Liberal Interventionists VS. strategic realism in international relations, an important conclusion:

“These leaders need to be treated as rational actors that, in turn with other members of their government, act based on strategy.”

Rajan Menon, professor emeritus of international relations at the City College of New York, told Newsweek: “If you stand for nonproliferation, you can’t say it’s OK because they already have them.” And the reality is, Menon continued, “there’s no reasonable way to undo the fact that North Korea is a nuclear-armed state.”

*  *  *

An archived interview where retired diplomat Jim Jatras talks nukes and ‘rogue’ actors getting ‘respect’…

Tyler Durden
Thu, 10/01/2026 – 22:10

“The Cycle’s TXU?”: Paramount’s Record Bond Offering Craters Before The Ink Is Dry

0
“The Cycle’s TXU?”: Paramount’s Record Bond Offering Craters Before The Ink Is Dry

On Monday we flagged that September was shaping up as the worst month for junk since 2022. We also noted that Paramount’s $12.4 billion high-yield tranche would be bigger than SoftBank’s recently issued record $11 billion junk deal. The next morning the company kicked off the high-grade portion. By Tuesday afternoon it reported $109 billion of demand. 

With so much excess demand, the offering was supposed to fly off the shelves. It did not: the deal priced on Wednesday, the same day a judge accepted the states’ settlement and the merger was scheduled to close on Oct. 6. It is the biggest takeover financing Hollywood has seen, for the biggest Hollywood buyout ever. Paramount won Warner Bros. from Netflix back in February.

While underwriters usually leave a little on the table for new-issue buyers, they didn’t this time, and all the new issues faceplanted the moment they broke for trading.

What was sold

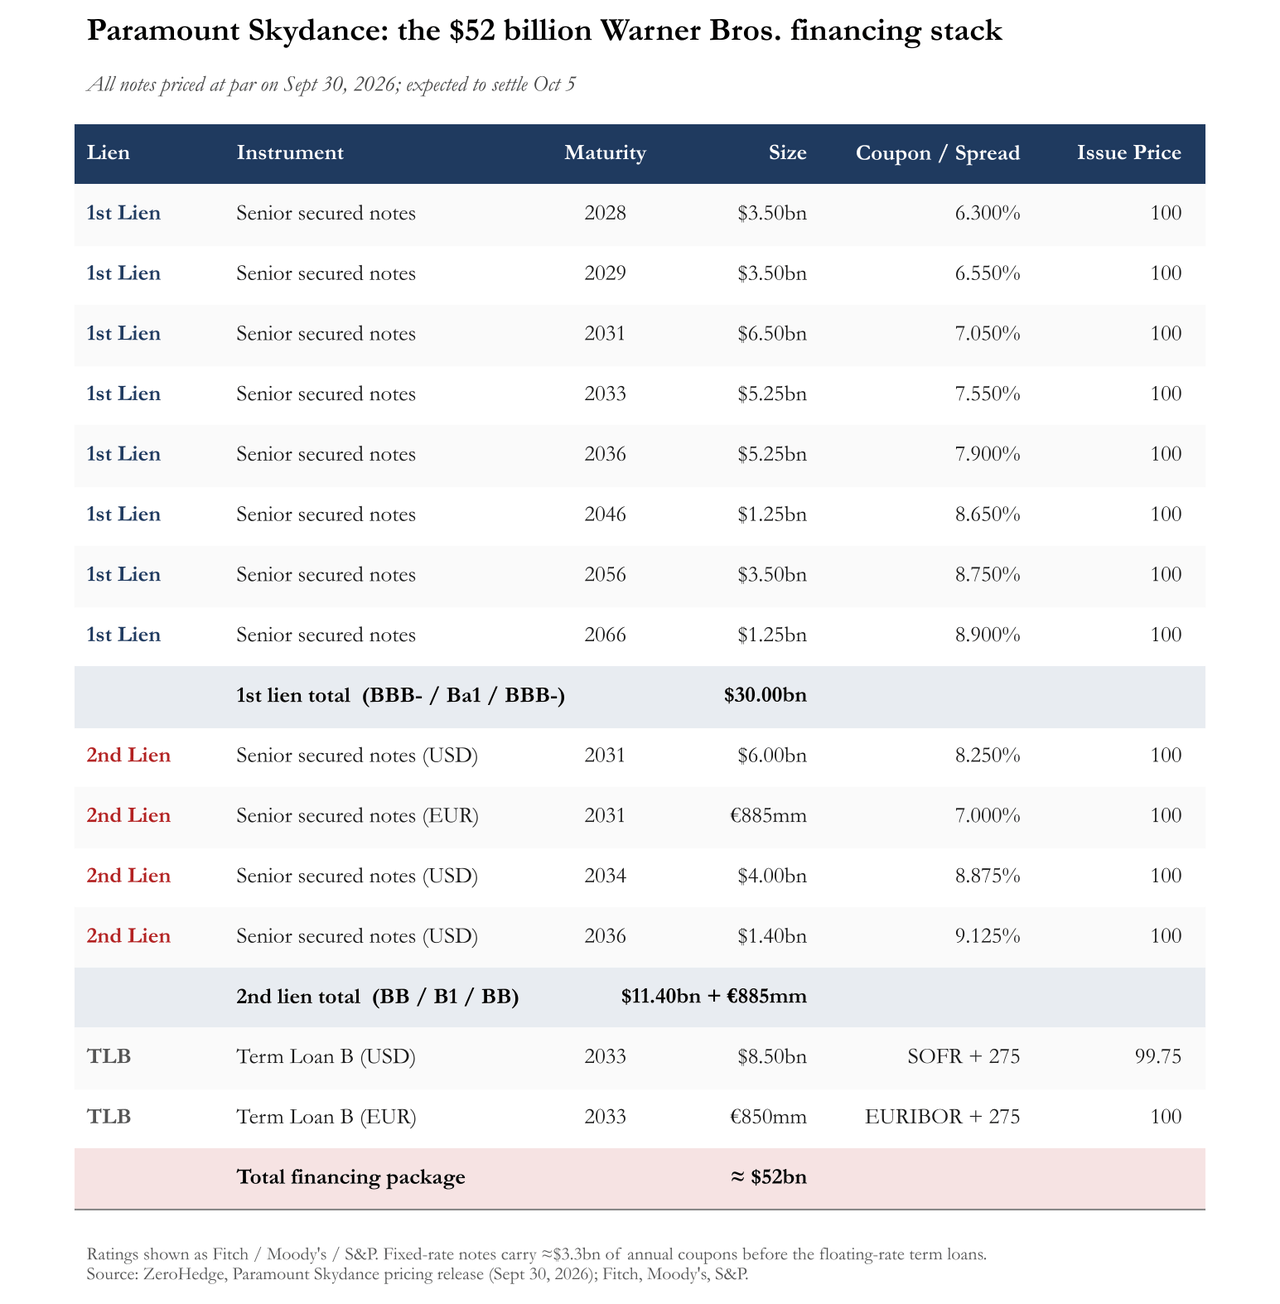
Here is the full stack from the company’s pricing release. The $52 billion package has three parts:

  • $30 billion of first-lien notes across eight tranches, from 2028 to 2066, rated BBB-/Ba1/BBB-.
  • $11.4 billion plus €885 million of second-lien notes (i.e. junk) rated BB/B1/BB.
  • An $8.5 billion and €850 million term loan B at SOFR/EURIBOR+275.

Every note priced at par.

Every tranche priced at par. The junk second-lien notes come with junk-sized coupons.

What happened next

On Wednesday evening, Goldman’s credit desk wrote that “IG cash felt firm, supported by beta compression and outperformance from PSKY.” That lasted about one night.

Here is Goldman’s credit desk Thursday’s 7:38am macro update:

“Despite IG cash feeling firm most of the day, PSKY traded heavy and is now +10 from the break, and the WBD 2L bonds are down ~3pts from new issue price. Generically, HY cash has continued to lag HQ with insurance and mortgage originators feel the most pain.”

Things got much worse from there. According to Bloomberg and TRACE data:

  • The 8-year dollar second-lien notes, which priced at 100 on Wednesday, traded a touch above 95. That works out to a yield of about 9.7%. On the $4 billion tranche, that is roughly $200 million of paper losses within minutes of breaking .
  • The $5.25 billion 10-year first-lien bond, issued at T+262.5, was quoted near T+278.
  • Investment-grade paper alone booked more than $200 million of unrealized losses.
  • Paramount’s 5-year CDS rose as much as 53bp to 432bp, the highest since April 2009.
  • The stock fell as much as 7.5%.

Day-one returns for anyone who got a full allocation.

While widely trumpeted as a sign of relentless demand ahead of pricing, the (alleged) $109 billion order book shrank to about $80 billion by pricing. Demand at the long end fell by more than half. That is the same pattern as June’s $25 billion SpaceX deal, which also struggled once it was free to trade. The investors who stayed in received most or all of what they asked for, especially in the long bonds. Many of them didn’t feel like staying after the bonds didn’t rise after the break… and immediately sold on Thursday morning.

Traders reportedly called and messaged the lead banks (Apollo, BofA and Citi, syndicated across 18 banks) to complain. The bank, for their part, were quick to point out what a great offering this was (for them, and the company perhaps): Citi’s Leon Kalvaria said the financing “turned out incredibly well in a choppy market.” CFO Dennis Cinelli called the selloff “one-day choppiness.”

Goldman’s desks saw it coming

To be fair to the bankers, nobody who reads Goldman’s credit traders should be surprised. Goldman’s portfolio-trading desk (Sarah Zappone) wrote on Sept 26, before launch:

“$32bn in 1L secured IG bonds (whispered ~50bps steep on 10s30s!)… We suspect this package prices well wide of CHTR given the deal scale and elevated pro-forma leverage.”

Brad Shelofsky on the IG trading desk said the same day that “~$30bn will be wide trading 1L secured IG bonds.” Just the whispers about the deal had been enough to hit the market. Bonds trading wider than 200bp ended that week 9bp wider, versus 3.5bp for the 0-100bp bucket. He also warned that the risk was to credit curves steepening, since “the likes of PSKY will bring some wide trading duration.” Paramount alone was expected to push September high-grade supply close to the desk’s $230 billion estimate.

Alisha Pasi’s weekly “What’s Trending Across Credit” summed up the setup. SoftBank had just printed the largest non-IG bond sale on record, and Paramount was lining up “another potentially record-setting ~$12.4bn HY financing.” Pasi wrote:

“The ability of the market to absorb back-to-back jumbo transactions should be a useful test of demand at still-tight valuations… the margin for error has clearly narrowed.”

The test had a clear result.

Paramount also had no control over its timing. The lawsuits blocking the financing were only settled late last month, and the ticking fee kept running every day the deal stayed open. Goldman’s special situations desk calculates that WBD holders will receive $31.0167 a share at the Oct. 6 close, based on a ticking fee of 0.278 cents per day. Impax’s Tony Trzcinka put it simply: the timing was “partly forced.”

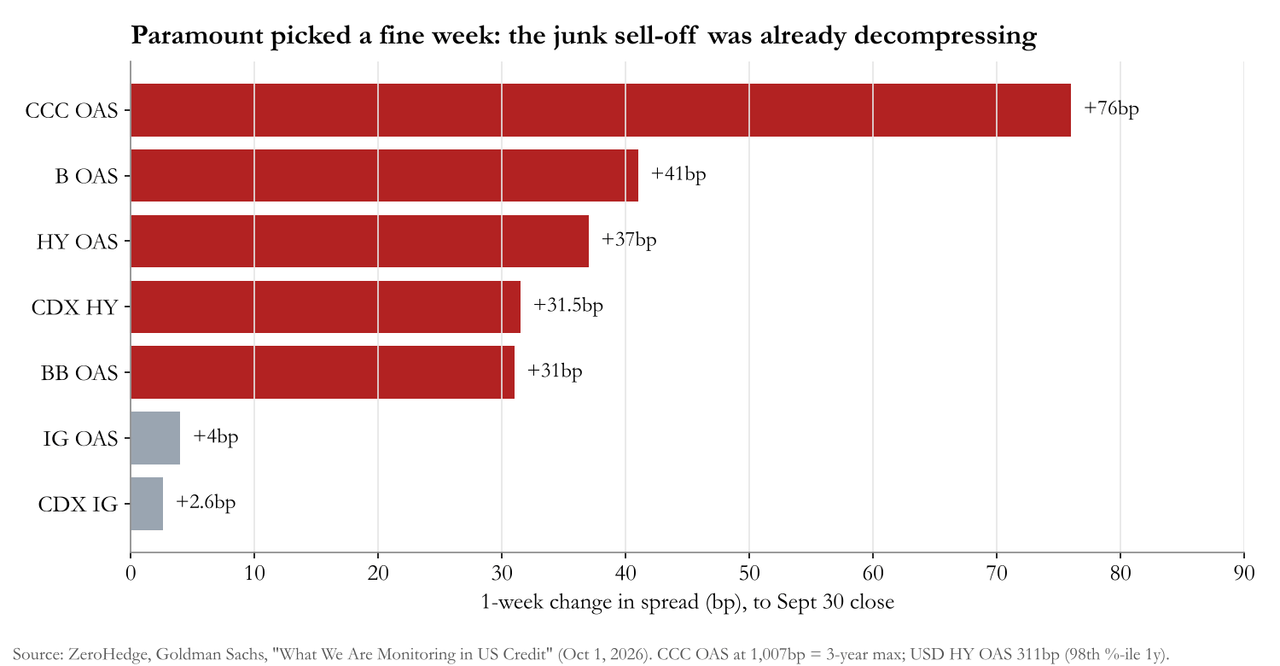
Needless to say, the window Paramount was forced into was one of the worst for credit in years. As we noted on Wednesday, credit was “cracking big time.” CCC spreads turned distressed for the first time since the 2023 bank crisis. Goldman’s credit monitor (Reid Zhou) shows how lopsided the damage was as of Wednesday’s close:

  • USD HY OAS 311bp, up 37bp in a week (98th percentile over one year)
  • CCCs at 1,007bp, a three-year high, up 76bp on the week
  • IG OAS up just 4bp
  • iBoxx IG all-in yields at 6.50%, the 100th percentile going back to 2004

The lower the rating, the bigger the move, and Paramount just brought $12.4bn of BB/B1 paper smack into the middle of it.

Rates added to the pressure. Goldman’s rates desk said the long end hit new highs on Wednesday “after US consumer spending rose at this fastest pace in a year… and Paramount priced their $30bn eight part offering.” It also said the long end was “potentially weighed down by corporate supply alongside hedging flows.” The 10-year went above 5.30% for the first time since 2002. The 30-year touched 5.60%. As Deutsche’s Jim Reid put it this week, “Equity investors see the growth, and bond investors see the bill.”

The “cycle’s TXU”?

The Bear Traps chat was less charitable. One CIO wrote:

“A mkt taking on 2 or 3 record / MONSTER equity IPOs (SpaceX, Anthropic) and this MONSTER debt offering at the same time – these are cycle TOP signposts… Paramount’s existing unsecured bonds? Primed. TXU (2007) is still the largest LBO ever, but this is our cycle’s TXU.”

That point about priming deserves attention. Holders of Paramount’s legacy unsecured debt now rank behind $30 billion of first-lien and $12.4 billion of second-lien secured paper.

And here is a technical twist on the Paramount loans, flagged by Goldman. The new Paramount term loan (marketed at $7.5 billion and upsized to about $9.5 billion at pricing) comes alongside repayment of WBD’s roughly $15 billion term loan. Nearly 90% of US CLOs under Fitch surveillance hold that loan, and O’Connor says “upon settlement, it will amount to one of the largest paydowns in history.” That is a large amount of CLO cash that will need a new home, at the same time the CLOs’ favorite collateral is being repriced.

The other side

For the bulls, JPMorgan’s Saul Doctor notes that the bank’s Fear & Greed index has hit oversold (83, versus a trigger of 80). CDX IG is just shy of 60bp, which is 6bp from the YTD wides. According to Doctor, three months of carry on CDX IG (30c) would recoup a move back to the wides. In other words, panic sellers of high grade have historically been the ones who lost money.

The problem is that Paramount’s new bonds are not CDX IG. They are a split-rated, 7x-levered, record-sized new issue whose biggest buyers were left holding more than they wanted. Those investors also learned within 24 hours that the “concession” was a markdown. Whether this was “one-day choppiness” will be clear soon enough: Paramount is still looking for equity, CDS is at 2009 levels, and the deal closes on Tuesday. And as for the key sponsor, Larry has many other problems on his mind.

Tyler Durden
Thu, 10/01/2026 – 21:38

Australia’s Tobacco Taxes Have Fueled A Massive Black Market For Cigarettes

0
Australia’s Tobacco Taxes Have Fueled A Massive Black Market For Cigarettes

One lesson governments never seem to learn is that when taxes push the legal price of something high enough, a black market will eventually show up to collect the difference.

Australia is now getting a particularly ugly demonstration of that principle. After more than a decade of relentlessly increasing tobacco taxes in an effort to crush smoking, the country has created an enormous price gap between legal and illegal cigarettes, and organized crime has rushed in to fill it, according to the Financial Times.

A legal pack of cigarettes now costs close to A$60, or roughly US$42, making Australian cigarettes the most expensive in the world. Excise taxes account for more than 70% of that price, and the cost of legally purchased tobacco has roughly tripled since the end of 2016. Meanwhile, contraband cigarettes can be bought for around one-fifth of the legal price.

Charts: Financial Times

Not surprisingly, smokers have migrated to the underground market. Australia’s tobacco regulator estimated that illegal cigarettes accounted for roughly 55% of the market last year, although other government estimates suggest illicit tobacco’s share of consumption may be considerably higher.

Criminology professor James Martin estimates Australians spend about A$8.5 billion each year on illegal cigarettes and vaping products, roughly twice what the country spends on cannabis, cocaine, ecstasy and heroin combined. In practical terms, criminal organizations have become major tobacco distributors.

FT writes that the consequences are no longer limited to lost tax revenue or smokers buying cheap cigarettes under the table. The business has become lucrative enough to produce violent competition between criminal groups, including extortion, robberies and a wave of firebombings in Melbourne and Sydney. A recent Senate report cited three deaths connected to the violence, while the convenience-store industry says there have been roughly 300 arson attacks associated with the tobacco trade.

The Senate report described the situation as reaching a breaking point and recommended halting further excise increases while substantially reducing tobacco taxes. The government has resisted, maintaining that expensive cigarettes remain an effective deterrent. There is evidence for that argument: the smoking rate among Australians over 14 reportedly fell from 8.3% to 5.6% between 2023 and 2025.

Charts: Financial Times

But nicotine consumption tells a less straightforward story. Wastewater measurements from the Australian Bureau of Statistics indicate that nicotine consumption increased by almost 40% between 2017 and 2025, with illicit tobacco driving much of the increase. Illegal vaping products have also captured an overwhelming share of their market.

The fiscal side of the experiment has deteriorated just as dramatically. Tobacco excise revenue reached about A$16 billion in 2020, fell by more than half by 2025 and is projected to sink toward A$2 billion by 2030.

Authorities have committed A$365 million since 2024 to fighting the illicit trade, including efforts against smugglers and retailers. One recent joint operation with Chinese authorities intercepted roughly 60 million cigarettes shipped from Shanghai to Sydney, valued at about A$92 million. But the market continues to spread, with contraband reportedly sold online, from parking lots and through ordinary businesses such as barbers and fruit shops.

Australia’s tobacco experiment has therefore arrived at a strange destination. Legal cigarettes have been taxed to extraordinary prices, government revenue is collapsing, billions of dollars are flowing through an underground economy, and criminal groups are fighting over the proceeds. Whatever public health benefits higher taxes initially produced, policymakers are now confronting what happens when the legal price of a widely demanded product becomes disconnected enough from its black-market price to make breaking the law enormously profitable.

Tyler Durden
Thu, 10/01/2026 – 21:20

How The Iran Conflict Opened A New Threat To The Global Monetary System

0
How The Iran Conflict Opened A New Threat To The Global Monetary System

Authored by Milan Adams via Preppgroup,

Midnight fell differently on February 28, 2026. Across trading floors from Singapore to Chicago, monitors flickered with data streams that would soon curdle into panic. At 0400 hours Tehran time, American B-2 Spirit bombers and Israeli F-35I Adir fighters crossed into Iranian airspace, unleashing Operation Epic Fury. Nine hundred strikes in twelve hours. Ali Khamenei, Supreme Leader of the Islamic Republic, perished in the initial bombardment, his body recovered from the rubble of a command bunker beneath Tehran’s northern suburbs. Markets had anticipated conflict. They had not anticipated decapitation.

Brent crude, trading at $72.48 per barrel at market close on February 27, surged past $120 within seventy-two hours. By March 19, Dubai crude reached $166 per barrel, an all-time record. California gasoline exceeded $5 per gallon.

Kristalina Georgieva, Managing Director of the International Monetary Fund, stood before cameras in Washington on April 9, 2026. “All roads now lead to higher prices and slower growth,” she declared. Her institution had just slashed global growth projections to 3.1 percent, down from 3.4 percent anticipated before the first missiles launched. “Had it not been for this shock, we would have been upgrading global growth.” Instead, the Fund warned of a “severe scenario” where global growth collapses to 2.0 percent, brushing against the technical definition of worldwide recession – a threshold breached only four times since the Second World War. “This would mean a close call for a global recession,” the World Economic Outlook stated.

Donald Trump, returned to the presidency for a second non-consecutive term, addressed the nation from the Oval Office on August 20, 2026. “Any country that allows its financial institutions, businesses, airports, or government entities to provide any type of lifeline to Iran will itself face tremendous economic consequences,” he warned, announcing what he termed “the toughest sanctions in history.” Earlier, he had posted an image on social media showing the Strait of Hormuz crudely labeled as “New US Territory,” a digital annexation that sent tremors through diplomatic channels. His administration’s Operation Economic Fury sought to complete what Operation Epic Fury had begun. “To the ordinary soldiers supporting this regime,” Trump addressed Iranian conscripts directly, “as more and more of your paychecks stop or are supposedly just delayed, ask whether your commanders are leading your country to triumph or to ruin.”

Jerome Powell, in his final months as Federal Reserve Chair, confronted the economic paradox that would define 2026. At a Harvard forum on March 30, he admitted the central bank’s predicament with uncharacteristic candor. “Nobody knows,” he stated, referring to the war’s ultimate economic impact, while acknowledging that “you can be confident that an inflationary shock will fade, but have very little idea how long it will take.” The Fed’s March 18 decision to hold interest rates steady – projecting only a single rate cut for the year despite inflation spiking to 3.3 percent – represented a capitulation to uncertainty. Powell’s institution projected higher inflation, steady unemployment, and minimal monetary relief.

Nouriel Roubini, the economist whose prescient warnings preceded the 2008 financial collapse, offered scenarios in May 2026 that chilled institutional investors. “Oil prices could spike past $200 a barrel in the worst-case scenario,” he predicted, describing a return to “1970s stagflation.” Mohamed El-Erian, former Pimco chief and now Chief Economic Advisor at Allianz, tweeted his assessment of the IMF’s April report: “Reading between the lines, the message of today’s IMF flagship report is sobering: Virtually every challenge facing the global economy is poised to intensify due to the fallout of the Middle East War.“

The World Bank’s June 11, 2026 Global Economic Prospects report confirmed these apprehensions. Global growth would slow to 2.5 percent in 2026, the weakest expansion since the COVID-19 pandemic. For developing and emerging markets, the forecast plummeted to 3.6 percent. Iran’s economy contracted by 6.1 percent, with the Bank noting that “real GDP is projected to contract by 6.4 percent in 2026, reflecting the collapse in tourism, weaker consumption, disrupted supply chains, heightened insecurity, and prolonged displacement.” Qatar and Kuwait faced potential GDP contractions of 14 percent. The Institute for Economics and Peace calculated that a resumption of full-scale hostilities would deliver a $2.2 trillion hit to the world economy.

Economic Impact Projections by Institution, 2026

Institution Global Growth Forecast Inflation Projection Severe Scenario Oil Price Assumption
IMF (April 2026) 3.1% (down from 3.4%) 4.4% 2.0% growth, 5.4% inflation $100/bbl (reference), $140+ (adverse)
World Bank (June 2026) 2.5% (down from 2.9%) 4.0% 2.0% or below $120/bbl average
OECD (March 2026) 2.7% 3.2% US, 3.0% Eurozone Technical recession in energy-intensive economies $90-110/bbl range
Oxford Economics 2.8% 4.2% 1.5% growth if Hormuz closed 3+ months $140/bbl threshold for demand destruction

Regional GDP Contraction Projections, 2026

Economy Pre-War Forecast Post-War Projection Revision Primary Transmission Channel
Iran +1.1% -6.1% to -6.4% -7.2 pp Infrastructure destruction, sanctions
Qatar +3.2% -14.0% -17.2 pp LNG export disruption, Hormuz closure
Kuwait +2.8% -14.0% -16.8 pp Oil export cessation
Iraq +2.1% -8.5% -10.6 pp Supply chain fracture, refugee costs
Bahrain +1.9% -6.8% -8.7 pp Financial sector exposure
Saudi Arabia +3.5% -3.0% -6.5 pp Reduced oil volumes, price volatility
UAE +3.8% -5.0% -8.8 pp Trade finance disruption
Eurozone +1.2% +0.8% -0.4 pp Energy import costs, manufacturing
United States +2.1% +1.8% -0.3 pp Gasoline prices, consumer sentiment

Oil Market Disruption Metrics, February-September 2026

Metric Pre-War (Feb 27) Peak Crisis (Mar 19) Recovery Phase (Jun 24) Current (Sep 30)
Brent Crude ($/barrel) $72.48 $166.00 (Dubai) $72.24 $73.23-$97.00
Daily Oil Flow via Hormuz (mbpd) 21.0 0.5 8.2 14.5
Strategic Reserve Drawdown (US, mb) 0 180 120 85
Gasoline Price California ($/gal) $4.12 $5.08+ $4.45 $4.28
LNG Force Majeure Declarations 0 12 (QatarEnergy) 3 0

Beneath these statistics lies a more troubling reality. Global debt reached $348 trillion in 2025, according to the Institute of International Finance, expanding by nearly $29 trillion in that single year. By mid-2026, estimates placed the figure above $365 trillion. This edifice of obligation, constructed during fifteen years of central bank suppression of interest rates, now faces a refinancing crisis as monetary authorities maintain elevated borrowing costs to combat inflation. The OECD’s Global Debt Report 2026 warned of “increasing pressures from sustained fiscal deficits, rising interest costs and investment needs, a structural decline in long-term demand, and growing refinancing risks as the maturity of issuance shortens.”

Small and medium enterprises find themselves particularly exposed. S&P Global’s 2026 banking risk analysis noted that SMEs “have thinner capital buffers and proportionately more floating-rate exposure,” rendering them acutely vulnerable to the higher interest costs that the Iran war’s inflationary impact necessitates. When the Federal Reserve chose steady rates over relief in March 2026, these businesses absorbed the blow directly.

The weaponization of the dollar has generated blowback that Washington’s Treasury Department struggles to contain. China’s Cross-Border Interbank Payment System (CIPS), processing the equivalent of $245 trillion in yuan-denominated transactions in 2025, has emerged as a functional alternative to SWIFT. By January 2026, CIPS linked 1,467 indirect participants across 119 countries, connecting 4,800 banks in 185 nations. While still smaller than SWIFT, its trajectory suggests a fragmentation of monetary infrastructure that the Iran conflict has only accelerated.

The petrodollar system faces unprecedented stress. Russia and Saudi Arabia, the two largest oil producers, generated “essentially zero petrodollars” in 2025 according to Wright Research analysis, having shifted to yuan-denominated settlements. Iran, excluded from dollar markets since 1979, pioneered this transition. Now the template spreads. BRICS nations conducted an estimated 90% of intra-bloc transactions in local currencies by 2025.

This matters profoundly for American fiscal sustainability. Foreign holdings of U.S. Treasury securities have plateaued as central banks diversify reserves. The dollar’s share of global foreign exchange reserves declined from 73% in 2001 to approximately 54% in 2025, per IMF data. Each percentage point shift represents hundreds of billions in reduced demand for dollar-denominated assets, increasing the interest premium Washington must pay to finance its $34.6 trillion national debt.

The Iran war operates as an accelerant upon these pre-existing trends. When Trump threatened “crushing economic warfare” in August 2026, he extended a sanctions regime that had already demonstrated diminishing returns. Iran’s economy, while battered by 6.4 percent contraction and currency collapse, had developed sophisticated evasion mechanisms through shadow banking networks and cryptocurrency channels. The Islamic Republic’s oil smuggling to China, estimated at 1.2 million barrels daily despite sanctions, continued through “dark fleet” tankers operating with disabled transponders.

European Central Bank President Christine Lagarde, in deliberations that postponed planned rate cuts on March 19, 2026, confronted the dilemma that would define transatlantic economic divergence. Energy-intensive European economies faced technical recession risks if the Hormuz maritime blockade persisted. German manufacturing, already weakened by the cessation of Russian natural gas supplies following the Ukraine conflict, confronted additional input cost shocks. The ECB raised its 2026 inflation forecast while slashing growth projections.

Japan’s position proved equally precarious. As the world’s largest liquefied natural gas importer, Tokyo faced energy security vulnerabilities that the Iran war exposed with brutal clarity. QatarEnergy’s declaration of force majeure on LNG exports during the March 2026 Hormuz closure sent Japanese utilities scrambling for alternative suppliers at premium prices. The yen, already depreciating against the dollar amid interest rate differentials, faced additional pressure as import costs surged.

China’s strategic calculus shifted in response. While publicly advocating de-escalation, Beijing accelerated yuan internationalization through energy purchase agreements denominated in renminbi. Saudi Arabia’s 2024 decision to allow yuan-settled oil sales, followed by similar arrangements with Iraq and the UAE, created the infrastructure for a parallel monetary order. The Iran war’s disruption of dollar-denominated energy flows provided practical demonstration of the vulnerabilities inherent to single-currency dependence.

India’s position illustrated the impossible choices facing emerging economies. As the third-largest oil importer, New Delhi faced inflationary pressures that threatened the Modi government’s economic credibility. Yet India’s strategic partnership with the United States constrained options for evading American sanctions on Iranian oil. The result: higher import bills, currency depreciation, and postponed infrastructure spending as fiscal resources diverted to energy subsidies.

The banking sector’s exposure to these stresses remains imperfectly understood. Commercial real estate loans, particularly those financing office properties in urban centers hollowed out by remote work trends, carry default risks that energy price shocks amplify. Regional banks in the United States, having faced depositor flight in the 2023 Silicon Valley Bank collapse, now confront renewed pressure as bond portfolios lose value amid interest rate volatility. The $1.5 to $2.1 trillion private credit market operates with opacity that systemic risk assessments struggle to penetrate.

Corporate debt maturities in 2026-2027 present a refinancing cliff of historic proportions. Companies that borrowed at near-zero rates during the quantitative easing era must now roll obligations at 6-8 percent interest, if markets remain open to them at all. The “zombie firm” phenomenon – enterprises kept operational only through continuous debt refinancing rather than operational profitability – threatens mass insolvency if credit conditions tighten further.

Agricultural markets compound these vulnerabilities. Wheat and corn prices, already elevated by Ukraine conflict disruptions and climate anomalies, face additional pressure from energy-intensive fertilizer production costs. Natural gas, the primary feedstock for nitrogen fertilizer manufacturing, saw European prices spike 300% during the March 2026 Hormuz closure. The transmission to food prices operates with inevitable lag but equal certainty.

Humanitarian consequences extend beyond abstract statistics. Iran’s population of 87 million faces food insecurity as sanctions disrupt import financing and currency collapse destroys purchasing power. The rial’s depreciation against the dollar, exceeding 80% since 2021, has rendered imported medicines unaffordable for ordinary families. Brain drain accelerates as professionals emigrate to Dubai, Istanbul, and European capitals.

Israel’s economy, despite receiving $14.3 billion in American military aid during 2026, faces its own contradictions. The Bank of Israel slashed growth prospects as the war’s toll mounted, with defense spending consuming resources that might otherwise support social services. Military mobilization of reservists disrupted technology sector productivity, while tourism revenues collapsed amid security concerns.

The United States enters the final quarter of 2026 with economic indicators that defy simple categorization. Unemployment remains near historic lows at 4.1%, yet labor force participation among prime-age males continues declining. GDP growth, projected at 1.8% for the year, masks distributional shifts that concentrate gains in asset-owning classes while wage workers confront eroded purchasing power. The Federal Reserve’s preferred inflation metric, core PCE, hovers above target at 3.3%, constraining monetary policy flexibility.

Presidential rhetoric in this environment oscillates between triumphalism and threat. Trump’s August 2026 declaration that Iran “outsmarted themselves” over Hormuz control, accompanied by social media posts depicting the waterway as American territory, suggests a transactional approach to territorial sovereignty that unsettles international law. His simultaneous threats against nations maintaining economic ties to Tehran create compliance dilemmas for allies whose strategic interests diverge from Washington’s.

The configuration of military confrontation, monetary stress, and debt fragility creates conditions for systemic stress that would exceed the 2008 financial crisis in scope. Not through single catastrophic event but through cascading failures that compound across interconnected systems. An oil price spike above $200 per barrel, as Roubini warned, would trigger demand destruction in transport sectors that eliminates millions of jobs. Corporate defaults in energy-intensive industries would cascade through credit default swap markets that remain opaque to regulators. Sovereign debt crises in emerging markets would force IMF interventions that impose austerity conditions, generating political instability that feeds further conflict.

The dollar’s reserve currency status faces its most credible challenge since Bretton Woods. Not because rivals possess superior alternatives – the yuan remains non-convertible, the euro fragmented – but because Washington’s weaponization of financial infrastructure has created irresistible incentives for diversification. Each sanctions round against Iran accelerates this process. Each threat of secondary sanctions against allies hastens the construction of parallel systems.

The optimistic scenario, increasingly dismissed by market participants, envisions negotiated settlement by early 2027, Hormuz reopening, and gradual price normalization. Even this outcome, Georgieva emphasized, leaves “permanent scarring” on growth trajectories. Output levels in 2030 will remain 2% below pre-war trends according to IMF projections. The opportunity cost of military confrontation – the infrastructure unbuilt, the research unfunded, the human potential unrealized – accumulates across decades.

The pessimistic scenario defies precise modeling because its variables interact non-linearly. Oil at $200 per barrel simultaneously triggers recession and accelerates energy transition investments that strand fossil fuel assets. Banking crises in vulnerable jurisdictions propagate through derivatives exposures that regulatory stress tests failed to capture. Political radicalization, fed by economic desperation, produces leadership incapable of crisis management.

Historical analogies offer limited guidance. The 1973 oil shock occurred within a Bretton Woods framework that no longer exists. The 2008 financial crisis, while demonstrating interconnected fragility, benefited from coordinated central bank responses that current geopolitical polarization may preclude.

What distinguishes the present moment is the convergence of multiple stressors upon a system already operating near capacity. Global debt at $365 trillion represents claims that cannot all be satisfied simultaneously. The Iran war’s energy price shock applies pressure to this leveraged structure in ways that individual components – sovereign borrowers, corporate issuers, financial intermediaries – may withstand in isolation but cannot survive collectively.

The Strait of Hormuz, that narrow channel through which one-fifth of global petroleum flows, embodies this vulnerability. Twenty-one million barrels daily transit waters barely twenty-one miles wide at their narrowest point. Iranian missile batteries, mines, and fast attack craft can interdict this flow with minimal warning. American carrier groups can suppress such threats at enormous cost but cannot eliminate them entirely.

Trump’s social media annexation of Hormuz as “New US Territory” in August 2026, however rhetorical, signaled an American willingness to assert direct territorial control over international waterways that precedent has long treated as global commons. Such assertions, if operationalized, would encounter resistance not merely from Iran but from China, Russia, and regional powers whose energy security depends upon unimpeded navigation.

Economic warfare, as practiced against Iran in 2026, operates through mechanisms that escape traditional accounting. The exclusion of Iranian banks from SWIFT messaging does not merely inconvenience; it severs commercial relationships built over decades. The secondary sanctions threatening foreign entities that transact with Iran force impossible choices upon multinational corporations between American market access and Iranian commercial relationships. The cumulative effect is a fragmentation of global commerce into competing blocs that reduces overall efficiency and prosperity.

The BRICS bloc’s expansion in 2024 to include major oil producers Iran, Saudi Arabia, and the UAE created an organizational framework for this monetary diversification. While the proposed common BRICS currency remains technically distant, the infrastructure for reduced dollar dependence develops apace.

For American households, these macroeconomic abstractions translate into concrete hardships. Gasoline prices above $5 per gallon, as experienced in California during March 2026, reduce discretionary spending that drives consumer-dependent growth. Home heating costs surge in northern winters. Food prices, transported by diesel-powered logistics networks, follow energy costs upward. The Federal Reserve’s interest rate restraint, maintained despite these pressures to combat underlying inflation, keeps mortgage rates elevated and housing affordability diminished.

The political economy of these stresses generates feedback loops that complicate resolution. Populist movements, fed by economic grievance, demand more aggressive confrontation with perceived adversaries rather than diplomatic compromise. Interest groups benefiting from military expenditure lobby for sustained confrontation. Media ecosystems amplify threat perception, reducing the political space for negotiation.

Iran’s leadership, despite decapitation and economic devastation, maintains negotiating positions that reflect their assessment of American political constraints. They observe the American electoral cycle, the influence of pro-Israel constituencies, and the transactional nature of Trump’s diplomacy. Their strategy of brinkmanship – escalating to de-escalate – assumes that Washington’s pain threshold, while higher than Tehran’s, remains finite.

The September 2026 ceasefire, brokered through Qatari intermediation, paused direct military confrontation but resolved nothing. Iranian nuclear facilities, though damaged, remain operational at undeclared sites. Israeli security guarantees, demanded as condition for permanent settlement, exceed what Tehran’s fractured leadership can deliver. American troops remain deployed across the region in configurations vulnerable to proxy attack.

Economic forecasts for 2027 diverge based upon assumptions about this unresolved confrontation. The IMF’s reference scenario assumes short-lived conflict with gradual normalization, projecting 3.1% global growth recovery. Its adverse scenario, increasingly probable as negotiations stall, envisions 2.5% growth with 5.4% inflation. The severe scenario – 2.0% growth brushing recession – requires only modest additional escalation: Hormuz closure persisting beyond three months, Iranian missile strikes on Saudi infrastructure, or Israeli expansion of operations into Lebanon and Syria.

Each of these triggers remains plausible. Iranian Revolutionary Guard factions, empowered by Khamenei’s death and competing for succession influence, may calculate that renewed confrontation serves domestic political purposes. Israeli leadership, facing domestic pressure for decisive security solutions, may authorize strikes that previous restraint avoided. American electoral considerations in the approach to 2028 may incentivize foreign policy aggression that rallies domestic support.

The debt dimension compounds these risks. Sovereign borrowers facing recessionary revenue shortfalls and inflationary expenditure increases encounter debt servicing requirements that crowd out productive investment. Corporate issuers with 2027 maturities confront rollover costs that render previously viable enterprises insolvent. Financial intermediaries, holding claims upon these borrowers, face capital constraints that restrict new lending. The resulting credit contraction amplifies recessionary dynamics.

Central banks, having deployed extraordinary measures during the COVID-19 pandemic, possess diminished capacity for repetition. Balance sheets already swollen with asset purchases offer limited room for additional expansion. Interest rates, while above zero, remain below inflation in real terms, constraining traditional monetary policy space. Fiscal authorities, confronting debt burdens that limit countercyclical spending, face political resistance to deficit expansion.

A system that requires 3%+ growth to service $365 trillion debt will struggle to maintain stability at 2% growth without structural adjustment that political processes resist. The Iran war, by reducing growth and increasing inflation simultaneously, forces this adjustment upon unwilling participants. Whether through negotiated settlement that restores energy flows and reduces risk premiums, or through continued confrontation that amplifies systemic stress, adjustment will occur.

The form it takes – gradual normalization or sudden rupture – remains the variable that will define economic experience for the decade ahead. Current trajectory favors rupture: unresolved confrontation, accumulating sanctions, escalating rhetoric, and structural fragility that compound across months rather than years. The optimistic scenario requires not merely ceasefire but durable settlement, not merely sanctions relief but economic reconstruction, not merely diplomatic engagement but fundamental reassessment of regional order.

Such reassessment appears improbable given current leadership configurations. Trump approaches his final term’s conclusion with incentive to cement confrontational legacy rather than compromise. Iranian factions compete for succession advantage through nationalist positioning rather than pragmatic accommodation. Israeli security establishment, validated by apparent military success, resists territorial concessions that might address underlying grievances.

The economic consequences of this political configuration will unfold across quarters and years with accumulating damage. Growth forecasts will revise downward repeatedly. Inflation projections will revise upward. Debt sustainability assessments will deteriorate. Financial market volatility will increase. Each revision, each deterioration, each increase reduces the margin for error that prevents systemic crisis.

The Iran war has demonstrated that geopolitical confrontation can impose economic costs that exceed the combatants’ calculations. Those costs, interacting with pre-existing vulnerabilities in global debt and monetary architecture, create conditions for crisis that policy instruments cannot readily address. Whether this crisis arrives in 2026, 2027, or beyond matters less than its likelihood given current trajectory.

Markets, having priced some risk premium, may remain complacent until rupture occurs. Policymakers, having normalized extraordinary measures, may discover their exhaustion only in crisis. Populations, having accommodated gradual deterioration, may confront sudden deprivation with inadequate social infrastructure. The Iran war’s ultimate economic legacy may prove not the direct costs of military confrontation but the revelation that global economic integration, assumed permanent, rests upon political foundations more fragile than understood.


Tyler Durden
Thu, 10/01/2026 – 20:55

The $40 Billion Minerals Gamble: Can Trump Break China’s Chokehold Before The West’s Rearmament Hits A Wall?

0
The $40 Billion Minerals Gamble: Can Trump Break China’s Chokehold Before The West’s Rearmament Hits A Wall?

The Trump administration has committed billions of dollars to rebuild conflict-free critical materials supply chains outside China. The question remains whether these supply chains will be up and running in time for the West’s rearmament cycle, which desperately needs missiles, bombs, drones, fighter jets, submarines, and even night-vision equipment.

Bloomberg Intelligence analysts published a note today titled “Defense-Critical Mineral Capital Moves Downstream,” analyzing whether more than $40 billion in announced support will translate into reliable near-term supplies and improve defense readiness.

“Execution, not government support alone, will determine if US critical-minerals policy translates into durable revenue and stronger defense readiness,” the analysts wrote.

They continued, “Policy is moving beyond grants toward equity, price floors, loans, offtake and stockpiles designed to preserve capacity through commodity cycles.”

Adding, “MP Materials and ATALCO offer the clearest near-term links to magnets and gallium, while IperionX and Perpetua provide targeted titanium and antimony exposure. Defense-grade output, customer qualification and contracted volume still need to follow announced capacity.”

Beyond the mining aspect of rejiggering critical materials supply chains, refining and downstream production remain critically important, including heavy-rare-earth separation, manufacturing yields, customer qualification, and reliable deliveries.

These high-grade critical materials are essential for missiles, drones, satellites, and undersea platforms. The F-35 alone requires more than 900 pounds of rare-earth materials, the analysts noted.

Breaking China’s “quasi-monopolistic position” in critical materials is unlikely to be a this-decade story. Christian Keller, Barclays’ global head of economics research, recently pointed out that mining and refining of these critical materials will persist through 2030. 

Stifel aerospace and defense analyst Jonathan Siegmann wrote in a note last week that investors want to “own the bottlenecks” in the critical materials space, mainly the producers that can deliver today. 

Siegmann’s most important chart in the report was the near-depletion of US tungsten reserves. 

Adrien Rabier, Bernstein’s equity analyst covering European aerospace and defense, put a timeline on the EU’s defense rearmament supercycle, which is already ramping up and will last through 2030.

Bloomberg Intelligence analysts added that the Trump administration’s Project Vault, intended to rebuild the nation’s critical materials stockpiles, provides another buffer by financing inventories for civilian and dual-use manufacturers can draw down and replenish. It complements the National Defense Stockpile but does not replace its emergency role or guarantee that material will be available in military-qualified form.

The only problem is that new mining projects take years to commission, while refining supply chains also take time to come online, as this shortage of critical materials collides with a rearmament supercycle in the West. As for tungsten, Jefferies, Goldman, and Stifel favor this miner, which is set to become the West’s largest ex-China supplier. 

Tyler Durden
Thu, 10/01/2026 – 20:30

3 Huge Storms Will Combine Over The Central United States To Form A Gigantic “Hybrid Storm” That Will Cause Widespread Flooding

0
3 Huge Storms Will Combine Over The Central United States To Form A Gigantic “Hybrid Storm” That Will Cause Widespread Flooding

Authored by Michael Snyder via End Of The American Dream,

We are about to witness something extremely rare. At the same time that a historic financial storm is brewing on Wall Street as bond yields go wild, a historic weather event threatens to dump trillions of gallons of rain over the middle of the country. Meteorologists are telling us that 3 enormous storms will combine to create an absolutely colossal “hybrid storm” that will cause “considerable” flooding over large stretches of the nation. We have never seen anything quite like this before, and it appears that this disaster will be significantly worse than the experts were originally anticipating.

The remnants of Hurricane Polo are about to merge with the remnants of Hurricane Odalys and an upper level low that will be funneling massive amounts of moisture from the Gulf of Mexico to form “a new, hybrid storm” which will be very dangerous…

A soggy, potentially dangerous week is ahead for a “huge” section of the central United States, forecasters warned, as the remnants of Hurricane Polo interact with a separate, sprawling weather system to bring days of rain and possible flooding.

“As these features combine into a new, hybrid storm, the influx of moisture spreading across the central United States will pose the risk for flash flooding,” AccuWeather meteorologist Alyssa Glenny said.

The National Weather Service explained that tropical moisture from the remnants of Hurricane Odalys and Hurricane Polo will surge over the Southwest into the central U.S. this week with several days of heavy to excessive rainfall, which may bring limited to “considerable” flooding. The threat area is “huge,” the weather service said in an online forecast.

This wasn’t supposed to happen.

But it is happening.

Even if the remnants of Hurricane Polo and Hurricane Odalys were not an issue, the upper level low which is about to move into the center of the nation “would still be a heavy rain and flood threat”…

In addition to the moisture from Polo, the other system, known as an upper-level low, or trough, will be moving into the central U.S. from the West, Marc Chenard, a meteorologist with NOAA’s Weather Prediction Center, told USA TODAY.

That low will help funnel plentiful moisture northward from the Gulf, he said. “This will produce a widespread area of heavy rainfall.”

“Even if we didn’t have Polo,” there would still be a heavy rain and flood threat in the central U.S. this week, Chenard told USA TODAY.

It is very unusual to see three major systems come together like this.

On Tuesday, flood watches were issued in 10 different states, and we are being warned that this is just the beginning…

Flood watches have been issued in ten states Tuesday morning as meteorologists warn that the widespread effects of Hurricane Polo are merging with leftover moisture from Hurricane Odalys and a dip in the natural jet stream running across the US to create one massive storm.

This ‘triple flood’ is expected to bring the heaviest rainfall to Arizona, Colorado, New Mexico, Kansas, Oklahoma and Texas on Tuesday, but the storm threat will continue throughout the entire week.

To say that the worst hit areas will get a lot of rain is a major understatement.

According to Accuweather, there are a few isolated locations that could see up to 18 inches of rainfall…

AccuWeather’s latest forecast has warned that as much as eight inches of rain could flood parts of Colorado, Iowa, Kansas, Missouri, Nebraska, New Mexico, Oklahoma and Texas this week.

However, the weather service’s worst-case scenario noted up to 18 inches of rain could fall in isolated areas.

If you live in an area that is prone to flooding, you may want to brace for the worst.

We are being told that in some parts of New Mexico this could be “the most dangerous flash flooding risk in the last 5 years or more”…

“In some places, especially in New Mexico, this may be the most dangerous flash flooding risk in the last 5 years or more,” AccuWeather Chief Meteorologist Jon Porter said.

Accuweather is normally very conservative in their forecasts, and so I would take this warning very seriously.

Even if you do not live in one of the danger zones, that doesn’t mean that you won’t get rain.

In fact, Accuweather is projecting that 30 U.S. states will receive at least one inch of rain this week…

There are many parts of the nation that could desperately use some rain.

But we didn’t want to get it all at once.

Hopefully the flooding will not be quite as bad as they are currently forecasting.

There is one other thing that I wanted to mention in this article.

An extremely vast “Kelvin wave” will soon bring “an untold amount of warm water” to the west coast…

Concerns are mounting about an ocean phenomenon known as a Kelvin wave that could raise sea levels along the California coastline by up to a foot, as scientists say El Niño is supercharging the threat of storm surges and flooding in the coming months.

As an incredibly strong El Niño continues to develop in the Pacific, the phenomenon brings with it a strange shift in the ocean. The Kelvin wave phenomenon is created when trade winds that usually blow from South America towards Asia die down or reverse in El Niño years, setting off a massive, slow-moving slosh of water.

Kelvin waves are not like crashing waves at the beach. They are planetary in scale, spanning thousands of miles. And when a Kelvin wave kicks off, it brings with it an untold amount of warm water that slowly moves from the western Pacific, along the equator, towards South, Central and North America.

This “Kelvin wave” hit South America late last month, and now it is traveling north toward California…

“You can follow them along … we see the higher sea levels along the equator, and when the wave reaches the coast of South America, it cannot continue to go eastward,” Severine Fournier, a research scientist studying ocean circulation at Nasa’s Jet Propulsion Laboratory, said. “So it goes north and south.”

One such wave hit the northern tip of South America in late August and has begun moving up towards the west coast of the US. That wave could reach California shores within days, and when it does, ocean scientists say it may raise sea levels by up to a foot for months as El Niño lingers and keeps that warm water trapped along the coast.

Ocean levels along the west coast will rise significantly.

But that is only temporary.

Of much greater importance is what all of this warm water will mean for storms that approach the California coastline.

Normally, very cool water along the California coastline causes tropical storms and hurricanes to fizzle out as they approach.

But now conditions will be ideal for a tropical storm or a hurricane to come slamming right into the state.

The Super El Niño that is causing this to occur will be sticking around for quite a while, and so this is a story that is not going to go away any time soon.

Tyler Durden
Thu, 10/01/2026 – 20:05

Trump Sees Likely Iran Link In FlyDubai Attack, Vows ‘Very Hard’ Response

0
Trump Sees Likely Iran Link In FlyDubai Attack, Vows ‘Very Hard’ Response

It hasn’t taken long at all for Israeli and US officials to strongly suggest a link between Wednesday’s scary FlyDubai security incident and Iran.

President Trump raised Thursday that Iran may be linked to the copilot who tried to crash an Israel-bound plane, which forced it to make a dangerous rapid descent and an emergency landing, after passengers and crew rushed the cockpit.

But while investigators have yet to disclose a motive in what Israel called a full-fledged terror attack, which also left the flight’s captain with a stab wound, Trump laid out the following on Thursday:

Fox’s Peter Doocy: “Has anybody briefed you about whether or not the guy, the pilot of the flight in FlyDubai plane is linked to Iran?“

President Trump: “We’re working on it right now. They’re being very open with us. I would say the answer based on what I’m hearing is yes, but we’re working on it right now.”

Doocy: “So this guy might have been either put in there by the IRGC or ratified some other way, and then he tried to take down the plane.”

Trump: “It could have been, yeah.”

So we’ve gone from no motive yet being publicly offered to assertions that the IRGC may have clandestinely inserted the pilot onto the flight with an aim to conduct some kind of 9/11-style terror attack against Israel and the over 170 passengers who were inbound from Dubai.

Trump was further asked whether – if it is established that Iran was behind it – he would retaliate, to which he responded: “Oh they’ll be hit, very hard, don’t worry.”

“You just ask them,” he added. “They know what happened. They’ll be hit very hard.”

Netanyahu too has been quick to suspect Iran – though without saying if this is based on any evidence, though this is perhaps to be expected considering his history of such linkages.

“I spoke to the president of the United Arab Emirates, Sheikh Mohammed bin Zayed, and he agreed that Israel would join the investigation and we’ll find out,” Netanyahu told CNN..

“Look, we know that Iran is sponsoring a lot of this, but I can’t speak specifically of this. I can say that they did stand behind the attack in Britain. We passed that information to the Brits.”

He still acknowledge that ultimately it’s too early to tell, while confirming that co-pilot accused of stabbing the captain and trying to bring down the plane is currently in the custody Saudi Arabia (where the plane diverted upon the emergency) and is expected to be sent to the UAE.

The timing of the horrible episode couldn’t be worse (or also some pundits might also say the timing is curious), set against the background of the Iran conflict. Trump is said to be mulling resuming a major bombing campaign against the Islamic Republic by end of November, after the midterm elections in the US. The terror incident will likely exacerbate US-Iran tensions, and seems to already be doing so.

Tyler Durden
Thu, 10/01/2026 – 19:40

Why Congress Should Restore The Monetary Veto

0
Why Congress Should Restore The Monetary Veto

Authored by Sean Fieler via RealClearMarkets,

American democracy prides itself on being “of the people, by the people, and for the people.” But the people lack control over a key part of their daily lives: the money supply.

Its expansion and contraction affect the value of every paycheck, every dollar of savings, and the price of virtually everything that can be purchased. Americans once had the ability to redeem their dollars for gold at a fixed rate. Congress should restore that power. Doing so would give every American a direct check on monetary expansion and force Washington to reckon with the consequences of fiscal excess.

The idea is actually simpler than it sounds. If Americans believed Washington was undermining the value of their money, they could exchange dollars for a legally fixed quantity of gold. As those redemptions drew down the nation’s gold reserves, monetary authorities would face pressure to contract rather than continue expanding the money supply. In effect, every dollar holder would possess a monetary veto.

For 55 years, America has relied upon a small group of experts to manage our money supply without the external discipline imposed by gold convertibility. The impact on fiscal policy has been disastrous and stands in stark contrast to much of the historical record before 1971. For much of the 182 years after the first federal budget in 1789, the nation treated balanced budgets – and, during prosperous peacetime years, surpluses – as the fiscal norm. Even accounting for spending spikes during crises like the Civil War, America’s average budget deficit remained modest. Our democracy survived existential threats with reasonable fiscal discipline.

The developed world remained fiscally disciplined even after the enormous strain of WWII, crawling out from under mammoth wartime debts within a few decades. By 1971, the 23 countries in the OECD had an average debt-to-GDP ratio of just 35%. This discipline was encouraged in part by the design of Bretton Woods, which created a self-correcting feedback loop. The system of fixed exchange rates subjected countries, including America, to external discipline. Foreign monetary authorities could redeem dollars for gold if they lost confidence in American monetary policy. France famously exercised that power in the 1960s after Charles de Gaulle rebuked the U.S. for glutting the globe with dollars. The French government redeemed hundreds of millions of dollars of its foreign exchange reserves for gold, drawing down America’s stock.

Yet foreign governments were not the first to possess such power. A century ago, ordinary Americans could redeem dollars for gold at $20.67 per ounce. Prior to 1933, the Federal Reserve was required to maintain gold reserves equal to at least 40% of the value of the currency it issued. Gold redemption therefore placed direct pressure on the monetary system and constrained its expansion. Washington, in other words, could not expand money without facing potential consequences from the people holding it. Americans did not need to understand the arcane financial terminology that bedevils monetary policy today. They could simply convert their dollars into gold.

That right disappeared in 1933 under President Franklin Roosevelt and was solidified into law the following year. Foreign monetary authorities could still redeem dollars at the new rate of $35 per ounce under the postwar monetary system. That lasted until 1971, when President Richard Nixon ended dollar-gold convertibility, beginning the collapse of Bretton Woods. The end of gold convertibility did not by itself cause the modern era of chronic deficits. But it removed one external constraint governments faced when financing them. The OECD countries’ debt-to-GDP ratio has risen dramatically since the end of Bretton Woods.

Congress should use its authority clearly granted in Article 1, Section 8 of the Constitution to establish a statutory right of dollar-gold redemption and determine the conversion rate, appropriate gold backing, eligibility for redemption and responsibilities of the Treasury and Federal Reserve. Those are difficult questions of design, but they are precisely the questions Congress should begin examining.

Congress could start with hearings on convertibility and require the Treasury and Federal Reserve to report on possible redemption mechanisms, reserve requirements, conversion rates and transition periods. The objective would be to give millions of Americans an exit right. If citizens lose confidence in the stewardship of their currency, they could exchange it for an asset Washington cannot create at will.

Such a system would carry real costs. Gold redemption could contract the money supply and leave the Federal Reserve with little freedom to respond during financial crises. Indeed, the constraint of gold redemptions can certainly intensify economic contractions. But the alternative of monetary discretion carries the greater cost: fiscal profligacy and ultimately insolvency. Americans should not be expected to entrust something as fundamental as the value of their money exclusively to a small circle of experts. They deserve a direct check – and Congress should give it back to them.

Sean Fieler is Chief Investment Officer of Equinox Partners.

Tyler Durden
Thu, 10/01/2026 – 19:15

Bridgewater CEO Warns Unregulated AI Could Trigger ‘Societal Breakdown’ – Even As The Firm Profits From It

0
Bridgewater CEO Warns Unregulated AI Could Trigger ‘Societal Breakdown’ – Even As The Firm Profits From It

Artificial intelligence could displace nearly one-fifth of the US labor market, threatening profound societal disruption if left unregulated, according to Bridgewater Associates CEO Nir Bar Dea. Speaking on an upcoming episode of The David Rubenstein Show: Peer-to-Peer Conversations, Bar Dea projected an 18% labor dislocation rate, noting that a technology capable of radically improving the world carries equally severe downside risks.

Nir Bar Dea Photographer: Zak Bennett/Bloomberg

The stark warning aligns Bar Dea with other prominent financial executives sounding the alarm on rapid technological upheaval. Bridgewater Managing Co-Chief Investment Officer Greg Jensen – an early backer of OpenAI and Anthropic – has likened the current public underestimation of AI to the early, dismissive days of the Covid-19 pandemic. Similarly, billionaire investor Paul Tudor Jones recently characterized the looming AI transition as “waiting for a Category 6 hurricane.”

Despite these existential concerns, the $100 billion macroeconomic hedge fund remains deeply committed to integrating machine learning into its core operations. In 2024, Bridgewater raised nearly $2 billion for a dedicated AI-driven fund where technology generates market insights and human analysts manage the risk. Since its launch, the fund has beaten the market while producing distinct investment theses that diverge from the firm’s traditional human traders.

“That just blows your mind thinking what the future holds,” Bar Dea said, though he cautioned that achieving an institutional edge requires more than off-the-shelf software. Profitable integration, he argued, relies heavily on proprietary training and unique data sets to combine human intuition with technological processing.

Bar Dea, a former major in the Israel Defense Forces, has transformed the 51-year-old firm since taking over as sole CEO from founder Ray Dalio in 2023 – paring down in size. Both of its flagship funds are currently closed to new investors.

Bar Dea’s is the third such warning from a hedge-fund heavyweight in three weeks. Jones, whose Skynet-style alarm we covered last year, took to the Wall Street Journal on Sept. 10 to argue AI is becoming a “third superpower” that Trump and Xi must jointly contain. Jensen followed a day later, telling Bloomberg that AI will probably have to kill people before regulators move.

Every one of these warnings comes from a firm that is long the trade. Bridgewater’s machine-learning fund is beating its human traders; Jensen holds early stakes in two of the labs; Tudor’s flagship is not short Nvidia. Which is roughly where this audience landed when the AI labs themselves started asking for regulation earlier this month: the people best positioned to profit from AI are also the ones most insistent that somebody else slow it down.

Tyler Durden
Thu, 10/01/2026 – 18:50