63.3 F
Chicago
Friday, October 2, 2026
Home Blog Page 2321

“Atlantic Tropics Are Completely Broken” 

0
“Atlantic Tropics Are Completely Broken” 

The Gulf of Mexico and the Caribbean Sea are hot, yet hurricane season has entered a lull just days before its peak. Earlier this year, climate alarmists warned about elevated tropical activity due to ‘climate change,’ but their forecast has proven incorrect. 

Meteorologist Ryan Maue has offered his take on why tropical development activity remains depressed: 

The Atlantic tropics are completely broken, unable to produce tropical storms even w/off the charts “climate fueled” oceans. Our models no longer work, forecasters can’t figure it out. This is not normal.

Maue said: 

While Saharan dust clouds have contributed to dry and stable air just above the surface, the circulation from the Northeast Atlantic over the cold Canary Current has penetrated even more dry air deep into the tropics. We haven’t seen this in 50 years.

The meteorologist pointed to the massive 2022 eruption of the underwater volcano in Tonga, known as Hunga Tonga-Hunga Ha’apai, that catapulted plumes of soot, water vapor, and sulfur dioxide into the stratosphere, leading to what some are saying is the driving force behind the Earth’s most recent warming trends…

What can cause all of this? The massive submarine Hunga Tonga volcano in 2022 is the obvious culprit for tampering with the Hadley Cell and ITCZ. But it could also be some entirely new pattern we haven’t seen caused by a combination of solar activity and unprecedented warming.

He continued:

Reminder the lack of hurricanes is not entirely inconsistent with climate change predictions. We will see fewer hurricanes, but the ones that do develop will be climate fueled and reach Category 6+ Right now, the oceans up to the lower stratosphere are overheating — too hot.

Maue concluded: 

I think it’s all the 🌋 + ☀️ and weird effects of pandemic shutting down industry + pollution. The Earth 🌎 absorbed way too much shortwave radiation!

Separately, John Shewchuk, a certified consulting meteorologist, wrote on X:

“This is expected because of the unprecedented Tonga volcano which is causing an unprecedented global warming spike which is now showing up in the models as unprecedented failures — because the models are tuned to only known air/ocean dynamics. Tonga is causing unknown effects.”

Recall our weather note in mid-July titled “Tonga Volcano Contributed To Global Warming, Not Cow Farts Or Taylor Swift’s Private Jet.”

In 2023, we asked: “Is Tonga’s Volcano Eruption Set To Warm Earth?“

Why do leftist corporate media outlets refuse to even acknowledge the Tonga volcano as a possible driver in the recent tick-up in global warming?  It’s probably because it doesn’t align with the narrative that human-produced carbon dioxide drives climate change.

Tyler Durden
Tue, 09/03/2024 – 09:00

Shares Of US Steel Melt After Kamala Harris Opposes Nippon’s $15BN Buyout Deal 

0
Shares Of US Steel Melt After Kamala Harris Opposes Nippon’s $15BN Buyout Deal 

US Vice President and Democratic presidential candidate Kamala Harris visited Pittsburgh for the Labor Day holiday with President Biden. There, she declared that United States Steel should remain domestically owned and operated, yet another high-profile critic of US Steel’s proposed sale to Japan’s Nippon Steel. 

“US Steel is a historic American company, and it is vital for our nation to maintain strong American steel companies,” Harris told the audience at Union Hall in Pittsburgh, where US Steel is headquartered. 

She said, “I couldn’t agree more with President Biden — US Steel should remain American-owned, and American-operated. And I will always have the backs of America’s steelworkers.”

Harris commented on the Nippon Steel deal while visiting Pennsylvania on Monday. The state has become a critical battleground area as she is attempting to shore up support for blue-collar workers ahead of the November election. 

“I will continue to count on the strength, the determination, and the hard work of the leaders in this room to knock on doors, to get folks to the polls and, bluntly put … to help us win Pennsylvania,” Harris told the crowd. 

Harris has revealed she is essentially a mirror image of Biden – not shocking whatsoever – and will follow the president’s pro-union footsteps. Her campaign’s block of Nippon Steel’s US Steel bid is identical to Biden’s. 

Nippon’s planned $15 billion acquisition of US Steel has faced bipartisan political backlash since the deal was announced in late 2023. The Japanese company has conducted a bold lobbying campaign in recent months to ensure the deal goes through amid concerns about a faltering steel industry in the US. 

Despite the critics, Nippon executives remain “confident” that its “acquisition of US Steel will revitalize the American steel rustbelt, benefit American workers, local communities and national security in a way no other alternative can.”

Meanwhile, Republican nominee and former President Donald Trump has also vowed to block the transaction. This is yet another policy that Harris closely aligns with Trump on.

In markets, shares of US Steel in New York were 6% lower in premarket trading around the mid-point of the $35 handle. 

If US Steel’s headquarters weren’t based in a critical swing state and didn’t have large production facilities in the Pittsburgh area, Harris would likely have little to no interest in this. 
 

Tyler Durden
Tue, 09/03/2024 – 08:35

Futures Slide As US Returns From Holiday And Data Deluge Looms

0
Futures Slide As US Returns From Holiday And Data Deluge Looms

US equity futures are trading near session lows, tracking Monday’s slide in global markets which sent Chinese stocks to 7 month lows, after US markets were closed for Labor day yesterday. As of 8:00am, S&P futures are lower by 0.5% trading around 5630 and unchanged since mid-August even as they nearly hit a new all time high on Friday, while Nasdaq futs lag, down 0.6% with both Mag7 and Semis are under pressure (NVDA -2.4%). Bond yields are ~2bps higher with the USD trading near session highs. Commodities are weaker with all 3 complexes coming for sale; gold and natgas are relative bright spots. Today’s macro data focus is on ISM-Mfg and construction spending as we have a heavy data week capped with Friday’s NFP which is likely the determinant for the Fed cutting 25bps or 50bps. Friday also has the last 2 Fedspeakers before the Fed’s blackout window.

In premarket trading, Nvidia fell more than 2% in premarket trading as most members of the Magnificent Seven technology stocks lost ground. Boeing dropped 3% after Wells Fargo downgraded the stock to underweight, giving the planemaker a rare negative analyst rating. Wells Fargo also cut its price target to a Street low. Here are the other notable premarket movers:

  • Dyne Therapeutics (DYN) tumbles 32% after saying Chief Medical Officer Wildon Farwell is stepping down from the role; the company also announced clinical data from the Phase 1/2 trial of DYNE-251 in Duchenne muscular dystrophy
  • Polestar (PSNY) rises 4% after appointing Jean-Francois Mady as CFO.
  • United States Steel (X) falls 5% after Vice President Kamala Harris joined President Joe Biden in declaring the company should remain domestically owned and operated.
  • Unity Software (U) climbs 5% as Morgan Stanley turned bullish on the stock, saying there’s a clear potential for upward revisions in the video-game tool maker’s Create business.
  • Vaxcyte (PCVX) soars 30% after posting positive topline data from a Phase 1/2 study of VAX-31; based on the strength of the results from the study, the company has selected VAX-31 to advance to an adult Phase 3 program.

The month of September – known for being historically brutal for stocks, bonds and gold – has begun in a more benign fashion, with global equities hovering near all-time highs, although selling pressure has emerged out of the gate.

In what is historically a poor month for virtually all assets, traders are bracing for fresh bouts of volatility in the runup to the anticipated start of the Fed’s rate-easing cycle this month. Swap traders are currently pricing a roughly one-in-five chance of a 50 basis-point opening cut, a decision which will be cemented by Friday’s jobs report.

The publication of US manufacturing data later Tuesday will mark the start of a busy week of economic reports (previewed here), culminating with the nonfarm payrolls report on Friday. A similar series of releases in August induced fears that the US economy was heading for a hard landing, whiplashing markets.

“Markets need to be careful what they wish for to some extent,” Daniel Murray, deputy chief investment officer and global head of research at EFG Asset Management, said in an interview on Bloomberg Television. “If rates decline by a lot, and very quickly, then that would typically signify a very weak macro environment, and that usually isn’t very good for equity markets.”

European stocks fell, tracking declines in commodities as global growth concerns sap investor sentiment. The Stoxx 600 is down 0.3%, led by losses in mining and energy names.

Earlier in the session, Asian equities traded in a narrow range following their biggest drop in nearly a month on Monday, as consumer and financial shares rose while the region’s major semiconductor-related stocks fell. The MSCI Asia Pacific Index was little changed, with Mitsubishi UFJ and Sumitomo Mitsui Financial Group among the biggest boosts while TSMC and Samsung declined. Japan’s Topix rose for a sixth straight session, its longest streak since March, boosted by banks. Volumes were thin, outside of China, with a lack of clues from overseas as US markets were closed Monday for a holiday. Chinese stocks swung between gains and losses. Equities in Asia’s largest economy have fluctuated this year amid persistent concerns over slowing growth and a weak property market, while some investors have touted their cheap valuations.

“I think currently bad news is reflected in stocks — the problem is the timing of when the recovery is going to take place,” Lorraine Tan, director of Asia equity research at Morningstar, said on Bloomberg TV. “The good news” is that consumption is not falling off a cliff, with people in lower-tier cities upgrading to more premium products, she said.

In FX, the dollar rose for a fifth day, its longest winning streak since mid-April. The Japanese yen rebounded from Monday’s fall, rising 0.7% against the greenback and to the top of the G-10 FX pile after Bank of Japan Governor Ueda reiterated the central bank will continue to raise interest rates if the economy and prices perform as expected. The Australian dollar is the weakest with a 0.7% drop.

In rates, treasury yields were little changed vs Friday’s closing levels as US markets reopen after Labor Day holiday. Front-end lags slightly, flattening 2s10s curve, amid weakness in Japan’s front-end rates (and yen gains) after Bank of Japan Governor Kazuo Ueda reiterated the central bank will continue to raise interest rates if the economy and prices perform as expected. US 10-year yields trade around 3.91% with bunds and gilts outperforming by ~2bp on the day. US 2s10s, 5s30s spreads flatter by 0.8bp and 1.5bp as front-end and belly slightly lags rest of the curve. European bonds gain. The US session includes S&P Global and ISM manufacturing PMIs, and the investment-grade corporate bond issuance slate is expected to be heavy.

In commodities, Brent crude futures drop 1.5% to $76.40 while iron ore falls over 3% in Singapore. Goldman slashed its copper forecast for next year by almost $5,000 a ton, saying China’s increasingly disappointing economic recovery will delay an expected rebound. The same pessimism over China is also hurting iron ore, which dropped to a two-week low Tuesday after losing its hold above $100 a ton.

The US event calendar includes August S&P Global US manufacturing PMI (9:45am), July construction spending and August ISM manufacturing (10am). No Fed speakers are scheduled; Williams and Waller are slated to speak Friday

Market Snapshot

  • S&P 500 futures down 0.2% to 5,651.50
  • STOXX Europe 600 down 0.1% to 524.29
  • MXAP up 0.1% to 185.89
  • MXAPJ down 0.5% to 572.97
  • Nikkei little changed at 38,686.31
  • Topix up 0.6% to 2,733.27
  • Hang Seng Index down 0.2% to 17,651.49
  • Shanghai Composite down 0.3% to 2,802.98
  • Sensex little changed at 82,505.78
  • Australia S&P/ASX 200 little changed at 8,103.23
  • Kospi down 0.6% to 2,664.63
  • German 10Y yield down 2 bps at 2.32%
  • Euro down 0.2% to $1.1052
  • Brent Futures down 0.9% to $76.84/bbl
  • Gold spot up 0.2% to $2,505.21
  • US Dollar Index little changed at 101.70

Top Overnight News

  • Chinese steel exports set to hit an 8-year high this year as slowing domestic growth forces companies to seek out foreign markets, a dynamic that will escalate trade tensions between Beijing and other countries. China also opened a trade investigation into imports of certain Canadian agricultural and chemical products, a move that follows Canada’s decision to impose tariffs on Chinese autos, steel, and aluminum imports. FT / WSJ
  • Turkey has formally asked to join the BRICs group of emerging market countries as Erdogan feels the “center of gravity” is shifting away from developed economies. BBG
  • Israel sees massive worker strike as the country looks to pressure Netanyahu into striking a ceasefire deal. FT
  • Poland says it has a duty to shoot down Russian missiles flying over Ukraine that could be a potential threat to Polish airspace. FT
  • Germany’s far-right AfD has won a regional election in the country (the first time a far-right party has secured victory in Germany’s postwar history) in another sign of sinking support for the current Scholz government. FT
  • Harris plans to spend a massive ~$370M on advertising between now and the election, including the biggest digital ad campaign in history. FT
  • Growing number of Americans think the country and economy are headed in the right direction (the upward shift comes largely from Democrats, who are feeling more optimistic since Harris entered the race). WSJ
  • Washington prepared to make a “take it or leave it” Gaza ceasefire proposal to Israel and Hamas and is prepared to exit the negotiations if a deal isn’t struck. WaPo
  • Apartment rents are set to face upside risk thanks to a sharp slump in new unit construction over the last several quarters. WSJ
  • Intel and Japan will establish a research and development hub for advanced semiconductor manufacturing equipment in Japan: Nikkei.
  • Japanese firms will not be supplying Apple iPhone displays as the Co. is ending LCD usage excluding Japan Display (6740 JT) and Sharp (6753 JT) from the iPhone supply chain: Nikkei

A more detailed look at global markets courtesy of Newsquawk

APAC stocks eventually faltered and traded in the red across the board, albeit with losses somewhat limited amid cautious trade ahead of the US return and accompanying risk events, such as ISM Manufacturing today and NFP on Friday. ASX 200 saw mild pressure from its Consumer Staples and Mining stocks, but losses are cushioned by Tech, Telecoms, and Energy. Nikkei 225 was initially firmer amid the weaker JPY with the upside is led by the Industrial sector, however, gains later trimmed as the JPY gained ground. Hang Seng and Shanghai Comp were subdued and in-fitting with a broader risk tone with pressure in Real Estate continuing to be a grey cloud over the nation, whilst PBoC liquidity injections get more and more tepid.

Top Asian News

  • South Korean Vice Finance Minister said inflation is expected to stabilize in the lower 2% range going forward, according to Reuters.
  • BoK sees inflation maintaining the current stable trend for the time being, according to Reuters.
  • Japan says it will spend about JPY 989bln from the reserve fund to cover energy subsidies, according to Reuters
  • PBoC injected CNY 1.2bln via 7-day Reverse Repo at a maintained rate of 1.70%
  • Japanese Chief Cabinet Secretary Hayashi wishes to declare the end of inflation as soon as is possible, adds that they should not hesitate to deploy fiscal spending if required to bolster the economy.
  • BoJ’s Ueda submitted documents to a government panel explaining the recent policy announcement, via Bloomberg; article writes the document suggests the central bank will continue to hike if the economy/prices perform as expected.

European bourses, Stoxx 600 (-0.1%) are mixed, having opened with a generally positive bias. Indices initially traded sideways, but have slowly deteriorated as the morning progressed, currently near session lows. European sectors are mixed. Consumer Product & Services top the pile, whilst Basic Resources is the clear laggard, hampered by losses in metals prices. US Equity Futures (ES -0.4%, NQ -0.6%, RTY -0.8%) are lower across the board, as US participants return from US Labour Day holiday. The docket for today includes US PMIs (Finals) and more importantly the ISM Manufacturing data.

Top European News

  • ECB decisions look get more contentious once interest rates fall to about 3%, according to Bloomberg sources.
  • Oil Swings as Traders Weigh China Demand Against Libya Outage
  • Swiss Inflation Slows as SNB Prepares September Rate Cut
  • BBVA’s Sabadell Takeover Bid Gets Approval from UK Regulator
  • EU’s Merger Powers Take Hit in Illumina-Grail Court Defeat

FX

  • DXY was flat for most of the European morning, but has edged higher in recent trade. Currently in a 101.62-83 range. The key inflection point will be on US ISM Manufacturing data, with a particular focus on the employment components, ahead of the NFP report on Friday.
  • EUR is softer and trading towards the lower end of a 1.1035-72 range, and dipping below its 20 DMA. European docket is thin, with only ECB’s Nagel scheduled.
  • GBP is on the backfoot, in what has been yet another session free from any UK-specific catalysts. Cable currently sits in a 1.3108-85 range, a trough which marks the lowest in 7 days. BoE’s Breeden is due to speak today at 13:45BST.
  • The JPY is by far the best performer among G10 peers, with USD/JPY slipping below 146.00. Pressure in the pair could be attributed to Bloomberg reports which stated that BoJ’s Ueda submitted documents to the gov’t, which noted that the BoJ would continue to hike if the economy/prices perform as expected.
  • Antipodeans are amongst the worst performers across the G10s, given the subdued risk tone in APAC trade which led a sharp sell-off in metals prices.
  • CHF began the European session on the front-foot, largely attributed to its safe-haven status; however, it saw modest weakness on the back of a slightly softer inflation report.
  • PBoC set USD/CNY mid-point at 7.1112 vs exp. 7.1120 (prev. 7.1127)

Fixed Income

  • USTs are flat as we await the return of US participants from Monday’s holiday, but as focus remains on US ISM Manufacturing data later. No real follow-through from JGB pressure overnight after a relatively subdued short-dated tap. In a narrow sub-10 tick range which is at the mid-point of Monday’s 113-14 to 113-30+ band.
  • Bunds are essentially unchanged in a much narrower c. 20 tick range vs. the 40+ tick range seen on Monday in the wake of weekend political developments. Bunds are in a 133.27-133.48 band which is entirely within Monday’s 133.16-133.62 range.
  • Gilts are trading similar to the above, with the benchmark also within a slim 15-tick range which has just eclipsed yesterday’s peak to a 98.39 high.
  • Japan sold JPY 2.6tln 10-year JGB; b/c 3.17x (prev. 2.98x), average yield 0.915% (prev. 0.926%).
  • Books close on sale of a 2040 Gilt via syndication, orders topped GBP 107bln, via Reuters citing bookrunner

Commodities

  • Crude benchmarks are both significantly lower, but with differing performances given the lack of settlement in WTI, attributed to the the US Labour Day holiday. Nothing specific driving the pressure in the complex, but comes alongside incremental strength in the Dollar index. Brent’Nov as low as USD 76.05/bbl.
  • Spot gold is slightly firmer and has climbed back above USD 2.5k/oz after losing that figure on Monday. Strength which comes as the general risk tone remains tepid and as focus turns to US ISM Manufacturing later. Currently trading in a USD 2490-2506/oz range.
  • Base metals are pressured, with 3M LME Copper extending further below the USD 9.2k mark and now beginning to approach USD 9k.
  • Libya’s NOC declared force majeure on the El Feel oil field from 2nd September, according to Reuters.
  • UN hosts talks in Tripoli aimed at resolving Libya’s central bank crisis, key understandings reached, according to a statement cited by Reuters.
  • Goldman Sachs has cut its 2024 copper forecast to USD 10,100/ton (prev. saw 12,000/ton), due to China’s weak economic recovery. It also reduced its 2025 aluminium price estimate to USD 2,540, and remains bearish on iron ore and nickel, Bloomberg reports. The bank favours gold as a hedge, and maintained its USD 2,700 price target.

Geopolitics

  • “Israel Today: The security establishment is considering declaring the West Bank a zone of military security operations”, according to Sky News Arabia.
  • On the Israel-Hamas talks, “Sources: The US administration is not particularly optimistic about the chances of success of the new outline, even in light of the declarations made by both sides”, according to Kann News
  • US President Biden said they are still in the middle of ceasefire and hostage-deal negotiations, according to Reuters.
  • Two oil tankers, one Saudi-flagged and the other Panama-flagged, were attacked on Monday in the Red Sea off Yemen, according to Reuters sources.
  • China Commerce Ministry, in response to Canada’s tariffs on Chinese products, said China to initiate an anti-dumping investigation into canola imports from Canada, according to Reuters.

US event calendar

  • 09:45: Aug. S&P Global US Manufacturing PM, est. 48.1, prior 48.0
  • 10:00: Aug. ISM Employment, prior 43.4
  • 10:00: July Construction Spending MoM, est. 0.1%, prior -0.3%
  • 10:00: Aug. ISM New Orders, prior 47.4
  • 10:00: Aug. ISM Prices Paid, est. 52.0, prior 52.9
  • 10:00: Aug. ISM Manufacturing, est. 47.5, prior 46.8

DB’s Jim Reid concludes the overnight wrap

I’m back from the annual ritual of constantly shouting at kids for two weeks that mascarades as a holiday. Since I was last here I’ve also spent 8 hours in an online queue trying to get Oasis reunion tickets only to reach the end of it to find they’d just sold out. I’m not sure there’s been anything like it in history. So if you’ve ordered some and have two spare please let me know! If you bought them and aren’t too sure if you want to go and want to hand them over, all I can say is that the first of the two record breaking Oasis Knebworth gigs in 1996 was the worst gig I’ve ever been to. I was two-thirds of the way back in a huge field listening to the concert from the front speakers and also from the speakers half way down the field that had a delay. So the sound was terrible.

As my chances of getting tickets are sliding away, so is the memory of an incredibly strange start to August with markets completely becalmed again. But now we’ve hit September it’s back to the serious stuff with the market soon to be fully staffed again with schools fully back over the next few days. Ahead of an important payrolls print on Friday, today we see the US ISM and PMI manufacturing prints which will be interesting as both are expected to stay below 50 where they’ve been for most of the last couple of years. The headline ISM printed at 46.8 last month which was below every economists’ estimate, with the employment subcomponent (43.4) at its lowest since the initial Covid shock. This helped kick start the chain of events that culminated in the VIX printing above 65 and Japanese equity markets being down over -10% on the Monday the following week just after the weak payrolls number. So it is important to see if that ISM release was distorted or not.

The week has started quietly due to the Labor Day holiday in the US yesterday but European equities and bonds lost ground. By the close, yields on 10yr bunds (+3.7bps) were up to a one-month high, and the STOXX 600 (-0.02%) had posted a very modest decline from its record high on Friday.

One factor behind the bond selloff was actually some better-than-expected economic data from Europe, which led investors to dial back their expectations for aggressive rate cuts from the ECB. In particular, we had the final manufacturing PMIs for August, and in general there were upward revisions from the flash prints a week-and-a-half ago. In the Euro Area, the final print was at 45.8 (vs. flash at 45.6), Germany went up to 42.4 (vs. flash 42.1), and France saw a very large upward revision to 43.9 (vs. flash 42.1). So positive news relative to expectations, and by the close investors were pricing in 61bps of ECB rate cuts by the December meeting, down -1.8bps relative to the previous day.

With investors expecting slightly less dovish policy, that hurt bonds across the continent, with yields on 10yr bunds (+3.7bps), OATs (+1.5ps) and gilts (+3.7bps) all moving higher. Equities hovered either side of unchanged, with losses for the UK’s FTSE 100 (-0.15%) and Italy’s FTSE MIB (-0.15%), alongside gains for the DAX (+0.13%) and the CAC 40 (+0.20%).

Given the Labor Day holiday, US markets themselves were closed yesterday, but we did get a bit of a clue on their performance from futures. For bonds, they were consistently negative across the curve, and investors lowered the chance of a 50bp cut from 32% on Friday to 30.8% by the European close. This morning US futures are edging lower with those on the S&P 500 (-0.16%) and NASDAQ 100 (-0.34%) trading in the red. US Treasuries have recovered a little this morning versus futures yesterday and are now only around a basis point higher than Friday’s close.

Traditionally, the Labor Day holiday has been seen as the start of the home stretch towards the US election, which is taking place 9 weeks from today. Current polls and forecast models are pointing to a very tight race, with FiveThirtyEight’s projection currently giving a 57% chance of victory to Kamala Harris, and 43% to Donald Trump. The polls are similarly tight, with ReaclClearPolitics’ polling average currently giving Harris a lead of just +1.8pts, so inside the margin of error of most polls.

Given the pretty divergent proposals from the two candidates, this election is going to be one of the biggest issues for markets over the next two months. And this morning, our European economics team has put out a note (link here) looking at the economic impact of a second Trump presidency – particularly in relation to any future trade wars. They run through several trade scenarios that could be in play and how that would impact the EU and UK picture for growth and inflation. They also look at some of the policy implications that could be in consideration on both the fiscal and monetary side.

Staying on politics, one of the main developments at the weekend was the German state elections, where the far-right AfD came in first place in Thuringia, marking the first time that they’d won a state election. However, as our economists write in their post-election piece (link here), the AfD are very unlikely to enter either government, as all the other parties are expected to stick to their pledges not to enter into coalition with them. They also don’t see the results at the state level triggering early federal elections either, and their base case remains that the next federal election will be in September 2025.

Asian equity markets are trading in a narrow range amid a lack of any new catalysts after the holiday on Wall Street. As I check my screens, the Hang Seng (-0.34%), the Nikkei (-0.25%) and the KOSPI (-0.10%) are all dipping. Elsewhere, mainland Chinese stocks are mixed with the CSI (+0.07%) trading just above flat while the Shanghai Composite (-0.52%) is trading in the red.
Early morning data showed that South Korea’s inflation hit a 42-month low of +2.0% y/y in August (v/s +2.1% expected), down from +2.6% in July, mostly due to base effects, but highlighting that inflation has been stabilising more quickly than in other major economies and thus increasing the likelihood of an October rate cut.

To the day ahead, and data releases include the ISM manufacturing print for August from the US. Otherwise from central banks, we’ll hear from Bundesbank President Nagle and BoE Deputy Governor Breeden.


Tyler Durden
Tue, 09/03/2024 – 08:18

Why Kamala Harris Will Not Bring Prices Down… Her Plan Needs Inflation

0
Why Kamala Harris Will Not Bring Prices Down… Her Plan Needs Inflation

Authored by Daniel Lacalle,

In a recent interview with CNN, Kamala Harris said that Bidenomics is working and that she is “proud of bringing inflation down.”

However, the Bureau of Labor Statistics published the latest CPI at 2.9%, despite annual inflation being 1.4% when she took office. Inflation is a disguised tax and accumulated inflation since January 2021, when the Biden-Harris administration started, has increased more than 20%.

Of course, Democrats blame inflation on the war, the pandemic, and the science-fantasy concept of “supply chain disruptions.” No one believed it, because most commodities have declined and supply tensions disappeared back to normality, but prices continued to rise.

As a result, Harris invented the concept of greedy grocery stores and evil corporations to blame for inflation and justify price controls. Is it not ironic? She blames grocery stores and corporations for inflation, but when price inflation drops, she proudly takes credit.

The reality is that the Kamala Harris plan, like all interventionist governments, creates and strives for inflation. Inflation is a hidden tax. Governments love it and perpetuate it by printing money through deficit spending and imposing regulations that harm trade, competition, and technological creative destruction. Big government is big inflation.

Inflation is the way in which the government tricks citizens into believing that administrations can provide for anything. It disguises the accumulated debt, quietly transfers wealth from the private sector to the government and condemns citizens to being dependent hostages of government subsidies. It is the only way in which they can continue to spend a constantly depreciated currency and present themselves as the solution. Furthermore, it is the perfect excuse to blame businesses and anyone else who sells in the currency that the government creates.

Kamala Harris will do nothing to cut inflation because she wants inflation to disguise the monster deficit and debt accumulation. In the latest figures, the deficit has soared to $1.5 trillion in the first ten months of the fiscal year. Public debt has soared to $35 trillion, and in the administration’s own forecasts, they will add a $16.3 trillion deficit from 2025 to 2034. It is worse. The previously mentioned figure does not include the $2 trillion in additional debt coming from Kamala’s economic plan.

Harris is aware that her proposals to impose an unrealized capital gains tax, an economic aberration, and other tax hikes will not generate the $2 trillion in additional taxes she seeks. So, she needs the Fed to monetize as much as possible, eroding the US dollar’s purchasing power and making all Americans poorer in the process, only to blame corporations and grocery stores later. Furthermore, it is a way to present the government as the solution to the problem they create, promising the lunacy of price controls and enormous subsidies in a constantly depreciated currency.

It is a perfect plan to nationalize the economy in the style of Peronist socialism in Argentina.

Increase spending, deficits, and debt, making the size of government larger on the way in. Monetize as much debt as possible and cut rates to make it easier for the bankrupt government to borrow. When deficits balloon and inflation soars, increase taxes to the private sector and hike rates, which increases further the size of government in the economy. And you blame corporations?

Governments do not reduce prices. Governments create and perpetuate inflation by printing currency that loses value every year.

Corporations, landlords, and grocery stores do not create or increase inflation; they reduce it through competition and efficiency. Even if all corporations, grocery stores, and landlords were evil and stupid at the same time, they would not make aggregate prices rise and consolidate a constant trend of increases. For the same quantity of money, even a monopoly would not be able to increase aggregate prices. The only one that can make aggregate prices rise, consolidate, and continue increasing, although at a slower pace, is the government issuing and printing more currency than the private sector demands.

By admitting that the deficit will soar by $16.3 trillion in ten years in a budget that expects record revenues, no recession, and continued employment growth, the Harris team is conceding that they will strive for inflation to dilute the currency in which that debt is issued… and make you poorer.

Interventionists argue that the government does not have a budget constraint, only an inflation constraint, and can always tax the excess money in the system. Beautiful. This implies an increase in the size of the government during periods of economic expansion and further government expansion during periods of perceived normalcy. The government receives an enormous transfer of wealth from the productive sector, resulting in the creation of a dependent citizen class.

High taxes are not a tool to reduce debt. High debt and high taxes are tools to confiscate the productive sector’s wealth and create a subclass of dependent citizens.

Socialism redistributes middle-class wealth to bureaucrats, not rich to poor.

Massive government spending, constantly increasing taxes, and printing money. A plan to reduce the economy to serfdom.

Harris’ economic plan is not aiming to reduce inflation but to perpetuate it. Indeed, this economic policy mirrors Argentina’s 21st-century socialism, and it threatens the US dollar’s status as the world’s reserve currency. The government does not determine the level of confidence in a currency. When confidence in a currency declines, it does so quickly.

Saying it will not happen in the US because it has not occurred yet is the equivalent of driving at 200mph and saying, “We have not killed ourselves yet; accelerate.”

Tyler Durden
Tue, 09/03/2024 – 08:10

German Elites Call For “Firewall” To Prevent Conservative Governance After AfD Election Win

0
German Elites Call For “Firewall” To Prevent Conservative Governance After AfD Election Win

The coalition system of government common to European nations is supposedly designed to prevent the formation of authoritarian regimes by diluting power among a greater number of parties.  But, as the last decade has shown, it has only allowed for increasing socialist control in the EU under progressive and globalist politicians.  Most parties do not represent the will of the public but they collude to form bureaucratic cartels that gatekeep conservatives out of the process. 

The majority of Europeans do not support open immigration from the third world, they do not support oppressive carbon controls and they do not support the expansion of wars with eastern nations like Russia.  These are all policies which EU progressives are trying to force on the public anyway.  That’s called tyranny.

Far from stopping authoritarianism, coalition parties have normalized leftist oligarchy.  But the people of Europe (and the UK) are not staying quiet any longer. 

In Germany, the conservative AfD party (labeled right wing extremists by German Intel) have won their biggest victory since the party was launched in 2013.  The movement has secured an election win in the state of Thuringia by a wide margin and a very close second in Saxony.  The AfD is largely supported by younger voters (18-24) who are tired of the German socialist status quo of high taxes, high inflation and rising crime.   

The outcome has stunned German leftists who are now worried that future state elections and the national election in 2025 will have a similar result.

Elections in all the German states are hugely important. Not only are they some of the most powerful subnational bodies in Europe, they also have influence at the federal level through the Bundesrat – Germany’s upper house.  The AFD’s founding was in direct response to Germany and the EU’s mass immigration policies, inviting millions of third-world migrants and Islamic fundamentalists into the west without any vetting process.

Progressive and globalist leaders across Europe continue to pretend as if the concerns over immigration are held by a fringe minority, then act shocked when parties like the AfD win elections.  Olaf Scholz, the German Chancellor and lawmaker for the center-left Social Democratic Party (SPD), asserts that conservatives cannot be allowed to hold power in Germany regardless of voter decisions.  He stated this week:

“Our country cannot and must not get used to this…The AfD is damaging Germany. It is weakening the economy, dividing society and ruining our country’s reputation…”

The Chancellor failed to explain how the AfD could be “weakening the economy” when the economy has been under socialist control for decades.  Mr. Scholz urged other parties to block the AfD from governing by maintaining a so-called “firewall” against it.

“All democratic parties are now called upon to form stable governments without right-wing extremists,” he said, calling the results “bitter” and “worrying”.

The establishment media is now engaged in a vicious propaganda war against the AfD, with numerous outlets comparing them directly to “Nazis” despite the fact that the Nazis were far-left, not far-right. 

Adolph Hitler and Benito Mussolini were both open proponents of Marxism and sought to apply Marxist ideals within their National Socialist governments.  As Hitler noted in a January 27, 1934, interview with Hanns Johst in Frankforter Volksblatt:

“National Socialism derives from each of the two camps the pure idea that characterizes it, national resolution from bourgeois tradition; vital, creative socialism from the teachings of Marxism…”

Fascism has very little in common with conservative movements.  Defense of national borders and cultural identity are not intrinsically fascist ideals.  The political left would like everyone to believe otherwise.  

Scholz’s call for a coalition “firewall” in Thuringia, Saxony and other states as a means to prevent the AfD from governing is the same tactic used by Emmanuel Macron in France to shut out Marine Le Pen’s conservative National Front party despite their numerous election victories.  Macron pressed “moderate” progressives to align with full-bore communists as a means to overrule French voters and keep conservatives out of the process once again.

While this strategy is technically legal, it is an affront to the democratic process that leftists claim to hold so sacred.  The champions of “democracy” are enraged that the majority isn’t voting their way and so they have decided to usurp the election process entirely.

Under these conditions, conflict is inevitable.

Tyler Durden
Tue, 09/03/2024 – 07:45

Volkswagen Considers First-Ever Germany Factory Closures As Economic Troubles Mount  

0
Volkswagen Considers First-Ever Germany Factory Closures As Economic Troubles Mount  

News broke Monday that Volkswagen is considering plant closures in Germany. The auto giant faces falling profits due to slowing sales in China and other major markets. This development comes as Europe’s largest economy teeters on the verge of recession after reporting a slight contraction in second-quarter growth. Earlier this summer, VW’s Audi revealed a billion-dollar investment in Mexico, as the company’s future manufacturing could be overseas in the Americas. 

Several financial outlets are reporting VW’s potential factory closure plan, including Bloomberg, which said, “VW is considering unprecedented factory closures in Germany in a bid for deeper cutbacks, delivering another blow to Chancellor Olaf Scholz’s government.” 

“The economic environment has become even tougher and new players are pushing into Europe,” VW CEO Oliver Blume wrote in a statement, adding, “Germany as a business location is falling further behind in terms of competitiveness.” 

Bloomberg noted, “Any shutdowns would mark the first closures in Germany during the company’s 87-year history, setting VW up for a clash with powerful unions.” 

Financial Times quoted Daniela Cavallo, chair of the council that represents VW’s workers, who wrote in a note to workers that VW brand chief executive Thomas Schäfer “admitted” on Monday that cost savings programs had failed by several billions of euros, pushing VW into the red.

“As a result, the executive board is now questioning German plants, the VW in-house collective wage agreements and the job security programme running until the end of 2029,” said Cavallo.

Cavalla called the plans “an attack on our employment, workplaces, and collective bargaining agreements.” 

VW deliveries in China were down 20% amid a broader decline in petrol-powered vehicles in the second quarter. A spokesperson told Reuters in June, “We do not expect an easy year.” 

Meanwhile, VW’s Audi plant in Brussels has come under scrutiny this summer after the carmaker announced a one billion euro ($1.08 billion) investment in electric vehicle projects in the Mexican state of Puebla. There are mounting risks Audi could start moving EV production to Mexico. 

Besides sputtering VW sales and the largest economy in the EU at risk of recession, the country’s political environment has also become more chaotic. 

Populist Alternative for Germany, or AfD, has become the first far-right party to win a state election in Germany since 1945.

Rising populism is driven by a national government run by weak liberals that have overseen an economy with high inflation, disastrous immigration, and growing skepticism for military aid for Ukraine. These are all new pressures Chancellor Olaf Scholz’s center-left government.

In markets, VW shares trading in Germany recently slipped below Covid lows, touching levels not seen since 2011. 

Maybe the West sabotaging Russia’s Nord Stream pipeline that hooked Germany on cheap NatGas wasn’t such a great idea as Europe’s top economic powerhouse becomes less competitive. This only suggests increasing deindustrial risks, loss of jobs, and more socio-economic discontent across the bloc. 

Tyler Durden
Tue, 09/03/2024 – 06:55

Persistent Economic Pressures, Changing Consumer Habits Send More Restaurants Into Bankruptcy

0
Persistent Economic Pressures, Changing Consumer Habits Send More Restaurants Into Bankruptcy

Authored by Mark Gilman via The Epoch Times (emphasis ours),

It’s been a rocky year for the restaurant industry, with rising costs due to inflation and changing consumer habits driving a slew of chains with household names into Chapter 11 bankruptcy. According to those who follow the industry, there is no definable silver lining ahead for an industry in deep trouble.

A sign is posted in front of a Red Lobster restaurant in Fremont, Calif., on May 14, 2024. Justin Sullivan/Getty Images

“Most restaurants lose money, and there’s a reason for that. It’s a hard business with low margins and trends that are hard to navigate,” Jonathan Carson, the co-CEO of market strategy company Stretto, told The Epoch Times.

“When you add higher prices and a continually and increasingly overburdened consumer balance sheet, I think it makes the industry prime for restructuring,” he said.

Carson, who handles business reorganizations, said his company is aware of at least 17 national restaurant chains that have filed for bankruptcy in 2024.

Among the higher profile restaurant casualties this year which have filed for Chapter 11 bankruptcy protection this year are Roti, Buca di Beppo, Tijuana Flats, Sticky’s finger Joint, and Red Lobster.

Consumer Habits Have Changed

Laura Adams, a money expert and award-winning author who also hosts the weekly Money Girl podcast, told The Epoch Times that changes in consumer habits such as cooking at home and ordering home delivery have especially plagued the fast-casual tier of the restaurant industry.

“Consumers who dine at lower-end restaurants are the ones who will stop dining out first, and they’ll be the last ones to return because of unaffordability,” she said. “I think people have become used to ordering out, eating casually at home, and wearing casual clothes while watching Netflix.”

One of the changes in the restaurant industry that exploded during the pandemic was home-delivery services like Uber Eats, Grubhub, and DoorDash. The delivery companies, though, take large commissions from restaurants already struggling to make a profit.

Doordash orders can take as much as a 30 percent commission from restaurants.

“Doordash is a double-edged sword. It gives you the opportunity to get more food to more people, but it takes a pretty sizeable chunk off the bottom line,” said Justin Winslow, president and CEO of the Michigan Restaurant and Lodging Association.

“In third-party delivery, you have a real prisoner’s dilemma. You either shun the opportunity and limit your top-line gross sales, or you accept it and realize your ability to profit from those customers is harder than those inside your restaurant,” he told The Epoch Times.

Doordash is now the top restaurant-delivery app in the United States. At the end of 2023, DoorDash had 550,000 partner restaurants and grocery stores using its platform. However, the company is still looking for its first quarter of profitability.

In a written response to The Epoch Times, DoorDash’s corporate communications group wrote: “Our mission at DoorDash is to grow and empower local economies, and we’ve built tools that help restaurants expand their business and reach more people in their community.”

A Variety of Issues

Adams said that to survive, restaurants must offer something unique to make consumers leave their homes to experience it.

“I think if companies can’t differentiate themselves, they’re going to have a hard time. Maybe a restaurant like Red Lobster gets transformed, but it’s sad to see such a well-known brand wither away. When you see folks cutting back on dining out, you need to offer something unique,” she said.

The reason behind many Chapter 11 restaurant-restructuring filings this year needs to be discussed more, according to Carson, who has more than 20 years of bankruptcy experience.

He believes many of the filings have much to do with getting out of rent agreements. “You can walk away from a lease with Chapter 11 bankruptcies. The company can take the liability off their PNL [profit and loss],” he said. “But you do still have some casualties along the way.”

As tough as the restaurant economic and consumer market is today, Winslow says the restaurants in his organization are still reeling from the response to the pandemic that ended two years ago.

“The long tail of COVID is still impacting this industry more than any others. We did a poll in June, and I wasn’t prepared for how severe the fallout has been, with 60 of our members losing foot traffic in the last year and only 25 seeing an increase in top-line sales,” Winslow said.

“Forty of them are currently not profitable, and two out of every five of our restaurants are at risk for closure in the near future.”

Asked if she would advise anyone to open a restaurant today in this economic environment, Adams said, “I would say it is one of the most difficult businesses you can choose to run, and I would make sure you have the expertise and a record of success before you do it.”

Tyler Durden
Tue, 09/03/2024 – 06:30

Record Anti-Netanyahu Protests, Labor Strikes, Bring Israel To A Standstill

0
Record Anti-Netanyahu Protests, Labor Strikes, Bring Israel To A Standstill

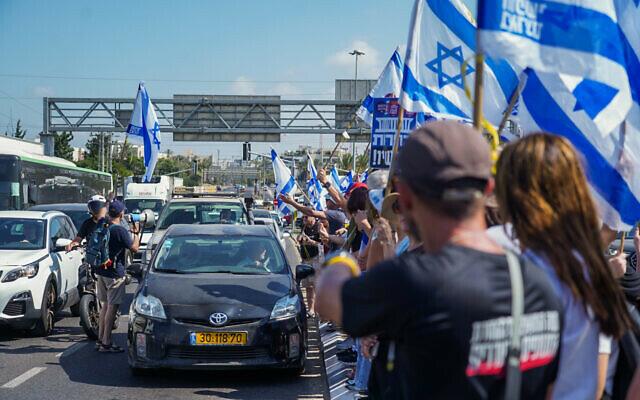
What by many accounts is the largest protest Israel has ever seen in its history filled the streets of Tel Aviv overnight, with more expected Monday, in the wake of Israel recovering the bodies of six Israeli hostages who were held in a Gaza tunnel.

Estimates by journalists said the anti-Netanyahu protest ranged anywhere from 300,000+ to 750,000 people. They accuse the Israeli prime minister of intentionally stalling and thwarting a hostage swap deal with Hamas, instead prioritizing the military operation which could put some 100 remaining captives in harm’s way. Watch: the largest rally of the war…

“For 11 months, the Israeli government led by Netanyahu failed to do what a government is expected to do — return its sons and daughters home,” The Hostages and Missing Families Forum said in a fresh statement. “A deal for the return of the abductees has been on the table for over two months. If it weren’t for the thwarting [of the deal], the excuses, and the spins, the abductees whose deaths we learned of this morning would probably be alive.”

Among the hostages was an Israeli American. The deceased and recovered bodies have been identified as American Hersh Goldberg-Polin, and Eden Yerushalmi, Ori Danino, Alex Lobanov, Carmel Gat, and Almog Sarusi.

The IDF had stated it believes they had been shot not long before its troops reached the tunnels under Rafah. Subsequently health authorities announced they were likely killed 48 to 72 hours before their autopsy, and that they were all executed at close range by multiple bullets.

All of these emerging details have only further served to outrage the victims’ families as well as demonstrators, who are calling for a new government. Huge protests have taken over parts of Jerusalem as well, and in front of government buildings.

Meanwhile, exacerbating the political divide over Gaza policy is the new announcement by Israel’s largest labor union the Histadrut, which has called a general nationwide strike to begin Monday. This marks an unprecedented first of the Gaza war.

The union said it is striking as it’s become clear that a truce deal is “more important than anything else,” according to the words of Arnon Bar-David, the head of Histadrut. “We are getting body bags instead of a deal.”

Israeli media on Monday says the country for some eight hours effectively came to a standstill:

Workers shut down public services, tech firms and other businesses, and activists snarled traffic at intersections across the country Monday as hundreds of thousands of people joined a one-day general strike aimed at pressuring the government to seal a hostage-ceasefire deal in Gaza after the military recovered the bodies of six hostages executed just days ago.

According to more:

With limited bus service forcing commuters to find alternate means of travel and many employees declining to show up for work, activists began gathering Monday morning at major junctions and on other roads around the country.

Demonstrators blocked major streets in Tel Aviv and shut down highways leading to the city from the north and east, bringing traffic on the Route 1 and Route 4 highways to a standstill. To the deafening beat of drums, they vowed not to abandon those still believed held hostage in Gaza, and accused the government of leaving them to die there.

Protesters have been heard chanting throughout the day, “Why are they still in Gaza” – in reference to the hostages.

TOI/Flash90

The pressure from the streets, and now that the large one-day union strike is sure to deal a blow to the economy (with future strikes still a looming threat), will increasingly result in political division at the top of the government.

However, an Israeli court has ruled against the Histadrut strike, and ordered workers back to their jobs, a decision which the union says it will respect:

A court ordered strikers back to work Monday afternoon, cutting short a labor action aimed at pressuring the government to seal a ceasefire and hostage deal in Gaza as thousands protested for an agreement nationwide.

Tel Aviv’s labor court ruled that the Histadrut labor federation had until 2:30 p.m. to wrap up a general strike that had shut down government offices and limited access to clinics, banks, public transportation and other services.

There are also widespread reports that during a Sunday night security cabinet meeting Israeli Defense Minister Yoav Gallant confronted Netanyahu.

Source: Times of Israel

Gallant told him: “Continuing to impose constraints such as the decision on the Philadelphi corridor will result in us not meeting the goals of the war. The fact that we prioritize the Philadelphi corridor at the cost of the lives of the hostages is a serious moral disgrace,” the defense chief said.

Tyler Durden
Tue, 09/03/2024 – 05:45

Kremlin Spokesman Suggests Moscow Prefers Kamala Harris Over Donald Trump

0
Kremlin Spokesman Suggests Moscow Prefers Kamala Harris Over Donald Trump

Authored by Paul Joseph Watson via modernity.news,

After Vladimir Putin said he preferred Biden over Trump, the Kremlin now appears to favor Kamala Harris, saying that, “The Democrats are more predictable.”

Before Biden was forced out of the race, Putin indicated that he had a preference for Biden over Trump, noting that the president was an experienced “old school” type of politician.

With Biden having disappeared from the ticket, Kremlin spokesman Dmitry Peskov was asked by pro-Russia TV reporter Pavel Zarubin, “Then who is our candidate now?”

“We have no candidate. But, of course, the Democrats are more predictable. And what Putin said about Biden’s predictability applies to almost all Democrats, including Ms. Harris,” responded Peskov.

The Kremlin spokesman was also dismissive towards Trump’s claim that he could end the war with Ukraine within 24 hours.

Peskov said there was no “magic wand” to immediately resolve the issue and that if Trump announced he was cutting all aid and demanding peace talks, it would still be “fantasy” to believe this would change mindsets in Kyiv.

The fact that Moscow has now twice indicated that if anyone, they’d prefer the Democrats to win, confounds the relentless legacy media narrative that Russia is attempting to meddle in the election to help Trump win.

As we highlighted earlier, one of the primary reasons as to why Robert Reich is calling for global regulators to threaten to “arrest” Elon Musk is to prevent Russia from meddling in the US election.

However, the primary example of election meddling before the 2020 election was on behalf of Democrats when they pressured social media companies to censor the Hunter Biden laptop story.

This was based on claims that the story was a ‘Russian disinformation’ operation which turned out to be completely incorrect.

Last month, Facebook founder Mark Zuckerberg apologized for censoring the story and promised not to allow it to happen again.

Your support is crucial in helping us defeat mass censorship. Please consider donating via Locals or check out our unique merch. Follow us on X @ModernityNews.

Tyler Durden
Tue, 09/03/2024 – 05:00

Hungary Is First Central Bank To Pause Rate Cuts As Inflation Suddenly Jumps

0
Hungary Is First Central Bank To Pause Rate Cuts As Inflation Suddenly Jumps

While the Fed has made it abundantly clear that it will officially end its hiking cycle in just over two weeks when it cuts rates for the first time since March 2020, the reality is that the US central bank is far behind the curve when it comes to easing monetary policy, with most other G7 central banks – including the ECB, BOE, BOC, SNB and so on – having already cut rates at least once. In fact, one may not realize it with inflation still at nosebleed levels for most people, but a few weeks ago, Bank of America calculated that 2024 is already the 3rd best year for rate cuts on record, with just the crisis 2009 and 2020 ahead!

Then again, cutting rates is easy: the problem is what happens when you have cut rates a few times and suddenly inflation is roaring back with a vengeance, and the central bank is facing a catastrophic credibility collapse similar to that experienced by the Arthur Burns Fed, when the US central bank hiked rates in the early 1970s as inflation soared, before cutting as inflation seemed to normalize, only to see a second, far more brutal surge in inflation over the next few years leading to the calamity that was the Volcker Fed’s 20% interest rates.

Impossible? Well, maybe reread what we wrote a week ago when we explained how Powell pivoted dovishly at Jackson Hole – and this for real – just as stocks, home prices, rents and food are at all time highs… and M2 once again positive and about to surge!

But while the Fed will have at least a few months to enjoy its “mission accomplished” before the next, far more crippling leg of inflation returns, for some central banks the day of reckoning has already arrived.

One such place is Hungary, whose central bank just paused rate cuts for the first time in more than a year as inflation jumped and the currency tumbled.

Last week, policymakers in Budapest left the benchmark rate at 6.75% on Tuesday following 15 consecutive cuts, a decision which was in line with the forecasts of most economists and left the country’s borrowing costs at the highest level in the European Union.

The National Bank of Hungary ended its easing cycle after inflation quickened more than its own forecast in July and breached the 4% upper bound of its tolerance range. Meanwhile, the forint, a key factor for monetary settings due to its impact on inflation, has slumped since last month’s (final) rate cut.

While Hungary’s rate setters signaled the pause was temporary and that they were looking for openings to ease monetary policy further, the reality is that absent a deflationary shock, the country’s easing cycle is most likely over and just like in the 1970s US, another, far more painful hiking cycle is on deck.

“There may be scope for cautiously lowering interest rates further in the coming period, depending on the expected interest rate policies of the world’s leading central banks, as well as developments in the domestic inflation outlook and changes in Hungary’s risk perception,” the rate-setting Monetary Council said in a statement.

The forint strengthened modestly after the decision, but remained down 2.5% versus the euro since the start of the year. The forint kept its gains after the guidance on further rate cuts, suggesting those were largely priced in.

Inflation may return to within the 1 percentage-point band around the 3% target in the coming months, Deputy Governor Barnabas Virag told reporters at a briefing, expressing his wishes more than some credible version of reality. At the same time, he said policymakers will closely monitor August data on potential stickiness in price growth, including in core inflation that strips out volatile food and energy items. Which is now rapidly rising once again…

The Monetary Council will weigh a 25 basis-point cut or no change to the key rate at each of its meetings this year, with room for one or two more quarter-point cuts by the end of 2024, Virag said, but don’t be surprised when the next move by the central bank is a hike instead of a cut.

Meanwhile, and as always when the central bank removes the Kool-Aid, Hungary’s politicians were immediately outraged that the money printers threaten to put their political career at risk over something as inconsequential as runaway inflation. Economy Minister Marton Nagy, a potential successor to Governor Gyorgy Matolcsy after his term expires early next year, last week lashed out at the central bank for its approach. He compared rate-setters to “cyclops” for a perceived singular focus on inflation at a time of lackluster economic growth. Nagy has in the past called for looser monetary policy, because that’s what politicians want: they want loose monetary policy (ideally QE) so they can bribe as many people as possible by literally printing money. That’s how the system works. 

Meanwhile, the cental bank – while it still has independence – is focusing not just on preserving the careers of corrupt politicians who summarily embezzle about 20% of whatever money they hand out to buy votes, but on avoiding hyperinflation and currency collapse which would happen in an instant should politicians ever get their hands on the money print.  The central bank has been clear that its priority is achieving price stability. Policymakers have progressively reduced the size of the cuts this year from a full percentage point to 25 basis points in the past two months. The key rate peaked at 18% last year.

And now that the easing cycle has hit its limits, deflation has dropped as low as it could go and inflation is once again rising, the next move will be a rate hike: first in Hungary, and then – when inflation comes roaring back across the world – everywhere else too…

Tyler Durden
Tue, 09/03/2024 – 04:15