57.6 F
Chicago
Saturday, October 3, 2026
Home Blog Page 25

Biden-Nominated Judge Dismisses Michigan Case Accusing Oil Majors Of Suppressing Renewables

0
Biden-Nominated Judge Dismisses Michigan Case Accusing Oil Majors Of Suppressing Renewables

Authored by Owen Evans via The Epoch Times,

A federal judge dismissed an antitrust lawsuit in which Michigan accused four major oil companies of acting as a cartel to block renewable energy.

U.S. District Judge Jane Beckering in Grand Rapids on Tuesday rejected a lawsuit filed in January by Michigan Attorney General Dana Nessel, a Democrat, against BP, Chevron, Exxon, Shell, and the American Petroleum Institute.

Nessel claimed they caused Michigan residents to suffer “artificially high home and transportation energy costs.”

She said that defendants acted “as a cartel in an unlawful conspiracy in restraint of trade to forestall meaningful competition from renewable energy in order to maintain their dominance in the transportation energy market and primary energy markets in Michigan and nationally in order to reap windfall, and illegal, profits.”

The complaint said that the defendants’ conspiracy “restrained competition in the primary energy market by suppressing renewable alternatives like solar and wind power in favor of fossil fuels.”

The judge said antitrust laws protect against none of the injuries for which Michigan sought a remedy, except for energy overcharges.

“The distance is too great between the alleged conspiracy and Michigan’s and its residents’ overcharges to find that the conspiracy proximately caused the overcharges,” Beckering said.

Other judges have rejected similar climate lawsuits, including in Delaware, Maryland, New Jersey, New York, Pennsylvania, Puerto Rico, and South Carolina.

A lawyer for Chevron previously called Michigan’s lawsuit “baseless as demonstrated by multiple related court dismissals.”

“Michigan’s lawsuit was part of a coordinated campaign against an industry that is vital to everyday life and serves as the engine of America’s economy,” the American Petroleum Institute’s SVP and general counsel Ryan Meyers told The Epoch Times by email. “Climate policy is a federal, not state, issue, and we are pleased with the court’s decision.”

The Justice Department (DOJ) had submitted a brief in support of the companies in the Michigan lawsuit.

“Michigan is attempting to impose liability for wholly out-of-state conduct related to global greenhouse gas emissions and regulate that conduct under state law,” the department wrote.

“Federal law exclusively governs interstate air emissions, including remedies for global climate change.”

It said that Michigan is attempting to use state law to “hold energy producers liable for a worldwide problem caused by indivisible greenhouse gas emissions, all because the problem has far downstream alleged effects in Michigan that are no different from, and may indeed be dwarfed by, alleged effects in other states or other parts of the world.”

The Epoch Times has contacted Attorney General Dana Nessel’s office to ask if the state will appeal.

The Epoch Times contacted BP, Chevron, Exxon, and Shell for comment but received no reply by publication time.

The Trump administration has also taken legal action against the Democratic-led states of Michigan, Hawaii, Vermont, and New York over their climate-related actions, alleging that they interfere with federal authority and the country’s energy development, according to the DOJ.

The DOJ in May 2025 accused the four states of overreach through their climate laws and lawsuits.

“These burdensome and ideologically motivated laws and lawsuits threaten American energy independence and our country’s economic and national security,” then-Attorney General Pamela Bondi said in a statement at the time.

“The Department of Justice is working to ‘Unleash American Energy’ by stopping these illegitimate impediments to the production of affordable, reliable energy that Americans deserve.”

The lawsuits against the four states followed President Donald Trump’s April 2025 executive order designed to protect American energy from state overreach, which stated that the nation’s energy independence is threatened when state and local governments seek to regulate energy beyond their statutory authorities.

In 2023, California Attorney General Rob Bonta, backed by Newsom, sued California’s biggest oil producers for “climate change-related harms,” including extreme drought, flooding, and wildfires. A judge paused the litigation in April this year as the Supreme Court takes up the companies’ request to quash similar lawsuits.

* * *

Tyler Durden
Thu, 09/24/2026 – 09:30

Panic At CNN As Paramount Seeks Elon Musk Equity Investment

0
Panic At CNN As Paramount Seeks Elon Musk Equity Investment

Paramount is weighing whether to bring Elon Musk on as an equity investor in its takeover of Warner Bros. Discovery, according to a report from Semafor. David Ellison has been sizing up potential investors as he works to lock down financing before the merger closes. Paramount has not said how much money it hopes to raise, and the size of any Musk investment remains undetermined. A Paramount spokesperson declined to comment, and Musk did not respond to a request for comment.

The news prompted panic inside CNN, which is owned by Warner Bros. Discovery. Staffers at the network had plenty to worry about before Musk’s name entered the conversation. Layoffs loom over the newsroom, nobody knows who will run the place once Ellison takes the keys, and now the man who took a chainsaw to Twitter’s payroll might own a slice of the operation.

“Amazing it comes out now of course,” one CNN source said, pointing to the awkward timing for California Gov. Gavin Newsom, who threw his support behind the merger to keep Paramount jobs in his state. “Not good for Gavin!”

“When it rains…[it pours],” another source said. “It’s really scary given what he did at X and DOGE.”

At CBS News, David Ellison installed Bari Weiss as editor-in-chief after Skydance acquired Paramount, and she has drawn fierce criticism for firing longtime 60 Minutes correspondents and for how she manages the newsroom’s coverage. CNN staffers have watched that saga unfold, and they have taken notes.

Once the merger is complete, David Ellison will control HBO Max, Paramount+, HBO, CBS, CNN, and thousands of film titles. That makes him one of the most powerful figures in American entertainment, and it makes who backs him financially a matter of real consequence.

Larry Ellison, David’s father and the founder of Oracle, has personally guaranteed more than $40 billion of the equity financing that makes the acquisition possible. But an investment from Musk would still carry significance.

“An investment from Musk would be a significant vote of confidence in the combined Paramount Warner Bros. from a businessman who also has a devoted retail investor following,” explained Semafor business reporter Rohan Goswami. “A check from Musk or other big financial backers would also give Paramount a more diversified investor base, and reduce Larry Ellison’s financial burden.”

The relationship between the two men runs deep in both directions. Larry Ellison invested in Tesla in 2018 and sat on its board for several years. When Musk took Twitter private in 2022, Ellison invested $1 billion in the deal.

“Musk’s dollars and political influence were concerning to Democrats during the 2024 election, given his control of X,” writes Goswami. “The possibility of him having even partial ownership in CNN and CBS would likely raise alarm bells in Washington, even though it is unlikely Musk would have formal input over the company’s operations.”

The news of Musk’s potential involvement comes days after the $110 billion merger cleared its final hurdle. Paramount settled the antitrust lawsuit that California Attorney General Rob Bonta brought against the deal.

Paramount agreed to spend an additional $1.5 billion on domestic production over five years. The company must release 30 films in theaters every year, rising to 32 after the first two years, with at least 20 wide releases, rising to 21, and four independent films each year. If Paramount misses any of those targets, it must sell Miramax Studios and pay $30 million for every film it comes up short. The settlement also forces Paramount to negotiate cable deals separately and commits it to raising domestic production from 5% of all films to 20%, or even 30%, if Congress passes certain tax credits. The settlement also created a News Editorial Independence Board for CBS News and CNN, though nobody has spelled out what powers it will hold. The agreement said nothing about layoffs.

Still, for a newsroom that has spent years telling viewers to fear Elon Musk, the prospect of him buying in carries a certain poetry.

Tyler Durden
Thu, 09/24/2026 – 09:15

Futures Tumble As Yields Hit Multi-Decade Highs, Oil Surges

0
Futures Tumble As Yields Hit Multi-Decade Highs, Oil Surges

Futures are lower with Tech underperforming as part of a global risk-off tone with few areas of safety, driven by a global bond rout that has sent yields across the globe to levels not seen in a generation. As of 8:00am ET, S&P futures are 0.6% lower with Nasdaq futures sliding 1.0% and reflecting the fallout from Wednesday’s barrage of inflationary signals, which sent stocks in Asia and Europe lower. In premarket trading, semis and memory are lagging the broader tech tape for the 2nd day, with software seeing slight outperformance, but still lower. Defensives and energy are leading cyclicals. The yield curve is bear steepening with the back-end yields making multi-year highs; pushing the 10Y yield to 5.14% and the 30Y yield to the highest since 2004. This follows Wednesday’s US data and auction-led selling in US paper with an ascent in energy prices today driving the moves further. The rout in bonds swept into Asia, with yields in Japan, Australia and New Zealand climbing by more than 10 basis points on Thursday. The USD remains bid and DXY is less than 40bp from its 52-wk high. In commodities, energy and ags resume their leadership as the market reduces its optimism for an imminent solution in the MidEast; metals are weaker with precious lagging ase.  The Trump-Xi meeting will be one to watch on today’s calendar, following US Treasury Secretary Bessent’s announcement of a two-month extension to the trade truce which appears to have disappointed markets as it was less than what China expected. US economic data slate includes 2Q current account balance and weekly jobless claims (8:30 a.m.), August new home sales (10 a.m.) and September Kansas City Fed manufacturing activity (11 a.m.) 

In premarket trading Magnificent Seven: Alphabet (GOOGL) -0.7%, Amazon (AMZN) -0.9%, Apple (AAPL) unchanged, Microsoft (MSFT) -0.6%, Tesla (TSLA) -1%, Nvidia (NVDA) -1.1%, Meta Platforms (META) -2%

  • Darden (DRI) falls 5% after the restaurant-chain operator posted first quarter sales that disappointed.
  • Dropbox (DBX) declines 5% after Citi downgraded the file management software company to sell, writing that recent optimism about its AI strategy “derives too much success too early.”
  • Etsy Inc. (ETSY) slips 2% after Arete downgraded the online retail platform to neutral, citing concerns over its valuation and growth sustainability.
  • Everpure (P) jumps 7% after the data-storage company forecast revenue for 2028 that exceeded the average analyst estimate.
  • MGM Resorts International (MGM) is down 9% after Barry Diller’s People Inc. dropped plans to acquire the rest of the casino giant.
  • Stitch Fix (SFIX) falls 19% after the online personal styling platform forecast a much weaker full-year 2027 Ebitda that analysts expected.
  • Viking Therapeutics (VKTX), which had surged 36% Tuesday on experimental weight-loss drug results, is down 12% after offering $200 million in common shares and another $200 million in convertible notes to help fund clinical development.

In other corporate news, a consortium backed by BlackRock and IFM are said to be closing in on $25 billion deal to buy Stack Infrastructure’s Asia Pacific data centers. Morgan Stanley is working to contain the damage from a leaked deal list after one of its top bankers accidentally sent an email to some clients containing a list of deals the firm was working on and monitoring.

Wednesday’s strong economic data, a weak debt auction, and mounting concerns over diesel prices and policy is rattling both Wall Street and Main Street, driving yields across most maturities to the highest in almost two decades. This has pushed inflation anxiety back to being front and center for investors, with concerns about Brent above $100 and an overheating US economy piling fresh pressure on bond markets. That’s taken the shine away from stocks, pulling the Nasdaq 100 down from a record high.

“Higher bond yields are becoming a more meaningful headwind for equities,” said Simon Wiersma at ING Bank. “Middle East de-escalation could take some pressure off bond markets, but the bigger story is the structural rise in global borrowing needs.”

Futures reflect the fallout from Wednesday’s barrage of inflationary signals. According to BBG, Traders are unlikely to commit fresh capital before tonight’s Trump-Xi summit, despite Bessent saying the US and China have extended their trade truce.

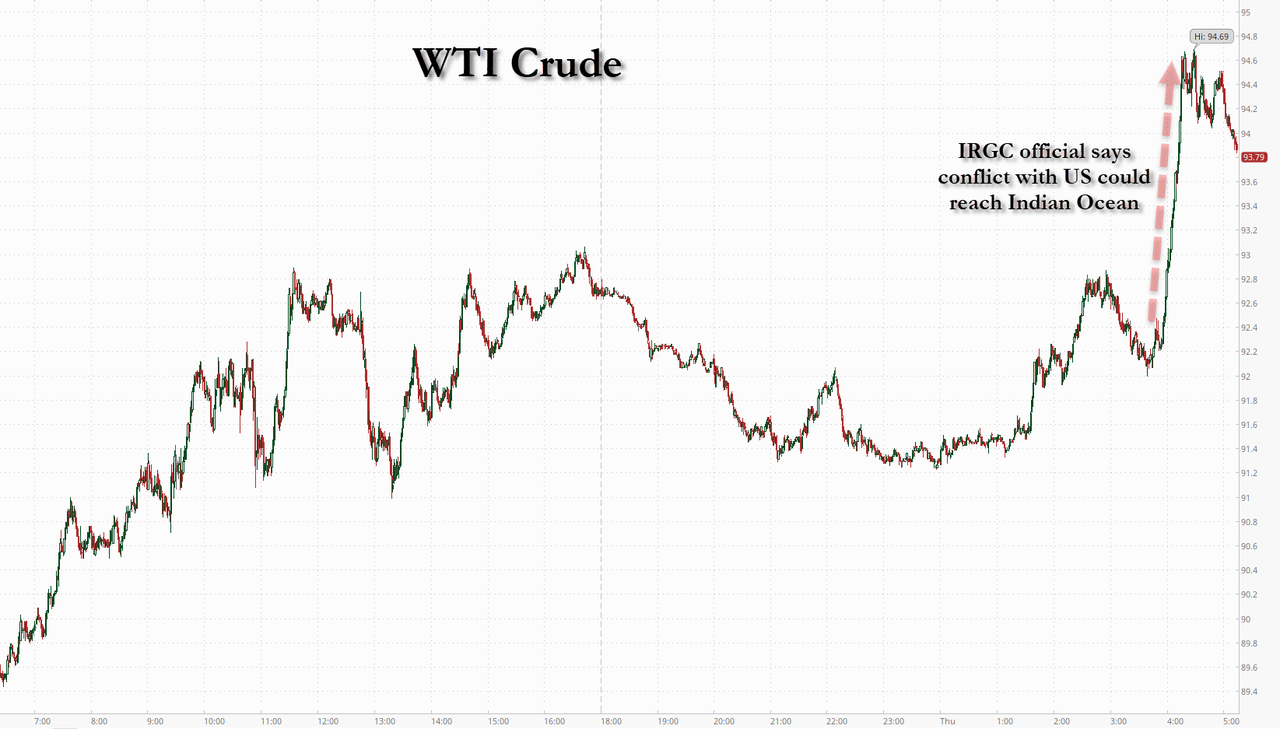
Oil’s latest leg higher came after an Iranian official warned Tehran may expand the war to the Indian Ocean if the US or Israel attacks again. “Now that the war has expanded from the Persian Gulf and the Strait of Hormuz to the Red Sea, it may, in the next phase of a potential conflict, widen further,” Iran’s semi-official Fars cited Yahya Rahim Safavi, who’s also a senior member of the Islamic Revolutionary Guard Corps, as saying.

“Oil prices remain the key driver overall,” said Nadege Dufosse, head of multi-asset at Candriam. “Investors are flying blind as it’s impossible to guess which way the talks between Iran and the US will go.”

Energy Secretary Chris Wright told oil industry leaders to brace for possible US curbs on diesel exports amid an intensifying debate within the Trump administration over that approach.  A potential diesel export ban would carry “significant implications” and even have the counterintuitive effect of an increase in gasoline prices if US refiners cut runs, notes Morgan Stanley.

Meanwhile, as extensively noted here, the entwined mix of AI and inflation is causing angst. Debt pressures return with Amazon, Alphabet CDSs topping the year’s highs, and Nvidia insurance costing more amid circular financing concerns.

“Before the year draws to a close, a choice is likely to be needed between inflation and the debt-financed capital expenditure boom,” notes Jonestrading Chief Strategist Mike O’Rourke. “Main Street has paid the price for five-plus years and does not have much left to give,” O’Rourke adds.

Fresh warnings about price pressures were raised at two rate decisions in Europe. The Swiss National Bank lifted its inflation forecast as it dialed down its threat of intervention to support the franc. Norges Bank increased borrowing costs for a second time this year and said it was primed to hike again. For the Fed, swaps fully reflect three quarter-point hikes over the next year, with significant hedging for a fourth. 

“A resolution in the Middle East would certainly bring some relief, particularly to European rates given the energy channel, but in the US the story goes beyond oil at this stage,” said Alessandro Gabellone at Bank Degroof Petercam. 

“Inflation has been above target for years, while fiscal imbalances and rising interest costs are increasingly part of the discussion around long-term yields,” he said.

Traders will follow the summit between Trump and China’s Xi Jinping later today at a time when tensions between the world’s two biggest economies persist over rare earths, technology curbs and Taiwan. “Super Intelligence” would be a big topic of discussion, Trump said on social media. “I want to leave it exactly where it is. That is China’s position also.”

Treasury Secretary Scott Bessent announced that a trade agreement struck by the leaders last year will now run an additional two months until Jan. 10, clearing the way for two more meetings in the coming months at summits in Shenzhen and Miami.

In Europe, the Stoxx 600 is down 0.4% with the average yield rising to levels not seen in almost two decades. Tech and autos are the worst performers. Energy gains. Here are some of the biggest movers on Thursday:

  • Mitchells & Butlers shares rise as much as 3.9% after the pub chain reported a pick-up in like-for-like growth in the final quarter, aided by a strong showing over the August bank holiday weekend.
  • Motor Oil Hellas shares rise as much as 1.9% after Goldman Sachs upped its price target on the Greek refiner, predicting it to benefit from higher diesel crack spreads.
  • BioGaia gains as much as 5.1% after Danske Bank reiterated its buy rating and raised its price target on the Swedish health additives company, seeing a good risk/reward opportunity going into the company’s third-quarter report, due on Oct. 22.
  • Raspberry Pi rises 23% after first-half revenue at the micro-computer maker jumped 90% to $256.9 million.
  • OVS shares rose as much as 4% in Milan trading after the Italian fashion retailer’s adjusted net sales grew 11% year on year.
  • H&M shares fall as much as 3.7% after US tariff refunds were largely credited for driving a beat in third-quarter profits at the Swedish fast-fashion retailer.
  • Tryg shares fall as much as 3.5% after Danske Bank downgraded the Danish insurance firm to hold from buy, predicting headwinds from inflation and rising interest rates.
  • Verbio declines as much as 6.9% as Jefferies says that despite a solid finish to the year, the biodiesel and bioethanol fuel producer’s new FY26/27 Ebitda guidance is below consensus.
  • Vistry shares drop as much as 11% after the housebuilder reported weak interim results and outlined the findings from the review conducted by its CEO.

Asian stocks declined for a second day amid renewed pressure from elevated oil prices and US bond yields. The MSCI Asia Pacific Index dropped 0.9%, with China the worst performer in the region. Indian equities dropped the most in over two months amid a selloff in the heavyweight financial sector after the nation’s insurance regulator proposed changes that include capping commissions. Japanese stocks were mixed as markets reopened following a three-day holiday. South Korea was shut for a holiday.  .

In FX, the Bloomberg Dollar Spot Index continues to carve out fresh multi-month highs, adding 0.2%. The Norwegian Krone leads G10 FX, whilst the Swiss Franc lags after respective rate decisions. USD/JPY has eclipsed its 200DMA for the first time since early September.

In rates, treasuries are mixed in early US session with the yield curve steeper around a little-changed 7-year sector. Front-end tenors unwind some of Wednesday’s steep losses while long-end has added to them, lifting 30-year yield to 5.44%, highest since 2004. 10-year reached 5.15%, highest since 2007. US 2-year yields are lower by around 3bp with long-end yields higher by around 3bp, close to cheapest levels of the day, steepening 2s10s and 5s30s curves by 4bp-5bp. 10-year yield is little changed near 5.125%, with bunds in the sector lagging by 1bp and gilts outperforming by 2bp. European rates are a touch higher with the French-German 10-year spread widening to about 111bps. Higher energy costs have hit sentiment in Europe. $44 billion 7-year note auction at 1 p.m. New York time follows poor demand for Wednesday’s 5-year note sale, which tailed by more than 3bp. WI 7-year yield near 5.055% is ~54bp cheaper than last month’s, which stopped on the screws. IG dollar issuance slate empty so far. Five borrowers priced a combined $5.2b Wednesday, paying about 6bp in new issue concessions on deals that were 1.9 times covered. Weekly volume stands near $33b, about $6.5b short of the $40b projected by dealers. Focal points of US session include weekly jobless claims data and 7-year note auction. 

In commodities, WTI crude oil futures are up around 1.4%, off session highs, extending Wednesday’s rally after an IRGC official threatened to expand the war in the Middle East into the Indian Ocean.Brent is higher by 2.5% and up nearly 10% from the week-to-date low as hopes of a US-Iran deal fade and rhetoric remains hostile. Brent gained after US Energy Secretary Chris Wright told oil industry leaders to brace for possible US curbs on diesel exports amid an intensifying debate within the Trump administration over such a move. The firmer greenback is dragging precious metals lower with spot gold down 0.6%. Bitcoin declines nearly 1%. 

US economic data slate includes 2Q current account balance and weekly jobless claims (8:30 a.m.), August new home sales (10 a.m.) and September Kansas City Fed manufacturing activity (11 a.m.) Fed speaker slate includes Richmond’s Barkin (8:30 a.m.), Cleveland’s Hammack (8:50 a.m.) and Philadelphia’s Paulson (10:10 a.m.). New York President John Williams said in a London event Thursday that more work needs to be done to lower US inflation.

Market Snapshot

Top Overnight News

  • The US 30-year yield climbed to its highest level since 2004 as comments from Iran further stoked oil-driven inflation fears and fiscal concerns. Equity futures fell. BBG
  • Brent surged to around $106 after a military adviser to Iran’s supreme leader said Tehran may expand the war to the Indian Ocean if the US or Israel attacks again, further undercutting hopes of a deal. BBG
  • Saudi Arabia has sold almost 100 million barrels of oil to Asian buyers since the middle of last week, helping to avert a looming supply crunch in the region. The crude will be sent via the Strait of Hormuz to buyers including Chinese state-run and independent refiners, as well as processors in India, Japan and South Korea. BBG
  • President Donald Trump’s strong rapport with Xi Jinping is set to be on display in Washington this week as the Chinese leader makes his first U.S. state visit in more than a decade. But below the surface-level pageantry at the White House, little is likely to be resolved as the world’s two biggest economies continue to spar over trade, Taiwan, AI and more. NBC
  • US Treasury Secretary Scott Bessent announced on Wednesday that Washington and Beijing have agreed to extend the trade agreement reached in South Korea for just two months, as Chinese President Xi Jinping arrives in Washington for a state visit. SCMP
  • Large cargo ships have recently paid up to $5 million to pass through the Panama Canal, as the global shipping industry reacts to trade disruptions from the Iran war and extreme weather patterns in the Western Hemisphere. WSJ
  • The AI build-out is on track to become the biggest economic bet in U.S. history, dwarfing the investments made to fund other huge U.S. infrastructure projects such as the railroads, the highway system and the plumbing for the internet. WSJ
  • AI firms are rushing to discount their products as some enterprises express caution about paying full price for all the new tools. The Information
  • Sellers are feeling the strain of US mortgage rates around 7%. Nearly one in five homes for sale had a price cut in August, while 45% of sales involved a seller concession, according to Redfin data. BBG
  • Mark Carney said he had seriously considered the “extreme tail risk” of a US invasion when asked about the possibility in a NYT interview. BBG
  • A US judge issued an order blocking the Trump administration’s White House ban on CNN, MS NOW and Politico.
  • US Senate Majority Leader Thune believes President Trump is open to implementing AI guardrails despite his public defiance on the issue: Axios.
  • An industry group representing US tech companies is reportedly pushing the US administration to withdraw its proposal to charge for H-1B visas: WSJ.
  • BofA Total Card Spending (w/e Sep 19th) +6.9% Y/Y (prev. +5.8% W/W); surging gas prices have opened up a gap in ex-gas spending between higher and lower income households.

A more detailed look at global markets courtesy of Newsquawk

APAC stocks were mostly pressured following on from the declines in global peers alongside the recent bond turmoil and jump in yields, owing to several factors including strong US data, hawkish Fed rhetoric and mixed reports regarding a US diesel export ban.
ASX 200 retreated with the declines led by weakness in miners, real estate and materials, while sentiment was not helped by mixed jobs data including an unexpected rise in the Unemployment Rate to a five-year high. Nikkei 225 outperformed after Japanese participants returned from the long weekend and with tech names playing catch-up to the recent AI-related momentum. Hang Seng and Shanghai Comp retreated despite early optimism from President Xi’s state visit to the US, while a two-month extension to the US-China trade truce until January 10th also failed to spur risk appetite.

Top Asian News

  • PBoC will offer lenders a record amount of up to CNY 1tln in overnight funds each day over the upcoming holiday period, according to Bloomberg.
  • PBoC to comprehensively use and timely adjust monetary policy tools to keep liquidity ample; to step up counter cyclical adjustments.
  • Japan’s Finance Ministry is to consider cutting issuances in liquidity-enhancement auctions for medium-term JGBs, according to sources.
  • Japanese Finance Minister Katayama said the principles on forex established since the joint US-Japan intervention remain in effect, while she won’t comment on specific FX levels.
  • Japan reportedly plans to finance economic security spending mainly through “bridging bonds”, reducing the need for the issuance of deficit bonds, Nikkei reported citing sources.

European bourses (STOXX 600 -0.3%) opened entirely in the red and has come under a fresh leg of pressure in recent trade amid the upside across the energy space. The source of the move came amid comments by the Senior adviser to Iran’s Supreme Leader Major General Safavi, saying the US conflict could expand further into the Indian Ocean. Sectors highlight the negative bias. Energy, Food, Beverages & Tobacco and Optimised Personal Care are the only sectors in the green. Leading the downside is Tech, followed by Autos and Financial Services. 

Top European News

  • The UK Treasury is open to smaller fiscal headroom and Chancellor Healey may accept a smaller fiscal buffer to reduce tax rises in next month’s Budget, according to FT.
  • German Ifo Expectations (Sep) 90.4 vs. Exp. 89.3 (Prev. 89.1).
  • German Ifo Current Conditions (Sep) 89.5 vs. Exp. 89 (Prev. 88.5).
  • German Ifo Business Climate (Sep) 89.9 vs. Exp. 89 (Prev. 88.8).
  • French Business Confidence (Sep) 101 vs. Exp. 102 (Prev. 101).
  • French Consumer Confidence (Sep) 86 vs. Exp. 85 (Prev. 86).

Central Banks

  • Norges Bank hiked rates by 25bps to 4.50%. Expectations heading into the announcement were split. The Bank noted that inflation has been above target for several years, and that by raising the rate, it will help reduce inflation and that the policy rate will be elevated for a time. The Committee is prepared to raise the policy rate further if warranted by the inflation outlook. The decision was backed by continued elevated inflation metrics, with the Bank alert to upward risks to the inflation outlook; it stated that “Inflation may then become stickier and harder to bring down again”. Governor Bache suggested that the inflation outlook has not materially changed, as such, stated that the Bank is prepared to deliver further rate hikes to bring inflation down to target. This is reflected in the rate path projection, which does not point to further tightening later this year, but will continue into Q1/Q2’27.
  • The Riksbank left rates unchanged at 1.75%, as expected. With the commentary, and particularly the forecasts, a hawkish bias can be seen with the language being that “it is expected that the increases to the policy rate will begin this year”, while the forecasts imply a hike around end-2026/start-2027 and then another one in the Q2/Q3-2026 period, and then thereafter there is some optionality of another hike by Q3-2028, a marked hawkish tilt vs the June projections. Albeit, this is caveated by the assessment that Q2 GDP strength was somewhat due to temporary factors, though the general commentary remains constructive. Overall, the strengthening of the SEK highlighted the overall hawkish tone.
  • The SNB left rates unchanged at 0%, as expected. The main update was the tweak to the FX language, which now shows “…willing to be active in the foreign exchange market…” from the June line of “If necessary, the SNB has an increased willingness to intervene in the foreign exchange market”, omitting the “increased” framing. In terms of the Bank’s inflation forecast, they were lifted across 2026, 27 and 28, primarily due to higher energy prices. They also noted that the recent uptick in inflation was attributed to a rise in goods inflation, driven by higher prices for oil products. In an immediate reaction, the CHF weakened given the aforementioned change to the intervention language.
  • Fed’s Williams (voter, Neutral) said the big challenge is on inflation and need to get it back to target in a timely manner while stating that it is reasonable to see another rate hike by year-end. He said short-run inflation expectations have been more encouraging, though the longer term they have not. On the economy, Williams said it has been remarkably resilient and downside risk to achieving maximum employment have receded.
  • BoE’s Lombardelli said policy is increasingly likely to need to tighten if elevated energy prices persist. On second-round effects, she said the absence of evidence is something but not much, and that it is likely still too early to see evidence in the data. On policy, Lombardelli described it as restrictive and that it is increasingly likely to need to tighten if elevated energy prices persist, absent clear evidence of disinflation or weaker activity.
  • BoE’s Dhingra said most of the financial conditions have done a lot of tightening work already in the UK and is encouraged on what pricing is doing. Dhingra added that the labour market looks pretty weak, while highlighting that winter energy prices will be critical for second round effects.
  • ECB’s Kocher said the ECB must prevent excessively high inflation from becoming entrenched and that the Eurozone economy remains fragile. Kocher added that there has been signs of somewhat more Eurozone momentum since summer.
  • ECB’s Schnabel said the energy shock is much more persistent than thought.

FX 

  • G10s are mostly lower against the USD, albeit only marginally. The EUR holds afloat, joined by the Kiwi, Loonie and GBP, whilst the CHF underperforms a touch.
  • DXY holds within a 101.00 to 101.23 range. The Dollar traded steady throughout overnight and early-European trade, but then moved higher alongside a bout of strength in the energy complex. This came after an IRGC official noted that the “war could expand” to the Indian Ocean or Bab el Mandeb Strait if the US decides to go to war again. More generally, crude benchmarks will be digesting reports that the US dismissed Iran’s Hormuz offer during UN talks, saying Tehran does not control the Strait.
  • Fed’s Williams spoke this morning, where he suggested it was reasonable to see another rate hike by year-end. Markets are pricing in a 38.4% chance of one 25bps hike by year-end, with a c. 50% chance of another this year.
  • Policy announcements from the SNB, Riksbank and Norges Bank have led to some volatility in the respective currencies. Kicking off with SNB, the Bank opted to hold rates, lifted inflation projections and removed its “increased willingness” for intervention. As such, the CHF moved lower following the announcement. Over in Sweden, the SEK was initially choppy following the Bank’s decision to hold rates. But then gradually strengthened, as the Bank lifted its rate path forecasts to imply a hike towards the end of this year/start of next year. Elsewhere, the only hike today was delivered by Norges Bank. It lifted its Key Policy rate by 25bps to 4.50%, and reiterated its tightening bias. EUR/NOK knee-jerked lower as traders unwound their bets of a hold, before paring around half of that move.

Fixed Income

  • The very modest bearish action at the start of the morning has given way to downside of c. 40 ticks in Bunds. Amidst a combination of factors, namely: energy upside on Iranian commentary, hawkish central banks, strong German Ifo & trade/tariff concern ahead of the US-China meeting, and also from Germany via the VDA.
  • Unsurprisingly, the bulk of the move was on the Iranian adviser Safavi intimating that the “scope of the war may expand…”, to include the Indian Ocean and other regions. An update that, over the course of around one hour, lifted Brent by over USD 2.00/bbl and pushed the US 30yr yield to its highest in over 20 years.
  • Bunds hit a 119.87 trough, nine ticks above Wednesday’s contract low. As mentioned, much of the focus has been on yield action, with upside seen across curves globally and a slightly steepening bias seen.
  • For USTs, no real move to Fed’s Williams, though he did note that pricing for another hike by end-2026 is “reasonable”. As it stands, markets imply a 38% chance of one 25bps hike by year-end, and just over a 50% chance of two. At a 104-28 contract low with yields bid across the curve.
  • Ahead, the focus remains on central banks with several speakers due, before the Trump-Xi meeting begins and the readout which is scheduled for just after 15:00BST commences. A meeting that is framed by recent remarks from Treasury Secretary Bessent that while the truce has been extended to January 2027, he does not know if a bigger deal can be done.
  • Italy sells EUR 2.5bln vs Exp. 2.5-3bln 3.00% 2028 BTP: b/c 1.64x (prev. 1.58x), average yield 3.64% (prev. 3.02%).

Commodities

  • WTI Nov and Brent Dec futures started the European morning with only modest gains, but gradually picked up as the session progressed. The bullish bias potentially comes amidst the lack of US-Iran diplomatic progress and after an IRGC official noted that the “war could expand” to the Indian Ocean or Bab el Mandeb Strait if the US decides to go to war again.
  • Focus also remains on the potential US diesel export ban, although the White House denied reports that the Trump administration is preparing a 90-day ban. Morgan Stanley warned that such a move, while not its base case, could have significant implications and potentially raise gasoline prices as barred diesel exports fill storage and force refiners to cut runs. The bank estimated refiners could need to reduce runs by around 2mln BPD, in turn cutting gasoline supply by roughly 650k BPD.
  • WTI trades around USD 93.70/bbl within a USD 91.23-94.69/bbl range, while Brent trades above USD 100.00/bbl within a USD 97.09-100.94/bbl range. Dutch TTF is firmer, with the contract trading within a EUR 73.39-75.04/MWh range. The Trump-Xi meeting could provide some impact amid reports of potentially reducing or removing China’s 15% tariff on US LNG.
  • Precious metals remain subdued following Wednesday’s surge in the USD and global yields, with hawkish Fed rhetoric and strong US data continuing to weigh on the complex. Spot gold trades towards the bottom of a USD 4,254-4,303/oz range, with the 100 DMA at USD 4,309/oz. Spot silver similarly trades around the lower end of a USD 63.52-64.55/oz range.
  • Base metals are mixed/rangebound against a subdued risk backdrop, with copper also digesting news that BHP suspended operations at its Escondida mine in Chile following an accident. 3M LME copper resides in a USD 14,575.08-14,677.78/t range.
  • Saudi Aramco CEO said that it is studying a “a fourth and a fifth route” for crude oil exports and noted that the Co. can restore disrupted operations within days.
  • China’s NDRC raised retail fuel prices in the current bi-monthly cycle, effective September 25th, with gasoline prices up CNY 395/tonne and diesel prices up CNY 385/tonne.
  • BHP (BHP AT) said operations at the Escondido mine in Chile were suspended following an accident.

Trade/Tariffs

  • US President Trump said it was a great greeting with Xi and that the entire tech and banking world will be at Thursday’s dinner. Trump also stated that he had some great conversations with leaders at the UN General Assembly.
  • Chinese President Xi said he looks forward to in-depth exchanges with US President Trump and will expand cooperation between the two countries in various areas, while he is confident the US trip will produce fruitful results. Xi also commented that China and the US must be allies, not adversaries, and he is confident China and the US can find the right path to coexist in a new era.
  • US Treasury Secretary Bessent said the US-China trade truce was extended to January 10th, while he doesn’t know if a bigger trade deal can be done with China and could just roll the current deal forward. Furthermore, Bessent said that presidents Trump and Xi are expected to meet four times this year and that China is doing well so far in meeting 2026 pledges.
  • China’s MOFCOM said they discussed AI with the US under the bilateral economic and trade consultation mechanism.
  • Germany’s VDA is reportedly endorsing new tariffs against China for the first time, according to Handelsblatt.
  • India cut import duties on crude palm oil and soybean oil to 5% (prev. 10%).

Geopolitics: Iran

  • Senior adviser to Iran’s Supreme Leader Major General Safavi said the scope of the war may expand to the Indian Ocean and other regions, if the US starts a new war.
  • Israeli source said an additional round of strikes against Iran seems to be a matter of time, Al Hadath reported. The source added that Iran is intensifying the transfer and fortification of the Natanz nuclear project. Additionally, the source said Israel does not see a real chance of reaching an agreement between the US and Iran, and that the US wants to end the Iran war with a political agreement or a decisive attack that topples the regime. On further strikes, the Israeli source said they will strike Iranian nuclear facilities again if Iran crosses the red lines, with or without US involvement.
  • US Treasury Secretary Bessent said they are getting sometimes up to 17mln oil barrels out of Hormuz and noted that probably 80-90% of Iran’s external flights are shut down.
  • Chinese Foreign Minister said the Strait of Hormuz conflict must be resolved through dialogue and calls on all parties to seek a peaceful solution, Al Arabiya reported.
  • Pakistan’s Foreign Minister told Iran’s Foreign Minister that they must remain committed to dialogue and diplomacy.
  • Iran’s Foreign Ministry noted that Iran’s Foreign Minister held a meeting with Pakistani counterpart at the UN General Assembly.
  • UK Chancellor Healey said he spoke with US Treasury Secretary Bessent today about stepping up pressure on Iran and how to work together to drive growth in both nations.
  • EU’s Costa spoke to Iran’s President Pezeshkian and urged Iran to resume its cooperation with the IAEA, while he also called for an end to Iran’s strikes against its neighbours and a full restoration of freedom of navigation in the Strait of Hormuz.
  • Initial reports noted two explosions in Bandar Abbas and one in Sirik, southern Iran, with the explosion in Sirik reportedly coming from near the coast, off to the sea.

Geopolitics: Ukraine

  • Russia’s Kremlin said no decision yet has been made on a December summit between US President Trump and Russian President Putin and that discussing a possible agenda is premature.
  • Waves of Russian missiles attacked Kyiv and more than a dozen heavy explosions were heard in 30 minutes, according to an FT reporter.

US Event Calendar

  • 5:00 am: Aug F Building Permits, prior 1394k
  • 8:30 am: 2Q Current Account Balance, est. -257.4b, prior -226.83b
  • 8:30 am: Sep 19 Initial Jobless Claims, est. 200k, prior 196k
  • 8:30 am: Sep 12 Continuing Claims, est. 1740k, prior 1730k
  • 10:00 am: Aug New Home Sales, est. 615.55k, prior 607k

Central Bank Speakers 

  • 4:10 am: Fed’s Williams Speaks During Moderated Discussion
  • 8:30 am: Fed’s Barkin In Fireside Chat With Economic Club of Washington
  • 8:50 am: Fed’s Hammack Delivers Opening Remarks at Inflation Conference
  • 10:10 am: United States Fed’s Paulson Speaks At Fintech Conference

DB’s Jim Reid concludes the overnight wrap

As we go to press, the main story is still the huge global bond selloff, with yesterday seeing the biggest jump in the 10yr Treasury yield (+15.2bps) since the market turmoil around Liberation Day in April 2025. The main driver was a strong batch of PMIs, along with a rebound in oil prices, which both led to mounting speculation about faster rate hikes. Indeed, futures this morning are pricing a 71% chance of a Fed rate hike at the next meeting in October. So that drove a bunch of records, and we even saw the 5yr Treasury yield (+16.7bps) rise above 5% for the first time since 2007. In addition, there were growing signs of stress in Europe, where the Franco-German 10yr spread (+6.2bps) rose to 110bps by the close, marking its highest level since the Euro crisis in 2012. So it was a rough day all round, and risk assets came under fresh pressure, with the S&P 500 (-0.75%) posting its biggest decline in a month, with futures down another -0.21% this morning.

Those moves had several catalysts, but the biggest were the US flash PMI numbers, where the composite PMI unexpectedly hit a 5-year high of 58.4 in September (vs. 55.3 expected). So that played into the narrative of resilient growth, which in turn would enable the Fed to keep hiking rates to deal with inflation. And significantly, this was part of a global theme, as we found out earlier that the Eurozone composite PMI hit a 3-year high of 53.1 (vs. 51.7 expected). So if anything, the initial signal from the PMIs suggested that growth was accelerating in September across many of the world’s biggest economies.

That positive data drove the hawkish repricing, but it got a further boost thanks to a fresh rebound in oil prices. Indeed, Brent crude (+3.86%) ended a run of 5 consecutive declines yesterday, closing back up at $103.08/bbl. That came amidst growing doubts about the chance of a US-Iran deal, despite the talks at the UN this week. For instance, a spokesman for Iran’s foreign ministry said that Iran had presented a list of conditions to the US for restarting negotiations via Qatari mediation. That included the US accepting a shipping route agreed by Oman and Iran, along with an end to the naval blockade and the release of Iran’s frozen assets. And Iran’s President Pezeshkian struck a defiant tone, saying that Iran would not allow freedom of navigation through Hormuz while the US blockade and sanctions remain in place. So for investors, the sense was that the two sides were still far apart, and the 12-month Brent future (+0.42%) hit a 3-month high of $80.96/bbl by the close. So it was clear that investors were still expecting a protracted period of higher oil prices.

Collectively, that strong data and the oil rebound led to growing speculation about faster rate hikes. But interestingly, this fits into the usual pattern of recent cycles, where investors have tended to underestimate the scale of hikes at the outset, before adjusting in a hawkish direction. We explored this pattern on Monday (link here), where we pointed out several reasons that leant in the direction of faster hikes. For instance, much as inflation is lower than in the 2022 cycle, broader financial conditions are much more accommodative today. Moreover, another historical pattern is that central banks tend to correct for the last crisis, and in 2021-22 they faced criticism for not reacting to inflation fast enough, so we’re already seeing a more hawkish reaction function this time. And looking forward, the latest uptick in commodity prices hasn’t filtered through to the inflation numbers yet either.

This hawkish repricing was clear over the last 24 hours, and when it came to the Fed, market pricing for an October hike rose from 53% on Tuesday, to 69% by last night’s close. Similarly for the ECB, the chance of an October hike rose from 48% on Tuesday to 66% by the close. So in other words, there was a mounting sense that central banks would need to accelerate the hiking cycle, and that hikes at every other meeting might not be enough to get inflation back to target again. Looking beyond the next meeting as well, market pricing also shifted hawkishly. So for year-end, investors are now pricing in 37bps of Fed hikes, implying a near-even chance that they’ll deliver two more hikes before the year is out, which is the most hawkish pricing for December 2026 so far. That backdrop led to another huge bond selloff yesterday, with yields seeing big rises across the board. That was particularly clear for US Treasuries, where the 10yr yield (+15.2bps) saw its biggest daily jump since the market turmoil after Liberation Day in April 2025, taking it up to a post-2007 high of 5.11%. The moves were clear across the curve as well, with the 2yr yield (+14.2bps) jumping to its highest since May 2024, at 4.90%, whilst the 30yr yield (+9.9bps) hit a post-2007 high of 5.40%. A weak 5yr auction also didn’t help matters, with yields up to their intraday highs after $70bn of notes were sold at 5.03%, +3.1bps above the pre-sale yield. And in turn, the rise in US yields saw the dollar index (+0.49%) rise to its highest since July, while gold (-1.68%) had its biggest decline in two weeks.

That selloff was echoed in Europe, where the energy price gains and the strong PMIs drove a hawkish repricing as well. So that pushed bond yields up to fresh multi-year highs, with the 10yr bund yield (+9.2bps) at a post-2009 high of 3.55%, whilst the 10yr OAT yield (+15.4bps) hit a post-2008 high of 4.66%. Notably as well, it also pushed the Franco-German 10yr spread up to 110.4bps, which was a level last seen in July 2012, a few weeks before Mario Draghi delivered his famous “whatever it takes” speech that was a key turning point in resolving the crisis.

All that put a lot of pressure on equities, even though the growth data surprised on the upside. So the S&P 500 (-0.75%) posted its biggest decline in a month, with all the major sector groups apart from energy (+1.04%) losing ground. The NASDAQ (-1.13%) and the small-cap Russell 2000 (-1.77%) saw even larger falls. Meanwhile in Europe, the STOXX 600 (-0.44%) also saw a pullback, alongside declines for the DAX (-0.66%) and the CAC 40 (-0.39%) as well.

Overnight in Asia, the bond selloff has continued, with Japan’s 2yr yield (+4.8bps) up to a post-1995 high of 1.88%, whilst the 10yr yield (+11.1bps) is up to its highest since 1996, at 3.07%. And that’s been echoed in other countries, with Australia’s 10yr yield (+10.4bps) up to 5.32%, whilst New Zealand’s 10yr yield (+14.1bps) is up to 5.04%, the highest since November 2023. So equities have also struggled, with losses for the Hang Seng (-0.52%), the CSI 300 (-1.29%), the Shanghai Comp (-0.93%) and the S&P/ASX 200 (-0.80%). The main exception has been the Nikkei (+0.94%) although that reflects a catch-up after the index has been closed for the previous three days. Meanwhile in South Korea, markets are closed for a public holiday.

Looking forward, a key event today will be the summit between Presidents Trump and Xi. From a market standpoint, the main news was US Treasury Secretary Bessent saying they’d agreed to extend last year’s trade truce by two months, which will now keep tariffs lower until January 10. This extension was shorter than had been floated by US officials beforehand, but does offer more time to potentially reach a longer deal.

Finally, as oil prices were rising, another energy story yesterday was around whether the US might restrict diesel exports. Trump said on Tuesday that he was considering a possible export ban, and US diesel prices then slumped yesterday after Politico reported that the US was preparing a plan for a 90-day export ban. However, Reuters then reported a White House official who said this wasn’t accurate, while US Energy Secretary Wright said that “a full blanket ban or zero exports of diesel” are not being discussed. However, he did say that the administration was working with refiners to voluntarily curb exports of diesel. So despite the rises in crude, US wholesale diesel prices settled -3.35% lower after trading as low as -7.45% intra-day.

Looking at the day ahead now, and US data releases include the weekly initial jobless claims, new home sales for August, and the Kansas City Fed’s manufacturing index for September. Then in Europe, we’ll also get the Ifo’s business climate indicator from Germany for September. Otherwise from central banks, we’ll hear from the Fed’s Williams, Barkin, Hammack and Paulson, the ECB’s Schnabel and Lane, and the BoE’s Dhingra, Breeden and Lombardelli. The ECB will also publish their Economic Bulletin.


Tyler Durden
Thu, 09/24/2026 – 08:46

“Way Shorter Than Beijing Hoped”: China Stocks Tumble As Trade Truce Disappoints

0
“Way Shorter Than Beijing Hoped”: China Stocks Tumble As Trade Truce Disappoints

Chinese stocks slipped overnight as the two-month extension of the US-China trade truce fell short of some Wall Street expectations (some desks were hoping for +6 months), offering limited reassurance that today’s talks would deliver a long-lasting trade deal, stabilize bilateral ties, and ease uncertainty over global trade.

The mainland CSI 300 Index dropped 1.7%, while the Hang Seng China Enterprises Index pared losses and closed flat. Broader Asian equities also came under pressure after a global bond selloff gathered pace as investors responded to stronger-than-expected US economic data on Wednesday and weak Treasury auction demand amid increasing fears of further Federal Reserve tightening

The two-month truce extension through Jan. 10 removes an immediate source of uncertainty but falls short of the three-to-six-month extension some Wall Street desks were hoping for. 

As we detailed in an overnight note titled “Mr. Xi Comes To Washington: What Wall Street Banks Are Expecting,” President Trump rolled out the red carpet for President Xi Jinping at Joint Base Andrews on Wednesday.

Xi’s first White House visit since September 2015 includes bilateral talks, a South Lawn ceremony and a black-tie dinner later today with technology executives including Nvidia’s Jensen Huang, Tesla/SpaceX’s Elon Musk and OpenAI’s Sam Altman. Private tea with the Trumps and a National Archives visit are also on the books. 

The high-level diplomatic visit comes as unresolved disputes mount. Trade talks center on the duration of the tariff truce, a proposed “Board of Trade” arrangement covering roughly $30 billion in goods on each side, and potential Chinese purchases of soybeans, Boeing aircraft and LNG. Rare earth supplies, technology restrictions, Iran and Taiwan also loom over the summit.

On the AI front, low-cost Chinese open-weight models are pressuring US frontier labs and eroding moats. Restrictions on advanced chips, allegations that Chinese companies distilled US models, and a proposed AI hotline add another layer to negotiations.

The broad expectation across JPMorgan, Deutsche Bank, TD Cowen and Raymond James is that the summit will produce limited breakthroughs. Wall Street’s focus now shifts to how long the truce lasts and whether either side makes concrete concessions.

Earlier this morning, former acting deputy US Trade Representative Wendy Cutler told Bloomberg TV that the temporary US-China trade truce extension signals Trump’s dissatisfaction with Beijing’s rare earth exports and agricultural purchases.

It’s a “way, way shorter time than China had hoped for; China wanted to extend that truce until the end of Trump’s term,” Cutler told Bloomberg’s Heidi Stroud-Watts.

She continued, “We’re at a point in our relationship with China where big deliverables are just no longer possible, and we’re talking about managing the relationship and keeping it stable, but not improving and strengthening it.”

Matt Maley, a veteran Wall Street strategist and chief market strategist at Miller Tabak + Co., wrote in a note that the two-month extension may disappoint investors who were hoping for a longer-term deal and may not bode well for equities. “A lot of investors that I have been speaking to were hoping for a six-month extension,” he said.

Read what JPMorgan, Deutsche Bank, TD Cowen and Raymond James have to say here.

Tyler Durden
Thu, 09/24/2026 – 08:45

They Used AI To Race-Swap Him…

0
They Used AI To Race-Swap Him…

Authored by Steve Watson via Modernity.news,

Stanford University took a real photograph of three students in a dining hall, ran it through artificial intelligence, and published the result as a “Welcome Home” banner. However, one of those students, Hispanic undergrad Billy Ramirez, class of 2027, was gone.

In his place stood an AI-generated Black woman. The two students next to him had their faces slimmed and altered. Clothing was even changed into Stanford merchandise.

This was not a student meme. It was official marketing from Residential & Dining Enterprises, the office that runs housing and dining for one of the richest universities in America – an institution that still soaks up hundreds of millions in taxpayer money while preaching ethics about “synthetic media.”

Ramirez recognized the shot. A Stanford photographer had taken it at a 2024 Lunar New Year dinner as he held a plate of noodles. Dining posted the unedited picture the next day. Years later it came back as campus décor, but completely redesigned.

“I was driving to school from my hometown when my friend sent me the images comparing the banner to the original photos, and I was immediately baffled,” Ramirez told The Stanford Review, which broke the story.

Ramirez further explained, “At first, I found it hilarious that they had used AI to completely change our appearances, including my race and gender. But after looking at the comparison, I was also upset because I don’t agree with Stanford making those choices about how we were represented. Seeing my identity changed and being left out of the picture made me feel, in a way, silenced and erased from a representation that was supposed to include me.”

He later told The New York Times, “To see me erased like that so easily was kind of very upsetting.” To the San Francisco Chronicle he added that the doctored banners were “all over campus. It’s the first thing you see when you walk in.”

The conservative campus paper posted the side-by-side.

Stanford’s own AI guidelines for marketing and communications are not vague. The university forbids creating or publishing AI-generated content that “falsely depicts Stanford people, events, research, facilities, or achievements.”

It requires clear identification of AI-manipulated images when leaving that out could mislead people about what is real. It also bars synthetic media depicting real individuals without explicit consent.

Residential & Dining Enterprises did all of it anyway: no consent from Ramirez, no disclosure on the banners, and a fabricated person dropped into a photo of actual students.

After the Review published, the university stopped pretending it hadn’t happened. Public relations director Charlene Gage said the school had reviewed the matter and confirmed AI was used “in violation of university policy.”

“Stanford’s A.I. policy is clear: The use of A.I. in producing or altering images of Stanford people, events, research, facilities or achievements is strictly prohibited,” the university said. “Both the alteration and lack of disclosure in this case violate that policy. We are working with Residential and Dining Enterprises to provide additional training and ensure proper review of all materials.”

The banners came down. Officials promised more training. The Chronicle also noted the same dining shop appeared to have used AI on meal-deal posters earlier in the year. The instinct was already there. This time they race-swapped a living student and hung the result where freshmen walk in.

The punchline writes itself. A real minority student was deleted and replaced with a computer generated person so the brochure could appear to be more diverse.

Stanford has spent years treating race as a branding problem to be managed. In 2022 it rolled out the “Elimination of Harmful Language Initiative,” a list that treated “American” as suspect and put “grandfather” and “brave” on the chopping block before national ridicule forced a retreat.

In 2024 it was still demanding DEI statements from students applying to an engineering marketing class. This year it was still funding racialized research titles even after claiming it had wound that machinery down.

When the real campus does not match the poster in their heads, they no longer have to hunt for a different group of volunteers. They generate one.

The same racial script is not confined to Palo Alto. At the University of Illinois Urbana-Champaign, a required first-year education course walked future teachers through slides on “undocumented” language rules, “internalized oppression,” “minoritized identities,” and how “white peers” supposedly silence everyone else.

A whistleblower told Fox News Digital the professor kept repeating that “you as future educators” must carry this into classrooms – while the class taught almost nothing about how to actually teach math or reading.

Further down the pipeline, schools have been sorting children into “affinity groups” by race. White kids get the lecture on privilege and America’s sins. The other room gets praise and, in the New York example that spread last year, cupcakes. Parents described children coming home in tears. The program is not a rumor from a single district. It has shown up across progressive school networks.

Ramirez was not asking to be a symbol. He was in a photo holding noodles. That was too inconvenient. His race and sex were edited out, two classmates were digitally put on a diet, and a fictional black woman was invented to complete the set.

Absolute ideological obsessive insanity.

Tyler Durden
Thu, 09/24/2026 – 08:33

Aramco CEO Eyes “Fourth & Fifth” Oil Export Routes To Break Hormuz Chokehold

0
Aramco CEO Eyes “Fourth & Fifth” Oil Export Routes To Break Hormuz Chokehold

Brent crude futures climbed back above $104 a barrel early Thursday as Iran threatened to widen the Middle East conflict into the Indian Ocean and optimism surrounding yesterday’s meetings between US and Iranian officials on the sidelines of the UN General Assembly faded.

A focal point this morning is Nikkei Asia’s interview with Saudi Aramco CEO Amin Nasser, who said Aramco is studying additional crude export routes to bypass the Strait of Hormuz.

Nasser said Aramco is conducting engineering and feasibility work on “a fourth and a fifth route” for crude exports. He did not disclose their locations.

He warned, “This crisis is not really getting better. The situation will get worse because this interruption is significant. It’s not a small interruption,” adding, “I don’t think things are getting better.”

The plan for two more oil export routes builds on the current three primary routes, one of which passes through the Hormuz chokepoint that Iran has disrupted. This comes after drone attacks earlier this month disrupted Saudi Arabia’s East-West pipeline to the Red Sea, but media reports this week suggest the pipeline could restart soon at half capacity.

“When people talk about the East-West [pipeline], they think it’s one pipeline. It’s not, it’s multiple lines,” he said. “It’s not easy to interrupt all the lines at the same time. So it gives us the flexibility to respond and cater to our customers.”

Beyond the Hormuz chokepoint and the East-West pipeline, Aramco can move crude north through Egypt’s Sumed pipeline to the Mediterranean, Nasser said.

“People think about interruptions in Hormuz, interruptions in Bab-el-Mandeb, [but] we never stopped. We continue to supply our customers,” he said. “The only thing you do [is] shift more vessels, one way or the other. … We do have this multiple optionality that allows us to meet our customers’ demand.”

Last weekend, Qatari Energy Minister Saad Al-Kaabi blasted Treasury Secretary Scott Bessent for saying he was “wrong” to claim that the Hormuz chokepoint would be “worthless” to the oil industry in two years. 

“I think this is completely wrong,” Saad Al-Kaabi said at the Qatar Economic Forum in New York.

Speaking to Fox Business’s Larry Kudlow on the sidelines of the Group of 20 finance ministers’ summit in North Carolina earlier this month, Bessent said the Hormuz maritime chokepoint, in about “two years will be… a worthless piece of water,” adding that oil “will be going on pipelines across land.”

Bessent has a point. Aramco’s push for new export routes reinforces the outcome we first pointed out at the war’s start: energy flows will reroute around Hormuz, gradually eroding Tehran’s leverage. Iran’s threat to widen the conflict may be an attempt to keep that leverage alive. And it won’t be just the Saudis rewiring energy flows; it’ll be all the Gulf allies with the capability to do so. 

Tyler Durden
Thu, 09/24/2026 – 07:45

Judge Orders Trump To Temporarily Restore CNN, MS NOW, And Politico Access To White House

0
Judge Orders Trump To Temporarily Restore CNN, MS NOW, And Politico Access To White House

Authored by Melanie Sun via The Epoch Times,

A federal judge has ordered President Donald Trump to temporarily restore White House access for CNN, MS NOW, and Politico while they challenge the revocation of their press passes in court.

Federal Judge Timothy Kelly of the U.S. District Court for the District of Columbia issued a temporary restraining order against the White House ban, reinstating hard pass access for CNN, MS NOW, and Politico in the early hours of Sept. 24.

Trump announced on Sept. 18 that he was banning the three news outlets from White House premises over their “constant ‘reporting’ fake news.”

The White House revoked their access the following day.

In letters to the outlets dated Sept. 22, the White House said the organizations had violated “the standards of professionalism and decorum expected of those given access to the White House Complex, including by trafficking in verifiable falsehoods about national security and other issues, and publishing sensitive or classified information.”

The outlets subsequently filed for a temporary restraining order, and a remote hearing was held on Sept. 23.

The judge issued the order hours after the hearing, saying the court’s decision was “dictated by the application of well-known D.C. Circuit precedent that this Court must faithfully apply.”

Kelly pointed to two prior court decisions. A 2019 decision sided with reporter Brian Karem, whose White House press pass was restored because the government failed to provide prior notice.

The other decision was the landmark 1977 Sherrill v. Knight case, which held that once the White House makes press facilities available to bona fide journalists, it cannot deny access arbitrarily or for less than compelling reasons. Denied applicants are entitled to notice of the factual basis for the decision, a chance to respond, and a written statement of reasons.

The Trump administration has argued that these precedent cases were wrongly decided.

Kelly said the media outlets and the three journalists listed as plaintiffs had shown that without the court’s relief, they were likely to suffer irreparable harm, and that at a minimum, their procedural due process claim under the Fifth Amendment had a “likelihood of success.”

Plaintiffs are also likely to succeed in showing that their hard passes were revoked without constitutionally adequate due process.

They did not “receive fair notice” of either the “conduct” that would lead to a sanction or of “the magnitude of the sanction that the White House might impose,” Kelly said.

Balance-of-hardships and public-interest arguments also favor the plaintiffs, Kelly said.

In a filing after the hearing, the government submitted an MS NOW report dated Sept. 23 to support its case. The article claimed that unnamed administration officials were considering attaching Trump’s name to Ford’s Theatre in Washington.

Trump dismissed the report as “a ridiculous lie” in a Sept. 24 post on Truth Social.

Tyler Durden
Thu, 09/24/2026 – 07:20

Poland Suspects “Hybrid Warfare” After Starlink Station Fire As War Spillover Fears Mount

0
Poland Suspects “Hybrid Warfare” After Starlink Station Fire As War Spillover Fears Mount

A fire erupted at a ground-based Starlink communications station in central Poland, raising new concerns about sabotage as spillover risks from the Russia-Ukraine war mount.

Reuters reports that the fire broke out overnight Wednesday at the ground station’s power equipment and generator. The report cited Deputy Prime Minister Krzysztof Gawkowski.

“The fire engulfed the power station and the generator; it is clear that this act of sabotage was deliberately designed to disable the station, effectively cutting off the internet connection… and disrupting internet access for various institutions, including the Ukrainian military,” Gawkowski said.

Gawkowski added, “While everything is operational today, we must recognise, as Prime Minister Tusk recently noted, that this is an element of hybrid warfare.”

Bad actors could’ve targeted the ground station because Ukraine’s military relies heavily on Starlink for battlefield communications, coordinating units and supporting one-way attack drone operations. The internet service, which is repeated from Poland and elsewhere and then beamed down into Ukraine through a network of low Earth orbit satellites, has been critical to Kiev’s war effort.

Beyond Ukraine, US intelligence services warned this week of potential spillover risks from possible Russian operations using Geran long-range attack drones against targets in Spain, France or Italy, according to Euronews.

There were numerous drone incidents targeting Germany’s Leipzig/Halle Airport early last month, with a drone laden with explosives found on the tarmac.

Tyler Durden
Thu, 09/24/2026 – 06:55

60 Minutes’ “Pardon Economy” Bombshell Ignored The Clintons… And Joe Biden

0
60 Minutes’ “Pardon Economy” Bombshell Ignored The Clintons… And Joe Biden

Authored by Paul D. Thacker via RealClearInvestigations,

When Bari Weiss was hired to lead CBS News last year, many of the network’s star reporters feared the centrist founder of The Free Press news site would turn the network into a mouthpiece for the Trump administration. Longtime “60 Minutes” correspondent Scott Pelley was fired after he accused Weiss of “murdering the show.”

If the season premiere of “60 Minutes” is any indication, progressives have little to complain about. In a segment titled “The Pardon Economy,” veteran CBS reporter Lesley Stahl alleges that Trump has upended the way U.S. presidents have dispensed pardons for “100 years or more” by creating a “new system” that involves lobbyists and high-priced “pardon brokers.”

Stahl’s report suggests that Trump has replaced the normal order – in which pardons typically go through an apolitical review by the Justice Department’s Office of the Pardon Attorney – with a scheme that looks like “pay-to-play.” It has already led Democrats to vow they will investigate the issue if they retake the House in the November mid-term elections.

To situate Trump in this “pardon lobbyists” narrative, Stahl links the White House to two convicted con artists who claim close ties to Trump without disclosing one critical detail: There is no evidence the two have ever succeeded in getting anyone a pardon. While their efforts suggest that some in Washington may be trying to capitalize on the narrative about Trump’s alleged corruption – inspired, in part, by questionable pardons he has issued previously – “60 Minutes” offers no concrete proof connecting the administration to these money-making schemes.

Stahl’s report also ignored the long history of wrongdoers paying exorbitant fees for lobbyists to get their pardons viewed by the Oval Office – most famously Bill Clinton’s brother, Roger, and Hillary’s brothers, Hugh and Tony Rodham.

Although Stahl’s report quotes Trump officials denying her claims, a DOJ official who was outraged by her “misleading” report provided RealClearInvestigations with documents showing that well-connected D.C. insiders are routinely involved in the pardon process.

Leaked Documents

The DOJ documents shared with RCI involve the high-profile and controversial pre-emptive pardons issued by President Biden to Trump antagonists on his final day in office in 2025 – specifically top NIH official Anthony Fauci, U.S. Army Gen. Mark Milley, and former Congresswoman Liz Cheney.

The release of pardon documents is highly unusual. Pardon documents are zealously guarded by the White House, in part because they can reveal lobbying and political considerations – the very matter Stahl’s report insinuates is novel under Trump. The official shared them under the condition that screenshots of the documents not be made public out of concern they might anger Trump, who has pushed for criminal investigations of document leaks.

The official noted that there is no evidence that “pardon brokers” put on camera by CBS have influenced the president and said that the documents were being released specifically to show that many pardon recipients retain expensive legal counsel to represent them. And despite the assertion in the “60 Minutes” report that pardons under prior administrations normally required admitting guilt, none of the three – or any of those pardoned by Biden, including his family members – has expressed the slightest contrition.

What the leaked documents – the letters Milley, Cheney and Fauci sent accepting the pardons – do show is that Fauci, Milley, and Cheney were all using the services of high-priced attorneys at politically connected law firms. They do not, however, provide any insight into how the pardons came about. Milley and Cheney’s letters to Biden were sent through attorneys at Williams & Connolly, a top-tier, white-shoe law firm based in Washington, D.C., that has long represented a wide range of powerful Democrats and Republicans.

Now a retired congressional investigator, Jason Foster helped to lead the House investigation of the Clinton pardon scandal. He said the Fauci, Milley, and Cheney pardon papers raise questions about when their attorneys first contacted the Justice Department and the Biden White House about the pardons.

“Based on my experience leading these investigations in the past, this is clearly not a first interaction their attorneys are having with the administration,” Foster said. “This doesn’t mean they’ve done anything wrong, but there’s no constitutional requirement that anyone go through the pardon attorney office.”

First Contact?

Williams & Connolly attorneys did not respond to RCI’s questions asking when they first contacted the Biden administration about pardons for retired General Milley and former Congresswoman Cheney. Nor did they answer questions regarding how much they charged for this work.

Records show that Fauci also had an attorney, David Schertler, send the letter accepting the pardon. That letter, however, was addressed not to the Justice Department, but to Biden’s White House Counsel.

“On behalf of Dr. Anthony S. Fauci, we appreciate the President’s consideration and his action this morning on Dr. Fauci’s behalf,” reads the letter Schertler sent to Edward Siskel, Biden’s top legal advisor. “Dr. Fauci accepts the President’s pardon.”

Fauci emailed the Hill and contacted reporters at Reuters and other outlets that same day, claiming that the White House approached him about the pardon a month prior and that he did not ask for one. He added, “I have committed no crime and there are no possible grounds for any allegation or threat of criminal investigation or prosecution of me.”

At a July Senate hearing, Senator Ashley Moody asked Fauci whether he spoke with President Biden and asked for the pardon. “On the advice of counsel, I respectfully decline to answer based upon my rights under the Fifth Amendment to the Constitution,” Fauci replied. When asked multiple follow-up questions about how he got his pardon, Fauci again asserted his Fifth Amendment rights – as he did to every other question he was asked on a wide range of topics, including the color of his tie.

RCI emailed David Schertler extensive questions, asking when he first contacted the Justice Department and the White House about Fauci’s pardon. RCI also asked about his communications with attorneys in the pardon office and how much his firm charged Fauci for help with the pardon.

Schertler did not respond to RCI’s questions asking when he first contacted the Biden administration about Fauci’s pardon and how much his firm charged the former NIH official for pardon work.

Hidden Cameras

The centerpiece of the “60 Minutes” “pardon lobbyist” segment was an undercover investigation of Jack Burkman and Jacob Wohl, two characters offering to secure pardons for $300,000. But almost every fact detailed by “60 Minutes” on Burkman and Wohl had already been reported six months earlier by The New York Times.

Burkman and Wohl are conservative activists who were convicted of felonies for a robocall scheme to frighten black people against voting by mail in the 2020 presidential election, the Times reported. The two now work as lobbyists who allege special access to Trump and influencers such as Laura Loomer. The Times reporting established that Burkman and Wohl were selling their alleged access to secure pardons. The newspaper, for example, reported on an audio recording in which Burkman said that he and Wohl “use a combination of influencers and members of Congress,” as well as going “direct to the president, and I think that’s a very good approach.”

White House spokeswoman Lauren Bis emailed RCI that the Trump administration has a “robust pardon review process,” and President Trump makes the final decision. “Anyone spending money to lobby for pardons is foolishly wasting their money and the President doesn’t even know who these so-called ‘lobbyists’ are.”

“60 Minutes” also regurgitated details first reported last March in the Times of Burkman’s lobbying for pardons on behalf of nursing home owner Joseph Schwartz, who paid Burkman’s firm almost $1 million, and the rapper Torrence Ivy Hatch Jr., known as Boosie BadAzz, who paid the pair $600,000.

To create TV drama, “60 Minutes” worked with convicted felon Ammon Covino, who met with Burkman and Wohl at the Ritz-Carlton. “60 Minutes” recorded the interaction with hidden cameras. To make Burkman and Wohl look good, Stahl introduced them to listeners as purported accomplished “pardon brokers.”

Although he reportedly paid $600,000 to convicted felons, the rapper known as Boosie BadAzz has not received a presidential pardon.

“They claim they got one for this owner of a nursing home chain convicted of massive tax fraud,” Stahl said. “He paid them nearly a million dollars for their promise to reach the president.”

This is misleading. The Times reported that nursing home owner Joseph Schwartz stopped paying Burkman and Wohl after they failed to get him a pardon, a detail “60 Minutes” seems to have ignored. In fact, there is no evidence that Burkman and Wohl have gotten a pardon for anyone. Instead, Burkman and Wohl make money off felons by promising pardons that never seem to materialize.

RCI sent CBS News an extensive list of questions, noting apparent contradictions in their reporting, such as failing to note that two felons they recorded by hidden camera claiming they can get pardons have never actually gotten anyone a pardon. CBS News did not respond to these questions. A spokesperson sent this statement: “60 MINUTES stands behind our reporting and the investigative work our team did to shed light on the pardons process.”

Instead of advancing a narrative about a “new system” of “pardon lobbyists,” “60 Minutes” seems to have recycled key findings from the Clinton pardon scandal of 2001, while claiming their reporting has uncovered something new and unique about pardons in the Trump administration.

Clinton Pardon Scandals

During his final hours in office, President Bill Clinton signed a flurry of pardons that led to a years-long scandal that found his own brother, Roger Clinton, had accepted hundreds of thousands of dollars to lobby for pardons, as did brothers of first lady Hillary Clinton and an attorney who worked on her Senate campaign that year.

“Pardon for Felon Considered After Kin Paid Roger Clinton,” reported the New York Times in 2001 regarding a $50,000 payment to Roger by the family of Rosario Gambino, a convicted heroin trafficker and reputed organized crime figure. Just as Burkman and Wohl make wild claims of pardon success but never seem to deliver, the Gambino family told the Times that Roger Clinton led them to believe that a pardon for Rosario was a “lock.”

While Roger Clinton failed to get anyone a pardon, House investigators released a 2002 report that found that he accepted hundreds of thousands of dollars to lobby for pardons. However, one person who did succeed in lobbying the Clinton administration for a pardon was Hillary Clinton’s brother, Hugh Rodham.

Two felons – a convicted drug dealer and a businessman who marketed a bogus baldness cure – paid Hugh Rodham a combined $400,000 to get them pardons, which included lobbying White House staff. House investigators found that Rodham’s lobbying efforts also involved telling White House staff that one of the pardons was “very important” to First Lady Clinton.

The House investigation also detailed similar actions by Hillary’s other brother, Tony Rodham, who secured pardons over the objection of the Justice Department by lobbying his brother-in-law, President Bill Clinton: “Tony Rodham lobbied President Clinton to grant pardons to Edgar and Vonna Jo Gregory while he was receiving substantial sums of money from the Gregorys.”

The findings that felons had hired both Bill and Hillary’s family members to lobby the Clinton White House for pardons were widely covered by news outlets, including reporters at CBS News. Stahl joined the CBS News Washington bureau in the early 1970s and moved to “60 Minutes” in 1991, almost a decade before the Clinton scandal became national news. So it’s hard to understand how she missed these details of the Clinton pardon scandal to now claim the Trump administration has created a new “pardon economy,” as “60 Minutes” calls its news segment.

More Trump Probes

Although Stahl’s “60 Minutes” segment did not support its claim that Trump has created a unique new system for pardons, it is already prompting fresh partisan attacks against the president. In an online story that followed the “60 Minutes” piece, CBS News reported that Democrats were alarmed by the undercover video: “Senior Democratic lawmakers vowed Monday to investigate the new market that has sprung up around President Trump’s pardons, citing CBS News video of lobbyists offering to ‘put pressure on the president’ in exchange for a hefty fee from a convicted felon.”

Now the top Democrat on the House Judiciary Committee, Congressman Jamie Raskin will likely lead these investigations. Raskin told CBS News that pardons are “kind of an underground market because not everybody knows how to get to it.”

CBS News failed to report, however, that one of the people who benefited from this underground market was Raskin himself, who Biden pardoned along with Liz Cheney on his final day in office.

Tyler Durden
Thu, 09/24/2026 – 06:30

Escobar: The Calm Before The Showdown

0
Escobar: The Calm Before The Showdown

Authored by Pepe Escobar via LewRockwell.com,

The only art that the Prince must totally master it’s the art of war

– Machiavelli

The Supreme Warrior Wins Without Fighting

-Sun Tzu

This was supposed to be the calm before the storm. Where the Epstein Syndicate would schmooze the Global South gathered in New York for the – comatose – UN General Assembly and seduce them with assorted “gifts”, wooing them away from the impending Great Debacle and deflecting attention from the breathtaking speed of the collapse of Pax Americana.

Cut to Wednesday, when we have Day One of the UN General Assembly Debate, with Neo-Crassus/Neo-Caligula/Goldfinger/Psycho Toddler supposed to deliver a speech.

On the same day, he meets with the Gulf petro-sheiks for what could become some sort of suicidal pact.

And then on Friday, Xi Dada in person comes to the U.S. on an official state visit. (Invisible) sparks are guaranteed to fly.

All that would guarantee that the nearly inevitable New Demented Offensive on Iran and the Axis of Resistance might be postponed for a few days.

But then hysteria re-reigned all over again, as panicked imperial stakeholders were faced with some startling facts on the ground, from zero Saudi oil exports and to “burn, baby burn” at Riyadh airport.

Cue to the thundering sound of scurrying bling bling cockroaches. They seem to realize that hitting Iran again, now, is beyond dangerous, as the escalation ladder will go totally out of control – complete with Tehran finishing off the scared-to-death petro-sheikhs.

So the cockroaches did find out, the hard way, that whatever happens Iran is bound to become the oil hegemon of the Persian Gulf.

Cue to Pakistan and Turkiye – the other two members of the dodgy as hell Mecca Defense Alliance – freaking out in tandem, promising to defend Saudi Arabia even physically.

For context, cut to Ansarallah spokesman Mohammad Al-Bukhaiti:

“By God, if Turkey or Pakistan get involved, we will strike them with an iron fist. And just as we are disciplining Saudi Arabia today, we will discipline them as well.”

That was the polite advice from the elder al-Bukhaiti. The younger, Hussain, a journalist, was way more heavy metal: if Pakistan attacks Yemen, Yemen will not allow any Pakistani commercial ship to pass through the Red Sea; will launch a direct attack on Pakistan; and will consider Pakistan a Zionist partner.

How the House of Saud is going down

It’s now Escalation Ladder A-Go-Go. The Energy Shock’n Awe is at hand. All buffers are gone; the U.S. Strategic Petroleum Reserves (SPR); the Saudi East-West pipeline (for at least a month, maybe more); and China’s methodical, hefty cut on oil imports.

What’s left is the UAE’s Fujairah – moving only 2 million barrels a day. But if the U.S. attacks the Axis of Resistance, that will also be gone in a flash.

Saudi Arabia cannot export oil and/or gas. So there’s only one way out to Clumsy Lone Decider MbS; to surrender. Accept Yemen’s terms. And expect the bill to include the 3 southern provinces stolen by the Brits and given to the Saudis in 1934.

No surrender means the very slim possibility of the House of Saud surviving at all.

Alastair Crooke, in fine form, nailed it to perfection. The Ansarallah/Yemeni Armed Forces lightning-fast campaign had been planned for as long as 7 years. Sana’a takes a very long view. This represents total Yemen ownership of the process; but with an outcome completely aligned with Tehran.

There’s a stunning parallel with Afghanistan 5 years ago – a story I followed in detail. The then Ghani puppet government collapsed in only 10 days because of patient Pashtun tribal interconnection conducted under the aegis of Gen. Soleimani.

Now it’s the same process, involving tribal Arabian leaders. It’s an easy sell. The mongrel “Saudi” state was built around an ultra-sectarian Wahhabi nucleus, a bunch of illiterate camel-herding Bedouins, with a single family monopolizing the money, political power and all decisions.

Many of roughly 100 tribes will have no trouble to become part of a process of folding the Kingdom into what could be called the Iran-Ansarallah compound. They will take back their oil; Arabia then will no longer be reduced to an American replacement of Persian power; and that will be the end of the free lunch for U.S. oil companies. China cannot but approve this vision.

The petro-sheiks have chosen their table

Sana’a did send a clear message to the U.S. via Oman. Yemen would only attack Saudi shipping – and not American or international shipping. That stands as long as Washington does not attack Yemen. Yet if that happens, Yemen obliterates the American base in Djibouti, essential for surveillance of the whole Horn of Africa.

The key question now is whether the U.S. – and the Mecca pact – really dumped Saudi Arabia. Or if this is just a realignment fog before a concerted attack – GCC included – on Ansarallah.

If that happens, Tehran has made it crystal clear it will strike U.S. military and commercial assets all across the Gulf, especially in the UAE and Saudi, and all the way to Iraq.

Major General Mohsen Rezaee, secretary of the Supreme National Security Council in Iran, and Leader Mojtaba Khamenei’s personal representative, provided the context with a single sentence:

“We invited them [GCC nations] to the Salalah meeting [in Oman]…and they reciprocated with a secret meeting in Germany with the U.S. Central Command and Israel.”

It’s all here. Iran invited the GCC petro-sheiks to a common regional table. The GCC instead chose the Washington/Tel Aviv table.

Rezaee has also outlined how Iran upgraded supersonic missiles from Mach 6 to Mach 10; expanded electronic warfare and air defenses; and is now able to hit U.S. vessels anywhere in the – distant – Indian Ocean.

Then there’s that ship-targeting missile that splits into 80 projectiles tested – successfully – on a U.S. aircraft carrier. The Pentagon is mum on the subject.

Rezaee, in more ways than one, has gently advised the U.S. Navy to get out of Dodge – as in the Indian Ocean – before sparks fly again.

Cue once again to the young al-Bukhaiti:

“A major escalation by Saudi Arabia is expected in the coming day or days… It will be met with a surprise retaliatory response that will make Saudi Arabia and its allies forget that they lost Mocha and Bab al-Mandab.”

So the Epstein Syndicate may have planned for a solo op on Yemen, just to find out that Iran and Yemen come as a package.

Respect Iran’s terms. Or else.

Tehran conveyed its new terms to the U.S. through Qatar, even as Rezaee continues to define “the respected Pakistani government” as a steady consultation partner.

The terms include the release of frozen assets and the end of the Trump naval blockade. Rezaee said there are 7 conditions, but he disclosed only 6. The list did not include “removal of economic sanctions”. The public first item is “an end to the war on all fronts.”

That is exactly what was written at the start of the dead cat MoU.

The June memorandum of understanding already contained crude-export waivers and a no-new-sanctions clause.

Then there’s the Strait of Hormuz reciprocation. That is part of Tehran’s bargaining structure. Rezaee said Iran is “a short step” from announcing a Hormuz management deal with Oman that may need regional endorsement.

A Tasnim-sourced description calls the arrangement “a step towards Iran exercising sovereignty over the Strait”. In parallel, Foreign Minister Araghchi told his counterpart and friend Wang Yi in Beijing that Iran “has reached a plan with Oman to open the Strait.” Then Ghalibaf repeated on Sunday that the Strait of Hormuz stays closed until Iran’s conditions are met.

Washington’s answer, on Sunday, was demented rhetoric – as usual. Neo-Crassus/Psycho Toddler told Fox News he is in “deciding mode”. And then he came up with an intergallactic howler: he’s deciding “if and when do I blow the entire nation up”.

No comments necessary.

He has essentially three options.

1. Renewed strikes.

2. Let Iran “rot” economically (that’s the plan for now).

3. A deal.

In an access of common sense, he also said he would “probably be open” to meeting President Pezeshkian at the UN General Assembly.

Iran’s Armed Forces, for their part, claimed they have intel that Washington has decided “with the green light from certain regional countries” to resume action and threatened “continuous, effective and painful strikes.”

When it comes to the Big Picture, Pakistan insisted there is no military response under discussion regarding Yemen. Türkiye “does not want to enter the fray”. Still, Pakistan’s military spokesman has pledged to go “to any extent”, and the Foreign Office confirmed “some deployments” under the Mecca Defense Alliance. Insiders in Islamabad swear this is only for show: Pakistan cannot afford to be dragged into a war against Ansarallah.

The heart of the matter is that the Epstein Syndicate simply cannot afford not (italics mine) to make a move. Consider the dire circumstances: they already connot control currency collapse, food supply chain elimination and widespread lack of oil/diesel. They need massive diversionist tactics.

Meanwhile, Yemen’s revolutionary surge accelerates the timetable to the showdown. While Iran concentrates on ensuring a definitive neo-Crassus/Goldfinger/Psycho toddler mid-term debacle, in tandem with honing its new offensive doctrine: as in being ready to preemptively strike at any sign of U.S. rumblings.

It’s nearly impossible to draw reason out of an illogical geopolitical universe where nothing matters and the Hegemon is totally out of control. Yet we persist.

We are all riders on the (coming) storm.

Pepe Escobar is an independent geopolitical analyst and author. His latest book is Raging Twenties. He’s been politically canceled from Facebook and Twitter. Follow him on Telegram.

We publish a variety of perspectives. Nothing written here is to be construed as representing the views of ZeroHedge.

Tyler Durden
Thu, 09/24/2026 – 05:00