62.3 F
Chicago
Monday, September 21, 2026
Home Blog Page 2697

Falling Bond Yields Show It’s Crunch Time In China

Falling Bond Yields Show It’s Crunch Time In China

Authored by Simon Black, Bloomberg macro strategist,

Sovereign yields in China have been falling in recent months, in marked contrast to almost every other major country. This is a key macro variable to watch for signs China is ready to ease policy more comprehensively as its tolerance is tested for an economy that is becoming increasingly deflationary. Further, vigilance should be increased for a yuan devaluation. Though not a base case, the tail-risk of one occurring is rising.

Year of the Dragon in China it may be, but the economy has yet to exhibit the abundance of energy and enthusiasm those born under the symbol are supposed to possess. China failed to exit the pandemic with the resurgence in growth seen in many other countries, and the outlook has been lackluster ever since.

But we are entering the crunch phase, where China needs to respond forcefully, or face the prospect of a protracted debt-deflation. The signal is coming from falling government yields. They have been steadily falling all year, at a faster pace than any other major EM or DM country. Indeed yields have been rising in almost every other country.

That’s a problem for the yuan. The drop in China’s yields is adding pressure on the currency. Widening real-yield differentials show that there remains a strong pull higher on the dollar-yuan pair.

The question is: will this prompt a devaluation in the yuan? The short answer is less likely than not, but it can’t be discounted, and the risks are rising as long as capital outflows continue to climb.

We can’t measure those directly in China as the capital account is nominally closed. But we can proxy for them by looking at the trade surplus, official reserves held at the PBOC, and foreign currency held in bank deposits. The trade surplus is a capital inflow, and whatever portion of it that does not end up either at the PBOC or in foreign-currency bank accounts we can infer is capital outflow.

This measure is rising again, as more capital typically tries to leave the country when growth is sub-par, as it is today.

So far, China appears to be managing the decline in the yuan versus the dollar. USD/CNY has been bumping up against the 2% upper band above the official fix for the pair. But China is stabilizing the yuan’s descent through the state-banking sector. As Brad Setser noted in a recent blog, the PBOC has stated that it has more or less exited from the FX market. Instead, that intervention now takes place unofficially using dollar deposits held at state banks.

China has plenty of foreign-currency reserves to stave off continued yuan weakness (more so than is readily visible, according to Setser), but there is always the possibility policymakers decide to ameliorate the destructive impact on domestic liquidity from capital outflow by allowing a larger, one-time devaluation. There is speculation this is where China is headed, and that it is behind its recent stockpiling of gold, copper and other commodities.

However, there are risks attached to such a move, given it might be detrimental to the more normalized markets that China covets in the name of financial stability, as well potentially prompting a tariff response from the US.

A devaluation is a low, but non-zero, possibility that has risen this year. Either way, the drop in bond yields underscores that China will soon need to do something more dramatic to avert the risk of a debt deflation.

In the past, the current rate of decline in sovereign yields has led to a forthright easing response from China, with a rise in real M1 growth typically seen over the next six-to-nine months.

But M1 growth in China has singularly failed to bounce back so far despite several hints that it was about to. This is likely a deliberate policy choice as rises in narrow money are reflective of broad-based “flood-like” stimulus that policymakers in China have explicitly ruled out as recently as January, in comments from Premier Li Qiang. Policymakers are laser-focused on not re-inflating the shadow-finance sector, which continues to be squeezed.

Shadow finance led to unwanted speculative froth in markets, real estate and investment that China does not want to see reprised. But its curbs have been too successful. Credit remains hard-to-get where it is needed most, typically the non state-owned sectors.

The slowdown this fostered was amplified by China’s response to the pandemic. Rather than supporting household demand, policymakers in China supported the export sector, leading to a surge in outward-bound goods.

Stringent lockdowns prompted households to become exceptionally risk averse, increasing their savings, and being reluctant to spend even after restrictions were lifted, lest the government decided to paralyze the economy again at some future time.

This also caused the real estate sector to implode, prompting multiple piecemeal easing measures to support housing prices and indebted property developers, to little avail so far: leading indicators for real estate such as floor-space started remain muted or weak, while the USD-denominated debt of property companies continues to trade at less than 25 cents in the dollar.

China has a large and growing debt pile that is only set to get worse as its demographics continue to deteriorate. The alarming chart below from the IMF projects public debt (including local government financing vehicles) in China to accelerate way ahead of that in the US in the coming years, to around 150% of GDP by the end of the decade. Total non-financial debt is already closing in on 300% of GDP.

Source: IMF

This raises the risk of a debt-deflation, when the value of assets and the income from them fall in relation to the value of liabilities. Debt becomes increasingly difficult to service and pay back, leading to lower consumption and investment, entrenched deflation and derisory growth that is difficult to escape.

Woody Allen once quipped that mankind is at a crossroads, one road leads to despair and utter hopelessness and the other to total extinction. China’s choices are not yet that stark, but the longer it waits to deliver an emphatic response to its predicament, they may soon become that way.

Tyler Durden
Thu, 04/25/2024 – 10:30

BHP Proposes $39 Billion Takeover Over Anglo To Form Copper Mining Giant

BHP Proposes $39 Billion Takeover Over Anglo To Form Copper Mining Giant

The world’s largest global diversified miner, BHP Group, is making a monster bet on surging future copper demand with the proposed takeover of Anglo American Plc. The bet is based on the thesis that the world’s power grids need a major overhaul and that the electrification of the economy will unleash new demand for base metals. This also comes as market observers have warned about an impending shortfall of global copper mining supply.

According to Bloomberg, BHP proposed an all-share deal valued at £31.1 billion ($38.9 billion). The transaction depends on Anglo spinning off its South African iron ore and platinum businesses to its shareholders. The offer is conditional and non-binding at £25.08 a share, or about a 14% premium to Anglo’s closing share price on Wednesday. 

Anglo shares in London jumped 13% to £24.89, giving the company a market capitalization of about £30.5 billion. 

BHP’s proposed acquisition of Anglo would dwarf its 2023 takeover of Australian copper producer OZ Minerals. The top miner believes copper demand will double over the next three decades. 

Copper is a critical base metal for infrastructure and renewable energy. BHP bets that the world’s power grids must be upgraded as fossil fuel demand slides and the global economy’s electrification ramps up. 

If the deal closes, BHP will become the world’s biggest copper producer (controlling roughly 10% of the global copper mining supply), which comes as some market observers are warning about supply shortfalls

About a year ago, billionaire mining investor Robert Friedland explained to Bloomberg TV in an interview that copper prices are set to soar because the mining industry is failing to increase supply ahead of ‘accelerating demand.’ He warned

“We’re heading for a train wreck here.” 

Friedland is the founder of Ivanhoe Mines Ltd. He continued, “My fear is that when push finally comes to shove,” copper prices might explode ten times. 

Jefferies’ commodity desk recently warned, “Disruptions have significantly increased, and a market deficit is now increasingly likely. We could be at the foothills of the next copper cycle.”

BofA recently warned, “The copper supply crisis is here.” 

Let’s not forget about our note titled “The Next AI Trade,” which explains the investment opportunities in upgrading the nation’s grid as generative AI data centers increase power demand. 

And Jefferies is on it: “Copper Demand in Data Centers.” 

Back to BHP, the company said in a statement to London Stock Exchange that the takeover would increase its “exposure to future-facing commodities through Anglo American’s world-class copper assets” as well as “complementing BHP’s iron ore and metallurgical coal portfolios.” 

Jefferies analysts commented on the proposed takeover, indicating BHP might face competition in its pursuit of Anglo. 

“Our analysis suggests that Anglo consists of an undervalued portfolio of multiple tier 1 assets several of which are in low-risk jurisdictions (Australia, Chile, Peru and Brazil),” Jefferies said.

Jefferies Christopher LaFemina said:

“We would be surprised if this is BHP’s final offer,” adding, “We estimate that a price of at least £28/sh would be necessary for serious discussions to take place, and a takeout price of well above £30 per share would be the outcome if other bidders were to get involved.”

A successful takeover would mark the first mega mining deal in more than a decade and signify the importance of critical metals and their use in upgrading the world’s power grid. 

Tyler Durden
Thu, 04/25/2024 – 10:15

Wall Street Reacts To Today’s Stagflationary Data Dump

Wall Street Reacts To Today’s Stagflationary Data Dump

After today’s stagflationary GDP print, which came below the lowest Wall Street estimate even as core PCE came in above the highest estimate

… there has been an outcry of horror from Wall Street’s traders, analysts and strategists as the BEA once again steamrolled all over Wall Street’s benevolent forecasts for a soft, or no, landing and crash-landed right into stagflation nation.

Below we excerpt from some of the most notable kneejerk responses and comments:

Ian Lyngen at BMO Capital Markets, on the potential implication of the core PCE inflation gauge this morning on tomorrow’s monthly release:

“The question has quickly become whether this is due to revisions from Jan/Feb or if tomorrow’s monthly core-PCE report will reveal a stronger-than-consensus (+0.3%) print.”

Ira Jersey, Bloomberg Intel chief Rates strategist

“The rate market is keenly focused on the PCE deflator beating expectations in 1Q. We still target 4.70% as a key technical level for 10-year Treasury yield. A break of that targets the cycle highs around 5%.”

“It looks like the fiscal drag on the economy may have begun with federal government consumption actually a drag on GDP this quarter. Not huge, but any negative print is still a shift from the past few years. But 2.5% consumption growth still isn’t anywhere near recession, and services consumption growing at 4% suggests a more pronounced slowdown could be a long way off.”

Sebastian Boyd, Bloomberg analyst

Bond traders can read the GDP data in two ways. The growth number was a big miss, but prices rose faster than expected. Of course this is the first pass at the data, but if it holds up then it shows the US economy is considerably weaker than thought, which would open the way to earlier interest rate cuts. On the other hand, the Fed is more likely to focus on inflation than growth, and the price index, especially the core price index, doesn’t offer any comfort on that front. Two-year yields initially fell, but are now much higher on the day. Stock futures are down; the dollar is spiking. Keep an eye on the yen.

Lindsay Rosner, head of multisector fixed income investing at GSAM

“The report has a disappointing headline and consumption line item, but at this point, inflation concerns weigh more than GDP softness for the Fed.”

Quincy Krosby, Chief Global Strategist at LPL Financial:

“The softer first read of Q1 GDP could shift — again- the Fed’s timetable for initiating the rate easing cycle, with July coming back into play. If the PCE report due tomorrow similarly suggests the downward path of inflation has begun to once again momentum, it could serve as a catalyst for the market.”

Dan Suzuki, deputy CIO at Richard Bernstein Advisors,

“The GDP print is not as bad a print as it appears on the surface.  The main drags were in goods demand (which we already knew based on the manufacturing PMIs), government spending and exports. I think it was actually pretty encouraging to see solid investment spending in both capex and housing, while weaker net exports reflect the robust domestic demand for imports, even as economic growth outside the US has been a bit more tepid.”

Enda Curran, Bloomberg Fed watcher and commentator

“The other political takeaway from today’s data is that just six months out from the presidential election, it looks like the economy is finally slowing down. The details of the data are overall robust — but it’s the headline that counts for politicos.”

Rubeela Farooqi, chief US economist at High Frequency Economics:

“The outlook going forward is uncertain. Strength in the labor market is likely to keep household spending and growth positive for now. However, a delay in Fed rate cuts to counter sticky inflation could be headwinds for consumption and the growth trajectory over coming quarters.”

Olu Sonola, head of US economic research for Fitch Ratings:

“The hot inflation print is the real story in this report. If growth continues to slowly decelerate, but inflation strongly takes off again in the wrong direction, the expectation of a Fed interest rate cut in 2024 is starting to look increasingly more out of reach.”

Jan Hatzius, Goldman economist

Real GDP rose 1.6% annualized in the advance reading for Q1 (qoq ar)—0.9pp below consensus and the first quarter below 2% since the second quarter of 2022. The composition was not as soft, as the contribution from inventories (-0.4pp vs. GS +0.2pp) and foreign trade (-0.9pp vs. -0.4pp) accounted for the bulk of the miss. Indeed, domestic demand growth proceeded at a strong pace of +2.8% annualized. This reflected a double-digit pace of residential investment growth (+13.9%) and solid growth in consumption (+2.5%) and business fixed investment (+2.9%), the latter reflecting gains in two of the three capex subcategories (equipment +2.1%, intellectual property +5.4%, structures -0.1%). Government spending growth slowed more than we expected to +1.2% (vs. GS +1.9% and Q4 +4.6%), reflecting a surprising decline in federal (-0.2%) and a smaller-than-forecast rise in state and local (+2.0%) spending.

Alan Detmeister, UBS economist

We had 3.5% so were slightly less surprised than the consensus. The months that go into the Q1 number released today will be used in the 12-month change on Thursday, however the weighting across those months is quite different with the January monthly change getting much more weight in today’s quarterly number than it does in the 12-month change released tomorrow (and the opposite for the March monthly change). Nonetheless the 0.2pp upward surprised on the annualized Q1 core PCE price change definitely increases the risk of an upward surprise to the 12-month change tomorrow. (Treating months equally it would suggest tomorrow’s estimate of the 12-month change around 5bp higher than what we have.)  It is more difficult to say anything on the March monthly because it is quite possible that today’s surprise was upward revisions to January or February, so again today’s data raises the upside risk on March, but hard to say how much.

Source: Bloomberg

Tyler Durden
Thu, 04/25/2024 – 10:07

US Pending Home Sales Rise In March, But…

US Pending Home Sales Rise In March, But…

After new home sales soared (thanks to prior downward revisions) and existing home sales plunged in March (along with the collapse in housing starts and permits in March), this morning’s pending home sales data was expected to rise very modestly MoM (less than in February) but remain lower on a YoY basis.

In an odd turn of events, pending home sales beat on a MoM (SA) basis (+3.4% vs +0.4% exp) but missed on a YoY (NSA) basis (-4.5% vs -3.0% exp). Sales were up 0.1% YoY on a seasonally-adjusted basis…

Source: Bloomberg

This is the 28th straight month of YoY declines for non-seasonally-adjusted pending home sales.

That leaves pending home sales hovering just off record lows…

Source: Bloomberg

The gains were led by the South and the West, and, to a lesser extent, the Northeast, with the MidWest seeing sales slump 4.3$ MoM. All regions are lower on a YoY basis.

While the pending-sales index reached a high point, “it still remains in a fairly narrow range over the last 12 months without a measurable breakout,” NAR Chief Economist Lawrence Yun said in a statement.

“Meaningful gains will only occur with declining mortgage rates and rising inventory.”

And given the tight correlation with mortgage rates, it looks like pending home sales are set to continue their downward slope…

Source: Bloomberg

As a reminder, the pending-home sales report is a leading indicator of existing-home sales given houses typically go under contract a month or two before they’re sold.

Tyler Durden
Thu, 04/25/2024 – 10:06

US Births Alarmingly Slide To Lowest Level Since 1979, Failing To Exceed Replacement Rate Since Before GFC

US Births Alarmingly Slide To Lowest Level Since 1979, Failing To Exceed Replacement Rate Since Before GFC

“There are certainly some big risks that humanity faces. Population collapse is a really big deal, but I wish more people would think about…the birth rate is far below what’s needed to sustain civilization at its current level,” Elon Musk explained in a recent interview posted on X.  

Musk wrote in a post on X early last week, “Any nation with a birth rate below replacement will eventually cease to exist.” 

This leaves us with a new report from the US National Center for Health Statistics showing US births continued a multi-decade slide to levels not seen in more than four decades. 

There were 3.59 million babies born in 2023, down 2% from 3.66 million recorded in 2022. This number is the lowest since 1979, when 3.4 million babies were born. 

“People are making rather reasoned decisions about whether or not to have a child at all,” Karen Benjamin Guzzo, director of the Carolina Population Center at the University of North Carolina at Chapel Hill, said, who was quoted by The Wall Street Journal

Guzzo continued, “More often than not, I think what they’re deciding is, ‘Yes, I’d like to have children, but not yet.'”

America’s declining total fertility rate peaked at 3.75 births per woman after World War II and has since collapsed to about 1.617, well below the replacement rate of 2.1. 

Source: The Wall Street Journal

A nation without children is a nation without a future. The intersection of deaths exceeding births per year appears imminent. 

Source: The Wall Street Journal

US birth rates for most age groups are all declining, except for women ages 35-39 and 40-44. 

Source: The Wall Street Journal

Only the Hispanic fertility rate has rebounded. 

Source: The Wall Street Journal

With the total birth rate well under the level of replacement since 2007, it should now make sense (read here) why the Biden administration has facilitated the greatest illegal alien invasion this nation has ever seen. 

Tyler Durden
Thu, 04/25/2024 – 07:45

Silicon Valley Artificial Intelligence Is Running On Eastern Coal

Silicon Valley Artificial Intelligence Is Running On Eastern Coal

Authored by John Seiler via The Epoch Times,

When your cell phone gets hot, that means its processors are computing faster or you have a lot of apps open. The same is true for “server farms,” which Gigabyte.com explains are “a large number—up to thousands—of servers grouped together to provide better functionality and accessibility.”

It takes a lot of energy to run those hot servers and air-conditioning to keep them cool. Artificial intelligence (AI) requires even more servers and energy.

As The Real Deal reported, “Silicon Valley vies with SF as ‘AI capital of the world.’” So far, California remains ahead of everyone else, including Communist China, in the race for AI dominance.

So where would San Francisco and Silicon Valley AI companies, conscious of the need for energy from such renewable sources as wind and solar power, get the energy for their AI servers? Surely from California energy companies, especially Northern California’s PG&E?

Actually, there’s another, unexpected, source:

“Internet data centers are fueling drive to old power source: Coal,” headlined the Washington Post on April 17. Datelined Charles Town, W.Va., it reported surveyors are “eyeing space for yet another power line next to the property—a line that will take electricity generated from coal plants in the state to address a drain on power driven by the world’s internet hub in Northern Virginia 35 miles away.

There, massive data centers with computers processing nearly 70 percent of global digital traffic are gobbling up electricity at a rate officials overseeing the power grid say is unsustainable unless two things happen:

1. Several hundred miles of new transmission lines must be built, slicing through neighborhoods and farms in Virginia and three neighboring states.

2. And antiquated coal-powered electricity plants that had been scheduled to go offline will need to keep running to fuel the increasing need for more power, undermining clean energy goals.”

Note the number: 70 percent of global digital traffic.

This is being processed in Northern Virginia, the center of the U.S. government and a major location for these server farms.

Silicon Valley Hypocrisy

This affirms what I have written several times in The Epoch Times: The world isn’t following California’s obsession with ending all reliance on carbon-based energy.

Communist China certainly isn’t, as I detailed recently in, “‘Green Innovation’ Study Shows California CO2 Policies Mainly Help China.”

Now it’s obvious our own globe-leading computer, internet, and AI industries are not following that anti-progress development, either. That’s despite almost all of Silicon Valley and San Francisco backing Gov. Gavin Newsom and his mandate to achieve 100 percent zero-emission vehicles by 2035.

In his 2022 reelection, Mr. Newsom, a Democrat, received 59.2 percent statewide to 40.8 percent for Republican opponent Brian Dahle. But Mr. Newsom garnered 85.4 percent in San Francisco. And for Silicon Valley, it was 75 percent in San Mateo County and 70 percent in Santa Clara County.

In the 2020 presidential election, President Joe Biden grabbed 63.5 percent statewide to 34.3 percent for former President Donald Trump. But President Biden got 85.3 percent in San Francisco, 77.9 percent in San Mateo County, and 72.7 percent in Santa Clara County.

By contrast, in West Virginia, President Biden won just 29.7 percent to former President Trump’s 68.6 percent.

Silicon Valley might back green energy, but its business benefits from coal. The reason it can advance this hypocrisy is because of the vast network of fiberoptic cables crisscrossing the country. They hook up everything from computer companies to all kinds of businesses, and probably the computer network in your home. I’m writing this using Google Fiber.

TechTarget explains, “Fiber optics, or optical fiber, refers to the technology that transmits information as light pulses along a glass or plastic fiber.” And light, of course, travels at the speed of light: 299,792,458 meters, or 186,000 miles, per second.

The whole world also is entwined in fiberoptic cables, as well as signals from satellites. So computer servers are all around the world. But it makes sense for Silicon Valley and San Francisco companies to plant their servers in the United States, because our country is well-defended by the U.S. military.

Since the cables between California and West Virginia traverse our vast continent, they can’t be cut by a foreign sea power like undersea cables.

Computer Money Talks

As the Washington Post reported, coal use to generate power continues, even in Virginia, despite the state “fully embracing” clean energy. The server farms bring in massive revenues to local governments from the state’s property tax, which applies to land and equipment.

With Amazon Web Services pursuing a $35 billion data center expansion in Virginia, rural portions of the state are the industry’s newest target for development.

“The growth means big revenue for the localities that host the football-field-size buildings. Loudoun collects $600 million in annual taxes on the computer equipment inside the buildings, making it easier to fund schools and other services. Prince William, the second-largest market, collects $100 million per year.”

President Biden won Virginia 54.4 percent to 44.2 percent for former President Trump. But President Biden won Loudon County with 61.9 percent and Prince William County with 62.8 percent.

Northern Virginia might be liberal Democratic now. But as in California, green activists walk, but AI money talks.

Tyler Durden
Thu, 04/25/2024 – 07:20

To Appease Environmentalists, The FTC Will Cripple U.S. Energy

To Appease Environmentalists, The FTC Will Cripple U.S. Energy

Authored by Justin Bis via RealClear Markets,

In the movie The Perfect Storm, George Clooney and Mark Wahlberg are among the crew of a boat off the Northeast coast that is caught in the convergence of multiple powerful storms. The combination of tempests ultimately takes down the craft and its crew. We should all hope one of our nation’s most vital industries doesn’t succumb in similar fashion as it is caught in a perfect storm of ideological rigidity, bureaucratic arrogance, and regulatory overreach.

From fueling cars to heating homes to providing raw materials for much of the stuff that makes modern life possible, the oil and gas industry is indispensable to economic activity and comfortable living. Significant disruptions to the smooth functioning of the industry could have ripple effects throughout the entire economy, impacting businesses and consumers alike. At a time when inflation remains stubbornly high, the industry is a bright spot in the U.S. economy. Spurred on by technological development, abundant natural resources, and a dynamic market built upon the rule of law, America’s energy industry is undergoing a major renaissance. Despite political assaults grounded in the Biden administration’s hostility to fossil fuels, it remains the world’s largest supplier fuel supplier. But hasty and politically motivated FTC investigations, cheered on by allies in Congress, could erode progress and prosperity.

The FTC is currently blocking at least four mergers and acquisitions in the industry – between Chesapeake Energy and Southwest Energy, Chevron and Hess, Exxon and Pioneer Natural Resources, and Occidental and Crown Rock. The allegation is that mergers of these American companies would limit competition and hurt consumers. Count me unconvinced. The only unusual aspect of these deals is the lengths the FTC is willing to go to stop them. For an example of the unprecedented nature of this obstruction, Occidental (or “Oxy”) completed an acquisition valued at $57 billion less than four years ago gaining FTC approval about one month after it was announced. The FTC has now delayed Oxy’s deal with Crown Rock, which is less than one-fourth the size of the earlier acquisition, for more than six months. And there appears to be no light at the end of the tunnel.

These deals present the perfect opportunity for opposition based on the convergence of the storms of the Biden administration’s desire to accelerate a transition away from oil and gas, whether consumers want it or not, with the FTC’s efforts to entertain novel theories and to push the bounds of the law in order to amass even more power. As the Wall Street Journal recently revealed, “Some staff think failure in court may even be Ms. Khan’s goal. As one wrote: ‘I’m not sure being successful (or doing things well) is a shared goal, as the Chair wants to show that we can’t meet our mission mandate without legislative change.’” As the Journal’s editorial board opined, “This isn’t the role of the FTC, which is supposed to follow the law that Congress has already written.”

Blocking deals will send shockwaves throughout energy and capital markets and signal once and for all that America’s flirtation with energy independence is coming to an ignominious end. Most importantly, the decline of the oil and gas industry would be disastrous for the American people. The industry supports more than 10 million jobs in the United States.  The product: cheap, reliable, and local energy is critical to American manufacturing and to the high standard of living we all enjoy. Beyond America’s shores, the export of liquified natural gas is decoupling European and Asian countries from the grips of authoritarian Russia and China. A robust oil and gas industry makes America wealthier, safer, and promotes peace abroad.

Rather than fostering competition and protecting consumers, the FTC’s wonton use of authority stifles innovation, threatens American security, and undermines the vitality of a critical sector of our economy. Instead of focusing on unnecessary market interventions, policymakers should prioritize policies that promote innovation, encourage investment, and ensure a level playing field for all participants in the oil and gas industry. My organization, the Financial Fairness Alliance, is dedicated to informing the public on what their government is really doing.  Our goal is to uncover attempts from unelected bureaucrats to rig markets in favor of the politically connected.  In this vein, the FTC’s intervention in oil and gas mergers should be viewed with great scrutiny by the American public.  FTC Chair Lina Khan promised to Republican senators to be a fair and an independent minded regulator.  We will soon find out if this was an empty promise.

Justin Bis is the Director of the Financial Fairness Alliance. He has held senior government roles, including at the White House and the U.S. Department of Energy, where he assisted with recruiting top-level governmental leaders responsible for regulating the U.S. financial and energy markets.

Tyler Durden
Thu, 04/25/2024 – 06:30

Cashless Society: WEF Boasts That 98% Of Central Banks Are Adopting CBDCs

Cashless Society: WEF Boasts That 98% Of Central Banks Are Adopting CBDCs

Whatever happened to the WEF?  One minute they were everywhere in the media and now they have all but disappeared from public discourse.  After the pandemic agenda was defeated and the plan to exploit public fear to create a perpetual medical autocracy was exposed, Klaus Schwab and his merry band of globalists slithered back into the woodwork.  To be sure, we’ll be seeing them again one day, but for now the WEF has relegated itself away from the spotlight and into the dark recesses of the Davos echo chamber. 

Much of their discussions now focus on issues like climate change or DEI (Diversity, Equity, Inclusion), but one vital subject continues to pop up in the white papers of global think tanks and it’s a program that was introduced very publicly during covid.  Every person that cares about economic freedom should be wary of Central Bank Digital Currencies (CBDCs) as perhaps the biggest threat to human liberty since the attempted introduction of vaccine passports.

The WEF recently boasted in a new white paper that 98% of all central banks are now pursuing CBDC programs.  The report, titled ‘Modernizing Financial Markets With Wholesale Central Bank Digital Currency’, notes:

“CeBM is ideal for systemically important transactions despite the emergence of alternative payment instruments…Wholesale central bank digital currency (wCBDC) is a form of CeBM that could unlock new economic models and integration points that are not possible today.”

The paper primarily focuses on the streamlining of crossborder transactions, an effort which the Bank for International Settlements (BIS) has been deeply involved in for the past few years.  It also highlights an odd concept of differentiated CBDC mechanisms, each one specifically designed to be used by different institutions for different reasons.  Wholesale CBDCs would be used only by banking institutions, governments and some global corporations, as opposed to Retail CBDCs which would be reserved for the regular population.

How the value and buying power of Wholesale CBDCs would differ is not clear, but it’s easy to guess that these devices would give banking institutions a greater ability homogenize international currencies and transactions.  In other words, it’s the path to an eventual global currency model.  By extension, the adoption of CBDCs by governments and global banks will ultimately lead to what the WEF calls “dematerialization” – The removal of physical securities and money.  The WEF states:

“As with the Bank of England’s (BOE) RTGS modernization programme, the intention is to introduce a fully digitized securities system that is future-proofed for incremental adoption of DLT (Distributed Ledger Technology). The tokenization of assets involves creating digital tokens representing underlying assets like real estate, equities, digital art, intellectual property and even cash. Tokenization is a key use case for blockchain, with some estimates pointing towards $4-5 trillion in tokenized securities on DLTa  by 2030.” 

Finally, they let the cat out of the bag:

“The BIS proposed two models for bringing tokenization into the monetary system: 1) Bring CBDCs, DTs and tokenized assets on to a common unified ledger, and 2) pursue incremental progress by creating interlinking systems.

They determined the latter option was more feasible given that the former requires a reimagination of financial systems. Experimentation with the unified ledger concept is ongoing.”

To interpret this into decoded language – The unified ledger is essentially another term for a one world digital currency system completely centralized and under the control of global banks like the BIS and IMF.  The WEF and BIS are acknowledging the difficulty of introducing such a system without opposition, so, they are recommending incremental introduction using “interlinking systems” (attaching CBDCs to paper currencies and physical contracts and then slowly but surely dematerializing those assets and making digital the new norm).  It’s the totalitarian tip-toe.   

The BIS predicts there will be at least 9 major CBDCs in circulation by the year 2030; this is likely an understatement of the intended plan.  Globalists have hinted in the past that they prefer total digitization by 2030.

A cashless society would be the end game for economic anonymity and freedom in trade.  Unless alternative physical currencies are widely adopted in protest, CBDCs would make all transactions traceable and easily interrupted by governments and banks.  Imagine a world in which all trade is monitored, all revenues are monitored and transactions can be blocked if they are found to offend the mandates of the system.  Yes, these things do happen today, but with physical cash they can be circumvented. 

Imagine a world where your ability to spend money can be limited to certain retailers, certain services, certain products and chosen regions based on your politics, your social credit score and your background.  The control that comes with CBDCs is immense and allows for complete micromanagement of the population.  The fact that 98% of central banks are already adopting this technology should be one of the biggest news stories of the decade, yet, it goes almost completely ignored.   

Tyler Durden
Thu, 04/25/2024 – 05:45

I Kant Even: German Chancellor Triggered After Putin Quotes Legendary Philosopher

I Kant Even: German Chancellor Triggered After Putin Quotes Legendary Philosopher

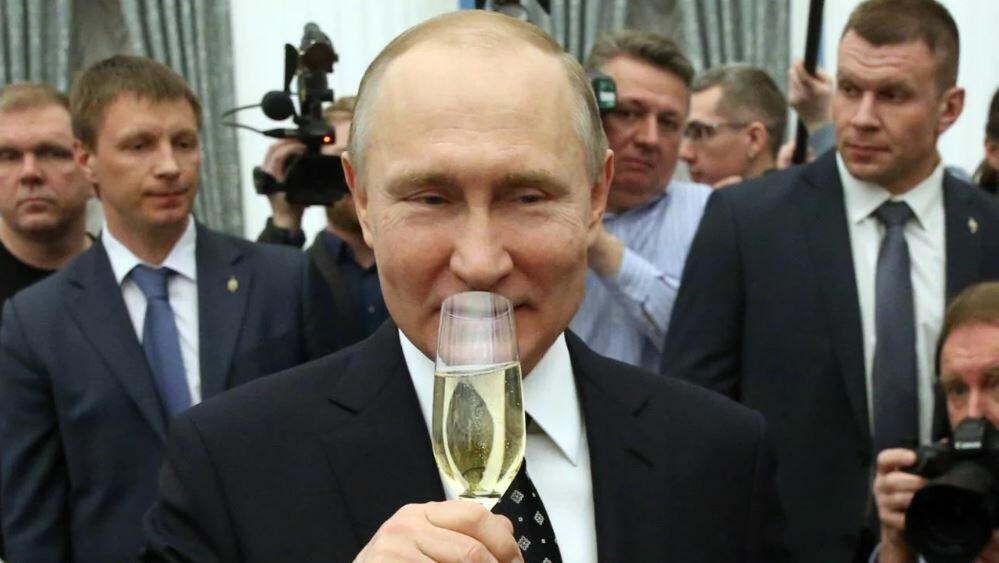
German Chancellor Olaf Scholz is quite upset, after Vladimir Putin quoted German philosopher Immanuel Kant – who the Russian president called “one of the greatest thinkers of both his time and ours,” and said that the philosopher’s call “to live by one’s own wits” is relevant today.

“A country must live by its own wits… This does not mean that we do not care about the interests of others… but we will never allow Russia’s interests to be neglected. In some countries, among our neighbors, this thesis has been forgotten. Many live by someone else’s wits. This will not bring them any good,” Putin told a group of college students in Kaliningrad – where Kant was born in 1724 (previously known as Königsberg, which belonged to the Kingdom of Prussia before becoming part of the Russian empire).

According to Scholz, “Putin doesn’t have the slightest right to quote Kant, yet Putin’s regime remains committed to poaching Kant and his work at almost any cost,” he told an audience at the Berlin-Brandenburg Academy of Sciences, Die Zeit reports.

According to Scholz, the Russian invasion of Ukraine is not in alignment with Kant’s teachings – noting that the philosopher spoke of the interference of states in the affairs of other nations. He also defended Ukraine’s decision not to enter into peace talks with Moscow, and that ‘forced treaties’ could not achieve ‘perpetual peace’ – something Kant spoke of.

Putin has praised Kant over the years – suggesting in 2013 that he should be made an official symbol of the Kaliningrad Region.

Kaliningrad administrators hit back at Scholz’ comments – saying in a Tuesday statement that nobody has done more than Russia to “perpetuate the memory of the great philosopher and his teachings,” adding “Immanuel Kant died as a subject of the Russian crown. It seems to me that this, more than any words of all possible German politicians, shows the position of the great philosopher regarding Russia.”

Kant was born in 1724 and died in 1804, and spent his entire life in Königsberg. During his later years, specifically from 1758 until his death, Königsberg and the entirety of East Prussia temporarily came under Russian control due to the events of the Seven Years’ War (1756-1763). Although Prussia regained control over Königsberg after the war, Kant’s status during those specific years was technically as a subject of the Russian Empire.

Tyler Durden
Thu, 04/25/2024 – 04:15

UK Government-Funded Trans-Lobbyist Group Calls Puberty Blockers “Wonderful”

UK Government-Funded Trans-Lobbyist Group Calls Puberty Blockers “Wonderful”

Authored by Steve Watson via Modernity.news,

A government funded LGBT activist group that is active in more than half of Scotland’s schools has called puberty blocking drugs, which effectively sterilise children, “wonderful.”

LGBT Youth Scotland, which is registered as a charity, has also declared that children should have the “autonomy” to decide whether to take puberty blockers without the views of their parents interfering.

The group, which receives almost £1 million per year in taxpayer funding, issued a statement in opposition to a decision to suspend the prescription of the drugs to children by the country’s gender reassignment centre, Sandyford Clinic in Glasgow.

The Telegraph reports that LGBT Youth Scotland’s Trans Rights Youth Commission declared “We would like to be clear about the wonderful impacts that accessing gender affirming care can have,” adding “Gender affirming care is about our right to do what we want with our own body. It is freedom. We deeply urge Sandyford to reconsider this decision.”

The comments come in the wake of a major long term study in the UK that concluded that treatment gender-confused children have been offered was built entirely on “shaky foundations” and that there is “no good evidence to support the global clinical practice of prescribing hormones to under-18s to pause puberty or transition to the opposite sex.”

The review also noted possible risks such as infertility and damage to brain function and growth.

The author of the review, retired consultant paediatrician Dr Cass, formerly the president of the Royal College of Paediatrics, called the evidence for life altering drugs “remarkably weak” and warned that transgender activists are the ones “deliberately spread(ing) misinformation.”

Since the review was published, Cass has been subject to abuse and cannot use public transport over fears for her safety.

As we highlighted last week, LGBT Youth Scotland is also encouraging teachers in Scottish schools not to communicate with parents if their children express a desire to ‘transition’ to a different gender.

It was also revealed earlier last week that schools signed up to the LGBT Youth Scotland charter scheme are appointing children as “LGBT champions” and being encouraged to question pupils about their sexual orientation and gender.

Earlier this week, Scotland’s education secretary Jenny Gilruth, defended the group as helping to create “inclusive” environments, and said that it is up to schools whether they sign up for the charter scheme.

Scottish Conservative deputy leader Meghan Gallacher hit back noting that parents have been “outraged” by “cult like” materials distributed by LGBT Youth Scotland, and pointing to an account of one parent who claimed her daughter had been “radicalised” by trans ideology after her school became involved with the group.

The account notes that the child’s decision to begin identifying as male was kept from the parents by the school, but that the girl soon reverted after being sent to a private school in England.

Gallacher urged that “LGBT Youth Scotland’s ideological and dogmatic response to the Cass review sums up why many are extremely concerned about their continued influence on kids in our schools.”

On top of all this, LGBT Youth Scotland was recently embroiled in a scandal with one of its employees under investigation for alleged grooming and child sex abuse:

We have previously highlighted how radical lobbyist trans activist groups such as Stonewall are injecting LGBTQ+ propaganda into teaching, and even recruiting ‘activist’ teachers to ignore government guidance that has essentially said schools do not have to adopt ‘gender identity ideology’ or recognise ‘social transitions’ among pupils.

These groups masquerading as charities are siphoning taxpayer money to fund their extreme operations, which are directly targeting children.

*  *  *

Your support is crucial in helping us defeat mass censorship. Please consider donating via Locals or check out our unique merch. Follow us on X @ModernityNews.

Tyler Durden
Thu, 04/25/2024 – 03:30