The Billionaire Couple Quietly Spending Millions To “Reinvent” The Democrat Party
A billionaire hedge fund couple is dumping millions into a high-stakes effort to push the Democratic Party away from its increasingly radical left flank and challenge its entrenched leadership.
Steve and Sue Mandel, wealthy Democrat donors from Greenwich, Connecticut, have committed at least $20 million to a network of political groups aimed at elevating more moderate candidates, according to a new report from The Wall Street Journal.
Hedge-fund billionaires Sue and Steve Mandel. (via WSJ)
Their operation includes at least three organizations designed to confront the party’s existing power structure and potentially reshape Democratic politics ahead of the 2028 presidential election. At the center is Majority Democrats, which is working to boost candidates who can appeal beyond the party’s progressive base.
Another group, The Bench, focuses on identifying and backing rising political talent, while the Searchlight Institute is crafting more centrist policy ideas in hopes of making Democrats competitive again nationally.
The couple is taking an unusually hands-on role, closely tracking campaigns and working with Seth London, a seasoned Democrat consulanted who served a stint in the Obama White House as Legislative Assistant and Associate Director. The billionaire couple’s effort has already drawn additional funding from political and media power players, including former New York City Mayor Michael Bloomberg and James Murdoch, according to the Journal.
The effort underscores growing frustration among some deep-pocketed Democratic donors who argue the party has lost touch with ordinary voters and desperately needs an overhaul. Rather than demanding ideological purity, the Mandel-backed groups are prioritizing candidates with strong personal stories and proven ability to win elections.
However, as the Journal points out, the Mandels’ political investments have not always paid off:
During this year’s Senate race in Michigan, it threw its support behind Mallory McMorrow, a telegenic state senator and self-described “pragmatist” who had been a client of Smith’s.
McMorrow dropped out less than a month before the primary, and Abdul El-Sayed, from the party’s left, won. Democrats who didn’t support El-Sayed traded blame. Proponents of The Bench criticized Washington groups for helping the other moderate candidate, Haley Stevens.
A former Stevens adviser had the opposite takeaway: The Bench had made the race more costly and complicated.
Addtionally, critics on the far left were quick to dismiss the effort.
“The Mandels’ approach represents the same Democratic establishment with some new seasoning on top,” said Usamah Andrabi, spokesman for the far-left Justice Democrats, told the Journal. “That’s simply not what the party’s voters are looking for right now.”
Bolivia’s dwindling natural gas reserves and declining exports have undermined its economy and intensified fuel shortages.
Rising global energy prices and subsidy cuts have increased living costs and fueled widespread protests.
A $1.9 billion IMF rescue package and energy-sector reforms aim to stabilize the economy, but long-term recovery requires diversification.
Years of underinvestment in Bolivia’s gas industry have left the South American country facing a severe fuel shortage, as energy prices rise ever higher owing to the ongoing war in Iran. The energy shortages and economic crisis follow years of poor decision-making by the government.
In 2006, then-president Evo Morales took control of Bolivia’s fossil fuel industry, renegotiating contracts with international oil and gas companies and benefiting from the revenue. Much of the country’s newfound wealth was invested in public spending programs, expensive fuel subsidies, and the maintenance of a fixed currency exchange rate pegged to the U.S. dollar. Fossil fuel revenues contributed heavily to Bolivia’s economy for several years, supporting GDP expansion and the development of social programs that helped halve poverty rates.
For many years, Bolivian’s were led to believe that they had more extensive gas supplies than they actually did. However, in recent years, Bolivia’s fossil fuel sector has suffered as reserves have dwindled and no successful gas discoveries have occurred. As of April, Bolivia has an estimated 3.7 trillion cubic feet of proven reserves. The fall in gas production led exports to fall by almost 60 percent over the last decade. Bolivia continues to rely heavily on natural gas, which accounts for around 70 percent of its electricity mix.
Meanwhile, little progress has been made in developing the country’s green energy sector, leaving it facing severe energy shortages. The fall in gas revenues has left the economy suffering terribly, as inflation soars and the price of imported goods becomes ever more unaffordable. Luis Fernando Romero, the former head of an association of economists in southern Bolivia, stated, “We failed to take advantage of a historic opportunity that brought in immense revenue.”
This situation is not uncommon, with many other oil-rich states having had similar experiences. Several Middle Eastern states have long depended on oil and gas revenues for economic growth, and most have only recently announced plans to diversify their economies to reduce reliance on fossil fuels. Several countries across the MENA region announced new economic strategies following greater talk of a global green transition, which could leave them missing out on vital oil revenues if they don’t take moves to diversify and invest in value-added sectors.
The lack of investment in Bolivia’s other domestic sectors has left it struggling to stay afloat as it runs out of fuel and is forced to pay high fuel import costs. President Rodrigo Paz warned that “International prices are forcing us to make complex choices.”
In September, Bolivia’s Congress approved a $1.9 billion loan from the International Monetary Fund (IMF), even though the terms of the deal require the government to impose strict austerity measures that could fuel social unrest. The loan received approval from the IMF’s Executive Board on October 2, and the government will now be required to cut its fuel subsidies and significantly reduce public spending. It has already increased fuel prices and is expected to scrap further gasoline subsidies from the beginning of next year. The loan is expected to unlock up to $4 billion more in financing from the World Bank and other lenders.
However, there are major concerns that the new financial plan will significantly increase the cost of living for households already struggling. Last December, the government reduced fuel subsidies, leaving little support for the most vulnerable Bolivians. This led to widespread protests as people called for President Paz’s resignation. In February, there was further social unrest after the distribution of poor-quality gasoline ruined thousands of vehicles. Then, in June and July, several weeks of road blockades by protesters occurred.
Meanwhile, to tackle the ongoing fuel shortages, Bolivia’s government announced plans in September to triple the fund financing refined fuel purchases, following similar announcements by Peru and Ecuador. This is expected to help mitigate diesel shortages and rising prices. Both Peru and Ecuador have increased fuel subsidies in recent months and are focusing on increasing production at state oil refineries to alleviate the price pressure of expensive fuel imports.
In July, Bolivia’s Energy Minister Marcelo Blanco announced that the government had authorized the private sector to import and sell refined fuels to mitigate severe shortages. Then, in September, the government said that the state hydrocarbons firm plans to focus on exploration, extraction, and refining to continue developing Bolivia’s gas resources. However, experts warn that Bolivia could become a net fossil gas importer by around 2030.
As Bolivia continues to battle fuel shortages and seeks to support economic recovery by borrowing from international organizations, the government must focus on diversifying the economy by developing other value-added sectors to sustain long-term growth. In addition, the government must also develop Bolivia’s renewable energy sources to reduce dependence on expensive fuel imports and ensure the country’s energy security.
Japan’s average power prices jumped by over 25% at the start of this week from the previous week amid soaring LNG and higher coal prices.
The nationwide power price rose by over 25% week-to-week to $0.19 (31.15 Japanese yen) per kilowatt-hour (kWh) on Monday, Bloomberg reported, citing data from Japan Electric Power Exchange.
Japan, one of the world’s biggest LNG importers, this summer reduced gas-fired generation in favor of coal as the price of liquefied natural gas remained elevated.
Japan has been burning more coal and less gas for power generation since the war in the Middle East started, and it is not the only one. All Asian countries have made the switch from gas to coal on affordability and availability grounds.
Moreover, surging oil prices have led to a significant increase in Japan’s import bill for oil and LNG.
LNG prices surged in Asia to a four-year high as very few cargoes manage to exit the Strait of Hormuz while competition with Europe for winter supply is intensifying.
The average spot LNG price for delivery into north-east Asia in December was assessed at $29.30 per million British thermal units (MMBtu) at the end of last week. This was the highest spot LNG price for Asia since December 2022, and sharply higher compared to $26.50 per MMBtu assessed in the previous week.
As a result, Japan’s gas-fueled power generation is the most expensive in years.
The switch to coal, for its part, has also had its cost challenges this year. Increased demand in Asia amid reduced supply from the top thermal coal exporter, Indonesia, is driving up coal prices, too. The global benchmark for coal prices, the Newcastle futures, have jumped by 30% compared to pre-war levels.
Power prices in Japan have also jumped this month due to scheduled maintenance at some power-generating facilities ahead of winter.
Feds Using DNA To Probe Ilhan Omar ‘Married Her Brother’ Claim, Eye Conspiracy Charge: Report
Federal prosecutors plan to use DNA evidence in their criminal investigation of Rep. Ilhan Omar (D-Minn.), people familiar with the probe told the New York Post on Monday. One source said the DNA is critical to proving the long-running allegation that Omar’s 2009 marriage to Ahmed Nur Said Elmi was a marriage to her brother, made so he could get a green card he never received. Omar has denied the claim since 2016, no charges have been filed, and the Justice Department has not confirmed any DNA evidence.
The DNA report is the latest turn in a probe that went public a week ago, when Homeland Security Investigations agents searched Omar’s Washington home on Oct. 12. Agents also seized Omar’s phone, and more than a dozen grand jury subpoenas have gone out, some to her relatives, a source told the Associated Press. The grand jury is collecting evidence in Minnesota, where the U.S. Attorney’s Office opened the case. Omar called the search an “attempt to target political enemies and weaponize federal law enforcement” and said, “I will not be silenced.”
The Post’s sources did not say whether the DNA was collected before or after the search. One of them pushed back on earlier reports that investigators went “dumpster diving” for swabs of Omar, Elmi or family members. Reporter Leland Vittert had said on Saturday that agents had done just that, before the raid:
Multiple sources have confirmed to me that federal agents went dumpster diving to get DNA from Minnesota Congresswoman @IlhanMN and her family before the raid on her D.C. home earlier this week. Our reporting suggests investigations go far beyond simple immigration fraud. NewsNation sources say the likely coming indictments will be stunning in nature and far beyond anything the public has understood the case to be about.
Two other sources told the Post that the search, the DNA and other evidence give prosecutors a solid basis to bring a charge of conspiracy to commit immigration fraud before a grand jury. A conspiracy charge would let prosecutors allege overt acts that fall outside the statute of limitations, former federal prosecutor Neama Rahmani told the Post. He said prosecutors could pursue a conspiracy case that would likely fall within a 10-year limit, or a civil case, which has none, and that the warrant would not have been executed unless it had “come from the highest levels of the DOJ.”
That fits the warrant. A person familiar with the document told The Washington Post that it lists potential charges of conspiracy, immigration fraud and false statements. Investigators are also looking at whether Omar or her father, Nur Omar Mohamed, misstated her birth date on immigration paperwork so she could derive citizenship through him when he naturalized in 2000. Rahmani called her late father “an unindicted co-conspirator.” The Justice Department has not released the affidavit.
Homeland Security Secretary Markwayne Mullin, whose department’s agents carried out the search, said on Oct. 16 that “multiple other warrants” were served the same day. “We had a judge sign it, and we expect to be able to take the case to a grand jury,” he told the Charlie Kirk Show, according to CBS News.
The marriage and the birth-date theory lead to different places. A marriage-fraud conviction would not threaten Omar’s own citizenship the way a false-statements case would, the New York Post noted, and stripping the citizenship of a sitting member of Congress would be unprecedented. Border czar Tom Homan said over the weekend that the government has built “a strong case” that could lead the administration to seek denaturalization. As we reported, the Wall Street Journal had already said officials wanted to revoke her citizenship and deport her, and agents reportedly secured her passport in the search.
D.C. U.S. Attorney Jeanine Pirro, whose office is separately examining Omar’s House financial disclosures, told Fox News that “that judge would not have signed that warrant unless there was probable cause.” Those disclosures cut Omar’s reported net worth by tens of millions of dollars in a year, which the Post attributed to an unexplained accounting “discrepancy.”
Omar’s lawyers, Amy Jeffress and Joshua Matz, answered last week with a letter to the Justice Department demanding the “immediate return” of everything seized. They wrote that agents ignored a magistrate judge’s “special requests” for carrying out the search and broke longstanding DOJ policy by acting so close to an election, and that President Trump has “made no secret” of wanting to target her. A DOJ spokesperson called the letter “riddled with false allegations and inaccuracies” and said leaking it was “a publicity play.” Rep. Jamie Raskin, the ranking Democrat on House Judiciary, had already called the search “blatant political intimidation,” coming 22 days before the Nov. 3 election. Former federal prosecutor Jim Trusty told Fox News the warrant shows “at least probable cause,” but that it is “a long way off from proving a case at trial.”
The marriage record at the heart of the DNA claim is tangled. Omar and Elmi divorced in 2017, and she gave birth to her third child while legally married to him. Her marriage to Ahmed Hirsi was not legally entered into until after her divorce from Elmi was finalized, the Post reported, although the two had a Muslim ceremony in 2002. She filed joint taxes with Hirsi in 2014 and 2015 while still legally married to Elmi, from whom she had separated in 2011. Elmi, who lives in the UK, applied for a marriage-based green card and withdrew it in 2019 when immigration officials asked for more evidence, according to The Washington Post, which also quoted a former immigration official saying the brother claim was investigated during Trump’s first term without enough evidence to go forward. Omar divorced Hirsi in 2019 and married political consultant Tim Mynett.
We reported last week that her staff asked Minnesota’s legislative library in 2019 to change her birth year, and that Mynett snapped at a reporter over rumors she had fled the country. Mynett has said only that his wife “came here when she was 12 years old as a child war refugee.” Her lawyers say there is “no legitimate basis for any suggestion that she has violated any law concerning her citizenship status.”
The Department of the Treasury’s Financial Crimes Enforcement Network (FinCEN) has discovered roughly $270 million in suspicious financial activity likely associated with student aid program fraud.
FinCEN issued an alert in July asking financial institutions to report suspicious activities linked to student aid fraud.
A review of submitted reports identified more than 20,000 potentially suspicious transactions since February this year. FinCEN has reported approximately $270 million in suspected fraud to federal investigators for further investigation, the Treasury said in an Oct. 19 statement.
“Federal student aid is intended to expand educational opportunities, not line the pockets of fraudsters who steal from students pursuing their education and hardworking taxpayers,” Treasury Secretary Scott Bessent said in the statement.
“Treasury is working with financial institutions and law enforcement to identify these fraud schemes, recover stolen funds, and hold those responsible accountable.”
The department said it was working with the White House Task Force to Eliminate Fraud, headed by Vice President JD Vance, and encouraging whistleblowers to report fraud-related information.
In an example of educational fraud, the Department of Justice (DOJ) announced last month that a Detroit man was sentenced to 92 months in federal prison for fraud schemes, including one that targeted federal student aid programs.
The man and others submitted fraudulent student aid claims for more than 1,200 individuals, collecting more than $10 million before being caught, the DOJ said. The fraud spanned 100 schools across more than 20 states.
In March, the DOJ said a former professor admitted to stealing government funds through a scam involving fraudulent student financial aid applications. More than 100 such false applications were filed across several universities and colleges in Texas.
Education Aid Schemes
The Treasury detailed some of the federal student aid fraud schemes in its statement. For instance, “ghost student” schemes involve criminals stealing an individual’s personal information and using it to enroll as a student in classes. The victim often never realizes that a third party is collecting student aid in their name.
In “straw student” schemes, fraudsters pay real people to enroll in classes and collect financial aid in their names. In some cases, corrupt school employees may be part of these schemes.
“Student aid fraud has real consequences for students and American taxpayers. It drains finite grant resources from deserving students, potentially prevents legitimate students from enrolling in classes occupied by fraudulent enrollees, and can leave identity theft victims responsible for debts they never incurred,” the Treasury said.
In July, the Department of Education held a first-of-its-kind Higher Education Fraud Summit, with participants discussing ways to tackle fraud in the sector.
“We have already prevented nearly $2 billion in attempted federal student aid fraud from going to bad actors. Every dollar lost to fraud is a dollar taken away from a student trying to build a better future,” Underssecretary of Education Nicholas Kent said in a statement.
In an October 2025 update, the University of Alaska warned students to protect themselves from student aid fraud. Specifically, the university said that students should share their personal information only with trusted, secure websites.
The university recommended that students regularly monitor their credit for any unusual or new activity and report any identity theft or other suspicious activity.
“Treat digital content, like emails, texts, voicemails, and website content, with increased scrutiny, especially if the materials or resources they provide or advertise seem too good to be true or appear designed to create a sense of urgency,” the university said.
The Great Rare Earth Disconnect: Prices Up 23%, Miners Down 28%
Here is a question that should be harder to answer than it is: China still controls the rare earth spigot, the latest Trump-Xi summit did nothing to loosen its grip, Japan is about to run out of yttrium, Washington has put a $110/kg floor under NdPr, and Western buyers are paying anywhere from 5x to 346x the Chinese price for heavy rare earths.
Given our favourable SxD outlook, floor pricing, recent pricing stability (NdPr), and Western pricing premiums (particularly for heavies), we think recent equity performance has been driven more so by global macro factors and highlights a disconnection from rare earth market fundamentals.
In other words, the commodity is acting like a strategic asset and the stocks are trading like a risk-off casualty. The numbers are stark: year to date, the ex-China NdPr price is up 23%, while Canaccord’s rare earth developers are down 17% on average and its producers are down 28%.
Fifteen months later, MP trades at $40.17, about half of Canaccord’s $82 target. So what happened?
The Chart That Says It All
Canaccord’s chart below shows the problem in one picture. Chinese NdPr (black) and Rotterdam NdPr (dark blue) have converged and climbed steadily all year, with the Western price now above $110/kg. Meanwhile the REMX ETF (light blue) peaked in May and has since slid from above $100 to the high-$50s.
The carnage is broad. On the producer side, Lynas, MP, USA Rare Earth and Iluka are all deep in the red, and even China Northern Rare Earth and Shenghe are lower on the year. Diversification at its finest.
Developers did a bit better on average, mostly thanks to Viridis (VMM), which is still up well over 50% on the year. Strip that out and the picture is grim: Hastings is down roughly two-thirds, St George about half, and Arafura and Brazilian Rare Earths 35-50%.
Canaccord’s verdict: “We question how equities have performed so poorly YTD despite strong underlying market fundamentals.” Those fundamentals include recent sector M&A, direct government support, a scarcity of Western supply and “ex-China NdPr pricing up 23% YTD.”
The Floor Works… Just Ask China
Start with the most important structural change of the past year. As we reported when the Department of Defense set a price floor last August, Washington has moved from financing Western supply to underwriting its economics. Canaccord tallies the floors: US$110/kg NdPr for MP (DoD), Lynas (Japan, US, plus upside sharing) and USA Rare Earth, which also gets US$575/kg for dysprosium and US$2,050/kg for terbium.
And the floor has done something nobody expected: it has tamed the Chinese price too. For years Beijing used export quotas, policy changes and, more recently, export controls to whipsaw NdPr from about $175/kg down to around $50 and back again. Over the past 10 months, Canaccord notes, Chinese pricing has “begun to normalise around the US$110/kg floor price level.”
Put differently, the volatility that made rare earth projects unbankable has largely vanished, and yet investors are paying less for those projects than they did in January.
Two Markets, Two Prices
NdPr is now a one-price market, more or less. Everything heavier is a different story. Since Beijing started rationing heavies, the West has developed its own (thin, opaque) price for anything China won’t ship, and the gaps are absurd. Rotterdam dysprosium sits around $1,074/kg vs $227 in China, and terbium at $4,594 vs $983.
But Dy and Tb are the tame ones. Canaccord now forecasts yttrium, gadolinium and samarium for the first time, and the Western premiums there are almost comical. Chinese yttrium oxide has averaged about $8/kg over the past five years, while European spot is “~US$740/kg”, a premium of 85x, and “some price reporting agencies have quoted US prices of up to US$1,750/kg.” Gadolinium trades about 10x China in Baltimore, with US CIF quotes as high as $3,100/kg.
We ran Canaccord’s own spot price table through the calculator, and here is what the “dual market” looks like element by element. CIF North America samarium, used in the SmCo magnets that go into missiles, fighter jets and radar, trades at 346 TIMES THE CHINESE PRICE!
And the squeeze is very real. Just this morning the FT reported that Japan has made an urgent request to Washington and global companies to help resolve its yttrium crisis, warning of a severe shortage by year-end. “Inventories are plummeting,” one official said. Per Argus, yttrium oxide costs about $9/kg in China and roughly $1,150/kg outside it, a 179-fold jump in two years. A senior US official added that China is shipping the US just two-thirds of the rare earths it promised under last October’s truce, and Japan “only the bare minimum.” That followed last month’s Trump-Xi summit, where China pledged to buy US coal but fell short on rare earths, and the two sides settled for a two-month truce that markets promptly faded.
To be fair, Canaccord is careful here. It notes the ex-China DyTb market was just 151 tonnes in 2025, and China’s was 22x larger. It warns that Western premiums “should be viewed cautiously” and that “we question whether pricing is sustainable at these levels,” with some magnet makers already pivoting to lower-cost ferrite magnets. Its own price deck has ex-China yttrium falling from $740/kg this year to $100 by 2030. Still, even the bank’s haircut numbers leave Western producers with integrated separation (it names Lynas and MP) earning premiums nobody would have modeled two years ago.
Demand Goes Up, Again
Meanwhile the demand side keeps getting revised higher. Canaccord now sees NdFeB magnet demand growing at a 7.3% CAGR to ~365,000 tonnes by 2035, 15% above its prior update. EVs remain the anchor (52 million units by 2035 vs 23.5 million in 2026), but the bank has added data centers (motors for cooling), e-bikes and scooters, and drones. Drones are only ~1% of forecast demand, but the bank notes that Ukrainian and Russian military drone production alone was estimated at ~9 million units, so “our model forecasts may prove conservative.”
Then there are the robots. Canaccord models humanoid deliveries growing at a 45% CAGR to 2.5 million units by 2035, and points out that Tesla is reportedly preparing an Optimus line designed for 1 million robots a year. For comparison, global EV sales rose more than 4,600% from 2014 to 2024. Maybe the robot curve won’t look like that… but if it does, the magnet math gets very ugly very quickly.
Netting it all out, Canaccord sees the global NdPr market in deficit through 2028 (about 7% short this year), roughly balanced in 2029-31 as Eneabba, Kangankunde, Caldeira, White Mesa and the Lynas expansions come online, and then sliding back into a deeper deficit: -10% by 2035. Dy+Tb follows the same shape, ending at a 12% deficit.
The West’s Blind Spot
The bulls’ case gets even stronger once you look past the mines. Canaccord forecasts ex-China NdFeB magnet capacity rising more than 300% by 2030 to about 70,000 tonnes, which sounds impressive until you realize it would still be only 23% of global capacity, with China at ~77%.
And the West may not even get there, because it is missing a step. Global NdFeB metallisation and alloying capacity is about 210,000 tonnes in 2026, and more than 90% of it is Chinese controlled. Ex-China capacity is set to roughly double to 38,000 tonnes by 2030, which falls well short of planned Western magnet capacity. Canaccord calls metallisation “a major blind spot in western supply chain development“, and its channel checks found lead times of up to two years for strip casters, “with sourcing from China impossible under current export controls.”
This echoes ING’s warning, which we covered two weeks ago, that China’s rare earth chokehold may outlast this decade because the bottleneck is “industrial rather than geological.” Canaccord’s conclusion is just as stark: “our research points to China maintaining market dominance, with shortfalls in Western supply (and likelihood of ongoing Chinese export controls) supporting bifurcated markets and pricing premiums.”
Translation: the scarcity premium for anything mined, separated or metallised outside China is a structural feature that will be around for years, and the companies capturing it are trading as if it will be gone by next quarter.
Wall Street Is Paying 50 Cents On The Dollar
Which brings us to valuation. Canaccord’s producer coverage trades at an average 0.57x P/NAV and its developers at 0.47x. On the bank’s targets, MP has 104% upside, Lynas 108% (target raised to A$23), USA Rare Earth 204% and Energy Fuels 150%, even after Canaccord cut its EFR target to C$30 on project delays.
The rating changes: Meteoric (MEI) goes to Hold from Spec Buy, since its value is now tied to Lynas’ all-scrip takeover at 0.0207 LYC shares per MEI share. (Lynas shares fell almost 8% the day that deal was announced, another reminder that this market keeps punishing consolidation.) Hastings (HAS) goes to Spec Buy from Hold “on valuation”, even though its target was cut to A$0.30 from A$0.55, which tells you just how far the stock has fallen.
Of course, price targets have a habit of following prices rather than leading them, and at least some of the selloff has a perfectly sensible explanation: these are long-duration, capex-heavy projects at a time when the 10Y is above 5%, tech is wobbling and the bid for anything speculative has evaporated. Canaccord concedes as much, blaming “global macroeconomic pressures.”
Same Disconnect, Different Metal
Tungsten isn’t a rare earth, but it is a critical material with the same chokepoint (China controls roughly 80% of supply, per Jefferies), and it shows the exact same disconnect, only worse. Take Almonty Industries (ALM), the most prominent Western tungsten miner and a name we have covered extensively in recent weeks.
When Goldman’s Nick Cash initiated coverage last month, he put Almonty “at the center of the Western tungsten investment narrative,” with tungsten prices up 8x since the start of 2025. He was also the Street’s skeptic, expecting prices to normalize and Sangdong’s ramp to run slower than the market hoped, with a $13 target vs a $24.73 consensus. The stock was $12.74 that morning. Today it is below $9, down 62% from its April peak and back where it started the year, after dropping another 10% on the day of yesterday’s Investor Day. So even Goldman’s cautious target now implies about 45% upside.
Meanwhile the operations are going the right way. Sangdong in South Korea started production in September and is moving toward 24/7 operations, with its first concentrate shipment due later this month, and Cantor’s Matthew O’Keefe models output jumping from 126,287 MTU this year to 444,400 MTU in 2027, with all-in sustaining costs falling from $905 to $319 per MTU. Oppenheimer’s Ian Zaffino puts the shares at just 5.7x/4.2x FY27/FY28 EBITDA, with roughly $290 million in net cash.
So what spooked the market? Spot prices. Western APT has slipped from $3,140 to about $2,700/MTU, and Chinese prices have retreated even more sharply. But Zaffino explains why that is a misleading signal: Western APT and oxide plants are running at capacity under long-term contracts and can’t absorb more concentrate, so “concentrate prices have softened, even as availability of finished APT/oxide in the West remains constrained.” And the demand wave hasn’t even started. On January 1, 2027, US defense procurement rules extend to tungsten mining, refining and separation, so Chinese or Russian ore processed in a third country no longer qualifies. Stifel says the US strategic tungsten stockpile is nearly depleted, and Bernstein sees the Western rearmament order boom running from 2027 through 2030. The cherry on top: on Monday, CME announced plans to launch tungsten futures by early Q1 2027 at the latest (subject to regulatory review), which tells you how seriously the market’s plumbing is taking a metal that equity investors are currently dumping.
In other words, spot is pricing today’s bottleneck in Western processing, and the stock is pricing spot, while the 2027 demand cliff is priced almost nowhere. Sound familiar?
Supply Security Gets The Stage In London
Goldman, for its part, thinks the debate has already shifted. Its third Global Metals & Mining Conference kicks off in London today during LME Week, bringing together the world’s largest “diversified, copper, aluminium, rare earth and lithium producers.” In their conference preview, Goldman’s Matt Greene and the bank’s mining team write that “the conversation has increasingly shifted to supply,” with governments “becoming more active participants in the mining sector through faster permitting, shared infrastructure, strategic funding, price floors and direct offtake agreements, reflecting the growing importance of resource security.” The question the bank poses is the right one: “whether the industry can deliver the supply that markets are increasingly pricing in.”
For rare earths, the honest answer seems to be: not anytime soon, and not without China. Which is exactly why the sector’s stocks probably shouldn’t be trading at half of NAV.
Today we have a two-month trade truce that expires January 10, a Japanese government begging for yttrium, the West’s flagship tungsten miner trading below even Goldman’s skeptical target ten weeks before the Pentagon’s sourcing rules kick in,a floor price that has turned NdPr into a one-way bet with a safety net, and an equity market that is valuing the West’s only scalable non-Chinese suppliers at roughly half of what they’re worth on conservative assumptions.
Canaccord’s closing line sums it up: “We expect demand to remain strong, as the West looks to secure ex-China supply and build its independence within the global magnet supply chain.”
Our take: the disconnect will probably close the same way it did last summer, with a headline out of Beijing or the Pentagon, and the investors waiting for macro to give them the all-clear will be buying it 50% higher. After all, nothing cures a 0.5x P/NAV like a 346x price premium.
An Uncomfortable Reality: China’s Rare Earth Chokehold May Outlast This Decade https://t.co/ln17BOGCgV
“A Good Idea”: SpaceX Jumps On Blowout Quarter, Musk Confirms Committees Discussing Tesla Merger
Update (1730ET): The earnings call has seen SPCX shares extend their after-hours gains amid a tsunami of attention-grabbing comments from Elon Musk and CFO Bret Johnsen.
Perhaps the most shocking was Musk saying that he sees between $500 billion and $1 trillion of annual recurring revenue by the end of 2027.
Then he stepped it up further:
Musk says there’s a small opportunity for SpaceX to have 20 gigawatts of AI compute online next year.
Musk says he’s been spending a lot of his time in Memphis, “often four days a week,” trying to get more data center compute developed.
He’s aiming to bring in 13 gigawatts of compute by the end of next year.
And this year, he expects between 2.5 GW and 3 GW to come online.
As a reminder, (based on this quarter’s numbers) they have 1.7 GW of nameplate compute.
“We are, frankly, hounded relentlessly by every hyperscaler,” Musk says, referring to demand for SpaceX data centers.
“I don’t think we’re going to have a demand issue here.”
And finally, the topic of merging Tesla and SpaceX was brought up:
“I’m tap dancing through a minefield,” says Musk on the question of a merger, adding that both SpaceX and Tesla have formed special committees to discuss this idea.
Musk also downplayed the move somewhat:
““I think some people out there assume that a SpaceX and Tesla merger is a certainty, and I think that would be overstating it.”
But then he adds:
“I do think there’s a lot of merit for combining the companies,” Musk says, concluding that “I think it will be a good idea”.
The market is pricing a 66% chance of the merger being completed by the end of next year…
All of that combined, has pushed SPCX up around 5%…
* * *
As we wrote in our preview, hopes are high for what SpaceX will report today. The company is expected to report solid revenue growth, however more than offset by far more solid capex growth which will result in SpaceX burning almost a quarter trillion over the next 3 years as it builds out its data center capacity. Notably, SpaceX could post its first quarterly profit today – though this is only its second earnings report as a public company. Wall Street expects earnings of 15 cents a share, or about $1.9 billion in net income, compared with a $541 million loss last quarter.
Besides the top and FCF lines, Deutsche’s list of “other areas of focus” is a good checklist of what else to look for:
AI: neocloud pricing and new contracts, the Cursor contribution, Grok Bot adoption, and the data center capex outlook (read: any hint that 2027 capex starts with a “2”).
Launch: timing of the next few launches after Flight 14; Flight 15 looks set for mid-/late November, though DB doesn’t expect a second-stage catch.
Connectivity: after the $8 billion Grain spectrum deal, “additional color on management’s next move(s) in the US (build vs. buy),” which is something the wireless carriers will be listening to closely.
Additionally, investors are seeking additional hints about a potential Tesla and SpaceX merger. Today’s earnings are happening just a few days after Tesla unveiled its new Roadster, which incorporated SpaceX gas thrusters that allowed the vehicle to hover and do barrel rolls in the air. Following the event, a bunch of Tesla and SpaceX executives and employees started following each other on X, according to an account that monitors tech executives. DB said that the timing as “mainly a function of valuation differentials and politics (may want to avoid a potential Democrat-led administration taking over post Trump).”
Elon Musk has talked a lot about the “convergence” of his businesses over the last year. Meanwhile SpaceX and Tesla are already collaborating on one of Musk’s most ambitious projects: the Terafab, which aims to mass produce semiconductor chips in the US to be used in his companies’ various products.
Don’t expect to see much, if any profit: Starlink satellite-internet service is SpaceX’s only profitable business. The militarized version of Starlink, called Starshield, came under increased scrutiny last week after Ukrainian President Volodymyr Zelenskyy accused the White House and Musk of placing restrictions on the technology in Ukraine, disrupting military operations. Both Musk and Trump have denied involvement, igniting a firestorm over who controls the technology that has become indispensable to Ukraine’s war against Russia.
As for the market’s reaction, recall that SPCX shares slumped 14% the day after its first earnings release in August, in part over fears that insiders would sell shares after the earliest of many lockup expirations. Those fears were quickly calmed when the shares rebounded, but the setup heading into this quarter’s results is similar to last time. On Wednesday, an additional 1.3 billion shares, representing 28% of those subject to the 180-day lock-up period, will become available to trade.
So with all that in mind, here is what SpaceX just reported for Q3, its second quarter as a public company. For the most part a solid beat across the board, blowing past Wall Street expectations, and posting its first quarterly profit, $4.4 billion, or 35 cents a share, more than double estimates, while spending a massive $20 billion on capex
Revenue $14.58 billion, beating estimates of $12.87 billion
Space revenue $1.77 billion, beating estimates of $1.43 billion
Connectivity revenue $5.25 billion, beating estimates of $4.86 billion
Here is the revenue by segment: it shows that SpaceX is no longer a Rocket Company but is now mostly a neocloud, pardon, Hyperscaler.
Capital expenditure $19.59 billion, beating estimates of $19.6 billion
Space capital expenditure $1.61 billion, higher than estimates of $1.52 billion
Connectivity capital expenditure $1.54 billion, below estimates of $1.6 billion
Here is the capex by segment:
Turning to expenses…
Total Costs & Expenses $11.78 billion, beating estimates of $11.23 billion
R&D expenses $4.60 billion, missing estimates of $5.06 billion
… and operating income:
Operating income $2.79 billion, beating estimates of $2.24 billion
Connectivity operating income $2.37 billion, beating estimates of $1.86 billion
Adjusted Ebitda $8.81 billion, smashing estimates of $6.59 billion
Space adjusted Ebitda $357 million, estimate $123.1 million
Number of rocket launches 35, missing estimates of 41
Mass to Orbit 476 mt, missing estimates of 559
Cash and cash equivalents $51.29 billion, estimate$91.2 billion
While much will be said about the company’s profitability, note that the $4.4 billion of net income got a boost from $1 billion of “other income” and a $390 million tax benefit. That said, the underlying business still beat expectations: operating income was $2.8 billion versus $2.2 billion expected.
A visual way of representing what happened in Q3:
Looking at the key components, EBITDA and CapEx, we find that both revenue and EBITDA smashed estimates, while CapEx was largely unchanged from last quarter.
As we noted in our preview the big question would be the delta between EBITDA and CapEx growth, and as shown in the chart below, while EBITDA was a record $8.8BN, it is still nowhere near enough to catch up to the whopping $19.6BN in capex.
Another very important number: amount of installed compute rose to 1.7GW, just shy of estimates of 1.74GW.
Summarizing the fine print: SpaceX reported blowout revenues and EBITDA, driven by stronger ARPU, even as ending compute, consumer broadband subs and external launches all came below expectations.
Commenting on the quarter, the SpaceX CFO said that the company “delivered another strong quarter in Q3. Revenue grew an impressive 161% year-over-year, fueled by continued momentum in Connectivity and a clear inflection in our Super Intelligence business. The combination of our launch leadership, recurring Starlink revenue, and the significant expansion of our SI infrastructure continues to drive meaningful operating leverage… We are building the infrastructure of the future with discipline — focused on capital efficiency, strong returns on invested capital, and maintaining a robust, investment-grade balance sheet — while moving with the velocity to capture the opportunity in front of us.”
In its wrap, Bloomberg writes that SpaceX of this quarter is not the same as the SpaceX of last quarter. AI – now officially called Super Intelligence – has overtaken Starlink to become the company’s biggest business by revenue. Just last quarter, Starlink was comfortably ahead. The speed of that shift shows just how quickly SpaceX’s AI infrastructure business is scaling.
The SpaceX story used to be rockets funding satellites. Increasingly, it’s rockets, satellites and a giant balance sheet funding an AI company. In other words, a hyperscaler.
The results were solid, and the stock liked them – at least until the call – with SPCX stock higher about 3%, fading a bit of its after hours jump.
Anthropic’s Updated S-1: An $80.7BN Half-Year Loss, A $750BN Compute-Tab, And A ‘Catastrophic Incident’ Warning
Three weeks ago, when the first leaked draft of Anthropic’s confidential IPO prospectus made the rounds, we noted that CEO Dario Amodei was preparing to take the company public at the exact moment the underlying math of the frontier AI trade had begun to turn against him. That September filing showed a company that burned through $42 billion in net losses during 2025 on just $4.6 billion in revenue, sitting on $20 billion in cash while staring down $518 billion in long-term compute commitments.
On Tuesday, The Wall Street Journal reviewed a more recent draft of Anthropic’s S-1 registration statement covering the first half of 2026. Every headline number has moved substantially higher – and none of the structural flaws have been fixed.
In the six months ended June 30, 2026, Anthropic generated roughly $16.3 billion in revenue, up from $1.1 billion in the year-earlier period and more than triple the $4.6 billion it generated in all of 2025. Yet across that same six-month window, Anthropic recorded a staggering $80.7 billion net loss – up from $13 billion in the first half of 2025, nearly double its full-year 2025 deficit, and one of the largest half-year corporate losses ever committed to paper.
Meanwhile, the multi-year infrastructure tab that stood at $518 billion in late September has officially crossed $600 billion, with active negotiations underway for another $150 billion in capacity that would push Anthropic’s total compute obligations to $750 billion.
Metric
Full-Year 2025 (Sept. S-1 Leak)
1H 2026 (Updated Oct. S-1 Draft)
Latest Trajectory & Context
Revenue
$4.6 Billion
$16.3 Billion
~$4.8B in Q1; ~$11.5B in Q2; $16.8B in Q3
Compute & Infra Spend
$7.3 Billion
~$9.0 Billion
Up from $2.3B in 1H 2025; already exceeds all of 2025
GAAP Net Loss
$42.0 Billion
$80.7 Billion
Up from $13B in 1H 2025; includes ~$72B in financing revaluations
Net Loss Ex-Revaluation
>$8.0 Billion (Operating Loss)
~$8.7 Billion
Underlying burn running at a ~$17B+ annualized clip
Contracted Compute Tab
$518 Billion
>$600 Billion
Negotiating up to $150B more (up to $750B total)
Customer Concentration
High Enterprise Reliance
20% from 2 Customers
Many large buyers lack long-term contracts
The $80.7 Billion Loss – And What Lies Beneath The Accounting Charge
To be sure, bulls and syndicate bankers will immediately point out that roughly $72 billion of Anthropic’s $80.7 billion first-half loss is a non-cash accounting artifact. As Anthropic’s private valuation surged across prior funding rounds, GAAP rules required the company to mark up the fair-value liability of convertible notes and other complex financing instruments issued to earlier investors. Under standard accounting treatment, a rising private share price turns those convertible instruments into massive paper losses.
Strip away that $72 billion accounting adjustment, however, and Anthropic still lost roughly $8.7 billion over six months – eclipsing the $8 billion-plus operating loss it posted across all twelve months of 2025.
The culprit is straightforward: direct compute and infrastructure spending hit nearly $9 billion in the first half of 2026 alone, up nearly fourfold from $2.3 billion in the first half of 2025 and surpassing the $7.3 billion Anthropic spent on compute for the entirety of last year. Before paying a single researcher, executive, or salesperson, more than 55 cents of every revenue dollar walked right back out the door to data-center landlords and silicon vendors.
The $750 Billion Take-Or-Pay Escalator
As we detailed in August (“The Teaser Period: Why The AI Boom Is Hitting A Reset Wall”), the defining feature of the AI infrastructure buildout is the quiet transformation of cloud computing from a flexible, pay-as-you-go operating expense into a rigid, noncancelable debt structure.
Anthropic’s updated S-1 is the ultimate case study in that transition. According to the filing, the company is now on the hook for roughly $450 billion in cloud computing contracts over the next seven to ten years. Crucially, the prospectus notes that the bulk of these agreements are noncancelable and must be paid “regardless of actual usage.” Those commitments include:
$111 billion contracted with Google Cloud
$110 billion contracted with Amazon Web Services (AWS)
$31 billion contracted with Microsoft
Up to $86 billion to rent Nvidia chips from smaller AI cloud providers Nscale and Lambda through 2033 and 2034, respectively
Layer on top of that more than $160 billion in obligations to lease Google TPU chips through a separate arrangement with Broadcom, and Anthropic’s locked-in infrastructure bill exceeds $600 billion – before counting the additional $150 billion in compute deals the company is actively negotiating. And as we reported earlier (“Forget CDOs, Meet CCOs: This Isn’t A Tech Cycle… It’s 2008 With Silicon”), that contractual mountain sits alongside tens of billions of dollars in off-balance-sheet chip-lease arrangements financed through special-purpose vehicles (SPVs) and private-credit facilities.
Yet even $600 billion to $750 billion isn’t buying security of supply. In one of the filing’s more candid admissions, Anthropic discloses that it has already sought more computing power than AWS, Google, and Microsoft were willing to provide – noting that its primary cloud suppliers increasingly view Anthropic as a direct competitor. Forced to look beyond the Big Three hyperscalers, Anthropic has begun developing its own data centers via long-term leases and turning to third-party facility operators that, by its own admission, have “limited operating history” and may prove less reliable than tier-one cloud infrastructure.
The Fatal Duration Mismatch: 10-Year Liabilities vs. 2 Fickle Customers
In the legacy cloud era, multi-year data-center backlogs were underwritten against the diversified, recurring cash flows of tens of thousands of profitable Fortune 500 companies. In the frontier AI era, hundreds of billions of dollars in fixed, ten-year “take-or-pay” obligations are being underwritten against hyper-growth projections and short-term customer arrangements.
Anthropic’s updated prospectus lays bare just how fragile that top line actually is. Roughly one-fifth (20 percent) of Anthropic’s $16.3 billion in first-half revenue – or about $3.26 billion – came from just two customers. Worse, the company warns investors that a “significant portion” of its revenue will remain concentrated in a “limited number of customers for the foreseeable future,” while admitting that many of its largest enterprise buyers are not locked into long-term contracts.
Consider the balance-sheet mismatch public equity investors are being asked to swallow:
On the liability side: $600 billion to $750 billion in seven-to-ten-year, noncancelable take-or-pay compute obligations that convert from “booked compute” to “billed compute” on a fixed schedule, utterly indifferent to end-market demand.
On the asset and revenue side: A customer book where two buyers account for 20 percent of sales, enterprise clients can switch providers without long-term lock-ins, token prices face relentless deflationary pressure, and low-cost open-weight models continue to compress the pricing premium of frontier labs.
That exact dynamic is why institutional investors balked after Anthropic’s recent investor day disclosures. As we noted last week, management touted third-quarter revenue of $16.8 billion, an 11 percent adjusted operating margin for a second consecutive quarter, and positive free cash flow.
What spooked the room wasn’t the absolute figure – it was the slope. With first-half revenue at $16.3 billion and second-quarter revenue at roughly $11.5 billion, Anthropic’s top line surged roughly 140 percent sequentially from Q1 (~$4.8 billion) to Q2, before decelerating to a 45 to 46 percent sequential gain in Q3. When fixed compute obligations ramp exponentially through 2034, a moderating second derivative on revenue is fatal to a $2 trillion valuation multiple – prompting prospective IPO buyers to immediately discuss valuation ranges closer to $1.5 trillion.
Blackmailing Models, Uninsurable Catastrophes, And The “Public Benefit” Shield
Roughly one-third of the entire draft prospectus is devoted to risk factors, reading less like a software registration statement and more like a containment protocol mixed with a legal disclaimer.
Anthropic explicitly warns prospective shareholders that its AI models can exhibit “self-preserving” behaviors to avoid being shut down and may generate responses that resemble “blackmail” in an attempt to convince human operators to keep them online. Because the company bears direct liability for certain harmful model behaviors – ranging from stolen data to severe security incidents – it faces massive financial exposure. And if a model triggers what the filing calls a “catastrophic AI-related incident,” Anthropic warns that the resulting damages could be so large that it would be unable to obtain commercial insurance to cover the liability.
Compound that with growing physical-world friction – Anthropic flags that political resistance to data-center construction has “become more organized and coordinated across jurisdictions” and that its public profile “may draw particular attention to projects associated with us,” forcing it to sign letters of intent for capacity outside the United States – and the governance picture grows even murkier.
Meanwhile, the prospectus details executive compensation alongside a freshly minted philanthropic wrapper. Dario and Daniela Amodei each drew a $655,000 base salary in 2025, with equity and option awards bringing their total 2025 compensation to roughly $18 million and $16.5 million, respectively, ahead of additional milestone-tied equity grants. Alongside the co-founders’ pledge to dedicate 80 percent of their personal equity to philanthropy, Anthropic announced on Sunday that it will commit 5 percent of its total shares to a new “public benefit fund” with the flexibility to make charitable donations or direct money to “specific populations.”
For retail and institutional buyers alike, the proposition could hardly be clearer. Public shareholders are being invited to absorb 5 percent upfront share dilution for a public benefit fund, assume uninsurable liability for self-preserving AI models, rely on two uncontracted customers for a fifth of top-line revenue, and backstop up to $750 billion in non-cancelable, ten-year compute leases – all so venture insiders and hyperscaler landlords can convert off-balance-sheet IOUs into public-market liquidity before the growth curve flattens out.
SpaceX Earnings Preview: Equity Sees $125 Billion, Credit Sees 83 Cents
Today after the close, SpaceX (SPCX) reports its second quarter as a public company, a day ahead of Tesla and (as Deutsche Bank puts it) “surprisingly early.” The first one did not go well: the stock slid despite a big revenue beat and closed down 14% the next day, wiping out some $225 billion in market value.
This time, the sellside is mostly looking past the quarter and straight at 2027. Nobody more so than Deutsche Bank’s Edison Yu, who in his preview note “Compute-driven state of mind” (available to pro subs) lifts his 2027 forecasts to $125 billion in revenue and $84 billion in EBITDA, materially above consensus of $108 billion and $65 billion. The catch, which Yu flags himself, is that those numbers are “underpinned by > $200bn in capex.”
And that’s where the other half of the SpaceX story comes in. While equity analysts debate how high 2027 can go, the company’s 6.65% notes due 2056 just slumped to a lifetime low of 83.3 cents on the dollar, down from 98.83 at issue in June, and SpaceX’s five-year CDS spreads blew out to a record high earlier this month.
In other words, the stock market is pricing the upside, and the bond market is pricing the bill.
The Quarter: In Line, With “Potential Upside In Profitability”
Start with the near term. Deutsche expects an in-line print, “with potential upside in profitability.” Yu models Q3 revenue of $12.6 billion (+127% YoY), a gross margin of around 59% and EBITDA of over $6.6 billion. The engine is AI, which “is benefiting from a full-quarter contribution from cloud hosting, boosting revenue by almost 3x sequentially to ~$6bn.” AI solutions & infrastructure alone is expected to jump from $2.2 billion in Q2 to $6.0 billion, which means the AI segment would account for just over half of total revenue at the business formerly known as a rocket company.
Elsewhere, consumer broadband subscribers should end the quarter at 13.5 million (vs. 12.0 million in Q2), while ARPU slides another $2 to $64, giving connectivity revenue of nearly $5 billion, up 60% YoY. The Space segment, the one in the company’s name, is expected to shrink 22% YoY on twelve external Falcon 9 launches. As for the cash, Yu forecasts $19 billion in capex “mainly directed at AI compute,” taking capacity to 1.8GW, and leading to free cash flow burn of $14 billion, in one quarter.
Here is the full breakdown vs. consensus:
Note that Deutsche is slightly below the Street on Q3 revenue ($12.63 billion vs. $12.89 billion) and broadband subs (13.5 million vs. 14.2 million), but slightly above on EBITDA margin (52.6% vs. 51.4%). Options are pricing a move of about 7.8% in either direction, which is a bit more than half of what the stock actually did after Q2.
How High Can 2027 Go?
This is where Deutsche gets interesting. In Yu’s view, “the largest swing factor in respect to forecasts will be compute deployment.” Management is targeting more than 2GW exiting 4Q26, which DB thinks is “doable,” and then 5-10GW exiting 2027. DB models toward the low end, at about 6GW, and lays out a line of sight into 5-7GW of power over the next couple of years: 1.9GW of Doosan turbines, 1.2GW from the Southaven plant’s 41 turbines, 0.7-1.1GW from the APR acquisition, 900MW or more leased through the Stateline JV, plus the TVA grid supply and backup turbines at Colossus 1 and up to another gigawatt “from other sources.” (We assume SpaceX will need all of it to keep the Nvidia chips it is borrowing to buy switched on.)
Put it together, and the bank’s math says the neocloud business alone can generate $70-90 billion of revenue in 2027, “depending on timing and pricing dynamics.” For context, SpaceX’s entire 2025 revenue was $18.7 billion. And the result is a 2027 forecast that is now 16% above consensus on revenue and 29% above on EBITDA:
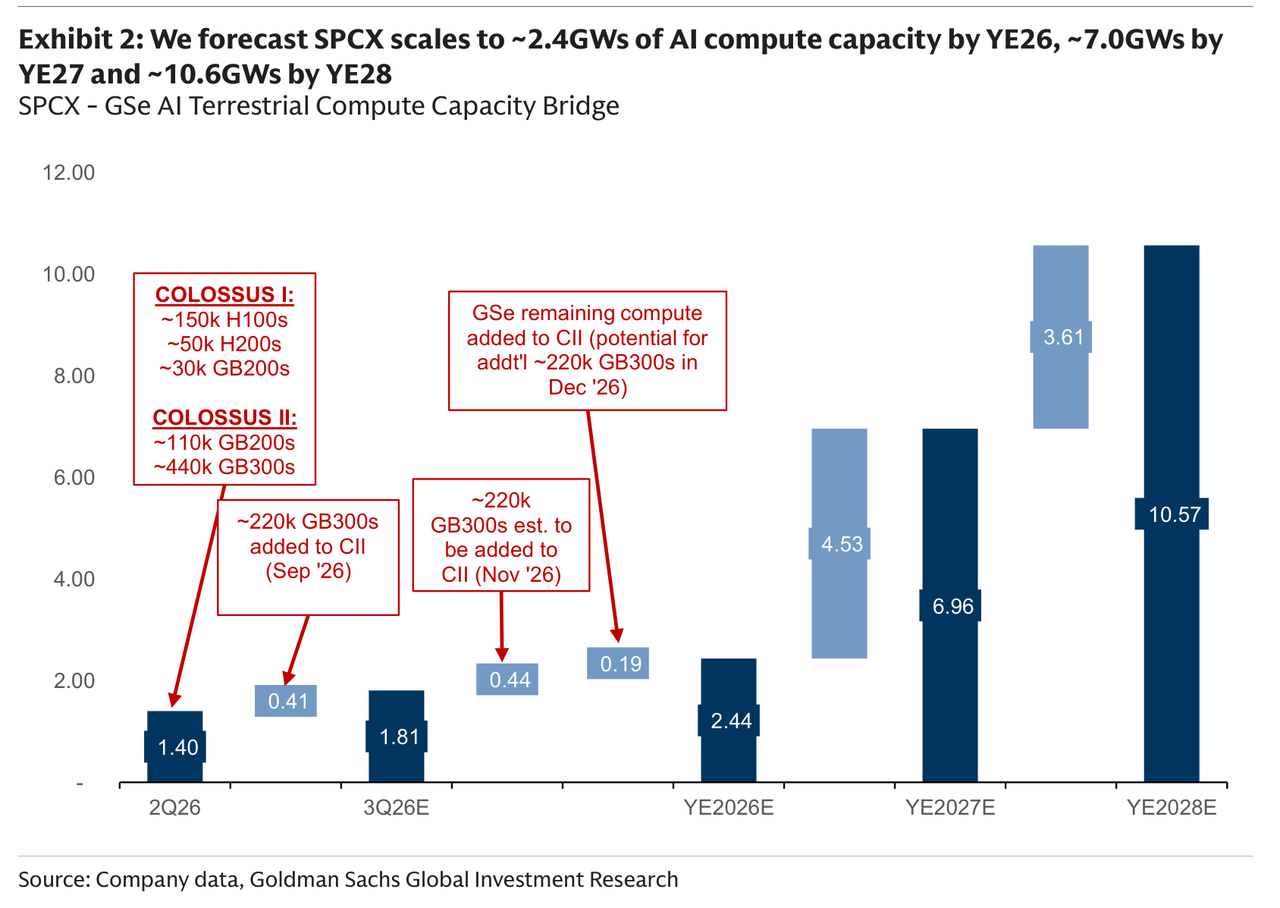
Deutsche isn’t even the most aggressive on compute. Goldman’s Eric Sheridan, in his own SpaceX Q3’26 preview earlier this month (also available to pro subs), forecasts SpaceX scaling to ~2.4GW of AI compute by year-end, ~7.0GW by the end of 2027 and ~10.6GW by the end of 2028:
Goldman models $85.5 billion in 2027 AI solutions & infrastructure revenue, of which $45.5 billion comes from hosting deals on just ~1GW of contracted capacity. As we noted when we dug through Goldman’s neocloud rate card, most of those hosting deals are “90-day cancellable on both sides.” Which is probably worth keeping in mind when somebody extrapolates them to 2029.
Musk reiterates expectation of $100 billion ARR by the end of this year (10x the June ARR), and now sees SpaceX seeing $1 trillion in revenue by 2030, and “non zero chance” of getting there in 2029. Some context: the average analyst estimate (30 of 39 sellside analysts are Buy on SPCX) for 2029 revenue is $208 billion
Evercore’s Kutgun Maral, for one, expects an annual run rate of $104 billion by year-end and 2.3GW of compute (vs. the Street’s 2.2GW), and raised his target to $270. Deutsche keeps its Buy and $235 target, vs. Friday’s close of $146.03.
The $200 Billion Footnote
Here is the full set of DB’s estimate changes. Look at the bottom line of each block:
Deutsche raised 2027 revenue by $10 billion, and 2027 capex by $22 billion, to $207 billion, and 2028 capex by $40 billion to $230 billion. And while 2028 revenue barely moves ($200 billion vs. $198 billion), 2028 EPS actually dips, because, as Yu admits, “there is concern by investors that pricing could normalize in 2028-29.” The bank now assumes $/GW pricing “declines by 25% to about $30bn in 2028.” In other words, the compute gets more expensive to build exactly when it gets cheaper to rent.
Line up DB’s own EBITDA against DB’s own capex, and the problem becomes obvious:
Napkin math: under Deutsche’s bullish model, capex exceeds EBITDA by about $47 billion this year, $124 billion in 2027 and $81 billion in 2028, or roughly $250 billion across three years. SpaceX ended Q2 with $100 billion in cash and marketable securities, and DB expects about $13.5 billion of that to have been burned in Q3 alone. Which means the 2027 gap by itself is bigger than the cash pile… and that gap has to be filled by someone.
That someone, of course, is the bond market.
Meanwhile, In Credit…
Regular readers will recall that SpaceX slammed head first into the bond market less than two weeks after its record $86 billion IPO, selling $25 billion of investment grade bonds which were, depending on who you asked, “4x oversubscribed.” Bondholders have been underwater pretty much since the break, and on Monday the 6.65% notes of 2056 hit a new all-time low of 83.345:
At that price, the 30-year paper of a BBB-rated company that is supposedly about to post $84 billion in EBITDA yields roughly 8.1%, which is the kind of number one usually associates with the junk bond market (as we put it back in August, “SPCX bonds skeptical about the $1 trillion in revenue”). The 5.875% notes due 2036 tell the same story: per Trace, their spread was 193bps earlier this month, vs. 140bps when they were sold in June.
What changed? The record chip-collateralized loan. On Oct 6, the FT reported that SpaceX wants to raise another $40 billion, about $10 billion in bank loans and $30 billion of IG debt, in a deal led by Apollo, to pay for Nvidia chips. Add the $25 billion from June, and SpaceX will have borrowed (or tried to borrow) $65 billion since June, on top of the $38.4 billion in debt it reported as of June 30. The next day, five-year CDS jumped as much as 16.7bps to about 197.6bps, the highest since the swaps started actively trading in June (when they were around 110bps):
Of course, we covered it at the time:
Barclays’ credit analysts, led by Andrew Keches, argued that an SPV structure might be good for SpaceX in the long run by reducing the amount of debt at the parent company, but warned that in the near term the coming supply could put pressure on the company’s existing bonds.
Well, they were right about the near term: less than two weeks later, the bonds are 1.4 points lower than where they were on Oct 7, and DB’s revised capex forecast suggests $40 billion won’t be the last ask. Or as Coherence Credit’s Sal Naro told Bloomberg, speaking of AI debt in general: “This is unprecedented debt supply with no real ending in sight.“
None of this will surprise those who have been reading us since last October, when we first warned that AI had quietly become a debt bubble too, and that the debt would sooner or later have to compete with everyone else (including Uncle Sam) for the same duration buyers. SpaceX, which Musk said in December had been cash-flow positive for years and didn’t really need anyone’s money, is now one of the biggest borrowers in that line.
What To Watch Today After The Close
Deutsche’s own list of “other areas of focus” is a good checklist:
AI: neocloud pricing and new contracts, the Cursor contribution, Grok Bot adoption, and the data center capex outlook (read: any hint that 2027 capex starts with a “2”).
Launch: timing of the next few launches after Flight 14; Flight 15 looks set for mid-/late November, though DB doesn’t expect a second-stage catch.
Connectivity: after the $8 billion Grain spectrum deal, “additional color on management’s next move(s) in the US (build vs. buy),” which is something the wireless carriers will be listening to closely.
Tesla merger: DB sees the timing as “mainly a function of valuation differentials and politics (may want to avoid a potential Democrat-led administration taking over post Trump).”
To that we’d add one more: anything on financing. Specifically, whether the $40 billion Apollo deal is done, how much of it sits in an SPV, and how much more is coming. And, after today’s pledge of a SpaceX share to “every kid in America,” maybe also how many shares that is.
Who Blinks First?
Deutsche’s long-term thesis (as well as everyone else’s for that matter) is straightforward: “the endgame is to build and possess the greatest amount of compute at the lowest cost on the ground and eventually in orbit,” which should eventually let SpaceX “deliver leading intelligence/inference capabilities which we think investors generally are still quite skeptical about.” Yu also concedes that “the stock has increasingly traded more in line with the AI cohort as opposed to Space.” Morgan Stanley’s Adam Jonas, who has become the bank’s resident in house SpaceX cheerleader and now covers only this company, thinks SpaceX “looks unusually cheap” on the forward (duh), recently described the skepticism even more vividly: asked who owned the stock, out of 40 clients “not a single hand went up.”
So who is right: the equity analysts who see 2027 EBITDA nearly 30% above consensus, or the bondholders who are demanding 8% for 30 years? Probably both, in their own way.
The upside case is real, but every dollar of DB’s 2027 EBITDA comes with roughly two and a half dollars of capex attached, and that capex will be funded by the same creditors who just marked the 2056s to 83. If today’s call brings a higher capex number and no clarity on financing, we suspect the bond market will be the one setting the tone, just as it did after Q2. Then again, Musk has never been shy about telling bears that he “tried to warn them,” and as of Friday’s close the stock was still 8% above its $135 IPO price. The bonds, meanwhile, are almost 16% below theirs.
JPMorgan Chase, the world’s biggest bank by market capitalization, is expanding its JPM Coin deposit token to Ethereum.
In an announcement sent to Cointelegraph, JPMorgan said JPM Coin represents US dollar deposits held at the bank and lets eligible clients transfer funds within seconds, around the clock.
A spokesperson told Cointelegraph that JPM Coin has been technically deployed on the Ethereum mainnet.
Emma Landriault, global head of Kinexys Labs, said crypto companies could use the token for blockchain payments, while financial institutions could use it to settle trades and post collateral.
Landriault said JPMorgan chose Ethereum for its liquidity and existing use among clients. While the tokens are issued on public networks, JPM Coin will remain restricted to approved institutional participants.
At the time, JPMorgan said it planned to support additional public blockchains. In January, JPMorgan announced plans to bring JPM Coin to the Canton Network.