67.9 F
Chicago
Saturday, September 19, 2026
Home Blog Page 2911

Yield-Curve Bear-Steepening Spells Trouble For Markets

0
Yield-Curve Bear-Steepening Spells Trouble For Markets

Authored by Simon White , Bloomberg macro strategist,

The yield curve has proven a poor (or very early) recession indicator in this cycle. This year, though, it will be far more useful in describing the evolution of liquidity and of funding markets, both critical to highlighting when the stock rally might be about to flounder.

Specifically a bear steepening – longer-term yields rising more than shorter-term ones – will indicate that liquidity and money velocity are in jeopardy from rising government interest payments, and that funding markets are approaching the point where reserves could shift from abundant to scarce abruptly.

Both will imperil risk assets.

Stocks and other risk assets face the perfect storm if longer-term yields continue to outpace their shorter-term counterparts in a bear steepening of the yield curve. An increasingly plausible re-acceleration in inflation makes this outcome more likely.

This year, jettison the yield curve as a recession predictor. With ever more blurring of fiscal and monetary policy, 2024 will be a liquidity battle between government interest payments and funding markets. Rather than anticipating a downturn, the yield curve will have enormous utility as a barometer of liquidity and funding conditions, and thus will act as a leading indicator for when risk assets are about to run into trouble.

A persistent bear steepening of the curve is the worst outcome for markets, as it implies Treasury bills are likely to continue being attractive to money market funds (MMFs), depleting the Federal Reserve’s reverse repo (RRP) facility and thus increasing the likelihood of funding stress.

At the same time, rising yields at the longer end of the curve will inflame the government’s already soaring interest bill, acting as a hoover on monetary velocity. The longer the steepening curve persists, the greater the chance that the economy and stocks – already facing an options-driven risk of a blow-off top – flounder.

Ironically, the issue lies in what was initially a solution to last year’s potential problem: markets facing steep selloffs due to heavy government issuance. The Yellen pivot — the Treasury’s decision to skew issuance toward T-bills — allowed MMFs to sop up the new debt using idle liquidity parked at the RRP, preventing the surfeit of government borrowing from crowding out risk assets.

The Yellen pivot is expected to continue for now. That means the yield curve should resume steepening. A rise in bill issuance would typically be expected to lead to a flatter yield curve as yields at the front-end rise, but that’s not what we observe. As can be seen in the chart below, rising bill issuance tends to lead to a steeper curve.

How so? Well, if bill demand is elastic, then rising issuance has little impact on the yield, while the increased short-term supply pulls demand away from longer-term tenors, and the curve steepens.

That outlook neatly tallies with the message from other leading indicators of the yield curve, such as excess liquidity. It’s also what most still currently expect. But what type of steepening we get matters greatly.

The curve has been bear steepening lately, and if inflation comes back on to the scene as I expect it to — and as this week’s CPI data hints it might already be doing — such steepening is likely to persist.

That’s bad news for markets, however. Rising longer-term yields will further swell the government’s already ballooning interest bill.

The 10-year yield does an excellent job of leading the US’s interest expense as a proportion of its debt outstanding.

Rising interest payments destabilize liquidity by reducing reserve velocity. Not so fast, you might say, as most interest is paid to the public and thus the proceeds continue to circulate in the economy. But only the household and corporate sectors are likely spend the interest remitted to them — yet they are the smallest holders of Treasuries, accounting for only about 10% of the issuance outstanding.

Financials, the biggest owners, are more likely to reinvest interest paid to them in financial assets. The money to pay the interest, which comes from tax payments or more borrowing, is met with bank deposits. The net result is that the reserves are still in the system, but they are held by savers with a lower propensity to spend, and so their velocity falls.

The relationship in the chart above projects the annual interest expense could be as high as $1.4 trillion (from $980 billion currently) within six months, based on where 10-year yields are.

That’s less than the Congressional Budget Office’s latest projections. It sees it at $1 trillion in 2026 and $1.6 trillion in 2034, or 3.9% of GDP. But take these numbers with a clump of salt. Shown in the chart below along with the CBO’s interest projections is its forecast of the 10-year yield over the next decade. Readers can decide for themselves if they think its projections are realistic, and thus the likelihood the interest bill could be much higher than the CBO’s predictions.

That’s already a terrible backdrop for risk assets. And there’s more bad news. The Treasury’s bill issuance is increasing the likelihood of a flare-up in funding markets, by keeping bill yields attractive enough for MMFs to carry on drawing down the RRP.

While this was beneficial for risk assets last year, as quantitative tightening continues and the so-called lowest comfortable level of reserves (LCLOR) is approached, it means we are nearing the “event horizon” in funding markets, where reserves can go from abundant to scarce in a heartbeat.

As discussed in a previous column, one prior portent of funding problems has been a sudden drop in fed funds (i.e. reserves) volumes, followed by a rapid rise — like a tsunami wave, drawing back before surging forward and releasing its force.

Reserves have risen lately and are still higher than they were when the Fed began QT in 2022. But the RRP has been falling, taking the sum of reserves and the RRP steadily lower. That typically means lower fed funds volumes and a harbinger of funding stress.

Encapsulating this is the Funding Stress Trigger (explained here), designed to go off ahead of a sharp rise in funding rates that will destabilize risk assets if left unchecked.

This year will thus see a delicate interplay between three things:

  • by how much higher yields absorb liquidity from the system;

  • how much liquidity they attract from the RRP; and

  • when total reserves in the system are about to become scarce.

The time horizons these operate over are different: the effect on liquidity from rising interest payments will happen over a period of weeks and months, while the impact from bill issuance and the RRP can be almost immediate.

Nonetheless, to give a very rough back-of-the-envelope idea, consider what happened after Tuesday’s higher-than-expected CPI print. Ten-year yields are about 12 bps higher since then, and three-month yields about two bps higher, i.e. a bear steepening of ten bps. Using the 10-year yield as a proxy for the interest expense predicts a potential rise of about $30 billion, while the domestic RRP fell about $27 billion on Tuesday.

The steepening thus indicates a weaker liquidity backdrop and a funding market closing in on levels of reserves that could abruptly trigger funding stress, neither of which are supportive of risk assets.

So: park the yield curve as a recession tool, and if you’re long risk assets, pray it doesn’t continue to bear steepen.

Tyler Durden
Thu, 02/15/2024 – 14:05

The Incoming Gold Shortage Nobody Is Talking About

0
The Incoming Gold Shortage Nobody Is Talking About

Authored by Peter Reagan via Birch Gold Group,

When private money follows central banks, will there be enough gold to go around?

Having been a bank director, Alasdair MacLeod knows a thing or two about the health of the banking system, and how to spot one that’s contracted something. Talking to Liberty and Finance, MacLeod explained that the banking crisis we’ve been seeing is very much a top-down issue starting from central banks.

Watch here, or read on for my summary and analysis:

It’s a tale as old as bailouts: if the average person managed their money as badly as big banks, they wouldn’t have a penny to their name. But then the same applies to an even greater extent in comparison between central and private banks, says MacLeod, with the former having basically zero accountability.

Liquidity is another thing they’re lacking, to summarize MacLeod’s lengthy and well-presented overview of the banking sector.

Most interestingly, perhaps, MacLeod says that central banks aren’t so much buying gold as they are getting rid of paper currency. We’ve all heard of this interpreted as diversification or de-dollarization. Maybe that’s just a polite way of talking around the issue. In reality, central banks are using paper money to buy gold – and not just foreign currencies, but their own as well.

Why would they do that? MacLeod says we only need to look to gold’s fundamentals for an answer. By 2025, the U.S. federal government will owe some $40 trillion in debt, which (if you’ll forgive the pun) there’s absolutely zero interest in ever paying off. Politicians might talk about balancing the budget, they might hand-wave about paying down the debt. Instead of listening to what they say, watch what they do. Find any elected government official willing to spend less on his own constituents – I challenge you.

I just don’t think the federal government is able to pay down its debt. Not without truly massive changes to “business as usual.” Interest payments already set us back over $1 trillion in the fourth quarter of 2023! As we’ve noted many times, inflation is the preferred method of “paying off” debt a government owes in its own currency.

To this end, MacLeod notes that governments are printing trillions in currency annually to prop up their economies with limited results – other than the certainty of inflation and higher interest rates down the line. As interest rates rise, money-printing will accelerate to match, resulting in even higher inflation to offset the debt and relieve pressure. (And to think, we’re yet to experience the effects of a single rate cut despite the current high rates!)

Despite gold’s price rising over the last three years, MacLeod believes we aren’t really seeing a bull market yet. He says that interest in gold is disappointing, with nearly every investor, public and private, severely underweight in gold. MacLeod estimates that, of the $150 trillion in global savings, less than 1% is currently in gold.

Nevermind prices: when these portfolios adjust to 5%, 10% or even what MacLeod finds a more reasonable 15%, where is the gold going to come from? Merely adjusting to 2% would require 23,000 tons of physical gold! That’s 10% of all the gold mined in human history…

We already know what a 1,000 ton annual purchase for two consecutive years does for gold. We’ve seen it over the past two years with the official sector. Since central banks aren’t likely to stop these purchases, MacLeod leaves us wondering just how soon the rest of the world will catch on.

When $150 trillion in global savings begins to diversify with gold, just how fast and how far will gold’s price rise?

Goldman targets $2,175 gold price; TDS predicts gold at $2,200 this summer

Will gold ever drop below $2,000/oz again? We’ve taken care to note how bearish outlooks have been coming in with increasingly lofty figures. Here is a quote from the research report:

The metal has been trading between $2,000 and $2,050, with the market adjusting to the Federal Reserve’s hawkish stance and delaying rate cuts until June 2024.

In other words, $2,000 to $2,050 are now “business as usual” targets. We find this to be a triumph of its own for gold prices, but of course, there is a whole lot more growth on the horizon. Goldman Sachs’ analysts are maintaining their $2,175 12-month target, citing both economic and geopolitical reasons for the forecast.

Tyler Durden
Thu, 02/15/2024 – 13:30

“This Is Scary”: Soros Prepares Takeover Of 200 Radio Stations Ahead Of US Presidential Election

0
“This Is Scary”: Soros Prepares Takeover Of 200 Radio Stations Ahead Of US Presidential Election

America’s second-largest radio broadcaster could soon emerge from bankruptcy with a new shareholder: Soros Fund Management. 

According to Bloomberg, the investment firm founded by the Trump-hating billionaire George Soros has acquired $400 million of Audacy’s highest-ranking debt. 

“The decision by our existing and new debtholders to become equity holders in Audacy represents a significant vote of confidence in our company and the future of the radio and audio business,” Audacy wrote in a statement. 

Audacy owns 235 radio stations in 48 media markets across the US and is the second-largest broadcaster behind iHeartMedia. 

“Under Audacy’s bankruptcy plan, existing shareholders would be wiped out and high-ranking creditors would be repaid with stock in the restructured company. The proposal requires bankruptcy court approval,” Bloomberg noted. 

An insider familiar with the matter, who identified as a Republican, expressed grave concerns that Soros might be acquiring the stake to sway public opinion ahead of the 2024 presidential election, according to The New York Post

“This is scary,” the source said.

Another source explained to NYPost that Soros’s stake equals about 40% of the company’s senior debt, although not a majority, and could yield effective control of the broadcaster when it emerges from bankruptcy. 

Last summer, Soros joined a group of lenders, including Fortress Investment Group, who paid $350 million for bankrupt Vice Media – a leftist media outlet that once commanded a $6 billion valuation

Unfortunately, broadcast radio and TV are in significant decline. Suppose Soros believes he can wield propaganda power through acquiring legacy media. In that case, he should reconsider the target audience demographics—hardly anyone with a smartphone and computer tunes in regularly to the radio. 

Also, Audacy better watch out so it doesn’t ‘Bud Light’ itself among conservatives. 

Tyler Durden
Thu, 02/15/2024 – 13:10

Fani Pounded As Nathan Wade Testifies To Cash Money ‘Reimbursements’ And Former Friend Flushes Her Defense

0
Fani Pounded As Nathan Wade Testifies To Cash Money ‘Reimbursements’ And Former Friend Flushes Her Defense

$hit has really hit the Fani in Fulton County.

On Thursday, special prosecutor Nathan Wade testified under oath that he charged several lavish vacations with DA Fani Willis to his corporate credit card while working on the Trump case, and was later reimbursed in cash by Fani.

The relationship between Wade and Willis is the subject of an evidentiary hearing as part of Willis’ sprawling racketeering case brought against former President Donald Trump and 18 co-defendants for their alleged efforts to overturn (or ‘correct’ – depending) the results of the 2020 US election in Georgia.

Wade also testified that his marriage was “irretrievably broken in 2015,” and that his wife agreed to a divorce – but they held off because their children were still in school. 

Oh…

Fani fudged…

In a confirmation of what we reported last week from Wade’s divorce proceedings, a former “good friend” of Willis’ testified that her romantic relationship with Wade began after they met at the judicial conference in the fall of 2019, directly contradicting assertions made by Willis in court filings about the timing of their relationship. Willis claimed that she and Wade “have been professional associates and friends since 2019,” and that “there was no personal relationship” between her and Wade in Nov. 2021 when she hired Wade and paid him over $600,000 to help her prosecute Trump.

Appearing before Fulton County Superior Court Judge Scott McAfee via Zoom, Yeartie said Willis and Wade may have begun dating in October or November 2019, shortly after the two met at the conference that year.

During questioning from Sadow, who is representing Trump in the case, Yeartie testified that Willis told her she was engaged in a romantic relationship with Wade in 2020 and 2021, and said she witnessed “hugging, kissing,” and “just affection” between the two before November 2021, when Wade was hired by Willis. -CBS News

Fulton County DA’s office lawyer Anna Cross attempted to raise doubts about Yeartie’s credibility, asking her questions about her performance while working for Willis, and whether she was ever disciplined for poor performance. Yeartie admitted that she’d been written up once, referencing a “situation” in which she was told she would be terminated if she didn’t resign.

This adds to previous reporting suggesting that Willis paid Wade’s divorce attorney!

You can watch a recap of Wade’s testimony below:

Tyler Durden
Thu, 02/15/2024 – 12:30

Another Mega-Merger Is Brewing In The U.S. Shale Patch

0
Another Mega-Merger Is Brewing In The U.S. Shale Patch

By David Messler of OilPrice.com

Summary:

  • Devon Energy seeks to fill gaps in its Bakken acreage through potential merger with Enerplus.

  • Enerplus’ high-productivity assets and low lease operating costs make it an attractive target for Devon.

  • Shareholder dissatisfaction looms amidst Devon’s past acquisitions and declining stock performance.

The merger and acquisition deals are coming in the shale patch, at a rate almost too fast to document. Last week news broke about Devon Energy, (NYSE:DVN), and Canadian-based producer, Enerplus, (NYSE:ERF) opening merger talks. Enerplus has some choice acreage in the Bakken play that would be very attractive to Devon as it fills in a lot of gaps in its own prime Bakken acreage. They also hold some non-operated acreage in the Marcellus, that would likely be sold off as Devon has no other operation in that basin. The Bakken is home to some of the longest shale laterals, and the ERF “jigsaw puzzle” pieces would assist DVN greatly in maximizing the production from the play.

Details are sketchy at this point, and I wouldn’t be surprised if ERF isn’t holding out for a cash premium given the liquids-rich “dirt”- 68%, they own. That would be the smart play for their shareholders. DVN has reached for its checkbook in its last couple of deals, for RimRock, and Validus. The stocks of both companies are off from peaks set in Q-3 of last year, DVN about 30% and ERF about 15%. This is the time to be merging with companies that can contribute immediately to the bottom line, and synergistically make Newco potentially a better entity than the two were separately. That’s what’s supposed to happen anyway.

The question arises, should Devon be the one buying? Here’s the problem with the moves Devon has made employing this fill-in-the-gaps, “bolt-on” strategy, from a shareholder perspective. They aren’t getting paid for it by the investing community! Perhaps ERF should be buying Devon’s Bakken acreage. The industrial logic works that way as well. We will table that thought for now, but return to it as we close out the article.

Put aside other factors, such as declines in oil and gas prices, and focus only on one thing. When Devon bought the RimRock acreage in June of 2022, the share price was $69. When they bought Validus in August of 2022, the stock price was $65. Since those halcyon days of 2022 when people talked glibly of $100 WTI going back to $120, DVN stock has nose-dived, along with WTI, to be fair, into the low $40’s. $2.7 bn in cash later and investors have lost 40% of their capital. This is the sort of thing that attracts activist investors, and it wouldn’t surprise me to see Engine #1 or Carl Icahn take a sizeable position to get board seats and start swinging a meat axe.

In this article, we will compare a couple the Devon/ERF potential merger with another M&A transaction now in process. There are some glaring differences that should put the proposed deal between Devon and Enerplus in the proper frame.

ExxonMobil and Pioneer Natural Resources

There is a limit to how far you can go comparing a Super Major like ExxonMobil, (NYSE:XOM) and even a large U.S.-focused shale producer like Devon Energy. That said, the “Industrial Logic” behind the XOM deal with Pioneer is evident if you look at the pro forma acreage footprint in the Midland basin, in the slide below. The difference between what ExxonMobil is doing with its merger with Pioneer and what Devon is proposing to do with Enerplus is that the former is enhancing its core acreage position in the most prolific shale basin in the country. It remains to be seen if XOM shareholders will reap any bounty, at least over the short term, from this deal. XOM stock was $112 in October, of 2023 when it was announced, and trades just above $100 today.

Devon, on the other hand, has been expanding into other shale plays, to take advantage of regional aspects of each. The problem with that approach is Devon has not performed in the top percentile in these other basins, nor have they delivered growth to their shareholders.

As noted, Devon’s share price has collapsed with each additional deal, while the management of Pioneer has delivered growth to its shareholders by focusing on expanding its empire in the Permian. In 2021 PXD’s $6.4 bn acquisition of Double Point Energy raised some eyebrows coming on the heels of its $7.6 bn (cash and debt assumption) acquisition of Parsley Energy. Nearly $14 bn in acquisitions in half a year, for a company Pioneer’s size was a bold move by management.

Pioneer filings

Pioneer wasted no time in monetizing assets from the Parsley Energy pickup, selling the Delaware basin acreage to Continental Resources for $3.25 bn in late 2021. Shareholders of Pioneer received $21.68 in regular and special dividends in 2022, and capital growth from $140 per share in early 2021 to the final sales to XOM of $253 per share. By any measure, shareholders of Pioneer have benefited from the shrewd empire-building in the Midland basin.

Scott Sheffield, Pioneer’s long-time CEO, and the architect of the empire in the Midland basin that drew ExxonMobil’s eye, is retiring this year at the top of his game. Capping his career with the company sale to XOM, he is set to receive a payout of cash and stock of $151 mm, according to this Bloomberg article. I expect few PXD shareholders will begrudge him this magnificent payday.

Let’s now look closer at what Devon hopes to achieve with the multi-billion dollar acquisition of Enerplus.

The DVN and ERF Industrial Logic

Here is what Devon management told us about the RimRock acreage pickup. The slide directly below discusses its “industrial logic.” As you can see, the rationale was obvious as the RimRock acreage facilitated several aspects of shale development laterals, optimized well spacing, critical mass-higher output, in theory-lower production costs, and enhanced logistics. 

They ticked every box, and shareholders were promised that increased free cash flow generation would result and increased amounts of cash would be returned to them. As previously noted, Devon Energy’s stock went from $69 to $65 per share in just a few months. What actually happened? Free cash declined from 60% of operational cash flow-OCF in 2021 to 40% of OCF in 2022. What about shareholder returns?

Dividends paid out to shareholders went from $1.97 in 2021 to $5.17 in 2022 but declined to $2.87 in 2023. If you add the value of share buybacks-$4.65, over this period, it gets better, but at a total of $12.67 all-in, Devon shareholders have fared much more poorly than PXD shareholders, with no capital appreciation to sweeten the medicine!

Now we come to the basics of what ERF might mean to DVN. Or what DVN’s Bakken acreage might mean to Enerplus.

The fit between ERF’s footprint in Dunn, and McKenzie counties becomes apparent when you transpose it against DVN’s current footprint in the slide above. The Industrial Logic only gets better with the two combined, when you look at the blocky acreage in Willams County. The three counties mentioned here are in the top ten and top twenty shale-producing counties nationally, according to my industry sources.

There is another aspect to DVN’s interest in ERF. Enerplus is killing it in productivity. If you look at the slide above the YoY growth rate from 2021 to 2022 is 13%. DVN’s Williston output by comparison has been fairly flat during this period. Industry sources confirm to me that ERF is one of the top producers in this basin, landing in the top 15 nationally. In their last conference call, DVN management noted a decline in the Bakken and a shift of capital focus to the Delaware basin.

Finally, on LOE-lease operating costs. Company filings reveal that ERF is light years ahead of DVN, coming in at $10.75-11.00 in Q-3, vs $13.04 for DVN. DVN reports a cash margin in the Williston of $32.14 on realized pricing of $52.64. If they had ERF’s numbers it would correlate to an 8% bump higher.

DVN last paid $23K per acreage to RimRock, so I expect that will be a starting point for ERF’s consideration. An equivalent offer for their 236K acres would total in the neighborhood of $5.4 bn, making quite a windfall for ERF shareholders with the company’s current capitalization of $3.15 bn.

I expect the cash side of this deal is the hard part. After shelling out ~$900 mm for RimRock and $1.8 bn for Validus in the last couple of years, DVN only has $1.3 bn in cash on the books. Just hypothesizing, if they were to put $1 bn in cash and use debt for 40% of it, leaving a share exchange for the other ~45%-say ~$2.0 BN, the cash flow would pay out the purchase pretty quickly. Figuring price realizations at $55, and a cash margin of $35, with ~160K BOEPD of combined production would pay out in a year. But that’s been true of the other acquisitions well, and so far, there is nothing to show for it.

At that sale price, ERF would bring $5.4 bn in new capitalization, ~$1 bn in EBITDA and ~100K BOEPD to DVN, and almost no debt, moving DVN’s EV/EBITDA metric incrementally a little higher (taking into account the new $2.0 bn in debt to close the deal) to around 3.4X from 3.0X. On a flowing barrel basis, it also moves up a bit to $52K from $46K per barrel. So the likelihood that shareholders will benefit from a deal where their basic financial metrics worsen defies logic.

The past is not necessarily a prologue. This deal could be the one that justifies itself with rewards to shareholders. Nothing in our review suggests this, quite the reverse, actually, but we have to allow for the possibility. The date for Devon’s 2024 annual meeting hasn’t been set yet. Typically it’s in early June. If enough disgruntled shareholders show up, it could be a raucous affair. They have ample reason to be unhappy.

Tyler Durden
Thu, 02/15/2024 – 12:20

JP Morgan Pulls Out Of $68 Trillion “Climate Action 100+” Group

0
JP Morgan Pulls Out Of $68 Trillion “Climate Action 100+” Group

We have been covering the full on implosion of ESG and “green” investing for the better part of the last 6 months and today, the wreckage continues.

That’s because mega-bank JP Morgan has officially left a $68 trillion investor coalition that is “focused on pressing the world’s biggest emitters of greenhouse gases to decarbonize,” according to Bloomberg.

In other words, the “fight” to decarbonize is imploding. 

JP Morgan said it is leaving the Climate Action 100+ because it has “made significant investments in developing its own climate risk engagement framework”, the report says. The bank claims to have 40 professionals now focused on sustainable investing. 

And the damage for the Climate Action 100+ may only be getting started. Lance Dial, a Boston-based partner at law firm K&L Gates LLP, told Bloomberg: “I wouldn’t be surprised if we see more defections, especially given that there’s now a cost, such as potential litigation, that wasn’t there when companies joined.”

He added: “Attorneys general have subpoenaed firms about their membership of these groups.”

The group responded by saying its 700+ members are “committed to managing climate risk and preserving shareholder value through their participation in the initiative.”

The bank’s involvement in CA100+ was initially seen as a significant step in its ESG investment journey. However, the initiative, alongside its participants, has faced increasing criticism from Republican circles in the U.S., labeling it and similar ESG efforts as politically motivated.

This criticism has led many investment firms to retreat from publicly aligning with net zero commitments and downplay their involvement in climate-focused finance groups, which are now considered more of a political burden than a merit.

Originally, CA100+ aimed to engage major companies like BP, Exxon Mobil, and Glencore in enhancing governance, cutting emissions, and improving climate financial disclosures, the report says. As the initiative enters a more proactive stage, asking members to ensure companies transition from plans to tangible emission reductions, the heightened activist stance poses additional difficulties for investors wishing to keep a lower profile in climate advocacy.

“The political winds aren’t rewarding climate-active firms today, but climate risk and regulations aren’t going away in the mid to long run, so short-term decisions may need to be undone when those longer term threats begin to manifest or regulators clamp down harder,” said Michael Sheren, a former senior adviser at the Bank of England who’s now a fellow at the Cambridge Institute for Sustainability Leadership.

“JPMorgan pulling out matters because it sends the wrong, short-sighted signal and gives cover for others to do the same,” he added.

And we’re sure they will…

We noted earlier this year, “ESG” has become a “dirty word” on Wall Street. 

For some context, peak ESG and related synonyms, such as “climate change” and “clean energy” and green energy” and net zero,” among other terms, peaked at 28,000 mentions in the first quarter of 2022. Ever since, the number of mentions has rapidly plunged. Halfway through the first quarter earnings season, mentions are around 4,800. 

Recall, we have written about the dying off of ESG and “green” investment products over the last few months. Most recently, at the end of 2023, Goldman Sachs shuttered its ActiveBeta Paris-Aligned Climate U.S. Large Cap Equity ETF. 

Bloomberg ETF analyst Eric Balchunas pointed out last month that “there was just way too much supply for the demand” with the ETF and that “it’s going to get worse too”. Balchunas says the ETF only took in $7 million over the course of 2 years. 

We also wrote about Jeff Ubben late last year, who shuttered his sustainability fund – calling traditional climate summitry an “echo chamber” of diplomats. 

Less than a week before that we noted that $30 billion had been shaved off the value of clean energy stocks over the preceding 6 months. 

Finally, we pointed out last year how the ESG grift was reaching endgame after Markus Müller, chief investment officer ESG at Deutsche Bank’s Private Bank stated that sustainability funds should include traditional energy stocks, arguing that not doing so deprives investors of a prime opportunity to invest in the transition to renewable energy.

Tyler Durden
Thu, 02/15/2024 – 12:00

You’ll Never Believe What Senator Elizabeth Warren Just Did

0
You’ll Never Believe What Senator Elizabeth Warren Just Did

As far as we can tell, this is not ‘The Onion’, not ‘Babylon Bee’, and it’s not the first of April…

After years of vilifying Bitcoin as money for criminals, terrorists, and climate change deniers, Senator Elizabeth Warren (D-MA) honored Satoshi Nakamoto for the 15th anniversary of the network’s launch with a commemorative flag flown over the United States Capitol, unveiled by NYC’s PubKey.

Bitcoin Magazine’s Mark Goodwin reports that in an unexpected turn of events, Elizabeth Warren, the long-time adversary of Bitcoin on Capitol Hill, has seen the orange-tinted light and quite literally raised a flag to praise the work of Bitcoin’s anonymous creator, Satoshi Nakamoto, celebrating 15 years since the network launched.

In participation of the Capitol Flag Program, Senator Warren’s office submitted a request to commemorate Nakamoto’s accomplishment of creating the first “truly inclusive financial system,” with the colors of the United States being flown above the Capitol on December 18, 2023 – a date known to Bitcoiners as HODL Day.

While the sudden embrace of Bitcoin by the Massachusetts Senator may seem a surprise, her career-long rhetoric about fighting for the financially under-served has finally taken shape within this tangible statement.

As if speaking to her campaign promises to champion the working class negatively affected by corruption within both the government and the banking sector, the certificate produced by the Architect of the Capitol in recognition of the flag notes the “new economic freedoms to populations previously ignored by both private and public institutions” brought forward by Nakamoto’s Bitcoin.

The Senator’s office filing for the flag flying itself was noticed by friends of Bitcoin MagazinePubKey, who are holding a public event in New York City this evening, February 15, at 6:00 PM EST, to unveil not only the story of the flag, but the flag itself, complete with a dramatized reading of the infamous December 18, 2013 post on BitcoinTalk that immortalized “HODL” within the Bitcoin lexicon from actor, comedian and Bitcoiner T.J. Miller.

Prior to the event itself, an X (formerly Twitter) Spaces hosted by Bitcoin Magazine and PubKey at 4:30 PM EST will further tell the story of how Satoshi’s Flag and Warren’s endorsement came to be. Much like during the mid-1770s, freedom-focused bars such as PubKey play an important role in socializing the ideas and stories that make up a revolution.

Thomas Pacchia, Co-Founder of PubKey, made note of the Senator’s pivot when speaking with Bitcoin Magazine. 

“This is a historic moment for how politicians in Washington view the promise and inclusivity of the Bitcoin protocol. What politicians do is much more important than what they say.”

Her website describes her as “a leading voice for consumer protection, financial reform, and social justice,” and her recent action of promoting Satoshi’s work seems to be in total alignment with her stated political mission.

Only one week before Warren ordered the flag flown, the Senator introduced legislation to give the Treasury more tools to restrict the criminal usage of Bitcoin, making bold comments that they “need new laws to crack down on crypto’s use in enabling terrorist groups, rogue nations, drug lords, ransomware gangs, and fraudsters to launder billions in stolen funds, evade sanctions, fund illegal weapons programs, and profit from devastating cyberattacks.”

She even went so far as to make note of creating “an anti-crypto army” in March of last year, in her bid for reelection. Warren had co-authored a letter to Fidelity CEO Abigail Johnson in May 2022 raising concerns about putting Bitcoin within their 401(k)s, stating that, “Investing in cryptocurrencies is a risky and speculative gamble, and we are concerned that Fidelity would take these risks with millions of Americans’ retirement savings.” 

Now that U.S. regulatory agencies such as the SEC have allowed the approval of 11 spot Bitcoin ETFs, including Fidelity’s FBTC, Warren has changed her tone, recognizing the immense economic freedom brought about by such a novel technology, and now joins a growing group of elected officials throwing their name behind Nakamoto’s protocol.

Bitcoin Magazine and PubKey encourage Bitcoiners to take polite note of this change of heart by reaching out to Warren’s office directly, as well as tagging her X (formerly Twitter) handle, and thanking her for championing Satoshi Nakamoto and recognizing him as the hero he is.

*  *  *

Of course, the socials were shocked…

Quite what prompted this full 180 in her views of bitcoin is unclear but speculation is centering on three main threads:

1) Uber-liberal, globalist donor Larry Fink (whose company BlackRock now maintains 109,000 BTC – worth ~$6 BN – under its new ETF) tapped her gently on the shoulder about how much money can be made from rent-seeking on this stuff…

2) Polls suggested she is on the wrong side of history with regard to personal sovereignty and voters matter (to some degree)…

3) CBDCs are imminent and somehow bad-mouthing this blockchain-backed asset does not align with the centralized power and control that a Digital Dollar would give her and her pals.

Finally, we are in wonderment that this ‘commemoration’ comes less than 24 hours after a US Treasury official admitted that terrorists are not using crypto to blow the world up, they prefer the good ol’ USDollar for that.

Tyler Durden
Thu, 02/15/2024 – 11:40

More Attacks On Red Sea Vessels As US Coalition Pounds Houthi-Held Port City

0
More Attacks On Red Sea Vessels As US Coalition Pounds Houthi-Held Port City

Attacks on Red Sea shipping from Yemen’s Houthis have continued over the last several days, but so has the US coalition’s response. 

On Wednesday many large explosions rocked the Houthi-held port city of Hodeidah, the result of the latest major US and British strikes. The last three days have seen some 30 missile strikes on Yemen from the coalition Operation Prosperity Guardian.

Hodeidah, Yemen

Yemeni sources have said that in total the US and UK have carried out 403 attacks on the country, including 203 airstrikes, since Red Sea hostilities began in reaction to Israeli’s offensive in Gaza.

A Houthi government spokesman this week announced the following claimed ‘stats’:

Shami added that Yemeni naval forces have carried out operations against 14 US vessels, three British vessels, and 17 Israeli vessels since the start of the Gaza–Israel war in October. 

“We banned the entry of 99 American commodities, merchandise, and companies that support the criminal Zionist entity,” Shami said. 

We shut down 354 agencies and 12 companies and 23 branches of companies … [linked to] American and Zionist trademarks,” he continued. 

But there are also fresh reports saying the Houthis are in many cases “firing blind” and even inadvertently targeting Iranian vessels. This means what Russian and Chinese ships could also come under fire, despite Houthis officials having declared they have been given safe passage. 

One maritime report describes of the latest friendly fire incident:

On Monday, Yemen’s Houthi rebels fired ballistic missiles at a ship bound for Iran, the militia’s main supporter. Would the Houthis really target their patrons in Tehran?

Almost certainly not. There’s no evidence to suggest a rupture between Iran and the Houthis, who have been attacking ships in the Red Sea in hopes of increasing global pressure on Israel to stop its assault on Gaza.

Rather, according to Eurasia Group’s Iran Expert Gregory Brew, the attack shows that the Houthis may be simply taking a different tack. “Houthi attacks may become more indiscriminate,” says Brew, “hitting ships they don’t intend to hit, or targeting ones with more sensitive cargoes.”

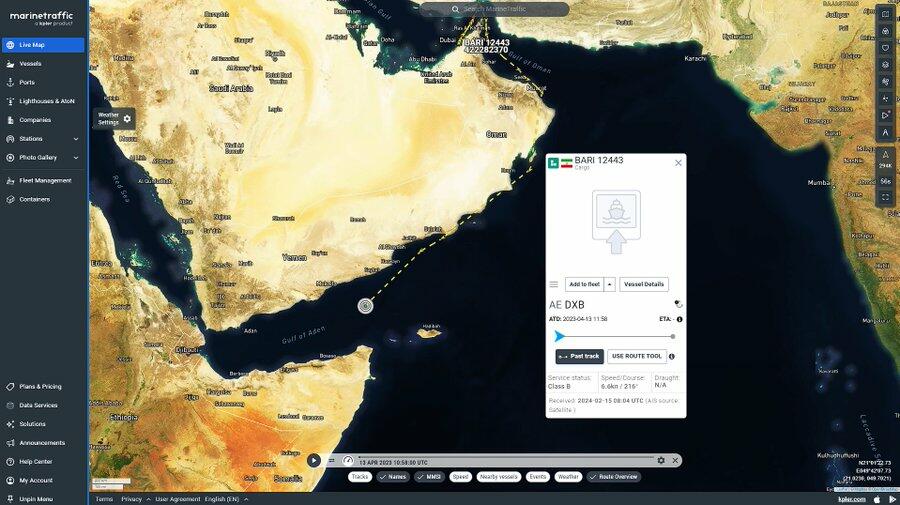
On Thursday there has been another incident, east of Yemen’s Aden, where a cargo vessel has suffered fresh damage – presumably from rocket or drone fire coming from Yemen.

British maritime security agency UKMTO has said in an alert that an explosion was reported near a ship traversing off Yemen’s coast. The ship reported “an explosion in close proximity to the vessel” while sailing to its next port of call. However details have been scant and the exact nature of what happened is still unclear.

Yemen’s Houthis have vowed to keep up their attacks on both foreign commercial vessels and Western warships in the Red Sea. Incidents have now become daily, and so have the US coalitions attacks, often against Houthi launch sites. But clearly the West’s deterrent measures haven’t worked.

Tyler Durden
Thu, 02/15/2024 – 11:20

Despite Ongoing Mass Corporate Layoffs, Govt-Supplied Jobless Claims Data Continues To Decline

0
Despite Ongoing Mass Corporate Layoffs, Govt-Supplied Jobless Claims Data Continues To Decline

As mass corporate layoffs continue to mount, with CSCO the latest to announce (a 5% global workforce reduction), why should we be shocked that expectations were for a very small rise in initial jobless claims (from 218k to 220k) last week.

Source: Layoffs.fyi

What does that look like – in the real world labor market – in 2024

1. Twitch: 35% of workforce
2. Roomba: 31% of workforce
3. Hasbro: 20% of workforce
4. LA Times: 20% of workforce
5. Spotify: 17% of workforce
6. Levi’s: 15% of workforce
7. Xerox: 15% of workforce
8. Qualtrics: 14% of workforce
9. Wayfair: 13% of workforce
10. Duolingo: 10% of workforce
11. Washington Post: 10% of workforce
12: Snap: 10% of workforce
13. eBay: 9% of workforce
14. Business Insider: 8% of workforce
15. Paypal: 7% of workforce
16. Charles Schwab: 6% of workforce
17. Docusign: 6% of workforce
18. UPS: 2% of workforce
19. Blackrock: 3% of workforce
20. Citigroup: 20,000 employees
21. Pixar: 1,300 employees
22. Cisco: 5% of workforce

And here’s the government-supplied statistics…

Instead, the number of Americans filing for jobless claims for the first time decline to 212k (of course it f**king did!)…

Source: Bloomberg

However, Continuing Claims ticked up from 1.86mm to 1.895mm (above exp of 1.88mm)…

Source: Bloomberg

As a reminder, here’s what Richmond Fed governor Tom Barkin warned last week:

“I am cautious about accuracy of numbers around the turn of the year.”

Cautious all year round more like…

Tyler Durden
Thu, 02/15/2024 – 08:46

US Retail Sales Plunged In January, Worst YoY Growth Since COVID Lockdown

0
US Retail Sales Plunged In January, Worst YoY Growth Since COVID Lockdown

As we detailed in our preview for premium subscribers, if the omniscient analyst at BofA are right this morning, the fecal matter is about to hit the rotating object as they saw retail sales declining bigly (more than expected) in January judging by real-time credit card spending data…

Source: BofA

After they unexpectedly surged in November and December (driven in large part by a jump in Food Services), headline retail sales in January were expected to decline just 0.2%, but BofA nailed it once again with a large 0.8% MoM drop. That dragged the YoY retail sales down to just 0.6%…

Source: Bloomberg

That is the worst monthly decline since March 2023 and worst YoY rise since May 2020.

Motor Vehicles and Parts and Building Materials saw the largest decline MoM…

Source: Bloomberg

Core Retail Sales also declined (-0.5% MoM vs +0.2% exp), which dragged the YoY levels down to their lowest since the COVID lockdowns…

Source: Bloomberg

Adjusted (crudely) for inflation, this was a huge drop in ‘real’ retail sales…

Source: Bloomberg

Finally, the control group – used to feed through to the GDP calculation – tumbled 0.4% MoM (vs expectations of +0.2%).

Soft-landing morphing into a stagflationary crash-landing?

Tyler Durden
Thu, 02/15/2024 – 08:42