82.7 F
Chicago
Tuesday, September 15, 2026
Home Blog Page 3041

The End Of Money As We Know It – What To Expect in 2024

0
The End Of Money As We Know It – What To Expect in 2024

Authored by Daniel Lacalle,

Markets closed 2023 with the strongest rally for equities, bonds, gold, and cryptocurrencies in years. The level of complacency was obvious, registering an “extreme greed” level in the Greed and Fear Index.

2023 was also an unbelievably bad year for commodities, particularly oil and natural gas, something that very few would have predicted in the middle of two wars with relevant geopolitical impact and significant OPEC+ supply cuts. It was also a poor year for Chinese equities, despite slower-than-expected but strong economic growth and robust earnings in the large components of the Hang Seng index.

Markets rallied due to a combination of optimistic expectations for inflation and aggressive rate cuts from central banks. The question now is, what can investors expect in 2024?

The year of disinflation can only come from a recession. The market expectations of a massive reduction in inflation cannot come from what economists call a soft landing. The reason we have not seen a recession in 2023 is because the global money supply did not fall below $103 trillion and ended almost at the record level of $107 trillion, according to Citi. Furthermore, governments in developed countries have continued to spend as if inflation and rate hikes did not exist. Fiscal policy has been exceedingly aggressive, while monetary policy has been restrictive. As such, the decline in monetary aggregates and the impact of rate hikes have fallen on the shoulders of the private sector.

Inflation declined in line with monetary aggregates, but we have not yet seen the true impact on the economy because of the lag effect. We are likely to see the full-scale impact of 2023’s monetary contraction in 2024. If the economy weakens and private sector aggregate demand slumps, inflation will decline as expected. However, it is almost impossible to see the kind of goldilocks economy that many investors predict and achieve 2% inflation.

Central bank rate cuts will only come from a very weak economy. Central banks never act preemptively. If they end up cutting rates by 150 basis points, it will be because the slowdown in the economy is severe. We cannot bet on one thing or the other. If you believe in a soft landing, you should not expect six rate cuts. Alternatively, if you believe central banks will cut rates five or six times, you should prepare your portfolio for a hard landing—a terribly bad one, in fact.

Commodities may bounce as geopolitical risk creates a floor and marginal demand from China picks up. Markets have ignored the strength of the Chinese economy, which will grow by at least 4.5% in 2023, because the stock market has not performed. However, an economy that grows at this pace despite the real estate sector’s immense challenges should not be ignored. It is probable that marginal demand in energy commodities picks up just as geopolitical risk maintains a floor on the price, leading to a bounce in the commodity complex thanks to China’s marginal demand and India’s rapid growth. As more of the newly created currency goes to relatively rare assets, a looser monetary policy may also support this recovery in commodities.

Latin America and Europe will continue to disappoint, while Asia leads in growth. Due to expectations that the worst is over and a relative bounce in the euro against the US dollar, markets have bought European stocks and bonds. The same is happening with LatAm’s risky assets. However, the problems are deeper and more complex. The euro may bounce, but its position as a world reserve currency is weakening relative to the US dollar and rising contenders like the yuan. Europe’s lack of growth is not due to exogenous factors but, like most of LatAm, self-inflicted. The euro area ended 2023 in recession despite low commodity prices and the EU Next Generation Fund. The problem in the euro area and most Latin American countries is the constant implementation of policies that damage growth and bloat governments. In order to undo the nightmare that collectivist interventionism has created, Argentina will probably go through a detox year.

Due to the monetary destruction that central banks have implemented, equity markets may continue to perform satisfactorily, but volatility will likely rise as market optimism clashes with economic reality. Although 2024 will probably not be the year of central bank digital currencies, they are in the pipeline, and this means even more monetary debasement. In this environment, Bitcoin and gold may continue to support the fight against the destruction of the purchasing power of currencies. We cannot ignore bitcoin’s high volatility and risk, but we cannot forget that it has started to separate itself from other cryptocurrencies to be an asset class of its own.

As central banks prepare the way for digital currencies, which are the closest thing to surveillance disguised as money, reserves of value are more needed than ever before. Gold is likely to be a good de-correlated asset that protects against the debasement of sovereign bonds and domestic currencies.

2024 is likely going to be a year of significant slowdown in the major economies considering the current trends in the private sector and a year of rising public debt, which governments will try to disguise with the destruction of the purchasing power of the currency. In that scenario, betting on the swift end of the inflation burst may be premature. If inflation declines as predicted, it will be a result of the economy’s deterioration and the overspending of the government. If debt and government deficits continue to rise, inflation may surprise on the negative side. Either way, the key in 2024 will be to protect ourselves from currency destruction. Thus, investing is not simply important but crucial to survive in this gradual end of money as we know it.

Tyler Durden
Tue, 01/02/2024 – 09:25

Tesla Delivers Record Q4 Deliveries But Falls Short Of 2 Million 2023 Delivery Goal

0
Tesla Delivers Record Q4 Deliveries But Falls Short Of 2 Million 2023 Delivery Goal

For Q4, Tesla announced this morning it had “produced approximately 495,000 vehicles and delivered over 484,000 vehicles”, putting up numbers in line with recently adjusted estimates for the quarter. Production beat estimates of about 482,336, per Bloomberg’s estimates. 

The company noted that its full year vehicle delivery number was up 38% to 1.81 million, slightly less than recently revised expectations for the year. Nonetheless, total deliveries mark a record quarter for the EV manufacturer. The company manufactured approximately 1.85 million vehicles for the period. 

The company delivered 461,538 Model 3/Ys and 22,969 in “other models”, which includes Model S, Model X and the new Cybertruck.

For now, the company’s Model 3 and Model Y sales continue to drive its deliveries, with Model S, Model X and Cybertruck deliveries accounting for still only about 5% of the company’s total deliveries for the quarter. 

As we noted days ago, analysts were expecting record deliveries but a miss on the company’s 2 million mark for the year. 

Analysts had predicted the company would deliver 1.82 million vehicles in 2023, up 37% from the year prior. Estimates were for about 473,000 vehicles delivered in the fourth quarter. 

Daiwa Capital Markets analyst Jairam Nathan revised Tesla’s 2024 delivery forecast down to 2.04 million from 2.14 million, anticipating a 4% drop in average revenue per vehicle compared to 2023.

Garrett Nelson, senior analyst at CFRA Research, told Reuters last week: “The fourth quarter is typically the strongest of the year in terms of deliveries for Tesla, we’re expecting that to be the case again this year.” 

The company is grappling with a decline in sales and has been using aggressive price cuts to move metal worldwide throughout the course of the year. This strategy was particularly emphasized in China, where Tesla has seen a reduction in its market share, challenged by domestic competitors such as BYD.

We have written extensively about how China’s EV market is becoming saturated and increasingly competitive. 

Tesla, intensifying its year-end sales with increased discounts, aims for a 50% average annual growth over several years. However, in 2024, the EV leader faces challenges such as the loss of federal tax credits in the U.S. and Germany’s cessation of its EV subsidy program.

Tyler Durden
Tue, 01/02/2024 – 09:05

“Not Buying Dips Here… Yet” – Starting The New Year “Mildly Bearish”

0
“Not Buying Dips Here… Yet” – Starting The New Year “Mildly Bearish”

Authored by Peter Tchir via Academy Securities,

Starting The New Year

As we start the first trading day of the year, a few “familiar” themes are in the headlines and driving price action:

Chips and China

Some chip stocks are trading lower pre-market as stories circulate about pressure from the U.S. government to block sales to China ahead of the January deadline. I am looking for some “thawing” in the U.S. / China economic relationship to start the year (as well as some stimulus out of China) but neither have occurred. In any case, high end chips will remain under careful scrutiny of the U.S. government for national security reasons.

The So-Called “Magnificent 7”

The Nasdaq 100 has re-balanced so it is not as lopsided to start 2024 as it was at the start of 2023, and certainly nowhere near as overweight as it got last year. Two stocks are just under 10% of the weighting in the index (or at least in QQQ, the Nasdaq 100 ETF). No other stock is above 5% of the weighting, and even the 7th largest holding is under 4%. So, even if the “so-called” Magnificent 7 stumble, it won’t hurt the index the way it would have last year. I’m still trying to figure out the implications for that, though I suspect trades like long QQQ vs Short IWM (Russell 2000 ETF) won’t perform intuitively.

In any case, I think some of the “compression” trade we saw from November on will continue as “laggards” outperform, but I think it will be in a bearish overall market, rather than a rallying market.

Energy

I like energy for both “good” and “bad” reasons. The realization that we need a strong domestic energy industry seems to have gathered momentum. Yes, at the height of inflation fears, the government was pressuring the industry to produce, but at the same time was threatening “windfall” taxes and other actions to hurt the industry longer term. While not everyone is embracing energy, even the more extreme elements of the “sustainability” community seem more willing to accept that the transition to other energy sources will be longer and require more traditional energy than previously thought. Realism will help us get there, which is good. Vision is important to that success, but planning is too, and that balance seems much better to me as we start 2024.

On the “bad” side of things is heightened tensions in the Middle East. The threat that Iran will become fully (and officially) engaged, sending some shockwaves through the oil industry seems more real by the day.

I continue to believe that the energy companies of the future are the energy companies of today and it is the sector I am most overweight now (out of all the laggards).

Bond Yields

The 10-year traded as low as 3.78% during last week’s “holiday” trading. It traded as high as 3.96% overnight (before 8 am) – pushing us back to levels not seen in a couple of weeks.

The market has gotten ahead of itself at the front-end (too many cuts priced in) and gotten ahead of itself in the long-end (inflation risks remain – driven by geopolitical and supply chain inflation, and the whole “debt fiasco”/”supply” story that pushed us to 5% on 10’s has not been resolved).

Bottom Line

Starting the year, where we ended the year (see The Party is Over) – mildly bearish bonds and stocks, with a preference to own the “laggards” but defining the “laggards” more narrowly.

Not buying dips here, at least not yet!

Happy 2024!

Tyler Durden
Tue, 01/02/2024 – 08:45

FDNY Responds To Report Of ‘Small Explosions’ Shaking Roosevelt Island

0
FDNY Responds To Report Of ‘Small Explosions’ Shaking Roosevelt Island

Firefighters were called to the 580 block of Main Street, located south of the Roosevelt Island Bridge & Tram, at approximately 0600 ET, in response to reports of multiple explosions and building shaking, the New York City Fire Department told MailOnline

Roosevelt Island residents were jolted awake this morning by at least “three instances of a boom and a shake,” with the third vibration “felt further away.” 

According to ABC7 New York, “Buildings at 2 and 4 River Road just south of the Roosevelt Island Bridge and Tram were experiencing power outages, indicating that the noise could have been electrical.” 

*Developing… 

Tyler Durden
Tue, 01/02/2024 – 08:25

ASML Shares Fall As Netherlands Blocks Some Chip-Making Machine Exports

0
ASML Shares Fall As Netherlands Blocks Some Chip-Making Machine Exports

Shares of ASML Holding NV fell in premarket trading in New York on the decision by the Dutch government to block the semiconductor manufacturer from exporting some advanced chip equipment to China.  

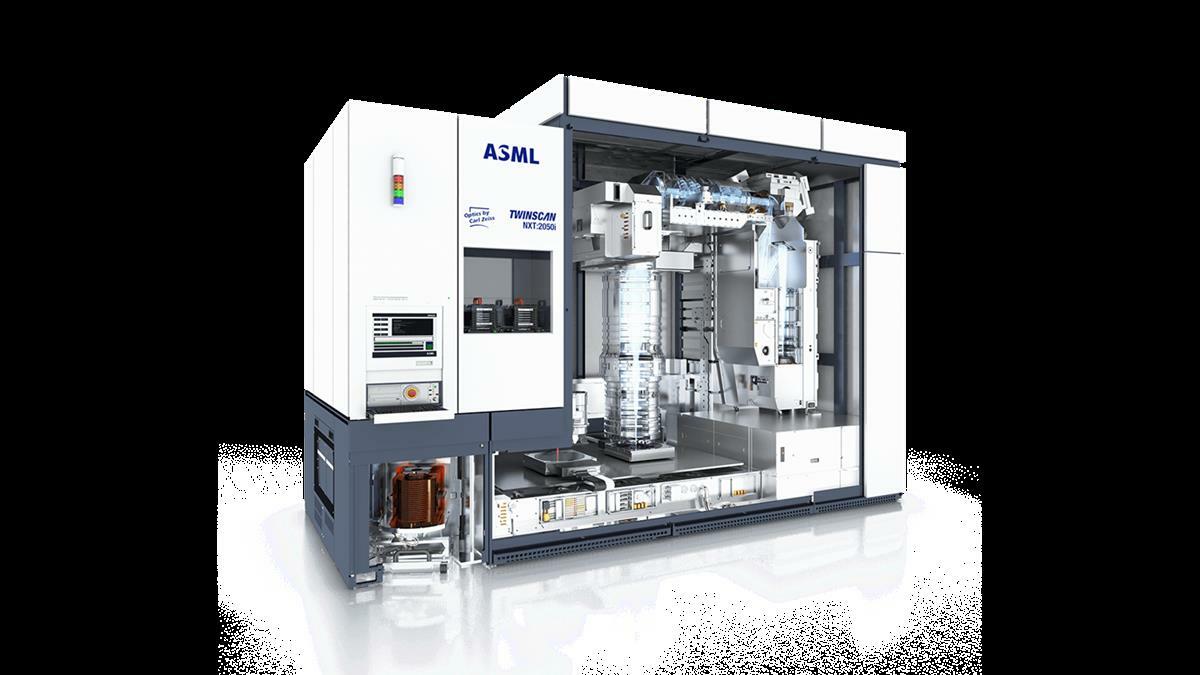
The Netherlands-based company said the Dutch government “partially revoked” its export license to ship NXT:2050i and NXT:2100i lithography machines to China. These lithography machines are used to make advanced chips. 

The cancellation of the export license comes after the Biden administration announced tighter trade restrictions on state-of-the-art artificial intelligence chips, sparking outrage from Beijing in October. 

ASML told CNBC in a statement that recent discussions with the US government allowed them to “obtain further clarification of the scope and impact” of the October export controls. These trade restrictions are “on certain mid-critical DUV immersion lithography systems for a limited number of advanced production facilities.” 

Under pressure from the Biden administration in June, the Dutch government enforced restrictions on exporting advanced semiconductor equipment.

The Biden administration has been cracking down on Beijing’s ability to manufacture advanced semiconductor chips, inhibiting Chinese firms’ access to lithography machines across the Western world. Despite all of this, China’s Huawei Technologies Co. has still been able to produce a smartphone to rival Apple’s iPhone

ASML does not believe these restrictions will “have a material impact on our financial outlook for 2023.”

However, shares of ASML were down in premarket trading by 2%. Other chipmaking companies, Applied Materials, Lam Research, and KLA, were lower in the premarket. 

Here’s what Wall Street analysts are saying (list courtesy of Bloomberg): 

Redburn Atlantic (Timm Schulze-Melander, sell)

  • Cancellation of shipments marks a step-up in enforcement of US-China trade restrictions
  • Analyst estimates mid-single-digit impact to 4Q23 earnings, as well as FY24 revenue decline of 4% vs. consensus expectation of flat revenue y/y

Equita (Gianmarco Bonacina, hold)

  • Revocation of export licenses impacts a limited number of Chinese customers, which analyst notes could include SMIC, a producer for Huawei among others
  • China accounted for more than 40% of group’s 3Q revenue, and the stock trades at the upper end of the valuation range — both reasons the broker sees the news as “negative” for ASML
  • “We believe China will further accelerate the race to its independence”
  • Analyst leaves estimates unchanged, though lowered recently

Oddo (outperform)

  • Assumption is that the ban concerns three machines at an average selling price of around €60m, i.e. €180m of sales
  • ASML indicated that US blocking deep ultraviolet (DUV) sales to China should have no material impact, so the group might have performed better on the rest of the business
  • Long-term outlook “unchanged”

Meanwhile, a spokesperson for the Chinese Foreign Ministry called the US’s intervention in limiting China’s access to chipmaking machines nothing more than “hegemony” and asked the Dutch government to “respect the spirit of the contract and world order, to safeguard the mutual benefits of the two countries.”

Tyler Durden
Tue, 01/02/2024 – 07:45

Japan Airlines Jet Collides With Coast Guard Plane While Landing At Airport In Tokyo

0
Japan Airlines Jet Collides With Coast Guard Plane While Landing At Airport In Tokyo

An Airbus A350, operated by Japan Airlines and carrying hundreds of passengers, collided with a Japan Coast Guard (JCG) plane while landing at Haneda Airport in Tokyo late Tuesday. 

Flight tracking website Flightradar24 wrote in a post on social media platform X, “Japan Airlines flight JL516 collided with a JCG aircraft and caught fire, during landing at Tokyo Haneda Airport Runway 34R.” 

The aviation app ForeFlight shows a diagram of Haneda Airport and Runway 34R. 

Public broadcaster NHK News said 367 passengers and 12 crew members were on board JL516, all of whom evacuated the aircraft after touchdown. One JCG plane crew member was evacuated, but five others were unaccounted for. 

Footage of the crash was posted on X. 

JCG confirmed to CNN its fixed-wing MA722 collided with JL516 on Runway 34R. They noted the fixed-wing MA722 was headed to Haneda airport to a JCG airbase in Niigata prefecture to support relief efforts following a powerful earthquake on Monday. 

Tyler Durden
Tue, 01/02/2024 – 06:55

12 (Or More) Reasons To Expect A Prosperous 2024

0
12 (Or More) Reasons To Expect A Prosperous 2024

Authored by Gary Alexander via The Epoch Times,

On the winter solstice, the shortest day of the year, the Dow Jones Industrial Average closed at a record high (37,404), the S&P 500 neared an all-time high, and the Russell 2000 soared nearly 25 percent in under two months, so it’s natural to see spreading euphoria in such a grossly overbought market. Wall Street’s favorite trophy wife, Rosy Scenario, is once again showing her smiling face when it comes to predictions for the coming year. Alas, we always seem to mirror the recent past when projecting the year to come.

This is reflected in sentiment surveys. The Bears were roaring in October, but they are now hibernating. The Investors Intelligence Bull/Bear Ratio (BBR) is now over 3-to-1, while the AAII ratio is 2.66-to-1. Discounting the neutrals, bears accounted for only 18.1 percent in the Bull/Bear poll and 19.3 percent on the AAII ballot. That’s not extreme by historical standards, but it does show a plurality of Pollyannas out there.

Our favorite economist, Ed Yardeni, is clearly in the “Roaring 20s,” camp, as am I, but I’m also on record as saying that a lot depends on the 2024 election. After all, Calvin Coolidge won the 1924 election, and the Roaring 20s really began in 2025. There would have been no “Roar” without Cal and his pro-business administration, including Secretary of the Treasury Andrew Mellon. That is not the case with the current administration. We need a change. I have said that my main fear is that 2024 will turn out to be so good that we’ll forget to “vote for a change” next November, so that the same policies limiting growth will remain in effect for the next four years, restricting the long-term bull market and any Roar in these ‘20s.

Also, we can look at all the positives in line for 2024 and forget that the Trickster will unveil several surprises. After all, we had several shocks in 2023 that interrupted an otherwise positive year—starting with the banking crisis in March, then the credit downgrade in July and the invasion of Israel in October.

The Biggest Market Shocks and Surprises of 2023

(Source: Yahoo! Finance; Bespoke Investment Group)

With the firm knowledge that we don’t know the future, let’s rehearse Ed Yardeni’s dozen bullish points:

Ed Yardeni’s Dozen (or More) Good Reasons for Expecting a Great 2024

(1) Interest rates are back to normal.

(2) Consumers have purchasing power.

(3) Households are wealthy and liquid.

Mr. Yardeni says, “The net worth of American households totaled a staggering record-high $151 trillion at the end of Q3-2023. A record $5.9 trillion is in money market mutual funds (MMMF) with a record $2.3 trillion in retail MMMFs. Commercial bank deposits in M2 totaled $17.3 trillion during the December 12 week. There are 86 million households who own their own homes, and 40 percent of them have no mortgages.”

That’s a ton of dry fuel to fund new market purchases in the coming year. The next six look solid, too:

(4) Demand for labor is strong. There are still 8.6 million job openings begging for willing workers.

(5) The onshoring boom is boosting capital spending and promising to end the manufacturing recession.

(6) Housing is set for a recovery due to the “plunge in mortgage interest rates since early November.”

(7) Corporate cash flow is at a record high—a record $3.4 trillion during the third quarter of 2023.

(8) Inflation is turning out to be transitory. The inflation of goods was back down to 0 percent in November.

(9) The High-Tech Revolution is boosting productivity in a trend Mr. Yardeni identified as starting in 2015.

The final reasons to be bullish are more defensive in nature, primarily arguing against the perma-bears:

(10) The Leading indicators are mostly misleading. The 10 leading economic indicators (LEI) have forecast a recession for a long time—a recession that has refused to arrive. One dominant example among the LEI is the “inverted yield curve,” which still prevails, due to the Fed fighting market rates—with their high short-term rates versus falling long-term rates. Mr. Yardeni argues that, “The LEI has misfired its recession signals because its composition is biased toward predicting the goods sector more than the services sector of the economy. There has been a rolling recession in the goods sector, but it has been more than offset by strength in services, nonresidential private and public construction, and high-tech capital spending.”

(11) The rest of the world’s challenges should remain contained. We already have two active wars, and we may see more, perhaps in Venezuela or China, but Mr. Yardeni argues that these threats are contained. “The wars between Russia and Ukraine, and between Israel and Gaza should remain contained regionally,“ he said. ”China’s economic woes reduce the chances that China will invade Taiwan. Nevertheless, these geopolitical hotspots will boost defense spending among the NATO members. The bursting of China’s property bubble should continue to weigh on global economic growth and commodity prices. China will remain a major source of global deflationary pressures. Europe is in a shallow recession and should recover next year as the European Central Bank lowers interest rates.”

(12) The Roaring 2020s will broaden the bull market, dodging a recession. The “soft landing” scenario is gaining traction as 2023’s AI-based rally broadens into several (virtually all) S&P sectors. Mr. Yardeni says, “We believe that reflects investors’ realization that the beneficiaries of the Roaring 2020s theme aren’t just the companies that make technology but also those that use it to boost their productivity.”

(13) How about all that government debt? This is my main concern. With the lowering of long-term interest rates, I’m afraid that gives Congress, the president, and most consumers and businesses a green light to keep running up more debt. Net interest paid on the federal debt reached a record high $716.7 billion in the 12 months ending Nov. 30. Mr. Yardeni argues that more federal spending will “stimulate onshore construction of manufacturing facilities” but I’ve always been skeptical of these “shovel-ready” federal boondoggles. Mr. Yardeni admits that too much federal debt could cause “an oversupply of Treasury bonds relative to demand, which could set off a debt crisis. And that certainly could trip up the Roaring 2020s scenario.” That remains my greatest concern—that all this anticipated good news will encourage more deficit spending and more voter apathy come next November, causing unsustainable future debt growth.

Enjoy a great growth year in 2024, but let’s not forget our responsibility to sustain that growth into 2025.

Tyler Durden
Tue, 01/02/2024 – 06:30

Visualizing Tesla’s Global Sales By Model & Year

0
Visualizing Tesla’s Global Sales By Model & Year

In the last five years, Tesla stock has exploded upwards more than 800%.

From a company that was perpetually on the verge of bankruptcy, Tesla has emerged as the EV manufacturer to beat in the automotive market.

A huge part of the success comes from Tesla’s sales which jumped 30x in the same time period.

Visual Capitalist’s Marcus Lu and Bhabna Banerkjee take a look at the numbers, as well as the sales share between the different Tesla models from 2016-2023 using data from CleanTechnica, an archive for news and data around clean technology.

Tesla’s Global Sales Sales Through the Years

From 2018 onwards, Tesla’s global sales began to skyrocket. Though quarter-on-quarter growth wasn’t always positive, dips were followed by more breakout numbers.

Here’s the model breakdown of Tesla’s global sales, from Q2 2016 to Q3 2023.

Date Tesla Model S Tesla Model X Tesla Model 3 Tesla Model Y
Q2 2016 9,764 4,638 N/A N/A
Q3 2016 16,047 8,774 N/A N/A
Q4 2016 12,700 9,500 N/A N/A
Q1 2017 13,481 11,570 N/A N/A
Q2 2017 12,010 10,010 N/A N/A
Q3 2017 14,065 11,865 220 N/A
Q4 2017 15,200 13,120 1,550 N/A
Q1 2018 11,730 10,070 8,180 N/A
Q2 2018 10,930 11,370 18,440 N/A
Q3 2018 14,470 13,190 55,840 N/A
Q4 2018 13,500 14,050 63,150 N/A
Q1 2019 6,000 6,100 50,900 N/A
Q2 2019 8,422 9,300 77,634 N/A
Q3 2019 8,383 9,100 79,703 N/A
Q4 2019 8,375 11,100 92,620 N/A
Q1 2020 4,525 7,705 73,975 2,291
Q2 2020 3,927 6,687 63,793 16,484
Q3 2020 4,583 10,693 94,049 30,269
Q4 2020 6,060 12,860 126,624 35,123
Q1 2021 1,010 1,010 115,077 67,780
Q2 2021 890 1,000 110,054 89,360
Q3 2021 9,000 275 111,225 120,800
Q4 2021 4,050 7,700 140,000 156,850
Q1 2022 7,362 7,362 129,764 165,560
Q2 2022 8,081 8,081 100,066 138,467
Q3 2022 7,469 11,203 120,308 204,850
Q4 2022 6,344 10,803 135,846 252,285
Q1 2023 3,695 7,000 132,180 280,000
Q2 2023 6,225 13,000 146,915 300,000
Q3 2023 5,985 10,000 117,074 302,000
Total 254,283 269,136 2,165,187 2,162,119

Note: Beginning in 2020, Tesla’s reporting began to combine Model 3 & Y sales together. Model-specific data from this point is based on CleanTechnica’s estimates.

Aside from this steep rise, another key factor to note is how Tesla’s lineup has changed. The company began ramping production with the Model S and X, two luxury models that helped the brand build a prestigious image.

However since 2020 , the company has successfully transitioned to cheaper high volume models like the Model 3 and Y.

In fact, 2020 was also the first year Tesla turned a profit thanks in part to the Model Y.

The Model 3 and Y were also the world’s best-selling EVs in 2023.

Tesla’s presumed rival, Amazon and Ford-backed Rivian, is planning a similar approach. Its first models include the relatively expensive, full-size R1T and R1S. However the company has hinted at a 2024 reveal for its cheaper R2 model, with production starting in 2026.

Tyler Durden
Tue, 01/02/2024 – 05:45

Diamond Prices Are Going To Collapse

0
Diamond Prices Are Going To Collapse

Authored by Jeffrey Tucker via The Epoch Times,

What is the modern world’s most powerful and successful industrial cartel?

You could say it is pharma today but there are too many competitors in the realm of drug production to qualify as a cartel.

It is a fantastically successful corporatist mess but it is not technically a cartel.

Until fairly recently, there was one institution that qualified: diamonds as produced and distributed mainly by DeBeers Consolidated Mines in South Africa.

For the better part of the 20th century, this one company controlled 90 percent or more of the global market for diamonds. Coming with that has been amazing amounts of corruption, graft, and even war to maintain control.

That control began to face real stress in the 21st century, as the company had failed to line up various distribution networks in Canada, the United States, and elsewhere, partly due to pressure from online commerce plus the unrelenting drive of the market to break down even the most powerful industrial monopolies.

Earlier last year, the diamond market faced a remarkable decline in the midst of a terrible global inflation, to the point that prices hit a 14-year low.

That prompted DeBeers to engage in a deliberate restriction of supply designed to stabilize the market. That seemed to work and now production is back up again.

And yet this is not going to last.

Just watch this market over the coming 5 years. We are going to see a stunning fall in prices. There is one major reason: lab-grown diamonds.

I was just at Macy’s and I was amazed to see a full display, more in the view of the consumer than the “natural” diamonds. I was truly dazzled at the beauty. I’m no specialist but I must say that they looked spectacular. The salesperson confirmed that she sees far more interest in these products than traditional diamonds.

And the price? For now at retail locations, they are 40 percent cheaper than regular diamonds. But they can be 60 percent lower or even as much as 90 percent lower. And this is with the market just now starting to mature. They are reaching the consumer marketplace as never before. We seem to be at a turning point.

The Gemological Institute of America stopped calling them “synthetic” in 2019 because that’s not accurate. According to the GIA, “Laboratory-grown diamonds have essentially the same chemical, optical and physical properties and crystal structure as natural diamonds. Like natural diamonds, they are made of tightly-bonded carbon atoms. They respond to light in the same way and are just as hard as natural diamonds. The main differences between laboratory-grown and natural diamonds lie in their origin. Think of it this way: laboratory-grown diamonds are like ice from your refrigerator, while natural diamonds are like ice from a glacier. They are both ice, although their formation stories and the age of each are very different.”

The dropping of that little word seems to have established lab-grown diamonds as authentic luxury goods. There is even a political twist here: the legend on the street is that they are more environmentally friendly than the naturally grown ones.

The Federal Trade Commission has also said that these products should be considered diamonds in every way this term can be used. This recognition has provoked a massive industry shift. Global sales for lab-grown diamonds increased to $12 billion in 2022, up 38 percent compared to the year before.

CBC News reports that “rapid growth has attracted the attention of mainstream jewelry giants like Pandora and Swarovski, which have launched their own lab-grown diamond lines. Luxury brands are beginning to embrace the created stones, with Prada introducing them into its latest fine jewelry collection. The gems are also showing up on red carpets, shining bright when worn by celebrities like Taylor Swift, Jennifer Lopez and Pamela Anderson.”

These days, I like to look for every reason to celebrate when markets seem to be working well, and this is one of those cases. For the better part of 100 years, diamonds have been the most overblown cartel good in the world, thanks to brilliant marketing (“A diamond is forever” is a DeBeers marketing pitch) that includes one of the century’s most popular songs (“Diamonds Are a Girl’s Best Friend”).

They came to be associated with wedding rings even though there is zero historical precedent for that, and the prices have been sending young men to the poorhouse for many generations.

Essentially, the diamond wedding ring reversed the ancient tradition of the dowry, which was the payment from the bride’s family to the groom. The idea was to make the daughters more marketable in the marriage market and it often meant that the newly formed family possessed new wealth at the very start of the match.

But with the diamond wedding ring, things got reversed: the groom would enter into marriage with new debt that had to be serviced just following marriage, and that was made worse with children, another car, and a house. Not a good way to start.

The lab-created diamond dramatically lessens the pressure, and allows the bride to wear a rock of magnificent size at a fraction of the price. So you get the high status without the high debt.

The development has sent DeBeers and the entire industry into an existential crisis, dealing what might be the final blow to Lloyd’s of London and the Rothschild family that has long controlled international diamond dealing through DeBeers. Give it a few years and we will see natural diamonds forced to relent with pricing. This time, fancy tricks like sudden reductions in supply will not work with ever more labs getting into the diamond business.

My own mentor Murray Rothbard would be cheering right now. He wrote in 1992:

“in South Africa, the major center of world diamond production, there has been no free enterprise in diamond mining. The government long ago nationalized all diamond mines, and anyone who finds a diamond mine on his property discovers that the mine immediately becomes government property …. In short: the international diamond cartel was only maintained and has only prospered because it was enforced by the South African government.”

Rothbard’s prediction of a long-term collapse of this market due to new pressure turns out to have been remarkably prescient.

Thanks to technology and declining costs of production, it seems as if the dream is finally coming true.

Diamonds could soon be within the reach of any budget, with some predictions that prices could fall into $100 or even $10 per carat. What a lovely world that would be!

Tyler Durden
Tue, 01/02/2024 – 05:00

“No Stomach” In US To Keep Funding Ukraine As ‘War Is Over’: Ex-Pentagon Official

0
“No Stomach” In US To Keep Funding Ukraine As ‘War Is Over’: Ex-Pentagon Official

Former Pentagon official Michael Maloof is predicting that Congress and the Pentagon are in for a “tumultuous” start of 2024, as the ongoing standoff over Biden’s billions more in Ukraine defense aid highlights the reality that there’s “no stomach” any longer to fund Ukraine

The ex-senior security policy analyst in the Office of the Secretary of Defense issued the words in a fresh interview with Russian media, wherein he also emphasized that the only way out for Kiev is through negotiations based on the current dire realities of the battlefield, which has seen setback after setback for Ukraine forces. 

Source: WaPo/Getty Images

This dire state of things has also been seen in the increasingly gloomy and negative coverage of Ukraine on the part of major mainstream media. For example the NY Times ran this surprising headline over the weekend: ‘People Snatchers’: Ukraine’s Recruiters Use Harsh Tactics to Fill Ranks. Weeks prior, in early December, the same publication issued this headline: U.S. and Ukraine Search for a New Strategy After Failed Counteroffensive.

Maloof issued his own even more pessimistic assessment, painting a picture of a domino effect spilling over into the halls of a tense and divided Congress which must belatedly acknowledge “the war is over”

According to Maloof’s assessment in the interview

“The United States has their appropriations hung up. The US government could shut down by January 17 if the administration and Congress can’t negotiate and work out an arrangement for funding Ukraine and Israel, but at the same time to enforce the border. I think the Republicans to date have held firm, and we’ll see if they’ll hold on. But there’s no stomach right now any longer to fund the Ukrainians.

Frankly, the people see that the war is over. Basically, the [Ukrainian] counteroffensive failed, and there’s no way that they can pick it back up and turn things around, because they’ve gone into total defensive mode. The so-called counteroffensive just does not exist,” said Maloof.

Michael Maloof, YouTube screengrab

This is a moment long past due where the American people and their leadership are being forced to put America first given the NATO’ization of Ukraine project has failed.

“We have got to worry about our whether our government is even going to be open for business,” he continued, and added: “there is a second tranche in February that would shut down as well if they have not reached a resolution on funding the government agencies the way the House has dictated.”

American public support for funding Ukraine amid the Russian invasion was already slipping as early as last summer…

And looming heavily in the background is the unpredictability of other global flashpoints which threaten to stretch US forces and resources thin. Speaking of Israel’s escalatory policies in Gaza, Maloof said, “I guess he [Benjamin Netanyahu] thinks he can go ahead and start raising all kinds of havoc not only with Iran, but also with Hezbollah up north. So are we going to help fund all of that?

“I mean, that’s the big question. And I don’t think there’s any stomach for that, considering that, you know, we are entering an election year,” emphasized Maloof again.

Tyler Durden
Tue, 01/02/2024 – 04:15