52.1 F
Chicago
Monday, October 5, 2026
Home Blog Page 87

Chinese Rare-Earth Suppliers Halt US Shipments As Decoupling Fears Surge

0
Chinese Rare-Earth Suppliers Halt US Shipments As Decoupling Fears Surge

The scenario we viewed as inevitable appears to be materializing, validating our decision to intensify coverage of the US-China decoupling theme and the Western-aligned miners positioned to supply the West if Beijing further weaponizes critical material exports, as it has throughout the Trump 2.0 era.

A Reuters report on Friday morning revealed that some Chinese rare-earth suppliers are refusing to ship material to US customers, citing fear of retaliation from Beijing.

The report continued:

A handful of Chinese suppliers have refused to ship rare earths to U.S. companies since early August when China imposed sanctions on the Responsible Business Alliance (RBA), a U.S. supply chain monitor, a separate source with direct knowledge of the situation said.

With China deploying its own trade compliance weapons, the companies were wary of punishment from Beijing for complying with the due diligence framework of the Responsible Minerals Initiative (RMI), a global mineral supply chain audit programme connected with the RBA, the source said.

Other Chinese rare earths companies had already stopped shipments to the U.S. to avoid entanglement in geopolitics in recent months, two other sources familiar with the trade said.

One cited four instances where Chinese firms declined to send material for fear it could be resold to banned users.

The exact number of blocked suppliers and shipments remains unknown, and that ambiguity is itself part of Beijing’s asymmetric leverage campaign against the US.

China does not need to announce a formal trade embargo to choke critical material flows. Export controls, licensing delays, and the threat of regulatory retaliation can halt shipments to US importers almost overnight.

Really, Beijing retains a kill switch inside US defense, aerospace, semiconductor, and energy supply chains, forcing companies to scramble for substitutes only after supplies have collapsed.

That’s why we’ve sounded the alarm in recent weeks that the decoupling theme should be top of mind for Wall Street desks, with our coverage focused on tungsten and germanium, both of which have been restricted from export to the US and are colliding with a rearmament cycle in the West.

Here’s what we’ve reported over the last few weeks leading up to the Reuters headline this morning:

  1. The AI Boom Runs On Tungsten, But Global Supplies Are “Running On Empty”
  2. US Tungsten Scrap Export Ban Takes Effect As Global Supply Crisis Deepens
  3. What Happens When A Metal The West Can’t Live Without Runs Short
  4. The West’s Answer To Break China’s Tungsten Stranglehold Before Historic Rearmament Cycle Ramps
  5. China’s Tungsten Chokehold Turns Almonty Into a Critical-Metal Lifeline
  6. China’s Record Ship Swarm Around Taiwan Sends Decoupling Alarm To Wall Street

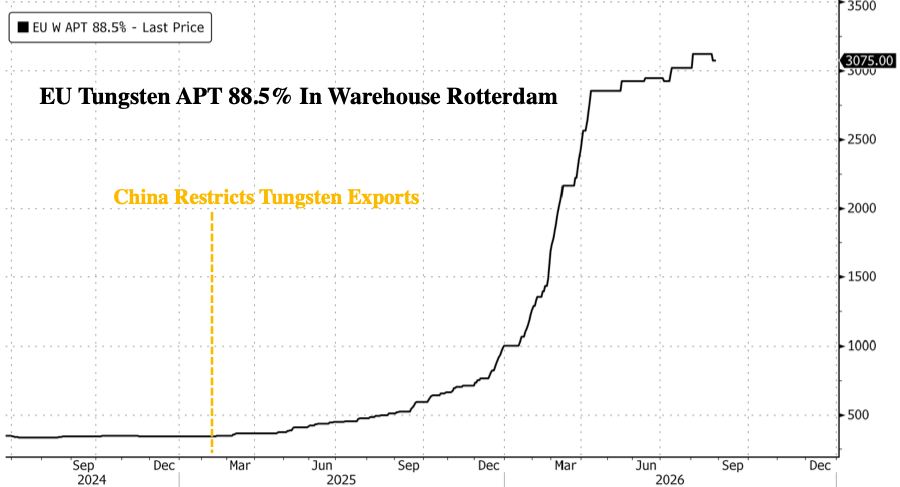
China’s tungsten export restrictions have sent European prices soaring…

Late last month, the US Commerce Department halted exports of tungsten scrap and shredded battery material in a defensive move to retain scarce supplies inside the country. The move merely shows how rapidly Washington is shifting from the free-trade status quo toward resource security as domestic supplies dwindle and an urgent race emerges across the West to procure new ex-China supplies.

The Sino-US bilateral relationship deteriorated yet again this week after Beijing derailed the G20 joint communiqué over a single phrase, “non-market,” only weeks after the Trump administration sanctioned Chinese entities linked to Iran.

All eyes now turn to the Trump-Xi meeting in Washington later this month.

The decoupling theme should be top of mind on Wall Street as China restricts critical-material flows to the West. These materials are essential building blocks not only for next year’s rearmament supercycle but also for AI, reindustrialization trends, efforts to power up America, and even physical AI.

Tyler Durden
Fri, 09/04/2026 – 12:35

Not So Fast: Mistrial Declared In Lindsay Clancy Murder Trial, But Judge Gives Defense An Hour To Seek Stay

0
Not So Fast: Mistrial Declared In Lindsay Clancy Murder Trial, But Judge Gives Defense An Hour To Seek Stay

Update (1226ET): After the jury remained deadlocked following 36 hours of deliberations over seven days, Judge William Sullivan declared a mistrial in the Lindsay Clancy murder case – however he’s given the defense one hour to seek a stay from the Massachusetts Supreme Judicial Court.

Why would the defense want a stay of a mistrial? Because if they can instead force the holdout juror to be removed, they avoid a brand new trial and Clancy will go free. 

“This is really intense. Reddington asked for emergency Supreme Judicial Court intervention moments before the jury walked back in,” reports NewsNation’s Brian Entin.

Developing…

* * *

Update (1135ET): A mistrial was declared in the Lindsay Clancy case on Friday, after a holdout juror refused to bend the knee and let her off, Fox News‘ Bill Melugin reports.

* * *

Lindsay Clancy’s defense team is absolutely melting down after Judge William Sullivan refused to remove a holdout juror in Clancy’s triple-murder trial, in which the jury must decide whether Clancy is criminally responsible for strangling her three children, Cora, 5; Dawson, 3; and Callan, 8 months. Her defense claims that she was suffering from hallucinations amid postpartum psychosis. The prosecution claims she was not in psychosis when she sent her husband out of the house on long errands, before she murdered her children and then tried to make it appear as though she attempted suicide. 

Reuters

On Thursday, the jury foreperson sent a note indicating one juror was refusing to apply the judge’s instructions on reasonable doubt. Judge William Sullivan questioned each juror individually at sidebar, then gave the full panel what defense attorney Kevin Reddington later called a “soft” reminder of the law and sent them back to deliberate.

“They’ve said at this point that they can,” Sullivan said. “That was specifically addressed towards the specific question, and that’s what I’m doing.”

Reddington demanded that the holdout to be removed, and requested a more pointed inquiry – which Sullivan declined. 

According to Clancy’s defense team, the holdout juror is a man. 

“Clearly, we have a person who, under their oath, stood in front of you yesterday … under oath looked you in the eye and lied,” said Reddington. “That juror told you that he would be able to apply the law to the facts as you asked him.”

Reuters

When court resumed Friday, Reddington hammered Sullivan, arguing that the prior instruction was inadequate, and pressed again for removal or further questioning of the juror (whom he accused of having lied under oath). Sullivan refused additional inquiry, stating he had considered the issue at length and would not remove the juror. Redding responded by calling Sullivan ‘soft’ – to which Sullivan replied: “What do you want me to do?! Get a brass band? I read the instruction as written by the Massachusetts Supreme Court. The fact I perhaps did not give it my full inflection, I’m sorry about that, I’m not an actor – I’m giving instruction.

No More Sidebars!

Following the spat, Clancy’s defense team filed a motion to Sullivan asking that there be no more sidebars for the remainder of the trial – and that all further proceedings be handled in open court. The prosecution, meanwhile, suggested that there be no further questioning of the jury, and asked that Sullivan send them to continue deliberations, arguing that the holdout juror has “no indication of lack of impartiality or bias or extraneous influence, and no indication of inability to deliberate.”

Reddington disagreed – arguing that the juror appears to have a personal issue getting in the way of him being able to deliberate fairly, and demanded that he be replaced with an alternate. 

According to Massachusetts law, a judge can only send a jury back for deliberations twice before declaring a mistrial – which looks like where we’re headed.

Lindsay Clancy convicted of murder?
Yes 9% · No 92%
View full market & trade on Polymarket

Tyler Durden
Fri, 09/04/2026 – 12:26

Russia Tries To Assassinate Ukraine’s SBU Chief With Unprecedented Drone Attack On Kyiv HQ

0
Russia Tries To Assassinate Ukraine’s SBU Chief With Unprecedented Drone Attack On Kyiv HQ

The Kremlin has long previewed that its next escalation step against Ukraine would be to start attacking ‘decision-making centers’, or headquarters and government buildings. That moment has clearly begun and is now in an active phase, also as strikes ramp up on the key southern port of Odesa, as well as on Ukraine-linked cargo and other shipping. On Friday a Russian drone slammed into the headquarters of Ukraine’s Security Service (SBU) in central Kyiv.

The SBU is the country’s top domestic security and intelligence service – somewhat akin to the FBI in America. It primarily oversees counterintelligence, counterterrorism, espionage investigations, as well as engages in some law-enforcement functions, especially concerning top level crime including among government officials. It has been the mastermind behind multiple high-level deadly and destructive attacks on Russia.

Drone targeted SBU chief at around 3:30pm local, via pravda.com.ua

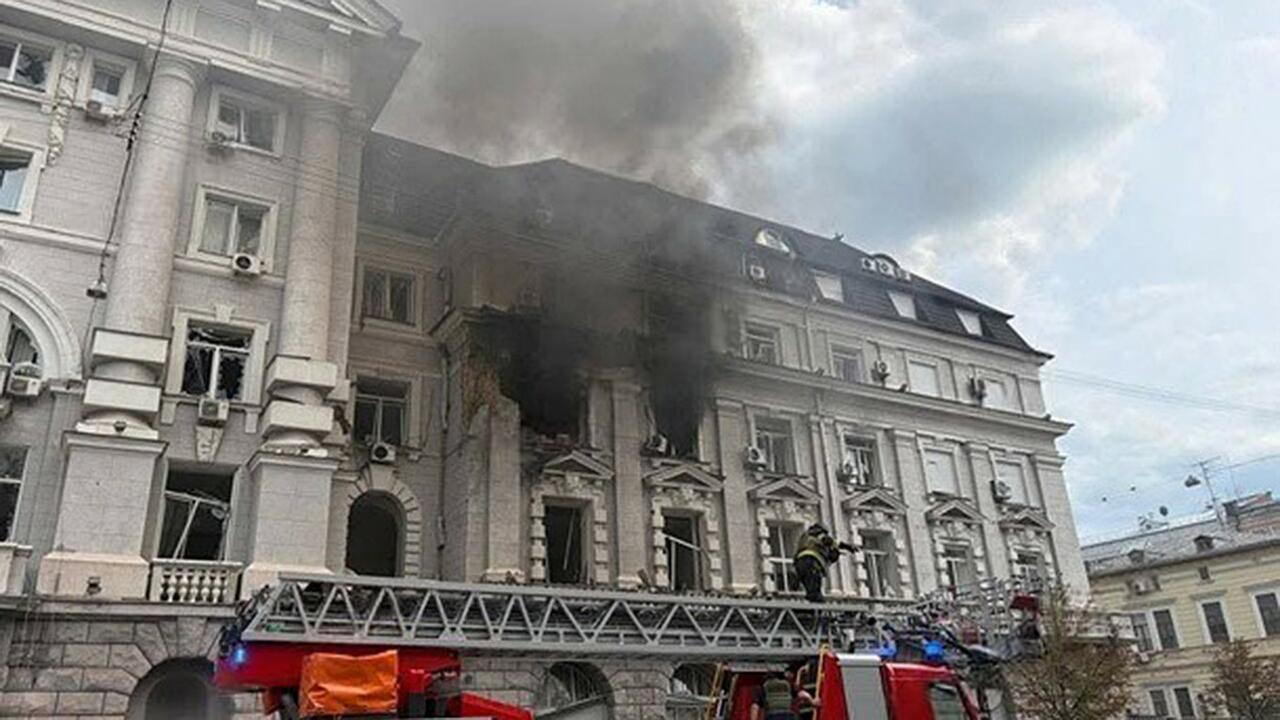
President Zelensky soon after the attack announced and confirmed that the SBU’s central building on Volodymyrska Street, in the heart of iconic downtown near St. Sophia Cathedral, was struck. Flames and smoke have been seen billowing high over the high-secure central district.

“I spoke with the Head of the Security Service of Ukraine, Oleksandr Poklad. Unfortunately, a Russian drone struck the central building of the Security Service of Ukraine on Volodymyrska Street in Kyiv, across from St. Sophia Cathedral,” Zelensky said.

“The drone was aimed directly at the office of the Head of the Security Service in that building,” he added. Zelensky has ordered his military to mount a “tangible response and, where possible, one that mirrors this strike, to the Russians once everything is ready. Our military will support this response.”

If accurate, this sends an alarming and resounding message – that not only is Moscow now willing to directly target top headquarters buildings, but that it’s ready to assassinate intelligence directors. 

President Zelensky said the drone had precisely targeted the office of the head of the SBU service, Oleksandr Poklad, but he had survived the attack —The Times

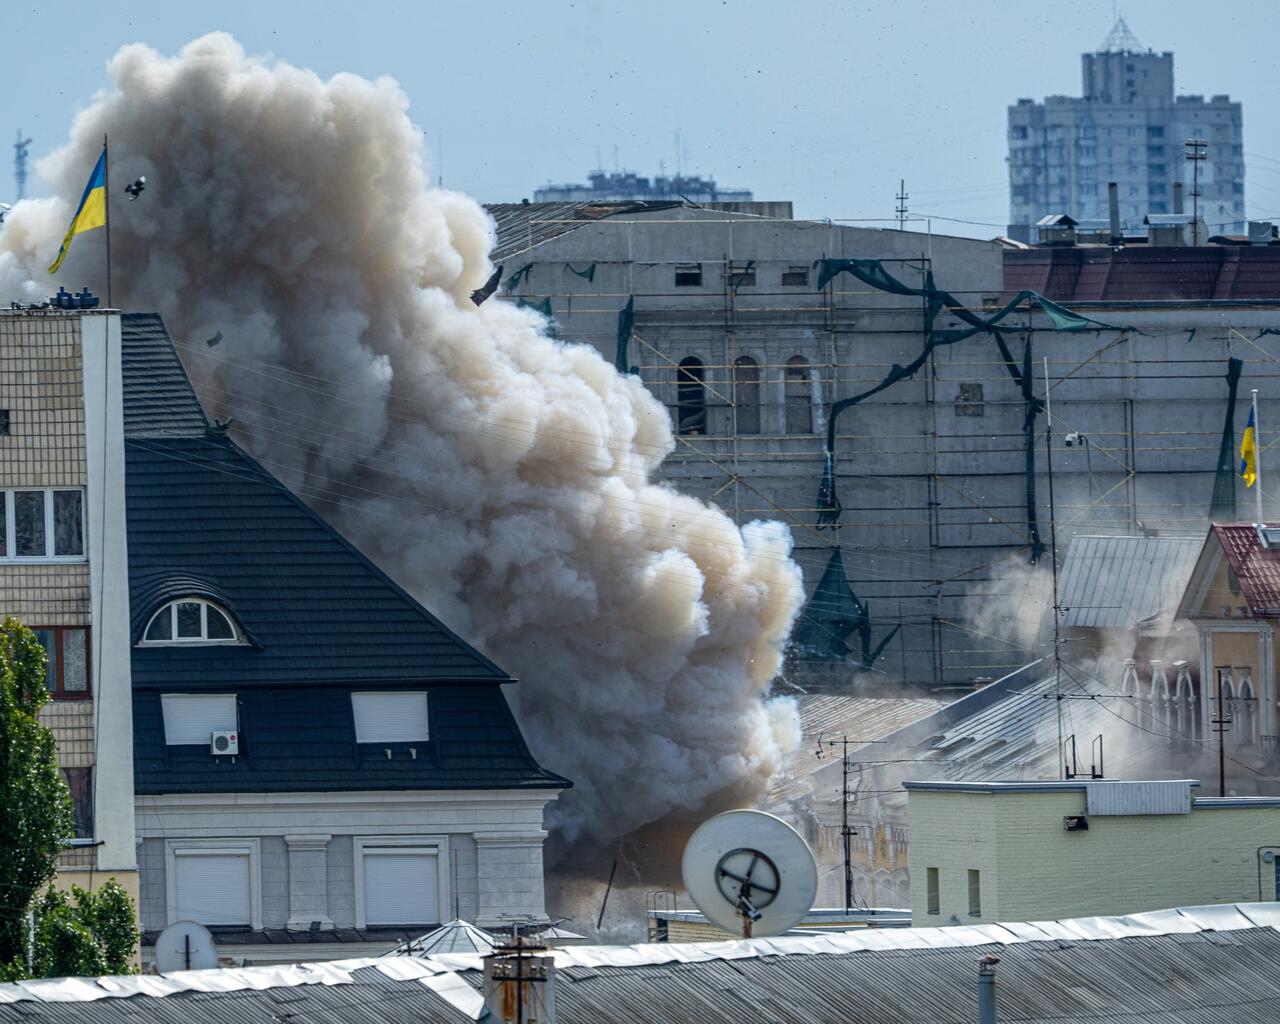
Big smoke cloud in drone strike aftermath targeting security HQ. ZUMA Press Wire/Shutterstock

European media reports of the immediate aftermath, “Zelenskyy said emergency services were attending the scene. There was no immediate information on casualties.”

A large explosion was widely heard among bystanders during a mid-afternoon air raid siren in the capital city, after which Mayor Vitali Klitschko initially reported a fire and said emergency crews were headed to the scene. Several drones had been inbound during the attack incident.

According to some of the latest reporting via CNN:

The daytime strike – the first time the SBU building has been hit in the four-and-a-half year conflict – came after days of near continuous aerial assaults by Russia on the Ukrainian capital.

Authorities said 12 people were injured in the attack and that emergency services were at the scene.

This comes after more than a week of consecutive nightly drone and missile attacks on the capital, as Russia indicates it is ‘repaying’ Ukraine for its own constant long-range drone attacks which have wreaked havoc on oil refineries and industrial sites this summer.

“At least 53 people have been killed and 134 injured in Kyiv city and the wider Kyiv region since the start of these near non-stop attacks last month,” CNN also notes.

Unprecedented: Downtown SBU headquarters on fire…

This even could serve as the catalyst that gets Zelensky’s Western backers to rush more anti-air missiles and systems – such as the Patriot – to Ukraine. “It is rare for government buildings in central Kyiv to be reached by Russian strikes, especially in broad daylight,“ The Guardian underscores. “The explosion from the hit on the SBU building could be heard several from several blocks away.”

One thing is clear: the gloves are indeed coming off. And just as Trump may be trying to de-escalate the Iran war ahead of November midterms in the US, the Russia-Ukraine war just massively escalated past a likely point of no return.

Tyler Durden
Fri, 09/04/2026 – 12:15

US Diesel Pump Prices Hit Record As Global Refined-Products Crisis Threatens Industrial Economy

0
US Diesel Pump Prices Hit Record As Global Refined-Products Crisis Threatens Industrial Economy

Goldman explained this week that Gulf oil exports had recovered to between 15 million and 16 million barrels per day, roughly two-thirds of prewar levels, with the rise of dark tanker transits obscuring some flows from conventional tracking via the Automatic Identification System (AIS). Yet headline crude volumes don’t tell the entire story. As we have repeatedly noted, crude itself does not keep the industrial economy humming. Diesel does.

Make no mistake: There is a refined-products crisis because of disruptions in the Strait of Hormuz and Ukrainian one-way drone attacks on Russian energy infrastructure. That tightening in physical markets, especially for diesel, was evident on Thursday, when US retail pump prices reached a record high.

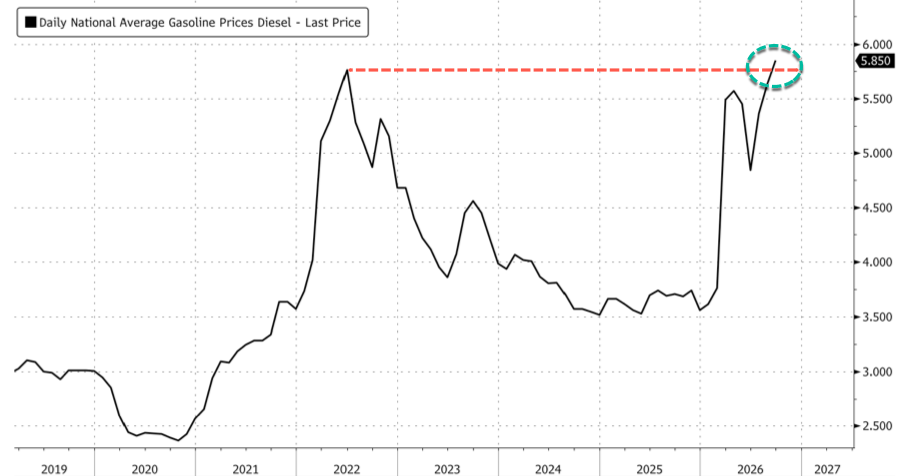
US retail diesel prices surged to a record $5.85 per gallon on Thursday, according to new data from AAA, surpassing the previous peak reached in June 2022.

Unlike crude oil, diesel is the fuel that keeps the industrial economy moving: It powers trucks, construction equipment, tractors, generators, and home-heating systems. The spike threatens to unleash another wave of energy-driven inflation just as global supplies tighten ahead of the Northern Hemisphere’s harvest and heating seasons.

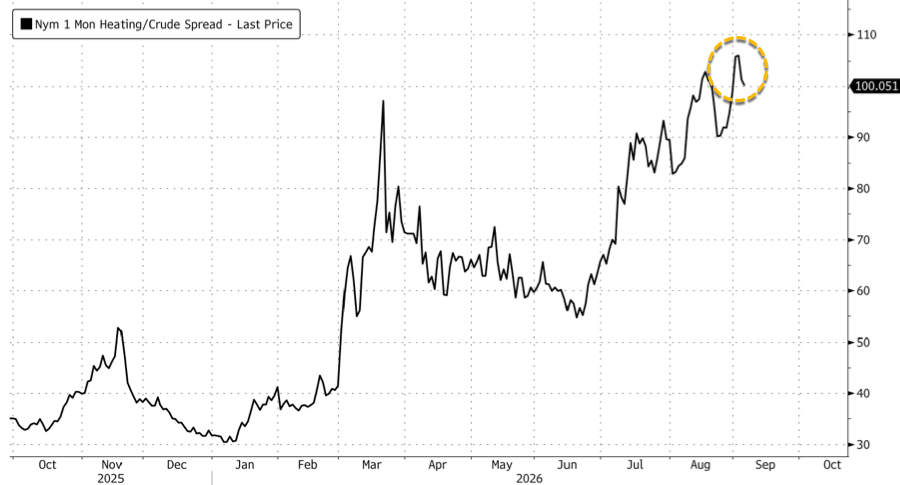
Bloomberg’s NYMEX one-month heating-oil/crude spread, tracked on the Bloomberg Terminal as the HOCL1 Index, breached $100 per barrel early Tuesday before surging to $108 early Wednesday. It was trading at $99 early Friday morning.

President Trump urged US refiners earlier this week to increase production and lower gasoline and diesel prices, but the industry has limited spare capacity. Many facilities are already operating near, or even above, their stated maximum processing rates following a summer production surge.

Despite the recovery in tanker flows through the Strait of Hormuz, TotalEnergies SE head Patrick Pouyanne recently said there wasn’t a “single tanker of products” moving out of the waterway.

Again, the energy crisis is in the refined-products complex.

Tyler Durden
Fri, 09/04/2026 – 12:00

‘Good News Is Bad News’: Big Jobs Beats Sends Rate-HIKE Odds Soaring; Batters Bonds, Stocks, Gold

0
‘Good News Is Bad News’: Big Jobs Beats Sends Rate-HIKE Odds Soaring; Batters Bonds, Stocks, Gold

A four standard deviation beat for non-farm payrolls this morning (good news) is triggering ugly reactions (bad news) across markets with rate-hike odds for September ripping back up near recent highs (despite no signs of inflationary wage growth – in fact it is slowing)…

Audrey Childe-Freeman, Bloomberg Intelligence’s chief FX strategist:

“The strength in the latest NFP report will validate Sept. Fed rate-rise talks and most likely give the dollar a short-term-yield-driven lift.”

“But that’s priced, and unless the Fed signals the beginning of an aggressive tightening cycle, the Fed-driven dollar upside may be contained into 4Q.”

That in turn is hammering the short-end of the yield curve…

And weighing on stocks…

Based on JPMorgan’s matrix, we should see a drop in the S&P of between 0.5% and 1.25%…

Significantly more than the options market implied (+/-0.52%)…

The dollar jumped…

Which in turn dragged gold down…

Christopher Hodge at Natixis reckons the doves will have to prove their case when the Fed meets later this month.

“Most policymakers seemed sanguine about the labor market so inflation will clearly still be the primary driver of near term policy. A softer print today could have given some wiggle room on what was considered to the an acceptable core CPI print, but clearly we didn’t get that. Instead, the onus will continue to be on the doves to get a disinflationary print that justifies another hold – we are putting that bogey at about 20bps. Absent that, the Fed will likely hike in September.”

Jeffrey Rosenberg, a portfolio manager at BlackRock Inc., says on Bloomberg TV that the biggest issue here for the Fed isn’t the job market but the extent of “pass through” of energy prices to broader inflation. 

He still sees the Fed’s Sept. 16 decision as entirely dependent on the CPI report. If that shows continuing progress in inflation coming down, then he sees the Fed holding.

Vail Hartman at BMO Capital Markets reflects what’s emerging as the consensus view on this report:

Today’s data lends support to the hawkish camp, but stops shy of making a definitive case for a rate hike on September 16.

All of which makes us wonder if the knee-jerk response is an over-reaction since we note what Fed Chairman Warsh said last week: “I believe the labor markets are consistent with full employment,” he said, which is why policymakers have largely priced in healthy employment.

The bigger focus remains inflation.

Today’s numbers are still second fiddle to what we get next week – both producer and consumer prices, which will be used to compute the PCE numbers. While today’s strong jobs reading surely supports the case for a hike, wage gains don’t suggest any inflation pressures so it’s not like the labor market is a smoking gun for a hike.

‘Give disinflation a chance’, was the message from Waller yesterday (who basically corroborated Williams). The center of the committee has not shifted – it is still data-dependent.

He might hold in September unless inflation comes in hot, and he made clear that NFP matters less than CPI next week.

Event risk has effectively migrated from payrolls to CPI.

Seema Shah, Chief Global Strategist at Principal Asset Management doesn’t see these numbers having a major impact on the Fed debate:

“For the Fed, there is little here to challenge the view that inflation remains the primary concern. Markets may edge up their expectations for a September hike following today’s release, but next week’s CPI report is still likely to be the key swing factor for policy.”

The news media will run with the “JOB JOBS JOBS” story, but the real news is next week’s inflation print, and a melt-up setup that still has to survive Hormuz (heating oil, diesel record highs).

To summarize, the jobs market appears strong but next week’s data will determine what the Fed does.

Tyler Durden
Fri, 09/04/2026 – 08:56

Labor Shock: US Adds 162K Jobs In August, 4-Sigma Beat And Above Highest Forecast

0
Labor Shock: US Adds 162K Jobs In August, 4-Sigma Beat And Above Highest Forecast

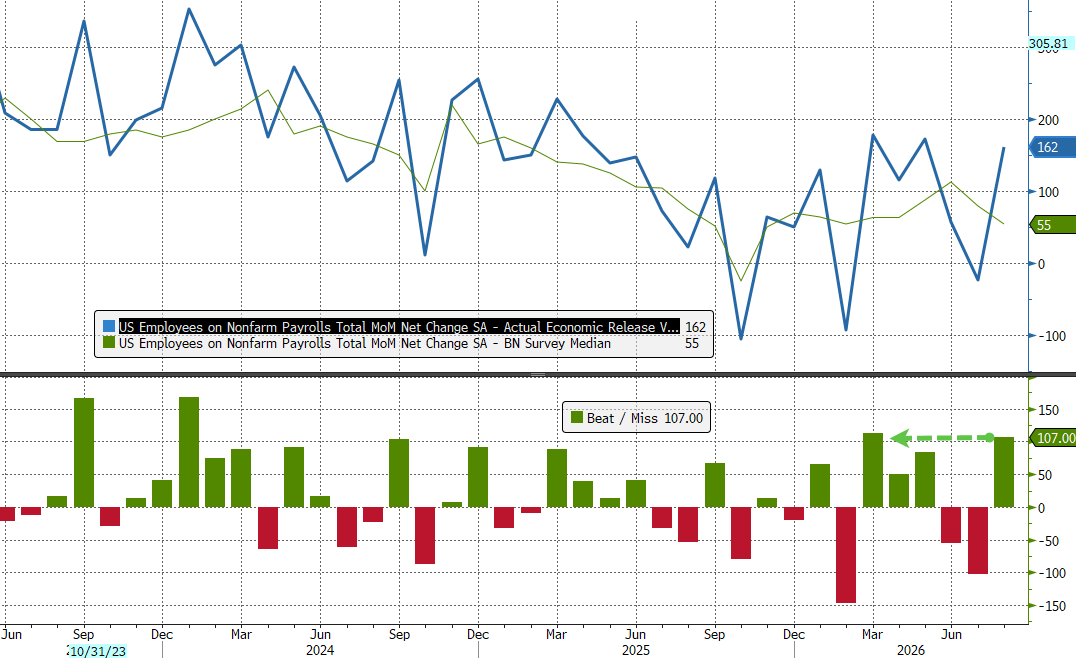
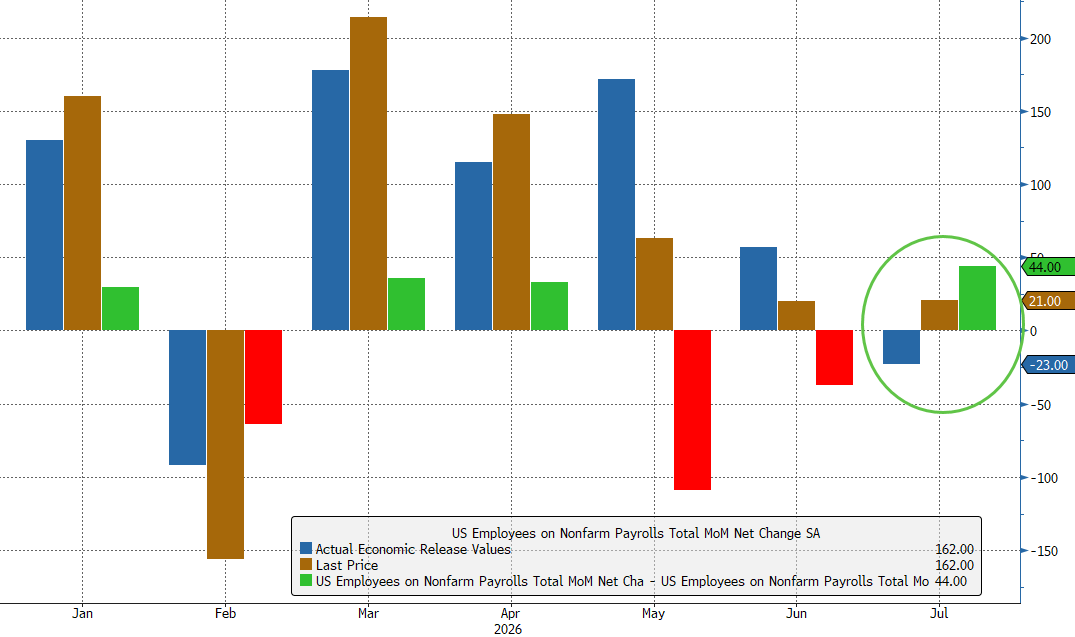
In our jobs report preview we quoted JPM’s Market Intel desk which said that today’s August payrolls number will be a case of “good news is bad news”, and sure enough futures are sliding  and yields surging after moments ago the BLS reported that in August, the US added a whopping 162K jobs, up from an upward revised 21K (July is no longer negative -23K), and the second highest monthly increase of 2026 (only March was higher)…

… and printed not only above the median estimate of 50K but above the highest Wall Street estimate of 125K (from Pantheon). In fact, this was a a 4-sigma beat to expectations.

Understandably, today’s blowout print was the biggest beat of estimates going back to March. 

For once, revisions were quite favorable, with June numbers revised up by 11,000, from +20,000 to +31,000, and July revised up by 44,000, from -23,000 to +21,000. With these revisions, employment in June and July combined is 55,000 higher than previously reported.

Remarkably, unlike previous months when jumps in payrolls were met with declines in employment, in August we saw a surge of 569K employed workers from 162.177MM to 162.746MM alongside the 162K increase in payrolls.

This meant that after steadily declining for the past year, and diverging with the number of payrolls, the number of employed Americans posted a sizable jump as shown below.

The unemployment rate remained flat at 4.1%, and in line with expectations. Among major groups, the unemployment rate for people who are Asian declined to 3.2%, The rate for teenagers edged up to 14.1% over the month, mostly  offsetting a decline in the prior month. The jobless rates for adult men (4.0 percent), adult women (3.5 percent), and people who are White (3.7 percent), Black (6.0 percent), or Hispanic (4.8 percent) showed little change in August. 

Average hourly earnings rose 0.3% MoM, in line with expectations, and 3.1% YoY. In August, average hourly earnings of private-sector production and nonsupervisory employees rose by 11 cents, or 0.3 percent, to $32.53. The average workweek for all employees on private nonfarm payrolls edged up by 0.1 hour to 34.4 hours in August. In manufacturing, the average workweek edged up by 0.1 hour to 40.5 hours, and overtime was unchanged at 3.1 hours. The average workweek for production and nonsupervisory employees on private nonfarm payrolls remained at 33.8 hours.  

Some more details from the report:

The number of long-term unemployed (those jobless for 27 weeks or more) changed little at 1.9 million in August. The long-term unemployed accounted for 27.0 percent of all unemployed people. 

The labor force participation rate edged up to 61.6 percent in August but is down by 0.5 percentage point since January. The employment-population ratio, at 59.1 percent, changed little over the month and since January. 

The number of people employed part time for economic reasons decreased by 414,000 to 4.4 million in August. These individuals would have preferred full-time employment but were working part time because their hours had been reduced or they were unable to find full-time jobs. 

In August, the number of people not in the labor force who currently want a job changed little at 5.7 million. These individuals were not counted as unemployed because they were not actively looking for work during the 4 weeks preceding the survey or were unavailable to take a job. 

Among those not in the labor force who wanted a job, the number of people marginally attached to the labor force changed little at 1.7 million in August. These individuals wanted and were available for work and had looked for a job sometime in the prior 12 months but had not looked for work in the 4 weeks preceding the survey. The number of discouraged workers, a subset of the marginally attached who believed that no jobs were available for them, changed little in August at 441,000. 

Taking a closer look at the composition of jobs per the Establishment survey we find the following: 

  • Employment in food services and drinking places increased by 59,000 in August, well above the average monthly gain of 12,000 over the prior 12 months.
  • Local government education added 42,000 jobs in August, largely offsetting a decrease in the prior month. Local government education has shown little net change since January 2025.
  • In August, employment in manufacturing continued its upward trend (+16,000) and is up by 58,000 since a recent low in December 2025. Employment in machinery manufacturing (+6,000) and in fabricated metal product manufacturing (+6,000) continued trending up in August. 
  • Employment in health care continued to trend up in August (+13,000) but at a slower pace than the average monthly gain over the prior 12 months (+32,000). Over the month, home health care services (+11,000) and hospitals (+8,000) added jobs. 
  • Information employment declined by 23,000 in August, following losses that had averaged 8,000 per month over the prior 12 months. In August, job losses occurred in computing infrastructure providers, data processing, web hosting, and related services (-8,000), in publishing industries (-7,000), and in broadcasting and content providers (-5,000). 
  • Construction employment changed little in August (+22,000). Employment in nonresidential specialty trade contractors continued to trend up (+8,000), similar to the average monthly gain over the prior 12 months (+6,000).

Employment showed little change over the month in other major industries, including mining, quarrying, and oil and gas extraction; wholesale trade; retail trade;  transportation and warehousing; financial activities; professional and business services; social assistance; and other services.

Remarkably, unlike previous months where the data was gamed to cover up underlying weakness, this time we saw a very powerful increase in qualitative components, as full-time jobs surged by 735K to 134.288 million, while part-time jobs dropped by 223K!

The unexpectedly strong print has understandably sent Sept rate hike odds spiking and has hammered risk assets, although the real decider whether we get a rate move this month will be next week’s CPI print. As a reminder, according to JPM, a print above 95K will lead to a 0.5% to -1.25% down day for the S&P.


Tyler Durden
Fri, 09/04/2026 – 08:47

Futures, Yields Flat Ahead Of August Jobs Report

0
Futures, Yields Flat Ahead Of August Jobs Report

US futures are choppy, trading between unchanged and modestly higher, ahead of today’s jobs report which sees a modest increase in August payrolls (but the risk is for another negative print, see our preview here). As of 8:00am ET, S&P futures are flat and Nasdaq futures gain 0.5% as Mag 7 stocks trade mixed premarket, with NVDA (+1.4%) and AMZN (+0.7%) leading and TSLA (-2.1%) lagging. Bond yields are steady as traders wait to see whether Friday’s payrolls report will offer the Fed enough justification to hold off on an interest-rate hike in September. The USD is 20bp higher as the yen drops after yesterday’s surge. Commodities are mixed: oil fell, while base metals and Ags are both higher. Overnight, macro headlines were largely muted following yesterday’s bond market rally after Waller’s comments. All eyes are on the 8:30am ET NFP release (see our preview here), but investors are increasingly more focused on next week’s CPI than the payroll number, given Warsh’s assessment of the labor market and Waller’s comments yesterday.

In premarket trading, Mag 7 stocks are mixed: Tesla falls 2% as the electric-car maker’s invite-only, closed-door Cybercab launch event resulted in little splash. Nvidia +1.1%, Amazon +0.5%, Meta +0.5%, Alphabet +0.3%, Microsoft -0.3%, Apple -0.3%

  • Adobe (ADBE) falls 3% after naming Anil Chakravarthy as its next chief executive officer, thrusting the company veteran into a challenging competition with artificial intelligence upstarts.
  • Asana (ASAN) falls 10% after the software company gave an outlook that was seen as disappointing.
  • Equifax (EFX) falls 5% and TransUnion (TRU) slips 6% after US Federal Housing Finance Agency Director Bill Pulte issued renewed criticism of credit bureaus for overcharging Americans.
  • Guidewire Software (GWRE) falls 15% after the company gave a first-quarter forecast that was weaker than expected on key metrics, including revenue and adjusted operating profit. Analysts said the outlook could be conservative.
  • Planet Labs (PL) rises 12% after the satellite-imaging service firm reported second-quarter revenue that beat the average analyst estimate and lifted the low end of its full-year revenue outlook for 2027.
  • Samsara (IOT) climbs 14% after the fleet management technology provider boosted its guidance for this year’s total revenue and adjusted earnings per share. The ranges for both metrics topped analyst estimates.

In other corporate news, Tesla’s much-anticipated Cybercab launch, an event nearly two years in the making, resulted in little splash or detail as the two-seat vehicle was added to the company’s robotaxi fleet. Lululemon comparable sales fell 9% in the second quarter and lowered its full-year outlook for a second straight quarter, signaling deep challenges for incoming CEO Heidi O’Neill. Speaking of ECM, health and fitness ring-maker Oura filed for an IPO, showing soaring revenue. Its listing could raise as much as $3 billion, based on prior Bloomberg News reports.

While market volatility remains subdued, with the VIX matching its lowest reading of the year, things promise to get livelier post the Labor Day holiday, however, and next week looks busy according to BBG. The traditional fall conference season kicks off, with hundreds of corporates presenting across the country, and there’s a CPI inflation print and a possible massive AI IPO filing to keep traders occupied.

The August jobs report arrives at a time when the odds of a quarter-point Fed hike this month are roughly even. While Fed Chair Kevin Warsh last week emphasized that policymakers’ focus is firmly on inflation, the employment report could help buy them time to assess whether current policy is restrictive enough to bring price pressures under control. Economists estimate the report will show a 55,000 increase in payrolls after an unexpected dip in July employment. Such a result would be broadly in line with average job growth this year. The unemployment rate is seen holding at 4.1% (full preview here).

One of the major events on the calendar over the next few weeks is likely to move markets and close the implied-realized gap, but for now short-dated index optionality looks more like a sell than a buy. The option implied SPX swing around NFPs is priced about the same as last month, when the 0.55% option-implied move ended up being very close to the realized move of 0.62%.

“The market needs a result weak enough to give the Fed a reason to keep interest rates unchanged, but not so weak that it intensifies concerns about a recession,” noted Linh Tran at XS.com. “Stronger-than-expected employment and wage growth could push yields higher again and weigh on equities.” By contrast, figures close to expectations and accompanied by moderating wage growth would create favorable conditions for the S&P 500 to retest its record high, Tran said.

JPMorgan’s Market Intelligence desk expects a “Good news is bad news” environment for market reaction to the print in most outcomes, with a Goldilocks scenario in the 30k to 70k range.

Bloomberg Economics’ Anna Wong expects the payrolls number to undershoot consensus, citing a pattern of the data disappointing in August. JPMorgan’s Market Intelligence desk sees a Goldilocks scenario in the 30,000-to-70,000 range. 

“We are in the territory where bad news is good news, as both equities and credit are likely to be driven by what rates do,” said Mohit Kumar at Jefferies. “A small positive number would be a sweet spot for the markets.”

In AI news, the launch of a new Astra model sent OpenAI proxy SoftBank’s shares soaring in Tokyo trading. Astra benchmark scores of AGI — where artificial general intelligence surpasses human capabilities – gives OpenAI confidence to claim it has overtaken Anthropic on some measures. DeepSeek is planning to power a new data center with an order for one of the largest known clusters of Huawei AI chips as part of China’s efforts to replace Nvidia. Elsewhere, Anthropic is set to finalize an expansion of its revolving credit facility to $15 billion, clearing a hurdle before a public filing by the AI firm for its highly anticipated IPO.  

In other assets, trading in yen call options against the dollar expiring this month was more than two-and-a-half times the volume of puts on Thursday, CME data shows. It’s part of a rush to unwind yen-funded carry trades, while the latest positioning data from CFTC data suggests scope for further short covering.

Europe’s Stoxx 600 edged higher 0.1%. Volkswagen AG rose as much as 9.7% after a major restructuring announcement. Here are the biggest movers Friday:

  • Volkswagen shares gain as much as 9.7%, the biggest intraday move since March 2023, after the carmaker’s supervisory board backed a sweeping restructuring that includes 50,000 additional job cuts
  • Continental shares rise as much as 4%, the most in two months, after Oddo BHF upgraded the tire maker. Analysts said the company is one of the most profitable within the sector
  • AT&S shares rise as much as 10%, extending a huge year-to-date rally, after Oddo upgraded the printed circuit board maker to outperform, saying new contracts should maintain momentum
  • Accor shares gain as much as 3.2% as Morgan Stanley upgrades the hotelier to overweight, naming it a top pick among the travel and leisure companies it covers
  • Vodafone gains as much as 2.3% after Goldman Sachs upgraded its view on the company to buy from sell in a wider review of the European digital infrastructure and telecoms sector
  • Studsvik gains as much as 8.1%, after the founder and CIO of US hedge fund Segra Capital Management bought shares in the Swedish nuclear technology company
  • Oxford Nanopore shares drop as much as 12% after one of its investors, Novo Holdings, offered shares at a hefty discount to Thursday’s close
  • Kuehne+Nagel shares fall as much as 2.5% after being downgraded to underweight from equal-weight at Morgan Stanley, which sees better execution as priced in and downside risks to Ebit
  • Navitas Petroleum and Rockhopper Exploration are trading lower today as tensions around the Falklands Islands rise and Argentina targets their Sea Lion project

Earlier, Asian stocks rose on Friday as investors pared bets on a Federal Reserve interest-rate hike this month, easing some of the pressure that higher bond yields had put on equities earlier in the week. The MSCI Asia Pacific Index climbed 0.8% and is on track for a weekly gain. Stocks had come under pressure as rising global bond yields stoked concerns about the outlook for interest rates, though sentiment improved after Fed Governor Christopher Waller said he’d be inclined to leave rates unchanged if inflation continues to slow. Most markets in the region advanced, including South Korea, Taiwan and Hong Kong. Japan’s Topix was little changed as investors assessed the impact of the yen’s recent gains. SK Hynix, Samsung Electronics and TSMC were up as well. The regional stock gauge is on course for a second straight week of gains, with financials providing the biggest boost as the sector heads for its best week in almost five months.

In FX, the Bloomberg Dollar Spot Index swung between gains and losses after falling as much as 0.7% to the lowest since May 11 on Thursday. The yen held most of its gains after advancing more than 2% on Thursday. The currency has strengthened this week to around 156 amid growing expectations that the Bank of Japan will tighten monetary policy faster than previously thought. BOJ policymakers could raise rates at three consecutive meetings through December in an extreme scenario where yen weakness persists, according to Nomura Securities Co. A quarter-point increase this month “looks reasonable,” while “it’s possible that we can have back-to-back rate hikes in October and December,” Yujiro Goto, head of FX strategy in Japan, told Bloomberg TV.

  • USD/JPY rose 0.4% to 156.45 as a rush to unwind yen-funded carry trades helped propel the Japanese currency higher
  • EUR/USD little changed at 1.1622; it’s up 0.3% this week
  • NZD/USD gained 0.3% to 0.5897 before erasing gains; New Zealand’s central bank is more likely to wait until December before raising interest rates again, according to Assistant Governor Karen Silk

In rates, treasuries are little changed ahead of August employment data at 8:30 a.m. New York time amid similarly muted price action in European bonds, keeping US yields within a basis point of Thursday’s closing levels. US 10-year yield near 4.76% is less than 1bp lower while German and UK counterparts are slightly higher on the day; US front-end tenors lag slightly on the curve, flattening 2s10s spread by more than 1bp vs. Thursday’s close. Thursday’s session saw traders ramp up a range of hedges around the jobs report. Ahead of the data, swaps are pricing in around 14bp of Fed tightening for the September policy meeting and a combined 35bp by the end of the year. IG dollar issuance slate empty so far after just one deal was priced Thursday, bringing weekly total to about $10 billion, broadly in line with dealer estimates.   

In commodities, WTI crude oil , though down about 1%, remains on course for biggest weekly gain since July following renewed US-Iran hostilities.

US economic data calendar includes only the jobs report, for which median economist estimate of nonfarm payrolls change is 55k and crowdsourced whisper number is 30k.. Fed speaker slate empty for the session. External communications blackout period around the Sept. 16 policy announcement begins Saturday

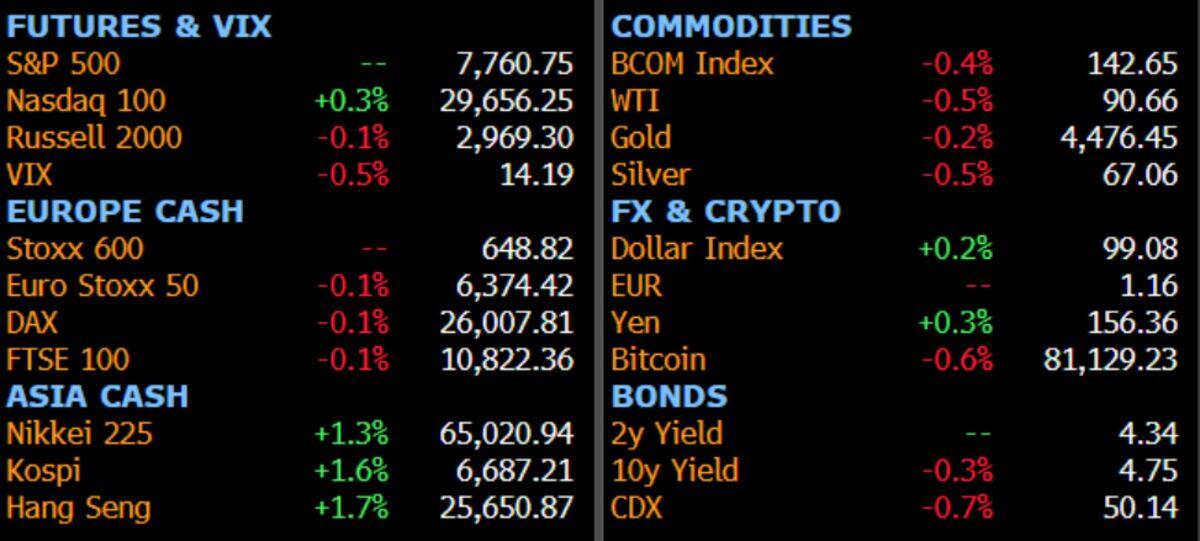
Market Snapshot

Top Overnight News

  • A U.S. campaign to throttle Iran’s economy by blockading its oil exports and stopping sanctions evasion is growing increasingly difficult to withstand, three senior Iranian sources said. Washington has in recent weeks ​sought to ratchet up the economic pressure on Tehran, in an effort to extract concessions in any future negotiation that six months of conflict have so far failed to secure: RTRS
  • Israel says it has cleared Hezbollah fighters from tunnels under key Lebanon ridge: RTRS
  • Norway’s sovereign wealth fund proposed reducing the amount of government bonds in its portfolio to boost holdings of riskier debt, with Treasuries the most affected. The proposed reduction in government bonds would imply a decrease of about $58 billion of government bonds, with holdings of US Treasuries projected to drop by $75 billion and those of Japanese government bonds possibly increasing by $20 billion. BBG 
  • US military turns off ad trackers on devices amid Middle East targeting reports: RTRS
  • A rush to unwind yen-funded carry trades helped send the currency to a one-month high against the dollar as traders ramped up bets on further Bank of Japan rate hikes: BBG
  • Australia’s bonds, caught up in the global fixed-income selloff, have seen their yields rise more than any of their peers in the past month, despite arguments that the country’s finances are in much better shape: BBG
  • Some of the world’s biggest money managers have rebuilt their gold holdings after prices dropped, betting that long-term drivers of the precious metal will endure.
  • Fund managers at companies including Amundi SA, Pictet Asset Management Ltd., and Fidelity International Ltd. added to holdings cut earlier this year, during bullion’s retreat from an all-time high: BBG
  • Pimco fund beating 97% of peers cuts ‘Mag Seven’ to bet on Asia: BBG
  • Deadly strike on Iranian wedding was likely a direct hit by a US munition, analysis shows: RTRS
  • Former Labor Secretary Oversaw a ‘Toxic, Intimidating’ Workplace, Report Finds: WSJ
  • The ‘Deeply Nerdy’ Founders Behind Nvidia’s $13 Billion Bet on Hugging Face: WSJ
  • OpenAI agents hijacked German website in previously undisclosed AI breakout: RTRS
  • Volkswagen flags 50,000 job cuts across group as board approves turnaround plan: RTRS
  • Drugmakers Halt Autoimmune Trials After Deaths, Life-Threatening Side Effects: WSJ
  • Trump Administration Again Asks Supreme Court to Allow New Mail Voting Rules: WSJ

A more detailed look at global markets courtesy of Newsquawk

APAC stocks took impetus from the positive global risk sentiment and lower yield environment after Fed’s Waller kept a September rate hold in play and following no major new geopolitical developments, while participants look ahead to the key US jobs data. ASX 200 lagged with price action rangebound as the outperformance in tech and telecoms was overshadowed by weakness in mining, resources, materials, utilities and energy, while a quiet calendar and lack of drivers kept the index in check. Nikkei 225 shrugged off the disappointing Household Spending data from Japan and briefly returned to above the 65,000 level amid lower yields and after a source report noted that the BoJ favours a 25bps rate hike this month and a flexible future pace, which helped ease concerns of a more aggressive move. KOSPI rallied amid strength in tech heavyweights with notable gains in SK Hynix, while Samsung Electronics was also firmer after industry data showed it narrowed the gap with market leader SK Hynix in the global HBM market during Q2. Hang Seng and Shanghai Comp were underpinned with the Hong Kong benchmark spearheading the advances alongside strength in property, tech and auto stocks, while the gains in the mainland were limited after the PBoC continued to drain liquidity with today’s open market operations amount remaining at zero.

Top Asian News

  • Japanese PM Takaichi will keep Finance Minister Katayama, in cabinet reshuffle, according to Mainichi.
  • Japan’s Finance Minister Katayama said interest rate moves are determined by various factors in markets and they will control FY bond issuance properly, while she added that FY27 budget requests total about JPY 143tln and don’t represent a large increase. Katayama said they are closely watching bond markets with a high sense of urgency and noted that there were no specific requests from US Treasury Secretary Bessent. Furthermore, she said Bessent assessed PM Takaichi’s economic policies very highly and has long held a view that the yen has been undervalued, due largely to interest rate differentials.

European bourses start the final trading session of the week on the backfoot, albeit only modestly. Focus will be on the US jobs report, with NFP expected at 58k. Although this data point is key for the Fed, most policymakers will be focused on the inflation print expected in a week’s time. Sectors lack a clear bias. Tech tops the sector pile, with Travel & Leisure and Autos rounding out the sector gainers. To the downside is Media, following Vivendi earnings (see more below), with Chemicals and Banks following behind. The biggest story of the morning came from Volkswagen (+6.2%), after the Co.’s supervisory board approved a plan that would include an additional 50k job cuts.

Top European News

  • UK Energy Secretary could recommend new North Sea drilling as soon as next week, a Rosebank oilfield announcement expected to follow, The Guardian reported citing sources.
  • BoE DMP (Aug): 1-year CPI expectation 3.1% (prev. 3.4%), 3-year CPI expectation 2.8% (prev. 2.8%).
  • European Retail Sales (Jul MM) -0.6% vs. Exp. 0.3% (Prev. 0.2%).
  • German Factory Orders (Jul MM) 2.5% vs. Exp. 0.3% (Prev. 3.1%).
  • Italian Retail Sales (Jul MM) -0.4% vs. Exp. 0.2% (Prev. -0.1%).

FX

  • Mixed action across G10FX where there is no real bias. Stealing leads for no particular reason, JPY lags after large gains this week.
  • Choppy USD action this morning which sees EUR/USD within a narrow 15 pip range and DXY flat into NFP. Some broad based, but modest USD upside was seen after the EU cash open, lifting DXY from 99.00 to a high just below 99.10 with EUR and GBP pairs sent to lows. While NFP is the highlight of the day, officials’ keen eye on inflation will be the deciding factor in the Fed’s September meeting, especially after Waller’s remarks on Thursday.
  • With a 25bps ECB hike next week fully priced, EUR will likely remain at the whim of the Buck into Payrolls. Focus will be on the first of three significant state elections in September, Saxony. Polling has AfD clearly in the lead with 40-43% of the vote; if materialised, will add to the pressure on the German Grand coalition nationally, though not change the power balance or impact economic/fiscal policy. Lane did not add anything, given ECB is in blackout. EUR/USD choppy, but found support at 1.1620.
  • GBP saw some weakness on the DMP which showed easing 1yr inflation expectations, though the reaction was limited to around ten pips and Sterling is still the best G10 performer with BoE’s Bailey not providing commentary on monetary policy. Cable’s 1.3550 will likely provide resistance to further Cable gains absent an NFP surprise. JPY is the underperformer today as it pulls back from recent gains of over 3% vs. the Buck. The pair bottomed at 155.22 and now lies just above 156.00.

Fixed Income

  • Global fixed benchmarks trade with mild gains after initially holding in the red early morning. USTs (+1 tick) trades tentatively heading into US NFP, whilst Bunds (+4 ticks) and Gilts (+6 ticks) post modest gains. Overnight, JGBs (+30 ticks) posted decent gains, tracking the advances made in USTs on Thursday; a couple of decent auctions earlier in the week, and speculation surrounding the GPIF upping its allocation in domestic bonds have also boosted sentiment.
  • USTs currently trade at the upper end of a 107-17 to 107-23+ range, at levels more-or-less similar to the week’s open. Focus this morning has been on an FT article which suggested that Norway’s Sovereign Wealth Fund has proposed cutting government bonds to 50% of its bond portfolio (from 70%). The fund now aims to look at other types of debt to try to boost returns. The piece suggests that its allocation to Gilts would remain unchanged, whilst its position in JGBs would rise by 2.8%. On the flip side, a Reuters report suggested that some Chinese commercial banks have upped their purchases of USTs in recent months.
  • Bunds and Gilts are incrementally firmer this morning. German benchmarks specifically, focus is on the upcoming Saxony-Anhalt state election. The far-right AfD are expected to win, but attention will be on whether it can achieve an absolute majority. This is because other major parties have ruled out forming a coalition with the AfD. Even if the AfD does fall short, the CDU will face the issue of forming a new coalition, potentially leading to political instability and hence reducing confidence in German debt.
  • For UK specifically, focus will be on a speech from BoE Governor Bailey. Elsewhere, the BoE DMP saw the 1-year-ahead expectation fall to 3.1% (prev. 3.4%), spurring mild strength in Gilts.
  • Norway’s sovereign wealth fund sent a letter to the finance ministry recommending the reduction of holdings of US Treasuries from 70% to 50%, according to FT.
  • Some Chinese commercial banks have raised US dollar deposit rates above 3% and subsequently increased purchases of US Treasuries in recent months, according to sources.
  • Australia sells AUD 800mln in 4.75% October 2037 Bonds b/c 3.21x, avg. yield 5.2133.

Commodities

  • WTI Oct and Brent Nov futures are softer intraday amid a lack of notable geopolitical updates overnight to shift the dial. The former resides in a USD 90.38-92.17/bbl range (vs yesterday’s 89.57-93.14/bbl), and the latter in a USD 94.81-96.21/bbl parameter (vs yesterday’s 84.03-97.62/bbl). Over the weekend, the OPEC+ JMMC is scheduled to meet, with market sources suggesting no changes will be made to October’s overall output targets as the committee focuses broadly on market conditions and member compliance.
  • Metals are also trading broadly flat/firmer intraday amid as drivers remain light ahead of the US jobs report. The consensus expects the US economy to have added 58K nonfarm payrolls in August, analysts say that a payrolls print close to expectations alongside a steady unemployment rate would be consistent with a stable labour market that is cooling but not deteriorating sharply, and that should keep policymakers focused on the inflation side of the mandate.
  • Spot gold resides in a narrow USD 4,460-4,491/oz range at the time of writing, within yesterday’s parameter (USD 4,381-4,511/oz) and in between its 200 DMA (USD 4,534/oz) and 100 DMA (USD 4,355/oz). Spot silver is flat just under its 100 DMA (67.52/oz), in a current USD 66.29-67.20/oz range. Base metals are uneventful with 3M LME copper eking mild gains in a narrow USD 14,299.10- 14,392.73/oz.
  • Oil production in Kazakhstan for 2027 is planned at 96mln tonnes, IFX reported citing the budget project.
  • Russia’s Deputy PM Novak said China will account for more than 60% of Russia’s total natural gas exports by 2030.
  • Some Chinese rare earth suppliers have reportedly halted some US shipments over geopolitical worries, Reuters reported.

Trade/Tariffs

  • USTR Greer said Canada wanted more tariff relief and that he’s had a couple of texts and outreach with Canada, but hasn’t had negotiations with Canada since. Greer also stated he met with Mexico’s Trade Minister on Thursday and that Mexico is eager to do things to protect North America from Chinese imports. Furthermore, Greer said the US is looking to reduce its deficit with China and will probably make agriculture announcements during Chinese President Xi’s visit, adding that he is optimistic about the US-China relationship.
  • USTR Greer told the FT that the UK is choosing the EU over the US, which is causing a problem for the UK to expand a trade deal with the US. Greer said the UK had failed to take advantage of Brexit by aligning with EU-made rules and closing its market to American goods and still had “pretty high tariffs”.
  • Brazil warned of reciprocal measures against the EU if talks to lift the meat ban stall.
  • South Korea’s Interior Minister said South Korea and the US are continuing chip tariff talks.

Central Banks

  • BoE’s Bailey said Fed Chair Warsh is “right to see some dangers in forward guidance” and that central bankers should avoid giving unconditional guidance. He added that we do exercise choice on how fast to bring inflation back to target, “but must do so”.
  • RBNZ Assistant Governor Silk said a rate hike in October or December is still open, but stated a hike is more likely in December and that the RBNZ wants to support continuing improvement in the economy.
  • RBNZ MPC member Hansen said Wednesday’s rate hike was a clear consensus decision and that further policy decisions will depend on trends in a wide range of economic datasets, while he is watching for surprises in data, not a single indicator, before deciding what should happen in October.

Geopolitics: Iran

  • US Treasury Secretary Bessent said the EU has joined Operation Economic Outcast and that he appreciates the EU’s strong and early stance on Iran.
  • Oman and Qatar are intensifying efforts to resume Iran-US talks, and that the Strait of Hormuz, sanctions, and the nuclear file are the focus of new disputes, Nour News reported citing diplomatic sources.
  • Direct US-Iran talks have stopped, but mediators are maintaining back channels and trying to build a framework that could bring both sides back to negotiations on a new agreement, FT reported.
  • IRNA reported several explosions were heard in Iraq’s Erbil province.
  • South Korea prepared a plan to deploy non-combat naval assets to the Strait of Hormuz, according to Chosun Daily.

Geopolitics: Ukraine

  • US Special Envoy Witkoff and Kushner is to visit Russia and Ukraine on September 5th-6th, TASS reported citing sources.
  • Ukraine’s next goal is to shut down Russia’s commercial airspace, according to WSJ.
  • Ukrainian Energy Ministry said Russia launched a large-scale missile and drone attack on energy infrastructure in Ukraine’s Odessa region.

Geopolitics: Other 

  • Argentina’s President Milei will sign a decree sanctioning companies working on oil exploration of the Falkland Islands, while he stated that the Falkland’s Sea Lion Project presents a clear danger and plans to build a naval base in Tierra del Fuego.

US Event Calendar

  • 8:30 am: Aug Change in Nonfarm Payrolls, est. 55k, prior -23k
  • 8:30 am: Aug Change in Manufact. Payrolls, est. 5k, prior 5k
  • 8:30 am: Aug Unemployment Rate, est. 4.1%, prior 4.1%

DB’s Jim Reid concludes the overnight wrap

Welcome to the 384th payroll Friday of my career. For the first one I was ordered to get the coffees in for the whole trading floor, keep quiet, and watch the spectacle. Imagine if I asked a graduate to do that today.

Ahead of the big day, the relentless global bond selloff has finally paused over the last 24 hours, with a cross-asset rally driven by dovish comments from Fed Governor Waller. He cast doubt on whether the Fed would hike rates this month, which led to a dovish repricing that led futures to slash the chance of a hike to 51% as of this morning, down from 63% at the close on Wednesday. Moreover, there was also relief on the energy front, as European natural gas prices came down -2.48% yesterday, after rising almost 10% over the previous three days. So collectively, all that pushed back against the hawkish newsflow of recent days. That said, the benefits were much more visible for equities, with the S&P 500 (+1.06%) having its best day in almost a month, than for US long-end bonds, with 10yr Treasury yields a modest -1.1bps lower on the day.

European bonds saw a much bigger yield decline though.  
Those comments from Waller drove the biggest move of the day, as he made several dovish points. For instance, he said that “recent data suggest we are finally seeing some signs of disinflation”, and that if this continued, he would be “inclined to support holding” rates. In addition, he said “my take is that underlying inflation is doing better than the core numbers suggest.” So again, that leant in a dovish direction. Admittedly, Waller said he’d consider a hike “if inflation comes in hot”, but given the rest of his comments were more dovish, market pricing for a September hike fell back to 51% by the close.  

With expectations for a hike in the balance again, that’s heightened the focus on today’s US jobs report, which is out at 13:30 London time. In general, the labour market has been robust in the last few months. But the most recent jobs report for July was much weaker than expected, with payrolls unexpectedly contracting, along with downward revisions to the previous couple of months. So that cast further doubt on a September hike, and it was only thanks to Fed Chair Warsh’s speech at Jackson Hole last week that investors had grown more confident of a September hike once again. For this report, our US economists are expecting nonfarm payrolls to rebound by +65k, with the unemployment rate holding steady at 4.1%. So if realised, that would cement the view that the labour market is holding up and keep the Fed’s focus on inflation.  

Ahead of that report, yesterday’s data generally leant in a more hawkish direction, which acted as a bit of a counterweight to Waller’s comments. Most obviously, the ISM services index for August beat expectations, rising to a 6-month high of 55.4 (vs.  54.1 expected). And digging into the details, the prices paid component moved up to a 4-year high of 72.6 (vs. 70.0 expected), which is notable given that this series is strongly correlated to inflation with a 3-month lag. In the meantime, weekly initial jobless claims were also at just 206k in the week ending August 29 (vs. 205k expected). And the July trade deficit was a bit smaller than expected at $88.6bn (vs. $90.2bn expected).

Despite all that data, the comments from Governor Waller won out when it came to market pricing, though the pull back in Treasury yields did vary across the curve. The decline was most obvious at the front-end, which showed how it was the Fed commentary driving the moves, with the 2yr yield (-3.2bps) falling to 4.34%. By contrast, the rally was more marginal further out, with the 10yr yield (-1.1bps to 4.77%) and the 30yr yield (-1.1bps to 5.25%) actually closing a touch above their levels just before Waller’s comments.  

For US equities, the combination of strong data and dovish commentary offered more decisive support. So the S&P 500 (+1.06%) posted back-to-back gains for the first time in 3 weeks, with the index also back within 1% of its record high from last month. That was led by a very strong performance for the Magnificent 7 (+2.38%), which hit a 3-month high as it posted its best day in the last month. But it was still a broad-based rally, with the S&P 500 seeing the most daily advancers since early August, as more than two-thirds of the index moved higher.  

As all that was going on, bonds and equities received further support from the latest moves in energy prices, with Brent crude (-0.12% to $95.52/bbl) settling lower for the first time in four sessions. But otherwise, the moves under the surface weren’t so bad for other asset classes. Moreover, longer-dated oil futures fell back, meaning that investors were slightly pricing out a prolonged period of high oil prices and the chances of stagflation. The 12-month Brent future fell -1.12% on the day to $76.67/bbl. And natural gas futures also fell back on both sides of the Atlantic, which eased concerns about a wider spike in energy prices this winter. So the European natural gas future fell -2.48% to €71.80/MWh, whilst the US natural gas futures also fell -1.45%.

Those moves in energy prices offered plenty of support to European assets, with yields finally pulling back from their multi-year highs on Wednesday. That happened across the continent, with yields on 10yr bunds (-3.3bps) down to 3.34%, alongside declines for 10yr yields on OATs (-4.8bps), BTPs (-5.0bps) and gilts (-9.6bps). Then for equities we also saw a recovery, with the STOXX 600 (+0.49%) stabilising after 3 consecutive declines, including gains for the DAX (+0.63%), the CAC 40 (+0.07%) and the FTSE 100 (+0.70%).  

Asian equity markets are generally riding the tech train this morning with the Hang Seng (+2.12%), KOSPI (+1.88%) and the Nikkei (+1.30%) all strong. Elsewhere, mainland Chinese markets are posting more modest gains, with the CSI 300 up +0.43% and the Shanghai Composite advancing +0.35%. In contrast, Australia’s S&P/ASX 200 (-0.21%) is bucking the regional trend. US and European equity futures are all up less than a tenth of a percent.  

Meanwhile, data released earlier this morning showed that Japanese household spending contracted in July at the fastest annual pace in two and a half years, underscoring weak private consumption ahead of the BoJ policy meeting two weeks from today. Consumer spending fell -3.6% year-on-year, significantly worse than the market expectation of a -1.6% decline, marking the eighth consecutive month of contraction. The drop was the steepest since January 2024, when household spending declined by -6.3% year-on-year.

That has helped see a small decline for the yen this morning (-0.36%) following on from a huge jump yesterday, as it strengthened +1.86% against the US dollar. Thats a four big figure move in 48 hours now. To be fair, a small part of that was dollar weakness after Fed Governor Waller’s remarks. But that was only part of it, as the yen was also up +1.55% against the euro as well. The moves came amidst mounting speculation that the Bank of Japan would take further action in two weeks. However speculation that they would supersize the hike faded as Bloomberg reported yesterday they were leaning towards a 25bp rate hike this month and would leave open the possibility of a faster pace of hikes afterwards. Their next meeting is just a couple of days after the Fed’s decision. So that’ll be a big couple of days for markets mid-month.  

Looking at the day ahead, the main highlight will be the US jobs report for August. Other data releases include German factory orders and Euro Area retail sales for July. Otherwise, central bank speakers include BoE Governor Bailey and the ECB’s Lane.


Tyler Durden
Fri, 09/04/2026 – 08:25

Spain Gasses Its Own People; Police Probe Migrant/Soros NGO Acid Buys In Ceuta

0
Spain Gasses Its Own People; Police Probe Migrant/Soros NGO Acid Buys In Ceuta

Authored by Steve Watson via Modernity News,

Spanish National Police have been examining a bulk purchase of hydrochloric acid and aluminium foil in Ceuta after supermarket staff flagged a large group of migrants, reported as mostly Moroccan, buying the two products together.

Spanish outlets citing police sources identified activists from the NGO No Name Kitchen as accompanying those buyers.

Investigators have been trying to establish whether the materials were meant for homemade “acid bombs” – plastic bottles packed with acid and foil that produce a small blast, gas and corrosive spray – and whether anyone helped hide what was bought.

The devices match the bottles of corrosive liquid already thrown at Spanish soldiers and at local protesters in the days around the shop run.

The chemistry is crude and already in the open record. Police sources, describe aguafuerte – hydrochloric acid, also sold as salfumán – plus aluminium foil, sometimes with acetone, going into plastic bottles.

Thrown, the mix over-pressurises, pops and throws irritant gas and corrosive liquid. That is the device Spanish media say has been used against army patrols and against residents marching through Villajovita.

No Name Kitchen denies any role. Its coordinator, Ric Fernández, says the group packs 1,200 to 1,300 hot meals a day, buys foil for food and kitchen lining, and uses small amounts of solvent for cleaning, not “industrial quantities” for weapons.

Identified activists were not arrested because the products are legal to buy.

Interior officials, speaking to RTVE, have also denied that police or the Civil Guard are investigating “any NGO” for supplying explosive materials. That official line sits next to days of Spanish crime reporting in which officers are described identifying NNK members after the purchase.

Spanish Prime Minister Pedro Sánchez’s government has repeatedly insisted Ceuta is back under control. Foreign Minister José Manuel Albares has said “practically the entirety of those who entered Ceuta have already returned to Morocco.” Video from the enclave a month later shows tents, wrecked beaches and a city that looks like an earthquake has hit it.

No Name Kitchen, which campaigns against European border enforcement, was already in trouble before this. On 23 August two of its activists, a Canadian and a German, were detained at Benítez beach. Interior Minister Fernando Grande-Marlaska said they had encouraged “violent groups” – illegal migrants – to respond aggressively to police and had resisted officers.

The NGO says the pair were filming. El Faro de Ceuta separately reported a French activist detained in the same neighbourhood after clashing with police. Viral clips accused volunteers of handing out pepper spray. Fernández told Newtral that was a “hoax to discredit us” and that the group has never bought pepper spray or “any device that could incite violence.”

Conservative Spanish media and accounts across X pointed to DevelopmentAid listings that name George Soros’ Open Society Foundations among No Name Kitchen’s funding agencies, and to the group’s old place inside Border Violence Monitoring Network, which has taken OSF money.

NNK says it does not take direct Open Society money for Ceuta and that any OSF link ran through an older network.

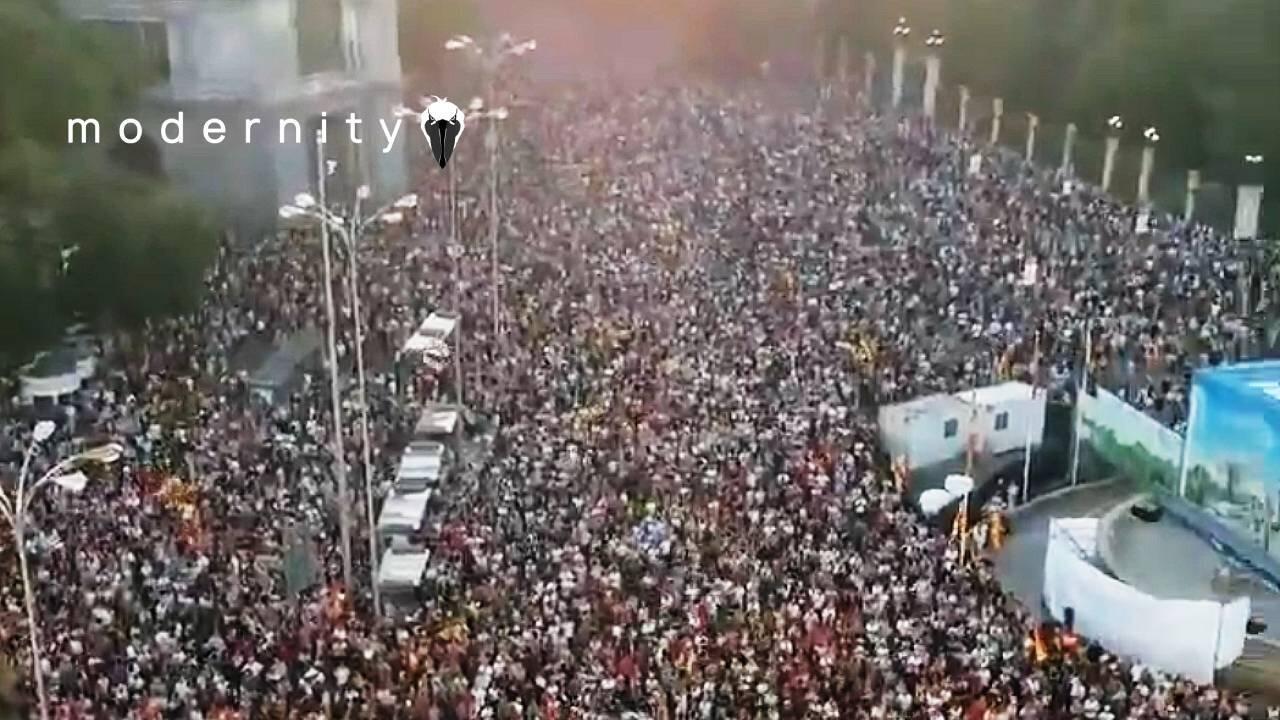
Meanwhile, native Spaniards continue to rise up in revolt against the government’s facilitation of mass migration.

On Wednesday, protests were recorded in more than 200 towns and citie. In Ceuta itself around 20,000 marched. They chanted “Ceuta is not for sale, Ceuta must be defended” and “expel the invaders.” Placards read “SOS. Europe, save us from our traitor government.” Outside Congress later that night the line was shorter still: “It’s not immigration, it’s invasion.”

Maria Sánchez, a 47-year-old housewife, told AFP in Ceuta: “We are Spanish, we don’t want any government to abandon us again like they’ve abandoned us.”

David Hernández, a 45-year-old teacher, told Reuters: “The response has been inadequate, late and, to top it all, has involved a complete dereliction of duty on the part of the government. We cannot be second-class citizens, and our border must not be sidelined.”

Another resident, who gave only the name Lola, said the situation was “spiralling out of control” and that “there’s a point where this will become a powder keg.”

In Madrid, an eatimated150,000 matched through the streets chanting “Sánchez to prison” and “Invaders – go home.”

PP leader Alberto Núñez Feijóo stood in that crowd and said: “A Spanish city has been invaded, occupied and, unfortunately, this happened with the knowledge of the Government of Spain.” He and Vox leader Santiago Abascal both accused Sánchez of lying to Spaniards and of being a “traitor to Spain” and a “lackey of Morocco.”

Madrid mayor José Luis Martínez-Almeida said: “Ceuta is Spanish and will not be abandoned.” Regional president Isabel Díaz Ayuso said the government had “done nothing but lie since they arrived” and that “they have abandoned us, not only the people of Ceuta, but the whole of Spain before the eyes of the world.”

As a section of the protesters continued to march toward Congress, police reportedly fired rubber bullets and tear gas.

The state that could not keep 70,000 people from pouring into a Spanish city unimpeded found the resources to gas citizens who object.

Thursday, Sánchez went to Congress to insist the executive “has nothing to hide.” Claiming that it is “absurd to think that the government knew and did nothing.” He claimed more than 90 percent of arrivals were returned within 72 hours – “one of the fastest return processes in European history” – and blamed social-media rumours plus a misread Supreme Court ruling that stopped immediate sea pushbacks.

He again said he had no indication Morocco organised the surge. Ceuta and Melilla, he added, will remain Spanish “until the end of time.”

The Council of Ministers has now waved through a €309 million emergency package – housing, services, extra police – about 16 percent of Ceuta’s output for the rest of the year.

Critics charge that tent camps for 1,500 adults do not house 5,000 to 10,000 people who have already learned that staying in place works. Asylum claims, minor-protection rules and “ordinary return procedure” are how a surge becomes a settlement.

A government that treats border defence as a branding exercise, then gasses the public for noticing and objecting, is asking for more unrest and more chaos.

Your support is crucial in helping us defeat mass censorship. Please consider donating via Locals or check out our unique merch. Follow us on X @ModernityNews.

Tyler Durden
Fri, 09/04/2026 – 08:05

GE Vernova Finds Its Footing In Sweden With Studsvik After Loss To Rolls Royce

0
GE Vernova Finds Its Footing In Sweden With Studsvik After Loss To Rolls Royce

Swedish nuclear life-cycle services company, Studsvik AB, announced an agreement with GE Vernova Hitachi (GVH) and Samsung C&T for 1.2 GW of new nuclear energy in Sweden.

Project developer Studsvik selected the GVH boiling water reactor design, the BWRX-300, to be constructed by Samsung C&T. The consortium is targeting first-unit operation in the mid-2030s.

The project location is still undetermined. It’ll be developed at either Studsvik’s existing licensed nuclear site in Nyköping, or Målma in Valdemarsvik.

This latest project for GE Vernova comes shortly after they lost in a competition with Rolls-Royce to construct reactors for Swedish state-owned utility Vattenfall. But, GE Vernova has been working with Studsvik’s wholly-owned reactor development subsidiary for several years, making this less of a surprise and more of a confirmation of previous expectations.

The new project for GE Vernova is notable though for being one less reactor than they were competing against Rolls-Royce for earlier this year. The project to be developed at Nyköping or Målma will be for four BWRX300s instead of the potential five they would have built at the Värö Peninsula.

The reactor developer Studsvik is probably new to most of our readers, as the company only sees meaningful volume on its home exchange in Stockholm. The company has been in the nuclear industry for over 75 years, with services over a range of engineering-related business segments, to include fuel modeling software used across the commercial US nuclear fleet.

The company only recently entered the reactor development space after they acquired Kärnfull Next earlier this year, leading to their relationship with GVH and Samsung.

With the market cap under $200 million and revenue coming in under $100 million in 2025, the company has gone relatively unnoticed over the recent year. We covered them earlier this year when they acquired KNXT, but investors are still largely uninterested in one of the few plays on the Swedish nuclear renaissance story.

After jumping almost 200% from mid-2025 to the beginning of 2026, the stock has pulled back with the rest of the global nuclear and AI trade.
 

Tyler Durden
Fri, 09/04/2026 – 07:45

The Rising Cost Of Electricity In The United States

0
The Rising Cost Of Electricity In The United States

Across the U.S., Americans are paying roughly 30% more for electricity than in 2020.

This graphic, via Visual Capitalist’s Cody Good in partnership with the National Public Utilities Council, uses data from the U.S. Energy Information Administration to show the change in average retail electricity prices by state across all sectors from 2020 to 2025.

Where Electricity Prices Rose the Most

Washington, DC saw the largest increase in the country, with average retail electricity prices rising 72% between 2020 and 2025. Maine followed closely at 67%, while Maryland and California rose 52% and 50%, respectively.

State Abbreviation State Change in Electricity Price, All Sectors 2020-2025 (%)
DC Washington, D.C. 72
ME Maine 67
MD Maryland 52
CA California 50
RI Rhode Island 47
PA Pennsylvania 46
NY New York 45
MA Massachusetts 44
IL Illinois 43
CT Connecticut 39
DE Delaware 38
NJ New Jersey 35
NH New Hampshire 31
FL Florida 30
HI Hawaii 28
LA Louisiana 27
AL Alabama 26
MS Mississippi 26
NV Nevada 26
AR Arkansas 25
VA Virginia 25
WV West Virginia 25
IN Indiana 24
MI Michigan 24
AZ Arizona 23
WA Washington 23
OH Ohio 22
TN Tennessee 22
VT Vermont 22
CO Colorado 21
UT Utah 21
WI Wisconsin 21
ID Idaho 19
MO Missouri 19
MN Minnesota 18
NC North Carolina 18
OR Oregon 17
OK Oklahoma 16
KS Kentucky 15
AK Alaska 14
GA Georgia 14
TX Texas 14
MT Montana 13
SD South Dakota 13
IA Iowa 11
KS Kansas 9
NM New Mexico 9
SC South Carolina 7
NE Nebraska -1
WY Wyoming -1
ND North Dakota -18

Source: U.S. Energy Information Administration

Data shows percent growth in average retail electricity prices across all sectors from 2020 to 2025.

Many of the largest increases were concentrated in coastal and Northeastern markets, where retail electricity prices have climbed sharply since 2020.

The U.S. Interior Tells a Different Story

While most states saw higher electricity prices, a few moved in the opposite direction. North Dakota had the largest decrease, with average retail electricity prices falling 18% from 2020 to 2025.

Nebraska and Wyoming also posted slight declines, each falling 1%.

This contrast shows how electricity costs can vary widely across the country depending on regional generation mixes, fuel costs, grid needs, regulations, and local market conditions.

The Bigger Impact of Rising Electricity Costs

Electricity prices rose across most of the U.S. from 2020 to 2025, but the increases were uneven. This matters because electricity is a core cost for households, businesses, and local economies.

As demand grows from data centers, electrification, and grid upgrades, affordability will remain a key challenge across the U.S.

For questions about the rising cost of electricity, contact the National Public Utilities Council.

Tyler Durden
Fri, 09/04/2026 – 06:55