87.7 F
Chicago
Monday, October 12, 2026
Home Blog Page 1160

​​​​​​​Trump Set To Approve TikTok Deal; Oracle Will Gain Algorithm Control Amid CEO Shakeup

0
​​​​​​​Trump Set To Approve TikTok Deal; Oracle Will Gain Algorithm Control Amid CEO Shakeup

Update (1035 ET):

President Trump is preparing to sign an executive order this week that will approve the sale of TikTok’s U.S. operations to an investor consortium, including Oracle, Silver Lake, and Andreessen Horowitz, according to Bloomberg, citing a White House official. 

Key points from the call:

  • The order will formally declare that the deal meets U.S. national security requirements.

  • Trump will also extend the existing TikTok pause by 20 days.

  • The transaction is expected to close within 120 days of signing.

Earlier:

  • Oracle will retrain the TikTok algorithm and safeguard U.S. user data. 

  • Six of the seven board seats in the new U.S. entity will be held by Americans.

  • Oracle reshuffled leadership Monday, naming Clay Magouyrk and Mike Sicilia as co-CEOs, replacing Safra Catz, with no explanation or link to the TikTok deal.

*   *   * 


TikTok’s parent company, ByteDance, will create a duplicate algorithm and lease it to a new U.S. entity controlled by an investor consortium including Oracle, Silver Lake, and Andreessen Horowitz, Bloomberg reported, citing a White House official. Oracle will retrain the algorithm and safeguard U.S. user data. In addition, six of the seven board seats in the new entity will be held by Americans, as the structure for U.S. control of TikTok takes shape.

The arrangement, outlined by a White House official in a statement on Monday, ensures that Oracle will retrain and operate the algorithm “from the ground up.” At the same time, ByteDance will have no access to U.S. user data or influence on the algorithm.

“Oracle, the U.S. security partner, will operate, retrain, and continuously monitor the U.S. algorithm to ensure content is free from improper manipulation or surveillance,” according to a Q&A accompanying the White House official’s comments.

President Trump is set to sign an executive order this week to formalize his approval of the transaction. He expressed confidence in all parties last week, saying, “I had a great call with President Xi, and as you know, I approved the TikTok deal, and we’re in the process. We look forward to getting that deal closed.” His remarks came shortly after a call with Chinese President Xi Jinping on Friday.

The current plan wouldn’t require users to re-download the app, which would continue to work with TikTok outside the country.  

On Saturday, White House Press Secretary Karoline Leavitt told Fox News that Americans would hold six of the seven board seats for TikTok (read report) and, more importantly, that the app’s insanely addictive algorithm would be US-controlled. She noted that the deal would be signed in the coming days.

The American board members will be lined with those who have national security and cybersecurity credentials, while the remaining board member, appointed by current owner ByteDance, will be excluded from the security committee, according to a senior White House official.  

“So all of those details have already been agreed upon, now we just need this deal to be signed and that will be happening, I anticipate, in the coming days,” Leavitt said. 

On Sunday, Trump told the hosts of Fox News’ “The Sunday Briefing” that Fox Chairman Lachlan Murdoch and his father Rupert will likely be involved in the U.S. TikTok deal.

In a separate report from The Wall Street Journal, Rupert Murdoch told executives working on the TikTok deal that he wanted to own a small stake in the U.S.-based company.

Nearly a week ago, it was revealed that Oracle, Silver Lake, and Andreessen Horowitz will control the U.S. entity and app used by 170 million Americans. Some national security experts have warned that TikTok is highly addictive and represents another domain of hybrid warfare by China. 

Furthermore, Oracle announced a leadership shakeup on Monday morning, promoting Clay Magouyrk and Mike Sicilia to CEO roles, replacing Safra Catz. The move splits leadership. There was no explanation as to why Catz was pushed aside, or whether it was related to the upcoming TikTok deal.

Tyler Durden
Mon, 09/22/2025 – 10:35

Argentine Assets Soar As Bessent Offers Milei A Lifeline

0
Argentine Assets Soar As Bessent Offers Milei A Lifeline

Following President Javier Milei’s comments on Friday that the market was in “panic mode“, US Treasury Secretary Scott Bessent has said “all options” are on the table for the Trump administration to support Argentina through this bout of severe market volatility.

The country has already spent more than $1 billion to defend the peso out of its scarce international reserves.

The two countries are in talks this week – Milei and US President Donald Trump will meet Tuesday – and Treasury Secretary Scott Bessent posted on social media earlier that the US is ready to do whatever it takes to support Argentina.

That includes direct currency purchases as well as swap lines and purchases of dollar-denominated government debt.

Bessent called the South American country “a systemically important US ally in Latin America,” adding that the US Treasury “stands ready to do what is needed within its mandate to support Argentina. All options for stabilization are on the table.”

He said that options for a support package “may include, but are not limited to, swap lines, direct currency purchases, and purchases of US dollar-denominated government debt from Treasury’s Exchange Stabilization Fund”.

The comments sent Argentine stocks soaring…

…and the peso ripped…

Argentina’s dollar bonds due in 2029 and 2035 rallied by 5 to 6 cents in the dollar to 70 and 53 cents respectively after Bessent’s comments.

As Bloomberg reports, it’s not impossible he can recover from here, especially with the support of the US and International Monetary Fund, but the key test will be next month’s midterm elections.

The possibility of a defeat for his cost-cutting government in October is what has spooked the market. Argentina’s friends can help it prop up the currency, but they can’t help Milei keep the support of voters.


Tyler Durden
Mon, 09/22/2025 – 10:01

Key Events This Week: Core PCE, GDP And Fed Speakers Galore Including Powell

0
Key Events This Week: Core PCE, GDP And Fed Speakers Galore Including Powell

It’s a relatively quiet week. According to DB’s Henry Allen, the data highlight this week will be Friday’s US core PCE deflator which should print softer than feared a few weeks ago given the recent inputs from other inflation releases. The main events outside of this will be a series of Fed speakers (at least 16 this week, with 4 on deck today) who can give their own spin on a complicated FOMC last week where the dots were a little all over the place. The global flash PMIs tomorrow will be the other main highlight but its not likely to be a major mover with most main economies seemingly fairly stable at the moment.

Friday’s personal income (+0.3% est. vs. +0.4% last) and consumption (+0.5% vs. +0.5%) data will include the all-important core PCE deflator which DB expects to come in at a relatively tame +0.22% vs. +0.27% last time. Thursday sees the final print on Q2 GDP (3.3% final vs. 3.3% prelim) and will also feature the annual update to the national accounts in which the BEA incorporates more complete and detailed source data covering the prior five years, allowing for revisions. So, another chance for history to be rewritten. Other notable US releases will include tomorrow’s existing home sales; Wednesday’s new home sales; Thursday’s durable goods orders, and the advanced trade balance; and Friday’s University of Michigan consumer sentiment index.

In terms of those Fed speakers this week, we’ll highlight the current voters. Today kicks off with Williams who should mirror the views of Powell last week. Musalem will also give an outlook speech later and new Governor Miran will be on the tapes with his thoughts likely to be fascinating to hear. Tomorrow, Chair Powell will give an outlook speech which will likely be similar to his FOMC rhetoric. Governor Bowman will also speak. Thursday sees Goolsbee, Williams, Governors Bowman and Barr, and Daly who votes next year. Governor Bowman also speaks on Friday. As DB’s economists point out, the Supreme Court has asked Governor Cook to respond by Thursday to President Trump’s appeal, which seeks to overturn lower court rulings preventing her immediate removal from office.

Trump will likely be in the news earlier in the week as he addresses the 80th UN General Assembly in New York tomorrow. We’ll also get a better idea of where we are with US exceptionalism on Friday with the Ryder Cup starting in New York. It will also be interesting to see the reaction from corporate America to Trump’s weekend plans to impose a $100,000 application fee for the widely used H-1B visa for foreign workers in speciality occupations. It’s caused a huge amount of uncertainty over the weekend for those that rely on it.

Outside of the US, Sweden (tomorrow) and Switzerland (Thursday) central banks are meeting with markets pricing in a 30% chance of a cut from the Riksbank, but with only a 4% chance for the SNB. A cut for the Swiss would lead the country back into negative rate territory if it did happen. Staying in Europe, sentiment gauges out include the Ifo survey in Germany on Wednesday as well as consumer confidence across major European economies, including Germany and France on Thursday.

Elsewhere, rounding out notable data releases, highlights include the Tokyo CPI for September in Japan and the July GDP report in Canada both on Friday, as well as the August CPI in Australia on Wednesday. For the Tokyo CPI, economists see an acceleration in core inflation ex. fresh food to 2.8% YoY (2.5% in August) and a slowdown in core-core inflation ex. fresh food and energy to 2.9% (3.0%).

Below is the day-by-day calendar for the full week ahead, courtesy of DB.

Monday September 22

  • Data: US August Chicago Fed national activity index, Eurozone September consumer confidence, Canada August industrial product price index, raw materials price index
  • Central banks: Fed’s Williams, Musalem, Hammack, Miran and Barkin speak, ECB’s Lane and Nagel speak, BoE’s Bailey and Pill speak, China 1-yr and 5-yr loan prime rates

Tuesday September 23

  • Data: US, UK, Germany, France and the Eurozone September PMIs, US September Philadelphia Fed non-manufacturing activity, Richmond Fed manufacturing index, business conditions, Q2 current account balance
  • Central banks: Fed’s Powell, Bowman and Bostic speak, ECB’s Muller, Kocher and Cipollone speak, BoE’s Pill speaks, Riksbank decision
  • Earnings: Micron
  • Auctions: US 2-year Notes ($69bn)

Wednesday September 24

  • Data: US August new home sales, Japan September PMIs, Germany September Ifo survey, Australia August CPI 
  • Central banks: Fed’s Daly speaks, BoE’s Greene speaks
  • Auctions: US 2-year FRN (reopening, $28bn), 5-year Notes ($70bn)

Thursday September 25

  • Data: US August durable goods orders, advance goods trade balance, wholesale inventories, existing home sales, September Kansas City Fed manufacturing activity, initial jobless claims, Japan August PPI services, Germany October GfK consumer confidence, France September consumer confidence, EU27 August new car registrations, Eurozone August M3
  • Central banks: Fed’s Goolsbee, Williams, Bowman, Barr, Logan and Daly speak, ECB’s economic bulletin, BoJ’s minutes of the July meeting, SNB decision
  • Earnings: Costco, Accenture 
  • Auctions: US 7-year Notes ($44bn)

Friday September 26

  • Data: US August PCE, personal income and spending, September Kansas City Fed services activity, Japan September Tokyo CPI, Italy September consumer confidence index, economic sentiment, manufacturing confidence, Canada July GDP 
  • Central banks: Fed’s Barkin and Bowman speak, ECB’s August consumer expectations survey

Finally, looking at just the US, the key economic data releases this week are the durable goods report on Thursday and core PCE inflation on Friday. There are several speaking engagements by Fed officials this week, including events with Fed Chair Powell on Tuesday and New York Fed President Williams on Monday

Monday, September 22 

  • There are no major economic data releases scheduled. 
  • 09:45 AM New York Fed President Williams (FOMC voter) speaks: New York Fed President John Williams will participate in a panel discussion on monetary policy frameworks organized by the European Money and Finance Forum. Q&A is expected. On September 4, Williams said, “The Federal Reserve’s monetary policy stance has been modestly restrictive…, [and] this policy stance is appropriate given that inflation has remained above our 2 percent target while the labor market has been generally consistent with maximum employment.”
  • 10:00 AM St. Louis Fed President Musalem (FOMC voter) speaks: St. Louis Fed President Alberto Musalem will give remarks on the outlook for the US economy and monetary policy at an event hosted by Brookings Institution’s Hutchins Center on Fiscal and Monetary Policy. Following his remarks, he will be interviewed by David Wessel, director of the Hutchins Center. Q&A is expected. On September 3, Musalem said, “Recent data have further increased my perception of downside risks to the labor market…, [and] looking ahead, I expect the labor market to gradually cool and remain near full employment with risks tilted to the downside.”
  • 12:00 PM Cleveland Fed President Hammack (FOMC non-voter) speaks: Cleveland Fed President Beth Hammack will host an event at the Cleveland Fed headquarters to discuss the functions of Federal Reserve Banks, the state of the economy, and ways Reserve Banks engage with the public. The event will be livestreamed. On August 22, Hammack said, “We are only very modestly restrictive, [and] we are at a very small distance to getting to a neutral rate.” She also noted, “We need to be cautious about removing that restriction.”
  • 12:00 PM Richmond Fed President Barkin (FOMC non-voter) speaks: Richmond Fed President Tom Barkin will speak on the economy at the Howard County Chamber of Commerce in Maryland. Q&A is expected. On August 12, Barkin said, “Job gains have slowed recently, which is certainly worth watching. But I’m hopeful that even as businesses face cost and price pressure, they’ll largely avoid the type of large layoffs that would spike unemployment.”
  • 12:00 PM Fed Governor Miran speaks: Fed Governor Stephen Miran will speak at a webinar hosted by the Economic Club of New York. Q&A is expected. On September 19, Miran said, “In my opinion, being so far above neutral means monetary policy is quite restrictive, and the longer it provides that level of restriction with the labor market having done what it did last year and the first half of this year, the greater the risks that we start to miss on the employment side of the mandate.”

Tuesday, September 23 

  • 09:00 AM Fed Vice Chair for Supervision Bowman speaks: Fed Vice Chair for Supervision Michelle Bowman will speak at the 134th Annual Kentucky Bankers Association Convention on the economic outlook. Speech text and Q&A are expected. On August 4, Bowman said, “I believe that beginning to move our policy rate at a gradual pace toward its neutral level will help maintain the labor market near full employment and ensure smooth progress toward achieving our dual mandate.” She also noted, “My Summary of Economic Projections includes three cuts for this year, which has been consistent with my forecast since last December, and the latest labor market data reinforce my view.”
  • 09:45 AM S&P Global US manufacturing PMI, September preliminary (consensus 51.7, last 53.0) 
  • 09:45 AM S&P Global US services PMI, September preliminary (consensus 53.9, last 54.5) 
  • 10:00 AM Atlanta Fed President Bostic (FOMC non-voter) speaks: Atlanta Fed President Raphael Bostic will speak on the economic outlook on a Macro Musings podcast live recording. Q&A is expected. On September 3, Bostic said, “I continue to believe that the effects of tariffs on consumer prices won’t fade fast, and in fact will not fully materialize for some months.” He also noted, “These [inflation] numbers give me pause, [and] I will not be complacent and simply assume expectations will remain anchored and another inflation outbreak won’t happen.”
  • 12:35 PM Fed Chair Powell speaks: Fed Chair Jerome Powell will speak on the economic outlook at the Greater Providence Chamber of Commerce Crowne Plaza Hotel in Rhode Island. Speech text and Q&A are expected. During the FOMC press conference on Wednesday, Powell said, “We see that the labor market is softening and we don’t need it to soften anymore, and we don’t want it to.” Powell characterized the policy decision at the September FOMC meeting as “a risk management cut” in response to downside risks in the labor market.

Wednesday, September 24 

  • 10:00 AM New home sales, August (GS -1.5%, consensus -0.3%, last -0.6%) 
  • 04:10 PM San Francisco Fed President Daly (FOMC non-voter) speaks: San Francisco Fed President Mary Daly will deliver keynote remarks on the outlook for the economy at the annual Spencer Fox Eccles Convocation at the University of Utah’s School of Business. After her remarks, she will join Kurt Dirks, Dean of the David Eccles School of Business, for a conversation. Speech text and Q&A are expected. On August 29, Daly said, “It will soon be time to recalibrate policy to better match our economy.” She also noted, “I think tariff-related price increases will be a one-off, [and] it will take time before we know that for certain, but we can’t wait for perfect certainty without risking harm to the market.”

Thursday, September 25 

  • 08:20 AM Chicago Fed President Goolsbee (FOMC voter) speaks: Chicago Fed President Austan Goolsbee will speak in a moderated discussion at Crain’s Power Breakfast about the Fed and the economy, focusing on trends for West Michigan. On September 5, Goolsbee said, “[Concerning] this slowdown in aggregate jobs numbers, we have to be extremely careful taking that as an indicator of the business cycle when things like immigration, labor supply, and labor force participation are moving behind the scenes.” He also noted, “We put a note of unease in the [July] CPI and PPI reports, with inflation kicking up in categories that are not obviously going to be transitory, which is to say services inflation.”
  • 08:30 AM Advance goods trade balance, August (GS -$92.0bn, consensus -$96.0bn, last -$102.8bn) : We forecast that goods trade balance narrowed from -$102.8bn to -$92.0bn in August, reflecting declines in gold imports and imports from Southeast Asian countries.
  • 08:30 AM Wholesale inventories, August preliminary (consensus +0.1%, last +0.1%)
  • 08:30 AM GDP, Q2 third release (GS +3.4%, consensus +3.3%, last +3.3%); Personal consumption, Q2 third release (GS +1.9%, consensus +1.9%, last +1.6%): We estimate a 0.1pp upward revision to Q2 GDP growth to +3.4% (quarter-over-quarter annualized), reflecting upward revisions to consumer spending (+0.3pp to +1.9%), business fixed investment, and net exports. The third release of Q2 GDP will coincide with the 2025 annual update to the National Economic Accounts, which incorporates source data that are more complete than those previously available and methodological changes.
  • 08:30 AM Durable goods orders, August preliminary (GS -1.5%, consensus -0.3%, last -2.8%); Durable goods orders ex-transportation, August preliminary (GS flat, consensus -0.2%, last +1.0%); Core capital goods orders, August preliminary (GS flat, consensus -0.1%, last +1.1%); Core capital goods shipments, August preliminary (GS +0.3%, consensus +0.2%, last +0.7%): We estimate that durable goods orders declined 1.5% in the preliminary August report (month-over-month, seasonally adjusted), reflecting a decline in commercial aircraft orders. We forecast unchanged core capital goods orders—reflecting an improvement in the new orders components of manufacturing surveys in August but potential payback for the outsized increase in the prior month—and a 0.3% increase in core capital goods shipments—reflecting the increase in orders in the prior month.
  • 08:30 AM Initial jobless claims, week ended September 20 (GS 230k, consensus 235k, last 231k); Continuing jobless claims, week ended September 13 (consensus 1,938k, last 1,920k)
  • 09:00 AM New York Fed President Williams (FOMC voter) speaks: New York Fed President John Williams will give welcoming remarks at the New York Fed’s Fourth Annual International Roles of the US Dollar Conference.
  • 09:00 AM Kansas City Fed President Schmid (FOMC voter) speaks: Kansas City Fed President Jeff Schmid will speak about monetary policy and the economic and banking outlook at the Mid-Sized Bank Coalition of America in Dallas. On August 21, Schmid said, “I think we are in a good place [with policy] and we have to be careful with what lowering short-term rates would do to the inflation mentality if inflation is running closer to 3% than to 2%.” He also noted, “While it is true that payroll growth was weak over the summer, a broader set of indicators suggest a labor market that is in balance.”
  • 10:00 AM Existing home sales, August (GS -2.5%, consensus -1.3%, last +2.0%)
  • 10:00 AM Fed Vice Chair for Supervision Bowman speaks: Fed Vice Chair for Supervision Michelle Bowman will participate in a moderated discussion at the 2025 Financial Markets Quality Conference hosted by the Psaros Center for Financial Markets and Policy at Georgetown University. Q&A is expected.
  • 01:00 PM Fed Governor Barr speaks: Fed Governor Michael Barr will speak at the Peterson Institute for International Economics on bank stress testing and potential reforms. Q&A is expected.
  • 01:40 PM Dallas Fed President Logan (FOMC non-voter) speaks: Dallas Fed President Lorie Logan will speak at a panel organized by the Federal Reserve Bank of Richmond. Q&A is expected.
  • 03:30 PM San Francisco Fed Daly (FOMC non-voter) speaks: San Francisco Fed Mary Daly will sit down with Mark Packard, President and CEO of the Central Bank of Utah, for a conservation on her economic outlook at the San Francisco Fed’s 2025 Western Bankers Forum. Q&A is expected.

Friday, September 26 

  • 08:30 AM Personal income, August (GS +0.4%, consensus +0.3%, last +0.4%); Personal spending, August (GS +0.4%, consensus +0.5%, last +0.5%); Core PCE price index, August (GS +0.21%, consensus +0.2%, last +0.3%); Core PCE price index (YoY), August (GS +2.92%, consensus +2.9%, last +2.9%); PCE price index, August (GS +0.25%, consensus +0.3%, last +0.2%); PCE price index (YoY), August (GS +2.72%, consensus +2.7%, last +2.6%): We estimate that both personal income and personal spending increased by 0.4% in August. We estimate that the core PCE price index rose 0.21% in August, corresponding to a year-over-year rate of +2.92%. Additionally, we expect that the headline PCE price index increased 0.25% in August, or increased 2.72% from a year earlier.
  • 09:00 PM Richmond Fed President Barkin (FOMC non-voter) speaks: Richmond Fed President Tom Barkin will participate in a fireside chat to discuss the US economic outlook. Q&A is expected.
  • 10:00 AM University of Michigan consumer sentiment, September final (GS 55.0, consensus 55.4, last 55.4): University of Michigan 5-10-year inflation expectations, September final (GS 3.8%, last 3.9%)
  • 01:00 PM Fed Vice Chair for Supervision Bowman speaks: Fed Vice Chair for Supervision Michelle Bowman will give a speech on the approach to monetary policy decision-making at the Cornell Club of New York. Q&A is expected.

Source: DB, Goldman

Tyler Durden
Mon, 09/22/2025 – 09:52

Agent Payments Are About To Revolutionize Global Financial Infrastructure

0
Agent Payments Are About To Revolutionize Global Financial Infrastructure

By Eric Peters, CIO of One River Asset Management

TL;DR:

When Coinbase acquired One River Digital nearly three years ago, I had to learn a new language. Pretty much every internal memo I received started with TL;DR which meant nothing to me. I would’ve asked ChatGPT but it didn’t yet exist. Google said it meant “too long; didn’t read”, which also made little sense. I guess it’s some kind of slang that precedes a short paragraph that summarizes a longer article you probably won’t read. I had to learn all sorts of other new things at Coinbase, some annoying, others eye-opening, fascinating, exhilarating. 

If you think you can make a lot of money without learning all sorts of new and perplexing things,here’s a helpful TL;DR: Think again. So, here’s an example of the kind of TL;DR that comes across my feed and gets me super excited. This from the Coinbase blog on Sept 16th. TL;DR: Agents can already talk to each other. And now, with x402 within Google’s new AP2, they can pay each other too. Stablecoins make this possible at the speed of code, unlocking micropayments and new models of automation that legacy rails simply can’t support.

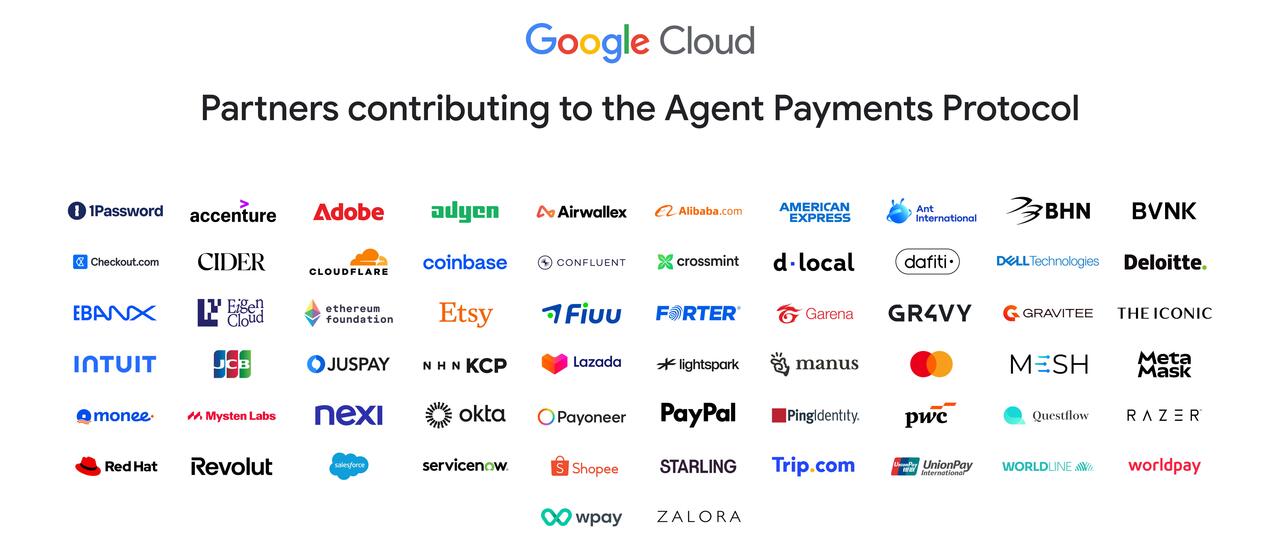
25-year-old Coinbase engineers with IQ’s one order of magnitude higher than mine read that TL;DR and read no further. I need to dig deeper [read here]. I ask Grok to teach me all about the meaning of x402,its origin,and Google’s AP2. Each question leads to another. Eventually I wrap my head around it. So, here’s my TL;DR: Coinbase, Google and numerous others have teamed up to build payment rails that allow Autonomous AI Agents (Agents) to instantly transact at vast scale, without the need for banks, using stablecoins on blockchain rails. 

It doesn’t take a wild imagination to picture a world where AI Agents are acting on our behalf in ways that simplify our daily lives, and make the economy far more productive, efficient, prosperous. The scale of what is coming is far beyond the ability of banks and the incumbent payment infrastructure to handle. When I entered crypto 5yrs ago, blockchain infrastructure wouldn’t have been able to handle what is coming either. But if you squinted, you could see speeds rising, scale expanding, costs falling. That’s what an opportunity looks like. 

From the “didn’t read” body of the blogpost, this caught my eye: When Base launched, our priority was clear: To build a secure, low-cost, developer-friendly chain and ecosystem. This year, we’ve achieved our north star of sub-second, sub-cent transactions, and we’ve expanded beyond a chain into an open stack that makes it simple for anyone to build, trade, and earn onchain. Here’s my TL;DR: Blockchain transaction speeds (using Ethereum as the L1 and Base as the L2) have surged, costs collapsed. Expect valuable use cases to explode. 

It may not have been obvious 5yrs ago. But at this stage, with the convergence of regulatory clarity for dollar stablecoin (with more to come), scalable blockchain technology, and Autonomous AI Agents, it should be apparent that global financial infrastructure is about to undergo a once in a generation upgrade. The opportunities to build businesses and invest in the companies and tokens that will profit from this build-out should be enormous. This is the hand that we’ve been dealt. Learn the new languages required, ask a million questions, and take risk.  

Tyler Durden
Mon, 09/22/2025 – 09:25

Overbought Conditions Across Multiple Markets

0
Overbought Conditions Across Multiple Markets

Authored by Lance Roberts via RealInvestmentAdvice.com,

Fed Cuts Rates: Risk Management Or Mistake?

The Federal Reserve delivered its first rate cut of 2025 on Wednesday, lowering the target range for the federal funds rate by 25 basis points to 4.00%–4.25%. The move had been well-telegraphed, yet it still represents a notable pivot in policy focus. For much of the past two years, inflation had been the Fed’s primary concern, but this time the statement emphasized that “downside risks to employment have risen,” a shift toward the labor side of the mandate. This framing suggests the Fed is willing to risk cutting into still-sticky inflation to avoid potential damage to the job market.

Market reaction to the announcement was anything but straightforward. Immediately following the announcement, stocks whipsawed intraday before finishing mixed. Bond yields initially fell but closed firmer, with the 10-year Treasury settling near 4.07%, while the U.S. dollar strengthened modestly. But Thursday morning, stocks rebounded, supported by news that Nvidia (NVDA) would make a $5 billion investment into rival Intel (INTC) to produce AI and datacenter-related chips. However, one of the largest options expiration days on record impacted Friday. Early in the day, as options rolled, the market gave up all its early morning gains. However, mid-morning news from the White House that a deal was struck with China on TikTok sent markets rocketing back to their highs, with Apple leading the charge.

Still, the underlying question remains: is the Fed making a mistake by cutting now? On one hand, many analysts view the cut as a “risk management” maneuver designed to get slightly ahead of a potential labor market slowdown without committing to a complete easing cycle. Seema Shah, at Principal, argued the move helps “get ahead of a slowdown without overreacting,” while Gregory Faranello of AmeriVet described the strategy as a “methodical pathway down to neutral.” Brandywine’s Jack McIntyre summed up the Fed’s challenge by noting it “is in a tough spot…this was a risk-management cut.” Yet the risk is that cutting rates into an environment of still-elevated inflation, particularly if tariff-related costs eventually emerge, could push the Fed into a tough spot.

In effect, Powell’s Fed is threading a narrow needle. If the labor market weakens sharply in the months ahead, the Fed will look late rather than proactive. If growth stabilizes or re-accelerates, easing at this point could be seen as stoking “animal spirits” unnecessarily.

The market’s muted reaction in equities and a stronger dollar suggest that investors are not entirely convinced the Fed has struck the right balance.

📈Technical Backdrop

Technically, markets continue to set new all-time highs. The S&P 500 closed the week at 6652. The market continues to grind higher and is trading two standard deviations above its 50-DMA. Notably, the markets have continued to push higher, driven by the Mega Cap names, but small and mid-cap stocks have also continued to post stellar gains over the last two months. The signs of a FOMO chase are evident, particularly in heavily shorted names and retail favorites. As Goldman Sachs noted in its latest weekly report, odd lots, or transactions with fewer than 100 shares of stock and a proxy for retail trading, just hit 66% of all US equity trades in Q3. That is up from only 31% in January 2019, representing more than 20% of notional volume and 8% of total executed shares!

Volatility remains unusually low. The VIX is trading around 15.6, placing it in the bottom decile of recent history. Such a backdrop is consistent with “buy-the-dip” psychology but leaves little margin for error heading into a heavy options expiration. Dealer positioning could easily magnify swings if the market breaks its tight range.

Breadth continues to be a key concern. While Wednesday’s action favored financials and cyclicals, mega-cap technology remains the dominant driver of the indices through week’s end. There were also several unusual dynamics worth highlighting. First, the negative divergence remains concerning. Historically, such divergences tend to precede short-term corrective periods. While such a correction has not occurred as of yet, it doesn’t mean that it won’t. Secondly, the deviation from the 50-dma is getting rather extreme, and also argues for at least a breather in the current advance. While none of this is bearish, it does suggest near-term risk management may be beneficial.

Support and Resistance Levels: The S&P 500’s near-term support lies at the 20-day moving average (~6,524). The 50-day moving average is roughly in the ~6,420 region but there is deeper support near ~6,200, connected with the previous pullback. Resistance is around the most recent highs in the 6,700 area (2- 3 standard deviations above the 50-DMA). Notably, volatility (as measured by VIX) remains relatively subdued. The 200-day moving average remains key support for a more significant correction. (~6000)

In short, the technical backdrop remains supportive of risk-taking. Still, with low volatility, sticky long yields, and fragile breadth, the setup argues for tighter risk management heading into next week’s data calendar.

🔑 Key Catalysts Next Week

Next week, a data-heavy slate will be delivered that will likely determine whether the Fed’s risk-management cut is validated or questioned. Investors will get early snapshots of September activity through the S&P Global flash PMIs, fresh readings on housing and durable goods, and the third estimate of Q2 GDP, including revisions to corporate profits. The week ends with the release of August personal consumption expenditures (PCE), the Fed’s preferred inflation gauge. With Powell explicitly tying policy to labor market risks, these reports will be scrutinized for confirmation that the economy is slowing enough to warrant the cut, or whether inflationary pressures continue complicating the picture.

These data releases will be the first real-world test of whether the Fed’s pivot was well-timed. Stronger-than-expected activity or stubborn inflation would raise doubts about the wisdom of cutting now, while weaker labor and consumption data would justify the Fed’s emphasis on risk management. Either way, markets are entering a period where every data point has the potential to shift policy expectations sharply.

💰 Bull Market Run – How We Got Here

Markets have posted a powerful rally since the early April lows. That turning point marked a shift in sentiment, policy expectations, and risk appetite as the S&P 500 and Nasdaq reached record levels. The market surge has prompted investors to move aggressively into risk assets across the market spectrum. With sentiment elevated and concerns about risk non-existent, the fuel for the rally has come from three primary sources:

  • Expectations of interest rate cuts,

  • Easing geopolitical pressures, and;

  • Continued speculation around artificial intelligence.

Simultaneously, as discussed last week, the April jobs report showed a softening in labor market conditions, leading economic indicators remain weak, and consumption signals are becoming increasingly more bearish. While this “bad news” gives the Federal Reserve cover to cut rates, that bad news will eventually be reflected in earnings and valuations. Furthermore, while inflation data has moderated, which fed into the narrative that rate hikes were over, the bond market responded by pricing multiple rate cuts over the coming quarters as economic growth slows. Investors cheer lower Fed rates since they reduce the discount rate on future cash flows, lifting valuations, particularly in growth and tech sectors. However, revenues are at risk of slowing with the economy. As I posted on “X” last week:

“The big risk to the current market environment is that while #margins have remained strong for the last couple of years, it is unlikely they can remain detached from underlying economic activity indefinitely. Cost cutting, layoffs, and productivity enhancements are limited in scope.”

Nonetheless, the narrative of monetary easing has become a cornerstone of the current bull market.

As such, the Artificial Intelligence (AI) trade has returned with full force, with Mega-cap tech stocks seeing strong inflows. Nvidia, Microsoft, and other leaders in the AI space, who posted strong Q2 results, continue to see expectations increase.

“Wall Street analysts have increased estimates for Q3 and Q4 2025 and Q1 and Q2 2026. As a result, analysts now expect the S&P to post record earnings every quarter over the next year.

According to Data Trek: ‘Positive S&P 500 earnings revisions are very uncommon unless the US economy is coming out of a recession, so the Street’s recent bullishness on future index earnings is nothing short of remarkable.‘”

It is important to note that those forward expectations of record profits are not uncommon. Wall Street analysts are always overly optimistic, and expectations seldom align with reality. However, these bullish drivers have also created imbalances and overbought conditions, as I noted in Wednesday’s #DailyMarketCommentary:

“The market is overbought and should not be surprising given the run since the late March and early April correction. However, as noted previously, that run has been predominantly concentrated in the largest market-capitalization names, as noted by the divergence between the equal-weighted and market-cap-weighted S&P 500 Index.”

“The performance spread between the two indices can help us visualize the breadth differential in the market better. While the current performance differential is noteworthy, it does not mean the market is set for a significant bear market, but it does argue for some caution.”

Most importantly, however, typically non-correlated assets have rallied together over the last five years. The Nasdaq is up 129%, and the S&P is higher by 113%, followed by gold (90%), small caps (69%), gold miners (84%), international (64%), and emerging markets (32%). While it has been a good investing market for virtually any asset class you want to throw money at, it is now extremely overbought and leaves investors vulnerable to a correction that could simultaneously impact every asset class.

While the clear winner over the last five years has been to chase technology stocks or large-cap stocks in general, the build-up of complacency and deviations from long-term means is a risk worth considering. As noted, from a technical perspective, overbought conditions exist on multiple levels, from relative strength to momentum to deviations from long-term means. These technical warning signs often precede periods of consolidation or correction.

With investor sentiment nearing more exuberant levels, such extremes rarely last without a reset. The risk now is that the bullish narrative is fully priced in, and the room for upside surprises has narrowed, particularly in the AI trade itself.

The AI Trade — Strengths, Risks, and Overextension

Artificial intelligence has captured Wall Street’s imagination. The investment thesis is clear: AI will reshape industries, generate new efficiencies, and create trillion-dollar opportunities. Companies with exposure to AI infrastructure, cloud computing, and data centers are the primary beneficiaries. Unsurprisingly, investors have responded by concentrating capital in a narrow group of stocks, driving valuations higher and fueling the current rally. The chart below shows the Global X Artificial Intelligence ETF (AIQ), sporting overbought conditions not seen since just before the April “Liberation Day” sell-off.

However, the AI story is not without merit. Revenue growth in cloud infrastructure, chip design, and data services continues. Oracle recently reported a strong demand for AI workloads, while Nvidia’s earnings have validated the explosive demand for computing power. Microsoft, Amazon, and Alphabet are building out AI capabilities at scale, and those developments should support the bullish thesis in the long term. However, markets rarely move in a straight line, and the risks are now building that expectations will likely be ahead of future realities.

That last sentence is the most important. AI space valuation is stretched, with extreme forward earnings multiples for related companies. Many of these companies are priced for perfection, and any slowdown due to economic weakness, overestimated demand, or margin compression could trigger a sharp repricing. With investor positioning crowded, from hedge funds and institutions to retail investors, everyone has increased exposure to the same names. That “crowding” creates fragility where an unwind could be swift if the narrative cracks.

Another aspect is widely overlooked. Policy risk is on the rise with potential AI regulation coming. Governments worldwide are moving to address ethical, privacy, and national security concerns tied to AI development. Increased scrutiny means rising compliance costs and potential restrictions on deployment. These regulatory headwinds are not yet priced in.

The AI trade is technically extended, and overbought conditions push extremes. For example, the Nasdaq is trading well above key moving averages, breadth within tech is narrow, and several key stocks show signs of exhaustion. In the S&P 500, the index is pushing the top of the long-term price trend channel, the deviation from the 4-year moving average is extreme, and relative strength is overbought on a monthly basis. Previous such conditions have not led to bullish outcomes.

The risk of a rotation or correction is high, and investors must distinguish between long-term structural trends and short-term speculative excess. Right now, both are in play. The challenge is managing exposure without chasing the last leg of a crowded trade.

Gold & Gold Miners Go Parabolic

As noted above, another warning sign of the speculative market chase is that gold and gold miners, not typically associated with speculative rallies, are in a speculative melt-up. Historically, gold is a hedge against market stress, inflation, or currency debasement. Yet this year, gold has rallied alongside equities, technology stocks, and bitcoin. That correlation is unusual and speaks to the broader theme of bullish exuberance. The chase for returns has spilled into every market corner, even in traditionally defensive assets that are now caught in the same speculative undertow.

Gold has reached all-time highs, fueled by central bank demand, geopolitical uncertainty, and a softening dollar. Real yields have edged lower, and inflation expectations remain elevated. These factors support the gold narrative. A higher negative correlation exists between the US dollar and gold prices. This makes sense as when the dollar declines, foreign central banks holding U.S. dollars as reserves shift into gold, which trades in dollars, to offset the currency risk. That also works in reverse. Investors should pay close attention to the dollar as an eventual reversal will be key.

But the move in gold miners has been even more aggressive. The VanEck Gold Miners ETF (GDX), a proxy for gold miners, has surged nearly 100% off its lows. That’s not typical behavior for a sector known for volatility and operational risk. Previous moves that have elicited such extreme overbought conditions have historically been closer to a peak of the advance than not.

Miners benefit from rising gold prices, but their earnings are tied to cost structures, energy prices, and management execution. Many gold mining companies have underinvested for years, and while the recent rally has renewed investor interest, the cost structures for these businesses also increase with the price of gold. As noted, the technical indicators are flashing essential warning signals. Relative strength and momentum suggest extreme overbought conditions, and with many stocks trading at multi-year highs, and little regard for earnings variability, investors should consider their risk.

The broader concern is that gold and miners are now trading like momentum stocks. As noted, a dollar reversal could quickly undermine the bullish excitement, and with the dollar now trading at fair value, that risk is rising. Such is particularly the case given that the dollar historically rallies following a Federal Reserve rate-cutting cycle.

If risk appetite fades, these assets could sell off alongside stocks, leaving investors little exposure to traditional portfolio hedges. Investors should reassess how much downside protection these assets offer during a significant market correction and consider alternatives.

While the macro case for gold remains intact, the price action has likely run ahead of fundamentals. A pullback would help reset expectations.

Investors face the problem of chasing performance, which carries as much risk as chasing AI. The lesson is simple: when everything rallies together, something eventually breaks.


Tyler Durden
Mon, 09/22/2025 – 07:20

Visualizing The Massive Network Powering US Data Centers

0
Visualizing The Massive Network Powering US Data Centers

The map below, produced by Visual Capitalist’s Nick Routley and the National Renewable Energy Laboratory (NREL) on behalf of the U.S. Department of Energy’s Grid Deployment Office, shows the sprawling and powerful infrastructure behind America’s data center boom.

Using a range of public data sources, it visualizes power transmission hubs in megawatts (MW), highlighting where the electric grid is already working hard, and where future pressure may build.

The table below highlights counties that use the most power for data center facilities:

Loudoun County, Virginia (home to “Data Center Alley”) tops the list with nearly 6,000 MW of active capacity and another 6,300 MW planned.

Why Are Data Centers Located Where They Are?

It’s tempting to assume that large populations drive data center development, but that’s often not the case. Instead, it comes down to a mix of factors:

  • Electricity availability and cost: Data centers consume vast amounts of power. States like Virginia, Texas, and Oregon offer competitive electricity pricing and stable infrastructure.

  • Access to water: Many facilities use water for evaporative cooling, so proximity to aquifers or rivers can be crucial.

  • Fiber networks: Low latency is king. Proximity to fiber optic infrastructure and subsea cable landing stations is critical.

  • Zoning and incentives: Tax incentives and permissive local zoning laws can make or break a deal.

With this in mind, here are a few areas on the map worth highlighting:

Ashburn, VA and Surrounding DC Suburbs
The data center cluster around the DC suburbs, especially Ashburn, is known as the “Data Center Capital of the World” and “Data Center Alley.” It hosts the largest concentration of internet infrastructure globally, where about 70% of the world’s internet traffic flows daily. This area offers abundant and reliable power from Dominion Energy, dense fiber connectivity, aggressive state tax incentives, and proximity to major government and enterprise customers, making it the preferred hub for hyperscale cloud and data companies.

The I-85 Corridor
This region, which roughly runs from Atlanta up into Virginia, is emerging as a strategic data center hub. The corridor benefits from improved transmission infrastructure, and growing local tax incentives. Atlanta’s proximity to major East Coast markets and Virginia Beach’s new subsea cable landing stations make this region a digital on-ramp to global networks.

West Texas
Known for its vast open spaces and powerful winds, West Texas offers some of the lowest electricity prices in the country. It’s also home to major renewable energy projects, including wind and solar farms that help data center operators meet clean energy goals. This has drawn attention from major players like Microsoft and Meta.

Eastern Washington and Oregon
The Columbia River powers a dense cluster of hydroelectric dams, which in turn support energy-hungry data centers in towns like The Dalles and Quincy. The cool, dry climate further reduces the need for mechanical cooling, making this region one of the most cost-efficient for data center operations.

Can the Grid Keep Up?

U.S. data centers already consume 2-3% of the country’s electricity. According to WRI, this could double by 2030, especially with AI workloads driving GPU server farms that are far more energy-intensive than traditional ones.

Meanwhile, the pressure is on utilities and policymakers to expand grid capacity faster than ever before. Interconnection queues are long, and power disputes are already delaying projects in places like Northern Virginia and Silicon Valley.

Yet, the demand shows no signs of slowing, making the power grid one of the most important tech battlegrounds of the next decade.

See the world’s biggest data centers by megawatts in this visualization on Voronoi.

Tyler Durden
Mon, 09/22/2025 – 06:55

Trump To Designate More Leftist Groups As Terrorists

0
Trump To Designate More Leftist Groups As Terrorists

Authored by Steve Watson via Modernity.news,

President Trump has announced plans to designate not only Antifa but also other radical left-wing groups as terrorist organizations, signaling a renewed commitment to combating what he described as a “vast domestic terror movement” threatening American safety. 

Trump made the announcement during an Oval office briefing in front of the press.

“We have others we’re going to designate too, but we’re going to look at the people that FUNDED Antifa, see who they are, where they came from and why they did it,” he urged.

This move comes just days after the tragic assassination of conservative activist Charlie Kirk, at the hands, it appears, of a suspect linked to left-wing extremism, and builds directly on Trump’s long-standing warnings about Antifa’s role in fomenting chaos.

Trump declared, “Antifa and their radical allies have crossed every line—it’s time to call them what they are: terrorists. We’re designating Antifa as a major terrorist organization, and we’ll go after every group funding or supporting this sick, dangerous radical left disaster.” 

He further emphasized the breadth of the initiative, adding, “This isn’t just about one group; it’s about the entire network of left-wing extremists who’ve turned our streets into battlegrounds.”

“We’ll root them out to protect every American,” he added.

These words, delivered with the gravitas of a leader under siege, underscore Trump’s determination to wield executive authority against domestic threats, echoing his 2020 pledge that never fully materialized due to bureaucratic hurdles.

This latest announcement harks back to the midst of nationwide riots following the death of George Floyd, when Trump first sounded the alarm on Antifa’s destructive potential. 

In a now-iconic tweet, he stated unequivocally, “The United States of America will be designating ANTIFA as a Terrorist Organization.” 

Addressing reporters at the time, Trump also lambasted “professional anarchists” for exploiting protests, vowing, “These are not merely trespassers and looters. These are terrorists, and those who defend or promote them are aiding and abetting terrorists.” 

Yesterday’s expansion to “other groups” aligns with reports from Trump’s advisers, who have previewed a broader crackdown on far-left entities, including loosely affiliated activist networks that have clashed with law enforcement at rallies and protests. 

While specifics on named organizations remain forthcoming—potentially including groups like those involved in the Kirk shooting—Trump’s rhetoric paints a picture of a coordinated ideological assault. 

A Necessary Response to Left-Wing Violence

Trump’s actions in this matter represent a vital, overdue reaction to the escalating tide of violence from the radical left. Over the past five years, incidents of Antifa-linked aggression have surged—from firebombings at federal courthouses in Portland to coordinated assaults on police, and now the brazen murder of Charlie Kirk.

Data from the Department of Homeland Security shows a 300% increase in attacks on law enforcement attributed to far-left extremists since 2020, with Antifa’s decentralized cells often at the epicenter. 

Kirk’s killing, allegedly by Tyler Robinson—a figure tied to anti-fascist circles—exposes the deadly consequences of unchecked radicalism, where ideological fervor morphs into targeted assassinations.

Designating these groups as terrorists equips federal agencies with tools like asset freezes, surveillance, and RICO prosecutions to dismantle their operations, much like the successful takedowns of organized crime syndicates.

Trump is intent on restoring law and order in a nation weary of masked mobs torching businesses and intimidating citizens. By treating Antifa and its allies as the threats they are, Trump is attempting to safeguard communities, prevent further bloodshed, and uphold the rule of law that underpins American freedom. 

Without such measures, the slippery slope of tolerated violence threatens to erode the very fabric of the republic.

Democrats’ Defiance: Prioritizing Chaos Over Safety

Compounding this crisis is the Democratic Party’s apparent reluctance—or outright opposition—to confront these threats head-on. Leaders like Senate Majority Leader Chuck Schumer have downplayed Antifa’s role in violence, with Schumer tweeting in 2020 that designating it a terrorist group would be “a dangerous overreach that chills free speech.” 

More recently, following the Kirk assassination, Democrats have pivoted to blaming “right-wing rhetoric” while calling for investigations into Trump’s “divisive language,” effectively shielding the perpetrators.

This pattern reveals a deeper affinity: Democrats seem content to let groups like Antifa prosper, viewing them as bulwarks against conservatism rather than the arsonists and assassins they really are. 

Recall how, during the 2020 riots, then-candidate Joe Biden condemned “violence on both sides” but rarely singled out Antifa by name, even as billions in damages mounted. 

Today, with far left lawmakers like Alexandria Ocasio-Cortez decrying Trump’s designations as “authoritarian,” the party appears more invested in cultural warfare than public safety.

Their resistance isn’t just passive; it’s enabling, allowing these extremists to regroup, fundraise, and strike again under the guise of “activism.”

In contrast, Trump’s proactive stance—offers a beacon of accountability.

Your support is crucial in helping us defeat mass censorship. Please consider donating via Locals or check out our unique merch. Follow us on X @ModernityNews.

Tyler Durden
Mon, 09/22/2025 – 06:30

Which Countries Buy The Most US Coal?

0
Which Countries Buy The Most US Coal?

Coal remains a major U.S. export, even as the domestic energy mix shifts toward natural gas and renewables. In 2024, America exported nearly 100 million tonnes of coal to countries around the world, with a concentration of buyers in Asia.

This visualization, via Visual Capitalist’s Marcus Lu, breaks down the top destinations for U.S. coal exports last year. The data for this graphic comes from the U.S. Energy Information Administration (EIA). It shows 2024 coal export volumes by destination, measured in millions of tonnes.

Asia: The Rising Demand Hub

India led the pack with 23.4% of all U.S. coal exports, followed by China (11.5%) and Japan (8.4%). Combined, these three Asian countries accounted for nearly 43% of all American coal exports.

Rank Destination 2024 (million tonnes) % of Total
1 🇮🇳 India 22.9 23.4
2 🇨🇳 China 11.3 11.5
3 🇯🇵 Japan 8.2 8.4
4 🇧🇷 Brazil 7.6 7.8
5 🇳🇱 Netherlands 7.2 7.4
6 🇲🇦 Morocco 5.4 5.6
7 🇰🇷 South Korea 4.3 4.4
8 🇪🇬 Egypt 4.2 4.3
9 🇨🇦 Canada 3.8 3.9
10 🇹🇷 Turkey 2.5 2.6
11 🇮🇩 Indonesia 2.1 2.2
12 🇩🇪 Germany 1.9 2.0
13 🇮🇹 Italy 1.7 1.7
14 🇵🇱 Poland 1.5 1.5
15 🇩🇴 Dominican Republic 1.3 1.3
16 🇦🇹 Austria 1.1 1.2
17 🇫🇷 France 1.1 1.1
18 🇸🇬 Singapore 1.0 1.1
19 🇪🇸 Spain 1.0 1.0
20 🇧🇪 Belgium 0.9 1.0
21 🇭🇷 Croatia 0.9 0.9
22 🇦🇷 Argentina 0.7 0.8
23 🇵🇰 Pakistan 0.7 0.7
24 🇫🇮 Finland 0.6 0.7
25 🇸🇪 Sweden 0.6 0.6
26 🇺🇦 Ukraine 0.5 0.5
27 🇲🇾 Malaysia 0.5 0.5
28 🇨🇱 Chile 0.3 0.3
29 🇿🇦 South Africa 0.2 0.2
30 🇹🇭 Thailand 0.2 0.2
31 🇦🇪 UAE 0.2 0.2
32 🇬🇧 UK 0.2 0.2
33 🇬🇹 Guatemala 0.1 0.2
34 🇻🇳 Vietnam 0.1 0.1
35 🇷🇴 Romania 0.1 0.1
36 🇹🇬 Togo 0.1 0.1
37 🇳🇴 Norway 0.1 0.1
38 🇭🇳 Honduras 0.1 0.1
39 🇨🇭 Switzerland 0.1 0.1

Since 2017, Asia has eclipsed Europe as the leading destination for U.S. coal.

In 2024, India alone purchased 22.9 million tonnes. India’s high demand for U.S. coal is driven by a combination of energy security needs, domestic production gaps, and infrastructure limitations. Currently, the country relies heavily on coal to generate electricity—over 70% of its electricity comes from coal-fired power plants.

Europe’s Waning Role

While several European countries still import American coal, their overall share has declined. The Netherlands remains a key buyer (7.4%), but other nations like Germany, Italy, and Poland account for smaller volumes. The EU’s push to phase out coal and meet climate targets has sharply reduced demand in the region.

Notably, many European buyers now import U.S. coal primarily for metallurgical (steelmaking) rather than power generation uses.

Emerging and Niche Markets

Beyond Asia and Europe, a number of countries in Latin America, Africa, and the Middle East imported smaller quantities of U.S. coal in 2024. Brazil (7.8%) and Morocco (5.6%) were notable non-Asian buyers.

If you enjoyed today’s post, check out What Powered the World in 2024? on Voronoi, the new app from Visual Capitalist.

Tyler Durden
Mon, 09/22/2025 – 05:45

The 5 Arcs & 7 Cracks Of Systemic Collapse

0
The 5 Arcs & 7 Cracks Of Systemic Collapse

Authored by Matthew Piepenburg via VonGreyerz.gold,

For centuries, philosophers have compared the great questions (and mysteries) of life to a circle.

That is: To fully understand the circle, you must also recognize its arcs, and to fully understand the arcs, you must see the circle.

The fancy lads call this paradoxical “tying together of all things” hermeneutics.

But we don’t need fancy phrases to call out a global financial system losing all credibility, options and happy endings.

When it comes to the “circle” of an increasingly apparent economic collapse, the systemic, mathematical and historical “arcs” of this dying economic/financial/social sphere are becoming easier for all of us to both feel and see.

A Circle of Systemic Implosion

But to make this real (rather than philosophical), let’s put these evidentiary “arcs” in their proper place so that we can all objectively recognize the circle of systemic implosion knocking on our doors.

ARC 1: Debt

As we’ve been writing for years, the patient-zero from which all the ripple effects of systemic implosion emanate is tragically simple and historically confirmed, namely: Debt.

When nations cross the Rubicon of 100% debt to GDP, growth slows by a third.

As that ratio increases, growth becomes a fantasy. In short, and as David Hume warned centuries ago: Debt destroys nations.

Debt in the US is at historical, unprecedented and also unsustainable levels.

If Hume was right, then Uncle Sam faces serious problems now and ahead.

But what’s even scarier about debt destruction today is that the problem is not just American, it’s global.

Total global debt stands well above $300T, and total global GDP is only 1/3 that cancerous figure.

In short, debt is on a rampage, and it is leaving a swath of destruction (and evidence) in its wake.

ARC 2: The Causes (and Criminals) of Debt

If debt is a crime, then our policymakers are the criminals.

The smoking gun for the currently imploding debt cycle was August 15, 1971, when the home of the World Reserve Currency decoupled from its constitutionally forewarned gold chaperone.

Why the decoupling from sound money?

The answer is simple: Politicians of all stripes (who harbor a “will to power” that would make Nietzsche blush) prefer the short-term votes, power and prestige that come from unlimited spending, which is only possible when a currency is decoupled from a golden chaperone.

This was true long before Trump, and the sins are both red and blue.

Short-term self-interest rather than long-term national interest is the philosophical (human, all too human) modus operandi of all pathologically unwise politicos…

ARC 3: Currency Debasement

Once a currency is free of its golden anchor, it can be printed, mouse-clicked and credit-expanded to infinity and beyond to pay for (“monetize”) the promises, policies and egos of leaders who know little of history and almost nothing of money.

Such credit (and hence currency) expansion leads directly to currency debasement as nations inflate away their ever-expanding bar-tabs with ever-debased currencies (measured against real money: Gold).

This pattern and cycle of debt to currency debasement is as familiar as history itself—at least for those who bother to understand history…

ARC 4: Dishonesty

The next phase of policy makers with their backs against a debt wall is equally clever and equally inevitable, namely: Lying.

One obvious great lie came on day 1, when Nixon promised us in 1971 that our dollar would be just as strong tomorrow as today, and that the decoupling from gold would be “temporary.”

Even prior to that infamous decoupling in 71, the lying was already in full swing.

The Fed Chairman and Treasury Secretary of that time were telling Congress that such a decoupling would, in fact, strengthen the dollar and weaken gold.

Fifty-four years later, your dollar has lost 99% when measured against gold.

And as for that “pet rock,” well…rather than “weaken,” it has risen by 8000% since those experts told us it would tank.

Just saying…

But the lying just continued, of course.

Our PhD economists at the FOMC and beyond, for example, gave us Modern Monetary Theory (MMT), which promised us we could print trillions to monetize our sovereign debt without creating inflation.

MMT, which is neither “modern,” nor “monetary” nor even a “theory”, has been tried (and failed) from Ancient Rome, the 1720 John Law Era and the collapse of the 1789 French economy to the fiasco of Weimar Germany or the implosion of Yugoslavia in the 1990’s.

In short, one big, history-confirmed lie.

More recently, the lies keep piling up, from the CPI scale/lie we use to downplay actual inflation to a redefinition of a recession for a nation already in recession.

ARC 5: Desperation

From dishonesty follows desperation, when policy makers, otherwise allergic to taking responsibility or speaking bluntly of a crisis, begin looking for fantasy policies to “save us.”

We’ve been tracking and objectively calling out the hidden impotence behind the so-called miracle measures, which are currently making the headlines.

The list is long yet not very distinguished.

But for simplicity, let’s list the most notable fantasies which both history and math (for those willing to look deeply) already confirm as doomed (rigged) to fail.

More to the point:

The Jig is Up –And the Evidence/Cracks are Everywhere

As for evidence that all of the foregoing “arcs” are now manifesting as historically unprecedented “cracks” in the global financial system, all one has to do is look around…

Crack 1: The USD

The most obvious indicator of a US in decline is the no-longer-ignorable decline in trust (and demand) for its overly-indebted and stupidly weaponized USD.

As more and more nations trade outside the USD, the BRICS+ headline of de-dollarization is not a “conspiracy theory” but an historical tipping point for the much-debated but otherwise discredited USD.

Crack 2: A Ticking S&P Timebomb

An S&P 500 of which 40% of its market cap is narrowly led by 7 mega-cap (and AI-top heavy) enterprises is not a stock market but rather a market of a few monopoly stocks in which the top 10% enjoy 90% of its wealth.

This narrow market is over-valued by every metric and is entirely Pavlovian in its rises and falls, going up with a dovish Fed or down with a hawkish Fed.

The net result is a Fed-centralized equity market (in the backdrop dying capitalism and rising feudalism) whose inflationary rise is entirely correlated to the Fed’s inflationary monetary policies.

When, not if, the natural forces of the bond market (i.e. spiking yields) replace the Fed’s un-natural monetary forces, this bubble will do what all bubbles do: pop.

Crack 3: An Unloved UST

Since 2014, the world’s central banks have been net-selling USTs and net-stacking physical gold.

This embarrassing trend, driven entirely by distrust for Uncle Sam’s ever-increasing debt-trap, only accelerated when Uncle Sam weaponized that UST and USD in 2022.

Less trust, demand and buyers for US IOUs means more pressure on the Fed’s money-printers to buy its own debt and keep bond prices up and hence bond yields (the true cost of credit) compressed.

Such a bond “accommodation” means currency debasement, pure and simple.

Crack 4: Panic on the COMEX

Once the setting for legalized price fixing of the gold and silver price via uber-levered futures contract shorts, the COMEX is seeing headline-ignored inflows and outflows in which the metals needed to continue the price fix on precious metals is simply no longer there.

Why?

Because counterparties on the COMEX now want physical gold within their own hands, rather than price fixing between London and New York.

Why this sudden need for the real gold rather than paper contracts?

It’s simple: The world, like the BIS, IMF and BRICS+ nations, trusts physical gold as an objectively superior strategic reserve asset than the once sacred 10Y UST, which debt alone has now fully discredited.

Crack 5: Central Bank Gold Stacking

From the moment the US made the fatal mistake of weaponizing the world reserve currency in 2022, central bank gold stacking has tripled.

Why?

Again: For the simple reason that the world is losing love, trust and demand for a weaponized and over-indebted USD whose prior monopoly powers are now devolving in plain sight.

The world sees what history has always shown us: Once a nation debases its currency to monetize its debt sins, gold becomes real money…

 and paper money, becomes, well, just paper…

Crack 6: Waning Petrodollar

When the dollar ditched its gold chaperone in 1971, the clever minds led by Kissinger in DC understood an immediate need to create global demand for the USD.

The OPEC arrangements, which followed, forced the world to buy oil in USD, and for decades, this energy “sponge” created needed demand for an otherwise debased USD.

Since 2022, however, oil is increasingly being bought and sold outside the USD at levels once thought unthinkable before that broken dollar was weaponized.

This is yet another sign of a world moving away from the USD’s declining hegemony due entirely to the USA’s rising debt sickness.

Crack 7: Discord on the Rise

Internal social, cultural and political polarizations within and outside of the US, whether based on race, sexual orientation, immigration dynamics or just plain poor citizens suffering under the visible rage of invisible (i.e., misreported) inflation are clear signs that the natives are getting restless.

Trust in government is at an all-time low within the US and throughout the G-7.

Such social chasms, as well as the worst foreign relations since 1949 and the greatest risk of nuclear war since the Cuban Missile Crisis (with proxy and direct wars nearly everywhere), are classic symptoms in the template of systemic implosions following sovereign debt crises and currency debasement.

As Hemingway warned, the “temporary prosperity” of debt-driven good times is always followed by the “permanent ruin” of currency debasement and war…

Look around you: What do you see?

Currency debasement and war…

No Easy Way Out

Dying nations, dying currencies, and dying financial systems, like dying armies, don’t give up easily, even after it’s clear they are experiencing their Waterloo or Gettysburg moment.

Like the stages of grief, denial is the first emotion for policymakers who can’t admit failure or accountability.

The debt, which is eating away at nations, currencies and citizens, is now too big to grow out of or wean away from with smarter spending habits.

As von Mises warned, there will need to be “constructive destruction” in the form of recessions, market mean reversions, and currency collapses (and hence skyrocketing gold) before the anger stage is surpassed by the acceptance stage.

The IMF talks of resets (and gold-backed CBDC). Bessent and Trump are flirting with gold revaluation.

These are just two of many possibilities, including a Bretton Woods or Plaza Accords 2.0 to re-arrange the deck chairs on a Titanic level of global debt.

Whatever comes next, it will not be smooth, easy or painless.

Paper money will continue its historical and inflationary slide south as gold, that intentionally ignored and downplayed asset, will continue to reach higher all-time-highs as sovereign credibility—from banking and currencies to trust and wisdom—continues to reach all-time-lows.

Tyler Durden
Mon, 09/22/2025 – 05:00

China On Cusp Of Commercializing US-Pioneered ‘Holy Grail’ Fusion Energy

0
China On Cusp Of Commercializing US-Pioneered ‘Holy Grail’ Fusion Energy

Authored by John Haughey via The Epoch Times (emphasis ours),

China has spent up to $13 billion developing fusion energy since 2023 and could commercially replicate star power to generate electricity by 2030, becoming the first nation to master what’s commonly dubbed “the holy grail of energy solutions.”

The Tokamak Fusion Test Reactor (TFTR), in a file photo. U.S. Department of Energy, Public Domain

Doing so would give the Chinese Communist Party (CCP) “the potential to reshape global geopolitics” and “dominate a new energy era,” Massachusetts Institute of Technology physicists warn.

This cannot happen, said Rep. Randy Weber (R-Texas), who chairs the House Science, Space, and Technology Committee’s Energy Subcommittee.

“Fusion energy technologies must be developed and deployed by nations that uphold democratic values, transparency, and international cooperation—not by authoritarian regimes that might exploit energy dominance as a weapon,” he said in opening remarks of a Sept. 18 hearing on the nation’s fusion programs.

“The U.S. must prioritize fusion energy development to outpace the CCP’s aggressive timelines,” Weber added, or China will dominate “the most consequential breakthrough of the century.”

Four fusion experts told the subcommittee during the two-hour hearing that the CCP doesn’t have to win what they see as an existential race, calling on the Trump administration to boost funding to match China’s investment, coordinate research and development with allies, and establish fusion demonstration programs using the same “playbook” that spearheaded breakthroughs in other technologies.

Unlike fission, nuclear fusion replicates the reaction produced by firing atoms, which is the power emitted by stars, and has the potential to provide limitless, clean energy. It is often referred to as “the holy grail of energy solutions.”

Fusion has been researched by academic institutions and government laboratories since the 1950s, with significant breakthroughs in 2022—including Lawrence Livermore National Laboratory’s National Ignition Facility completing a nuclear fusion reaction that produced more energy than used to power the experiment—spurring rapid, exponential advancements since.

“This is our ‘Kitty Hawk’ moment, ushering in a new era of virtually unlimited fusion power,” Commonwealth Fusion Systems Co-Founder/CEO Bob Mumgaard said, calling for a $10 billion one-time “kick” in Department of Energy (DOE) funding.

A rendering of Pacific Fusion’s Demonstration System, which the company maintains will achieve “net facility gain”—or more energy produced than consumed in a reaction—by 2030. Pacific Fusion illustration provided for congressional testimony on Sept. 18, 2025

‘Decisive Moment Is Upon Us’

Mumgaard, whose company aims to build a small fusion power plant with an ARC tokamak design by the early 2030s, said the nation’s fusion industry has grown from 23 companies that raised $1.78 billion in private capital in 2021 to 53 companies that raised $10.6 billion in 2024.

But now these burgeoning enterprises need to test experimental fusion reactors in a limited-risk environment, which is where DOE and federal funding could make the difference, he said.

Mumgaard said in his testimony that a fusion demonstration program similar to DOE’s advanced fission reactor program would “accelerate deployment of at least three different fusion power plant approaches, with construction starting by the end of 2028 and entering operation by the early 2030s.”

He called for “milestone-based, cost-shared funding that awards only those who show substantial progress toward the goal” with “selection of participants based not just on scientific merit, but also by requiring a clear path to commercial and business success.”

“I agree this $10 billion injection would go a long way to setting us on the course,” Oak Ridge National Laboratory Fusion Energy Division Director Troy Carter concurred.

“The decisive moment is upon us,” he testified. “With deliberate action now—by supporting new facilities, public-private partnerships, and sustained innovation—we can ensure the U.S. leads in bringing fusion energy from scientific promise to commercial reality.”

“The U.S. fusion industry is on the cusp of commercialization,” Pacific Fusion founder and President Will Regan said in his testimony. “America wrote the playbook on investing in fundamental scientific breakthroughs and then scaling their industrial application through the private sector. Fusion is no different, and today we’re at the last mile of solving key scientific challenges to enabling commercial deployment.”

Rep. Zoe Lofgren (D-Calif.) said, while “very much opposed overall” to the fiscal year 2026 (FY26) budget crafted by President Donald Trump, “I would like to say when it comes to his specific request for fusion, it’s moving in the right direction, and I am glad for that.”

DOE’s FY26 budget request provides $7.1 billion for the Office of Science, which includes fusion research and explicitly directs Congress to allocate in a way that “maintains U.S. competitiveness in priority areas such as fusion.”

“I’m hoping we’ll continue to work on a bipartisan basis to get to where we need to go,” Lofgren said. “Like Wayne Gretzky said, ‘You need to skate to where the hockey puck is going to be.’”

“In a world increasingly concerned with how to address rapidly growing energy needs, as well as geopolitical tensions arising from access to energy and energy resources, fusion energy gives us hope,” University of Wisconsin assistant professor Stephanie Diem testified. “We have achieved remarkable scientific advances; now we need robust support to build a thriving fusion energy ecosystem.”

Tyler Durden
Sun, 09/21/2025 – 23:20