46.4 F
Chicago
Friday, November 6, 2026
Home Blog Page 173

US Embassy Issues Health Alert For Cuba After ‘Significant Increase In Diarrheal Illness’

0
US Embassy Issues Health Alert For Cuba After ‘Significant Increase In Diarrheal Illness’

Authored by Jacki Thrapp via The Epoch Times,

The U.S. Embassy in Cuba has issued a health alert, warning Americans about a rise in gastrointestinal illnesses caused by the island nation’s water and energy grid collapses.

“The U.S. Embassy has noted a significant increase in diarrheal illness across Cuba, associated with the continuing degradation of the water and energy infrastructure,” the Sept. 4 alert reads.

The embassy stated that the degradation affected the country’s water supply, food storage, and temperature control, sparking infections such as E. coli, norovirus, Shigella, and other gastrointestinal pathogens.

Americans are urged to “be cautious” around meat, poultry, seafood, eggs, dairy, and other perishable foods that have not been stored properly.

People are also encouraged to stay away from foods that have been at room temperature for a long time, avoid eating raw or improperly washed vegetables, and be careful before they eat any cooked food that has cooled and then is reheated.

Frequent hand washing was also encouraged.

Embassy officials encouraged people to stay hydrated and “seek medical attention for persistent or severe diarrhea, bloody stools, high fever, significant abdominal pain, repeated vomiting, signs of dehydration, or symptoms not improving.”

On Aug. 28, U.S. embassy officials warned that Cuba’s water delivery infrastructure was growing increasingly unstable as some neighborhoods reported going long periods without receiving water from the regime.

Officials suggested that the water issues and power outages were caused by the communist regime’s “mismanagement of public infrastructure” across the entire island.

“Water often only flows to residences when city power is on for a sufficient amount of time,” the August alert reads.

Eight months ago, the Trump administration started a fuel blockade on Cuba to force negotiations around returning democracy to the island, including allowing Cuban exiles to return to vote for the first time since the communist takeover in 1959.

The blockade cut off oil deliveries to Cuba from Venezuela’s socialist regime. The island faces an energy crisis that has left about 10 million people in the dark multiple times this year.

Energy authorities reported two nationwide grid collapses in March and three in July, along with several partial outages.

U.N.-appointed human rights experts said in February that the fuel blockade was a serious violation of international law.

However, in March, U.S. Secretary of State Marco Rubio said Cuba’s grid has long been unreliable due to years of neglect by the regime.

“They were having blackouts last year,” Rubio said. “They’re having blackouts because they have equipment from the 1950s in their grid that they’ve never maintained and never upgraded, because they’re incompetent.”

Tyler Durden
Tue, 09/08/2026 – 11:05

Canada’s Counter-Tariffs Take Effect As Trump Targets Bombardier And Midterm Battlegrounds

0
Canada’s Counter-Tariffs Take Effect As Trump Targets Bombardier And Midterm Battlegrounds

Canada’s retaliatory tariffs on U.S. goods took effect at 12:01 a.m. Tuesday – raising duties of 15%, 25%, and 50% on hundreds of American products after last month’s collapse of bilateral talks. Ottawa says the package matches the United States “dollar for dollar, rate for rate.” Finance Canada values the covered U.S. imports at $27.6 billion; some U.S. accounts put the figure nearer $20 billion. Either way, it is a small share of total two-way trade – and a large share of the political risk.

GEOFF ROBINS/AFP/Getty Images

The list is drawn from goods already hit by U.S. Section 338 and Section 232 tariffs. Section 338, a long-dormant provision of the Tariff Act of 1930, had not previously been used by a president to impose duties; Trump invoked it in July to levy 50% on selected Canadian goods after talks failed, and those U.S. duties took effect August 22. Canada’s matching rates now apply as follows: 50% on most steel and aluminum products (up from an earlier 25% Canadian counter-duty), plus furniture and clothing; 25% on appliances, dairy including cheese, and some metal derivatives; 15% on selected electronics, tools, and machinery. Goods already in transit when the rules took effect are exempt. The surtaxes apply to U.S.-origin goods under Canadian marking rules, not merely to shipments that happen to cross the border.

Seafood and fish were on Ottawa’s original list at 25% but were pulled on August 27 after warnings from Canada’s Atlantic processors and Maine’s lobster industry. About half of Maine’s fall catch is processed in New Brunswick; a tariff on those lobsters would have hit both sides. Finance Canada called the change “select adjustments… based on feedback” while adding other items, including copper wire and charcoal, to keep the dollar-for-dollar total. Sen. Susan Collins (R-ME) applauded the retreat – evidence that the targeting was political, and that it can be walked back when the politics cut the wrong way.

Prime Minister Mark Carney has framed the response as measured but non-negotiable. Canadian officials have described the country as under economic assault and have pledged not to match every rhetorical escalation. The practical strategy is twofold: impose a politically targeted list at home, and shop for other markets abroad.

Why Michigan and Ohio matter more than the headline total

Heading into November midterms, Canada’s new tariffs are designed to land in states that do a high volume of business with Canada, and which have competitive races. Ohio shipped the largest dollar volume of newly covered goods. Michigan, Indiana, Pennsylvania, and Wisconsin follow close behind. Michigan sends roughly a third of its merchandise exports to Canada; auto parts often cross the Detroit-Windsor corridor more than once before a vehicle is finished. The new Gordie Howe International Bridge was meant to ease that flow. It now sits at the center of a fight over who pays the tariff.

Those same industrial states host competitive House and Senate races. Michigan’s Senate contest between Republican Mike Rogers and Democrat Abdul El-Sayed is one of several Great Lakes races that will test whether tariff costs show up at the ballot box; it is not the only possible pivot for Senate control. Ohio’s Republican-held Senate seat is also in play. Canadian ministers have said openly that the product list was chosen to concentrate pressure where U.S. politics would feel it. Industry Minister Mélanie Joly, at the August announcement, said Canada was “targeting products that will target states in the U.S.” and added: “we’re being wise and strategic to put political pressure. And that’s why we think it’s the right thing to do right now.”

Trade groups on both sides warn that the first-round dollar amounts understate the damage. Integrated supply chains mean a duty on steel, parts, or appliances shows up as higher costs for factories and households on both sides of the border. Brad Wood, senior director for trade and innovation at the National Foreign Trade Council, called the cycle “bad for Canadian businesses and consumers, and bad for American businesses and consumers,” and said each new layer is another barrier the two governments will eventually have to unwind.

Trump’s next pressure points: autos, Bombardier, and Lake America

Washington has not treated Canada’s move as the last word. President Trump has already threatened higher auto tariffs in 2027 and, last week, floated cutting off bilateral trade altogether. On Sunday he attacked what he called Canada’s “dollar imbalance.”

Hours before the Canadian tariffs took effect, Trump turned to Bombardier. In a Truth Social post he declared “NO MORE SELLING BOMBARDIER IN THE UNITED STATES,” called the company’s products “not good enough,” and said that if it wants the U.S. market it “must build here.” He closed with a list of commands: buy American, fly American airliners, drink American liquor, and “SAIL ON LAKE AMERICA.”

Bombardier did not answer the president by name. It noted that aerospace is a major U.S. export industry, that it builds wings and other components in California and Texas, and that it supports tens of thousands of American jobs through plants and a supply chain spanning dozens of states. About 55% of its 2025 revenue came from U.S. customers. The White House has not said how a sales ban would be enforced on aircraft already certified by the FAA.

The Bombardier fight is not new. Trump threatened decertification and a 50% aircraft tariff earlier this year over Gulfstream certification in Canada. Ottawa later certified several Gulfstream models. In 2018 a first-term Commerce Department case against Bombardier airliners produced a huge preliminary duty that the U.S. International Trade Commission later rejected.

Trump has also rewritten the map. On August 27 he signed an executive order directing the Interior Department to update geographic systems immediately from Lake Ontario to Lake America; Great Lakes placards went up in the Oval Office. 

Carney hit back, saying “We know that America is changing. Their trading relationships, their foreign policies, their national monuments, their hydronyms. Canadians also know that naming reality means calling it Lake Ontario – then, now and always.“

Supreme Tariff Tiff

Canada aside – on February 20, the Supreme Court ruled 6-3 that Trump could not use the International Emergency Economic Powers Act (IEEPA) to impose his sweeping “reciprocal” and emergency tariffs. Chief Justice John Roberts wrote that IEEPA contains no reference to tariffs and that no prior president had read such a power into the statute. Section 232 metal tariffs were left standing. The administration has since rebuilt parts of the program under other authorities, including Section 338 for Canada and a forthcoming roster of duties against other countries accused of “excess capacity” and persistent surpluses with the United States. Trump has also threatened to block trade with countries that export more to the United States than they import. A consumer-price report due this week will test how much earlier tariff rounds have already fed inflation.

Ottawa’s hedge: Europe, and a quiet channel to Beijing

Carney will attend Ursula von der Leyen’s State of the Union address in Strasbourg on September 16 and speak to the European Parliament on September 17 – the first foreign head of government invited into that ritual. He has said Canada will open “intense discussions” this fall on a deeper economic and security partnership with the EU, already its second-largest trading partner under CETA.

In parallel, Canadian and Chinese defence officials held a coordination dialogue on September 4, the first such formal talks in more than eight years. Beijing announced the meeting; Ottawa later confirmed working-level military-to-military contact. The optics – reopening a channel closed after the 2018 detentions of two Canadians, while NATO and EU ties remain the stated priority – have already drawn criticism at home.

The immediate economic hit from Tuesday’s list is limited by design. The larger question is whether a two-month window before U.S. midterms produces a deal or another round.

Tyler Durden
Tue, 09/08/2026 – 10:30

More – And Less – Of The Same Things

0
More – And Less – Of The Same Things

By Michael Every of Rabobank

It’s more of the same to start this Tuesday, and less too: and that isn’t good news.

Japanese Q2 GDP came in at 0.4% q-o-q, 1.3% y-o-y at the second read, backing the BOJ hiking rates again on September 18 – but is it really going to be ‘one and done’? The 2-year JGB yield is at 1.84% today, close to a new multi-decade high, and vs. the more usual 0% seen for years, while the 10-year is at 2.91%, off recent highs.

Alongside suspicions of further FX market intervention, USD/JPY swung from 154.37 to 153.21, with market chatter of a test of 152 next: recall it was at 160.35 at the start of the month. That’s quite the volatility shock for some books and for those who thought the Yen Carry trade was going to stay one way even after the recent warning from Bessent. Finance Minister Katayama said she will maintain an orderly currency market: but following whose order(s)?

The US and Canada return from a long weekend to a trade war. Trump is threatening to ban US sales of Bombardier’s Canadian-built jets unless production moves south of the border; Canada is set to impose counter tariffs. Showing the direction of travel, the press announced Canada had resumed defense talks with China after an eight-year hiatus, which as one Korean paper puts it, “reflects [an] effort to diversify partnerships amid strained US relations and defence procurement shifts.” How would that work with NATO and the EU unless the latter is dominated by a Germany run by the pro-Beijing AfD? The symbolism, and stakes, matter far more than that benign action, but as the FT argues, Canada “is fated” to keep trying to strike a better deal with the US.

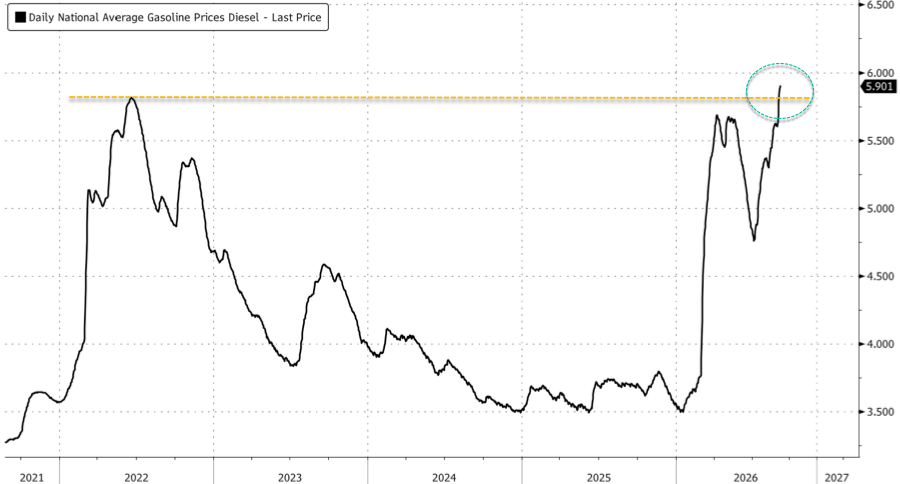
Oil is close to $100 as the Financial Times quotes traders that attacks on shipping and eroding inventories mean “something has to break” soon, and Qatar warned of an “industrial catastrophe” if this crisis continues – and in logistics, things can go non-linear. US diesel is already at a record high, and the Middle East press reports bunker fuel for ships is running out in some places. Tellingly, Japanese shipping companies are considering a return to sails and kites to cut fuel consumption. That fits given Letters of Marque are a thing again now.

Meanwhile, the Houthis struck Saudi Aramco facilities; the UN envoy warned of a wider conflict in Yemen; Israel hit Hezbollah after ceasefire violations; the IAEA’s Grossi said the inspecting body is “completely blind” on Iran’s nuke program; and Iran floated a Hormuz exclusion zone with Oman “in days”, as the Wall Street Journal claims its oil dollars are gone, plunging it “into crisis – and pushing it to escalate. Markets are starting to accept that disruption is going to linger well into 2027. The question is how much worse things could get as well as better.

In Russia, Trump’s peace envoys reportedly found that Putin was still unwilling to compromise on Ukraine, which is little surprise, despite their official statement that there was “movement” towards three-way talks, as Zelenskyy stated the US wants to explore Russia-Ukraine winter de-escalation steps – like stopping attacks on oil refineries(?) That’s as the EU is urging the UK, Canada, Japan, and Norway to “step up to the plate” on funding Ukraine as Kyiv faces a $27bn budget gap in 2026, as it puts €200m into Greenland to try to counter Trump’s approach – but protecting that territory from all interested parties will take many multiples of that sum annually. For its part, Russia just opened a road to North Korea border, showing how they are working more closely together.

In geoeconomics, China’s Huawei goes to trial in the US over sanctions and trade secrets eight years after the first allegations were made against it, as Brussels floated an EU ‘anti-China’ procurement rule where national capitals would be urged (is urging a rule?) to reduce their “strategic dependence” on Beijing when issuing public contracts. At the same time, Germany is reportedly worried that France’s Palantir rival risks creating a new dependency for it – on Paris.

Chinese export growth was a staggering 25% y-o-y in US dollar terms while imports were up 28.2%. The trade surplus rose again to a new record high of CNY809.3bn, up 11.9% y-o-y. We will have to wait to parse the detailed China-EU trade numbers ahead of the looming European decision on whether to start Trump-style trade protections vs. Beijing.

On top of all that, Trump posted a slew of messages, including: the ‘moon is ours’, meaning American; of himself in a spaceship; and of what claim to be proposed designs of a new Space Force uniform based on those from the 1997 movie ‘Starship Troopers’…

… which were based on those of the Wehrmacht, SS, and Gestapo as a more-is-more satire: the new look certainly smacks of Grand Moff Tarkin as much as Grand Macro Strategy.

Tyler Durden
Tue, 09/08/2026 – 09:50

Houthis Pummel Southwest Saudi Arabia With Ballistic Missiles, As Yemen Air & Ground War Erupts

0
Houthis Pummel Southwest Saudi Arabia With Ballistic Missiles, As Yemen Air & Ground War Erupts

The heaviest fighting since the Iran war began is taking place in Yemen currently, also involving significant overnight attacks on Saudi energy and military sites by the Houthis.

The Houthis have since unveiled new operations, in a Tuesday statement saying the Iran-aligned group is targeting critical Saudi oil and military infrastructure. Widely circulating local videos suggest the attacks on multiple sites were in some case simultaneous and overwhelming.

“In response to this brutal aggression and in confronting comprehensive escalation with comprehensive escalation, the YAF carried out a large-scale … operation, targeting Aramco facilities in Abha and Najran, the Economic City, Aramco in Jizan, and Khamis Mushait Air Base, using dozens of ballistic missiles and drones,” said the Houthi statement.

Yemen state media/The Independent: Smoke billows from burning trucks on Yemen-Saudi border after claimed Houthi attack

“The strikes, by God’s grace, were accurate and direct and caused significant damage to those facilities,” it added. 

The kingdom’s Energy Ministry has indeed acknowledged fires and operations stoppages at several sites as a result, as well as damage and injured personnel.

“Several energy sector facilities and installations in the southern region of the kingdom were targeted this morning,” the energy ministry stated.

“The attacks caused fires at several locations, leading to a temporary halt in some operations. Specialized field teams have begun containing the fires, securing the sites, and assessing the damage,” the statement said. Aramco sites have been targeted on multiple occasions this summer, resulting in operations halts, particularly at key sites near the Yemeni border. Damage is still being assessed at the Aramco Jisan oil facilities, which were targeted yet again.

Also military and supply missions were hit, with the Houthi statement also indicating the destruction of Saudi military equipment and convoys of Saudi-backed forces of the internationally-recognized government.

For anyone putting a lot of faith in those pipelines that bypass Hormuz…

“Arms trucks coming from Saudi Arabia were targeted and caught fire at the Al-Wadiah military camp,” the Houthis stated.

In response later on Tuesday, Saudi airstrikes have reportedly resumed on Yemen in the governorates of Al-Jawf, Al-Bayda, Ma’rib, Taiz, and Al-Hudaydah. Already the death toll is mounting from these renewed strikes:

Houthi rebels in Yemen accused Saudi Arabia of striking a prison on Monday in the country’s north, killing seven, including a child, as tensions escalate between the Iran-backed group and Saudi-backed Yemeni forces.

The strike on the Central Corrective Facility in the strategic city of Hazm in Jawf province also wounded at least seven people, including a woman, said Anees al-Asbahi, a spokesman for the Houthi-run health ministry.

The prison’s warden told the Houthi al-Masirah news channel 35 prisoners and a woman who was visiting her husband were trapped under the rubble.

The Saudi side has meanwhile said that dozens were injured in the Houthi attacks. Major General Turki Al-Maliki, spokesman for the Saudi-led Coalition Forces, blasted the new Houthi aggression as “dangerous” and “senseless” – and announced that at lest 73 people have been wounded, including women and children.

Both sides are now vowing escalation:

Houthi military spokesperson Brig. Gen. Yahya Saree accused Saudi Arabia of launching airstrikes and “committing massacres” in Jawf, as well as deploying a reconnaissance drone and supplying mercenaries with various weaponry.

“The ongoing Saudi aggression against Yemen will not go unanswered or unpunished,” he said.

The aerial war is additionally heating up: “Saree said later Monday that Houthi forces downed a total of four reconnaissance drones belonging to Saudi Arabia over the past 24 hours, including one that was spotted Monday morning in Bayda province,” as cited in The Associated Press.

Oil prices on world markets continue to steadily inch higher, rising more than 1% as a result of Tuesday’s Saudi-Yemen escalation.

The Saudi coalition says it aims to liberate the country’s capital of Sanaa from the Iran-backed rebels. “The decision has been made to retake Sana’a. There are surprises we will not reveal now,” the Deputy Defense Minister Major General Samir Al-Sabri told state-run Yemen TV.

The Yemeni army further released a statement saying that “From today, we declare that our goal is clear and unequivocal: to liberate Yemen from the grip of the terrorist Houthi militias and restore Sana’a as a capital for all Yemenis.“

This appears a return to the kind of bull-blown war in Yemen which marked the latter half of the last decade. But this time it’s more complicated and dangerous in terms of regional spillover, given it comes in the context of the Iran conflict, the Strait of Hormuz crisis, and Houthi efforts to close Red Sea shipping to the Saudis, Israelis, and their allies.

Below are more developments via Al Jazeera:

  • Saudi Arabia has carried out new attacks in Yemen against al-Jubah district in Marib, in the Houthi-controlled part of the country, according to a news report in Houthi-run media.
  • Forces loyal to Yemen’s internationally recognised government have launched a counteroffensive against the Houthi rebels, with officials saying they aim to recapture the capital Sanaa from the Iran-backed group.
  • The Houthis say they repelled an offensive in al-Jawf, and at least seven people were killed in an air strike on a prison in the town of al-Hazm, pledging that the “aggression will not go unpunished”.
  • Saudi Foreign Minister Prince ⁠Faisal bin Farhan Al Saud has described Yemen’s Houthi rebels as “selfish” for putting their own interests above the welfare of the country’s people. “The Houthis choose to prioritise their narrow interests over the interests of Yemen and resort to violence,” he said at a news conference in the Russian capital.
  • Russia’s Foreign Minister Sergey Lavrov has told his ⁠Saudi counterpart, Prince Faisal bin Farhan Al Saud, in Moscow that Russia is ready to help resolve the spiralling situation in the Middle ⁠East.

Saudi-led forces in Yemen bombed Al-Jawf Central Prison:

More Overnight News

via Newsquawk

  • US President Trump posted, “Oil prices will drop precipitously, like everything else is dropping (but more!), when we WIN the war with Iran. Three Dollars a gallon, but ultimately, below Two Dollars a gallon. It will all happen quickly, and Iran will never have a Nuclear Weapon. MAGA!”
  • Iranian President Pezeshkian said Iran has always opposed war but will continue to resist aggression with full force until the aggressors are made to regret their actions.
  • Iran’s top national security official Rezaei said Washington has received a clear warning from Iran’s new missiles and that economic warfare will be met with a maritime exclusion zone across the Persian Gulf to the blockade perimeter, while he added that the operational posture toward US warships and bases has been fundamentally recalibrated.
  • Tasnim analysis suggests that commentary from Iranian official Rezaei signals that Iran is considering expanding the geographic scope of its maritime confrontation into the northern Indian Ocean.
  • Saudi Energy Minister said a number of energy facilities and utilities were hit and that some operations have been temporarily halted. This was later confirmed by the Houthis, in which they added that they struck the Khamis Mushait Air Base in retaliation to recent Saudi airstrikes. The group warned that further attacks on Yemen will be met with broader strikes on Saudi.

Tyler Durden
Tue, 09/08/2026 – 09:25

“It’s Pretty Tight”: Vitol Chief Warns Of Global Fuel Squeeze As Refineries Max Out, Leaving Little Room For More Chaos

0
“It’s Pretty Tight”: Vitol Chief Warns Of Global Fuel Squeeze As Refineries Max Out, Leaving Little Room For More Chaos

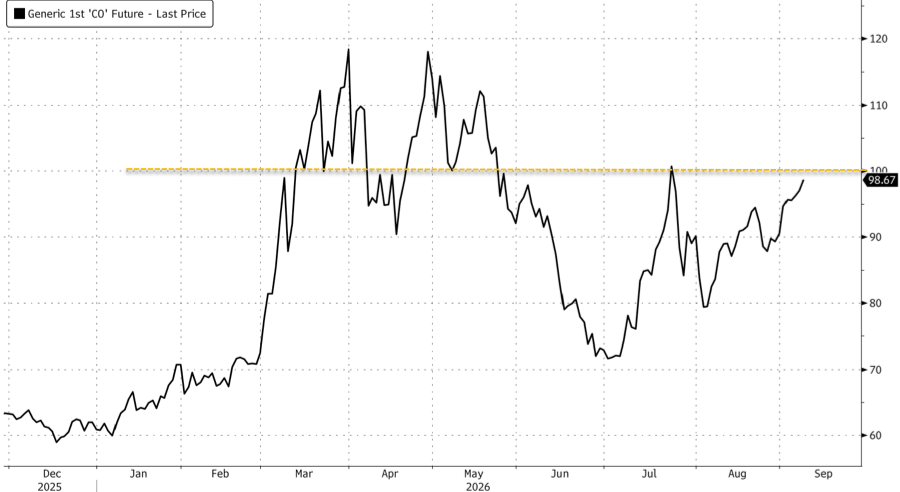
Geopolitical risks in the Gulf pushed Brent crude futures toward $100 a barrel overnight as Yemen’s Iranian-backed Houthi rebels launched new attacks on Saudi cities and economic infrastructure.

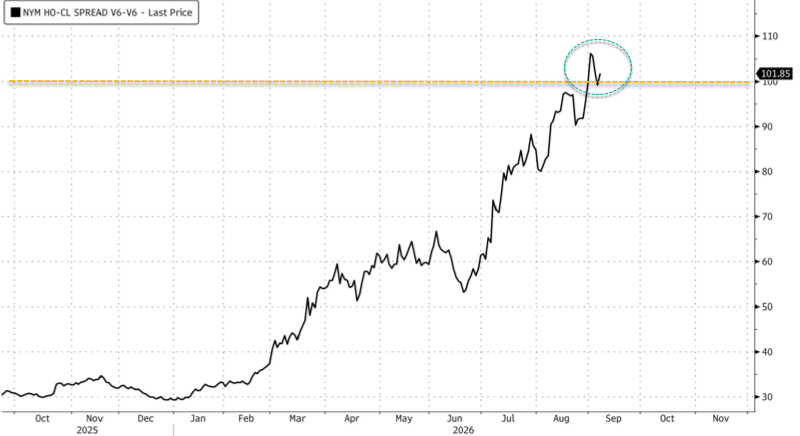
At 7:45 a.m. ET, the US diesel crack spread remained above $101 a barrel as severe tightness across the world’s refined-product markets continued, with a late-summer squeeze threatening to extend into fall and winter (twin crisis for Europe). 

Notably, the global industrial economy runs on usable fuels, particularly diesel, making refinery output and product availability super critical. Persistent disruptions through the Strait of Hormuz, Russian energy export restrictions, and Ukrainian drone strikes on Russian refineries have compounded the squeeze into crisis territory, leaving fuel markets vulnerable to further supply shocks.

Vitol CEO Russell Hardy was quoted by Bloomberg earlier today as saying the refined-product market is in turmoil.

Hardy, who runs one of the world’s largest energy traders, said that even as recovering tanker shipments through the Hormuz chokepoint ease pressure on crude supply, limited refining capacity leaves little room for further disruptions.

“It’s pretty, pretty tight and inflexible out there as far as the market is concerned,” Hardy told an industry conference in Singapore on Tuesday. He noted that product stockpiles are near their lows and continue to slide. 

Hardy warned that global oil-product stockpiles are “still drawing,” adding, “We’re still not running enough refining capacity to prevent those draws, and we keep eating into the surplus that exists around the world.”

The strain is particularly visible in the US. Just go to any gas station, and you can see the wide gap between 87-octane gasoline and diesel prices. Last week, diesel prices hit a record high nationwide.

Also in the US, distillate inventories, including diesel, are at their lowest seasonal level in at least 25 years despite high refinery utilization.

In Europe, gasoil futures have more than doubled this year, while Brent rose as much as 2.3% on Tuesday to $99.20 a barrel.

Vitol estimates Hormuz tanker flows stand around 10 million barrels a day, but Hardy cautioned that this volume “isn’t guaranteed to get out every day.” He said, “It depends on ships, it depends on insurance, it depends on captains and crew being in to do that difficult job.”

However, Goldman commodities strategist Yulia Zhestkova Grigsby and her team wrote in a note last week (read here) that Hormuz tanker flows were between 15 million and 16 million barrels per day, accounting for ships that switch off their Automatic Identification Systems to avoid detection by Iran.

Also at the conference, Mark Senn, senior vice president of global trading at US processor Phillips 66, warned, “We came into this shock with very little flex” in the refining system, adding that the US system is running at full capacity.

Tyler Durden
Tue, 09/08/2026 – 09:05

Futures Fall As Inflation Fears Mount With Oil Set To Top $100

0
Futures Fall As Inflation Fears Mount With Oil Set To Top $100

US futures fell as Brent crude approached $100 a barrel, chasing Shanghai crude which is now trading above $102, reinforcing expectations that central banks will have to raise interest rates to contain inflation while a key CPI print looms on Friday. As of 8:15am, S&P 500 futures were 0.3% lower while Nasdaq futures were fractionally negative after reversing an earlier rise. In premarket trading, Mag 7 stocks are mostly lower:

Stocks in Europe and Asia were also weaker. Brent traded around $99 after Saudi Arabia said operations at facilities in the kingdom’s south were halted by attacks. As discussed here, strong Chinese purchases added to tightness in oil markets. The dollar gained as the yen erased gains of as much as 1% deriving support from expectations of more restrictive Bank of Japan policy, which had pushed the USDJPY as low as 152, levels last seen in February.  Treasuries slipped ahead of a $58 billion auction of three-year notes. Today’s US economic data slate includes August NY Fed 1-year inflation expectations (11 a.m.) and July consumer credit (3 p.m.). Fed speaker slate is blank during Sept. 5-17 external communications blackout period around the Sept. 15-16 FOMC meeting.

In premarket trading, Mag 7 stocks are mostly lower: Nvidia +0.3%, Tesla +0.2%, Alphabet -0.7%, Apple -0.4%, Amazon -0.9%, Microsoft -0.8%, Meta Platforms -0.5%

  • Best Buy (BBY) slips 2% after DA Davidson cut the recommendation on the consumer electronics retailer to neutral, citing the stock’s valuation following a 35% year-to-date gain.
  • Bloom Energy (BE) rises 6% and Everpure (P) gains 2% after S&P Dow Jones Indices said the companies will join the S&P 500 Index.
  • Boston Scientific (BSX) slips 2% after the company said that the cyber attack that recently affected operations is likely to have a material impact on third quarter and fiscal 2026 results.
  • Herbalife (HLF) rises 7% after the maker of dietary supplements announced a $250 million share buyback.
  • Ionis Pharmaceuticals (IONS) falls 10% and Amgen (AMGN) slumps 5% after Novartis AG said its heart medication, pelacarsen, failed in a final-stage study.
  • Pharvaris (PHVS) soars 25% after a Phase 3 trial of its deucrictibant extended-release tablet for the prevention of hereditary angioedema attacks met its primary and secondary endpoints.
  • Rigetti Computing (RGTI) rises 5% after the quantum computing firm signed a $100 million pact with the US Department of Commerce to accelerate superconducting quantum computing R&D.
  • Roivant (ROIV) gains 20% after the drugmaker said a mid-stage study of its inhaled drug, mosliciguat, met its primary endpoint in the treatment for a lung disease.
  • Sigma Lithium (SGML) drops 16% after a Brazilian court ordered the suspension of all environmental permits for an operating subsidiary of the company and the complete halt of mining activities for the firm’s Grota do Cirilo lithium project.
  • Sweetgreen (SG) is up 5% after KeyBanc raised its recommendation on the salad restaurant chain to overweight, calling it a compelling turnaround opportunity.

In other corporate news, Brookfield landed a $1 billion commitment from the UK’s Nuclear Liabilities Fund to invest across several strategies, as the New York-based firm builds a new division that packages and sells multi-asset portfolios. Volkswagen is considering offloading motorcycle manufacturer Ducati as part of a sweeping overhaul of its portfolio. Novartis shares plunged after its del-desiran treatment for a muscle-wasting disease failed to meet the primary endpoint in a phase 3 trial; it’s the third drug setback in a week for the Swiss drugmaker.

Fear of upheaval in the Middle East is driving markets in the early part of a week that builds toward Friday’s US inflation print, data that may be decisive in whether the Federal Reserve raises rates or holds them steady this month. September hikes by the European Central Bank and BOJ are largely priced in.

“We are likely to be in some sort of period of digestion, because we are going through a pretty meaningful adjustment in terms of central bank policy around the world,” Anastasia Amoroso at Partners Group told Bloomberg TV. “So we might give a little bit of those gains back or at least some consolidation here.”

Stock futures are lower as traders return to their desks after the Labor Day holiday, with markets facing multiple tests including PPI and CPI prints, Oracle earnings and a conference season that includes tech events on both coasts. On top of that, a flare-up in Middle East hostilities and an escalating trade war between the US and Canada are adding risk.

As BBG notes, stocks have been trading sideways for a month, caught between strong earnings and mounting macro risks. Events like next week’s Fed decision carry binary outcomes that argue for some protection, according to today’s Taking Stock column. Fed officials have made it clear that Friday’s inflation print will be key for rates. While the bond market sees a 60% chance of a hike next week, such a move isn’t fully priced in until December. In fact, Fed funds futures signal the most uncertainty in years.

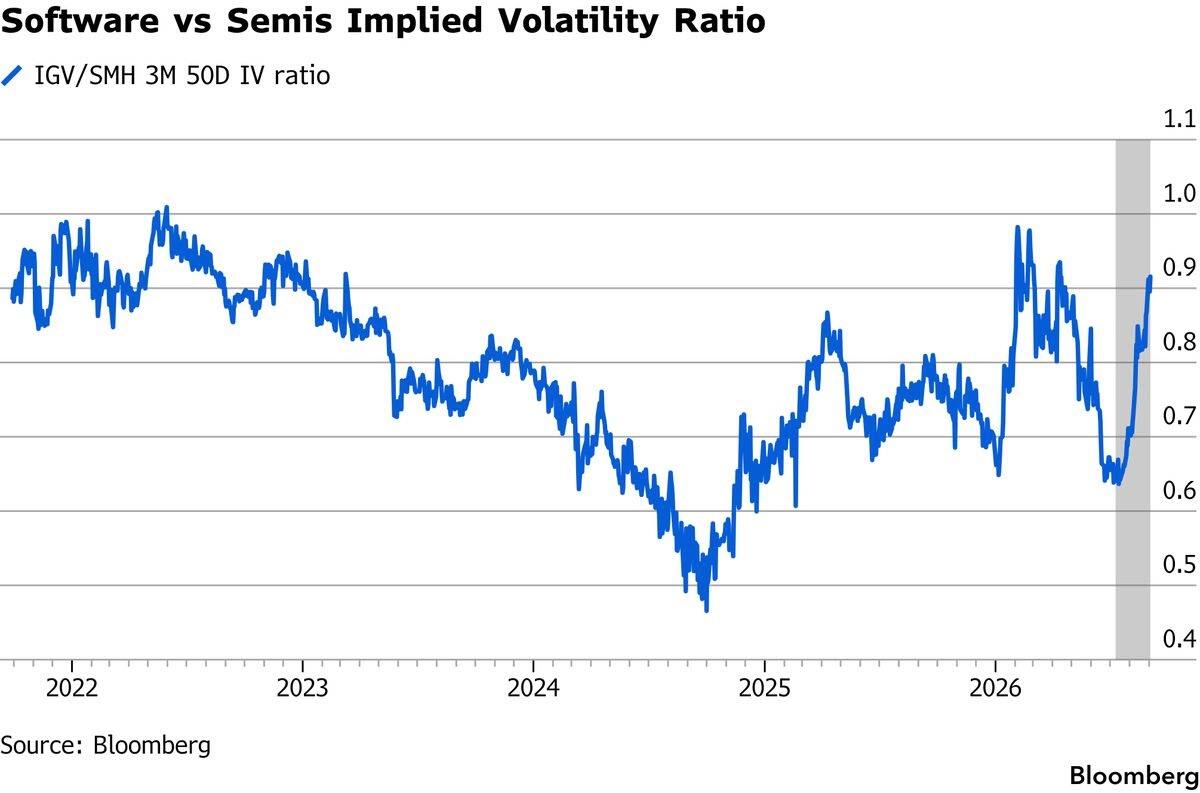
The tech trade is also in focus, with traders looking to Oracle earnings and conference comments for clues on current dynamics within the sector. Of note, software implied volatility has firmed up recently versus other areas of the tech complex. The implied volatility ratio of software vs semiconductors has been unstable this year as option volumes and open interest have exploded in both groups.

In AI, there’s been a rapid change in narrative around AGI, or Artificial General Intelligence. OpenAI’s rollout of GPT-6 on Thursday prompted Nvidia’s Jensen Huang to proclaim that “AGI has arrived,” sparking a renewed melt-up in Asian tech stocks and especially SoftBank which is a big backer of OpenAi. Still, the definition of AGI is nebulous, and not everyone is convinced. JonesTrading chief strategist Mike O’Rourke noted that the whole AGI conversation “was started by self-interested promotional individuals,” which damages credibility.

Elsewhere, ByteDance is readying an AI model geared for real-time spatial video generation, taking on Meta and Alphabet. An experimental lung disease drug developed using AI showed promise in reversing biological signs of aging. Anthropic is said to have walked away from $6 billion Decart purchase.

Global stocks may now be poised for a period of consolidation given the outlook for tightening, said Anastasia Amoroso, chief investment strategist at Partners Group. “We are likely to be in some sort of period of digestion, because we are going through a pretty meaningful adjustment in terms of central bank policy around the world,” Anastasia Amoroso at Partners Group told Bloomberg TV. “So we might give a little bit of those gains back or at least some consolidation here.”

Other assets have been active, with Yen strength triggering stop-loss orders, volatility gauges ticking up and copper hitting all-time highs. Oil prices are rising and Brent is grinding closer to $100/bbl after attacks halted several facilities in Saudi Arabia. That sent global bonds, European stocks, US futures and gold lower. German 10-year yields hit the highest since 2011, a UK 30-year sale is set for the highest borrowing costs since at least 1998, and Amazon has mandated banks for a four-part sterling-denominated sale.

Copper’s rally added to the inflationary pressure from commodities. The metal hit a record for a second straight session, with constrained near-term supplies and expectations of US tariffs on imports of refined metal buoying prices.

In geopolitics, Canada imposed tariffs of 15% to 50% on hundreds of products from the US, risking a wider trade war.  Trump threatened to bar Bombardier Jets, while the manufacturer noted it creates tens of thousands of US jobs.

The Stoxx 600 is falling by 0.4%, with health care the underperformer owing to a big drop for Swiss pharma group Novartis. Banks, insurance and tech stocks are weaker too. 

Asian stocks fell, reversing earlier gains, as inflationary concerns reemerged after oil prices neared the $100 a barrel level. The MSCI Asia Pacific Index retreated 0.9% after climbing as much as 0.6% earlier in the session. Japan’s Topix led declines as a sharp rally in the yen put downward pressure on exporters. South Korea’s Kospi closed lower, erasing gains of as much as 2.5% led by the tech sector. Stocks also fell in Hong Kong, Singapore, India and Australia.

“The catalyst for the turnaround is the news coming out of the Middle East that the Houthis have targeted more Saudi oil infrastructure,” said Tony Sycamore, analyst at IG Australia. “It’s all about oil being back in the driver’s seat.” There’s also fear of a “potential rate hike in America that’s kind of really pushing these Asian stocks,” said Sycamore.

In FX, the Bloomberg Dollar Spot Index is little changed while the yen has continued its rally to put its 2026 high in sight. USDJPY last traded around 154, erasing earlier gains having hit a session low of 152.89.

In rates, Treasuries hold small losses led by long-end tenors as US trading resumes after Monday’s holiday, pressured by Brent crude oil approaching $100 a barrel after Saudi Arabia said operations at several energy facilities were halted by fresh attacks. Supply considerations also are in play, including the 3-year note auction and anticipated seasonal rebound in corporate new-issue activity. Also, details of Thursday’s expanded Treasury buyback in the 10- to 20-year bucket are slated to be announced Wednesday, US long-end yields are about 2bp higher on the day with 2s10s and 5s30s spreads wider by around half a basis point. 10-year, higher by 1.6bp near 4.8%, lags bunds and gilts in the sector by 3bp and 2bp. Treasury issuance resumes with $58 billion 3-year new-issue auction at 1 p.m. New York time; $39 billion 10-year note and $22 billion 30-year bond reopenings follow on Wednesday and Thursday. WI 3-year yield near 4.47% is ~18bp cheaper than last month’s sale, which stopped through by half a basis point, and exceeds 3-year auction results since June 2024. IG dollar issuance slate already includes a handful of offerings; dealers expect a cumulative $70 billion this week and $215 billion this month, including at least one jumbo and capital-raising for AI data infrastructure.

Stretched positioning in bonds means that a short-term pullback in yields may be on the cards soon, noted Mohit Kumar at Jefferies International. A trigger could come from Friday’s inflation data or next week’s Fed decision, he said.

“If we do get a benign CPI print, which is our view, we could see a round of position covering, which would lead to a rates rally,” Kumar said. “Any pullback in rates is likely to support risky assets.”

In commodities, oil prices are rising and Brent is grinding closer to $100/bbl after attacks halted several facilities in Saudi Arabia. That sent global bonds, European stocks, US futures and gold lower. German 10-year yields hit the highest since 2011, a UK 30-year sale is set for the highest borrowing costs since at least 1998, and Amazon has mandated banks for a four-part sterling-denominated sale. WTI crude oil futures trade are up 2.5%, near session highs. Gold erased its rise too as oil prices rallied, falling below $4,400/oz.

Today’s US economic data slate includes August NY Fed 1-year inflation expectations (11 a.m.) and July consumer credit (3 p.m.). Fed speaker slate is blank during Sept. 5-17 external communications blackout period around the Sept. 15-16 FOMC meeting

Market Snapshot

Top Overnight News

  • The war in Iran has now cost U.S. consumers $100 billion in higher energy prices, and the bill is rising another $1 million about every two minutes, per a real-time estimate from Brown University as of Monday morning. Inflation shows up across the entire economy, and the recent surge in diesel prices threatens to have a dramatic impact on freight and travel in the weeks and months to come. Axios
  • Yemen’s Tehran-backed Houthis attacked four cities in the south of U.S. ally Saudi Arabia on Tuesday, wounding more than 70 people and setting oil installations ablaze in what appeared to be a major expansion of the six-month-old Middle East war. They used ‌drones and missiles to strike a Saudi airbase in the southern city of Khamis Mushait, and targets belonging to Saudi Arabia’s state oil company in nearby Abha, Najran on the Yemeni border and Jazan, a major Red Sea port city that houses a large refinery and power plant. Reuters
  • In offices across the military and in the intelligence community, there have been recent quiet discussions about cutting the number of people and facilities typically stationed in the Middle East if the Trump administration succeeds in ending the Iran conflict. CNN
  • New Canadian tariffs targeting roughly $20 billion in U.S. imports officially snapped into place on Tuesday, the latest escalation in an increasingly costly trade war that has ensnarled two longtime allies. NYT
  • Japanese workers’ nominal wages rose at the fastest pace in nearly three decades on the back of strong corporate earnings and a tight labor market, in data likely to keep the Bank of Japan on course for further monetary tightening. BBG
  • Two hawks on the Bank of Japan’s monetary policy board are calling more strongly for the central bank to accelerate its interest rate increases, pushing it to do more to rein in inflation before their terms end next July. Nikkei
  • China’s export growth accelerated in August, swelling its trade surplus near $806 billion for the year. Its surplus with the US surged almost 44% to more than $29 billion. BBG
  • China’s car exports stayed robust in August as BYD and ‌other automakers shipped a record number of vehicles overseas, in sharp contrast to a sluggish domestic market where their sales fell for the 11th month in a row. Passenger vehicle exports jumped 77.5% from a year earlier to 894,000 units in August, easing from an increase of 88.2% a month earlier. Reuters.
  • Goldman raised its oil price outlook by $5 a barrel, forecasting Brent at $85 by December and $80 in 2027 on expectations Middle East shipping disruptions will persist. BBG

Labor Day Recap

  • On the geopolitical front, the US launched strikes against three Iranian crude oil tankers on Saturday in retaliation for the IRGC targeting US Navy warships with ballistic missiles. Iran’s navy also said it targeted three oil tankers that were travelling through unauthorised routes in the Strait of Hormuz and three additional US vessels in other areas. Since the weekend, the Iranian Foreign Ministry Spokesperson said a deal with Oman regarding the Strait of Hormuz will be registered soon, while the FT reported that Saudi Aramco’s oil facilities in Jizan were hit, which caused upside in energy benchmarks.
  • European bourses were lower across the board, given the upside seen in energy benchmarks.
  • In the FX space, G10s were firmer against the greenback, with the JPY the clear outperformer, while the EUR was steady despite the AfD victory in Saxony-Anholt.
  • In the metals space, spot gold was choppy but was helped amid data from China that the PBoC boosted its gold reserves for a 22nd straight month.

A more detailed look at global markets coutesy of Newsquawk

APAC stocks traded mixed in the absence of a lead from Wall Street and as attention turned to several data releases from the region, including Japanese GDP and Chinese trade data. ASX 200 underperformed with sentiment not helped by a deterioration in the Westpac Consumer Sentiment and NAB Business Confidence surveys. Nikkei 225 was choppy amid recent currency strength and as the latest data, including upward GDP revisions and hot Labour Cash Earnings, solidified the case for a BoJ rate hike next week.
KOSPI outperformed on tech momentum and after South Korean GDP matched initial estimates. Hang Seng and Shanghai Comp were mixed as the Hong Kong benchmark was dragged lower by weakness in the local tech and biopharma stocks, while the mainland was kept afloat as participants digested the ultimately mixed Chinese trade data, in which Exports and Imports accelerated and continued to show strong double-digit percentage growth, but missed estimates.

Top Asian News

  • Japanese Finance Minister Katayama said they will bolster efforts to secure funding for a consumption tax cut on food and will communicate fully with markets and the public to gain credibility in their fiscal policy. Furthermore, she said they won’t comment on specific FX levels and there is no change to their forex stance since the Japan-US joint intervention, while they will closely communicate with the US to achieve orderly forex markets.
  • Japan LDP policy chief Kobayashi will retain post and Japan’s Ishin party seeks a special mission post in reshuffle, according to Japanese press.

European bourses are softer across the board, Euro Stoxx 50 -0.4%, with clear underperformance in the SMI, -1.4% (see Novartis below). The disappointing risk tone comes amid upside in energy prices. The Saudi Energy Minister said a number of energy facilities and utilities were hit, resulting in operations being temporarily halted. This was later confirmed in a Yemeni Houthis statement.
Sectors point to a mixed picture. Food, Beverages & Tobacco is the clear outperformer, with Optimised Personal Care and Chemicals rounding out the top 3 sector gainers. On the other hand, Health Care is the laggard, with Banks and Insurance completing the underperformers. Another setback for Novartis (-8.9%) this morning, after it announced that its del-desiran failed to meet the primary endpoints in its late-stage trial. Other key movers: Computacenter (-0.2%), strong H1 metrics and raises its FY26 outlook; Sandoz (+1.8%), confirms its 2028 outlook and set out new 2030 guidance and targets 100 biosimilars by 2040; Infineon (-3.6%), downgraded to equal weight at Morgan Stanley; Schneider Electric (-0.2%), downgraded to neutral at Santander.

Top European News

  • German Trade Balance (Jul) 21.3B vs. Exp. 16B (Prev. 15.4B).
  • German Exports (Jul MM) -0.8% vs. Exp. 0% (Prev. 0.9%).
  • German Imports (Jul MM) -5.7% (Prev. 4.4%).
  • French Trade Balance (Jul) -6.7B vs. Exp. -6B (Prev. -5.8B).
  • UK BRC Retail Sales Monitor (Aug YY) 0.5% vs. Exp. 1.2% (Prev. 1.0%).

FX

  • Snapshot: G10s are mixed against the USD. JPY continues to extend on recent strength, whilst the Kiwi is the clear underperformer this morning amidst the downbeat risk tone. Also factoring in is the mixed Chinese Trade data, which rose from the prior, albeit less than consensus.
  • DXY is incrementally firmer this morning, and holds within a 98.71-99.00 range. Overnight, the USD was mildly pressured, but then picked up in early European trade alongside a pick-up in yields. US-specific news flow has been lacking as participants return from holiday, but focus will be on trade updates between the US and Canada. On that note, Canada’s retaliatory tariffs against US goods took effect, as scheduled. The Loonie is a touch firmer vs USD this morning, but likely benefiting from the surge in energy prices rather than any trade-related optimism.
  • The Yen story remains much more pertinent for the USD. Recent thin liquidity (due to Labor Day) has allowed the JPY to take more ground against the USD, with USD/JPY briefly dipping below the 153.00 mark. The pair is now trading at levels not seen since early February of this year. As mentioned in Monday’s FX update, the recent hawkish BoJ repricing, potential intervention/rate check, and increased possibility of larger GPIF purchases have lifted the JPY over the past couple of weeks.
  • Also helping the outperformance today is the firmer-than-expected Labour Cash Earnings and an upward Q2 GDP revision. There were also comments from Japanese Finance Minister Katayama, who stated there was no change to their forex stance since the Japan-US joint intervention and that they will closely communicate with the US to achieve orderly forex markets.
  • EUR is a touch lower this morning, pressured by the ongoing strength in the energy space. The ECB will hike rates by 25bps this Thursday, though the outlook beyond September remains more uncertain. If oil prices continue to lift energy prices, and second-round effects begin to filter through into the Eurozone economy, another hike in December could be likely. The single currency currently holds around 1.1611, with the high of the day a couple pips above its 200-DMA (1.1633).

Fixed Income

  • Despite some slight respite being found overnight, fixed income is back in the red as energy extends to fresh highs and Brent surpasses the USD 99.0/bbl handle, bringing a return back to USD 100/bbl into view. As such, yields are bid across the globe and the curve, with the UK feeling this most keenly given its energy sensitivity and after AMZN filing for GBP-denominated issuance.
  • Continuing with Gilts, the benchmark opened higher by around 13 ticks, taking initial respite from the brief overnight pause and potentially reports that PM Burnham is set to meet with businesses next week to reassure them into the budget. However, that swiftly faded with Gilts now down by over 10 ticks and at an 85.56 base following the Amazon update. For the curve, the 2yr is 4bps higher at 4.61%, but off the 4.69% recent peak from last week. While the 10yr is c. 3bps higher, and similarly off last week’s 5.29% near 20yr peak.
  • Bunds lower, by about 10 ticks at the time of writing and just off worst in 121.65-95 confines. Pressure a function of the discussed energy upside on Saudi and Houthi updates this morning (see Commodities/headline feed). For Germany, the docket features Green supply which should pass without issue. More pertinently, we continue to await a concrete response from Chancellor Merz on the strength of AfD, something that will become increasingly acute into more regional elections this month. Before that though, the ECB looms on Thursday, and while a 25bps hike is all but priced, the market will be keenly attentive to any dovish/hawkish signal from the statement/forecasts/presser, particularly at the short-end of the curve.
  • USTs are also under pressure on the resumption of cash trade after the US holiday on Monday. Currently, it finds itself lower by a handful of ticks and at a 107-09+ base, approaching Monday’s 107-08 trough. The docket today features supply and updates from President Trump as the scheduled highlights; though, geopolitics may well dominate.
  • Amazon (AMZN) to sell GBP-denominated bonds; 3yr, 6yr, 12yr & 19yr.
  • Germany sells EUR 1.374bln vs exp. 1.5bln 2.30% 2033 and 2.60% 2041 Green Bund.
  • Japan sells JPY 1.9tln 5-year JGBs; b/c 3.42x (prev. 4.15x), average yield 2.239% (prev. 2.020%), Tail in price 0.04 (prev. 0.02).
  • The Netherlands sells EUR 3bln vs exp. 2.5-3bln 2.75% 2036 DSL: Avg. yield 3.463% (prev. 3.206%).
  • Australia sells AUD 400mln in 5.00% June 2036 Bonds: b/c 5.76x, avg. yield 5.1874%.

Commodities

  • Firmer trade across energy once again as geopolitical tensions remain high, and with hardly any signs of peace between the US and Iran (more details below). WTI Oct resides towards the top of a USD 90.87-94.73/bbl range (vs Friday’s USD 88.72-92.17/bbl band), while Brent Nov sits towards the upper end of a USD 96.78-99.46/bbl range (vs yesterday’s USD 95.97-98.06/bbl band). Dutch TTF front-month resides just above the EUR 74/MWh mark after finding earlier support at EUR 73/MWh and then resistance at EUR 74.50/MWh.
  • Precious metals are subdued as higher energy prices keep the USD underpinned. Spot gold resides towards the bottom of a USD 4,388-4,443/oz range (vs yesterday’s USD 4,381-4,435/oz band), while spot silver sits towards the lower end of a USD 65.69-67.19/oz range (vs yesterday’s USD 65.40-66.74/oz band).
  • Base metals are mostly firmer despite the aforementioned crude prices and effect on the USD, with supply concerns and tariff fears cited by desks, alongside ongoing hopes of Chinese stimulus. 3M LME copper resides near record highs in a current USD 14.51k-14.64k/t range.
  • In terms of the main geopolitical updates, Iran warned that economic warfare will be met with a maritime exclusion zone from the Persian Gulf to the blockade perimeter, and said it has the ability to strike ships participating in the US blockade. Further, Yemeni forces launched ballistic missile and drone attacks on targets in Saudi Arabia, including around Khamis Mushait, Abha airport and King Khalid Airbase. Houthi spokesperson warned that further attacks on Yemen will be met with broader strikes on Saudi Arabia. Saudi Energy Minister confirmed that several energy facilities and utilities were hit; are temporarily halting some operations. Further, Tasnim analysis suggests that recent Iranian commentary indicates that Iran is considering expanding the geographic scope of its maritime confrontation into the northern Indian Ocean.
  • Iraqi Oil Minister said they will soon announce refinery development and construction opportunities for investors.
  • Russia’s Kremlin spokesperson said cooperation between India and Russia on rare earth explorations are being discussed.

Trade/Tariffs

  • Canada’s retaliatory tariffs against US goods took effect, as scheduled.
  • US President Trump called for a stop to US sales of Canada’s Bombardier aircraft.
  • Japanese Chief Cabinet Secretary Kihara said China’s anti-dumping move targeting Japan defies practice and they will act to prevent an undue impact from China’s actions.

Central Banks

  • RBA’s Hauser said that the RBA stands ready to raise rates again if needed, the question is whether more is needed on interest rates.
  • RBA’s Assistant Governor Hunter said the board is concerned about inflation and has low tolerance, adding the board may have to raise rates if there is a sense inflation will be stronger.

Geopolitics: Middle East

  • US President Trump posted, “Oil prices will drop precipitously, like everything else is dropping (but more!), when we WIN the war with Iran. Three Dollars a gallon, but ultimately, below Two Dollars a gallon. It will all happen quickly, and Iran will never have a Nuclear Weapon. MAGA!”
  • Iranian President Pezeshkian said Iran has always opposed war but will continue to resist aggression with full force until the aggressors are made to regret their actions.
  • Iran’s top national security official Rezaei said Washington has received a clear warning from Iran’s new missiles and that economic warfare will be met with a maritime exclusion zone across the Persian Gulf to the blockade perimeter, while he added that the operational posture toward US warships and bases has been fundamentally recalibrated.
  • Tasnim analysis suggests that commentary from Iranian official Rezaei signals that Iran is considering expanding the geographic scope of its maritime confrontation into the northern Indian Ocean.
  • Saudi Energy Minister said a number of energy facilities and utilities were hit and that some operations have been temporarily halted. This was later confirmed by the Houthis, in which they added that they struck the Khamis Mushait Air Base in retaliation to recent Saudi airstrikes. The group warned that further attacks on Yemen will be met with broader strikes on Saudi.

Geopolitics: Russia-Ukraine

  • Russia’s Defence Ministry said Russian forces struck energy infrastructure and drone-manufacturing facilities in Odessa and the Odessa region.
  • Russian Foreign Minister Lavrov rejected a proposal to halt strikes on civilian supply vessels in the Black Sea, Interfax reported.
  • Ukrainian President Zelensky said he hopes to meet US President Trump later in September to discuss the winter air defence package.

Crypto

  • Bitcoin has extended on Monday’s losses and currently trades at the lower end of its USD 78.2k-USD79.5k range.
  • Republican senators have suggested that the bipartisan crypto regulatory bill is likely to fail next week, Semafor reported.

US Event Calendar

  • 6:00 am: United States Aug NFIB Small Business Optimism, est. 99.3, prior 99.8
  • 11:00am: NY Fed 1-Yr Inflation Expectations, est 3.60%
  • 3:00pm: Consumer Credit

DB’s Jim Reid concludes the overnight wrap

Today kicks off the “home straight” to the end of the year after yesterday’s Labor Day holiday where markets were understandably quiet with what focus there was on oil and German politics. Brent (+0.75%) continued to edge higher which helped the 10yr bund (+4.8bps) close at another post-2011 high of 3.39% with equities fairly subdued. US equity futures have just ticked very slightly into positive territory this morning after being slightly below for most of the session yesterday when the cash market was closed. Elsewhere the Yen is up half a percent to 153.52 and to the highest level since February.

This has likely been helped by Japan’s real wages increasing by +2.4% year-on-year in July, exceeding expectations of +1.8% and marking the strongest growth since May 2021. This also represents the seventh consecutive month of wage gains, indicating a gradual improvement in income trends. Meanwhile, total cash earnings rose +4.7%, the largest increase since January 1997, accelerating from a revised +4.0% increase in June. The stronger-than-expected wage data reinforces the overwhelming case for the Bank of Japan (BOJ) to raise interest rates at next week’s policy meeting, following its previous hike three months ago, and supports the prospect of further monetary policy tightening in the months ahead. Q2 GDP has also been revised up overnight, moving from 1.1% annualised to 1.4%. However, expectations were at 1.8%.

In the rest of Asia, the KOSPI (+1.54%) is being driven by the tech rebound again, while the Nikkei is close to flat. The Hang Seng (-0.27%) and Shanghai Comp (+0.32%) are moving in different directions with the ASX (-0.84%) the largest decliner. 

In a low energy 24 hours the Middle East story has rumbled on as concerns about fresh US-Iran hostilities pushed oil prices higher still. In part, that followed the tanker attacks over the weekend, but it was also reported that the Houthi rebels had hit Saudi Arabian oil infrastructure yesterday. So that helped push Brent crude (+0.75%) to a 6-week high of $97.00/bbl, with WTI also up +1.33% to $92.70/bbl. Brent is up another +0.62% this morning. And there was no sign of respite on the gas front either, with European natural gas futures (+1.93%) also rising back to €73.34/MWh. So that exacerbated fears about European inflation, with the 1yr Euro inflation swap (+10.6bps) up to its highest level since May 2026, at 3.37%. 

With inflation fears mounting, that lifted European bond yields across the continent. So by the close, the German 2yr yield (+5.6bps) was back up to 3.00%, which is its highest level since June 2024. And further out the curve, the 10yr yield (+4.8bps) was up to a post-2011 high of 3.39%. Moreover, those moves were echoed elsewhere, with yields on 10yr OATs (+5.5bps), BTPs (+5.6bps) and gilts (+4.2bps) all rising as well. 

That rise in yields came as traders grew increasingly confident in future ECB rate hikes this year. In fact, investors were pricing 48bps of further hikes by the ECB’s December meeting at the close, up +2bps on the day. And as a reminder, our own European economics team also revised their ECB forecasts last week, so they expect the ECB to hike this week, and follow that up with another hike at the December meeting. See here for more on their view.  

Amidst all that, European equities were fairly steady, despite the rise in energy prices and the slightly hawkish rates repricing. The STOXX 600 ultimately closed up a whisker (+0.003%), with gains for France’s CAC 40 (+0.33%), alongside declines for the FTSE 100 (-0.08%) and the DAX (-0.15%). Sentiment was bolstered by positive revisions to the Q2 GDP numbers in the Eurozone, which were revised up to a +0.6% print from +0.4% at the preliminary reading. However, there was some weakness in Germany, where data showed industrial production fell -1.1% on the month (vs. +0.2% expected). 

Staying on Europe, German politics remained front and centre yesterday after the AfD came first in Saxony-Anhalt’s state election, winning 43.8% of the total votes, and just a few seats short of an absolute majority. Following the result, Chancellor Merz said in a press conference that he would double down on the reform course, with no indication of planned changes despite Merz saying he was “deeply shocked” by his CDU’s weak performance.

Early morning data from China indicated continued strength in trade activity, providing support for economic growth despite uneven domestic demand. Exports surged +25.0% y/y in August (v/s +25.9% expected), accelerating from +23.9% in the previous month. Imports also remained robust, rising +28.2%, up from a revised +27.6% previously, although slightly below forecasts for a +31.0% increase. As a result, China’s trade surplus expanded to $119.09 billion, compared with $112.34 billion in the prior month and broadly in line with market expectations of $119.10 billion.

Finally on the inflation theme, copper hit an all-time high (+0.57%) on the London Metal Exchange yesterday, rising above $14,415 per ton. That comes amidst ongoing supply concerns, and the prospect of potential US tariffs on copper. So one to watch going forward.
Finally in another research advert, Henry published his latest market dislocations report yesterday. This month, he looked at why the current cross-asset equilibrium remains unsustainable, and how several asset classes are vulnerable to the impact of building inflationary pressures and a faster tightening cycle from central banks. See the full report here.

Looking at the day ahead, US markets are back open with the NFIB’s small business optimism index for August, the NY Fed’s Survey of Consumer Expectations, and July consumer credit data releases. In Europe, we’ll also get Germany’s July trade balance and France’s July current account. Finally, Canada’s counter-tariffs on US imports are set to enter force today
Tyler Durden
Tue, 09/08/2026 – 08:40

Europe’s Von der Leyen Wants To Put Private Bank Deposits Under State Direction

0
Europe’s Von der Leyen Wants To Put Private Bank Deposits Under State Direction

Submitted by Thomas Kolbe

How will we deal with private property in Europe in the future?

A highly complex debate follows from this question, one that European Commission President Ursula von der Leyen interpreted in her own very particular way on Friday. In a speech to French business leaders at the MEDEF’s La Rencontre des Entrepreneurs de France in Paris, the former defense minister talked about using EU citizens’ bank deposits to get the ailing eurozone, the European economy, back on its feet.

An unmistakable message: In the view of the EU’s chief Eurocrat, private property as a protective wall shielding citizens from an overreaching state has served its purpose as a pillar of civilization.

Central planning, subsidy madness – this is Brussels under the magnifying glass.

Certainly: In the face of towering government debt and capital flight from the old continent, in whose wake thousands of patents and tens of thousands of highly qualified professionals are being swept away, citizens’ wealth is bound to awaken political appetites. A ruthless expropriation or the decreed redirection of cash, as the finest bureaucratic German puts it, is supposed to solve the problems Brussels itself has caused through its stubborn climate policy, its overregulation and its continuing insanity of interventionism.

Von der Leyen was explicit before the business leaders: Europe has savings, she said, but unfortunately those savings are sitting on the sidelines. Ten trillion euros are sitting as cash savings in the hands of private households in bank accounts, lectures von der Leyen in the manner of a classic central planner who can no longer take her eyes off citizens’ wealth. The European economy must now put this capital to work for its companies, the chief bureaucrat decreed.

None of this merely sounds like Erich Honecker. Von der Leyen is increasingly turning into a socialist sister in spirit to this disastrous regime.

Von der Leyen is following the path of the German chancellor. Friedrich Merz, too, discovered the cash holdings of Germans as political capital for himself more than a year ago – thoroughly socialist, indeed almost dictatorial, the chancellor also pointed to the possibilities opened up by what he called an activation of this money.

Ursula von der Leyen and Friedrich Merz reveal not merely an ethical and ideological abyss; they are contemplating dictatorial control over the private wealth of citizens who are still sovereign.

Almost tragically comical is the economic ignorance of these two political protagonists of an EU that is now openly turning toward an illiberal ideology.

Bank deposits are by no means useless cash. From the perspective of the banking sector, customer deposits are a central source of refinancing and liquidity, embedded in the money and credit cycle and enabling the provision of loans. Bank credit in the modern monetary system does not simply arise from passing on existing deposits. Commercial banks create new bank money through lending, although this process cannot simply be understood as a mechanical “leveraging” of existing deposits. Customer deposits thus fulfill numerous functions, from private liquidity planning and cash holdings to the financing and management of banking processes.

Such a massive intervention in the highly complex and fragile liquidity and credit structure of the banking sector would not merely be a barbaric act of socialism – it would be a frontal assault on the functionality of the banking system as such.

Nevertheless, the EU will resort to massive interventions – financially, after all, they have run into a wall.

Starting in 2028, repayment of the €800 billion Eurobond “NextGenerationEU” will come due. Von der Leyen’s speech before business leaders was ostensibly directed at the private sector, but in reality it concerned the financing of the European debt club, which is now moving toward tapping every financial source that can help keep the Ponzi scheme of European credit alive – the activation of cash appears to be one of those sources.

France is caught in a debt spiral, with new borrowing amounting to 5.7% of GDP this year and a parliamentary deadlock that rules out any form of fiscal consolidation.

Germany, too, will post new borrowing of more than 5 percent next year if the municipal deficit, the special funds and the social insurance funds are included – making common financing through Eurobonds, the consolidation of the mountain of debt under the roof of the European Commission and under the active liquidity assistance of the ECB increasingly likely.

And here the circle closes.

While capital is leaving the old continent through every remaining, every still-open channel, the financial needs of the EU’s ideological grand experiment and its nation-states are growing beyond measure.

The green subsidy machine alone destroys billions year after year. The final push over the economic cliff, however, will come from Europe’s rediscovered appetite for militarism. Military Keynesianism is not, however, an economic alternative to the free market. It is merely another fiscal grave that the political leadership is digging in its panic in these months.

The following final chapter is essentially known: Brussels will opt for massive capital controls.

The framework for this is already taking shape: In two years, the digital euro is to be introduced, initially as a pilot phase and, almost certainly at a later stage, as a monetary standard that will allow Brussels to exercise complete control over transfers abroad.

A ban on foreign bank accounts for EU citizens is also on the table and is being introduced step by step, just like the digital ID and the harsh regulation of the crypto sector. Slowly but steadily, the gates are closing.

Basically, this is how it always works in socialism: One day, the central planners will run out of other people’s money. Only then does the grinding machinery of repression by the powerful central authority begin.

* * * 

About the author:  Thomas Kolbe, a German graduate economist, has worked for over 25 years, he has worked as a journalist and media producer for clients from various industries and business associations. As a publicist, he focuses on economic processes and observes geopolitical events from the perspective of the capital markets. His publications follow a philosophy that focuses on the individual and their right to self-determination.

Tyler Durden
Tue, 09/08/2026 – 07:20

Europe Finally Gets Its Own SpaceX Challenger As Isar Reaches Orbit

0
Europe Finally Gets Its Own SpaceX Challenger As Isar Reaches Orbit

At 10:12pm local time on Saturday, a 92-foot rocket built by Munich startup Isar Aerospace lifted off from a windswept island above the Arctic Circle and reached orbit,  where it deployed five small satellites into a roughly 500-km orbit on what was only its second flight, making it the first commercial European company to deliver payloads to orbit and the first successful commercial orbital launch from continental Europe. 

Isar Aerospace’s Spectrum rocket takes off from the Andøya Spaceport in Norway on Sept. 5. Source: Isar Aerospace

Readers may recall how the first attempt went. As we noted in March 2025, Spectrum’s maiden flight lasted about 30 seconds before the rocket flipped over and dropped into the sea in a fireball. The post-mortem, per NASASpaceflight: a vent valve popped open at T+25 seconds during the pitch-over maneuver, the vehicle lost attitude control, and the flight termination system cut all nine engines at T+30. Isar went back to the drawing board, rewrote the software, and widened the vehicle’s margins.

According o European Spaceflight, the 2026 campaign was not a smooth affair: January, scrubbed for a pressurization valve. March, delayed by weather, then scrubbed when an unauthorized boat wandered into the maritime exclusion zone. April, a leak in a composite pressure vessel. June, “off-nominal behaviour” in the fluid systems. September 4, called off hours after the road closures went into effect. September 5, orbit.

On Sunday their Spectrum rocket finally reached orbit. 

CEO Daniel Metzler said in a statement that Europe now has sovereign access to space, and that vehicle launches remain “the largest bottleneck for the global space industry.”

Welcome To The Big Leagues

In response to the launch, Berlin, Brussels, Paris and Oslo all rushed out excited statements on Saturday night – which come after a series of dismal European ‘failures to launch’ (both literal and figurative).

Between 2022 and 2024, Europe lost access to Russian Soyuz after the Ukraine invasion, grounded the medium-lift capable Vega-C after a December 2022 failure, retired Ariane 5, and watched Ariane 6 slip four years past its planned 2020 debut. The upshot: Galileo, the navigation constellation Europe built specifically so it wouldn’t have to depend on America’s GPS, went up on a Falcon 9 in April 2024 under a €180 million contract with SpaceX, alongside ESA’s Euclid telescope, the EarthCARE climate satellite and the Hera asteroid mission. European officials “studiously avoided” mentioning which rocket had carried them.

In 2025, Europe managed seven orbital launches: four Ariane 6 and three Vega-C, all from French Guiana. The United States did 193. China did 93. SpaceX alone flew 165 Falcon 9 missions, roughly one every 2.2 days, with individual boosters now on their 32nd flight.

ESA’s answer was the European Launcher Challenge: rather than build yet another agency rocket, pay commercial upstarts to prove they can reach orbit by the end of 2027, then buy launches from the survivors through 2030. Member states were so keen that at last November’s ministerial in Bremen they more than doubled the €420 million ESA had asked for, subscribing €902 million inside a record €22.07 billion three-year budget. Isar signed its €197.8 million contract on August 27, nine days before clearing the first milestone more than a year ahead of the deadline. Rocket Factory Augsburg (€186.9 million) and Spain’s PLD Space (€158.9 million) got the other two contracts; ArianeGroup’s own MaiaSpace was conspicuously left waiting, and Britain’s Orbex went into administration in February, leaving the UK’s contribution unassigned.

Timing… 

The launch landed four days before Emmanuel Macron opens his international space summit in Paris on Wednesday, a two-day affair whose stated theme is European sovereignty in space, and which SpaceX, Blue Origin, Stoke Space and Starcloud pulled out of last Thursday after a White House Office of Science and Technology Policy official told U.S. companies on a private call, per Politico, that attending “could look like tacit support for EU policy positions.”

The policies in question: the EU Space Act, which would require any operator serving EU users to obtain prior authorization and appoint an EU legal representative, and a Franco-German push to carve out more satellite spectrum for European operators, including the €10-billion-plus IRIS² constellation. That is to say, for someone other than Starlink.

The French research ministry said it was “difficult not to link” the cancellations to the reports of pressure; an Élysée official shrugged that it was the absentees’ loss. Chinese delegations are expected to fill the empty chairs. And in a detail that undercuts the drama somewhat, the same American companies are due back in Paris a week later for World Space Business Week, where they will presumably be happy to sell to the Europeans they declined to meet.

So: Washington leans on its rocket companies to boycott a summit about Europe not depending on American rocket companies, and 96 hours before it opens, a German rocket reaches orbit from Norway. You could not script it.

Funding Fuels Flight

In the 17 months between fireball and orbit, Isar says its demand flipped from almost entirely civil to roughly 60% defense, with the manifest now booked through 2028. German Defense Minister Boris Pistorius toured the Ottobrunn factory in July to reiterate the €35 billion Germany intends to pour into space over the coming years, calling it “an indispensable security domain that cannot be replaced.” Chancellor Friedrich Merz visited the Andøya pad in March and on Saturday called the launch “the beginning of a new era.” EU defense and space commissioner Andrius Kubilius chimed in from Brussels along the same lines. Norway’s trade minister cast it as a matter of Norwegian and European security; Oslo has already contracted Spectrum to launch two Arctic Ocean surveillance satellites by 2028.

Isar’s Spectrum rocket rolls out to its launch pad in Norway. Credit: Isar Aerospace

The NATO Innovation Fund made Isar its first-ever investment in a launch provider in 2024. State-owned KfW Capital co-invested in June’s €270 million Series D, which valued the company at roughly €2 billion and took total funding to about €870 million alongside Lakestar, HV Capital, UVC Partners, Molten Ventures, Island Green Capital, Airbus Ventures, Porsche SE and Eldridge. And on the day NATO leaders gathered in Ankara in July, Isar signed a 10-year, roughly $112 million deal for a dedicated pad at Spaceport Nova Scotia, pitched explicitly as sovereign access for Canada, with first launches targeted for 2028.

Chief commercial officer Stella Guillen told CNBC on Monday that the industry is “desperate” for launch capacity and that Isar’s pipeline now exceeds €10 billion ($11.6 billion). CNBC noted the company did not immediately clarify how much of that is actually under contract. Metzler, for his part, told reporters an IPO is not being considered.

Spectrum lifts up to 1,000 kg to low Earth orbit (700 kg to sun-synchronous), roughly a twentieth of a Falcon 9, and it is fully expendable; Isar has signaled reusability only for later versions. Its long-advertised target of about €10,000 per kilogram sits above the $5,000 to $7,000 per kilogram SpaceX charges on Transporter rideshares, though those prices have been climbing and the slots are getting scarcer as Kuiper, Chinese constellations and military customers eat the manifest. Isar’s pitch is that governments will pay a premium for a dedicated ride to a specific orbit on a rocket built and launched inside NATO territory. Saturday’s payloads, for what it’s worth, were DLR competition winners flying on ESA’s dime, not paying customers.

Right now, Spectrum vehicles 3 through 7 are in production, and the new 40,000 m² factory at Parsdorf is meant to eventually turn out 40 rockets a year, a figure that would put a company that has flown twice at roughly a quarter of SpaceX’s 2025 cadence.

Tyler Durden
Tue, 09/08/2026 – 06:55

Bolsonaro Leads Socialist Lula As “Huge Bet” On Right-Wing Victory Fuels Brazil ETF Options Frenzy

0
Bolsonaro Leads Socialist Lula As “Huge Bet” On Right-Wing Victory Fuels Brazil ETF Options Frenzy

Summary:

  • “Explosive Surge” in iShares MSCI Brazil ETF (EWZ) call open interest
  • BTG Pactual/Nexus Survey Shows Bolsonaro Leads Over Socialist Lula 
  • UBS Calls Brazil Election “Extremely Close” – Bolsonaro Win Would Cement LatAm’s Political Shift

The BTG Pactual/Nexus survey released earlier today puts right-wing Senator Flávio Bolsonaro narrowly ahead of socialist President Luiz Inácio Lula da Silva, though within the margin of error, as a deepening Supreme Court scandal strengthens the conservative challenger’s campaign.

At the center of the political turmoil is Justice Alexandre de Moraes, who oversaw the case that sent former President Jair Bolsonaro to prison for plotting a coup. Newly published private messages, according to Bloomberg, suggest closer ties between Moraes and Daniel Vorcaro, the former owner of failed lender Banco Master, which is under investigation for fraud.

“Anyone who votes for Lula is voting for Alexandre de Moraes,” Bolsonaro recently told supporters.

Polymarket odds for next month’s Brazilian election show the gap between Bolsonaro and Lula narrowing dramatically.

Overnight, we ​​​​​​showed an “explosive surge” in iShares MSCI Brazil ETF (EWZ) call open interest.

“The Brazil FOMO is real,” The Market Ear wrote on X. 

A Bolsonaro victory would reinforce South America’s broader shift from unhinged left-wing regimes toward the common sense right.

UBS Calls Brazil Election “Extremely Close” – Bolsonaro Win Would Cement LatAm’s Political Shift 

Socialist Brazilian President Luiz Inácio Lula da Silva’s polling lead over right-wing Senator Flávio Bolsonaro has eroded in recent weeks, leaving both statistically tied in UBS’ latest runoff polling average. 

Arend Kapteyn, UBS’ global head of economics and strategy research, described the upcoming election in early October as “extremely close” in a note to clients on Monday.

Lula (Left); Bolsonaro (Right)

Kapteyn’s note today puts Bolsonaro at 50.4% in a hypothetical runoff, against 49.6% for Lula, adding that the narrowing spread leaves the candidates statistically tied. 

Kapteyn continued:

On 4 October, Brazilians will vote for a president, the entire Chamber of Deputies and two-thirds of the Senate. Brazil currently has one of the highest real interest rates in the world, contributing to increasingly adverse debt dynamics. In our view, an election outcome that delivers a credible fiscal consolidation program could significantly improve the macroeconomic outlook. Relative to our baseline, real interest rates could fall by at least 2.5 percentage points (to around 5% from 7.5%), potential growth could be 1pp higher (2.5% rather than 1.5%), and inflation could be around 1pp lower (3.5% rather than 4.5%).

Our poll aggregator currently shows first-round voting intentions of 42.5% for Lula and 36.0% for Flávio Bolsonaro. Given the historical polling error of approximately 3 percentage points, the candidates’ confidence intervals overlap. Rejection rates are elevated for both candidates, while other contenders collectively attract 21.5% of voting intentions. If no candidate secures an outright majority in the first round, a runoff will be held on 25 October.

The second round appears even tighter. Lula currently polls at 49.6% of voting intentions versus 50.4% for Flávio. Compared with our poll update a week ago, the lead has effectively changed hands. Importantly, these surveys were conducted before the latest controversy involving a Supreme Court justice, who is alleged to have advised an individual under fraud investigation, a case that could potentially implicate key allies within Lula’s inner circle.

Historically, incumbent presidents have generally secured re-election when their “good or great” approval rating exceeded 40%. Lula currently stands at 37% on this measure. Conversations with two political consultants also suggest that momentum may be shifting in Flávio’s favor. Nevertheless, prediction markets continue to assign Lula a modest advantage. Polymarket implies odds of roughly 55%-43% in Lula’s ffavor while Kalshi places the race at approximately 55%-44%.

Polymarket Odds:

Read:

The election may determine whether Brazil moves further left or right politically. Across the continent, the latest country to shift right was Colombia. Many others have followed:

By mid-2026, South America had already flipped. Argentina (Milei), Chile (Kast), Colombia (de la Espriella), Peru (Keiko Fujimori), Ecuador (Noboa), Bolivia (Paz), and Paraguay (Peña) sit on the right.

The remaining large left-wing governments are Brazil and Uruguay. Brazil accounts for about half of South America’s GDP and population. If Brazil goes right, the region would be entirely aligned with the Trump administration and would be on track to rid itself of nation-killing socialism and other failed progressive experiments.

In Germany on Sunday, right-wing Alternative für Deutschland delivered its strongest election result ever in Saxony-Anhalt, dealing a sharp blow to the political establishment. Nomura analysts indicate that Europe may be in the early stages of “lurching right” (read the report).

Putting this all together, Western voters are rejecting nation-killing left-wing regimes that have done nothing more than allow mass migration, pursue progressive experiments, and neuter the West’s industrial and power grids with climate change policies, which has only given China a leg up in the AI and weapons race. 

Tyler Durden
Tue, 09/08/2026 – 06:55

The Bond Selloff Isn’t Fiscal Armageddon, It’s The End Of A Decade Of Financial Repression; Deutsche Bank

0
The Bond Selloff Isn’t Fiscal Armageddon, It’s The End Of A Decade Of Financial Repression; Deutsche Bank

Authored by Jim Reid, Deutsche Bank global head of macro research,

The latest global bond sell-off has revived the idea that markets are fretting over unsustainable public finances. As concerned as I am by this issue in the longer term, the recent bond market weakness at the moment should be seen more as a continuation of the long normalisation from the historic anomaly of the 2010s.

That was a decade of financial repression with central banks buying trillions in government debt, benchmark policy rates sitting near zero, and sovereign borrowing costs held down for years. Had you been on a desert island for a couple of decades, the level of yields today would look perfectly normal at the end of your sabbatical from the world, not at crisis levels.

At Deutsche Bank, our house view has consistently been in recent years that yields would rise due to heavy government issuance, the retreat of quantitative easing programmes of bond buying by central banks and inflation levels that have been persistently higher and more volatile than the pre-pandemic period. In the US, inflation has now been above the Federal Reserve’s 2 per cent target for more than five years.

There is also some positive news that has supported higher yields. Global growth has held up better than most expected since the conflict with Iran began. US nominal GDP growth in the second quarter was 6.6 per cent year on year, which, outside the Covid-19 bounceback period, was the highest level since 2005. Clearly, part of this reflects higher energy prices and inflation, but there is no doubt that real growth is also holding up, partly thanks to the continuing AI boom. This has also increased corporate debt supply, which has competed with government bonds for investor demand in recent months. European growth, meanwhile, is also performing better than many thought possible in the face of an all-too-familiar energy shock for the continent.

And make no mistake, fiscal concerns are real and higher borrowing costs potentially worsen debt arithmetic, especially if growth fades.

The big shift, though, is that the equilibrium rate for bond yields is higher than markets became accustomed to in the ultra-loose era.

This has raised understandable concern, but one thing has been under-reported: returns for investors are starting to stabilise and, in many cases, have been positive over recent months and years.

This has been a welcome change from the early 2020s, when low starting yields offered no protection from the bear market. Rolling five- and 10-year total returns are still around their lowest on record across many government bond markets. However, the worst of the negative-return period is probably behind us.

Over the past year, the Bloomberg US Treasury Total Return index delivered a positive return even as 10-year yields rose by about 0.60 percentage points. From current levels, the 10-year yield would need to rise to roughly 5.5 per cent over the next year, or 6.4 per cent over two years, before total returns turned negative. An investor who bought 10-year Treasuries at the October 2023 yield peak of 4.99 per cent would now have a total return of more than 16 per cent. It is a useful reminder of how much starting yield now matters.

The UK provides an even clearer example, given the constant negative headlines. Ten-year gilt yields are now about 0.65 percentage points above the peaks reached during the 2022 mini-Budget crisis. Yet the broad gilt index has returned roughly 12 per cent since those crisis highs. There hasn’t been any prolonged period of negative returns in gilts over those four years.

This does not mean the secular adjustment is complete. Outside of a material downgrade to growth expectations or an external shock, the forces encouraging yields to move upwards are unlikely to disappear, but at least we’re in the ballpark of normal again. Over the past 100 years, a period with regular and large swings in prices, inflation has averaged 3 per cent in the US and 4 per cent in the UK — a higher level than that seen since 1990 but lower than current long-dated yields.

After years in which returns depended heavily on capital gains, more normal levels of yields are again providing income that can compound over time, which is helping to cushion volatility and steadily reward patience. The pressures will remain, and it’s hard to see spectacular returns, especially in real terms, but at least bonds have become bonds again, and investors should bear this in mind when the next inevitable bad headline comes through.

Tyler Durden
Tue, 09/08/2026 – 06:30