70.4 F
Chicago
Monday, October 12, 2026
Home Blog Page 227

Yet Another Wildberries Facility – Russia’s Amazon – Goes Up In Flames After Ukraine Drone Strike

Yet Another Wildberries Facility – Russia’s Amazon – Goes Up In Flames After Ukraine Drone Strike

Another large warehouse and logistics hub for major online Russian retailer Wildberries has been targeted and struck by Ukrainian drones.

This is the third time in a week the company widely considered to be the ‘Russian Amazon’ has seen its warehouses go up in flames. At least eight of its shipping facilities have been attacked overall this month. Wildberries co-founder Tatyana Kim confirmed the fresh attack on company facilities Friday morning:

Kim, Russia’s wealthiest woman, said Wildberries facilities in St. Petersburg and the surrounding Leningrad region, as well as in annexed Crimea, were hit overnight. Fires broke out at several locations, though Kim said “parts” of the warehouses were saved.

While Kim said none of the company’s employees were injured, Leningrad region Governor Alexander Drozdenko wrote in a post on Telegram earlier in the morning that three people were hurt during the attack in his region.

Moscow Times via Telegram

Operations at these facilities have been halted, while all personnel a the impacted warehouse in Crimea have been evacuated.

The St. Petersburg attack resulted in especially dramatic scenes of a huge smoke plume stretching high into the atmosphere, and even visible from space, NASA satellite imagery showed.

It was just last week that the company’s warehouses in central Russia were struck, which killed eight people. In the face of the Kremlin calling the attacks acts of terrorism and war crimes, Ukrainian President Volodymyr Zelensky has claimed that the hubs were “involved in providing the Russian army with drone components, navigation equipment and other gear.”

The Wildberries facilities have been increasingly targeted amid broader nightly drone waves out of Ukraine, with a separate Friday attack in the Kirov region killing at least six people.

Anadolu/Getty Images

NBC News has noted, “Wildberries, whose banking arm had sanctions imposed on it by the European Union this week over its financial contribution to the Russian budget, plays a central role in Russia’s consumer economy.”

“Its targeting by Ukraine appears to be part of Kyiv’s attempts to ensure ordinary Russians feel the impact of the war which has raged on Ukrainian territory for more than four years,” the report adds.

The company says it is working around the clock to restore service to areas impacted by the warehouse attacks. 

Stunning footage of Wildberries hub fully on fire from earlier this week in Krasnodar:

Reuters has reviewed that “Together with smaller rivals, Wildberries and Ozon sell goods and services worth the equivalent of 8.5% of Russia’s gross domestic product. They provide jobs for 4 million people, or more than 5% of the country’s workforce.”

Tyler Durden
Fri, 07/24/2026 – 09:40

“It’s Getting Worse”: HSBC Warns Commodities Face Squeeze As Chokepoint Chaos Spreads

“It’s Getting Worse”: HSBC Warns Commodities Face Squeeze As Chokepoint Chaos Spreads

The key takeaway heading into the weekend is that maritime chokepoint chaos has spread from the Strait of Hormuz to the Bab el-Mandeb Strait, while fighting across the Black Sea has intensified between Russia and Ukraine. The widening disruptions have prompted several institutional desks this week to warn that a potential squeeze on physical commodity markets could send prices from energy to agricultural goods higher.

“The Middle East conflict has escalated, putting a substantial squeeze back into commodity markets,” Paul Bloxham, HSBC’s chief economist for Australia, New Zealand and global commodities, wrote in a note on Friday morning.

Bloxham continued, “Traffic through Hormuz has almost stalled again, and the disruption has spread to the Bab el-Mandeb Strait, the key access point for the Red Sea, for Saudi oil going to Asia and Europe-Asia trade through the Suez Canal.”

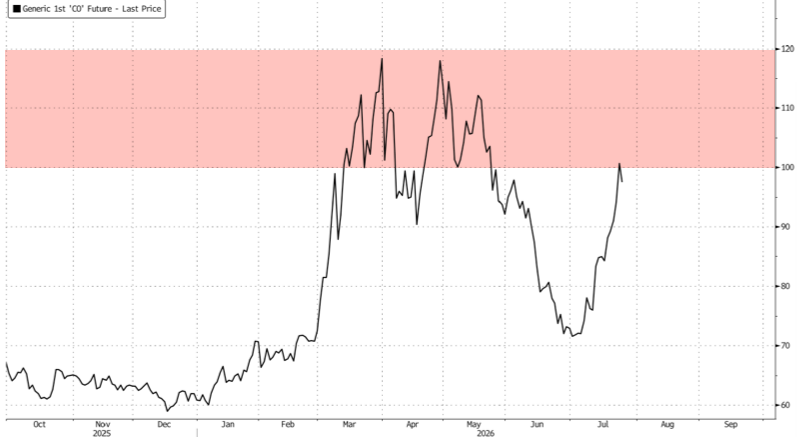
Bloxham warned that with Brent trading above $100 a barrel and strategic petroleum reserves being rapidly depleted worldwide, energy markets face a mounting risk of a “super-squeeze.”

His message was blunt: “It’s not over yet,” adding, “Hormuz, Mandeb, oil at 100 … it’s getting worse. “

Here’s more:

The Brent oil price has risen sharply, to over USD100/b recently; European and Asian gas prices are more than 40% m-o-m; refined product prices, like jet fuel and diesel are surging; urea prices are up 13%; and wheat prices are at a three year high – all on supply constraint concerns. With inventory rundown having been a key adjustment factor preventing much bigger prices spikes earlier in the conflict, and stocks now much lower, concerns about ‘tank bottom’ levels and non-linearities are expected to come back into focus. It’s a ‘super-squeeze’. And it’s not over yet.

Bloxham also highlighted the market mechanics that prevented Brent from spiking even higher a few months back, including US strategic reserve releases and China’s reduction of oil imports and SPR.

But he warned that these buffers are finite and can suppress the price shock for only so long:

As we have actively written about over the past few months, a key reason that commodity prices – particularly oil – did not spike higher earlier has been active reduction of inventories, particularly with the US release of strategic reserves and in China, where oil imports have been drawn down (see ‘Better, but the Hormuz disruption is not over yet’, 25 June 2026; and ‘Hormuz is reshaping commodity markets’, 25 May 2026).

However, the challenge is that inventory reduction can only provide an offset for so long.

At some point, concerns about stocks falling to critical levels may show up in non-linearities in markets (see Hormuz still closed: Beware Strait non-linearities, 28 April 2026). However, even with a deep-dive looks at measured stocks and supply pathways, it is hard to be definitive about when reserves will reach these critical levels. Commodity markets are highly adaptable, and when the demand is there, flexible markets often find a way to deliver. Aggregate price benchmarks also only go so far. In the face of acute supply shocks, commodity markets tend to fragment, with many different prices for the same products in different locations and for different delivery times (see More fragmentation as Hormuz blockage continues, 13 April 2026).

That said, the longer the disruption is in place – and the recent escalation suggests it is, indeed, going on for longer – the more likely it becomes that commodity prices will spike higher, in non-linear ways, as stocks are depleted.

A growing list of institutional commodity desks, including Goldman Sachs, RBC Capital Markets and JPMorgan, has warned that the expanding maritime chokepoint crisis is entering a more dangerous phase.

Helima Croft, RBC’s head of global commodity strategy, cautioned that the “war enters a dangerous phase with the Red Sea and critical infrastructure at risk.“

These desks have raised their near-term Brent forecasts as the disruption spreads. Goldman commodities strategist Daan Struyven warned that Brent could exceed $120 a barrel in the fourth quarter if the Hormuz crisis persists.

Related:

With the US national average for regular gasoline now above $4 a gallon, the energy shock has crossed a politically sensitive level (again), which could increase pressure on the Trump administration to pursue a diplomatic off-ramp.

Tyler Durden
Fri, 07/24/2026 – 09:20

Braggawatts, Cheap Chinese Compute, & Simple ROI

Braggawatts, Cheap Chinese Compute, & Simple ROI

Authored by Peter Tchir via Academy Securities,

With weakness in chips and AI the prior week, that was a major topic of conversation, as was the escalation in Iran (please see Academy’s Geopolitical Analysis for the latest on Iran and geopolitics more broadly).

Two key themes from last weekend’s From Trinkets to Compute seem to be playing out:

Cheap Chinese Compute

Most importantly, the story of Cheap Chinese Compute is garnering staying power. While DeepSeek may have been a one-off, the story is increasingly about China delivering Cheap Compute. We have seen China flood/control markets in the past. I didn’t see it coming in compute (at least not yet), but it might be here?

  • China doesn’t have to deal with NIMBY, but they do make a lot of chips (generally lower quality, but a lot), and have been ramping up all forms of electricity production and storage for years. The U.S. is finally getting on board with this ProSec™ theme, while the rest of the world is only starting to wake up to the need and potential opportunity that adopting a ProSec™ mindset delivers.

  • On the less “savory” side are “allegations” (and I’m being polite here) that a lot of the Chinese compute trains by “distilling” from existing models (inundating existing models with requests, to somewhat “copy” their answers) rather than training their models from scratch. It is a big cost advantage and time saving mechanism.

Earnings

Less important was my flipping from “earnings will matter” to “earnings might not matter.”

We don’t really spend a lot of time on single stock earnings. It isn’t our “thing” in general. But we do follow the earnings. What we can say so far on this front is that when the earnings and announcements hit the tape, they seem very strong. The instant reaction in the media (and social media) tends to support the strength of the results. Then the stocks seem to drift lower (in some cases worse than drift). 

The earnings bar seems to be set incredibly high, so far.

This is concerning when trying to determine the direction of the next leg.

Braggawatts

I’m not sure how I missed the term Braggawatts, but it caught my attention when my friends at ZeroHedge sent out a tweet that used the term.

  • Basically, braggawatts is a term used to express skepticism over how much in the data center and AI space can be physically constructed (i.e., in the real world) versus all the existing announcements and expectations of future announcements.

    • From access to chips, to water, to electricity, to getting all of the various state and local regulatory approvals, the argument is that a lot more compute has been announced than can be completed within the timeframe of the announcements.

    • This is consistent with some anecdotal evidence of cost and time overruns on projects (that is something we were hearing about more frequently than in the past).

If braggawatts are real (we need to explore this more):

  • This should be good for credit spreads in the sector. The logical conclusion would be to announce fewer new projects and prioritize existing projects.

  • Would be bad for the “picks and shovels” in the AI / Data Center industry.

Simple ROI.

To a large degree, return on investment analysis surrounding AI and the AI spend has been minimal in my view.

  • On the one side you have a “build it and they will come” mentality (often the “only” risk has been described as not building enough, fast enough – which hardly encourages traditional scrutiny of costs versus revenue).

  • On the other side, no CEO in their right mind would say anything other than that they were launching AI initiatives within their firm to capture efficiencies. The cost of compute has gone up. Actually, let me rephrase that, companies are being charged a cost of compute more in line with the cost of producing the compute than they were before. While the cost of providing compute seems to be increasing (shortages, etc.) part of what users are seeing is that the price that was subsidized to encourage use and to create moats (to the extent moats can be created and held) is being subsidized less. Increasing, and we’ve been writing about this for months, we are moving from “we have to try AI, or be left behind” to “we’ve been using AI, now let’s analyze the cost benefit of that.” Is that why some of the token utilization charts are showing declines from the peak?

If I’m right and some of these forces connect, it could bring pressure to bear on the space. That is “fine and normal.” What concerns me is how much money has flown into passive vehicles in the space, and how many leveraged products there are in the space. Not just the very large SOXL (which is index based) but also a lot of individual stocks in this have leveraged ETFs. 

I fear that this is a risk that can and will accentuate moves to the downside (just like it does on the upside).

Bottom Line

The escalation in Iran is not good for my view on potential rate cuts. While my outlook on inflation wasn’t entirely dependent on the free flow of oil (including more oil that had previously been sanctioned), it helped a lot.

On the AI front, I’m positive on credit spreads, but remain vigilant on valuations. The recent reaction in markets to what seemed like strong earnings releases only accentuates that concern.

Tyler Durden
Fri, 07/24/2026 – 09:00

Trump Losing Patience, In ‘Revenge Mode’ After 13th Consecutive Night Of US Strikes On Iran

Trump Losing Patience, In ‘Revenge Mode’ After 13th Consecutive Night Of US Strikes On Iran

The latest little peace overture by Washington widely reported Thursday night was apparently a big nothingburger, as on Friday the Iraqi prime minister’s office has denied a New York Times report claiming that Iran rejected a US ceasefire proposal delivered to Tehran by Iraqi Prime Minister Ali al-Zaidi.

The fresh statement from the prime minister’s office said what was published in the Times was “entirely unfounded” and had “no relation to reality.” The statement underscored the temporary nature of the proposal and that it was the “only offer on the table” and still left the question of control over the Strait of Hormuz unresolved – and so Tehran was uninterested.

It’s also the reality that Tehran wants to see Trump sweat and impose economic and political costs particularly ahead of the midterms in November, where Congressional Republicans must face voters over failing to rein in Trump’s Iran war. The Iranians continue to openly voice this, for example in the following from the parliament speaker:

Meanwhile, in what is becoming a brutal, nightly routine, US Central Command (CENTCOM) has wrapped up its 13th consecutive wave of airstrikes against Iran. The Pentagon said it targeted military command centers, drone storage facilities, communication networks, and coastal surveillance sites. 

Iranian state media reported overnight into Friday heavy explosions rocking major hubs across the country, including Khorramabad, Jask, Ahvaz, Bandar Abbas, and the strategic outpost of Qeshm Island. Iranian media further said a US missile strike left four dead and five injured in the key industrial and transportation hub of Ahvaz.

As the bombs fall, Tehran is still signaling that military pressure won’t force a cheap surrender – with Iranian Foreign Minister Abbas Araghchi lashing out at the US escalation, warning that “mindless aggression” will only see Trump pay a “heavier price” for a deal to end the war.

Iranian retaliation on US-linked sites in the Gulf have continued at the same steady pace, with on Friday Bahrain’s military having intercepted “several treacherous Iranian air attacks” – according to the general command of the Bahrain Defense Force.

The Bahraini military further denounced Iran’s “systematic hostile approach” and “criminal attacks targeting civilians”. The statement emphasized, “The general command emphasises that the deliberate use of missiles and drones to target civilians and private property constitutes a flagrant violation of international humanitarian law.”

Throughout the morning the Iranian military’s targets also included locations in Jordan, Kuwait, and northern Iraq. Sky News is reporting that “Explosions were also heard near a base hosting the US in Iraq, near the Erbil International Airport.”

Fox feeding its Boomer audience some Freedom Viagra with a helping of war crimes on the side:

But Fox News also reports the results of its latest poll which finds 56% oppose the ongoing American military action against Iran, including 40% who “strongly” oppose. “Disapproval of President Donald Trump’s handling of Iran hit a record high in July,” Fox writes.

“A majority of voters oppose U.S. military action, and nearly two thirds think the conflict will last at least a year,” the report says.

 This as The Wall Street Journal does an entire investigative report which should be laughably obvious to any careful observer to what’s been going on and the deepening quagmire the US is getting itself into:

As the war in Iran enters its fifth month, Trump is increasingly frustrated that a conflict he once thought would be over in a matter of weeks has dragged on with no end in sight, administration officials and others close to the president said.

Some of Trump’s advisers now worry that the war—which has resulted in higher prices, falling approval ratings and the deaths of more than a dozen U.S. servicemembers—is consuming his presidency and damaging Republicans’ already dim prospects in the coming midterm elections.

Alarmingly, the WSJ noted that Trump seems in “revenge mode” against Tehran, and apparently sees no other options than to try and keep bombing his way out of it. Of course, this script has been written many times – not only during the “Global War on Terror” and this millennium’s “forever wars” – but going all the way back to the Vietnam war.

NBC: The four service members being flown from the Middle East to Dover Air Force Base were 28-year-old Angel S. Rampersad of New York, 30-year-old Michael Emmanuel Swinton of North Carolina, 25-year-old Tyler James Feehan of Hawaii and 19-year-old Isabella Gonzales of Texas.

President Trump attends a dignified transfer on Wednesday.

The war is said to be taking a heavy “toll” on Trump and his top officials. According to more of what’s also been glaringly obvious for anyone who has had a shred of independent thought:

The war is splitting the conservative coalition over which Trump once had an iron grip, worrying some Republicans close to the White House. Longtime Trump allies such as Fox News host Laura Ingraham have used their platforms to express concerns about how the war might affect Republicans in November’s midterm elections. On Monday, she said the “clock is ticking” to the midterms.

“Netanyahu has led us into a horrible conflict filled with lies,” Steve Bannon, a longtime Trump adviser, said. “People can see with their own eyes what’s going on.”

While this part about Netanyahu is true, it is ultimately President Trump who made the decision, after for years prior – and especially on the campaign trail – articulately spelling out that attacking Iran and starting new Mideast wars would be one of most idiotic foreign policy moves a president could make.

Trump on Thursday said he would take funds from Iran to pay for damage inflicted on US bases and assets throughout the war. Iran responded in the following…

Perhaps the utter folly of Operation Epic Fury has finally begun to dawn on the president. WSJ also observed that “Last month, the president was so excited at the prospect of signing the memorandum of understanding with Tehran to reopen the Strait of Hormuz that he was dismissive of Republican allies who said the Iranians would never stick to the agreement, according to a senior administration official. He wanted it to be over, Trump told them.”

Tyler Durden
Fri, 07/24/2026 – 08:40

NANO Nuclear And Fortil Advance Critical KRONOS Fuel System

NANO Nuclear And Fortil Advance Critical KRONOS Fuel System

NANO Nuclear Energy has pushed another critical piece of its KRONOS MMR program toward preliminary design, this time with French engineering group Fortil.

If there’s a corner of the French industrial sector that America should be comfortable leaning into, their nuclear segment is arguably the safest bet. Their 57-reactor fleet, accounting for 70% of the country’s electricity generation, is only surpassed by the US and Chinese commercial fleets.

The companies said conceptual design work is nearly complete on the reactor’s Fuel Handling & Storage System, which will manage the safe handling, storage and movement of nuclear fuel throughout operations. The work includes defining subsystem interfaces, evaluating engineering solutions and producing documentation needed for the next design stage.

It’s not the most glamorous part of a reactor, but it’s the sort of picks-and-shovels engineering that separates a reactor rendering from an operating nuclear plant.

Fortil’s dedicated nuclear team is handling multidisciplinary work across mechanical and systems engineering, nuclear safety, instrumentation and control, and radiation protection. The consultancy has more than 2,500 employees across 30 offices in 14 countries, giving NANO access to an international engineering bench as KRONOS moves toward potential fleet deployment.

The milestone follows the NRC’s formal acceptance of the KRONOS Construction Permit Application for a full-scale reactor at the University of Illinois Urbana-Champaign. The agency began formal review activities in June, with environmental and safety evaluations expected to progress through 2027. Initial construction could begin in the second half of next year.

NANO’s story has increasingly become about more than a single reactor. The company recently acquired Secured Transportation Services for $13 million, turning itself into a revenue-generating nuclear logistics operator. That business helped execute a record 1.7-metric-ton HALEU shipment from Japan and supported the removal of highly enriched uranium from Venezuela.

The company is in the midst of an aggressive and wide-ranging expansion plan with business segments across the nuclear value chain. In just the past year, they’ve advanced a proprietary HALEU transportation package, won a U.S. Air Force innovation contract, and signed an agreement with Supermicro targeting nuclear-powered AI data centers. Additional partnerships are targeting South Korea, the Gulf region and a potential 1-gigawatt Texas data center campus.

Tyler Durden
Fri, 07/24/2026 – 08:25

Inside Global Aerospace & Defense Boom: 12 Takeaways From World’s Most Important Airshow

Inside Global Aerospace & Defense Boom: 12 Takeaways From World’s Most Important Airshow

The Farnborough International Airshow is coming to a close in the UK, marking the end of one of the aerospace and defense industry’s top gatherings. Institutional research desks have had boots on the ground, tracking commercial-aircraft orders, defense procurement and other industry trends.

A team of Citi analysts led by John Godyn attended Farnborough earlier this week and reported back to clients Thursday morning.

Their findings pointed to accelerating missile demand and a wave of new aircraft orders that could fuel a stronger and more robust growth cycle for aerospace and defense companies.

Godyn highlighted the event’s key takeaways, giving clients a clearer picture of the aerospace and defense industries heading into fall and 2027:

1) Aftermarket channel checks across multiple companies extend recent strength.

We spoke with a wide range of aftermarket exposed companies including engine manufacturers, parts/component manufacturers, MROs, and aircraft lessors. Consistently, across all meetings, companies expressed the view that the key themes driving aftermarket continue including: (1) low retirement rates, (2) high lease renewals and tight secondary market trends for AC/engines, (3) strong demand for lift from global airline customers, (4) capacity constrained MROs, and (5) no impact from the conflict in the Middle-East. Given how strong recent trends have been, companies did caution that mean reversion to long term growth rates, which GE described as LDD revenue growth and many non-engine aftermarket players described as HSD revenue growth, was inevitable. We view the read-through as clearly positive across multiple stocks in our aftermarket coverage (GE/RTX/VSEC/LOAR/HEI) and EU analyst Conor Dwyer echoed that sentiment for Safran’s 2026. To be fair, we note that investor expectations are already set for continued beats in this category of stock so the bar isn’t obviously low.

2) M&A heating up?

Multiple companies we spoke to described an M&A backdrop that is much more active with many deals coming to market. Management teams described multiple drivers with notable emphasis on self-help activities at corporates focused on ramping production leading to non-core assets or underperforming suppliers being put up for sale, as well as PE-owned assets coming to market. We get the sense from most of our companies that the Aero M&A pipeline remains robust and multiple companies expect M&A to be a larger driver of growth. Valuations were regularly cited as reasonably full, but there remain opportunities to find deals at reasonable prices.

3) Airbus Next-Gen has been a dominant theme throughout the week.

The next generation Narrowbody Jet on the part of Airbus has been a ubiquitous theme throughout the week. GE indicated CFM collaboration with Airbus was very active on the RISE program (meeting 2x per month). Other component manufacturers expressed similarly heightened activity and discussion around the next generation Narrowbody Jet. Suppliers described conversations with BA on similar topics to be far earlier stage and having less consistent cadence.

4) GE emphasized more upside on CFM56 aftermarket $ profit and a quicker ramp on LEAP aftermarket $ profit than investors may appreciate.

GE noted that LEAP:CFM56 $ profits should be roughly equal by 2030. GE expects CFM $ profits to continue to grow until 2028 before flattening out, while LEAP $ profits continue to catch up until 2030. LEAP % margin will lag CFM56 even in 2030 and will continue to move higher as the LEAP installed base ages. We see a similar shape in our above-consensus expectations and see the possibility of additional upside as the belief that the aftermarket cycle lasts ultimately proves to be more robust than even GE management expects.

5) GE engine read-through positive.

The aforementioned CFM56:LEAP view is similar to Conor Dwyer’s assumed split for Safran within the next 5 years (he is 45:55 in 2030, reaching 49:51 in 2031). Conor notes that GE was quite relaxed about the threat of rising retirements in the coming years to the CFM56 program, but did note it is managing the risk of rising USM (used serviceable materials) already with slightly slower price increases on the CFM56 vs the LEAP and acknowledged the possibility of risk in 2029-31 (this is a risk Conor highlighted here in 2028).

6) Bullishness on emerging engine technologies was palpable.

Although we did not speak to RTX, we felt that GE upped the volume on its RISE engine and is increasingly and more loudly making the case for the innovative technology. Separately, multiple EVTOL players we met with showed evidence of progress on hybrid-electric engines punctuated by a GE/BETA hybrid-electric engine which was demonstrated live and recently was the first such engine to be tested above 30,000 feet.

7) Demand for accelerating missile production was a frequent topic of conversation.

At face value, this is no surprise, but channel checks emphasized 3 interesting points: (1) targets of 3-10x growth in production by program are likely to prove low because these forecasts do not incorporate international demand, so as ‘framework agreements’ are definitized, the supply chain is already being asked to ramp even higher to satisfy allies’ needs, (2) solutions for scalable hypersonic missile production are being requested, and (3) supplying into emerging affordable mass designs may be a bigger opportunity than initially thought. We continue to believe that Missile Defense/Munitions Replenishment are themes that will exceed expectations for years to come.

8) Positive secondary market trends supportive of aircraft lessors.

In particular: (1) a continued, favorable supply/demand mismatch in the secondary market driving lease rates higher across a wide range of aircraft types, (2) among narrowbodies, notable strength in the A321neo and 737MAX, (3) among widebodies, even greater strength in the A330neo and 787 families of aircraft, (4) a belief among lessors that existing production outlooks across the OEMs are unlikely to be a meaningful headwind to secondary market trends until the end of the decade, and (5) the view that a lack of customer support will dissuade airframe OEMs from pursuing new clean sheet designs this decade. In totality, these channel checks were not only positive for AER, but also much of our aerospace coverage.

9) Are 737 -7 and -10 certifications imminent?

Suppliers to whom we spoke expressed a tremendous amount of confidence in rate increases at BA in the short/medium-term. Suppliers also felt that events supportive of BA’s case for raising rates, namely the -7/10 certifications, were likely to happen sooner rather than later.

10) ETN mentioned that Aero could be in a historic “feast” cycle.

ETN Aero Management mentioned that it expects 16 new Aero-focused platforms launching over the next ten years vs. the last big Aero cycle in the 2000s where only five were launched. The majority of the new expected platforms will be military, and ETN Management seems confident that the company can enjoy considerable content on these platforms. We sense Management is particularly excited about the Bell MV-75 Helicopter program and the Collaborative Combat Aircraft program (CCA), although these programs are still in the early stages in terms of ramp up for ETN.

11) Aero supply chain slowly healing but will be tested with further rate increases.

In general, nearly every company we spoke to described the current aerospace supply chain as healthy and struggled to identify any major problem areas. In fact, being part of the solution was cited as an opportunity by many, such as VSEC, DCO, and HEI. Separately, both PH and ETN mentioned an increased focus on dual/multi-sourcing, which is leading to greater supply chain resiliency. Anecdotes of supply chain issues don’t seem widespread, and we also think Aero suppliers are increasingly leaning on improved software, electronics, and even additive manufacturing to further support the Aero manufacturing food chain. That said, the topic of defense orders using DPAS at some point in the future did come up as a risk factor that was cited as a realistic scenario that could disrupt the aero supply chain.

12) Aerospace suppliers’ ability to price still strong.

Suppliers throughout the A&D supply chain described negotiations as much more focused on availability, performance, quality, and on-time delivery rather than price and margins. We get the sense that A&D suppliers will continue to outpace inflation with solid pricing and likely expanding margins without much pushback. Pricing muscle seemed to improve substantially during the COVID supply chain “crunch”” and that has allowed suppliers to continue to rea

Another potential tailwind for the defense industry emerged Wednesday, when House Republicans narrowly passed the fiscal 2027 National Defense Authorization Act, authorizing a record $1.15 trillion in military spending.

The measure passed 216-212, largely along party lines. While it is below President Trump’s $1.5 trillion budget request, it still is a jump from the roughly $900 billion last year.

The NDAA faces an uncertain future in the Senate, where Democrats are expected to oppose its cost and several controversial policy provisions.

Related coverage:

If passed in the Senate and signed by Trump, the spending surge would provide tailwinds for defense stocks.

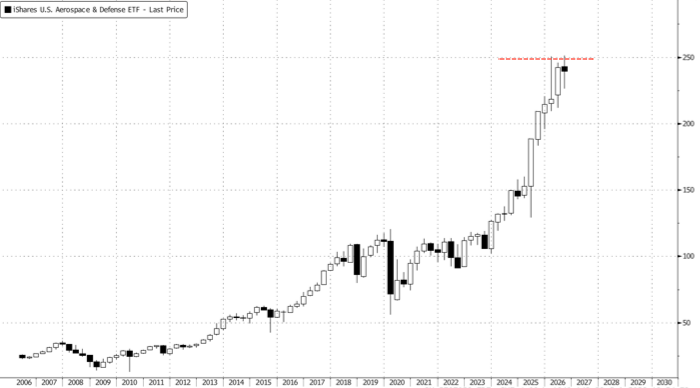
The iShares U.S. Aerospace & Defense ETF (ITA) has moved up and to the right, reflecting the boom in military spending as multiple wars rage across Eurasia. The global boom in defense spending has a lot more room to run.

ITA’s next leg up will require a sustained upside break above the $250 level. 

Professional subscribers can read military trends notes at our new Marketdesk.ai portal.

Tyler Durden
Fri, 07/24/2026 – 06:55

India’s Fuel Exports Set To Soar In July As Refining Margins Jump

India’s Fuel Exports Set To Soar In July As Refining Margins Jump

By Charles Kennedy of OilPrice.com,

India is on track to export the highest volume of refined petroleum products in months as refining margins have jumped with the re-escalation of the Middle East conflict.

India is estimated to ship as many as 1.55 million barrels per day (bpd) of light and middle distillates in July, per data by commodity analysts Kpler cited by Reuters columnist Clyde Russell.

The July volumes would be nearly double the fuel export volumes of just 866,000 bpd in May, when the Strait of Hormuz crisis hit crude supplies to India and the rest of Asia. In May, India saw its lowest fuel exports in four years.

The tightening fuel markets in Asia and the rest of the world added to a renewed rally in refining margins after the U.S.-Iran ceasefire collapsed two weeks ago. This has encouraged Indian refiners to ramp up refined petroleum exports.

The expected volumes in July would be the second-highest level in Kpler’s data series dating back to 2017.

Earlier this month, Kpler estimated that India’s refined petroleum exports would hit in July the highest level since September 2025 as refiners race to capture soaring margins amid tight Asian fuel markets.

India’s high export levels in July could ease some of the pressure on the Asian fuel market, but not all of it, as crude supplies from the Middle East are once again at high risk of delay.

Asian refiners that had bet on a flood of crude supply from the Middle East in August are now faced with potential delays in deliveries amid the re-escalation of hostilities, which could thwart their plans to ramp up crude processing rates in the coming weeks.

Refiners in the U.S. and Europe are operating at near capacity, but those in Asia may not see the expected increase in throughput now that the July and August loadings and delivery schedules have been upended by the re-escalation of the Middle East conflict.

Tyler Durden
Fri, 07/24/2026 – 06:30

Deaths Now Outnumber Births In 17 US States

Deaths Now Outnumber Births In 17 US States

Natural population growth is slowing across much of America.

According to the latest U.S. Census Bureau estimates, 17 states recorded more deaths than births between July 2024 and July 2025, up from only four states during much of the 2010s.

Using U.S. Census Bureau data, Visual Capitalist’s Dorothy Neufeld created this map showing natural population change in every state.

Because the measure excludes domestic and international migration, it highlights where population growth increasingly depends on people moving in.

Natural Population Change by State

The table below ranks every state by natural population change between July 2024 and July 2025, highlighting where births continued to outpace deaths—and where they no longer did.

State Natural Population Change
Jul 2024–Jul 2025
Pennsylvania -10,708
West Virginia -7,887
Maine -5,019
Michigan -4,998
Oregon -3,764
Mississippi -2,607
Alabama -2,188
New Hampshire -2,167
New Mexico -1,885
Vermont -1,769
Florida -1,333
Arkansas -1,224
Ohio -729
Delaware -554
Rhode Island -304
Montana -90
Kentucky -83
Missouri 177
Wyoming 295
South Carolina 564
Wisconsin 1,161
Hawaii 2,024
Connecticut 2,283
District of Columbia 2,516
Oklahoma 2,559
South Dakota 2,605
North Dakota 2,630
Louisiana 2,774
Iowa 2,949
Nevada 3,051
Alaska 3,308
Tennessee 3,597
Kansas 4,951
Nebraska 6,136
Idaho 6,900
Massachusetts 8,419
Indiana 8,561
Illinois 10,903
Maryland 11,444
Minnesota 12,071
Virginia 13,817
North Carolina 15,129
Washington 17,230
Colorado 20,608
Utah 24,961
New Jersey 26,023
Georgia 28,631
Arizona 20,914
New York 42,815
California 109,715
Texas 157,711

Pennsylvania recorded the nation’s largest natural decline (-10.7K), followed by West Virginia, Maine, and Michigan. Most states with natural decreases were concentrated in the Northeast and Appalachia, regions that include several states with some of the country’s oldest populations.

Florida also recorded more deaths than births, yet remained one of America’s fastest-growing states because of migration.

The South remained the engine of natural population growth. Texas (+158K), Georgia (+29K), and North Carolina (+15K) posted strong gains. California (+110K) and New York (+43K) also recorded far more births than deaths despite slower overall population growth.

America’s Population Is Increasingly Shaped by Migration

Natural population change tells only part of the story.

Several states with more deaths than births, including Florida, Maine, and Pennsylvania, can still grow overall when migration offsets their natural decline. Others continue losing population even after attracting newcomers.

Meanwhile, states such as Texas, North Carolina, and Arizona benefit from both natural population growth and migration, helping drive some of the country’s fastest population gains.

As America’s population ages and birth rates remain historically low, natural population growth is becoming less common. For a growing number of states, migration—not births—is now the primary driver of population growth, making migration trends increasingly important to their long-term demographic outlook.

To learn more about this topic, check out this graphic on immigration’s role in U.S. population growth by state.

Tyler Durden
Fri, 07/24/2026 – 05:45

EU Is Launching A Mission To Board Russian Shadow Fleet Tankers In The Indian Ocean

EU Is Launching A Mission To Board Russian Shadow Fleet Tankers In The Indian Ocean

The European Union has authorized its naval mission in the Indian Ocean (apparently there is one) to stop and board Russian shadow fleet tankers suspected of operating under false flags, the bloc announced on Wednesday.

The Spanish Navy frigate Santa María F81, deployed as part of the European Union Naval Force Operation ATALANTA, seen off the coast of Mogadishu, Somalia, on April 24, 2025.

EU member states have authorized Operation Atalanta, the union’s counter-piracy naval mission off the Horn of Africa, to begin conducting flag-verification boardings of vessels suspected of belonging to Russia’s shadow fleet in the western Indian Ocean, DefenseNews reported. The decision, announced this week by EU foreign policy chief Kaja Kallas, extends to Atalanta a power already exercised by the EU’s Mediterranean mission, Operation Irini.

Kallas made the announcement alongside news that Irini forces had boarded the sanctioned oil tanker MV South Star on July 20, acting on suspicion that the vessel was sailing under a false flag. “Every illicit voyage helps sustain Russia’s war machine. We are matching our sanctions with action at sea,” Kallas said, adding that the Atalanta authorization “further tightens the net.”

The move considerably widens the EU’s geographic reach against the shadow fleet, a loosely defined network of tankers with opaque ownership structures that Moscow uses to sell oil above the Western-imposed price cap. While Irini patrols the Mediterranean, Atalanta operates across the Somali Basin, the Gulf of Aden, the Red Sea, the Gulf of Suez, the Gulf of Aqaba and waters around Oman, and was launched as the EU’s first-ever naval mission in 2008 to combat piracy.

It is separate from the EU mission ASPIDES, which is designed to protect shipping in the Red Sea from attacks by the Iran-backed Yemeni Houthi rebels. One look at the exploding price of oil shows just how much the market thinks of Europe “defending” this particular waterway. 

The corridor where the mission operates is a critical transit route for tankers carrying Russian crude toward buyers in Asia. Brussels has already sanctioned more than 600 vessels suspected of belonging to the network.

Generally, ships on the high seas cannot simply be stopped and boarded by any third country. However, Article 110 of the UN Convention on the Law of the Sea permits warships to stop and inspect a vessel only where there is reasonable suspicion it is stateless or flying a flag to which it is not entitled. This falls short of a blanket authority to stop any sanctioned or Russia-linked ship, but flying false flags has been a frequent practice on Russian shadow fleet vessels.

The council decision, the operational plan and the rules of engagement that would spell out exactly how far Atalanta’s new powers extend have so far not been made public.

The approach has already produced results elsewhere. Irini’s flag checks contributed to pressure that culminated in a Cameroon purge of 39 vessels from its shipping registry after investigators uncovered fraudulent paperwork and fake registry websites used to disguise shadow fleet tankers.

Russian President Vladimir Putin has previously denounced such interceptions as “piracy,” underscoring how the expanded mandate is likely to further sharpen tensions between Brussels and Moscow over enforcement at sea.

One caveat to all this: unlike oil, Russian LNG (which Europe is absolutely desperate for) will remain exempt from EU sanctions. Which prompted Rabobank’s Michael Every earlier today to ask rhetorically “realpolitik or real weakness?“

Tyler Durden
Fri, 07/24/2026 – 04:15

Eco Loon Lobbies For Cameo In British Soap To Spread Climate Alarmism

Eco Loon Lobbies For Cameo In British Soap To Spread Climate Alarmism

Authored by Steve Watson via Modernity News,

BBC naturalist Chris Packham has openly requested a guest role on the fictional soap EastEnders so he can turn the nation’s most-watched entertainment show into a vehicle for climate crisis messaging.

In comments reported by GB News and drawn from a Radio Times interview, the veteran naturalist described his fantasy appearance: an environmental disaster such as a flood hitting the fictional London borough, followed by him marching through as himself with a placard to lecture the locals.

Packham told Radio Times he wants the role because it “would give me the capacity to communicate to an audience which I don’t talk to in my sphere of work.”

He complained that while some people understand the “scale of the crisis,” broader media fails at “truth telling” to “bring it home to everyone.”

“The trouble is, I keep popping that bubble and looking outside, and I see that other people are not aware of the gravity of that crisis, or some of them are still in the position where actually they’re denying … and that’s really scary,” he said.

He called for the messaging to be “integrated into broader output, so properly into news obviously, properly into weather where we talk about climate as well as weather – but also into dramas.”

This is not subtle. It is an explicit pitch to hijack prime-time entertainment and insert alarmist talking points into the daily lives of millions who never tune into nature documentaries.

British soaps have a documented history of being quietly weaponised for official narratives. FOI documents obtained last year revealed that during the Covid period the Department for Culture, Media and Sport held secret meetings with the BBC, ITV and Channel 4 to coordinate “national unity programming.”

Officials explored inserting pro-vaccine storylines into EastEnders and Coronation Street. Characters were scripted to celebrate jabs as winning the lottery while sceptics were mocked as “anti-vaxxers.” One MP later described the broadcasters as reduced to “mere arms of the state.”

The same playbook has been applied to immigration. EastEnders has featured storylines about exploited African migrants and racially motivated murders of immigrants after hiring campaigner Ade Lamuye in 2022.

Lamuye sits on the advisory board of the Power of Pop Fund, which has directed nearly £5 million to organisations that use media to reframe migration debates.

Similar influence operations have shaped sympathetic asylum-seeker characters in the other popular long running British soap Coronation Street. Activists openly boast that entertainment “holds influence and power to make real change.”

Far from being organic storytelling, this is coordinated social engineering, the same approach visible in other mainstream dramas that lecture audiences on pronouns, “deadnaming” and the supposed problems with classic literature. Channel 5’s The Teacher delivered some of the most direct examples yet, training viewers to treat biological reality and cultural heritage as potential sources of harm.

Watch the pattern laid bare across programming:

Even children’s programming is being enlisted. Netflix is developing a live-action reboot of the 1990s cartoon Captain Planet, the original of which pushed environmental panic, progressive multiculturalism, population control and the idea that humanity itself is the enemy requiring global governance.

Ted Turner’s creation was steeped in Club of Rome thinking that treated pollution and climate as a common enemy to justify changed attitudes and supranational control.

The method is consistent: identify a captive, trusting audience, embed the message inside drama so it feels organic, and watch compliance rise. Packham is simply asking for the same treatment for net-zero ideology.

While Packham demands soaps lecture viewers about “climate breakdown,” the actual evidence keeps undercutting the apocalyptic script. A bombshell Royal Society paper concluded that climate change is not causing mass extinctions, directly challenging one of the most repeated scare claims.

The IPCC itself has admitted that its most extreme apocalyptic scenarios are implausible, a quiet but significant climb-down from the catastrophe rhetoric used to justify rapid policy upheaval.

Research examining three million years of data has found no consistent link between CO2 levels and temperature, leaving net-zero activists without a straightforward causal story.

Temperature records underpinning the COP30 alarmist agenda have been shown to rest on heavily adjusted and questionable data, further eroding the foundation of official claims.

Even Bill Gates has publicly walked back the idea that climate change will end the world, prompting a triumphant response from those who have long argued the threat was overstated.

Meanwhile the Great Barrier Reef continues to defy the narrative, recording its fifth-highest coral cover on record even as media outlets insist a tipping point has been reached.

A major US government report has catalogued the systematic abuses of “settled” climate science and the role those abuses have played in driving net-zero policies that impose heavy economic costs for uncertain benefits.

The milder public messaging about weather reports and soap storylines sits alongside far more radical demands. Some German climate groups have openly called for total deindustrialisation of their country within 15 years, treating economic self-destruction as a moral necessity.

Others treat the entire agenda as a quasi-religious cult, complete with orthodoxy, heretics and demands for collective sacrifice that go well beyond practical environmental protection.

When the warming narrative softens under the weight of contradictory data, the same voices simply pivot. Scientists have revived ice-age doom scenarios, and Al Gore has shifted his public emphasis in ways that suggest the next scare is already being prepared.

Earlier claims of imminent climate armageddon have been quietly cancelled or scaled back, yet the institutional machinery that produced them remains intact and ready for the next iteration.

Packham’s EastEnders pitch is the latest attempt to keep the emotional temperature high after the hard data has cooled.

Flood Albert Square on screen, march through with a placard, and hope the audience never notices that the real-world evidence keeps failing to match the script.

Your support is crucial in helping us defeat mass censorship. Please consider donating via Locals or check out our unique merch. Follow us on X @ModernityNews.

Tyler Durden
Fri, 07/24/2026 – 03:30