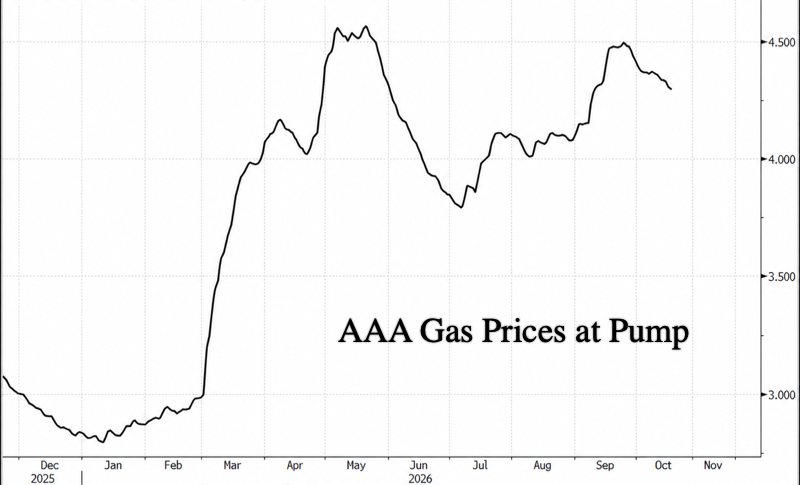
US futures are higher – but well off session highs hit before the European open – as dip buyers storm back into chipmakers after the Nasdaq’s worst week since the April 2025 tariff turmoil, while oil slides after President Trump waived Russian sanctions to seal a diesel deal and Energy Secretary Chris Wright said Persian Gulf flows have recovered to about 80% of pre-conflict levels; as a result Nasdaq futures are up more than 1% and the Philly semis index is set to snap its longest losing streak in 18 years, even as Europe slides on a weekend of riots in France. As of 8:00am ET, S&P futures were 0.4% higher at 7,741.75 while Nasdaq futures rose 1.1% to 29,705.50 and Dow futures are down 0.2%. That follows a Friday session in which the S&P fell 1.09% to 7,659 (sliding from flat just before the European close), the Nasdaq 100 sank 2.5% and the SOX tumbled 3.8% for an eighth straight loss, capping a week in which the SOX lost 11.4%, the Nasdaq 4.5% and CoreWeave a quarter of its value. In premarket trading, semis lead with Intel up 4.2% on a JPMorgan upgrade and Nvidia up 1.4%, neoclouds and optical names are bid (CoreWeave +6% after a Goldman upgrade from Neutral ($139PT) to Buy ($106PT?!) week in which it became “the market’s beta barometer”), Disc Medicine soars 35% ahead of Phase 3 data and Cleveland-Cliffs jumps 13% after an earnings beat. The day’s driver is Washington’s Russia pivot: Trump signed an executive order waiving Graham Act sanctions, restrictions and duties on Russian energy revenues (Russia will initially supply over 300k tonnes of diesel), Putin proposed a summit with Trump and Xi to negotiate an end to the war, and Zelenskyy accused Trump of pressuring Kyiv to surrender, which has sent Brent down 1.2% to $108.59. Treasuries dip slightly with shorter-dated yields edging higher in a bear flattener as traders keep a muted bid for an October hike, leaving the 10Y at 5.08% after last week’s 16.5bp plunge (its biggest weekly drop since August 2025), while French bonds tumble after the riots, with the OAT-Bund spread widening to 146bps. The dollar index is up 0.1% to 101.93, with the euro the G10 laggard below $1.12 and the Aussie leading after strong Chinese data. In commodities, WTI is little changed near $101.30, European gas (Dutch TTF) hit its highest since 2022, gold is up 0.1% at $4,169 and silver adds 0.9% to $57.49. Bitcoin rises 2.5% to about $82,850 after briefly topping $83,000. US economic data slate includes the October NAHB housing market index (10am). The Fed is in its external communications blackout through Oct. 29, so there are no Fed speakers. The Treasury sells $95 billion of 13-week and $82 billion of 26-week bills at 11:30am.

In premarket trading, Nvidia outperforms Magnificent Seven peers as chip stocks look set to rebound: Nvidia (NVDA) +1.4%, Amazon (AMZN) +1.2%, Alphabet (GOOGL) +0.6%, Meta Platforms (META) +0.2%, Microsoft (MSFT) +0.2%, Tesla (TSLA) -0.1%, Apple (AAPL) -0.1%
- Semiconductor stocks gain, setting the chip benchmark up to snap its longest losing streak in 18 years. Shares in neoclouds and optical firms are also rising amid a broad-based rally in AI-related firms.
- Cleveland-Cliffs (CLF) rises 13% after the steel producer reported adjusted Ebitda for the third quarter that beat the average analyst estimate.
- Disc Medicine (IRON) soars 63% after announcing that its investigational drug bitopertin met all primary and secondary endpoints in the Phase 3 Apollo trial in adults and adolescents with erythropoietic protoporphyria.
- Intel (INTC) rises 3% as JPMorgan upgrades its rating to neutral (with a PT of $85 or below where it closed on Friday), noting that the chipmaker’s turnaround might take years, but the management’s execution has been solid.
- Silgan (SLGN) gains 5% after the food packaging company and funds affiliated with American Industrial Partners announced a deal to buy Trivium Packaging in an all-cash deal.
- Pinterest (PINS) gains 1.1% as Phillip Securities initiates coverage with a recommendation of buy, noting that the company has significant international monetization potential.
- Disc Medicine (IRON) jumps 35% ahead of the company’s webcast to discuss topline results from the APOLLO Phase 3 trial of Bitopertin in erythropoietic protoporphyria.
- BYD US (+1.4%): Boyd Gaming shares rise as Morgan Stanley upgrades to overweight from equal-weight following a selloff across gaming stocks.
- RCAT US (+6.4%): Red Cat rises after the US drone and robot maker offered a 29% cash premium to buy Austrian engine specialist Steyr Motors, in order to boost its European defense portfolio.
In other corporate news, Anthropic, apparently undeterred by a week in which the market discovered that AI costs money to fund, is offering Blackstone a yield above 10% to anchor a $60 billion TPU-backed debt package (per JPMorgan’s desk), and separately said it will put 5% of its shares into a new public benefit fund. Nvidia-backed Nscale faces investor pushback over its IPO valuation after Microsoft exited its UK data center deal, as we reported over the weekend. Silgan is said to be near a $3.4 billion purchase of Trivium Packaging; KKR is selling Infinity Transportation to Ares for about $2.9 billion (WSJ); SoftBank is said to weigh buying top US security firm Allied; Starboard sees value in Apple chip supplier Skyworks; and Accenture is working on a potential sale of its China business that could value the unit at up to $1.5 billion (FT). Oaktree’s deal to take over a life insurer owned by Advantage Capital has collapsed after regulators raised alarms over exposure to 777 Partners. EQT agreed to buy Australia’s Cleanaway Waste Management for about A$9.3 billion including debt. Red Cat offered to buy Steyr Motors for EUR 39 a share in cash, and Ivanhoe Electric is in advanced talks to sell its US copper assets. Kimberly-Clark could kick off this week’s IG issuance as its Kenvue acquisition nears closing, while Citigroup and Wells Fargo launched their first euro bond deals of the year. Elon Musk pledged to give one SpaceX share to “every kid in America” next year, and Hyperscale Data plans to take its AI subsidiary askROI public.
Stock futures are rebounding from the Nasdaq’s worst week since the tariff turmoil of April 2025, with dip buyers stepping in after the tech index broke below its closely watched 10- and 20-week moving averages; this week’s earnings from Netflix, Tesla and Meta (which UBS hinted may have pulled its earnings a week sooner as it may be raising capital ahead of its peers) will provide the next test for the still-shaky AI trade. The bounce comes as bond yields stabilize and oil pulls back below $100 (at least for a bit), and on the 39th anniversary of Black Monday, which DB’s Jim Reid notes is a “more memorable one” since it falls on a Monday. Yet as is so often the case, markets keep doing what they’re not supposed to: Friday brought what Goldman’s desk called record put buying and the “first real sign of panic in index protection” (as we detailed), even as retail poured a record amount into levered ETFs, and the S&P barely flinched while Morgan Stanley’s AI basket suffered its worst week ever.
The Nasdaq 100 now needs to reclaim 30,000: the slide below 30K unwound the October breakout and cost the Nasdaq its 10 and 20-week moving averages; futures point to a sharp rebound, making 30K the first hurdle for bulls, with the 40-week moving average near 27.5K the next major support if it fails.

JPMorgan’s Mislav Matejka says that a stabilization in bond yields would “go a long way to support stocks” if it continues, especially given concerns over AI financing costs. Morgan Stanley’s Mike Wilson advised that investors should prepare to add risk, reiterating a preference for quality stocks, while Citi strategists say tech is still set to account for nearly 70% of global earnings growth next year, making this week’s results a key gauge of whether Monday’s bounce can become something more durable.
“Asia’s cash markets are catching up with Friday’s Wall Street selloff,” said Anna Wu, founder of Floodlines Research in Sydney. “Investors want more evidence that AI spending is translating into returns. Until then, Asia’s chip-heavy markets remain particularly exposed to swings in that conviction.”
Hedging demand, meanwhile, has gone vertical: S&P 500 puts are getting bid up, with the normalized 3-month put skew reaching the highest since late July, after trading near the lows of the past two years as recently as the beginning of this month.

JPM’s Market Intel desk under Andrew Tyler admits last week’s selloff “ran against our tactical bullish call,” but after reassessing, the team retains its tactically bullish stance, albeit “more selective”: the momentum/tech unwind and AI credit fears drove the selloff while ASML and TSMC delivered healthy earnings and consumer data stayed resilient. JPM does not expect the rotation out of tech to end abruptly, and favors cyclicals outside tech while selectively buying semis and memory weakness via defined-risk options; all eyes are on Meta earnings and Nvidia’s GTC Berlin. JPM credit strategist Nathaniel Rosenbaum notes hyperscaler spreads widened 12bp last week to 148bp, the widest since July, but sees the widening as overdone unless earnings reveal fundamental weakness. JPM credit trader Christian Crosby was less sanguine: the funding cost concerns “are now more about levered borrowers, specifically neoclouds, data center project finance, and GPU deals,” where “every point higher in borrowing costs is worth multiple points on the equity.”
Over at Goldman, Tony Pasquariello writes that “we’ve entered a new phase in the AI sequence, one that is unequivocally more complicated (for both the credit market and the equity market),” and that “for the first time in three years, a number of key asset markets have felt the ‘speed limit’ from the bond market” (on which more here). Goldman’s Prime book saw the largest net selling of tech on record, with US long/short net leverage down to 43.7%, a 5-year low, and shorts near 5-year highs, which is why Lee Coppersmith thinks “the market is moving into a different volatility environment but not necessarily a more bearish one.” GS flow trader Giulio Esposito flags a “sharp rotation out of AI hardware into real-economy defensives,” with the equal-weight S&P beating the cap-weighted index by 225bp last week, the most since November 2020, while Sam Dunn reckons “the AI trade is still long but roughly 6/10 on length and materially cleaner than Jun/July.”
In geopolitics, Ukrainian President Zelenskyy accused Trump of trying to pressure Kyiv into surrendering to Russia, escalating a week-long row. Trump wrote on social media over the weekend that he cut a diesel export deal with Russia and delayed imposing further sanctions because he doesn’t want to drive Putin away from peace talks, and Republican lawmakers, including some of the president’s strongest allies, blasted Trump over the sanctions waiver (Moscow, for its part, celebrated a “historic moment”). In global news, China’s growth accelerated more than expected in the third quarter, boosting the odds of the economy reaching Beijing’s annual target and dimming the prospects for additional easing measures.
In France, cost-of-living protests degenerated into looting and burning nationwide over the weekend, with nearly 2,400 arrests and almost 1,000 police injured, and protests also took place in Italy, Belgium and Portugal. Ten-year OAT yields are up more than 9bps to about 4.90%, with the OAT-Bund spread widening to 146bps, not far from the recent 151bps peak and just days before Moody’s review on Friday. Macron appealed for calm but stopped short of declaring a state of emergency, which Reid warns “won’t make it easy for the international community to be totally comfortable buying OATs.

In Europe, the Stoxx 600 is down 0.7% at around 640, with 478 members down and just 103 up, as France’s CAC 40 leads declines after the weekend’s violence; the CAC 40 and Spain’s IBEX 35 are both down 1.3% and Italy’s FTSE MIB 1.4%. Banks are the sector laggard, followed by travel & leisure and autos, while tech and energy are the only sectors in the green. JPM’s desk notes weakness is broad, with autos, industrials, basic resources, banks and utilities lagging. Defense names are lower, with BAE, Thales and Leonardo all down more than 2.5%, while Norwegian energy names hit 52-week highs. Here are the biggest European movers:
- Verbio shares rise as much as 4.2% following remarks from the German transport minister, cited by Augsburger Allgemeine, who floated the idea of using fuel containing up to a fifth of ethanol.
- Mowi shares rise as much as 5.2% to a six-month high after the salmon-farming company reported earnings well ahead of expectations thanks to record harvest volumes in the latest quarter.
- Pets at Home shares gain as much as 5.7% after Peel Hunt upgrades the retailer to buy from hold on signs that trading and execution are improving.
- French stocks underperform after cost-of-living protests over the weekend.
- DHL shares fall as much as 2.3% after the German logistics company reported preliminary third-quarter earnings, which Morgan Stanley said may augur more muted growth in the future.
- Imperial Brands falls as much as 2.1% after being downgraded at Jefferies. The bank thinks the tobacco company could fail to impress investors with its FY27 guidance due to slower growth in Germany.
Asian stocks were mixed, extending tech-led losses from the previous week before paring them as US futures rebounded: the MSCI Asia Pacific Index fell as much as 1%, with chipmakers SK Hynix, TSMC and Advantest among the top decliners as DeepSeek’s latest model sparked concerns over demand for chips. Japan’s Nikkei 225 fell 0.6% after last week’s 5.4% slide, while South Korea’s Kospi staged an impressive comeback, rising 1.8% after plunging as much as 3.2% at the open. Taiwan’s Taiex slid 1.8% in early trading and the Taiwan dollar fell to its weakest since April 2025 on stock outflows. The CSI 300 rose 0.1% after China’s Q3 GDP grew 4.5% y/y (vs 4.4% expected) and September retail sales doubled expectations, while Australia’s ASX 200 gained 0.4%, led by Cleanaway, which jumped as much as 21% after EQT agreed to buy it. Hong Kong was closed for the Chung Yeung Festival. Indonesia’s rout deepened, with stocks down more than 5% to a six-year low and more than 16% in two sessions after MSCI warned of a potential two-step downgrade; Goldman estimates a full removal from MSCI indexes could trigger about $5.6 billion of passive outflows.
In FX, the Bloomberg Dollar Spot Index is little changed while the DXY is up 0.1% to 101.93, at the upper end of a 101.76-102.08 range. The euro is the G10 laggard, slipping below 1.12 (to the middle of a 1.1182-1.1234 range) on the French unrest, and speculative euro positioning is already the most pessimistic in a decade. The Aussie outperforms, rising 0.5% to 0.6977 after China’s data beat, and the loonie is also firmer after Trump touted an “amazing” deal with Canada at some point. USD/JPY is back around 158.10, while EUR/CHF dropped 0.4% to a fresh three-month low of 0.92264.
In rates, Treasuries dip slightly, with shorter-dated yields edging higher and the curve bear flattening as traders maintain a muted expectation for an October hike: the 10Y is up about 1bp to 5.08% and the 2Y is at 4.73%, while money markets assign a 14% chance of a hike next week and 75% for December. That follows last week’s 16.5bp drop in the 10Y, its biggest weekly decline since August 2025, as the AI growth scare revived the haven bid even as hot CPI and PPI prints should have done the opposite (we are told this is normal). In Europe, OATs are hit by over 70 ticks as the French riots push the OAT-Bund spread to 146bps, BTPs are down around 25 ticks on protests in Italy, and gilts are down almost 50 ticks on spillover selling, while Bunds are flat around 3.44%. The Treasury sells $95 billion of 13-week and $82 billion of 26-week bills today, and dealers expect about $25 billion of IG issuance this week, which would leave 2026 less than $10 billion short of the record set in 2020.
“Yields above 5% provide far more income protection against being early, while a meaningful growth shock would bring capital gains on top,” writes Bloomberg macro strategist Skylar Montgomery Koning. “Last week’s willingness to buy the dip in bonds suggests the market is starting to recognise that trade-off.”
In commodities, oil retreats from a five-month high, with Brent down 1.2% to $108.59 and WTI little changed at $101.30, as traders book profits after a blistering rally and Trump’s Russia sanctions waiver frees up diesel supply; the US is also negotiating with European allies to release diesel stockpiles and the DoE issued an RFP to exchange up to 17 million barrels of SPR crude. The Middle East remains tense, however: the IRGC said two tankers caught fire in the Strait of Hormuz after hitting mines, and explosions were reported in Jeddah after Houthi attacks. Dutch TTF gas rose to its highest since 2022, trading in a EUR 87.66-89.32/MWh range. Spot gold is contained in a $4,155-4,190 band, silver is up about 1%, and LME copper hit $14,480/t on the China data before falling back to $14,350/t. US natgas is up 0.6% to $3.14.
US economic data slate includes the October NAHB housing market index (10am). There are no Fed speakers as the FOMC is in blackout ahead of the Oct. 27-28 meeting. Cleveland-Cliffs and Fifth Third report before the open, with Zions, Crown Holdings, W R Berkley, FNB, RLI, Western Alliance, Steel Dynamics, BOK Financial, AGNC and Wintrust after the close; the week ahead brings Netflix on Tuesday, Meta and Tesla on Wednesday, and Nvidia’s GTC Berlin from Oct. 20-22.
Market Snapshot

Top Overnight News
- Intensifying concerns about the cost and availability of funding have caused investors to reduce their equity market exposures and price a deceleration in the growth outlook. Rising energy prices and interest rates have weighed on the performance of many cyclical equities since early August. During the last two weeks, however, the potential implications of a sharply rising cost of capital on the AI build-out have weighed further on the market outlook for economic and earnings growth. Exacerbating these rotations, this week GS Prime Services noted a sharp reduction in hedge fund net leverage alongside a positioning pullback in AI-related stocks. GIR
- Nvidia Chief Executive Officer Jensen Huang took a sanguine view toward the latest AI stock-market rout, saying the benefits of the technology will soon outweigh the concerns of investors. BBG
- President Trump, defending his decision to ease tariffs and other sanctions against Russia, said on Sunday that he was making “great progress” in a peace deal with the Kremlin and suggested for the first time that the process included “hostage negotiations.” NYT
- Russian President Vladimir Putin has proposed that he, President Trump and Chinese leader Xi Jinping meet next month to talk about Ukraine in an attempt to negotiate an end to the four-year conflict that would favor Moscow, said people familiar with the discussions. WSJ
- Washington is pushing an idea whereby Europe would resume buying Russian gas an inducement for Putin to end the war in Ukraine. NYT
- Iranian support has helped the Houthis mount the most potent and sophisticated attacks yet on Saudi Arabia and its Yemeni allies, including help targeting drone and missile attacks, as well as training, intelligence and tactical guidance, people briefed on intelligence from Saudi Arabia and Yemen’s anti-Houthi alliance said. WSJ
- Ukrainian President Volodymyr Zelenskyy accused Donald Trump of trying to pressure Kyiv into surrendering to Russia, escalating a week-long row with the US president. BBG
- Republican lawmakers, including some of the president’s strongest allies on Capitol Hill, blasted Donald Trump for waiving new tariffs and sanctions on Russia, prompting the president to defend himself against members of his own party. BBG
- US Energy Secretary Chris Wright told Fox News that Persian Gulf oil flows had recovered to about 80% of their pre-conflict level, although refined-product shipments remained constrained. Wright said he’s in talks with European allies to release diesel stockpiles. BBG
- China’s growth accelerated more than expected last quarter, putting Beijing’s annual target within reach and dimming the prospects for further easing measures. GDP expanded 4.5% year on year. BBG
- Apple on Friday said its foldable iPhone Duo had seen “nothing short of extraordinary” demand, as the device sold out on the company’s website until next year within hours of going on sale. FT
- The US government’s debt interest burden reached a record high for fiscal 2026, with net interest costs coming to $1.05 trillion, up more than 8% from the $970 billion in fiscal 2025. BBG
- Elon Musk pledged to give one SpaceX share to “every kid in America” next year. BBG
- Weeks ahead of Election Day, 71% of U.S. adults think the country is on the “wrong track.” It’s the highest share yet in President Donald Trump’s second term, illustrating the grim national mood his party faces in the midterm elections. NBC
- Nvidia-backed data center developer Nscale faces opposition to the valuation target it’s pursuing in its IPO, according to people familiar with the matter. BBG
- The violence that rocked France this weekend as cost-of-living protests degenerated into looting and burning nationwide is raising alert levels across Europe, where elections will be held in at least half a dozen countries next year. BBG
- Indonesian markets extended their selloff, with stocks deepening their worst rout in almost 30 years and losses spreading to bonds and the rupiah after MSCI Inc. warned the country may face a two-step downgrade. BBG
- China’s financial regulators are establishing a liquidity support facility to cushion non-bank financial institutions against potential large scale redemption pressures, People’s Bank of China Governor Pan Gongsheng said at the Financial Street Forum annual meeting in Beijing, CCTV reported. BBG
- The Bank of England is examining whether Barclays traders misrepresented illiquid private credit loans to understate their risk after the Prudential Regulation Authority received a complaint earlier this year. FT
- IRGC said two oil tankers caught fire in the Strait of Hormuz after hitting mines. Newsquawk
- US President Trump pledged USD 5k for every adult if the GOP wins Congress, speaking at a Kentucky rally ahead of the 3rd November midterms; separately, Reuters reported he blamed aides for a faltering Republican midterm strategy as Democrats led House polls. Newsquawk
- JPM credit strategist Nathaniel Rosenbaum notes hyperscaler spreads widened 12bp last week to 148bp, the widest since July 2026, but sees the widening as overdone unless upcoming earnings reveal fundamental weakness. JPM
A more detailed look at global markets courtesy of Newsquawk
APAC stocks were mixed following Friday’s tech-led sell-off on Wall Street, with Japanese and Korean stocks underperforming amid continued pressure on AI and semiconductor names. However, losses were pared as US equity futures recovered alongside a pullback in crude prices. Sentiment was also supported by Trump’s latest Russia-Ukraine peace efforts and easing of restrictions on Russian energy, while Chinese activity data generally topped expectations but prompted little reaction. ASX 200 bucked the regional weakness, supported by Cleanaway Waste Management surging after EQT agreed to acquire the Co. Elsewhere, RBA’s Kent noted evidence of rising neutral interest rates in Australia and abroad. Nikkei 225 and KOSPI underperformed as tech stocks caught up with Friday’s losses in their US counterparts, although the indices pared earlier losses of over 2%. For Japan, BoJ Governor Ueda also spoke overnight but offered little fresh. Shanghai Comp was marginally softer despite Chinese activity data generally topping expectations, although Fixed Asset Investment remained weak. Hang Seng was closed for the Chung Yeung Festival.
Top Asian News
- China PBoC Governor said overnight open-market repo rate will become the main policy rate, with a potential shift to overnight open-market operations to improve interest-rate regulation. The Governor added that monetary policy framework reform will remain gradual and ongoing, and plans to widen access to standing lending facility, introduce a liquidity tool for non-bank institutions and pilot further facilitation of onshore RMB purchases and sales by overseas financial institutions.
- China’s Stats Bureau said the economy showed more positive developments in Jan-Sept, though weak demand and a complex international environment remain challenges; its Deputy Head said new growth drivers, including high-end manufacturing and the digital economy, accounted for over 40% of growth, while consumption contributed 46.7% of GDP growth.
- Japanese PM Takaichi said the government has no predetermined plans on whether to compile a supplementary budget and a robust economy can boost market confidence in the JPY; her approval rating fell below 50%, the lowest since she took office, Kyodo reported.
European bourses (STOXX 600 -0.8%) are broadly lower to start the week, as Dutch TTF rises to its highest level since 2022. Reasons for this weakness are two-fold: 1) continued Russia-Ukraine strikes, and 2) protests across the EZ (Italy, Portugal, Spain, Belgium, France). As a result, clear underperformance is seen in the CAC 40 (-1.3%), IBEX 35 (-1.3%) and FTSE MIB (-1.4%). Sectors point to a clear negative bias. Tech and Energy are the only sectors in the green, while Banks is the sector laggard, followed by Travel & Leisure and Autos. US equity futures are firmer across the board, contrary to their European peers. Strength which appears to be a slight rebound following last week’s hefty losses seen across chip and memory names. With the US data docket fairly light and Fed speakers in blackout, focus will be on some key earnings, namely SpaceX, Netflix, IBM, Tesla and Meta.
Top European News
- France’s Saturday cost-of-living protests drew around 550,000 people, with some 1,800 arrested and more than 500 police, gendarmes and firefighters injured, according to the Interior Minister; one demonstrator died and Limoges’ historic town hall was torched. Clashes, fires and looting hit Paris, Lyon and other cities, and President Macron and PM Lecornu said violence would not be tolerated.
- French President Macron ordered a review of police preparedness and intelligence, empowered prefects and mayors to ban gatherings, and asked the government to hold cost-of-living talks this week.
- No decision expected from the UK regarding the Jackdaw gas field just yet, according to Politico, but a decision is still expected this week.
- Morningstar DBRS affirmed Italy at A (low); trend stable.
- S&P affirmed the Netherlands at AAA/A-1+; outlook stable.
FX
- G10s are mixed against a firmer USD. The Aussie holds towards the top of the pile, benefiting from strong Chinese activity data. The Loonie also outperforms, with Trump touting an “amazing” deal with Canada, at some point. To the downside resides the EUR, which digests ongoing civil unrest in France.
- DXY started the London session flat, but gradually moved higher as the morning progressed; currently sits at the upper end of a 101.76 to 102.08 range. The US data docket is light for the day, and remains that way for the remainder of the week; the Fed is in blackout ahead of next week’s confab, where rates are expected to remain on hold. Money markets assign a 14% chance of a hike next week; 75% chance of a hike in December.
- The pressure in the index seen last week was partly due to tech sell-off, and debt concerns surrounding AI spending. This appears to have abated at the start of this week, with CoreWeave +1.8% in pre-market trade. Given that the data and speaker docket is light this week, USD action will likely be dictated by the AI theme (Mag-7 earnings due this week), some also bring attention to Taiwan chip exports to signal a top in equities (due tomorrow).
- EUR/USD is currently underperforming vs peers; it fell beneath the 1.12 mark, to currently trade at the midpoint of a 1.1182-1.1234 range. Pressure potentially factors in the civil unrest in France, with protests reportedly causing damages of “hundreds of millions of euros”, in the region. As such, the OAT-Bund spread has once again widened to c. 144bps (vs recent peaks of 151bps).
- The Aussie is the clear outperformer this morning, taking positive leads from strong Chinese Activity Data overnight. In brief, Q3 GDP, Industrial Production and Retail Sales all topped forecasts; figures which lessen the odds of further near-term stimulus within the region. Nonetheless, the PBoC Governor has been on the wires this morning, where he mentioned that “we will launch a liquidity support tool for large-scale redemptions by non-bank institutions”.
- More interestingly, the Governor mentioned that the open market overnight reverse repo rate will correspondingly become the main policy rate. A change, which in theory, allows the PBoC greater control over policy and improves the stability of the CNY. Whilst no move was seen on the announcement itself, CNY will likely take positive leads from improving regional data and the shift in the PBoC’s framework. USD/CNY currently holds at the bottom end of a 6.6805 to 6.6862 range.
Central Banks
- ECB’s Lagarde said Eurozone headline inflation rose to 3.8% in September on energy, with no material wage response yet; sees growth of 0.9% in 2026 and 1.4% in 2027 after 25bps hikes in June and September, according to her IMFC statement.
- ECB’s Nagel said the job of fighting inflation is not done and the ECB may have to do more.
- BoJ Governor Ueda said Japan is in a positive cycle of rising wages and recovering prices and anchoring core inflation near 2% is increasingly important; the steady recovery, tight labour market, strong AI-driven capex and exports, and Middle East energy costs are fuelling inflation. He said it would be inappropriate to signal in advance when the BoJ might conduct emergency bond market operations, with any intervention to depend on the speed of long-term rate rises and signs of market instability; long-term rates would likely rise steadily in line with policy rate hikes, financial conditions remain accommodative and fiscal spending is adding upward pressure on prices and wages.
- RBA Assistant Governor Kent said there is reasonable evidence neutral rates are rising in Australia and abroad, and that policy is somewhat restrictive but it is questionable whether it is restrictive enough; household demand is softening while business credit remains strong, and housing tax adjustments move policy in a favourable direction. He is cautious about monthly employment figures but said the labour market has become less tight and the market reaction to the jobs data was reasonable.
Fixed Income
- USTs are modestly firmer, benefiting from the downside seen in energy on the updates between the US and Russia over the weekend. Otherwise, the fixed income space is under pressure given civil unrest in Europe.
- For USTs, they are at the low end of a 105-18+ to 105-19 band, but still post upside of c. five ticks as things stand. As alluded to, US President Trump said that he is negotiating a Ukraine-Russia peace, and significant progress is being made. Additionally, he signed an executive order waiving sanctions and tariffs on Russian energy. Points that have weighed on the energy space.
- Ahead, aside from updates to those points and expected continued bipartisan criticism, the US docket is very thin today, with participants still digesting last week’s price prints ahead of the PCE print towards month end.
- EGBs in focus, and particularly OATs. Currently, at a 108.96 low, hit by over 70 ticks after the significant protest activity seen across France during the weekend, and widespread political dispute over it, all largely to the benefit of Le Pen’s RN. Action that has taken the OAT-Bund 10yr yield spread to a 144bps peak today, just shy of the recent 151bps peak. A widening and unrest that adds to pressure into Moody’s review on Friday.
- Protest activity also occurred outside of France, with Italy seeing notable activity, enough to weigh on BTPs by around 25 ticks, with the BTP-Bund spread also modestly wider.
- Gilts opened on the backfoot, despite the energy pullback, as the region has similar fiscal/dissatisfaction themes that sparked the unrest seen in mainland Europe, and thus some spillover selling has occurred. Enough, as it stands, to send Gilts to an 84.29 low, off by just under 50 ticks.
Commodities
- Crude futures are softer to start the week, after Trump waived certain sanctions and restrictions on Russian energy and signalled progress towards ending the Russia-Ukraine war. Furthermore, the WSJ reported that Russian President Putin proposed a Trump-Xi-Putin meeting to discuss the Ukraine war; however, China’s Foreign Ministry did not share any information regarding the potential meeting. Despite this positive signalling by Trump, Russia and Ukraine launched large-scale attacks, with energy infrastructure being the main targets.
- In the Middle East, the environment remains tense. The IRGC stated that two oil tankers caught fire in the Strait of Hormuz, whilst in Saudi, explosions were heard. In terms of the path to diplomacy, Pakistan’s Army Chief is set to visit Tehran this week, whilst the Iranian FM mentioned that Tehran’s seven-day proposal on the Strait of Hormuz remains on the table.
- WTI and Brent currently trade at the lower end of their USD 96.72-99.24/bbl and USD 106.82-109.65/bbl range, respectively. On the US-Iran front, Pakistan’s army chief Munir may visit Tehran this week, while the IRGC said two tankers hit mines in the Strait of Hormuz.
- Dutch TTF has risen to its highest level since 2022, currently trading in a EUR 87.66-89.32/MWh range.
- Precious metals are relatively contained, with spot gold oscillating in a USD 4,155-4,190/oz band. The yellow metal has held above the USD 4100/oz handle since the selloff at the start of September, while the USD 4k/oz mark has held firm as its lowest point since the start of the Iran conflict.
- 3M LME Copper found a bid at the start of the Asian session, reaching a peak of USD 14.48k/t, amid strong Chinese activity data, before falling to a low of USD 14.35k/t amid the broader risk-off tone.
- US President Trump signed an executive order waiving certain Graham Act sanctions, restrictions and duties on Russian energy revenues. Russia will initially supply over 300k tonnes of diesel.
- US Energy Secretary said the US is negotiating with European countries to release large diesel stockpiles, but their response has been slow.
- US DoE issued an RFP to exchange up to 17mln bbls of crude from the SPR.
Trade/Tariffs
- US Ambassador to the EU Puzder warned of devastating retaliation if Brussels limits spectrum access for non-EU firms, after the EU decided to allocate most mobile satellite spectrum to domestic companies, FT reported.
- French President Macron said the EU needs to extend the China deal to include plastics, chemicals and ferroalloys.
- China’s MOFCOM announced the tightening of export controls on specific drones, autopilots, engines, radios and related technologies, effective November 18, while also saying they will further optimise procedures for screening and identifying export control queries on dual-use items.
Geopolitics: Middle East
- US President Trump said the Iran war will be over very soon and that Iran had been systematically destroyed militarily and financially, warning the US would soon finish the job unless Iran rapidly changes course. He endorsed Netanyahu ahead of Israel’s 27th October election, where polls show a tight race between Netanyahu’s bloc and its rivals, adding that if anyone else led Israel the US would have to do the work itself.
- US President Trump is reportedly mulling an attack on oil and military facilities in Iran’s Kharg Island, ILNA reported citing UAE press.
- Pakistani Army Chief Asim Munir may visit Tehran this week, ISNA reported.
- Iran’s Foreign Minister Araghchi said Tehran’s seven-day proposal to reopen the Strait of Hormuz remains on the table: the strait could reopen within six days if the US meets Iran’s conditions, with talks resuming on day seven; Iran said it is still studying US comments on the proposal.
- IRGC said two oil tankers caught fire in the Strait of Hormuz after hitting mines.
- UKMTO said a southbound tug was struck by two unknown projectiles northeast of Khor Fakkan, UAE, sustaining damage and one minor casualty but continuing its route. It also reported a tanker struck by an unknown projectile 68NM northeast of Saudi Arabia’s Jubail on 16th October (crew safe and evacuated) and a tanker hit by an RPG fired from a small boat 78NM northeast of Jubail, possibly the same incident, and an LNG tanker fired upon by a skiff 140NM southeast of Al Mukalla, Yemen, before its security team fired warning shots.
- US CENTCOM said the US has helped ship over 100mln bbls through Hormuz in the past seven days, and a US commander said the naval blockade had stopped Iran exporting USD 25bln of oil and the US helped freeze USD 350mln of Iranian crypto.
- Explosions were reportedly heard in Saudi Arabia’s Jeddah, Tasnim reported, with flight operations at King Abdulaziz International Airport disrupted according to Naya for Iraq, and in Jizan and Abha following attacks by Yemeni forces, Sabreen News reported.
- Houthis have repeatedly struck Riyadh airport and Saudi Aramco headquarters, with 19 killed in Houthi strikes as Saudi Arabia struggles to counter the attacks, AP reported; Iran is providing the Houthis with intelligence and targeting data for attacks on Saudi Arabia, WSJ reported.
Geopolitics: Ukraine
- US President Trump said he is negotiating peace between Russia and Ukraine and that significant progress is being made.
- Russian President Putin proposed a meeting with US President Trump and Chinese President Xi on the sidelines of the APEC summit in China (Nov 18th-19th) to discuss ending the war, WSJ reported. However, China’s Foreign Ministry Spokesperson said there is no information to share on any meeting between leaders of Russia, China and the US.
- The Trump administration has proposed resuming Russian gas imports to Europe as part of a potential Ukraine peace deal, with US envoys Witkoff and Kushner raising the idea with Ukrainian and European officials despite opposition from European governments, NYT reported.
- US Secretary of State Rubio said US President Trump is open to anything to end the Ukraine war, while discussions have taken place over a potential meeting between Putin, Xi and Trump.
- Ukrainian President Zelensky told Bloomberg that the Trump administration is pressuring Ukraine to capitulate to Russia through restrictions on Starlink speeds and delays in Patriot missile deliveries. Zelensky proposed halting strikes on Russian oil refineries in exchange for additional US air-defence missiles and added that Washington wants strikes halted without reciprocal support. Furthermore, he said that US-Ukraine relations could improve after the November midterm elections and that talks are underway with US envoys Kushner and Witkoff over a possible meeting this week.
- In comments elsewhere, Ukrainian President Zelensky said Russia launched attacks on Kyiv overnight on energy facilities and that Russian President Putin does not want to end this war. On intelligence, he said they did not receive a warning from partners on the Russian ballistic missile.
- Ukraine launched more than 1,000 drones at Russia, which set oil terminal and depot facilities ablaze, while Russia launched one of its largest attacks on Ukraine’s energy sector, using 320+ drones and missiles against more than 15 energy sites, and hit Metinvest’s Zaporizhstal steelworks with six ballistic missiles.
Crypto
- Bitcoin has steadily climbed to start the week and briefly topped the USD 83k mark.
US Event Calendar
- 10:00am: Oct NAHB Housing Market Index, est. 31, prior 32
- 11:30am: US to sell $95bn 13-week bills
- 11:30am: US to sell $82bn 26-week bills
Central Bank Speakers
- Fed external communications blackout (through Oct. 29); no Fed speakers scheduled
DB’s Jim Reid concludes the overnight wrap
39 years ago today we woke up to the origins of what would forever be known as Black Monday, where the Dow fell -22.6% on the day. It’s rare the anniversary falls on a Monday so it’s a more memorable one today. The late US trading session on Friday almost felt people were worried we’d get a repeat today as the S&P fell from flat just before the European close to -1.09% by the US one. However, this morning we are seeing a bounce with S&P (+0.79%) and Nasdaq (+1.29%) futures making up most of their late Friday losses.
Clearly the main nervousness last week was around AI-related names, with credit markets starting to show some distress in that sector. The Philly semiconductor index was down -11.41% last week (-3.83% Friday), whilst the NASDAQ was down -4.48% (-2.14% Friday). At the heart of the sell-off was CoreWeave, which was down -25.21% last week (-11.91% Friday), whilst their 5yr CDS was up +225bps on the week to 1128bps with their cash bonds trading at around a 15% yield. Meanwhile, Oracle’s share price was down -9.31% (-4.64% Friday), and their 5yr CDS was up +44bps on the week to 300bps.
Asia has started the week relatively calm with the KOSPI (+0.55%) and S&P/ASX 200 (+0.32%) both trading higher, while the CSI 300 (+0.09%) and Shanghai Composite (+0.16%) are just above flat. The Nikkei (-0.73%) is the region’s weakest performer, extending losses after falling -5.4% last week as technology stocks came under heavy pressure. Elsewhere, Indonesia’s benchmark stock index is down more than 5% to its lowest level in six years, as concerns over the potential MSCI downgrade we discussed on Friday continues to heighten fears of further foreign investor outflows. The index is down over -16% in these past two sessions.
Early morning data showed that China’s economic expansion accelerated marginally in the third quarter of 2026, with real GDP growing by +4.5% y/y. This print slightly surpassed the consensus expectation of +4.4% and marked a modest step up from the +4.3% expansion recorded in the second quarter. On a sequential basis, GDP grew by +1.2% q/q outperforming the +1.1% forecast and accelerating from +0.9% in the prior period. The quarterly performance was primarily underpinned by resilient export volumes and robust demand within the artificial intelligence infrastructure supply chain.
Separately, China’s September activity indicators were on the decent side. Industrial production rose by +5.5% y/y, beating expectations of +5.4% and accelerating from +5.2% in August. On the demand side, consumer spending showed signs of firming as retail sales expanded by +1.1% y/y – more than double the consensus forecast of +0.5% and a notable improvement from the +0.4% growth recorded in August.
Elsewhere, France’s political and fiscal problems gained another complication over the weekend as nationwide cost-of-living protests descended into some of the country’s worst unrest in years. Around 550,000 people demonstrated on Saturday according to the Interior Ministry, although the CGT put the figure at 800,000, and the violence continued into Sunday with fresh clashes in Paris and Marseille. The latest official figures put arrests at 2,400 and police injuries at nearly 1,000. This won’t make it easy for the international community to be totally comfortable buying OATs, so the modest recovery in French spreads over the last week or so will be tested today. In a televised address last night, President Macron appealed for calm, saying France felt “anger and shame” at the violence. He stopped short of declaring a state of emergency, but said prefects could ban protests where necessary to protect public buildings and businesses, while distinguishing peaceful demonstrators from ultra-left groups and criminals blamed by the government for the rioting. With France already facing a difficult fiscal backdrop and the 2027 election approaching, the weekend adds another layer of political risk for markets. OAT futures are down around a third of a percent in price terms this morning as other DM bond futures are flat to slightly higher so there has been some small impact so far.
The week ahead doesn’t really have a big focal point but instead a broad global range of releases, with the flash October PMIs on Friday providing the first coordinated read on activity across the US, UK, Japan and the major euro-area economies. Before then, the UK has a busy run of labour-market data tomorrow and inflation on Wednesday. Japan’s national CPI arrives on Friday, while Canada also has inflation data today. Central-bank action is quieter, with the Bank of Korea deciding on Thursday and the Fed already in its communications blackout ahead of next week’s FOMC. Earnings season also broadens out, with Netflix tomorrow and Meta and Tesla on Wednesday among the highlights. We have 76 S&P 500 and 69 Stoxx 600 companies releasing with next week being even larger.
In the US, the calendar itself is relatively light, which should leave markets continuing to digest last week’s much stronger-than-expected inflation numbers. Headline CPI rose +0.65% in September, taking the annual rate from 3.4% to 3.7%, while core CPI increased +0.33%, with its annual rate up two-tenths to 2.6%. The important point was that the upside surprise was broad-based across core goods, shelter and services rather than being driven by one idiosyncratic component. PPI was also stronger than expected on Thursday, and our economists’ current tracking for September core PCE is +0.36% month-on-month, or about 3.14% year-on-year absent revisions. So there is plenty for the Fed to consider even though officials are now in blackout.
As for this week’s US releases, the housing data come first. Our economists expect the NAHB housing-market index to slip to 31 from 32 today. Tomorrow, our economists expect housing starts to rise to an annualised 1.300mn from 1.275mn, while building permits are expected at 1.400mn versus 1.403mn previously. Large surprises could still shift estimates of Q3 activity, with our economists continuing to expect annualised real GDP growth of 3.3%. More broadly, they expect inflation-adjusted output to expand 2.5% on a Q4/Q4 basis in 2026 and 2.2% in 2027.
Later in the week, our economists expect initial jobless claims to rise to 206k from 199k on Thursday. The main US releases then come with the flash S&P Global PMIs on Friday, where our economists expect manufacturing to ease to 55.5 from 55.9 and services to 57.5 from 58.8. These numbers have recently mattered for markets: the sharp rise in the September PMIs helped drive an almost 15bp increase in both 2yr and 10yr Treasury yields on September 23. Our economists still expect the Fed to remain on hold at next week’s October meeting, allowing policymakers more time to assess the underlying inflation trend and the tightening in financial conditions from the recent rise in global yields.
Recapping last week now, and as mentioned at the top, the biggest story was the selloff in AI-related assets, with chip stocks taking a particular hit. For instance, the Philly semiconductor index was down -11.41% last week (-3.83% Friday), whilst the NASDAQ was down -4.48% (-2.14% Friday). Moreover, there were even larger declines for some of the most affected names, with CoreWeave down -25.21% last week (-11.91% Friday), whilst CoreWeave’s 5yr CDS was up +225bps on the week to 1128bps. Meanwhile, Oracle’s share price was down -9.31% (-4.64% Friday), and their 5yr CDS was up +44bps to 300bps. So given the weighting of tech in US equities more broadly, that meant the S&P 500 took a hit as well, with the index down -1.94% last week (-1.09% Friday). However, that selloff in the AI space didn’t carry over to other sectors in general, with the equal-weighted S&P 500 posting a weekly gain of +0.50% (-0.40% Friday). Moreover, European equities actually posted solid gains, with the STOXX 600 up +2.13% (+0.72% Friday), marking its best weekly performance since July. That said, some indices more exposed to chip stocks struggled, and Japan’s Nikkei fell -5.37% (+1.39% Friday), marking its worst week since July.
As all that was happening, AI-related growth concerns helped to drive a decent rally for sovereign bonds, with the US 10yr Treasury yield down -16.5bps last week (+1.5bps Friday) to 5.07%. Indeed, it was the biggest weekly decline for the 10yr yield since August 2025, whilst the 30yr Treasury yield fell -17.5bps (+1.5bps Friday) in its biggest weekly decline since April 2025. Interestingly, that came despite some very hawkish data last week, as the US core CPI print was at +0.3% in September, which briefly saw futures price in a greater-than-50% chance of a hike at the Fed’s October meeting. However, the AI selloff then meant that quickly unwound, and Fed Chair Warsh’s comments at the end of the week saw market pricing for an October Fed hike at 17% by the close on Friday.
Staying on rates, last week saw the stress around French bonds continue to stabilise. Indeed, the 2yr Franco-German spread came down another -4.5bps to 47bps, whilst the 10yr spread was broadly steady, up just +0.5bps at 137bps. We’ll see what the weekend riots do to sentiment this morning. That came alongside a wider decline in sovereign bond yields across the continent, with 10yr bund yields down -5.5bps (+1.3bps Friday) to 3.42%. Nevertheless, there was more stress in HY credit, with Euro HY spreads up +12bps last week, and US HY up +24bps as well. However, IG spreads were more contained, with Euro IG down -2bps, and US IG up +3bps.
Finally, the risk-off tone wasn’t helped by the continued rise in oil prices, with Brent crude up +4.91% last week (+3.72% Friday) to $109.86/bbl. That marks a second consecutive weekly increase, and it also came alongside fresh gains for European natural gas futures, which moved up +7.51% last week to their highest level since 2022, at €87.55/MWh. So that exacerbated inflation concerns in Europe and saw the 1yr Euro inflation swap rise another +21bps last week to +3.69%. And similarly in the US, the 1yr inflation swap was up +17bps last week to +2.74%.