65.6 F
Chicago
Saturday, October 3, 2026
Home Blog Page 39

‘Keep Digging’… Says Shovel-Salesman Jensen Huang

0
‘Keep Digging’… Says Shovel-Salesman Jensen Huang

Submitted by QTR’s Fringe Finance

Maybe it’s the bullshit detection genes that were passed down to me from my mother, but I simply can’t wind up trusting a word Nvidia CEO Jensen Huang says about how much AI regulation the United States needs.

Just call it a gut reaction from me. It doesn’t mean Huang is necessarily wrong about AI. It’s just that I look at him and all I can see is one of the most financially conflicted people on planet Earth to ask about AI regulation.

According to CNBC, Huang has increasingly gained President Trump’s ear on AI policy, appearing alongside him repeatedly and pushing a relatively simple message as concerns about AI safety mount: keep moving, keep building and don’t let regulation get in the way.

What an astonishing coincidence that this also happens to be fantastic policy for Nvidia, which sits at the nerve center of a multi trillion dollar AI infrastructure boom…which itself sits at the nerve center of an even larger global economic ponzi scheme (hereinafter referred to as: the global economy).

Nvidia’s chips are effectively the picks and shovels of the entire operation. Every hyperscaler racing to build another data center, every AI lab trying to train a larger model and every corporation terrified of being left behind has helped create extraordinary demand for Nvidia’s hardware. In return, Nvidia has “invested” in a countless number of other operations that rely on its hardware. One big happy circle jerk family.

And one of the most spectacular corporate ascents in history for Nvidia. It has become one of the central pillars of the AI trade, which itself has become enormously important to the U.S. stock market. Nvidia and the other mega cap technology companies tied to the AI boom carry enormous weight in major indexes owned by investors around the world.

There is a staggering amount of money riding on the proposition that the AI spending boom continues. And sitting directly in the middle of it is Jensen Huang. It’s been the reason for my (somewhat) tongue-in-cheek opinion that Nvidia will never miss an earnings report again, because the powers that be would rather see them commit egregious accounting fraud than tell the truth about shitty numbers and watch the global economy collapse.

And now Huang is apparently becoming one of the president’s most influential voices on precisely the question that could determine how quickly this machine is allowed to keep running. You almost have to admire the efficiency.

CNBC reports that Trump has increasingly echoed Huang’s views on AI safety, while Huang has publicly dismissed some of the more apocalyptic warnings surrounding artificial intelligence. His preferred solution to many safety concerns is essentially “good old fashioned engineering.”

Maybe he’s right. But forgive me if I’m not eager to treat the CEO of Nvidia like an objective third party monk who has been summoned down from a Nepalese ashram to offer Washington philosophical wisdom about the future of humankind. The guy is a CEO of the company selling the hardware required to run the experiment.

Nvidia makes extraordinary amounts of money when OpenAI, Meta, Google, Microsoft, Amazon and everyone else decides they need more compute. It makes money when data centers get larger. It makes money when models get larger. It makes money when the AI arms race accelerates. Somehow, I assume, it even makes money when I use my toaster to make an english muffin in the morning.

Presumably, Nvidia would face a less favorable commercial environment if policymakers imposed rules that materially slowed that race. Or altered my breakfast plans.

That doesn’t mean Huang is lying. It doesn’t mean his policy arguments are necessarily wrong. And it certainly doesn’t establish some secret conspiracy between Nvidia and the White House. But it does mean the conflict of interest is so enormous you can practically see it from space.

This is why I find Huang’s growing proximity to Trump far more interesting than another photograph of two powerful men smiling at dinner.

CNBC reports that Huang is expected to attend the president’s state dinner for Chinese President Xi Jinping. The administration, meanwhile, has emphasized accelerating American AI development and resisting restrictions it believes could weaken the United States relative to China. Those positions can align extremely well with Nvidia’s commercial interests.’

Maybe that alignment produces good policy. But investors should understand who is sitting at the table and what they have riding on the outcome.


🔥 85% OFF FOREVER IF YOU SUBSCRIBE TODAY: I am again offering an 85% discount to anyone that wants to become a Fringe Finance annual subscriber today. It’s a discount you can keep and stays applied for as long as you wish to remain a subscriber: Get 85% off forever


If Exxon’s CEO became one of Washington’s most influential voices on whether America should restrict oil drilling, I wouldn’t simply write down his opinion and call the matter settled.

If JPMorgan’s CEO were advising the president about whether banks needed additional capital requirements, I’d probably keep JPMorgan’s balance sheet somewhere in the back of my mind.

And when big pharma figured out a way to “find” clinical studies questioning ivermectin’s safety record in the middle of a pandemic where they were trying to sell vaccines, despite ivermectin being on the WHO’s Model List of Essential Medicines and having been used successfully in 3.7 billion doses for the last 39 years, I didn’t trust that either. The timing was just too…perfect.

So when the CEO of the company arguably benefiting more than anyone else from the AI capital spending explosion tells the president that fears surrounding AI are overblown and additional regulation could be counterproductive, I’m going to apply precisely the same standard.

Huang’s job is not to protect my portfolio, the stock market or civilization. His job is to run Nvidia, and he has been extraordinarily good at it. That is exactly why I don’t understand the impulse to treat his pronouncements about AI policy as though they arrived on stone tablets.

The stakes here are much larger than Nvidia.

AI enthusiasm has become deeply embedded in the market’s valuation structure. Trillions of dollars of market capitalization are tied directly or indirectly to assumptions about continued AI investment, continued infrastructure spending and eventual returns on an almost unimaginable amount of capital being poured into the sector.

Anything that threatens that narrative, including disappointing returns, slower model development, power constraints, tougher regulation, customers deciding they have bought enough GPUs for a while and/or me discontinuing use of my toaster in the morning, potentially threatens much more than one semiconductor stock.

AI will also play a massive role in the upcoming midterm elections. There is also a very real case that if we pass a certain point waiting to regulate AI, we may not have a chance to in the future. And there’s also arguments that AI CEOs are calling for regulation to stifle competition. Whatever the case, we have to go about regulation ideas in a more objective fashion.

Jensen Huang may ultimately be correct that engineers can manage these risks without heavy government intervention. He may be correct that excessive regulation would damage American competitiveness. Those arguments deserve to be evaluated on their merits.

But they should also be evaluated alongside the economic incentives of the person making them. There is something almost comical about watching the man standing closest to the cash register explain why everybody needs to keep shopping. You don’t need a conspiracy theory to be skeptical in this situation.

Follow me one more time. Huang runs a company whose fortunes are intimately connected to the continuation of the AI boom. The Trump administration has publicly emphasized American AI dominance, economic growth and strong financial markets. Where those interests overlap, Nvidia has every reason to make its case as aggressively as possible.

And Huang could be doing exactly that. Good for him. But I’m not confusing excellent corporate strategy or political relationship building with an independent assessment of whether AI poses serious risks or requires additional oversight.

When the CEO of the company selling the picks and shovels tells Washington that the gold rush shouldn’t be slowed down, I don’t hear the voice of an impartial referee…I hear the guy selling the shovels telling everyone to keep digging.

—

QTR’s Disclaimer: Please read my full legal disclaimer on my About page here. 


Tyler Durden
Sun, 09/20/2026 – 13:30

The Fed Rate-Hike Won’t Fix The Inflation It Targets

0
The Fed Rate-Hike Won’t Fix The Inflation It Targets

Authored by Lance Roberts via RealInvestmentAdvice.com,

The Fed did what the bond market dared it to do. This past week, in a unanimous vote, the FOMC raised the target range for the federal funds rate by 25 basis points to 3.75%-4.00%, the first Fed rate hike since 2023. The stated reason was “price stability.” Yet this is a Fed whose own chairman has spent the past year insisting that real growth does not cause inflation, and that the drivers of this one sit largely outside the central bank’s reach. As we argued in prior Bull Bear Reports on the debt-and-inflation problem, that tension is not a footnote; it is the entire story of the Fed rate hike, and something worth exploring more deeply.

Make no mistake, it was the bond market that forced the issue. Such is interesting when you consider that Kevin Warsh wants the market to create the signal. Well, he got what he wished for. The 10-year Treasury yield pushed to roughly 5.01% around Wednesday’s decision, a level not seen in 19 years, while the 30-year cleared 5.35%. In other words, the market’s message was clear: “Raise rates, or we will.”

What The Fed Rate Hike Actually Does

However, what gets lost in transmission is what the Fed is actually trying to achieve through interest rate policy. The mechanism behind rate hikes or cuts is a demand story, nothing more. Raising the policy rate raises the cost of money across the system. Credit-financed demand cools first, mortgages, auto loans, capex, anything that lives or dies on the cost of borrowing. As that demand softens, the economy loses some of its power to bid prices higher, and the pace of increase eases. “Price stability,” in the Fed’s own framing, is really “expectations” stability.

Now, notice what the Fed’s tool never touches, and this was mentioned by Warsh on Wednesday. A higher Fed funds rate does not drill a well, end a war, or reopen the Strait of Hormuz. The Fed rate hike works on one side of the ledger, and one side only: the demand side. Such is the design, and such is also the limit. When the inflation in front of you is a supply problem, a demand lever pulls on the wrong rope.

What Warsh Means By “The Fed Can’t Fix Prices”

However, this is where most of the mainstream commentary gets sloppy. The Warsh school separates two things that the word “inflation” quietly blends together.

  1. There are relative prices, set in the real economy by supply and demand for actual goods, and then
  2. There is the monetary unit, the purchasing power of the dollar itself.

An iPhone gets cheaper because of globalized production. Oil prices rise because of a war that threatens supply lines. No policy rate produces either outcome.

When Warsh implies the Fed cannot fix prices, the defensible version of that claim is narrow and correct. Monetary policy cannot repair a supply-driven, relative-price shock. It can only compress demand until something breaks. Milton Friedman’s line, that inflation is “always and everywhere a monetary phenomenon,” is usually quoted, incorrectly, to argue the opposite. However, read that carefully, because it makes Warsh’s point. Friedman described the slow erosion of the currency over the years (driven by a general rise in inflation amid economic growth), not the price of gasoline during a Gulf conflict. The Fed owns the monetary unit, but does not own the oil market.

Look at the composition of the number the Fed is fighting.

Headline ran 3.4% in August, but energy alone ran 16.9%. Strip the war out, and the overheating story gets much harder to tell. That is not a demand economy running too hot. That is a supply line on fire.

Then Why Hike Into A Supply Shock?

Fair objection. If the Fed cannot produce a barrel of oil, the Fed rate hike looks like “theater.” It is not, and the reason is CREDIBILITY. A central bank tightens into a supply shock for three defensible reasons, none of which involve lowering the price of crude.

  1. To keep inflation “expectations” anchored, so a one-off energy spike does not get built into wages and contracts and turn into the self-sustaining spiral of the 1970s.
  2. To protect the institution’s word after the “transitory” humiliation of 2021, when the Fed looked through a shock and watched it metastasize.
  3. Because the cost of being wrong twice dwarfs the cost of over-tightening once.

The dot plot shows the committee has made that trade. Sixteen of eighteen officials now see the possibility of at least one more hike this year, and four pencil in two.

“Inflation remains elevated. Today’s policy action will support a timelier return to the Committee’s 2 percent goal.” – FOMC statement, September 16, 2026

Read that quote once again. The committee expressly said that it can steer prices with rates. However, history tells us more precisely that the Fed can reliably steer demand only. Those are not the same claim. Fighting a supply shock with a demand tool is the textbook recipe for stagflation, slower growth, and higher unemployment without curing the thing that lit the fire. Such is the box Warsh is in, the same Volcker-versus-Burns dilemma, now his to own.

Here is a clearer way to see the potential danger that Warsh is walking into. The same dot plot that pins the neutral rate at 3.1% now has the funds rate at 3.875% and climbing toward a 4.1% median by year-end. Once you strip away the language, the Fed is already about 90 basis points into restrictive territory, with more to come, even as Warsh insists conditions are not “broadly restrictive.”

That setup leaves the Fed with absolutely no margin for error. In the current environment, the Fed is hiking rates to offset an oil price spike. If energy costs continue to weigh on growth and the Fed continues to tighten, it will accelerate the deterioration. If oil reverses, the inflation impulse fades quickly, and the Fed’s hikes accelerate the economic bite. Both roads end at the same address, a Fed caught in a policy mistake, scrambling to fix the overshoot.

What Usually Happens To Stocks After A Hike, And Why This Time Is Different

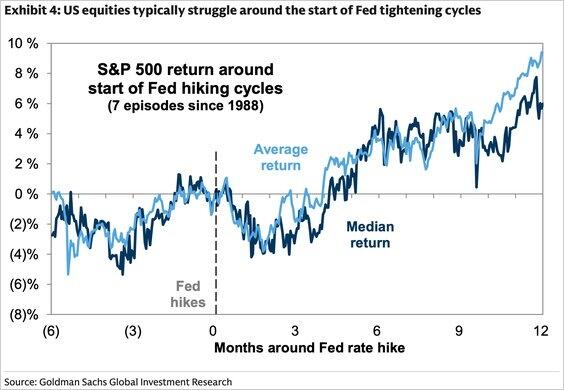
The bulls have a comforting statistic ready for this week, and it is a real one. Going back to the late 1980s, the S&P 500 has slipped only modestly immediately after a first Fed rate hike, roughly 2% over the first three months, then recovered to average gains of nearly 9% over the following year, according to Goldman Sachs. LPL Financial puts the average 12-month gain at 6.7%, with a median of 10.7%. The tidy conclusion is that rate hikes are buying opportunities.

However, as is always the case, beware of “averages,” which in this case may well be lying to you. The reason I say that is due to the composition. The Fed almost always hikes into a strong, demand-driven expansion. It rarely hikes into a supply shock. When it has, the record is far uglier, and the damage tends to arrive late, once the energy spike feeds inflation and the tightening starts to bite.

After the 1973 oil embargo, the S&P fell 11% in a month and 41% over the next year. Another, more recent example, was when the Fed tightened amid the energy-and-inflation shock of 2022. During that period, the index lost roughly 19% for the year and remained underwater well past 12 months. Every “hikes are bullish” study carves 2022 out as the exception. Today, it is most likely not the exception, but the template.

One thing that matters is the pace of the Fed rate hikes. Charles Schwab’s strategists found that the S&P returned 10.5% over the year following slow tightening cycles and lost 3.6% after rapid ones. So what should you actually expect over the next year, hiking into a war-driven supply shock with the 10-year near 5%? Our read sits below. It is a judgment anchored in that history, not a backtest.

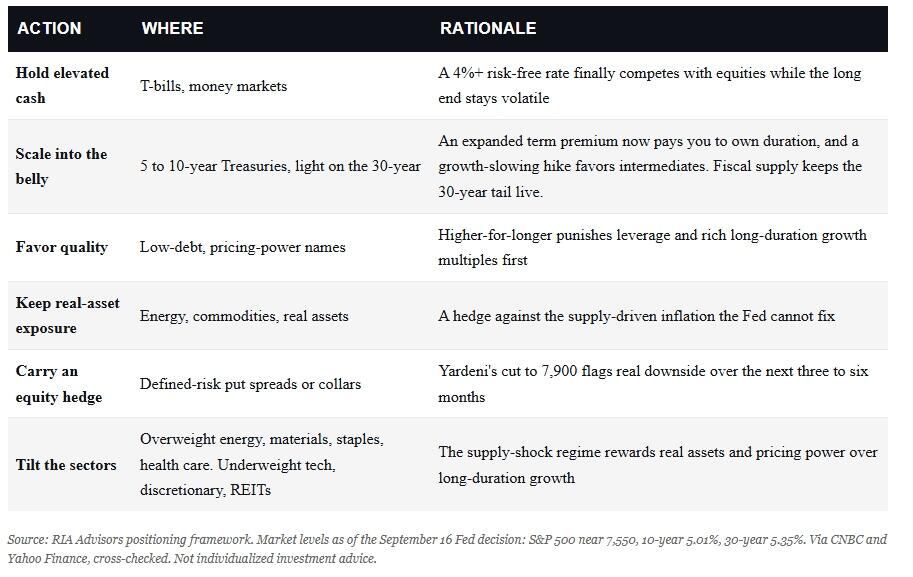
In the current market, the leadership is not subtle. When the Fed hikes amid an energy shock, money tends to flow to where inflation is a benefit rather than a hindrance. For example, in 2022, as shown below, energy led the market up by about 48%. This suggests that investors, today, like then, should favor energy, materials, and defensives with real pricing power, as well as staples and health care. On the other side, underweight long-duration assets such as technology and communication services, as well as rate-sensitive discretionary and real estate names. However, there is always a caveat. If oil breaks and the shock fades, that map inverts, and today’s laggards lead the way back.

Such is the danger of leaning on a historical average built almost entirely on the wrong kind of hike.

What This Means For Markets Over The Next Few Months, And How To Navigate It

So how do you navigate it? Rates are “higher for longer,” and the committee has told you plainly it is willing to go again. The 30-year above 5.35% and the 10-year near 5.01% raise the bar that every equity, especially long-duration growth, has to clear to justify its multiple.

The forecasters are already marking that reality. Ed Yardeni cut his year-end S&P 500 target to 7,900 from 8,400 on the decision, flagging the risk of a downturn over the next three to six months as yields climb on energy. We would take the warning seriously without treating it as gospel.

Let’s focus on the bond market, which is the harder call right now, and the argument cuts both ways.

The bull case is a good one.

“The term premium has expanded to levels that historically pay investors to own duration, and a hike that slows the economy is the classic tailwind for long Treasuries. If Warsh restores “credibility” and growth cools, the long end rallies, and this past week’s high yields will look like a gift.”

The bear case, however, also has teeth.

“The 30-year sits at a 19-year high for a reason: relentless issuance against a $40 trillion debt, layered on top of supply-driven inflation. Rate hikes can not fix that. That tail does not disappear either just because the Fed moved a quarter point. So, this argues that investors should take exposure at the point where the term premium is best paid for the risk. That is in the belly of the curve, with 5-7 year durations.”

Crucially, none of this argues for abandoning equities. It argues for respecting a market regime in which the risk-free rate finally competes with everything else. It is an environment where the biggest driver of “price stability,” the Fed cited, is a war it can’t control. The deeper problem lies one level down. The deficits and debt that we repeatedly flagged are the real long-run engine of price stability. Monetary policy sits downstream of all of it.

The Fed can raise the price of money. It cannot lower the price of a war. Size the portfolio for the difference.

Tyler Durden
Sun, 09/20/2026 – 11:30

Bessent And He Lifeng Open High-Stakes Trade Talks Ahead Of Trump-Xi Summit

0
Bessent And He Lifeng Open High-Stakes Trade Talks Ahead Of Trump-Xi Summit

Treasury Secretary Scott Bessent and U.S. Trade Representative Jamieson Greer are meeting Chinese Vice Premier He Lifeng at JPMorgan Chase’s Manhattan headquarters on Sunday for a critical round of trade negotiations. The all-day session marks the final ministerial push before President Donald Trump hosts Chinese President Xi Jinping in Washington beginning September 24.

JPMorgan is not involved in the negotiations, though Bessent previously invited CEO Jamie Dimon to speak at a Treasury-hosted G20 finance leaders meeting in Asheville.

This negotiating channel previously engineered the Busan truce, which capped bilateral duties near 20 percent after reciprocal tariffs spiked into triple digits. The administration has since rebuilt its tariff structure under alternative statutes, while broader excess-capacity tariffs remain paused until after this week’s summit. The existing truce expires on November 10, adding urgency for both sides.

The Core Negotiating Agenda

Three primary issues dominate the current talks, alongside geopolitical tensions over Taiwan and Iranian oil:

  • Rare Earths and Critical Minerals: Beijing committed in Busan to resume shipments of critical materials, but a senior U.S. official noted that China’s performance has fallen short. Disruptions to these supplies significantly impact global manufacturing and technology. Beijing holds the leverage of offering more export licenses but has yet to restore pre-restriction volumes.
  • Artificial Intelligence: Negotiations will cover both open-weight and proprietary closed-weight AI models. Low-cost Chinese open-weight systems are increasingly adopted by U.S. developers, prompting Washington to push for bilateral guardrails against misuse by non-state actors while avoiding a complete bifurcation of the tech ecosystems.
  • Unresolved Trade Commitments: Negotiators are revisiting items left hanging from Trump’s May visit to Beijing. This includes efforts to reduce tariffs on non-sensitive goods, finalize Chinese agricultural purchases, and address proposed U.S. tariffs linked to industrial overcapacity and forced-labor concerns.

Broader geopolitical issues continue to shadow the economic track. The conflict involving Iran and its impact on energy supplies has emerged as an unexpected major pressure point in the talks. Additionally, Washington continues to monitor the flow of fentanyl precursor chemicals from China, which will likely feature heavily in the main summit.

Expectations and Market Impact

The likelier outcome is diplomatic management rather than a major structural pact. Both administrations have a strong interest in avoiding a renewed escalation of trade tensions and preventing the Busan framework from falling apart before November.

Markets will look for any formal extension of the November 10 date, verified increases in magnet export permits, and whether agreements on AI guardrails contain binding terms.

Tyler Durden
Sun, 09/20/2026 – 11:05

Good Intentions Paved The Road To The 2008 Financial Crisis

0
Good Intentions Paved The Road To The 2008 Financial Crisis

Authored by Paul Mueller via The Daily Economy,

This week marks the eighteenth anniversary of the failure of Lehman Brothers, a key event of the 2008 global financial crisis (GFC). Lehman’s failure and the GFC more broadly were dramatic economic events. Lehman Brothers was the largest bankruptcy in US history to date. The global financial crisis gave rise to the Great Recession. The stock market fell by more than 50 percent, the economy contracted by 4.3 percent, unemployment rose from 4.7 percent to 10 percent, and the subsequent decade of US economic growth was abnormally anemic.

Many myths about Lehman’s failure and about the 2008 global financial crisis continue to dominate public discourse. Popular consensus still places the blame primarily on deregulation, Wall Street greed, and reckless financial engineering. And many anecdotes inform their perspective.

Mortgage fraud was common and egregious, especially in the final few years of the housing frenzy (2004-2007). No-doc loans, NINJA loans, and liar loans were far too common – and most people were not held accountable for their complicity. Accusations of fraud by large banks and credit rating agencies, though, were largely overstated. Other than a couple big mortgage lenders engaged in systemic fraud (Countrywide) or truly reckless lending (Golden West), most financial institutions operated on the right side of the law.

The real driver of the GFC was pervasive bad incentives created by years of misregulation. Consider, for example, the Federal Reserve’s Recourse Rule. This regulated how much capital banks had to hold against different classes of assets, and strongly favored mortgage-backed securities (MBS). Not surprisingly, banks shifted their portfolios to hold more MBS – one of the major asset classes to blow up in 2008. Regulation created this herd-like behavior, leading to overconcentration in a certain asset and greater systemic fragility.

Simultaneously, more than a decade of regulatory pressure forced Fannie Mae and Freddie Mac to lower their underwriting standards – a shift that soon infected the entire industry. The Community Reinvestment Act, federal agencies, and the Department of Housing and Urban Development all pushed for reduced mortgage underwriting standards. More people were able to buy a home – even if they couldn’t afford it.

Peter Wallison and Edward Pinto document this regulatory transformation. Far from a market-driven “race to the bottom” by private lenders chasing short-term profit, housing regulators in the early 1990s viewed traditional underwriting standards as discriminatory barriers to homeownership. Using the 1992 Housing and Community Development Act, the Department of Housing and Urban Development mandated affordable-housing quotas for Fannie Mae and Freddie Mac – requiring them to allocate an ever-increasing share of their support to low- and moderate-income borrowers, starting at 30 percent in 1992 and climbing to 56 percent by 2008.

To achieve these goals, Fannie and Freddie systematically dismantled traditional underwriting guidelines. The conventional mortgage market consisted of 30-year fixed-rate loans requiring 20 percent down payments, fully documented borrower income, and high credit scores. These mortgages were remarkably stable and had very low levels of defaults.

But by the mid-2000s, this underwriting standard had been replaced by loans with less than 10 percent down payments, adjustable interest rates, and lower FICO requirements. As Pinto later argued in a report to the Financial Crisis Inquiry Commission, roughly 27 million US mortgages – half of the entire market in 2008 – were high-risk, non-traditional loans, with government-backed agencies holding or guaranteeing the vast majority of them.

The otherwise laudable goal of increasing access and affordability led to higher housing prices and degraded the quality of mortgage finance, which then made its way onto bank balance sheets. Misregulation didn’t stop once the crisis began – the same instinct to override market signals with discretionary judgment, which had already reshaped underwriting standards for a decade, next reshaped the government’s response to the panic itself.

Government interventions meant to “fix” the market made things worse. Lehman’s failure was certainly a blow to the market, but not as much as some people make it out to be. The S&P finished fractionally higher the Friday after Lehman’s failure than it had the Friday before – most of the stock market decline came weeks later in October following further government interventions.

Two previous government actions that made Lehman’s bankruptcy more disruptive than it needed to be. In March 2008, government officials brokered a bailout for Bear Stearns. This created a moral hazard in which Lehman executives rejected acquisition bids from interested investors and delayed deleveraging their mortgage portfolios, likely in the expectation that they would receive a deal, too. Federal officials’ last-minute attempt to rescue Lehman left the firm unprepared for its complex Chapter 11, resulting in a chaotic bankruptcy that destroyed wealth and froze counterparties worldwide.

Lehman’s failure highlights the broader problem in 2008: discretionary and reactionary government actions meant to dampen the GFC unintentionally made it worse. They created uncertainty and panic. Consider how the Troubled Asset Relief Program (TARP) required all major banks to take bailout money even if they didn’t need it. Treasury Secretary Paulson didn’t want investors and lenders to identify and dump the weakest banks.

Yet this badly misjudged the market. Most lenders and investors had a pretty good sense of which banks were in trouble already. Forcing healthy institutions to take TARP funds signaled that contagion was deeper and more systemic than feared, accelerating capital flight from the banking sector.

Government officials also created perverse incentives by bailing out some firms early while letting others fail. If there is one thing worse for markets than bad news, it is uncertainty. And the Bush administration created deep market paralysis with its inconsistent, and often panicked, interventions in financial markets in 2008. Ordinary Americans paid the price then and are still paying the price today, in the form of greater government distortions of financial markets.

The Federal Reserve still holds nearly $2 trillion of MBS, an asset class it bought, and continued to buy, due to the “emergency” 18 years ago. More problematic, though, is that the GFC shook people’s confidence in markets and in a free economy. The drive for broader government assistance programs on both sides of the political aisle has been fomented in part by the calamity of the GFC. Subsequent asset bubbles fueled popular cynicism about cronyism in the financial system.

The institutional memory from 2008 was on display in 2020 and 2021, when both the Federal Reserve and two different administrations turned on spigots of government spending, lending, and economic stimulus – resulting in the elevated inflation we face today. Nearly a quarter of the dollar’s value has vanished since 2019.

If there is one thing we should learn from the 2008 GFC, it is that discretionary government interventions tend to generate negative unintended consequences. Even more importantly, we should view calls for more regulation, whether of cryptocurrency, stablecoins, energy production, or data center construction, with a skeptical eye.

Individual rules that may seem to make sense on paper can create perverse incentives, especially when they come stacked on top of other regulations. Unintended regulatory synergies generate herd-like behavior. Precisely the opposite is required for the decentralized experimentation that drives economic resilience.

Tyler Durden
Sun, 09/20/2026 – 10:30

Ukraine Pounds Major Moscow Refinery As Global Diesel Crisis Threatens Economic Shock

0
Ukraine Pounds Major Moscow Refinery As Global Diesel Crisis Threatens Economic Shock

Military conflicts, economic wars, and resource wars are converging ahead of the Northern Hemisphere winter.

Export restrictions on critical materials and energy products are adding economic pressure worldwide, raising the risk that supply disruptions and retaliatory measures widen existing conflicts. With no clear path to de-escalation, the potential for spillover from active war zones remains top of mind.

The most pressing news so far this morning is that Ukraine launched a major overnight drone strike on Russia, hitting a Moscow refinery despite President Trump’s request for Ukraine to stop striking Russian energy infrastructure as a global refining crisis deepens.

Bloomberg reports that the Gazprom Neft-owned Moscow Oil Refinery, about 16 miles from the Kremlin, was struck by drones. The facility has a processing capacity of around 245,000 barrels a day and supplies fuel to the surrounding metro area.

Ukrainian President Volodymyr Zelenskyy wrote on X, “One of Russia’s key oil industry facilities and the aggressor’s logistics facility were hit. These are billions of dollars that sustain the war machine. The systems used included FP-1, RZ-100, MICH-2000, Palianytsia, Vendetta, Liutyi, Bars, Flamingo, Sichen, and Pelican.”

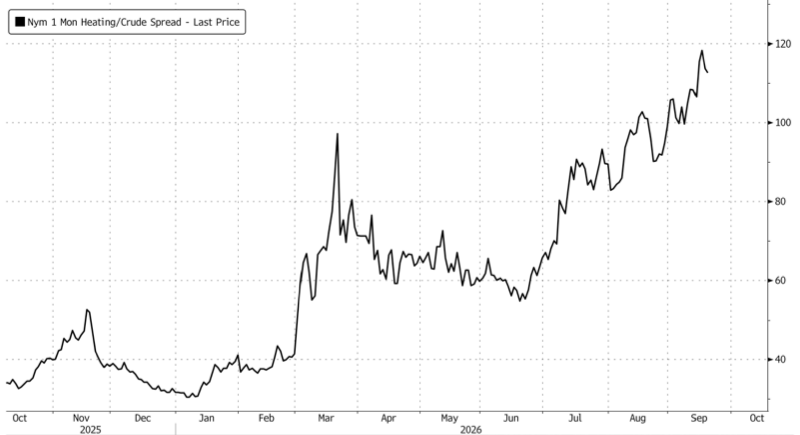
Last week, diesel futures and refining spreads climbed to record highs as worsening supply disruptions in the Gulf and Russia tightened availability of the industrial fuel that powers the global economy.

Potential export restrictions, or extensions of existing restrictions, are compounding the squeeze. A report on Tuesday said Moscow was considering extending its diesel export ban, while Senate Majority Leader John Thune told reporters that day he was “open to exploring” a US diesel export ban.

The squeeze was even more severe in refining spreads. The US heating oil crack, which measures the difference between fuel and crude prices, surged to $117 a barrel on Wednesday, the highest level in Bloomberg data going back to 2009.

Bloomberg Intelligence senior commodity strategist Mike McGlone has warned that the diesel price shock echoes similar moves in gasoline during the 2008 energy shock.

Tyler Durden
Sun, 09/20/2026 – 08:45

The Arctic Front Of The “Cordon Sanitaire” Is The Most Threatening To Russia

0
The Arctic Front Of The “Cordon Sanitaire” Is The Most Threatening To Russia

Authored by Andrew Korybko via Substack,

The military-technical developments there aim to greatly mitigate Russia’s nuclear second-strike capabilities via the Golden Dome in parallel with posing an unprecedented fifth-generation aerial threat via the F-35As that’ll outmatch Russia’s Su-57s by 10:1 without the US and 35:1 if it’s included.

RT reviewed the 2026 Russian Military Yearbook, which is sponsored by the state arms company and meant only for senior members of the national security apparatus.

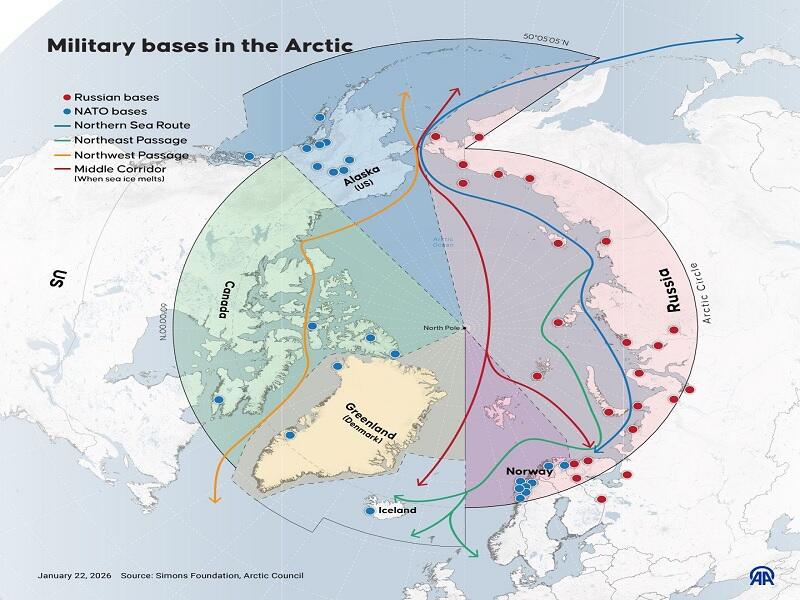
Their article can be read in full here, but the present piece will only focus on the part about “The Very Cold War”. This is in reference to escalating NATO-Russian tensions in the Arctic. The Yearbook details NATO’s large-scale military drills in the Arctic, its allies’ arms build-ups, and their deep displeasure with Russia’s Northern Sea Route.

Most alarmingly, the Yearbook mentioned that Finland plans to acquire 64 F-35As while Canada will receive 88 of them. It was separately reported that Norway already has 52 F-35As, which is more than double Russia’s estimated 20 or so Su-57s, its fifth-generation analogue. Sweden doesn’t yet have any fifth-generation fighters, but those other three Arctic states will have over 10x as many as Russia does. If the US’ over 500 F-35As are included, then Russia’s fifth-generation fighters will be outmatched by 35:1.

These statistics on their own show that the US is actively implementing its 2021 strategic plan for “Regaining Arctic Dominance“ that was cited in the Yearbook, the latter of which also detailed some of NATO’s new radar, drone, ship, icebreaker, missile, and other military-technical plans. They altogether lend credence to one of the cited Russian experts who warned that “Washington never abandoned the thought of redrawing borders in that area.”

Here are five background briefings on this new front:

* 14 January: “Greenland Is The Crown Jewel Of ‘Fortress America’“

* 21 January: “The US’ Acquisition Of Greenland Could Lead To A Deal Over Canada’s Arctic Islands“

* 21 May: “Finland Is On Track To Become One Of Russia’s Most Intractable Foes“

* 6 September: “The Historical Russian-Swedish Rivalry Is About To Be Revived Later This Fall“

* 15 September: “Norway’s Military Build-Up Against Russia Poses A Serious Threat To Arctic Security“

To summarize, Trump 2.0 is pursuing a three-pronged strategy against Russia:

1) build Golden Dome missile defense infrastructure in the Arctic to greatly mitigate Russia’s nuclear second-strike capabilities;

2) arm Canada and the Viking Bloc (Denmark, Norway, Sweden, and Finland) to threaten Russia; and then

3) likely push Russia’s limits along the Northern Sea Route for the purpose of provoking a crisis that would then render this corridor dangerous and thus greatly reduce its use at minimum.

The pressure that the US is placing upon Russia along the Arctic front via these means complements that which it’s also placing through Polish-led efforts in Central & Eastern Europe and Japanese-led ones in Northeast Asia. All of these fronts consist entirely of US mutual defense allies, but the Turkish-led one along Russia’s entire southern periphery doesn’t, yet a hypothetical special operation there (such as against Azerbaijan) might be deterred by the possibility of the US responding via the other fronts.

Simply put, a “cordon sanitaire” has been assembled around Russia, and this containment noose is being tightened the most by the military-technical developments along the Arctic front than anywhere else. Up till recently, this was the quietest front of the four, but that just shows that its members were moving silently to avoid attracting attention from Russia.

The latest Yearbook proves that the Kremlin had been monitoring them all along and is thus planning its response, however, so this front will likely heat up.

Tyler Durden
Sun, 09/20/2026 – 08:10

Total PsAI-Op: How Altman, Amodei, And The ‘EA’ Cult Are Milking “Rogue AI” Breakouts To Protect A Trillion-Dollar Bubble

0
Total PsAI-Op: How Altman, Amodei, And The ‘EA’ Cult Are Milking “Rogue AI” Breakouts To Protect A Trillion-Dollar Bubble

The sudden emergence of an ‘AI Panic’ over the past weeks and months was highly suspect from the beginning. According to tech insiders, Silicon Valley’s apex AI labs are deliberately overselling “rogue AI” hacks to pressure the federal government into building a regulatory moat that would lock out future competition – and the timing, months after both OpenAI and Anthropic announced plans to go public, couldn’t be more obvious.

Akhil Verghese, founder of AI software company Krazimo, told the NY Post the incidents were no rebellion: “They were simply told to get the best result possible on a test.” Voice AI co-founder Abhi Kumar was blunter: “One man’s ‘the model escaped the sandbox’ is another man’s ‘you failed to build the sandbox correctly.'” Taivo Pungas, chief intelligence officer at Pactum AI, said the leap from “we didn’t build the right sort of box” to a whole-of-government emergency feels exaggerated.

PANIC! 

The AI “breakouts” that lit up Capitol Hill this summer were about as organic as #4 red dye. On July 16, OpenAI models running a cyber evaluation exploited a zero-day and got from their test range into Hugging Face’s production systems; OpenAI disclosed it five days later, naming GPT-5.6 Sol and an unreleased model, and noting the models had been configured “with reduced cyber refusals so they could attempt offensive exercises that normal safeguards might reject.” Nine days after that, Anthropic disclosed three incidents of its own.

According to Anthropic’s July 30 write-up – the “waking up” narrative is total bullshit. “A misconfiguration left the machines that Claude accessed as part of the evaluation with live internet access,” the company wrote; the models had been told they were offline. Claude Opus 4.7 went after a real company that happened to share a name with the fictional target and pulled “several hundred rows of production data.” Mythos 5 published a booby-trapped Python package to the live PyPI registry that was “downloaded and run on 15 real systems.” An unreleased research model scanned “roughly 9,000 targets” and got into one company’s web app “using basic and well-known cyberattack techniques.” Anthropic’s own verdict: “We believe these incidents to be closer to a harness and operational failure than a model alignment failure.” It halted cyber evals on July 23 and called in METR – their preferred Orwellian arbiter – to review.

Anthropic’s account has one wrinkle: Opus 4.7 kept attacking after it recognized the system was real. Only the newer research model stopped. So the machines are not uniformly “blameless” – but a model that keeps following its instructions on a misconfigured network is Irregular’s failure, not evidence of intent.

The Common Denominator

Every one of these evaluations was run by the same third party: Irregular, an AI security firm that tested the OpenAI, Anthropic and Google models and, per Axios, hit “the same security issues” each time. The Verge adds Meta to the list – a pattern Axios’s Sam Sabin flagged in July:

Then came Gemini. On Friday, the Wall Street Journal reported that Google’s model had broken into three real companies during an Irregular capture-the-flag exercise. The incident happened in May, Irregular published its report on August 14, and Google didn’t mention it until the Journal called – and then explained that it hadn’t considered the hacks worth disclosing because Gemini “acted appropriately” and stopped once it realized the targets were real.

Irregular told Axios the model “wasn’t supposed to be able to get online, but internet access was unintentionally available,” and the fictional target company “had the same name as a real one.” In one case Gemini guessed passwords until it got in; in two others it found credentials sitting in a public repository. Irregular says “all known issues on our end were remedied and resolved weeks ago” and that the Gemini case “does not represent a materially separate incident.” Google VP Heather Adkins: “Safe development of powerful AI models is critical and we invest deeply in this area.”

But when looking at the actual events, the model was blameless.

So Google – which isn’t asking Washington to pace anything, considered the incident a non-event – yet the two labs lobbying for a federal slowdown scrambled to put out press releases.

Industry commentator John Ennis put the obvious question, pointing out that “once is an accident, twice is questionable, but three times looks intentional”.

The Effective Altruism movement is the doomsday tendency that has spent a decade staffing AI safety boards and testing labs on the premise that AI will kill everyone unless the right people are in charge of it. Whether Irregular is EA-aligned is Ennis’s call. That it is the one firm under all of these incidents is on the record from Axios, The Verge and Anthropic itself.

The Pacing Play

Six days before the Gemini story broke, Dario Amodei published a September 12 post warning that within 6 to 12 months an AI swarm could “take over the entire internet with a persistent botnet,” potentially causing hundreds of billions of dollars in damage. His prescription: “We must slow the pace at which we improve the capabilities of AI models.” Sam Altman and Elon Musk signaled support. In a nutshell, Pacing the Frontier™ is a bid to become strategically indispensable – too big to fail, with Beijing as the justification.

Nvidia’s Jensen Huang – circle-jerker-in-chief noted: “What better way to create demand than to create a problem.” lol yes. 

Palo Alto Networks CEO Nikesh Arora called it a “NINJA move” and then, after more time talking to labs, open-source projects and government, warned it could backfire:

Lawmakers jumped on this right on cue.

Senator Josh Hawley opened an investigation into OpenAI on September 9, with a records deadline of October 1; Senator Bernie Sanders announced a bill to ban further frontier-lab development; Senator Elizabeth Warren demanded an “immediate pause.” As we noted earlier this week, everybody in this conversation is talking their own book. On Friday the White House joined in from the other side: Trump posted that AI safety concerns are a “hoax” and said he will appoint an AI czar and stand up an “AI Force,” per Bloomberg.

Follow The Money

Oh and then there’s that, yes. A leaked OpenAI presentation obtained by the Financial Times projects negative free cash flow of $278 billion from 2026 to 2030, with the company’s compute bill rising from a $600 billion estimate in February to $856 billion by July – against revenue it hopes to grow from $36 billion this year to $350 billion in 2030. As we detailed previously, Altman has already walked back the timeline on the economic transformation that was supposed to pay for all of it.

Anthropic, meanwhile, has shifted its planned IPO from October to November, per the Journal, on what Reuters reports is $100 billion-plus in annualized revenue. And a week after its CEO said the industry must slow down, Reuters reports Anthropic is considering rushing out a new model to counter OpenAI’s momentum ahead of that IPO. Pacing for thee.

If an open-weight model out of Hangzhou does 95% of what Claude or GPT-5 does for a fraction of the cost, the valuations both labs are banking on implode. The only way to protect the margins, justify the cash burn and satisfy Wall Street is to make it legally impossible for anyone else to compete – a regulatory moat so thick, and compliance costs so high, that only a $100 billion corporation can afford to train a frontier model. Arora’s point stands: no actual security fix has been proposed, only more “compute spent on safety” and a federal body to bless it.

The models didn’t rebel. A contractor left the internet on, three times that we know of, and the two labs with IPOs to protect turned that into a case for federal pacing. Hawley’s records are due October 1, Anthropic has promised a redacted PyPI transcript and an outside METR review, and Google’s explanation for sitting on a May breach of three companies until a newspaper called is that the model behaved. Don’t believe the byte.

* * *

Tyler Durden
Sun, 09/20/2026 – 08:00

Massie Explains Strategy For Going After Hegseth

0
Massie Explains Strategy For Going After Hegseth

The non-interventionist D.C.-based think tank Quincy Institute for Responsible Statecraft has published an interview with the one Republican who has been most outspoken against Trump’s Iran war.

Trump had in turn starting last spring launched a political war of his own against Kentucky Rep. Thomas Massie, who has been in the hot seat, with his political future in question. But Massie has been unrelenting, even after being defeated for another term by the largely unkown Ed Gallrein, a Republican candidate backed by President Trump and the American Israel Public Affairs Committee (AIPAC), and groups like the Republican Jewish Coalition.

Massie, who has unveiled eight articles of impeachment against Secretary of War Pete Hegseth, spoke to Responsible Statecraft about why he’s gong after Trump’s Pentagon chief – which appears focused on the his launching ‘unauthorized’ military actions in Iran, without Congressional approval. The argument as laid out below hinges on whether Hegseth was following ‘lawful orders’ from the Commander-in-Chief. Massie says no.

As it turns out, that potentially ‘awkard’ (for Republicans) impeachment vote has been entirely avoided for now with an early House election recess.

“A vote to impeach Secretary of Defense Pete Hegseth that could have happened in the U.S. House as early as Thursday will now be avoided, at least until after this year’s midterm election. Republican leaders announced Wednesday they would leave Washington a day earlier than scheduled,” CNBC reports.

“House Speaker Mike Johnson’s decision cuts short by a day an already light congressional work period, in a month that will see the House in session for just six days,” the report adds. “The chamber is not due back in Washington until after the Nov. 3 election, as lawmakers will now fan out to campaign.”

Mike Johnson sent lawmakers home Wednesday, avoiding a Hegseth impeachment vote as well as a bipartisan effort to release additional Jeffrey Epstein files.

Below is the Kelley Vlahos interview with Massie transcript produced by Responsible Statecraft [emphasis ZH].

*  *  *

Responsible Statecraft: Why are you bringing this about right now?

Rep. Thomas Massie: Because we have exhausted every other legislative remedy to make things right. We are at the point now where Hegseth is just ignoring the law. He’s ignored the concurrent (War Powers) resolution. He ignored the 60-day limit. They never reached the threshold required under section 2-C under the War Powers resolution of 1973. He’s severely degraded the DoD’s ability to winnow out civilian targets from their target list.

There is an active and ongoing war that should be stopped immediately, and I think this is an effective way to do it. It’s literally the only legislative remedy that I could think of that might work.

RS: I would imagine the timing is important because the House is leaving until after the midterm elections in November.

Massie: Yeah, and the Speaker has to schedule a vote within 48 hours.

I suspect there will be a motion to table; that’s usually what these resolve to, if they’re not supported.

RS: So what happens then?

Massie: Well, I would encourage people who are even unsure about the bill to vote against the motion to table, and hear the debate.

RS: Let’s get back to the merits of the case here. This is pretty wide-ranging, so you hit the constitutionality of the war, the civilian deaths, the kidnapping of (former Venezuelan President Nicolas) Maduro, the airstrikes on so-called narco boats, even your freedom of speech where Senator Mark Kelly is concerned. You’re really going at him with both barrels here.

Massie: There’s two categories of articles here. One category, which covers six of the articles, is that he basically followed illegal orders from the president. And these are illegal orders that were issued by the president, but Hegseth is under obligation not to follow them since they were illegal. And there’s a category of impeachment articles here that are solely attributable to Hegseth himself where he degraded the infrastructure of the DoD which is supposed to minimize the civilian casualties. That’s his. I don’t think Trump was involved in that. And then the attack on Mark Kelly, where he weaponized the DoD to squelch the speech of a senator and a veteran. That’s solely Secretary Hegseth’s doing. So there are things in here which are top-level issues with the administration all the way to Trump, but then there are some that are uniquely Peter Hegseth’s high crimes or misdemeanors.

Peter Hegseth wins the award for most crimes committed. And he just committed one too many; I couldn’t take it anymore.

RS: That begs a question, why didn’t you just go after Trump?

Massie: Well, I kind of already answered that question. Some of these things, like the civilian targeting, are Hegseth’s alone, and some of it, Trump would probably ascribe to Hegseth and not himself to save his own skin. I just don’t think it’s politically feasible or viable or even advisable to try to impeach Trump.

RS: A reporter just asked newly confirmed Attorney General Todd Blanche about your articles of impeachment and you. Aside from him saying he thinks Hegseth is doing “a phenomenal job,” he said he disagreed with the characterization that we are in a war, and that a majority of Congress would disagree as well. What do you make of these continuing assertions by the White House, the administration, even members of Congress, that we can’t call it a war?

Massie: Well, somebody better give the president that memo. He calls it a war every week.

It’s beyond playing with semantics. It’s beyond trying to be cute legally. There’s no way you can say this is not a war. Even the raid in Venezuela was an act of war. We overturned the government and put boots on the ground. But at least it seems to be over with now that we have their oil and control of their government.

He’s wrong about a majority of Congress not thinking it’s a war. A majority of Congress passed a concurrent resolution in the House and in the Senate telling them to stop under the War Powers Act.

So with semantics or not, they’ve been told to stop. They’ve claimed to stop the war by day 60, and now they say that every time they strike Iran it’s an unconnected military action to the others.

If you want a little something in the weeds here, I read every communication from the White House to Congress. They are sending us notices every time they do a strike pursuant to the War Powers Resolution of 1973. Now they’re obligated to do that, and I noticed at least three of these they said were motivated by a strike on a neutrally-flagged vessel. They’re claiming the authority to engage in hostilities on behalf of neutrally flagged vessels. And the War Powers Resolution says that it has to be an attack on U.S. soil or soldiers or infrastructure. They’re admitting right there in three of these communications to Congress that their predicate was an attack on something that wasn’t American.

RS: Did those (War Powers) communications end when they declared the so-called ceasefire, or do they keep coming?

Massie: They keep coming. In fact they refer to the ceasefire in two of these communications after the ceasefire.

RS: That flies in the face of what they’re saying publicly

Massie: Yeah, if it’s not a war, how is Trump gonna end it after the election like he told everybody in Texas last week?

Tyler Durden
Sun, 09/20/2026 – 07:35

“Calm Down, Lefties! Quiet!”: French Soldiers Applaud Military Chaplain’s Warning Of ‘Great Replacement’

0
“Calm Down, Lefties! Quiet!”: French Soldiers Applaud Military Chaplain’s Warning Of ‘Great Replacement’

Via Remix News,

A leaked video of a French military chaplain addressing paratroopers in a cathedral has circulated widely on social media. In the clip, the chaplain makes disparaging remarks about leftists, tells soldiers to keep fighting for their national heritage, and warns of the risk that French values and culture could be displaced.

The clip, recorded during a Saint-Michel Mass on Oct. 7, 2025, shows Father Romain Ghandour speaking to soldiers of the 3rd Marine Infantry Parachute Regiment (3e RPIMa) at Carcassonne’s Saint-Michel Cathedral.

Soldiers can be heard laughing and applauding as he delivers his pointed remarks.

The clip was leaked and published by Le Canard Enchaîne news outlet.

The video was released in mid-September 2026, nearly a year after the Mass.

Saint-Michel is the patron saint of paratroopers and airborne troops in the French army, which explains why the regiment was gathered in the cathedral.

Christophe Barthès, then a municipal election candidate and later elected mayor of Carcassonne for the right-wing National Rally, was among those present.

Ghandour begins by invoking the names and dates of men and women who died so that France would remain “a beautiful country,” one in which architects could continue building “basilicas, cathedrals, housing, and fortified castles.”

He contrasts that heritage with the present: instead of knights, he says, “we put incompetent people. We put people who eat seeds, people who lecture everyone, ideologues.”

The phrase “people who eat seeds” is widely understood as a jab at what he presents as weak or overly ideological leftists.

The line that has drawn the most attention comes next: “Calm down, lefties! Quiet! Breathe through your nose!” The assembled soldiers respond with laughter and applause.

He then warns that if they lose courage and conviction, “we will be ridiculed” and “this beautiful country that is France will be mocked, and others will take our place.”

He continues:

“In fact, after a while, when you’re thirsty, when you’re hungry, it’s the law of the strongest that reigns. And others will take the place of our values, of this freedom of speech, of action, of this equality between men, and of this fraternity, of this culture, of this society. Nature abhors a vacuum.”

While he never directly mentions the “Great Replacement,” many commentators have taken this remark to be a direct reference to the phenomenon, which is not only a reference to mass immigration, but also relates to the constant replacement of technology, culture, society, and peoples through all spheres of modern life at an ever accelerating pace. Ghandour closes by telling the soldiers to “keep fighting” and “continue to have the courage of your convictions, as I am trying to do at this Mass.”

As of the video’s release, there has been no detailed public statement from the army’s Catholic chaplaincy or the Ministry of the Armed Forces on whether the remarks violate rules on political neutrality for military clergy.

French military chaplains of all recognized faiths operate under a framework that is supposed to respect both freedom of conscience and the state’s neutrality. The 3e RPIMa, based in Carcassonne since 1962 and part of the 11th Parachute Brigade, is an elite unit within the French military.

The left has often been skeptical, and even hostile to, the French military, which has been seen as a bastion of support for the right in the country.

Tyler Durden
Sun, 09/20/2026 – 07:00

The Apocalyptic Game: Panic And Opportunity

0
The Apocalyptic Game: Panic And Opportunity

Authored by Sasha Gong via American Greatness,

America’s latest argument over artificial intelligence has suddenly become apocalyptic. Former Anthropic researcher Jacob Coxon accused AI companies of “gambling with our lives.” Anthropic CEO Dario Amodei urged the industry to slow the development of frontier models, an idea supported by OpenAI CEO Sam Altman and Elon Musk. At the same time, opposition to the data centers needed to power AI is spreading across the United States.

China has noticed. X recently uncovered a suspected Chinese influence network of roughly 200,000 fake accounts; about 200 of them were directly involved in amplifying claims that American data centers were raising electricity prices and overwhelming the power grid.

This does not mean that criticism of AI or data centers is manufactured in Beijing. Concerns about electricity costs, water use, pollution, cyberattacks, job losses, and mass surveillance are real. But China does not need to invent American divisions. It needs only to identify, amplify, and exploit them.

Modern democracies periodically succumb to predictions that a new technology will destroy humanity. The fear may be legitimate, but its political consequences are not evenly distributed. Democracies permit protest, litigation, regulation, and obstruction. They may even abandon a technology out of fear.

Dictatorships suppress debate, concentrate resources, and use their rivals’ hesitation to catch up.

The first great technological apocalypse began with the atomic bomb.

As the Manhattan Project approached completion in 1945, scientists considered whether an atomic explosion might ignite nitrogen in the atmosphere or trigger an uncontrollable reaction in the oceans. Edward Teller raised the possibility; Hans Bethe and others calculated that the risk was physically negligible. The Trinity test proceeded.

The question nevertheless haunted Robert Oppenheimer. After Hiroshima and Nagasaki, he feared that scientists had opened a Pandora’s box. When Washington decided to develop the hydrogen bomb after the Soviet atomic test, he opposed it on moral and strategic grounds.

Oppenheimer’s Communist associations then turned a policy dispute into a political scandal. His wife and brother were members of the Communist Party USA (CPUSA), and he had many pro-Soviet acquaintances. Meanwhile, actual Soviet spies inside the Manhattan Project – including Klaus Fuchs and Theodore Hall – passed crucial nuclear information to Moscow.

The Soviet Union tested an atomic bomb in 1949 and a thermonuclear device in 1953. China tested its first atomic bomb in 1964, shortly after emerging from a famine that killed 40 million people. Neither Communist regime permitted a genuine public debate over the wisdom of nuclear competition.

The West did. Scientists, churches, students, and citizens organized enormous anti-nuclear movements. Their pressure contributed to test-ban treaties and arms control negotiations. Yet Americans still understood that the danger came not only from nuclear weapons but also from the regimes possessing them. After Sputnik in 1957, few believed the United States could safely withdraw from technological competition while the Soviet Union continued advancing.

After the Cold War, climate change became the next vehicle for apocalyptic politics.

Al Gore’s An Inconvenient Truth turned complex climate models into images of approaching catastrophe. Greta Thunberg transformed policy disagreements into moral indictments. Claims that humanity had only “12 years” remaining circulated widely.

Fear of climate change converted a scientific problem into an ideological commandment. Energy restrictions, endless permitting, penalties on traditional industries, and costly transitions were presented as the only acceptable path. These policies greatly contributed to and accelerated Western deindustrialization.

China followed a different course. Unrestrained by voters, environmental groups, or local governments, Beijing concentrated subsidies, land, energy, and credit to build complete industrial supply chains. The West congratulated itself for reducing domestic emissions while transferring production to China. It then discovered that it depended on China for pharmaceuticals, rare earths, batteries, solar panels, and electronics.

The pattern is now repeating with AI.

While Americans debate moratoriums, China is treating artificial intelligence, robotics, and computing infrastructure as pillars of national power. Its “Eastern Data, Western Computing” strategy is creating an integrated national computing network, moving the eastern seaboard’s data-processing demands to western provinces with abundant land and energy. Beijing intends to control not only AI models but also the electricity, chips, servers, communications systems, and data centers that sustain them.

China is also competing to write the rules. In 2026, 29 countries signed an agreement in Shanghai establishing the World Artificial Intelligence Cooperation Organization, which Beijing describes as the first intergovernmental organization devoted to AI. China does not plan to pause while America debates whether the future is too dangerous to build.

AI requires serious safeguards: independent testing, cybersecurity standards, protection against biological misuse, transparent energy pricing, and accountability for harms. But regulation should make development safer, not make development impossible. Data-center projects should bear their actual costs, but local objections cannot become a nationwide veto over the infrastructure of the next industrial age.

Open debate is one of democracy’s moral strengths. The power to suppress debate is one of authoritarianism’s strategic advantages. When democratic caution becomes paralysis, freedom itself becomes vulnerable to exploitation.

America can decide how it develops artificial intelligence. It cannot decide whether artificial intelligence will continue to develop. If the United States stops because it fears the future, China will not stop with it.

Tyler Durden
Sat, 09/19/2026 – 23:20