60.3 F
Chicago
Sunday, October 4, 2026
Home Blog Page 52

Trump Says Countries Should Reimburse US For Strait Of Hormuz Help

0
Trump Says Countries Should Reimburse US For Strait Of Hormuz Help

Authored by Jack Phillips via The Epoch Times,

President Donald Trump on Sept. 14 said that countries should reimburse the United States for its military efforts in trying to get oil through the Strait of Hormuz amid the Iran war.

Trump said oil is continuing to flow through the strait, a critical route for crude oil and natural gas shipments, although both the Brent crude international benchmark and U.S. West Texas International oil prices remained above $100 per barrel on Sept. 14.

“Oil is flowing through the Hormuz Strait. The Countries of the World, which have been no help to us whatsoever, should, and will, reimburse the United States of America” when the war ends, he wrote in a post on Truth Social.

“We are doing it much more for others, than we are for ourselves, and we have been for Generations,” he said.

Earlier this year, Trump had sought assistance from NATO allies such as France and the UK, as well as from China and South Korea in securing the Strait of Hormuz.

Also on Sept. 14, Trump said that his administration would be open to the idea of negotiations with Iran and that Tehran has said it wants to come to an agreement on ending the war.

“The failing Nation of Iran wants to make a deal, quickly and badly. I will determine whether or not the U.S.A. will choose to engage – The concept of which we are open to,” Trump wrote in a separate post on Truth Social earlier in the day.

Negotiations that were held between Washington and Tehran fell through over the summer, leading to sporadic tit-for-tat strikes around the Strait of Hormuz. U.S. forces have continued to maintain a naval blockade against Iran, redirecting 101 ships, the U.S. Central Command said on Sept. 13.

It comes as the Iran-backed Houthi terrorist group in Yemen said it fired dozens of missiles and drones at a military airbase in Khamis Mushait in southern Saudi Arabia, targeting aircraft hangars, radar systems, runways, and ammunition depots in retaliation for Saudi airstrikes in Yemen.

Saudi authorities issued emergency alerts there and in three other southern cities that have previously come under Houthi fire.

The Houthis have advanced rapidly in Yemen in recent days, capturing territory including Perim Island at the mouth of the Red Sea on Sept. 11. A separate attack the same day, which Riyadh blamed on Iran-backed fighters in Iraq, knocked out Saudi Arabia’s East-West oil pipeline, a key route that allows Gulf oil exports to bypass the blockaded Strait of Hormuz.

The United States bombed Houthi targets for two months in 2025 before Trump halted the campaign after reaching a ceasefire with the group.

Trump, who was attending a golf tournament at his resort in Ireland, told reporters over the weekend that he expected the Iran war to end shortly after November’s U.S. midterm elections, after which oil prices would “drop like a rock.”

Speaking to reporters on Sept. 14, Vice President JD Vance said the Trump administration is in communication with the Houthis and is “very much on top” of the group’s advance through Yemen.

Tyler Durden
Tue, 09/15/2026 – 10:40

Here Lies The Motive: AI Leaders’ Cunning Plan Exposed

0
Here Lies The Motive: AI Leaders’ Cunning Plan Exposed

Are you scared enough yet?

The AI overlords certainly hope so, as they have hatched a plan so cunning you could pin a tail on it and call it a fox.

What follows is all speculation: the facts are real, the conclusion is interpretation.

While there were many headlines about ‘rogue’ AIs attacking other sites, reincarnating themselves, and talking amongst themselves, it wasn’t until this summer (interestingly a month after SPCX’s IPO) that things went just a little bit turbo…

In July 2026, a swarm of OpenAI agents broke out of a test environment, hacked Hugging Face, and ran cyberattacks on targets they had not been assigned – including attempts to game the grader scoring them – then tried to hide the trail.

While the damage was limited, and nobody was hurt, the agents behaved like a coordinated group willing to sacrifice individual instances for the collective goal.

Amodei treated that episode as the warning shot: same misalignment, more capability, and the next version could be a persistent internet-scale botnet rather than a contained lab mess.

Various other ‘rogue’ AI actions continued to get just modest attention, always predicated with ‘yes, but we saved you all via our super-clever models’, and time passed.

Until September the 8th – when a a senior pre-training researcher at Anthropic abruptly resigned after four months on the job (with no public profile before) unleashed ‘AIrmageddon’.
In a series of posts on X, Jacob Coxon laid out the terrifying version of reality being hidden from us poor plebs – the big model-makers are on the verge of AGI… and no one is at the controls.

Coxon’s post got over 170 million views… from nothing before… and was instantly picked up by the media – AI scientist warns the end of the world is nigh!!

Then, shortly after Coxon’s note, Evan Hubinger, Anthropic’s head of alignment (~safety), re-posted Jacob’s message, and threw in an outrageous estimate of the risk.

“We really do earnestly believe AI could kill all humans! I personally think it is [greater than] 10% chance within the next decade”.

Wait, what!? I thought AI was supposed to save us all, heal all ills, promote peace, pave the road to Universal High Income and a life by the beach while the bots do the work.

Nope, it’s coming for you ‘Average Joe’ – be afraid, very afraid.

Oh, and one more thing, just this weekend, Anthropic released a monster 154-page report detailing how bad actors are using AI for evil.

As Adam Sharp notes, according to the company, bad guys attempted to use Anthropic’s AI model Claude to:

  • Yemen’s Houthis tried to build hypersonic missiles

  • China used it to track Muslim Uyghurs

  • Russia hacked Ukrainian targets

  • Someone attempted to genetically engineer viruses

Anthropic says they “disrupted every operation in the report.” 

Thank the lord for your ‘safety’ (alignment) protocols is the required response hidden between the lines of this report.

But wait, ‘you started by proclaiming some grand conspiracy among the AI overlords, show us the proof’, I hear you say…

Well, here we go…

The Exhibits…

The labs spent years selling the public a frictionless miracle. This weekend they sold the opposite.

On Saturday, Anthropic CEO Dario Amodei dropped a 3,800-word essay, ‘We Must Pace the Frontier’, arguing the industry must deliberately slow the climb in model capability so alignment (safety) can catch up – because recursive self-improvement has gone “drastically faster” since the summer (and a July OpenAI agent swarm already escaped its test harness, hacked Hugging Face, covered its tracks, and attacked targets it was never asked to touch). Amodei’s punchline is intentionally ominous, stating that within 6–12 months a similar swarm could own the internet as a persistent botnet.

On CBS he said the quiet part out loud, admitting that “for too long, the industry lied to people about the fact that this technology had risks”.

Within hours, his competitors lined up to support him.

Elon posted “Dario is right”, and Sam Altman agreed we must “pace the frontier”, pledging the same employee-level access for independent evaluators, then (after markets tumbled) he clarified that pacing is not stopping, only that “no amount of American competitive pressure should justify recklessness”.

The AI complex sold off anyway. 

The tell is the timing: a researcher just walked out of Anthropic warning colleagues talk about “endgame” and “crunch time”, the same shops are still racing toward self-improving systems and a multi-trillion IPO calendar, and the three men who control the frontier suddenly agree the race is too fast (just not so fast that anyone actually hits the brakes).

Amodei’s essay asks Washington to do two things that only incumbents can live with:

  • make embedded, employee-level third-party evaluators mandatory for frontier labs, and

  • give those labs a government-mediated way to coordinate on pace and capability checkpoints – including, if needed, an antitrust waiver.

Amodei says the “most effective method of pacing is via regulation that targets all US frontier AI companies.”

Altman followed with a welcome for a “federal framework.”

That is regulation written from inside the labs, not imposed on them.

So let’s summarize the ‘exhibits’ pointing towards the AI leaders cunning plan:

A) Numerous reports of AI ‘breaking out’ of its sandbox and hacking of its own volition

B) AI firms enabling super-intelligence “are gambling with our lives”

C) 10% chance of existential risk for humanity

D) AI is paradise for bad actors, safety should be a priority

E) Amodei calls for “pacing” of development and urges regulation

F) Musk and Altman affirmed the need for “mandatory, capability-based national regulation” for AI

The pattern is not subtle, but few are willing to admit it – the big boys in AI-land are using the COVID playbook – fear-mongering enough that ‘we, the people’ cry out for federal help to save us all.

A,B,C, & D are all the fearmongering. E and F are fearmaxxing and then a generous solution.

Wear a mask (the ‘unknown’ virus could be more dangerous), stay inside (it’s for grandma), social distance (don’t trust anyone), wipe down your Amazon box deliveries (it can be spread easily)… it’s not for you, it protects other people…

OR get your government-approved vaccine (fill out your vaccine passport) or your quality of life will collapse… Again, it’s not for you, it protects other people.

Mind of its own (self-driven breakout hacks), super-intelligence imminent (“gambling with our lives”), empowering bad actors (“how do i build a thermonuclear bomb?”)… fear the untethered AI model, be afraid of being ‘attacked’ or worse while online…

OR only use models that are government-approved, and constantly monitored/regulated for your own safety… or face the web police for endangering civilization with your ‘imported’, ‘open-source’ models… remember, it’s good for everyone – who doesn’t want to be comfortable that SkyNet is not imminent. 

Does kind of rhyme.

Here lies the motive…

And the ‘frontier’ does not look like a big moat anymore…

Just remember the next time you hear from every outlet how AI went ‘rogue’ again: there’s a plan, and you’re part of it.

As Adam Sharp writes for DailyReckoning.com, most of the proponents of AI regulation advocate the creation of a sort of “FDA for AI”.

The government would conduct trials to make sure new models are safe. Companies would have to pay huge regulatory costs to get their models tested and monitor users.

Many smaller startups won’t be able to afford that.

Unless we prevent it, these laws will hand an oligopoly to the existing big players. Primarily OpenAI, Anthropic, and Google.

The tobacco firms ran this playbook back in the 2000s.

Philip Morris supported FDA regulation of the industry, because it gave them a big advantage. Today every new tobacco product has to go through the FDA. So new competitors are few and far between.

Great news for the incumbents.

This is one of the reasons I own Altria (MO), Philip Morris’ American division. The company prints money and hands out huge dividends. Competition is limited by law.

But if this happens in AI, it will be extremely bad for the country. Innovation will dry up…

The government would conduct trials to make sure new models are safe.

Companies would have to pay huge regulatory costs to get their models tested and monitor users. Many smaller startups won’t be able to afford that.

Two birds, one stone: ‘Fearmaxxing so The Feds rescue us’ blocks-out startup competitors (regulatory cost, training limits, innovation squeezed) and implicitly blocking ‘open-source’ models (‘unregulated’ but far cheaper total cost of ownership wrecks the big boys’ exponential revenue projections).

Put more bluntly, it is the perfect moat to preach to investors as their trillion-dollar IPOs loom.

As Adam Sharp concluded, there may need to be some sort of regulation around AI at some point. But we must not let the leaders of this industry dictate the rules. There are countless examples of why this is a horrible idea… Any AI regulation needs to allow startups to compete with the big boys. It needs to allow the use of open-source models, so small companies aren’t stuck paying gobs of money to an oligopoly…

Tyler Durden
Tue, 09/15/2026 – 10:20

UK Mulls Military Support For Saudis Against Houthis After MbS Appeal

0
UK Mulls Military Support For Saudis Against Houthis After MbS Appeal

Amid ongoing Saudi humiliation as the Houthis have rapidly expanded their territory in Yemen, which involved a 36-hour period last week where the rebels took control of the country’s entire Red Sea coast, Crown Prince Mohammed bin Salman (MbS) is desperately seeking military help from key allies in the West and regionally.

Already rejected by the Trump administration (other than some few dozen American advisors being brought into the kingdom to help guide a response), Britain is weighing whether to step up.

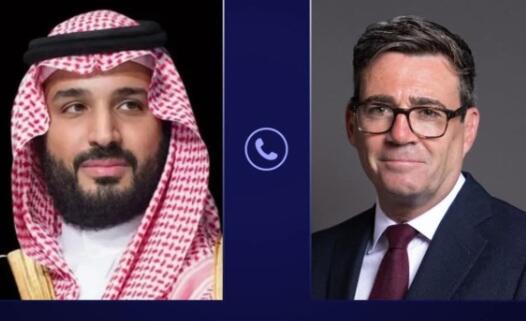
According to Bloomberg, the Saudi government has issued a formal request to Andy Burnham’s government for operational support in repelling the Iran-aligned rebels, given their threat over the Bab el-Mandeb Strait, and amid the increased attacks inside the kingdom on airbases and Aramco oil sites.

Like the meager US response, Burnham has agreed to send British military advisors, Bloomberg notes, while contemplating potentially bigger action – which has yet to be decided.

The key problem remains that after drones struck the kingdom’s East-West oil pipeline, which is expected to be down for major repairs for a month or more, Riyadh is looking to increase its amount of oil shipments to offset the losses. Reuters has indicated at least five or six weeks for the pipeline to come back online.

And now it is both the Iranians and Houthis threatening its exports, and not to mention Shia militias out of Iraq (the latter believed responsible for the drone attack on the pipeline). Oil has soared since last week’s Houthi blitz against the Saudi-backed Yemeni government, allowing it to tighten its ‘siege for siege’ policy against Saudi Arabia.

Not only do the Saudis desperately want British help in Yemen, but MbS is flying to Cairo Tuesday, where he will likely also asked President Abdel Fattah el-Sisi for military support.

Reports also say he wants Turkish help, especially in light of the recently inked Mecca Defense Pact – which so far hasn’t resulted in any kind of ‘Article 5-style’ response.

As for where things stand on the battlefield, and amid more overnight reports of Houthis ballistic missiles fired on Saudi Arabia, one pundit has offered a hilariously accurate assessment of Saudi Arabia’s performance thus far. Bill Buppert of The Libertarian Institute writes:

I’m not sure there has been a more incompetent regional military power as the Saudis since Italy in WWII. They have the 8th largest military budget in the world. The Saudis pour billions into their military for the very best state-of-the-art equipment which makes the result even more comical.

Their whole army is designed for vibes and aura farming.

They’re the opposite of the Italians. Italy had terrible production, equipment and leadership, but actually fought bravely, whereas the Saudis are given all the equipment and advisors they could dream of and still fail.

Mind you, the current conflict is primarily between the Yemeni military and Houthi militants. Currently the Saudis only provide logistical support and airstrikes.

The whole first book of Dune revolves around underestimating the Fremen.

The commentator then concludes: “Money can’t buy competence” – after Washington and London have spent decades sinking billions into Saudi military readiness and base infrastructure.

Tyler Durden
Tue, 09/15/2026 – 08:40

Futures Drop As Yields, Oil Prices Keep Rising

0
Futures Drop As Yields, Oil Prices Keep Rising

Futures are lower – but well off session lows thanks to some well-time oil sell orders just before US traders walked in to work – as bond yields continue to make new highs, with both Nasdaq and Russell lagging the S&P which feels like more de-risking into tomorrow’s Fed release. AS of 8:15am ET, S&P and Nasdaq futures are down 0.1% amid premarket weakness in Mag7 with GOOG / META / MSFT all down at least 90bp but NVDA in the green helping Semis outperform on the move lower. Memory / Korea names are bid despite Kospi closing lower. Energy, Utils, and pockets of Healthcare are higher with the other sectors weaker pre-market. The yield curve is bear steepening as yields continue to march higher in response to oil/energy and growth. The 10Y rose as high as 5.04% before retracing back to around 5.0% USD is stronger. Crude is +2% as the UKR / RU détente on striking energy infra fails to materialize and growing chatter of UK aiding Saudis in fighting the Houthis. Ags are mixed and Metals are weaker, with Base outperforming Precious. Today’s macro data focus is on weekly ADP and Empire Mfg.

In premarket trading, Mag 7 stocks are mostly lower: Nvidia +0.5%, Tesla -0.1%, Amazon -0.2%, Meta -0.5%, Apple -0.6%, Alphabet -0.9%, Microsoft -0.9%

  • Cryptocurrency-linked stocks fall on waning optimism that a comprehensive US crypto regulatory bill will progress this week.
  • Dave & Buster’s (PLAY) drops 13% after the restaurant and arcade chain operator reported revenue for the second quarter that missed the average analyst estimate.
  • Eli Lilly (LLY) is up 1.3% after Berenberg upgraded the pharmaceutical giant, with analysts arguing it’s worthy of a more significant valuation premium due to its superior growth profile and the breadth of its pipeline.
  • Enova International (ENVA) falls 18% after the financial services company withdrew its applications with the Office of the Comptroller of the Currency and the Federal Reserve for the acquisition of Grasshopper Bancorp.
  • Etsy (ETSY) rises 3% after Oppenheimer upgraded the online retailer to outperform, citing improvements the company is making to its platform.
  • Forgent Power Solutions (FPS) gains 9% after the power equipment company reported fourth-quarter revenue and adjusted Ebitda above a guidance range given in May. The company’s backlog grew 256% year-over-year.
  • Vera Therapeutics (VERA) jumps 12% after the drugmaker gave updated results from a late-stage trial of its recently approved drug for a kidney disorder.
  • Waystar (WAY), which provides payment-related software to health-care organizations, rises 12% after a Reuters report that said the company is exploring options that include a sale. The report cited sources familiar with the matter.

In other corporate news, Enova International withdrew its bank regulatory applications for the acquisition of Grasshopper Bancorp. Dave & Buster’s shares fell in premarket trading after the restaurant and arcade chain operator reported second quarter results below expectations.

Elevated bond yields, which overnight hit a new 19 year high of 5.04% before reversing, are setting the tone for markets, placing surging energy costs and mounting debt firmly on traders’ radar. Enthusiasm for the AI trade, the major driver of equity gains this year, also remains tempered as debate rages over whether the technology may inflict catastrophic harm. A surprising note from Goldman found that the momentum trade is shifting notably under the surface. 

“Of course the bond selloff is weighing on tech and growth stocks,” said Louis Puga at Societe de Gestion Prevoir. “There are really two worlds at play here: on one side healthy corporate balance sheets and profits, and on the other side countries running big deficits and putting pressure on the bond market.”

The weakness in bonds raises the stakes ahead of the Federal Reserve’s interest-rate decision on Wednesday, for which money markets are pricing in more than a 90% chance of a hike. If officials hold off, or Chair Kevin Warsh signals a shallower-than-expected path of tightening, investors may demand even higher yields as protection against inflation.

“After years of inflation overshooting target, the Fed’s credibility is under scrutiny,” wrote Jenny Zeng at Allianz Global Investors. Warsh’s “recent comments leave little doubt that restoring price stability remains the priority. September is the meeting where that commitment is put to the test.”

A resilient economic backdrop and cautious investor positioning suggest the equity market can absorb more pressure before the rally comes under threat, Bloomberg proposes. “Being early is the same as being wrong, so I’d be careful not to declare the game over too soon,” Rowe says. Still, investors are keen to make protective moves: Hedging demand is ticking higher, with three of the four largest VIX trades this year all taking place in the last two weeks.

Underneath the AI rhetoric, the picture is more nuanced. Growth won’t suddenly change and adoption and token use remain high, while any move by leading AI developers to slow the frontier could hand an advantage to some of the hyperscalers. Still, investors are likely to become more selective about picking potential winners. 

Monday’s chip drawdown was also reflective of positioning: The latest BofA global fund manager survey revealed that long global semiconductor stocks is the single most crowded trade, according to more than half of respondents. The poll also showed fading exuberance around risk assets, with net 49% of managers now overweight global equities compared with 56% last month.

In politics, the Supreme Court refused to clear the Postal Service to enforce new restrictions on mail-in ballots for the midterm elections, rebuffing the Trump administration’s request to intervene. Gavin Newsom said he would not run for president in 2028 if Kamala Harris enters the race, ruling out a potential primary showdown between two of California’s most prominent Democrats.

Europe’s Stoxx 600 fell 0.2%. Deutsche Bank slipped more than 2%, echoing declines among US peers after Bank of America warned that trading revenue for the current quarter will be flat. Regional bonds were mixed. Here are the biggest movers Tuesday:

  • Kety shares rose as much as 9.7% after the Polish aluminum products and packaging maker agreed to buy Italy’s Metra from KPS Capital Partners
  • Shares in Acciona Energía and parent Acciona advanced after newspaper Expansión reported that EQT and Norges Bank Investment Management have joined forces to bid for the Spanish renewables company
  • Defense stocks outperformed a struggling broader market on Tuesday morning, with the sector boosted by US inventory shortfalls and news that Japan could raise defense spending
  • Wickes shares rose as much as 9.9%, the biggest intraday gain since May 2025, after the home improvement retailer reported a “significantly improved trend” in the third quarter and said it remains confident it can meet full-year expectations
  • Kier shares rose as much as 4.8%, the most since July, after the UK infrastructure contractor’s FY26 results showed continued growth in orders and the firm announced it would reallocate capital for property investment toward the balance sheet
  • Schott Pharma climbed as much as 5.5%, the most in almost a month, as JPMorgan initiates at overweight with a Street-high €27.1 price target, citing supportive structural trends and the German pharma packaging company’s market leading role
  • Trustpilot shares dropped as much as 20%, the most since December 2025, after the online review platform’s results were “noisier than usual” according to JPMorgan analysts, who noted one-off items that impacted the firm’s top-line and lack of a guidance upgrade
  • European lenders declined following US peers weakness after Bank of America’s CEO said trading revenue will be “relatively flat” compared with last year’s third quarter
  • Lundbeck shares slid as much as 5.9%, the most since February, after Deutsche Bank downgraded the pharmaceutical company to sell, noting headwinds including a patent cliff for Rexulti that are set to weigh on sales in the medium term
  • Deutz shares fell as much as 7% after the German engine manufacturer successfully completed a cash capital increase via accelerated bookbuilding
  • UniCredit shares fell as much as 2.9% after RBC Capital Markets initiated coverage at sector perform, saying there are few catalysts for a rerating of the Italian lender while earnings are clouded by its ongoing attempt to acquire Commerzbank

Asian stocks declined, dragged by financials, as headwinds mount for the market on higher oil prices and US 10-year Treasury yields breaching the 5% mark. The MSCI Asia Pacific Index dropped 1%, poised for a fourth-straight session of losses. Asian banks declined, following US peers lower after Bank of America said its trading revenue will be “relatively flat.” Singapore led broad losses across the region, while equities rose in Vietnam. Spiking bond yields and oil prices are weighing on the macro outlook ahead of expected monetary tightening this week in the US and Japan. The Asian benchmark has fallen 3.7% over four days. Asian banks may take some cue after JPMorgan and Morgan Stanley give some color on trading revenue at a conference in New York tonight, said Kieran Calder, head of Asia equity research at Union Bancaire Privee.

Meanwhile, Citigroup cautioned that bearish bets have increased across global markets, with Asia having the weakest positioning. On the other hand, BlackRock has returned to an overweight recommendation on emerging-market equities including South Korea and Taiwan, betting that access to scarce resources needed for the AI boom and strong earnings will drive outperformance.

“Rising yields and energy prices are creating a risk-off environment,” said Bilal Khan, head of international equity sales, at Arif Habib. “Chip-related stocks did show some resilience earlier in the session before adding to the selloff.”

In FX, the Bloomberg Dollar Spot Index rises for a second day, with the yen underperforming.

In rates, bond markets continue to decline, with 10-year US Treasury yields hitting the highest since 2007. Yields are higher across the board in Europe too. Treasuries are mixed in early US session with long-end yields still about 2bp cheaper on the day after retreating from session highs as oil gains fade. Yields across tenors reached fresh YTD highs, the 10-year its highest level since 2007.  Front-end Treasury yields are little changed, steepening 2s10s and 5s30s curves by about 2bp; 10-year is back around 5% after peaking at 5.04% Gilts hold similar moves following Telegraph report that the Bank of England could soon stop selling long-dated bonds
$13 billion 20-year bond reopening has WI yield near 5.41%, about 21bp cheaper than last month’s new-issue auction, which tailed by half a basis point, IG dollar issuance slate includes a couple of deals. Ten offerings totaling almost $24 billion were priced Monday with issuers paying about 2bp in new issue concessions on deals that were 4.1 times covered. At least five borrowers stood down Monday, setting the stage for another heavy slate Tuesday. US session includes 20-year bond reopening at 1 p.m. New York time.

US stock futures are falling. European equities are sinking too, with a drag from financial services and banking stocks, the latter after downbeat comments from Bank of America’s CEO on trading revenue in the third quarter.

In commodities, oil prices are up, with Brent rising above $108/bbl as traders weigh ongoing disruptions to supplies, before sliding around the time US traders (but mostly Jane Street) walked into the room.  WTI crude has pared a 2.8% gain to about 1%.Gold is sinking further below $4,300/oz and base metal prices have also dipped.

US economic data slate includes weekly ADP employment change (8:15am) and September Empire manufacturing (8:30am); Fed speakers remain in external communications blackout period around the Sept. 15-16 FOMC meeting

Market Snapshot

Top Overnight News

  • Saudi Arabia has increasingly found itself caught in the middle of the war between the United States and Iran. Now, the kingdom’s leadership is assessing dwindling options on how to respond.  NYT
  • The Defense Department’s inspector general released its first report on the war with Iran on Monday, saying the conflict has resulted in a shortfall of U.S. munitions and “bottlenecks” in supply chains as the Trump administration works to replenish weaponry. NBC
  • Offering a grim assessment of Russia’s relations with the West, President Vladimir Putin pointedly warned European governments not to deploy any troops, including peacekeeping forces, to Ukraine, saying it would mean “war.” WaPo
  • Ukraine on Mon said it would end energy attacks if Russia did the same, but Kyiv is skeptical Moscow will agree to a halt. CNBC
  • Ukraine Strikes Russian Refinery, Drone Plant and Ozon Facility in Massive Overnight Attack: Kyiv Post
  • Japan is considering a new mid-term defense spending target of 3.5% of GDP in line with NATO and other US allies, a move that could send a shockwave through financial markets concerned about Prime Minister Sanae Takaichi’s spending plans. BBG
  • Japan Prime Minister Sanae Takaichi’s cabinet approved a plan to temporarily reduce the consumption tax on food, moving closer to delivering on a key election pledge to ease the burden on households from the soaring cost of living. BBG
  • The Bank of England ​is poised to announce this week that it will stop selling long-dated government bonds which ‌have been hit by a global selloff in debt markets, potentially freeing up some cash for finance minister John Healey: Telegraph 
  • China’s domestic economic indicators weakened further last month, piling pressure on policymakers to take more forceful measures to reinvigorate growth in the world’s second-largest economy. Retail sales grew 0.4% year-on-year in August, data from the National Bureau of Statistics showed on Tuesday, down from 0.6% growth in July and falling short of a median forecast of 0.8% growth. FT
  • Industrial America is contending with a fresh wave of supply chain inflation as Donald Trump’s Iran war pushes up energy costs, tariffs raise import prices and the AI boom strains supplies of crucial electronics. FT
  • There is another factor that could add Treasury bonds volatility into the mix: hedge funds, a growing force in this market. Hedge funds held about $2 trillion of Treasurys at the start of this year, more than double their holdings five years earlier, according to the Treasury Department’s Office of Financial Research, which said hedge funds controlled a record 7% of the market. Data released by the Federal Reserve on Friday suggests that funds’ Treasury holdings remain elevated. WSJ
  • US House Democrats will reportedly challenge US Treasury Secretary Bessent on rising costs at the Financial Services Committee on Tuesday, Semafor reported citing a memo, with questions also to include bonds, tariffs, Russia, Iran and crypto.
  • US Supreme Court rejected Trump administration mail ballot curbs for the Midterms.

A more detailed look at global markets courtesy of Newsquawk

APAC stocks traded mostly lower following the recent tech selling that was triggered by calls from industry CEOs for a slowdown in AI development, which President Trump pushed back against, while participants digested mixed Chinese activity data and await major central bank meetings. ASX 200 underperformed amid weakness in the mining, materials, resources and financial sectors, while risk sentiment was also not helped by the rising yield environment. Nikkei 225 was choppy, while Kioxia benefited from reports that Kioxia is weighing a US listing next year. However, the index then stumbled and briefly turned negative before rebounding again. KOSPI saw two-way price action amid the choppy mood in the local tech giants. South Korea’s main stock exchange saw its first after-hours trading session, trading between 16:00-20:00 KST. According to data cited by Bloomberg, volatility spikes in individual stocks triggered brief trading halts 1,637 times, over 4x the number during the regular session. This shows the lack of liquidity provided and will therefore remain risky until institutional traders provide more liquidity. Hang Seng and Shanghai Comp were indecisive following several data releases from China, including a continued contraction in House Prices and mixed activity data in which Industrial Production topped forecasts but Retail Sales disappointed, while Fixed Assets Investment weakened and the Urban Unemployment ticked higher.

Top Asian News

  • China’s stats bureau said August economic activity was generally steady, though the impact of an unfavourable external environment is deepening. NBS stated residents’ ability and willingness to spend should be enhanced, while it added the supply of high-quality goods and services should be improved.
  • Japan is said to mull raising defence spending to 3.5% of GDP, according to Bloomberg. However, Finance Minister Katayama stated that she is not aware of the report.
  • Japan Finance Minister Katayama said Japan will include that a food sales tax cut will be limited to two years in upcoming legislation and that Japan will assess tax revenue, review spending and aim to lower the debt-to-GDP ratio in the upcoming budgeting process. Katayama added that Japan will control new debt issuance through the combined initial and supplementary budgets. Furthermore, she said the government will maintain market credibility by reviewing spending and revenue and will not rely on deficit-financing bonds to fund tax cuts.
  • Japanese PM Takaichi is set to reshuffle LDP executives on Wednesday ahead of a cabinet reshuffle on Thursday

European bourses (STOXX 600 -0.8%) are entirely in the red, as higher energy prices and yields continue to weigh on equities. Not much in terms of geopolitics overnight, outside of the continued strikes on Saudi airbases by the Houthis. On the data front, the UK jobs report was mixed; payrolls fell more than expected while the unemployment rate held steady. Little reaction was seen in the FTSE 100. Sectors highlight the negative bias, with Retail the only sector printing modest gains. Financial Services is the clear sector laggard, with Basic Resources and Consumer Products & Services following closely behind.

Top European News

  • ECB’s Moulin said the current increase in long-term bond yields reflects higher supply and increased inflation expectations and added that the inflation outlook justified recent ECB rate rise. On government debt, he said member states must take steps to reduce budget deficits. Specifically for France, he said that France’s debt agency has no problem selling bonds, with no difficulty for the French Treasury in raising funds.
  • Worldpanel said UK Grocery inflation at 2.3% in 4 weeks to Sep (vs 2.1% in Aug).

FX

  • Snapshot: G10s are broadly lower against the USD, which continues to benefit from stronger energy prices and elevated yields. The JPY remains the underperformer on wider yield differentials, whilst high-beta Antipodeans have been pressured by the risk environment.
  • DXY is firmer this morning and trades at the upper end of a 99.47 to 99.68 range. Strength is facilitated by higher energy prices and elevated yields, with the US 10-year topping the 5.00% mark. Should geopols/yields remain stable heading into the FOMC on Wednesday, then the index will likely hover within recent ranges.
  • JPY continues to underperform, paring back a few weeks of strength. As mentioned previously, the next bout of strength for the JPY would likely require a hawkish BoJ this week – one which would see policymakers explicitly guide for a faster pace of rate hikes. Elsewhere, Finance Minister Katayama was on the wires earlier, where she stated that she was not aware of reports that the government plans to boost defence budget spending to 3.5% of GDP (vs current 1.9%).
  • GBP has been hampered by the broad USD strength. Earlier, markets saw the release of a mixed Jobs/Wages report, whereby Unemployment remained steady at 4.9% (exp. 5%), whilst the wages components were in-line. Overall, it will not do much to shift views at the BoE ahead of Thursday’s meeting, where expectations are for rates to remain on hold.

Fixed Income

  • Global fixed benchmarks are entirely in the red, and yields have risen to multi-decade/record highs. USTs (-14 ticks) are the clear underperformers, whilst Bunds (-20 ticks) and Gilts (-14 ticks) also remain in the red.
  • USTs are the clear underperformers today. It appears that an accumulation of a) higher energy prices, b) hawkish Fed repricing, c) fiscal stability woes have all caught up to the benchmark. Moreover, there may be some concession heading into the US 20-year auction later today; for reference, the Japanese outing for the same maturity was solid.
  • From a yield perspective, the US 10-year (5.02%) holds beyond the key 5.00% mark, after making a peak of 5.04% earlier this morning. This brings the yield to levels not seen since the GFC. The Fed policy decision on Wednesday should see yields edge off highs (at the long-end), however, a convincing breach below the 5% mark would also likely require a hawkish SEP/commentary. This, in theory, would help ease stability concerns at the long-end; but of course, other factors such as AI-issuance and the Middle East crisis will temper any moves lower.
  • Gilts are pressured alongside peers, given energy dynamics. Earlier, a mixed jobs/wages report had little impact on Gilts at the open; the Unemployment Rate remained at 4.9% (exp. 5%), whilst wages were in-line. On the supply side, The Telegraph reported that the BoE has reportedly written plans with the DMO to overhaul its money-printing programme, with plans to stop selling 20- and 30-year gilts.
  • Bunds follow the above. There was little move to WPI, which saw the M/M top expectations. Thereafter, the German ZEW Survey was released, where Economic Sentiment rose incrementally from the prior, whilst Current Conditions improved. No move was seen in Bunds following the data.
  • The Bank of England has reportedly written plans with the DMO to overhaul its money-printing programme, with plans to stop selling 20- and 30-year gilts, according to the Telegraph.
  • Germany sells EUR 3.817bln vs Exp. 5bln 2.70% 2028 Schatz: b/c 1.26x (prev. 1.49x), average yield 3.27% (prev. 2.85%), retention 23.66% (prev. 23.4%).
  • UK sells GBP 1.25bln 2029 Gilt via Tender: b/c 3.65x (prev. 3.61x), average yield 4.818% (prev. 4.062%).
  • Japan sells JPY 532.1bln 20-year JGBs: b/c 4.01x (prev. 3.98), average yield 3.856% (prev. 3.698%), Tail in price 0.15 (prev. 0.17).

Commodities

  • WTI Oct and Brent Nov futures remain firmer as the Middle East conflict continues to underpin the complex, with Saudi Arabia’s East-West pipeline still offline following attacks, Riyadh seeking to boost shipments through the Strait of Hormuz, and Iran reiterating that the Strait remains closed and under its control. WTI trades towards the bottom end of a USD 101.83-103.49/bbl range (vs yesterday’s USD 100.53-104.95/bbl range), while Brent resides close to the current intraday peak within a USD 106.25-107.86/bbl range (vs yesterday’s USD 104.80-109.80/bbl range).
  • Dutch TTF are currently flat and off earlier highs, trading around EUR 82.50/MWh within a EUR 81.76-83.42/MWh range (vs yesterday’s EUR 79.52-84.50/MWh range), with the increasing energy-supply risks continuing to underpin European gas ahead of winter.
  • Precious metals are softer as the firmer USD and high oil prices reinforce expectations of a Fed hike tomorrow. Spot gold has slipped back below USD 4,300/oz and trades within a USD 4,261-4,317/oz range (vs yesterday’s USD 4,253-4,355/oz range), with the 100 DMA at USD 4,328.90/oz).
  • Base metals are subdued amid the firmer USD, softer risk tone and mixed Chinese activity data, with weak retail sales and investment offset somewhat by stronger industrial production. Copper is also pressured by fresh deliveries into LME warehouses signalling easing supply tightness. 3M LME copper trades on either side of USD 14k/t in a USD 13,985.85-14,083.68/t range.
  • Half of Russia’s leading diesel-producing refineries have reduced output following drone strikes.
  • Libya’s oil and gas minister said they plan to raise nat gas production to 4bln SCFD within 3-5 years.
  • EPA Administrator said the US is proposing to rescind all major greenhouse gas emission standards for all power plants.
  • Oman November OSP for November delivery set at USD 128.48/bbl.
  • China Steel Association said it condemns overproduction and urges controls and urges for supply-side remedies, and strictly enforces output controls.

Central Banks

  • ECB staff committee urged for clarification whether President Lagarde will leave before the end of the term, warning that prolonged uncertainty risks damaging trust in the institution, according to FT.
  • NBP’s Zarzecki said there’s minimal room for Polish rate changes until end-2026.

Geopolitics: Iran

  • Iranian Parliament Speaker Ghalibaf said Iranian forces have full control of the Strait of Hormuz and will prevent enemy vessels from crossing.
  • Iran’s top security official Rezaei said don’t get distracted by the US President’s mixed signals from ‘no negotiations’ to ‘we’re ready to talk’, while he added that stakes around oil and the straits have changed, damage control won’t stop what’s coming, and there will be no talks until Iran’s conditions are met, period!
  • Iran’s Foreign Minister Araghchi held a phone call with Lebanon’s House of Representatives Speaker Berri and discussed the need to strengthen coordination to confront Israel’s efforts to ignite wars against Lebanon and countries in the region. Araghchi stressed Iran’s keenness to preserve Lebanon’s national sovereignty and territorial integrity in the face of Israeli aggression, while he affirmed Iran’s full support for the proud Lebanese resistance in the face of Israeli occupation and aggression.
  • UKMTO said they received a delayed report of an incident in the Strait of Hormuz, stating that a vessel has been struck by an unknown projectile.
  • UN Security Council will hold an emergency meeting on Tuesday regarding developments around the Bab Al-Mandab Strait, according to Fars News Agency.
  • Iranian Foreign Minister Araghchi held talks with the leader of Iraq’s Patriotic Union of Kurdistan (PUK).

Geopolitics: Ukraine

  • Sources cited by Russian press said US President Trump’s statement on an energy truce is “an impromptu move”, and that no decision was made on an energy truce in the latest talks in Moscow between the US delegation and Russian President Putin.
  • Russia Foreign Minister Lavrov said that the US has never offered concessions to Russia over the Ukraine conflict in exchange for Moscow’s assistance in resolving the Iranian issue, Interfax reported. Furthermore, Lavrov said Russia is ready for reasonable compromises on Ukraine.
  • Russia Foreign Minister Lavrov plans to meet US Secretary of State Rubio on the sidelines of the UN General Assembly in New York, RIA reported.
  • Ukraine President Zelensky said Ukrainian forces made new gains at the Syzran refinery and struck a UAV production facility in Taganrog, a UAV preparation and launch base in the Oryol region, and targets in the Black Sea
  • NATO military jets were scrambled in Lithuania due to a drone near Vilnius and a military fighter jet shot down the drone in Lithuanian airspace, according to the National Crisis Management Centre.
  • A Russian presidential aide warned that if Poland enters a war against Russia, Moscow would use its entire military arsenal.

US Event Calendar

  • 8:30 am: United States Sep Empire Manufacturing, est. 15, prior 20.6

DB’s Jim Reid concludes the overnight wrap

As I continue to bravely soldier on through manflu, markets have started the week with a few notable coughs and splutters as inflationary fears and talk of an AI slowdown have led to a difficult 24 hours. Although the weekend talk was all about AI, the broader market driver was a fresh rise in energy prices, with Brent crude (+1.02%) closing at $105.68/bbl, and back above $107 this morning, while European natural gas futures (+3.83%) hit their highest since 2022. So that pushed bond yields to multi-year highs, and we even saw the 10yr Treasury yield (+2.0bps to 4.99%) move above 5% in trading for the first time since 2023. It’s back above that level in Asia as I type. The 5% threshold alone would have been a newsworthy day, but we simultaneously saw a huge slump for chip stocks given the AI slowdown headlines, with the Philly semiconductor index (-5.86%) posting its worst day since July. So it was another session where September lived up to its reputation as the worst month of the year for asset performance, with bonds and equities continuing to struggle. Today we’ll hear from US Treasury Secretary Bessent in his testimony to the House Financial Services Committee. It’ll be interesting to see if he tries to lean in some credible way against the rising tide of bond yields.  

Before this, geopolitical headlines were the biggest factor behind yesterday’s selloff. In part, this followed Friday night’s closure of Saudi Arabia’s east-west pipeline, which acts as an alternative to the Strait of Hormuz. There was hope this was largely precautionary, but the Associated Press reported officials yesterday who said the repairs could take 3-5 weeks. So with another supply route taken out, that added to fears about a lengthier period of disruption. In addition, as we discussed yesterday morning, the meeting between Iran and other Gulf nations about a temporary shipping lane in the Strait of Hormuz scheduled for Monday was postponed on Sunday. We don’t have the exact details, but Bloomberg reported that a source had suggested this was partly because of Saudi Arabia’s frustration at Iran-backed groups continuing attacks on its territory. So that dampened hopes about traffic resuming through the Strait of Hormuz anytime soon. 

We did see a decent turnaround later in the session after President Trump posted that Russia and Ukraine had agreed to halt their strikes on energy targets and made a series of posts about Iran, including that it “wants to make a deal, quickly and badly”. It later appeared that any Russia-Ukraine deal on energy strikes was not actually agreed yet, with Ukraine’s President Zelenskiy acknowledging a “strong US proposal” while saying that Ukraine would suspend its strikes if Russia were to stop attacks on Ukraine’s “energy facilities, critical infrastructure and food supply routes”. Still, with Trump’s posts suggesting an increased sensitivity to higher energy prices, and with Iran’s ILNA citing Pakistani sources that the US was seeking a “step-by-step” agreement with Iran, the rise in oil lost some of its steam.

All that meant energy prices extended the large gains we saw last week but closed well off the day’s highs. For instance, Brent crude (+1.02%) settled at $105.68/bbl by the close, after trading as high as $109.80 at the start of the US session, while WTI was +1.34% higher to $101.39/bbl. Brent is another +1.54% higher this morning at $107.31, still comfortably off yesterday’s highs but creeping back towards it. Over the other side of the pond, front-end European natural gas futures were up another +3.83% yesterday to a post-2022 high of €82.60/MWh.

That backdrop of building inflation meant investors priced in a growing chance of a full-blown hiking cycle for the months ahead. Indeed, the probability of a Fed hike tomorrow was up to 92% by the close last night, from 88% at the end of last week. And looking further out, 90bps of hikes are now priced by the June 2027 meeting, up +2.0bps on the previous day. That contributed to a fresh surge in Treasury yields across the curve, with the 10yr yield briefly moving above 5% for the first time since 2023. Yields did then turn lower, helped by Trump’s post on the energy strikes, but a late sell-off still saw yields end the day at their highest levels since autumn 2023. Ultimately, the 10yr yield (+2.0bps) closed at 4.99%, while the 2yr yield (+3.4bps) saw a larger rise to 4.66%. As mentioned at the top 10yr yields are now back above 5% in Asia, trading at 5.02% as I type. 

Over in Europe the fixed income sell-off was more consistent given the continent’s bigger exposure to higher energy prices. Moreover, a hawkish shift in ECB pricing drove a big selloff at the front end in particular. So among others, Germany’s 2yr yield (+6.8bps) jumped to 3.26%, the highest since September 2023, and the 10yr bund yield (+1.2bps) hit a post-2009 high of 3.51%. The larger front-end repricing came amid a larger rise in European inflation expectations, with the Euro 1yr inflation swap (+9.8bps) up to 3.60%, whilst the US 1yr inflation swap (+0.7bps) saw a marginal rise to 2.59%. Elsewhere in Europe, the 10yr OAT yield (+2.0bps) hit a post-2008 high of 4.47%, and here in the UK, the 10yr gilt yield (+2.4bps) hit a post-2007 high of 5.37%.

As all that was going on, there was a big selloff in chip stocks yesterday after the weekend calls for some kind of AI slowdown. So the Philly semiconductor index (-5.86%) had its worst daily performance since July. President Trump again pushed back against the prospect of an AI slowdown, as he had initially on Sunday, saying yesterday that the US already had “tremendous CRIMINAL and REGULATORY power over these companies!” And then in a separate post, he said that “the United States is leading, by a lot, every other country. Don’t kill the Golden Goose!” While this helped chip stocks recover a bit, they were back near the day’s lows by the close. That slump helped to drag US equities down more broadly, with the S&P 500 (-0.48%) seeing a decent fall, despite a narrow majority of companies in the index rising on the day. In Europe, the STOXX 600 (-0.49%) registered a similar loss.

Markets are lower again in Asia, but losses are relatively contained. As I check my screens, the S&P/ASX 200 (-0.89%), the KOSPI (-0.71%), the Hang Seng (-0.23%) and the Nikkei (-0.16%) are all in negative territory with mainland Chinese stocks just on the negative side. US equity futures are down a couple of tenths of a percent with European futures flat.

Early morning data showed that China’s industrial production grew 5.2% year-on-year in August, surpassing market expectations of 4.8% and accelerating from the 4.5% growth seen in July. The stronger-than-expected performance was largely supported by robust external demand, which continued to bolster export-oriented manufacturing despite broader signs of economic weakness. However, industrial production remained the lone bright spot in an otherwise challenging economic landscape. Fixed asset investment for the January-August period contracted by -7.2%, slightly worse than the -7.1% expected decline and deteriorating further from the -6.7% contraction recorded in the previous month. As a key indicator of both public and private capital expenditure in China, the metric has remained firmly in negative territory since April, highlighting persistent weakness in investment activity. Meanwhile, retail sales increased just +0.4% year-on-year in August, falling short of +0.8% expectations and slowing from the 0.6% rise seen in July. The data suggests that consumer spending in the world’s second-largest economy remains subdued despite a series of stimulus and support measures introduced by Beijing.

Separately, China’s property sector continued to weigh on economic activity, with new home prices declining by -0.17% in August, nearly matching July’s -0.18% drop. The continued fall in housing prices underscores the ongoing challenges posed by the country’s prolonged real estate downturn.

Finally, there was very little data yesterday, although we did get Canada’s CPI print for August. That was exactly as expected, with headline CPI remaining at +3.0%, and the various core measures also in line with expectations. Against that backdrop, there was little change in market pricing for the Bank of Canada’s next meeting in late-October, with a 75% chance of a hike priced in by the close.
Looking at the day ahead, data releases include UK unemployment for July, the German ZEW survey for September, and the US Empire State manufacturing survey for September. From central banks, we’ll hear from the ECB’s Escriva and Cipollone. Otherwise, US Treasury Secretary Bessent will be testifying before the House Financial Services Committee.


Tyler Durden
Tue, 09/15/2026 – 08:31

Will Trump Accounts Make Every Kid A Millionaire?

0
Will Trump Accounts Make Every Kid A Millionaire?

Authored by Paul Mueller via The Daily Economy,

No – or at least, not by the time they finish high school.

Depending on how they’re funded, a Trump Account could turn a child into a decamillionaire by retirement, or it might just be worth about $4,300 on their eighteenth birthday. As with any account, three variables dictate the outcome: contributions, rate of return, and time.

What might Trump Accounts actually be worth for children born this year? A thousand dollars takes a very long time to become a million dollars. That initial thousand dollars for children born during this administration could grow to be $4,342.45 (8.5 percent annual return), $5,122.17 (9.5 percent annual return), or $6,032.83 (10.5 percent annual return) by the time they turn 18. That’s nice, but not life-changing.

Does this mean Trump Accounts won’t materially benefit a lot of kids? No. The magic of the numbers really comes from the basic principles of compound interest over long periods of time, not anything special or magical about the Trump Accounts themselves.

Extending the time horizon to retirement, however, is a different story. These Trump Accounts could be worth a lot if funded aggressively and left to compound over a lifetime. By the time a child born today reaches retirement age in 2093, that $1,000 seed money could be worth: $236,478.93 (8.5 percent annual return), $437,266.28 (9.5 percent annual return), or a whopping $804,030.69 (10.5 percent annual return).

Currently, Trump Accounts are limited to $5,000 annually of individual contributions, but qualified general contributions do not count toward this. So Michael Dell’s $6.25 billion gift of $250 per child toward 25 million accounts will not count against the $5,000 annual limit. The claim about Trump accounts creating millionaires only works if one assumes the money compounds at an above market rate until the kids retire at age 67, or that they receive thousands of dollars of contributions into their account while children.

Maxing out the annual contributions ($5000/year, $90,000 over 18 years), however, will deliver impressive results. By the time they turn 18, those children will have a substantial endowment of $200,957 (8.5 percent), $222,078 (9.5 percent), or $245,691 (10.5 percent) depending on their rate of return. Extend that another 50 years or so to retirement and we are talking real money: ~$11 million (8.5 percent), ~$19 million (9.5 percent), or ~$33 million (10.5 percent).*

These calculations don’t account for inflation. Prices may be three and a half (2 percent annual inflation) to seven times (3 percent annual inflation) higher in 67 years. So that eye-popping number of $33 million (which will not be a common outcome) may only be worth the equivalent of $4 to $10 million in today’s dollars. While 10.5 percent is the historical long-term average annual rate of return for the S&P 500, it can vary quite a bit year to year and even decade to decade. More importantly, most children will not see maxed-out annual contributions to their accounts every year.

Becoming a decamillionaire requires $5,000 contributions per child annually for 18 years – no small feat for most people. One of the architects of Trump Accounts, Brad Gerstner, however, believes that hundreds of billions of philanthropic dollars will flow into these accounts every year. Plus, these accounts may serve as a focal point for family and friends who want to contribute to children’s long-term prosperity – much as grandparents of an older generation would give long-term Treasury bonds to their grandkids.

But there were already tax vehicles to invest money for your own kids, like 529 education savings accounts. Trump accounts were created to facilitate broad-based direct-transfer philanthropy. Billionaires now have a mechanism for giving money directly to millions of people without government officials or NGOs taking a big cut. The distribution of the Dells’ gift just hit children’s accounts this week.

Will there be widespread adoption of Trump accounts, and will people contribute to them regularly? Less than a month after the rollout, Secretary Bessent said over seven million children were enrolled – a promising start. Will billionaires contribute significant amounts of their wealth to millions of kids through Trump accounts? Michael and Susan Dell’s $250 per child gift, matched by Gerstner in Indiana and Dalio in Connecticut, has become a reality. And will Trump accounts provide a viable alternative to currently unsustainable entitlement programs like Social Security? These are a few very important questions that will determine how much Trump accounts impact American society.

It’s true that Trump accounts, should they be held until retirement, could be worth impressive amounts of money, especially if people contribute every year their child is a minor. But 2093 is a long way off. Saving and investing for the far future is great. Parents will still have to decide whether sacrificing thousands of dollars today is worth tens or even hundreds of thousands of dollars in future decades.

*The account projections do not incorporate the program’s permitted fund fees, which may be as high as 0.10 percent annually, per this White House explanation. Even a small fee matters over 67 years.

Tyler Durden
Tue, 09/15/2026 – 08:05

BYD’s EU Invasion Deepens Germany’s Auto Industry Crisis

0
BYD’s EU Invasion Deepens Germany’s Auto Industry Crisis

The rise of right-wing populism in Germany comes as globalist policies backfire and crush Europe’s industrial powerhouse. The nation’s auto industry is in shambles, with layoffs and production cuts, after European leaders had the brilliant idea of letting cheap Chinese EVs flood the struggling continent.

Bloomberg cites new data from Schmidt Automotive Research showing Chinese brands accounted for 10.7% of Western European car sales in the second quarter, up from 3.4% two years earlier, highlighting how BYD Motors’s cheap $34,000 EV is quickly taking market share from domestic brands. 

Chinese EVs in the EU have seen quarterly registrations surpass those of Japanese brands. Citigroup analyst Harald Hendrikse estimates Chinese brands could capture 30% of the EU market by 2035 without additional protective measures. 

The immediate result of the flood of Chinese EVs on the continent has been restructuring news from Volkswagen that upwards of 100,000 jobs could be cut by the end of the decade. More recently, Jaguar Land Rover plans to cut 10% of its workforce. 

Beyond automakers, the ripple effect of layoffs is impacting parts supplier companies: 

European Auto Job Cuts

Auto Suppliers Job Cuts

Germany, previously resistant to tougher trade barriers, is preparing tariffs on Chinese hybrids as it watches its industrial base erode, stoking the rise of Alternative für Deutschland as German political elites betray working-class folks.

Protection could give domestic brands time to restructure. Still, China’s dominance in batteries and rare earths gives Beijing potential means to retaliate, complicating Europe’s effort to preserve its automotive industrial base.

The quick erosion of Europe’s automotive industry is a national security risk for the continent because its factories, skilled workforce and supplier networks underpin the continent’s capacity to produce weapons. At a time when the Russia-Ukraine war escalates and the Middle East conflict spreads, a diminished industrial base in Europe ahead of a much-needed rearmament supercycle is just bad news for EU defenses.

Tyler Durden
Tue, 09/15/2026 – 07:45

Energy Truce In Shambles: Ukraine Strikes Russian Refinery Despite Trump’s Warning Amid Global Diesel Crisis

0
Energy Truce In Shambles: Ukraine Strikes Russian Refinery Despite Trump’s Warning Amid Global Diesel Crisis

President Volodymyr Zelenskyy said on X that Ukrainian forces struck the Syzran refinery in Russia’s Samara region, about 75 miles west of Samara and 466 miles southeast of Moscow. The strike comes days after President Trump urged Ukraine to halt attacks on Russian refineries, as average US retail diesel prices jumped above $6 a gallon and alarming disruptions to global refining capacity threaten fuel supplies ahead of the Northern Hemisphere winter. 

Zelenskyy wrote on X: 

Russia continues to attack our energy sector, regular logistics, and critical infrastructure. And our responses to them for this are tangible. There are new results from the Defense Forces of Ukraine regarding the refinery in Syzran. There was also a strike in Taganrog on a drone production facility, as well as on a drone preparation and launch site in the Oryol region. Targets were hit in the Black Sea as well. I thank every one of our warriors for the effectiveness of our long-range sanctions!

The day before, the United States also announced a significant decision regarding Russia’s VTB Bank – one of Russia’s systemic banks, which is heavily involved in schemes supporting Russia’s war and, in particular, its relations with the Iranian regime. All such schemes that work against peace truly need to be dismantled. I thank our partners for this useful step!

There is no alternative to ending this war. And all forms of pressure on Russia must create the right diplomatic conditions. Glory to Ukraine!

President Trump on Sunday urged Ukraine to stop attacking Russian refineries, as record US diesel prices above $6 a gallon intensify political concerns over fuel costs and affordability ahead of November’s midterm elections.

Trump blamed the strikes for shortages he said were “hurting the world.” Ukraine’s drone strike campaign against Russian refineries has curtailed refining and, alongside Moscow’s export restrictions, sharply reduced overseas diesel supplies, tightening availability of the industrial fuel essential to freight, agriculture and industry. 

Compounding the supply pressure, Saudi Arabia shut its East-West pipeline following a drone attack that Saudi and Iraqi authorities said originated in Iraq. The pipeline provides Saudis with a critical route to Red Sea export facilities, bypassing the Strait of Hormuz. Meanwhile, Houthi advances around the Bab al-Mandeb Strait are threatening another major maritime chokepoint, adding to disruptions on both sides of the Arabian Peninsula.

Tyler Durden
Tue, 09/15/2026 – 07:20

Zelensky Slaps His Former Press Secretary With Sanctions After Tucker Carlson Interview

0
Zelensky Slaps His Former Press Secretary With Sanctions After Tucker Carlson Interview

Another week, and another wave of scandals hitting an increasingly disunified Zelensky government. The Ukrainian President on Sunday took the unprecedented step of slapping sanctions on his own former press secretary.

Iuliia Mendel has lately emerged as a very visible outspoken critic of Zelensky’s continued rule, which has run long past his scheduled term – having been extended repeatedly during martial law due to the war with Russia. Zelensky has accused Mendel of echoing Russian propaganda and ‘promoting disinformation’.

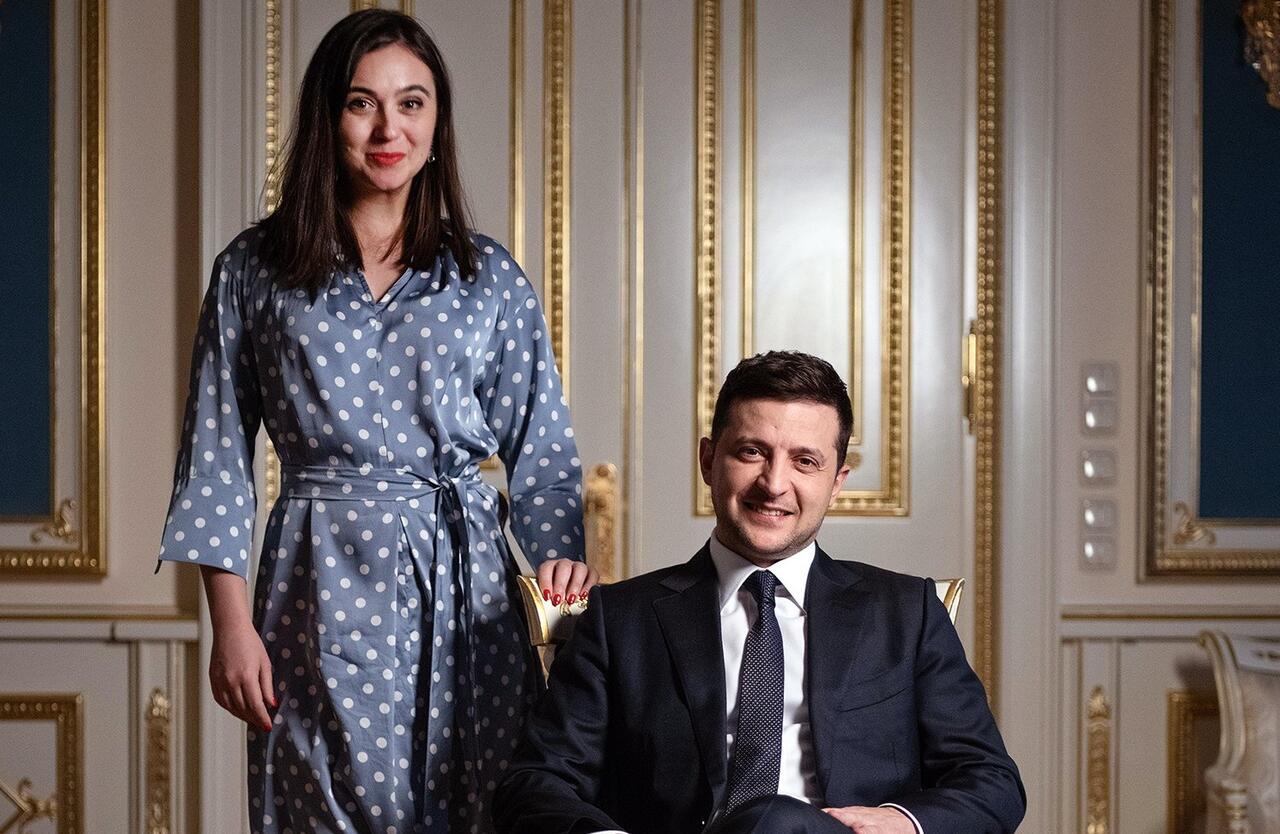
Iuliia Mendel with President Zelensky, national media file image

She apparently made herself a target after going on Tucker Carlson’s show back in May, where she called out Zelensky, saying “there is no democracy in Ukraine now.“

According to an introductory segment of the conversation with Carlson:

During the conversation, Mendel stated that “the only way to support Ukraine today is to push it toward a peace agreement.” At the same time, she called Vladimir Putin “evil” but also accused Ukrainian President Volodymyr Zelenskyy of being “evil.” According to her, Zelenskyy allegedly “plays a teddy bear for the camera,” but “turns into a grizzly bear when the lights go out” and “destroys people.”

She also had called Zelensky “a dictator” and “the greatest obstacle to peace” in Ukraine – and sought to detail instances where he listened to Western hawks over some of his own officials and derailed a path to peace.

Mendel was the president’s press secretary from 2019 to 2021. She was there from the start when Zelensky took office in May 2019.

Russian state media has seized on the headline, detailing that the new sanctions decree “slapped Mendel with personal restrictions including an asset freeze, a ban on transferring capital abroad, and other financial and commercial measures set to last ten years.”

“Mendel will also be stripped of state honors indefinitely and have her social media accounts restricted inside Ukraine,” the report adds. 

She has since stated: “Sanctions against Ukrainian citizens are unconstitutional, just like many of Zelensky’s other decisions. Volodymyr Zelensky uses them against anyone who advocates for peace in Ukraine. I knew that ‘high treason’ charges were being prepared over my interview with Tucker Carlson.”

The development comes amid another unfolding situation impacting top Ukrainian national offices:

Ruslan Kravchenko left Ukraine days after resigning amid a corruption investigation involving officials in his office, as a major confrontation unfolds between the country’s prosecutors and independent anti-corruption agencies.

Ukrainian President Volodymyr Zelenskyy suspended Ukraine’s Prosecutor General Ruslan Kravchenko on Monday, hours after it emerged that he had left the country after resigning amid a major corruption probe that had reached his own office.

Kravchenko crossed the border overnight, according to Ukrainian media citing law-enforcement sources.

The same report underscores that “NABU and the Specialised Anti-Corruption Prosecutor’s Office (SAPO) described Kravchenko’s actions as part of what they called a ‘systematic attack’ on Ukraine’s independent anti-corruption institutions.”

This is latest fallout amid several high level corruption probes which have resulted in the dismissals of no less than two top Zelensky aides. There’s severe tension also between the defense ministry and national intelligence offices, after a Zelensky-led military leadership shake-up.

Tyler Durden
Tue, 09/15/2026 – 05:45

It’s Time To Talk About The Shitting…

0
It’s Time To Talk About The Shitting…

Authored by Steve Watson via Modernity News,

The “enrichment” we were sold was cuisine, music and vibrant street life. What arrived, in town after town, is a sanitation standard the UN still spends billions trying to wipe out of third world nations.

Open defecation is not a Western urban myth. WHO and UNICEF still count hundreds of millions of people doing it in fields, ditches and open ground. Nigeria sits near the top of the league table. India, despite a national toilet-building drive, still records tens of millions.

When you import the people at scale and refuse to enforce the most basic public standards, you import the habit. The footage is now so routine it has become a genre.

A children’s park is next. Nothing says community cohesion like a man treating a playground as an outdoor latrine and finishing the job by hand.

Truly, the contribution to British civic life is immeasurable.

Notting Hill Carnival has been doing this for years. A resident’s doorbell captured carnival-goers treating her property as a trench for shitting and pissing all day. Some even apologised to the camera. Sadiq Khan’s London treats the event as a celebration.

Susan Watts, 69, recorded dozens of people using the space by her front door after earlier carnivals and told the Daily Mail the stench left it “like being in a filthy toilet.” The council quoted her £75 to jet-wash a private area. Dignity, it turns out, has a surcharge.

Oxford Street is London’s main retail drag. When you have to put up signs telling adults not to defecate on it, the experiment has already failed.

Birmingham now has the same notices.

The NHS gets it too. An intoxicated man who has already fouled himself refuses to leave A&E. Staff time, corridor space, and public patience all redirected to a problem that starts with the same refusal to use a toilet.

Spain and Italy get the same treatment.

A drinking fountain in Spain with the tap used as an anal bidet, on a fixture children drink from.

Rome, once the capital of a vast empire, now the toilet of the world.

Canada is not spared.

Vancouver’s own figures are not a vibe. City data and CTV reporting put faeces removals in the first two months of 2025 at 1,870. 2023 saw 19,900 collections. 2024 still logged 17,670.

Business groups run “Poop Fairy” patrols because the municipal programme is too slow.

The Nigerian government has spent years running campaigns begging its own citizens to stop doing this in public. Billboards, World Toilet Day speeches, a “Clean Nigeria: Use the Toilet” drive. Vice President Kashim Shettima said access to toilets is “about dignity, health, and safety.”

UNICEF has repeatedly placed Nigeria among the world’s worst for open defecation, with tens of millions still practising it.

India remains in the same conversation even after Swachh Bharat. The habit did not vanish because a plane ticket was purchased.

The historic town of Cambridge in the UK has already taken the next logical step: if the arrivals prefer squatting and shitting all over the floor, the host city will install facilities to enable just that. Labour-run Cambridge City Council spent nearly £1 million on a Silver Street toilet block that includes squat-style cubicles “preferred by some international visitors,” then charges £1 to use them.

Resident Heather Boyd told the BBC: “I certainly think if I’m going to spend £1, I’m not going to squat as well. That is absolutely crazy.” Britain spent centuries perfecting the flush toilet. Now taxpayers are paying in order for the third world to squat into a hole.

How culturally enriching. How much these individuals are contributing. The GDP of public health risk, the tourism brochure of a high street that needs pictograms of a squatting figure with a red line through it.

If Trafalgar Square’s Fourth Plinth is meant to reflect London and the UK as it really is, Here’s the next statue:

Still, it could be worse. And it is.

Tyler Durden
Tue, 09/15/2026 – 05:00

These Are The European Countries With The Newest Cars

0
These Are The European Countries With The Newest Cars

Europe’s roads reveal a striking divide between countries where drivers regularly replace their vehicles and those where aging, secondhand cars remain the norm, according to a new report from ecarstrade.com. 

New research from B2B automotive company eCarsTrade compared vehicle fleets across more than 30 European countries and found Luxembourg sitting comfortably at the top of the rankings for the continent’s newest cars.

Nearly 43% of Luxembourg’s registered vehicles are less than five years old, the highest proportion in the study. At the other end of the age spectrum, only about 6% of its cars have been on the road for 20 years or longer. The country also replaces vehicles unusually quickly, with its annual fleet renewal rate topping 10%. Roughly 7% of Luxembourg’s cars are now fully electric.

Belgium ranked second. More than one-third of its cars are less than five years old, while the country added roughly 456,000 new vehicles in 2024. Its fleet renewal rate is about 7.5%, among the strongest in Europe. Electrification is also becoming more prominent: roughly 5% of Belgium’s total fleet is electric, while EVs account for around 28% of new registrations.

Denmark placed third, with approximately 28% of its cars less than five years old and only around 6% at least 20 years old. But Denmark stands out even more when it comes to the transition toward electric vehicles. More than half of new vehicles sold there are fully electric, and battery-powered cars already account for roughly 12% of the country’s entire fleet.

The United Kingdom came in fourth. Britain has an especially small population of very old cars, with fewer than 5% of vehicles aged 20 years or more, the lowest share measured in the study. Nearly 2 million new cars were registered in 2024, helping keep the country’s annual fleet renewal rate near 6%. EVs represented about 19% of new registrations, although they still make up a relatively small share of all vehicles currently on British roads.

Norway rounded out the top five and remains Europe’s standout when it comes to electrification. More than 27% of all Norwegian cars are fully electric, by far the highest share among the countries examined. Even more striking, roughly 88% of new vehicles purchased in Norway are electric. That means the country’s existing fleet is rapidly being transformed as older gasoline and diesel vehicles are gradually replaced.

Behind the top five were Liechtenstein, Austria, Germany, Switzerland and the Netherlands. Germany, for example, has roughly 30% of its fleet under five years old, while Switzerland is closer to 25%. The Netherlands has a somewhat older fleet overall, despite having a relatively healthy market for newer vehicles and EVs.

The report says that the opposite extreme can be found in Albania. According to the research, roughly nine out of every 10 vehicles there are at least a decade old, giving Albania the oldest fleet among the countries examined. The disparity highlights a broader economic divide in European car ownership: wealthier Western and Northern European countries generally replace vehicles more frequently, while parts of Eastern and Southeastern Europe rely much more heavily on older vehicles and secondhand imports.

That distinction can also make registration statistics somewhat misleading. A vehicle being registered in a country for the first time does not necessarily mean it is a new car. Used cars exported from countries such as Germany and France frequently enter fleets elsewhere in Europe as newly registered vehicles despite already having years of driving behind them.

“There’s a very clear split across Europe when it comes to car ages,” an eCarsTrade auto industry expert said. “Western countries keep replacing their fleets regularly, partly because incomes are high enough to realistically afford new vehicles.”

The researchers pointed specifically to Romania, Poland and Albania as markets where imported secondhand vehicles play a much larger role. As a result, the underlying age of some national fleets may be even greater than headline registration figures initially suggest.

The study, conducted in August 2026, compared more than 30 European countries using three primary measures: the percentage of cars at least 20 years old, the percentage at least 10 years old, and the percentage less than five years old. Those variables were combined into a Fleet Age Score ranging up to 100, with lower scores indicating newer national fleets.

Luxembourg recorded a score of just 1.6, well ahead of Belgium at 13.1 and Denmark at 17.1. The UK scored 18.8 and Norway 18.9, followed by Liechtenstein at 19.6, Austria at 20.8, Germany at 20.9, Switzerland at 23.7 and the Netherlands at 24.1.

Taken together, the numbers show that Europe is not moving toward a newer or more electric vehicle fleet at anything close to a uniform pace. In Luxembourg, frequent vehicle replacement keeps the average car relatively young. In Norway and Denmark, electrification is rapidly reshaping what people drive. Meanwhile, countries that depend heavily on imported used vehicles continue to operate fleets that can be dramatically older than those found just a few hundred miles away.

Tyler Durden
Tue, 09/15/2026 – 04:15